Military Robots Market Size, Share and Trends by Type (Land, Marine, and Airborne), Application, Range, System, Launch Mode, Level of Autonomy (Human-in-the-Loop, Human-on-the-Loop, and Highly Autonomous), Collaboration Architecture (Single-Robot, Multi-Robot, Manned-Unmanned Team, and Swarm Operations) – Global Forecast to 2031

icon1
USD 128.92 BN
MARKET SIZE, 2031
icon2
CAGR 25.1%
(2026-2031)
icon3
300
REPORT PAGES
icon4
200
MARKET TABLES

MILITARY ROBOTS MARKET OVERVIEW

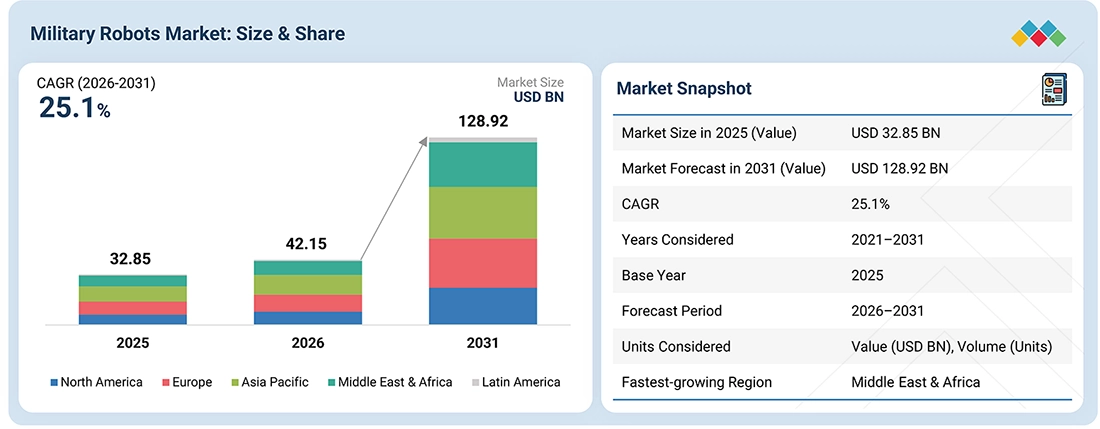
According to Marketsandmarkets, the Global Military Robots Market Size was valued at USD 42.15 billion in 2026 and is projected to reach USD 128.92 billion by 2031, growing at a CAGR of 25.1% from 2026-2031 In terms of volume, the market is projected to grow from 74,817 units in 2026 to 109,010 units by 2031. Armed forces are increasing the use of military robots for dangerous missions to reduce direct soldier exposure to battlefield threats. These systems are being deployed for surveillance, combat, explosive ordnance disposal, transportation, mine disposal, and other mission-support activities across land, marine, and airborne operations.

REPORT SCOPE

REPORT METRIC DETAILS
Market Size in 2025 USD 32.85 Billion
Market Forecast in 2031 USD 128.92 Billion
CAGR 25.1%
Years Considered 2021–2031
Base Year 2025
Forecast Period 2026-2031
Units Considered Value (USD Million/Billion), Volume (Units)
Report Coverage Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Top Companies
  • Milrem Robotics (Estonia)
  • Tencore (Ukraine)
  • Teledyne FLIR Defense (US)
  • Rheinmetall (Germany)
  • Elbit Systems (Israel)
Growth Drivers
  • Growing demand for unmanned systems in high risk military missions
  • Increasing need for persistent intelligence, surveillance, and reconnaissance capabilities
  • Expansion of robotic applications in battlefield logistics and casualty evacuation
  • Advancements in autonomous navigation, artificial intelligence, and sensor fusion
  • Rising demand for modular and multipurpose robotic platforms
Segments Covered
  • By Type:
    • Land (Wheeled
    • Tracked
    • Legged & Humanoid
    • Hybrid)
    • Marine (Unmanned Surface Vehicles (USV)
    • Unmanned Underwater Vehicles (UUV))
    • Airborne (Small
    • Tactical
    • Strategic)
  • By Application:
    • Land (Intelligence
    • Surveillance & Reconnaissance (ISR)
    • Explosive Ordnance Disposal (EOD)
    • Combat
    • Transportation & Delivery
    • Other Mission Support)
    • Marine (Intelligence
    • Surveillance & Reconnaissance (ISR)
    • Mine Disposal
    • Search & Rescue
    • Combat
    • Other Mission Support)
    • Airborne (Intelligence
    • Surveillance & Reconnaissance (ISR)
    • Combat
    • Delivery
    • Other Mission Support)
  • By Range:
    • Land (<1 KM
    • 1–5 KM
    • >5 KM)
    • Marine (<3 Nautical Miles / 5.5 KM
    • 3–5 Nautical Miles / 5.5–9.3 KM
    • >5 Nautical Miles / >9.6 KM)
    • Airborne (Visual Line of Sight (VLOS)
    • Extended Visual Line of Sight (EVLOS)
    • Beyond Visual Line of Sight (BVLOS))
  • By System:
    • Land (Payload
    • Navigation System
    • Controller System
    • Power System
    • Others)
    • Marine (Camera
    • Sensors & Radar
    • Lighting
    • Navigation System
    • Combat System
    • Others)
    • Airborne (Payload
    • Communication Systems
    • Navigation System
    • Propulsion System
    • Others)
  • By Launch Mode:
    • Land (Airdropped
    • Hand/Ground Launched)
    • Marine (Tube Launched
    • Surface Deployed
    • Airdropped)
    • Airborne (Hand/Ground Launched
    • Catapult Launched
    • Air Launched
    • Runway Launched)
  • By Level of Autonomy:
    • Human-in-the-Loop
    • Human-on-the-Loop
    • Highly Autonomous
  • By Collaboration Architecture:
    • Single-Robot Operation
    • Homogeneous Multi-Robot Team
    • Heterogeneous Multi-Robot Team
    • Manned-Unmanned Team
    • Swarm Operation
Regions Covered North America, Asia Pacific, Europe, Middle East & Africa, Latin America

KEY TAKEAWAYS

  • By Region
    The Middle East & African military robots market is expected to register the highest CAGR of 31.8% between 2026 and 2031.
  • By Type
    Marine is expected to register the highest CAGR of 26.7% between 2026 and 2031.
  • By Application
    Airborne is estimated to be the most dominant segment in 2026.
  • Competitive Landscape
    Milrem Robotics, Tencore, and Teledyne FLIR Defense were identified as some of the star players in the military robots market (global), given their strong market share and product footprint.

The Military Robots Industry is growing as armed forces increasingly adopt advanced sensor systems, autonomous navigation, and AI-based decision support. These technologies allow robots to operate with greater accuracy in complex and GPS-denied environments, detect obstacles, identify targets, and adjust their movement with limited human input. This is increasing the use of military robots across land, marine, and airborne missions where reliable autonomous operation is becoming more important.
military-robots-market Overview

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS

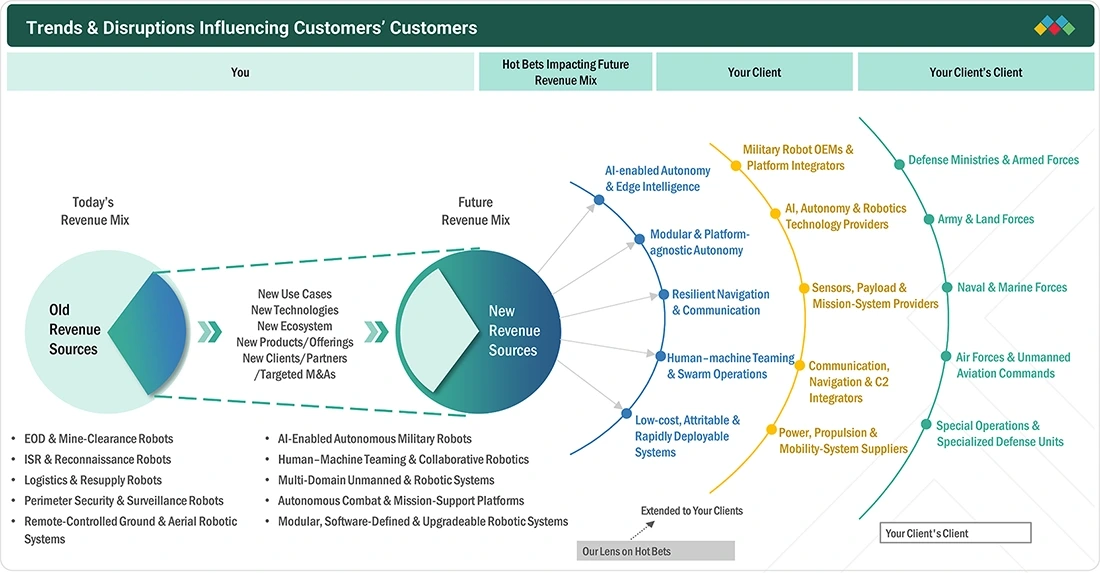
The impact on customers in the military robots market is driven by the need to improve mission efficiency with limited personnel and resources. A single robotic platform can support different tasks by using interchangeable payloads and mission equipment, which reduces the need for separate specialized systems. Common platforms, components, and controls can also simplify operator training, maintenance, and spare parts management. This helps defense organizations improve operational flexibility, equipment availability, and overall lifecycle cost.
military-robots-market Disruptions

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

MILITARY ROBOTS MARKET DYNAMICS

Drivers
Impact
Level
  • Growing requirement to reduce personnel exposure in high-risk military operations
  • Increasing requirement for persistent ISR and expanded battlespace awareness
RESTRAINTS
Impact
Level
  • Limited endurance, payload capacity, and onboard power availability of military robotic platforms
  • Regulatory, safety, and human-control requirements for weaponized autonomous systems
OPPORTUNITIES
Impact
Level
  • Expansion of military robots into battlefield logistics, combat engineering, EOD, mine warfare, and casualty support
  • Development of coordinated multi-robot and swarm operations for military missions
CHALLENGES
Impact
Level
  • Maintaining command, navigation, and communications in GPS-denied and electronically contested environments
  • Achieving interoperability across military robots, mission payloads, control stations, and allied forces

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Driver: Growing requirement to reduce personnel exposure in high-risk military operations

Military forces are increasingly using robots for missions where sending personnel directly can involve high risk. Military robots can support tasks such as explosive ordnance disposal, mine clearance, reconnaissance, combat support, and operations in hazardous areas. By using robots for these activities, armed forces can reduce direct exposure of soldiers to threats while maintaining mission capability. This supports wider adoption of military robots across land, marine, and airborne operations.

Restraint: Limited endurance, payload capacity, and onboard power availability of military robotic platforms

Military robots have limits on how long they can operate, how much equipment they can carry, and how much onboard power they can provide to sensors, communication systems, and mission payloads. These limitations can reduce mission duration and restrict the use of heavier or more power-intensive equipment. In demanding environments, frequent battery replacement, recharging, or refueling can also affect operational continuity and increase logistics requirements.

Opportunity: Expansion of military robots into battlefield logistics, combat engineering, EOD, mine warfare, and casualty support

Military robots are being considered for a wider range of support missions beyond surveillance and combat. They can be used to move supplies, support engineering work, handle explosive threats, clear mines, and assist with casualty evacuation in dangerous areas. Wider use across these mission areas can reduce the burden on personnel and improve support to frontline units, creating additional demand for specialized land, marine, and airborne robotic platforms.

Challenge: Maintaining command, navigation, and communications in GPS-denied and electronically contested environments

Military robots depend on reliable communication and navigation to operate effectively, but these functions can be disrupted by jamming, signal interference, cyber threats, or loss of GPS access. In contested environments, weak or interrupted links can reduce control, situational awareness, and mission effectiveness. Military robot developers therefore need resilient communication, alternative navigation, and secure control systems that can continue operating under electronic warfare conditions.

MILITARY ROBOTS MARKET SIZE, SHARE & TRENDS: COMMERCIAL USE CASES ACROSS INDUSTRIES

COMPANY USE CASE DESCRIPTION BENEFITS
company logo
Milrem Robotics’ THeMIS unmanned ground vehicles are being used by Ukrainian forces for demining, route clearance, resupply, and transporting equipment through areas that are difficult or dangerous for conventional vehicles. Milrem has delivered 14 THeMIS UGVs to Ukraine, with operational feedback confirming their use against anti-tank mines and unexploded ordnance. Reduces the need to send soldiers into mined or exposed areas. The same modular platform can support logistics, casualty evacuation, ordnance disposal, and other frontline missions, improve mission flexibility while lower personnel risk.
company logo
Tencore’s TerMIT UGVs are being used by the Armed Forces of Ukraine mainly for frontline logistics, including supply movement and casualty evacuation, with additional use in combat and engineering roles. Tencore stated in 2026 that it has delivered more than 4,000 UGVs to Ukrainian forces, while its systems have been developed continuously using frontline feedback. Enables supplies, equipment, and casualties to be moved along exposed frontline routes without requiring soldiers or crewed vehicles to enter the same areas. Its modular design also allows the platform to be adapted for combat, engineering, mine-related, and electronic-warfare support missions.
company logo
Teledyne FLIR Defense supplies Centaur unmanned ground vehicles to the US Army, Navy, Air Force, and Marine Corps under the MTRS Increment II program. EOD teams use Centaur to identify and dispose of improvised explosive devices, landmines, and unexploded ordnance, while additional payloads can support CBRN-related missions. Provides EOD personnel with greater stand-off distance from explosive and hazardous threats. Common robotic platforms across military services also support joint training, maintenance, and mission flexibility through interchangeable sensors and payloads.

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MILITARY ROBOTS MARKET ECOSYSTEM

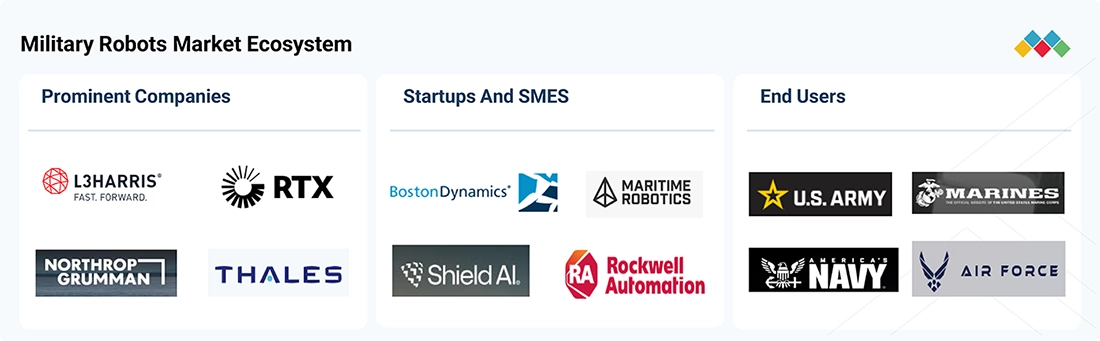
The military robots market includes unmanned platform manufacturers, sensor and payload suppliers, autonomy software developers, propulsion providers, and system integrators. Major companies such as Northrop Grumman, Boeing, Israel Aerospace Industries, Lockheed Martin Corporation, Teledyne Technologies Incorporated, BAE Systems, Elbit Systems Ltd., EDGE Group PJSC, L3Harris Technologies, Inc., Leonardo S.p.A., Thales, General Dynamics Corporation, Textron Inc., RTX, Kratos, General Atomics, Rheinmetall AG, QinetiQ, AeroVironment, Inc., Saab AB, Anduril Industries, Milrem AS, and Tencore provide military robotic systems across land, marine, and airborne applications. Other players such as Boston Dynamics, Shield AI, Rockwell Automation, Inc., Maritime Robotics, Saronic Technologies, Overland AI, and Havoc provide specialized robotic platforms, autonomous systems, mission software, and related technologies for surveillance, logistics, combat support, maritime operations, and other military applications.
military-robots-market Ecosystem

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MILITARY ROBOTS MARKET SEGMENTS
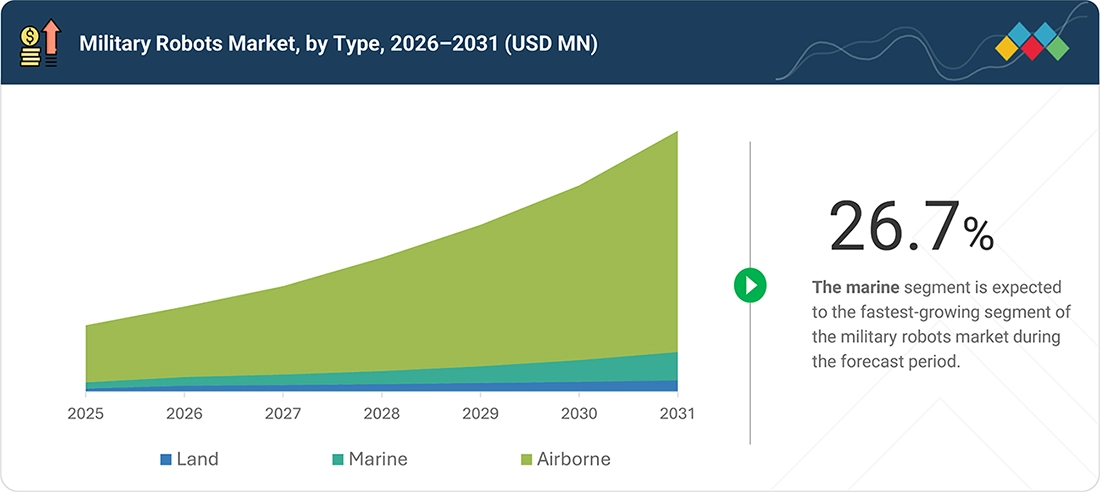
military-robots-market Segments

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Military Robots Market, By Type

The Airborne – Tactical segment holds the largest share of the market. Tactical military UAVs are widely used for ISR, targeting, communications support, and combat missions. Their ability to operate beyond frontline positions, cover large areas, and carry different mission payloads supports strong adoption across defense forces. NATO also identifies unmanned systems as increasingly central to military operations because they improve operational reach, persistence, and situational awareness.

Military Robots Market, By Application

The Airborne – Intelligence, Surveillance & Reconnaissance (ISR) segment holds the largest share of the market. Military UAVs can remain over operational areas for extended periods and provide real-time imagery, surveillance, target tracking, and battlefield information. This makes airborne ISR useful for monitoring large areas while limiting the need to place personnel close to threats.

Military Robots Market, By Range

The Airborne – Beyond Visual Line of Sight (BVLOS) segment holds the largest share of the market. BVLOS capability allows military UAVs to operate far beyond the operator’s direct sight and support long-range surveillance, reconnaissance, and combat missions. This extended operational reach is particularly important where forces need persistent coverage across large or difficult-to-access areas.

Military Robots Market, By System

The Airborne segment holds the largest share of the market. Airborne robotic systems depend on integrated payloads, communication systems, navigation systems, propulsion systems, and other mission equipment. The wide deployment of military UAVs across surveillance, reconnaissance, targeting, and combat missions creates continued demand for these onboard systems.

Military Robots Market, By Launch Mode

The Airborne – Runway Launched segment holds the largest share of the market. Runway-launched UAVs generally include larger tactical and strategic platforms designed for longer endurance, greater payload capacity, and extended operating range. These systems support persistent ISR, combat, and other long-duration missions that require larger aircraft and supporting ground infrastructure.

Military Robots Market, By Level of Autonomy

The Human-in-the-Loop segment holds the largest share of the market. Many fielded military robots continue to rely on operators for mission control and important operational decisions. Human involvement remains particularly relevant for complex missions and weapon-related actions, while autonomous functions are increasingly used for navigation, sensing, and other supporting tasks.

Military Robots Market, By Collaboration Architecture

The Single-Robot Operation segment holds the largest share of the market. Most operational military robots are currently deployed as individual platforms for defined missions such as ISR, EOD, logistics, combat support, and mine countermeasures. For example, the US Navy’s MCM USV operates as an individual semi-autonomous platform carrying modular payloads for minehunting, minesweeping, and mine neutralization.

MILITARY ROBOTS MARKET REGION

Middle East & Africa to be fastest-growing region in global military robots market during forecast period

The Middle East & African military robots market is expected to grow at the fastest rate during the forecast period. Growth is supported by increasing use of unmanned and autonomous systems for surveillance, reconnaissance, force protection, border security, and operations in high-risk environments. Military exercises in Africa are expanding the use of AI-enabled autonomous vehicles and unmanned aerial systems for reconnaissance, combat identification, and mission support. At the same time, rising security concerns and the need to reduce personnel exposure are encouraging armed forces across the region to adopt military robots across land, marine, and airborne operations.
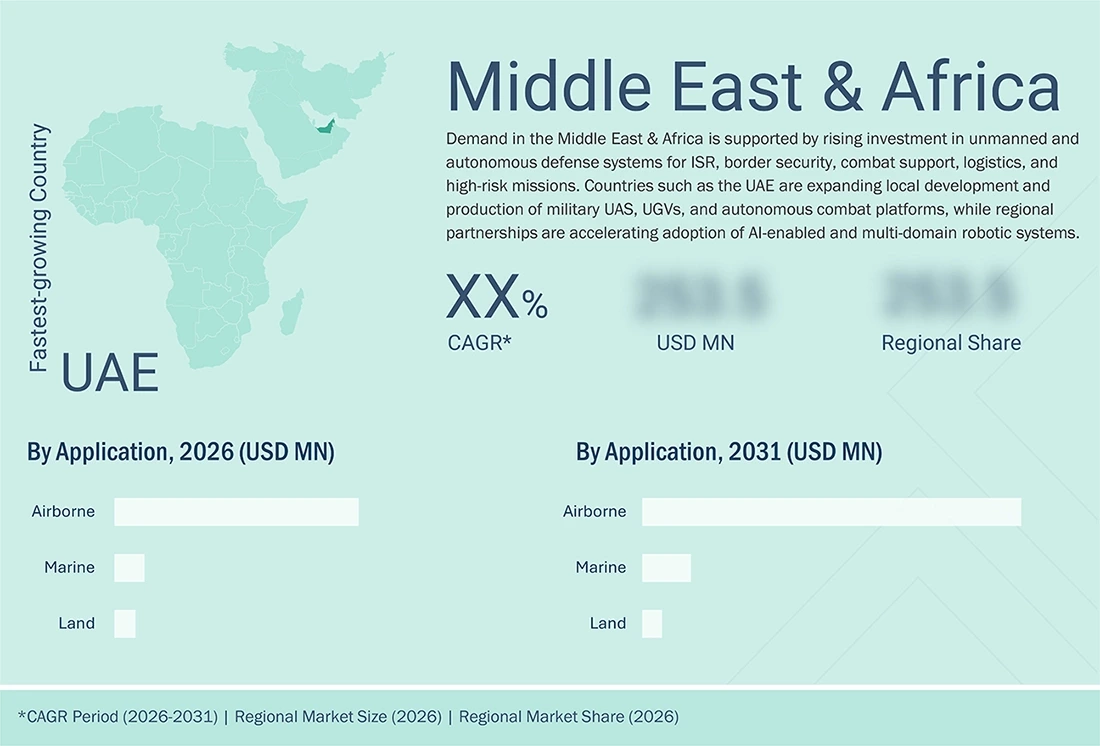
military-robots-market Region

MILITARY ROBOTS MARKET SIZE, SHARE & TRENDS: COMPANY EVALUATION MATRIX

The military robots market matrix includes Milrem AS (Star), supported by its strong position in unmanned ground vehicles and autonomous military systems. Its THeMIS platform supports combat, intelligence, logistics, CASEVAC, and ordnance-disposal missions and is in service or robotics programs across 20 countries. Milrem is also expanding its portfolio through systems such as HAVOC, VECTOR, MRCV and ARCOS. Boston Dynamics, Inc. (Emerging Leader) has built a strong position in legged robotic systems through its Spot platform. Spot supports non-weaponized military and government applications such as hazardous-area inspection, EOD, ISR, rescue, logistics, and CBRNE response, while its mobility and modular payload architecture allow operation in difficult environments.
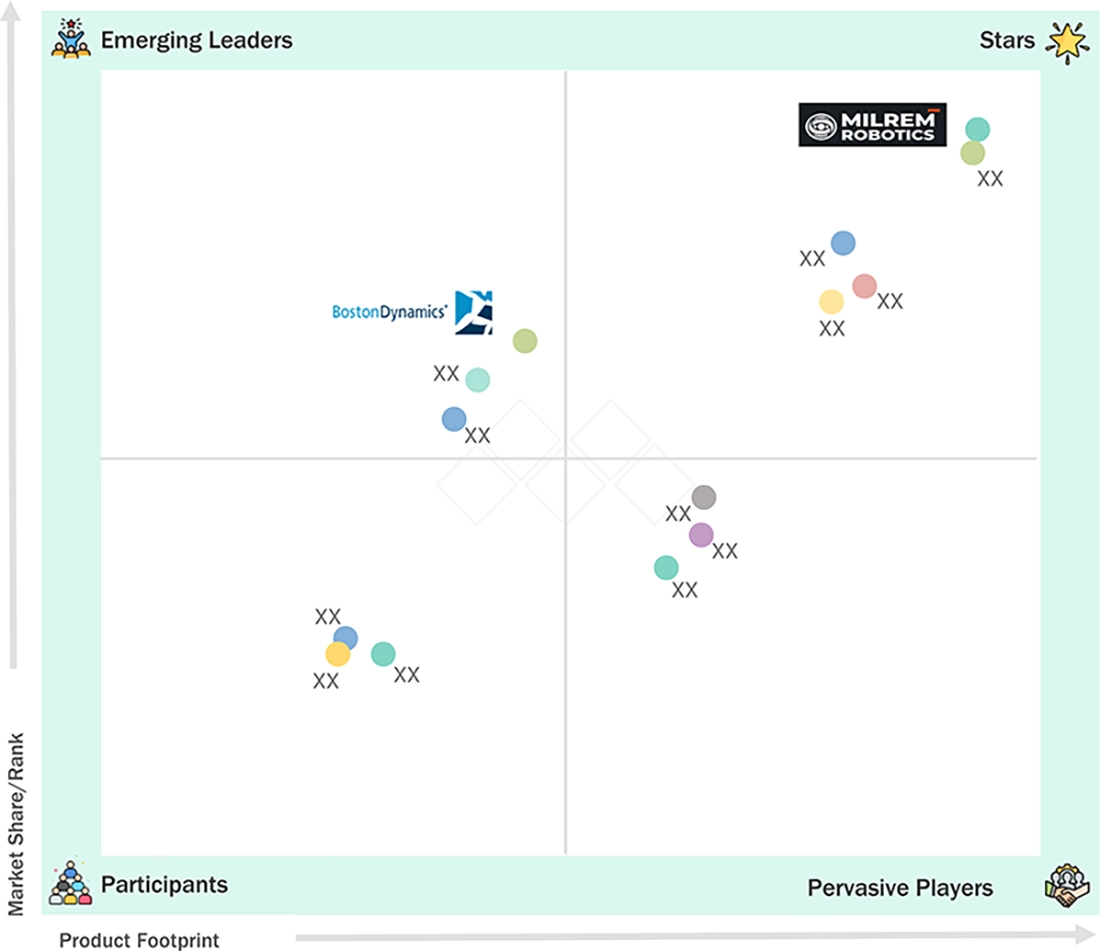
military-robots-market Evaluation Metrics

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

KEY MILITARY ROBOTS MARKET PLAYERS

List of Top Military Robots Companies

WHAT IS IN IT FOR YOU: MILITARY ROBOTS MARKET SIZE, SHARE & TRENDS REPORT CONTENT GUIDE
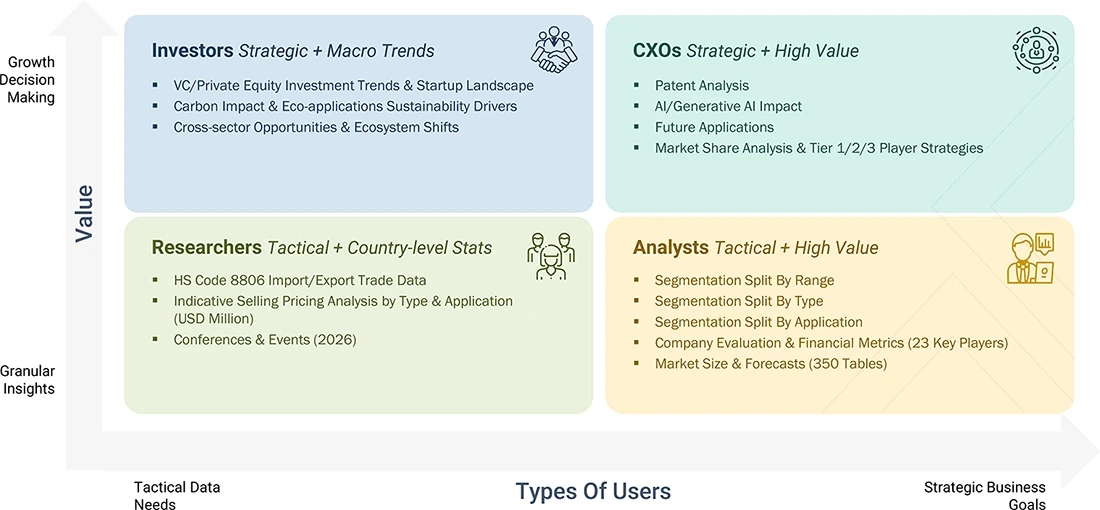
military-robots-market Content Guide

DELIVERED CUSTOMIZATIONS

We have successfully delivered the following deep-dive customizations:

CLIENT REQUEST CUSTOMIZATION DELIVERED VALUE ADDS
Leading Manufacturer Additional segment breakdown for countries Additional country-level market sizing tables for segments/sub-segments covered at the regional/global level to gain an understanding of market potential by each country
Emerging Leader Additional company profiles Competitive information on targeted players to gain granular insights on direct competition
Regional Market Leader Additional country market estimates Additional country-level deep dive for a more targeted understanding of the total addressable market

RECENT DEVELOPMENTS

  • July 2026 : Rheinmetall AG (Germany) completed the acquisition of a 51% majority stake in DOK-ING (Croatia). The deal directly expands Rheinmetall’s military robotics portfolio through DOK-ING’s unmanned ground systems for mine clearance, military engineering, reconnaissance, logistics, and other high-risk operations. The acquired business operates as Rheinmetall Unmanned Vehicles and is intended to support the development of autonomous combat and combat-support vehicles.
  • November 2025 : EDGE Group PJSC (UAE) and Anduril Industries, Inc. (US) agreed to form the EDGE-Anduril Production Alliance, a joint venture for developing, manufacturing, selling, and sustaining autonomous systems. Its first platform is the Omen Group 3 autonomous air vehicle, with the UAE committing to an initial 50 systems and EDGE contributing nearly USD 200 million toward the program and related development.
  • May 2025 : AeroVironment, Inc. (US) completed the acquisition of BlueHalo LLC (US). The transaction substantially broadened AeroVironment’s defense technology portfolio across autonomous systems, unmanned platforms, AI, counter-UAS, and related capabilities spanning air, land, and sea domains. The transaction was originally valued at approximately USD 4.1 billion during the announcement.


Table of Contents

checkmarkExclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.

TITLE
PAGE NO
1
INTRODUCTION


32
2
EXECUTIVE SUMMARY


38
3
PREMIUM INSIGHTS


44
4
MARKET OVERVIEW
Military robotics market poised for growth through modular platforms and multi-robot operations.


47
 
4.1
INTRODUCTION


4.2
MARKET DYNAMICS


4.2.1
DRIVERS


4.2.1.1
GROWING REQUIREMENT TO REDUCE PERSONNEL EXPOSURE IN HIGH-RISK MILITARY OPERATIONS


4.2.1.2
INCREASING REQUIREMENT FOR PERSISTENT ISR AND EXPANDED BATTLESPACE AWARENESS


4.2.1.3
BATTLEFIELD VALIDATION OF UNMANNED SYSTEMS ACCELERATING INTEGRATION INTO ROUTINE MILITARY OPERATIONS


4.2.2
RESTRAINTS


4.2.2.1
LIMITED ENDURANCE, PAYLOAD CAPACITY, AND ON-BOARD POWER AVAILABILITY OF MILITARY ROBOTIC PLATFORMS


4.2.2.2
REGULATORY, SAFETY, AND HUMAN CONTROL REQUIREMENTS FOR WEAPONIZED AUTONOMOUS SYSTEMS


4.2.3
OPPORTUNITIES


4.2.3.1
EXPANSION OF MILITARY ROBOTS INTO BATTLEFIELD LOGISTICS, COMBAT ENGINEERING, EOD, MINE WARFARE, AND CASUALTY EVACUATION MISSIONS


4.2.3.2
DEVELOPMENT OF COORDINATED MULTI-ROBOT AND SWARM OPERATIONS FOR MILITARY MISSIONS


4.2.3.3
ADOPTION OF MODULAR MILITARY ROBOTIC PLATFORMS SUPPORTING MISSION-SPECIFIC PAYLOAD INTEGRATION


4.2.4
CHALLENGES


4.2.4.1
MAINTAINING COMMAND, NAVIGATION, AND COMMUNICATIONS IN GPS-DENIED AND ELECTRONICALLY CONTESTED ENVIRONMENTS


4.2.4.2
ACHIEVING INTEROPERABILITY ACROSS MILITARY ROBOTS, MISSION PAYLOADS, CONTROL STATIONS, AND ALLIED FORCES


4.3
UNMET NEEDS AND WHITE SPACES


4.3.1
RESILIENT NAVIGATION AND COMMUNICATIONS IN CONTESTED ENVIRONMENTS


4.3.2
HIGHER ENDURANCE, PAYLOAD CAPACITY, AND POWER EFFICIENCY


4.3.3
CROSS-PLATFORM AND CROSS-OEM INTEROPERABILITY


4.3.4
MODULAR AND RAPIDLY RECONFIGURABLE MILITARY ROBOTIC PLATFORMS


4.4
INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES


4.4.1
AI, AUTONOMY, AND EDGE COMPUTING MARKET


4.4.2
MILITARY SENSORS AND ISR PAYLOADS MARKET


4.4.3
TACTICAL COMMUNICATIONS AND RESILIENT NETWORKING MARKET


4.4.4
MILITARY POWER AND ENERGY SYSTEMS MARKET


4.5
STRATEGIC MOVES BY TIER-1/2/3 PLAYERS


5
INDUSTRY TRENDS
Explore transformative shifts in defense industries with key insights on global trade and tech innovations.


59
 
5.1
ECOSYSTEM ANALYSIS


5.1.1
PROMINENT COMPANIES


5.1.2
STARTUPS AND SMES


5.1.3
END USERS


5.2
VALUE CHAIN ANALYSIS


5.3
TRADE ANALYSIS


5.3.1
IMPORT SCENARIO (HS CODE 8806)


5.3.2
EXPORT SCENARIO (HS CODE 8806)


5.4
CASE STUDY ANALYSIS


5.4.1
RHEINMETALL VALIDATED MISSION MASTER AUTONOMOUS UGV IN NATO REPMUS/DYMS 2025 EXERCISE


5.4.2
ANDURIL ADVANCED GHOST SHARK XL-AUV INTO ROYAL AUSTRALIAN NAVY PROGRAM OF RECORD


5.4.3
BOEING ADVANCED MQ-25A STINGRAY TOWARD US NAVY CARRIER OPERATIONS AND INITIAL PRODUCTION


5.5
KEY CONFERENCES AND EVENTS (2026-2027)


5.6
INVESTMENT AND FUNDING SCENARIO


5.7
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS


5.8
MACROECONOMIC OUTLOOK


5.8.1
INTRODUCTION


5.8.2
GDP TRENDS AND FORECAST


5.8.3
TRENDS IN GLOBAL MILITARY ROBOTS INDUSTRY


5.8.4
TRENDS IN GLOBAL DEFENSE INDUSTRY


5.9
PRICING ANALYSIS


5.10
VOLUME ANALYSIS


5.11
IMPACT OF 2025 US TARIFFS


5.11.1
INTRODUCTION


5.11.2
KEY TARIFF RATES


5.11.3
PRICE IMPACT ANALYSIS


5.11.4
IMPACT ON COUNTRY/REGION


5.11.4.1
US


5.11.4.2
EUROPE


5.11.4.3
ASIA PACIFIC


5.11.5
IMPACT ON END-USE INDUSTRIES


6
TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
AI-driven innovations redefine military robotics with autonomous control, multi-robot coordination, and strategic market impacts.


80
 
6.1
KEY TECHNOLOGIES


6.1.1
AUTONOMY & INTELLIGENT CONTROL


6.1.2
PERCEPTION & SENSOR FUSION


6.1.3
MOBILITY, PROPULSION & ROBOTIC ACTUATION


6.2
COMPLEMENTARY TECHNOLOGIES


6.2.1
RESILIENT COMMUNICATIONS & TACTICAL NETWORKING


6.2.2
ONBOARD COMPUTING & EDGE PROCESSING


6.2.3
MODULAR OPEN ARCHITECTURE & MISSION SYSTEM INTEGRATION


6.3
ADJACENT TECHNOLOGIES


6.3.1
HUMAN-MACHINE TEAMING & OPERATOR INTERFACES


6.3.2
MULTI-ROBOT COORDINATION & SWARMING


6.3.3
DIGITAL ENGINEERING, SIMULATION & VIRTUAL TESTING


6.4
TECHNOLOGY ROADMAP


6.5
PATENT ANALYSIS


6.6
FUTURE APPLICATIONS


6.6.1
IMPACT OF AI/GENERATIVE AI


6.6.2
IMPLEMENTATION OF AI IN MILITARY ROBOTS MARKET: TOP USE CASES AND MARKET POTENTIAL


6.6.3
IMPLEMENTATION OF AI IN MILITARY ROBOTS MARKET: CASE STUDIES


6.6.4
INTERCONNECTED ECOSYSTEM AND IMPACT ON MARKET PLAYERS


6.6.5
CLIENTS’ READINESS TO ADOPT AI/GENERATIVE AI


7
SUSTAINABILITY AND REGULATORY LANDSCAPE
Navigate complex global regulations to drive sustainable innovation in military robotics.


94
 
7.1
REGIONAL REGULATIONS AND COMPLIANCE


7.1.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


7.1.2
KEY REGULATIONS


7.1.3
INDUSTRY STANDARDS


7.2
SUSTAINABILITY INITIATIVES


7.2.1
ENERGY-EFFICIENT PROPULSION & POWER SYSTEMS


7.2.2
MODULAR DESIGN & PRODUCT LIFE EXTENSION


7.2.3
PREDICTIVE MAINTENANCE & DIGITAL TWIN-BASED SUSTAINMENT


7.2.4
ADDITIVE MANUFACTURING & LOCAL SPARE-PART PRODUCTION


7.2.5
DIGITAL ENGINEERING & VIRTUAL TESTING


7.3
CERTIFICATIONS, LABELING, AND ECO-STANDARDS


8
CUSTOMER LANDSCAPE & BUYER BEHAVIOR
Unlock unmet needs and stakeholder influence shaping military robotics purchase decisions.


103
 
8.1
DECISION-MAKING PROCESS


8.2
BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA


8.2.1
BUYING EVALUATION CRITERIA


8.2.2
BUYING CRITERIA


8.3
ADOPTION BARRIERS & INTERNAL CHALLENGES


8.4
UNMET NEEDS OF VARIOUS END-USE INDUSTRIES


9
MILITARY ROBOTS MARKET, BY TYPE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 8 Data Tables


111
 
9.1
INTRODUCTION


9.2
LAND


9.2.1
WHEELED


REQUIREMENT FOR FASTER ROBOTIC LOGISTICS ACROSS TACTICAL AREAS


9.2.2
TRACKED


9.2.2.1
DIFFICULT-TERRAIN MOBILITY AND HIGHER PAYLOAD REQUIREMENTS TO DRIVE GROWTH


9.2.3
LEGGED & HUMANOID


9.2.3.1
REQUIREMENT TO CROSS TERRAIN INACCESSIBLE TO CONVENTIONAL VEHICLES TO DRIVE GROWTH


9.2.4
HYBRID


9.2.4.1
HIGHER ENDURANCE AND ONBOARD POWER REQUIREMENTS TO DRIVE GROWTH


9.3
MARINE


9.3.1
UNMANNED SURFACE VEHICLE (USV)


9.3.1.1
FLEET-LEVEL USE OF CREWLESS SURFACE PLATFORMS TO DRIVE GROWTH


9.3.2
UNMANNED UNDERWATER VEHICLE (UUV)


9.3.2.1
LONGER-DURATION UNDERSEA SURVEILLANCE AND MINE MISSIONS TO DRIVE MARKET


9.4
AIRBORNE


9.4.1
SMALL


9.4.1.1
WIDER DISTRIBUTION OF DRONES TO TACTICAL UNITS TO DRIVE GROWTH


9.4.2
TACTICAL


9.4.2.1
CREWED-UNCREWED AIR TEAMING REQUIREMENTS TO DRIVE GROWTH


9.4.3
STRATEGIC


9.4.3.1
PERSISTENT WIDE-AREA SURVEILLANCE REQUIREMENTS TO DRIVE GROWTH


10
MILITARY ROBOTS MARKET, BY APPLICATION
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 8 Data Tables


119
 
10.1
INTRODUCTION


10.2
LAND


10.2.1
INTELLIGENCE, SURVEILLANCE & RECONNAISSANCE (ISR)


10.2.1.1
REQUIREMENT TO EXTEND BATTLEFIELD SENSING AHEAD OF TROOPS TO DRIVE GROWTH


10.2.2
EXPLOSIVE ORDNANCE DISPOSAL (EOD)


10.2.2.1
GREATER STAND-OFF FROM EXPLOSIVE THREATS TO DRIVE GROWTH


10.2.3
COMBAT


10.2.3.1
INTEGRATION OF ROBOTIC FIREPOWER INTO GROUND FORMATIONS TO DRIVE GROWTH


10.2.4
TRANSPORTATION & DELIVERY


10.2.4.1
CONTESTED BATTLEFIELD RESUPPLY REQUIREMENTS TO DRIVE GROWTH


10.2.5
OTHER MISSION SUPPORT


10.2.5.1
EXPANSION OF CASUALTY EVACUATION AND SPECIALIZED SUPPORT TASKS TO DRIVE GROWTH


10.3
MARINE


10.3.1
INTELLIGENCE, SURVEILLANCE & RECONNAISSANCE (ISR)


10.3.1.1
DISTRIBUTED MARITIME SENSING REQUIREMENTS TO DRIVE GROWTH


10.3.2
MINE DISPOSAL


10.3.2.1
REMOVAL OF SAILORS FROM MINE DANGER AREAS TO DRIVE GROWTH


10.3.3
SEARCH & RESCUE


10.3.3.1
SAFER ACCESS TO HAZARDOUS MARITIME AREAS TO DRIVE GROWTH


10.3.4
COMBAT


10.3.4.1
ADDITION OF STRIKE AND WARFARE PAYLOADS TO DRIVE GROWTH


10.3.5
OTHER MISSION SUPPORT


10.3.5.1
LONGER AUTONOMOUS ENDURANCE TO DRIVE GROWTH


10.4
AIRBORNE


10.4.1
INTELLIGENCE, SURVEILLANCE & RECONNAISSANCE (ISR)


10.4.1.1
WIDER DISTRIBUTION OF AERIAL SENSORS ACROSS TACTICAL FORMATIONS TO DRIVE GROWTH


10.4.2
COMBAT


10.4.2.1
CREWED-UNCREWED COMBAT TEAMING TO DRIVE GROWTH


10.4.3
DELIVERY


10.4.3.1
REQUIREMENT TO RESUPPLY FORWARD FORCES WITHOUT CREWED AIRCRAFT TO DRIVE GROWTH


10.4.4
OTHER MISSION SUPPORT


10.4.4.1
EXPANSION OF COMMUNICATION RELAY AND SPECIALIZED SUPPORT ROLES TO DRIVE GROWTH


11
MILITARY ROBOTS MARKET, BY RANGE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 8 Data Tables


129
 
11.1
INTRODUCTION


11.2
LAND


11.2.1
<1 KM


11.2.1.1
CLOSE-RANGE HAZARD INSPECTION AND EOD REQUIREMENTS TO DRIVE GROWTH


11.2.2
1–5 KM


11.2.2.1
FORWARD LOGISTICS AND CASUALTY MOVEMENT ACROSS TACTICAL AREAS TO DRIVE GROWTH


11.2.3
>5 KM


11.2.3.1
LONG-DISTANCE AUTONOMOUS LOGISTICS AND RECONNAISSANCE TO DRIVE GROWTH


11.3
MARINE


11.3.1
<3 NAUTICAL MILES / 5.5 KM


11.3.1.1
LOCAL MINE HUNTING AND UNDERWATER INSPECTION REQUIREMENTS TO DRIVE GROWTH


11.3.2
3–5 NAUTICAL MILES / 5.5–9.3 KM


11.3.2.1
GREATER STAND-OFF DISTANCE IN MINE WARFARE TO DRIVE GROWTH


11.3.3
>5 NAUTICAL MILES / >9.6 KM


11.3.3.1
PERSISTENT DISTRIBUTED MARITIME OPERATIONS TO DRIVE GROWTH


11.4
AIRBORNE


11.4.1
VISUAL LINE OF SIGHT (VLOS)


11.4.1.1
UNIT-LEVEL LOCAL RECONNAISSANCE REQUIREMENTS TO DRIVE GROWTH


11.4.2
EXTENDED VISUAL LINE OF SIGHT (EVLOS)


11.4.2.1
REQUIREMENT FOR DEEPER TACTICAL OBSERVATION TO DRIVE GROWTH


11.4.3
BEYOND VISUAL LINE OF SIGHT (BVLOS)


11.4.3.1
LONG-RANGE PERSISTENT ISR AND REMOTE OPERATIONS TO DRIVE GROWTH


12
MILITARY ROBOTS MARKET, BY SYSTEM
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 20 Data Tables


137
 
12.1
INTRODUCTION


12.2
LAND


12.2.1
PAYLOAD


12.2.1.1
EXPANSION OF MISSION-SPECIFIC TASKS TO DRIVE MODULAR PAYLOAD REQUIREMENTS FOR LAND MILITARY ROBOTS


12.2.1.2
RADAR/SENSORS


12.2.1.3
CAMERA


12.2.1.4
LASERS


12.2.1.5
ROBOTIC ARMS


12.2.1.6
COMBAT SYSTEM


12.2.2
NAVIGATION SYSTEM


12.2.2.1
OPERATION IN GPS-DENIED AND COMPLEX TERRAIN TO DRIVE NAVIGATION SYSTEMS FOR LAND MILITARY ROBOTS


12.2.3
CONTROLLER SYSTEM


12.2.3.1
HUMAN-MACHINE TEAMING REQUIREMENTS TO DRIVE MORE CAPABLE CONTROLLER SYSTEMS FOR LAND MILITARY ROBOTS


12.2.4
POWER SYSTEM


12.2.4.1
HIGHER SENSOR AND COMPUTING LOADS TO DRIVE POWER SYSTEM REQUIREMENTS FOR LAND MILITARY ROBOTS


12.2.5
OTHERS


12.3
MARINE


12.3.1
CAMERA


12.3.1.1
REQUIREMENT FOR REMOTE MARITIME OBSERVATION TO DRIVE GROWTH


12.3.2
SENSORS & RADAR


12.3.2.1
WIDER MARITIME THREAT DETECTION REQUIREMENTS TO DRIVE GROWTH


12.3.3
LIGHTING


12.3.3.1
DAY-AND-NIGHT MARINE OPERATIONS TO DRIVE GROWTH


12.3.4
NAVIGATION SYSTEM


12.3.4.1
LONGER AUTONOMOUS MISSIONS AND REDUCED OPERATOR CONTROL TO DRIVE MARINE ROBOT NAVIGATION SYSTEMS


12.3.5
COMBAT SYSTEM


12.3.5.1
INTEGRATION OF STRIKE AND WARFARE MISSIONS TO DRIVE GROWTH


12.3.6
OTHERS


12.4
AIRBORNE


12.4.1
PAYLOAD


12.4.1.1
WIDER ASSIGNMENT OF ISR AND ELECTRONIC MISSIONS TO DRIVE GROWTH


12.4.1.2
RADAR


12.4.1.2.1
SYNTHETIC APERTURE RADAR


12.4.1.2.2
ACTIVE ELECTRONICALLY SCANNED ARRAY RADAR


12.4.1.3
CAMERA


12.4.1.3.1
HIGH-RESOLUTION CAMERA


12.4.1.3.2
MULTISPECTRAL/HYPERSPECTRAL CAMERA


12.4.1.3.3
THERMAL CAMERA


12.4.1.3.4
EO/IR CAMERA


12.4.1.4
CBRN SENSORS


12.4.1.5
COMBAT SYSTEM


12.4.2
COMMUNICATION SYSTEM


12.4.2.1
LONGER-RANGE REMOTE CONTROL AND SENSOR DATA TRANSFER TO DRIVE GROWTH


12.4.3
NAVIGATION SYSTEM


12.4.3.1
GREATER AUTONOMOUS FLIGHT IN CONTESTED ENVIRONMENTS TO DRIVE GROWTH


12.4.3.2
GPS/GNSS


12.4.3.3
INERTIAL NAVIGATION SYSTEMS/INERTIAL MEASUREMENT UNITS (INS/IMU)


12.4.3.4
SENSE & AVOID SYSTEM


12.4.4
PROPULSION SYSTEM


12.4.4.1
HIGHER ENDURANCE AND PAYLOAD REQUIREMENTS TO DRIVE GROWTH


12.4.4.2
FULLY ELECTRIC


12.4.4.3
FUEL-BASED


12.4.5
OTHERS


13
MILITARY ROBOTS MARKET, BY LAUNCH MODE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 8 Data Tables


156
 
13.1
INTRODUCTION


13.2
LAND


13.2.1
AIRDROPPED


13.2.1.1
RAPID INSERTION BEYOND GROUND ACCESS ROUTES TO DRIVE GROWTH


13.2.2
HAND/GROUND LAUNCHED


13.2.2.1
ROUTINE DEPLOYMENT DIRECTLY FROM TACTICAL UNITS TO DRIVE GROWTH


13.3
MARINE


13.3.1
TUBE LAUNCHED


13.3.1.1
REQUIREMENT TO EXTEND SUBMARINE REACH WITHOUT EXPOSING HOST PLATFORM TO DRIVE GROWTH


13.3.2
SURFACE DEPLOYED


13.3.2.1
WIDER USE OF UNMANNED SYSTEMS FROM SHIPS AND SHORE TO DRIVE GROWTH


13.3.3
AIRDROPPED


13.3.3.1
RAPID MARITIME FORCE PROJECTION OVER LONG DISTANCES TO DRIVE GROWTH


13.4
AIRBORNE


13.4.1
HAND/GROUND LAUNCHED


13.4.1.1
REQUIREMENT FOR IMMEDIATE DRONE ACCESS AT SMALL-UNIT LEVEL TO DRIVE GROWTH


13.4.2
CATAPULT LAUNCHED


13.4.2.1
RUNWAY-FREE DEPLOYMENT OF LARGER FIXED-WING UAVS TO DRIVE GROWTH


13.4.3
AIR LAUNCHED


13.4.3.1
REQUIREMENT TO EXTEND CREWED AND UNCREWED AIRCRAFT REACH TO DRIVE GROWTH


13.4.4
RUNWAY LAUNCHED


13.4.4.1
LONG-ENDURANCE AND HEAVY-PAYLOAD MISSIONS TO DRIVE GROWTH


14
MILITARY ROBOTS MARKET, BY LEVEL OF AUTONOMY
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 2 Data Tables


164
 
14.1
INTRODUCTION


14.2
HUMAN-IN-THE-LOOP


14.2.1
REQUIREMENT FOR DIRECT HUMAN CONTROL IN HIGH-CONSEQUENCE MISSIONS TO DRIVE GROWTH


14.3
HUMAN-ON-THE-LOOP


14.3.1
REQUIREMENT TO REDUCE OPERATOR WORKLOAD WHILE RETAINING HUMAN OVERSIGHT TO DRIVE GROWTH


14.4
HIGHLY AUTONOMOUS


14.4.1
OPERATION IN COMPLEX AND COMMUNICATION-CONSTRAINED ENVIRONMENTS TO DRIVE GROWTH


15
MILITARY ROBOTS MARKET, BY COLLABORATION ARCHITECTURE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 2 Data Tables


168
 
15.1
INTRODUCTION


15.2
SINGLE-ROBOT OPERATION


15.2.1
REQUIREMENT FOR SIMPLE DIRECT CONTROL IN SPECIALIZED MISSIONS TO DRIVE GROWTH


15.3
HOMOGENEOUS MULTI-ROBOT TEAM


15.3.1
REQUIREMENT TO COVER LARGER AREAS WITH SIMILAR PLATFORMS TO DRIVE GROWTH


15.4
HETEROGENEOUS MULTI-ROBOT TEAM


15.4.1
COMBINING DIFFERENT ROBOTIC CAPABILITIES FOR SAME MISSION TO DRIVE GROWTH


15.5
MANNED-UNMANNED TEAM


15.5.1
REQUIREMENT TO EXTEND CREWED PLATFORM REACH AND REDUCE PERSONNEL EXPOSURE TO DRIVE GROWTH


15.6
SWARM OPERATION


15.6.1
REQUIREMENT TO COORDINATE LARGE NUMBERS OF ROBOTS WITH LIMITED OPERATOR INPUT TO DRIVE GROWTH


16
MILITARY ROBOTS MARKET, BY REGION
Comprehensive coverage of 9 Regions with country-level deep-dive of 14 Countries | 120 Data Tables.


173
 
16.1
INTRODUCTION


16.2
NORTH AMERICA


16.2.1
US


16.2.1.1
HUMAN-MACHINE FORMATIONS ACCELERATE INTEGRATION OF MILITARY ROBOTS ACROSS US FORCES


16.2.2
CANADA


16.2.2.1
MARITIME SURVEILLANCE REQUIREMENTS EXPAND CANADA’S ADOPTION OF MILITARY ROBOTIC PLATFORMS


16.3
EUROPE


16.3.1
UK


16.3.1.1
FRONT-LINE RISK REDUCTION ADVANCES UK'S DEPLOYMENT OF ROBOTIC MILITARY PLATFORMS


16.3.2
FRANCE


16.3.2.1
ROBOTIC COMBAT FORMATIONS ADVANCE FRANCE’S MILITARY ROBOTS MARKET


16.3.3
GERMANY


16.3.3.1
MINE-WARFARE MODERNIZATION STRENGTHENS GERMANY'S USE OF AUTONOMOUS UNDERWATER ROBOTS


16.3.4
ITALY


16.3.4.1
OPERATIONAL EXPERIMENTATION ADVANCES ITALY’S INTEGRATION OF MILITARY ROBOTIC PLATFORMS


16.3.5
POLAND


16.3.5.1
BATTLEFIELD READINESS AND DOMESTIC PROCUREMENT STRENGTHEN POLAND’S MILITARY ROBOTS MARKET


16.3.6
UKRAINE


16.3.6.1
FRONTLINE PERSONNEL SUBSTITUTION ACCELERATES UKRAINE’S MILITARY ROBOTS MARKET


16.3.7
REST OF EUROPE


16.4
ASIA PACIFIC


16.4.1
CHINA


16.4.1.1
MULTI-DOMAIN FORCE INTEGRATION ADVANCES CHINA’S MILITARY ROBOTS MARKET


16.4.2
INDIA


16.4.2.1
HIGH-ALTITUDE AND REMOTE-BORDER OPERATIONS STRENGTHEN INDIA’S ADOPTION OF MILITARY ROBOTS


16.4.3
JAPAN


16.4.3.1
ISLAND-DEFENSE AND UNDERSEA REQUIREMENTS EXPAND JAPAN’S MILITARY ROBOTS MARKET


16.4.4
SOUTH KOREA


16.4.4.1
MANPOWER CONSTRAINTS AND FRONTLINE READINESS STRENGTHEN SOUTH KOREA’S MILITARY ROBOTS MARKET


16.4.5
AUSTRALIA


16.4.5.1
LONG-RANGE OPERATIONS AND DISTRIBUTED FORCE REQUIREMENTS BROADEN AUSTRALIA’S MILITARY ROBOT DEPLOYMENT


16.4.6
REST OF ASIA PACIFIC


16.5
MIDDLE EAST


16.5.1
GCC


16.5.1.1
UAE


16.5.1.1.1
LARGE-SCALE AUTONOMOUS PROCUREMENT ACCELERATES MILITARY ROBOT ADOPTION IN UAE


16.5.1.2
SAUDI ARABIA


16.5.1.2.1
DEFENSE LOCALIZATION EXPANDS SAUDI ARABIA’S DOMESTIC BASE FOR MILITARY ROBOTIC SYSTEMS


16.5.2
ISRAEL


16.5.2.1
COMBAT EXPERIENCE ACCELERATES ISRAEL’S DEPLOYMENT OF ROBOTIC SYSTEMS ACROSS MULTIPLE DOMAINS


16.5.3
TURKEY


16.5.3.1
DOMESTIC PLATFORM DEVELOPMENT BROADENS TURKEY’S MILITARY ROBOT DEPLOYMENT ACROSS LAND AND SEA


16.5.4
REST OF MIDDLE EAST


16.6
REST OF THE WORLD


16.6.1
LATIN AMERICA


16.6.1.1
TERRITORIAL COVERAGE AND SELECTIVE MODERNIZATION SUSTAIN THE LATIN AMERICA MILITARY ROBOTS MARKET


16.6.2
AFRICA


16.6.2.1
COUNTER-INSURGENCY AND PERSISTENT SURVEILLANCE REQUIREMENTS EXPAND AFRICA’S MILITARY ROBOTS MARKET


17
COMPETITIVE LANDSCAPE
Analyze strategic maneuvers and market positions to identify emerging leaders and pervasive players.


262
 
17.1
INTRODUCTION


17.2
KEY PLAYER STRATEGIES/RIGHT TO WIN, 2021–2025


17.3
REVENUE ANALYSIS, 2021–2025


17.4
MARKET SHARE ANALYSIS, 2026


17.5
BRAND/PRODUCT COMPARISON


17.6
COMPANY VALUATION AND FINANCIAL METRICS


17.7
COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025


17.7.1
STARS


17.7.2
EMERGING LEADERS


17.7.3
PERVASIVE PLAYERS


17.7.4
PARTICIPANTS


17.7.5
COMPANY FOOTPRINT KEY PLAYERS


17.7.5.1
COMPANY FOOTPRINT


17.7.5.2
REGION FOOTPRINT


17.7.5.3
TYPE FOOTPRINT


17.7.5.4
APPLICATION FOOTPRINT


17.7.5.5
SYSTEM FOOTPRINT


17.8
COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025


17.8.1
PROGRESSIVE COMPANIES


17.8.2
RESPONSIVE COMPANIES


17.8.3
DYNAMIC COMPANIES


17.8.4
STARTING BLOCKS


17.8.5
COMPETITIVE BENCHMARKING


17.8.5.1
LIST OF STARTUPS/SMES


17.8.5.2
COMPETITIVE BENCHMARKING OF STARTUPS/SMES


17.9
COMPETITIVE SCENARIO


17.9.1
PRODUCT LAUNCHES


17.9.2
DEALS


17.9.3
OTHER DEVELOPMENTS


18
COMPANY PROFILES
In-depth Company Profiles of Leading Market Players with detailed Business Overview, Product and Service Portfolio, Recent Developments, and Unique Analyst Perspective (MnM View)


291
 
18.1
KEY PLAYERS


18.1.1
NORTHROP GRUMMAN


18.1.1.1
BUSINESS OVERVIEW


18.1.1.2
PRODUCTS OFFERED


18.1.1.3
RECENT DEVELOPMENTS


18.1.1.3.1
DEALS


18.1.1.3.2
OTHER DEVELOPMENTS


18.1.2
BOEING


18.1.3
ISRAEL AEROSPACE INDUSTRIES


18.1.4
LOCKHEED MARTIN CORPORATION


18.1.5
TELEDYNE TECHNOLOGIES INCORPORATED


18.1.6
BAE SYSTEMS


18.1.7
ELBIT SYSTEMS LTD.


18.1.8
EDGE GROUP PJSC


18.1.9
L3HARRIS TECHNOLOGIES, INC.


18.1.10
LEONARDO S.P.A.


18.1.11
THALES


18.1.12
GENERAL DYNAMICS CORPORATION


18.1.13
TEXTRON INC.


18.1.14
RTX


18.1.15
KRATOS


18.1.16
GENERAL ATOMICS


18.1.17
RHEINMETALL AG


18.1.18
QINETIQ


18.1.19
AEROVIRONMENT, INC.


18.1.20
SAAB AB


18.1.21
ANDURIL INDUSTRIES


18.1.22
TENCORE


18.2
OTHER PLAYERS


18.2.1
BOSTON DYNAMICS


18.2.2
SHIELD AI


18.2.3
ROCKWELL AUTOMATION, INC.


18.2.4
MARITIME ROBOTICS


18.2.5
SARONIC TECHNOLOGIES


18.2.6
OVERLAND AI


18.2.7
HAVOC


19
RESEARCH METHODOLOGY


406
 
19.1
RESEARCH DATA


19.1.1
SECONDARY DATA


19.1.1.1
KEY DATA FROM SECONDARY SOURCES


19.1.2
PRIMARY DATA


19.1.2.1
PRIMARY SOURCES


19.1.2.2
KEY DATA FROM PRIMARY SOURCES


19.1.3
BREAKDOWN OF PRIMARY INTERVIEWS


19.2
FACTOR ANALYSIS


19.2.1
INTRODUCTION


19.2.2
DEMAND-SIDE INDICATORS


19.2.3
SUPPLY-SIDE INDICATORS


19.3
MARKET SIZE ESTIMATION


19.3.1
BOTTOM-UP APPROACH


19.3.1.1
MARKET SIZE ESTIMATION METHODOLOGY (DEMAND SIDE)


19.3.1.2
MARKET SIZE ESTIMATION METHODOLOGY (SUPPLY SIDE)


19.3.2
TOP-DOWN APPROACH


19.4
DATA TRIANGULATION


19.5
RESEARCH ASSUMPTIONS


19.6
RESEARCH LIMITATIONS


19.7
RISK ASSESSMENT


20
APPENDIX


419
 
20.1
DISCUSSION GUIDE


20.2
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL


20.3
CUSTOMIZATION OPTIONS


20.4
RELATED REPORTS


20.5
AUTHOR DETAILS


LIST OF TABLES


TABLE 1
USD EXCHANGE RATES


TABLE 2
UNMET NEEDS AND WHITE SPACES


TABLE 3
CROSS-SECTOR OPPORTUNITIES


TABLE 4
STRATEGIC MOVES BY TIER-1/2/3 PLAYERS


TABLE 5
ROLE OF COMPANIES IN ECOSYSTEM


TABLE 6
IMPORT DATA FOR HS CODE 8806-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025 (USD THOUSAND)


TABLE 7
EXPORT DATA FOR HS CODE 8806-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025 (USD THOUSAND)


TABLE 8
KEY CONFERENCES AND EVENTS, 2026–2027


TABLE 9
GDP PERCENTAGE CHANGE, BY COUNTRY, 2021–2030


TABLE 10
INDICATIVE PRICING ANALYSIS (2025)


TABLE 11
VOLUME ANALYSIS MILITARY ROBOTS BY TYPE, 2021-2025 (UNITS)


TABLE 12
US-ADJUSTED RECIPROCAL TARIFF RATES


TABLE 13
EVOLUTION AND ROADMAP FOR MILITARY ROBOTS MARKET


TABLE 14
KEY PATENTS, 2021–2026


TABLE 15
COLLABORATIVE MULTI-ROBOT COMBAT & ISR OPERATIONS


TABLE 16
AUTONOMOUS LOGISTICS, RESUPPLY & CASUALTY SUPPORT


TABLE 17
IMPLEMENTATION OF AI IN MILITARY ROBOTS MARKET: TOP USE CASES AND MARKET POTENTIAL


TABLE 18
IMPLEMENTATION OF AI IN MILITARY ROBOTS MARKET: CASE STUDIES


TABLE 19
INTERCONNECTED ECOSYSTEM AND IMPACT ON MARKET PLAYERS


TABLE 20
NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 21
EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 22
ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 23
MIDDLE EAST: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 24
REST OF THE WORLD: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 25
MAJOR REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS, BY COUNTRY/REGION


TABLE 26
INDUSTRY STANDARDS IN MILITARY ROBOTS MARKET


TABLE 27
SUSTAINABILITY INITIATIVES IN MILITARY ROBOTS MARKET


TABLE 28
CERTIFICATIONS, LABELING, AND ECO-STANDARDS


TABLE 29
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY TYPE


TABLE 30
KEY BUYING CRITERIA, BY TYPE


TABLE 31
UNMET NEEDS IN MILITARY ROBOTS MARKET, BY SYSTEM


TABLE 32
MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 33
MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 34
MILITARY ROBOTS MARKET, BY LAND, 2021–2025 (USD MILLION)


TABLE 35
MILITARY ROBOTS MARKET, BY LAND, 2026–2031 (USD MILLION)


TABLE 36
MILITARY ROBOTS MARKET, BY MARINE, 2021–2025 (USD MILLION)


TABLE 37
MILITARY ROBOTS MARKET, BY MARINE, 2026–2031 (USD MILLION)


TABLE 38
MILITARY ROBOTS MARKET, BY AIRBORNE, 2021–2025 (USD MILLION)


TABLE 39
MILITARY ROBOTS MARKET, BY AIRBORNE, 2026–2031 (USD MILLION)


TABLE 40
MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 41
MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 42
MILITARY ROBOTS MARKET, BY LAND, 2021–2025 (USD MILLION)


TABLE 43
MILITARY ROBOTS MARKET, BY LAND, 2026–2031 (USD MILLION)


TABLE 44
MILITARY ROBOTS MARKET, BY MARINE, 2021–2025 (USD MILLION)


TABLE 45
MILITARY ROBOTS MARKET, BY MARINE, 2026–2031 (USD MILLION)


TABLE 46
MILITARY ROBOTS MARKET, BY AIRBORNE, 2021–2025 (USD MILLION)


TABLE 47
MILITARY ROBOTS MARKET, BY AIRBORNE, 2026–2031 (USD MILLION)


TABLE 48
MILITARY ROBOTS MARKET, BY RANGE, 2021–2025 (USD MILLION)


TABLE 49
MILITARY ROBOTS MARKET, BY RANGE, 2026–2031 (USD MILLION)


TABLE 50
MILITARY ROBOTS MARKET, BY LAND, 2021–2025 (USD MILLION)


TABLE 51
MILITARY ROBOTS MARKET, BY LAND, 2026–2031 (USD MILLION)


TABLE 52
MILITARY ROBOTS MARKET, BY MARINE, 2021–2025 (USD MILLION)


TABLE 53
MILITARY ROBOTS MARKET, BY MARINE, 2026–2031 (USD MILLION)


TABLE 54
MILITARY ROBOTS MARKET, BY AIRBORNE, 2021–2025 (USD MILLION)


TABLE 55
MILITARY ROBOTS MARKET, BY AIRBORNE, 2026–2031 (USD MILLION)


TABLE 56
MILITARY ROBOTS MARKET, BY SYSTEM, 2021–2025 (USD MILLION)


TABLE 57
MILITARY ROBOTS MARKET, BY SYSTEM, 2026–2031 (USD MILLION)


TABLE 58
MILITARY ROBOTS MARKET, BY LAND, 2021–2025 (USD MILLION)


TABLE 59
MILITARY ROBOTS MARKET, BY LAND, 2026–2031 (USD MILLION)


TABLE 60
MILITARY ROBOTS MARKET, BY PAYLOAD, 2021–2025 (USD MILLION)


TABLE 61
MILITARY ROBOTS MARKET, BY PAYLOAD, 2026–2031 (USD MILLION)


TABLE 62
MILITARY ROBOTS MARKET, BY MARINE, 2021–2025 (USD MILLION)


TABLE 63
MILITARY ROBOTS MARKET, BY MARINE, 2026–2031 (USD MILLION)


TABLE 64
MILITARY ROBOTS MARKET, BY AIRBORNE, 2021–2025 (USD MILLION)


TABLE 65
MILITARY ROBOTS MARKET, BY AIRBORNE, 2026–2031 (USD MILLION)


TABLE 66
MILITARY ROBOTS MARKET, BY PAYLOAD, 2021–2025 (USD MILLION)


TABLE 67
MILITARY ROBOTS MARKET, BY PAYLOAD, 2026–2031 (USD MILLION)


TABLE 68
MILITARY ROBOTS MARKET, BY RADAR, 2021–2025 (USD MILLION)


TABLE 69
MILITARY ROBOTS MARKET, BY RADAR, 2026–2031 (USD MILLION)


TABLE 70
MILITARY ROBOTS MARKET, BY CAMERA, 2021–2025 (USD MILLION)


TABLE 71
MILITARY ROBOTS MARKET, BY CAMERA, 2026–2031 (USD MILLION)


TABLE 72
MILITARY ROBOTS MARKET, BY NAVIGATION SYSTEM, 2021–2025 (USD MILLION)


TABLE 73
MILITARY ROBOTS MARKET, BY NAVIGATION SYSTEM, 2026–2031 (USD MILLION)


TABLE 74
MILITARY ROBOTS MARKET, BY PROPULSION SYSTEM, 2021–2025 (USD MILLION)


TABLE 75
MILITARY ROBOTS MARKET, BY PROPULSION SYSTEM, 2026–2031 (USD MILLION)


TABLE 76
MILITARY ROBOTS MARKET, BY LAUNCH MODE, 2021–2025 (USD MILLION)


TABLE 77
MILITARY ROBOTS MARKET, BY LAUNCH MODE, 2026–2031 (USD MILLION)


TABLE 78
MILITARY ROBOTS MARKET, BY LAND, 2021–2025 (USD MILLION)


TABLE 79
MILITARY ROBOTS MARKET, BY LAND, 2026–2031 (USD MILLION)


TABLE 80
MILITARY ROBOTS MARKET, BY MARINE, 2021–2025 (USD MILLION)


TABLE 81
MILITARY ROBOTS MARKET, BY MARINE, 2026–2031 (USD MILLION)


TABLE 82
MILITARY ROBOTS MARKET, BY AIRBORNE, 2021–2025 (USD MILLION)


TABLE 83
MILITARY ROBOTS MARKET, BY AIRBORNE, 2026–2031 (USD MILLION)


TABLE 84
MILITARY ROBOTS MARKET, BY LEVEL OF AUTONOMY, 2021–2025 (USD MILLION)


TABLE 85
MILITARY ROBOTS MARKET, BY LEVEL OF AUTONOMY, 2026–2031 (USD MILLION)


TABLE 86
MILITARY ROBOTS MARKET, BY COLLABORATION ARCHITECTURE, 2021–2025 (USD MILLION)


TABLE 87
MILITARY ROBOTS MARKET, BY COLLABORATION ARCHITECTURE, 2026–2031 (USD MILLION)


TABLE 88
MILITARY ROBOTS MARKET, BY REGION, 2021–2025 (USD MILLION)


TABLE 89
MILITARY ROBOTS MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 90
NORTH AMERICA: MILITARY ROBOTS MARKET, BY COUNTRY, 2021–2025 (USD MILLION)


TABLE 91
NORTH AMERICA: MILITARY ROBOTS MARKET, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 92
NORTH AMERICA: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 93
NORTH AMERICA: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 94
NORTH AMERICA: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 95
NORTH AMERICA: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 96
US: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 97
US: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 98
US: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 99
US: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 100
CANADA: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 101
CANADA: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 102
CANADA: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 103
CANADA: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 104
EUROPE MILITARY ROBOTS MARKET, BY COUNTRY, 2021–2025 (USD MILLION)


TABLE 105
EUROPE LOITERING MUNITIONS MARKET, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 106
EUROPE: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 107
EUROPE: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 108
EUROPE: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 109
EUROPE: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 110
UK: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 111
UK: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 112
UK: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 113
UK: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 114
FRANCE: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 115
FRANCE: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 116
FRANCE: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 117
FRANCE: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 118
GERMANY: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 119
GERMANY: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 120
GERMANY: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 121
GERMANY: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 122
ITALY: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 123
ITALY: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 124
ITALY: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 125
ITALY: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 126
POLAND: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 127
POLAND: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 128
POLAND: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 129
POLAND: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 130
UKRAINE: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 131
UKRAINE: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 132
UKRAINE: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 133
UKRAINE: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 134
REST OF EUROPE: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 135
REST OF EUROPE: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 136
REST OF EUROPE: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 137
REST OF EUROPE: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 138
ASIA PACIFIC MILITARY ROBOTS MARKET, BY COUNTRY, 2021–2025 (USD MILLION)


TABLE 139
ASIA PACIFIC MILITARY ROBOTS MARKET, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 140
ASIA PACIFIC: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 141
ASIA PACIFIC: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 142
ASIA PACIFIC: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 143
ASIA PACIFIC: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 144
CHINA: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 145
CHINA: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 146
CHINA: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 147
CHINA: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 148
INDIA: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 149
INDIA: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 150
INDIA: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 151
INDIA: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 152
JAPAN: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 153
JAPAN: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 154
JAPAN: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 155
JAPAN: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 156
SOUTH KOREA: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 157
SOUTH KOREA: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 158
SOUTH KOREA: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 159
SOUTH KOREA: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 160
AUSTRALIA: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 161
AUSTRALIA: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 162
AUSTRALIA: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 163
AUSTRALIA: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 164
REST OF ASIA PACIFIC: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 165
REST OF ASIA PACIFIC: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 166
REST OF ASIA PACIFIC: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 167
REST OF ASIA PACIFIC: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 168
MIDDLE EAST MILITARY ROBOTS MARKET, BY COUNTRY, 2021–2025 (USD MILLION)


TABLE 169
MIDDLE EAST MILITARY ROBOTS MARKET, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 170
MIDDLE EAST: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 171
MIDDLE EAST: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 172
MIDDLE EAST: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 173
MIDDLE EAST: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 174
UAE: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 175
UAE: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 176
UAE: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 177
UAE: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 178
SAUDI ARABIA: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 179
SAUDI ARABIA: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 180
SAUDI ARABIA: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 181
SAUDI ARABIA: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 182
ISRAEL: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 183
ISRAEL: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 184
ISRAEL: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 185
ISRAEL: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 186
TURKEY: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 187
TURKEY: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 188
TURKEY: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 189
TURKEY: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 190
REST OF MIDDLE EAST: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 191
REST OF MIDDLE EAST: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 192
REST OF MIDDLE EAST: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 193
REST OF MIDDLE EAST: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 194
REST OF THE WORLD: MILITARY ROBOTS MARKET, BY REGION, 2021–2025 (USD MILLION)


TABLE 195
REST OF THE WORLD: MILITARY ROBOTS MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 196
REST OF THE WORLD: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 197
REST OF THE WORLD: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 198
REST OF THE WORLD: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 199
REST OF THE WORLD: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 200
LATIN AMERICA: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 201
LATIN AMERICA: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 202
LATIN AMERICA: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 203
LATIN AMERICA: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 204
AFRICA: MILITARY ROBOTS MARKET, BY TYPE, 2021–2025 (USD MILLION)


TABLE 205
AFRICA: MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 206
AFRICA: MILITARY ROBOTS MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 207
AFRICA: MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 208
KEY PLAYER STRATEGIES/RIGHT TO WIN, 2021–2025


TABLE 209
MILITARY ROBOTS MARKET: DEGREE OF COMPETITION


TABLE 210
REGION FOOTPRINT


TABLE 211
TYPE FOOTPRINT


TABLE 212
APPLICATION FOOTPRINT


TABLE 213
SYSTEM FOOTPRINT


TABLE 214
LIST OF STARTUPS/SMES


TABLE 215
COMPETITIVE BENCHMARKING OF STARTUPS/SMES


TABLE 216
MILITARY ROBOTS MARKET: PRODUCT LAUNCHES, JANUARY 2021–AUGUST 2026


TABLE 217
MILITARY ROBOTS MARKET: DEALS, JANUARY 2021– AUGUST 2026


TABLE 218
MILITARY ROBOTS MARKET: OTHER DEVELOPMENTS, JANUARY 2021– AUGUST 2026


TABLE 219
NORTHROP GRUMMAN: COMPANY OVERVIEW


TABLE 220
NORTHROP GRUMMAN: PRODUCTS OFFERED


TABLE 221
NORTHROP GRUMMAN: DEALS


TABLE 222
NORTHROP GRUMMAN: OTHER DEVELOPMENTS


TABLE 223
BOEING: COMPANY OVERVIEW


TABLE 224
BOEING: PRODUCTS OFFERED


TABLE 225
BOEING: PRODUCT ENHANCEMENTS


TABLE 226
BOEING: DEALS


TABLE 227
BOEING: OTHER DEVELOPMENTS


TABLE 228
ISRAEL AEROSPACE INDUSTRIES: COMPANY OVERVIEW


TABLE 229
ISRAEL AEROSPACE INDUSTRIES: PRODUCTS OFFERED


TABLE 230
ISRAEL AEROSPACE INDUSTRIES: DEALS


TABLE 231
ISRAEL AEROSPACE INDUSTRIES: OTHER DEVELOPMENTS


TABLE 232
LOCKHEED MARTIN CORPORATION: COMPANY OVERVIEW


TABLE 233
LOCKHEED MARTIN CORPORATION: PRODUCTS OFFERED


TABLE 234
LOCKHEED MARTIN CORPORATION: DEALS


TABLE 235
LOCKHEED MARTIN CORPORATION: OTHER DEVELOPMENTS


TABLE 236
TELEDYNE TECHNOLOGIES INCORPORATED: COMPANY OVERVIEW


TABLE 237
TELEDYNE TECHNOLOGIES INCORPORATED: PRODUCTS OFFERED


TABLE 238
TELEDYNE TECHNOLOGIES INCORPORATED: DEALS


TABLE 239
TELEDYNE TECHNOLOGIES INCORPORATED: OTHER DEVELOPMENTS


TABLE 240
BAE SYSTEMS: COMPANY OVERVIEW


TABLE 241
BAE SYSTEMS: PRODUCTS OFFERED


TABLE 242
BAE SYSTEMS: PRODUCT ENHANCEMENTS


TABLE 243
BAE SYSTEMS: DEALS


TABLE 244
ELBIT SYSTEMS LTD.: COMPANY OVERVIEW


TABLE 245
ELBIT SYSTEMS LTD.: PRODUCTS OFFERED


TABLE 246
ELBIT SYSTEMS LTD.: DEALS


TABLE 247
ELBIT SYSTEMS LTD.: OTHER DEVELOPMENTS


TABLE 248
EDGE GROUP PJSC: COMPANY OVERVIEW


TABLE 249
EDGE GROUP PJSC: PRODUCTS OFFERED


TABLE 250
EDGE GROUP PJSC: PRODUCT LAUNCHES


TABLE 251
EDGE GROUP PJSC: DEALS


TABLE 252
EDGE GROUP PJSC: OTHER DEVELOPMENTS


TABLE 253
L3HARRIS TECHNOLOGIES, INC.: COMPANY OVERVIEW


TABLE 254
L3HARRIS TECHNOLOGIES, INC.: PRODUCTS OFFERED


TABLE 255
L3HARRIS TECHNOLOGIES, INC.: PRODUCT ENHANCEMENTS


TABLE 256
L3HARRIS TECHNOLOGIES, INC.: DEALS


TABLE 257
L3HARRIS TECHNOLOGIES, INC.: OTHER DEVELOPMENTS


TABLE 258
LEONARDO S.P.A.: COMPANY OVERVIEW


TABLE 259
LEONARDO S.P.A.: PRODUCTS OFFERED


TABLE 260
LEONARDO S.P.A.: DEALS


TABLE 261
LEONARDO S.P.A.: OTHER DEVELOPMENTS


TABLE 262
THALES: COMPANY OVERVIEW


TABLE 263
THALES: PRODUCTS OFFERED


TABLE 264
THALES: DEALS


TABLE 265
THALES: OTHER DEVELOPMENTS


TABLE 266
GENERAL DYNAMICS CORPORATION: COMPANY OVERVIEW


TABLE 267
GENERAL DYNAMICS CORPORATION: PRODUCTS OFFERED


TABLE 268
GENERAL DYNAMICS CORPORATION: PRODUCT LAUNCHES


TABLE 269
GENERAL DYNAMICS CORPORATION: DEALS


TABLE 270
GENERAL DYNAMICS CORPORATION: OTHER DEVELOPMENTS


TABLE 271
TEXTRON INC.: COMPANY OVERVIEW


TABLE 272
TEXTRON INC.: PRODUCTS OFFERED


TABLE 273
TEXTRON INC.: DEALS


TABLE 274
TEXTRON INC.: OTHER DEVELOPMENTS


TABLE 275
RTX: COMPANY OVERVIEW


TABLE 276
RTX: PRODUCTS OFFERED


TABLE 277
RTX: DEALS


TABLE 278
KRATOS: COMPANY OVERVIEW


TABLE 279
KRATOS: PRODUCTS OFFERED


TABLE 280
KRATOS: PRODUCT LAUNCHES


TABLE 281
KRATOS: DEALS


TABLE 282
KRATOS: OTHER DEVELOPMENTS


TABLE 283
GENERAL ATOMICS: COMPANY OVERVIEW


TABLE 284
GENERAL ATOMICS: PRODUCTS OFFERED


TABLE 285
GENERAL ATOMICS: DEALS


TABLE 286
GENERAL ATOMICS: OTHER DEVELOPMENTS


TABLE 287
RHEINMETALL AG: COMPANY OVERVIEW


TABLE 288
RHEINMETALL AG: PRODUCTS OFFERED


TABLE 289
RHEINMETALL AG: DEALS


TABLE 290
RHEINMETALL AG: OTHER DEVELOPMENTS


TABLE 291
QINETIQ: COMPANY OVERVIEW


TABLE 292
QINETIQ: PRODUCTS OFFERED


TABLE 293
QINETIQ: DEALS


TABLE 294
QINETIQ: OTHER DEVELOPMENTS


TABLE 295
AEROVIRONMENT, INC.: COMPANY OVERVIEW


TABLE 296
AEROVIRONMENT, INC.: PRODUCTS OFFERED


TABLE 297
AEROVIRONMENT, INC.: PRODUCT LAUNCHES


TABLE 298
AEROVIRONMENT, INC.: DEALS


TABLE 299
AEROVIRONMENT, INC.: OTHER DEVELOPMENTS


TABLE 300
SAAB AB: COMPANY OVERVIEW


TABLE 301
SAAB AB: PRODUCTS OFFERED


TABLE 302
SAAB AB: DEALS


TABLE 303
SAAB AB: OTHER DEVELOPMENTS


TABLE 304
ANDURIL INDUSTRIES: COMPANY OVERVIEW


TABLE 305
ANDURIL INDUSTRIES: PRODUCTS OFFERED


TABLE 306
ANDURIL INDUSTRIES: PRODUCT LAUNCHES


TABLE 307
ANDURIL INDUSTRIES: DEALS


TABLE 308
ANDURIL INDUSTRIES: OTHER DEVELOPMENTS


TABLE 309
TENCORE: COMPANY OVERVIEW


TABLE 310
TENCORE: PRODUCTS OFFERED


TABLE 311
TENCORE: DEALS


TABLE 312
TENCORE: OTHER DEVELOPMENTS


TABLE 313
BOSTON DYNAMICS: COMPANY OVERVIEW


TABLE 314
SHIELD AI: COMPANY OVERVIEW


TABLE 315
ROCKWELL AUTOMATION, INC.: COMPANY OVERVIEW


TABLE 316
MARITIME ROBOTICS: COMPANY OVERVIEW


TABLE 317
SARONIC TECHNOLOGIES: COMPANY OVERVIEW


TABLE 318
OVERLAND AI: COMPANY OVERVIEW


TABLE 319
HAVOC: COMPANY OVERVIEW


LIST OF FIGURES


FIGURE 1
MARKET SCENARIO


FIGURE 2
MILITARY ROBOTS MARKET, 2021-2031


FIGURE 3
MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN MILITARY ROBOTS MARKET


FIGURE 4
HIGH-GROWTH SEGMENTS IN MILITARY ROBOTS MARKET


FIGURE 5
AI, SWARM ROBOTICS, AND OPEN ARCHITECTURES SHAPING MILITARY ROBOTS MARKET


FIGURE 6
MIDDLE EAST TO BE FASTEST-GROWING REGIONAL MARKET DURING FORECAST PERIOD


FIGURE 7
RISING ADOPTION OF AUTONOMOUS AND ROBOTIC SYSTEMS TO DRIVE MILITARY ROBOTS MARKET


FIGURE 8
AIRBORNE TYPE SEGMENT TO ACCOUNT FOR LARGEST SHARE DURING FORECAST PERIOD


FIGURE 9
AIRBORNE APPLICATION SEGMENT TO EXHIBIT HIGHEST GROWTH DURING FORECAST PERIOD


FIGURE 10
HUMAN-ON-THE-LOOP SEGMENT TO ACCOUNT FOR LARGEST MARKET SHARE IN 2026


FIGURE 11
SWARM OPERATION SEGMENT TO ACCOUNT FOR HIGHEST GROWTH DURING FORECAST PERIOD


FIGURE 12
MILITARY ROBOTS MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES


FIGURE 13
ECOSYSTEM ANALYSIS


FIGURE 14
VALUE CHAIN ANALYSIS


FIGURE 15
IMPORT DATA FOR HS CODE 8806-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025 (USD THOUSAND)


FIGURE 16
EXPORT DATA FOR HS CODE 8806-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025 (USD THOUSAND)


FIGURE 17
INVESTMENT AND FUNDING SCENARIO, 2021−2025 (USD BILLION)


FIGURE 18
INVESTMENT AND FUNDING SCENARIO, BY FUNDING STAGE, 2021−2025 (USD BILLION)


FIGURE 19
INVESTMENT AND FUNDING SCENARIO, BY COUNTRY, 2021−2025 (USD BILLION)


FIGURE 20
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS


FIGURE 21
TECHNOLOGY ROADMAP FOR MILITARY ROBOTS MARKET


FIGURE 22
PATENT ANALYSIS, 2016–2026


FIGURE 23
FUTURE APPLICATIONS


FIGURE 24
IMPACT OF AI/GENERATIVE AI


FIGURE 25
MILITARY ROBOTS MARKET: DECISION-MAKING FACTORS


FIGURE 26
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY TYPE


FIGURE 27
KEY BUYING CRITERIA, BY TYPE


FIGURE 28
ADOPTION BARRIERS & INTERNAL CHALLENGES


FIGURE 29
MILITARY ROBOTS MARKET, BY TYPE, 2026–2031 (USD MILLION)


FIGURE 30
MILITARY ROBOTS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


FIGURE 31
MILITARY ROBOTS MARKET, BY RANGE, 2026–2031 (USD MILLION)


FIGURE 32
MILITARY ROBOTS MARKET, BY SYSTEM, 2026–2031 (USD MILLION)


FIGURE 33
MILITARY ROBOTS MARKET, BY LAUNCH MODE, 2026–2031 (USD MILLION)


FIGURE 34
MILITARY ROBOTS MARKET, BY LEVEL OF AUTONOMY, 2026–2031 (USD MILLION)


FIGURE 35
MILITARY ROBOTS MARKET, BY COLLABORATION ARCHITECTURE, 2026–2031 (USD MILLION)


FIGURE 36
ASIA PACIFIC TO ACCOUNT FOR LARGEST MARKET SHARE IN 2026


FIGURE 37
NORTH AMERICA: MILITARY ROBOTS MARKET SNAPSHOT


FIGURE 38
EUROPE: MILITARY ROBOTS MARKET SNAPSHOT


FIGURE 39
ASIA PACIFIC: MILITARY ROBOTS MARKET SNAPSHOT


FIGURE 40
MIDDLE EAST: MILITARY ROBOTS MARKET SNAPSHOT


FIGURE 41
REST OF THE WORLD: MILITARY ROBOTS MARKET SNAPSHOT


FIGURE 42
REVENUE ANALYSIS OF TOP 5 PLAYERS, 2021–2025


FIGURE 43
MARKET SHARE ANALYSIS, 2026


FIGURE 44
BRAND/PRODUCT COMPARISON


FIGURE 45
FINANCIAL METRICS OF PROMINENT PLAYERS, 2026


FIGURE 46
COMPANY VALUATION OF PROMINENT PLAYERS, 2026


FIGURE 47
MILITARY ROBOTS MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025


FIGURE 48
COMPANY FOOTPRINT


FIGURE 49
COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025


FIGURE 50
NORTHROP GRUMMAN: COMPANY SNAPSHOT


FIGURE 51
BOEING: COMPANY SNAPSHOT


FIGURE 52
LOCKHEED MARTIN CORPORATION: COMPANY SNAPSHOT


FIGURE 53
TELEDYNE TECHNOLOGIES INCORPORATED: COMPANY SNAPSHOT


FIGURE 54
BAE SYSTEMS: COMPANY SNAPSHOT


FIGURE 55
ELBIT SYSTEMS LTD.: COMPANY SNAPSHOT


FIGURE 56
L3HARRIS TECHNOLOGIES, INC.: COMPANY SNAPSHOT


FIGURE 57
LEONARDO S.P.A.: COMPANY SNAPSHOT


FIGURE 58
THALES: COMPANY SNAPSHOT


FIGURE 59
GENERAL DYNAMICS CORPORATION: COMPANY SNAPSHOT


FIGURE 60
TEXTRON INC.: COMPANY SNAPSHOT


FIGURE 61
RTX: COMPANY SNAPSHOT


FIGURE 62
KRATOS: COMPANY SNAPSHOT


FIGURE 63
RHEINMETALL AG: COMPANY SNAPSHOT


FIGURE 64
QINETIQ: COMPANY SNAPSHOT


FIGURE 65
AEROVIRONMENT, INC.: COMPANY SNAPSHOT


FIGURE 66
SAAB AB: COMPANY SNAPSHOT


FIGURE 67
RESEARCH DESIGN MODEL


FIGURE 68
RESEARCH DESIGN


FIGURE 69
BOTTOM-UP APPROACH


FIGURE 70
TOP-DOWN APPROACH


FIGURE 71
DATA TRIANGULATION


Methodology

The study used four main activities to estimate the current size of the military robots market. First, detailed secondary research was conducted to collect information on military robotic platforms, manufacturers, system types, applications, defense programs, procurement contracts, military budgets, deliveries, deployments, and ongoing development programs. The collected information and key assumptions were then checked through primary interviews with industry participants and experts across the value chain. Demand-side analysis was used to estimate spending on military robots by platform, application, end user, and region. Finally, market breakdown and data triangulation were used to calculate the size of each segment and subsegment.

Secondary Research

Secondary research included information from government procurement portals, defense ministries, armed forces, defense agencies, company annual reports, regulatory filings, investor presentations, product documents, press releases, technical papers, journals, along with the recognized defense databases. Sources such as SIPRI were used to review military spending, equipment transfers and procurement activity, while government budget documents and procurement records were used to track military robot programs, contracts, orders and deliveries. Company filings and official product information were used to study military robot portfolios, revenues, contracts, technologies, applications, customers and geographical presence.

Primary Research

Primary research was conducted after completing the secondary research. Interviews were conducted with military robot manufacturers, component suppliers, system integrators, technology providers, distributors, defense procurement officials, armed forces personnel, defense experts, and other industry participants. The interviews covered major countries across North America, Europe, Asia Pacific, the Middle East & Africa, and Latin America. Primary information was collected through questionnaires, emails, and telephone interviews and was used to check market estimates, procurement trends, pricing, demand patterns, applications, platform adoption, and segment-level assumptions.
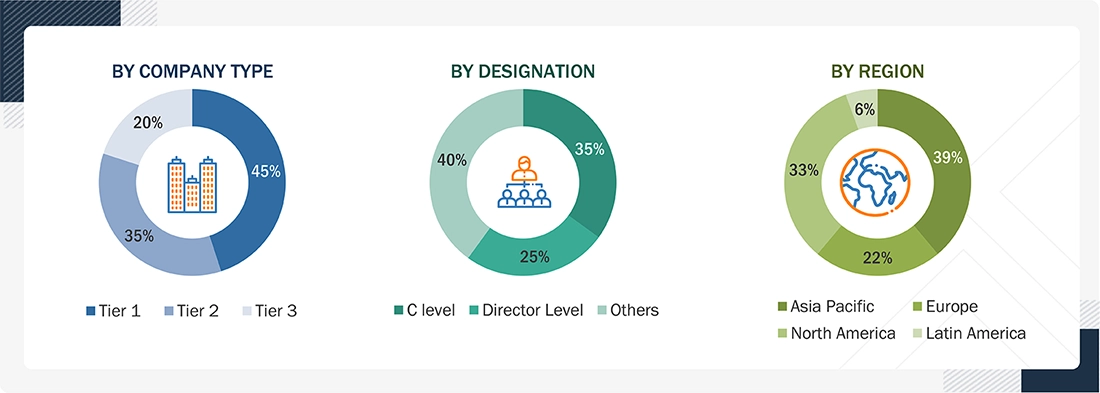
Military Robots Market Size, and Share

To know about the assumptions considered for the study, download the pdf brochure

Market Size Estimation

The top-down and bottom-up approaches were used to estimate and validate the size of the military robots market. The research methodology used to estimate the size of the market included the following details:

  • Key military robot companies were identified through secondary research. Their market shares were estimated using company revenues, military robot product portfolios, contract activity, delivery units, application presence and regional presence. Annual reports, financial filings, product documents, procurement records, and interviews with company executives, engineers, system integrators, distributors, and other industry participants were used for the analysis.
  • Market shares, segment splits, regional shares, and growth rates were first estimated using secondary sources and then checked through primary interviews. The analysis covered military robot type, application, range, system, launch mode, level of autonomy, collaboration architecture, pricing, delivery volumes, and deployment activity.
  • Demand for military robots across defense applications was considered. Defense procurement plans, military modernization programs, operational requirements, platform replacement, autonomy requirements, payload integration, interoperability, and deployment needs were also reviewed because they affect military robot adoption.
  • The collected information was compared and combined through data triangulation. The final market values were calculated using company-level revenues, military robot delivery units, average selling prices, contract values, procurement activity, regional demand patterns, and primary interview validation.

Military Robots Market : Top-Down and Bottom-Up Approach
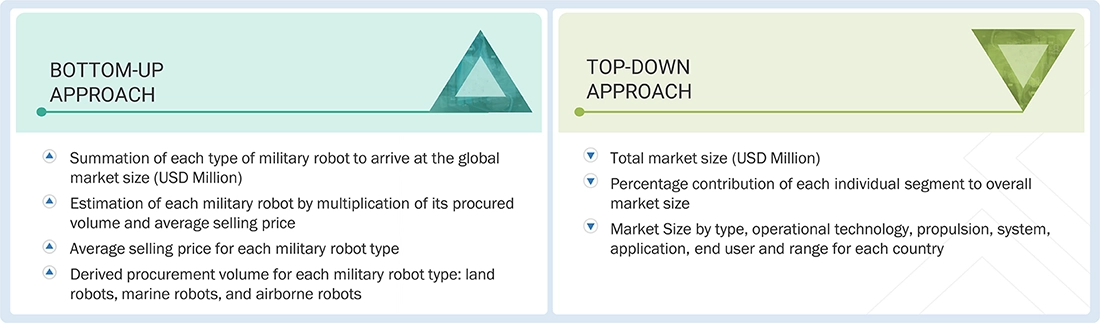
Military Robots Market Top Down and Bottom Up Approach

Data Triangulation

After determining the overall market size, the military robots market was divided into its main segments and subsegments. Data triangulation and market breakdown were used to develop estimates for each segment and subsegment. The analysis considered factors from both the demand and supply sides, including military robot procurement, delivery volumes, defense programs, platform requirements, applications, pricing, company participation, and regional demand. The final market estimates were then checked using both top-down and bottom-up approaches to ensure consistency across the overall market, regions, segments, and subsegments.

Market Definition

A robot is a machine designed to carry out several tasks by sensing, analyzing in a deliberative and non-mechanical way, and acting according to the requirements. In the military, robots are used for various functions, including warfare, picking and placing objects, firefighting, and detecting metal. Military robots can be operated semi- or fully autonomously and do not depend entirely on humans for control. For example, teleoperated drones, such as the US Air Force Predator, are unmanned aerial vehicles that make most decisions independently. Military robots can be expendable or recoverable and are designed to carry a lethal or a non-lethal payload.

Military robots form a dynamic segment of the defense industry focused on the production and deployment of robotic systems designed to enhance operational capabilities across land, air, and maritime domains. These systems leverage advanced technologies such as artificial intelligence, autonomous navigation, and state-of-the-art sensors to support mission-critical applications, including surveillance, reconnaissance, logistics, and combat operations. Driven by increasing defense budgets, technological advancements, and the need to minimize human risk in high-stakes environments, this market represents a significant area of innovation and strategic investment for military modernization initiatives worldwide.

Key Stakeholders

  • Defense Ministries & Procurement Agencies
  • Armed Forces & Military End Users
  • Military Robot OEMs & Defense Prime Contractors
  • Component, Subsystem & Payload Suppliers
  • AI, Autonomy, Communications & C2 Technology Providers
  • System Integrators & Engineering Service Providers
  • Defense R&D, Testing & Certification Organizations
  • Maintenance, Training & Lifecycle Support Providers
  • Defense Alliances & Multinational Standardization Bodies

Report Objectives

  • To define, describe, segment, and forecast the size of the military robots market based on type, application, range, system, launch mode, level of autonomy, collaboration architecture, and region
  • To forecast the size of market segments across five regions: North America, Europe, Asia Pacific, the Middle East & Africa, and Latin America
  • To identify and analyze key drivers, restraints, opportunities, and challenges influencing the growth of the market
  • To identify industry trends, market trends, and technology trends in the market
  • To analyze micro markets with respect to individual technology trends, growth prospects, and their contribution to the overall market
  • To strategically profile key market players and analyze their market position and core capabilities
  • To provide a detailed competitive landscape of the market and analyze competitive strategies such as product launches, partnerships, agreements, and collaborations adopted by key players
  • To assess the financial position of key players along with their key products, unique offerings, and recent developments

Available customizations:

MarketsandMarkets offers the following customizations for this market report:

  • Additional country-level analysis of the military robots market
  • Profiling of other market players (up to 5)

Product Analysis

  • Product matrix, which provides a detailed comparison of the product portfolio of each company in the military robots market


Key Questions Addressed by the Report

What is the current size of the Military Robots Market?

The global Military Robots Market is estimated at USD 18.20 billion in 2024 and is projected to reach USD 26.49 billion by 2029.

What is the expected CAGR of the Military Robots Market?

The market is expected to grow at a CAGR of 7.8% during 2024–2029, driven by rising defense modernization programs and increasing adoption of autonomous systems.

What are the key growth drivers of the Military Robots Market?

Major growth drivers include increasing demand for autonomous military operations, AI-enabled battlefield systems, ISR missions, force protection requirements, and rising investments in unmanned land, air, and marine platforms.

Which region dominates the Military Robots Market?

North America leads the market, accounting for over 40% of global revenue in 2024, supported by high defense spending and advanced robotics development programs.

Which region is expected to witness the fastest growth?

Asia Pacific is projected to register the highest growth rate through 2030 due to increasing military modernization initiatives in China, India, Japan, and South Korea.

What are the major trends shaping the Military Robots Market?

Key trends include AI-powered autonomous decision-making, swarm robotics, human-machine teaming, GPS-denied navigation technologies, unmanned maritime systems, and advanced ISR capabilities.

Which segment holds the largest market share?

The Airborne Robots/UAV segment accounted for more than 51% of the market share in 2024, owing to their extensive use in surveillance, reconnaissance, and combat missions.

Who are the leading companies in the Military Robots Market?

Major companies include Lockheed Martin, Northrop Grumman, BAE Systems, Elbit Systems, Saab AB, QinetiQ, and Thales Group.

What opportunities exist in the Military Robots Industry?

Opportunities are emerging from increased procurement of unmanned combat systems, autonomous logistics platforms, naval drones, counter-drone technologies, and AI-enabled robotic warfare solutions.

What does a Military Robots Market report typically analyze?

The report analyzes market size, growth forecasts, technology trends, platform segmentation (land, air, marine), competitive landscape, regional outlook, procurement trends, and strategic developments among key defense contractors.
Personalize This Research

  • Triangulate with your Own Data
  • Get Data as per your Format and Definition
  • Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
  • Any level of Personalization
Request A Free Customisation

Let Us Help You

  • What are the Known and Unknown Adjacencies Impacting the Military Robots Market
  • What will your New Revenue Sources be?
  • Who will be your Top Customer; what will make them switch?
  • Defend your Market Share or Win Competitors
  • Get a Scorecard for Target Partners
Customized Workshop Request

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements

Get 10% Free Customisation

TESTIMONIALS

Growth opportunities and latent adjacency in Military Robots Market
avtar

Parv

Jun, 2019

Need to analyze the market for defense robots in the US, Canada, China, and the Middle East and prepare a report..

avtar

Rashid

Jan, 2019

I am doing a landscape analysis in the robotics sector to establish a business case in my job. I need estimates of the robot market, both past and future, especially for MENA region. If MENA is not there, it is fine to have others and I will make assumptions. Regards.

DMCA.com Protection Status
popup img