Data Center Transformer Market

Data Center Transformer Market by Insulation Type (Oil Immersed, Dry Type), Power Rating (Below 625 kVA, 625-1,250 kVA, 1,250-3,750 kVA, Above 3,750 kVA), Phase, Data Center Type, Technology, End User, and Region - Global Forecast to 2031


OVERVIEW
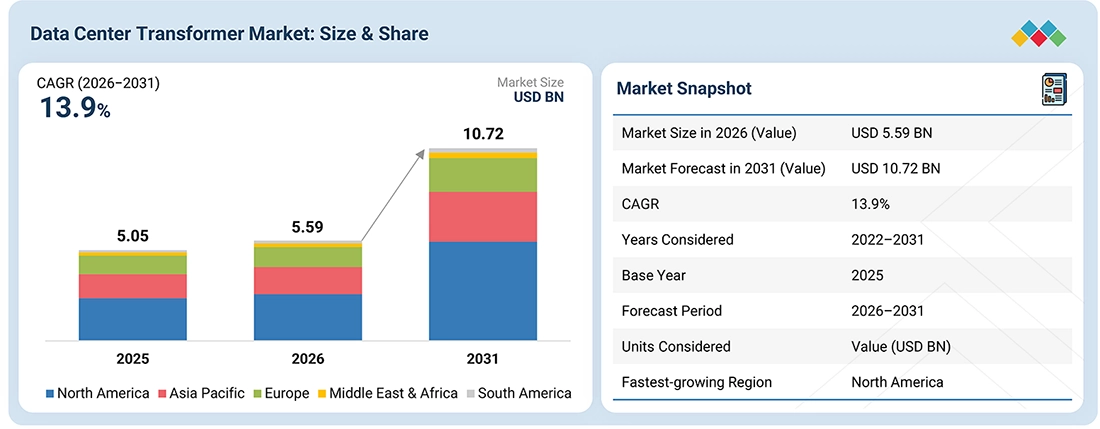
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
The data center transformer market is projected to grow from USD 5.59 Billion in 2026 to USD 10.72 Billion by 2031, at a CAGR of 13.9%. Growth is driven by rising investments in hyperscale, colocation, and enterprise data centers, increasing demand for reliable power distribution, and the expansion of cloud computing, AI, and digital infrastructure. Manufacturers are developing advanced oil-immersed and dry-type transformers with improved energy efficiency, thermal performance, compact designs, and enhanced reliability to support growing power demands and ensure uninterrupted data center operations.
KEY TAKEAWAYS
-
BY REGIONBy region, North America is expected to register the highest CAGR of 16.3% during the forecast period.
-
BY INSULATION TYPEBy insulation type, the dry type segment is expected to register the highest CAGR of 16.2% during the forecast period.
-
BY POWER RATINGBy power rating, the 1,250–3,750 kVA segment holds the largest market share during the forecast period.
-
BY PHASEBy phase, the three-phase segment is projected to register the highest CAGR of 14.7% during the forecast period.
-
BY DATA CENTER TYPEBy data center type, the hyperscale segment is projected to register the highest CAGR during the forecast period.
-
BY END USERBy end user, the technology & software segment is expected to register the highest CAGR during the forecast period.
-
COMPETITIVE LANDSCAPE - KEY PLAYERSCompanies such as ABB Ltd. (Switzerland), Schneider Electric SE (France), and Eaton Corporation plc (Ireland) were identified as some of the star players in the data center transformer market.
-
COMPETITIVE LANDSCAPE - STARTUPSCompanies such as Nordic Transformer (Denmark) and TMC Transformers S.p.A. (Italy) have distinguished themselves among startups and SMEs in the data center transformer market.
Growth in the data center transformer market is driven by rising investments in hyperscale, colocation, and enterprise data centers, increasing demand for reliable power distribution, and the expansion of cloud computing, AI, and digital infrastructure. Manufacturers are developing advanced oil-immersed and dry-type transformers with improved energy efficiency, thermal performance, compact designs, and enhanced reliability to support growing power demands and ensure uninterrupted data center operations.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
The data center transformer market is being reshaped by AI-driven demand, supply constraints, and a shift toward smarter, more efficient equipment. Hyperscale and AI campuses now require gigawatt-scale power and much higher rack densities, which is pushing buyers to lock in multi-year capacity as lead times stretch and grain-oriented electrical steel stays tight. At the same time, tougher efficiency standards and the adoption of dry-type, amorphous-core, and ester-fluid designs are changing product specifications. Digital monitoring, prefabricated power blocks, and emerging solid-state transformers (SST) for 800 VDC architectures are opening new revenue streams for providers beyond conventional units. For clients such as hyperscalers, colocation providers, and AI cloud operators, these shifts translate into faster time-to-power, better energy cost optimization, and grid-interactive, lower-carbon operations. Providers that move early into smart, modular, and high-efficiency solutions are best placed to capture the growing share of new revenue.
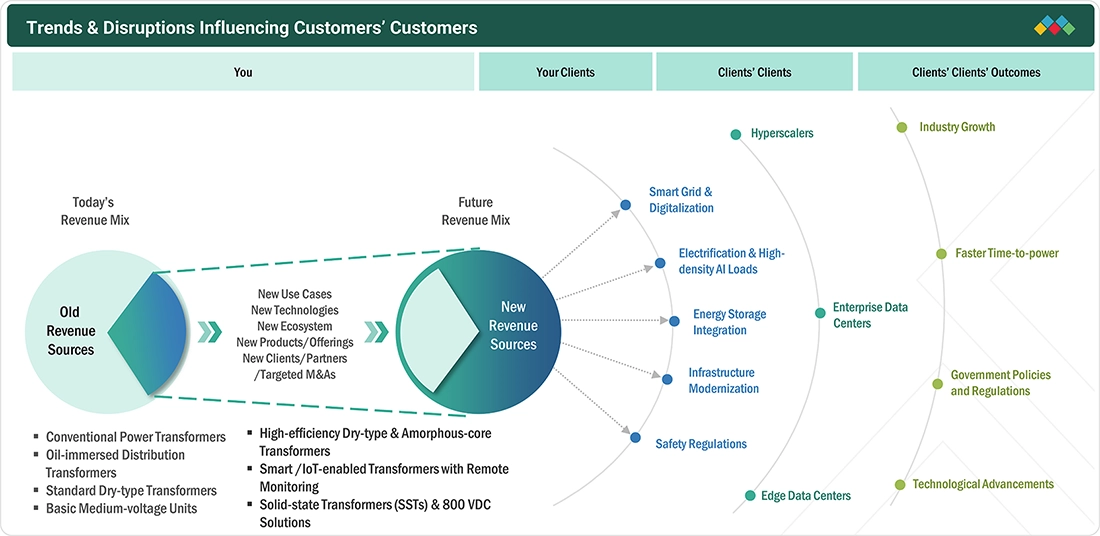
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Level
-
Increasing data center capacity

-
Focus on energy efficiency and reliability


Level
-
High initial investment

-
Space and installation constraints


Level
-
Increasing deployment of high-density computing infrastructure

-
Smart monitoring and digitalization


Level
-
Delays in grid connections

-
Stringent performance and reliability requirements

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Increasing data center capacity
The growing capacity of data centers is a major driver of the data center transformer market, supported by increasing investments in hyperscale, colocation, and enterprise facilities. Businesses are expanding their digital infrastructure to accommodate rising data storage, processing, and connectivity requirements. Hyperscale operators are developing large campuses, while colocation providers are expanding facilities to serve cloud service providers, enterprises, and telecommunications companies. These developments increase demand for electrical distribution infrastructure, including oil-immersed and dry-type transformers used to step down medium-voltage electricity to levels suitable for data center equipment. Additionally, the expansion of existing facilities requires upgrades to transformer capacity to accommodate additional server racks, cooling systems, and auxiliary loads. As data center developers prioritize scalable and reliable electrical infrastructure, demand for distribution transformers is expected to increase alongside new facility construction and capacity expansion.
Restraint: High initial investment
High initial investment is a key restraint in the data center transformer market, as the procurement and installation of distribution transformers contribute to the overall capital expenditure of data center projects. Advanced oil-immersed and dry-type transformers designed to meet data center requirements may involve higher costs due to specialized insulation systems, enhanced thermal management, efficiency requirements, and monitoring capabilities. In addition to equipment costs, developers must account for installation, electrical integration, protection systems, testing, and commissioning expenses. Large-scale hyperscale and colocation facilities may require multiple transformers to support different electrical loads and maintain operational reliability, further increasing upfront investment. These costs can be particularly challenging for smaller data center operators and developers with limited capital budgets. Furthermore, project cost pressures may delay equipment upgrades or encourage buyers to prioritize initial purchase prices over long-term energy efficiency. Consequently, high upfront expenditure can influence transformer selection, procurement timelines, and investment decisions across the data center industry.
Opportunity: Increasing deployment of high-density computing infrastructure
The increasing deployment of high-density computing infrastructure presents significant growth opportunities for the data center transformer market. The expansion of artificial intelligence (AI), machine learning, and high-performance computing is driving the development of data centers with higher power densities and greater electricity requirements. These facilities require reliable distribution transformers capable of handling substantial electrical loads while maintaining stable operating temperatures and efficient power delivery. Manufacturers can capitalize on this trend by developing oil-immersed and dry-type distribution transformers with higher power-handling capacities, improved insulation systems, optimized winding designs, and enhanced thermal management capabilities. Compact transformer designs can also help address space constraints in modern data center facilities. Additionally, integrating temperature sensors and digital monitoring systems can enable operators to identify abnormal operating conditions and support predictive maintenance. By offering application-specific transformer solutions that meet the evolving power requirements of AI-driven data centers, manufacturers can strengthen their market positions and capture emerging opportunities in the expanding digital infrastructure sector.
Challenge: Delays in grid connections
Delays in grid connections and limitations in electricity availability pose significant challenges to the data center transformer market. New data center projects require adequate grid capacity and timely access to electricity before their electrical distribution infrastructure can be fully commissioned. However, transmission and distribution network constraints, lengthy grid connection approval processes, and delays in substation development can postpone project timelines. These issues may affect transformer procurement schedules, as developers often align equipment installation with the availability of grid connections and the progress of other electrical infrastructure. Furthermore, increasing electricity demand from AI workloads and hyperscale facilities can intensify pressure on local power networks, requiring additional investments in grid upgrades and distribution infrastructure. Such delays may lead to deferred transformer orders, extended project commissioning periods, and increased development costs. Transformer manufacturers must therefore coordinate closely with data center developers, utilities, and electrical contractors to align production and delivery schedules with project requirements.
DATA CENTER TRANSFORMER MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Schneider Electric provides medium-voltage transformer solutions for data center electrical distribution, helping operators step down incoming electricity to the voltage levels required by downstream distribution systems. These transformers can be integrated into broader power infrastructure that includes switchgear, power distribution equipment, and monitoring systems. This application is particularly relevant to hyperscale and colocation facilities that require scalable electrical infrastructure to support expanding IT loads. | Integrated transformer and power distribution solutions help simplify system design, improve coordination across electrical equipment, and support reliable power delivery. Efficient transformer designs can also help reduce electrical losses, while scalable configurations support capacity expansion as data center demand increases. |
 |
ABB supplied main transformers alongside medium- and low-voltage switchgear and an uninterruptible power supply for Telia’s data center in Helsinki, Finland. The project focused on improving the efficiency and reliability of the facility’s power distribution infrastructure by reducing electrical losses. | High-efficiency transformers and coordinated electrical distribution equipment help reduce power losses and associated energy consumption. Redundant power infrastructure supports operational continuity, while integrated equipment and scalable design help data center operators accommodate future capacity requirements. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
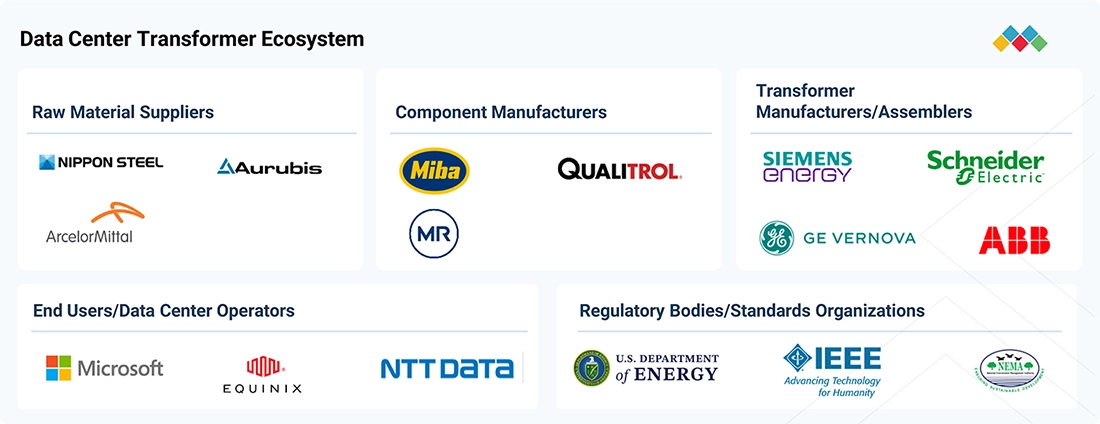
The Data Center Transformer ecosystem comprises several interconnected segments that collectively support the design, production, and deployment of transformers for critical power infrastructure. Raw material providers and suppliers supply essential inputs such as copper, aluminum, electrical steel, insulation materials, and cooling fluids. Component manufacturers produce specialized parts including cores, windings, bushings, tap changers, and monitoring sensors. Transformer manufacturers and assemblers integrate these elements into finished dry-type, liquid-filled, and high-efficiency units tailored for data center applications. End users—primarily hyperscale and colocation data center operators, as well as industrial and commercial facilities—deploy these transformers to ensure reliable power distribution under high-density loads. Regulatory bodies and standards organizations establish safety, efficiency, and environmental requirements that guide product design, testing, and compliance across the value chain.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
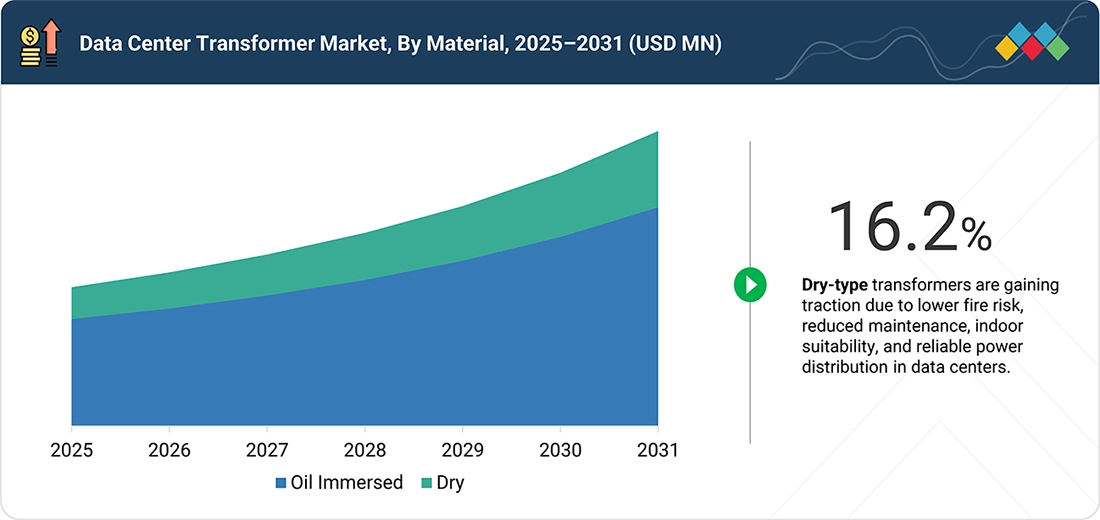
Dry is the fastest segment during the forecast period.
Dry-type transformers are expected to be the fastest-growing segment during the forecast period, driven by increasing demand for safe, reliable, and space-efficient power distribution solutions. These transformers use solid insulation and air for cooling, eliminating the need for liquid dielectric fluids. Their suitability for indoor installations, reduced risk of fluid leakage, and relatively low maintenance requirements make them attractive for hyperscale and colocation data centers. Growing investments in AI-ready facilities and the need for dependable electrical infrastructure are expected to further support adoption.
Above 3750 segment is the fastest segment during the forecast period.
Transformers rated above 3,750 kVA are expected to be the fastest-growing segment during the forecast period, supported by rising electricity demand from hyperscale data centers and AI-driven computing workloads. These facilities require high-capacity power distribution systems to support large server clusters, advanced cooling infrastructure, and auxiliary equipment. Increasing rack power density and investments in large-scale data center campuses are creating demand for transformers capable of handling substantial electrical loads. This trend is expected to strengthen the adoption of higher-rated transformers.
Three phase is the fastest segment during the forecast period.
Three-phase transformers are expected to be the fastest-growing segment during the forecast period, driven by their suitability for high-capacity data center power distribution. They efficiently supply power to large server installations, cooling systems, and other critical infrastructure while supporting balanced electrical loads. Their ability to accommodate substantial power requirements makes them particularly suitable for hyperscale and colocation facilities. As data centers expand to support AI, cloud computing, and high-performance computing, demand for three-phase transformers is expected to increase alongside investments in reliable and scalable electrical infrastructure.
Hyperscale is the fastest segment during the forecast period.
Hyperscale data centers are expected to be the fastest-growing segment during the forecast period, driven by rising investments in cloud computing, artificial intelligence, and large-scale digital infrastructure. Major technology companies are expanding their data center capacity to support growing data processing, storage, and computing requirements. These facilities require substantial transformer capacity to ensure reliable voltage conversion and power distribution across server halls, cooling systems, and auxiliary infrastructure. Increasing AI workloads and high-density computing requirements are expected to further accelerate demand for transformers in hyperscale facilities.
Solid-state transformer (SST) is the fastest segment during the forecast period.
Solid-state transformers (SSTs) are expected to be the fastest-growing technology segment during the forecast period, supported by ongoing innovation in power electronics and next-generation data center power architectures. SSTs enable flexible voltage conversion, advanced power control, and potential integration with direct-current distribution systems. These capabilities may help address the evolving power requirements of AI workloads and high-density computing infrastructure. Increasing research, strategic investments, and technology development are creating growth opportunities for SSTs. However, their commercial deployment remains less established than that of conventional transformers.
Technology & Software is the fastest segment during the forecast period.
Technology and software companies are expected to be the fastest-growing end-user segment during the forecast period, driven by expanding investments in cloud platforms, artificial intelligence, and high-performance computing. These companies require additional data center capacity to support software applications, digital services, data storage, and AI model development. The resulting increase in electricity demand creates opportunities for transformer manufacturers to supply reliable, high-capacity, and energy-efficient power distribution solutions. Continued investment in AI infrastructure and hyperscale data center expansion is expected to strengthen transformer demand from this end-user segment.
REGION
Asia Pacific is expected to account for the largest market share during the forecast period
North America is expected to remain a leading market for data center transformers during the forecast period, driven by ongoing modernization of power distribution infrastructure, rapid expansion of hyperscale and colocation data centers, and increasing adoption of high-efficiency dry-type and liquid-filled transformer systems. The United States represents the key market in the region, supported by utility and data center operator investments in low-, medium-, and high-voltage solutions, compact designs, and advanced thermal management. ABB, Eaton, and Schneider Electric have expanded their North American transformer portfolios with modular, high-efficiency, and smart-monitoring systems, while broader power infrastructure deployments demonstrate continued investment in grid modernization and data center electrification. These developments are supporting the transition toward more reliable, efficient, and digitally integrated power distribution networks.
DATA CENTER TRANSFORMER MARKET: COMPANY EVALUATION MATRIX
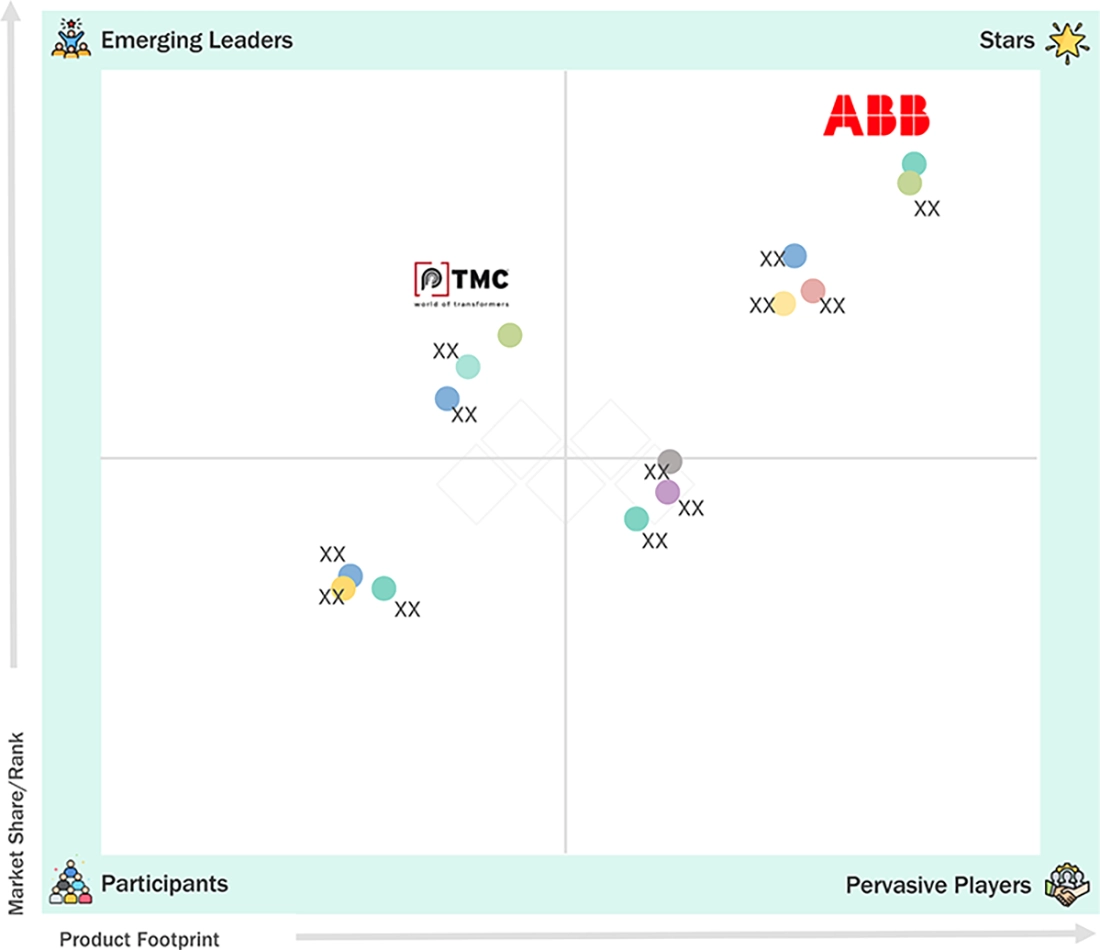
ABB holds a clear leadership position in the Stars quadrant, combining a broad product footprint with high market share and rank. Its comprehensive range of transformer solutions for data center power distribution, backed by significant scale and brand strength, enables it to address the full spectrum of critical power infrastructure requirements across hyperscale, colocation, and enterprise facilities. This dual strength in coverage and commercial standing gives ABB a decisive competitive edge. TMC occupies the Emerging Leaders quadrant, reflecting solid market share and rank relative to many peers, while its product footprint remains more focused. Although competitive in market standing, TMC has clear opportunity to broaden its offering—particularly in efficiency, thermal performance, monitoring capabilities, and form-factor options—to better meet the evolving demands of modern data centers and progress toward Star-level positioning
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- ABB (Switzerland)
- Schneider Electric (France)
- Legrand (France)
- Siemens (Germany)
- Eaton (Ireland)
- Hitachi Energy (Switzerland)
- GE Vernova (US)
- TMC Transformers S.p.A. (Italy)
- Virginia Transformer Corp. (US)
- Rex Power Magnetics (Canada)
- ELSCO Transformers (US)
- MGM Transformers (US)
- Nordic Transformer (Denmark)
- Varelen Electric Co., Ltd. (China)
- Mission Critical Group (US)
- Fuji Electric Co., Ltd. (Japan)
- SGB-SMIT (Germany)
- Daelim Transformer (South Korea)
- Hammond Power Solutions (Canada)
- Danish Powers (India)
- Voltamp Transformers (India)
- CG Power & Industrial Solutions Ltd. (India)
- Milestone (Xiong'an) Electrical Technology Co., Ltd. (China)
- CEEG (China)
- DG Matrix (US)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2025 (Value) | USD 5.05 Billion |
| Market Size in 2026 (Value) | USD 5.59 Billion |
| Market Forecast in 2031 (Value) | USD 10.72 Billion |
| Growth Rate | CAGR of 13.9% from 2026–2031 |
| Years Considered | 2022–2031 |
| Base Year | 2025 |
| Forecast Period | 2026–2031 |
| Units Considered | Value (USD Billion) |
| Report Coverage | Revenue Forecast, Company Ranking, Competitive Landscape, Growth Factors, and Trends |
| Segments Covered |
|
| Regions Covered | North America, Europe, Asia Pacific, Middle East & Africa, South America |
WHAT IS IN IT FOR YOU: DATA CENTER TRANSFORMER MARKET REPORT CONTENT GUIDE
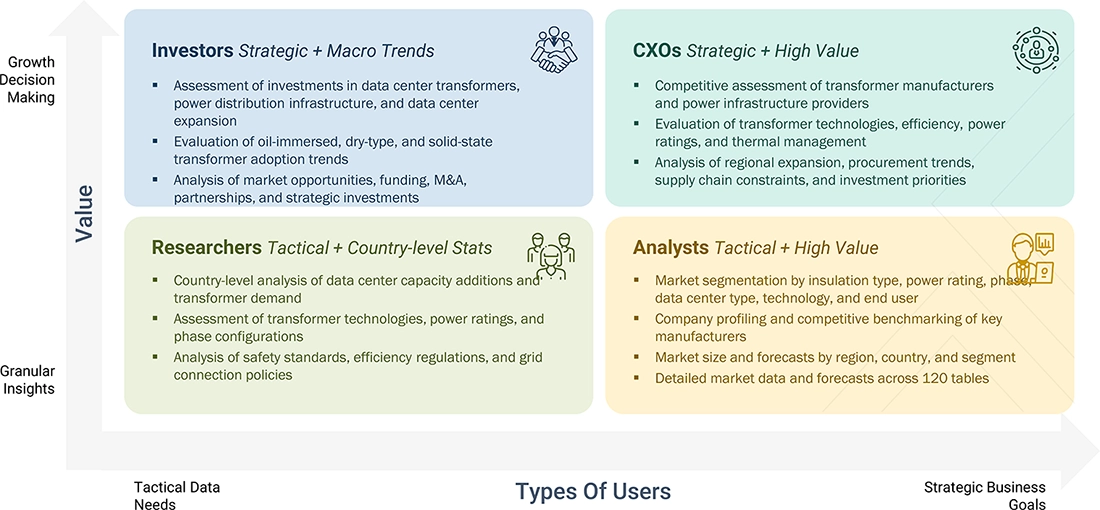
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Customize the data center transformer market report to address the client’s specific requirements and incorporate the requested scope, segmentation, and research insights | Market sizing for data center transformers across key countries and regions | Country-wise market attractiveness analysis and competitive landscape overview (Siemens, Schneider Electric, ABB, Legrand, Eaton, and others) |
RECENT DEVELOPMENTS
- August 2026 : Siemens and Reinhausen partnered to develop and industrialize a solid-state transformer for AI-ready data centers. The proposed system connects grid voltages up to 36 kV and delivers an 800 V DC output, targeting reduced footprint, improved power conversion, scalability, and rapid response to changing AI workloads.
- August 2025 : Eaton completed its acquisition of Resilient Power Systems, strengthening its capabilities in medium-voltage solid-state transformers. The technology is being developed for future data center applications, with potential to improve power density, reduce equipment footprint, and support efficient power distribution.
- March 2025 : ABB acquired a minority stake in DG Matrix to accelerate the commercialization of solid-state power electronics for AI data centers. DG Matrix’s Power Router platform integrates multiple power-conversion functions into a compact system, offering a potential alternative to conventional transformer-based electrical architectures.
- December 2024 : Siemens and Compass Datacenters signed a multi-year agreement for modular medium-voltage power skids integrating switchgear and transformers. The agreement covered up to 1,500 units over five years, supporting faster data center construction and lower total electrical infrastructure costs.
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
Methodology
The study involved major activities in estimating the current size of the data center transformer market. Exhaustive secondary research was done to collect information on the peer and parent markets. The next step was to validate these findings, assumptions, and sizing with industry experts across the value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the complete market size. Thereafter, market breakdown and data triangulation were used to estimate the market size of the segments and subsegments.
Secondary Research
This research study on the data center transformer market involved the use of extensive secondary sources, directories, and databases, such as D&B Hoovers, Bloomberg Businessweek, Factiva, International Energy Agency, and BP Statistical Review of World Energy, to identify and collect information useful for a technical, market-oriented, and commercial study of the data center transformer market. The other secondary sources included annual reports, press releases, and investor presentations of companies, white papers, certified publications, articles by recognized authors, manufacturer associations, trade directories, and databases.
Primary Research
The data center transformer market comprises stakeholders such as data center transformer manufacturers, technology providers, system integrators, and service providers across the supply chain. On the demand side, the market is driven by the growing development of hyperscale, colocation, and enterprise data centers, supported by increasing demand for cloud computing, artificial intelligence (AI), and digital infrastructure. The need for reliable, energy-efficient, and compact power distribution solutions is driving the adoption of transformers, including medium-voltage, dry-type, cast-resin, and other transformers suitable for data center applications. On the supply side, manufacturers are witnessing increasing opportunities through data center construction and expansion projects, partnerships with data center operators and electrical infrastructure providers, and strategic initiatives such as mergers, acquisitions, and product innovations to strengthen their market presence and technological capabilities. Various primary sources from both the supply and demand sides of the market were interviewed to obtain qualitative and quantitative information. The following is the breakdown of primary respondents:
BREAKDOWN OF PRIMARY PARTICIPANTS:
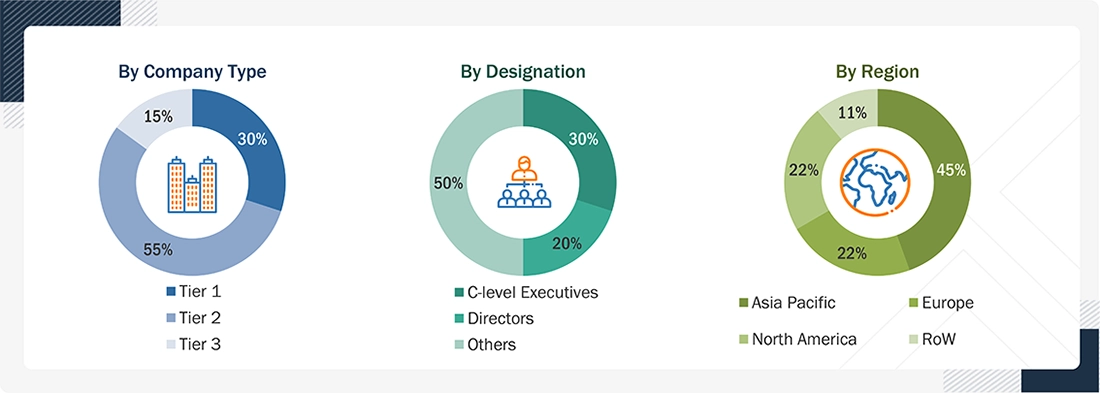
Note: “Others” include sales managers, engineers, and regional managers.
The tiers of the companies are defined based on their total revenue as of 2025: Tier 1: >USD 1 billion, Tier 2: USD 500 million–1 billion, and Tier 3: <USD 500 million
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
Both the top-down and bottom-up approaches were used to estimate and validate the size of the data center transformer market and its dependent submarkets. The key players in the market were identified through secondary research, and their market share in the respective regions was obtained through primary and secondary research. The research methodology includes the study of the annual and financial reports of top market players and interviews with industry experts, such as chief executive officers, vice presidents, directors, sales managers, and marketing executives, for key quantitative and qualitative insights related to the data center transformer market.
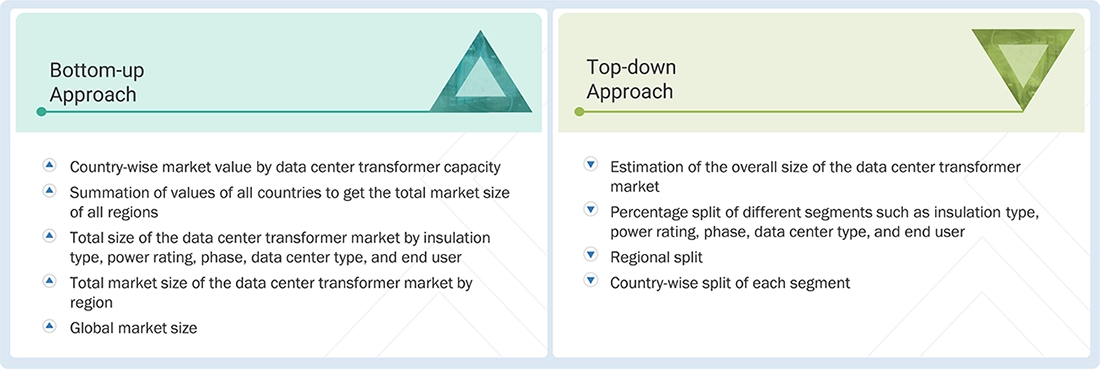
Data Triangulation
After arriving at the overall market size from the estimation process explained above, the total market was split into several segments and subsegments. To complete the overall market engineering process and arrive at the exact statistics for all the segments and subsegments, the data triangulation and market breakdown processes were employed, wherever applicable. The data was triangulated by studying various factors and trends from both the demand and supply sides. Along with this, the market was validated using both the top-down and bottom-up approaches.
Market Definition
A data center transformer is an electrical device used to step up or step down voltage levels to ensure safe and efficient power distribution within data center facilities. It supplies electricity at appropriate voltage levels to critical infrastructure, including servers, storage systems, networking equipment, cooling systems, and auxiliary facilities. Data center transformers are available in oil-immersed and dry-type configurations, with different power ratings and single-phase or three-phase designs to meet varying capacity and operational requirements. They are deployed across hyperscale, colocation, and enterprise data centers to support reliable power delivery, operational efficiency, and the growing electricity demands of digital infrastructure.
Key Stakeholders
- Government and research organizations
- State and national regulatory authorities
- Organizations, forums, alliances, and associations
- Institutional investors
- Investors/Shareholders
- Environmental research institutes
- Manufacturers’ associations
- Integrated device manufacturers (IDMs)
- Transformer and raw material/component manufacturers
- Transformer manufacturers, dealers, and suppliers
- Electrical equipment manufacturers’ associations and groups
- Power utilities and other end-user companies
- Consulting companies in the energy and power domain
- Investment banks
Report Objectives
- To describe and forecast the data center transformer market, by insulation type, power rating, phase, data center type, end user, and region, in terms of value
- To describe and forecast the data center transformer market across key regions and end-user segments, with regional-level analysis covering North America, Asia Pacific, Europe, Middle East & Africa, and South America, in terms of value
- To describe and forecast the data center transformer market, by region, in terms of value
- To provide detailed information regarding drivers, restraints, opportunities, and challenges influencing market growth
- To provide a detailed overview of the data center transformer supply chain analysis, use case analysis, key stakeholders and buying criteria, patent analysis, trade analysis, tariff analysis, regulations, macroeconomic outlook, pricing analysis, Porter’s five forces analysis, impact of gen AI/AI, and the 2025 US tariff impact
- To strategically analyze micromarkets with respect to individual growth trends, prospects, and contributions to the total market
- To analyze opportunities in the market for various stakeholders by identifying high-growth segments
- To strategically profile the key players and comprehensively analyze their market position in terms of ranking and core competencies, along with detailing the market’s competitive landscape
- To analyze growth strategies, such as acquisitions, investments, expansions, and product launches, adopted by market players in the data center transformer market
Available customizations:
MarketsandMarkets offers customizations according to the specific needs of the companies with the given market data.
The following customization options are available for the report:
Product Analysis
- Product matrix, which gives a detailed comparison of the product portfolio of each company
Regional Analysis
- Further breakdown of the data center transformer market, by country
Company Information
- Detailed analysis and profiling of additional market players (up to five)

Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the Data Center Transformer Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Custom Market Research Services
We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements
Get 10% Free CustomisationTESTIMONIALS
Kimberly Murphy
GLOBAL MARKETING DIRECTOR
Bently Nevada,
Leading Condition Monitoring & Asset Protectionwww.bakerhughesds.com/bently-nevada
MarketsandMarkets™ showed consistent rigor for success and relentlessly worked with Bently Nevada stakeholders to positively impact go-to-market strategy. Their proactiveness and flexibility has been instrumental in achieving the objectives to grow our sales pipeline in key industrial markets.
DARRICK HUEBER
Business Development Leader
Nexus Controls LLC,
Leading Manufacturer of Automation System & Electrical Panelswww.bakerhughesds.com/nexus-controls
We partnered with MarketsandMarkets to expand our business further by tapping into new industrial segments. It was critical for us to gather crucial business insights about specific markets to achieve this goal. MarketsandMarkets engagement model and client services helped us provide those insights, it was really impressive and valuable for my business. The team was extremely flexible and helpful.
Mike Schoff
Global Industrial Commercial Strategy Leader
Nexus Controls LLC
Leading Manufacturer of Automation System & Electrical Panelswww.bakerhughesds.com/nexus-controls
We consulted MarketsandMarkets for potential Partner Identification. Overall, it was a good experience. The insights provided through interviews conducted by the team helped us put together the questionnaire required for discussion with the selected partners. Their ability to provide insights through interviews with customers in a timely manner was quite impressive.


Growth opportunities and latent adjacency in Data Center Transformer Market