Liquid Handling System Market

Liquid Handling System Market by Product (Pipette, Workstation, Software), Type (Automated, Electronic), Application (Drug Discovery, NGS, PCR, Diagnostics, Proteomics, Forensics), End User (Labs, Academia, F&B, Pharma-biopharma) – Global Forecast to 2031


LIQUID HANDLING SYSTEM MARKET SIZE, SHARE & GROWTH SNAPSHOT
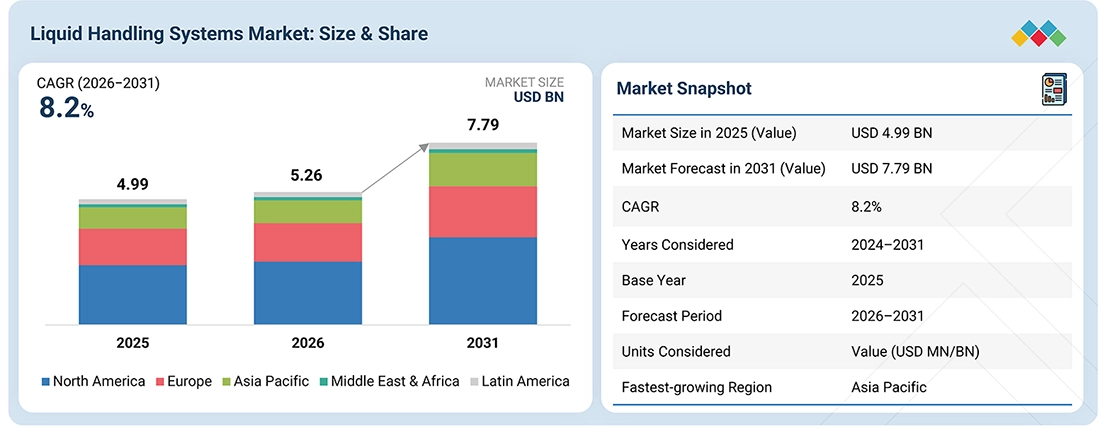
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
The global liquid handling systems market is projected to grow from USD 5.26 billion in 2026 to USD 7.79 billion by 2031, at a CAGR of 8.2% during the forecast period. The market was valued at USD 4.99 billion in 2025. The global liquid handling systems market is expected to be increasingly driven by the growing adoption of laboratory automation, high-throughput workflows, and the need for enhanced precision, accuracy, and reproducibility. Pharmaceutical and biotechnology companies, CROs, diagnostic laboratories, and academic research institutions are increasingly transitioning from manual processes to automated and semi-automated solutions for pipetting, dispensing, sample preparation, dilution, and microplate handling. The growing complexity and volume of laboratory workflows are further encouraging the adoption of robotic workstations and integrated liquid handling platforms, particularly across drug discovery, genomics, clinical diagnostics, and cell-based research. In addition, the need to minimize manual errors, improve workflow consistency, and reduce turnaround times is expected to support the continued adoption of automated liquid handling solutions.
KEY TAKEAWAYS
-
MARKET SNAPSHOT:
Base Year Market Size (2025): USD 4.99 Billion
Current Market Size (2026): USD 5.26 Billion
Forecast Market Size (2031): USD 7.79 Billion
CAGR (2026–2031): 8.2% -
SEGMENT LEADERSHIP:
Regional Outlook: Asia Pacific is expected to register the highest CAGR during the forecast period.
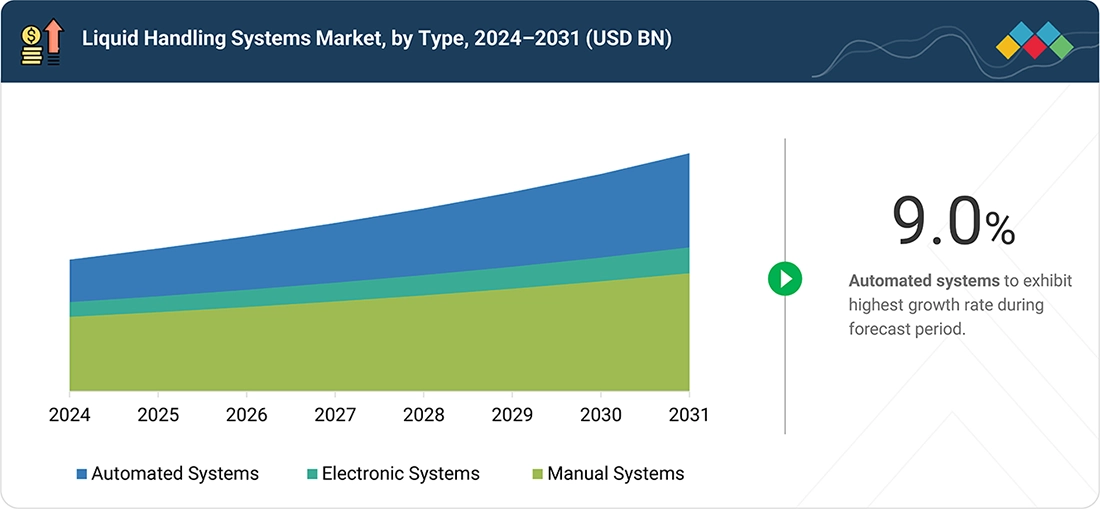
Type Leader: Automated systems are expected to register the highest CAGR of 9.0% during the forecast period.
Product Leader: Pipettes segment is expected to register the highest CAGR of 9.5% during the forecast period.
Application Leader: Genomics segment is expected to grow at the highest CAGR of 9.0% during the forecast period.
End User Leader: Hospitals & diagnostic laboratories segment is expected to register the highest CAGR during the forecast period. -
MARKET OUTLOOK & COMPETITIVE LANDSCAPE:
Thermo Fisher Scientific, Danaher, Eppendorf, Tecan, Agilent Technologies, Hamilton Company, and Sartorius are driving market growth through their automated, high-throughput, software-integrated, and scalable liquid handling platforms.
SPT Labtech, Opentrons, Formulatrix, Gilson, Hudson Robotics, and Aurora Biomed are gaining traction by offering specialized, modular, flexible, and cost-effective liquid handling solutions for niche applications and smaller laboratories.
A key growth driver for automated systems in the liquid handling systems market is rising demand for greater accuracy, speed, efficiency, and reproducibility in laboratory workflows. As research and testing volumes continue to rise across pharmaceutical and biotechnology companies, clinical diagnostic laboratories, and academic institutions, laboratories are increasingly transitioning from manual pipetting to automated platforms to minimize human errors, improve sample consistency, and accelerate high-throughput processes. Automation also enables the execution of complex workflows in genomics, drug discovery, and precision medicine, where scalability and reproducibility are critical. Furthermore, rising labor costs and shortages of skilled laboratory personnel are encouraging organizations to adopt automated liquid handling systems to optimize resource utilization, maintain productivity, and improve overall operational efficiency.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
The liquid handling systems market is increasingly aligned with major trends and disruptions affecting customers’ customers, such as digital innovation, automation, and precision-focused science. Today’s end-users across clinical laboratories, pharmaceutical and biopharmaceutical companies, academic research institutes, and forensic laboratories are demanding higher accuracy, reproducibility, and data traceability to support advanced research, faster diagnostics, and regulatory-compliant workflows. Technologies such as AI-powered data analytics, connected automation, robotics, and high-throughput screening are reshaping lab operations and enabling real-time decision-making. A growing emphasis on personalized medicine, advanced therapeutics such as cell & gene therapy, forensic digitalization, and multi-omic research is accelerating adoption of automated, scalable platforms. At the same time, challenges like labor shortages, rising sample volumes, stricter regulatory frameworks, and the need for decentralized and remote-enabled testing are pushing laboratories to re-engineer processes, integrate smart lab systems, and invest in flexible solutions. Together, these disruptions are redefining efficiency standards, raising quality expectations, and pushing laboratories toward digital-first, data-centric, and automation-driven operating models.
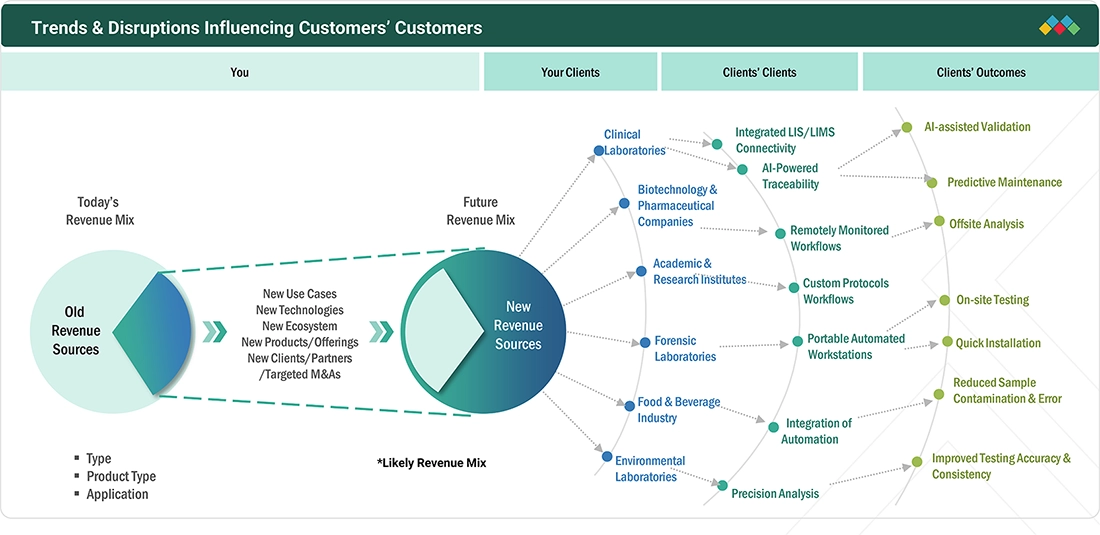
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Level
-
Growing demand for automated solutions in drug discovery processes

-
Innovation in artificial intelligence and robotic systems


Level
-
High cost of liquid handling systems

-
Limited uptake of liquid handling systems in developing markets


Level
-
Growing healthcare spending across regions

-
Rising activities in pharma and biotech industries


Level
-
System integration issues

-
Lack of skilled workforce for operating advanced labs

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Growing demand for automated solutions in drug discovery processes
Liquid handling is critical in drug discovery because it streamlines complex, repetitive tasks, improves precision, and increases efficiency. By automating high-throughput screening, researchers can rapidly test thousands of compounds, significantly accelerating the identification of promising drug candidates compared with traditional manual methods. Automation reduces human error, maintains experimental consistency, and supports robust data management and analysis. Given the complexity of molecular testing, biochemical assays, and genomic research, automation enables better handling of large datasets and optimizes workflows, ultimately shortening the drug development timeline. Automation also benefits other key areas of drug discovery and development, including target identification and regulatory compliance. Leading companies, like Tecan Group, are at the forefront of advancing target discovery and hit identification through cutting-edge automation technologies. ArrayJet, for instance, leverages bioprinting to deposit proteins and compounds onto slides and microplates efficiently, minimizing sample usage and speeding up screening. Tecan also addresses automation challenges in cell-based models with end-to-end cellomics workflows integrating steps from cell seeding to imaging. These advancements highlight a major shift toward more efficient, reliable, and integrated automation solutions in drug discovery. For instance, Tecan Group, a Switzerland-based company, offers advanced liquid handling technologies through its end-to-end cellomics workflows. These solutions integrate cutting-edge instruments, such as single-cell dispensers, automated liquid handling workstations, and multimode plate readers, to support fully automated processes. Designed to streamline drug discovery, the workflows enable seamless operations from cell seeding to live-cell imaging and analysis, enhancing efficiency and precision in cellular research.
Restraint: Limited uptake of liquid handling systems in developing markets.
In developing regions, cost barriers significantly hinder the adoption of liquid handling automation systems. Although automation offers long-term gains in accuracy, productivity, and sample reliability, the financial burden associated with purchasing, deploying, and maintaining these systems remains substantial. Beyond the initial capital cost, laboratories face considerable ongoing expenses, including routine maintenance, hardware and software upgrades, replacement parts, and service contracts, which often represent 20–30% of total cost of ownership and frequently surpass the initial software investment. Training, system integration, and implementation activities add another ~15% to overall expenditure, further stretching already-tight operating budgets in emerging markets. Many small and mid-sized laboratories in developing regions operate with limited funding, restricted technology budgets, and dependence on government or institutional grants. As a result, they prioritize essential operational needs over capital-intensive automation. In addition, limited access to skilled operators and service engineers increases reliance on external technical support, adding to long-term expenses and creating downtime risks. Poor infrastructure, such as inconsistent power supply, also discourages investments in sensitive automated systems that require stable environments. Evaluating cost-efficiency is further complicated by the low penetration of automation in these regions. With fewer reference installations and limited real-world performance data, laboratories struggle to accurately forecast ROI and justify the upfront investment. Consequently, decision-makers adopt a cautious, risk-averse approach, delaying automation deployments until local performance, cost-savings, and throughput benefits are demonstrated. This scarcity of proven outcomes, combined with budget limitations, insufficient technical expertise, and concerns over system reliability in resource-constrained settings, represents a key restraint to the uptake of liquid handling systems in developing markets.
Opportunity: Growing healthcare spending across regions.
Emerging markets are poised to present substantial growth opportunities for manufacturers and distributors of liquid handling system products during the forecast period. This growth potential is largely driven by increased healthcare spending and ongoing enhancements in healthcare infrastructure across these regions. Notable examples include the following: 1) In the US, healthcare spending was estimated to have risen by 7.5% in 2023, reaching USD 4.8 trillion and outpacing the projected GDP growth rate of 6.1%, according to federal data published in June 2024. 2) Austria’s healthcare expenditure in 2023 was approximately USD 56.58 billion, accounting for 10.9% of its GDP, based on preliminary data from Statistics Austria released in June 2024. 3) The Asia Pacific region is projected to be the fastest-growing market in terms of healthcare spending. It is expected to contribute over 20% to global healthcare expenditures by 2030 (Source: Bain & Company, April 2024). 4) The Economic Survey 2023–24, presented by Union Finance Minister Nirmala Sitharaman, underscores that India’s robust economic growth is paralleled by notable social and institutional advancements, driven by effective government initiatives. Since FY16, social sector spending has consistently risen, with overall social welfare expenditure increasing at a compounded annual growth rate (CAGR) of 12.8% and health expenditure at 15.8% between FY18 and FY24. In the 2023–24 Budget Estimates, ?23.5 lakh crore (approximately USD 283.13 billion) is allocated for social services, with ?5.85 lakh crore (approximately USD 70.42 billion) designated for health. This marks a significant rise from ?11.39 lakh crore (approximately USD 137.23 billion) for social services and ?2.43 lakh crore (approximately USD 29.28 billion) for health in 2017–18. As a percentage of GDP, expenditure on social services grew from 6.7% in 2017–18 to 7.8% in 2023–24, while health expenditure increased from 1.4% to 1.9% over the same period. Within total expenditure, social services now comprise 26%, with health accounting for 6.5%.
Challenge: Lack of skilled workforce for operating advanced labs.
Effective use of life science and analytical technologies requires a high level of expertise and practical experience in areas such as high-throughput screening, compound weighing and dissolution, DNA/RNA purification, next-generation sequencing (NGS), PCR, and sample preparation. Inadequate knowledge and skills can lead to direct and indirect costs and increase researchers’ workload and time pressure. This skill gap often results in inefficient hands-on experience and a limited understanding of the phenotypic implications of sequencing-based data. A research paper on NGS published by the National Center for Biotechnology Information (US) highlights the rising demand and adoption of NGS technologies in Australia, underscoring the urgent need for trained biologists to manage and interpret NGS data. This underscores the critical need for skilled professionals in method development, validation, operation, and troubleshooting. This talent shortage presents a significant obstacle to market expansion. A pronounced deficit of qualified personnel for these technical activities poses a challenge to the growth of the liquid handling system market. This lack of skilled labor, particularly in key regions, is anticipated to constrain the market’s full growth potential over the forecast period. Moreover, as laboratories in the pharmaceutical and biotechnology sectors increasingly work with smaller liquid volumes and complex multi-step processes like serial dilution and PCR, even a minor error such as a one-microliter variation can critically impact results. These procedures are susceptible to volume discrepancies, making operator proficiency essential. Limited awareness, especially in developing nations, contributes to this shortage of diverse and rewarding career paths in the life sciences. These collective issues are expected to hamper the market’s growth in the coming years.
LIQUID HANDLING SYSTEM MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Thermo Fisher excels in integrating automated liquid handling with high-content imaging, enabling seamless dispense-to-image workflows for advanced cell-based assays. | Delivers up to ~90% time savings and higher throughput by automating cell-based workflows, combining precise liquid handling with integrated high-content imaging for faster, consistent results and reduced manual effort. |
 |
Danaher’s core strength in the liquid handling systems market lies in high-throughput genomic, proteomic, and cellular workflow automation, enabling efficient NGS library prep, advanced sample processing, and large-volume dispensing for large-scale research and screening applications. | Provides adaptable automation across miniaturized acoustic dispensing for reagent savings and reliable tip-based systems, enabling labs to scale throughput and workflows seamlessly as their demands increase. |
 |
Encore Multispan system, combining multispan pipetting and robotics to automate high-throughput sample prep, compound management, and screening workflows. | Delivers higher throughput and productivity through dual pipetting banks and extended-reach robotic arms, enabling seamless automation of both upstream and downstream workflow steps. |
 |
High-throughput, modular Fluent Automation Workstations, which seamlessly integrate advanced pipetting, detection, and handling capabilities across plates, tubes, and tips for scalable and versatile lab workflows. | Delivers highly modular and configurable automation, with multi-arm systems that adapt to diverse labware, combine multiple pipetting technologies, and integrate detection tools enabling tailored, scalable workflows for varied research needs. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
The liquid handling systems market ecosystem includes liquid handling system manufacturers, component and consumable suppliers, software and automation providers, regulatory and standards organizations, and end users, each playing a critical role in enabling accurate, efficient, and reproducible laboratory workflows. Leading manufacturers such as Thermo Fisher Scientific, Danaher, Eppendorf, Tecan, Hamilton Company, Agilent Technologies, and Sartorius develop manual, electronic, and automated liquid handling systems, including pipettes, automated liquid handlers, dispensing platforms, and integrated workstations. Component and technology suppliers provide essential elements such as pumps, valves, sensors, robotic arms, controllers, microplates, and other laboratory consumables, while software and automation providers support workflow management, instrument integration, data handling, and LIMS connectivity. Regulatory and standards organizations, including the US FDA, EMA, ISO, and other national regulatory authorities, set requirements for laboratory equipment performance, quality, safety, and data integrity. End users, including pharmaceutical and biotechnology companies, hospitals and diagnostic laboratories, CROs, academic and research institutes, and clinical laboratories, utilize liquid handling systems for drug discovery, genomics, proteomics, molecular diagnostics, PCR, cell-based assays, and sample preparation. Overall, the ecosystem is increasingly driven by laboratory automation, high-throughput processing, precision and reproducibility, workflow integration, digital connectivity, and the growing demand for efficient and scalable laboratory operations.
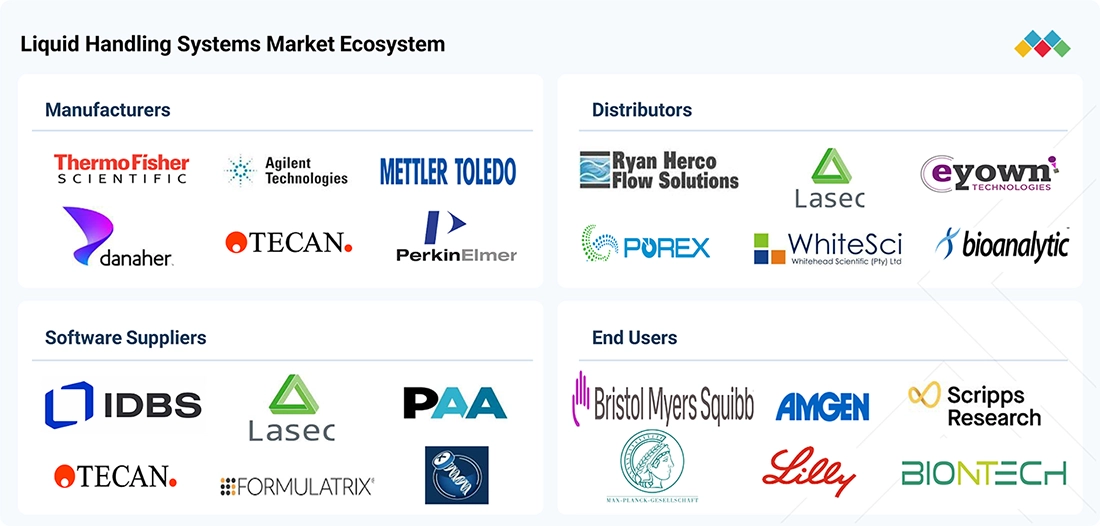
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Liquid Handling Systems Market, by Type
The growth of automated liquid handling systems is driven primarily by increasing laboratory automation and the expanding range of applications these systems support. Demand for reduced human intervention in laboratory workflows, the rise of high-throughput screening in drug discovery, and the growing use of precision medicine are key factors driving market expansion. Additionally, the increasing prevalence of infectious and chronic diseases has driven greater R&D investment, further boosting adoption of automated systems for efficient sample processing. Moreover, technological advancements in robotics, artificial intelligence, and cloud-based laboratory informatics have enhanced the precision, speed, and reproducibility of liquid handling processes, making them integral to modern research and diagnostic practices.
Liquid Handling Systems Market, by Product
The pipettes segment accounted for the largest share of the liquid handling systems market. Growth in the pipettes segment is driven by extensive use across industries such as biotech and pharma, research and academic institutions, hospitals, and diagnostic laboratories. Demand is rising due to the growing need for accurate liquid handling in drug discovery, molecular biology, and clinical diagnostics. In addition, advances in pipette technologies such as electronic and multi-channel pipettes are improving efficiency and precision, driving market growth. A growing emphasis on laboratory automation and quality control in healthcare and life sciences is also driving pipette adoption.
Liquid Handling Systems Market, by Application
The drug discovery segment is expected to dominate the market throughout the forecast period. This growth is primarily driven by rising R&D activity in the pharmaceutical and biopharmaceutical industries to develop treatments for chronic diseases. Liquid handling systems play a critical role in various stages of the drug discovery process, including sample preparation, assay setup, high-throughput screening, in vitro experiments, cellular assays, and in vivo toxicity testing, contributing to their strong demand in this segment.
Liquid Handling Systems Market, by End User
Hospitals and diagnostic laboratories are increasingly adopting liquid handling systems because of the growing volume of clinical testing and the need for faster, more accurate, standardized sample processing. The rising use of molecular diagnostics, PCR, immunoassays, genomics, and clinical chemistry is driving demand for automated pipetting, sample preparation, aliquoting, and reagent dispensing solutions. In addition, the need to reduce manual errors, improve turnaround time, enhance sample traceability, and address repetitive laboratory workloads is expected to support the growing adoption of automated liquid handling systems in hospitals and high-throughput diagnostic laboratories.
REGION
Asia Pacific to be fastest-growing region in liquid handling systems market during forecast period
The Asia Pacific region is seeing strong growth in the liquid handling system market, driven primarily by the rapid expansion of the pharmaceutical and biotechnology industries, increasing investments in healthcare infrastructure, and growing adoption of advanced laboratory automation technologies. Rising government funding for life science research, expanding diagnostic testing capabilities, including molecular and genomic testing, and the growing burden of chronic and infectious diseases are further accelerating demand for precise, efficient liquid handling solutions. Additionally, the growth of academic and research institutions, coupled with the rising presence of global and regional life-science companies, is fueling greater uptake of automated and semi-automated liquid handling systems across the region.
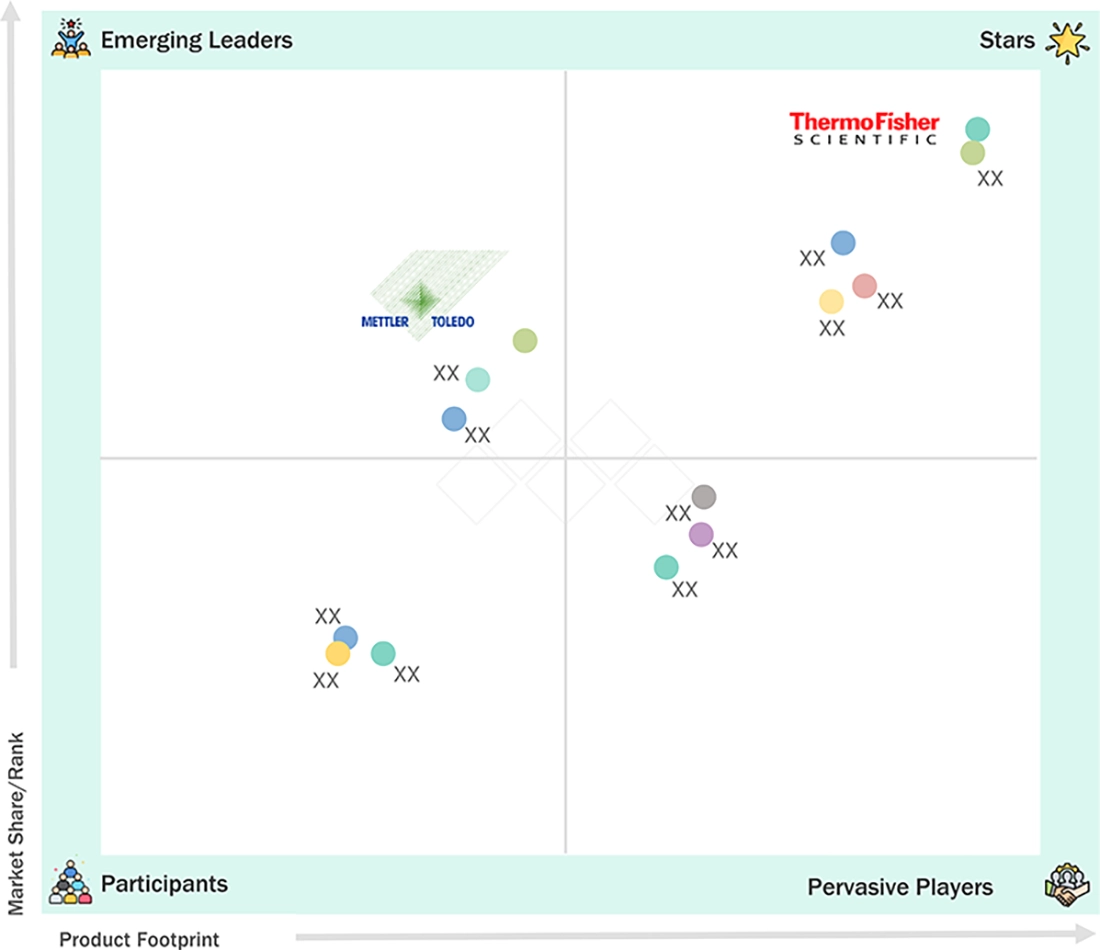
LIQUID HANDLING SYSTEM MARKET: COMPANY EVALUATION MATRIX
The Company Evaluation Matrix visually categorizes companies by market share/rank and product footprint. Thermo Fisher Scientific is positioned as a Star, indicating a strong market position with a broad product footprint. Mettler Toledo is identified as an Emerging Leader, showing growth potential but with a more limited product footprint compared to the leading players. Companies in the Participants and Pervasive Players categories have varying degrees of market influence and product range, with the latter group offering more widespread product availability but with lower market share. The matrix provides insights into the competitive landscape, highlighting key players and their strategic positioning in the liquid handling systems industry.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- Thermo Fisher Scientific Inc (US)
- Agilent Technologies Inc (US)
- Eppendorf (Germany)
- PerkinElmer Inc. (US)
- Sartorius AG (Germany)
- Mettler-Toledo International Inc. (US)
- Qiagen (Netherland)
- Corning Incorporated (US)
- Lonza Group Ltd. (Switzerland)
- Tecan Group Ltd. (Switzerland)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2025 (Value) | USD 4.99 Billion |
| Market Forecast in 2026 (Value) | USD 5.26 Billion |
| Market Forecast in 2031 (Value) | USD 7.79 Billion |
| Growth Rate | CAGR of 8.2% from 2026–2031 |
| Years Considered | 2024–2031 |
| Base Year | 2025 |
| Forecast Period | 2026–2031 |
| Units Considered | Value (USD Million/Billion) |
| Report Coverage | Revenue Forecast, Company Ranking, Competitive Landscape, Growth Factors, Trends |
| Segments Covered |
|
| Country Covered | North America, Asia Pacific, Europe, Latin America, Middle East & Africa |
WHAT IS IN IT FOR YOU: LIQUID HANDLING SYSTEM MARKET REPORT CONTENT GUIDE
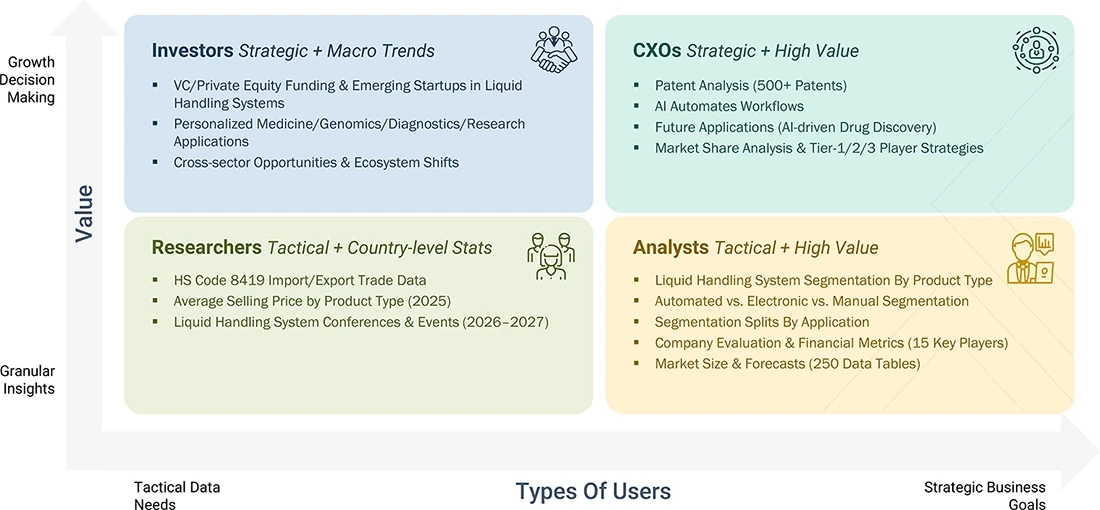
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Leading Liquid Handling OEM |
|
|
| Raw Material Supplier |
|
|
RECENT DEVELOPMENTS
- March 2026 : Thermo Fisher Scientific showcased new liquid handling and laboratory automation technologies at SLAS 2026, including the Multidrop Pico 8 digital dispenser and the upcoming FluidEase Cliptip electronic pipette. The company positioned these technologies alongside automated workflow solutions such as the Spinnaker 3 Microplate Mover and Momentum Workflow Scheduling Software to support higher-throughput, connected, and more efficient laboratory workflows.
- March 2024 : Agilent Technologies and the University of Vermont (UVM) announced the establishment of the Agilent Laboratory for Chemical Analysis, which will provide advanced instrumentation enabling students, institutional colleagues, industrial partners, and regional high-tech start-ups to study the composition and structure of chemical samples.
- June 2023 : Agilent Technologies Inc. launched the BioTek 406 FX Washer Dispenser, a compact device that combines plate washing and multifunctional reagent dispensing.
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
Methodology
The study involved four major activities to estimate the current size of the liquid handling systems market. We conducted extensive secondary research to gather information on the market, peer markets, and parent markets. The findings, assumptions, and market estimates were subsequently validated through primary research with industry experts across the value chain. Both top-down and bottom-up approaches were employed to estimate the overall market size. The report then segmented the market and triangulated data to estimate the size of key segments and subsegments across product types, applications, end users, and regions.
Secondary Research
The secondary research process involved the extensive use of industry databases, company websites, annual reports, investor presentations, SEC filings, white papers, financial reports, trade publications, and commercial databases such as Bloomberg Businessweek, Factiva, and D&B Hoovers. Secondary research gathered comprehensive technical, market-oriented, and commercial information on liquid handling systems, including their applications across pharmaceutical and biotechnology companies, hospitals, diagnostic laboratories, academic and research institutes, and other end users. It was also used to identify key market players, establish detailed market classification and segmentation, assess industry and technology trends, and identify key market developments and growth opportunities. Secondary research also helped develop a database of key industry participants and stakeholders.
Primary Research
During the primary research process, we interviewed supply- and demand-side stakeholders to obtain qualitative and quantitative insights for the study. Supply-side respondents included industry experts such as CEOs, vice presidents, marketing and sales directors, product managers, technology and innovation directors, and other senior executives from leading liquid handling system manufacturers and solution providers. Demand-side respondents included professionals from pharmaceutical and biotechnology companies, hospitals, diagnostic laboratories, academic and research institutions, CROs, and other laboratory end users. Primary research validated market segmentation and estimates, identified and assessed key market participants, and provided insights into technology adoption, application trends, purchasing criteria, competitive dynamics, and key market drivers and challenges influencing the liquid handling systems market.
A breakdown of the primary respondents is provided below:
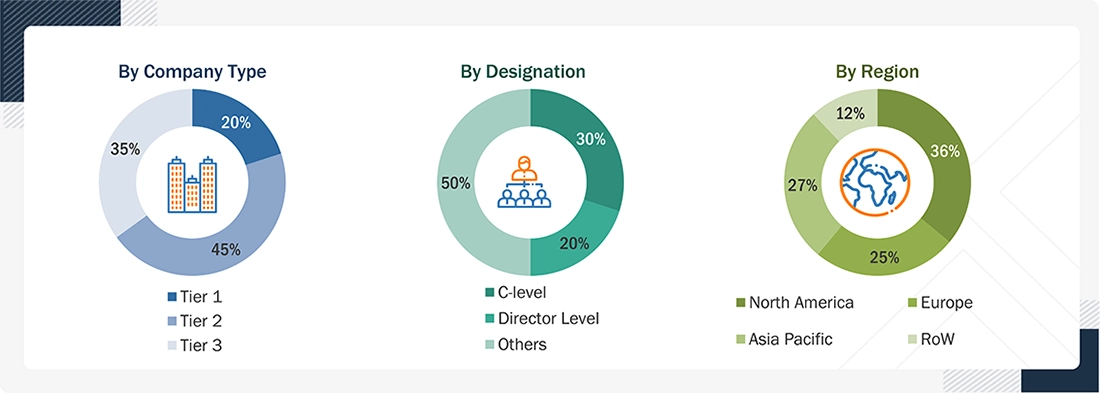
*Others include sales managers, marketing managers, business development managers, product managers, distributors, and suppliers.
Note: Companies are classified into tiers based on their total revenue. Tier 1 = >USD 400 million, Tier 2 = USD 200 million, and Tier 3 = <USD 100 million.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
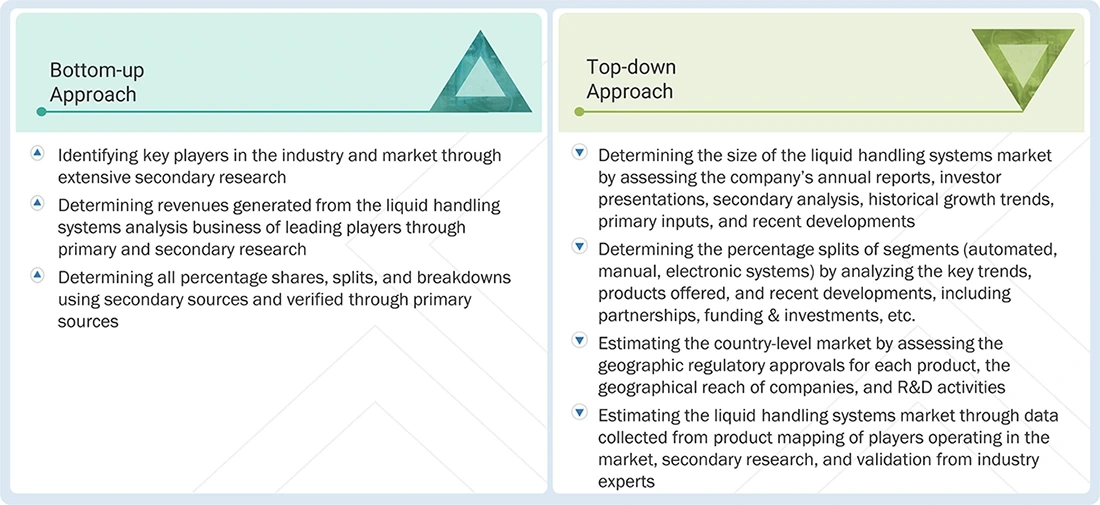
In this report, the liquid handling systems market size was determined using the revenue share analysis of leading players. For this purpose, we identified key market players and determined their revenues from the market business through insights gathered during the primary and secondary research phases. Secondary research included reviewing the annual and financial reports of the top market players. In contrast, primary research included extensive interviews with key opinion leaders, such as CEOs, directors, and key marketing executives at hospital procurement and biobanking divisions.
Segmental revenues were calculated by mapping the revenues of major solution/product providers to estimate the global liquid handling systems market value. This process involved the following steps:
- Generating a list of major global players operating in the liquid handling systems market.
- Mapping annual revenues generated by major global players from the liquid handling systems storage consumables segment (or nearest reported business unit/product category).
- Revenue mapping of major players to cover a major share of the global market, as of 2025.
- Extrapolating the global value of the liquid handling systems market, with specific attention to the healthcare end-user segment.
Liquid Handling System Market : Top-Down and Bottom-Up Approach
Data Triangulation
After arriving at the overall market size from the market size estimation process explained above, the global liquid handling systems market was split into segments and subsegments. We used data triangulation and market-breakdown procedures to complete the overall market engineering process and arrive at exact statistics for all segments and subsegments, including the hospitals and diagnostic laboratories end-user category. The data was triangulated by studying various factors and trends from both the demand and supply sides. Additionally, the liquid handling systems market was validated using top-down and bottom-up approaches.
Market Definition
The liquid handling systems market comprises manual, semi-automated, and automated instruments and solutions designed to accurately aspirate, dispense, transfer, and handle liquid samples and reagents in laboratory environments. These systems are widely used across pharmaceutical and biotechnology research, clinical diagnostics, life sciences, chemical analysis, and drug discovery to improve precision, reproducibility, and workflow efficiency. Liquid handling systems support a broad range of downstream applications, including next-generation sequencing (NGS), polymerase chain reaction (PCR), mass spectrometry, cell analysis, flow cytometry, genomics, epigenetics, and proteomics.
Key Stakeholders
- Manufacturers of liquid handling products
- Liquid handling product distributors
- Venture capitalists and investors
- Genomics and proteomics associations
- Drug discovery and development research centers
- Hospitals and diagnostic laboratories
- Research & consulting firms
- Contract manufacturers of liquid handling systems and consumables
- Research institutes and contract research organizations (CROs)
- Government associations
Report Objectives
- To define, describe, and forecast the size of the liquid handling systems market based on type, product, application, end user, and region
- To provide detailed information regarding the major factors influencing the growth potential of the global liquid handling systems market (drivers, restraints, opportunities, challenges, and trends) from a healthcare industry perspective
- To analyze the micromarkets with respect to individual growth trends, prospects, and contributions to the global liquid handling systems market, with emphasis on hospitals and diagnostic laboratories
- To analyze key growth opportunities in the global liquid handling systems market for key stakeholders and provide details of the competitive landscape for market leaders
- To forecast the size of market segments and/or subsegments with respect to five major regions: North America (US and Canada), Europe (Germany, France, the UK, Italy, Spain, and the Rest of Europe), Asia Pacific (Japan, China, India, Australia, South Korea, and the Rest of Asia Pacific), Latin America (Brazil, Mexico, and the Rest of Latin America), and the Middle East & Africa
- To profile the key players in the liquid handling systems market and comprehensively analyze their market shares and core competencies
- To track and analyze the competitive developments undertaken in the global liquid handling systems market, such as product launches, agreements, expansions, and mergers & acquisitions
Available customizations:
Based on the market data provided, customizations are offered to meet the company's specific needs. The following customization options are available for the present global liquid handling systems market report:
Product Analysis
- Product matrix, which gives a detailed comparison of the product portfolios of the top five companies.
- Detailed analysis and profiling of additional market players (up to five).
Geographic Analysis
- Further breakdown of the Rest of Europe liquid handling systems market into Russia, Belgium, the Netherlands, Switzerland, Austria, Finland, Sweden, Poland, and Portugal, among others.
- Further breakdown of the Rest of Asia Pacific liquid handling systems market into Singapore, Taiwan, New Zealand, the Philippines, Malaysia, and other APAC countries.
- Further breakdown of the Latin American liquid handling systems market into Colombia, Chile, Argentina, and Peru, among others.
Frequently Asked Questions (FAQ)
What is the estimated market value of the global liquid handling system market?
The global liquid handling system market is estimated at USD 5.1 billion in 2025.
What is the CAGR of the global liquid handling system market for the next five years?
The global liquid handling system market is projected to grow at a CAGR of 8.0% from 2025 to 2030.
Which product segment of the liquid handling system market is projected to witness the fastest growth?
The pipettes segment is projected to grow at the highest CAGR during the forecast period.
What are the major revenue pockets in the liquid handling system market currently?
The Asia Pacific market is projected to experience the highest CAGR, driven by increased R&D investment, emphasis on cancer research, and growth in pharmaceutical research outsourcing.
Which end user segment is likely to show the highest growth in the liquid handling system market?
Hospitals & diagnostic laboratories are expected to grow at the highest rate in the liquid handling system market by end user.


Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the Liquid Handling System Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Custom Market Research Services
We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements
Get 10% Free CustomisationTESTIMONIALS
JAYANT RAJPUROHIT
Director of Market Insights, Data and Analytics
SFI Health,
Leading Pharmaceutical Companywww.sfihealth.com/
We at SFI Health approached MarketsandMarkets for an Opportunity Assessment on "Incidence and Prevalence of Focus Indications" as we wanted to know the most attractive HCPs like Physician, Functional MD, Naturopath and Pharmacist. The project was critical for us to ensure our focus on the right target which would enable sustainable growth and profitability for SFI Health. The business insights provided exceeded our expectations and we were extremely impressed. The team at MarketsandMarkets is highly professional and detail oriented and very well understood our business needs. MarketsandMarkets offers a unique combination of expertise and dedicated engagement model. We identified 2 new products to be launched in coming months, based on the research findings provided by MarketsandMarkets. We are happy with the services and would strongly recommend MarketsandMarkets to my peers in the industry.
BEATRIZ DE LA CALLE
Head of Commercial Analytics
Qualicaps,
Leading Pharmaceutical Companywww.qualicaps.com/
We partnered with MarketsandMarkets for an assessment study on hard empty capsules. The team was extremely professional in understanding our business requirements and we received timely responses to all our queries. The market intelligence and the recommendations has met our business requirements. We were extremely impressed to see the final study results; it really exceeded our expectations. The market intelligence offered by MarketsandMarkets, and clarity on next steps will help us achieve our business objective for the Year 2021. We are happy with the services and would strongly recommend MarketsandMarkets to my peers in the industry.

Bob Williams,
Senior Director Business Development & Innovation
Bracco Diagnostics Inc.,
Italian Multinational in life sciences sector and a World Leader in imaging diagnosticsimaging.bracco.com/us-en
We were pleased with targeted insights that MarketsandMarkets identified from a custom study on the 'Radiation Dose Management Solutions Market'. Your team identified and characterized the market participants as well as underlying trends accurately. This study was useful to Bracco in formulating business strategies for our dose monitoring product lines and we thank MarketsandMarkets for the job well done.
Cody Coonradt,
Market Development and Strategy Manager
3M Health Information Systems,
Leader in Health care Coding, Payment & Analytics Solutions.www.3m.com/3M/en_US/health-information-systems-us
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarketsandMarkets, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer.
Their customer first approach and high value engagement model, have given us great analysis and excellent value for money
- Canada Liquid Handling System Market
- US Liquid Handling System Market
- Germany Liquid Handling System Market
- UK Liquid Handling System Market
- France Liquid Handling System Market
- Italy Liquid Handling System Market
- Spain Liquid Handling System Market
- China Liquid Handling System Market
- Japan Liquid Handling System Market
- India Liquid Handling System Market
- South Korea Liquid Handling System Market
- Australia Liquid Handling System Market
- Brazil Liquid Handling System Market
- Mexico Liquid Handling System Market
- Rest Of Europe Liquid Handling System Market
- Rest Of Asia Liquid Handling System Market
- Rest Of Latin America Liquid Handling System Market
- GCC Liquid Handling System Market
Growth opportunities and latent adjacency in Liquid Handling System Market





GILHO
Nov, 2019
Flow sensor of Liquid Handling System .