Space-based Data Center Market by Payload (Communication & Data Transfer, Data Processing, Data Storage), Power Capacity (<100 kW, >100 kW-<1 MW, >1 MW), Application (AI/ML, Cloud, Analytics, Data Storage), End User, and Region - Global Forecast to 2040

icon1
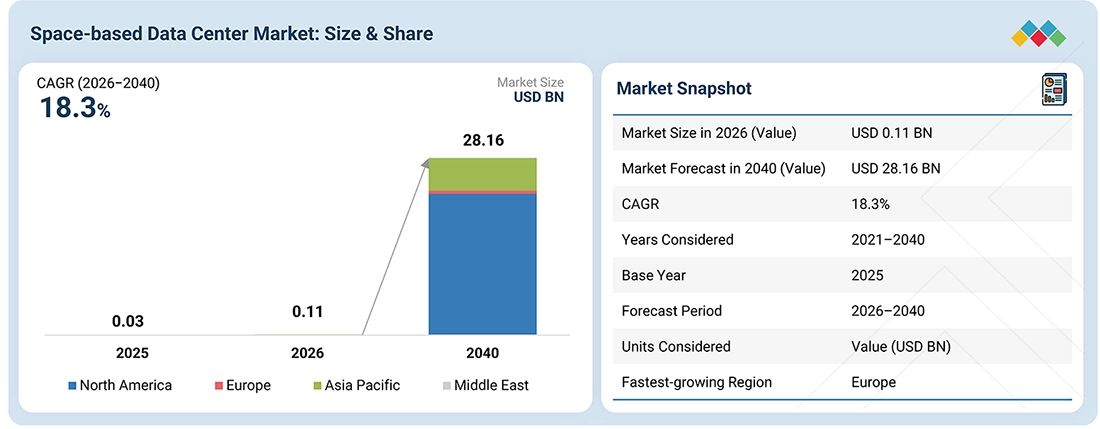
USD 28.16 BN
MARKET SIZE, 2040
icon2
CAGR 18.3%
(2026-2040)
icon3
300
REPORT PAGES
icon4
200
MARKET TABLES

OVERVIEW

space-based-data-center-market Overview

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

The space-based data center market is projected to grow from USD 0.11 billion in 2026 to USD 28.16 billion by 2040, at a CAGR of 18.3%. The space-based data center market is projected to grow from 56 deployed satellites/nodes in 2026 to 14,332 satellites/nodes by 2040. This growth is driven by the rising volume of space-generated data and growing demand for space computing, space edge computing, cloud computing in space, and AI data centers in space to process and store data closer to where it is generated. The increasing use of AI inference in space, GPU computing in space, optical satellite communication, and distributed data center infrastructure is supporting the development of the space-based data center market.

KEY TAKEAWAYS

  • By Region
    Europe is expected to register a CAGR of 43.6% during the forecast period.
  • By Payload
    By payload, the data storage unit segment will register the highest growth rate of 18.3% during the forecast period.
  • By Communication Infrastructure
    By communication infrastructure, the solution segment accounts for the largest market share.
  • By Application
    By application, the data processing & analytics segment is expected to hold the largest market share during the forecast period.
  • By Power Capacity
    By power capacity, ≥1 MW segment will register the highest CAGR of 32.6% during the forecast period.
  • By End User
    By end user, the government & defense segment will register the highest growth during the forecast period.
  • Competitive Landscape - Key Players
    Starcloud, Inc., Axiom Space, Inc., Kepler Communications Inc., and Cowboy Space Corporation were identified as some of the star players, given their strong market share and product footprint.
  • Competitive Landscape - SME
    NVIDIA Corporation has identified itself among SMEs by securing strong footholds in specialized niche areas, underscoring its potential as an emerging leader in the space-based data center market.

The space-based data center market is growing as satellites and other spacecraft generate more data. This has increased demand for in-orbit computing and space edge computing, which allow processing information directly in space before transmitting it to Earth. Onboard processing can help reduce data transfer requirements and support faster analysis of data generated in space.

TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS

The space-based data center market is primarily driven by the need to process, store, and manage increasing volumes of data closer to where it is generated in space. Historically, the market has focused on space-qualified computing and storage payloads, onboard data processing units, spacecraft integration, launch support and ground station services. However, the market is shifting toward space computing, orbital computing, in-orbit computing, space edge computing, and cloud computing in space, supported by modular compute and storage systems, high-capacity optical links, and distributed data center infrastructure. New use cases such as sovereign data storage, disaster recovery, onboard analytics, AI data centers in space, space-based AI computing, in-orbit AI computing, AI inference in space, and GPU computing in space are expected to change the future revenue mix. These changes are supported by advances in edge computing, edge AI, distributed computing, machine learning, cloud computing, GPU, optical satellite communication, and space-to-space and space-to-ground connectivity. This shift is increasing the role of computing and data storage hardware suppliers, optical communication providers, satellite manufacturers, launch companies, and ground network operators. The evolution of the orbital data center market and in-orbit data center market is also expanding potential demand from government and defense organizations, critical infrastructure operators, financial institutions, satellite operators, and research organizations.
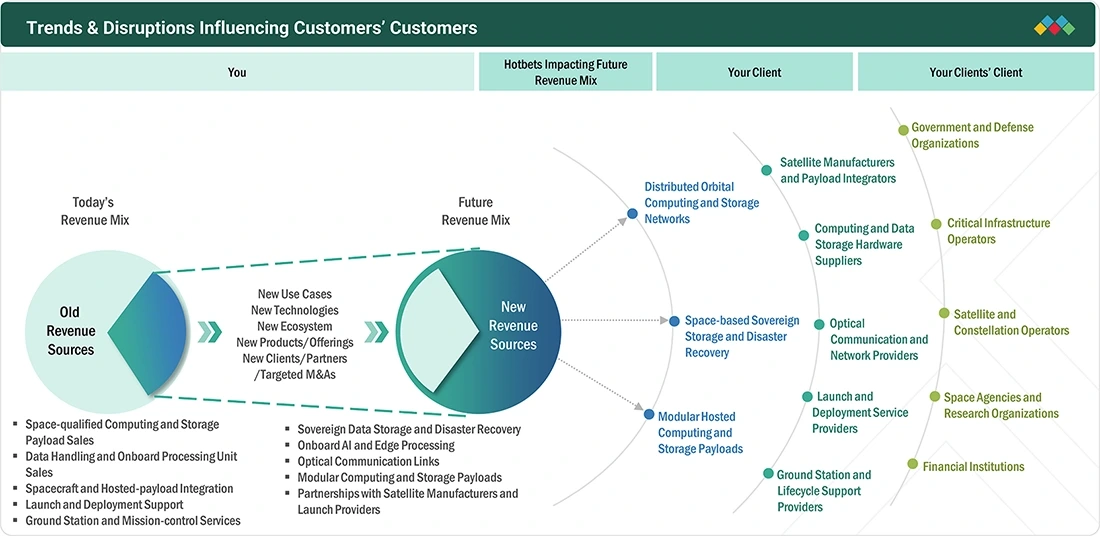
space-based-data-center-market Disruptions

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

MARKET DYNAMICS

Drivers
Impact
Level
  • Rising Demand for AI and High-performance Computing Infrastructure
  • Growing Volume of Space-generated Data Requiring Real-time Processing
RESTRAINTS
Impact
Level
  • High Initial Deployment and Lifecycle Ownership Costs
  • Long Development and Space Qualification Cycles
OPPORTUNITIES
Impact
Level
  • On-orbit Edge Processing for Satellite-generated Data
  • Orbital Cloud Computing and Data Storage Services
CHALLENGES
Impact
Level
  • Thermal Management and Heat Rejection in Space
  • Radiation Resilience and Computing Reliability

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Driver : Rising Demand for AI and High-performance Computing Infrastructure

The space-based data center market is supported by rising demand for AI data centers in space, space-based AI computing, and GPU computing in space. AI training, inference and data processing workloads require greater computing capacity, increasing interest in deploying compute infrastructure closer to space-generated data sources.

Restraint : High Initial Deployment and Lifecycle Ownership Costs

The space-based data center market requires significant investment in space qualified computing hardware, launch, power systems, thermal management, satellite communication, and ground infrastructure. These costs can limit near term adoption compared with terrestrial data center infrastructure, especially for workloads that do not require in-orbit computing.

Opportunity : On-orbit Edge Processing for Satellite-generated Data

Space edge computing allows satellites to process and filter data before sending it to Earth, reducing the amount of raw data that must be transmitted. This creates opportunities for edge computing, edge AI, AI inference in space, and in-orbit AI computing for Earth observation, defense, scientific, and commercial applications.

Challenge: Thermal Management and Heat Rejection in Space

High-density space computing hardware generates heat that must be removed without conventional air or water cooling systems. Effective thermal control and heat rejection are therefore important for maintaining the performance and reliability of cloud computing in space, distributed computing, and other orbital data center systems.

SPACE-BASED DATA CENTER MARKET SIZE, SHARE & TRENDS: COMMERCIAL USE CASES ACROSS INDUSTRIES

COMPANY USE CASE DESCRIPTION BENEFITS
company logo
Lonestar tested its Independence data storage payload during the IM-1 lunar mission in February 2024. The payload stored, transmitted, retrieved, and restored digital records in cislunar space and on the lunar surface, demonstrating data storage, backup, and archival for the space-based data center market. Supports off-Earth data backup and disaster recovery I Reduces dependence on terrestrial data center infrastructure | Demonstrates storage, retrieval and recovery of digital data in space | Supports future space-based data center market services
company logo
AWS Snowcone was deployed to the International Space Station during the Ax-1 mission in 2022 for local storage and image processing. The system used onboard solid-state storage and a machine learning model to process photographs in about three seconds, demonstrating space edge computing and AI inference in space. Processes data closer to where it is generated | Reduces the volume of raw data sent to Earth | Supports machine learning, edge computing, and local storage in orbit | Demonstrates commercial in-orbit computing on the ISS
company logo
Axiom Space successfully launched two dedicated orbital data center nodes into low Earth orbit in January 2026. The nodes were connected through Kepler Communications' optical relay satellites and were designed to provide cloud computing in space, data storage, and onboard processing for satellites and other spacecraft. Provides space computing and storage capacity in orbit | Supports distributed computing through optical connectivity | Reduces dependence on terrestrial data centers for selected workloads | Creates infrastructure for the space-based data center market for future AI data centers in space

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET ECOSYSTEM

The space-based data center market ecosystem includes direct solution providers, technology enablers, and end users. Key players such as Lonestar Data Holdings Inc. (US), Axiom Space, Inc. (US), Starcloud, Inc. (US), Kepler Communications Inc. (Canada), Space Exploration Technologies Corp. (US), and SpaceBilt Incorporated (US), among other orbital infrastructure companies, are developing space computing, orbital computing, in-orbit computing, data storage, and space edge computing platforms. These companies are building data center infrastructure to support cloud computing in space, AI data centers in space, GPU computing in space, and distributed computing across satellites and other orbital platforms. Technology enablers such as NVIDIA Corporation (US), Skycorp Incorporated (US), Sidus Space, Inc. (US), and Red Hat, Inc. (US) provide computing hardware, AI processors, software platforms, and system integration technologies used in the orbital data center market. The main end users include government agencies, defense and intelligence organizations, cloud and technology companies, satellite and Earth observation operators, and research and scientific organizations. These users are evaluating the in-orbit data center market for AI inference in space, machine learning, data processing, storage, backup, and secure satellite communication applications.
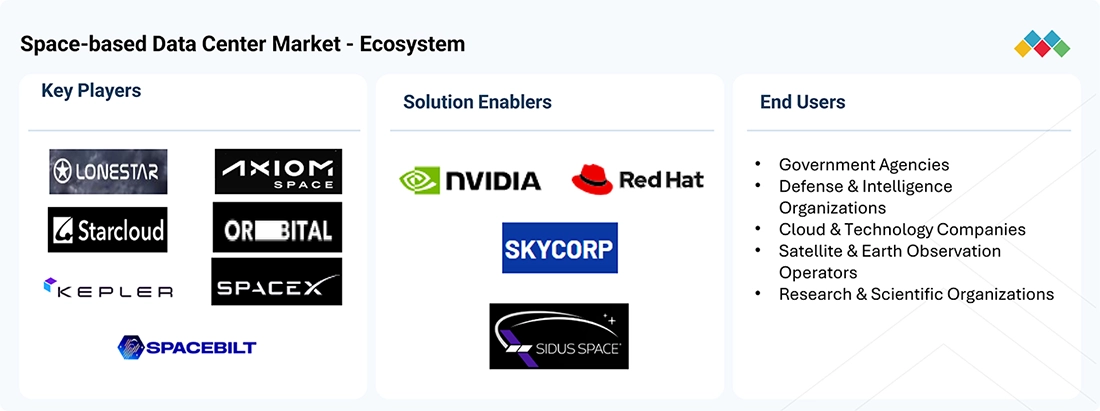
space-based-data-center-market Ecosystem

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET SEGMENTS
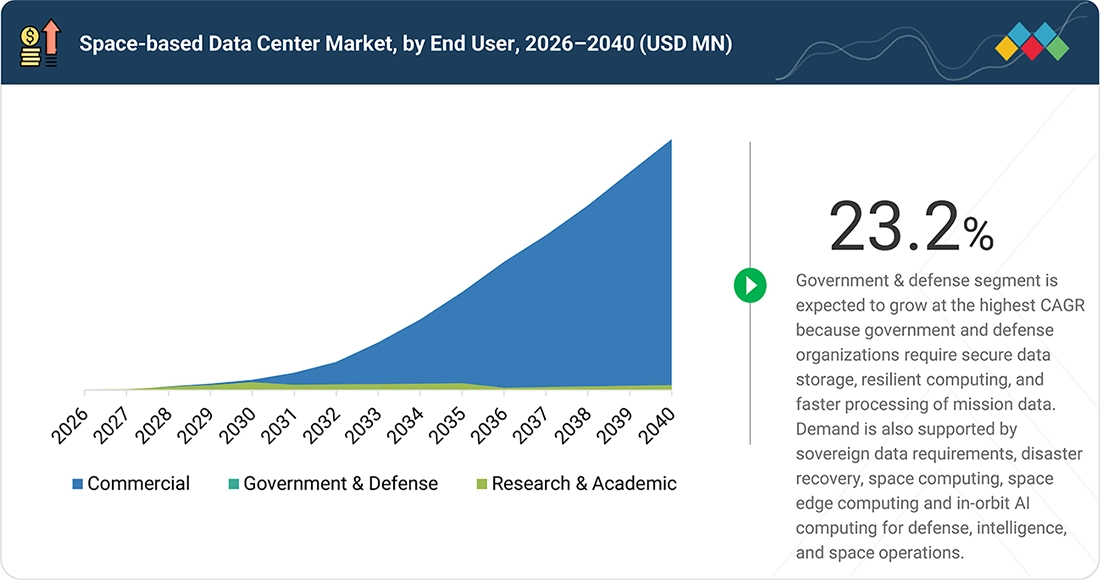
space-based-data-center-market Segments

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Space-based Data Center Market, by Payload

By payload, the data storage unit segment is expected to grow at the highest rate during the forecast period. Growth is supported by rising demand for onboard storage, backup, and archival of space-generated data, along with increasing use of space computing, cloud computing in space, and distributed data center infrastructure.

Space-based Data Center Market, by Communication Infrastructure

By communication infrastructure, the solution segment is expected to hold the dominant market position during the forecast period. Demand is supported by the need for space-to-space and space-to-ground connectivity for orbital computing, distributed computing, and data transfer between orbital platforms and terrestrial systems through satellite communication networks.

Space-based Data Center Market, by Application

By application, data processing & analytics is expected to hold the dominant market position during the forecast period. The segment is supported by growing volumes of satellite-generated data and increasing use of in-orbit computing, space edge computing, machine learning, and AI inference in space to process data closer to where it is generated.

Space-based Data Center Market, by Power Capacity

By power capacity, the ≥1 MW segment is expected to register the highest growth rate during the forecast period. Higher power capacity is required to support larger AI data centers in space, GPU computing in space, cloud computing GPU workloads, and other high-performance space-based AI computing applications.

Space-based Data Center Market, by End User

By end user, the government & defense segment is expected to register the highest growth rate during the forecast period. Demand is supported by requirements for secure data processing, sovereign storage, disaster recovery, edge AI, and resilient orbital data center infrastructure for defense, intelligence, and government missions.

REGION

Europe to be fastest-growing region in space-based data center market during forecast period

Europe is expected to record the fastest growth in the space-based data center market during the forecast period, supported by increasing investment in space computing, orbital computing, and secure data center infrastructure. The region is also seeing growing interest in cloud computing in space, space edge computing, and AI data centers in space for government, defense, research, and commercial applications. In addition, European space programs, optical satellite communication, and work on sovereign data storage and distributed computing are supporting the development of the space-based data center market.
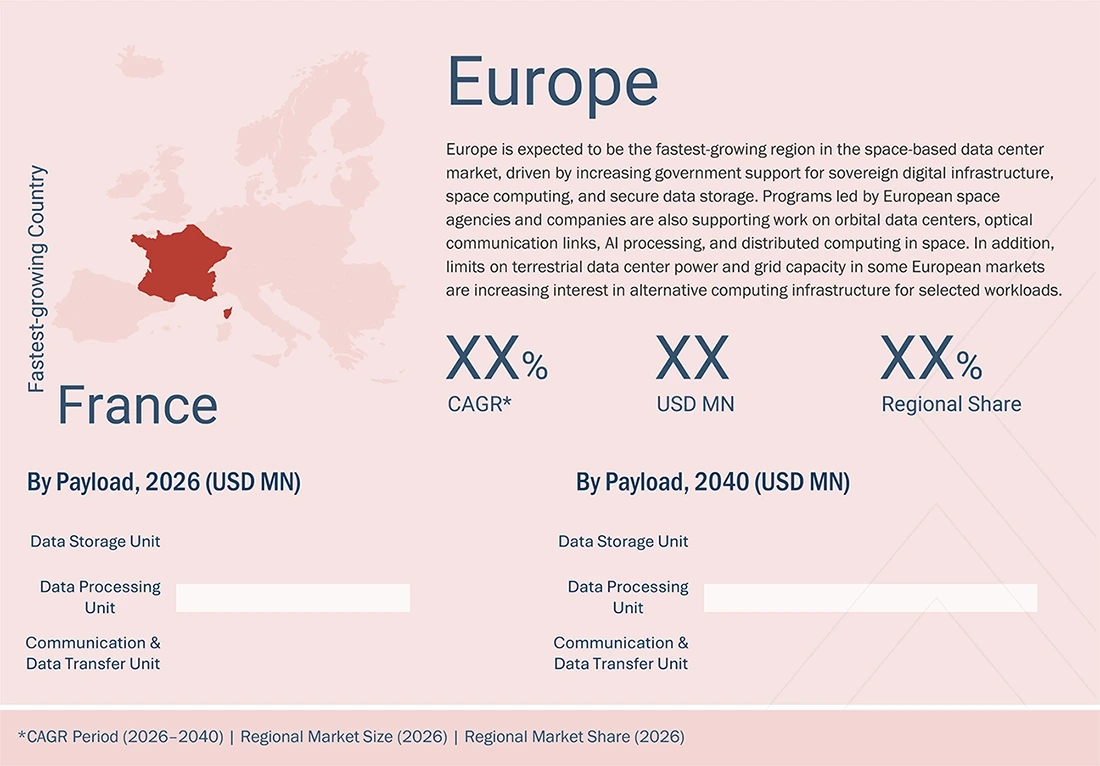
space-based-data-center-market Region

SPACE-BASED DATA CENTER MARKET SIZE, SHARE & TRENDS: COMPANY EVALUATION MATRIX

In the space-based data center market matrix, Starcloud Inc. is categorized as a “Star” because it directly focuses on AI data centers in space, has demonstrated the use of an NVIDIA H100 GPU in orbit, and plans to expand into larger orbital computing systems through Starcloud-2. The company is developing capabilities in GPU computing in space, in-orbit AI computing, persistent data storage, and cloud computing in space, giving it a broader position across computing, storage, and data center infrastructure. Lonestar Data Holdings, on the other hand, is classified as an “Emerging Player” because its current activities are focused mainly on sovereign data storage, backup, disaster recovery and space edge computing through its lunar and orbital platforms. Lonestar has demonstrated storage and retrieval of data in space and is developing StarVault, StarSafe, StarDrive and StarAI, but its large-scale space-based AI computing and orbital computing infrastructure is still at an earlier stage than Starcloud's. In summary, companies with demonstrated high-performance space computing, scalable AI processing, and broader orbital data center market infrastructure rank higher in the matrix, while companies focused mainly on storage, backup, and developing in-orbit computing services are positioned in the emerging category.
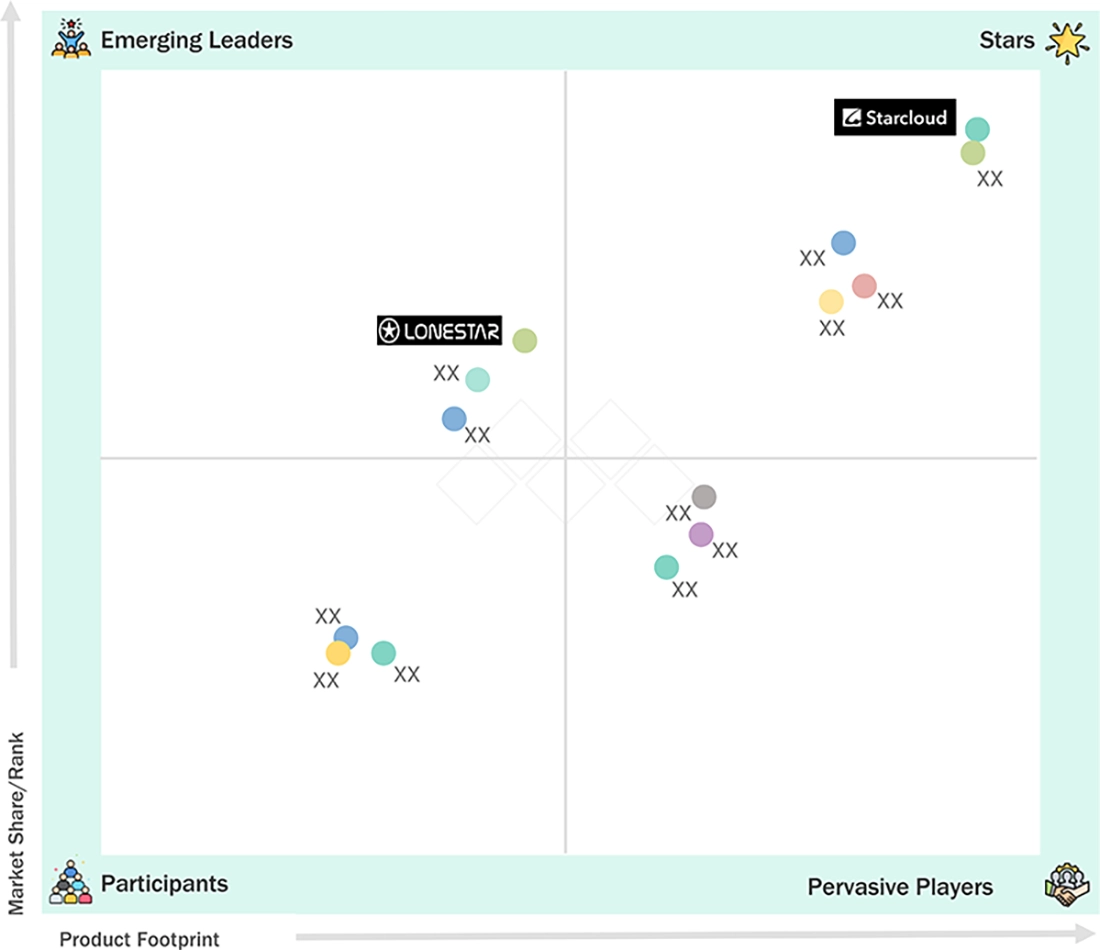
space-based-data-center-market Evaluation Metrics

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

KEY MARKET PLAYERS

  • Starcloud, Inc. (US)
  • Axiom Space, Inc. (US)
  • Kepler Communications Inc. (Canada)
  • Cowboy Space Corporation (US)
  • SpaceX (US)
  • Lonestar Data holdings Inc. (US)
  • Red Hat, Inc. (US)
  • Rotonium srl (Italy)
  • OrbitsEdge, Inc. (US)
  • space compass corporation (Japan)
  • Cloud Constellation Corporation (US)
  • Thales Alenia Space (France)
  • Voyager Technologies, Inc. (US)
  • Madari Space (UAE)
  • Hewlett Packard Enterprise Development LP (US)
  • NVIDIA Corporation (US)
  • International Business Machines Corporation (US)
  • Microsoft Azure Space (US)
  • Amazon Web Services, Inc. (US)
  • Intel Corporation (US)
  • KIOXIA Europe GmbH (Germany)
  • Cerebras (US)
  • Space Forge (UK)
  • Blue Origin (US)
  • Sophia Space Inc. (US)
  • International Astronautical Federation (France)

MARKET SCOPE

REPORT METRIC DETAILS
Market Size in 2025 (Value) USD 0.03 Billion
Market Size in 2026 (Value) USD 0.11 Billion
Market Forecast in 2040 (Value) USD 28.16 Billion
CAGR 18.3%
Years Considered 2021–2040
Base Year 2025
Forecast Period 2026–2040
Units Considered USD Billion/Million
Report Coverage Revenue Forecast, Company Ranking, Competitive Landscape, Growth Factors, and Trends
Segments Covered By Payload: Data Processing Unit, Data Storage Unit, Communication & Data Transfer Unit I By Application: AI & Machine Learning Computing, Data Processing & Analytics, Cloud & General-Purpose Computing, Data Storage, Backup & Archival I By End User: Commercial, Government & Defense, Research & Academic I By Power Capacity: ≤100 kW, >100 kW to <1 MW, ≥1 MW I By Communication Infrastructure: Technology, Payload, Hardware, Solution
Regions Covered North America, Europe, Asia Pacific, Middle East

WHAT IS IN IT FOR YOU: SPACE-BASED DATA CENTER MARKET SIZE, SHARE & TRENDS REPORT CONTENT GUIDE
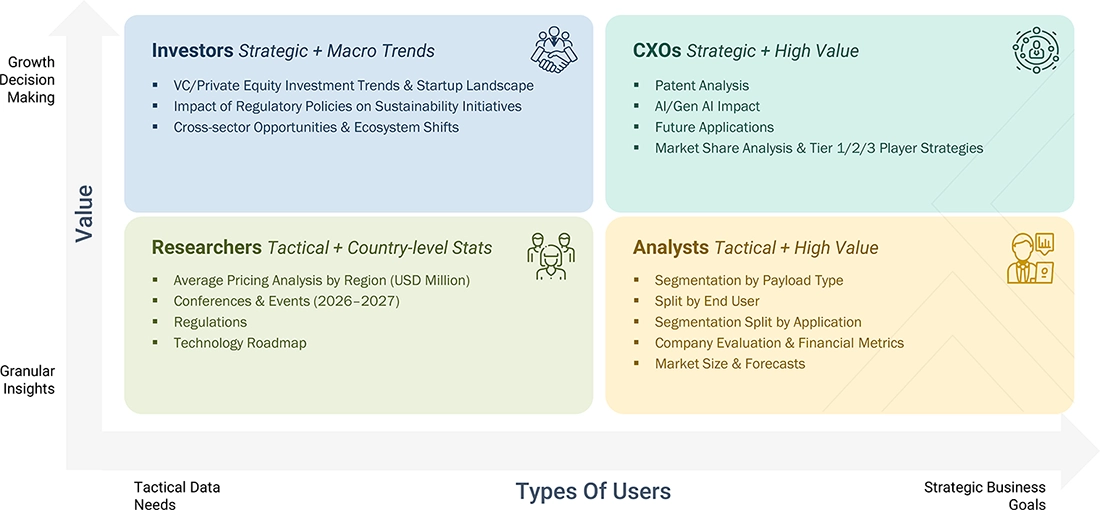
space-based-data-center-market Content Guide

DELIVERED CUSTOMIZATIONS

We have successfully delivered the following deep-dive customizations:

CLIENT REQUEST CUSTOMIZATION DELIVERED VALUE ADDS
Leading Manufacturer Additional segment breakdown for countries Additional country-level market sizing tables for segments/subsegments covered at the regional/global level to gain an understanding of market potential by each country
Emerging Leader Additional company profiles Competitive information on targeted players to gain granular insights on direct competition
Regional Market Leader Additional country market estimates Additional country-level deep dive for a more targeted understanding of the total addressable market

RECENT DEVELOPMENTS

  • July 2026 : Sophia Space and Caltech entered into a sponsored research agreement covering thermal management and lightweight deployable structures for future space-based data center systems. The work supports larger Orbital Computing platforms and higher-capacity data center infrastructure in space.
  • June 2026 : Madari Space and Mindlogicx signed an agreement covering AI, sovereign cloud, cybersecurity, space edge computing, and secure orbital data platforms. The cooperation supports cloud computing in space, in-orbit AI computing, and secure data-processing services.
  • May 2026 : Cowboy Space Corporation raised USD 275 million in Series B funding to support the development of its Stampede orbital data center system, satellites, compute payloads, and related infrastructure. The program is focused on AI data centers in space, GPU computing in space, and large-scale orbital data center deployment.

Table of Contents

checkmarkExclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.

TITLE
PAGE NO
1
INTRODUCTION


29
2
EXECUTIVE SUMMARY


33
3
PREMIUM INSIGHTS


37
4
MARKET OVERVIEW
Space data centers revolutionize real-time processing with AI, despite high costs and technical hurdles.


40
 
4.1
INTRODUCTION


4.2
MARKET DYNAMICS


4.2.1
DRIVERS


4.2.1.1
RISING DEMAND FOR ARTIFICIAL INTELLIGENCE (AI) AND HIGH-PERFORMANCE COMPUTING INFRASTRUCTURE


4.2.1.2
INCREASING CONSTRAINTS ON TERRESTRIAL DATA CENTER EXPANSION


4.2.1.3
GROWING VOLUME OF SPACE-GENERATED DATA REQUIRING REAL-TIME PROCESSING


4.2.1.4
ADVANCEMENT IN LAUNCH, POWER, COMMUNICATION, AND SPACE COMPUTING TECHNOLOGIES


4.2.2
RESTRAINTS


4.2.2.1
HIGH INITIAL DEPLOYMENT AND LIFECYCLE OWNERSHIP COSTS


4.2.2.2
LIMITED ECONOMIC VIABILITY FOR EARTH-CENTRIC COMPUTING WORKLOADS


4.2.2.3
LIMITED COMMERCIAL HERITAGE AND CUSTOMER CONFIDENCE


4.2.2.4
LONG DEVELOPMENT AND SPACE QUALIFICATION CYCLES


4.2.3
OPPORTUNITIES


4.2.3.1
ON-ORBIT EDGE PROCESSING FOR SATELLITE-GENERATED DATA


4.2.3.2
ORBITAL CLOUD COMPUTING AND DATA STORAGE SERVICES


4.2.3.3
SOVEREIGN AND RESILIENT COMPUTING INFRASTRUCTURE FOR GOVERNMENT AND DEFENSE


4.2.3.4
GROWING DEMAND FOR SPACE DATA CENTER SUBSYSTEMS AND SUPPORT SERVICES


4.2.4
CHALLENGES


4.2.4.1
THERMAL MANAGEMENT AND HEAT REJECTION IN SPACE


4.2.4.2
RADIATION RESILIENCE AND COMPUTING RELIABILITY


4.2.4.3
MAINTENANCE, REPAIR, AND TECHNOLOGY REFRESH LIMITATIONS


4.3
UNMET NEEDS AND WHITE SPACES


4.3.1
SCALABLE POWER AND THERMAL MANAGEMENT FOR HIGH-DENSITY COMPUTING


4.3.2
SPACE-QUALIFIED HIGH-PERFORMANCE COMPUTING AND UPGRADEABLE HARDWARE


4.3.3
HIGH CAPACITY SPACE-TO-SPACE AND SPACE-TO-GROUND DATA CONNECTIVITY


4.3.4
PROVEN COMMERCIAL SERVICE MODELS AND CUSTOMER CONFIDENCE


4.4
INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES


4.4.1
SATELLITE, EARTH OBSERVATION, AND IN-SPACE DATA PROCESSING


4.4.2
CLOUD COMPUTING, AI, AND HIGH-PERFORMANCE COMPUTING


4.4.3
OPTICAL COMMUNICATIONS AND SPACE NETWORKING


4.4.4
POWER, THERMAL MANAGEMENT, LAUNCH, AND IN-ORBIT SERVICING


4.5
STRATEGIC MOVES BY TIER 1/2/3 PLAYERS


5
INDUSTRY TRENDS
Discover transformative shifts in data center ecosystems with space-based solutions leading industry innovation.


55
 
5.1
ECOSYSTEM ANALYSIS


5.1.1
KEY ENABLERS


5.1.2
SOLUTION PROVIDERS


5.1.3
END USERS


5.2
VALUE CHAIN ANALYSIS


5.2.1
RESEARCH AND SYSTEM DESIGN


5.2.2
CORE PRODUCT DEVELOPMENT


5.2.3
PAYLOAD AND PLATFORM MANUFACTURING


5.2.4
LAUNCH, INTEGRATION, AND COMMISSIONING


5.2.5
SERVICE DELIVERY AND LIFECYCLE SUPPORT


5.3
COST COMPARISON OF TERRESTRIAL AND SPACE DATA CENTERS


5.4
PRICING ANALYSIS


5.4.1
INDICATIVE PRICING, BY POWER CAPACITY


5.4.2
AVERAGE SELLING PRICE TREND, BY REGION, 2021-2025 (USD MILLION)


5.5
TRADE DATA ANALYSIS


5.5.1
IMPORT SCENARIO (HS CODE 880260)


5.5.2
EXPORT SCENARIO (HS CODE 880260)


5.6
COMPARISON OF CONVENTIONAL DATA CENTER AND SPACE-BASED DATA CENTER


5.7
CASE STUDY ANALYSIS


5.7.1
LONESTAR INDEPENDENCE LUNAR DATA-CENTER TEST


5.7.2
AWS SNOWCONE EDGE-COMPUTING TEST ON ISS


5.7.3
AXIOM SPACE ORBITAL DATA CENTER NODES


5.7.4
KEPLER DISTRIBUTED ON-ORBIT COMPUTING NETWORK


5.8
KEY UPCOMING PROGRAMS


5.9
PARAMETRIC ANALYSIS OF TERRESTRIAL AND SPACE DATA CENTER


5.10
KEY CONFERENCES & EVENTS, 2026-2027


5.11
INVESTMENT AND FUNDING SCENARIO


5.12
TRENDS AND DISRUPTIONS IMPACTING CUSTOMER BUSINESS


5.13
MACROECONOMIC OUTLOOK


5.13.1
INTRODUCTION


5.13.2
GDP TRENDS AND FORECAST


5.13.3
TRENDS IN GLOBAL DATA CENTER INDUSTRY


5.13.4
TRENDS IN GLOBAL SPACE INDUSTRY


5.14
BUSINESS MODELS


5.14.1
ORBITAL COMPUTE AND STORAGE AS A SERVICE


5.14.2
HOSTED COMPUTE PAYLOAD MODEL


5.14.3
DEDICATED ORBITAL DATA CENTER INFRASTRUCTURE


5.14.4
INTEGRATED COMPUTE AND DATA-TRANSFER SERVICE


5.15
BILL OF MATERIALS


5.16
TOTAL COST OF OWNERSHIP


5.17
VOLUME DATA


6
TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
AI-driven innovations redefine space-based data centers, unlocking unprecedented market potential and technological advancements.


81
 
6.1
KEY EMERGING TECHNOLOGIES


6.1.1
HIGH-PERFORMANCE COMPUTING & EDGE COMPUTING


6.1.2
HIGH-DATA-BANDWIDTH OPTICAL LINKS


6.1.3
RADIATION HARDENED & RADIATION TOLERANT PROCESSORS / SOCS


6.1.4
ADVANCED THERMAL MANAGEMENT / MICROGRAVITY LIQUID COOLING


6.1.5
HIGH-POWER DEPLOYABLE SOLAR ARRAYS


6.2
COMPLEMENTARY TECHNOLOGIES


6.2.1
ROBOTIC SERVICING & REPAIR


6.2.2
ON-ORBIT ROBOTIC ASSEMBLY


6.2.3
REUSABLE HEAVY LIFT LAUNCH VEHICLES


6.2.4
ORBITAL TRANSFER VEHICLE (OTV)


6.3
ADJACENT TECHNOLOGIES


6.3.1
IN-SPACE MANUFACTURING


6.3.2
SPACE DEPOTS


6.4
TECHNOLOGY ROADMAP


6.5
PATENT ANALYSIS


6.6
FUTURE APPLICATIONS


6.7
IMPACT OF AI/ GENERATIVE AI ON SPACE-BASED DATA CENTER MARKET


6.7.1
TOP USE CASES AND MARKET POTENTIAL


6.8
SUCCESS STORIES AND REAL-WORLD APPLICATIONS


6.8.1
LONESTAR DATA HOLDINGS-INDEPENDENCE & FREEDOM LUNAR DATA CENTERS


6.8.2
STARCLOUD-1: IN-ORBIT AI COMPUTING


6.8.3
HPE-SPACEBORNE COMPUTER-2


7
SUSTAINABILITY & REGULATORY LANDSCAPE
Navigate complex regulations and drive eco-innovation in space-based data centers globally.


96
 
7.1
REGIONAL REGULATIONS AND COMPLIANCE


7.1.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


7.1.2
KEY REGULATIONS


7.1.3
INDUSTRY STANDARDS


7.2
SUSTAINABILITY INITIATIVES


7.2.1
CARBON IMPACT AND ECO-APPLICATIONS OF SPACE-BASED DATA CENTERS


8
CUSTOMER LANDSCAPE & BUYER BEHAVIOR
Understand stakeholder influence and unmet needs to optimize buyer engagement strategies.


104
 
8.1
DECISION MAKING PROCESS


8.2
BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA


8.2.1
KEY STAKEHOLDERS IN BUYING PROCESS


8.2.2
BUYING EVALUATION CRITERIA


8.3
ADOPTION BARRIERS & INTERNAL CHALLENGES


8.4
UNMET NEEDS OF VARIOUS END-USE INDUSTRIES


9
SPACE-BASED DATA CENTER MARKET, BY APPLICATION
Market Size & Growth Rate Forecast Analysis to 2040 in USD Million | 4 Data Tables


110
 
9.1
INTRODUCTION


9.2
AI & MACHINE LEARNING COMPUTING


9.2.1
GROWING NEED TO PROCESS SATELLITE DATA WITH ONBOARD GPUS AND AI ACCELERATORS TO DRIVE MARKET


9.3
CLOUD & GENERAL-PURPOSE COMPUTING


9.3.1
EXPANSION OF CLOUD-NATIVE WORKLOADS AND SHARED COMPUTING INFRASTRUCTURE IN ORBIT TO DRIVE MARKET


9.4
DATA PROCESSING & ANALYTICS


9.4.1
RISING SATELLITE DATA VOLUMES AND LIMITED DOWNLINK CAPACITY INCREASE IN-ORBIT PROCESSING AND ANALYTICS DEMAND


9.5
DATA STORAGE, BACKUP & ARCHIVAL


9.5.1
GROWING NEED FOR RESILIENT DATA COPIES, ORBITAL BUFFERING, AND STORAGE SEPARATED FROM TERRESTRIAL INFRASTRUCTURE TO DRIVE MARKET


10
SPACE-BASED DATA CENTER MARKET, BY COMMUNICATION INFRASTRUCTURE
Market Size & Growth Rate Forecast Analysis to 2040 in USD Million | 12 Data Tables


116
 
10.1
INTRODUCTION


10.2
SOLUTION


10.2.1
NEED FOR INTEGRATED SPACE-TO-SPACE AND SPACE-TO-GROUND CONNECTIVITY TO DRIVE MARKET


10.2.2
SPACE-TO-SPACE


10.2.3
SPACE-TO-GROUND


10.3
TECHNOLOGY (PAYLOAD)/HARDWARE


10.3.1
INCREASING NEED FOR HIGH-CAPACITY AND RELIABLE OPTICAL COMMUNICATION HARDWARE TO DRIVE MARKET


10.3.2
OPTICAL HEAD


10.3.3
OPTICAL TRANSMITTER & RECEIVER


10.3.4
MODEM & SIGNAL PROCESSING UNIT


10.3.5
POINTING, ACQUISITION & TRACKING (PAT) SYSTEM


11
SPACE-BASED DATA CENTER MARKET, BY END USER
Market Size & Growth Rate Forecast Analysis to 2040 in USD Million | 4 Data Tables


124
 
11.1
INTRODUCTION


11.2
COMMERCIAL


11.2.1
GROWING DEMAND FOR IN-ORBIT PROCESSING, STORAGE, AND DATA SERVICES FROM COMMERCIAL OPERATORS TO DRIVE MARKET


11.3
GOVERNMENT & DEFENSE


11.3.1
GROWING NEED FOR SECURE IN-ORBIT PROCESSING AND RESILIENT MISSION DATA INFRASTRUCTURE TO DRIVE MARKET


11.4
RESEARCH & ACADEMIC


11.4.1
INCREASING USE OF IN-ORBIT COMPUTING FOR SCIENTIFIC DATA PROCESSING AND EXPERIMENTATION TO DRIVE MARKET


12
SPACE-BASED DATA CENTER MARKET, BY PAYLOAD
Market Size & Growth Rate Forecast Analysis to 2040 in USD Million | 4 Data Tables


128
 
12.1
INTRODUCTION


12.2
DATA PROCESSING UNIT


12.2.1
INCREASING USE OF AI AND HIGH-PERFORMANCE EDGE COMPUTING IN ORBIT TO DRIVE MARKET


12.3
DATA STORAGE UNIT


12.3.1
GROWING NEED FOR PERSISTENT ORBITAL STORAGE AND OFF-EARTH DATA BACKUP TO DRIVE MARKET


12.4
COMMUNICATION & DATA TRANSFER UNIT


12.4.1
GROWING NEED FOR HIGH-CAPACITY SPACE-TO-SPACE AND SPACE-TO-GROUND CONNECTIVITY TO DRIVE MARKET


13
SPACE-BASED DATA CENTER MARKET, BY POWER CAPACITY
Market Size & Growth Rate Forecast Analysis to 2040 in USD Million | 4 Data Tables


132
 
13.1
INTRODUCTION


13.2
< 100 KW


13.2.1
LOWER-POWER ORBITAL COMPUTING NODES AND EARLY COMMERCIAL PAYLOADS TO DRIVE MARKET


13.3
>100 KW TO <1 MW


13.3.1
INCREASING DEPLOYMENT OF DEDICATED AI AND HIGHER-DENSITY ORBITAL COMPUTING PLATFORMS TO DRIVE SEGMENTAL GROWTH


13.4
≥1 MW


13.4.1
GROWING REQUIREMENT FOR LARGE-SCALE AI AND HIGH-PERFORMANCE COMPUTING IN ORBIT TO DRIVE MARKET


14
SPACE-BASED DATA CENTER MARKET, BY REGION
Comprehensive coverage of 4 Regions with country-level deep-dive of 7 Countries | 110 Data Tables.


136
 
14.1
INTRODUCTION


14.2
NORTH AMERICA


14.2.1
US


14.2.1.1
DEEP LAUNCH CAPACITY, DEFENSE DEMAND, AND A DOMESTIC AI-SPACE SUPPLY CHAIN TO DRIVE MARKET


14.2.2
CANADA


14.2.2.1
CONCENTRATION OF OPTICAL-RELAY EXPERTISE, PUBLIC INVESTMENT, AND ARCTIC SOVEREIGN REQUIREMENTS TO DRIVE MARKET


14.3
EUROPE


14.3.1
FRANCE


14.3.1.1
INTEGRATED SPACE MANUFACTURING, LAUNCH CAPABILITY, AND SOVEREIGN DIGITAL INFRASTRUCTURE PROGRAMS TO DRIVE MARKET


14.3.2
REST OF EUROPE


14.4
ASIA PACIFIC


14.4.1
CHINA


14.4.1.1
STATE-LED SPACE COMPUTING PROGRAMS, DOMESTIC SATELLITE PRODUCTION, AND LARGE-SCALE AI INFRASTRUCTURE PLANS TO DRIVE MARKET


14.4.2
SOUTH KOREA


14.4.2.1
GOVERNMENT-BACKED DEVELOPMENT OF SPACE-QUALIFIED AI PROCESSORS, STORAGE SYSTEMS, AND HIGH-CAPACITY LEO COMMUNICATIONS TO DRIVE MARKET


14.4.3
INDIA


14.4.3.1
PRIVATE SPACE REFORM, SOVEREIGN AI DEVELOPMENT, AND GROWING EARTH OBSERVATION DATA VOLUMES TO DRIVE MARKET


14.5
MIDDLE EAST


14.5.1
UAE


14.5.1.1
SOVEREIGN-DATA REQUIREMENTS, ABU DHABI’S ORBITAL-COMPUTE DEVELOPMENT, AND LOCAL SPACE AND AI INFRASTRUCTURE TO DRIVE MARKET


14.5.2
ISRAEL


14.5.2.1
STRENGTH IN RADIATION-TOLERANT COMPUTING, SPACE PROCESSORS, AND DIGITAL PAYLOADS TO DRIVE MARKET


15
COMPETITIVE LANDSCAPE
Discover dominant players and emerging leaders shaping future market dynamics and competitive strategies.


173
 
15.1
INTRODUCTION


15.2
KEY PLAYER STRATEGIES/RIGHT TO WIN, 2021–2026


15.3
MARKET SHARE ANALYSIS, 2025


15.4
BRAND/PRODUCT COMPARISON


15.5
COMPANY VALUATION AND FINANCIAL METRICS


15.6
COMPANY EVALUATION MATRIX: SOLUTION PROVIDERS, 2025


15.6.1
STARS


15.6.2
EMERGING LEADERS


15.6.3
PERVASIVE PLAYERS


15.6.4
PARTICIPANTS


15.6.5
COMPANY FOOTPRINT


15.6.5.1
REGION FOOTPRINT


15.6.5.2
PAYLOAD FOOTPRINT


15.6.5.3
END USER FOOTPRINT


15.6.5.4
APPLICATION FOOTPRINT


15.7
COMPANY EVALUATION MATRIX: KEY ENABLERS, 2025


15.7.1
STARS


15.7.2
EMERGING LEADERS


15.7.3
PERVASIVE PLAYERS


15.7.4
PARTICIPANTS


15.7.5
COMPANY FOOTPRINT


15.7.5.1
REGION FOOTPRINT


15.7.5.2
PAYLOAD FOOTPRINT


15.7.5.3
END USER FOOTPRINT


15.7.5.4
APPLICATION FOOTPRINT


15.8
COMPETITIVE SCENARIO


15.8.1
PRODUCT LAUNCHES


15.8.2
DEALS


15.8.3
OTHER DEVELOPMENTS


16
COMPANY PROFILES
In-depth Company Profiles of Leading Market Players with detailed Business Overview, Product and Service Portfolio, Recent Developments, and Unique Analyst Perspective (MnM View)


208
 
16.1
KEY PLAYERS (SOLUTION PROVIDERS)


16.1.1
STARCLOUD, INC.


16.1.1.1
BUSINESS OVERVIEW


16.1.1.2
PRODUCTS OFFERED


16.1.1.3
RECENT DEVELOPMENTS


16.1.1.3.1
PRODUCT LAUNCHES/DEVELOPMENTS


16.1.1.3.2
DEALS


16.1.1.3.3
OTHER DEVELOPMENTS


16.1.1.4
MNM VIEW


16.1.1.4.1
RIGHT TO WIN


16.1.1.4.2
STRATEGIC CHOICES


16.1.1.4.3
WEAKNESSES AND COMPETITIVE THREATS


16.1.2
AXIOM SPACE, INC.


16.1.3
KEPLER COMMUNICATIONS INC.


16.1.4
SPACEX


16.1.5
COWBOY SPACE CORPORATION


16.1.6
LONESTAR DATA HOLDINGS INC.


16.1.7
RED HAT, INC.


16.1.8
ROTONIUM S.R.L.


16.1.9
ORBITSEDGE, INC.


16.1.10
SPACE COMPASS CORPORATION


16.1.11
CLOUD CONSTELLATION CORPORATION


16.1.12
THALES ALENIA SPACE


16.1.13
VOYAGER TECHNOLOGIES, INC.


16.1.14
MADARI SPACE


16.2
KEY PLAYERS (KEY ENABLERS)


16.2.1
HEWLETT PACKARD ENTERPRISE DEVELOPMENT LP


16.2.2
NVIDIA CORPORATION


16.2.3
INTERNATIONAL BUSINESS MACHINES CORPORATION


16.2.4
MICROSOFT


16.2.5
AMAZON WEB SERVICES, INC.


16.2.6
INTEL CORPORATION


16.2.7
KIOXIA EUROPE GMBH


16.2.8
CEREBRAS


16.2.9
SPACE FORGE


16.2.10
BLUE ORIGIN


16.2.11
SOPHIA SPACE INC.


17
RESEARCH METHODOLOGY


290
 
17.1
RESEARCH DATA


17.1.1
SECONDARY DATA


17.1.1.1
KEY DATA FROM SECONDARY SOURCES


17.1.2
PRIMARY DATA


17.1.2.1
PRIMARY SOURCES


17.1.2.2
KEY DATA FROM PRIMARY SOURCES


17.1.3
BREAKDOWN OF PRIMARY INTERVIEWS


17.2
FACTOR ANALYSIS


17.2.1
INTRODUCTION


17.2.2
DEMAND-SIDE INDICATORS


17.2.3
SUPPLY-SIDE INDICATORS


17.3
MARKET SIZE ESTIMATION


17.3.1
BOTTOM-UP APPROACH


17.3.1.1
MARKET SIZE ESTIMATION METHODOLOGY (DEMAND SIDE)


17.3.2
TOP-DOWN APPROACH


17.4
DATA TRIANGULATION


17.5
RESEARCH ASSUMPTIONS


17.6
RESEARCH LIMITATIONS


17.7
RISK ASSESSMENT


18
APPENDIX


300
 
18.1
DISCUSSION GUIDE


18.2
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL


18.3
CUSTOMIZATION OPTIONS


18.4
RELATED REPORTS


18.5
AUTHOR DETAILS


LIST OF TABLES


TABLE 1
SPACE-BASED DATA CENTER MARKET: INCLUSIONS AND EXCLUSIONS


TABLE 2
USD EXCHANGE RATES, 2021–2025


TABLE 3
UNMET NEEDS AND WHITE SPACES


TABLE 4
CROSS-SECTOR OPPORTUNITIES


TABLE 5
STRATEGIC MOVES BY TIER 1/2/3 PLAYERS


TABLE 6
ROLE OF COMPANIES IN ECOSYSTEM


TABLE 7
INDICATIVE PRICING, BY POWER CAPACITY, 2025 (USD/KW)


TABLE 8
AVERAGE SELLING PRICE TREND, BY REGION, 2021–2025 (USD MILLION)


TABLE 9
IMPORT DATA FOR HS CODE 880260-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025 (USD THOUSAND)


TABLE 10
EXPORT DATA FOR HS CODE 880260-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025 (USD THOUSAND)


TABLE 11
KEY CONFERENCES AND EVENTS, 2026-2027


TABLE 12
GDP PERCENTAGE CHANGE, BY COUNTRY, 2021–2030


TABLE 13
ADVANTAGES AND DISADVANTAGES OF BUSINESS MODELS


TABLE 14
BILL OF MATERIALS


TABLE 15
TOTAL COST OF OWNERSHIP OF SPACE-BASED DATA CENTER SYSTEMS


TABLE 16
VOLUME DATA OF SPACE-BASED DATA CENTER, 2021-2030


TABLE 17
VOLUME DATA OF SPACE-BASED DATA CENTER, 2031-2040


TABLE 18
EVOLUTION OF SPACE-BASED DATA CENTER TECHNOLOGIES


TABLE 19
PATENT ANALYSIS, 2021-2026


TABLE 20
IN-ORBIT AI AND DATA PROCESSING: FUTURE OF SPACE-BASED DATA PROCESSING


TABLE 21
SOVEREIGN STORAGE AND DISASTER RECOVERY: FUTURE OF OFF-EARTH DATA BACKUP


TABLE 22
TOP USE CASES AND MARKET POTENTIAL


TABLE 23
NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 24
EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 25
ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 26
MIDDLE EAST : REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 27
KEY REGULATIONS IN SPACE-BASED DATA CENTER MARKET, BY COUNTRY/REGION


TABLE 28
GLOBAL INDUSTRY STANDARDS IN SPACE-BASED DATA CENTER MARKET


TABLE 29
SUSTAINABILITIES INITIATIVES IN SPACE-BASED DATA CENTER MARKET


TABLE 30
CERTIFICATIONS, LABELING, AND ECO-STANDARDS


TABLE 31
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY PAYLOAD


TABLE 32
KEY BUYING EVALUATION CRITERIA, BY PAYLOAD


TABLE 33
UNMET NEEDS IN SPACE-BASED DATA CENTER MARKET, BY END USER


TABLE 34
SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 35
SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2026–2030 (USD MILLION)


TABLE 36
SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2031–2035 (USD MILLION)


TABLE 37
SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2036–2040 (USD MILLION)


TABLE 38
SPACE-BASED DATA CENTER MARKET, BY COMMUNICATION INFRASTRUCTURE, 2021–2025 (USD MILLION)


TABLE 39
SPACE-BASED DATA CENTER MARKET, BY COMMUNICATION INFRASTRUCTURE, 2026–2030 (USD MILLION)


TABLE 40
SPACE-BASED DATA CENTER MARKET, BY COMMUNICATION INFRASTRUCTURE, 2031–2035 (USD MILLION)


TABLE 41
SPACE-BASED DATA CENTER MARKET, BY COMMUNICATION INFRASTRUCTURE, 2036–2040 (USD MILLION)


TABLE 42
SPACE-BASED DATA CENTER MARKET, BY SOLUTION, 2021–2025 (USD MILLION)


TABLE 43
SPACE-BASED DATA CENTER MARKET, BY SOLUTION, 2026–2030 (USD MILLION)


TABLE 44
SPACE-BASED DATA CENTER MARKET, BY SOLUTION, 2031–2035 (USD MILLION)


TABLE 45
SPACE-BASED DATA CENTER MARKET, BY SOLUTION, 2036–2040 (USD MILLION)


TABLE 46
SPACE-BASED DATA CENTER MARKET, BY TECHNOLOGY (PAYLOAD)/HARDWARE, 2021–2025 (USD MILLION)


TABLE 47
SPACE-BASED DATA CENTER MARKET, BY TECHNOLOGY (PAYLOAD)/HARDWARE, 2026–2030 (USD MILLION)


TABLE 48
SPACE-BASED DATA CENTER MARKET, BY TECHNOLOGY (PAYLOAD)/HARDWARE, 2031–2035 (USD MILLION)


TABLE 49
SPACE-BASED DATA CENTER MARKET, BY TECHNOLOGY (PAYLOAD)/HARDWARE, 2036–2040 (USD MILLION)


TABLE 50
SPACE-BASED DATA CENTER MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 51
SPACE-BASED DATA CENTER MARKET, BY END USER, 2026–2030 (USD MILLION)


TABLE 52
SPACE-BASED DATA CENTER MARKET, BY END USER, 2031–2035 (USD MILLION)


TABLE 53
SPACE-BASED DATA CENTER MARKET, BY END USER, 2036–2040 (USD MILLION)


TABLE 54
SPACE-BASED DATA CENTER MARKET, BY PAYLOAD, 2021–2025 (USD MILLION)


TABLE 55
SPACE-BASED DATA CENTER MARKET, BY PAYLOAD, 2026–2030 (USD MILLION)


TABLE 56
SPACE-BASED DATA CENTER MARKET, BY PAYLOAD, 2031–2035 (USD MILLION)


TABLE 57
SPACE-BASED DATA CENTER MARKET, BY PAYLOAD, 2036–2040 (USD MILLION)


TABLE 58
SPACE-BASED DATA CENTER MARKET, BY POWER CAPACITY, 2021–2025 (USD MILLION)


TABLE 59
SPACE-BASED DATA CENTER MARKET, BY POWER CAPACITY, 2026–2030 (USD MILLION)


TABLE 60
SPACE-BASED DATA CENTER MARKET, BY POWER CAPACITY, 2031–2035 (USD MILLION)


TABLE 61
SPACE-BASED DATA CENTER MARKET, BY POWER CAPACITY, 2036–2040 (USD MILLION)


TABLE 62
SPACE-BASED DATA CENTER MARKET, BY REGION, 2021–2025 (USD MILLION)


TABLE 63
SPACE-BASED DATA CENTER MARKET, BY REGION, 2026–2030 (USD MILLION)


TABLE 64
SPACE-BASED DATA CENTER MARKET, BY REGION, 2031–2035 (USD MILLION)


TABLE 65
SPACE-BASED DATA CENTER MARKET, BY REGION, 2036–2040 (USD MILLION)


TABLE 66
NORTH AMERICA: SPACE-BASED DATA CENTER MARKET, BY COUNTRY, 2021–2025 (USD MILLION)


TABLE 67
NORTH AMERICA: SPACE-BASED DATA CENTER MARKET, BY COUNTRY, 2026–2030 (USD MILLION)


TABLE 68
NORTH AMERICA: SPACE-BASED DATA CENTER MARKET, BY COUNTRY, 2031–2035 (USD MILLION)


TABLE 69
NORTH AMERICA: SPACE-BASED DATA CENTER MARKET, BY COUNTRY, 2036–2040 (USD MILLION)


TABLE 70
NORTH AMERICA: SPACE-BASED DATA CENTER MARKET, BY PAYLOAD, 2021–2025 (USD MILLION)


TABLE 71
NORTH AMERICA: SPACE-BASED DATA CENTER MARKET, BY PAYLOAD, 2026–2030 (USD MILLION)


TABLE 72
NORTH AMERICA: SPACE-BASED DATA CENTER MARKET, BY PAYLOAD, 2031–2035 (USD MILLION)


TABLE 73
NORTH AMERICA: SPACE-BASED DATA CENTER MARKET, BY PAYLOAD, 2036–2040 (USD MILLION)


TABLE 74
NORTH AMERICA: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 75
NORTH AMERICA: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2026–2030 (USD MILLION)


TABLE 76
NORTH AMERICA: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2031–2035 (USD MILLION)


TABLE 77
NORTH AMERICA: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2036–2040 (USD MILLION)


TABLE 78
NORTH AMERICA: SPACE-BASED DATA CENTER MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 79
NORTH AMERICA: SPACE-BASED DATA CENTER MARKET, BY END USER, 2026–2030 (USD MILLION)


TABLE 80
NORTH AMERICA: SPACE-BASED DATA CENTER MARKET, BY END USER, 2031–2035 (USD MILLION)


TABLE 81
NORTH AMERICA: SPACE-BASED DATA CENTER MARKET, BY END USER, 2036–2040 (USD MILLION)


TABLE 82
US: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 83
US: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2026–2030 (USD MILLION)


TABLE 84
US: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2031–2035 (USD MILLION)


TABLE 85
US: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2036–2040 (USD MILLION)


TABLE 86
US: SPACE-BASED DATA CENTER MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 87
US: SPACE-BASED DATA CENTER MARKET, BY END USER, 2026–2030 (USD MILLION)


TABLE 88
US: SPACE-BASED DATA CENTER MARKET, BY END USER, 2031–2035 (USD MILLION)


TABLE 89
US: SPACE-BASED DATA CENTER MARKET, BY END USER, 2036–2040 (USD MILLION)


TABLE 90
CANADA: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 91
CANADA: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2026–2030 (USD MILLION)


TABLE 92
CANADA: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2031–2035 (USD MILLION)


TABLE 93
CANADA: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2036–2040 (USD MILLION)


TABLE 94
CANADA: SPACE-BASED DATA CENTER MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 95
CANADA: SPACE-BASED DATA CENTER MARKET, BY END USER, 2026–2030 (USD MILLION)


TABLE 96
CANADA: SPACE-BASED DATA CENTER MARKET, BY END USER, 2031–2035 (USD MILLION)


TABLE 97
CANADA: SPACE-BASED DATA CENTER MARKET, BY END USER, 2036–2040 (USD MILLION)


TABLE 98
EUROPE: SPACE-BASED DATA CENTER MARKET, BY COUNTRY, 2021–2025 (USD MILLION)


TABLE 99
EUROPE: SPACE-BASED DATA CENTER MARKET, BY COUNTRY, 2026–2030 (USD MILLION)


TABLE 100
EUROPE: SPACE-BASED DATA CENTER MARKET, BY COUNTRY, 2036–2040 (USD MILLION)


TABLE 101
EUROPE: SPACE-BASED DATA CENTER MARKET, BY PAYLOAD, 2021–2025 (USD MILLION)


TABLE 102
EUROPE: SPACE-BASED DATA CENTER MARKET, BY PAYLOAD, 2026–2030 (USD MILLION)


TABLE 103
EUROPE: SPACE-BASED DATA CENTER MARKET, BY PAYLOAD, 2036–2040 (USD MILLION)


TABLE 104
EUROPE: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 105
EUROPE: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2026–2030 (USD MILLION)


TABLE 106
EUROPE: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2036–2040 (USD MILLION)


TABLE 107
EUROPE: SPACE-BASED DATA CENTER MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 108
EUROPE: SPACE-BASED DATA CENTER MARKET, BY END USER, 2026–2030 (USD MILLION)


TABLE 109
EUROPE: SPACE-BASED DATA CENTER MARKET, BY END USER, 2036–2040 (USD MILLION)


TABLE 110
FRANCE: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2036–2040 (USD MILLION)


TABLE 111
FRANCE: SPACE-BASED DATA CENTER MARKET, BY END USER, 2036–2040 (USD MILLION)


TABLE 112
REST OF EUROPE: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 113
REST OF EUROPE: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2026–2030 (USD MILLION)


TABLE 114
REST OF EUROPE: SPACE-BASED DATA CENTER MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 115
REST OF EUROPE: SPACE-BASED DATA CENTER MARKET, BY END USER, 2026–2030 (USD MILLION)


TABLE 116
ASIA PACIFIC: SPACE-BASED DATA CENTER MARKET, BY COUNTRY, 2021–2025 (USD MILLION)


TABLE 117
ASIA PACIFIC: SPACE-BASED DATA CENTER MARKET, BY COUNTRY, 2026–2030 (USD MILLION)


TABLE 118
ASIA PACIFIC: SPACE-BASED DATA CENTER MARKET, BY COUNTRY, 2031–2035 (USD MILLION)


TABLE 119
ASIA PACIFIC: SPACE-BASED DATA CENTER MARKET, BY COUNTRY, 2036–2040 (USD MILLION)


TABLE 120
ASIA PACIFIC: SPACE-BASED DATA CENTER MARKET, BY PAYLOAD, 2021–2025 (USD MILLION)


TABLE 121
ASIA PACIFIC: SPACE-BASED DATA CENTER MARKET, BY PAYLOAD, 2026–2030 (USD MILLION)


TABLE 122
ASIA PACIFIC: SPACE-BASED DATA CENTER MARKET, BY PAYLOAD, 2031–2035 (USD MILLION)


TABLE 123
ASIA PACIFIC: SPACE-BASED DATA CENTER MARKET, BY PAYLOAD, 2036–2040 (USD MILLION)


TABLE 124
ASIA PACIFIC: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 125
ASIA PACIFIC: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2026–2030 (USD MILLION)


TABLE 126
ASIA PACIFIC: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2031–2035 (USD MILLION)


TABLE 127
ASIA PACIFIC: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2036–2040 (USD MILLION)


TABLE 128
ASIA PACIFIC: SPACE-BASED DATA CENTER MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 129
ASIA PACIFIC: SPACE-BASED DATA CENTER MARKET, BY END USER, 2026–2030 (USD MILLION)


TABLE 130
ASIA PACIFIC: SPACE-BASED DATA CENTER MARKET, BY END USER, 2031–2035 (USD MILLION)


TABLE 131
ASIA PACIFIC: SPACE-BASED DATA CENTER MARKET, BY END USER, 2036–2040 (USD MILLION)


TABLE 132
CHINA: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 133
CHINA: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2026–2030 (USD MILLION)


TABLE 134
CHINA: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2031–2035 (USD MILLION)


TABLE 135
CHINA: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2036–2040 (USD MILLION)


TABLE 136
CHINA: SPACE-BASED DATA CENTER MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 137
CHINA: SPACE-BASED DATA CENTER MARKET, BY END USER, 2026–2030 (USD MILLION)


TABLE 138
CHINA: SPACE-BASED DATA CENTER MARKET, BY END USER, 2031–2035 (USD MILLION)


TABLE 139
CHINA: SPACE-BASED DATA CENTER MARKET, BY END USER, 2036–2040 (USD MILLION)


TABLE 140
SOUTH KOREA: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2031–2035 (USD MILLION)


TABLE 141
SOUTH KOREA: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2036–2040 (USD MILLION)


TABLE 142
SOUTH KOREA: SPACE-BASED DATA CENTER MARKET, BY END USER, 2031–2035 (USD MILLION)


TABLE 143
SOUTH KOREA: SPACE-BASED DATA CENTER MARKET, BY END USER, 2036–2040 (USD MILLION)


TABLE 144
INDIA: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 145
INDIA: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2026–2030 (USD MILLION)


TABLE 146
INDIA: SPACE-BASED DATA CENTER MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 147
INDIA: SPACE-BASED DATA CENTER MARKET, BY END USER, 2026–2030 (USD MILLION)


TABLE 148
MIDDLE EAST: SPACE-BASED DATA CENTER MARKET, BY COUNTRY, 2026–2030 (USD MILLION)


TABLE 149
MIDDLE EAST: SPACE-BASED DATA CENTER MARKET, BY COUNTRY, 2031–2035 (USD MILLION)


TABLE 150
MIDDLE EAST: SPACE-BASED DATA CENTER MARKET, BY COUNTRY, 2036–2040 (USD MILLION)


TABLE 151
MIDDLE EAST: SPACE-BASED DATA CENTER MARKET, BY PAYLOAD, 2026–2030 (USD MILLION)


TABLE 152
MIDDLE EAST: SPACE-BASED DATA CENTER MARKET, BY PAYLOAD, 2031–2035 (USD MILLION)


TABLE 153
MIDDLE EAST: SPACE-BASED DATA CENTER MARKET, BY PAYLOAD, 2036–2040 (USD MILLION)


TABLE 154
MIDDLE EAST: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2026–2030 (USD MILLION)


TABLE 155
MIDDLE EAST: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2031–2035 (USD MILLION)


TABLE 156
MIDDLE EAST: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2036–2040 (USD MILLION)


TABLE 157
MIDDLE EAST: SPACE-BASED DATA CENTER MARKET, BY END USER, 2026–2030 (USD MILLION)


TABLE 158
MIDDLE EAST: SPACE-BASED DATA CENTER MARKET, BY END USER, 2031–2035 (USD MILLION)


TABLE 159
MIDDLE EAST: SPACE-BASED DATA CENTER MARKET, BY END USER, 2036–2040 (USD MILLION)


TABLE 160
UAE: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2026–2030 (USD MILLION)


TABLE 161
UAE: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2031–2035 (USD MILLION)


TABLE 162
UAE: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2036–2040 (USD MILLION)


TABLE 163
UAE: SPACE-BASED DATA CENTER MARKET, BY END USER, 2026–2030 (USD MILLION)


TABLE 164
UAE: SPACE-BASED DATA CENTER MARKET, BY END USER, 2031–2035 (USD MILLION)


TABLE 165
UAE: SPACE-BASED DATA CENTER MARKET, BY END USER, 2036–2040 (USD MILLION)


TABLE 166
ISRAEL: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2026–2030 (USD MILLION)


TABLE 167
ISRAEL: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2031–2035 (USD MILLION)


TABLE 168
ISRAEL: SPACE-BASED DATA CENTER MARKET, BY APPLICATION, 2036–2040 (USD MILLION)


TABLE 169
ISRAEL: SPACE-BASED DATA CENTER MARKET, BY END USER, 2026–2030 (USD MILLION)


TABLE 170
ISRAEL: SPACE-BASED DATA CENTER MARKET, BY END USER, 2031–2035 (USD MILLION)


TABLE 171
ISRAEL: SPACE-BASED DATA CENTER MARKET, BY END USER, 2036–2040 (USD MILLION)


TABLE 172
KEY PLAYER STRATEGIES/RIGHT TO WIN, 2021–2026


TABLE 173
SPACE-BASED DATA CENTER MARKET: DEGREE OF COMPETITION


TABLE 174
REGION FOOTPRINT (SOLUTION PROVIDERS)


TABLE 175
PAYLOAD FOOTPRINT (SOLUTION PROVIDERS)


TABLE 176
END USER FOOTPRINT (SOLUTION PROVIDERS)


TABLE 177
APPLICATION FOOTPRINT (SOLUTION PROVIDERS)


TABLE 178
REGION FOOTPRINT (KEY ENABLERS)


TABLE 179
PAYLOAD FOOTPRINT (KEY ENABLERS)


TABLE 180
END USER FOOTPRINT (KEY ENABLERS)


TABLE 181
APPLICATION FOOTPRINT (KEY ENABLERS)


TABLE 182
SPACE-BASED DATA CENTER MARKET: PRODUCT LAUNCHES/DEVELOPMENTS, JANUARY 2021–AUGUST 2026


TABLE 183
SPACE-BASED DATA CENTER MARKET: DEALS, JANUARY 2021–AUGUST 2026


TABLE 184
SPACE-BASED DATA CENTER MARKET: OTHER DEVELOPMENTS, JANUARY 2021–AUGUST 2026


TABLE 185
STARCLOUD, INC.: COMPANY OVERVIEW


TABLE 186
STARCLOUD, INC.: PRODUCTS OFFERED


TABLE 187
STARCLOUD, INC.: PRODUCT LAUNCHES/DEVELOPMENTS


TABLE 188
STARCLOUD, INC.: DEALS


TABLE 189
STARCLOUD, INC.: OTHER DEVELOPMENTS


TABLE 190
AXIOM SPACE, INC.: COMPANY OVERVIEW


TABLE 191
AXIOM SPACE, INC.: PRODUCTS OFFERED


TABLE 192
AXIOM SPACE, INC.: PRODUCT LAUNCHES/DEVELOPMENTS


TABLE 193
AXIOM SPACE, INC.: DEALS


TABLE 194
KEPLER COMMUNICATIONS INC.: COMPANY OVERVIEW


TABLE 195
KEPLER COMMUNICATIONS INC.: PRODUCTS OFFERED


TABLE 196
KEPLER COMMUNICATIONS INC.: PRODUCT LAUNCHES/DEVELOPMENTS


TABLE 197
KEPLER COMMUNICATIONS INC.: DEALS


TABLE 198
KEPLER COMMUNICATIONS INC.: OTHER DEVELOPMENTS


TABLE 199
SPACEX: COMPANY OVERVIEW


TABLE 200
SPACEX: PRODUCTS OFFERED


TABLE 201
SPACEX: DEALS


TABLE 202
COWBOY SPACE CORPORATION: COMPANY OVERVIEW


TABLE 203
COWBOY SPACE CORPORATION: PRODUCTS OFFERED


TABLE 204
COWBOY SPACE CORPORATION: PRODUCT LAUNCHES/DEVELOPMENTS


TABLE 205
COWBOY SPACE CORPORATION: DEALS


TABLE 206
COWBOY SPACE CORPORATION: OTHER DEVELOPMENTS


TABLE 207
LONESTAR DATA HOLDINGS INC.: COMPANY OVERVIEW


TABLE 208
LONESTAR DATA HOLDINGS INC.: PRODUCTS OFFERED


TABLE 209
LONESTAR DATA HOLDINGS INC.: PRODUCT LAUNCHES/DEVELOPMENTS


TABLE 210
LONESTAR DATA HOLDINGS INC.: DEALS


TABLE 211
LONESTAR DATA HOLDINGS INC.: OTHER DEVELOPMENTS


TABLE 212
RED HAT, INC.: COMPANY OVERVIEW


TABLE 213
RED HAT, INC.: PRODUCTS OFFERED


TABLE 214
RED HAT, INC.: PRODUCT ENHANCEMENTS


TABLE 215
RED HAT, INC.: DEALS


TABLE 216
RED HAT, INC.: OTHER DEVELOPMENTS


TABLE 217
ROTONIUM S.R.L.: COMPANY OVERVIEW


TABLE 218
ROTONIUM S.R.L.: PRODUCTS OFFERED


TABLE 219
ROTONIUM S.R.L.: PRODUCT LAUNCHES/DEVELOPMENTS


TABLE 220
ROTONIUM S.R.L.: OTHER DEVELOPMENTS


TABLE 221
ORBITSEDGE, INC.: COMPANY OVERVIEW


TABLE 222
ORBITSEDGE, INC.: PRODUCTS OFFERED


TABLE 223
ORBITSEDGE, INC.: PRODUCT LAUNCHES/DEVELOPMENTS


TABLE 224
ORBITSEDGE, INC.: DEALS


TABLE 225
ORBITSEDGE, INC.: OTHER DEVELOPMENTS


TABLE 226
SPACE COMPASS CORPORATION: COMPANY OVERVIEW


TABLE 227
SPACE COMPASS CORPORATION: PRODUCTS OFFERED


TABLE 228
SPACE COMPASS CORPORATION: PRODUCT LAUNCHES/DEVELOPMENTS


TABLE 229
SPACE COMPASS CORPORATION: DEALS


TABLE 230
SPACE COMPASS CORPORATION: OTHER DEVELOPMENTS


TABLE 231
CLOUD CONSTELLATION CORPORATION: COMPANY OVERVIEW


TABLE 232
CLOUD CONSTELLATION CORPORATION: PRODUCTS OFFERED


TABLE 233
CLOUD CONSTELLATION CORPORATION: DEALS


TABLE 234
CLOUD CONSTELLATION CORPORATION: OTHER DEVELOPMENTS


TABLE 235
THALES ALENIA SPACE: COMPANY OVERVIEW


TABLE 236
THALES ALENIA SPACE: PRODUCTS OFFERED


TABLE 237
THALES ALENIA SPACE: PRODUCT LAUNCHES/DEVELOPMENTS


TABLE 238
THALES ALENIA SPACE: DEALS


TABLE 239
THALES ALENIA SPACE: OTHER DEVELOPMENTS


TABLE 240
VOYAGER TECHNOLOGIES, INC.: COMPANY OVERVIEW


TABLE 241
VOYAGER TECHNOLOGIES, INC.: PRODUCTS OFFERED


TABLE 242
VOYAGER TECHNOLOGIES, INC.: PRODUCT LAUNCHES/DEVELOPMENTS


TABLE 243
VOYAGER TECHNOLOGIES, INC.: DEALS


TABLE 244
VOYAGER TECHNOLOGIES, INC.: OTHER DEVELOPMENTS


TABLE 245
MADARI SPACE: COMPANY OVERVIEW


TABLE 246
MADARI SPACE: PRODUCTS OFFERED


TABLE 247
MADARI SPACE: DEALS


TABLE 248
MADARI SPACE: OTHER DEVELOPMENTS


TABLE 249
HEWLETT PACKARD ENTERPRISE DEVELOPMENT LP: COMPANY OVERVIEW


TABLE 250
HEWLETT PACKARD ENTERPRISE DEVELOPMENT LP: PRODUCTS OFFERED


TABLE 251
HEWLETT PACKARD ENTERPRISE DEVELOPMENT LP: PRODUCT LAUNCHES/DEVELOPMENTS


TABLE 252
HEWLETT PACKARD ENTERPRISE DEVELOPMENT LP: DEALS


TABLE 253
HEWLETT PACKARD ENTERPRISE DEVELOPMENT LP: OTHER DEVELOPMENTS


TABLE 254
NVIDIA CORPORATION: COMPANY OVERVIEW


TABLE 255
NVIDIA CORPORATION: PRODUCTS OFFERED


TABLE 256
NVIDIA CORPORATION: PRODUCT LAUNCHES/DEVELOPMENTS


TABLE 257
NVIDIA CORPORATION: OTHER DEVELOPMENTS


TABLE 258
INTERNATIONAL BUSINESS MACHINES CORPORATION: COMPANY OVERVIEW


TABLE 259
INTERNATIONAL BUSINESS MACHINES CORPORATION: PRODUCTS OFFERED


TABLE 260
INTERNATIONAL BUSINESS MACHINES CORPORATION: PRODUCT LAUNCHES/DEVELOPMENTS


TABLE 261
INTERNATIONAL BUSINESS MACHINES CORPORATION: DEALS


TABLE 262
INTERNATIONAL BUSINESS MACHINES CORPORATION: OTHER DEVELOPMENTS


TABLE 263
MICROSOFT: COMPANY OVERVIEW


TABLE 264
MICROSOFT: PRODUCTS OFFERED


TABLE 265
MICROSOFT: PRODUCT LAUNCHES/DEVELOPMENTS


TABLE 266
MICROSOFT: DEALS


TABLE 267
MICROSOFT: OTHER DEVELOPMENTS


TABLE 268
AMAZON WEB SERVICES, INC.: COMPANY OVERVIEW


TABLE 269
AMAZON WEB SERVICES, INC.: PRODUCTS OFFERED


TABLE 270
AMAZON WEB SERVICES, INC.: DEALS


TABLE 271
AMAZON WEB SERVICES, INC.: OTHER DEVELOPMENTS


TABLE 272
INTEL CORPORATION: COMPANY OVERVIEW


TABLE 273
INTEL CORPORATION: PRODUCTS OFFERED


TABLE 274
INTEL CORPORATION: PRODUCT LAUNCHES/DEVELOPMENTS


TABLE 275
INTEL CORPORATION: DEALS


TABLE 276
INTEL CORPORATION: OTHER DEVELOPMENTS


TABLE 277
KIOXIA EUROPE GMBH: COMPANY OVERVIEW


TABLE 278
KIOXIA EUROPE GMBH: PRODUCTS OFFERED


TABLE 279
KIOXIA EUROPE GMBH: DEALS


TABLE 280
KIOXIA EUROPE GMBH: OTHER DEVELOPMENTS


TABLE 281
CEREBRAS: COMPANY OVERVIEW


TABLE 282
CEREBRAS: PRODUCTS OFFERED


TABLE 283
CEREBRAS: PRODUCT LAUNCHES/DEVELOPMENTS


TABLE 284
SPACE FORGE: COMPANY OVERVIEW


TABLE 285
SPACE FORGE: PRODUCTS OFFERED


TABLE 286
SPACE FORGE: DEALS


TABLE 287
SPACE FORGE: OTHER DEVELOPMENTS


TABLE 288
BLUE ORIGIN: COMPANY OVERVIEW


TABLE 289
BLUE ORIGIN: PRODUCTS OFFERED


TABLE 290
BLUE ORIGIN: PRODUCT LAUNCHES/DEVELOPMENTS


TABLE 291
BLUE ORIGIN: DEALS


TABLE 292
BLUE ORIGIN: OTHER DEVELOPMENTS


TABLE 293
SOPHIA SPACE INC.: COMPANY OVERVIEW


TABLE 294
SOPHIA SPACE INC.: PRODUCTS OFFERED


TABLE 295
SOPHIA SPACE INC.: PRODUCT LAUNCHES/DEVELOPMENTS


TABLE 296
SOPHIA SPACE INC.: DEALS


TABLE 297
SOPHIA SPACE INC.: OTHER DEVELOPMENTS


LIST OF FIGURES


FIGURE 1
SPACE-BASED DATA CENTER MARKET SEGMENTATION & REGIONAL SNAPSHOT


FIGURE 2
MARKET SCENARIO


FIGURE 3
SPACE-BASED DATA CENTER MARKET, 2021–2040


FIGURE 4
MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN SPACE-BASED DATA CENTER MARKET


FIGURE 5
DISRUPTIONS INFLUENCING GROWTH OF SPACE-BASED DATA CENTER MARKET


FIGURE 6
HIGH-GROWTH SEGMENTS IN SPACE-BASED DATA CENTER MARKET (2026-2040)


FIGURE 7
EUROPE TO BE FASTEST-GROWING MARKET DURING FORECAST PERIOD


FIGURE 8
RISING IN-ORBIT COMPUTING DEMAND, GROWING AI & HIGH-PERFORMANCE COMPUTING ADOPTION, AND INCREASING GOVERNMENT INVESTMENT TO DRIVE EUROPEAN SPACE-BASED DATA CENTER MARKET


FIGURE 9
DATA PROCESSING UNIT SEGMENT TO HOLD LARGEST MARKET SHARE IN 2026


FIGURE 10
AI & MACHINE LEARNING COMPUTING SEGMENT TO EXHIBIT FASTEST GROWTH DURING FORECAST PERIOD


FIGURE 11
≥1 MW SEGMENT TO GROW AT HIGHEST CAGR DURING FORECAST PERIOD


FIGURE 12
TECHNOLOGY (PAYLOAD)/HARDWARE TO BE LARGER SEGMENT THAN SOLUTION SEGMENT DURING FORECAST PERIOD


FIGURE 13
SPACE-BASED DATA CENTER MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES


FIGURE 14
ECOSYSTEM ANALYSIS


FIGURE 15
VALUE CHAIN ANALYSIS


FIGURE 16
AVERAGE SELLING PRICE TREND, BY REGION, 2021–2025 (USD MILLION)


FIGURE 17
IMPORT DATA FOR HS CODE 880260-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025 (USD THOUSAND)


FIGURE 18
EXPORT DATA FOR HS CODE 880260-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025 (USD THOUSAND)


FIGURE 19
INVESTMENT AND FUNDING SCENARIO, 2021−2026 (USD MILLION)


FIGURE 20
TRENDS AND DISRUPTIONS IMPACTING CUSTOMER BUSINESS


FIGURE 21
TECHNOLOGY ROADMAP FOR SPACE-BASED DATA CENTER MARKET


FIGURE 22
PATENT ANALYSIS, 2016-2026


FIGURE 23
FUTURE APPLICATIONS


FIGURE 24
SPACE-BASED DATA CENTER MARKET: IMPACT OF AI/GENERATIVE AI


FIGURE 25
SPACE-BASED DATA CENTER MARKET: DECISION-MAKING FACTORS


FIGURE 26
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY PAYLOAD


FIGURE 27
KEY BUYING EVALUATION CRITERIA, BY PAYLOAD


FIGURE 28
ADOPTION BARRIERS & INTERNAL CHALLENGES


FIGURE 29
DATA PROCESSING & ANALYTICS SEGMENT TO WITNESS HIGHEST CAGR DURING FORECAST PERIOD


FIGURE 30
SOLUTION SEGMENT TO WITNESS HIGHER CAGR THAN TECHNOLOGY (PAYLOAD)/ HARDWARE SEGMENT DURING FORECAST PERIOD


FIGURE 34
ASIA PACIFIC TO ACCOUNT FOR LARGEST MARKET SHARE IN 2026


FIGURE 35
NORTH AMERICA: SPACE-BASED DATA CENTER MARKET SNAPSHOT


FIGURE 36
EUROPE: SPACE-BASED DATA CENTER MARKET SNAPSHOT


FIGURE 37
ASIA PACIFIC: SPACE-BASED DATA CENTER MARKET SNAPSHOT


FIGURE 38
MIDDLE EAST: SPACE-BASED DATA CENTER MARKET SNAPSHOT


FIGURE 39
MARKET SHARE ANALYSIS OF KEY PLAYERS, 2025


FIGURE 40
BRAND/PRODUCT COMPARISON


FIGURE 41
FINANCIAL METRICS (EV/EBITDA)


FIGURE 42
COMPANY VALUATION (USD BILLION)


FIGURE 43
COMPANY EVALUATION MATRIX (SOLUTION PROVIDERS), 2025


FIGURE 44
COMPANY FOOTPRINT (SOLUTION PROVIDERS)


FIGURE 45
COMPANY EVALUATION MATRIX (KEY ENABLERS), 2025


FIGURE 46
COMPANY FOOTPRINT (KEY ENABLERS)


FIGURE 47
VOYAGER TECHNOLOGIES, INC.: COMPANY SNAPSHOT


FIGURE 48
HEWLETT PACKARD ENTERPRISE DEVELOPMENT LP: COMPANY SNAPSHOT


FIGURE 49
NVIDIA CORPORATION: COMPANY SNAPSHOT


FIGURE 50
INTERNATIONAL BUSINESS MACHINES CORPORATION: COMPANY SNAPSHOT


FIGURE 51
MICROSOFT: COMPANY SNAPSHOT


FIGURE 52
AMAZON WEB SERVICES, INC.: COMPANY SNAPSHOT


FIGURE 53
INTEL CORPORATION: COMPANY SNAPSHOT


FIGURE 54
RESEARCH DESIGN MODEL


FIGURE 55
RESEARCH DESIGN


FIGURE 56
BOTTOM-UP APPROACH


FIGURE 57
TOP-DOWN APPROACH


FIGURE 58
DATA TRIANGULATION


Methodology

The study involved four major activities to estimate the current size of the space-based data center market. Exhaustive secondary research was conducted to gather information on the space-based data center market, its adjacent markets, and its parent market. The next step was to validate these findings, assumptions, and sizing with industry experts across the value chain through primary research. Demand-side analysis was conducted to estimate the overall market size. Thereafter, data triangulation procedures were employed to estimate the sizes of various segments and subsegments within the space-based data center market.

Secondary Research

During the secondary research process, various sources were consulted to collect information for the space-based data center market. The sources included government and regulatory organizations such as NASA, ESA, FCC, ITU, UNOOSA, and national space agencies; company annual reports, regulatory filings, press releases, investor presentations, and official product documents; and white papers, technical journals, conference papers, and recognized industry publications. Additional sources were reviewed to track developments in orbital data centers, space computing, orbital computing, cloud computing in space, space edge computing, AI data centers in space, and related satellite communication and data center infrastructure technologies.

Primary Research

Extensive primary research was conducted after acquiring information on the space-based data center market through secondary research. Several primary interviews were conducted with market experts from the demand and supply sides across major countries in North America, Europe, the Asia Pacific, and the Middle East. Primary data was collected through questionnaires, emails, and telephonic interviews.
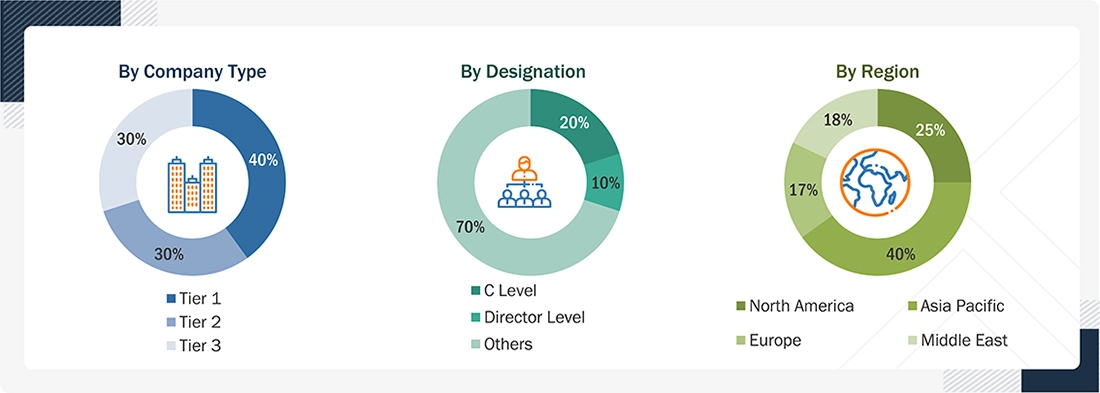
Space-Based Data Center Market Size, and Share

To know about the assumptions considered for the study, download the pdf brochure

Market Size Estimation

Top-down and bottom-up approaches were used to estimate and validate the size of the space-based data center market. The research methodology used to estimate the size of the market included the following details:

  • Key players in the space-based data center market were identified through secondary research, and their market shares were determined through a combination of primary and secondary research. This included a study of the annual and financial reports of the top market players, as well as extensive interviews with leaders, including directors, engineers, marketing executives, and other key stakeholders of leading companies operating in the market.
  • All percentage shares, splits, and breakdowns were determined using secondary sources and verified through primary sources.
  • All possible parameters that affect the markets covered in this research study were accounted for, viewed in extensive detail, verified through primary research, and analyzed to obtain the final quantitative and qualitative data on the space-based data center market. This data was consolidated, enhanced with detailed input, analyzed by MarketsandMarkets, and presented in this report.

Space-Based Data Center Market : Top-Down and Bottom-Up Approach
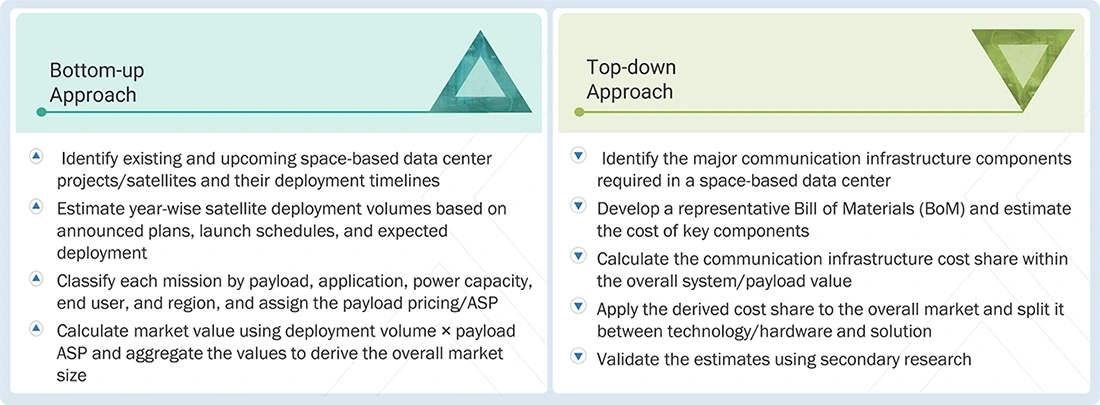
Space-Based Data Center Market Top Down and Bottom Up Approach

Data Triangulation

After determining the overall market size, the total market was divided into several segments and subsegments. The data triangulation and market breakdown procedures explained below were implemented, wherever applicable, to complete the overall market engineering process and arrive at the estimated market numbers for the market segments and subsegments. The data was triangulated by examining various factors and trends on both the demand and supply sides. Additionally, the market size was validated using top-down and bottom-up approaches.

Market Definition

The space-based data center market encompasses computing and data infrastructure deployed in space to process, store, manage, and transfer data in orbit. These systems combine computing, storage, data handling, and high-speed communication capabilities to reduce reliance on ground-based processing and support applications such as AI/ML, Earth observation analytics, scientific computing, cloud and edge computing, secure data storage, and data transfer.

Key Stakeholders

  • Government Space Agencies and Defense Organizations
  • Space-based Data Center Platform Developers and Operators
  • Satellite and Spacecraft Manufacturers
  • Data Storage, Server, Processor, and AI Hardware Suppliers
  • On-board Data Processing and Data Handling Unit Providers

Report Objectives

  • To define, describe, and forecast the space-based data center market based on payload, communication infrastructure, power capacity, end user, application, and region in terms of value
  • To forecast the size of various segments of the market across North America, Europe, Asia Pacific, and the Middle East in terms of value
  • To identify and analyze the drivers, restraints, opportunities, and challenges influencing the growth of the market
  • To identify industry trends, market trends, and technology trends currently prevailing in the market
  • To analyze micromarkets with respect to growth trends, prospects, and their contribution to the overall market
  • To analyze opportunities in the market for stakeholders by identifying key market trends
  • To profile key market players and comprehensively analyze their market share and core competencies
  • To evaluate the degree of competition in the market by analyzing recent developments, such as contracts, agreements, and acquisitions adopted by leading market players
  • To identify detailed financial positions, key products, and unique selling points of leading companies in the market
  • To provide a detailed competitive landscape of the market, along with market share analysis and revenue analysis of key players

Available customizations:

MarketsandMarkets offers the following customizations for this market report:

  • Additional country-level analysis of the space-based data center market
  • Profiling of other market players (up to five)

Product Analysis

  • Product matrix, which provides a detailed comparison of the product portfolios of each company in the space-based data center market

 

Personalize This Research

  • Triangulate with your Own Data
  • Get Data as per your Format and Definition
  • Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
  • Any level of Personalization
Request A Free Customisation

Let Us Help You

  • What are the Known and Unknown Adjacencies Impacting the Space-based Data Center Market
  • What will your New Revenue Sources be?
  • Who will be your Top Customer; what will make them switch?
  • Defend your Market Share or Win Competitors
  • Get a Scorecard for Target Partners
Customized Workshop Request

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements

Get 10% Free Customisation

TESTIMONIALS

Growth opportunities and latent adjacency in Space-based Data Center Market

DMCA.com Protection Status
popup img