Flooring Market by Material (Carpet & Rugs, Resilient Flooring, Non-Resilient Flooring), Application (New Construction, Renovation, Maintenance/Repair), End-use Industry (Residential, Non-Residential), and Region - Global Forecast to 2031

icon1
USD 255.35 BN
MARKET SIZE, 2031
icon2
CAGR 4.17%
(2026-2031)
icon3
300
REPORT PAGES
icon4
370
MARKET TABLES

OVERVIEW

flooring-market Overview

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

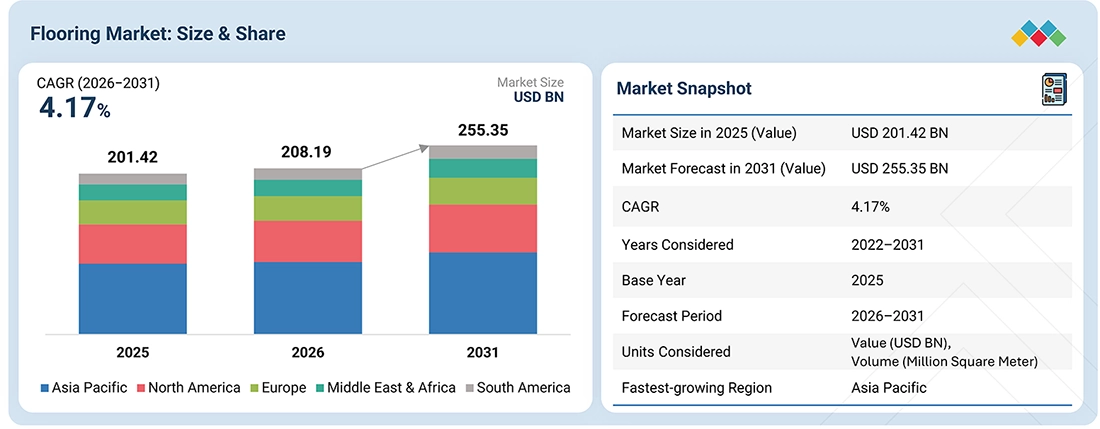
The flooring market is projected to grow from USD 208.19 billion in 2026 to USD 255.35 billion in 2031, at a CAGR of 4.17% from 2026 to 2031. Surging global urbanization and commercial real estate expansion have created an unprecedented need for durable, large-scale flooring installations in both residential and office spaces.

KEY TAKEAWAYS

  • By Region
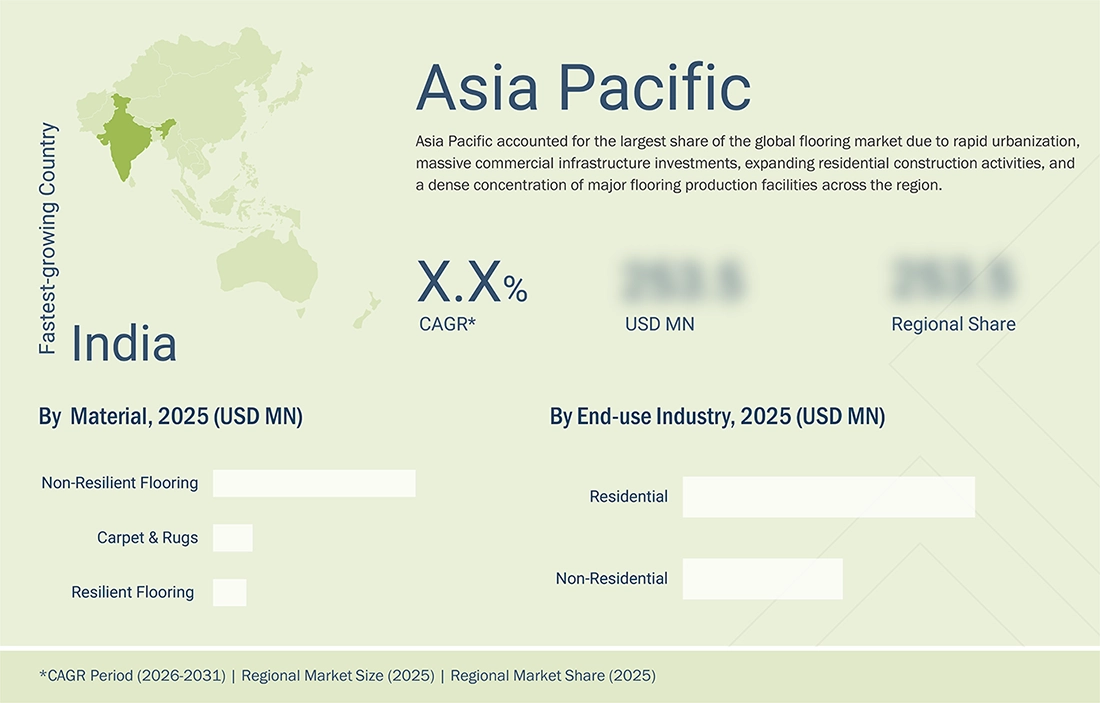
    Asia Pacific accounted for the largest share of 44.08% of the global flooring market in 2025.
  • By Material
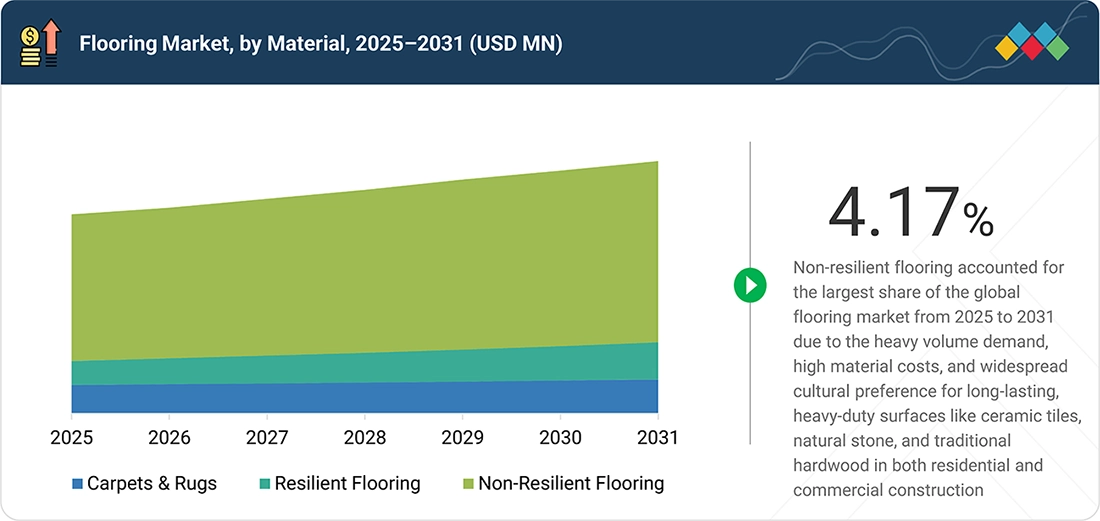
    By material, the non-resilient flooring segment accounted for the largest share of 73.57% of the overall market in 2025.
  • By Application
    By application, the new construction segment accounted for the largest share of 49.22% of the overall market in 2025.
  • By End-use Industry
    By end-use industry, the residential segment accounted for the largest share of 64.61% of the overall market in 2025.
  • Competitive Landscape - Key Players
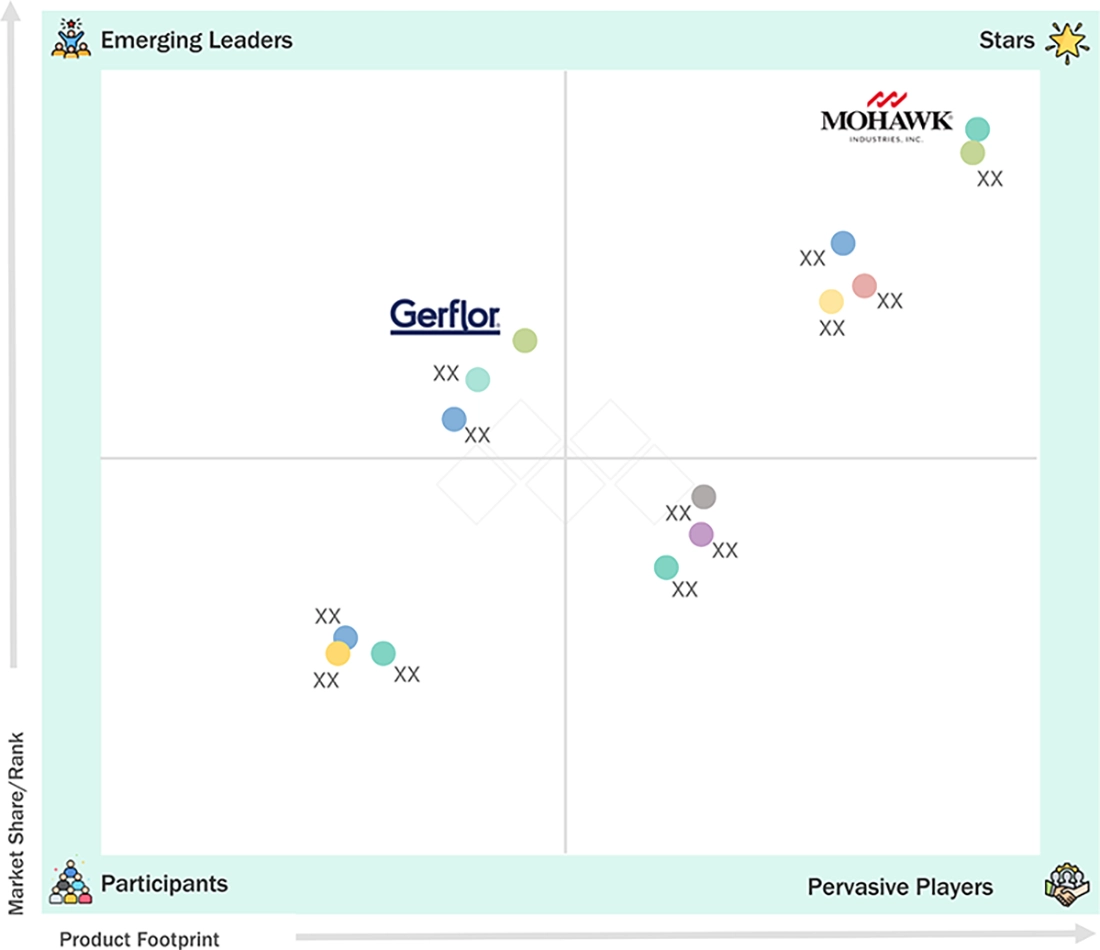
    Mohawk Industries, Inc. (US), Tarkett (France), Forbo Holding AG (Switzerland), Shaw Industries Group, Inc. (US), and Interface, Inc. (US) were identified as key players in the flooring market (global), given their strong market share and product footprint.
  • Competitive Landscape - Startups/SMEs
    The Dixie Group, Inc. (US), James Halstead plc (UK), and Hamberger Flooring GmbH & Co. KG (Germany) have distinguished themselves among startups and SMEs by securing strong footholds in specialized niche areas, underscoring their potential as emerging market leaders.

A massive surge in global construction activity spanning both new infrastructure and dense urban developments automatically scales the raw square footage of surfaces that require finish materials.

TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS

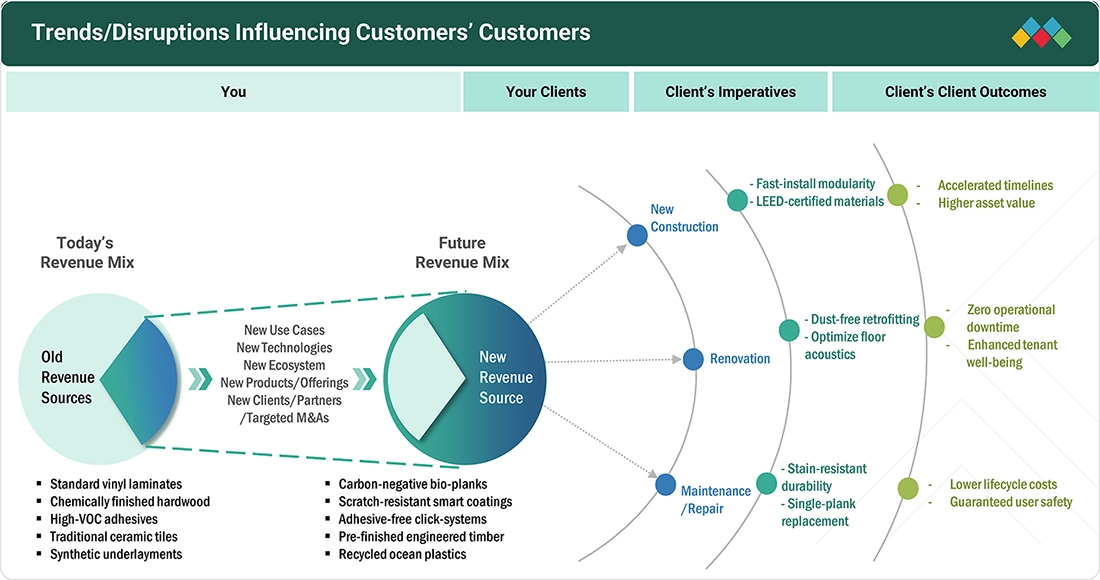
The flooring industry is rapidly transforming as it shifts from traditional materials to sustainable, quick-to-install solutions. Many flooring manufacturers still generate most of their income from traditional products, such as classic wood, vinyl tiles, and high-VOC adhesives. However, modern technologies, including stringent carbon regulations and smart buildings, are disrupting the market and creating new industry demand for carbon-neutral bio-materials, adhesive systems and more. To earn revenue from new streams, companies must target customers' needs with solutions that fit their specific purposes. In new buildings, it is crucial to use modular technology and provide LEED-certified products to expedite construction. In renovation situations, creating flooring without dust ensures no interruption to the work process and improves occupant well-being. Finally, tackling the maintenance and restoration issues ensures that the operational costs are minimized.

flooring-market Disruptions

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

MARKET DYNAMICS

Drivers
Impact
Level
  • Increasing Global Construction Expenditure
  • Renovation and Replacement of Existing Flooring
RESTRAINTS
Impact
Level
  • Volatility in PVC, Wood, and Other Flooring Raw Material Costs
  • High Logistics Costs Relative to Product Value
OPPORTUNITIES
Impact
Level
  • Recycled and Circular Flooring Systems
  • Bio-Based and Low-Emission Flooring Materials
CHALLENGES
Impact
Level
  • Meeting Diverse Regional Building and Environmental Standards
  • High Share of Flooring Replacement Costs Attributable to Installation

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Driver: Increasing Global Construction Expenditure

A key factor driving the flooring market's growth is rising global construction spending. Investment in infrastructure projects and residential and commercial construction increases demand for different floor coverings in existing and new buildings. Expenditure on transportation and healthcare projects, as well as educational institutions and urban planning, drives high demand for floor coverings in buildings. Investments in residential and commercial construction, hotels, new retail facilities, and industry increase the need to implement flooring solutions for various applications. Urbanization and the growth of real estate projects mean more buildings need installation. The construction sector in emerging markets creates opportunities to develop distribution channels and expand supply options for producers. Thus, investments in construction activities will support the growth of the flooring market.

Restraint: High Logistics Costs Relative to Product Value

The flooring market is adversely affected by volatility in the prices of raw materials such as PVC, timber, resins, metals, and other materials. Pricing becomes uncertain because of fluctuations in the costs of PVC, plastics, and synthetic resins. Timber availability, logging restrictions, transport, and customs rules also influence the production of wood-based flooring. This volatility makes it harder for companies to fix their prices with customers and distributors. Passing on input price increases to customers is difficult; small manufacturers face this more acutely because they usually lack sufficient purchasing power or storage and are often constrained by supply contracts and agreements. Moreover, frequent price changes complicate planning and management of purchasing, inventory, and project budgeting matters.

Opportunity: Recycled and Circular Flooring Systems

Introducing recycled and circular flooring systems creates a new opportunity in the flooring market, enabling material value recovery, reduced waste generation, and the development of products that meet heightened sustainability requirements. Flooring products made from recycled PVC, reclaimed wood, recycled rubber, and recovered textile fibers reduce dependence on raw materials and offer alternative ways to manage post-consumer and post-industrial waste. In addition, manufacturers make their products unique by introducing modular floor designs allowing for easy dismantling, repair, parts replacement, and material recovery after the product reaches the end of its service life. This can be especially beneficial for commercial buildings, offices, retail spaces, and other properties where flooring replacement generates large amounts of waste. Circular product designs also support take-back programs, refurbishment services, and partnerships with recycling companies, enabling companies to engage more customers and increase material recovery capacity. As building owners increasingly consider lifecycle costs and product performance, flooring suppliers that can develop consistent recycled-material supply and recycling methods gain stronger competitive advantages and access sustainability-oriented construction projects.

Challenge: Meeting Diverse Regional Building and Environmental Standards

The flooring industry faces a significant challenge due to differing regional building and environmental standards. Manufacturers must modify their products to comply with different rules in different international markets. Building codes, fire resistance classifications, slip resistance requirements, indoor air quality standards, and acoustic performance specifications vary by country. As a result, manufacturers must ensure the correct specifications when developing flooring products. Environmental standards further complicate matters because they limit volatile organic compound emissions, toxicity levels, building blocks, and the disposal of flooring waste. Meeting these requirements often means additional work for companies, such as product testing, reformulation, certification, and documentation. This means extra costs and longer product development. Moreover, manufacturers may struggle to enter markets because they must conduct additional tests for a flooring product that has already been certified in one country. Small manufacturers are known to undergo even more difficulties attempting to adapt themselves to all regulatory frameworks rather than keep their prices affordable on the market.

FLOORING MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES

COMPANY USE CASE DESCRIPTION BENEFITS
company logo
Agile Workplace Flooring: The brand installed custom carbon-neutral carpet tiles and luxury vinyl tile (LVT) flooring to support flexible layouts for a global financial institution's multi-floor corporate office. Addresses lifestyle trends by serving flexible workspaces with diverse flooring sizes | Bypasses extensive maintenance requirements to seamlessly deliver long-lasting durability at room temperatures | Extends product lifecycle while preserving visual appearance and structural performance without harsh chemical sealants
company logo
Resilient Biophilic Flooring: The organization deployed modular acoustic carpet tiles and heavy-duty nora® rubber flooring systems designed for clinical zones across healthcare facilities. Slashes acoustic footprint by drastically reducing floor-impact noise and ambient sound transmission | Enables lightweighting by cutting structural slab load requirements compared to heavy traditional hard flooring surfaces | Supports clean-label product portfolios like certified carbon-neutral carpet and PVC-free bio-based materials

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET ECOSYSTEM

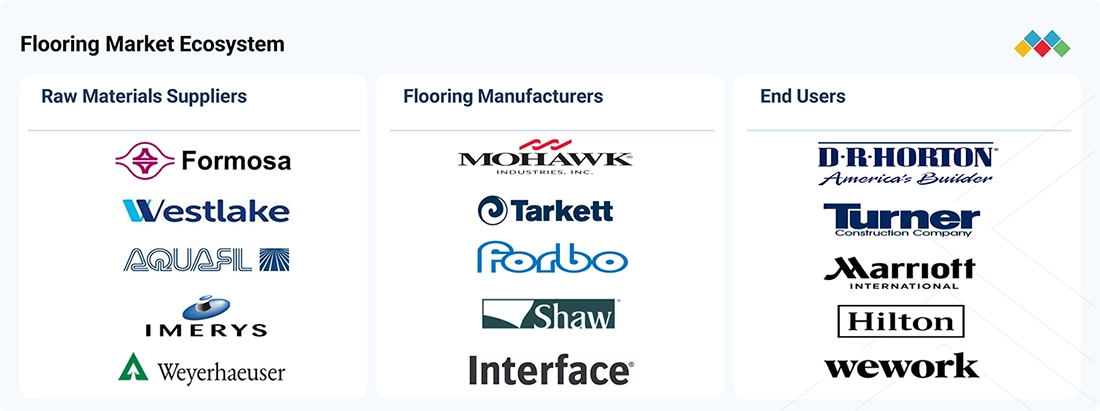
Key players in the flooring ecosystem include raw material suppliers, manufacturers, fabricators, installers, and consumers. After acquiring raw materials from suppliers of timber, PVC resins, stone aggregates, clay, nylon fibers, and adhesives, manufacturers use their machinery, operated by various types of automated systems, for milling, extrusion, and tufting to convert raw materials into a variety of flooring products such as wooden boards, luxury vinyl tiles, ceramic tiles, laminates, and carpets. Manufacturers and fabricators both use CAD systems to translate requirements into project elements. In addition, other key players in production provide installation materials such as underlay, transition strips, grout, and baseboards. Installers and contracting firms use CAD systems when working on floors in private homes, offices, hotels, industrial buildings and more. Finally, consumers use this flooring in hospitals, schools, stadiums, and large infrastructure projects.

flooring-market Ecosystem

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET SEGMENTS

flooring-market Segments

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Flooring Market, By Material 

The non-resilient flooring segment leads the overall market, mainly because it is used across a wide range of construction applications, including residential, commercial, and institutional. The category includes products such as ceramic tiles, porcelain tiles, natural stone, concrete, and other hard-surface flooring materials that provide durability and longevity of use. These products are extensively used in construction projects where there is foot traffic, moisture, and periodic cleaning, such as kitchens, bathrooms, hallways, shops, and public buildings. Their durability, diverse designs, and adaptability to architectural styles further boost their popularity in construction projects. Furthermore, strong production capacity, availability, and distribution networks enable the segment to be present in many developed and developing countries. Growing investments in housing and commercial real estate will increase demand for durable flooring products. Product availability at different price points allows non-resilient flooring products to meet the needs of both budget and premium customers, helping maintain its leading market position.

Flooring Market, By Application

The new construction segment holds the largest share of the flooring market due to the constant construction of residential buildings, office buildings, factories, and public infrastructure. Since every new building needs to be installed with flooring, there is a significant demand for many materials like ceramic tiles, natural stone, wood, vinyl, laminate, and carpet. As the urban population grows, demand for flooring in new construction projects continues to rise, driven by urbanization and population growth. Other factors such as office construction and hospitals, schools, hotels, shops, and warehouse facilities have also opened up new flooring opportunities. Furthermore, selecting flooring types at the start of the project allows stakeholders to address aesthetics, durability, maintenance costs, and installation pricing from the outset. Large living-space construction projects and infrastructure investments in developing countries are another opportunity for flooring suppliers and producers. Finally, cooperation between the flooring producers, contractors, architects, and developers contributes to the purchase of large quantities of products for construction.

Flooring Market, By End-use Industry

The residential segment accounted for the largest share of the flooring market, supported by continuous housing construction, urbanization, and demand for home renovation and improvement projects. Flooring is an important feature of any residence, such as a flat or an individual house/multifamily housing development. The choice of flooring materials depends mainly on factors such as durability and maintenance. Property developers often choose different flooring materials for their durability, aesthetic appeal, ease of care, moisture resistance, and installation costs. Home renovation is a major driver of regular flooring purchases. In addition, consumers' interest in customized home interiors, luxurious finishing materials, and special flooring solutions supports market growth.

REGION

Asia Pacific to be the largest region in global flooring market during forecast period

Asia Pacific accounted for the largest share of the global flooring market, driven by extensive construction activity, rapid urbanization, population growth, and increasing investment in residential and commercial infrastructure. As countries like China, Indonesia, India, and Japan develop their housing and construction industries, the demand for flooring is growing significantly. As demand for residential homes increased, demand for flooring materials such as vinyl, tiles, laminate, and others also rose. Established flooring manufacturing facilities and easy access to raw materials have enabled countries such as China and India to meet growing domestic and international demand for flooring production. As consumer preferences change and incomes increase, people are now spending more money on making their interior spaces look better through quality flooring and decorative finish systems. The increasing number of buildings being constructed in the region has impacted the development of the area. Government investments in infrastructure and urban development programs continue to support construction activity across emerging economies

flooring-market Region

FLOORING MARKET: COMPANY EVALUATION MATRIX

Mohawk Industries, Inc. (US) holds a prominent position among key players in the flooring sector owing to its complete range of cutting-edge surface materials and expertise. It manufactures flexible and rigid flooring products, including multi-layered luxury vinyl tiles, planks, laminates, and related products used in residential, commercial, and institutional settings. The company's expertise in materials engineering, manufacturing processes, and project execution helps meet project requirements and provides effective ways to extend lifecycle and supply chain processes. Its broad network and manufacturing capabilities allow Mohawk Industries, Inc. to maintain a leading market position. Gerflor, based in France, has operated in the flooring industry for a long time, strengthening its position through its experience and expertise in producing durable flooring products. The company develops and offers products made from structural vinyl sheet material to meet different commercial needs, including education, healthcare, and sports. The firm's design engineering expertise enables it to produce customized systems tailored to specific needs. Its international presence and modern technological solutions guarantee its effective growth in the global flooring marketplace

flooring-market Evaluation Metrics

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

KEY MARKET PLAYERS

MARKET SCOPE

REPORT METRIC DETAILS
Market Size in 2025 (Value) USD 201.42 Billion
Market Forecast in 2026 (Value) USD 208.19 Billion
Market Forecast in 2031 (Value) USD 255.35 Billion
Growth Rate CAGR of 4.17% from 2026- 2031
Years Considered 2022–2031
Base Year 2025
Forecast Period 2026–2031
Units Considered Value (USD Billion), Volume (Million Square Meter)
Report Coverage Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments Covered
  • By Material:
    • Carpet & Rugs
    • Resilient Flooring
    • Non-Resilient Flooring
  • By Application:
    • New Construction
    • Renovation
    • Maintenance/Repair
  • By End-use Industry:
    • Residential
    • Non-Residential
Regions Covered North America, Asia Pacific, Europe, South America, Middle East & Africa

WHAT IS IN IT FOR YOU: FLOORING MARKET REPORT CONTENT GUIDE

flooring-market Content Guide

DELIVERED CUSTOMIZATIONS

We have successfully delivered the following deep-dive customizations:

CLIENT REQUEST CUSTOMIZATION DELIVERED VALUE ADDS
Modular Flooring Market – Product, Installation, and End-use Customization Focus Detailed, specific analysis of the modular flooring market with a dedicated focus on specialized sub-segments, covering market structure, custom product categories, demand across key commercial and residential industries, installation technique dynamics, competitive landscape, and identification of key manufacturers producing modular flooring solutions.
  • Identify key global and regional modular flooring manufacturers and assess their product capabilities
  • Evaluate manufacturing capacity and specialized materials offered across luxury vinyl tiles, ceramic, rubber, and polyolefin product types
  • Benchmark manufacturers based on product portfolio, technical installation engineering, applications, and market presence
  • Assess installation trends across Interlocking and Loose Lay techniques to identify sourcing opportunities
  • Analyze competitive gaps and whitespace across household, workplace, healthcare, education, and retail end-use applications
  • Support supplier selection, strategic partnerships, and market-entry decisions with specific competitive intelligence
CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS | | | |    
Deeper analysis of high-growth end-use industries | Detailed demand breakdown for semiconductor, healthcare, metal fabrication, and environmental monitoring sectors | Consumption pattern analysis across industries | Purity requirement mapping for specialt    
Assessment of competitive positioning in specialty gas mixtures | Benchmarking of key players based on blending capabilities, purity levels, distribution models, and technology integration | Comparative analysis of product portfolios and certification cap    

RECENT DEVELOPMENTS

  • August 2026 : Mohawk Industries, Inc. entered a landmark exclusive Executive Strategic Partnership with Certified Flooring Installers (CFI) Building the Trades of Tomorrow. This partnership establishes the brand as a key driver in national installer workforce development, focusing on expanding technical education and training programs to scale up proper installation execution for new high-performance accessories across commercial networks.
  • July 2026 : Shaw Industries Group, Inc. rolled out a comprehensive summer 2026 product launch across its prime residential and commercial divisions, including Anderson Tuftex, COREtec, and Shaw Floors. The new collection debuts next-generation multi-layer formats designed for advanced acoustic dampening, simple interlocking installation, and certified sustainable performance.
  • January 2026 : Mondi showcased Ad/Vantage TrayWrap at Fachpack 2025, a paper-based secondary tray-wrapping solution suitable for aseptic cartons, coffee vacuum packs, cans and bottles, replacing plastic stretch film on stackable retail products.

Table of Contents

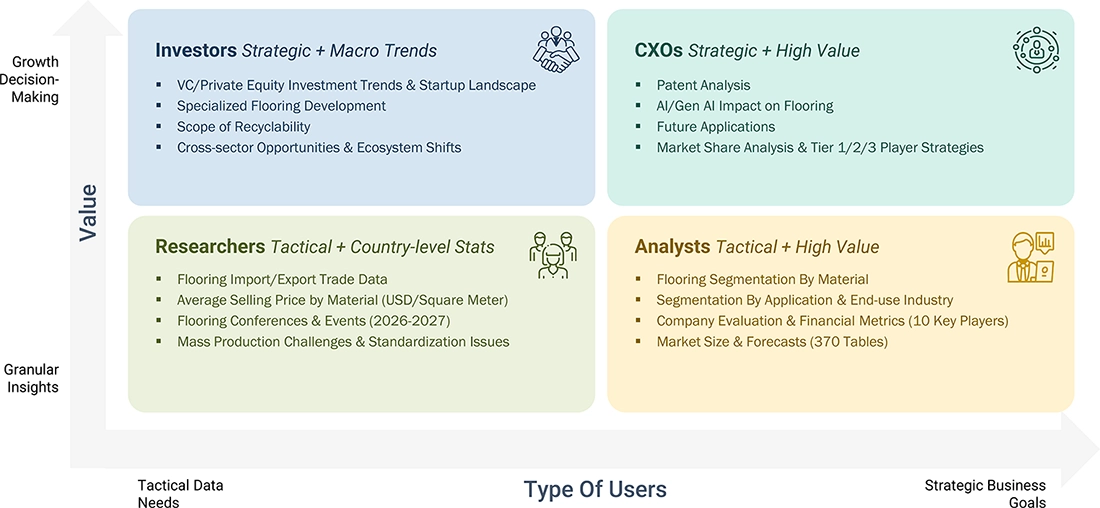
checkmarkExclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.

TITLE
PAGE NO
1
INTRODUCTION


15
2
EXECUTIVE SUMMARY


3
PREMIUM INSIGHTS


4
MARKET OVERVIEW
Maps the market evolution with focus on trend catalysts, risk factors, and growth opportunities across segments.


4.1
INTRODUCTION


4.2
MARKET DYNAMICS


4.2.1
DRIVERS


4.2.2
RESTRAINTS


4.2.3
OPPORTUNITIES


4.2.4
CHALLENGES


4.3
UNMET NEEDS AND WHITE SPACES


4.4
INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES


4.5
STRATEGIC MOVES BY TIER 1/2/3 PLAYERS


5
INDUSTRY TRENDS
Captures industry movement, adoption patterns, and strategic signals across key end-use segments and regions.


5.1
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS


5.2
PRICING ANALYSIS


5.2.1
AVERAGE SELLING PRICE TREND OF FLOORING, BY REGION (2022-2025)


5.2.2
AVERAGE SELLING PRICE OF FLOORING, BY KEY PLAYERS (2025)


5.3
VALUE CHAIN ANALYSIS


5.4
ECOSYSTEM ANALYSIS


5.5
TRADE ANALYSIS


5.5.1
IMPORT SCENARIO


5.5.2
EXPORT SCENARIO


5.6
KEY CONFERENCES AND EVENTS, 2026–2027


5.7
PORTER’S FIVE FORCES ANALYSIS


5.7.1
THREAT OF NEW ENTRANTS


5.7.2
THREAT OF SUBSTITUTES


5.7.3
BARGAINING POWER OF SUPPLIERS


5.7.4
BARGAINING POWER OF BUYERS


5.7.5
INTENSITY OF COMPETITIVE RIVALRY


5.8
CASE STUDY ANALYSIS


5.9
MACROECONOMIC OUTLOOK


5.9.1
INTRODUCTION


5.9.2
GDP TRENDS AND FORECAST


5.9.3
TRENDS IN GLOBAL CONSTRUCTION INDUSTRY


5.10
INVESTMENT AND FUNDING SCENARIO


5.11
IMPACT OF 2025 US TARIFF: FLOORING MARKET


5.11.1
INTORDUCTION


5.11.2
KEY TARIFF RATES


5.11.3
PRICE IMPACT ANALYSIS


5.11.4
IMPACT ON COUNTRIES/REGIONS


5.11.4.1
US


5.11.4.2
EUROPE


5.11.4.3
ASIA PACIFIC


5.11.1
IMPACT ON END USERS
 
 
6
TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS


6.1
KEY/EMERGING TECHNOLOGIES


6.2
COMPLEMENTARY TECHNOLOGIES


6.3
TECHNOLOGY/PRODUCT ROADMAP


6.4
PATENT ANALYSIS


6.5
FUTURE APPLICATIONS


6.6
IMPACT OF AI/GEN AI ON FLOORING MARKET


6.6.1
TOP USE CASES AND MARKET POTENTIAL


6.6.2
BEST PRACTICES FOLLOWED BY COMPANIES OFFERING FLOORING


6.6.3
CASE STUDIES OF AI IMPLEMENTATION IN FLOORING


6.6.4
INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS


6.6.5
CLIENTS’ READINESS TO ADOPT GENERATIVE AI IN FLOORING MARKET


6.7
SUCCESS STORIES AND REAL-WORLD APPLICATIONS


7
REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES


7.1
REGIONAL REGULATIONS AND COMPLIANCE


7.1.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


7.1.2
INDUSTRY STANDARDS


7.2
SUSTAINABILITY INITIATIVES


7.3
IMPACT OF REGULATORY POLICIES ON SUSTAINABILITY INITIATIVES


8
CUSTOMER LANDSCAPE AND BUYER BEHAVIOR


8.1
DECISION-MAKING PROCESS


8.2
KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA


8.2.1
KEY STAKEHOLDERS IN BUYING PROCESS


8.2.2
BUYING CRITERIA


8.3
ADOPTION BARRIERS AND INTERNAL CHALLENGES


8.4
UNMET NEEDS OF VARIOUS APPLICATIONS


8.5
MARKET PROFITABILITY


9
FLOORING MARKET, BY MATERIAL – (MARKET SIZE & FORECAST TO 2031 – IN VALUE, USD MILLION & IN VOLUME, MILLION SQUARE METERS)


9.1
INTRODUCTION


9.2
CARPET & RUGS


9.3
RESILIENT FLOORING


9.4
NON-RESILIENT FLOORING


9.4.1
CERAMIC TILES


9.4.2
WOOD


9.4.3
LAMINATE


9.4.4
STONE


9.4.5
OTHER NON-RESILIENT FLOORING
 
 
10
FLOORING MARKET, BY APPLICATION – (MARKET SIZE & FORECAST TO 2031 – IN VALUE, USD MILLION & IN VOLUME, MILLION SQUARE METERS)


10.1
INTRODUCTION


10.2
NEW CONSTRUCTION


10.3
RENOVATION


10.4
MAINTENANCE/REPAIR


11
FLOORING MARKET, BY END-USE INDUSTRY – (MARKET SIZE & FORECAST TO 2031– IN VALUE, USD MILLION & IN VOLUME, MILLION SQUARE METERS)


11.1
INTRODUCTION


11.2
RESIDENTIAL


11.3
NON-RESIDENTIAL


12
FLOORING MARKET, BY REGION – (MARKET SIZE & FORECAST TO 2031 – IN VALUE, USD MILLION & IN VOLUME, MILLION SQUARE METERS)


12.1
INTRODUCTION


12.2
NORTH AMERICA


12.2.1
US


12.2.2
CANADA


12.2.3
MEXICO


12.3
ASIA PACIFIC


12.3.1
CHINA


12.3.2
INDIA


12.3.3
JAPAN


12.3.4
SOUTH KOREA


12.3.5
AUSTRALIA


12.3.6
REST OF ASIA PACIFIC


12.4
EUROPE


12.4.1
GERMANY


12.4.2
FRANCE


12.4.3
UK


12.4.4
RUSSIA


12.4.5
SPAIN


12.4.6
NETHERLANDS


12.4.7
REST OF EUROPE


12.5
SOUTH AMERICA


12.5.1
BRAZIL


12.5.2
ARGENTINA


12.5.3
REST OF SOUTH AMERICA


12.6
MIDDLE EAST & AFRICA


12.6.1
GCC


12.6.1.1
SAUDI ARABIA


12.6.1.2
UAE


12.6.1.3
REST OF GCC


12.6.1
TURKEY


12.6.2
SOUTH AFRICA


12.6.3
REST OF MIDDLE EAST & AFRICA
 
 
13
COMPETITIVE LANDSCAPE


13.1
OVERVIEW


13.2
KEY PLAYERS’ STRATEGIES /RIGHT TO WIN (JANUARY 2024-SEPTEMBER 2026)


13.3
MARKET SHARE ANALYSIS


13.4
REVENUE ANALYSIS)


13.5
COMPANY VALUATION AND FINANCIAL METRICS


13.6
BRAND/PRODUCT COMPARISON


13.7
COMPANY EVALUATION MATRIX: KEY PLAYERS,


13.7.1
STARS


13.7.2
EMERGING LEADERS


13.7.3
PERVASIVE PLAYERS


13.7.4
PARTICIPANTS


13.7.5
COMPANY FOOTPRINT: KEY PLAYERS,


13.7.5.1
COMPANY FOOTPRINT


13.7.5.2
REGION FOOTPRINT


13.7.5.3
MATERIAL FOOTPRINT


13.7.5.4
APPLICATION FOOTPRINT


13.7.5.5
END-USE INDUSTRY FOOTPRINT
 
 
13.8
COMPANY EVALUATION MATRIX: STARTUPS/SMES,


13.8.1
PROGRESSIVE COMPANIES


13.8.2
RESPONSIVE COMPANIES


13.8.3
DYNAMIC COMPANIES


13.8.4
STARTING BLOCKS


13.8.5
COMPETITIVE BENCHMARKING: STARTUPS/SMES,


13.8.5.1
DETAILED LIST OF KEY STARTUPS/SMES


13.8.5.2
COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
 
 
13.9
COMPANY VALUATION AND FINANCIAL METRICS


13.10
COMPETITIVE SCENARIO


13.10.1
PRODUCT LAUNCHES


13.10.2
DEALS


13.10.3
EXPANSIONS


13.10.4
OTHER DEVELOPMENTS
 
 
14
COMPANY PROFILES


14.1
MOHAWK INDUSTRIES, INC.


14.1.1
BUSINESS OVERVIEW


14.1.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.3
RECENT DEVELOPMENTS


14.1.3.1
PRODUCT LAUNCHES


14.1.3.2
DEALS


14.1.3.3
EXPANSIONS


14.1.3.4
OTHER DEVELOPMENTS


14.1.4
MNM VIEW


14.1.4.1
KEY STRENGTHS


14.1.4.2
STRATEGIC CHOICES


14.1.4.3
WEAKNESSES AND COMPETITIVE THREATS
 
 
14.2
TARKETT


14.2.1
BUSINESS OVERVIEW


14.2.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.2.3
RECENT DEVELOPMENTS


14.2.3.1
PRODUCT LAUNCHES


14.2.3.2
DEALS


14.2.3.3
EXPANSIONS


14.2.3.4
OTHER DEVELOPMENTS


14.2.4
MNM VIEW


14.2.4.1
KEY STRENGTHS


14.2.4.2
STRATEGIC CHOICES


14.2.4.3
WEAKNESSES AND COMPETITIVE THREATS
 
 
14.3
FORBO HOLDING AG


14.3.1
BUSINESS OVERVIEW


14.3.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.3.3
RECENT DEVELOPMENTS


14.3.3.1
PRODUCT LAUNCHES


14.3.3.2
DEALS


14.3.3.3
EXPANSION


14.3.3.4
OTHER DEVELOPMENTS


14.3.4
MNM VIEW


14.3.4.1
KEY STRENGTHS


14.3.4.2
STRATEGIC CHOICES


14.3.4.3
WEAKNESSES AND COMPETITIVE THREATS
 
 
14.4
SHAW INDUSTRIES GROUP, INC.


14.4.1
BUSINESS OVERVIEW


14.4.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.4.3
RECENT DEVELOPMENTS


14.4.3.1
PRODUCT LAUNCHES


14.4.3.2
DEALS


14.4.3.3
EXPANSIONS


14.4.3.4
OTHER DEVELOPMENTS


14.4.4
MNM VIEW


14.4.4.1
KEY STRENGTHS


14.4.4.2
STRATEGIC CHOICES


14.4.4.3
WEAKNESSES AND COMPETITIVE THREATS
 
 
14.5
INTERFACE, INC.


14.5.1
BUSINESS OVERVIEW


14.5.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.5.3
RECENT DEVELOPMENTS


14.5.3.1
PRODUCT LAUNCHES


14.5.3.2
DEALS


14.5.3.3
EXPANSIONS


14.5.3.4
OTHER DEVELOPMENTS


14.5.4
MNM VIEW


14.5.4.1
KEY STRENGTHS


14.5.4.2
STRATEGIC CHOICES


14.5.4.3
WEAKNESSES AND COMPETITIVE THREATS
 
 
14.6
TOLI CORPORATION


14.6.1
BUSINESS OVERVIEW


14.6.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.6.3
RECENT DEVELOPMENTS


14.6.3.1
PRODUCT LAUNCHES


14.6.3.2
DEALS


14.6.3.3
EXPANSIONS


14.6.3.4
OTHER DEVELOPMENTS
 
 
14.7
BEAULIEU INTERNATIONAL GROUP


14.7.1
BUSINESS OVERVIEW


14.7.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.7.3
RECENT DEVELOPMENTS


14.7.3.1
PRODUCT LAUNCHES


14.7.3.2
DEALS


14.7.3.3
EXPANSIONS


14.7.3.4
OTHER DEVELOPMENTS
 
 
14.8
MILLIKEN & COMPANY


14.8.1
BUSINESS OVERVIEW


14.8.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.8.3
RECENT DEVELOPMENTS


14.8.3.1
PRODUCT LAUNCHES


14.8.3.2
DEALS


14.8.3.3
EXPANSIONS


14.8.3.4
OTHER DEVELOPMENTS
 
 
14.9
GERFLOR


14.9.1
BUSINESS OVERVIEW


14.9.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.9.3
RECENT DEVELOPMENTS


14.9.3.1
PRODUCT LAUNCHES


14.9.3.2
DEALS


14.9.3.3
EXPANSIONS


14.9.3.4
OTHER DEVELOPMENTS
 
 
14.10
KAJARIA CERAMICS LIMITED


14.10.1
BUSINESS OVERVIEW


14.10.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.10.3
RECENT DEVELOPMENTS


14.10.3.1
PRODUCT LAUNCHES


14.10.3.2
DEALS


14.10.3.3
EXPANSIONS


14.10.3.4
OTHER DEVELOPMENTS
 
 
14.11
JAMES HALSTEAD PLC


14.12
THE DIXIE GROUP, INC.


14.13
VICTORIA PLC


14.14
MANNINGTON MILLS, INC.


14.15
SWISS KRONO GROUP


14.16
LX HAUSYS


14.17
KÄHRS GROUP


14.18
CFL FLOORING


14.19
AHF PRODUCTS


14.20
INVISTA


14.21
ORIENTAL WEAVERS


14.22
NOX CORPORATION


14.23
FRITZ EGGER GMBH & CO. OG


14.24
WELSPUN FLOORING


14.25
HAMBERGER FLOORING GMBH & CO. KG


15
RESEARCH METHODOLOGY


15.1
RESEARCH DATA


15.1.1
SECONDARY DATA


15.1.1.1
KEY DATA FROM SECONDARY SOURCES


15.1.1.2
LIST OF SECONDARY SOURCES


15.1.2
PRIMARY DATA


15.1.2.1
KEY DATA FROM PRIMARY SOURCES


15.1.2.2
KEY INDUSTRY INSIGHTS


15.1.2.3
BREAKDOWN OF PRIMARY INTERVIEWS


15.1.2.4
LIST OF PRIMARY PARTICIPANTS
 
 
15.2
MARKET SIZE ESTIMATION


15.2.1
BOTTOM-UP APPROACH


15.2.1.1
APPROACH TO ESTIMATE MARKET SIZE BY BOTTOM-UP ANALYSIS (DEMAND SIDE)


15.2.2
TOP-DOWN APPROACH


15.2.2.1
APPROACH TO ESTIMATE MARKET SIZE BY TOP-DOWN ANALYSIS (SUPPLY SIDE)
 
 
15.3
MARKET BREAKDOWN AND DATA TRIANGULATION


15.4
RESEARCH ASSUMPTIONS


15.5
RESEARCH LIMITATIONS


15.6
RISK ASSESSMENT


16
APPENDIX


16.1
DISCUSSION GUIDE


16.2
AVAILABLE CUSTOMIZATIONS


16.3
CONNECTED MARKETS


16.4
AUTHOR DETAILS


Methodology

The study involved four major activities to estimate the current size of the global flooring market. Exhaustive secondary research was carried out to collect information on the market, the peer product market, and the parent product group market. The next step was to validate these findings, assumptions, and sizes with industry experts across the value chain of the flooring market through primary research. The top-down and bottom-up approaches were employed to estimate the overall size of the flooring market. After that, market breakdown and data triangulation procedures were used to determine the size of different market segments.

Secondary Research

The market for flooring companies was determined by reviewing secondary data from paid and unpaid sources, analysing the product portfolios of major companies in the ecosystem, and rating companies by performance and quality. Various secondary sources, such as Business Standard, Bloomberg, World Bank, and Factiva, were referred to identify and collect information for this study on the flooring market. In the secondary research process, various secondary sources were referred to identify and collect information related to the study. Secondary sources included annual reports, press releases, investor presentations, flooring vendors, forums, certified publications, and white papers. The secondary research was used to obtain critical information on the industry’s value chain, the total pool of key players, market classification, and segmentation from the market and technology-oriented perspectives.

Primary Research

In the primary research process, various primary sources from the supply and demand sides were interviewed to obtain qualitative and quantitative information for this report. The primary sources from the supply side included industry experts, such as Chief Executive Officers (CEOs), Vice Presidents (VPs), marketing directors, technology and innovation directors, and related key executives from several key companies and organizations operating in the flooring market. After the complete market engineering process (which includes calculations for market statistics, market breakdown, market size estimations, market forecasting, and data triangulation), extensive primary research was conducted to gather information and verify and validate the critical numbers arrived at. Primary research was also conducted to identify the segmentation types, industry trends, competitive landscape of flooring offered by various market players, and key market dynamics, such as drivers, restraints, opportunities, challenges, industry trends, and key player strategies. In the complete market engineering process, the top-down and bottom-up approaches and several data triangulation methods were extensively used to perform the market estimation and market forecasting for the overall market segments and subsegments listed in this report. Extensive qualitative and quantitative analysis was performed on the complete market engineering process to list key information/insights throughout the report.

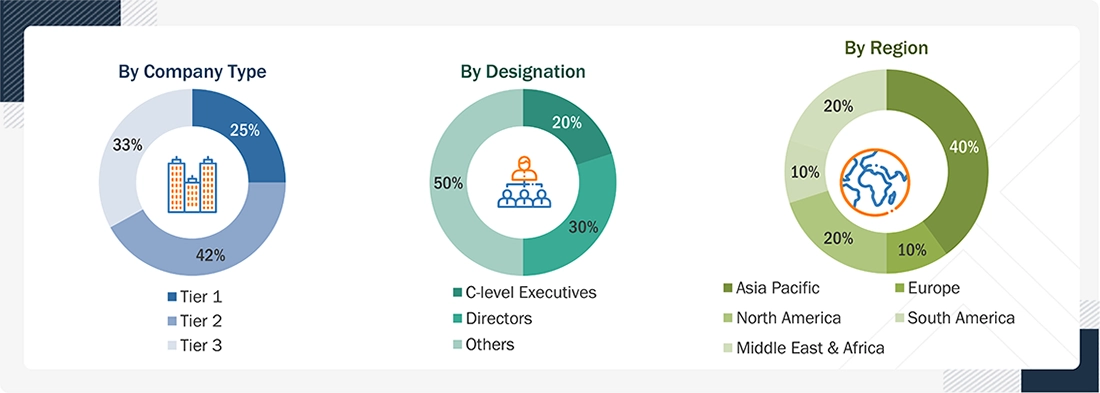
The following is the breakdown of primary respondents:

Flooring Market Size, and Share

Notes: Others include sales, marketing, and product managers.

Tier 1: > USD 1 billion; Tier 2: USD 500 million–1 billion; and Tier 3: < USD 500 million

To know about the assumptions considered for the study, download the pdf brochure

Market Size Estimation

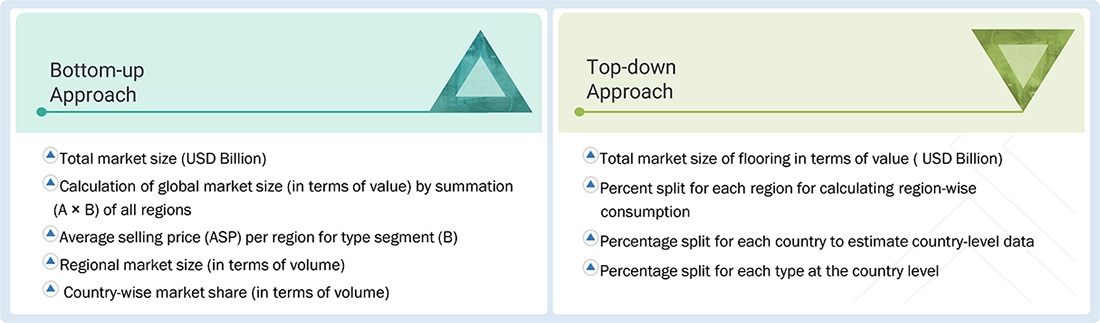
The top-down and bottom-up approaches were used to estimate and validate the size of the global flooring market. These approaches were also used extensively to estimate the size of various dependent market segments.

Flooring Market: Top-Down and Bottom-Up Approach

Flooring Market Top Down and Bottom Up Approach

Data Triangulation

After arriving at the overall market size using the market size estimation processes, the market was split into several segments and subsegments. Data triangulation and market breakup procedures were employed, wherever applicable, to complete the overall market engineering process and arrive at the exact statistics of each market segment and subsegment. The data were triangulated by studying various factors and trends from both the demand and supply sides.

Market Definition

Flooring refers to the permanent installation of a smooth, durable, and functional finish material onto a building’s subfloor structure to provide a walkable surface. It includes materials such as hardwood, carpet, ceramic tiles, and luxury vinyl planks engineered to withstand daily foot traffic, optimize building acoustics, and enhance the visual aesthetic of interior spaces.

Key Stakeholders

  • Flooring Manufacturers
  • Flooring Suppliers
  • Industry Associations and Regulatory Bodies
  • Research & Development Entities
  • Raw Material Suppliers
  • End Users

Report Objectives

  • To define, describe, and forecast the size of the global flooring market based on material, application, end-use industry, and region in terms of value and volume
  • To provide detailed information on the significant drivers, restraints, opportunities, and challenges influencing the market
  • To analyse and forecast the market based on material, application, and end-use industry
  • To strategically analyze micro markets concerning individual growth trends, prospects, and their contribution to the market
  • To assess the growth opportunities in the market for stakeholders and provide details on the competitive landscape for market leaders
  • To forecast the market size of segments for North America, Europe, Asia Pacific, South America, and the Middle East & Africa
  • To strategically profile key players and comprehensively analyze their market shares and core competencies
  • To analyze competitive developments, such as expansions, product launches, partnerships, and acquisitions in the flooring market
  • To assess the impact of AI on the flooring market

Available customizations:

With the given market data, MarketsandMarkets offers customizations according to client-specific needs.
The following customization options are available for the flooring report:

Product Analysis

  • A product matrix that gives a detailed comparison of the product portfolio of each company

Regional Analysis

  • A further breakdown of the flooring market for additional countries

Company Information

  • Detailed analysis and profiling of additional market players (up to five)


Personalize This Research

  • Triangulate with your Own Data
  • Get Data as per your Format and Definition
  • Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
  • Any level of Personalization
Request A Free Customisation

Let Us Help You

  • What are the Known and Unknown Adjacencies Impacting the Flooring Market
  • What will your New Revenue Sources be?
  • Who will be your Top Customer; what will make them switch?
  • Defend your Market Share or Win Competitors
  • Get a Scorecard for Target Partners
Customized Workshop Request

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements

Get 10% Free Customisation

TESTIMONIALS

Growth opportunities and latent adjacency in Flooring Market

THIS REPORT TELLS YOU

How big the Flooring market is, and who leads it.

GROWTHIQ TELLS YOU NEW

Where your company should play next, and who is taking your share.

Get your company's view of this market. Free snapshot.

DMCA.com Protection Status
popup img