Hindered Amine Light Stabilizers (HALS) Market by Type (Polymeric, Oligomeric, and Monomeric), End-use Industry (Automotive, Building & Construction, Packaging, Agriculture, and Other End-use Industries), and Region - Global Forecast to 2031

icon1
USD 2.49 BN
MARKET SIZE, 2031
icon2
CAGR 7.11%
(2026-2031)
icon3
250
REPORT PAGES
icon4
280
MARKET TABLES

OVERVIEW

hindered-amine-light-stabilizers-market Overview

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

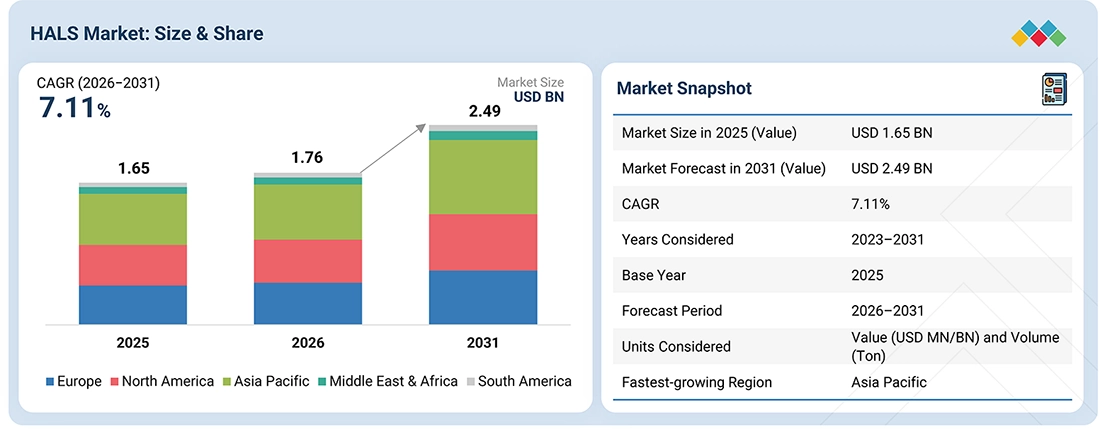
The HALS market is projected to grow from USD 1.76 billion in 2026 to USD 2.49 billion by 2031, at a CAGR of 7.11%. Hindered amine light stabilizers (HALS) are specialty additives that protect polymers from degradation caused by UV radiation and oxidative processes, helping maintain color, mechanical strength, and surface appearance. Their market growth is fueled by rising demand across industries such as automotive, packaging, agriculture, building & construction, and consumer products, along with increasing use of durable polymer materials in outdoor applications.

KEY TAKEAWAYS

  • BY REGION
    By region, Asia Pacific dominated the HALS market in 2025, accounting for a share of 36.0% in terms of value.
  • BY TYPE
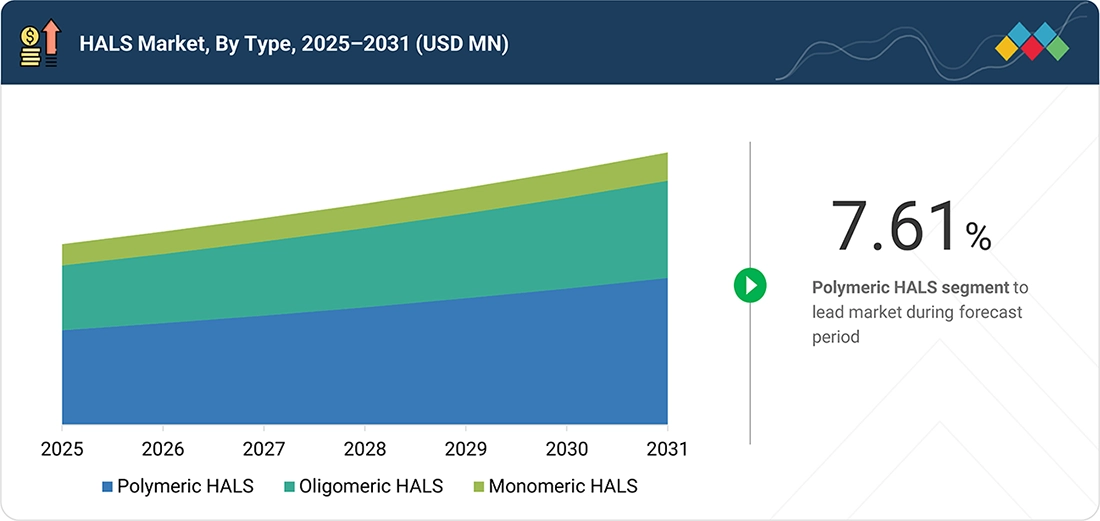
    By type, the polymeric HALS segment led the HALS market in 2025, accounting for a share of 52.4%.
  • BY END-USE INDUSTRY
    By end-use industry, the automotive segment is projected to register the highest CAGR of 8.21%, in terms of value, during the forecast period.
  • COMPETITIVE LANDSCAPE - KEY PLAYERS
    BASF SE, Rianlon Corporation, SABO S.p.A., Syensqo SA/NV, and Suqian Unitech Corp., Ltd. are identified as key players in the HALS market. These companies have strong market presence and extensive product portfolios.
  • COMPETITIVE LANDSCAPE - STARTUPS
    Yuanli Chemical Group Co., Ltd., 3V Sigma S.p.A., and CHEMIPRO KASEI, among other emerging players, hold strong positions in specialized niche segments, underscoring their potential to become future market leaders in the HALS market.

The HALS market is projected to grow steadily over the next decade, supported by advancements in polymer stabilization technologies and increasing demand for long-lasting plastic products. Industries are increasingly adopting HALS to protect polymers from UV degradation, maintain mechanical properties, and extend product service life, making them valuable in automotive components, packaging, agricultural films, construction materials, and outdoor products. Growing emphasis on material durability, product longevity, and performance in demanding environments further strengthens the role of HALS as an essential polymer additive, supporting broader industrial adoption.

TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS

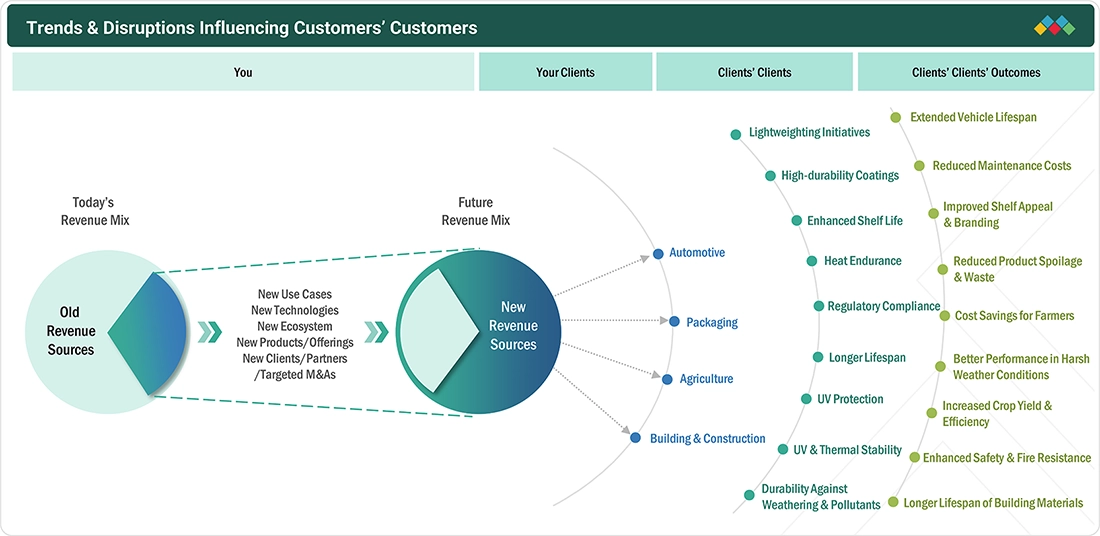
The impact on consumers’ business emerges from changing customer trends and market disruptions. Polymer processors and end-use industries are the clients of HALS manufacturers, while raw material suppliers and distributors support the HALS value chain. Shifts in polymer demand, UV protection requirements, sustainability preferences, and industry production levels will impact the revenues of end-use industries. Changes in end-user revenues will influence procurement volumes across the value chain, which will further affect the revenues of HALS manufacturers.

hindered-amine-light-stabilizers-market Disruptions

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

MARKET DYNAMICS

Drivers
Impact
Level
  • Rising market demand in plastics industry
  • Technological advancements
RESTRAINTS
Impact
Level
  • Supply chain disruptions and price volatility
  • Competition from alternative stabilization technologies
OPPORTUNITIES
Impact
Level
  • Customized solutions for specific applications
CHALLENGES
Impact
Level
  • Stringent environmental and regulatory compliance

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Driver: Rising market demand in plastics industry

The expanding plastics industry is increasing demand for HALS, as plastics are widely used in packaging, automotive, building & construction, agriculture, and consumer goods. Prolonged exposure to sunlight can cause discoloration, cracking, brittleness, and loss of mechanical strength in polymer materials. HALS help reduce these effects by stabilizing free radicals generated during photodegradation, thereby extending product service life. Their use is particularly relevant in outdoor plastic applications, including agricultural films, automotive components, construction products, and outdoor furniture. The growing adoption of lightweight and recycled plastics is further supporting demand, as these materials require effective stabilization to maintain durability and performance during prolonged environmental exposure.

Restraint: Supply chain disruptions and price volatility

Supply chain disruptions and raw material price volatility can constrain the HALS market by increasing production costs and creating uncertainty for manufacturers and customers. HALS production depends on specialty amines, acetone, and other organic intermediates, several of which are connected to petrochemical supply chains. Changes in feedstock availability, energy costs, transportation conditions, and regional production capacity can influence manufacturing economics. Geopolitical instability, trade restrictions, plant maintenance, and logistics interruptions may further affect the availability of specific HALS grades. Higher input costs can place pressure on product pricing and margins, particularly in price-sensitive applications. Manufacturers, therefore, need diversified sourcing, inventory planning, and reliable supplier networks to maintain consistent supply.

Opportunity: Customized solutions for specific applications

Customized HALS solutions offer significant opportunities as polymer formulations and performance requirements vary across applications. Automotive components require stabilization against prolonged UV exposure, temperature fluctuations, and moisture, while agricultural films require compatibility with pesticides and fertilizers. Building products demand long-term weathering resistance, whereas packaging applications may prioritize migration behavior, appearance, and processing stability. Specialized HALS grades can also address the specific degradation characteristics of recycled and bio-based polymers. Developing application-specific stabilization systems enables suppliers to provide higher-performance solutions than general-purpose products and strengthen technical relationships with polymer producers and compounders. Such customization can support premium product positioning, improve customer retention, and help HALS manufacturers enter specialized, higher-value application segments.

Challenge: Stringent environmental and regulatory compliance

Stringent environmental and regulatory requirements present an ongoing challenge for HALS manufacturers, particularly across North America and Europe. Regulations covering chemical registration, substance safety, emissions, waste management, and worker exposure require detailed product assessment and documentation. Requirements under REACH (Registration, Evaluation, Authorization, and Restriction of Chemicals) and regulations administered by the United States Environmental Protection Agency can increase testing, compliance, and development costs. Regulatory expectations may also differ across regions, complicating product registration and commercialization. Growing scrutiny from automotive, packaging, construction, and consumer-product manufacturers further increases demand for additives with suitable regulatory profiles. HALS producers must, therefore, continuously monitor regulations, maintain technical documentation, and adapt formulations to preserve market access.

HINDERED AMINE LIGHT STABILIZERS (HALS) MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES

COMPANY USE CASE DESCRIPTION BENEFITS
company logo
Use of hindered amine light stabilizers (HALS) in automotive exterior plastics, coatings, and polymer components exposed to prolonged sunlight. Improved ultraviolet resistance, reduced surface degradation, longer component life, and sustained appearance under outdoor exposure.
company logo
Incorporation of HALS into bumper systems, exterior trims, and other polymer-based automotive parts to maintain performance during vehicle operation. Enhanced color retention, improved resistance to cracking, extended durability, and reduced maintenance requirements.
company logo
Integration of HALS into automotive and protective coatings to protect polymer binders from degradation caused by ultraviolet radiation. Improved coating durability, better gloss retention, reduced chalking, and longer-lasting surface protection.
company logo
Application of HALS in flexible and rigid plastic packaging used for products exposed to light during storage, distribution, and retail display. Enhanced polymer stability, improved package appearance, extended material durability, and reliable performance throughout the packaging lifecycle.

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET ECOSYSTEM

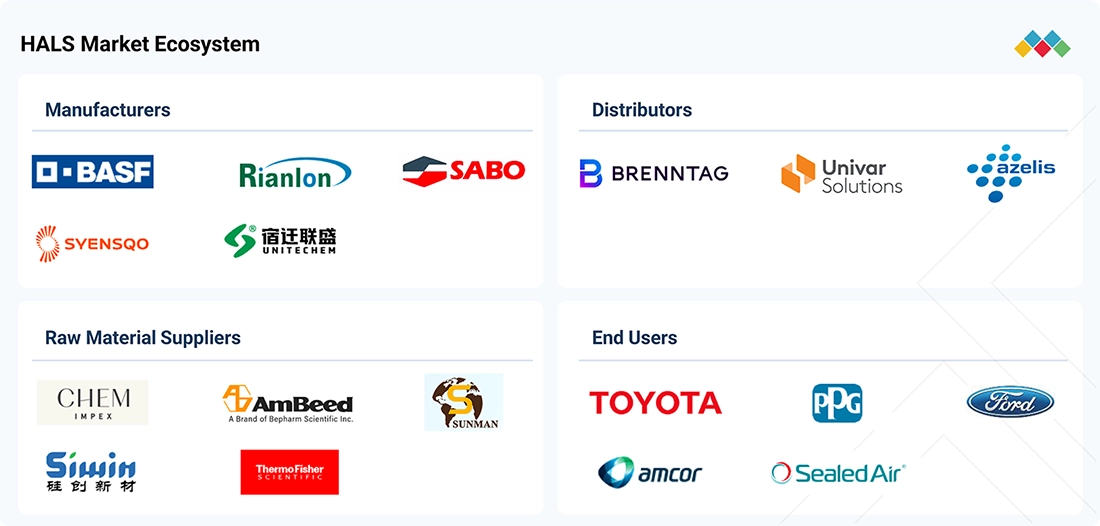
The HALS market ecosystem consists of raw material suppliers (Chem-Impex International, Inc., Thermo Fisher Scientific Inc., Ambeed, Inc., and Nanjing Siwin New Material Co., Ltd.), manufacturers (BASF SE, Rianlon Corporation, SABO S.p.A., Syensqo SA/NV, and Suqian Unitech Corp., Ltd.), and end users (Toyota Motor Corporation, Amcor plc, and PPG Industries, Inc.). Raw materials such as amine intermediates, specialty chemicals, polymer stabilizers, and chemical additives are processed into HALS and customized formulations that offer UV protection, thermal stability, weather resistance, and long-term polymer durability. End users in automotive, packaging, agriculture, building & construction, and consumer products sectors drive demand for high-performance stabilization solutions, while producers ensure consistent formulation and tailored performance. Collaboration across the value chain is crucial for advancing polymer durability, ensuring compliance with regulations, and driving the growth of HALS solutions.

hindered-amine-light-stabilizers-market Ecosystem

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET SEGMENTS

hindered-amine-light-stabilizers-market Segments

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

HALS Market, By Type

The polymeric segment accounted for the largest share of the HALS market, in terms of value, in 2025. Polymeric HALS are increasingly utilized in durable automotive plastic formulations due to their structures, which minimize additive migration. This characteristic helps maintain stabilization within polyolefin and engineering plastic matrices exposed to sunlight and heat. Automotive components, plastic outdoor equipment systems, and molded parts can retain protection for service periods. Formulators favor polymeric grades where surface cleanliness and additive retention are requirements. Growing use of durable plastic articles is expanding demand for polymeric HALS, as manufacturers seek stabilization systems that remain within the polymer matrix and provide consistent protection throughout exposure. Their retention profile supports formulations designed for outdoor applications where additive movement can affect surface quality.

HALS Market, By End-use Industry

The automotive segment accounted for the largest share of the HALS market, in terms of value, in 2025. Rising use of exterior polymer components is supporting HALS demand because these parts face ultraviolet exposure during vehicle service. Bumpers, mirror housings, grilles, body trim, spoilers, and exposed plastic components require protection against light-induced surface changes. HALS help control degradation pathways that can reduce appearance quality and material performance under sunlight. Automotive manufacturers therefore incorporate light stabilization into resin formulations for exterior parts where color retention and surface durability are important specifications. Growth in plastic content across vehicle exteriors is expanding the range of components requiring such protection. Use of molded polymer parts for styling flexibility and weight management is creating demand for HALS in automotive applications.

REGION

Asia Pacific to be fastest-growing region in global HALS market during forecast period

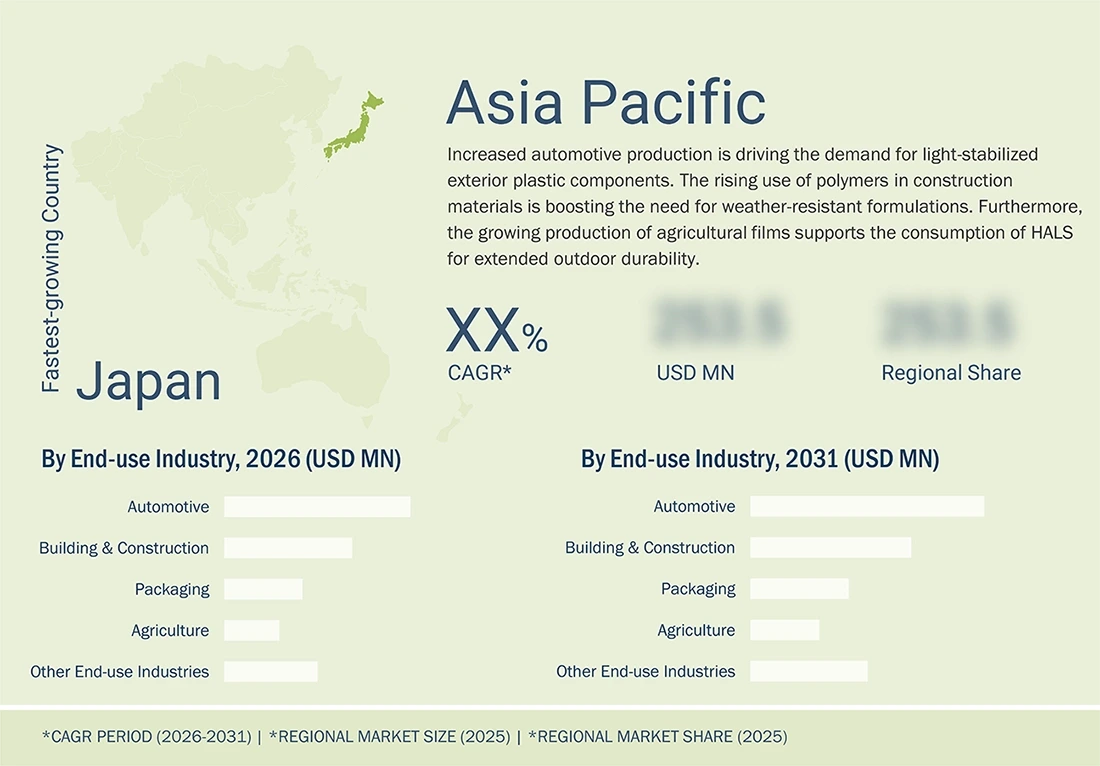
Asia Pacific accounted for the largest share of the HALS market in 2025. The region is also projected to be the fastest-growing regional market during the forecast period. Rapid industrialization across countries in the region is expanding manufacturing capacity for plastics, coatings, packaging, construction materials, agricultural products, and consumer goods. This broad industrial base increases the volume of polymer and coating materials requiring protection from ultraviolet exposure. Rising investment in factories, processing facilities, urban infrastructure, and industrial parks is supporting wider use of durable materials. HALS consumption benefits from this expansion because manufacturers increasingly incorporate light stabilization into products designed for outdoor or extended service. Industrial development across China, India, Southeast Asia, Japan, and South Korea is creating multiple demand centers for stabilization additives. This industrial scale supports sustained HALS demand across diverse manufacturing, polymer, coating, construction, consumer, agricultural, and industrial applications across the regional manufacturing base.

hindered-amine-light-stabilizers-market Region

HINDERED AMINE LIGHT STABILIZERS (HALS) MARKET: COMPANY EVALUATION MATRIX

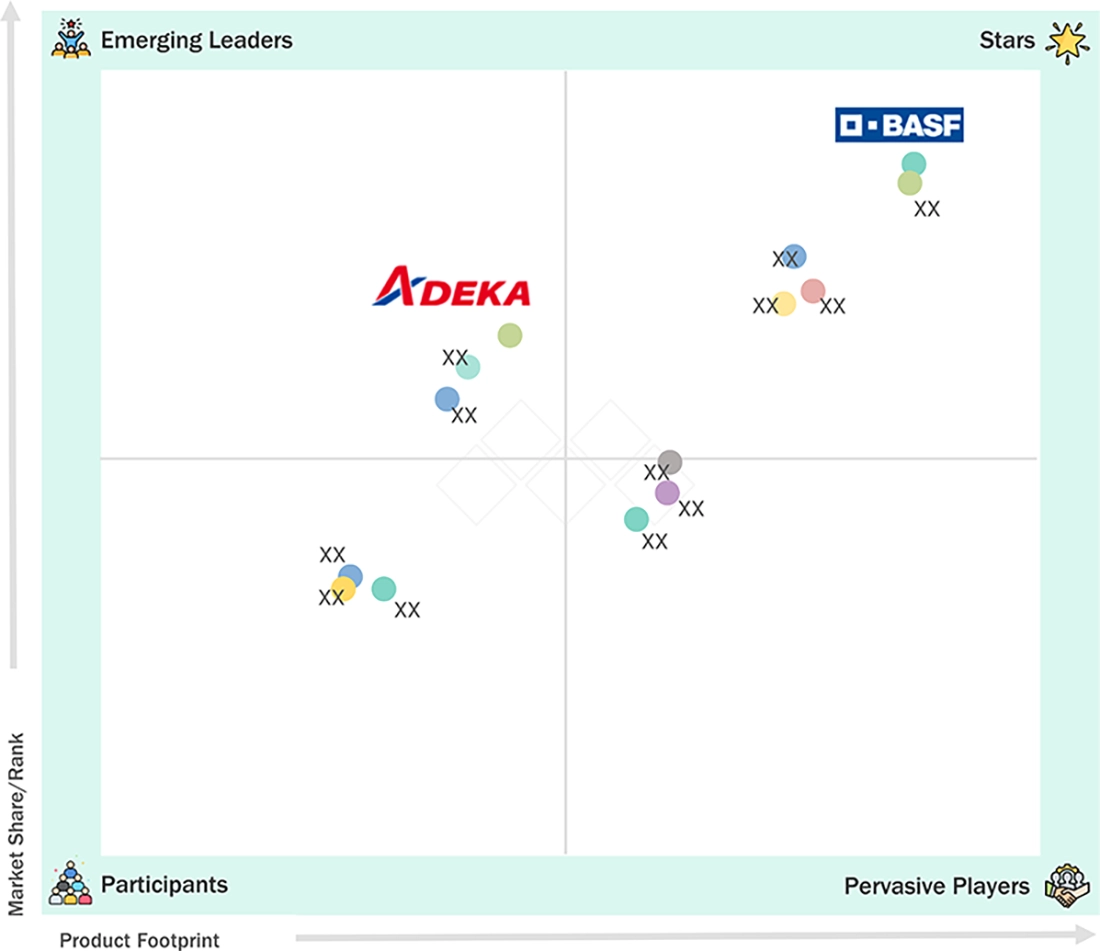
In the HALS market matrix, BASF SE (Star) leads with a strong global market presence and a broad portfolio of light stabilizers, supporting adoption across automotive, packaging, agriculture, and building & construction applications. ADEKA Corporation (Emerging Leader) is gaining traction through its advanced polymer stabilization technologies and HALS solutions designed to improve UV resistance and long-term material durability. While BASF dominates through its extensive product portfolio, global reach, and application expertise, ADEKA demonstrates strong growth potential through specialty additive development, technical capabilities, and focus on high-performance polymer stabilization, positioning it to advance toward the leaders' quadrant.

hindered-amine-light-stabilizers-market Evaluation Metrics

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

KEY MARKET PLAYERS

MARKET SCOPE

REPORT METRIC DETAILS
Market Size in 2025 (Value) USD 1.65 Billion
Market Forecast in 2031 (Value) USD 2.49 Billion
Growth Rate CAGR of 7.11% from 2026 to 2031
Years Considered 2023–2031
Base Year 2025
Forecast Period 2026–2031
Units Considered Value (USD Million/Billion) and Volume (Ton)
Report Coverage Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments Covered
  • By Type:
    • Polymeric
    • Oligomeric
    • Monomeric
  • By End-use Industry:
    • Automotive
    • Packaging
    • Building & Construction
    • Agriculture
    • Other End-use Industries
Regional Scope Asia Pacific, Europe, North America, Middle East & Africa, South America

WHAT IS IN IT FOR YOU: HINDERED AMINE LIGHT STABILIZERS (HALS) MARKET REPORT CONTENT GUIDE

hindered-amine-light-stabilizers-market Content Guide

DELIVERED CUSTOMIZATIONS

We have successfully delivered the following deep-dive customizations:

CLIENT REQUEST CUSTOMIZATION DELIVERED VALUE ADDS
Europe-based HALS Manufacturer
  • Country-level assessment of HALS demand across automotive, packaging, agriculture, and building applications
  • Competitive benchmarking of HALS suppliers based on product grades, stabilization performance, and application coverage
  • Identify high-growth opportunities for HALS product expansion
  • Strengthen portfolio positioning across applications requiring long-term polymer protection
Asia Pacific-based HALS Producer
  • Application-wise analysis of HALS consumption across polymer processing and plastic manufacturing facilities
  • Assessment of production capacity, grade preferences, and customer sourcing patterns across major regional manufacturing hubs
  • Optimize capacity expansion according to application-specific demand
  • Identify strategic partnerships with polymer producers and plastic converters

RECENT DEVELOPMENTS

  • April 2026 : BASF SE announced significant investments to expand production capacities for both standard HALS and NOR HALS products.
  • October 2025 : BASF SE introduced Tinuvin NOR 600, a next-generation NOR-HALS light stabilizer at K 2025.
  • September 2024 : SABO S.p.A. expanded its global footprint with a new US subsidiary, SABO International Americas, in Orlando, Florida, and a distribution center in Savannah, Georgia.
  • July 2023 : SONGWON Industrial Co., Ltd. expanded its reach in Italy by forming an exclusive distribution agreement with Krahn Italia S.p.A. for its coating’s portfolio, which includes antioxidants, UV absorbers, and HALS products.
  • November 2021 : Suqian Unitech Corp., Ltd. started full-scale production of advanced high-performance light stabilizers UniteChem LS2020 and LS119 in newly commissioned facilities.


Table of Contents

checkmarkExclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.

TITLE
PAGE NO
1
INTRODUCTION


22
2
EXECUTIVE SUMMARY


27
3
PREMIUM INSIGHTS


32
4
MARKET OVERVIEW
Explore booming demand and strategic innovations amid challenges in plastics and automotive markets.


35
 
4.1
INTRODUCTION


4.2
MARKET DYNAMICS


4.2.1
DRIVERS


4.2.1.1
RISING MARKET DEMAND IN PLASTICS INDUSTRY


4.2.1.2
TECHNOLOGICAL ADVANCEMENTS


4.2.1.3
EXPANSION OF AUTOMOTIVE INDUSTRY


4.2.2
RESTRAINTS


4.2.2.1
SUPPLY CHAIN DISRUPTIONS AND PRICE VOLATILITY


4.2.2.2
COMPETITION FROM ALTERNATIVE STABILIZATION TECHNOLOGIES


4.2.2.3
HIGH PRODUCTION AND R&D COSTS


4.2.3
OPPORTUNITIES


4.2.3.1
CUSTOMIZED SOLUTIONS FOR SPECIFIC APPLICATIONS


4.2.4
CHALLENGES


4.2.4.1
STRINGENT ENVIRONMENTAL AND REGULATORY COMPLIANCE


4.3
INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES


4.3.1
INTERCONNECTED MARKETS


4.3.2
CROSS-SECTOR OPPORTUNITIES


4.4
STRATEGIC MOVES BY TIER-1/2/3 PLAYERS


4.4.1
KEY MOVES AND STRATEGIC FOCUS


5
INDUSTRY TRENDS
Leverage industry insights to navigate competitive pressures and capitalize on emerging revenue opportunities.


41
 
5.1
PORTER'S FIVE FORCES ANALYSIS


5.1.1
THREAT OF NEW ENTRANTS


5.1.2
THREAT OF SUBSTITUTES


5.1.3
BARGAINING POWER OF SUPPLIERS


5.1.4
BARGAINING POWER OF BUYERS


5.1.5
INTENSITY OF COMPETITIVE RIVALRY


5.2
MACROECONOMIC OUTLOOK


5.2.1
INTRODUCTION


5.2.2
GDP TRENDS AND FORECAST


5.2.3
TRENDS IN AUTOMOTIVE INDUSTRY


5.3
SUPPLY CHAIN ANALYSIS


5.3.1
RAW MATERIALS


5.3.2
MANUFACTURERS


5.3.3
DISTRIBUTION NETWORK


5.3.4
END USERS


5.4
ECOSYSTEM ANALYSIS


5.5
PRICING ANALYSIS


5.5.1
AVERAGE SELLING PRICE OF KEY PLAYERS, BY END-USE INDUSTRY, 2025


5.5.2
AVERAGE SELLING PRICE TREND OF HALS, BY REGION, 2023–2025


5.6
TRADE ANALYSIS


5.6.1
IMPORT SCENARIO (HS CODE 3812)


5.6.2
EXPORT SCENARIO (HS CODE 3812)


5.7
KEY CONFERENCES & EVENTS, 2026–2027


5.8
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS


5.8.1
REVENUE SHIFTS & REVENUE POCKETS FOR HALS MARKET


5.9
INVESTMENT AND FUNDING SCENARIO


5.10
CASE STUDY ANALYSIS


5.10.1
CASE STUDY ON AGRICULTURAL GREENHOUSE FILMS


5.10.2
CASE STUDY ON ENHANCING UV RESISTANCE IN AUTOMOTIVE EXTERIOR COATINGS


5.10.3
CASE STUDY ON ENHANCING UV STABILITY IN INDUSTRIAL PACKAGING


5.11
IMPACT OF 2025 US TARIFF - OVERVIEW


5.11.1
INTRODUCTION


5.11.2
KEY TARIFF RATES


5.11.3
PRICE IMPACT ANALYSIS


5.11.4
IMPACT ON COUNTRIES/REGIONS


5.11.4.1
US


5.11.4.2
EUROPE


5.11.4.3
ASIA PACIFIC


5.11.5
IMPACT ON END-USE INDUSTRIES


6
CUSTOMER LANDSCAPE & BUYER BEHAVIOR
Understand how key stakeholders shape buying decisions and uncover unmet needs across industries.


61
 
6.1
DECISION-MAKING PROCESS


6.2
KEY STAKEHOLDERS AND BUYING CRITERIA


6.2.1
KEY STAKEHOLDERS IN BUYING PROCESS


6.2.2
BUYING CRITERIA


6.3
ADOPTION BARRIERS & INTERNAL CHALLENGES


6.4
UNMET NEEDS IN VARIOUS APPLICATIONS


7
REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
Navigate complex regulations and sustainability initiatives to drive eco-friendly compliance and innovation.


66
 
7.1
REGIONAL REGULATIONS AND COMPLIANCE


7.1.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


7.1.2
INDUSTRY STANDARDS


7.2
SUSTAINABILITY INITIATIVES


7.2.1
RESOURCE AND CARBON IMPACT REDUCTION


7.2.2
ECO-APPLICATION ENABLEMENT


7.3
SUSTAINABILITY IMPACT AND REGULATORY POLICY INITIATIVES


7.4
CERTIFICATIONS, LABELING, AND ECO-STANDARDS


8
TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
AI-driven innovations redefine HALS market with sustainable technologies and strategic patent advancements.


74
 
8.1
KEY EMERGING TECHNOLOGIES


8.1.1
FREE RADICAL SCAVENGING TECHNOLOGY


8.1.2
MOLECULAR STRUCTURE ENGINEERING TECHNOLOGY


8.2
COMPLEMENTARY TECHNOLOGIES


8.2.1
UV ABSORBER TECHNOLOGY


8.3
TECHNOLOGY/PRODUCT ROADMAP


8.3.1
SHORT-TERM (2026–2027) | FORMULATION OPTIMIZATION & PERFORMANCE IMPROVEMENT


8.3.2
MID-TERM (2027–2030) | ADVANCED STABILIZER SYSTEMS & APPLICATION STANDARDIZATION


8.3.3
LONG-TERM (2030–2035+) | NEXT-GENERATION STABILIZERS & SUSTAINABLE MATERIAL INTEGRATION


8.4
PATENT ANALYSIS


8.4.1
APPROACH


8.4.2
DOCUMENT TYPES


8.4.3
TOP APPLICANTS


8.4.4
JURISDICTION ANALYSIS


8.5
IMPACT OF AI/GEN AI ON HALS MARKET


8.5.1
TOP USE CASES AND MARKET POTENTIAL


8.5.2
BEST PRACTICES IN HALS PROCESSING


8.5.3
CASE STUDIES OF AI IMPLEMENTATION IN HALS MARKET


8.5.4
INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS


8.5.5
CLIENTS' READINESS TO ADOPT GENERATIVE AI IN HALS MARKET


9
HINDERED AMINE LIGHT STABILIZERS (HALS)MARKET, BY TYPE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Thousand and Tons | 16 Data Tables


84
 
9.1
INTRODUCTION


9.2
POLYMERIC HALS


9.2.1
NEED FOR ENHANCED MATERIAL DURABILITY IN OUTDOOR APPLICATIONS DRIVES GROWTH


9.3
OLIGOMERIC HALS


9.3.1
VERSATILITY IN POLYMER COMPATIBILITY DRIVES WIDESPREAD ADOPTION OF HALS


9.4
MONOMERIC HALS


9.4.1
SUSTAINED DEMAND FOR COST-EFFECTIVE HALS DRIVES MARKET


10
HINDERED AMINE LIGHT STABILIZERS (HALS) MARKET, BY END-USE INDUSTRY
Market Size & Growth Rate Forecast Analysis to 2031 in USD Thousand and Tons | 24 Data Tables


92
 
10.1
INTRODUCTION


10.2
AUTOMOTIVE


10.2.1
RISING RELIANCE ON POLYMER-BASED MATERIALS IN VEHICLE MANUFACTURING


10.3
BUILDING & CONSTRUCTION


10.3.1
EXPANDING CONSTRUCTION INDUSTRY TO PROPEL MARKET DEMAND


10.4
PACKAGING


10.4.1
GROWING NEED FOR UV PROTECTION AND SUSTAINABLE PACKAGING TO DRIVE MARKET


10.5
AGRICULTURE


10.5.1
MODERN FARMING PRACTICES AND ADVANCED EQUIPMENT TO FUEL MARKET GROWTH


10.6
OTHER END-USE INDUSTRIES


11
HINDERED AMINE LIGHT STABILIZERS (HALS) MARKET, BY REGION
Comprehensive coverage of 7 Regions with country-level deep-dive of 19 Countries | 140 Data Tables.


104
 
11.1
INTRODUCTION


11.2
ASIA PACIFIC


11.2.1
CHINA


11.2.1.1
GROWING INDUSTRIAL ACTIVITIES TO DRIVE MARKET


11.2.2
INDIA


11.2.2.1
RAPID INDUSTRIALIZATION TO DRIVE MARKET


11.2.3
JAPAN


11.2.3.1
EMPHASIS ON LONG-LASTING POLYMER PERFORMANCE TO STRENGTHEN DEMAND


11.2.4
SOUTH KOREA


11.2.4.1
ADVANCING AUTOMOTIVE MATERIAL TECHNOLOGY TO ACCELERATE GROWTH


11.2.5
THAILAND


11.2.5.1
EXPANSION OF ELECTRIC VEHICLE COMPONENT MANUFACTURING TO BOOST DEMAND


11.2.6
MALAYSIA


11.2.6.1
RISING PRODUCTION OF OUTDOOR PLASTIC PRODUCTS TO EXPAND MARKET


11.3
NORTH AMERICA


11.3.1
US


11.3.1.1
STRONG INDUSTRIAL INFRASTRUCTURE TO DRIVE MARKET


11.3.2
CANADA


11.3.2.1
DEMAND FOR DURABLE MATERIALS ACCOMPANIED BY CEPA REGULATIONS


11.3.3
MEXICO


11.3.3.1
GROWING MANUFACTURING CAPABILITIES


11.4
EUROPE


11.4.1
GERMANY


11.4.1.1
STRONG AUTOMOTIVE SECTOR TO ACCELERATE MARKET GROWTH


11.4.2
FRANCE


11.4.2.1
INCREASING RENOVATION ACTIVITY TO FOSTER MARKET EXPANSION


11.4.3
SPAIN


11.4.3.1
EXPANSION OF PROTECTED AGRICULTURE TO STIMULATE MARKET GROWTH


11.4.4
ITALY


11.4.4.1
GROWTH OF OUTDOOR FURNITURE MANUFACTURING TO CREATE OPPORTUNITIES


11.4.5
UK


11.4.5.1
GREATER ADOPTION OF WEATHER-RESISTANT INFRASTRUCTURE MATERIALS TO FUEL DEMAND


11.4.6
TURKEY


11.4.6.1
INCREASING USE OF DURABLE PLASTIC PRODUCTS TO BROADEN DEMAND


11.5
MIDDLE EAST & AFRICA


11.5.1
SAUDI ARABIA


11.5.1.1
EXPANSION OF CONSTRUCTION PROJECTS TO PROPEL DEMAND


11.5.2
UAE


11.5.2.1
EXPANSION OF LOCAL PLASTICS MANUFACTURING TO DRIVE MARKET


11.5.3
SOUTH AFRICA


11.5.3.1
INCREASING USE OF AGRICULTURAL PLASTICS TO BOOST MARKET GROWTH


11.6
SOUTH AMERICA


11.6.1
BRAZIL


11.6.1.1
ECONOMIC MOMENTUM TO PROPEL MARKET GROWTH


12
COMPETITIVE LANDSCAPE
Uncover strategic moves and market dominance shaping the competitive landscape through 2026.


162
 
12.1
INTRODUCTION


12.2
KEY PLAYER STRATEGIES/RIGHT TO WIN, JANUARY 2021–JULY 2026


12.2.1
STRATEGIES ADOPTED BY KEY HALS MANUFACTURERS, JANUARY 2021–JULY 2026


12.3
MARKET SHARE ANALYSIS, 2025


12.4
REVENUE ANALYSIS, 2023–2025


12.5
COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025


12.5.1
STARS


12.5.2
EMERGING LEADERS


12.5.3
PERVASIVE PLAYERS


12.5.4
PARTICIPANTS


12.5.5
COMPANY FOOTPRINT: KEY PLAYERS, 2025


12.5.5.1
COMPANY FOOTPRINT


12.5.5.2
REGION FOOTPRINT


12.5.5.3
TYPE FOOTPRINT


12.5.5.4
END-USE INDUSTRY FOOTPRINT


12.6
COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025


12.6.1
PROGRESSIVE COMPANIES


12.6.2
RESPONSIVE COMPANIES


12.6.3
DYNAMIC COMPANIES


12.6.4
STARTING BLOCKS


12.6.5
COMPETITIVE BENCHMARKING: STARTUPS/SMES


12.6.5.1
DETAILED LIST OF KEY STARTUPS/SMES


12.6.5.2
COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES


12.7
BRAND/PRODUCT COMPARISON ANALYSIS


12.8
COMPANY VALUATION AND FINANCIAL METRICS


12.9
COMPETITIVE SCENARIO


12.9.1
PRODUCT LAUNCHES


12.9.2
DEALS


12.9.3
EXPANSIONS


12.9.4
OTHER DEVELOPMENTS


13
COMPANY PROFILES
In-depth Company Profiles of Leading Market Players with detailed Business Overview, Product and Service Portfolio, Recent Developments, and Unique Analyst Perspective (MnM View)


181
 
13.1
KEY PLAYERS


13.1.1
BASF SE


13.1.1.1
BUSINESS OVERVIEW


13.1.1.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


13.1.1.3
RECENT DEVELOPMENTS


13.1.1.3.1
PRODUCT LAUNCHES


13.1.1.3.2
EXPANSIONS


13.1.1.4
OTHER DEVELOPMENTS


13.1.1.5
STRATEGIC INTELLIGENCE


13.1.1.5.1
FINANCIAL STRATEGY


13.1.1.5.2
OPERATIONAL STRATEGY


13.1.1.5.3
MARKET EXPANSION STRATEGY


13.1.1.5.4
STRATEGIC DNA


13.1.1.6
MNM VIEW


13.1.1.6.1
KEY STRENGTHS


13.1.1.6.2
STRATEGIC CHOICES


13.1.1.6.3
WEAKNESSES/COMPETITIVE THREATS


13.1.2
RIANLON CORPORATION


13.1.3
SABO S.P.A.


13.1.4
SYENSQO SA/NV


13.1.5
SUQIAN UNITECH CORP., LTD.


13.1.6
ADEKA CORPORATION


13.1.7
ARKEMA S.A.


13.1.8
SONGWON INDUSTRIAL CO., LTD.


13.1.9
CLARIANT AG


13.1.10
EVERLIGHT CHEMICAL INDUSTRIAL CORPORATION


13.1.11
SI GROUP, INC.


13.1.12
BEIJING TIANGANG AUXILIARY CO., LTD


13.2
OTHER PLAYERS


13.2.1
YUANLI CHEMICAL GROUP CO., LTD.


13.2.2
3V SIGMA S.P.A.


13.2.3
CHEMIPRO KASEI


13.2.4
FUJIAN DISHENG TECHNOLOGY CO., LTD.


13.2.5
EVERSPRING CHEMICAL CO., LTD.


13.2.6
DOUBLE BOND CHEMICAL IND. CO., LTD.


13.2.7
GREENCHEMICALS S.R.L.


13.2.8
CHITEC TECHNOLOGY CO., LTD.


13.2.9
RICHYU CHEMICAL CO


13.2.10
ALFA CHEMISTRY


13.2.11
MAYZO, INC.


13.2.12
EUTEC CHEMICAL CO., LTD.


13.2.13
TINTOLL PERFORMANCE MATERIALS CO., LTD.


13.2.14
QINGDAO JADE NEW MATERIAL TECHNOLOGY CO., LTD


13.2.15
MPI CHEMIE BV


13.2.16
SU QIAN CITY ZHENXING CHEMICAL., LTD


14
RESEARCH METHODOLOGY


233
 
14.1
RESEARCH DATA


14.1.1
SECONDARY DATA


14.1.1.1
KEY DATA FROM SECONDARY SOURCES


14.1.2
PRIMARY DATA


14.1.2.1
KEY DATA FROM PRIMARY SOURCES


14.1.2.2
PRIMARY INTERVIEW – DEMAND SIDE AND SUPPLY SIDE


14.1.2.3
BREAKDOWN OF PRIMARY INTERVIEWS


14.1.2.4
KEY INDUSTRY INSIGHTS


14.2
MARKET SIZE ESTIMATION


14.2.1
BOTTOM-UP APPROACH


14.2.2
TOP-DOWN APPROACH


14.3
GROWTH FORECAST


14.3.1
SUPPLY SIDE


14.3.2
DEMAND SIDE


14.4
DATA TRIANGULATION


14.5
FACTOR ANALYSIS


14.6
RESEARCH ASSUMPTIONS


14.7
RESEARCH LIMITATIONS


14.8
RISK ASSESSMENT


15
APPENDIX


245
 
15.1
DISCUSSION GUIDE


15.2
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL


15.3
CUSTOMIZATION OPTIONS


15.4
RELATED REPORTS


15.5
AUTHOR DETAILS


LIST OF TABLES


TABLE 1
HALS MARKET: PORTER’S FIVE FORCES ANALYSIS


TABLE 2
GDP TRENDS AND FORECAST OF MAJOR ECONOMIES, 2021–2031 (USD BILLION)


TABLE 3
HALS MARKET: ROLE OF COMPANIES IN ECOSYSTEM


TABLE 4
AVERAGE SELLING PRICE OF KEY PLAYERS FOR END-USE INDUSTRIES, 2025 (USD/KG)


TABLE 5
AVERAGE SELLING PRICE TREND OF HALS, BY REGION, 2023–2025 (USD/KG)


TABLE 6
IMPORT DATA FOR HALS, BY REGION, 2020–2025 (USD MILLION)


TABLE 7
EXPORT DATA FOR HALS, BY REGION, 2020–2025 (USD MILLION)


TABLE 8
HALS MARKET: LIST OF CONFERENCES & EVENTS, 2026-2027


TABLE 9
HALS MARKET: FUNDING/INVESTMENT SCENARIO, 2021–2026


TABLE 10
US ADJUSTED RECIPROCAL TARIFF RATES


TABLE 11
IMPACT OF STAKEHOLDERS ON BUYING PROCESS FOR TOP THREE END-USE INDUSTRIES (%)


TABLE 12
KEY BUYING CRITERIA FOR TOP THREE END-USE INDUSTRIES


TABLE 13
HALS MARKET: UNMET NEEDS IN KEY END-USE INDUSTRIES


TABLE 14
GLOBAL: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 15
NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 16
EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 17
ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 18
MIDDLE EAST & AFRICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 19
CERTIFICATIONS, LABELING, AND ECO-STANDARDS IN HALS MARKET


TABLE 20
PATENT COUNT: HALS MARKET


TABLE 21
LIST OF MAJOR PATENTS RELATED TO HALS MARKET, 2015–2025


TABLE 22
TOP USE CASES AND MARKET POTENTIAL


TABLE 23
BEST PRACTICES: COMPANIES IMPLEMENTING USE CASES


TABLE 24
HALS MARKET: CASE STUDIES RELATED TO GEN AI IMPLEMENTATION


TABLE 25
INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS


TABLE 26
HALS MARKET, BY TYPE, 2023–2025 (USD THOUSAND)


TABLE 27
HALS MARKET, BY TYPE, 2026–2031 (USD THOUSAND)


TABLE 28
HALS MARKET, BY TYPE, 2023–2025 (TON)


TABLE 29
HALS MARKET, BY TYPE, 2026–2031 (TON)


TABLE 30
POLYMERIC: HALS MARKET, BY REGION, 2023–2025 (USD THOUSAND)


TABLE 31
POLYMERIC: HALS MARKET, BY REGION, 2026–2031 (USD THOUSAND)


TABLE 32
POLYMERIC: HALS MARKET, BY REGION, 2023–2025 (TON)


TABLE 33
POLYMERIC: HALS MARKET, BY REGION, 2026–2031 (TON)


TABLE 34
OLIGOMERIC: HALS MARKET, BY REGION, 2023–2025 (USD THOUSAND)


TABLE 35
OLIGOMERIC: HALS MARKET, BY REGION, 2026–2031 (USD THOUSAND)


TABLE 36
OLIGOMERIC: HALS MARKET, BY REGION, 2023–2025 (TON)


TABLE 37
OLIGOMERIC: HALS MARKET, BY REGION, 2026–2031 (TON)


TABLE 38
MONOMERIC: HALS MARKET, BY REGION, 2023–2025 (USD THOUSAND)


TABLE 39
MONOMERIC: HALS MARKET, BY REGION, 2026–2031 (USD THOUSAND)


TABLE 40
MONOMERIC: HALS MARKET, BY REGION, 2023–2025 (TON)


TABLE 41
MONOMERIC: HALS MARKET, BY REGION, 2026–2031 (TON)


TABLE 42
HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 43
HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 44
HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 45
HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 46
AUTOMOTIVE: HALS MARKET, BY REGION, 2023–2025 (USD THOUSAND)


TABLE 47
AUTOMOTIVE: HALS MARKET, BY REGION, 2026–2031 (USD THOUSAND)


TABLE 48
AUTOMOTIVE: HALS MARKET, BY REGION, 2023–2025 (TON)


TABLE 49
AUTOMOTIVE: HALS MARKET, BY REGION, 2026–2031 (TON)


TABLE 50
BUILDING & CONSTRUCTION: HALS MARKET, BY REGION, 2023–2025 (USD THOUSAND)


TABLE 51
BUILDING & CONSTRUCTION: HALS MARKET, BY REGION, 2026–2031 (USD THOUSAND)


TABLE 52
BUILDING & CONSTRUCTION: HALS MARKET, BY REGION, 2023–2025 (TON)


TABLE 53
BUILDING & CONSTRUCTION: HALS MARKET, BY REGION, 2026–2031 (TON)


TABLE 54
PACKAGING: HALS MARKET, BY REGION, 2023–2025 (USD THOUSAND)


TABLE 55
PACKAGING: HALS MARKET, BY REGION, 2026–2031 (USD THOUSAND)


TABLE 56
PACKAGING: HALS MARKET, BY REGION, 2023–2025 (TON)


TABLE 57
PACKAGING: HALS MARKET, BY REGION, 2026–2031 (TON)


TABLE 58
AGRICULTURE: HALS MARKET, BY REGION, 2023–2025 (USD THOUSAND)


TABLE 59
AGRICULTURE: HALS MARKET, BY REGION, 2026–2031 (USD THOUSAND)


TABLE 60
AGRICULTURE: HALS MARKET, BY REGION, 2023–2025 (TON)


TABLE 61
AGRICULTURE: HALS MARKET, BY REGION, 2026–2031 (TON)


TABLE 62
OTHER END-USE INDUSTRIES: HALS MARKET, BY REGION, 2023–2025 (USD THOUSAND)


TABLE 63
OTHER END-USE INDUSTRIES: HALS MARKET, BY REGION, 2026–2031 (USD THOUSAND)


TABLE 64
OTHER END-USE INDUSTRIES: HALS MARKET, BY REGION, 2023–2025 (TON)


TABLE 65
OTHER END-USE INDUSTRIES: HALS MARKET, BY REGION, 2026–2031 (TON)


TABLE 66
HALS MARKET, BY REGION, 2023–2025 (USD THOUSAND)


TABLE 67
HALS MARKET, BY REGION, 2026–2031 (USD THOUSAND)


TABLE 68
HALS MARKET, BY REGION, 2023–2025 (TON)


TABLE 69
HALS MARKET, BY REGION, 2026–2031 (TON)


TABLE 70
ASIA PACIFIC: HALS MARKET, BY TYPE, 2023–2025 (USD THOUSAND)


TABLE 71
ASIA PACIFIC: HALS MARKET, BY TYPE, 2026–2031 (USD THOUSAND)


TABLE 72
ASIA PACIFIC: HALS MARKET, BY TYPE, 2023–2025 (TON)


TABLE 73
ASIA PACIFIC: HALS MARKET, BY TYPE, 2026–2031 (TON)


TABLE 74
ASIA PACIFIC: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 75
ASIA PACIFIC: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 76
ASIA PACIFIC: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 77
ASIA PACIFIC: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 78
ASIA PACIFIC: HALS MARKET, BY COUNTRY, 2023–2025 (USD THOUSAND)


TABLE 79
ASIA PACIFIC: HALS MARKET, BY COUNTRY, 2026–2031 (USD THOUSAND)


TABLE 80
ASIA PACIFIC: HALS MARKET, BY COUNTRY, 2023–2025 (TON)


TABLE 81
ASIA PACIFIC: HALS MARKET, BY COUNTRY, 2026–2031 (TON)


TABLE 82
CHINA: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 83
CHINA: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 84
CHINA: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 85
CHINA: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 86
INDIA: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 87
INDIA: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 88
INDIA: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 89
INDIA: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 90
JAPAN: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 91
JAPAN: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 92
JAPAN: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 93
JAPAN: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 94
SOUTH KOREA: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 95
SOUTH KOREA: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 96
SOUTH KOREA: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 97
SOUTH KOREA: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 98
THAILAND: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 99
THAILAND: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 100
THAILAND: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 101
THAILAND: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 102
MALAYSIA: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 103
MALAYSIA: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 104
MALAYSIA: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 105
MALAYSIA: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 106
NORTH AMERICA: HALS MARKET, BY TYPE, 2023–2025 (USD THOUSAND)


TABLE 107
NORTH AMERICA: HALS MARKET, BY TYPE, 2026–2031 (USD THOUSAND)


TABLE 108
NORTH AMERICA: HALS MARKET, BY TYPE, 2023–2025 (TON)


TABLE 109
NORTH AMERICA: HALS MARKET, BY TYPE, 2026–2031 (TON)


TABLE 110
NORTH AMERICA: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 111
NORTH AMERICA: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 112
NORTH AMERICA: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 113
NORTH AMERICA: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 114
NORTH AMERICA: HALS MARKET, BY COUNTRY, 2023–2025 (USD THOUSAND)


TABLE 115
NORTH AMERICA: HALS MARKET, BY COUNTRY, 2026–2031 (USD THOUSAND)


TABLE 116
NORTH AMERICA: HALS MARKET, BY COUNTRY, 2023–2025 (TON)


TABLE 117
NORTH AMERICA: HALS MARKET, BY COUNTRY, 2026–2031 (TON)


TABLE 118
US: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 119
US: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 120
US: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 121
US: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 122
CANADA: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 123
CANADA: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 124
CANADA: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 125
CANADA: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 126
MEXICO: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 127
MEXICO: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 128
MEXICO: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 129
MEXICO: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 130
EUROPE: HALS MARKET, BY TYPE, 2023–2025 (USD THOUSAND)


TABLE 131
EUROPE: HALS MARKET, BY TYPE, 2026–2031 (USD THOUSAND)


TABLE 132
EUROPE: HALS MARKET, BY TYPE, 2023–2025 (TON)


TABLE 133
EUROPE: HALS MARKET, BY TYPE, 2026–2031 (TON)


TABLE 134
EUROPE: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 135
EUROPE: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 136
EUROPE: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 137
EUROPE: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 138
EUROPE: HALS MARKET, BY COUNTRY, 2023–2025 (USD THOUSAND)


TABLE 139
EUROPE: HALS MARKET, BY COUNTRY, 2026–2031 (USD THOUSAND)


TABLE 140
EUROPE: HALS MARKET, BY COUNTRY, 2023–2025 (TON)


TABLE 141
EUROPE: HALS MARKET, BY COUNTRY, 2026–2031 (TON)


TABLE 142
GERMANY: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 143
GERMANY: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 144
GERMANY: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 145
GERMANY: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 146
FRANCE: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 147
FRANCE: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 148
FRANCE: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 149
FRANCE: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 150
SPAIN: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 151
SPAIN: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 152
SPAIN: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 153
SPAIN: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 154
ITALY: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 155
ITALY: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 156
ITALY: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 157
ITALY: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 158
UK: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 159
UK: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 160
UK: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 161
UK: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 162
TURKEY: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 163
TURKEY: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 164
TURKEY: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 165
TURKEY: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 166
MIDDLE EAST & AFRICA: HALS MARKET, BY TYPE, 2023–2025 (USD THOUSAND)


TABLE 167
MIDDLE EAST & AFRICA: HALS MARKET, BY TYPE, 2026–2031 (USD THOUSAND)


TABLE 168
MIDDLE EAST & AFRICA: HALS MARKET, BY TYPE, 2023–2025 (TON)


TABLE 169
MIDDLE EAST & AFRICA: HALS MARKET, BY TYPE, 2026–2031 (TON)


TABLE 170
MIDDLE EAST & AFRICA: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 171
MIDDLE EAST & AFRICA: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 172
MIDDLE EAST & AFRICA: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 173
MIDDLE EAST & AFRICA: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 174
MIDDLE EAST & AFRICA: HALS MARKET, BY COUNTRY, 2023–2025 (USD THOUSAND)


TABLE 175
MIDDLE EAST & AFRICA: HALS MARKET, BY COUNTRY, 2026–2031 (USD THOUSAND)


TABLE 176
MIDDLE EAST & AFRICA: HALS MARKET, BY COUNTRY, 2023–2025 (TON)


TABLE 177
MIDDLE EAST & AFRICA: HALS MARKET, BY COUNTRY, 2026–2031 (TON)


TABLE 178
SAUDI ARABIA: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 179
SAUDI ARABIA: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 180
SAUDI ARABIA: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 181
SAUDI ARABIA: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 182
UAE: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 183
UAE: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 184
UAE: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 185
UAE: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 186
SOUTH AFRICA: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 187
SOUTH AFRICA: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 188
SOUTH AFRICA: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 189
SOUTH AFRICA: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 190
SOUTH AMERICA: HALS MARKET, BY TYPE, 2023–2025 (USD THOUSAND)


TABLE 191
SOUTH AMERICA: HALS MARKET, BY TYPE, 2026–2031 (USD THOUSAND)


TABLE 192
SOUTH AMERICA: HALS MARKET, BY TYPE, 2023–2025 (TON)


TABLE 193
SOUTH AMERICA: HALS MARKET, BY TYPE, 2026–2031 (TON)


TABLE 194
SOUTH AMERICA: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 195
SOUTH AMERICA: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 196
SOUTH AMERICA: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 197
SOUTH AMERICA: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 198
SOUTH AMERICA: HALS MARKET, BY COUNTRY, 2023–2025 (USD THOUSAND)


TABLE 199
SOUTH AMERICA: HALS MARKET, BY COUNTRY, 2026–2031 (USD THOUSAND)


TABLE 200
SOUTH AMERICA: HALS MARKET, BY COUNTRY, 2023–2025 (TON)


TABLE 201
SOUTH AMERICA: HALS MARKET, BY COUNTRY, 2026–2031 (TON)


TABLE 202
BRAZIL: HALS MARKET, BY END-USE INDUSTRY, 2023–2025 (USD THOUSAND)


TABLE 203
BRAZIL: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (USD THOUSAND)


TABLE 204
BRAZIL: HALLS MARKET, BY END-USE INDUSTRY, 2023–2025 (TON)


TABLE 205
BRAZIL: HALS MARKET, BY END-USE INDUSTRY, 2026–2031 (TON)


TABLE 206
HALS MARKET: DEGREE OF COMPETITION


TABLE 207
HALS MARKET: REGION FOOTPRINT


TABLE 208
HALS MARKET: TYPE FOOTPRINT


TABLE 209
HALS MARKET: END-USE INDUSTRY FOOTPRINT


TABLE 210
HALS MARKET: DETAILED LIST OF KEY STARTUPS/SMES


TABLE 211
HALS MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES


TABLE 212
HALS MARKET: PRODUCT LAUNCHES, JANUARY 2021–JULY 2026


TABLE 213
HALS MARKET: DEALS, JANUARY 2021–JULY 2026


TABLE 214
HALS MARKET: EXPANSIONS, JANUARY 2021–JULY 2026


TABLE 215
HALS MARKET: OTHER DEVELOPMENTS, JANUARY 2021–JULY 2026


TABLE 216
BASF SE: COMPANY OVERVIEW


TABLE 217
BASF SE: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 218
BASF SE: PRODUCT LAUNCHES


TABLE 219
BASF SE: EXPANSIONS


TABLE 220
BASF SE: OTHER DEVELOPMENTS


TABLE 221
RIANLON CORPORATION: COMPANY OVERVIEW


TABLE 222
RIANLON CORPORATION: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 223
SABO S.P.A.: COMPANY OVERVIEW


TABLE 224
SABO S.P.A.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 225
SABO S.P.A.: DEALS


TABLE 226
SABO S.P.A.: EXPANSIONS


TABLE 227
SYENSQO SA/NV: COMPANY OVERVIEW


TABLE 228
SYENSQO SA/NV: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 229
SUQIAN UNITECH CORP., LTD.: COMPANY OVERVIEW


TABLE 230
SUQIAN UNITECH CORP., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 231
SUQIAN UNITECH CORP., LTD.: EXPANSIONS


TABLE 232
ADEKA CORPORATION: COMPANY OVERVIEW


TABLE 233
ADEKA CORPORATION: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 234
ARKEMA S.A.: COMPANY OVERVIEW


TABLE 235
ARKEMA S.A.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 236
SONGWON INDUSTRIAL CO., LTD.: COMPANY OVERVIEW


TABLE 237
SONGWON INDUSTRIAL CO., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 238
SONGWON INDUSTRIAL CO., LTD.: DEALS


TABLE 239
CLARIANT AG: COMPANY OVERVIEW


TABLE 240
CLARIANT AG: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 241
CLARIANT AG: EXPANSIONS


TABLE 242
EVERLIGHT CHEMICAL INDUSTRIAL CORPORATION: COMPANY OVERVIEW


TABLE 243
EVERLIGHT CHEMICAL INDUSTRIAL CORPORATION: PRODUCTS/SOLUTIONS/ SERVICES OFFERED


TABLE 244
SI GROUP, INC.: COMPANY OVERVIEW


TABLE 245
SI GROUP, INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 246
BEIJING TIANGANG AUXILIARY CO., LTD: COMPANY OVERVIEW


TABLE 247
BEIJING TIANGANG AUXILIARY CO., LTD: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 248
YUANLI CHEMICAL GROUP CO., LTD.: COMPANY OVERVIEW


TABLE 249
3V SIGMA S.P.A.: COMPANY OVERVIEW


TABLE 250
CHEMIPRO KASEI: COMPANY OVERVIEW


TABLE 251
FUJIAN DISHENG TECHNOLOGY CO., LTD.: COMPANY OVERVIEW


TABLE 252
EVERSPRING CHEMICAL CO., LTD.: COMPANY OVERVIEW


TABLE 253
DOUBLE BOND CHEMICAL IND. CO., LTD.: COMPANY OVERVIEW


TABLE 254
GREENCHEMICALS S.R.L.: COMPANY OVERVIEW


TABLE 255
CHITEC TECHNOLOGY CO., LTD.: COMPANY OVERVIEW


TABLE 256
RICHYU CHEMICAL CO: COMPANY OVERVIEW


TABLE 257
ALFA CHEMISTRY: COMPANY OVERVIEW


TABLE 258
MAYZO, INC.: COMPANY OVERVIEW


TABLE 259
EUTEC CHEMICAL CO., LTD.: COMPANY OVERVIEW


TABLE 260
TINTOLL PERFORMANCE MATERIALS CO., LTD.: COMPANY OVERVIEW


TABLE 261
QINGDAO JADE NEW MATERIAL TECHNOLOGY CO., LTD: COMPANY OVERVIEW


TABLE 262
MPI CHEMIE BV: COMPANY OVERVIEW


TABLE 263
SU QIAN CITY ZHENXING CHEMICAL., LTD: COMPANY OVERVIEW


TABLE 264
HALS MARKET: RISK ASSESSMENT


LIST OF FIGURES


FIGURE 1
HALS MARKET SEGMENTATION AND REGIONAL SCOPE


FIGURE 2
KEY INSIGHTS AND MARKET HIGHLIGHTS


FIGURE 3
GLOBAL HALS MARKET, 2023–2031


FIGURE 4
MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN HALS MARKET (2023–2025)


FIGURE 5
DISRUPTIONS INFLUENCING GROWTH OF HALS MARKET


FIGURE 6
HIGH-GROWTH SEGMENTS AND EMERGING FRONTIERS IN HALS MARKET, 2026–2031


FIGURE 7
ASIA PACIFIC TO REGISTER HIGHEST GROWTH DURING FORECAST PERIOD


FIGURE 8
RAPID URBANIZATION TO CREATE LUCRATIVE OPPORTUNITIES FOR MARKET PLAYERS


FIGURE 9
AUTOMOTIVE AND ASIA PACIFIC ACCOUNTED FOR LARGEST MARKET SHARE IN 2025


FIGURE 10
POLYMERIC HALS SEGMENT DOMINATED HALS MARKET IN 2025


FIGURE 11
JAPAN TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD


FIGURE 12
DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES IN HALS MARKET


FIGURE 13
HALS MARKET: PORTER’S FIVE FORCES ANALYSIS


FIGURE 14
HALS: SUPPLY CHAIN ANALYSIS


FIGURE 15
HALS MARKET: KEY PARTICIPANTS IN ECOSYSTEM


FIGURE 16
HALS MARKET: ECOSYSTEM ANALYSIS


FIGURE 17
AVERAGE SELLING PRICE OF KEY PLAYERS FOR TOP END-USE INDUSTRIES, 2025


FIGURE 18
AVERAGE SELLING PRICE TREND OF HALS, BY REGION, 2023–2025


FIGURE 19
IMPORT DATA FOR HALS, BY KEY COUNTRY, 2020–2025


FIGURE 20
EXPORT DATA FOR HALS, BY KEY COUNTRY, 2020–2025


FIGURE 21
REVENUE SHIFT & REVENUE POCKETS IN HALS MARKET


FIGURE 22
HALS MARKET: DECISION-MAKING FACTORS


FIGURE 23
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP THREE END-USE INDUSTRIES


FIGURE 24
KEY BUYING CRITERIA FOR TOP THREE END-USE INDUSTRIES


FIGURE 25
ADOPTION BARRIERS & INTERNAL CHALLENGES


FIGURE 26
PATENTS REGISTERED IN HALS MARKET, 2015–2025


FIGURE 27
MAJOR PATENT OWNERS OF HALS MARKET, 2015–2025


FIGURE 28
LEGAL STATUS OF PATENTS FILED FOR HALS


FIGURE 29
MAXIMUM PATENTS FILED IN US JURISDICTION, 2015–2025


FIGURE 30
IMPACT OF AI/GEN AI ON HALS MARKET


FIGURE 31
POLYMERIC HALS TO BE LARGEST TYPE SEGMENT DURING FORECAST PERIOD


FIGURE 32
AUTOMOTIVE SEGMENT TO ACCOUNT FOR LARGEST SHARE IN HALS MARKET DURING FORECAST PERIOD


FIGURE 33
ASIA PACIFIC TO BE FASTEST-GROWING REGION IN HALS MARKET DURING FORECAST PERIOD


FIGURE 34
ASIA PACIFIC: HALS MARKET SNAPSHOT


FIGURE 35
NORTH AMERICA: HALS MARKET SNAPSHOT


FIGURE 36
EUROPE: HALS MARKET SNAPSHOT


FIGURE 37
HALS MARKET SHARE ANALYSIS, 2025


FIGURE 38
HALS MARKET: REVENUE ANALYSIS OF KEY PLAYERS, 2023–2025


FIGURE 39
HALS MARKET: COMPANY EVALUATION MATRIX, KEY PLAYERS, 2025


FIGURE 40
HALS MARKET: COMPANY FOOTPRINT


FIGURE 41
HALS MARKET: COMPANY EVALUATION MATRIX, STARTUPS/SMES, 2025


FIGURE 42
HALS MARKET: BRAND/PRODUCT COMPARISON (1/2)


FIGURE 43
HALS MARKET: BRAND/PRODUCT COMPARISON (2/2)


FIGURE 44
HALS MARKET: EV/EBITDA OF KEY MANUFACTURERS


FIGURE 45
HALS MARKET: ENTERPRISE VALUATION OF KEY PLAYERS


FIGURE 46
BASF SE: COMPANY SNAPSHOT


FIGURE 47
SYENSQO SA/NV: COMPANY SNAPSHOT


FIGURE 48
ADEKA CORPORATION: COMPANY SNAPSHOT


FIGURE 49
ARKEMA S.A.: COMPANY SNAPSHOT


FIGURE 50
SONGWON INDUSTRIAL CO., LTD.: COMPANY SNAPSHOT


FIGURE 51
CLARIANT AG: COMPANY SNAPSHOT


FIGURE 52
EVERLIGHT CHEMICAL INDUSTRIAL CORPORATION: COMPANY SNAPSHOT


FIGURE 53
HALS MARKET: RESEARCH DESIGN


FIGURE 54
MARKET SIZE ESTIMATION METHODOLOGY – APPROACH 1 (SUPPLY SIDE): COLLECTIVE REVENUE AND SHARE OF MAJOR PLAYERS


FIGURE 55
MARKET SIZE ESTIMATION METHODOLOGY: APPROACH 2 BOTTOM-UP (SUPPLY SIDE): COLLECTIVE REVENUE OF ALL PRODUCTS


FIGURE 56
MARKET SIZE ESTIMATION METHODOLOGY - APPROACH 3 – BOTTOM-UP (DEMAND SIDE)


FIGURE 57
HALS MARKET: TOP-DOWN APPROACH


FIGURE 58
MARKET CAGR PROJECTIONS FROM SUPPLY SIDE


FIGURE 59
MARKET GROWTH PROJECTIONS FROM DEMAND SIDE: DRIVERS AND OPPORTUNITIES


FIGURE 60
HALS MARKET: DATA TRIANGULATION


Methodology

This study involved four major activities in estimating the market size for HALS. Exhaustive secondary research was conducted to collect information on the market, the peer market, and the parent market. The next step involved validating these findings, assumptions, and sizing with industry experts across the value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the complete market size. After that, the market breakdown and data triangulation procedures were used to estimate the market size of the segments and subsegments.

Secondary Research

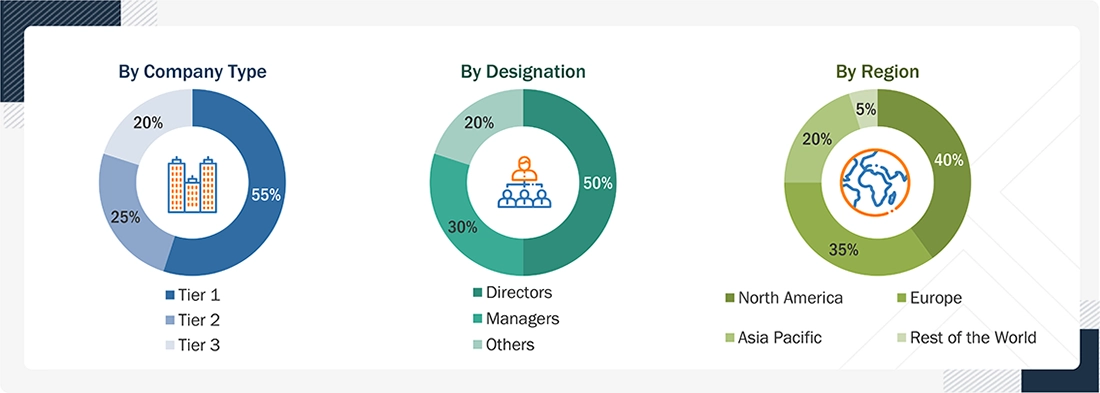
Secondary sources used in this study included annual reports, press releases, and investor presentations of companies; white papers; certified publications; articles from recognized authors; and gold-standard and silver-standard websites, such as Factiva, ICIS, Bloomberg, and others. The findings of this study were verified through primary research, which involved conducting extensive interviews with key officials, including CEOs, VPs, directors, and other executives. The breakdown of profiles of the primary interviewees is illustrated in the figure below:

Primary Research

The HALS market comprises several stakeholders, such as raw material suppliers, end-product manufacturers, and regulatory organizations in the supply chain. Various primary sources from both the supply and demand sides of the market were interviewed to obtain qualitative and quantitative information.

Breakdown of Primary Participants:

Hindered Amine Light Stabilizers (HALS) Market Size, and Share

Note: Tier 1, Tier 2, and Tier 3 companies are classified based on their market revenue in 2024/2025 available in the public domain, product portfolios, and geographical presence. Other designations include consultants and sales, marketing, and procurement managers.

COMPANY NAME

DESIGNATION

BASF SE

Senior Manager

Rianlon Corporation

Innovation Manager

SABO S.p.A.

Development Manager

Syensqo SA/NV

Production Supervisor

Suqian Unitech Corp., Ltd.

Sales Manager

To know about the assumptions considered for the study, download the pdf brochure

Market Size Estimation

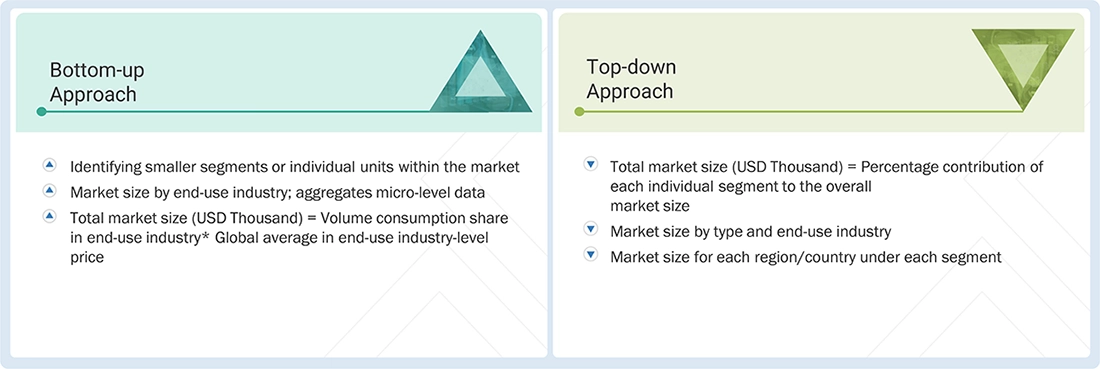
Both top-down and bottom-up approaches were used to estimate and validate the total size of the HALS market. These methods were also used extensively to estimate the size of various subsegments in the market. The research methodology used to estimate the market size includes the following:

  • The key players in the industry were identified through extensive secondary research.
  • The supply chain of the industry was determined through primary and secondary research.
  • All percentage shares, splits, and breakdowns were determined using secondary sources and verified through primary sources.
  • All possible parameters that affect the markets covered in this research study were accounted for, viewed in extensive detail, verified through primary research, and analyzed to obtain the final quantitative and qualitative data.

Hindered Amine Light Stabilizers (HALS) Market : Top-Down and Bottom-Up Approach

Hindered Amine Light Stabilizers (HALS) Market Top Down and Bottom Up Approach

Data Triangulation

After determining the overall market size using the market size estimation processes explained above, the market was divided into several segments and subsegments. To complete the overall market engineering process and determine the exact statistics for each market segment and subsegment, data triangulation and market breakdown procedures were employed, as applicable. The data were triangulated by studying various factors and trends from both the demand and supply sides in the HALS industry.

Market Definition

According to the American Coatings Association, HALS are a group of chemical additives based on 2,2,6,6-tetramethyl piperidine (TMP) that function as radical scavengers to prevent photo-oxidative degradation of polymers. They are widely employed in coatings, adhesives, and sealants to resist surface defects like loss of gloss, cracking, and discoloration. In contrast to UV absorbers, HALS deliver long-term stabilization by functioning independently of film thickness and regenerating their active species during the stabilization process.

Key Stakeholders

  • HALS manufacturers
  • HALS distributors
  • Raw material suppliers
  • Government and research organizations
  • Investment banks and private equity firms

Report Objectives

  • To analyze and forecast the size of the HALS market in terms of value and volume
  • To provide detailed information about the major drivers, restraints, challenges, and opportunities influencing the market growth
  • To define, describe, and segment the market based on type, end-use industry, and region
  • To forecast the size of the market segments based on regions such as Asia Pacific, North America, Europe, the Middle East & Africa, and South America
  • To strategically analyze micromarkets with respect to individual growth trends, prospects, and their contribution to the overall market
  • To strategically analyze the segmented markets with respect to individual growth trends, prospects, and contributions to the overall market
  • To identify and analyze opportunities for stakeholders in the market
  • To analyze competitive developments such as expansions, partnerships, joint ventures, mergers & acquisitions, agreements, and product launches in the market
  • To strategically profile the key companies and comprehensively analyze their core competencies

Available customizations:

Along with the given market data, MarketsandMarkets offers customizations according to the company’s specific needs. The following customization options are available for the report:

Regional Analysis

  • Further breakdown of a region with respect to a particular country or additional application

Company Information

  • Detailed analysis and profiles of additional market players (up to five)


Key Questions Addressed by the Report

Who are the major players in the HALS market?
BASF SE (Germany), Rianlon Corporation (China), SABO S.p.A. (Italy), Syensqo SA/NV (Belgium), Suqian Unitech Corp., Ltd. (China), ADEKA Corporation (Japan), Arkema (France), SONGWON Industrial Co., Ltd. (South Korea), Clariant AG (Switzerland), Everlight Chemical Industrial Corporation (Taiwan), SI Group, Inc. (US), and Beijing Tiangang Auxiliary Co., Ltd. (China).
What are the drivers and opportunities for the HALS market?
Rising demand in the plastics industry, technological advancements, and automotive industry growth are key drivers. Opportunities include offering customized solutions for specific applications.
Which strategies are the key players focusing upon in the HALS market?
Product launches, partnerships, and expansions to enhance global presence.
What is the expected growth rate of the HALS market between 2024 and 2030?
CAGR of 7.01% in terms of value.
Which major factors are expected to restrain the growth of the HALS market during the forecast period?
Supply chain disruptions, price volatility, competition from alternative stabilization technologies, and high production and R&D costs.

Personalize This Research

  • Triangulate with your Own Data
  • Get Data as per your Format and Definition
  • Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
  • Any level of Personalization
Request A Free Customisation

Let Us Help You

  • What are the Known and Unknown Adjacencies Impacting the Hindered Amine Light Stabilizers (HALS) Market
  • What will your New Revenue Sources be?
  • Who will be your Top Customer; what will make them switch?
  • Defend your Market Share or Win Competitors
  • Get a Scorecard for Target Partners
Customized Workshop Request

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements

Get 10% Free Customisation

TESTIMONIALS

Growth opportunities and latent adjacency in Hindered Amine Light Stabilizers (HALS) Market

THIS REPORT TELLS YOU

How big the Hindered Amine Light Stabilizers (HALS) market is, and who leads it.

GROWTHIQ TELLS YOU NEW

Where your company should play next, and who is taking your share.

Get your company's view of this market. Free snapshot.

DMCA.com Protection Status
popup img