Automotive Fuel Tank Market by Vehicle Type (PC, LCV, HCV), Propulsion (Gasoline, Diesel, AF), Tank Capacity (<45L, 45L-70L, >70L), Tank Type, Material (Plastic, Steel, Aluminum), CNG Tank Type, SCR Tank By Vehicle Type, Region - Global Forecast to 2033

icon1
USD 22.87 BN
MARKET SIZE, 2033
icon2
CAGR 4.4%
(2026-2033)
icon3
350
REPORT PAGES
icon4
250
MARKET TABLES

OVERVIEW

automotive-fuel-tank-market Overview

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

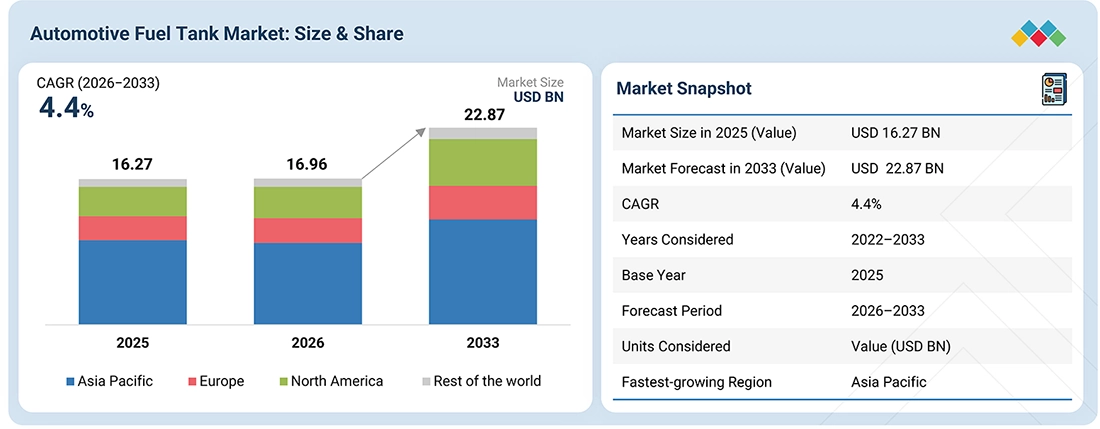
The automotive fuel tank market is projected to grow from USD 16.96 billion in 2026 to USD 22.87 billion by 2033, at a CAGR of 4.4%. The market is driven by rising vehicle production, continued demand for gasoline and diesel vehicles, increasing hybrid vehicle adoption, and stricter evaporative emission requirements. Growing use of lightweight multilayer plastic tanks, low-permeability materials, pressure-resistant tanks for hybrid applications, and optimized tank designs is supporting technology adoption across passenger cars and commercial vehicles. Increasing demand for higher fuel capacity in SUVs, pickups, and commercial vehicles, along with integration of fuel tanks with vapor management, fuel delivery, sensing, and leak detection systems, is further supporting market growth. Asia Pacific remains the largest regional market, supported by high vehicle production volumes across China, India, Japan, South Korea, and Southeast Asia.

KEY TAKEAWAYS

  • MARKET SNAPSHOT:
    Market Size (2025): USD 16.27 Billion
    Current Market Size (2026): USD 16.96 Billion
    Projected Market Size (2033): USD 22.87 Billion
    CAGR (2026–2033):  4.4%
  • By Region
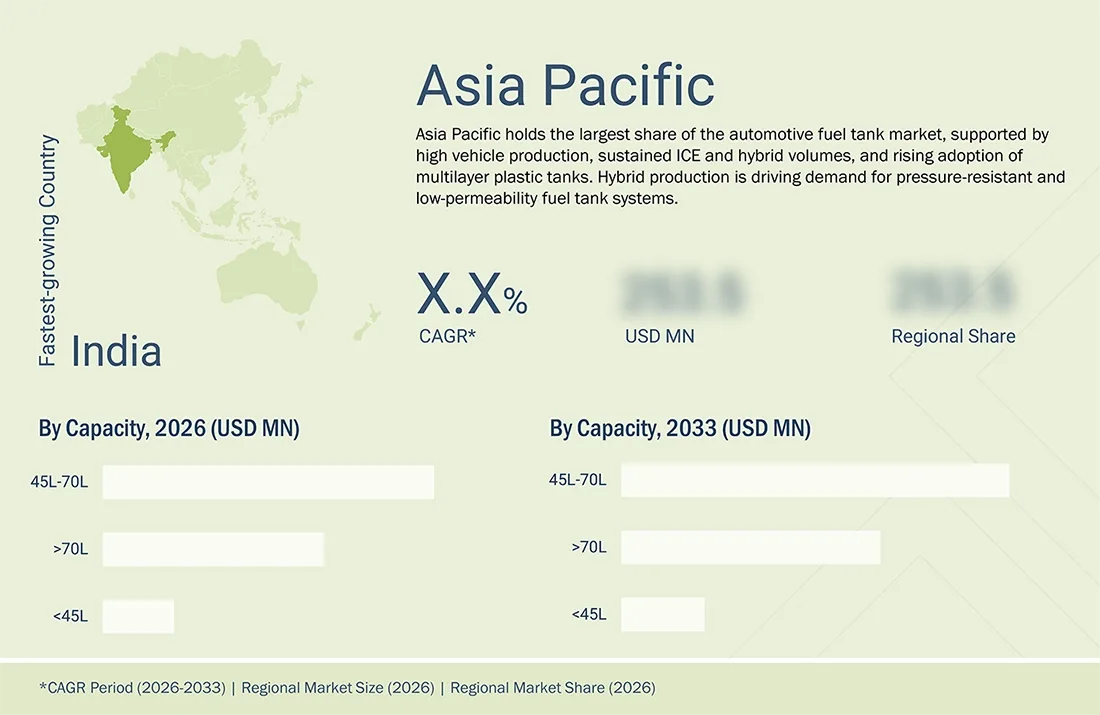
    Asia Pacific is projected to lead the automotive fuel tank market during the forecast period. This segment is projected to grow from USD 9.49 billion in 2026 to USD 12.22 billion in 2033 at a CAGR of 3.7%.
  • By Vehicle Type
    The passenger cars segment is projected to lead the automotive fuel tank market during the forecast period. This segment is projected to grow from USD 10.16 billion in 2026 to USD 13.58 billion by 2033 at a CAGR of 4.2%.
  • By Propulsion Type
    The gasoline segment is projected to lead the automotive fuel tank market during the forecast period. This segment is projected to grow from USD 9.48 billion in 2026 to USD 12.61 billion in 2033 at a CAGR of 4.2%.
  • By Capacity Type
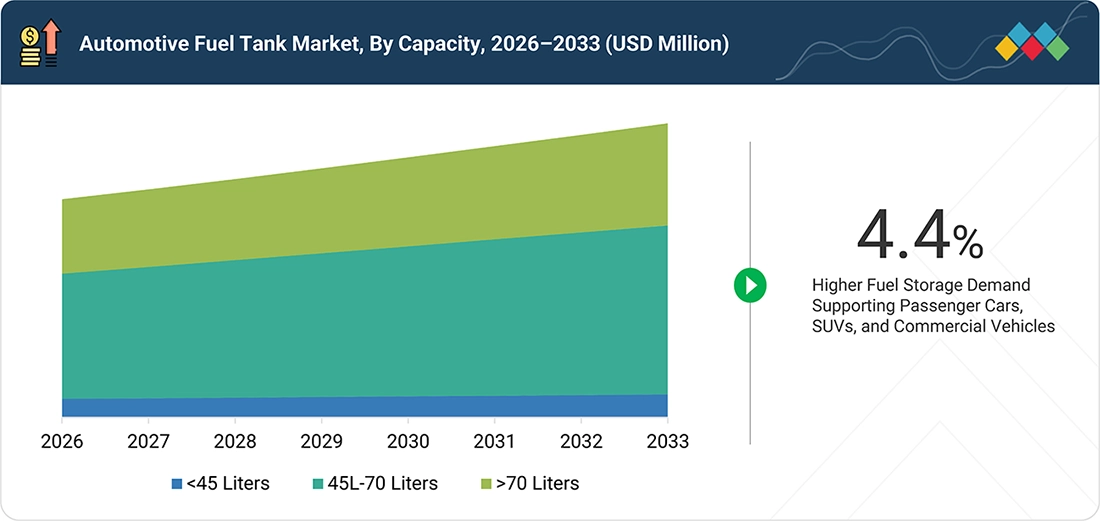
    The 45L-70L segment is projected to lead the automotive fuel tank market during the forecast period. This segment is projected to grow from USD 9.73 billion in 2026 to USD 13.14 billion by 2033 at a CAGR of 4.4%.
  • By SCR Tank Type
    The light commercial vehicles segment is projected to lead the automotive fuel tank market during the forecast period. This segment is projected to grow from USD 0.71 billion in 2026 to USD 0.86 billion in 2033 at a CAGR of 2.8%.
  • By Tank Type
    The saddle fuel tank segment is projected to lead the automotive fuel tank market during the forecast period.
  • By CNG Tank Type
    The Type 1 CNG tank segment is projected to lead the automotive CNG tank market during the forecast period.
  • By Material Type
    The plastic Segment is projected to lead the automotive fuel tank market during the forecast period.
  • Competitive Landscape
    The automotive fuel tank market is dominated by players such as OPmobility (France), Kautex Textron (Germany), TI Automotive (US), YAPP Automotive Systems (China), and Motherson Yachiyo Automotive Systems (Japan).
  • Competitive Landscape
    The automotive fuel tank market is dominated by other key players, such as Continental (Germany), Futaba Industrial (Japan), Benteler (Germany), Toyoda Gosei (Japan), and Kongsberg Automotive (Norway).

The automotive fuel tank market is set to be driven by increasing hybrid vehicle adoption, stricter evaporative emission regulations, lightweighting requirements, and growing demand for integrated fuel storage and vapor management systems. Rising requirements for low-permeability, pressure-resistant, lightweight, and compact tanks will accelerate adoption of advanced fuel tank technologies across OEMs and Tier 1 suppliers. In the coming years, opportunities will emerge through integrated fuel tank modules, advanced multi-layer barrier structures, smart fuel level and pressure sensing, automated leak detection, and integrated vapor management systems, enabling improved emission control, optimized packaging, lower vehicle weight, and enhanced fuel system performance.

TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS

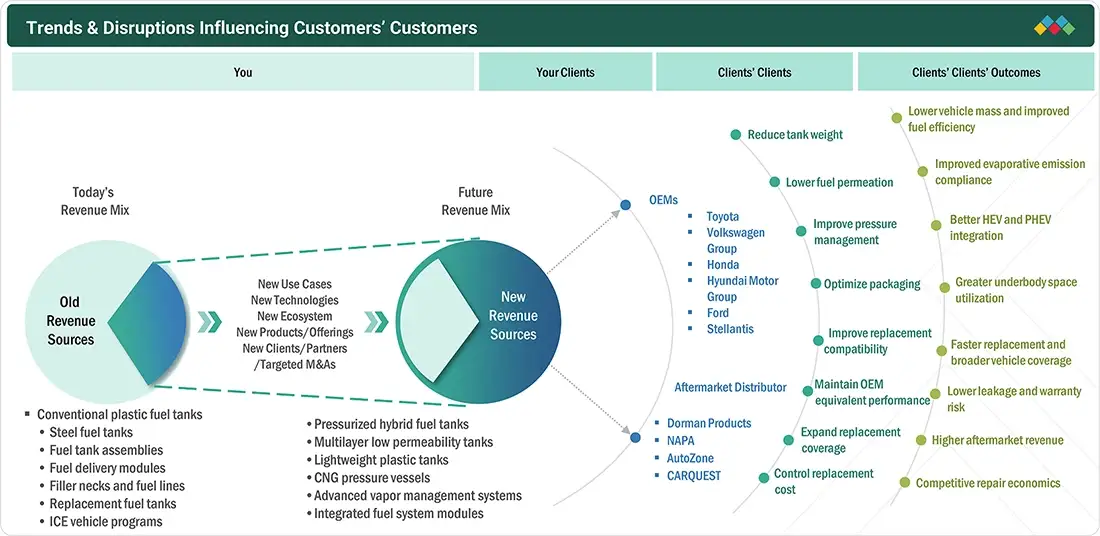
The automotive fuel tank market is shifting from conventional fuel storage toward integrated, lightweight, and low-permeability fuel system solutions. Traditional plastic and steel fuel tanks are increasingly complemented by pressurized hybrid tanks, multi-layer barrier tanks, integrated vapor management, smart sensing, and advanced fuel delivery systems. OEMs and Tier 1 suppliers are adopting these solutions to meet stricter emission requirements, optimize underbody packaging, reduce vehicle weight, and support hybrid powertrains. This is creating new revenue opportunities through integrated fuel tank modules, hybrid tank systems, vapor management, sensing, and leak detection, while enabling lower fuel permeation, improved packaging efficiency, reduced replacement costs, and greater vehicle platform compatibility.

automotive-fuel-tank-market Disruptions

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

MARKET DYNAMICS

Drivers
Impact
Level
  • Hybridization increasing demand for pressure-rated & low-purge fuel tanks  
  • Tighter evaporative-emission control driving fuel-tank system integration
RESTRAINTS
Impact
Level
  • ICE-to-EV transition eroding the addressable fuel-tank volume  
  • High raw material price volatility
OPPORTUNITIES
Impact
Level
  • Shift from fuel tank supplier to integrated fuel system partner
  • Expand high-value tank platforms across hybrid & alternative-fuel vehicles
CHALLENGES
Impact
Level
  • Maintaining leak-tightness & structural integrity under increasingly complex tank operating conditions 
  • Balancing tank packaging flexibility with integrated vapor & fuel-system components  

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Driver: Hybridization increasing demand for pressure-rated & low-purge fuel tanks  

Growing adoption of hybrid and plug-in hybrid vehicles is increasing demand for pressure-resistant, low-permeability, and low-purge fuel tanks. Longer engine-off periods and tighter evaporative emission requirements are driving improvements in tank sealing, vapor management, pressure control, and fuel system integration.

Restraint: ICE-to-EV transition eroding the addressable fuel-tank volume  

Increasing battery electric vehicle adoption is reducing the production base of internal combustion engine vehicles and, consequently, the addressable volume for conventional fuel tanks. Higher EV penetration across passenger vehicles is expected to constrain long-term demand for gasoline and diesel fuel storage systems.

Opportunity: Shift from fuel tank supplier to integrated fuel system partner

OEMs are increasingly seeking integrated solutions combining fuel tanks with fuel delivery, vapor management, sensing, valves, and leak detection. Suppliers can expand their role through integrated fuel tank modules, hybrid fuel systems, smart sensing, and system level validation.

Challenge: Maintaining leak-tightness & structural integrity under increasingly complex tank operating conditions 

Fuel tanks must maintain leak tightness, pressure resistance, structural integrity, and low permeation across temperature variations, crash conditions, fuel aging, and extended engine-off periods. Hybrid applications further increase requirements for pressure management, sealing, and long-term durability.

AUTOMOTIVE FUEL TANK MARKET SIZE, SHARE & ANALYSIS: COMMERCIAL USE CASES ACROSS INDUSTRIES

COMPANY USE CASE DESCRIPTION BENEFITS
company logo
Develops plastic fuel tanks, hybrid pressure resistant tanks, SCR systems, and integrated fuel systems for passenger and commercial vehicles Lightweighting, lower permeation, improved packaging, and greater system integration
company logo
Supplies conventional and pressurized plastic fuel systems, including multilayer and hybrid fuel tanks for cars, light trucks, and hybrid vehicles Reduced weight and emissions, flexible tank geometry, improved packaging, and hybrid compatibility
company logo
Provides fuel tank systems, filler pipes, pumps, and modules for gasoline, diesel, flex fuel, and hybrid applications Integrated fuel storage and delivery, reduced evaporative emissions, lightweight construction, and packaging flexibility
company logo
Develops plastic automotive fuel tanks and fuel system components for OEM vehicle platforms, with focus on lightweight and emission compliant designs Weight reduction, corrosion resistance, packaging flexibility, and improved emission performance
company logo
Manufactures multilayer plastic fuel tanks, including six-layer EVOH barrier tanks and pressure resistant tanks for hybrid applications Low hydrocarbon permeation, lightweight construction, pressure management, and hybrid compatibility

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET ECOSYSTEM

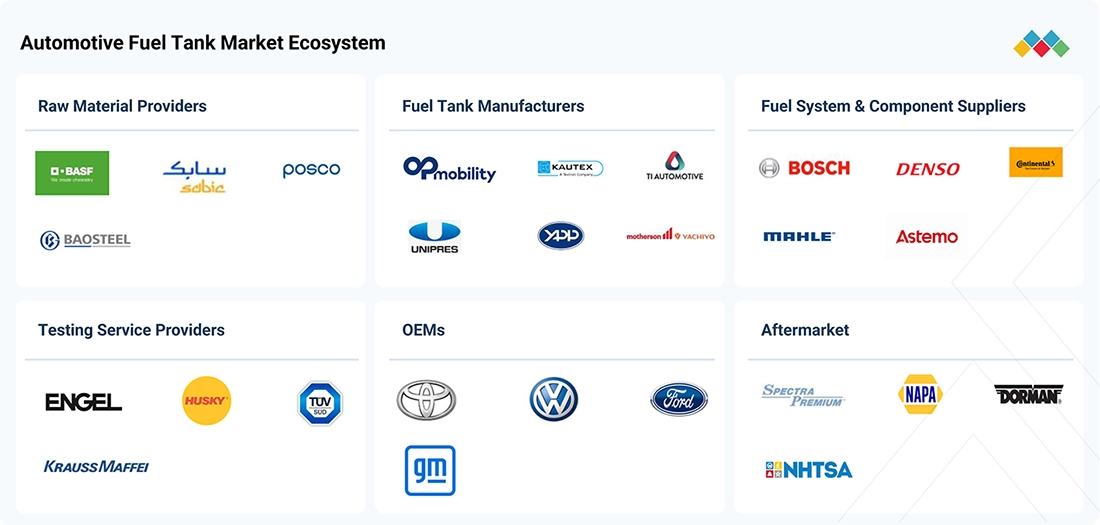
The automotive fuel tank market ecosystem is built around collaboration between raw material providers, fuel tank manufacturers, fuel system and component suppliers, testing service providers, automotive OEMs, and aftermarket companies to develop, manufacture, validate, and service fuel storage systems. Raw material providers such as BASF, SABIC, POSCO, and Baosteel supply polymers, barrier materials, and steel used in fuel tank production. Fuel tank manufacturers, including OPmobility, Kautex, TI Automotive, Unipres, YAPP, and Motherson Yachiyo, develop plastic, steel, multilayer, and hybrid fuel tank systems. Fuel system suppliers such as Bosch, DENSO, Continental, MAHLE, and AsteMo provide pumps, valves, sensors, fuel delivery, and vapor management components, while testing providers such as TÜV SÜD, ENGEL, and Husky support material, component, manufacturing, and compliance validation. OEMs including Toyota, Volkswagen, Ford, and General Motors integrate fuel tank systems into vehicle platforms, while aftermarket companies such as Spectra Premium, NAPA, Dorman, and NTSA support replacement fuel tanks and related components.

automotive-fuel-tank-market Ecosystem

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET SEGMENTS

automotive-fuel-tank-market Segments

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Automotive Fuel Tank Market, By Vehicle Type

Passenger cars account for the largest share, supported by high global production volumes and widespread use of gasoline, diesel, and hybrid powertrains. LCVs and HCVs support demand for higher-capacity and durable fuel tanks, particularly across logistics, commercial transport, and fleet applications.

Automotive Fuel Tank Market, By Propulsion

Gasoline accounts for the largest share, supported by high passenger vehicle production and continued ICE vehicle use. Diesel remains important in LCVs and HCVs, while hybrid and alternative fuel vehicles are increasing demand for pressure-resistant, low-permeability, and specialized fuel storage systems.

Automotive Fuel Tank Market, By Capacity

45- to 70-liter tanks account for a significant share, supported by widespread use across passenger cars, SUVs, and LCVs. Below-45-liter tanks serve compact vehicles, while above-70-liter tanks are increasingly used in pickups, SUVs, trucks, and commercial vehicles requiring extended operating range.

Automotive SCR Tank Market, By VehicleType

HCVs account for the largest share, driven by high diesel penetration, stringent emission regulations, and widespread SCR adoption in trucks and buses. LCV adoption is also increasing as emission standards drive greater use of SCR systems in diesel vans, pickups, and commercial fleets.

Automotive Fuel Tank Market, By Tank Type

Saddle tanks account for a significant share, supported by their ability to utilize available underbody space and provide higher fuel capacity in pickups, SUVs, and commercial vehicles. Their application is particularly relevant where vehicle platforms require optimized packaging around exhaust, suspension, driveshaft, and other underbody components.

Automotive CNG Tank Market, By Tank Type

Type 1 CNG tanks account for a significant share, supported by their cost advantage and widespread use in commercial vehicles and passenger vehicles. Type 2, Type 3, and Type 4 tanks are gaining adoption where lightweight construction, higher storage efficiency, and weight reduction are required.

Automotive Fuel Tank Market, By Material

Plastic fuel tanks account for a significant share, supported by their lightweight construction, corrosion resistance, design flexibility, and low permeability. Steel remains important for high capacity and commercial vehicle applications, while aluminum is used in weight sensitive and specialty applications requiring corrosion resistance and structural strength.

REGION

Asia Pacific is leading the automotive fuel tank market

Asia Pacific holds the largest share of the automotive fuel tank market, led by China, Japan, India, South Korea, and Southeast Asia, supported by high vehicle production, large passenger and commercial vehicle fleets, and established automotive supply chains. Plastic fuel tanks, particularly multilayer low-permeability systems, remain widely used, while China, Japan, and South Korea are driving adoption of lightweight and pressure-resistant tanks for hybrid vehicles. India and Southeast Asia continue to support demand through strong ICE vehicle production, commercial vehicle applications, and growing adoption of CNG and hybrid powertrains.

automotive-fuel-tank-market Region

AUTOMOTIVE FUEL TANK MARKET SIZE, SHARE & ANALYSIS: COMPANY EVALUATION MATRIX

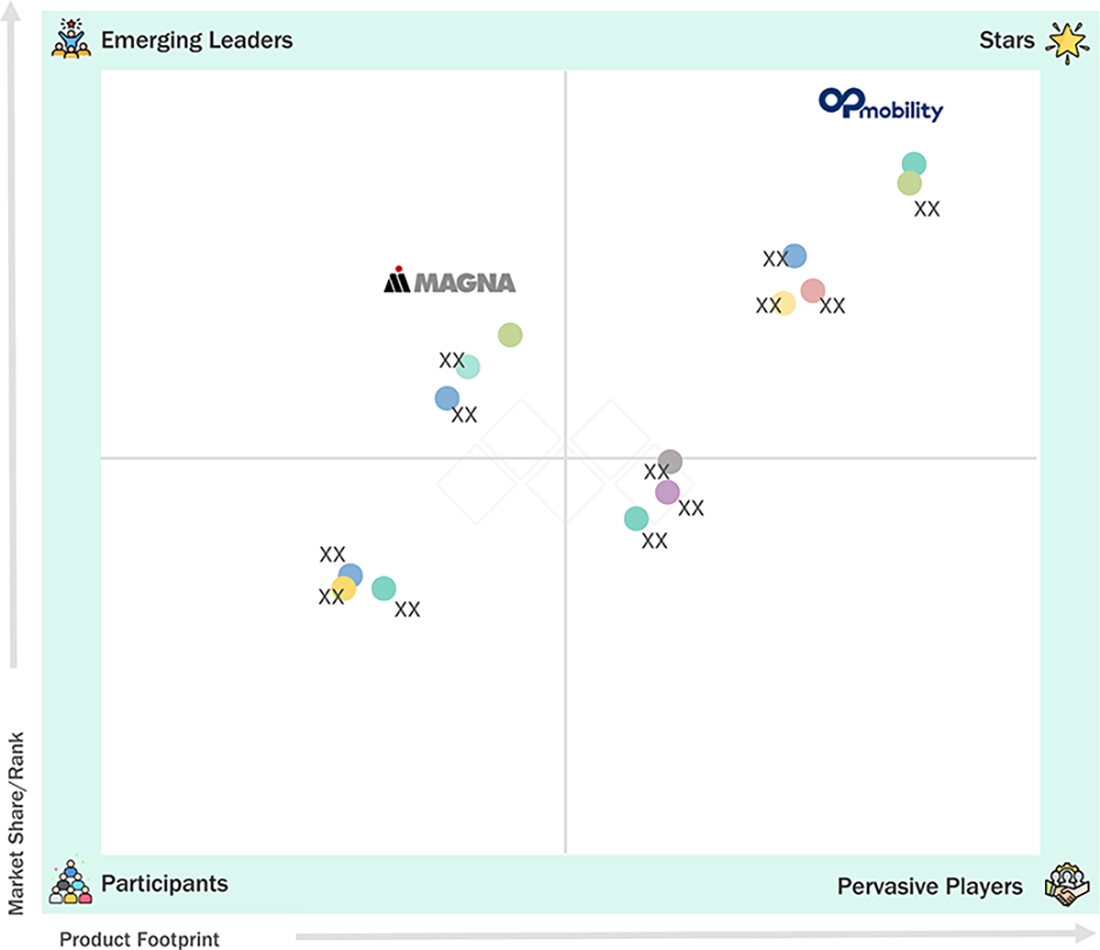
OPmobility is categorized as a Star Player in the automotive fuel tank market, supported by its strong position in plastic fuel systems and integrated fuel storage solutions. The company offers lightweight, low-permeability, multilayer, and pressure-resistant fuel tanks for conventional and hybrid vehicles. Its fuel system portfolio, including vapor management and fuel delivery integration, supports lower emissions, optimized packaging, and hybrid vehicle requirements. Strong relationships with global OEMs and investments in advanced fuel system technologies strengthen its position across the global automotive fuel tank market. Magna is categorized as a Key Emerging Player in the market, supported by its fuel system and vehicle component capabilities across passenger and commercial vehicle platforms. The company provides fuel tank-related solutions with a focus on lightweight construction, packaging efficiency, and system integration. Its global manufacturing footprint and relationships with major OEMs support expansion across vehicle platforms, while increasing demand for lightweight and integrated fuel storage solutions creates opportunities for further market development.

automotive-fuel-tank-market Evaluation Metrics

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

KEY MARKET PLAYERS

MARKET SCOPE

REPORT METRIC DETAILS
Market Size in 2025 (Value) USD 16.27 Billion
Market Size in 2026 (Value) USD 16.96 Billion
Market Forecast in 2033 (Value) USD 22.87 Billion
Growth Rate CAGR of 4.4% from 2026–2033
Years Considered 2022–2033
Base Year 2025
Forecast Period 2026-2033
Units Considered Value (USD Million/Billion), Volume (Thousand Units)
Report Coverage Revenue Forecast, Competitive Landscape, Company Share, Growth Factors and Trends
Segments Covered The report covers vehicle type (passenger cars, light commercial vehicles, heavy commercial vehicles), propulsion (gasoline, diesel, AF), tank capacity (< 45 L, 45L-70L, > 70 L), tank type (saddle, contoured, rectangular, others), material (plastic, steel, aluminum), CNG tank type (Type 1, Type 2, Type 3, Type 4), SCR tank by vehicle type (passenger cars, light commercial vehicles, heavy commercial vehicles)
Regional Scope Asia Pacific, North America, Europe, and Rest of the World

WHAT IS IN IT FOR YOU: AUTOMOTIVE FUEL TANK MARKET SIZE, SHARE & ANALYSIS REPORT CONTENT GUIDE

automotive-fuel-tank-market Content Guide

DELIVERED CUSTOMIZATIONS

We have successfully delivered the following deep-dive customizations:

CLIENT REQUEST CUSTOMIZATION DELIVERED VALUE ADDS
Fuel Tank Segmentation Developed separate analysis for passenger cars, LCVs, HCVs, tank capacity, tank type, material type, propulsion type, and fuel type including gasoline, diesel, CNG, and hybrid applications Helps prioritize high demand tank segments and technology opportunities
Fuel Tank Demand Drivers Mapped demand drivers including vehicle production, hybridization, lightweighting, evaporative emission regulations, CNG adoption, and transition toward integrated fuel systems Supports technology planning, capacity expansion, and investment decisions
OEM and Supplier Benchmarking Benchmarked OEMs, Tier 1 suppliers, fuel tank manufacturers, and fuel system companies based on tank technologies, material capabilities, production footprint, OEM relationships, and system integration Enables competitive positioning and partnership evaluation
Vehicle Platform Analysis Assessed fuel tank requirements across passenger cars, SUVs, LCVs, HCVs, hybrid vehicles, CNG vehicles, and commercial vehicle platforms based on packaging, capacity, pressure, and emission requirements Identifies platform specific fuel tank requirements and future technology needs
Application Level Insights Analyzed demand across plastic, steel, and aluminum tanks, multilayer barrier structures, pressure resistant hybrid tanks, CNG tanks, vapor management, fuel delivery, sensing, and leak detection Supports targeted product development and application specific positioning
Regional Market Deep Dive Delivered country-level analysis covering vehicle production, powertrain mix, hybrid and CNG penetration, regulatory requirements, OEM production, supplier presence, and fuel tank manufacturing capacity across major markets Supports regional expansion, manufacturing planning, and market prioritization
Regulatory and Compliance Assessment Evaluated FMVSS, UNECE, EPA, CARB, China, Japan, and CNG and hydrogen related requirements covering crash safety, evaporative emissions, permeation, pressure resistance, and leak prevention Identifies compliance driven demand and reduces regulatory investment risk
Fuel Tank Technology Mapping Mapped conventional plastic and steel tanks against multilayer plastic, EVOH barrier, pressure-resistant hybrid tanks, integrated fuel tank modules, smart sensing, and vapor management systems Improves technology visibility and supports future product and partnership strategies
Technology Investment Analysis Assessed investment trends across multilayer plastic tanks, EVOH barrier technology, pressure resistant hybrid tanks, CNG storage, integrated fuel tank modules, vapor management, smart sensing, and leak detection Identifies emerging technologies and future fuel tank opportunities
CAPEX and Utilization Analysis Evaluated manufacturing CAPEX, tooling requirements, production capacity, utilization rates, automation levels, material costs, maintenance requirements, and potential return periods across major fuel tank manufacturing technologies Supports manufacturing capacity planning, technology investment, and facility expansion decisions
Strategic Recommendations Provided recommendations on fuel tank technology priorities, material selection, manufacturing localization, regional expansion, OEM targeting, supplier partnerships, and integrated fuel system opportunities Enables informed investment decisions and stronger market positioning

RECENT DEVELOPMENTS

  • July 2026 : YAPP Automotive Systems inaugurated a new 25,000-square-meter tank factory for hybrid vehicles in Americana, São Paulo, on August 14, following an investment of approximately USD 25 million. This facility, YAPP’s third in Brazil, will create over 100 direct jobs and enhance its automotive fuel tank production capacity.
  • July 2026 : Korea FTS announced that it is supplying eco-friendly automotive parts, including carbon canisters, to five domestic automakers. The company is a leader in the carbon canister segment, which is linked to vehicle fuel systems and evaporative emissions control.
  • July 2026 : Unipres Corporation's Tochigi Plant-Moka received IATF 16949:2016 certification covering the manufacture of body metal parts and fuel tank parts, confirming that fuel tank component manufacturing remains within the plant's certified automotive production scope.
  • June 2026 : OPmobility will build its first US manufacturing plant in the greater Toledo area of Ohio, expanding its North American plastics manufacturing footprint. This facility will support regional production of plastic fuel tank systems for automakers.
  • June 2026 : Kautex Textron received an award to supply its Pentatonic thermoplastic battery enclosure system for a new hybrid vehicle platform. This contract enhances Kautex’s position in lightweight plastic structures for electrified vehicles, complementing its automotive fuel tank systems business.
  • April 2026 : A recall of certain 2026 Land Rover Defender vehicles was announced due to incorrectly manufactured fuel tanks supplied by OPmobility. The tanks may have thinner-than-normal walls, which could lead to fuel leakage in a crash, raising concerns about quality and safety in OPmobility’s manufacturing process.
  • March 2026 : Law firm Weil advised TI Automotive on the transformation and sale of its plastic injection molding business in Mühlacker, Germany. TI Automotive is restructuring non-core plastics operations that support components used in vehicle fluid and fuel systems.


Table of Contents

checkmarkExclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.

TITLE
PAGE NO
1
INTRODUCTION


27
2
EXECUTIVE SUMMARY


35
3
PREMIUM INSIGHTS


40
4
MARKET OVERVIEW
Hybridization and emission controls drive integrated fuel system innovation amidst market volatility.


44
 
4.1
INTRODUCTION


4.2
MARKET DYNAMICS


4.2.1
DRIVERS


4.2.1.1
HYBRIDIZATION INCREASING DEMAND FOR PRESSURE-RATED & LOW-PURGE FUEL TANKS


4.2.1.2
TIGHTER EVAPORATIVE-EMISSION CONTROL DRIVING FUEL-TANK SYSTEM INTEGRATION


4.2.2
RESTRAINTS


4.2.2.1
ICE-TO-EV TRANSITION ERODING THE ADDRESSABLE FUEL-TANK VOLUME


4.2.2.2
HIGH RAW MATERIAL PRICE VOLATILITY


4.2.3
OPPORTUNITIES


4.2.3.1
SHIFT FROM FUEL TANK SUPPLIER TO INTEGRATED FUEL SYSTEM PARTNER


4.2.3.2
EXPAND HIGH-VALUE TANK PLATFORMS ACROSS HYBRID & ALTERNATIVE-FUEL VEHICLES


4.2.4
CHALLENGES


4.2.4.1
MAINTAINING LEAK TIGHTNESS AND STRUCTURAL INTEGRITY UNDER INCREASINGLY COMPLEX TANK OPERATING CONDITIONS


4.2.4.2
BALANCING TANK PACKAGING FLEXIBILITY WITH INTEGRATED VAPOR AND FUEL SYSTEM COMPONENTS


4.3
UNMET NEEDS AND WHITE SPACES


4.3.1
LIGHTWEIGHT, HIGH BARRIER, AND FAIL-SAFE FUEL STORAGE ACROSS DIVERSE VEHICLE PLATFORMS


4.3.2
LIMITED END-TO-END FUEL SYSTEM INTEGRATION AND CONTINUOUS COMPLIANCE


4.3.3
LIMITED DATA UTILIZATION FOR INTELLIGENT FUEL TANK MANAGEMENT


5
INDUSTRY TRENDS
Hybridization and lightweight technologies are revolutionizing automotive fuel tank systems and market dynamics.


55
 
5.1
MACROECONOMIC INDICATORS


5.1.1
INTRODUCTION


5.1.2
GDP TRENDS AND FORECAST


5.1.3
TRENDS IN AUTOMOTIVE DRIVETRAIN MARKET


5.1.4
TRENDS IN GLOBAL AUTOMOTIVE INDUSTRY


5.2
SUPPLY CHAIN ANALYSIS


5.3
ECOSYSTEM MAPPING


5.3.1
RAW MATERIAL PROVIDERS


5.3.2
FUEL TANK MANUFACTURERS


5.3.3
FUEL SYSTEM & COMPONENT SUPPLIERS


5.3.4
TESTING SERVICE PROVIDER


5.3.5
OEMS


5.3.6
AFTERMARKET


5.4
PRICING ANALYSIS


5.4.1
AVERAGE SELLING PRICE TREND, BY TANK SIZE, 2024–2026


5.4.2
AVERAGE SELLING PRICE TREND, BY REGION


5.5
TRADE ANALYSIS


5.5.1
IMPORT SCENARIO (HS CODE 870899)


5.5.2
EXPORT SCENARIO (HS CODE 870899)


5.6
KEY CONFERENCES AND EVENTS, 2026–2027


5.7
TRENDS AND DISRUPTIONS IMPACTING CUSTOMER BUSINESSES


5.8
INVESTMENT AND FUNDING SCENARIO


5.9
CASE STUDY ANALYSIS


5.9.1
HYBRIDIZATION DRIVING DEVELOPMENT OF PRESSURIZED FUEL TANK SYSTEMS


5.9.2
MULTILAYER PLASTIC TECHNOLOGY IMPROVING FUEL TANK WEIGHT AND PERMEABILITY PERFORMANCE


5.9.3
LIGHTWEIGHT PLASTIC FUEL TANKS SUPPORTING VEHICLE WEIGHT REDUCTION


5.10
IMPACT OF HYBRIDIZATION ON AUTOMOTIVE FUEL TANK DEMAND


5.11
INSIGHTS ON LIGHTWEIGHT AND MULTILAYER FUEL TANK TECHNOLOGIES


5.12
EU-INDIA TRADE DEAL IMPACT ANALYSIS


5.12.1
INTRODUCTION


5.12.2
EU TARIFFS


6
OEM AND SUPPLIER ANALYSIS, AUTOMOTIVE FUEL TANK MARKET
Discover how OEMs tailor fuel tank strategies to enhance sustainability and localize manufacturing.


76
 
6.1
INTRODUCTION


6.2
TOYOTA GROUP


6.2.1
TOYOTA GROUP OEM FUEL TANK SELECTION CRITERIA


6.2.2
TOYOTA GROUP FUEL PERMEABILITY


6.2.3
TOYOTA GROUP: RECYCLABILITY


6.2.4
TOYOTA GROUP: MANUFACTURING LOCALIZATION


6.3
VOLKSWAGEN GROUP


6.3.1
VOLKSWAGEN GROUP OEM FUEL TANK SELECTION CRITERIA


6.3.2
VOLKSWAGEN GROUP FUEL PERMEABILITY


6.3.3
VOLKSWAGEN GROUP: RECYCLABILITY


6.3.4
VOLKSWAGEN GROUP: MANUFACTURING LOCALIZATION


6.4
HYUNDAI MOTOR GROUP


6.4.1
HYUNDAI MOTOR GROUP OEM FUEL TANK SELECTION CRITERIA


6.4.2
HYUNDAI MOTOR GROUP FUEL PERMEABILITY


6.4.3
HYUNDAI MOTOR GROUP: RECYCLABILITY


6.4.4
HYUNDAI MOTOR GROUP: MANUFACTURING LOCALIZATION


6.5
GENERAL MOTORS


6.5.1
GENERAL MOTORS FUEL PERMEABILITY


6.5.2
GENERAL MOTORS: RECYCLABILITY


6.5.3
GENERAL MOTORS: MANUFACTURING LOCALIZATION


6.6
STELLANTIS


6.6.1
STELLANTIS OEM FUEL TANK SELECTION CRITERIA


6.6.2
STELLANTIS FUEL PERMEABILITY


6.6.3
STELLANTIS: RECYCLABILITY


6.6.4
STELLANTIS: MANUFACTURING LOCALIZATION


6.7
BYD


6.7.1
BYD OEM FUEL TANK SELECTION CRITERIA


6.7.2
BYD FUEL PERMEABILITY


6.7.3
BYD: RECYCLABILITY


6.7.4
BYD: MANUFACTURING LOCALIZATION


6.8
SAIC MOTOR


6.8.1
SAIC MOTOR OEM FUEL TANK SELECTION CRITERIA


6.8.2
SAIC MOTOR FUEL PERMEABILITY


6.8.3
SAIC MOTOR: RECYCLABILITY


6.8.4
SAIC MOTOR: MANUFACTURING LOCALIZATION


6.9
FORD MOTOR


6.9.1
FORD MOTOR OEM FUEL TANK SELECTION CRITERIA


6.9.2
FORD MOTOR FUEL PERMEABILITY


6.9.3
FORD MOTOR: RECYCLABILITY


6.9.4
FORD MOTOR: MANUFACTURING LOCALIZATION


7
SUSTAINABILITY AND REGULATORY LANDSCAPE
Navigate complex global regulations to enhance automotive fuel tank sustainability and compliance.


88
 
7.1
REGULATORY LANDSCAPE


7.1.1
COUNTRY-WISE REGULATIONS


7.1.2
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


7.1.3
INDUSTRY STANDARDS AND REGULATIONS


7.1.4
REGIONAL REGULATORY COMPARISON


7.1.5
FUEL TANK CRASH SAFETY AND LEAKAGE REQUIREMENTS


7.1.6
ALTERNATIVE FUEL STORAGE STANDARDS


7.1.7
MATERIAL SPECIFICATIONS AND COMPATIBILITY REQUIREMENTS


7.1.8
PRESSURE RESISTANCE AND CONTAINMENT REQUIREMENTS


7.2
SUSTAINABILITY INITIATIVES


7.3
SUSTAINABILITY IMPACT AND REGULATORY POLICY INITIATIVES


7.4
CERTIFICATION, LABELING, AND ECO-STANDARDS


7.4.1
CERTIFICATION, LABELING, AND ENVIRONMENTAL STANDARDS RELEVANT TO AUTOMOTIVE FUEL TANK MARKET


8
TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS IN AUTOMOTIVE FUEL TANK MARKET
AI-driven innovations revolutionize fuel tank technologies, enhancing efficiency and sustainability in hybrid vehicles.


100
 
8.1
TECHNOLOGY ANALYSIS


8.1.1
INTRODUCTION


8.1.2
KEY EMERGING TECHNOLOGIES


8.1.2.1
ADVANCED MULTILAYER BARRIER FUEL TANKS


8.1.2.2
LOW-PERMEABILITY POLYMER TECHNOLOGIES


8.1.2.3
LIGHTWEIGHT COMPOSITE FUEL STORAGE SYSTEMS


8.1.2.4
SMART FUEL TANK SENSING AND CONDITION MONITORING


8.1.2.5
ADVANCED FUEL TANK ARCHITECTURES FOR HYBRID PLATFORMS


8.1.3
ADJACENT TECHNOLOGIES


8.1.3.1
END-OF-LIFE VEHICLE RECYCLING AND MATERIAL RECOVERY TECHNOLOGIES


8.1.3.2
FUEL DELIVERY AND THERMAL MANAGEMENT SYSTEMS


8.1.3.3
FUEL VAPOR MANAGEMENT AND EVAP SYSTEMS


8.2
TECHNOLOGY/PRODUCT ROADMAP


8.3
PATENT ANALYSIS


8.3.1
INTRODUCTION


8.3.1.1
LIST OF PATENTS


8.4
IMPACT OF ADVANCED TECHNOLOGIES ON THE AUTOMOTIVE FUEL TANK MARKET


8.4.1
TOP TECHNOLOGY APPLICATIONS AND MARKET POTENTIAL


8.4.1.1
MARKET POTENTIAL BY VEHICLE APPLICATION


8.4.1.2
MARKET POTENTIAL BY TECHNOLOGY


8.4.2
BEST PRACTICES FOLLOWED BY OEMS AND FUEL TANK MANUFACTURERS


8.4.3
CASE STUDIES RELATED TO ADVANCED FUEL TANK TECHNOLOGY IMPLEMENTATION


8.4.3.1
PRESSURIZED FUEL TANK DEVELOPMENT FOR PLUG-IN HYBRID VEHICLES


8.4.3.2
PURE PLASTIC PRESSURE TANK FOR THE VOLKSWAGEN PASSAT GTE


8.4.3.3
HIGH-VOLUME PRESSURIZED PLASTIC FUEL TANK FOR PHEV


8.4.3.4
MULTILAYER PLASTIC PHEV FUEL TANK SYSTEM


8.4.3.5
HIGH-PRESSURE HYDROGEN TANK FOR TOYOTA MIRAI


8.4.4
INTERCONNECTED FUEL SYSTEM ECOSYSTEM AND IMPACT ON MARKET PLAYERS


8.4.5
OEM READINESS TO ADOPT NEXT-GENERATION FUEL TANK TECHNOLOGIES


9
CUSTOMER LANDSCAPE AND BUYING BEHAVIOR
Uncover pivotal buying criteria and stakeholder influence shaping vehicle purchase decisions.


116
 
9.1
DECISION-MAKING PROCESS


9.2
KEY STAKEHOLDERS AND BUYING CRITERIA


9.2.1
PASSENGER VEHICLE


9.2.2
LIGHT COMMERCIAL VEHICLE


9.2.3
HEAVY COMMERCIAL VEHICLE


9.2.4
KEY STAKEHOLDERS IN BUYING PROCESS


9.2.5
BUYING CRITERIA


9.3
ADOPTION BARRIERS & INTERNAL CHALLENGES


9.4
UNMEET NEED TO VARIOUS END USERS


10
AUTOMOTIVE FUEL TANK MARKET, BY VEHICLE TYPE
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million and Units | 16 Data Tables


121
 
10.1
INTRODUCTION


10.2
PASSENGER CARS


10.2.1
OEM PACKAGING AND EMISSION REQUIREMENTS ACCELERATE ADVANCED PASSENGER CAR FUEL TANK ADOPTION


10.3
LIGHT COMMERCIAL VEHICLE


10.3.1
URBAN DELIVERY GROWTH DRIVES DEMAND FOR COMPACT AND LIGHTWEIGHT LCV FUEL TANKS


10.4
HEAVY COMMERCIAL VEHICLE


10.4.1
LONG DISTANCE FREIGHT DRIVES DEMAND FOR HIGH CAPACITY AND DURABLE HCV FUEL TANKS


10.5
KEY PRIMARY INSIGHTS


11
AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million and Liters | 16 Data Tables


130
 
11.1
INTRODUCTION


11.2
<45 LITERS


11.2.1
COMPACT VEHICLE PLATFORMS DRIVE DEMAND FOR SPACE EFFICIENT AND LIGHTWEIGHT FUEL TANKS


11.3
45–70 LITERS


11.3.1
HIGH VOLUME VEHICLE PLATFORMS DRIVE CONSISTENT DEMAND FOR MID CAPACITY FUEL TANKS


11.4
>70 LITERS


11.4.1
EXTENDED DRIVING RANGE REQUIREMENTS REINFORCE DEMAND FOR HIGH-CAPACITY FUEL TANKS


11.5
KEY PRIMARY INSIGHTS


12
AUTOMOTIVE SELECTIVE CATALYTIC REDUCTION (SCR) TANK MARKET, BY REGION AND VEHICLE TYPE
Comprehensive Coverage of Major Geographical Regions with Detailed Country-specific Data


139
 
12.1
INTRODUCTION


12.2
PASSENGER CARS


12.2.1
STRINGENT EMISSION REQUIREMENTS TO SUPPORT PASSENGER-CAR SCR TANK DEMAND


12.3
LIGHT COMMERCIAL VEHICLES


12.3.1
GROWING URBAN LOGISTICS AND EMISSION COMPLIANCE TO DRIVE LCV SCR TANK DEMAND


12.4
HEAVY COMMERCIAL VEHICLES


12.4.1
HIGH-DEF CONSUMPTION IN LONG-HAUL APPLICATIONS TO SUSTAIN HCV SCR TANK DEMAND


12.5
KEY PRIMARY INSIGHTS


13
AUTOMOTIVE CNG TANK MARKET, BY TYPE
Market Size & Growth Rate Forecast Analysis to 2033 in Units | 10 Data Tables


148
 
13.1
INTRODUCTION


13.2
TYPE 1


13.2.1
ESTABLISHED LOW-COST TECHNOLOGY TO SUSTAIN TYPE 1 CNG TANK DEMAND


13.3
TYPE 2


13.3.1
PARTIAL COMPOSITE REINFORCEMENT TO IMPROVE CNG TANK WEIGHT EFFICIENCY


13.4
TYPE 3


13.4.1
LIGHTWEIGHT COMPOSITE CONSTRUCTION TO ACCELERATE TYPE 3 CNG TANK ADOPTION


13.5
TYPE 4


13.5.1
HIGH WEIGHT SAVINGS AND ADVANCED STORAGE PERFORMANCE TO DRIVE TYPE 4 GROWTH


13.6
KEY PRIMARY INSIGHTS


14
AUTOMOTIVE FUEL TANK MARKET, BY PROPULSION
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million and Units | 16 Data Tables


155
 
14.1
INTRODUCTION


14.2
GASOLINE


14.2.1
WIDESPREAD PASSENGER-VEHICLE ADOPTION TO SUPPORT GASOLINE FUEL TANK DEMAND


14.3
DIESEL


14.3.1
HIGH RANGE REQUIREMENTS IN COMMERCIAL VEHICLES TO SUSTAIN DIESEL TANK DEMAND


14.4
ALTERNATIVE FUEL


14.4.1
SHIFT TOWARD LOWER-EMISSION POWERTRAINS TO ACCELERATE ALTERNATIVE-FUEL TANK ADOPTION


14.5
KEY PRIMARY INSIGHTS


15
AUTOMOTIVE FUEL TANK MARKET, BY TANK TYPE
Market Size & Growth Rate Forecast Analysis to 2033 in Units | 10 Data Tables


163
 
15.1
INTRODUCTION


15.2
SADDEL


15.2.1
SADDLE MOUNTED FUEL TANK ARCHITECTURES MAXIMIZE UNDERBODY PACKAGING AND FUEL CAPACITY


15.3
CONTOURED


15.3.1
CONTOURED FUEL TANKS SUPPORT SPACE OPTIMIZATION ACROSS ICE, HYBRID, AND COMMERCIAL VEHICLES


15.4
RECTANGULAR


15.4.1
RECTANGULAR FUEL TANKS SUPPORT STANDARDIZED PACKAGING ACROSS ICE AND COMMERCIAL VEHICLES


15.5
OTHERS


15.5.1
OTHER FUEL TANK TYPES ADDRESS APPLICATION SPECIFIC PACKAGING AND STORAGE REQUIREMENTS


15.6
KEY PRIMARY INSIGHTS


16
AUTOMOTIVE FUEL TANK MARKET, BY MATERIAL
Market Size & Growth Rate Forecast Analysis to 2033 in Units | 10 Data Tables


170
 
16.1
INTRODUCTION


16.2
PLASTIC


16.2.1
INCREASING VEHICLE LIGHTWEIGHTING TO SUPPORT PLASTIC FUEL TANK ADOPTION


16.3
STEEL


16.3.1
HIGH DURABILITY REQUIREMENTS TO SUSTAIN STEEL FUEL TANK DEMAND


16.4
ALUMINUM


16.4.1
LIGHTWEIGHT CONSTRUCTION TO EXPAND ALUMINUM FUEL TANK APPLICATIONS


16.5
OTHER


16.5.1
SPECIALIZED MATERIAL REQUIREMENTS SUPPORT SELECTIVE ADOPTION OF OTHER FUEL TANK MATERIALS


16.6
KEY PRIMARY INSIGHTS


17
AUTOMOTIVE FUEL TANK MARKET, BY REGION
Comprehensive coverage of 5 Regions with country-level deep-dive of 17 Countries | 100 Data Tables.


178
 
17.1
INTRODUCTION


17.2
ASIA PACIFIC


17.2.1
CHINA


17.2.1.1
HYBRIDIZATION AND STRINGENT EMISSION REQUIREMENTS TO DRIVE ADVANCED FUEL TANK DEMAND


17.2.2
JAPAN


17.2.2.1
HYBRIDIZATION TO SUSTAIN DEMAND FOR HIGH PERFORMANCE FUEL TANK SYSTEMS


17.2.3
INDIA


17.2.3.1
INCREASING LOCALIZATION AND ADVANCED PLASTIC TANK TECHNOLOGY TO SUPPORT FUEL TANK DEMAND


17.2.4
SOUTH KOREA


17.2.4.1
ADVANCED EMISSION CONTROL TO DRIVE HIGH SPECIFICATION FUEL TANK SYSTEMS


17.2.5
THAILAND


17.2.5.1
EXPORT ORIENTED VEHICLE MANUFACTURING TO EXPAND FUEL TANK PRODUCTION


17.2.6
INDONESIA


17.2.6.1
MPV AND SUV PRODUCTION TO SUSTAIN FUEL TANK DEMAND


17.2.7
REST OF ASIA PACIFIC


17.2.7.1
EXPANDING REGIONAL VEHICLE PRODUCTION TO SUPPORT MEDIUM CAPACITY FUEL TANK DEMAND


17.3
EUROPE


17.3.1
GERMANY


17.3.1.1
HYBRIDIZATION AND LOW PERMEATION REQUIREMENTS TO DRIVE ADVANCED FUEL TANK TECHNOLOGY


17.3.2
FRANCE


17.3.2.1
OEM ELECTRIFICATION AND EMISSION COMPLIANCE TO RESHAPE FUEL TANK TECHNOLOGY


17.3.3
ITALY


17.3.3.1
HYBRIDIZATION AND LIGHTWEIGHT FUEL SYSTEMS TO SUPPORT ADVANCED TANK TECHNOLOGY


17.3.4
SPAIN


17.3.4.1
ELECTRIFICATION OF VEHICLE PRODUCTION TO RESHAPE FUEL TANK TECHNOLOGY


17.3.5
UK


17.3.5.1
MIXED POWERTRAIN MANUFACTURING TO SUSTAIN ADVANCED FUEL TANK APPLICATIONS


17.3.6
RUSSIA


17.3.6.1
LOCALIZATION OF PLASTIC FUEL SYSTEMS TO STRENGTHEN DOMESTIC FUEL TANK MANUFACTURING


17.3.7
REST OF EUROPE


17.3.7.1
REGIONAL PRODUCTION HUBS TO SUPPORT LOCALIZED AND APPLICATION SPECIFIC FUEL TANK SYSTEMS


17.4
NORTH AMERICA


17.4.1
US


17.4.1.1
FUEL SYSTEM INTEGRATION TO INCREASE FUEL TANK VALUE PER VEHICLE


17.4.2
CANADA


17.4.2.1
CROSS BORDER VEHICLE MANUFACTURING TO SUSTAIN CANADA’S FUEL TANK SUPPLY CHAIN


17.4.3
MEXICO


17.4.3.1
LIGHT COMMERCIAL VEHICLE MANUFACTURING TO STRENGTHEN HIGH-CAPACITY FUEL TANK DEMAND


17.5
REST OF THE WORLD


17.5.1
BRAZIL


17.5.1.1
FLEX FUEL AND HYBRID VEHICLE PRODUCTION TO DRIVE ADVANCED FUEL TANK TECHNOLOGY


17.5.2
IRAN


17.5.2.1
DOMESTIC VEHICLE PRODUCTION TO ACCELERATE FUEL TANK TECHNOLOGY LOCALIZATION


17.5.3
SOUTH AFRICA


17.5.3.1
OEM EXPORT PLATFORMS TO ACCELERATE FUEL TANK TECHNOLOGY LOCALIZATION


18
COMPETITIVE LANDSCAPE
Discover strategies and market positions shaping the future of automotive fuel tank competition.


226
 
18.1
OVERVIEW


18.2
KEY PLAYER STRATEGIES/RIGHT TO WIN


18.2.1
OVERVIEW OF STRATEGIES ADOPTED BY PLAYERS IN AUTOMOTIVE FUEL TANK MARKET


18.3
MARKET SHARE ANALYSIS, 2025


18.4
REVENUE ANALYSIS, 2021–2025


18.5
COMPANY VALUATION AND FINANCIAL METRICS


18.5.1
COMPANY VALUATION


18.5.2
FINANCIAL METRICS


18.6
BRAND/PRODUCT COMPARISON


18.7
COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025


18.7.1
STARS


18.7.2
EMERGING LEADERS


18.7.3
PERVASIVE PLAYERS


18.7.4
PARTICIPANTS


18.7.5
COMPANY FOOTPRINT: KEY PLAYERS, 2025


18.7.5.1
COMPANY FOOTPRINT


18.7.5.2
REGIONAL FOOTPRINT


18.7.5.3
VEHICLE TYPE FOOTPRINT


18.7.5.4
MATERIAL TYPE FOOTPRINT


18.7.5.5
PROPULSION TYPE FOOTPRINT


18.8
COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025


18.8.1
PROGRESSIVE COMPANIES


18.8.2
RESPONSIVE COMPANIES


18.8.3
DYNAMIC COMPANIES


18.8.4
STARTING BLOCKS


18.8.5
COMPETITIVE BENCHMARKING, STARTUPS/SMES, 2025


18.8.5.1
DETAILED LIST OF KEY STARTUPS/SMES


18.8.5.2
COMPETITIVE BENCHMARKING OF STARTUPS/SMES


18.9
COMPETITIVE SCENARIO


18.9.1
PRODUCT LAUNCHES


18.9.2
DEALS


18.9.3
OTHER DEVELOPMENTS


19
COMPANY PROFILES
In-depth Company Profiles of Leading Market Players with detailed Business Overview, Product and Service Portfolio, Recent Developments, and Unique Analyst Perspective (MnM View)


245
 
19.1
KEY PLAYERS


19.1.1
OPMOBILITY


19.1.1.1
BUSINESS OVERVIEW


19.1.1.2
PRODUCTS OFFERED


19.1.1.3
RECENT DEVELOPMENTS


19.1.1.3.1
EXPANSIONS


19.1.1.3.2
OTHER DEVELOPMENTS


19.1.1.4
MNM VIEW


19.1.1.4.1
KEY STRENGTHS


19.1.1.4.2
STRATEGIC CHOICES


19.1.1.4.3
WEAKNESSES AND COMPETITIVE THREATS


19.1.2
KAUTEX TEXTRON


19.1.3
TI AUTOMOTIVE


19.1.4
YAPP AUTOMOTIVE SYSTEMS CO., LTD.


19.1.5
MOTHERSON YACHIYO AUTOMOTIVE SYSTEMS


19.1.6
MAGNA INTERNATIONAL


19.1.7
FUEL TOTAL SYSTEMS


19.1.8
UNIPRES CORPORATION


19.1.9
MARTINREA INTERNATIONAL INC.


19.1.10
DONGHEE HOLDINGS


19.1.11
SAKAMOTO INDUSTRY CO., LTD.


19.1.12
SMA SERBATOI


19.2
OTHER KEY PLAYERS


19.2.1
CONTINENTAL AG


19.2.2
FUTABA INDUSTRIAL CO., LTD.


19.2.3
BENTELER


19.2.4
TOYODA GOSEI CO., LTD.


19.2.5
KONGSBERG AUTOMOTIVE


19.2.6
SPECTRA PREMIUM


19.2.7
BOYD WELDING LLC


19.2.8
ALLGAIER AUTOMOTIVE GMBH


19.2.9
POSCO


19.2.10
BAOSTEEL


19.2.11
DORMAN PRODUCTS, INC.


19.2.12
YEEDAH COMPOSITE MATERIAL CO., LTD.


19.2.13
NORTHSIDE INDUSTRIES


20
RESEARCH METHODOLOGY


291
 
20.1
RESEARCH DATA


20.1.1
SECONDARY DATA


20.1.2
KEY SECONDARY SOURCES


20.1.2.1
LIST OF SECONDARY SOURCES


20.1.2.2
KEY DATA FROM SECONDARY SOURCES


20.1.3
PRIMARY DATA


20.1.3.1
PRIMARY INTERVIEWS – DEMAND AND SUPPLY SIDES


20.1.3.2
KEY INDUSTRY INSIGHTS AND BREAKDOWN OF PRIMARY INTERVIEWS


20.1.3.3
LIST OF PRIMARY PARTICIPANTS


20.2
MARKET SIZE ESTIMATION


20.2.1
BOTTOM-UP APPROACH


20.2.2
TOP-DOWN APPROACH


20.3
DATA TRIANGULATION


20.4
FACTOR ANALYSIS


20.5
RESEARCH ASSUMPTIONS


20.6
RESEARCH LIMITATIONS


20.7
RISK ASSESSMENT


21
APPENDIX


303
 
21.1
KEY INSIGHTS OF INDUSTRY EXPERTS


21.2
DISCUSSION GUIDE


21.3
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL


21.4
CUSTOMIZATION OPTIONS


21.4.1
AUTOMOTIVE FUEL TANK MARKET, BY VEHICLE TYPE, AT THE COUNTRY LEVEL (FOR REGIONS COVERED IN THE REPORT)


21.4.2
AUTOMOTIVE FUEL TANK MARKET, BY PROPULSION, AT THE COUNTRY LEVEL (FOR THE COUNTRIES ADDITION UP TO 3 IN THE REPORT)


21.4.3
COMPANY INFORMATION


21.4.3.1
PROFILES OF ADDITIONAL MARKET PLAYERS (UP TO FIVE)


21.5
RELATED REPORTS


21.6
AUTHOR DETAILS


LIST OF TABLES


TABLE 1
AUTOMOTIVE FUEL TANK MARKET DEFINITION, BY VEHICLE TYPE


TABLE 2
AUTOMOTIVE FUEL TANK MARKET DEFINITION, BY PROPULSION TYPE


TABLE 3
AUTOMOTIVE FUEL TANK MARKET DEFINITION, BY CAPACITY TYPE


TABLE 4
AUTOMOTIVE FUEL TANK MARKET DEFINITION, BY TANK TYPE


TABLE 5
AUTOMOTIVE FUEL TANK MARKET DEFINITION, BY MATERIAL TYPE


TABLE 6
AUTOMOTIVE CNG TANK MARKET DEFINITION, BY TANK TYPE


TABLE 1
AUTOMOTIVE SCR TANK MARKET DEFINITION, BY VEHICLE TYPE


TABLE 2
INCLUSIONS AND EXCLUSIONS IN AUTOMOTIVE FUEL TANK MARKET


TABLE 3
CURRENCY EXCHANGE RATES, 2021–2025


TABLE 4
AUTOMOTIVE FUEL TANK MARKET: IMPACT OF HYBRIDIZATION ON FUEL TANK DESIGN


TABLE 5
AUTOMOTIVE FUEL TANK MARKET: OEM SHIFT IN AUTOMOTIVE FUEL TANK REQUIREMENTS


TABLE 6
AUTOMOTIVE FUEL TANK MARKET: OEM EXPANSION INTO HIGH-VALUE FUEL TANK PLATFORMS


TABLE 7
AUTOMOTIVE FUEL TANK MARKET: IMPACT OF MARKET DYNAMICS


TABLE 8
GDP PERCENTAGE CHANGE, BY KEY COUNTRY, 2022–2031


TABLE 9
AUTOMOTIVE FUEL TANK MARKET: ROLE OF KEY PLAYERS IN ECOSYSTEM


TABLE 10
AVERAGE SELLING PRICE TREND, BY TANK SIZE, 2024–2026 (USD)


TABLE 11
AVERAGE SELLING PRICE TREND, BY REGION, 2024–2026 (USD)


TABLE 12
IMPORT DATA FOR HS CODE 870899-COMPLIANT PRODUCTS, BY COUNTRY, 2022–2025 (USD BILLION)


TABLE 13
EXPORT DATA FOR HS CODE 870899-COMPLIANT PRODUCTS, BY COUNTRY, 2022–2025 (USD BILLION)


TABLE 14
KEY CONFERENCES AND EVENTS, 2026–2027


TABLE 15
IMPACT ON AUTOMOTIVE FUEL TANK DEMAND, BY MANUFACTURER


TABLE 16
TOYOTA GROUP: OEM FUEL TANK SELECTION CRITERIA


TABLE 17
TOYOTA GROUP: FUEL PERMEABILITY


TABLE 18
VOLKSWAGEN GROUP: OEM FUEL TANK SELECTION CRITERIA


TABLE 19
VOLKSWAGEN GROUP: FUEL PERMEABILITY


TABLE 20
HYUNDAI MOTOR GROUP: OEM FUEL TANK SELECTION CRITERIA


TABLE 21
HYUNDAI MOTOR GROUP: FUEL PERMEABILITY


TABLE 22
GENERAL MOTORS: OEM FUEL TANK SELECTION CRITERIA


TABLE 23
GENERAL MOTORS: FUEL PERMEABILITY


TABLE 24
STELLANTIS: OEM FUEL TANK SELECTION CRITERIA


TABLE 25
STELLANTIS: FUEL PERMEABILITY


TABLE 26
BYD: OEM FUEL TANK SELECTION CRITERIA


TABLE 27
BYD: FUEL PERMEABILITY


TABLE 28
SAIC MOTOR: OEM FUEL TANK SELECTION CRITERIA


TABLE 29
SAIC MOTOR: FUEL PERMEABILITY


TABLE 30
FORD MOTOR: OEM FUEL TANK SELECTION CRITERIA


TABLE 31
FORD MOTOR: FUEL PERMEABILITY


TABLE 32
TAX BENEFITS AND INCENTIVES SUPPORTING THE AUTOMOTIVE FUEL TANK ECOSYSTEM


TABLE 33
NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 34
EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATION


TABLE 35
ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 36
GLOBAL INDUSTRY STANDARDS AND REGULATIONS


TABLE 37
REGIONAL REGULATORY COMPARISON


TABLE 38
POLICY INITIATIVES AFFECTING SUSTAINABILITY, SAFETY, EMISSIONS, AND TECHNOLOGY COMPLIANCE FOR AUTOMOTIVE FUEL TANK MARKET


TABLE 39
CERTIFICATION, LABELING, AND ENVIRONMENTAL STANDARDS


TABLE 40
TECHNOLOGY TRANSITION IN FUEL TANK ARCHITECTURE FOR HYBRID VEHICLES


TABLE 41
END-OF-LIFE VEHICLE RECYCLING AND MATERIAL RECOVERY TECHNOLOGIES


TABLE 42
FUEL DELIVERY AND THERMAL MANAGEMENT SYSTEMS: COMPANY TECHNOLOGY LANDSCAPE


TABLE 43
OEM HYBRIDIZATION IS DRIVING INTEGRATION OF FUEL TANK PRESSURE, VAPOR CONTROL, AND EVAP FUNCTIONS


TABLE 44
PATENT REGISTRATIONS IN AUTOMOTIVE FUEL TANK MARKET, SEPTEMBER 2024- SEPTEMBER 2026


TABLE 45
BEST PRACTICES FOLLOWED BY AUTOMOTIVE OEMS AND FUEL TANK MANUFACTURERS


TABLE 46
IMPACT OF INTERCONNECTED FUEL SYSTEMS ON AUTOMOTIVE FUEL TANK MARKET PLAYERS


TABLE 47
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP APPLICATIONS (%)


TABLE 48
KEY BUYING CRITERIA FOR TOP APPLICATIONS


TABLE 49
AUTOMOTIVE FUEL TANK MARKET, BY VEHICLE TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 50
AUTOMOTIVE FUEL TANK MARKET, BY VEHICLE TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 51
AUTOMOTIVE FUEL TANK MARKET, BY VEHICLE TYPE, 2022–2025 (USD MILLION)


TABLE 52
AUTOMOTIVE FUEL TANK MARKET, BY VEHICLE TYPE, 2026–2033 (USD MILLION)


TABLE 53
PASSENGER CARS FUEL TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 54
PASSENGER CARS FUEL TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 55
PASSENGER CARS FUEL TANK MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 56
PASSENGER CARS FUEL TANK MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 57
LIGHT COMMERCIAL VEHICLE FUEL TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 58
LIGHT COMMERCIAL VEHICLE FUEL TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 59
LIGHT COMMERCIAL VEHICLE FUEL TANK MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 60
LIGHT COMMERCIAL VEHICLE FUEL TANK MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 61
HEAVY COMMERCIAL VEHICLE FUEL TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 62
HEAVY COMMERCIAL VEHICLE FUEL TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 63
HEAVY COMMERCIAL VEHICLE FUEL TANK MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 64
HEAVY COMMERCIAL VEHICLE FUEL TANK MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 65
AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY, 2022–2025 (THOUSAND UNITS)


TABLE 66
AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY, 2026–2033 (THOUSAND UNITS)


TABLE 67
AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY, 2022–2025 (USD MILLION)


TABLE 68
AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY, 2026–2033 (USD MILLION)


TABLE 69
<45 LITER FUEL TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 70
<45 LITER FUEL TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 71
<45 LITER FUEL TANK MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 72
<45 LITER FUEL TANK MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 73
45–70 LITERS FUEL TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 74
45–70 LITERS FUEL TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 75
45–70 LITERS FUEL TANK MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 76
45–70 LITERS FUEL TANK MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 77
>70 LITER FUEL TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 78
> 70 LITER FUEL TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 79
>70 LITER FUEL TANK MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 80
> 70 LITER FUEL TANK MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 81
AUTOMOTIVE SELECTIVE CATALYTIC REDUCTION (SCR) TANK MARKET, BY VEHICLE TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 82
AUTOMOTIVE SELECTIVE CATALYTIC REDUCTION (SCR) TANK MARKET, BY VEHICLE TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 83
AUTOMOTIVE SELECTIVE CATALYTIC REDUCTION (SCR) TANK MARKET, BY VEHICLE TYPE, 2022–2025 (USD MILLION)


TABLE 84
AUTOMOTIVE SELECTIVE CATALYTIC REDUCTION (SCR) TANK MARKET, BY VEHICLE TYPE, 2026–2033 (USD MILLION)


TABLE 85
PASSENGER CARS SCR TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 86
PASSENGER CARS SCR TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 87
PASSENGER CARS SCR TANK MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 88
PASSENGER CARS SCR TANK MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 89
LIGHT COMMERCIAL VEHICLE SCR TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 90
LIGHT COMMERCIAL VEHICLE SCR TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 91
LIGHT COMMERCIAL VEHICLE SCR TANK MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 92
LIGHT COMMERCIAL VEHICLE SCR TANK MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 93
HEAVY COMMERCIAL VEHICLES SCR TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 94
HEAVY COMMERCIAL VEHICLES SCR TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 95
HEAVY COMMERCIAL VEHICLES SCR TANK MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 96
HEAVY COMMERCIAL VEHICLES SCR TANK MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 97
AUTOMOTIVE CNG TANK MARKET, BY TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 98
AUTOMOTIVE CNG TANK MARKET, BY TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 99
TYPE 1 CNG TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 100
TYPE 1 CNG TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 101
TYPE 2 CNG TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 102
TYPE 2 CNG TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 103
TYPE 3 CNG TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 104
TYPE 3 CNG TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 105
TYPE 4 CNG TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 106
TYPE 4 CNG TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 107
AUTOMOTIVE FUEL TANK MARKET, BY PROPULSION, 2022–2025 (THOUSAND UNITS)


TABLE 108
AUTOMOTIVE FUEL TANK MARKET, BY PROPULSION, 2026–2033 (THOUSAND UNITS)


TABLE 109
AUTOMOTIVE FUEL TANK MARKET, BY PROPULSION, 2022–2025 (USD MILLION)


TABLE 110
AUTOMOTIVE FUEL TANK MARKET, BY PROPULSION, 2026–2033 (USD MILLION)


TABLE 111
GASOLINE FUEL TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 112
GASOLINE FUEL TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 113
GASOLINE FUEL TANK MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 114
GASOLINE FUEL TANK MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 115
DIESEL FUEL TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 116
DIESEL FUEL TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 117
DIESEL FUEL TANK MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 118
DIESEL FUEL TANK MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 119
ALTERNATIVE FUEL TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 120
ALTERNATIVE FUEL TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 121
ALTERNATIVE FUEL TANK MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 122
ALTERNATIVE FUEL TANK MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 123
AUTOMOTIVE FUEL TANK MARKET, BY TANK TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 124
AUTOMOTIVE FUEL TANK MARKET, BY TANK TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 125
SADDLE FUEL TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 126
SADDLE FUEL TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 127
CONTOURED FUEL TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 128
CONTOURED FUEL TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 129
RECTANGULAR FUEL TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 130
RECTANGULAR FUEL TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 131
OTHER FUEL TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 132
OTHER FUEL TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 133
AUTOMOTIVE FUEL TANK MARKET, BY MATERIAL, 2022–2025 (THOUSAND UNITS)


TABLE 134
AUTOMOTIVE FUEL TANK MARKET, BY MATERIAL, 2026–2033 (THOUSAND UNITS)


TABLE 135
PLASTIC FUEL TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 136
PLASTIC FUEL TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 137
STEEL FUEL TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 138
STEEL FUEL TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 139
ALUMINUM FUEL TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 140
ALUMINUM FUEL TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 141
OTHER MATERIAL FUEL TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 142
OTHER MATERIAL FUEL TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 143
AUTOMOTIVE FUEL TANK MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)


TABLE 144
AUTOMOTIVE FUEL TANK MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)


TABLE 145
AUTOMOTIVE FUEL TANK MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 146
AUTOMOTIVE FUEL TANK MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 147
ASIA PACIFIC: AUTOMOTIVE FUEL TANK MARKET, BY COUNTRY, 2022–2025 (THOUSAND UNITS)


TABLE 148
ASIA PACIFIC: AUTOMOTIVE FUEL TANK MARKET, BY COUNTRY, 2026–2033 (THOUSAND UNITS)


TABLE 149
ASIA PACIFIC: AUTOMOTIVE FUEL TANK MARKET BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 150
ASIA PACIFIC: AUTOMOTIVE FUEL TANK MARKET, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 151
CHINA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 152
CHINA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 153
CHINA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (USD MILLION)


TABLE 154
CHINA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (USD MILLION)


TABLE 155
JAPAN: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 156
JAPAN: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 157
JAPAN: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (USD MILLION)


TABLE 158
JAPAN: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (USD MILLION)


TABLE 159
INDIA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 160
INDIA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 161
INDIA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (USD MILLION)


TABLE 162
INDIA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (USD MILLION)


TABLE 163
SOUTH KOREA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 164
SOUTH KOREA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 165
SOUTH KOREA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (USD MILLION)


TABLE 166
SOUTH KOREA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (USD MILLION)


TABLE 167
THAILAND: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 168
THAILAND: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 169
THAILAND: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (USD MILLION)


TABLE 170
THAILAND: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (USD MILLION)


TABLE 171
INDONESIA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 172
INDONESIA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 173
INDONESIA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (USD MILLION)


TABLE 174
INDONESIA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (USD MILLION)


TABLE 175
REST OF ASIA PACIFIC: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 176
REST OF ASIA PACIFIC: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 177
REST OF ASIA PACIFIC: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (USD MILLION)


TABLE 178
REST OF ASIA PACIFIC: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (USD MILLION)


TABLE 179
EUROPE: AUTOMOTIVE FUEL TANK MARKET, BY COUNTRY, 2022–2025 (THOUSAND UNITS)


TABLE 180
EUROPE: AUTOMOTIVE FUEL TANK MARKET, BY COUNTRY, 2026–2033 (THOUSAND UNITS)


TABLE 181
EUROPE: AUTOMOTIVE FUEL TANK MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 182
EUROPE: AUTOMOTIVE FUEL TANK MARKET, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 183
GERMANY: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 184
GERMANY: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 185
GERMANY: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (USD MILLION)


TABLE 186
GERMANY: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (USD MILLION)


TABLE 187
FRANCE: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 188
FRANCE: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 189
FRANCE: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (USD MILLION)


TABLE 190
FRANCE: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (USD MILLION)


TABLE 191
ITALY: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 192
ITALY: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 193
ITALY: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (USD MILLION)


TABLE 194
ITALY: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (USD MILLION)


TABLE 195
SPAIN: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 196
SPAIN: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 197
SPAIN: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (USD MILLION)


TABLE 198
SPAIN: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (USD MILLION)


TABLE 199
UK: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 200
UK: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 201
UK: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (USD MILLION)


TABLE 202
UK: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (USD MILLION)


TABLE 203
RUSSIA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 204
RUSSIA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 205
RUSSIA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (USD MILLION)


TABLE 206
RUSSIA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (USD MILLION)


TABLE 207
REST OF EUROPE: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 208
REST OF EUROPE: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 209
REST OF EUROPE: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (USD MILLION)


TABLE 210
REST OF EUROPE: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (USD MILLION)


TABLE 211
NORTH AMERICA: AUTOMOTIVE FUEL TANK MARKET, BY COUNTRY, 2022–2025 (THOUSAND UNITS)


TABLE 212
NORTH AMERICA: AUTOMOTIVE FUEL TANK MARKET, BY COUNTRY, 2026–2033 (THOUSAND UNITS)


TABLE 213
NORTH AMERICA: AUTOMOTIVE FUEL TANK MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 214
NORTH AMERICA: AUTOMOTIVE FUEL TANK MARKET, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 215
US: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 216
US: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 217
US: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (USD MILLION)


TABLE 218
US: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (USD MILLION)


TABLE 219
CANADA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 220
CANADA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 221
CANADA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (USD MILLION)


TABLE 222
CANADA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (USD MILLION)


TABLE 223
MEXICO: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 224
MEXICO: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 225
MEXICO: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (USD MILLION)


TABLE 226
MEXICO: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (USD MILLION)


TABLE 227
REST OF THE WORLD: AUTOMOTIVE FUEL TANK MARKET, BY COUNTRY, 2022–2025 (THOUSAND UNITS)


TABLE 228
REST OF THE WORLD: AUTOMOTIVE FUEL TANK MARKET, BY COUNTRY, 2026–2033 (THOUSAND UNITS)


TABLE 229
REST OF THE WORLD: AUTOMOTIVE FUEL TANK MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 230
REST OF THE WORLD: AUTOMOTIVE FUEL TANK MARKET, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 231
BRAZIL: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 232
BRAZIL: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 233
BRAZIL: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (USD MILLION)


TABLE 234
BRAZIL: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (USD MILLION)


TABLE 235
IRAN: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 236
IRAN: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 237
IRAN: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (USD MILLION)


TABLE 238
IRAN: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (USD MILLION)


TABLE 239
SOUTH AFRICA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 240
SOUTH AFRICA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 241
SOUTH AFRICA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2022–2025 (USD MILLION)


TABLE 242
SOUTH AFRICA: AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY TYPE, 2026–2033 (USD MILLION)


TABLE 243
OVERVIEW OF STRATEGIES DEPLOYED BY KEY COMPANIES


TABLE 244
AUTOMOTIVE FUEL TANK MARKET SHARE OF TOP FIVE PLAYERS, 2025


TABLE 245
AUTOMOTIVE FUEL TANK MARKET: REGIONAL TYPE FOOTPRINT, 2025


TABLE 246
AUTOMOTIVE FUEL TANK MARKET: VEHICLE TYPE FOOTPRINT, 2025


TABLE 247
AUTOMOTIVE FUEL TANK MARKET: MATERIAL TYPE FOOTPRINT, 2025


TABLE 248
AUTOMOTIVE FUEL TANK MARKET: PROPULSION TYPE FOOTPRINT, 2025


TABLE 249
AUTOMOTIVE FUEL TANK MARKET: KEY STARTUPS/SMES


TABLE 250
COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES


TABLE 251
AUTOMOTIVE FUEL TANK MARKET: PRODUCT LAUNCHES, JANUARY 2022–OCTOBER 2026


TABLE 252
AUTOMOTIVE FUEL TANK MARKET: DEALS, JANUARY 2022–OCTOBER 2026


TABLE 253
AUTOMOTIVE FUEL TANK MARKET: OTHER DEVELOPMENTS, JANUARY 2022–OCTOBER 2026


TABLE 254
OPMOBILITY: COMPANY OVERVIEW


TABLE 255
OPMOBILITY: PRODUCTS OFFERED


TABLE 256
OPMOBILITY: EXPANSIONS


TABLE 257
OPMOBILITY: OTHER DEVELOPMENTS


TABLE 258
KAUTEX TEXTRON: COMPANY OVERVIEW


TABLE 259
KAUTEX TEXTRON: PRODUCTS OFFERED


TABLE 260
KAUTEX TEXTRON: EXPANSIONS


TABLE 261
KAUTEX TEXTRON: OTHER DEVELOPMENTS


TABLE 262
TI AUTOMOTIVE: COMPANY OVERVIEW


TABLE 263
TI AUTOMOTIVE: PRODUCTS OFFERED


TABLE 264
TI AUTOMOTIVE: DEALS


TABLE 265
TI AUTOMOTIVE: EXPANSIONS


TABLE 266
TI AUTOMOTIVE: OTHER DEVELOPMENTS


TABLE 267
YAPP AUTOMOTIVE SYSTEMS CO., LTD.: COMPANY OVERVIEW


TABLE 268
YAPP AUTOMOTIVE SYSTEMS CO., LTD.: PRODUCTS OFFERED


TABLE 269
YAPP AUTOMOTIVE SYSTEMS CO., LTD.: EXPANSIONS


TABLE 270
MOTHERSON YACHIYO AUTOMOTIVE SYSTEMS: COMPANY OVERVIEW


TABLE 271
MOTHERSON YACHIYO AUTOMOTIVE SYSTEMS: PRODUCTS OFFERED


TABLE 272
MOTHERSON YACHIYO AUTOMOTIVE SYSTEMS: DEALS


TABLE 273
MOTHERSON YACHIYO AUTOMOTIVE SYSTEMS: OTHER DEVELOPMENTS


TABLE 274
MAGNA INTERNATIONAL: COMPANY OVERVIEW


TABLE 275
MAGNA INTERNATIONAL: PRODUCTS OFFERED


TABLE 276
MAGNA INTERNATIONAL INC.: PRODUCT LAUNCHES


TABLE 277
FUEL TOTAL SYSTEMS: COMPANY OVERVIEW


TABLE 278
FUEL TOTAL SYSTEMS: PRODUCTS OFFERED


TABLE 279
FUEL TOTAL SYSTEMS: OTHERS DEVELOPMENT


TABLE 280
UNIPRES CORPORATION: COMPANY OVERVIEW


TABLE 281
UNIPRES CORPORATION: PRODUCTS OFFERED


TABLE 282
UNIPRES CORPORATION: OTHERS DEVELOPMENT


TABLE 283
MARTINREA INTERNATIONAL INC.: PRODUCTS OFFERED


TABLE 284
MARTINREA INTERNATIONAL INC.: DEALS


TABLE 285
MARTINREA INTERNATIONAL INC.: OTHERS DEVELOPMENT


TABLE 286
DONGHEE HOLDINGS: COMPANY OVERVIEW


TABLE 287
DONGHEE HOLDINGS: PRODUCTS OFFERED


TABLE 288
DONGHEE HOLDINGS: DEALS


TABLE 289
SAKAMOTO INDUSTRY CO., LTD.: COMPANY OVERVIEW


TABLE 290
SAKAMOTO INDUSTRY CO., LTD.: PRODUCTS OFFERED


TABLE 291
SMA SERBATOI: COMPANY OVERVIEW


TABLE 292
SMA SERBATOI: PRODUCTS OFFERED


TABLE 293
SMA SERBATOI: PRODUCT LAUNCHES / DEVELOPMENTS


TABLE 294
CONTINENTAL AG: COMPANY OVERVIEW


TABLE 295
FUTABA INDUSTRIAL CO., LTD.: COMPANY OVERVIEW


TABLE 296
BENTELER: COMPANY OVERVIEW


TABLE 297
TOYODA GOSEI CO., LTD.: COMPANY OVERVIEW


TABLE 298
KONGSBERG AUTOMOTIVE: COMPANY OVERVIEW


TABLE 299
SPECTRA PREMIUM: COMPANY OVERVIEW


TABLE 300
BOYD WELDING LLC: COMPANY OVERVIEW


TABLE 301
ALLGAIER AUTOMOTIVE GMBH: COMPANY OVERVIEW


TABLE 302
POSCO: COMPANY OVERVIEW


TABLE 303
BAOSTEEL: COMPANY OVERVIEW


TABLE 304
DORMAN PRODUCTS, INC.: COMPANY OVERVIEW


TABLE 305
YEEDAH COMPOSITE MATERIAL CO., LTD.: COMPANY OVERVIEW


TABLE 306
NORTHSIDE INDUSTRIES: COMPANY OVERVIEW


LIST OF FIGURES


FIGURE 1
AUTOMOTIVE FUEL TANK SEGMENTATION AND REGIONAL SCOPE


FIGURE 2
STUDY PERIOD CONSIDERED


FIGURE 3
MARKET SCENARIO


FIGURE 4
AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY, 2026–2033 (USD MILLION)


FIGURE 5
MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN AUTOMOTIVE FUEL TANK MARKET, 2022–2026


FIGURE 6
DISRUPTIONS INFLUENCING GROWTH OF AUTOMOTIVE FUEL TANK MARKET


FIGURE 7
HIGH-GROWTH SEGMENTS IN AUTOMOTIVE FUEL TANK MARKET, 2026–2033


FIGURE 8
ASIA PACIFIC TO REGISTER HIGHEST CAGR IN AUTOMOTIVE FUEL TANK MARKET, IN TERMS OF VALUE, DURING FORECAST PERIOD


FIGURE 9
SHIFT TOWARD LIGHTWEIGHT AND INTEGRATED FUEL TANK SYSTEMS DRIVING AUTOMOTIVE FUEL TANK DEMAND


FIGURE 10
PASSENGER CARS DRIVE FUEL TANK DEMAND THROUGH HIGH PRODUCTION VOLUMES AND BROAD APPLICATIONS


FIGURE 11
GASOLINE PROPULSION MAINTAINS DEMAND THROUGH HIGH VEHICLE PRODUCTION AND FLEET PENETRATION


FIGURE 12
45 TO 70 LITER FUEL TANKS DRIVE DEMAND ACROSS HIGH-VOLUME VEHICLE APPLICATION


FIGURE 13
CONTOURED FUEL TANKS GAIN TRACTION THROUGH SPACE-EFFICIENT VEHICLE PACKAGING


FIGURE 14
PLASTIC FUEL TANKS LEAD THROUGH LIGHTWEIGHT, CORROSION RESISTANT, AND FLEXIBLE DESIGNS


FIGURE 15
CNG VEHICLE EXPANSION ACCELERATES DEMAND FOR ADVANCED HIGH-PRESSURE TANK SYSTEMS


FIGURE 16
COMMERCIAL VEHICLE GROWTH DRIVES SCR TANK DEMAND EXPANSION


FIGURE 17
AUTOMOTIVE FUEL TANK MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES


FIGURE 18
AUTOMOTIVE FUEL TANK MARKET: BEV VS TOTAL VEHICLE SALE, 2020–2026 (USD MILLION)


FIGURE 19
AUTOMOTIVE FUEL TANK MARKET: RAW MATERIAL PRICES, 2020–2025 (USD)


FIGURE 20
AUTOMOTIVE FUEL TANK MARKET: SUPPLY CHAIN ANALYSIS


FIGURE 21
AUTOMOTIVE FUEL TANK MARKET: ECOSYSTEM MAPPING


FIGURE 22
AVERAGE SELLING PRICE OF AUTOMOTIVE FUEL TANKS, BY TANK SIZE, 2024–2026 (USD)


FIGURE 23
AVERAGE SELLING PRICE OF AUTOMOTIVE FUEL TANKS, BY REGION, 2024–2026 (USD)


FIGURE 24
IMPORT DATA FOR HS CODE 870899-COMPLIANT PRODUCTS, BY COUNTRY, 2022–2025 (USD BILLION)


FIGURE 25
EXPORT DATA FOR HS CODE 870899-COMPLIANT PRODUCTS, BY COUNTRY, 2022–2025 (USD BILLION)


FIGURE 26
TRENDS AND DISRUPTIONS IMPACTING CUSTOMER BUSINESSES


FIGURE 27
INVESTMENT AND FUNDING, 2022–2025


FIGURE 28
SECTORS IMPACTED BY EU-INDIA FTA DEAL


FIGURE 29
IMPACT ON IMPORT DUTY FOR EUROPEAN VEHICLES DUE TO EU-INDIA FTA


FIGURE 30
IMPACT ON OEMS AND SUPPLIERS IN INDIA DUE TO EU-INDIA FTA


FIGURE 31
IMPACT ON AUTOMOTIVE COMPONENT TRADE DUE TO EU-INDIA FTA


FIGURE 32
AUTOMOTIVE FUEL TANK TECHNOLOGY AND PRODUCT ROADMAP


FIGURE 33
PUBLICATION TRENDS, 2015–2026


FIGURE 34
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP APPLICATIONS


FIGURE 35
KEY BUYING CRITERIA FOR TOP APPLICATIONS


FIGURE 36
AUTOMOTIVE FUEL TANK MARKET, BY VEHICLE TYPE, 2026 VS. 2033


FIGURE 37
AUTOMOTIVE FUEL TANK MARKET, BY CAPACITY, 2026 VS. 2033


FIGURE 38
AUTOMOTIVE SELECTIVE CATALYTIC REDUCTION (SCR) TANK MARKET, BY VEHICLE TYPE, 2026 VS. 2033


FIGURE 39
AUTOMOTIVE CNG TANK MARKET, BY TYPE, 2026 VS. 2033


FIGURE 40
AUTOMOTIVE FUEL TANK MARKET, BY PROPULSION, 2026 VS. 2033


FIGURE 41
AUTOMOTIVE FUEL TANK MARKET, BY TANK TYPE, 2026 VS. 2033


FIGURE 42
AUTOMOTIVE FUEL TANK MARKET, BY MATERIAL, 2026 VS. 2033


FIGURE 43
AUTOMOTIVE FUEL TANK MARKET, BY REGION, 2026 VS. 2033


FIGURE 44
ASIA PACIFIC: AUTOMOTIVE FUEL TANK MARKET SNAPSHOT


FIGURE 45
EUROPE: AUTOMOTIVE FUEL TANK MARKET SNAPSHOT


FIGURE 46
NORTH AMERICA: AUTOMOTIVE FUEL TANK MARKET SNAPSHOT


FIGURE 47
REST OF THE WORLD: AUTOMOTIVE FUEL TANK MARKET SNAPSHOT


FIGURE 48
AUTOMOTIVE FUEL TANK MARKET SHARE ANALYSIS, 2025


FIGURE 49
AUTOMOTIVE FUEL TANK MARKET: REVENUE ANALYSIS OF KEY PLAYERS, 2021–2025


FIGURE 50
COMPANY VALUATION OF KEY PLAYERS, 2025 (USD BILLION)


FIGURE 51
FINANCIAL METRICS OF KEY PLAYERS (EV/EBITDA)


FIGURE 52
AUTOMOTIVE FUEL TANK MARKET: BRAND/PRODUCT COMPARISON


FIGURE 53
AUTOMOTIVE FUEL TANK MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025


FIGURE 54
AUTOMOTIVE FUEL TANK MARKET: COMPANY FOOTPRINT, 2025


FIGURE 55
AUTOMOTIVE FUEL TANK MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025


FIGURE 56
OPMOBILITY: COMPANY SNAPSHOT


FIGURE 57
TI AUTOMOTIVE: COMPANY SNAPSHOT


FIGURE 58
YAPP AUTOMOTIVE SYSTEMS CO., LTD.: COMPANY SNAPSHOT


FIGURE 59
MAGNA INTERNATIONAL: COMPANY SNAPSHOT


FIGURE 60
UNIPRES CORPORATION: COMPANY SNAPSHOT


FIGURE 61
AUTOMOTIVE FUEL TANK MARKET: RESEARCH DESIGN


FIGURE 62
RESEARCH DESIGN MODEL


FIGURE 63
KEY INDUSTRY INSIGHTS


FIGURE 64
BREAKDOWN OF PRIMARY INTERVIEWS


FIGURE 65
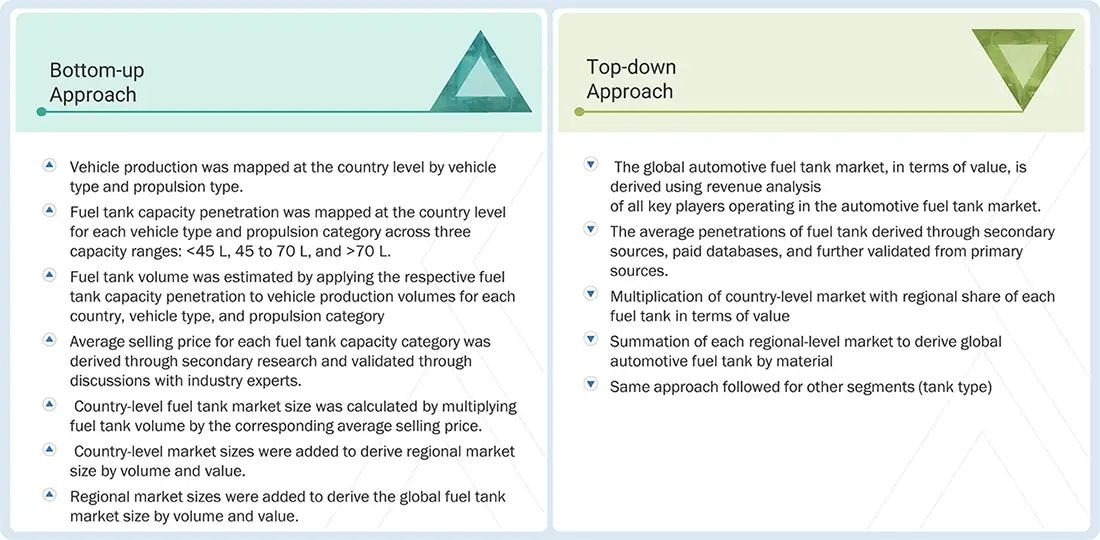
BOTTOM-UP APPROACH


FIGURE 66
TOP-DOWN APPROACH


FIGURE 67
MARKET BREAKDOWN AND DATA TRIANGULATION


FIGURE 68
MARKET GROWTH PROJECTIONS FROM SUPPLY-SIDE DRIVERS AND OPPORTUNITIES


Methodology

Various secondary sources, directories, and databases were used to identify and collect information for an extensive automotive fuel tank market study. The study involved four main activities in estimating the current size of the market: secondary research, validation through primary research, assumptions, and market analysis. The research study involved various secondary sources, such as company annual reports/presentations, industry association publications, automotive wiring harness magazine articles, directories, technical handbooks, World Economic Outlook, trade websites, technical articles, and databases, which were used to identify and collect information for an extensive study of the automotive fuel tank market. Primary sources experts from automotive OEMs, Tier 1 suppliers, and fuel tank manufacturers were interviewed to obtain and verify critical information and assess prospects and market estimations.

Secondary Research

Secondary sources referred to for this research study included automotive fuel tank industry organizations; corporate filings such as annual reports, investor presentations, and financial statements; trade and business whitepapers and databases; and articles from recognized associations and government publishing sources. The secondary data was collected and analyzed to arrive at the overall market size, which was further validated by primary research.

Primary Research

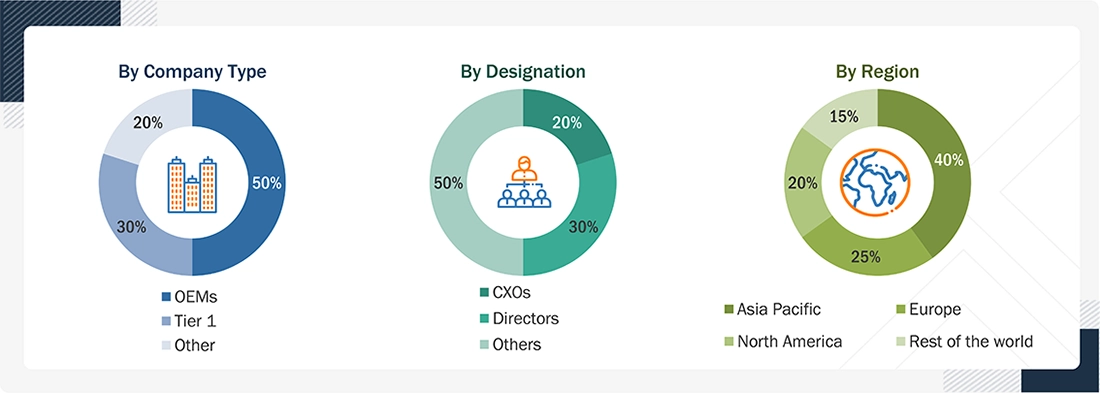
Extensive primary research was conducted after acquiring an understanding of this market scenario through secondary research. Several primary interviews were conducted with market experts from the demand- and supply-side OEMs (in terms of component supply, country-level government associations, and trade associations) and component manufacturers across four major regions, namely, Asia Pacific- 40%, Europe- 25%, North America- 20%, and Rest of the World-15%. Approximately 60% and 40% of primary interviews were conducted from the demand and supply side, respectively. Primary data were collected through questionnaires, emails, LinkedIn, and telephonic interviews. In the canvassing of primary interviews, various departments within organizations, such as sales, operations, and administration, were covered to provide a holistic viewpoint in the report.

Brief sessions with highly experienced independent consultants were conducted to reinforce findings from primaries after interacting with industry experts. This, along with the in-house subject matter experts’ opinions, led to the findings, as described in the remainder of this report.

In the primary research process, various primary sources from the supply and demand sides were interviewed to obtain qualitative and quantitative information for the report. The primary sources from the supply side included industry experts, such as Vice Presidents (VPs), marketing directors, technology and innovation directors, and related key executives from various key companies and organizations. The primary sources from the demand side included end users, such as Chief Information Officers (CIOs), consultants, service professionals, technicians and technologists, and managers at public and investor-owned utilities.

Automotive Fuel Tank Market 
 Size, and Share

Note: Tier 1 suppliers include automotive system and component suppliers using test equipment for component and system validation.

To know about the assumptions considered for the study, download the pdf brochure

Market Size Estimation

The automotive fuel tank market was estimated and validated using both top-down and bottom-up approaches. In the top-down approach, the global market value was derived through revenue analysis of key fuel tank manufacturers. Average fuel tank penetration was established using secondary sources, paid databases, and primary research. Country-level market values were allocated based on the regional share of fuel tank segments, with regional values aggregated to derive the global market by material type and other segments. In the bottom-up approach, fuel tank-equipped vehicle production units were considered at the country level. Fuel tank penetration was identified through OEM model mapping, vehicle production data, company disclosures, and secondary research across passenger cars, LCVs, and HCVs. Fuel tank-equipped vehicles are segmented by vehicle type, propulsion, and tank capacity. Average fuel tank value per vehicle was determined through primary and secondary research, considering capacity, material, configuration, and vehicle application. Country-level volumes were multiplied by the average tank value to determine market value, which was aggregated to regional and global levels.

Automotive Fuel Tank Market Top Down and Bottom Up Approach

Data Triangulation

After arriving at the overall market size using the market size estimation processes as explained above, the market was split into several segments and subsegments. To complete the overall market engineering process and arrive at the exact statistics of each market segment and subsegment, data triangulation and market breakdown procedures were employed, wherever applicable. The data was triangulated by studying various factors and trends from both the demand and supply sides.

Market Definition

Automotive fuel tanks refer to fuel storage systems designed to safely store and supply fuel to internal combustion engines and hybrid vehicles while meeting requirements for safety, emissions, durability, and vehicle packaging. The market encompasses plastic fuel tanks, steel fuel tanks, aluminum fuel tanks, multilayer plastic tanks, pressure-resistant hybrid tanks, CNG tanks, saddle tanks, rectangular tanks, contoured tanks, and other specialized tank designs. These systems support gasoline, diesel, CNG, and hybrid vehicle applications across passenger cars, LCVs, and HCVs. The market also includes integrated fuel tank solutions incorporating fuel delivery, vapor management, venting, sensing, valves, leak detection, and pressure management, while excluding hydrogen storage systems and fuel tanks for two-wheelers.

Key Stakeholders

  • Automotive OEMs
  • Tier 1 Automotive Fuel System and Component Suppliers
  • Automotive Fuel Tank Manufacturers
  • Plastic, Steel, and Aluminum Material Suppliers
  • Polymer and Barrier Material Manufacturers
  • Fuel Pump, Valve, and Fuel Delivery Suppliers
  • Vapor Management and EVAP System Suppliers
  • Fuel Level, Pressure, and Leak Detection Sensor Suppliers
  • CNG Fuel System and Tank Manufacturers
  • Automotive Testing, Inspection, and Certification Companies
  • Independent Fuel Tank Testing and Validation Service Providers
  • Automotive R&D and Engineering Centers
  • Automotive Manufacturing and Assembly Plants
  • Fuel Tank Tooling and Blow Molding Equipment Suppliers
  • Fuel Tank Component and Closure Manufacturers
  • Automotive Aftermarket Fuel Tank Suppliers
  • Commercial Vehicle and Fleet Operators
  • Fuel and CNG Infrastructure Providers
  • Government and Automotive Regulatory Authorities
  • Automotive Standards and Certification Organizations
  • Technical Universities and Research Institutes
  • Automotive Engineering and Consulting Firms
  • Automotive Quality and Compliance Service Providers

Report Objectives

  • To segment and forecast the automotive fuel tank market in terms of value (USD million)
  • By vehicle type
  • By propulsion
  • By Tank Capacity
  • SCR Tank By Vehicle Type
  • Region (Asia Pacific, Europe, North America, and Rest of the World)
  • To segment and forecast the automotive fuel tank market in terms of volume (thousand units)
  • By Tank Type
  • By Material Type
  • By CNG Tank Type
  • To analyze regional markets for growth trends, prospects, and their contribution to the overall market
  • To define, describe, and forecast the size of the market with respect to growth trends and prospects, and determine the contribution of the segments to the total market
  • To provide detailed information regarding the major factors (drivers, challenges, restraints, and opportunities) influencing market growth
  • To strategically analyze markets with respect to individual growth trends, prospects, and contribution to the total market
  • To analyze opportunities for stakeholders and the competitive landscape for market leaders
  • To study the following with respect to the market -
  • Supply Chain Analysis
  • Ecosystem Analysis
  • Pricing Analysis
  • Technology Analysis
  • HS Code
  • Case Study Analysis
  • Patent Analysis
  • Impact of 2025 India-EU Trade Deal
  • Regulatory Landscape
  • Key Stakeholders and Buying Criteria
  • Key Conferences & Events
  • To strategically profile key players and comprehensively analyze their market share and core competencies
  • To track and analyze competitive developments such as deals (mergers & acquisitions, partnerships, collaborations), product developments, and other activities carried out by key industry participants

Available customizations:

With the given market data, MarketsandMarkets offers customizations in line with company-specific needs.

  • Automotive fuel tank market, by propulsion, at the country level
  • Additional country mapping (up to 3 in the report)

Company Information

  • Profiling of additional market players (up to 5)


Personalize This Research

  • Triangulate with your Own Data
  • Get Data as per your Format and Definition
  • Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
  • Any level of Personalization
Request A Free Customisation

Let Us Help You

  • What are the Known and Unknown Adjacencies Impacting the Automotive Fuel Tank Market
  • What will your New Revenue Sources be?
  • Who will be your Top Customer; what will make them switch?
  • Defend your Market Share or Win Competitors
  • Get a Scorecard for Target Partners
Customized Workshop Request

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements

Get 10% Free Customisation

TESTIMONIALS

Growth opportunities and latent adjacency in Automotive Fuel Tank Market

avtar

Amey

Nov, 2019

I need asap a breakdown of the mexico passenger vehicle tank market by single layer plastic tank vs multi layer plastic tank vs metal tanks.

avtar

Amey

Nov, 2019

Please quote the price and please advise if there is any discount. Furthermore, could we have few pages for reference before purchase? Thank you..

avtar

cliff

Mar, 2020

What is the capacity of a 3.75-liter tank?.

THIS REPORT TELLS YOU

How big the Automotive Fuel Tank market is, and who leads it.

GROWTHIQ TELLS YOU NEW

Where your company should play next, and who is taking your share.

Get your company's view of this market. Free snapshot.

DMCA.com Protection Status
popup img