Automotive Seats Market

Automotive Seats Market ICE & EV, by Seat Type (Bucket, Split Bench), Trim Material (Synthetic Leather, Genuine Leather, Fabric), Vehicle Type (ICE, EV, OHV, ATV, LSV), Technology, Component, Material, Sales Channel and Region - Global Forecast to 2033


OVERVIEW
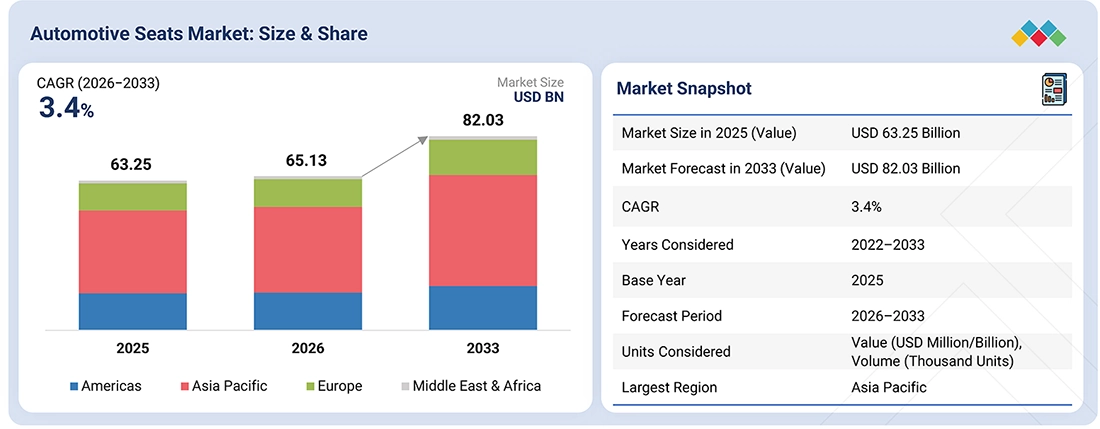
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
The global automotive seats market size was valued at USD 65.13 billion in 2026 and is expected to reach USD 82.03 billion by 2033, at a CAGR of 3.4%, during the forecast period. Asia Pacific remains the dominant market for automotive seats. The market is transitioning from supplying conventional seating assemblies to delivering highly integrated advanced seating systems that combine structural components, comfort technologies, electronics, and safety functions. The market spans a wide range of seat technologies, from standard and powered seats to heated, ventilated, massage, and memory-enabled seats, with feature adoption varying by vehicle segment and price point. Demand across the market is closely linked to vehicle type and propulsion technology. Passenger cars, particularly SUVs and premium models, are driving adoption of powered, heated, ventilated, and memory seats as manufacturers compete on cabin comfort and interior differentiation. In battery electric vehicles and plug-in hybrid vehicles, seat systems are engineered using advanced high-strength steel, aluminum, magnesium, and optimized polyurethane foam to reduce weight while accommodating additional electronic features that enhance the in-cabin experience.
KEY TAKEAWAYS
-
AUTOMOTIVE SEATS MARKET, BY REGIONAsia Pacific leads the regional automotive seats market, contributing 55.7% in 2026.
-
BY TECHNOLOGYPowered technology type is expected to register fastest growth of 4.6% by volume in automotive seats market during the forecast period.
-
BY VEHICLE TYPEThe passenger cars segment is expected to dominate the automotive seats market with an 81.7% share in 2026.
-
BY SEAT TYPEBucket seats are projected to hold a larger market share in terms of value than split bench seats in 2026.
-
BY TRIM MATERIALSynthetic leather segment is expected to dominate the automotive seats market in 2026.
-
OFF-HIGHWAY EQUIPMENT, BY VEHICLE TYPEConstruction and mining equipment is expected to grow at the fastest rate in the automotive seats market during the forecast period.
-
COMPETITIVE LANDSCAPE - KEY PLAYERS (AUTOMOTIVE SEATS)Major market players have adopted both organic and inorganic strategies, including partnerships and investments. Key players include Lear Corporation (US), Adient Plc (US), Forvia (France), Magna International (Canada), and Toyota Boshoku Corporation (Japan).
-
COMPETITIVE LANDSCAPE - KEY PLAYERS (AUTOMOTIVE SEAT COMPONENTS)Leading seat component manufacturers such as Brose Fahrzeugteile, NHK Spring, Aisin Shiroki Corporation, and Fisher Dynamics are strengthening their market positions through investments in lightweight structures, advanced seat mechanisms, electric adjustment systems, and integrated seating technologies tailored to evolving OEM requirements.
In the automotive seats market, product innovation is increasingly focused on integrating intelligent seating functions without compromising safety, weight, or manufacturing efficiency. The market is witnessing greater adoption of occupant classification sensors, seat occupancy detection, thermal comfort systems, and software-controlled seat adjustment that interact with vehicle electronic architectures. At the same time, OEMs are expanding the use of premium trim materials, including genuine leather and high-quality synthetic leather, while optimizing seat structures and foam designs to meet stringent crash performance, sustainability, and vehicle lightweighting targets. This shift is positioning automotive seats as one of the most sophisticated and value-intensive systems within modern vehicle interiors. In addition, ADAS and advanced safety features are shifting automotive seats from passive comfort components toward integrated safety systems, with occupant monitoring, seatbelt detection, smart airbags, and occupant classification increasingly linked with seat systems. This is driving greater integration of sensors, electronics, and safety functions within seats, while enabling adaptive seat positioning and occupant protection as vehicles move toward higher levels of automation.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
The automotive seats market is experiencing a shift as OEMs increasingly use seating systems to differentiate vehicles through comfort, safety, connectivity, and digital user experiences rather than treating seats as purely mechanical components. Rising demand for software-defined vehicles, electric vehicles, and premium cabin features is driving adoption of intelligent seating systems with integrated electronic controls, occupant sensing, thermal comfort, memory functions, and personalized settings. At the same time, pressure to reduce vehicle weight, improve sustainability, and simplify manufacturing is accelerating the transition toward lightweight materials, modular seat architectures, and digitally engineered platforms. These trends are reshaping customer requirements, encouraging seat suppliers to expand beyond conventional manufacturing and deliver integrated, software-enabled seating solutions that create higher value throughout the automotive ecosystem.
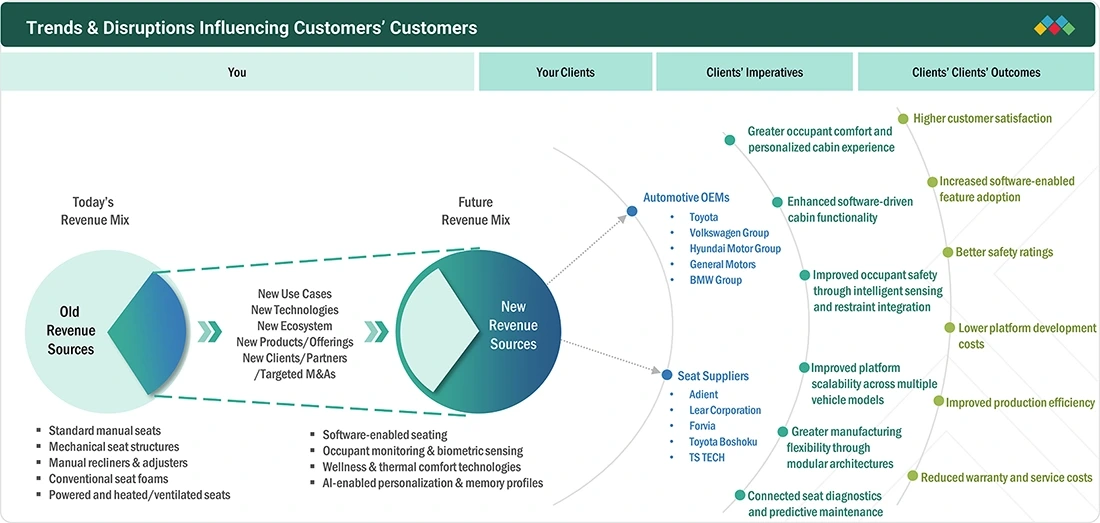
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Level
-
Software-defined vehicle (SDV) architectures transforming seats into intelligent cabin platforms

-
Interior premiumization increasing content value of automotive seating systems


Level
-
Increasing shift toward integrated interior modules reducing supplier value capture


Level
-
Intelligent seating systems creating new revenue pools beyond traditional hardware

-
Electrification and autonomous mobility driving demand for reconfigurable seating architectures


Level
-
Balancing comfort, safety, weight, and cost within a single seat platform

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Software-defined vehicle (SDV) architectures transforming seats into intelligent cabin platforms
Software-Defined Vehicle (SDV) architectures are transforming automotive seats from standalone mechanical components into intelligent cabin systems, increasing demand for advanced seating technologies. SDVs use centralized or zonal computing platforms that manage seat adjustment, heating, ventilation, massage, memory functions, occupant detection, and safety features through software. This allows new seat functions to be added or enhanced through over-the-air (OTA) updates without hardware replacement. As OEMs transition to centralized electrical and electronic architectures, seat manufacturers are integrating smart actuators, embedded controllers, communication modules, and software-capable electronics, increasing both seat functionality and value per vehicle
Restraint: Increasing shift toward integrated interior modules reducing supplier value capture
Vehicle interiors are being developed as integrated cabin systems, where seating is engineered together with instrument panels, center consoles, door panels, HVAC, airbags, occupant monitoring systems, ambient lighting, and digital cockpit technologies rather than as an independent component. OEMs are adopting this system-level approach to reduce assembly complexity, improve packaging efficiency, simplify vehicle architectures, and accelerate platform standardization across multiple vehicle models. As a result, procurement is gradually shifting from standalone seating systems toward complete interior modules supplied by companies capable of designing, validating, and integrating multiple cabin subsystems under a single engineering program. As OEMs award contracts to suppliers with broader interior integration capabilities, independent seat manufacturers face greater pricing pressure, lower differentiation opportunities, and reduced negotiating power, particularly in high-volume vehicle platforms where standardized modular interiors are prioritized
Opportunity: Intelligent seating systems creating new revenue pools beyond traditional hardware
The convergence of Software-Defined Vehicles (SDVs), artificial intelligence, and occupant-centric vehicle design is transforming automotive seats from passive mechanical assemblies into intelligent, connected systems capable of delivering software-enabled features throughout the vehicle lifecycle. Modern seating systems are increasingly integrating occupant monitoring systems (OMS), biometric sensing, pressure sensors, AI-based posture detection, wellness monitoring, adaptive lumbar support, haptic feedback, personalized memory profiles, and seat-based human-machine interfaces (HMIs). These technologies enable seats to continuously exchange data with ADAS, digital cockpits, climate control, and infotainment systems, allowing comfort, safety, and wellness functions to be optimized based on occupant behavior. Unlike conventional seating systems, many of these capabilities can be enhanced through over-the-air (OTA) software updates, extending functionality without requiring hardware replacement
Challenge: Balancing comfort, safety, weight, and cost within a single seat platform
Modern automotive seats are expected to deliver high levels of comfort, advanced safety, lightweight construction, and cost competitiveness simultaneously, making seat development increasingly complex. Consumers and OEMs demand features such as powered adjustment, heating, ventilation, massage, memory functions, ergonomic support, and premium materials, while safety regulations require integration of airbags, seat belt systems, occupant classification sensors, head restraints, and structures capable of withstanding stringent crash performance requirements. At the same time, vehicle manufacturers are pursuing aggressive weight reduction targets to improve fuel efficiency and electric vehicle driving range, requiring seat suppliers to adopt lightweight materials, optimized structures, and compact electronic systems without compromising durability or occupant protection. Achieving these conflicting objectives within a single seat platform presents a significant engineering challenge throughout the product development process
AUTOMOTIVE SEATS MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Lear developed INTU intelligent seating, which uses sensors, electronics, and software to continuously monitor seat and occupant conditions and automatically adjust functions such as lumbar support and bolsters. Lear has secured a production award with a European luxury automaker for this technology. | Enables personalized and automated seating comfort, while giving Lear an entry point into software-enabled seating and increasing the electronic content of its seat systems |
 |
Adient developed Flex 2, an autonomous vehicle seating concept that allows seats to rotate and change position while incorporating safety features such as integrated seat belts and controlled seat movement. | Enables flexible seating configurations for autonomous vehicles while maintaining occupant protection, allowing the cabin to support activities such as working, relaxing, and social interaction |
 |
FORVIA developed pneumatic lumbar support systems with compact packaging and four-way adjustment, and secured a production program with Hyundai Kia for three models in Europe and the US. | Provides greater lumbar comfort and adjustability while reducing packaging requirements, helping OEMs integrate advanced comfort functions within constrained seat space |
 |
Magna developed a reconfigurable seating system with power swivel seats, long power rails, and integrated seat belts. The seats could rotate up to 270 degrees, and the system entered mass production for a Chinese OEM in 2024. | Enables flexible cabin configurations and improved space utilization, allowing occupants to change seating orientation based on activities such as traveling, family use, or storage |
 |
Toyota Boshoku developed an autonomous driving safety seat with the seat belt integrated directly into the seat. The design supported occupant protection when the seat is positioned away from the conventional forward-facing position. | Enables safer alternative seating layouts for autonomous vehicles, allowing greater seating flexibility while retaining occupant restraint |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
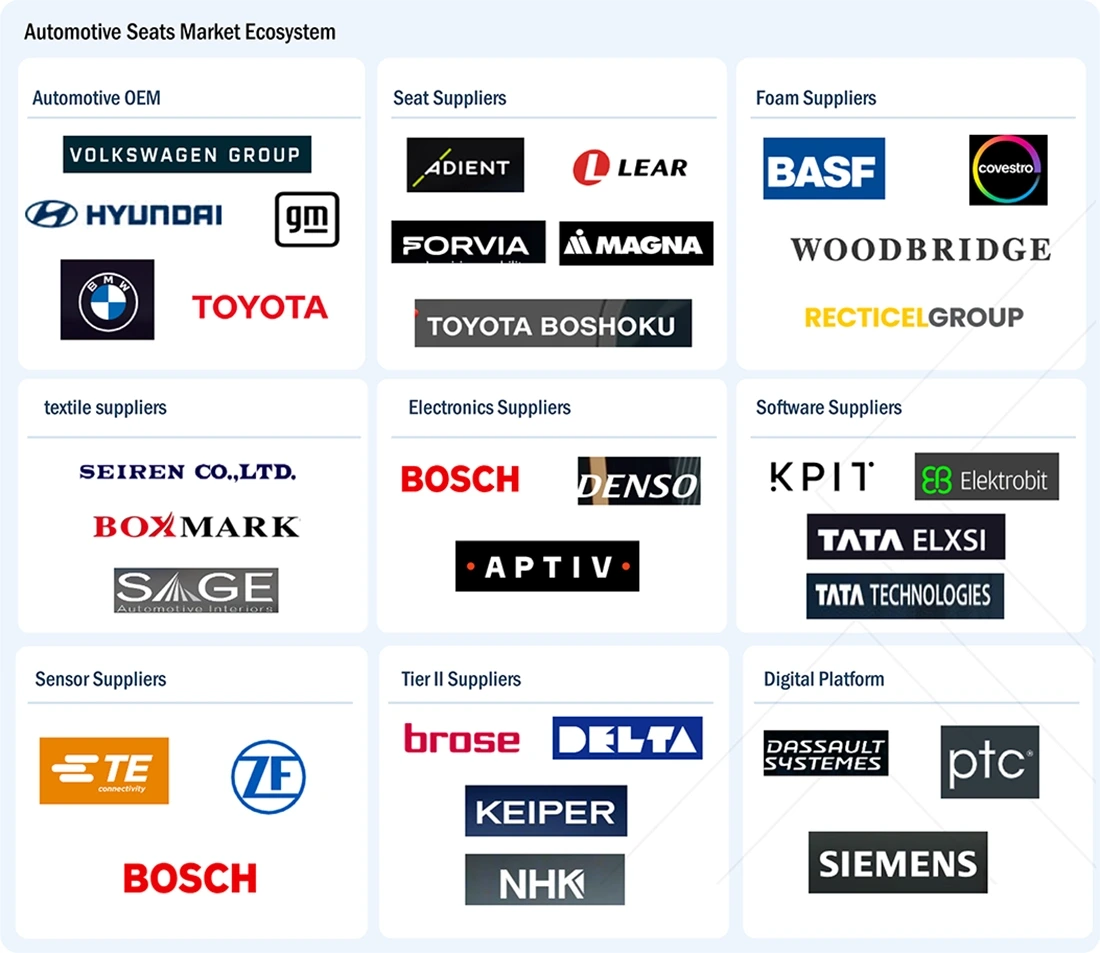
The automotive seats ecosystem consists of a network of material suppliers, component manufacturers, technology providers, and vehicle manufacturers working together to develop, manufacture, and integrate advanced seating systems. While OEMs define performance, safety, and comfort requirements, Tier 1 seat suppliers coordinate the integration of structural components, foam, trim materials, electronics, sensors, and software into complete seat modules. Supporting this ecosystem are specialized suppliers of materials, mechanisms, electronics, digital engineering platforms, and manufacturing technologies that enable the development of lightweight, intelligent, and highly customized seating systems for modern vehicles.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
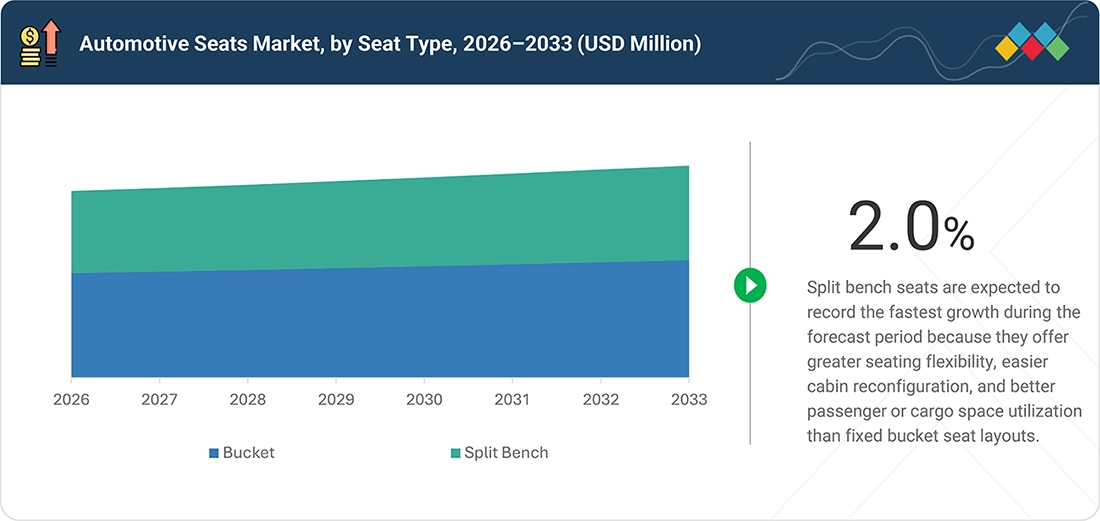
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
BY TECHNOLOGY
Powered technology type is expected to register the fastest growth by volume in the automotive seats market during the forecast period, at a projected 4.6%. Rising demand for adjustable, personalized, and comfort-focused seating is driving adoption across mid-range and premium vehicles. Powered seats use electric motors to control seat movement and positioning, letting occupants fine-tune their driving position with ease. As OEMs increasingly compete on cabin comfort and interior differentiation, powered functionality is shifting from a premium option toward a standard expectation.
BY VEHICLE TYPE
The passenger cars segment is expected to dominate the automotive seats market with an 81.7% share in 2026, supported by its maximum share in total vehicle production and higher seat installation volumes compared with commercial vehicles. Passenger cars, particularly SUVs and premium models, are also the primary adopters of powered, heated, ventilated, and memory seats. This concentration of advanced features raises the average seat content value within the segment. As global passenger car output continues to recover and premiumize, the segment is likely to retain its leading position throughout the forecast period.
BY SEAT TYPE
Bucket seats are projected to hold a larger market share, in terms of value, than split bench seats in 2026. Their individual occupant support and ergonomic design make them the preferred configuration across many passenger cars and SUVs. Because bucket seats accommodate powered adjustment, heating, ventilation, and side airbags more readily, they command a higher content value per unit. This positions bucket seats to benefit disproportionately as demand for comfort and safety features rises across vehicle segments.
BY TRIM MATERIAL
The synthetic leather segment is expected to dominate the automotive seats market in 2026. It offers a balance of premium appearance, durability, easy maintenance, and lower cost than genuine leather, supporting wider adoption across vehicle segments. Synthetic leather also aligns with growing sustainability and animal-free material preferences among OEMs and consumers. As manufacturers pursue premium interior aesthetics without the cost and variability of genuine leather, synthetic alternatives are increasingly specified across both mid-range and premium models.
OFF-HIGHWAY EQUIPMENT, BY VEHICLE TYPE
Construction and mining equipment is expected to grow at the fastest rate in the automotive seats market during the forecast period. Increasing equipment modernization and operator comfort requirements are driving adoption of suspension seats, ergonomic designs, and advanced seat adjustment features. Prolonged operating hours and harsh working conditions make vibration damping and operator support critical in these applications. As regulatory and productivity pressures push operators toward safer, more comfortable cabins, seat specifications in this segment continue to advance.
REGION
Asia Pacific is the largest region in global automotive seats market in 2026
Asia Pacific's automotive seat market is supported by rising adoption of SUVs, MPVs, and EVs, which are driving demand for more flexible, powered, heated, and ventilated seating. Growing vehicle localization and the expansion of domestic OEMs are also increasing demand for locally produced seat systems, while rising consumer expectations for comfort and premium interiors are encouraging the integration of advanced seating features beyond basic seat structures.
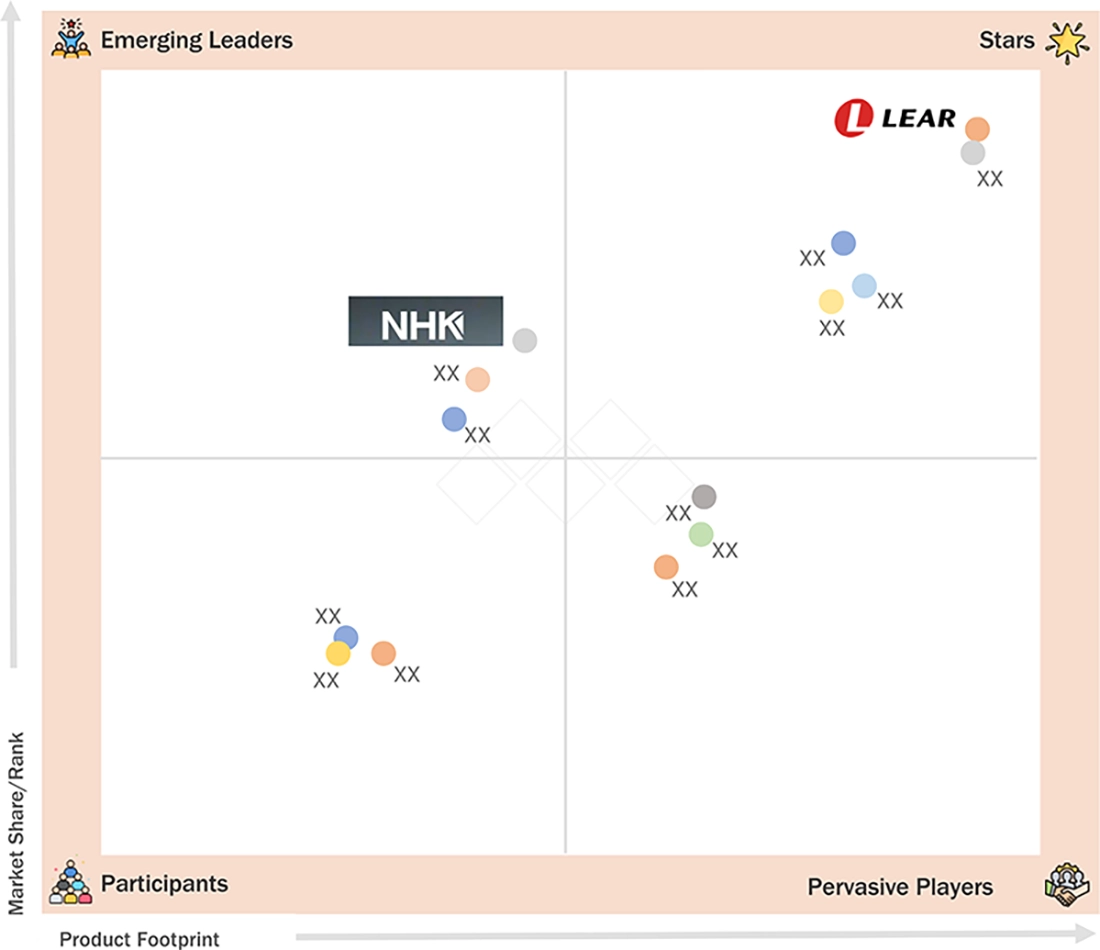
AUTOMOTIVE SEATS MARKET: COMPANY EVALUATION MATRIX
In the automotive seats market, Lear Corporation (Star) focuses on vertically integrated seating, combining complete seats, structures, mechanisms, materials, thermal comfort, and intelligent seating technologies, strengthening its position as a full seat system provider. NHK Spring Co., Ltd. (Emerging) focuses on lightweight seat structures, suspension seating, power seats, and application-specific designs for passenger cars and commercial vehicles, expanding its seating portfolio through specialized engineering capabilities.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- Lear Corporation (US)
- Adient Plc (US)
- Forvia (France)
- Magna International (Canada)
- Toyota Boshoku Corporation (Japan)
- NHK Spring Co., Ltd. (Japan)
- TS Tech Co., Ltd. (Japan)
- Aisin Corporation (Japan)
- Tachi-S Co., Ltd. (Japan)
- Gentherm (US)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2025 (Value) | USD 63.25 Billion |
| Market Forecast in 2033 (Value) | USD 82.03 Billion |
| Growth Rate | CAGR of 3.4% from 2026-2033 |
| Years Considered | 2022-2033 |
| Base Year | 2025 |
| Forecast Period | 2026-2033 |
| Units Considered | Value (USD Million/Billion), Volume (Thousand Units) |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered |
|
| Regions Covered | Asia Pacific, Europe, Americas, and Middle East & Africa |
WHAT IS IN IT FOR YOU: AUTOMOTIVE SEATS MARKET REPORT CONTENT GUIDE
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Benchmark supplier capabilities in intelligent and personalized seating | Conducted competitive benchmarking of leading seat suppliers across occupant sensing, thermal comfort, massage, wellness, and automated adjustment technologies, including technology maturity and OEM adoption | Identifies technology leaders and whitespace opportunities, helping prioritize intelligent seating technologies with strong OEM adoption potential |
| Assess the impact of EV architectures on seat design and space utilization | Evaluated EV specific seating developments across lightweight structures, slim seat architectures, long rail systems, battery packaging, and solutions designed to increase passenger footroom and cabin space | Supports EV seat architecture decisions by balancing seat weight, passenger space, battery packaging, and cabin flexibility |
| Identify opportunities to expand premium seating features across vehicle segments | Assessed adoption of heating, ventilation, massage, personalized adjustment, and wellness features across vehicle segments, including modular solutions designed for broader vehicle applications | Identifies premium features with potential for wider adoption and supports feature prioritization based on comfort, packaging, and cost considerations |
| Evaluate lightweighting approaches that maintain comfort and safety | Benchmarked lightweight seat structures, thin seat architectures, low weight cushioning, recyclable materials, and material reduction initiatives across leading seat suppliers | Identifies practical lightweighting pathways that support EV efficiency targets while maintaining seating performance and safety |
| Identify emerging sustainable seating technologies and materials | Assessed recyclable cushioning, recycled textiles, reduced material usage, and sustainable seat structures, including emerging material technologies from leading seat suppliers | Helps align seat portfolios with OEM sustainability targets while identifying opportunities to reduce material consumption, weight, and environmental impact |
RECENT DEVELOPMENTS
- July 2026 : Tachi-S Co., Ltd., through its joint venture subsidiary Uno Minda Tachi-S Seating (UMTS), announced plans to establish a new greenfield manufacturing plant in Chhatrapati Sambhajinagar, Maharashtra, to produce seating systems for four-wheeler passenger vehicles.
- June 2026 : Toyota Boshoku and Huaqin Technology established a joint venture, Toyota Boshoku Huaqin (Shanghai) Automotive Electronics Co., Ltd., which officially opened in Shanghai on June 30. The JV focused on smart cockpit integration, combining automotive interior expertise with electronics capabilities for next-generation vehicle interiors.
- April 2026 : Adient introduced its Proforce massage flow seating technology, aimed at enhancing comfort and innovation for global automakers. The mechanical massage system targets lower-back fatigue and is designed for integration into front and rear automotive seats, including Chinese OEM models.
- February 2026 : AISIN Corporation, Toyota Tsusho, and Minth formed a new joint venture in Ontario to boost aluminum body frame parts supply for electric vehicle battery structures across the North American market. The JV aimed to strengthen regional EV component manufacturing capabilities.
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
Methodology
The research study involved extensive use of secondary sources, such as company annual reports/presentations, industry association publications, automotive magazine articles, directories, technical handbooks, the World Economic Outlook, trade websites, technical articles, and databases, to identify and collect information on the Automotive Seats market. Primary interviews have been conducted to obtain and verify critical qualitative and quantitative information as well as assess the prospects of the industry. Primary sources include experts from core and related industries, suppliers, manufacturers, distributors, service providers, technology developers, and organizations related to various segments of the Automotive Seats market value chain. Detailed interviews have been conducted with various primary respondents that include key industry participants, Subject Matter Experts (SMEs), C-level executives of key market players, and industry consultants.
Secondary Research
Secondary sources referred for this research study include automotive industry organizations such as the, International Organization of Motor Vehicle Manufacturers (OICA), United Nations Economic Commission for Europe (UNECE), European Automobile Manufacturers’ Association (ACEA), China Association of Automobile Manufacturers (CAAM), National Highway Traffic Safety Administration (NHTSA), Society of Indian Automobile Manufacturers (SIAM) among others; corporate filings such as annual reports, investor presentations, and financial statements; and trade, business, and automotive associations. Secondary data has been collected and analyzed to arrive at the overall market size, which is further validated by primary research.
Primary Research
Extensive primary research was conducted after acquiring an understanding of the automotive seats market scenario through secondary research. Several primary interviews were conducted with market experts from the OEMs (automotive seat manufacturers) and automotive seat component providers across four major regions, namely, Asia Pacific, Europe, Americas, and Middle East & Africa. Approximately 55%, 25%, and 20% of the primary interviews were conducted with the automotive seat manufacturers, automotive seat component manufacturers, and OEMs, respectively. Primary data was collected through questionnaires, emails, and telephonic interviews. Various departments within organizations, including sales, operations, and administration, were contacted to provide a holistic viewpoint in reports while canvassing primaries. After interacting with industry participants, some brief sessions were conducted with experienced independent consultants to reinforce the findings from the primaries. This, along with the opinions of in-house subject matter experts, led to the findings delineated in the rest of this report.
Primary interviews have been conducted to gather insights, including automotive seats market sizing estimation and forecast, future trends, and upcoming technologies in the market. Data triangulation of all these points was done using the information gathered from secondary research and model mapping. Stakeholders from the demand and supply sides have been interviewed to understand their views on the aforementioned points.
The following is a breakdown of the primary respondents:
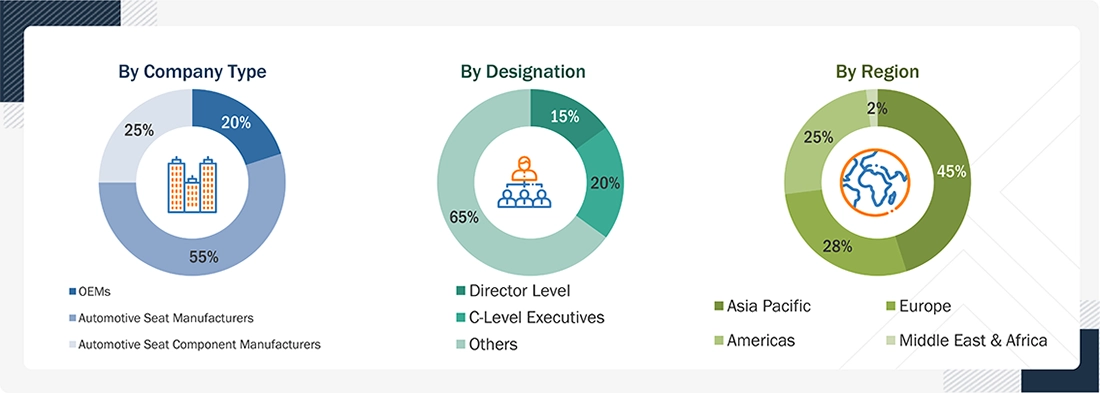
Note: Others include sales, marketing, and product managers.
Company tiers are based on the value chain; revenue of the company is not considered.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
A detailed market estimation approach was followed to estimate and validate the value and volume of the Automotive seats market and other dependent submarkets, as mentioned below:
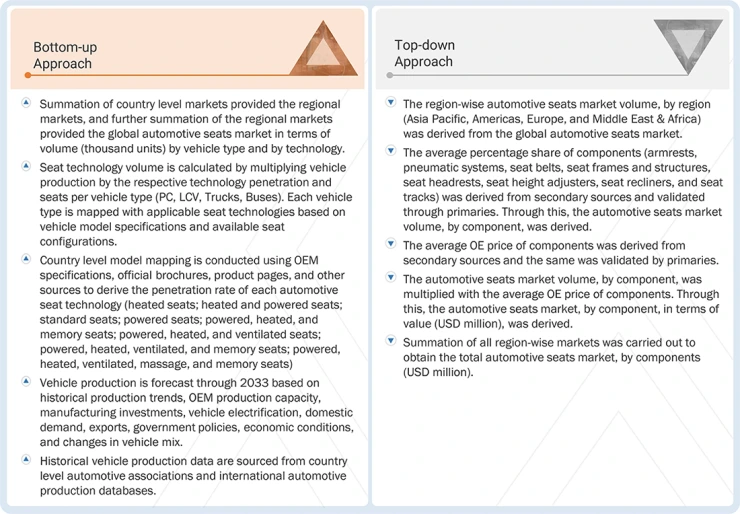
- The bottom-up and top-down approaches have been used to estimate and validate the size of the automotive seats market. The automotive seats market, by technology, in terms of value and volume, is derived by identifying the country-level production numbers of each vehicle type. Forecasts are based on the expected penetration of seat technologies across vehicle segments, considering OEM adoption plans, vehicle electrification, premiumization, safety and comfort requirements, and increasing integration of powered, heated, ventilated, massage, and memory functions.
- The market size was derived using parameters such as production of vehicle types (passenger cars, LCVs, heavy trucks, and buses) and corresponding penetration of the technologies considered under the scope. Forecasts are based on expected vehicle production by country and vehicle type, considering OEM production plans, regional demand trends, economic conditions, electrification, and capacity expansion or rationalization.
- Key players in the automotive seats market were identified through secondary research, and their global market rankings were determined through primary and secondary research.
- The research methodology included the study of annual and quarterly financial reports, regulatory filings of major market players, and interviews with industry experts to gain detailed market insights.
- All major penetration rates, percentage shares, splits, and breakdowns for the automotive seats market were determined through secondary sources and verified through primary sources.
- All key macro indicators affecting the revenue growth of the market segments and subsegments have been accounted for, viewed in extensive detail, verified through primary research, and analyzed to obtain validated and verified quantitative & qualitative data.
- The market data gathered was consolidated and added with detailed inputs, analyzed, and presented in this report.
The market data gathered was consolidated and added with detailed inputs, analyzed, and presented in this report.
Automotive Seats Market : Top-Down and Bottom-Up Approach
Data Triangulation
All percentage shares, splits, and breakdowns were determined using secondary sources and verified by primary sources. All parameters that are said to affect the markets covered in this research study were accounted for, viewed in extensive detail, and analyzed to obtain the final quantitative and qualitative data.
Market Definition
- Standard Seats: In a standard automotive seat, the driver and co-passenger can adjust seat settings manually by pulling levers.
- Powered Seats: A powered seat is typically the front seat in a vehicle. It is equipped with an electric motor that controls the movement and positioning of the seat. A control switch, such as a small joystick, is mounted on the lower side of the seat, allowing the driver to adjust the seating position in several ways.
- Heated Seats: According to Hyundai Motors (South Korea), the heated seat uses the same technology as electric blankets or other appliances and gadgets that use electricity to create heat. It uses a long strip of heating element through the material of the car seat called a resistor that heats up when an electrical current is run through it.
- Memory Seats: The memory seat saves and controls the driver’s personal comfort settings, which include the position of the seat, mirrors, steering wheel, pedal positions, and seat belt height. According to Chevrolet (US), the memory seat allows setting and recalling the preferred positions on more than just the driver's seat. It adjusts the possible seat positions and other adjustable features and saves their settings for future recall. Once the settings are saved, they can be recalled at any time.
- Massage Seats: The massage seat is mostly available for drivers. It has heating and mechanical massage functions for the lower back, ensuring reduced strain on the spinal column and improved circulation in the legs.
- Ventilated Seats: According to Chevrolet, ventilated seats may have several fans or blower systems in the seat cushion and backrest. The fans either draw air from inside the cabin and into the seat or draw air away from the seat/occupant and into the cabin to provide a cooling sensation. The air then passes through plastic ducts (air-permeable fabrics), which distribute it evenly throughout the seat via perforations in the leather.
Key Stakeholders
- Automotive original equipment manufacturers
- Automotive seat system manufacturers
- Automotive seat component & material suppliers
- Automotive safety system suppliers
- Automotive seating testing, certification, and standards organizations
- Regional manufacturer associations and automobile associations
- Traders, distributors, and suppliers of automotive seat systems
- Automotive regulatory bodies and government agencies
Report Objectives
-
To segment and forecast the size of the Automotive Seats Market in terms of volume (thousand/million units) and value (USD million/billion) from 2022 to 2033
- By technology (heated seats; heated and powered seats; standard seats; powered seats; powered, heated, and memory seats; powered, heated, and ventilated seats; powered, heated, ventilated, and memory seats; powered, heated, ventilated, massage, and memory seats) at the country and regional level
- By seat type (bucket and split bench) at the regional level
- By trim material (fabric, genuine leather, and synthetic leather), at the regional level
- The fabric material segment is further segmented into polyester woven fabric, woven velour fabric, and PVC and others at the regional level. The polyurethane foam is provided at the regional level as an additional segment
- By component (armrests, pneumatic systems, seat belts, seat frames and structures, seat headrests, seat height adjusters, seat recliners, seat tracks, and side curtain airbags) at the regional level
- By vehicle type (passenger cars, light commercial vehicles, heavy trucks, and buses), at the regional level
- By material (steel, aluminum, and carbon-amide-metal), at the regional level
- Off-highway vehicle seats market, by vehicle type (construction and mining equipment and agricultural tractors), at the regional level
- Electric vehicle seats market, by propulsion type (battery electric vehicles, plug-in hybrid electric vehicles and fuel cell electric vehicles), at the regional level
- Electric vehicle seats market, by seat type (bucket seat and split bench seat), at the regional level
- LSV seats market, by vehicle type (golf carts, commercial turf utility vehicles, industrial utility vehicles, and personal mobility vehicles), at the regional level
- Automotive seats trim market, by sales channel (OEM and aftermarket), at the regional level
- ATV seats market, by seating capacity (one-seater and two-seater), at the regional level
- By region (Asia Pacific, Europe, Americas, and the Middle East & Africa)
- To comprehensively evaluate the key market dynamics, including growth drivers, restraints, opportunities, and challenges, shaping the evolution of the market
- To strategically assess market segments based on their growth potential, emerging trends, future opportunities, and contribution to overall market revenue
- To analyze the competitive landscape by profiling leading market participants, benchmarking their core competencies, market positioning, business strategies, and market share
-
To study the following with respect to the market:
- Supply chain analysis
- Ecosystem analysis
- Technology analysis
- Trade analysis
- Case study analysis
- Patent analysis
- Regulatory landscape
- Pricing analysis
- Impact of AI
- Investment scenario
- Key stakeholders and buying criteria
- Automotive seat value evolution
- Seat content value analysis by vehicle segment
- Future revenue analysis
- Future cabin architecture
- OEM strategies for cabin differentiation
- Future of intelligent seating systems
- SDV & zonal architecture impact on seating electronics
- Lightweight seating technology roadmap
- Impact of EU FTA trade deal analysis on automotive & transportation industry
- Impact of Israel-Iran war analysis on automotive & transportation industry
- To analyze opportunities for stakeholders and the competitive landscape for market leaders
- To track and analyze competitive developments such as product developments, deals, and others undertaken by the key industry participants
Available customizations:
MarketsandMarkets offers the following customizations for this market report:
- Passenger Car Seats Market, by Body Type
- Sedans
- SUVs
- Hatchbacks
Note: The automotive seats market can be offered for vehicle body type at the country level.
- Automotive Seats Market, by Integrated Infotainment System
- Built-in screen
- Speakers
- Headphone jacks
Note: The automotive seats market can be offered for integrated infotainment systems at the country level.


Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the Automotive Seats Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Custom Market Research Services
We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements
Get 10% Free CustomisationTESTIMONIALS
JIM NAAS
PRODUCT DIRECTOR, WEASLER
Weasler Engineering, a CentroMotion organization
Global Provider of Industrial Actuation & Control Solutionswww.weasler.com
Our organization was interested in learning more about the attractiveness of a particular market space. We contacted MarketsandMarkets to help us based on previous positive experiences we had with them. The results did not disappoint! We discussed our objectives with them, and the team at MarketsandMarkets developed and executed a proposal that met our needs precisely. We were very impressed by their level of expertise, the quality of the analysis and their insightful recommendations. We would not hesitate in working with them again in the future.

Matt Kardel,
Vice President
Aptiv,
A global technology company that develops safer, greener and more connected solutions.www.aptiv.com
We contracted with
MarketsandMarkets to evaluate the value chain and potential go-to-market partners related to our
interest in the Fleet Management space. The team successfully completed the work on time and at the
pricing agreed. MarketsandMarkets listened and understood our objectives and collaborated well with
us to help us get the visibility we needed to make an investment.
We have subsequently used
MarketsandMarkets again related to Smart Cities to good results.
Growth opportunities and latent adjacency in Automotive Seats Market



Ajinkya
Jun, 2019
I would like to explore the various conditions and situations rising in PVC Leather for Automotive (Car Seat ) in UAE and Sudan for official purposes. .