



Carbon Capture, Utilization, and Storage Market
Report Code
CH 7763
Published in
Sep, 2026, By MarketsandMarkets™
Carbon Capture, Utilization, and Storage Market by Service (Capture, Storage, Utilization, Transportation), Technology (Chemical Looping, Solvents & Sorbents, Membranes), End-use Industry, and Region - Global Forecast to 2031

USD 13.53 BN
MARKET SIZE, 2031

CAGR 19%
(2026-2031)

320
REPORT PAGES

350
MARKET TABLES
OVERVIEW
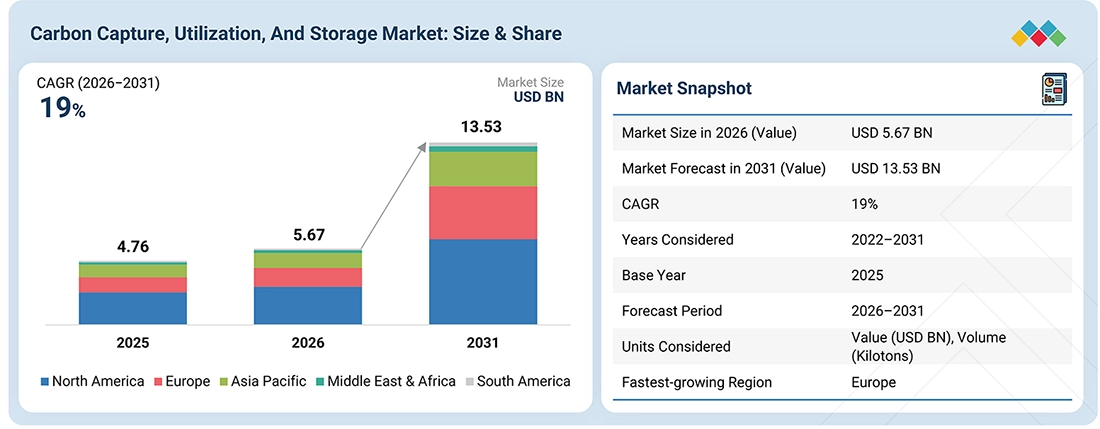
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
The carbon capture, utilization, and storage market is projected to reach USD 13.53 billion by 2031 from USD 5.67 billion in 2026, at a CAGR of 19%. Market growth can be attributed to increasing demand for industrial decarbonization solutions that achieve deep emission reduction while maintaining operational efficiency, energy reliability, and asset viability. The adoption of carbon capture, utilization, and storage (CCUS) services and technologies in power generation, cement, iron & steel, chemical, and oil & gas facilities is being driven by stringent net-zero mandates, expanding carbon-pricing frameworks, and supportive government incentives such as tax credits and subsidies. Key market trends include advancements in post-combustion and chemical looping technologies, development of hub-and-spoke transport infrastructure, part-chain business models, and integration of direct air capture (DAC) and bioenergy systems. However, high initial capital costs, energy-intensive solvent regeneration, limited transport and storage networks, and complex regulatory permitting processes are among the major restraints to market growth. North America is expected to represent the largest carbon capture, utilization, and storage market, supported by extensive industrial infrastructure, generous 45Q tax credits, and strong federal funding programs.
KEY TAKEAWAYS
-
By RegionEurope is projected to record the highest CAGR of 19.5% in the carbon capture, utilization, and storage market during the forecast period.
-
By ServiceBy service, the capture segment dominated the market, accounting for a share of 57.5%, in terms of value, in 2025.
-
By TechnologyBy technology, the chemical looping segment dominated the market, in terms of value, in 2025.
-
By End-use IndustryBy end-use industry, the oil & gas segment held the majority of market share of 75.6%, in terms of value, in 2025.
-
Competitive Landscape - Key PlayersEquinor ASA, Shell Plc, ExxonMobil Corporation, Fluor Corporation, and TotalEnergies SE are star players in the capture, utilization, and storage market, given their broad industry coverage and strong operational and financial strength.
-
Competitive Landscape - StartupsCarbon Clean, Tandem Technical, and C-Capture Ltd. have distinguished themselves among startups and SMEs due to their well-developed marketing channels and extensive funding to build their product portfolios.
The carbon capture, utilization, and storage market is set to grow as demand for industrial decarbonization solutions increases, offering high-volume emission reduction while enabling continuous baseline energy generation as a viable alternative to operational shutdowns. The increasing net-zero commitments, stringent environmental regulations, and corporate sustainability targets are driving market growth. CCUS technologies are increasingly adopted across power generation, cement, iron & steel, chemical, and oil & gas facilities because they capture CO2 emissions directly from flue gas streams or atmospheric sources before permanent underground storage or industrial utilization.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
CCUS revenue pools are shifting from a project-led model toward a more diversified, service- and product-led ecosystem. Today, revenues are concentrated in point-source capture for natural gas processing and fossil-fuel power, supported largely by EOR offtake agreements and integrated engineering and construction contracts. Going forward, growth is expected to broaden across capture in hard-to-abate industries such as cement, iron and steel, and chemicals; recurring revenues from CO2 transport networks, shared hubs, and geological storage; and high-value utilization applications, including synthetic fuels, low-carbon building materials, circular chemicals, and Direct Air Capture (DAC) removal credits. This shift is driven primarily by customer decarbonization needs: oil and gas majors are pursuing low-carbon fuels and asset decarbonization, cement producers are targeting net-zero construction, utilities are reducing power-sector emissions, and chemical companies are integrating captured CO2 into low-carbon feedstocks. These end-market outcomes are strengthening customer willingness to pay and supporting CCUS revenue growth through 2031.
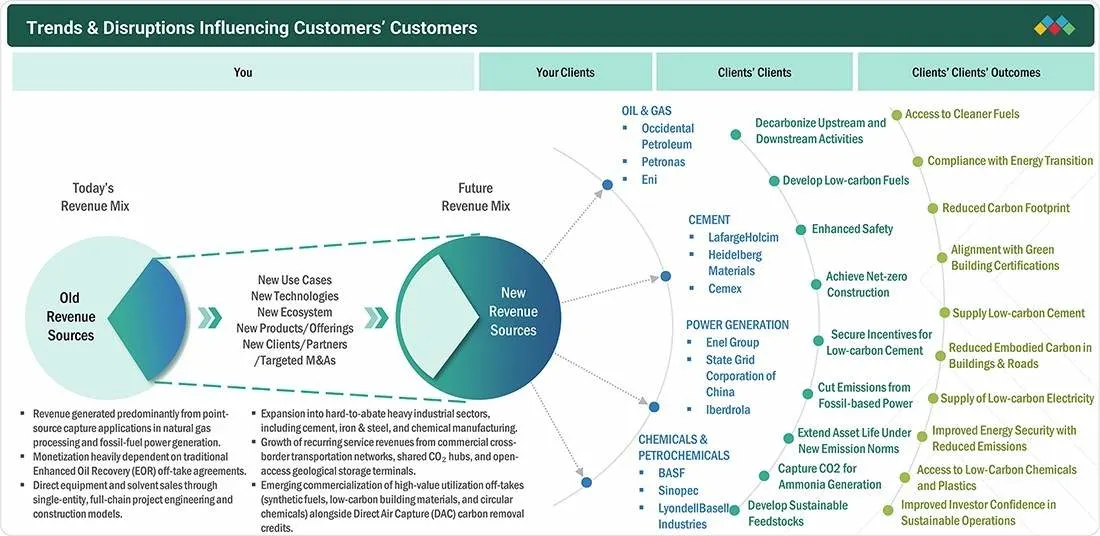
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Drivers
Impact
Level
Level
-
Rising global focus on decarbonization and strict CO2 emissions reduction mandate

-
Increasing demand for commercial CO2 utilization in enhanced oil recovery (EOR) applications


RESTRAINTS
Impact
Level
Level
-
Capital-intensive nature and high operational costs of carbon capture and storage infrastructure

-
Environmental and safety concerns associated with long-term geological storage integrity and potential CO2 leakage


OPPORTUNITIES
Impact
Level
Level
-
Expanding CCUS project pipelines and commercial deployment across Asia Pacific markets

-
Accelerating R&D and investments in advanced carbon capture technologies


CHALLENGES
Impact
Level
Level
-
Need to optimize capture efficiency and lower energy penalties to reduce overall capturing costs

-
Significant upfront capital requirements creating barriers to large-scale CCUS deployment

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Rising global focus on decarbonization and strict CO2 emissions reduction mandate
Government regulations and climate policies are accelerating CCUS adoption by requiring industries to reduce emissions and providing financial incentives for carbon capture and storage. Initiatives such as the European Union’s Net-Zero Industry Act and 2050 climate targets, along with the US Section 45Q tax credit, are improving the economic viability of CCUS projects. Rising carbon prices and tightening emissions thresholds across power generation, cement, steel, and chemicals are further encouraging industrial operators to deploy carbon capture systems.
Restraint: Capital-intensive nature and high operational costs of carbon capture and storage infrastructure
High capital and operating costs remain significant barriers to CCUS deployment. Capture facilities require specialized separation and compression equipment, pipeline infrastructure, and geological storage and monitoring systems. In addition, the energy required for solvent regeneration increases operating costs and reduces the efficiency of host facilities. These financial and energy requirements can extend project payback periods, particularly for medium-sized industrial facilities, without substantial policy support or favorable carbon pricing.
Opportunity: Expanding project pipeline and commercial deployment across high-growth Asia Pacific markets
The rapid industrialization of China, India, and Southeast Asia is creating opportunities for CCUS deployment, particularly across emissions-intensive power, steel, cement, and chemical facilities. CCUS retrofits can support decarbonization while extending the use of existing industrial assets. The development of shared CCUS hubs, supported by government initiatives and industry consortia, can further reduce costs by enabling multiple emitters to share CO2 transportation and storage infrastructure.
Challenge: Need to optimize capture efficiency and lower energy penalties to reduce overall capturing costs
Improving capture efficiency while reducing energy consumption remains a key technological challenge. Conventional amine-based systems require substantial thermal energy for solvent regeneration, increasing the energy penalty of host facilities. Advanced solvents, solid sorbents, and high-selectivity membranes can reduce this burden, but achieving consistent performance with high-volume flue gases containing impurities such as sulfur oxides, nitrogen oxides, and particulates remains a challenge for commercial-scale deployment.
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Carbon capture and storage across Gulf Coast heavy industrial facilities, including steel production, fertilizer plants, and power generation assets | Emissions reduction, regulatory compliance, asset preservation, scale efficiency |
 |
Carbon capture integration at cement manufacturing plants for industrial flue gas decarbonization and underground storage | Industrial decarbonization, green product differentiation, regulatory alignment, risk mitigation |
 |
Cross-border CO2 transport and offshore subsea geological storage (Northern Lights) for third-party industrial emitters. | Infrastructure access, scalable storage, regulatory compliance, shared Capex model |
 |
Direct Air Capture (STRATOS) for atmospheric CO2 removal and utilization in Enhanced Oil Recovery (EOR) and permanent sequestration | High-integrity removals, carbon credit generation, EOR efficiency, net-zero alignment |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
The carbon capture, utilization, and storage ecosystem includes carbon capture/storage equipment/technology/service providers; chemical solvent and sorbent suppliers; transport operators (pipeline, shipping, rail); geological storage site operators; engineering, procurement, and construction (EPC) contractors; regulatory bodies; carbon market verifiers (validation and verification bodies); project developers; emission source operators; and end users across power generation, cement, iron & steel, chemicals, and oil & gas industries. Collaboration across the value chain supports the deployment of integrated capture, transport, and storage infrastructure that meets stringent environmental regulations, safety standards, and regional net-zero mandates. Strong partnerships among technology licensors, pipeline developers, industrial emitters, and storage operators enable shared hub-and-spoke models for cross-border carbon management. Advanced absorption solvents, membrane separation technologies, subsea geological monitoring, MRV (monitoring, reporting, and verification) tools, and specialized distribution logistics improve capture efficiency, long-term storage safety, regulatory compliance, and project bankability. Overall, the integrated ecosystem strengthens supply chain resilience, supports process innovation, and accelerates the commercial scale-up of point-source capture, direct air capture, and carbon utilization technologies across global markets.
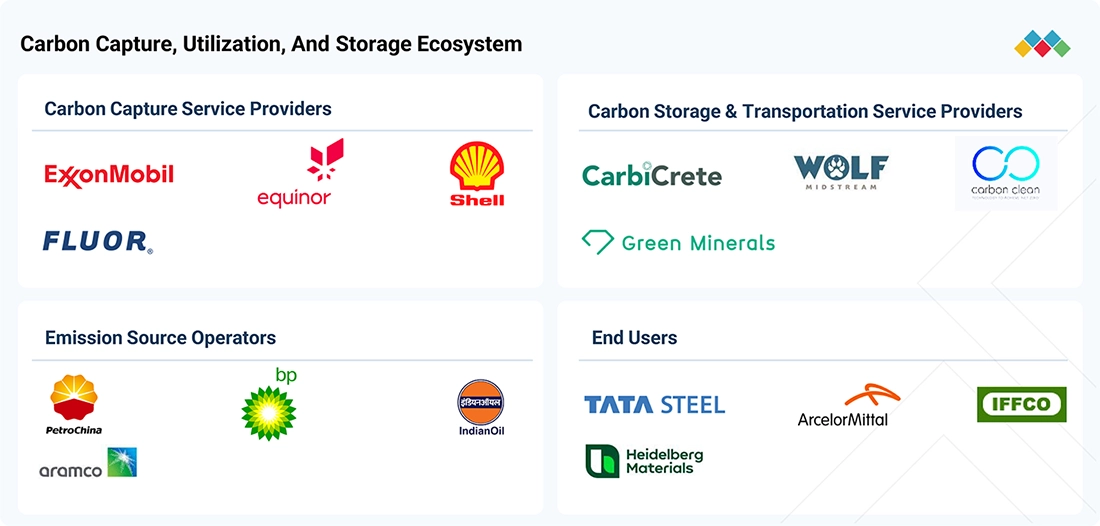
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
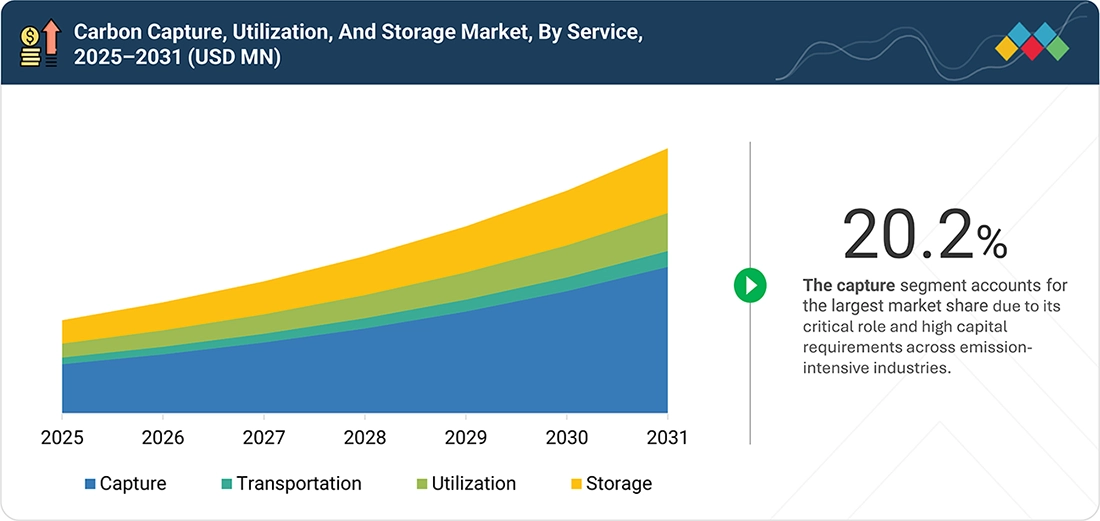
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Carbon Capture, Utilization, and Storage Market, By Service
Capture services account for the largest market share, as CO2 capture represents the critical first stage of the carbon management value chain and requires substantial capital investment. Capture technologies enable industrial emitters to separate CO2 from flue gases before it is released into the atmosphere, providing the feedstock required for downstream utilization or long-term geological storage. Demand for capture services is increasing across high-emitting industries, including power generation, cement, iron and steel, and chemicals, as companies seek to comply with increasingly stringent net-zero targets and carbon reduction frameworks. Furthermore, growing investments in CO2 transport infrastructure, including pipelines and shipping networks, along with the development of secure geological storage facilities, are supporting the deployment of integrated carbon capture, utilization, and storage projects worldwide.
Carbon Capture, Utilization, and Storage Market, By Technology
Chemical solvents & sorbents represent a dominant technology segment in the carbon capture, utilization, and storage market due to their established commercial viability, high capture efficiency, and widespread application in post-combustion processes. Amine-based liquid solvents and advanced solid sorbents effectively separate CO2 from low-pressure flue streams, making them ideal for retrofitting existing power plants and industrial infrastructure. Rising R&D investments, pilot-to-commercial scale deployment, and continuous innovation in solvent regeneration are further driving the growth of the technology segment.
Carbon Capture, Utilization, and Storage Market, By End-use Industry
Oil & gas is one of the largest end-use industries in the global carbon capture, utilization, and storage market, driven by the widespread adoption of Enhanced Oil Recovery (EOR) techniques and aggressive net-zero commitments from major energy companies. Furthermore, the power generation segment is expected to register rapid growth as coal- and gas-fired utilities retrofit facilities with carbon capture equipment to ensure reliable, low-carbon baseload electricity. Increasing application across hard-to-abate sectors such as cement, iron & steel, and chemical manufacturing is further expanding market demand. Supportive government incentives, tax credits (such as US 45Q), and carbon pricing mechanisms are strongly accelerating CCUS integration across these core process industries.
REGION
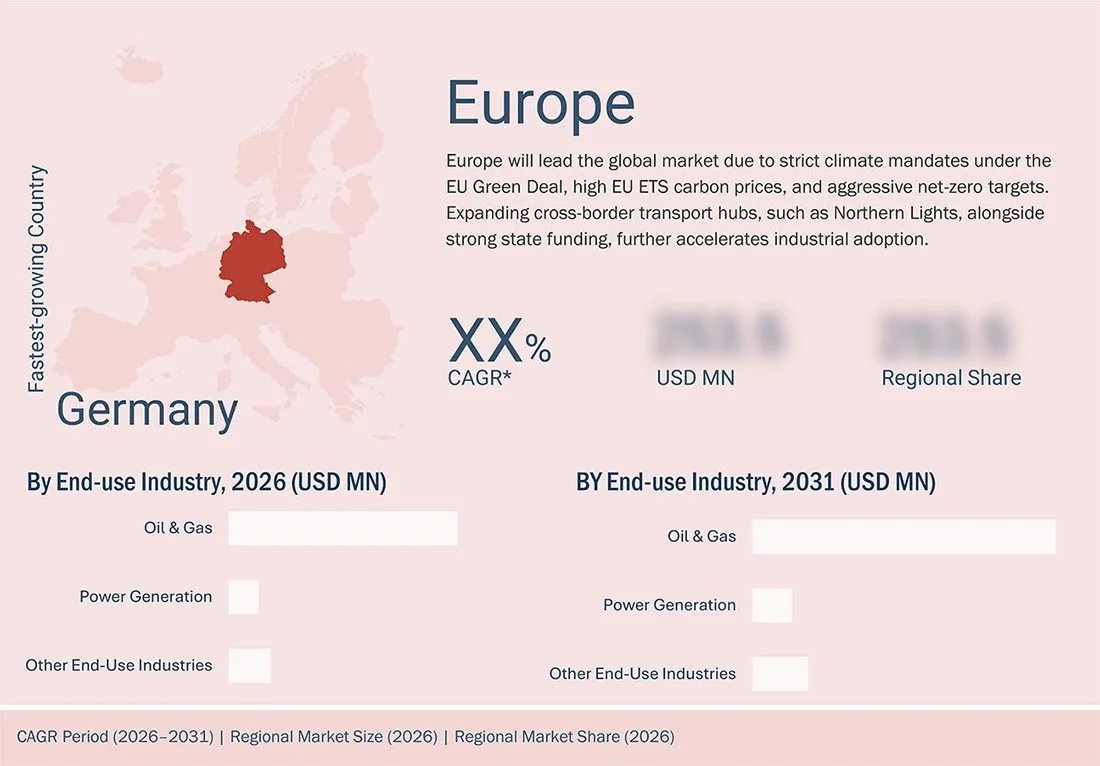
Europe to be fastest-growing carbon capture, utilization, and storage market during forecast period
Europe is projected to be the fastest-growing region in the global carbon capture, utilization, and storage market during the forecast period, driven by ambitious decarbonization targets, stringent environmental regulations, and robust state support. The implementation of legally binding climate policies, such as the EU Green Deal and 2050 net-zero targets, alongside high carbon pricing under the EU Emissions Trading System (EU ETS), is accelerating the adoption of CCUS services/technologies across energy-intensive industries. Expanding deployment in power generation, cement, iron & steel, and chemical manufacturing is further driving regional market growth. The rapid development of cross-border transport and storage infrastructure, which includes the Northern Lights, Porthos, and Aramis projects, and the establishment of shared industrial carbon hubs are creating scalable deployment opportunities. In addition, increasing government subsidies, innovation funding, and strategic public-private partnerships across European nations are expected to provide significant expansion opportunities for CCUS technology providers and infrastructure developers.
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET: COMPANY EVALUATION MATRIX
In the global carbon capture, utilization, and storage market, Equinor ASA (Star) leads with a broad portfolio of end-to-end decarbonization solutions, strong offshore infrastructure capabilities, advanced capture and storage technologies, and an established global presence across oil & gas, power generation, and industrial applications. Linde (Emerging Leader) is strengthening its market position through its modular point-source carbon capture technologies, specialized chemical engineering expertise, and focus on cost-effective, small-to-midscale industrial applications. While Equinor ASA maintains an advantage through its comprehensive CCUS project pipeline, technological capabilities, and global market presence, Linde shows strong potential to move toward the leaders’ quadrant as demand for commercialized, high-efficiency, and easily scalable carbon capture solutions continues to increase.
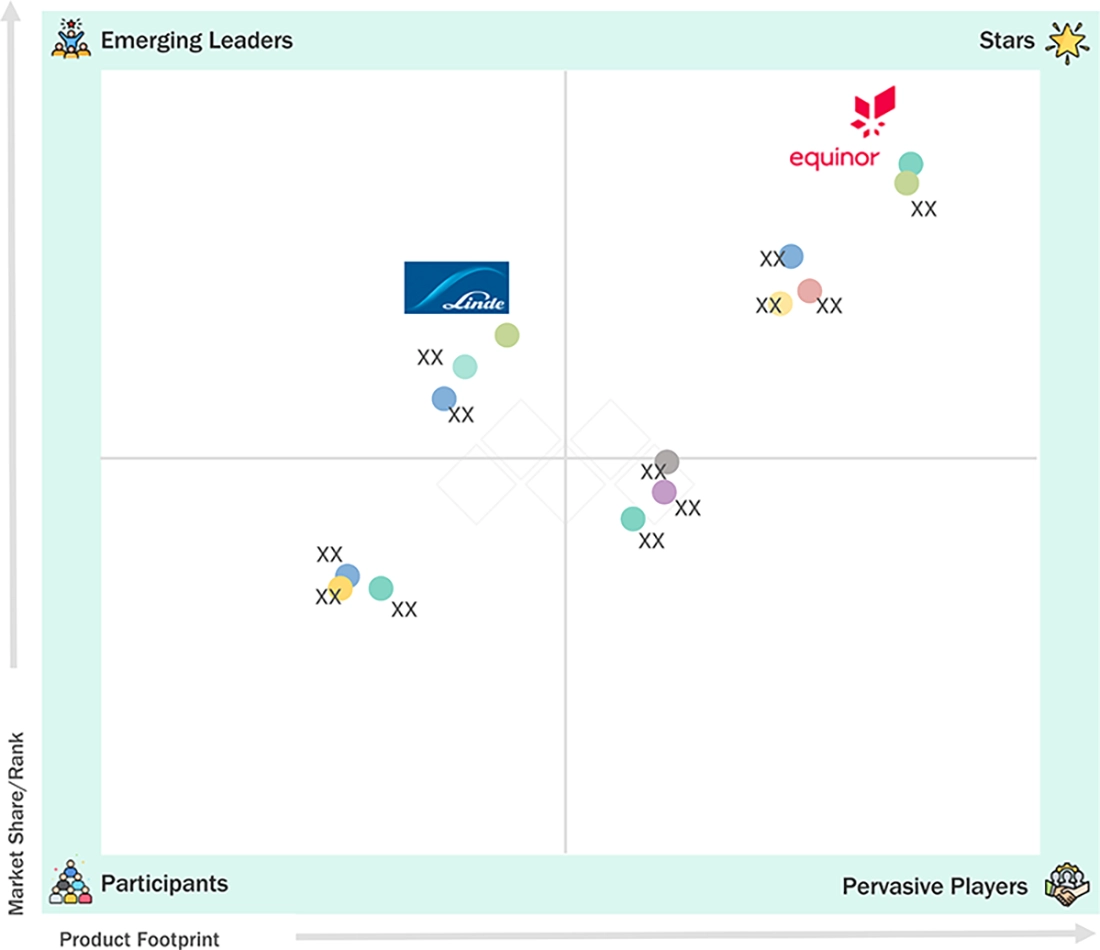
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- Fluor Corporation (US)
- Equinor ASA (Norway)
- ExxonMobil Corporation (US)
- Linde Plc (US)
- Shell Plc (UK)
- Mitsubishi Heavy Industries Ltd. (Japan)
- JGC Holdings Corporation (Japan)
- Schlumberger Ltd (US)
- Aker Solutions (Norway)
- Honeywell International (US)
- TotalEnergies SE (France)
- Hitachi Ltd (Japan)
- Siemens AG (Germany)
- GE Vernova (US)
- Halliburton (US)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2026 (Value) | USD 5.67 Billion |
| Market Forecast in 2031 (Value) | USD 13.53 Billion |
| CAGR | CAGR of 19.0% from 2026–2031 |
| Years Considered | 2022–2031 |
| Base Year | 2025 |
| Forecast Period | 2026–2031 |
| Units Considered | Value (USD Billion), Volume (Kilotons) |
| Report Coverage | Revenue Forecast, Company Ranking, Competitive Landscape, Growth Factors, and Trends |
| Segments Covered |
|
| Regions Covered | North America, Europe, Asia Pacific, Middle East & Africa, and South America |
WHAT IS IN IT FOR YOU: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET REPORT CONTENT GUIDE
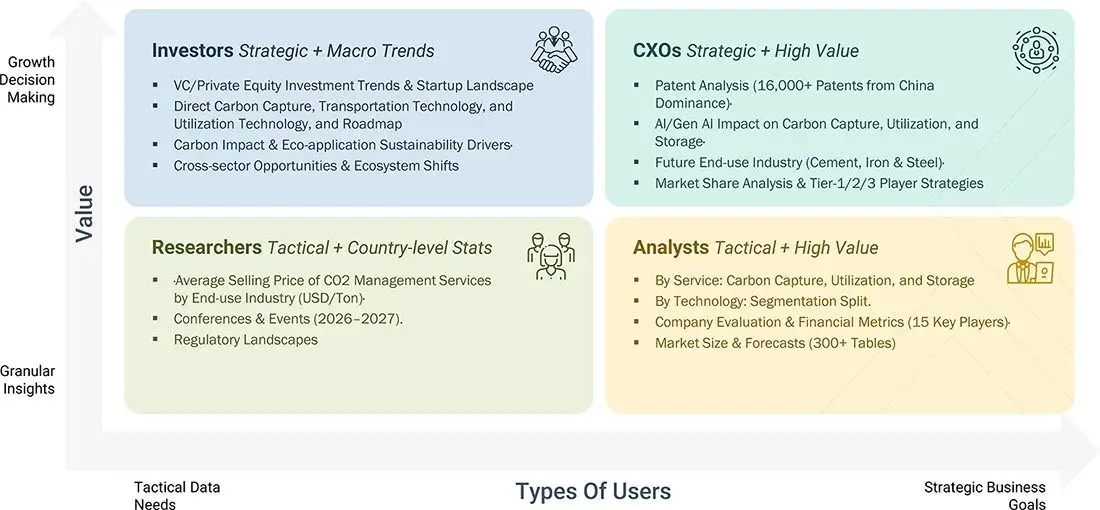
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Technology Licensors & Chemical Suppliers (Solvents, sorbents, membranes, chemical looping agents, cryogenic systems, catalyst manufacturers, and equipment OEMs) |
|
|
| CCUS Technology Developers & Equipment Integrators (Point-source capture system providers, Direct Air Capture (DAC) vendors, modular capture OEMs, and carbon utilization technology providers) |
|
|
| EPC Contractors & Project Developers (Engineering firms, pipeline operators, shipping/logistics providers, geological storage operators, and hub developers) |
|
|
| End-Use Industry Segments (Power Generation, Cement, Iron & Steel, Chemical & Petrochemical, Oil & Gas, Bioenergy/BECCS) |
|
|
RECENT DEVELOPMENTS
- August 2026: Schlumberger Ltd (US) was selected as the strategic reservoir partner for the Havstjerne carbon storage project in Norway’s North Sea, as announced on August 25, 2026. The scope includes reservoir analysis, injection-well design, subsea infrastructure and monitoring plans for stored CO2, supporting the project’s concept and front-end engineering and design phases ahead of a final investment decision.
- August 2026: Mitsubishi Heavy Industries Ltd. (Japan) announced a new model for its compact CO2 capture system, CO2MPACT™ Full-Module, on August 26, 2026. The expanded product lineup offers larger capture capacities while retaining a standardized modular design, allowing configurations to be tailored to customers’ flue-gas sources and helping shorten delivery times for carbon capture applications.
- October 2025: JGC Holdings Corporation (Japan) signed a memorandum of understanding with SLB Capturi and SLB on October 10, 2025, to explore strategic collaboration in post-combustion CO2 capture technologies. The proposed collaboration targets the Asia-Pacific and Middle East markets, combining SLB Capturi’s capture technology with JGC Group’s engineering expertise to pursue integrated solutions spanning early-stage engineering, project execution and implementation.
- August 2025: Equinor ASA (Norway) announced on August 25, 2025, that the Northern Lights project had successfully injected and stored its first CO2 volumes in a reservoir 2,600 metres beneath the North Sea seabed. CO2 captured at Heidelberg Materials’ cement plant in Brevik was transported by ship, received at Øygarden and conveyed through a 100-kilometre pipeline for permanent offshore storage, marking the start of operations at the cross-border CO2 transport and storage facility.
- March 2025: Shell Plc (UK) and its Northern Lights partners Equinor and TotalEnergies took a final investment decision on March 27, 2025, to proceed with Phase 2 of the Northern Lights carbon capture and storage project. The expansion is designed to increase CO2 transport and storage capacity from 1.5 million tonnes to more than 5 million tonnes annually from 2028, supported by a commercial agreement with Stockholm Exergi for up to 900,000 tonnes of CO2 per year.
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
TITLE
PAGE NO
1
INTRODUCTION
33
2
EXECUTIVE SUMMARY
38
3
PREMIUM INSIGHTS
44
4
MARKET OVERVIEW
Decarbonization mandates and tech innovations drive carbon capture growth amid high costs and strategic shifts.
47
4.1
INTRODUCTION
4.2
MARKET DYNAMICS
4.2.1
DRIVERS
4.2.1.1
RISING GLOBAL FOCUS ON DECARBONIZATION AND STRICT CO2 EMISSIONS REDUCTION MANDATES
4.2.1.2
INCREASING DEMAND FOR COMMERCIAL CO2 UTILIZATION IN ENHANCED OIL RECOVERY (EOR) OPERATIONS
4.2.1.3
GROWING TRANSITION TOWARD NATURAL GAS DRIVEN BY HEIGHTENED ENVIRONMENTAL REGULATIONS
4.2.2
RESTRAINTS
4.2.2.1
CAPITAL-INTENSIVE NATURE AND HIGH OPERATIONAL COSTS OF CARBON CAPTURE AND STORAGE INFRASTRUCTURE
4.2.2.2
ENVIRONMENTAL AND SAFETY RISKS REGARDING LONG-TERM GEOLOGICAL STORAGE SITE INTEGRITY AND LEAKAGE
4.2.3
OPPORTUNITIES
4.2.3.1
ONGOING INVESTMENTS AND R&D IN NEXT-GENERATION, HIGH-EFFICIENCY CAPTURE TECHNOLOGIES
4.2.3.2
EXPANDING PROJECT PIPELINE AND COMMERCIAL DEPLOYMENT ACROSS HIGH-GROWTH ASIA PACIFIC MARKETS
4.2.3.3
STRATEGIC INTEGRATION WITH LARGE-CAPACITY CLEAN HYDROGEN AND AMMONIA PRODUCTION PROJECTS
4.2.4
CHALLENGES
4.2.4.1
NEED TO OPTIMIZE CAPTURE EFFICIENCY AND LOWER ENERGY PENALTIES TO REDUCE OVERALL CAPTURE COSTS
4.2.4.2
SUBSTANTIAL INITIAL CAPEX REQUIREMENTS CREATING HIGH BARRIERS TO ENTRY FOR LARGE-SCALE ADOPTION
4.3
UNMET NEEDS AND WHITE SPACES
4.3.1
UNMET NEEDS IN CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET
4.3.2
WHITE SPACE OPPORTUNITIES
4.4
INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
4.4.1
INTERCONNECTED MARKETS
4.4.2
CROSS-SECTOR OPPORTUNITIES
4.5
EMERGING BUSINESS MODELS AND ECOSYSTEM SHIFTS
4.5.1
EMERGING BUSINESS MODELS
4.5.2
ECOSYSTEM SHIFTS
4.6
STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
4.6.1
KEY MOVES AND STRATEGIC FOCUS
5
INDUSTRY TRENDS
Navigate industry shifts with insights on competitive forces, pricing trends, and strategic partnerships.
58
5.1
PORTER’S FIVE FORCES ANALYSIS
5.1.1
THREAT OF NEW ENTRANTS
5.1.2
THREAT OF SUBSTITUTES
5.1.3
BARGAINING POWER OF SUPPLIERS
5.1.4
BARGAINING POWER OF BUYERS
5.1.5
INTENSITY OF COMPETITIVE RIVALRY
5.2
MACROECONOMIC INDICATORS
5.2.1
INTRODUCTION
5.2.2
GDP TRENDS AND FORECAST
5.2.3
TRENDS IN GLOBAL INDUSTRIAL & ENERGY SECTOR
5.3
VALUE CHAIN ANALYSIS
5.4
ECOSYSTEM ANALYSIS
5.5
PRICING ANALYSIS
5.5.1
AVERAGE SELLING PRICE, BY KEY PLAYERS
5.5.2
AVERAGE SELLING PRICE TREND OF CARBON CAPTURE, UTILIZATION, AND STORAGE, BY REGION
5.6
TRADE ANALYSIS
5.6.1
IMPORT SCENARIO (HS CODE 281121)
5.6.2
EXPORT SCENARIO (HS CODE 281121)
5.7
KEY CONFERENCES AND EVENTS, 2026–2027
5.8
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
5.9
INVESTMENT AND FUNDING SCENARIO
5.10
CASE STUDY ANALYSIS
5.10.1
EQUINOR PARTNERS WITH SHELL AND TOTALENERGIES TO DEVELOP NORTHERN LIGHTS CROSS-BORDER CO2 TRANSPORT AND STORAGE NETWORK
5.10.2
OCCIDENTAL PETROLEUM (1POINTFIVE) DEPLOYS STRATOS DIRECT AIR CAPTURE (DAC) FACILITY IN NORTH AMERICA
5.10.3
HEIDELBERG MATERIALS IMPLEMENTS BREVIK CCS PROJECT FOR CEMENT MANUFACTURING DECARBONIZATION
5.11
IMPACT OF 2025 US TARIFF ON CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET
5.11.1
INTRODUCTION
5.11.2
KEY TARIFF RATES
5.11.3
PRICE IMPACT ANALYSIS
5.11.4
IMPACT ON COUNTRIES/REGIONS
5.11.4.1
US
5.11.4.2
EUROPE
5.11.4.3
ASIA PACIFIC
5.11.5
IMPACT ON END-USE INDUSTRIES
6
STRATEGIC DISRUPTION THROUGH TECHNOLOGY, PATENTS, DIGITAL, AND AI ADOPTIONS
Leverage cutting-edge capture and transport technologies to revolutionize carbon management and energy systems.
84
6.1
KEY EMERGING TECHNOLOGIES
6.1.1
CAPTURE TECHNOLOGIES
6.1.1.1
POST-COMBUSTION CAPTURE
6.1.1.2
PRE-COMBUSTION CAPTURE
6.1.1.3
OXY-FUEL COMBUSTION
6.1.1.4
DIRECT AIR CAPTURE (DAC)
6.1.2
TRANSPORT TECHNOLOGIES
6.1.2.1
PIPELINE TRANSPORT
6.1.2.2
SHIP-BASED TRANSPORT
6.1.3
UTILIZATION TECHNOLOGIES
6.1.3.1
DIRECT UTILIZATION
6.1.3.2
CARBON MINERALIZATION
6.2
COMPLEMENTARY TECHNOLOGIES
6.2.1
GAS SEPARATION & PURIFICATION
6.2.2
LIQUEFACTION & PHASE CHANGE TECHNOLOGIES
6.3
TECHNOLOGY/PRODUCT ROADMAP
6.3.1
SHORT-TERM (2025–2027) | FOUNDATION & EARLY COMMERCIALIZATION
6.3.2
MID-TERM (2028–2030) | EXPANSION & STANDARDIZATION
6.3.3
LONG-TERM (2031–2035+) | MASS COMMERCIALIZATION & DISRUPTION
6.4
PATENT ANALYSIS
6.4.1
INTRODUCTION
6.4.2
METHODOLOGY
6.4.3
DOCUMENT TYPE
6.4.4
INSIGHTS
6.4.5
LEGAL STATUS OF PATENTS
6.4.6
JURISDICTION ANALYSIS
6.4.7
TOP APPLICANTS
6.4.8
LIST OF PATENTS BY UNIVERSITY OF CALIFORNIA
6.5
FUTURE APPLICATIONS
6.5.1
POWER GENERATION & ENERGY SYSTEMS: POINT-SOURCE CARBON CAPTURE FOR FOSSIL-FUEL AND BIOENERGY POWER PLANTS
6.5.2
HARD-TO-ABATE HEAVY INDUSTRIES: CARBON CAPTURE & MINERALIZATION FOR CEMENT, STEEL, AND CHEMICAL MANUFACTURING
6.5.3
DIRECT AIR CAPTURE (DAC) & ATMOSPHERIC REMOVAL: AMBIENT AIR CO2 CAPTURE & NEGATIVE-EMISSION TECHNOLOGIES
6.5.4
LOW-CARBON HYDROGEN & FUEL PRODUCTION: CCUS INTEGRATION IN STEAM METHANE REFORMING (SMR) AND SYNTHETIC FUEL SYNTHESIS
6.5.5
CIRCULAR CO2 UTILIZATION & GEOLOGICAL STORAGE: CARBON MINERALIZATION, EOR, AND DEEP SALINE AQUIFER SEQUESTRATION
6.6
IMPACT OF AI/GEN AI ON CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET
6.6.1
TOP USE CASES AND MARKET POTENTIAL
6.6.2
BEST PRACTICES IN CCUS PROCESS & SYSTEM OPTIMIZATION
6.6.3
CASE STUDIES OF AI IMPLEMENTATION IN CCUS MARKET
6.6.4
INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
6.6.5
CLIENTS’ READINESS TO ADOPT GENERATIVE AI IN CCUS MARKET
6.7
SUCCESS STORIES AND REAL-WORLD APPLICATIONS
6.7.1
SLB: AI & DIGITAL-TWIN-BASED CARBON STORAGE SCREENING & MMV
6.7.2
AKER CARBON CAPTURE: AI-POWERED MODULAR PROCESS OPTIMIZATION
7
SUSTAINABILITY AND REGULATORY LANDSCAPE
Navigate complex regulations and leverage eco-innovations to drive carbon reduction and sustainability success.
103
7.1
REGIONAL REGULATIONS AND COMPLIANCE
7.1.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
7.1.2
INDUSTRY STANDARDS
7.2
SUSTAINABILITY INITIATIVES
7.2.1
CARBON IMPACT AND ECO-APPLICATIONS OF CCUS TECHNOLOGIES
7.2.1.1
CARBON IMPACT REDUCTION
7.2.1.2
ECO-APPLICATIONS
7.3
SUSTAINABILITY IMPACT AND REGULATORY POLICY INITIATIVES
7.4
CERTIFICATIONS, LABELING, ECO-STANDARDS
8
CUSTOMER LANDSCAPE & BUYER BEHAVIOR
Unlock hidden profitability by understanding stakeholder influence and unmet needs in buyer behavior.
110
8.1
DECISION-MAKING PROCESS
8.2
BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA
8.2.1
KEY STAKEHOLDERS IN BUYING PROCESS
8.2.2
BUYING CRITERIA
8.3
ADOPTION BARRIERS & INTERNAL CHALLENGES
8.4
UNMET NEEDS FROM VARIOUS APPLICATIONS
8.5
MARKET PROFITABILITY
8.5.1
REVENUE POTENTIAL
8.5.2
COST DYNAMICS
8.5.3
MARGIN OPPORTUNITIES, BY APPLICATION
9
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million and Kilotons | 20 Data Tables
118
9.1
INTRODUCTION
9.2
CAPTURE
9.2.1
PRIMARY MECHANISMS AND OPERATIONAL SCOPE
9.2.2
CAPTURE, BY TECHNOLOGY
9.2.2.1
POST-COMBUSTION
9.2.2.1.1
HIGH SEPARATION EFFICIENCY UP TO 99% ACROSS DIVERSE SEPARATION MEDIA
9.2.2.2
OXY-FUEL
9.2.2.2.1
SIMPLIFIED CO2 SEPARATION VIA HIGH-PURITY FLUE GAS STREAMS AND ADVANCED CHEMICAL LOOPING
9.2.2.3
PRE-COMBUSTION
9.2.2.3.1
CONCENTRATED STREAM CO2 SEPARATION PRIOR TO AIR DILUTION AND HYDROGEN PRODUCTION
9.2.2.4
BIO-ENERGY CCS (BECCS)
9.2.2.4.1
ATMOSPHERIC CARBON REMOVAL AND LONG-TERM GEOLOGIC STORAGE STABILITY EXCEEDING 1,000 YEARS
9.2.2.5
DIRECT AIR CAPTURE
9.2.2.5.1
ESCALATING GLOBAL DEMAND FOR NEGATIVE EMISSION TECHNOLOGIES DRIVES SCALED COMMERCIALIZATION OF DAC FRAMEWORKS
9.3
TRANSPORTATION
9.3.1
PIPELINE INFRASTRUCTURE DOMINATES MIDSTREAM LOGISTICS DRIVEN BY SUPERIOR COST-EFFICIENCY AND LOW EMISSIONS
9.4
UTILIZATION
9.4.1
ENHANCED OIL RECOVERY AND COMMERCIAL FEEDSTOCK INNOVATIONS DRIVE MARKET SCALING
9.5
STORAGE
9.5.1
DEEP GEOLOGICAL FORMATIONS REPRESENT THE PRIMARY VECTOR FOR PERMANENT CARBON SEQUESTRATION
9.5.2
STORAGE SERVICE, BY TECHNOLOGY
9.5.3
GEOLOGICAL STORAGE
9.5.3.1
DEPLETED OIL & GAS RESERVOIRS
9.5.3.1.1
MOST EFFICIENT AND COMMERCIALLY PROVEN STORAGE VECTOR
9.5.3.2
UN-MINEABLE COAL BEDS
9.5.3.2.1
SIMULTANEOUS CARBON TRAPPING AND ENHANCED COAL BED METHANE RECOVERY
9.5.3.3
SALINE AQUIFERS
9.5.3.3.1
HIGH STORAGE POTENTIAL CONSTRAINED BY SUBSURFACE MAPPING REQUIREMENTS
9.5.4
DEEP OCEAN STORAGE
9.5.4.1
ENVIRONMENTAL RISKS AND ECOLOGICAL CONCERNS RESTRAIN LARGE-SCALE OCEAN SEQUESTRATION DEPLOYMENT
10
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million and Kilotons | 20 Data Tables
133
10.1
INTRODUCTION
10.2
CHEMICAL LOOPING
10.2.1
ECONOMIC SUPERIORITY AND OPERATIONAL DYNAMICS IN CCUS DEPLOYMENT
10.3
SOLVENTS & SORBENTS
10.3.1
PROVEN RETROFITTING SOLUTIONS DRIVING HIGH CAPTURE EFFICIENCY
10.4
MEMBRANES
10.4.1
HIGHLY EFFICIENT, CONTINUOUS CARBON CAPTURE TECHNOLOGY
10.5
OTHER TECHNOLOGIES
10.5.1
ADVANCED AND HYBRID TECHNOLOGIES ENHANCING CAPTURE EFFICIENCY AND OPERATIONAL FLEXIBILITY
11
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million and Kilotons | 28 Data Tables
145
11.1
INTRODUCTION
11.2
OIL & GAS
11.2.1
NATURAL GAS PROCESSING AND REFINING ABATEMENT DRIVE SECTOR DOMINANCE
11.3
POWER GENERATION
11.3.1
POINT-SOURCE RETROFITTING OF FOSSIL FUEL POWER PLANTS DRIVES SECTOR EXPANSION
11.4
CHEMICAL & PETROCHEMICAL
11.4.1
AMMONIA AND PETROCHEMICAL SYNTHESIS FEEDSTOCKS CONTRIBUTE TO SECTOR ADOPTION
11.5
CEMENT
11.5.1
REGULATORY PRESSURES AND PROCESS EMISSION ABATEMENT DRIVE TECHNOLOGY ADOPTION
11.6
IRON & STEEL
11.6.1
HIGH EMISSIONS FOOTPRINT AND DRI PROCESS INTEGRATION DRIVE SECTOR CCUS ADOPTION
11.7
OTHER END-USE INDUSTRIES
12
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION
Comprehensive coverage of 8 Regions with country-level deep-dive of 16 Countries | 168 Data Tables.
160
12.1
INTRODUCTION
12.2
NORTH AMERICA
12.2.1
US
12.2.1.1
FEDERAL POLICY SUPPORT AND ADVANCED INFRASTRUCTURE EXPANSION
12.2.2
CANADA
12.2.2.1
REGULATORY MANDATES AND CARBON STORAGE POTENTIAL TO DRIVE EXPANSION
12.2.3
MEXICO
12.2.3.1
OFFSHORE STORAGE INFRASTRUCTURE AND EMISSIONS MANDATES TO DRIVE EXPANSION
12.3
EUROPE
12.3.1
NETHERLANDS
12.3.1.1
ADVANCING OFFSHORE INFRASTRUCTURE AND R&D CAPABILITIES IN THE NETHERLANDS CCUS MARKET
12.3.2
ITALY
12.3.2.1
POLICY FRAMEWORKS AND OFFSHORE INFRASTRUCTURE DRIVING ITALY CCUS EXPANSION
12.3.3
FRANCE
12.3.3.1
INDUSTRIAL DECARBONIZATION STRATEGY AND PROJECT ANNOUNCEMENTS ACCELERATING FRANCE CCUS MARKET
12.3.4
UK
12.3.4.1
GOVERNMENT MANDATES AND INDUSTRIAL CLUSTER DEPLOYMENT ACCELERATING UK CCUS EXPANSION
12.3.5
NORWAY
12.3.5.1
OFFSHORE STORAGE LEADERSHIP AND STATE-BACKED INFRASTRUCTURE DRIVING NORWAY CCUS MARKET
12.3.6
REST OF EUROPE
12.3.6.1
REGIONAL DIVERSIFICATION AND INDUSTRIAL DECARBONIZATION DRIVING REST OF EUROPE CCUS GROWTH
12.4
ASIA PACIFIC
12.4.1
CHINA
12.4.1.1
STRATEGIC COLLABORATIONS AND POLICY FRAMEWORKS ACCELERATING CHINA CCUS MARKET EXPANSION
12.4.2
JAPAN
12.4.2.1
ROBUST INDUSTRIAL BASE AND ADVANCED TECHNOLOGY PROVIDERS DRIVING JAPAN CCUS MARKET GROWTH
12.4.3
INDIA
12.4.3.1
INDUSTRIALIZATION AND EMISSION REGULATIONS DRIVING INDIA CCUS MARKET EXPANSION
12.4.4
AUSTRALIA
12.4.4.1
STRATEGIC GOVERNMENT SUPPORT AND GEOLOGICAL ADVANTAGE ACCELERATING AUSTRALIA CCUS MARKET EXPANSION
12.4.5
REST OF ASIA PACIFIC
12.4.5.1
POLICY FRAMEWORKS AND SUSTAINABILITY COMMITMENTS DRIVING REST OF ASIA PACIFIC CCUS MARKET GROWTH
12.5
MIDDLE EAST & AFRICA
12.5.1
GCC COUNTRIES
12.5.1.1
UAE
12.5.1.1.1
COMMERCIAL PROJECT DEPLOYMENT AND EOR INTEGRATION DRIVING UAE CCUS MARKET
12.5.1.2
SAUDI ARABIA
12.5.1.2.1
STRATEGIC PROJECT DEPLOYMENT AND COMMERCIAL SCALING DRIVING SAUDI ARABIA CCUS MARKET
12.5.1.3
REST OF GCC COUNTRIES
12.5.1.3.1
HYDROCARBON INDUSTRY DECARBONIZATION AND INFRASTRUCTURE EXPANSION DRIVING REST OF GCC CCUS MARKET
12.5.2
REST OF MIDDLE EAST & AFRICA
12.6
SOUTH AMERICA
12.6.1
BRAZIL
12.6.1.1
DECARBONIZATION MANDATES AND PRE-SALT FIELD REINJECTION DRIVING BRAZIL CCUS MARKET
12.6.2
ARGENTINA
12.6.2.1
VACA MUERTA EXPANSION AND GAS INFRASTRUCTURE DRIVING ARGENTINA CCUS MARKET
12.6.3
REST OF SOUTH AMERICA
13
COMPETITIVE LANDSCAPE
Discover key strategies and market dynamics shaping the future of CCUS industry leaders.
248
13.1
OVERVIEW
13.2
KEY PLAYER STRATEGIES/RIGHT TO WIN
13.3
REVENUE ANALYSIS
13.4
MARKET SHARE ANALYSIS
13.5
BRAND/PRODUCT COMPARATIVE ANALYSIS
13.5.1
BRAND COMPARATIVE ANALYSIS
13.5.1.1
FLUOR ECONAMINE FG PLUS
13.5.1.2
EXXON MOBIL CORPORATION - CCUS
13.5.1.3
EQUINOR ASA
13.5.1.4
MITSUBISHI KM-CDR
13.6
COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
13.6.1
STARS
13.6.2
EMERGING LEADERS
13.6.3
PERVASIVE PLAYERS
13.6.4
PARTICIPANTS
13.6.5
COMPANY FOOTPRINT: KEY PLAYERS, 2025
13.6.5.1
COMPANY FOOTPRINT
13.6.5.2
REGION FOOTPRINT
13.6.5.3
SERVICE FOOTPRINT
13.6.5.4
END-USE INDUSTRY FOOTPRINT
13.7
COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
13.7.1
PROGRESSIVE COMPANIES
13.7.2
RESPONSIVE COMPANIES
13.7.3
DYNAMIC COMPANIES
13.7.4
STARTING BLOCKS
13.7.5
COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
13.7.5.1
DETAILED LIST OF KEY STARTUPS/SMES
13.7.5.2
COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
13.8
VALUATION AND FINANCIAL METRICS OF CCUS VENDORS
13.9
COMPETITIVE SCENARIO
13.9.1
DEALS
13.9.2
EXPANSIONS
13.9.3
OTHER DEVELOPMENT
14
COMPANY PROFILES
In-depth Company Profiles of Leading Market Players with detailed Business Overview, Product and Service Portfolio, Recent Developments, and Unique Analyst Perspective (MnM View)
272
14.1
KEY PLAYERS
14.1.1
FLUOR CORPORATION
14.1.1.1
BUSINESS OVERVIEW
14.1.1.2
PRODUCTS OFFERED
14.1.1.3
RECENT DEVELOPMENTS
14.1.1.3.1
DEALS
14.1.1.3.2
OTHER DEVELOPMENTS
14.1.1.4
MNM VIEW
14.1.1.4.1
RIGHT TO WIN
14.1.1.4.2
STRATEGIC CHOICES
14.1.1.4.3
WEAKNESSES AND COMPETITIVE THREATS
14.1.2
EXXON MOBIL CORPORATION
14.1.3
SHELL PLC
14.1.4
EQUINOR ASA
14.1.5
TOTALENERGIES SE
14.1.6
LINDE PLC
14.1.7
MITSUBISHI HEAVY INDUSTRIES, LTD.
14.1.8
JGC HOLDINGS CORPORATION
14.1.9
SCHLUMBERGER LIMITED
14.1.10
AKER SOLUTIONS
14.1.11
HONEYWELL INTERNATIONAL
14.1.12
HITACHI, LTD.
14.1.13
SIEMENS AG
14.1.14
GE VERNOVA
14.1.15
HALLIBURTON
14.2
OTHER KEY MARKET PLAYERS
14.2.1
CLIMEWORKS AG
14.2.2
CARBON CLEAN SOLUTIONS
14.2.3
OCCIDENTAL
14.2.4
GREEN MINERALS B.V.
14.2.5
CARBICRETE
14.2.6
CARBONFREE
14.2.7
SVANTE TECHNOLOGIES INC.
14.2.8
GREEN POWER INTERNATIONAL PVT. LTD.
14.2.9
WOLF MIDSTREAM
14.2.10
BABCOCK & WILCOX
15
RESEARCH METHODOLOGY
363
15.1
RESEARCH DATA
15.1.1
SECONDARY DATA
15.1.2
PRIMARY DATA
15.1.2.1
KEY PRIMARY INTERVIEW PARTICIPANTS
15.2
MARKET SIZE ESTIMATION
15.2.1
BOTTOM-UP APPROACH
15.2.2
TOP-DOWN APPROACH
15.3
BASE NUMBER CALCULATION
15.4
FORECAST NUMBER CALCULATION
15.5
DATA TRIANGULATION
15.6
RESEARCH LIMITATIONS AND RISK ASSESSMENT
16
APPENDIX
373
16.1
DISCUSSION GUIDE
16.2
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL
16.3
CUSTOMIZATION OPTIONS
16.4
RELATED REPORTS
16.5
AUTHOR DETAILS
LIST OF TABLES
TABLE 1
EMISSION REDUCTION TARGETS OF MAJOR COUNTRIES
TABLE 2
KEY BLUE HYDROGEN/AMMONIA AND ENABLING CCS PROJECTS
TABLE 3
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET: PORTER'S FIVE FORCES ANALYSIS
TABLE 4
GDP PERCENTAGE CHANGE, BY KEY COUNTRY, 2021–2029
TABLE 5
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET: ROLE OF COMPANIES IN ECOSYSTEM
TABLE 6
AVERAGE SELLING PRICE OF CARBON CCUS OFFERED BY KEY PLAYERS, BY SERVICE, 2025 (USD/KG)
TABLE 7
AVERAGE SELLING PRICE TREND OF CARBON CAPTURE, UTILIZATION, AND STORAGE, BY REGION, 2023–2025 (USD/KG)
TABLE 8
IMPORT DATA FOR HS CODE 281121-COMPLIANT PRODUCTS, 2021–2025 (USD THOUSAND)
TABLE 9
EXPORT DATA FOR HS CODE 281121-COMPLIANT PRODUCTS, 2021–2025 (USD THOUSAND)
TABLE 10
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET: LIST OF KEY CONFERENCES AND EVENTS, 2026–2027
TABLE 11
US-ADJUSTED RECIPROCAL TARIFF RATES
TABLE 12
EXPECTED CHANGE IN PRICES AND IMPACT OF TARIFFS ON END-USE MARKET
TABLE 13
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET: TOTAL NUMBER OF PATENTS, 2015–2025
TABLE 14
TOP USE CASES AND MARKET POTENTIAL
TABLE 15
BEST PRACTICES: USE CASES OF COMPANIES IMPLEMENTING AI
TABLE 16
CCUS MARKET: CASE STUDIES RELATED TO AI IMPLEMENTATION
TABLE 17
INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
TABLE 18
NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
TABLE 19
EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
TABLE 20
ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
TABLE 21
ROW: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
TABLE 22
GLOBAL STANDARDS IN CARBON CAPTURE, UTILIZATION, AND STORAGE (CCUS) MARKET
TABLE 23
CERTIFICATIONS, LABELING, ECO-STANDARDS IN CCUS MARKET
TABLE 24
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY APPLICATION (%)
TABLE 25
KEY BUYING CRITERIA, BY APPLICATION
TABLE 26
UNMET NEEDS IN CARBON CAPTURE, UTILIZATION, AND STORAGE (CCUS) MARKET, BY APPLICATION
TABLE 27
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE, 2021–2025 (KILOTON)
TABLE 28
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE, 2026–2031 (KILOTON)
TABLE 29
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE, 2021–2025 (USD MILLION)
TABLE 30
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE, 2026–2031 (USD MILLION)
TABLE 31
CAPTURE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION 2021–2025 (KILOTON)
TABLE 32
CAPTURE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (KILOTON)
TABLE 33
CAPTURE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 34
CAPTURE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 35
TRANSPORTATION: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (KILOTON)
TABLE 36
TRANSPORTATION: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (KILOTON)
TABLE 37
TRANSPORTATION: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 38
TRANSPORTATION: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 39
UTILIZATION: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (KILOTON)
TABLE 40
UTILIZATION: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (KILOTON)
TABLE 41
UTILIZATION: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 42
UTILIZATION: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 43
STORAGE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (KILOTON)
TABLE 44
STORAGE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (KILOTON)
TABLE 45
STORAGE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 46
STORAGE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 47
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY, 2021–2025 (KILOTON)
TABLE 48
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY, 2026–2031 (KILOTON)
TABLE 49
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY, 2021–2025 (USD MILLION)
TABLE 50
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY, 2026–2031 (USD MILLION)
TABLE 51
CHEMICAL LOOPING: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (KILOTON)
TABLE 52
CHEMICAL LOOPING: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (KILOTON)
TABLE 53
CHEMICAL LOOPING: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 54
CHEMICAL LOOPING: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 55
SOLVENTS & SORBENTS: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (KILOTON)
TABLE 56
SOLVENTS & SORBENTS: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (KILOTON)
TABLE 57
SOLVENTS & SORBENTS: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 58
SOLVENTS & SORBENTS: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 59
MEMBRANES: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (KILOTON)
TABLE 60
MEMBRANES: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (KILOTON)
TABLE 61
MEMBRANES: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 62
MEMBRANES: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 63
OTHER TECHNOLOGIES: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (KILOTON)
TABLE 64
OTHER TECHNOLOGIES: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (KILOTON)
TABLE 65
OTHER TECHNOLOGIES: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 66
OTHER TECHNOLOGIES: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 67
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 68
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 69
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 70
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 71
OIL & GAS: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (KILOTON)
TABLE 72
OIL & GAS: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (KILOTON)
TABLE 73
OIL & GAS: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 74
OIL & GAS: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 75
POWER GENERATION: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (KILOTON)
TABLE 76
POWER GENERATION: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (KILOTON)
TABLE 77
POWER GENERATION: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 78
POWER GENERATION: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 79
CHEMICAL & PETROCHEMICAL: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (KILOTON)
TABLE 80
CHEMICAL & PETROCHEMICAL: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (KILOTON)
TABLE 81
CHEMICAL & PETROCHEMICAL: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 82
CHEMICAL & PETROCHEMICAL: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 83
CEMENT: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (KILOTON)
TABLE 84
CEMENT: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (KILOTON)
TABLE 85
CEMENT: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 86
CEMENT: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 87
IRON & STEEL: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (KILOTON)
TABLE 88
IRON & STEEL: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (KILOTON)
TABLE 89
IRON & STEEL: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 90
IRON & STEEL: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 91
OTHER END-USE INDUSTRIES: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (KILOTON)
TABLE 92
OTHER END-USE INDUSTRIES: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (KILOTON)
TABLE 93
OTHER END-USE INDUSTRIES: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 94
OTHER END-USE INDUSTRIES: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 95
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (KILOTONS)
TABLE 96
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (KILOTONS)
TABLE 97
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 98
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 99
NORTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE, 2021–2025 (KILOTON)
TABLE 100
NORTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE, 2026–2031 (KILOTON)
TABLE 101
NORTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE, 2021–2025 (USD MILLION)
TABLE 102
NORTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE, 2026–2031 (USD MILLION)
TABLE 103
NORTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY, 2021–2025 (KILOTON)
TABLE 104
NORTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY, 2026–2031 (KILOTON)
TABLE 105
NORTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY, 2021–2025 (USD MILLION)
TABLE 106
NORTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY, 2026–2031 (USD MILLION)
TABLE 107
NORTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 108
NORTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 109
NORTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 110
NORTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 111
NORTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY COUNTRY, 2021–2025 (KILOTON)
TABLE 112
NORTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY COUNTRY, 2026–2031 (KILOTON)
TABLE 113
NORTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY COUNTRY, 2021–2025 (USD MILLION)
TABLE 114
NORTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY COUNTRY, 2026–2031 (USD MILLION)
TABLE 115
US: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 116
US: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 117
US: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 118
US: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 119
CANADA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 120
CANADA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 121
CANADA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 122
CANADA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 123
MEXICO: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 124
MEXICO: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 125
MEXICO: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 126
MEXICO: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 127
EUROPE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE, 2021–2025 (KILOTON)
TABLE 128
EUROPE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE, 2026–2031 (KILOTON)
TABLE 129
EUROPE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE, 2021–2025 (USD MILLION)
TABLE 130
EUROPE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE, 2026–2031 (USD MILLION)
TABLE 131
EUROPE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY, 2021–2025 (KILOTON)
TABLE 132
EUROPE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY, 2026–2031 (KILOTON)
TABLE 133
EUROPE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY, 2021–2025 (USD MILLION)
TABLE 134
EUROPE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY, 2026–2031 (USD MILLION)
TABLE 135
EUROPE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 136
EUROPE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 137
EUROPE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 138
EUROPE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 139
EUROPE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY COUNTRY, 2021–2025 (KILOTON)
TABLE 140
EUROPE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY COUNTRY, 2026–2031 (KILOTON)
TABLE 141
EUROPE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY COUNTRY, 2021–2025 (USD MILLION)
TABLE 142
EUROPE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY COUNTRY, 2026–2031 (USD MILLION)
TABLE 143
NETHERLANDS: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 144
NETHERLANDS: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 145
NETHERLANDS: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 146
NETHERLANDS: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 147
ITALY: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 148
ITALY: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 149
ITALY: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (MILLION SQUARE METERS)
TABLE 150
ITALY: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (MILLION SQUARE METERS)
TABLE 151
FRANCE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 152
FRANCE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 153
FRANCE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 154
FRANCE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 155
UK: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 156
UK: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 157
UK: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 158
UK: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 159
NORWAY: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 160
NORWAY: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 161
NORWAY: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 162
NORWAY: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 163
REST OF EUROPE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 164
REST OF EUROPE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 165
REST OF EUROPE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 166
REST OF EUROPE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 167
ASIA PACIFIC: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE, 2021–2025 (KILOTON)
TABLE 168
ASIA PACIFIC: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE, 2026–2031 (KILOTON)
TABLE 169
ASIA PACIFIC: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE, 2021–2025 (USD MILLION)
TABLE 170
ASIA PACIFIC: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE, 2026–2031 (USD MILLION)
TABLE 171
ASIA PACIFIC: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY, 2021–2025 (KILOTON)
TABLE 172
ASIA PACIFIC: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY, 2026–2031 (KILOTON)
TABLE 173
ASIA PACIFIC: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY, 2021–2025 (USD MILLION)
TABLE 174
ASIA PACIFIC: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY, 2026–2031 (USD MILLION)
TABLE 175
ASIA PACIFIC: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 176
ASIA PACIFIC: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 177
ASIA PACIFIC: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 178
ASIA PACIFIC: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 179
ASIA PACIFIC: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY COUNTRY, 2021–2025 (KILOTON)
TABLE 180
ASIA PACIFIC: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY COUNTRY, 2026–2031 (KILOTON)
TABLE 181
ASIA PACIFIC: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY COUNTRY, 2021–2025 (USD MILLION)
TABLE 182
ASIA PACIFIC: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY COUNTRY, 2026–2031 (USD MILLION)
TABLE 183
CHINA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 184
CHINA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 185
CHINA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 186
CHINA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 187
JAPAN: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 188
JAPAN: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 189
JAPAN: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 190
JAPAN: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 191
INDIA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 192
INDIA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 193
INDIA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 194
INDIA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 195
AUSTRALIA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 196
AUSTRALIA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 197
AUSTRALIA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 198
AUSTRALIA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 199
REST OF ASIA PACIFIC: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 200
REST OF ASIA PACIFIC: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 201
REST OF ASIA PACIFIC: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 202
REST OF ASIA PACIFIC: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 203
MIDDLE EAST & AFRICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE, 2021–2025 (KILOTON)
TABLE 204
MIDDLE EAST & AFRICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE, 2026–2031 (KILOTON)
TABLE 205
MIDDLE EAST & AFRICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE, 2021–2025 (USD MILLION)
TABLE 206
MIDDLE EAST & AFRICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE, 2026–2031 (USD MILLION)
TABLE 207
MIDDLE EAST & AFRICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY, 2021–2025 (KILOTON)
TABLE 208
MIDDLE EAST & AFRICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY, 2026–2031 (KILOTON)
TABLE 209
MIDDLE EAST & AFRICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY, 2021–2025 (USD MILLION)
TABLE 210
MIDDLE EAST & AFRICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY, 2026–2031 (USD MILLION)
TABLE 211
MIDDLE EAST & AFRICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 212
MIDDLE EAST & AFRICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 213
MIDDLE EAST & AFRICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 214
MIDDLE EAST & AFRICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 215
MIDDLE EAST & AFRICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY COUNTRY, 2021–2025 (KILOTON)
TABLE 216
MIDDLE EAST & AFRICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY COUNTRY, 2026–2031 (KILOTON)
TABLE 217
MIDDLE EAST & AFRICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY COUNTRY, 2021–2025 (USD MILLION)
TABLE 218
MIDDLE EAST & AFRICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY COUNTRY, 2026–2031 (USD MILLION)
TABLE 219
UAE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 220
UAE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 221
UAE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 222
UAE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 223
SAUDI ARABIA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 224
SAUDI ARABIA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 225
SAUDI ARABIA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 226
SAUDI ARABIA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 227
REST OF GCC COUNTRIES: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 228
REST OF GCC COUNTRIES: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 229
REST OF GCC COUNTRIES: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 230
REST OF GCC COUNTRIES: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 231
REST OF MIDDLE EAST & AFRICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 232
REST OF MIDDLE EAST & AFRICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 233
REST OF MIDDLE EAST & AFRICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 234
REST OF MIDDLE EAST & AFRICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 235
SOUTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE, 2021–2025 (KILOTON)
TABLE 236
SOUTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE, 2026–2031 (KILOTON)
TABLE 237
SOUTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE, 2021–2025 (USD MILLION)
TABLE 238
SOUTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY SERVICE, 2026–2031 (USD MILLION)
TABLE 239
SOUTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY, 2021–2025 (KILOTON)
TABLE 240
SOUTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY, 2026–2031 (KILOTON)
TABLE 241
SOUTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY, 2021–2025 (USD MILLION)
TABLE 242
SOUTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY TECHNOLOGY, 2026–2031 (USD MILLION)
TABLE 243
SOUTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 244
SOUTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 245
SOUTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 246
SOUTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 247
SOUTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY COUNTRY, 2021–2025 (KILOTON)
TABLE 248
SOUTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY COUNTRY, 2026–2031 (KILOTON)
TABLE 249
SOUTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY COUNTRY, 2021–2025 (USD MILLION)
TABLE 250
SOUTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY COUNTRY, 2026–2031 (USD MILLION)
TABLE 251
BRAZIL: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 252
BRAZIL: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 253
BRAZIL: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 254
BRAZIL: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 255
ARGENTINA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 256
ARGENTINA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 257
ARGENTINA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 258
ARGENTINA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 259
REST OF SOUTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (KILOTON)
TABLE 260
REST OF SOUTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)
TABLE 261
REST OF SOUTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2021–2025 (USD MILLION)
TABLE 262
REST OF SOUTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
TABLE 263
STRATEGIES ADOPTED BY CCUS SERVICE PROVIDERS
TABLE 264
DEGREE OF COMPETITION: CCUS MARKET
TABLE 265
CCUS MARKET: REGION FOOTPRINT
TABLE 266
CCUS MARKET: SERVICE FOOTPRINT
TABLE 267
CCUS MARKET: END-USE INDUSTRY FOOTPRINT
TABLE 268
CCUS MARKET: DETAILED LIST OF KEY STARTUPS/SMES
TABLE 269
CCUS MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
TABLE 270
CCUS MARKET: DEALS, JANUARY 2020– JULY 2026
TABLE 271
CCUS MARKET: EXPANSIONS, JANUARY 2020–JULY 2026
TABLE 272
CCUS MARKET: OTHER DEVELOPMENT, JANUARY 2020–JULY 2026
TABLE 273
FLUOR CORPORATION: COMPANY OVERVIEW
TABLE 274
FLUOR CORPORATION: PRODUCTS OFFERED
TABLE 275
FLUOR CORPORATION: DEALS
TABLE 276
FLUOR CORPORATION: OTHER DEVELOPMENTS
TABLE 277
EXXON MOBIL CORPORATION: COMPANY OVERVIEW
TABLE 278
EXXON MOBIL CORPORATION: PRODUCTS OFFERED
TABLE 279
EXXON MOBIL CORPORATION: DEALS
TABLE 280
EXXON MOBIL CORPORATION: EXPANSIONS
TABLE 281
EXXON MOBIL CORPORATION: OTHER DEVELOPMENTS
TABLE 282
SHELL PLC: COMPANY OVERVIEW
TABLE 283
SHELL PLC: DEALS
TABLE 284
SHELL PLC: EXPANSIONS
TABLE 285
SHELL PLC: OTHER DEVELOPMENTS
TABLE 286
EQUINOR ASA: COMPANY OVERVIEW
TABLE 287
EQUINOR ASA: PRODUCTS OFFERED
TABLE 288
EQUINOR ASA: DEALS
TABLE 289
EQUINOR ASA: EXPANSIONS
TABLE 290
EQUINOR ASA: OTHER DEVELOPMENTS
TABLE 291
TOTALENERGIES SE: COMPANY OVERVIEW
TABLE 292
TOTALENERGIES SE: PRODUCTS OFFERED
TABLE 293
TOTALENERGIES SE: DEALS
TABLE 294
TOTALENERGIES SE: EXPANSIONS
TABLE 295
TOTALENERGIES SE: OTHER DEVELOPMENTS
TABLE 296
LINDE PLC: COMPANY OVERVIEW
TABLE 297
LINDE PLC: PRODUCTS OFFERED
TABLE 298
LINDE PLC: DEALS
TABLE 299
LINDE PLC: EXPANSIONS
TABLE 300
MITSUBISHI HEAVY INDUSTRIES, LTD.: COMPANY OVERVIEW
TABLE 301
MITSUBISHI HEAVY INDUSTRIES, LTD.: DEALS
TABLE 302
MITSUBISHI HEAVY INDUSTRIES, LTD.: EXPANSIONS
TABLE 303
MITSUBISHI HEAVY INDUSTRIES, LTD.: OTHER DEVELOPMENTS
TABLE 304
JGC HOLDINGS CORPORATION: COMPANY OVERVIEW
TABLE 305
JGC HOLDINGS CORPORATION: PRODUCTS OFFERED
TABLE 306
JGC HOLDINGS CORPORATION: DEALS
TABLE 307
JGC HOLDINGS CORPORATION: EXPANSIONS
TABLE 308
JGC HOLDINGS CORPORATION: OTHER DEVELOPMENTS
TABLE 309
SCHLUMBERGER LIMITED: COMPANY OVERVIEW
TABLE 310
SCHLUMBERGER LIMITED: PRODUCTS OFFERED
TABLE 311
SCHLUMBERGER LIMITED: DEALS
TABLE 312
SCHLUMBERGER LIMITED: EXPANSIONS
TABLE 313
SCHLUMBERGER LIMITED: OTHER DEVELOPMENTS
TABLE 314
AKER SOLUTIONS: COMPANY OVERVIEW
TABLE 315
AKER SOLUTIONS: PRODUCTS OFFERED
TABLE 316
AKER SOLUTIONS: DEALS
TABLE 317
AKER SOLUTIONS: EXPANSIONS
TABLE 318
AKER SOLUTIONS: OTHER DEVELOPMENTS
TABLE 319
HONEYWELL INTERNATIONAL: COMPANY OVERVIEW
TABLE 320
HONEYWELL INTERNATIONAL: PRODUCTS OFFERED
TABLE 321
HONEYWELL INTERNATIONAL: DEALS
TABLE 322
HONEYWELL INTERNATIONAL: EXPANSIONS
TABLE 323
HONEYWELL INTERNATIONAL: OTHER DEVELOPMENTS
TABLE 324
HITACHI, LTD.: COMPANY OVERVIEW
TABLE 325
HITACHI, LTD.: PRODUCTS OFFERED
TABLE 326
HITACHI, LTD.: DEALS
TABLE 327
HITACHI LTD.: EXPANSIONS
TABLE 328
HITACHI LTD.: OTHER DEVELOPMENTS
TABLE 329
SIEMENS AG: COMPANY OVERVIEW
TABLE 330
SIEMENS AG: PRODUCTS OFFERED
TABLE 331
SIEMENS AG: DEALS
TABLE 332
SIEMENS AG: EXPANSIONS
TABLE 333
SIEMENS AG: OTHER DEVELOPMENTS
TABLE 334
GE VERNOVA: COMPANY OVERVIEW
TABLE 335
GE VERNOVA: PRODUCTS OFFERED
TABLE 336
GE VERNOVA: DEALS
TABLE 337
GE VERNOVA: OTHER DEVELOPMENTS
TABLE 338
HALLIBURTON: COMPANY OVERVIEW
TABLE 339
HALLIBURTON: PRODUCTS OFFERED
TABLE 340
CLIMEWORKS AG: COMPANY OVERVIEW
TABLE 341
CARBON CLEAN SOLUTIONS: COMPANY OVERVIEW
TABLE 342
OCCIDENTAL: COMPANY OVERVIEW
TABLE 343
GREEN MINERALS B.V.: COMPANY OVERVIEW
TABLE 344
CARBICRETE: COMPANY OVERVIEW
TABLE 345
CARBONFREE: COMPANY OVERVIEW
TABLE 346
SVANTE TECHNOLOGIES INC.: COMPANY OVERVIEW
TABLE 347
GREEN POWER INTERNATIONAL PVT. LTD.: COMPANY OVERVIEW
TABLE 348
WOLF MIDSTREAM: COMPANY OVERVIEW
TABLE 349
BABCOCK & WILCOX: COMPANY OVERVIEW
TABLE 350
LIST OF PRIMARY INTERVIEW PARTICIPANTS
LIST OF FIGURES
FIGURE 1
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET: SEGMENTATION AND REGIONAL SCOPE
FIGURE 2
KEY INSIGHTS AND MARKET HIGHLIGHTS
FIGURE 3
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, 2026–2031
FIGURE 4
MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN CARBON CAPTURE, UTILIZATION, AND STORAGE (CCUS) MARKET (2022–2025)
FIGURE 5
DISRUPTIVE TRENDS IMPACTING GROWTH OF CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET
FIGURE 6
HIGH-GROWTH SEGMENTS AND EMERGING FRONTIERS IN CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, 2026–2031
FIGURE 7
EUROPE TO BE FASTEST-GROWING REGION IN GLOBAL CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET
FIGURE 8
RISING INDUSTRIAL DECARBONIZATION MANDATES AND CARBON PRICING DRIVING GLOBAL CCUS MARKET
FIGURE 9
OIL & GAS AND NORTH AMERICA ACCOUNTED FOR LARGEST MARKET SHARE IN 2025
FIGURE 10
CAPTURE ACCOUNTED FOR LARGEST SHARE OF CCUS MARKET IN 2025
FIGURE 11
NETHERLANDS AND NORWAY TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD
FIGURE 12
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
FIGURE 13
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET: PORTER’S FIVE FORCES ANALYSIS
FIGURE 14
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET: VALUE CHAIN ANALYSIS
FIGURE 15
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET: KEY PARTICIPANTS IN ECOSYSTEM
FIGURE 16
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET: ECOSYSTEM ANALYSIS
FIGURE 17
AVERAGE SELLING PRICE TREND OF CARBON CAPTURE, UTILIZATION, AND STORAGE, BY REGION, 2023–2025
FIGURE 18
IMPORT SCENARIO FOR HS CODE 281121-COMPLIANT PRODUCTS, BY KEY COUNTRIES, 2021–2025
FIGURE 19
EXPORT SCENARIO FOR HS CODE 281121-COMPLIANT PRODUCTS, BY KEY COUNTRIES, 2021–2025
FIGURE 20
TRENDS/DISRUPTIONS INFLUENCING CUSTOMER BUSINESS
FIGURE 21
CCUS MARKET: INVESTMENT AND FUNDING SCENARIO, 2021–2025
FIGURE 22
PATENT ANALYSIS, BY DOCUMENT TYPE, 2015–2025
FIGURE 23
PATENT PUBLICATION TRENDS, 2015−2025
FIGURE 24
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET: LEGAL STATUS OF PATENTS, 2015–2025
FIGURE 25
JURISDICTION OF US REGISTERED HIGHEST SHARE OF PATENTS, 2015–2025
FIGURE 26
TOP PATENT APPLICANTS, 2015–2025
FIGURE 27
FUTURE APPLICATIONS OF CARBON CAPTURE, UTILIZATION, AND STORAGE
FIGURE 28
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET: DECISION-MAKING FACTORS
FIGURE 29
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY APPLICATION
FIGURE 30
KEY BUYING CRITERIA, BY APPLICATION
FIGURE 31
ADOPTION BARRIERS & INTERNAL CHALLENGES
FIGURE 32
CAPTURE SERVICE TO DOMINATE CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET, 2026–2031 (USD MILLION)
FIGURE 33
CHEMICAL LOOPING TO DOMINATE CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET
FIGURE 34
OIL& GAS TO DOMINATE CARBON CAPTURE, UTILIZATION,
FIGURE 35
AND STORAGE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)
FIGURE 36
NETHERLANDS AND NORWAY TO REGISTER HIGHEST GROWTH DURING FORECAST PERIOD
FIGURE 37
NORTH AMERICA: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET SNAPSHOT
FIGURE 38
EUROPE: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET SNAPSHOT
FIGURE 39
ASIA PACIFIC: CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET SNAPSHOT
FIGURE 40
CCUS MARKET: REVENUE ANALYSIS OF KEY PLAYERS, 2020–2025 (USD MILLION)
FIGURE 41
CCUS MARKET SHARE ANALYSIS, 2025
FIGURE 42
CCUS MARKET: TOP TRENDING BRAND/PRODUCT ANALYSIS
FIGURE 43
BRAND COMPARATIVE ANALYSIS, BY CCUS SERVICES
FIGURE 44
CCUS MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
FIGURE 45
CCUS MARKET: COMPANY FOOTPRINT
FIGURE 46
CCUS MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
FIGURE 47
CCUS MARKET: EV/EBITDA OF KEY VENDORS
FIGURE 48
YEAR-TO-DATE (YTD) PRICE TOTAL RETURN AND 5-YEAR STOCK BETA OF KEY VENDORS
FIGURE 49
PROMINENT CCUS SERVICE PROVIDER FIRMS IN 2025 (USD BILLION)
FIGURE 50
FLUOR CORPORATION: COMPANY SNAPSHOT
FIGURE 51
EXXON MOBIL CORPORATION: COMPANY SNAPSHOT
FIGURE 52
SHELL PLC: COMPANY SNAPSHOT
FIGURE 53
EQUINOR ASA: COMPANY SNAPSHOT
FIGURE 54
TOTALENERGIES SE: COMPANY SNAPSHOT
FIGURE 55
LINDE PLC: COMPANY SNAPSHOT
FIGURE 56
MITSUBISHI HEAVY INDUSTRIES, LTD.: COMPANY SNAPSHOT
FIGURE 57
JGC HOLDINGS CORPORATION: COMPANY SNAPSHOT
FIGURE 58
SCHLUMBERGER LIMITED: COMPANY SNAPSHOT
FIGURE 59
AKER SOLUTIONS: COMPANY SNAPSHOT
FIGURE 60
HONEYWELL INTERNATIONAL: COMPANY SNAPSHOT
FIGURE 61
HITACHI, LTD.: COMPANY SNAPSHOT
FIGURE 62
SIEMENS AG: COMPANY SNAPSHOT
FIGURE 63
GE VERNOVA: COMPANY SNAPSHOT
FIGURE 64
HALLIBURTON: COMPANY SNAPSHOT
FIGURE 65
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET: RESEARCH DESIGN
FIGURE 66
KEY DATA FROM SECONDARY SOURCES
FIGURE 67
KEY DATA FROM PRIMARY SOURCES
FIGURE 68
BREAKDOWN OF INTERVIEWS WITH EXPERTS
FIGURE 69
KEY INDUSTRY INSIGHTS
FIGURE 70
MARKET SIZE ESTIMATION METHODOLOGY: BOTTOM-UP APPROACH & TOP-DOWN APPROACH
FIGURE 71
APPROACH 1: TOP-DOWN PENETRATION-BASED MARKET ESTIMATION ANALYSIS
FIGURE 72
APPROACH 2: SUPPLY-SIDE ANALYSIS
FIGURE 73
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET: DATA TRIANGULATION
FIGURE 74
FACTOR ANALYSIS
FIGURE 75
RESEARCH ASSUMPTIONS
Methodology
This study consisted of two main tasks to determine the current size of the carbon capture, utilization, and storage market. The first task involved conducting extensive secondary research to gather information on the carbon capture, utilization, and storage market, related markets, and parent markets. The results, assumptions, and market sizing were further verified through primary research with industry players. Market size was estimated using both top-down and bottom-up approaches. Further market segmentation and data triangulation techniques were used to obtain the market size of segments and subsegments.
Secondary Research
Sources used for secondary research for this study include annual reports, financial documents, product portfolios, technical sheets, certificates, company websites, industry magazines, and industry associations. Secondary research was conducted to gain insights into the value chain of carbon capture, utilization, and storage service providers, major market players, market segmentation, and classification by service, technology, end-use industry, and geography. The data gathered through this process was further analyzed to estimate the size of the global carbon capture, utilization, and storage market and its segments and subsegments.
Primary Research
Extensive primary research was conducted after obtaining information regarding the market scenario through secondary research. We conducted several primary interviews with market experts on both the demand and supply sides across major countries. We collected primary data through questionnaires, emails, and telephonic interviews. The primary sources from the supply side included various industry experts, such as chief experience officers (CXOs), vice presidents (VPs), business development/marketing directors, product development/innovation teams, related key executives from the carbon capture, utilization, and storage service industry, system integrators, technology suppliers, EPC contractors, component providers, distributors, and key opinion leaders. Primary interviews were conducted to gather insights such as market statistics, revenue data from products and services, market breakdowns, market size estimates, market forecasts, and data triangulation. Primary research helped in understanding various trends related to service, technology, end-use industry, and region. Stakeholders from the demand side, such as CIOs, CTOs, CSOs, and installation teams of the customers/end users who are seeking carbon capture, utilization, and storage services, were interviewed to understand the buyer’s perspective on product/service providers, as well as their current usage of carbon capture, utilization, and storage products/services and future outlook of their business, which will affect the overall market.
Breakup of Primary Research:
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
The research methodology used to estimate the size of the carbon capture, utilization, and storage market includes the following details. The market size was estimated from the demand side. The market was expanded based on global demand for carbon capture, utilization, and storage products/services across different industries. These procurements provide demand-side information for each end-use industry in the carbon capture, utilization, and storage market. For each end-use industry, all possible segments of the carbon capture, utilization, and storage market were integrated and mapped.
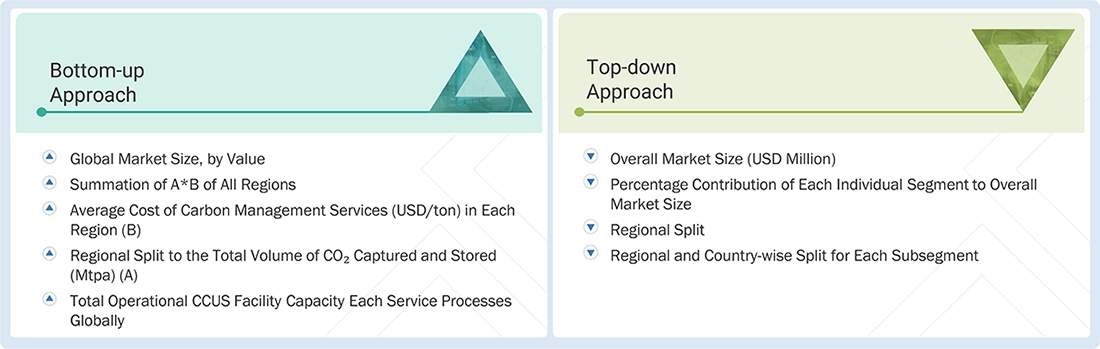
Data Triangulation
After determining the overall size through the market size estimation process explained above, the total market was split into several segments and subsegments. The data triangulation and market breakdown procedures explained below were implemented, wherever applicable, to complete the overall market engineering process and arrive at the exact statistics for various market segments and subsegments. The data were triangulated by studying factors and trends from both the demand and supply sides. In addition, the market size was validated using both the top-down and bottom-up approaches.
Market Definition
The carbon capture, utilization, and storage market comprises technologies, solutions, and associated services across the CO2 management value chain, including the capture of CO2 from industrial facilities, power generation plants, and the atmosphere; its conditioning, compression, and transportation; and its subsequent utilization or permanent geological storage. The market encompasses solutions/services for CO2 capture, transport, utilization, and storage, as well as integrated systems that connect these stages to enable carbon management and emission reduction across industrial and energy applications.
Key Stakeholders
- CCUS service providers
- Universities, governments, and research organizations
- Associations and industrial bodies
- Environmental support agencies
- Investment banks and private equity firms
- Fire safety testing and certification organizations
- R&D institutes and research organizations
- Raw material suppliers
- Government and regulatory authorities
Report Objectives
- To define, describe, and forecast the carbon capture, utilization, and storage market in terms of volume and value
- To provide detailed information regarding the key factors, such as drivers, restraints, opportunities, and challenges influencing market growth
- To analyze and project the market size by service, technology, end-use industry, and region
- To forecast the global carbon capture, utilization, and storage market size, along with regional and country-level data, and analyze key country-specific trends
- To strategically analyze micromarkets, including individual growth trends, prospects, and submarket contributions to the overall market
- To analyze the market opportunities and the competitive landscape for stakeholders and market leaders
- To assess recent market developments and competitive strategies, such as agreements, contracts, acquisitions, and product developments/product launches, to map the competitive landscape
- To strategically profile the key market players and comprehensively analyze their core competencies
Available customizations:
MarketsandMarkets offers the following customizations for this market report:
- Additional country-level analysis of the carbon capture, utilization, and storage market
Product Analysis
- Product matrix, which provides a detailed comparison of the product portfolio of each company in the market
Key Questions Addressed by the Report
Who are the major companies in the CCUS market? What key strategies have market players adopted to strengthen their market presence?
Key players include Fluor Corporation (US), Exxon Mobil Corporation (US), Linde plc (UK), Shell Plc. (UK), Mitsubishi Heavy Industries, Ltd. (Japan), JGC Holdings Corporation (Japan), Schlumberger Limited (US), Aker Solutions (Norway), Honeywell International (US), Equinor ASA (Norway), TotalEnergies SE (France), Hitachi Ltd (Japan), Siemens AG (Germany), GE Vernova (US), and Halliburton (US). Their key strategies include technology advancements, acquisitions, and expansions.
What are the drivers and opportunities for the CCUS market?
Increasing R&D activities and growing investments in the CCUS industry are key drivers fueling market growth.
Which region is projected to account for the largest market share?
North America is projected to be the largest market for CCUS due to the presence of major CCUS projects.
What is the projected growth rate of the CCUS market over the next five years?
The CCUS market is projected to grow at a CAGR of 25.0% during the forecast period, in terms of value.
How is the CCUS market aligned for future growth?
The CCUS market is rapidly expanding, driven by increasing demand in the oil & gas sector and growing government initiatives aimed at reducing carbon emissions.
Fact checked
Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the Carbon Capture, Utilization, and Storage Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Custom Market Research Services
We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements
Get 10% Free CustomisationTESTIMONIALS
We at Nissan Chemicals Corporation have been clients of MarketsandMarkets for more than a year now. We recently consulted MarketsandMarkets for a study, the team at MarketsandMarkets was extremely professional and organized. The business insights were very detailed and aligned well with our expectations that really helped us formulate the Business Plans and device new strategies for development themes. MarketsandMarkets offers a unique combination of expertise and dedicated engagement model. Their research findings have helped us in designing our Pricing Strategy which will make it easier for us to predict the future sales and profits for the next ten years. We look forward to working with MarketsandMarkets in the future.
VP of Strategy & New Business Development
Leading Specialty Chemical Company
The MarketsandMarkets Engagement Model, composed of both the Knowledge Store and advisory custom research, has greatly helped us in understanding our markets and making strategic decisions. The Knowledge Store is a fast way to allow everyone in our organization to understand more about most any market they are interested in. The ability to then get custom research done and get answers to specific strategic questions and market insight has been spectacular. The Markets and Markets team feel more like colleagues than vendors and their services have helped us change our culture where statements of things like growth opportunities and competitive position are always backed by industry research.

Rich Gibson,
Director, Corporate Strategy
Milliken & Company,
Leading Industrial Manufacturer of specialty chemical, floor covering, performance and protective textile materials, and healthcaremilliken.com
MarketsandMarkets is a trusted resource that helps us to better understand markets that are near-adjacencies-whether its technology, value chain or geography. Their Knowledge Store platform provides a dashboard of markets and their characteristics which is easy to use and saves us time.
Adam Shaw,
Market Development and Strategy Manager
AdvanSix Inc. USA,
An American Leader in Chemicalswww.advansix.com
The Knowledge Store from MarketsandMarkets is a valuable tool which has helped my team acquire greater insight in to the end markets that our business serves. This has enabled us to help our company build stronger strategies throughout our planning process.
TOSHIO KINOSHITA
Senior Chif Consultion Research & Consulting Division
Mitsubishi Chemical Research Corporation,
Leading Manufacturer of Chemical Productswww.mitsubishichem-res.co.jp/en/

We recently engaged with MarketsandMarkets for a study, the team not only clearly understood our business objectives but was also extremely professional in the way they handled the entire project. The study was efficiently conducted in a phase-wise manner, and the engagement model furnished us with high-quality business insights that far exceeded our expectations at each phase. We were especially happy that MarketsandMarkets could provide us with both, an English as well as a Japanese version of the study. A special thanks to the Analyst Team and Client Services Team, whose fluency in Japanese enhanced our comfort level, as we could converse with them in our preferred language.
Independent entrepreneurs
Arrow Precision
We approached MarketsandMarkets for study on Proppants Market, and their work exceeded our expectations. The study conducted was comprehensive and enabled us to view the market through the various dimensions. In addition, the team was extraordinarily responsive throughout the process and resolved our queries on time. I strongly recommend MarketsandMarkets and will certainly consider them for additional market assessments we will need in the future.
Global engineering company, Japan
Deputy Manager,
Strategic Planning OfficeThe high-quality insights shared by the MarketsandMarkets team helped us understand the pharmaceutical plant designers in a specific geography. It also captured the risks that we may likely face in communicating with our potential partners. The study would enable us identify partners, which would impact our future growth.
- US Carbon Capture, Utilization, and Storage Market
- Canada Carbon Capture, Utilization, and Storage Market
- Mexico Carbon Capture, Utilization, and Storage Market
- UK Carbon Capture, Utilization, and Storage Market
- France Carbon Capture, Utilization, and Storage Market
- Netherlands Carbon Capture, Utilization, and Storage Market
- Italy Carbon Capture, Utilization, and Storage Market
- Norway Carbon Capture, Utilization, and Storage Market
- China Carbon Capture, Utilization, and Storage Market
- Japan Carbon Capture, Utilization, and Storage Market
- India Carbon Capture, Utilization, and Storage Market
- Australia Carbon Capture, Utilization, and Storage Market
- Brazil Carbon Capture, Utilization, and Storage Market
- Argentina Carbon Capture, Utilization, and Storage Market
- Rest Of Europe Carbon Capture, Utilization, and Storage Market
- Rest Of Asia Pacific Carbon Capture, Utilization, and Storage Market






Growth opportunities and latent adjacency in Carbon Capture, Utilization, and Storage Market