Medical Coating Market

Medical Coatings Market by Coating Type (Active, Passive), By Material (Polymers, Metals), By Substrate (Metals, Polymers, Ceramics), By Application (Medical Devices, Medical Implants, Medical Equipment & Tools), By Region - Global Forecast to 2031




OVERVIEW
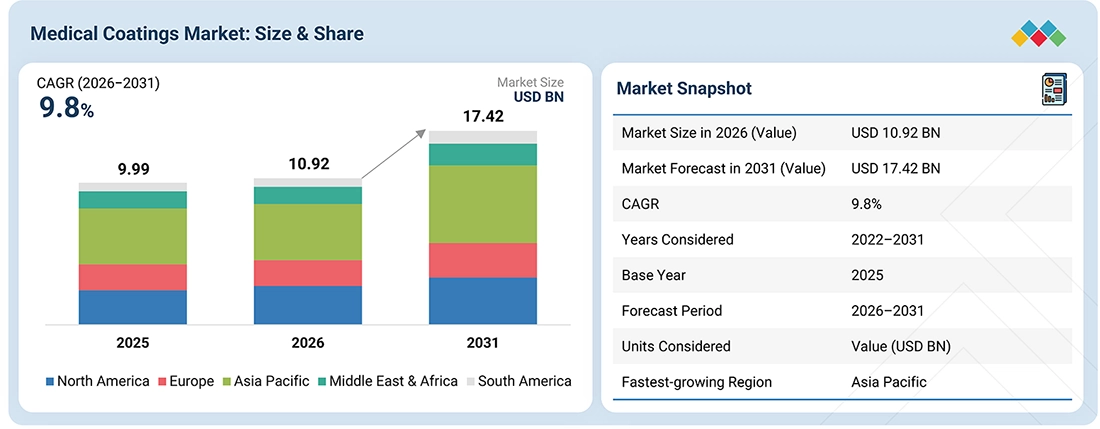
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
The medical coating market size is projected to grow from USD 10.92 billion in 2026 to USD 17.42 billion by 2031, registering a CAGR of 9.8% during the forecast period. The medical coatings market is predicted to witness stable growth during the forecast period due to the rising demand for medical coatings in medical devices and healthcare equipment. The application of medical coatings is increasing as medical coatings provide properties such as increased biocompatibility, enhanced wear and corrosion resistance, low friction, anti-microbial adhesion, among others. Increased demand for minimally invasive surgery procedures, increasing use of implantable medical devices, rising incidence of chronic conditions, and advances in medical device technology are likely to drive the growth of the medical coatings market. Furthermore, increased investment in healthcare infrastructure, increasing demand for anti-microbial and drug-eluting coatings, technological developments in coating materials, and stringent regulations concerning medical devices are expected to propel market growth.
KEY TAKEAWAYS
-
By RegionNorth America dominated the medical coating market, with a share of 40.9%, in terms of value, in 2025.
-
By TypeThe passive segment dominated the market with a share of 58.1%, in terms of value, in 2025.
-
By MaterialBased on material, the polymers segment is projected to register the highest CAGR of 10.3% in the medical coating market during the forecast period.
-
By SubstrateThe polymers segment held the largest market share of 43.9%, in terms of value, in 2025.
-
By ApplicationBased on the application the medical devices segment held the largest market share of 35.8%, in terms of value in 2025.
-
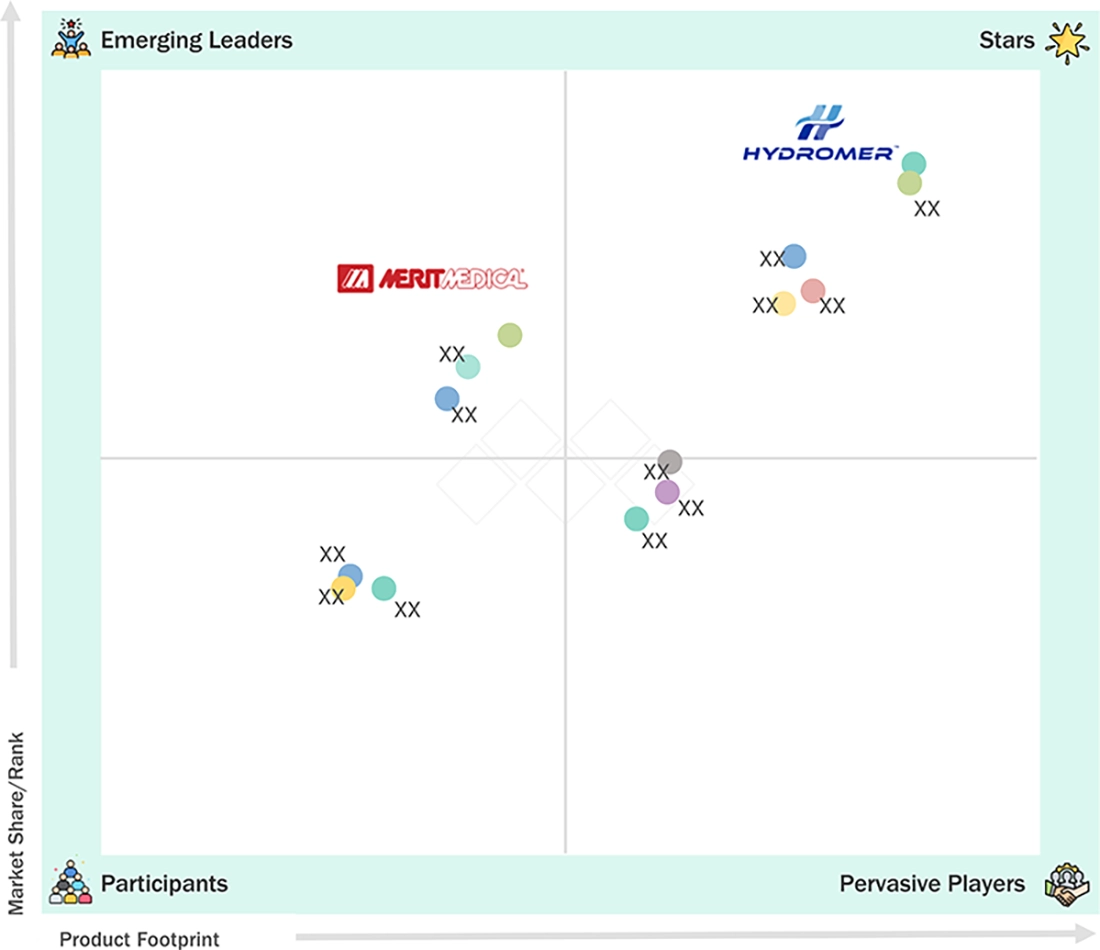
COMPETITIVE LANDSCAPE- KEY PLAYERSCompanies such as Hydromer, DSM-Firmenich, Surmodics were identified as some of the star players in the medical coating market , given their strong market share and product footprint
-
COMPETITIVE LANDSCAPE- STARTUPSApplied Membrane Technologies, Formacoat, TUA Systems among others, have distinguished themselves among startups and SMEs by securing strong footholds in specialized niche areas, underscoring their potential as emerging market leaders.
There are many factors which have contributed in the consistent growth of the market for green water treatment chemicals. One of the main factors for the consistent growth of the market is the growing need for sustainable water treatment solutions that can help in purifying the water without causing much damage to the environment. There are many other factors such as industrialization, urbanization, water scarcity, and growing consumption of these chemicals in sectors like municipal wastewater treatment, industrial water treatment, drinking water treatment, food & beverages, pharmaceuticals, chemicals, and power generation industries. Growing wastewater generation and investments in water recycling and reutilization infrastructure have been a major factor in the growing demand for these chemicals. Apart from this, growing environmental regulations and the growing demand for biodegradable and natural water treatment chemicals are some of the major factors in this market.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
Medical coating is increasingly being used in medical devices, implants, surgical instruments, catheters, guidewires, stents, orthopedic implants, and other applications where there is a need for better performance, durability, and biocompatibility of the medical device. Antimicrobial coating, drug-eluting coating, hydrophilic and hydrophobic coating, bioactive coating, and biodegradable coating materials are some of the latest advances which are enabling medical devices to improve their performance while at the same time making them safer from infections, thrombosis, corrosion, and wear and tear. Growing demand for minimally invasive procedures, increased adoption of implantable medical devices, rising prevalence of chronic diseases, and the increasing focus on infection prevention are emerging as the major drivers for the growth of the medical coating market. Apart from these, strict regulations, advances in coating technology, demand for long-lasting implants, and the emergence of multifunctional coatings are the other growth drivers for the medical coating industry.
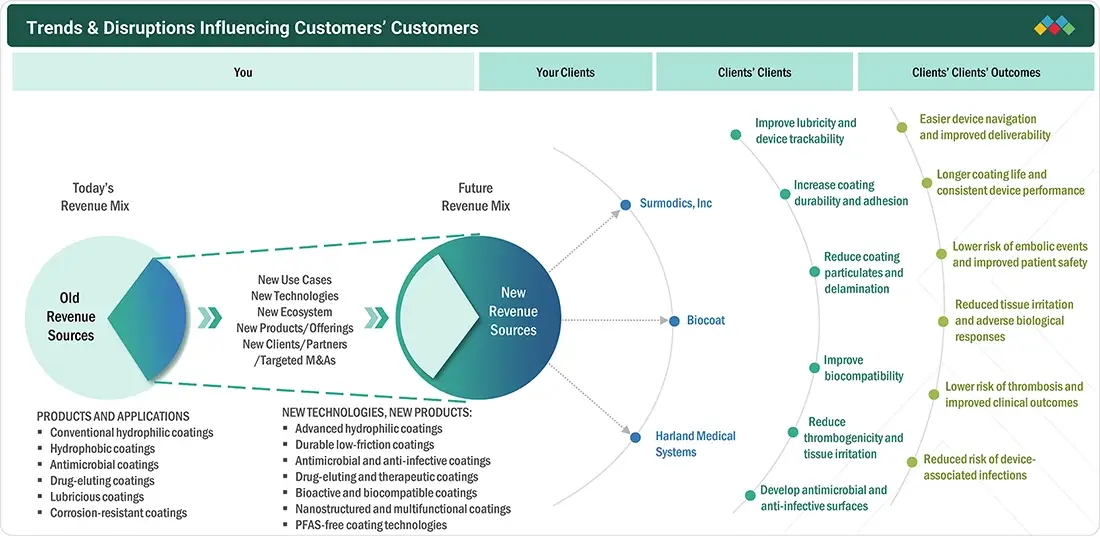
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Level
-
Increasing prevalence of chronic diseases and aging population

-
Rise in hospital-acquired infections


Level
-
Low shelf life and durability issues

-
Raw material price volatility and high costs


Level
-
Rise in demand for antimicrobial and drug-eluting coatings

-
Technological advancements and nanotechnology


Level
-
Biocompatibility and durability concerns

-
Complex application and quality control

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Increasing prevalence of chronic diseases and aging population
Medical coating products are mainly being influenced by the prevalence of chronic diseases, increase in geriatric population, and adoption of sophisticated medical devices. Heart diseases, diabetes, cancer, neurodegenerative disorders, and orthopedic diseases are prevalent diseases that require frequent monitoring, treatment, and management, thereby creating the need for catheters, guidewires, stents, implants, surgical devices, and other medical equipment. Medical coatings enhance the functioning of these devices by decreasing the friction, increasing lubricity, reducing the risk of clotting, reducing the risk of corrosion, ensuring tissue compatibility, and longevity of the medical device. Another factor contributing towards the growth of the medical coatings market is the increase in preference for minimally invasive procedures because of the lubricious and hydrophilic coating which allow medical devices to glide easily inside the blood vessels and other body parts. Moreover, increasing expenditure on healthcare, better access to healthcare, and patient safety concerns are fueling the demand further. Moreover, increase in awareness regarding the health care-associated infection is driving hospitals and medical devices manufacturers to go for antimicrobial coatings, which helps in decreasing microorganism colony on the medical devices.
Restraint: Low shelf life and durability issues
The medical coating market is constrained due to various factors such as restricted shelf life, coating durability, high cost of raw materials, difficult manufacturing process, and long approval procedures. Most coatings should maintain their chemical, physical, and biological properties during storage, transportation, sterilization process, and application in the human body. Nevertheless, the effect of heat, moisture, radiation, chemicals, and repeated mechanical action may change the coating properties, such as its adhesion to the surface, release mechanism of drugs, lubricating characteristics, and its antimicrobial action. Cracked, peeling, flaking, and premature degradation of coatings may negatively impact the functionality and safety of coated devices. Moreover, the high cost of specialized raw materials, such as silicone, PTFE, polymers, bioactive compounds, and antimicrobial compounds is another factor affecting the medical coating market. It is necessary for manufacturers to use specialized clean room facilities for the production process, precision coating equipment, validation process, and quality control system, which will increase capital and operational expenditure. Moreover, strict regulatory requirements need comprehensive testing on the biocompatibility, toxicity, extractable, and leachable nature of medical coatings.
Opportunity: Rise in demand for antimicrobial and drug-eluting coatings
Growth in demand for antimicrobial, drug-eluting, hydrophilic, lubricious and bioactive coatings presents ample opportunities for those in the medical coatings industry. Increasing importance of antimicrobial coatings is presented through hospitals' efforts towards decreasing infections resulting from usage of catheters, orthopedic implants, wound care products, surgical instruments and other invasive devices. Drug-eluting coatings present opportunities in cardiovascular and orthopedic markets because of the capability of delivering therapeutic substances straight to the point of application, which helps in preventing inflammation, re-stenosis, infections or excessive tissues growing. Hydrophilic and lubricious coatings become popular in minimally invasive products like guidewires, introducers, catheters, endoscopes and delivery systems due to their smooth moving capabilities. Nanotechnology, biomaterial science, polymer chemistry and surface engineering advances help in creating coatings with multiple functions including antimicrobial effects, corrosion resistance, drug delivery and increased integration with tissues. Growing healthcare markets also represent a significant source of opportunities because of developing infrastructure, increased procedures number and advanced devices utilization.
Challenge: Biocompatibility and durability concerns
Medical coatings face significant challenges relating to biocompatibility, durability, regulatory compliance, and uniform application of the coating. A medical coating needs to provide consistent performance without any toxic effects, inflammatory response, allergic reactions, thrombosis, or degradation of coating in the biological environment. This problem is particularly relevant when it comes to implantable devices where the coatings can remain in contact with tissue, blood, or bones for prolonged periods. In addition, it is necessary to make sure that the coating is applied evenly even to complicated device surfaces and remains stable under conditions of sterilization, exposure to body fluids, mechanical stress, pressure, deformation, and frequent use. However, solving these problems is complicated due to the fact that enhancing one characteristic of the coating affects other characteristics in a negative way. For instance, improving antimicrobial activity or drug delivery might have adverse effects on adhesion, elasticity, or biocompatibility. The development of multifunctional coatings adds up to the complexity of the formulations and manufacturing process. Regulatory authorities demand considerable evidence concerning safety, stability, toxicity, delivery profile, and long-term performance of the coatings, which prolongs the development period and leads to higher compliance expenses.
MEDICAL COATING MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Hydrophilic, antimicrobial, and specialty medical coatings for catheters, guidewires, cardiovascular devices, urological devices, and other medical devices requiring improved surface properties | Reduced friction, improved lubricity, enhanced device maneuverability, reduced bacterial adhesion, improved patient comfort, and enhanced device performance |
 |
Medical-grade coating technologies and biomaterials for catheters, medical devices, implants, and other healthcare applications, including hydrophilic and functional surface coatings | Improved biocompatibility, reduced friction, enhanced lubricity, improved device handling, reduced tissue trauma, and enhanced device functionality |
 |
Drug-delivery and surface modification technologies for medical devices, including hydrophilic coatings, drug-coated balloons, stents, and other interventional cardiovascular and peripheral vascular devices | Improved device lubricity, controlled drug delivery, reduced friction, enhanced navigation, improved biocompatibility, and support for minimally invasive procedures |
 |
Hydrophilic and specialty coatings for medical devices such as catheters, guidewires, and other interventional devices used in cardiovascular, neurovascular, peripheral vascular, and urological applications | Reduced surface friction, improved lubricity, enhanced device maneuverability, reduced tissue trauma, improved biocompatibility, and enhanced procedural performance |
 |
Hydrophilic, antimicrobial, lubricious, and specialty coatings for medical devices, including catheters, guidewires, stents, and other minimally invasive medical devices | Improved lubricity, reduced friction, enhanced device navigation, reduced tissue interaction, improved infection-control performance, and enhanced device functionality |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
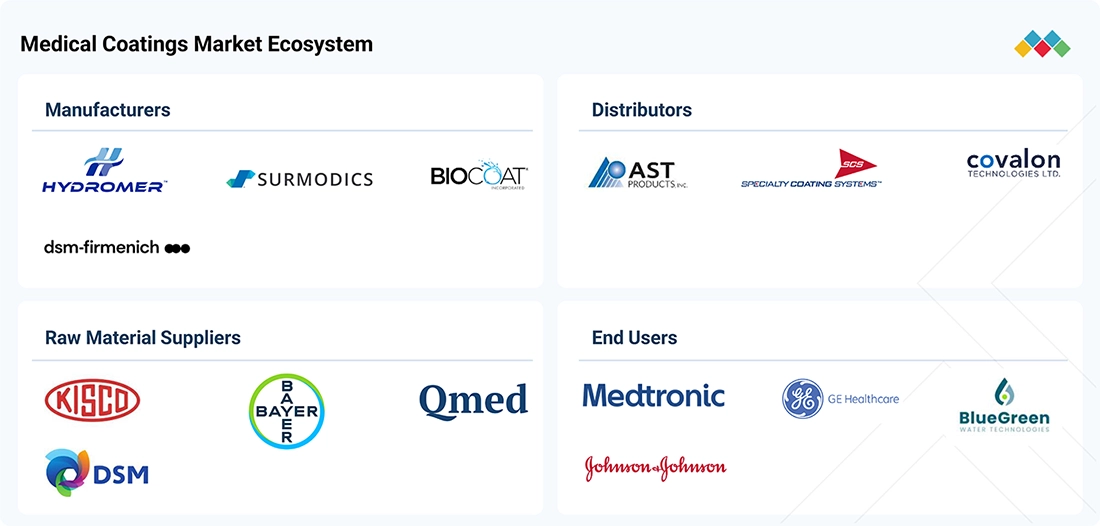
The medical coating market operates in various types of value chains that include coating materials suppliers, polymer or specialty chemicals manufactures, medical coatings formulation companies, coating technology companies, medical device manufactures, coating services companies, distribution channels, and end user industries like health care industry. The types of products available in the medical coatings market include hydrophilic coatings, antimicrobial coatings, drug-eluting coatings, antithrombogenic coatings, lubricious coatings, bioactive coatings, and many more. Other services included in the value chain includes surface preparations, formulation of coatings, application of coatings, curing, sterilization compatibility tests, biocompatibility tests, quality inspection, regulatory assistance, process validation, technical assistance and custom medical coatings. The facilities for manufacturing and application of medical coatings are mainly located in North America, Europe, and Asia Pacific due to the presence of medical device manufacturers, well-developed health care infrastructure, well-developed R&D facilities, stringent medical device regulations, and rising demand for minimally invasive surgical procedures and implantable medical devices.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
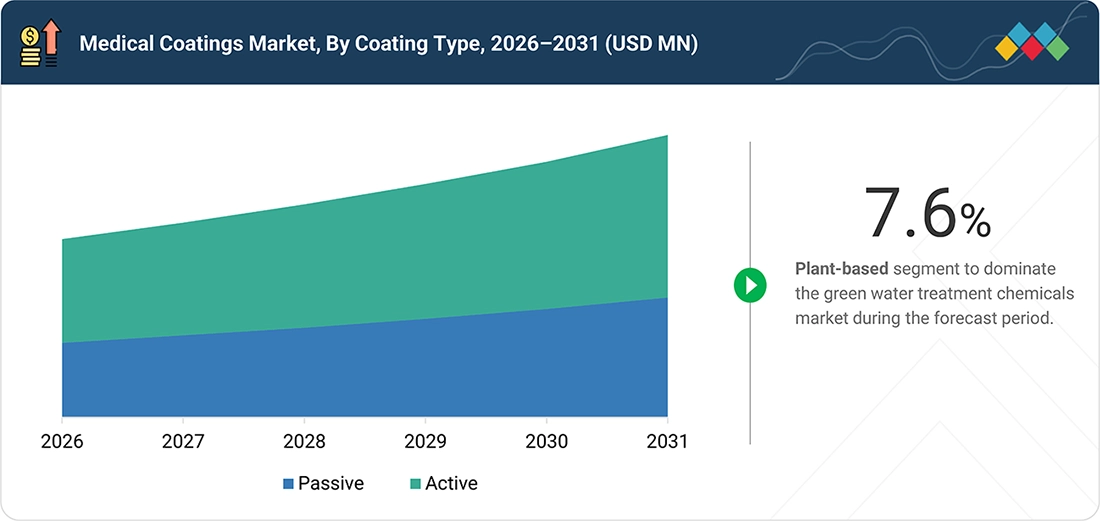
Medical Coating Market, by Type
The medical coatings market can be segmented on the basis of coating type into active and passive coatings, with passive coatings estimated to account for a higher market share. The dominant segment is witnessing considerable growth as passive coatings are widely used on medical devices including catheters, guidewires, stents, orthopedic implants, and surgical tools due to the benefits offered by these coatings in terms of reducing friction, increasing lubricity, biocompatibility, and offering wear and corrosion resistance. In addition, rising preference for minimally invasive surgery and high demand for high-end medical devices is contributing to the demand for passive coatings. Active coatings are being increasingly preferred due to the additional functionality that they offer in terms of being antimicrobial, offering drug delivery capability, and better biological interaction.
Medical Coating Market, by Materials
The medical coatings market can be divided, in terms of the materials used, into polymers, metals, and others, with polymers anticipated to be the leading segment. The segment is expected to witness substantial growth on account of the growing use of polymers and specialty polymers like polyurethane, polyethylene, silicone, etc., in medical coatings on account of their properties, including flexibility, biocompatibility, lubricity, chemical resistance, and durability. Rising use of polymer coatings in medical devices like catheters, guidewires, stents, implants, and many others is driving demand from this segment. The increasing popularity of metal-based coatings, on account of their superior mechanical strength and resistance to wear and corrosion, especially for use in orthopedic and implantable devices, is also propelling demand. Other materials including ceramics and composite materials are also witnessing increased usage for some special applications.
Medical Coating Market, by Substrate
The medical coatings market is segmented based on substrate as Metals, Ceramics, Polymers, Composites, and Glass, out of which Polymers are predicted to account for the maximum market share. The prominent segment has experienced substantial growth due to the usage of Polymer Substrates in medical devices like Catheters, Guidewires, Tubing, and other minimal invasive devices as they provide flexibility, lightweight properties, chemical resistance, and compatibility with different types of coating technologies. Also, the rising popularity of medical devices made from polymers and increasing demand for Hydrophilic, Antimicrobial, and Lubricious coatings are increasing the need for coatings on polymer substrates. Metal substrates have wide applications in orthopedic implants, stents, and surgical instruments because of their excellent strength and durability properties, while Ceramics and Composite substrates are becoming popular in specialized applications for their wear resistance, bioactive, and mechanical properties.
Medical Coating Market, by Application
The medical coating market, by application, is segmented into medical devices, medical implants, medical equipment and tools, protective clothing, and others, with medical devices being expected to constitute the largest market share. This is because the medical devices sector has been experiencing considerable growth due to the widespread use of medical coatings on medical devices like catheters, guidewires, stents, syringes, and minimally invasive medical devices, due to their ability to increase lubrication, reduce friction, and provide antimicrobial and corrosion resistance. In addition to the above reasons, there is a growing inclination toward minimally invasive procedures and advanced medical devices, as well as increasing concern about preventing infections, thus increasing the demand for medical coatings in this category. Medical implants are also gaining traction due to the increasing use of orthopedic, cardiovascular, and dental implants that need improved surface functionality, biocompatibility, and wear resistance.
REGION
Asia Pacific to be fastest-growing medical coating market during forecast period
Asia Pacific is projected to lead the medical coatings market over the forecast period. This can be attributed to the increased healthcare infrastructure, increased production of medical devices and the rise in the need for minimally invasive treatments in nations like China, India, Japan, and South Korea. The increase in chronic disease prevalence and expenditure on healthcare has been driving the demand for advanced medical devices and implants requiring surface coatings. Furthermore, there are opportunities due to the high patient base in the region, increased investments from foreign medical device manufacturers, as well as the expansion of the local healthcare and medical technologies sector. Awareness regarding infection control has also increased demand for antimicrobial surface coatings, while the increasing usage of catheters, guidewires, stents and orthopedic implants has led to increased demand for hydrophilic, lubricious and bioactive coatings.
MEDICAL COATING MARKET: COMPANY EVALUATION MATRIX
Hydromer (Star) is one of the leading companies in the industry of medical coatings. It offers a variety of hydrophilic, antimicrobial, lubricious, and specialized coatings available to cover medical devices, as well as the company's coating development and application capabilities. It provides coating services for catheters, guidewires, cardiovascular devices, urological devices, and other minimally invasive medical devices and assists manufacturers in improving lubricity, reducing friction, enhancing biocompatibility, and achieving better results with the use of medical devices. Applied Medical Coatings (Emerging) is an emerging company in the industry of medical coatings because of its advanced medical coating technologies, customized coating solutions, and surface treatment services for medical device manufacturers. This company is able to develop functional coatings that would improve the performance, longevity, lubricity, and biocompatibility of medical devices.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- 1. Hydromer (US)
- 2. DSM-Firmenich (Netherlands)
- 3. Surmodics, Inc (US)
- 4. Bicoat Incorporated (US)
- 5. AST Products Inc (US)
- 6. Covalon Technologies (Canada)
- 7. Freudenberg Medical (US)
- 8. Harland Medical Systems, Inc (US)
- 9. Merit Medical Systems (US)
- 10. The Sherwin-Williams Company (US)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2025 (Value) | USD 9.99 Billion |
| Market Forecast in 2026 (Value) | USD 10.92 Billion |
| Market Forecast in 2031 (value) | USD 17.42 Billion |
| Growth Rate | CAGR of 9.8% from 2026–2031 |
| Years Considered | 2022–2031 |
| Base Year | 2025 |
| Forecast Period | 2026–2031 |
| Units Considered | Value (USD Billion), Volume (Kiloton) |
| Report Coverage | Revenue Forecast, Company Ranking, Competitive Landscape, Growth Factors, and Trends |
| Segments Covered |
|
| Regions Covered | North America, Asia Pacific, Europe, South America, Middle East & Africa |
WHAT IS IN IT FOR YOU: MEDICAL COATING MARKET REPORT CONTENT GUIDE
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Demand for country-specific market insights | Analyzed the medical coatings market across key countries in North America, Europe, Asia Pacific, Middle East & Africa, and South America, covering regulatory landscape, healthcare infrastructure, medical device manufacturing, technology adoption, and market growth. Assessed demand for hydrophilic, antimicrobial, drug-eluting, anti-thrombogenic, lubricious, and other functional coatings across major countries. | Helps clients identify high-growth countries, understand country-specific demand drivers and regulatory requirements, assess market-entry opportunities, and develop localized expansion strategies. |
| Request for competitor benchmarking | Benchmarked Hydromer, DSM-Firmenich, Surmodics, Biocoat, AST Products, Applied Medical Coatings, and other market participants. Assessed product portfolios, coating technologies, application focus, geographic presence, manufacturing and coating capabilities, customer base, R&D activities, partnerships, product launches, and strategic developments. | Enables clients to evaluate competitive positioning, identify product and geographic gaps, assess competitive strengths, and formulate differentiated business and growth strategies. |
| Application- and industry-specific insights | Assessed demand across medical devices, medical implants, medical equipment & tools, protective clothing, and other applications. Analyzed coating requirements for catheters, guidewires, stents, orthopedic implants, cardiovascular devices, surgical instruments, and minimally invasive medical devices. | Supports identification of high-growth applications, facilitates product portfolio prioritization, and helps align business strategies with evolving medical device performance, safety, and patient-care requirements. |
| Technology and material assessment | Evaluated advancements in hydrophilic, antimicrobial, drug-eluting, anti-thrombogenic, lubricious, bioactive, and specialty coatings, along with developments in coating application and surface modification technologies. Assessed adoption of polymer, metal, ceramic, composite, and glass substrates, as well as emerging multifunctional and next-generation coating technologies. | Supports technology roadmaps, new product development, innovation planning, and identification of emerging opportunities for improving device lubricity, biocompatibility, durability, antimicrobial performance, and drug delivery. |
| Regulatory and sustainability assessment | Analyzed key medical device regulations, biocompatibility requirements, sterilization compatibility, chemical safety requirements, quality standards, and product approval requirements across major markets. Evaluated the impact of regulations and sustainability initiatives on coating materials, manufacturing processes, and medical device development. | Helps clients anticipate regulatory requirements, reduce compliance risks, support product certification and registration, and develop coating solutions aligned with evolving medical device safety, performance, and sustainability requirements. |
| Market opportunity and white-space analysis | Identified opportunities across hydrophilic and antimicrobial coatings, drug-eluting coatings, bioactive coatings, low-friction coatings, advanced implant coatings, and multifunctional surface technologies. Assessed white-space opportunities across high-growth applications, substrates, technologies, and geographic markets. | Enables clients to identify underserved market segments, prioritize investment areas, develop differentiated coating solutions, and capture emerging opportunities in the medical coatings market. |
RECENT DEVELOPMENTS
- February 2026 : Hydromer expanded into automated high-speed coating and UV-curing equipment, integrating proprietary coatings with machinery to provide end-to-end, compliant solutions for medical device manufacturers.
- October 2025 : Hydromer announced a strategic investment by jMedtech to build a global medical device coating platform integrating UV-curable and thermal-cure coatings, advanced equipment, and regionalized services across Asia and the Americas.
- January 2025 : Hydromer introduced PFAS-free hydrophilic coatings that offer high lubricity, durability, and biocompatibility while supporting medical device manufacturers in meeting tightening environmental regulations.
- June 2024 : Freudenberg medical is investing over USD 50 million in a new 130,000 sq. ft. facility in Germany to triple its coatings manufacturing capacity and meet growing demand for drug and hydrophilic medical coatings.
- October 2023 : Surmodics launched Preside, an advanced hydrophilic coating offering high lubricity, durability, low friction, and minimal particulates for complex neurovascular, coronary, and peripheral vascular devices.
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
Methodology
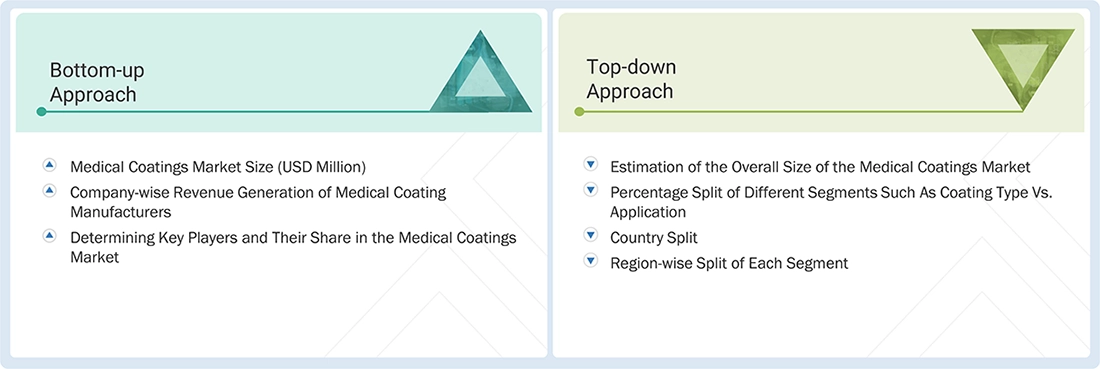
The study involves two major activities in estimating the current market size for the medical coatings market. Exhaustive secondary research was done to collect information on the market, peer market, and parent market. The next step was to validate these findings, assumptions, and sizing with industry experts across the value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the complete market size. After that, market breakdown and data triangulation were used to estimate the market size of segments and subsegments.
Secondary Research
Secondary sources referred to for this research study include financial statements of companies offering medical coating and information from various trade, business, and professional associations. Secondary research has been used to obtain critical information about the industry’s value chain, the total pool of key players, market classification, and segmentation according to industry trends to the bottom-most level and regional markets. The secondary data was collected and analyzed to arrive at the overall size of the medical coatings market, which was validated by primary respondents.
Primary Research
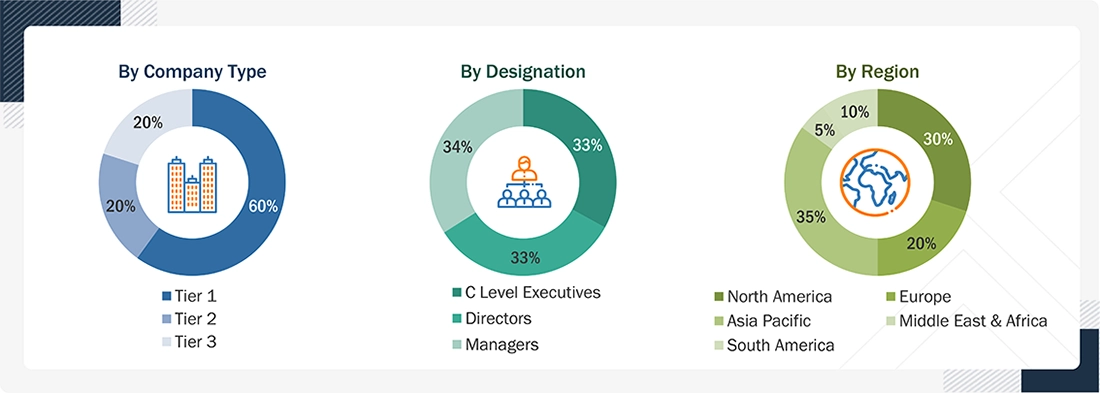
Extensive primary research was conducted after obtaining information regarding the medical coatings market scenario through secondary research. Several primary interviews were conducted with market experts from both the demand and supply sides across major countries of North America, Europe, Asia Pacific, Middle East & Africa, and South America. Primary data was collected through questionnaires, emails, and telephonic interviews. The primary sources from the supply side included various industry experts, such as chief executive officers (CXOs), vice presidents (VPs), directors from business development, marketing, product development/innovation teams, and related key executives from medical coatings industry vendors; material providers; distributors; and key opinion leaders. Primary interviews were conducted to gather insights into market statistics, revenue from products and services, market breakdowns, market size estimates, market forecasting, and data triangulation. Primary research also helped in understanding the various trends related to coating type, material type, substrate type, application, and region. Stakeholders from the demand side, such as CIOs, CTOs, CSOs, and installation teams of the customer/end users who are seeking medical coating, were interviewed to understand the buyer’s perspective on the suppliers, products, and their current usage of medical coatings and future outlook of their business, which will affect the overall market.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
The research methodology used to estimate the size of the medical coatings market includes the following details. The market sizing of the market was undertaken from the demand side. The market was upsized based on the demand for medical coatings in different end-use industries at a regional level. Such procurements provide information on the demand aspects of the medical coatings industry for each end-use industry. For each end-use, all possible segments of the medical coatings market were integrated and mapped.
Data Triangulation
After arriving at the overall size from the market size estimation process explained above, the total market was split into several segments and subsegments. The data triangulation and market breakdown procedures explained below were implemented, wherever applicable, to complete the overall market engineering process and arrive at the exact statistics for various market segments and subsegments. The data was triangulated by studying various factors and trends from the demand and supply sides. Along with this, the market size was validated using both the top-down and bottom-up approaches.
Market Definition
Market overview for the medical coatings market
Medical coatings are specialized layers or films applied to medical devices, instruments, and implants to reduce risks, improve performance, and enhance their longevity and durability. They are designed to provide benefits such as inhibiting the growth of microorganisms (e.g., antimicrobial), resisting corrosion, increasing lubricity, and improving biocompatibility. These features help devices function reliably within the body while meeting strict legal and regulatory standards. Medical coatings are essential for lowering infection risks and improving health outcomes.
Key Stakeholders
- Medical Coating Manufacturers
- Medical Coating Distributors and Suppliers
- End-use Industries
- Universities, Governments, and Research Organizations
- Associations and Industrial Bodies
- R&D Institutes
- Environmental Support Agencies
- Investment Banks and Private Equity Firms
- Research and Consulting Firms
Report Objectives
- To define, describe, and forecast the medical coatings market size in terms of volume and value
- To provide detailed information regarding the key factors, such as drivers, restraints, opportunities, and challenges influencing market growth
- To analyze and forecast the market by coating type, material type, substrate type, application, and region
- To forecast the market size concerning five main regions (along with country-level data), namely, North America, Europe, Asia Pacific, Middle East & Africa, and South America, and analyze the significant region-specific trends
- To strategically analyze micromarkets with respect to individual growth trends, prospects, and contributions of the submarkets to the overall market
- To analyze the market opportunities and the competitive landscape for stakeholders and market leaders
- To assess recent market developments and competitive strategies, such as agreements, contracts, acquisitions, partnerships & collaboration, and product developments/product launches, to draw the competitive landscape
- To strategically profile the key market players and comprehensively analyze their core competencies
Available customizations:
MarketsandMarkets offers the following customizations for this market report:
- Additional country-level analysis of the medical coatings market
Product Analysis
- Product matrix, which provides a detailed comparison of the product portfolio of each company’s market
Key Questions Addressed by the Report
What is the current size of the global medical coating market?
The medical coating market is projected to reach USD 15,813.6 million by 2030 from USD 9,983.0 million in 2025, at a CAGR of 9.6% during the forecast period.
Who are the key players in the global medical coating market?
Key players include Hydromer (US), DSM-Firmenich (Netherlands), Surmodics (US), Biocoat Incorporated (US), AST Products Inc (US), Covalon Technologies (Canada), Freudenberg Medical (US), Harland Medical Systems (US), Merit Medical Systems (US), Applied Medical Coatings (US), PPG Industries (US), and The Sherwin-Williams Company (US). These companies have strong potential to expand their product portfolios and compete in the global market.
What are some of the drivers for market growth?
Growth is driven by rising healthcare expenditure, increasing geriatric population, prevalence of chronic diseases, and growing demand for minimally invasive surgeries.
What are the different coating types used in medical coating?
Active and passive coatings are the most commonly used types in the medical coating market.
What are the major materials in the medical coating market?
The primary materials used are polymers and metals.


Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the Medical Coatings Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Custom Market Research Services
We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements
Get 10% Free CustomisationTESTIMONIALS
We at Nissan Chemicals Corporation have been clients of MarketsandMarkets for more than a year now. We recently consulted MarketsandMarkets for a study, the team at MarketsandMarkets was extremely professional and organized. The business insights were very detailed and aligned well with our expectations that really helped us formulate the Business Plans and device new strategies for development themes. MarketsandMarkets offers a unique combination of expertise and dedicated engagement model. Their research findings have helped us in designing our Pricing Strategy which will make it easier for us to predict the future sales and profits for the next ten years. We look forward to working with MarketsandMarkets in the future.
VP of Strategy & New Business Development
Leading Specialty Chemical Company
The MarketsandMarkets Engagement Model, composed of both the Knowledge Store and advisory custom research, has greatly helped us in understanding our markets and making strategic decisions. The Knowledge Store is a fast way to allow everyone in our organization to understand more about most any market they are interested in. The ability to then get custom research done and get answers to specific strategic questions and market insight has been spectacular. The Markets and Markets team feel more like colleagues than vendors and their services have helped us change our culture where statements of things like growth opportunities and competitive position are always backed by industry research.

Rich Gibson,
Director, Corporate Strategy
Milliken & Company,
Leading Industrial Manufacturer of specialty chemical, floor covering, performance and protective textile materials, and healthcaremilliken.com
MarketsandMarkets is a trusted resource that helps us to better understand markets that are near-adjacencies-whether its technology, value chain or geography. Their Knowledge Store platform provides a dashboard of markets and their characteristics which is easy to use and saves us time.
Adam Shaw,
Market Development and Strategy Manager
AdvanSix Inc. USA,
An American Leader in Chemicalswww.advansix.com
The Knowledge Store from MarketsandMarkets is a valuable tool which has helped my team acquire greater insight in to the end markets that our business serves. This has enabled us to help our company build stronger strategies throughout our planning process.
TOSHIO KINOSHITA
Senior Chif Consultion Research & Consulting Division
Mitsubishi Chemical Research Corporation,
Leading Manufacturer of Chemical Productswww.mitsubishichem-res.co.jp/en/

We recently engaged with MarketsandMarkets for a study, the team not only clearly understood our business objectives but was also extremely professional in the way they handled the entire project. The study was efficiently conducted in a phase-wise manner, and the engagement model furnished us with high-quality business insights that far exceeded our expectations at each phase. We were especially happy that MarketsandMarkets could provide us with both, an English as well as a Japanese version of the study. A special thanks to the Analyst Team and Client Services Team, whose fluency in Japanese enhanced our comfort level, as we could converse with them in our preferred language.
Independent entrepreneurs
Arrow Precision
We approached MarketsandMarkets for study on Proppants Market, and their work exceeded our expectations. The study conducted was comprehensive and enabled us to view the market through the various dimensions. In addition, the team was extraordinarily responsive throughout the process and resolved our queries on time. I strongly recommend MarketsandMarkets and will certainly consider them for additional market assessments we will need in the future.
Global engineering company, Japan
Deputy Manager,
Strategic Planning OfficeThe high-quality insights shared by the MarketsandMarkets team helped us understand the pharmaceutical plant designers in a specific geography. It also captured the risks that we may likely face in communicating with our potential partners. The study would enable us identify partners, which would impact our future growth.
- US Medical Coating Market
- Canada Medical Coating Market
- Mexico Medical Coating Market
- Germany Medical Coating Market
- UK Medical Coating Market
- France Medical Coating Market
- Italy Medical Coating Market
- Spain Medical Coating Market
- Russia Medical Coating Market
- China Medical Coating Market
- Japan Medical Coating Market
- India Medical Coating Market
- South Korea Medical Coating Market
- Australia Medical Coating Market
- South Africa Medical Coating Market
- Brazil Medical Coating Market
- Argentina Medical Coating Market
- Rest Of Europe Medical Coating Market
- Rest Of Asia Pacific Medical Coating Market
- GCC Countries Medical Coating Market
- –Other GCC Countries Medical Coating Market
- Rest Of South America Medical Coating Market






Growth opportunities and latent adjacency in Medical Coatings Market