Revenue Cycle Management (RCM) Market

Revenue Cycle Management (RCM) Market by Offering [Front (Prior Auth), Mid (CDI, Audit), Back-end (Claim, Submission, Denials), Outsourcing Service], Technology (AI-enabled RCM), End User [Inpatient (Hospital), Outpatient, Payer] - Global Forecast to 2031


REVENUE CYCLE MANAGEMENT MARKET SIZE, SHARE & GROWTH SNAPSHOT
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
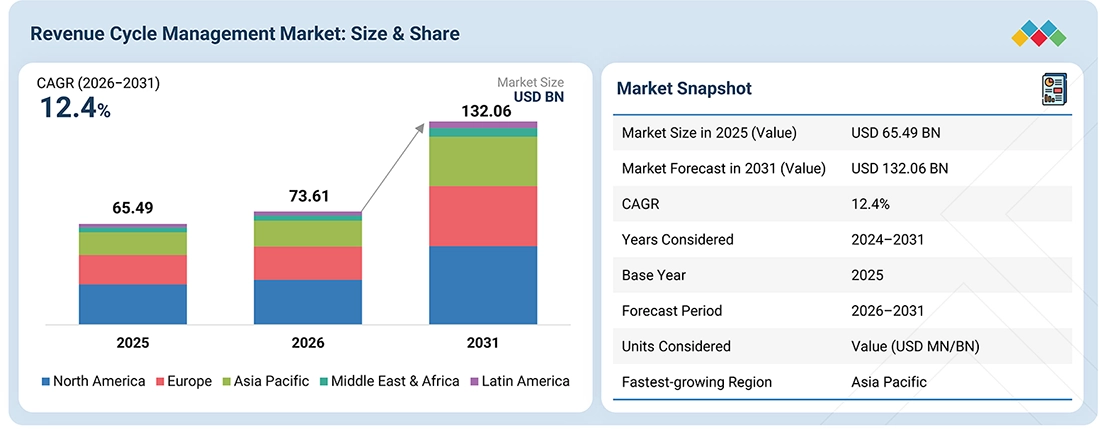
The global revenue cycle management market is projected to grow from USD 73.61 billion in 2026 to USD 132.06 billion by 2031, at a CAGR of 12.4% during the forecast period. The market was valued at USD 65.49 billion in 2025. According to the American Hospital Association's 2026 Cost of Caring Report, U.S. hospitals spent nearly USD 43 billion in 2025 pursuing payments owed by insurers. In 2026, CMS reported that 82.8% of Shared Savings ACOs now qualify as Advanced Alternative Payment Models, reinforcing value-based reimbursement's rise. According to Experian Health's State of Claims 2025 survey, 41% of providers said over 10% of claims were denied. In April 2026, Waystar reported that its AltitudeAI tools process 7.5 billion annual transactions across one in three U.S. hospital discharges, as providers increasingly turn to AI-enabled platforms and outsourced RCM partners to curb denials and stabilize collections.
KEY TAKEAWAYS
-
MARKET SNAPSHOT:
Base Year Market Size (2025): USD 65.49 Billion
Current Market Size (2026): USD 73.61 Billion
Forecast Market Size (2031): USD 132.06 Billion
CAGR (2026–2031): 12.4% -
SEGMENT LEADERSHIP:
Regional Leader: North America dominated the revenue cycle management market, with a share of 40.0% in 2025.
Solution Type: Integrated software segment is expected to witness the highest growth during the forecast period.
Offering Leader: Outsourcing services segment held the largest share in 2025.
Technology Maturity: AI-enabled RCM solutions segment is expected to grow at the fastest CAGR from 2026 to 2031.
Enterprise Size: Small & medium-sized enterprises segment is expected to register the fastest growth in the market, at a CAGR of 13.0%.
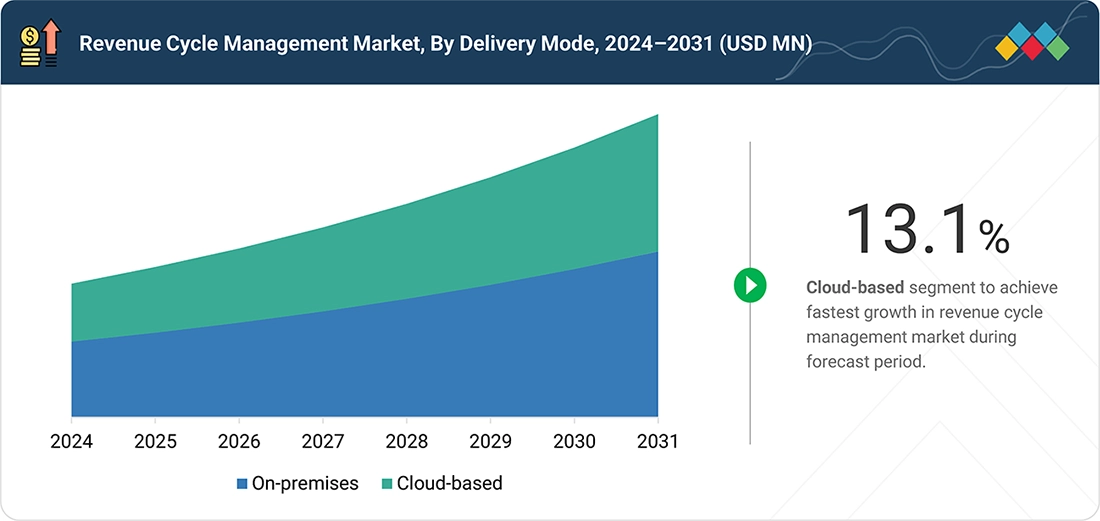
Delivery Mode Leader: On-premises segment holds the largest share of 56.4% in 2025.
End User Leader: Healthcare providers segment is expected to hold the largest share of the market. -
MARKET OUTLOOK & COMPETITIVE LANDSCAPE:
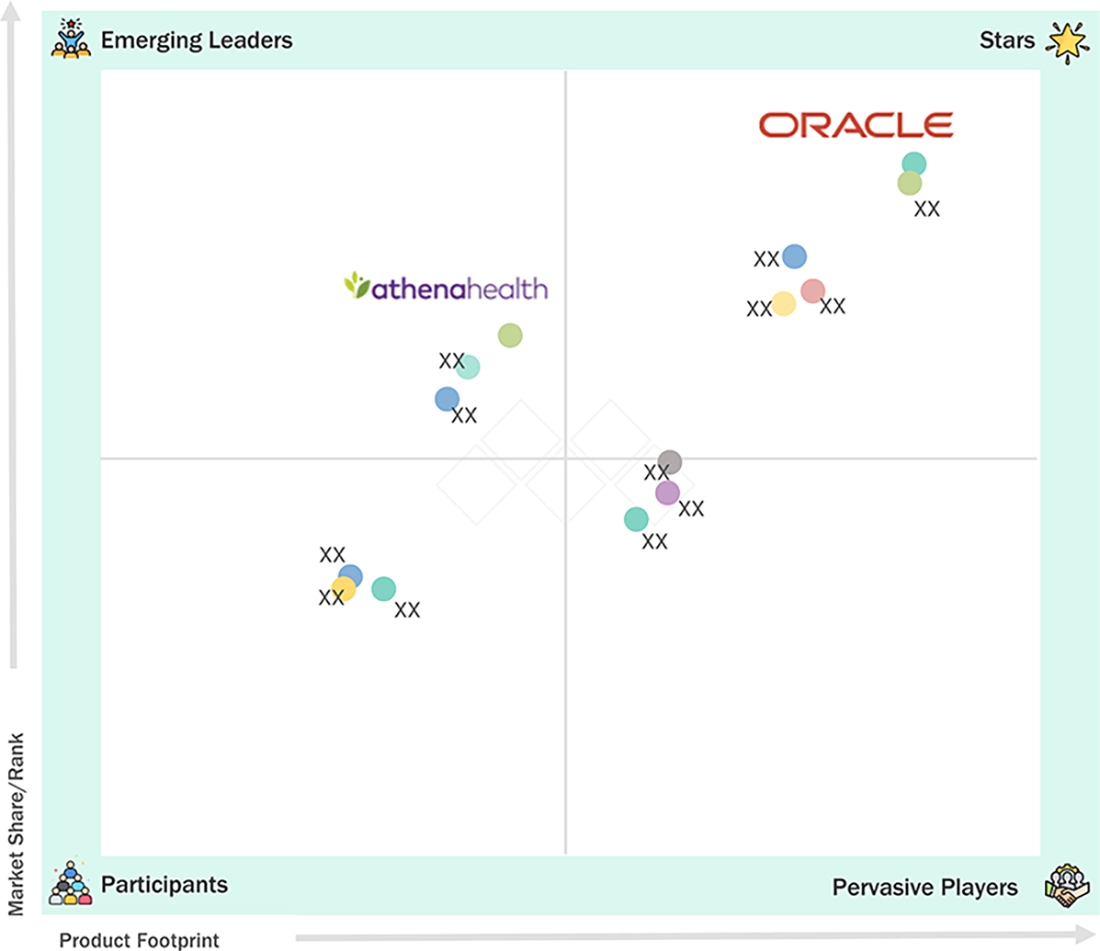
Oracle, Optum, Inc., Epic Systems Corporation, Cognizant, and Experian Information Solutions, Inc. were identified as Star players in the RCM market for their focus on innovation, broad industry coverage, and strong operational & financial strength.
Finthrive, Omega Healthcare Service, and Vee Healthtek, Inc. have distinguished themselves among startups and SMEs due to their strong product portfolios and business strategies.
The revenue cycle management market is experiencing consistent growth. In February 2026, HHS reported nearly 500 million health records exchanged via TEFCA, projecting USD 19.2 billion in administrative savings from deeper EHR-RCM integration. According to an April 2026 R1 RCM release, Providence expanded its outsourcing partnership to deploy Phare OS, whose predictive intelligence and denials-management agents strengthen cash flow and financial visibility.
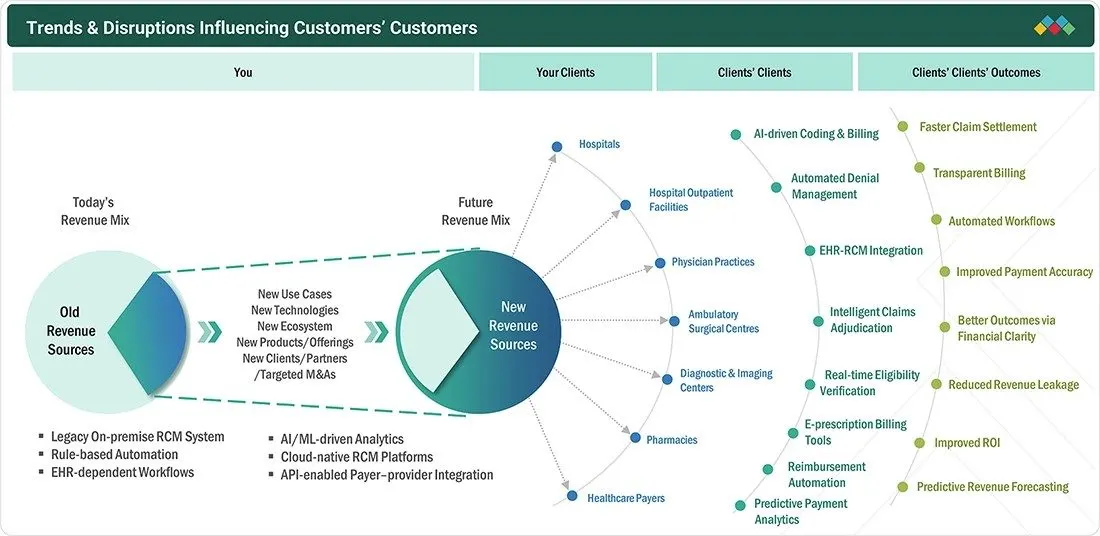
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
The revenue cycle management market is being disrupted by AI-native claims and adjudication platforms that are displacing legacy, batch-based billing systems. Real-time data exchange across payers, providers, and pharmacies is replacing siloed, delayed reimbursement workflows, while tightening billing-transparency requirements are pushing providers to disclose actual charges rather than estimates. Together, these forces are accelerating a structural shift toward transparent, forecasting-driven, digitally optimized revenue ecosystems.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Level
-
Growing regulatory requirements and government initiatives

-
Increasing patient volume and subsequent growth in health insurance


Level
-
High deployment costs

-
IT infrastructural constraints in emerging economies


Level
-
Increasing outsourcing services in emerging economies

-
Growing demand for AI and cloud-based deployment


Level
-
Issues related to data security and confidentiality

-
Reluctance to switch from conventional methods

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Growing regulatory requirements and government initiatives.
In the US, the Patient Protection and Affordable Care Act (PPACA) has led to the restructuring of private insurance, Medicare, and Medicaid systems. In line with these changes, the “Meaningful Use” rules of the American Recovery and Reinvestment Act (ARRA) and the Health Information Technology for Economic and Clinical Health Act (HITECH) have mandated the adoption of electronic medical/health records (EMR/EHR) that will increase data interoperability. This will ease data exchange between healthcare organizations, providers, and payers. This, in turn, would drive adoption of patient access solutions such as eligibility verification and medical necessity management. Under the Hospital Value-Based Purchasing (HVBP) Program, Medicare rewards hospitals with payments based on either how well they perform on certain quality measures or how much they improve their performance on those measures. Such programs motivate healthcare providers to perform their core and financial functions effectively, thereby increasing the adoption of RCM solutions.
Restraint: High deployment costs
High deployment costs present a significant restraint in the revenue cycle management market, particularly for small and medium-sized healthcare facilities with limited budgets. Implementing comprehensive RCM solutions requires substantial upfront investment in software licenses, infrastructure upgrades, hardware, and integration with existing systems. Additional expenses include staff training, data migration, system customization, and ongoing maintenance fees. These financial barriers often deter smaller practices from adopting advanced RCM technologies, forcing them to rely on manual processes or outdated systems. The lengthy implementation timeline and uncertainty about return on investment further discourage healthcare providers from investing in sophisticated RCM platforms, thereby limiting market penetration.
Opportunity: Increasing outsourcing services in emerging economies
The increasing adoption of RCM outsourcing services in emerging economies presents substantial growth opportunities for the market. Countries like India, the Philippines, and Latin American nations offer cost-effective solutions with skilled healthcare billing professionals at competitive rates. Healthcare providers in developed markets are leveraging these services to reduce operational expenses while maintaining quality. Emerging economies benefit from improved telecommunications infrastructure, favorable government policies, and large English-speaking workforces. This trend enables healthcare organizations to focus on core clinical activities while outsourcing complex billing and coding functions. Additionally, time zone advantages facilitate round-the-clock operations, accelerating claim processing and revenue collection, making outsourcing an attractive strategic option for maximizing efficiency and profitability.
Challenge: Issues related to data security and confidentiality
Data security and confidentiality concerns pose critical challenges for the revenue cycle management market, as RCM systems handle sensitive patient information, including medical records, insurance details, and financial data. Cyberattacks, ransomware, and unauthorized access threaten data integrity and patient privacy, potentially resulting in regulatory penalties, legal liabilities, and reputational damage. Notable breaches like the Change Healthcare cyberattack in February 2024, which disrupted healthcare operations nationwide, and R1 RCM's data security incidents highlight vulnerabilities in RCM infrastructure. These breaches exposed protected health information, causing significant financial losses and eroding trust among healthcare providers. Compliance with stringent regulations like HIPAA and GDPR requires substantial investment in cybersecurity measures, creating additional operational burdens and costs for RCM vendors and healthcare organizations alike.
REVENUE CYCLE MANAGEMENT (RCM) MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
AI-enabled RCM platform integrating coding automation, predictive denial prevention, and payer analytics for hospitals and physician groups. | Improves cash flow visibility, reduces claim denials, and enhances revenue recovery through real-time analytics. |
 |
Cloud-based RCM suite embedded with ERP and EHR data for unified billing, reimbursement, and contract management across health systems. | Enables financial transparency, streamlines charge capture, and supports scalability for multi-facility networks. |
 |
Data-driven RCM solutions supporting pharmacy and specialty care networks with automated claims adjudication and reimbursement tracking. | Enhances payer connectivity, reduces processing delays, and optimizes reimbursement for high-cost therapies. |
 |
Integrated RCM module within Epic EHR enabling real-time charge capture, patient cost estimation, and automated denial workflows. | Strengthens revenue integrity, enhances patient billing transparency, and reduces administrative overhead. |
 |
Workflow-automation tools and AI-driven compliance modules supporting payer-provider coordination and audit readiness in RCM processes. | Increases accuracy of financial reporting, improves compliance outcomes, and accelerates reimbursement cycles. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
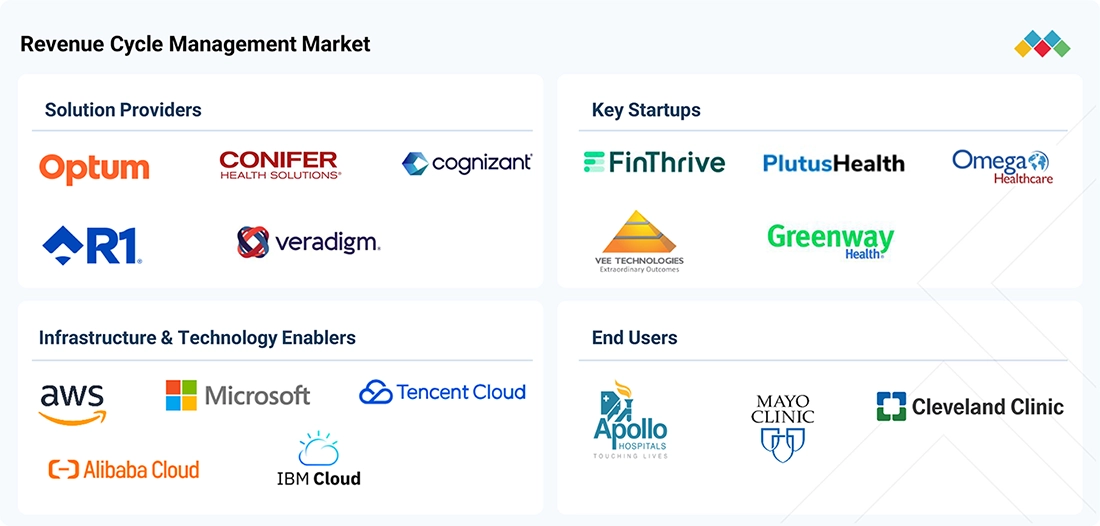
The revenue cycle management (RCM) ecosystem spans providers, payers, pharmacies, clearinghouses, and technology vendors operating on shared data rails. Clearinghouses such as Availity connect providers with payers for eligibility checks and claims routing, while pharmacy benefit administrators like CVS Caremark manage prescription claims within the same network. Payers rely on analytics vendors such as Cotiviti to safeguard payment integrity by detecting fraud, waste, and abuse. Evolving interoperability regulations are pushing AI/ML vendors toward compliant, API-driven infrastructure that links all stakeholders in the ecosystem.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
REVENUE CYCLE MANAGEMENT MARKET, BY TECHNOLOGY MATURITY
By technology maturity, the AI RCM solutions segment is expected to grow at the fastest CAGR from 2026 to 2031, as autonomous coding platforms move from pilots to enterprise-wide deployment. According to Fathom, whose autonomous coding platform recently secured strategic investment from CVS Health Ventures, its system now achieves automation rates exceeding 90% across multiple specialties. CodaMetrix, spun out of Mass General Brigham, has scaled its AI coding platform across more than 200 hospitals and 50,000 providers. A 2025 Bain & Company and KLAS report found that revenue cycle management has become the top priority for health IT investment, signaling accelerating enterprise adoption of AI-native coding, denial prevention, and reimbursement platforms.
REVENUE CYCLE MANAGEMENT MARKET, BY ENTERPRISE SIZE
By enterprise size, large health systems held the largest RCM market share in 2025, backed by scale that smaller providers cannot match. According to its FY2025 annual report, HCA Healthcare directed roughly USD 5.0 billion in capital expenditure toward hospital capacity, clinical technology, and a new electronic medical record platform, alongside expanded AI investment. Similarly, CommonSpirit Health reported deploying more than 200 AI tools across its ministry under a dedicated governance framework in fiscal 2025. Such enterprises operate dedicated IT teams and negotiate favorable multi-year vendor contracts, allowing them to absorb the cost and complexity of sophisticated RCM platforms that smaller hospitals and physician groups continue to approach cautiously, gradually increasing adoption as pricing models mature and cloud-based entry points lower barriers, supporting incremental growth beyond the largest systems.
REVENUE CYCLE MANAGEMENT MARKET, BY SOLUTION TYPE
By solution type, integrated RCM platforms held the largest share as health systems retreat from fragmented, best-of-breed billing tools. According to FinThrive's 2026 Transformative Trends Report, more than 70% of provider organizations expect to reduce reliance on third-party revenue cycle vendors, and nearly 60% plan to consolidate RCM vendors within three years, citing cybersecurity and clearinghouse disruptions as key drivers. By unifying eligibility verification, coding, claims submission, and payment posting on a single platform, providers eliminate data silos and vendor-management overhead, gaining the real-time financial visibility that disconnected, standalone systems have historically failed to deliver consistently.
REVENUE CYCLE MANAGEMENT MARKET, BY OFFERING
By offering, outsourcing captured substantial RCM market share as staffing shortages outpace what in-house billing teams can manage. According to Prolink's 2026 workforce research, two out of three health systems reported unfilled revenue cycle positions, pushing providers toward specialized vendors. A study by Access Healthcare found that agents typically spend less than 4 hours on productive tasks during an 8-hour shift, underscoring the efficiency gap that outsourcing partners aim to close. GeBBS Healthcare Solutions similarly reports that federally qualified health centers increasingly outsource billing to manage denials and vacant coding roles, as third-party vendors combine trained staff with technology to stabilize collections that internal teams alone cannot sustain reliably.
REVENUE CYCLE MANAGEMENT MARKET, BY DELIVERY MODE
By delivery mode, cloud-based RCM solutions are expected to register the fastest growth from 2026 to 2031, as health systems retreat from on-premises infrastructure that cannot scale with rising claim volumes. According to Oracle Health, its cloud-native RevElate patient accounting platform automates routine data movement from clinical documentation to billing, letting staff focus on exceptions rather than manual entry. CareCloud reported 40,000-plus providers on its cloud platform in Q1 2026, reflecting steady migration among smaller and mid-sized practices. Cloud deployment eliminates hardware refresh cycles and lets vendors push updates centrally, appealing to organizations that lack the dedicated infrastructure teams large hospitals maintain for on-premises systems.
REVENUE CYCLE MANAGEMENT MARKET, BY END USER
By end user, healthcare providers represented the largest end-user segment in the RCM market, encompassing hospitals, physician practices, ambulatory care centers, and specialty clinics that directly deliver patient care services. These organizations face mounting pressure to optimize revenue collection amid declining reimbursements, increasing patient financial responsibility, and complex payer requirements. Healthcare providers invest heavily in RCM solutions to streamline administrative workflows, reduce claim denials, accelerate payment cycles, and improve cash flow management. They require comprehensive systems addressing patient scheduling, insurance verification, charge capture, coding accuracy, claims submission, and accounts receivable management. Rising operational costs and staffing challenges make efficient revenue cycle operations critical for financial sustainability.
REGION
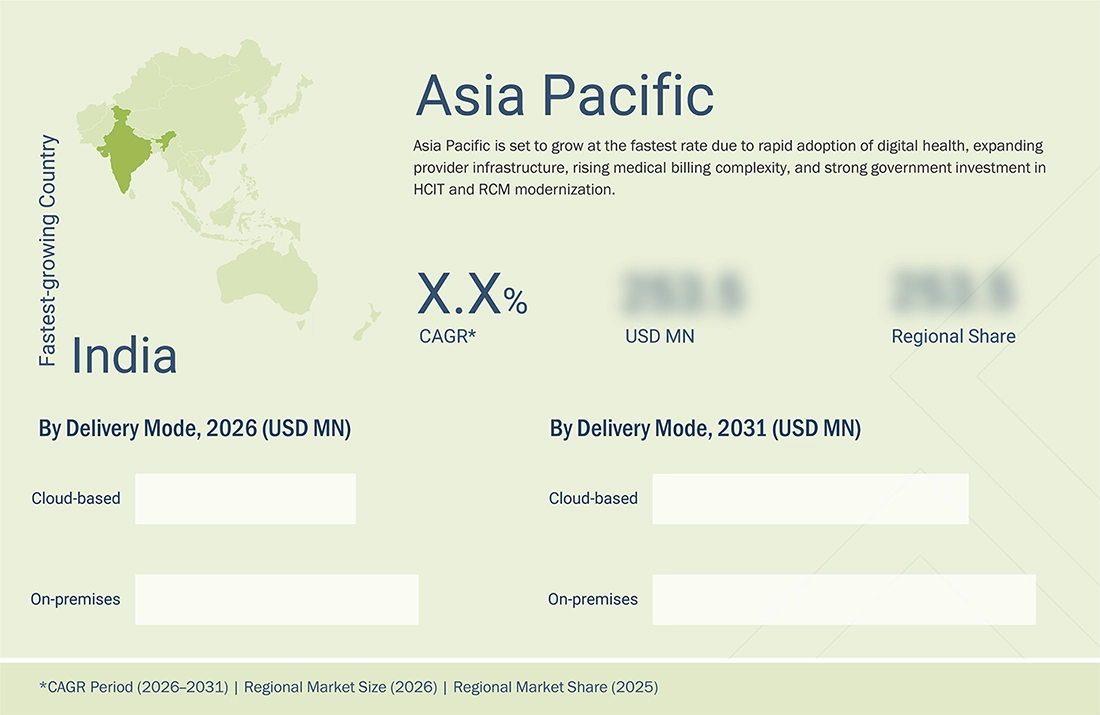
Asia Pacific to be fastest-growing region in global revenue cycle management market during forecast period
Asia Pacific emerged as the fastest-growing market for RCM solutions, driven by rapidly expanding healthcare infrastructure and rising healthcare expenditures across emerging economies. In India, the government's Ayushman Bharat Digital Mission has issued over 90 crore digital health IDs and built the National Health Claims Exchange, a dedicated platform for standardizing insurance claims processing nationwide. Australia's government committed AUD 745.1 million over four years, starting in 2026–27, to expand My Health Record and national digital health infrastructure, according to its federal budget. Meanwhile, the Philippines' healthcare BPO segment is growing at the fastest CAGR, per IBPAP data, as global providers outsource billing, coding, and claims operations to its 200,000-plus certified clinical professionals, reinforcing the region's dual role as both an adopter and a delivery hub for revenue cycle management.
REVENUE CYCLE MANAGEMENT (RCM) MARKET: COMPANY EVALUATION MATRIX
In the revenue cycle management (RCM) market matrix, Oracle Health (Star) leads with a strong, cloud-based RCM portfolio seamlessly integrated within its ERP and EHR ecosystem. Leveraging Oracle Cloud Infrastructure and advanced analytics, the company enables unified financial workflows, predictive revenue forecasting, and compliance-driven automation for large health systems. Its deep interoperability across clinical and financial data positions it as a preferred enterprise-grade solution for digital transformation and value-based care alignment. athenahealth (Emerging Leader) is rapidly expanding its footprint with its cloud-native, AI-powered RCM platform designed for ambulatory and mid-sized provider networks. Offering intelligent claims processing, automated patient billing, and real-time denial management, athenahealth delivers scalable, modular solutions that improve revenue capture, reduce administrative overhead, and enhance cash flow visibility, solidifying its role as a key growth contender in the next generation of healthcare financial management.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- Optum, Inc. (US)
- Oracle (US)
- McKesson Corporation (US)
- Solventum (US)
- Epic Systems Corporation (US)
- R1 RCM Inc. (US)
- Experian Information Solutions, Inc. (Ireland)
- Conifer Health Solutions. (US)
- Veradigm LLC (US)
- eClinicalWorks (US)
- Cognizant (US)
- athenahealth, Inc. (US)
- The SSI Group, LLC (US)
- Huron Consulting Group Inc. (US)
- GeBBS (US)
- Medical Information Technology, Inc. (US)
- IKS Health (India)
- CareCloud, Inc. (US)
- MEDHOST (US)
- Greenway Health, LLC (US)
- FinThrive (US)
- Plutus Health (US)
- Omega Healthcare Management Services (India)
- Vee Healthtek, Inc. (US)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2025 (Value) | USD 65.49 Billion |
| Market Forecast in 2026 (Value) | USD 73.61 Billion |
| Market Forecast in 2031 (Value) | USD 132.06 Billion |
| CAGR | Growth rate of 12.4% from 2026–2031 |
| Years Considered | 2024–2031 |
| Base Year | 2025 |
| Forecast Period | 2026–2031 |
| Units Considered | Value (USD Million/Billion) |
| Report Coverage | Revenue Forecast, Company Ranking, Competitive Landscape, Growth Factors, Trends |
| Segments Covered |
|
| Regions Covered | North America, Asia Pacific, Europe, Latin America, Middle East & Africa |
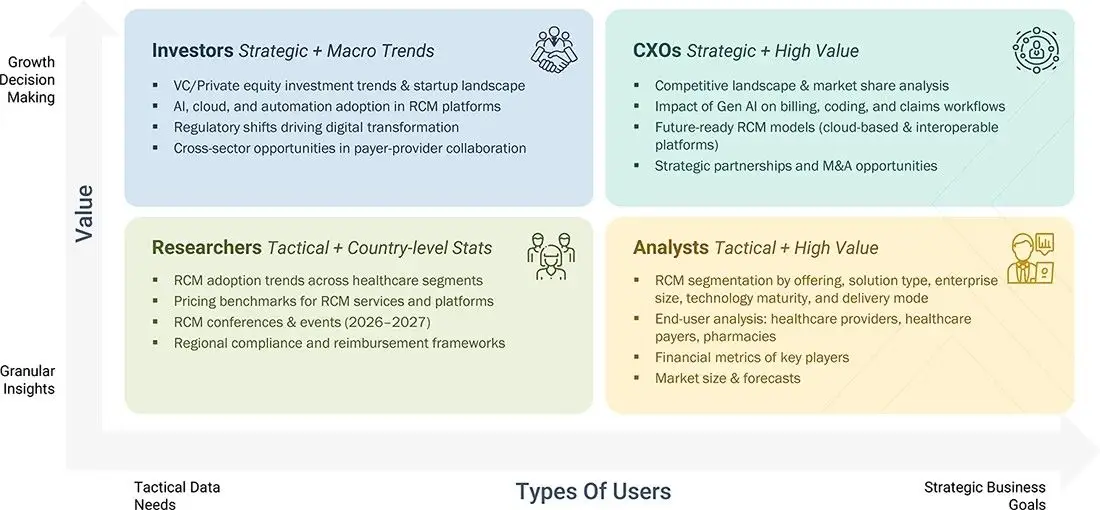
WHAT IS IN IT FOR YOU: REVENUE CYCLE MANAGEMENT (RCM) MARKET REPORT CONTENT GUIDE
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| U.S. RCM Outsourcing Services Provider |
|
|
RECENT DEVELOPMENTS
- July 2026 : Experity (US) acquired Exdion Healthcare, an AI-driven SaaS and services company specializing in the chart-to-cash lifecycle, including coding, billing, compliance, and RCM automation. According to Experity, the acquisition is intended to accelerate reimbursement, reduce manual work, minimize claim errors and denials, and improve payment velocity for urgent-care operators.
- April 2026 : Waystar (US) introduced an AI-powered solution for “silent denials”, targeting revenue losses arising from post-payment payer recoupments. According to Waystar, the solution uses its AltitudeAI platform and proprietary payment data to identify and help recover provider payments that have been reversed after initial reimbursement.
- March 2025 : R1 RCM Inc. (US) and Palantir Technologies launched R37, an AI lab aimed at transforming healthcare financial operations. By integrating R1's revenue cycle expertise with Palantir's advanced AI tools, R37 seeks to automate processes like coding, billing, and denials management to enhance efficiency and cash flow for healthcare providers
- February 2025 : Experian Information Solutions, Inc. (Ireland) and ValidMind (US) partnered to enhance model risk management for financial institutions. By integrating ValidMind's automated model governance tools with Experian's Ascend Platform, the collaboration aims to streamline regulatory compliance and operational risk management processes
- January 2024 : Materion Beryllium & Composites (a subsidiary of Materion Corporation) partnered with Liquidmetal Technologies Inc. and other Certified Liquidmetal Partners to use their alloy production technologies to provide high-quality products and support services to their customers.
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
Methodology
The study involved several key activities to estimate the current size of the revenue cycle management market. Extensive secondary research was conducted to gather information on this market. The next step was to validate the findings, assumptions, and size estimates by consulting industry experts throughout the value chain through primary research. We employed various methods, including top-down and bottom-up approaches, to estimate the overall market size. Following this, we used market segmentation and data triangulation to determine the sizes of specific segments and subsegments within the revenue cycle management market.
Secondary Research
This research study involved the extensive use of secondary sources, directories, and databases such as Dun & Bradstreet, Bloomberg Business, and Factiva; white papers, annual reports, and Companies House documents; investor presentations; and companies' SEC filings. The market for companies providing revenue cycle management solutions is assessed using secondary data from both paid and free sources. This involves analyzing the product portfolios of major industry players and evaluating these companies based on their performance and quality. Various resources were utilized in the secondary research process to gather information for this study. The sources include annual reports, press releases, investor presentations, white papers, academic journals, certified publications, articles by recognized authors, directories, and databases.
Secondary research was used to identify and collect information useful for the extensive, technical, market-oriented, and commercial study of the revenue cycle management market. It was also used to obtain important information about key players, market classification and segmentation according to industry trends down to the bottom level, and key developments from market and technology perspectives. A database of the key industry leaders was also prepared using secondary research.
Primary Research
In the primary research process, various primary sources from both the supply and demand sides were interviewed to obtain qualitative and quantitative information for this report. Primary sources are mainly industry experts from the core and related industries, as well as preferred suppliers, manufacturers, distributors, technology developers, researchers, and organizations across all segments of this industry’s value chain. In-depth interviews were conducted with various primary respondents, including key industry participants, subject-matter experts (SMEs), C-level executives of key market players, and industry consultants, among other experts, to obtain and verify critical qualitative and quantitative information and to assess prospects. Primary research was conducted to identify segmentation types, industry trends, key players, and key market dynamics, including drivers, restraints, opportunities, challenges, and strategies adopted by key players.
After completing the market engineering process, which included market statistics calculations, market breakdowns, size estimates, forecasting, and data triangulation, extensive primary research was conducted. This research aimed to gather information and verify the critical numbers obtained during the market analysis. Additionally, primary research was conducted to identify different types of market segmentation, analyze industry trends, evaluate the competitive landscape of revenue cycle management among various players, and understand key market dynamics, including drivers, restraints, opportunities, challenges, and strategies employed by key market participants.
In the complete market engineering process, top-down and bottom-up approaches, along with several data triangulation methods, were extensively used to estimate and forecast across the market segments and subsegments listed in this report. Extensive qualitative and quantitative analyses were conducted on the complete market engineering process to identify key information/insights throughout the report.
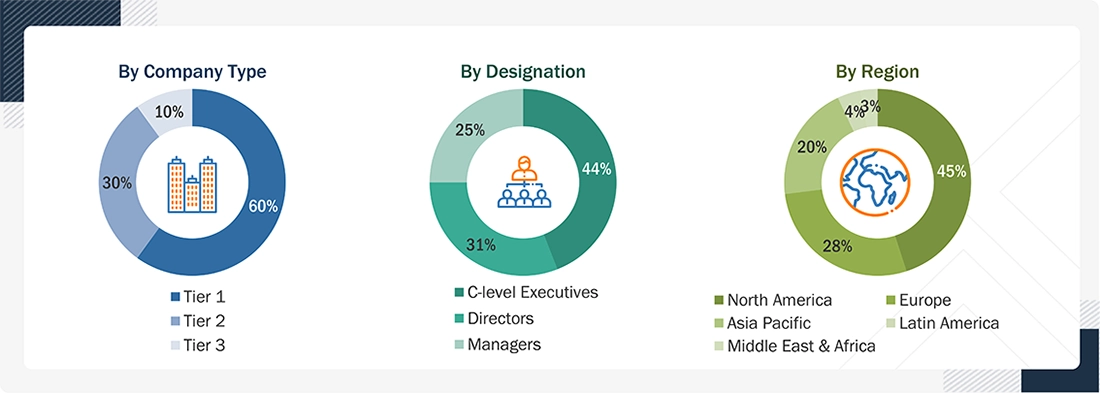
Note: Tiers are defined based on a company’s total revenue. As of 2025: Tier 1 = > USD 1 billion, Tier 2 = USD 500 million to USD 1 billion, and Tier 3 = < USD 500 million.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
The market size estimates and forecasts provided in this study are derived from a mix of the bottom-up approach (assessing adoption and average spending on RCM solutions by end users) and the top-down approach (revenue share analysis of leading players).
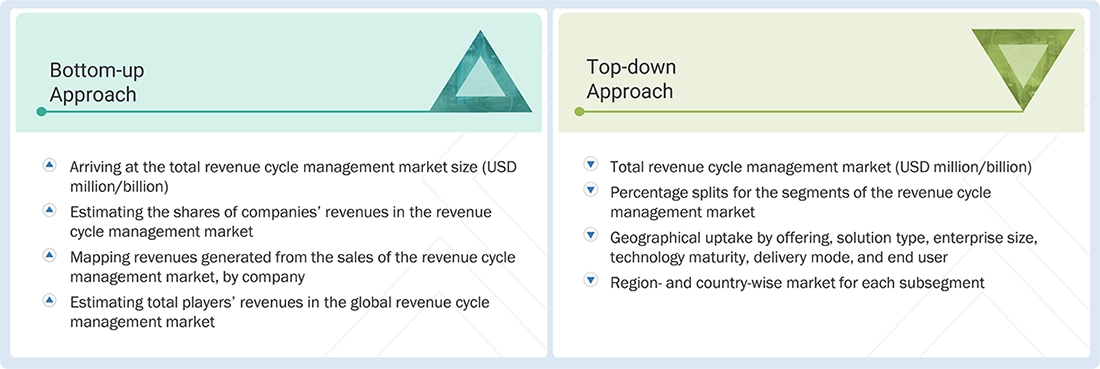
Data Triangulation
After arriving at the overall market size using the market size estimation processes, the market was split into several segments and subsegments. To complete the overall market engineering process and obtain the exact statistics for each market segment and subsegment, data triangulation and market breakdown procedures were employed wherever applicable. The data was triangulated by examining various factors and trends on both the demand and supply sides of the revenue cycle management market.
Market Definition
The revenue cycle management (RCM) market encompasses the technologies, platforms, and services that enable healthcare organizations to manage the financial lifecycle of patient care, from appointment scheduling and registration to claims submission, payment processing, and revenue reconciliation. RCM integrates clinical, administrative, and financial data to ensure accurate billing, regulatory compliance, and optimized reimbursement. The market includes software solutions for front-, mid-, and back-end processes, as well as outsourced services to reduce denials, enhance cash flow, and improve overall financial performance for healthcare providers and payers.
Key Stakeholders
- Healthcare Providers
- Healthcare Payers
- RCM Solution Vendors
- RCM Service Providers
- Healthcare IT Integrators & Consultants
- Regulatory Bodies & Government Agencies
- Investors & Venture Capital Firms
- Health Systems & Hospital Networks
- Medical Billing Companies
- EHR/EMR Vendors
- Cloud Service Providers
- Data Analytics & AI Technology Firms
- Clearinghouses
- Healthcare BPO Companies
- Compliance & Audit Firms
- Pharmaceutical & Life Sciences Companies
- Health Information Exchanges (HIEs)
- Academic & Research Institutions
- Professional Associations & Industry Bodies
- Patient Engagement Platform Providers
Report Objectives
- To define, describe, and forecast the global revenue cycle management market based on solution type, offering, technology maturity, enterprise size, delivery mode, end user, and region
- To provide detailed information regarding the factors influencing the growth of the market (such as the drivers, restraints, opportunities, and challenges)
- To strategically analyze micromarkets with respect to individual growth trends, prospects, and contributions to the overall revenue cycle management market
- To analyze market opportunities for stakeholders and provide details of the competitive landscape for market leaders
- To forecast the size of the revenue cycle management market in five main regions (along with their respective key countries): North America, Europe, the Asia Pacific, Latin America, and the Middle East & Africa
- To profile key players and comprehensively analyze their product portfolios, market positions, and core competencies in the market
- To track and analyze competitive developments such as product & service launches; expansions; partnerships, agreements, and collaborations; and acquisitions in the revenue cycle management market
- To benchmark players within the revenue cycle management market using the Company Evaluation Matrix framework, which analyzes market players on various parameters within the broad categories of business strategy, market share, and product offering
Available customizations:
With the given market data, MarketsandMarkets offers customizations as per your company’s specific needs. The following customization options are available for the report:
Company Information
- Detailed analysis and profiling of additional market players (up to 5)
Geographic Analysis
- Further breakdown of the Rest of Europe revenue cycle management market into Denmark, Norway, and others
- Further breakdown of the Rest of Asia Pacific revenue cycle management market into Vietnam, Pakistan, New Zealand, and others
- Further breakdown of the Rest of Latin America revenue cycle management market into Argentina, Chile, Colombia, and others
- Further breakdown of the Rest of Middle East & Africa revenue cycle management market into Egypt, Nigeria, Israel, and others
Frequently Asked Questions (FAQ)
Who are the leading industry players in the revenue cycle management market?
The prominent players include Optum, Inc. (US), R1 RCM Inc. (US), Oracle (US), Medical Information Technology, Inc. (US), McKesson Corporation (US), Solventum (US), Experian Information Solutions, Inc. (Ireland), Conifer Health Solutions (US), Veradigm LLC (US), eClinicalWorks (US), Cognizant (US), athenahealth, Inc. (US), The SSI Group, LLC (US), Huron Consulting Group Inc. (US), AdvancedMD, Inc. (US), GeBBS (US), Epic Systems Corporation (US), TruBridge (US), CareCloud, Inc. (US), MEDHOST (US), AdvantEdge Healthcare Solutions (US), FinThrive (US), Plutus Health (US), Omega Healthcare Management Services (India), and Vee Healthtek, Inc. (US).
What offerings have been included in the revenue cycle management market report?
Products and Outsourcing Services.
Which geographical region dominates the revenue cycle management market?
The market is segmented into North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. North America held the largest market share in 2024, while Asia Pacific is expected to witness the highest growth during the forecast period.
Which end-user segments have been included in the revenue cycle management market report?
Healthcare Providers and Healthcare Payers.
What is the total CAGR expected to be recorded for the revenue cycle management market during 2025–2030?
The market is expected to grow at a CAGR of 11.5% during the forecast period (2025−2030).


Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the Revenue Cycle Management (RCM) Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Custom Market Research Services
We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements
Get 10% Free CustomisationTESTIMONIALS
JAYANT RAJPUROHIT
Director of Market Insights, Data and Analytics
SFI Health,
Leading Pharmaceutical Companywww.sfihealth.com/
We at SFI Health approached MarketsandMarkets for an Opportunity Assessment on "Incidence and Prevalence of Focus Indications" as we wanted to know the most attractive HCPs like Physician, Functional MD, Naturopath and Pharmacist. The project was critical for us to ensure our focus on the right target which would enable sustainable growth and profitability for SFI Health. The business insights provided exceeded our expectations and we were extremely impressed. The team at MarketsandMarkets is highly professional and detail oriented and very well understood our business needs. MarketsandMarkets offers a unique combination of expertise and dedicated engagement model. We identified 2 new products to be launched in coming months, based on the research findings provided by MarketsandMarkets. We are happy with the services and would strongly recommend MarketsandMarkets to my peers in the industry.
BEATRIZ DE LA CALLE
Head of Commercial Analytics
Qualicaps,
Leading Pharmaceutical Companywww.qualicaps.com/
We partnered with MarketsandMarkets for an assessment study on hard empty capsules. The team was extremely professional in understanding our business requirements and we received timely responses to all our queries. The market intelligence and the recommendations has met our business requirements. We were extremely impressed to see the final study results; it really exceeded our expectations. The market intelligence offered by MarketsandMarkets, and clarity on next steps will help us achieve our business objective for the Year 2021. We are happy with the services and would strongly recommend MarketsandMarkets to my peers in the industry.

Bob Williams,
Senior Director Business Development & Innovation
Bracco Diagnostics Inc.,
Italian Multinational in life sciences sector and a World Leader in imaging diagnosticsimaging.bracco.com/us-en
We were pleased with targeted insights that MarketsandMarkets identified from a custom study on the 'Radiation Dose Management Solutions Market'. Your team identified and characterized the market participants as well as underlying trends accurately. This study was useful to Bracco in formulating business strategies for our dose monitoring product lines and we thank MarketsandMarkets for the job well done.
Cody Coonradt,
Market Development and Strategy Manager
3M Health Information Systems,
Leader in Health care Coding, Payment & Analytics Solutions.www.3m.com/3M/en_US/health-information-systems-us
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarketsandMarkets, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer.
Their customer first approach and high value engagement model, have given us great analysis and excellent value for money
- Rest Of Europe Revenue Cycle Management (RCM) Market
- Rest Of Asia Pacific Revenue Cycle Management (RCM) Market
- Rest Of Latin America Revenue Cycle Management (RCM) Market
- Canada Revenue Cycle Management (RCM) Market
- US Revenue Cycle Management (RCM) Market
- Germany Revenue Cycle Management (RCM) Market
- France Revenue Cycle Management (RCM) Market
- UK Revenue Cycle Management (RCM) Market
- Italy Revenue Cycle Management (RCM) Market
- Spain Revenue Cycle Management (RCM) Market
- Japan Revenue Cycle Management (RCM) Market
- China Revenue Cycle Management (RCM) Market
- India Revenue Cycle Management (RCM) Market
- Brazil Revenue Cycle Management (RCM) Market
- Mexico Revenue Cycle Management (RCM) Market
Growth opportunities and latent adjacency in Revenue Cycle Management (RCM) Market





Jessica
Mar, 2022
Which are the major growth driving factors for the End User segment of the Global Revenue Cycle Management Market?.
Karen
Mar, 2022
How the healthcare providers segment holds the largest share of the Revenue Cycle Management Market?.
Nancy
Mar, 2022
Which are the fastest growing economies in the global Revenue Cycle Management Market?.