Smart Gas Meter Market

Smart Gas Meter Market by Technology (AMR, AMI), Type (Smart Ultrasonic Gas Meter, Smart Diaphragm Gas Meter), Component (Hardware, Software), End User (Residential, Commercial, Industrial), and Region- Global Forecast to 2031


OVERVIEW
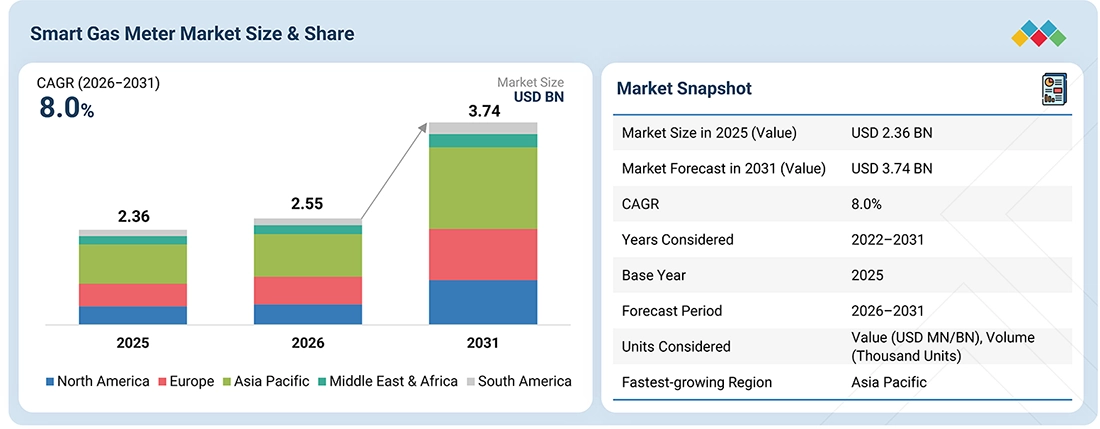
The smart gas meter market is projected to grow from USD 2.55 billion in 2026 to USD 3.74 billion by 2031, at a CAGR of 8.0%. The market is driven by the increasing modernization of gas distribution infrastructure, replacement of conventional meters, and growing adoption of automated and connected metering solutions. Rising demand for accurate consumption measurement, remote meter reading, automated billing, and improved utility operations is accelerating the deployment of smart gas meters across residential, commercial, and industrial applications. Furthermore, advancements in AMI and AMR technologies, ultrasonic and solid-state metering, cellular and NB-IoT connectivity, remote shutoff, leak detection, and IoT-enabled monitoring are expanding the functionality of smart gas meters, enabling utilities to improve network visibility, reduce field-service requirements, strengthen gas-network safety, and integrate metering data with digital utility-management platforms.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Smart Gas Meter Market Size and Forecast:
- Market Size (2025): USD 2.36 Billion
- Market Size (2026): USD 2.55 Billion
- Market Forecast (2031): USD 3.74 Billion
- Growth Rate: CAGR of 8.0% from 2026 to 2031
- Base Year: 2025
- Forecast Period: 2026–2031
Key growth drivers
- Increasing modernization of gas distribution infrastructure
- Replace conventional meters
- Growing adoption of automated and connected metering solutions
- Rapid utility digitalization
- Mounting deployment of AMR and AMI technologies
KEY TAKEAWAYS
-
BY REGIONBy region, North America is expected to register a CAGR of 5.2% in the smart gas meter market during the forecast period.
-
BY TYPEBy type, the smart diaphragm gas meters segment accounted for a 79.7% market share in 2025.
-
BY TECHNOLOGYBy technology, the advanced metering infrastructure (AMI) segment held a 71.7% share of the smart gas meter market in 2025.
-
BY COMPONENTBy application, the hardware segment is expected to register the highest growth rate from 2026 to 2031.
-
BY END USERBy end user, the residential segment is projected to be the fastest-growing during the forecast period
-
COMPETITIVE LANDSCAPE - KEY PLAYERSItron Inc. (US), Landis+Gyr Group AG (Switzerland), Honeywell International Inc. (US), Apator S.A. (Poland), Diehl Stiftung & Co. KG (Germany), Sensus (US), EDMI Limited (Singapore), Aclara Technologies (US), Wasion Holdings International (China), and Pietro Fiorentini S.p.A.(Italy) were identified as some of the star players in the smart gas meter market.
-
COMPETITIVE LANDSCAPE - STARTUPS/SMESSNS TECHNOSYS (India), Sagemcom(France), Adya Smart Metering(India), Ultan Technologies (Ireland), PowerCom(Israel), and Discovergy GmbH (Germany) have distinguished themselves among the startups and SMEs in the smart gas meter market.
The smart gas meter market is driven by the modernization of gas distribution infrastructure, increasing adoption of connected metering solutions, and growing demand for automated consumption measurement and remote utility operations. Rising deployment of AMR and AMI systems across residential, commercial, and industrial applications is supporting market growth, while advances in ultrasonic and diaphragm metering, wireless communication, remote shutoff, pressure monitoring, and IoT-enabled data management are expanding smart gas meter capabilities.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
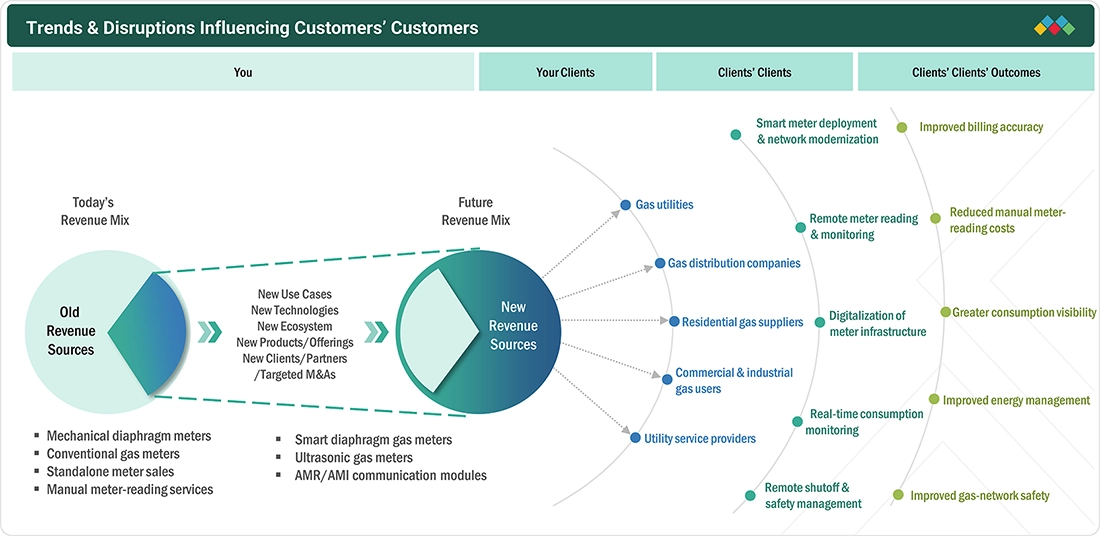
The smart gas meter market is undergoing a clear shift from traditional revenue streams—mechanical diaphragm meters, conventional gas meters, standalone meter sales, and manual meter-reading services—toward new revenue sources centered on smart diaphragm gas meters, ultrasonic gas meters, and AMR/AMI communication modules. This transition is driven by the imperatives of gas utilities, distribution companies, residential and commercial/industrial gas suppliers, and utility service providers, who are prioritizing smart meter deployment and network modernization, remote meter reading and monitoring, digitalization of meter infrastructure, real-time consumption monitoring, and remote shutoff and safety management. These capabilities ultimately deliver measurable outcomes for end customers, including improved billing accuracy, reduced manual meter-reading costs, greater consumption visibility, enhanced energy management, and improved gas-network safety.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Level
-
Rapid utility digitalization

-
Mounting deployment of AMR and AMI technologies


Level
-
High upfront deployment and infrastructure costs

-
Integration complexity with legacy utility systems


Level
-
Emergence of ultrasonic and solid-state smart gas meters

-
Availability of retrofit communication modules for existing meters


Level
-
Cybersecurity and data-privacy requirements

-
Compatibility issues with legacy gas infrastructure

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Rapid utility digitalization
Utility digitalization and gas-network modernization are accelerating the replacement of conventional gas meters with connected metering solutions that enable automated data collection, remote monitoring, and digital billing. Utilities are increasingly integrating smart meters with meter-data management, customer-management, and network-monitoring platforms to improve operational visibility. AMR and AMI deployment is further supporting adoption by reducing dependence on manual meter reading and enabling more frequent consumption-data collection. Smart metering can also support remote meter operations and faster identification of abnormal consumption patterns. Growing demand for accurate billing, reduced field-service requirements, improved network management, and enhanced customer visibility is encouraging utilities to modernize aging metering infrastructure. These benefits are particularly relevant as gas distributors pursue greater operational efficiency and digital transformation across residential, commercial, and industrial networks.
Restraint: High upfront deployment and infrastructure costs
High upfront deployment and infrastructure costs remain a key restraint for smart gas meter adoption, particularly where utilities must replace large installed bases of conventional meters and simultaneously establish communication and data-management infrastructure. Integration with legacy utility systems can further increase implementation complexity as existing billing, customer-management, communication, and meter-data platforms may require upgrades or interoperability solutions. Deployment can also be challenging in remote, rural, and low-density areas, where communication-network availability may be limited, and the economics of connectivity can be less favorable. In addition, utilities may need to invest in installation, commissioning, cybersecurity, software integration, maintenance, and workforce training alongside meter hardware. These requirements can extend project timelines and increase the total cost of smart-metering programs, particularly for smaller gas distribution companies with limited modernization budgets.
Opportunity: Emergence of ultrasonic and solid-state smart gas meters
Ultrasonic and solid-state smart gas meters are creating opportunities for manufacturers to move beyond conventional diaphragm-based metering toward digitally integrated platforms with advanced measurement and monitoring capabilities. Ultrasonic technologies can support compact designs, electronic measurement, and integration with communication and diagnostic functions. Another opportunity is the development of retrofit communication modules that allow utilities to add connectivity to portions of their existing meter base without immediately replacing every installed meter. Manufacturers can also expand value propositions through NB-IoT, cellular, RF, and other wireless communication technologies, enabling remote data transmission and utility connectivity. Integration with cloud-based meter-data platforms, analytics, remote monitoring, and automated billing can create additional recurring software and service opportunities. These developments allow market participants to address both new installations and modernization of existing gas-meter infrastructure.
Challenge: Cybersecurity and data-privacy requirements
Cybersecurity and data-privacy requirements are becoming increasingly crucial as smart gas meters connect physical metering infrastructure with communication networks and centralized utility platforms. Connected meters generate and transmit consumption information, increasing the need for secure authentication, encryption, access controls, monitoring, and controlled data sharing. Compatibility with legacy gas infrastructure is another challenge because utilities often operate heterogeneous meter fleets, communication networks, billing platforms, and data-management systems. Fragmentation across communication technologies and technical standards can make interoperability more difficult and increase integration costs. Utilities and manufacturers must therefore ensure that new smart-meter solutions can communicate reliably with existing infrastructure while meeting evolving security and regulatory requirements. The need for secure, interoperable, upgradeable systems can increase product-development and deployment complexity and influence procurement decisions across major gas distribution markets.
SMART GAS METER MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Itron's Intelis ultrasonic gas meter is being deployed by gas utilities as part of AMI-enabled gas distribution modernization. The platform combines ultrasonic metrology with connected communications, pressure and flow monitoring, and remote internal-valve actuation. Itron highlights its deployment with Spire, which uses Intelis gas meters to strengthen gas-safety management across its customer network. | Enables utilities to improve gas-network visibility and safety, detect high-flow, high-/low-pressure, temperature, and air-in-pipe conditions, and remotely actuate shutoff valves | Supports automated meter reading, more accurate billing, reduced manual investigations, and lower meter-operation costs |
 |
Apator manufactures gas meters that support accurate consumption measurement and remote management of gas-supply access. Its smart-gas portfolio is designed to connect metering with utility-management systems, supporting the transition from conventional gas metering toward remotely managed infrastructure. Apator also provides proprietary software and utility-management solutions alongside its metering portfolio. | Supports remote consumption monitoring and gas-supply management, reducing dependence on manual meter reading and enabling utilities to improve operational control | Supports utility digitalization, data management, and more efficient management of distributed gas-metering assets |
 |
Landis+Gyr provides smart gas metering solutions for utilities through its Surent ultrasonic gas meter and retrofit communication modules. Its G480 ultrasonic smart gas meter combines solid-state measurement with two-way cellular communication, while the M225 Commercial & Industrial Gas Communications Module enables two-way AMI communication for large diaphragm gas meters. These solutions allow utilities to collect consumption and interval data remotely and integrate gas metering with broader AMI and IoT infrastructure. | Supports accurate gas measurement, remote meter operations, automated data collection, and improved visibility into consumption patterns| Supports capacity planning, flexible rate structures, safety monitoring, and operational efficiency | Allows utilities to modernize existing gas-meter infrastructure through retrofit communication modules |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
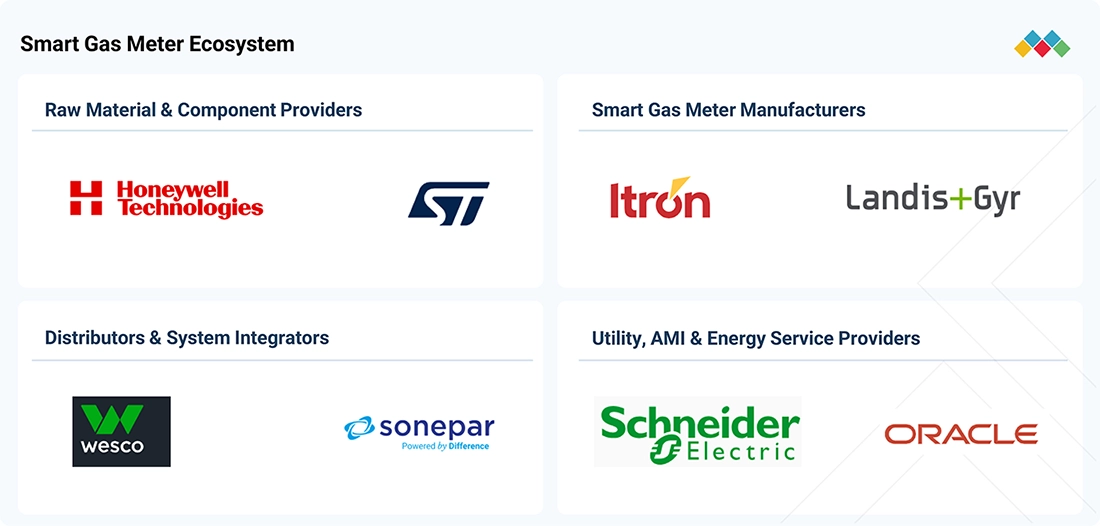
The smart gas meter market operates through an interconnected ecosystem comprising smart gas meter manufacturers, communication and metering technology providers, component suppliers, gas utilities and distributors, system integrators, and end users. Manufacturers such as Itron, Landis+Gyr, Honeywell (Elster), Diehl Metering, Apator, AEM, and Pietro Fiorentini develop smart gas meters, ultrasonic and diaphragm metering technologies, communication modules, and related software platforms, while semiconductor, battery, sensor, and communication-component suppliers support product development. Gas utilities and distribution companies procure and deploy these systems across residential, commercial, and industrial networks, supported by system integrators and technology partners for installation, connectivity, data management, and maintenance. Utilities remain the primary decision-makers, adopting smart gas meters to enable automated meter reading, improve billing accuracy, strengthen network monitoring, reduce field-service requirements, and enhance gas-network safety.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Smart Gas Meter Market, By Type
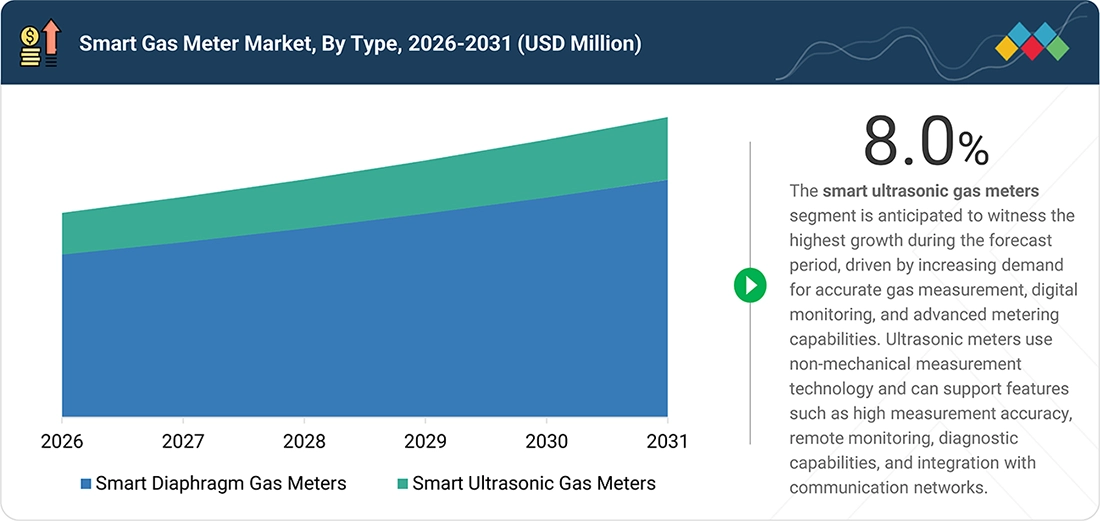
Ultrasonic smart gas meters are projected to register the highest CAGR during the forecast period. Their ability to provide accurate gas measurement without moving mechanical components is supporting adoption across modern utility networks. Integration with pressure sensing, remote shutoff, leak detection, and digital communication further enhances their functionality. Increasing replacement of conventional diaphragm meters and utility investment in advanced metering infrastructure are expected to accelerate adoption of ultrasonic smart gas meters.
Smart Gas Meter Market, By Technology
Advanced metering infrastructure (AMI) is projected to register the highest CAGR during the forecast period. AMI enables two-way communication between utilities and gas meters, allowing automated data collection, remote monitoring, diagnostics, and meter management. Utilities are increasingly adopting AMI to reduce manual meter-reading activities, improve billing accuracy, enhance network visibility, and support data-driven gas distribution operations.
Smart Gas Meter Market, By Component
Communication modules are projected to register the highest growth rate during the forecast period. Increasing adoption of cellular, NB-IoT, RF Mesh, and other wireless technologies is strengthening demand for integrated communication capabilities in smart gas meters. These modules enable remote data transmission, two-way communication, diagnostics, and connectivity with utility AMI platforms, supporting the digitalization of gas-metering infrastructure.
Smart Gas Meter Market, By End User
The residential segment is projected to register the highest CAGR during the forecast period. Residential utilities are increasingly replacing conventional gas meters with smart connected devices to automate meter reading, improve billing accuracy, monitor consumption remotely, and reduce field-service requirements. The large installed base of residential gas meters, combined with ongoing infrastructure modernization and increasing demand for digital utility services, is supporting smart gas meter deployment in this sector.
REGION
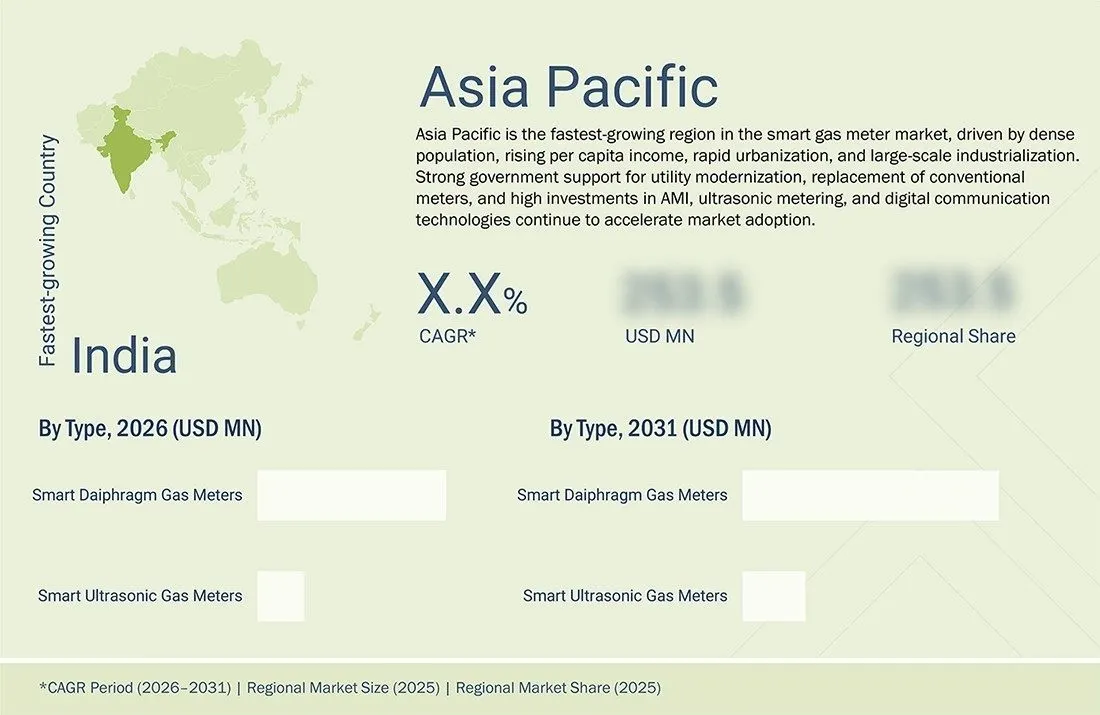
Asia Pacific to grow at the fastest rate in the smart gas meter market during the forecast period
Asia Pacific is expected to record the highest CAGR in the smart gas meter market during the forecast period, driven by rapid urbanization, large-scale utility modernization programs, replacement of conventional meters, and accelerating adoption of AMI-enabled gas metering. The region represents the key growth market, supported by expanding investments in two-way communication, remote meter operations, ultrasonic measurement, and advanced safety capabilities across major economies. These developments are supporting the transition toward more accurate, remotely managed, and data-enabled gas distribution networks.
SMART GAS METER MARKET: COMPANY EVALUATION MATRIX
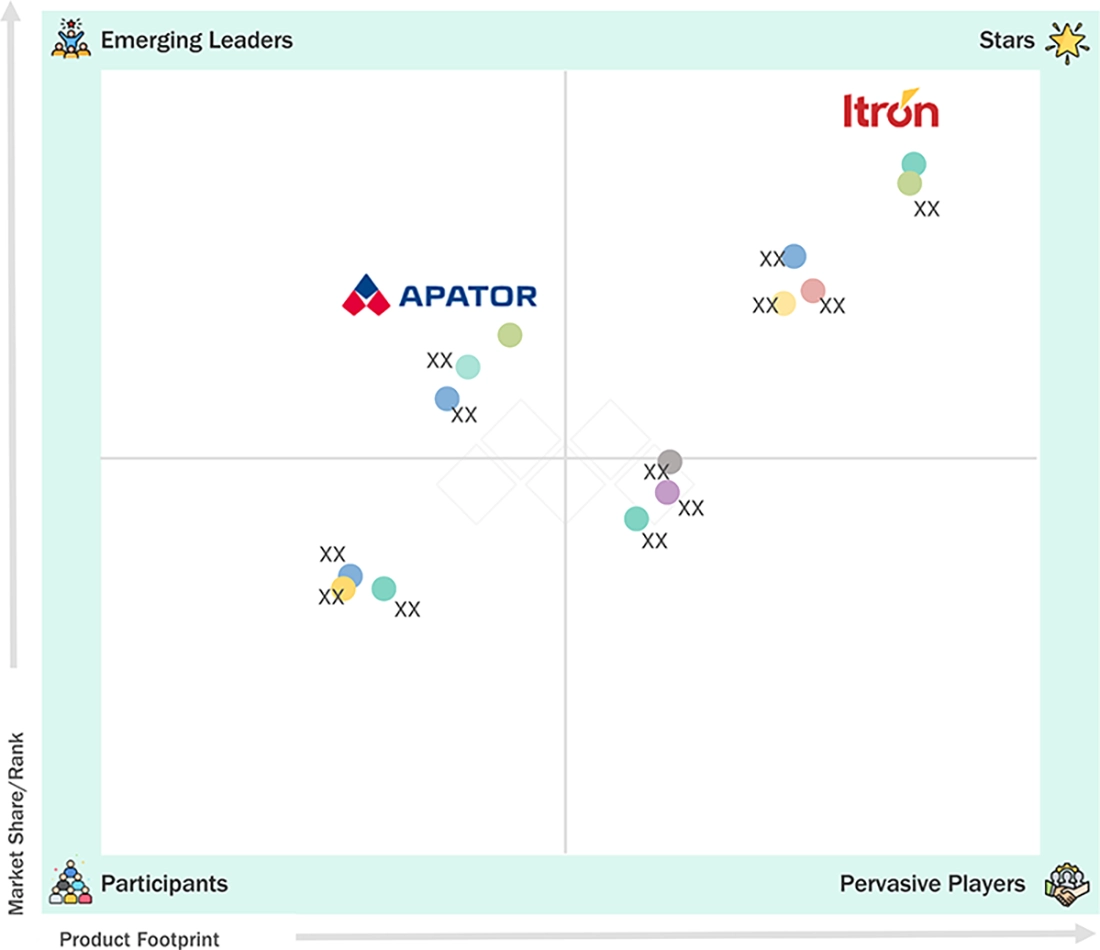
The smart gas meter market features two standout players positioned distinctly in the competitive landscape: Itron as a Star and Apator as an Emerging Leader. Itron occupies the high market-share/high product-footprint quadrant, offering a broad portfolio of smart residential gas meters, ultrasonic metering solutions, communication modules, and full AMR/AMI systems that support deep utility relationships and advanced network capabilities. Apator, positioned as an Emerging Leader with strong market ranking but a more focused product footprint, contributes through connected metering solutions, wireless communication technologies, and utility data-management offerings that are expanding its presence in the smart gas meter space.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- Itron Inc. (US)
- Diehl Stiftung & Co. KG (Germany)
- Honeywell International Inc. (US)
- Landis+Gyr (Switzerland)
- Sensus (Xylem) (US)
- EDMI Limited (Singapore)
- Chongqing Shancheng Gas Equipment Co., Ltd. (China)
- Dongfa (group) (China)
- Raychem RPG (India)
- CHINT Group. (China)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2025 (Value) | USD 2.36 Billion |
| Market Forecast in 2026 (Value) | USD 2.55 Billion |
| Market Forecast in 2031 (Value) | USD 3.74 Billion |
| Growth Rate | CAGR of 8.0% from 2026-2031 |
| Years Considered | 2022–2031 |
| Base Year | 2025 |
| Forecast Period | 2026–2031 |
| Units Considered | Value (USD Million/Billion), Volume (Thousand Units) |
| Report Coverage | Market size and forecast, company profiling, competitive landscape, market dynamics (drivers, restraints, opportunities, and challenges), technology trends, ecosystem analysis, commercial use cases, and regional analysis |
| Segments Covered |
|
| Regions Covered | North America, South America, Europe, Asia Pacific, and the Middle East & Africa |
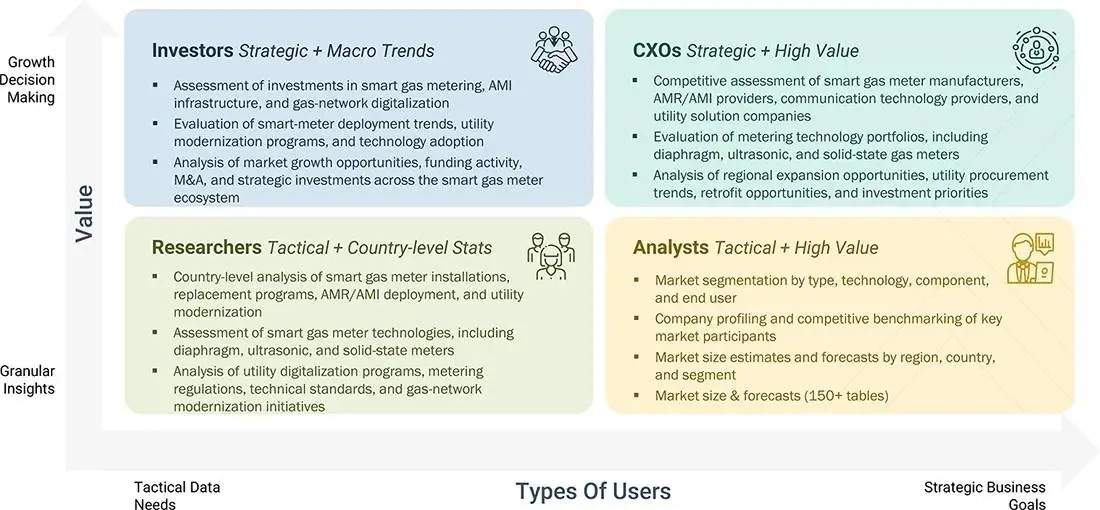
WHAT IS IN IT FOR YOU: SMART GAS METER MARKET REPORT CONTENT GUIDE
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Client requirement for smart water meter report | Market sizing for smart meter in countries | Country-wise market attractiveness analysis, competitive landscape overview, and installation of smart meter in high-growth economies |
RECENT DEVELOPMENTS
- September 2026 : Itron launched Itron Enterprise Edition (IEE) Cloud AI, an AI-enabled cloud meter-data management platform designed to help utilities extract greater value from AMI investments. The platform adds near-real-time data processing, anomaly detection, forecasting, revenue assurance, and cloud-based workflows, supporting the evolution of smart metering toward data-driven utility operations.
- June 2026 : Landis+Gyr received New York Public Service Commission approval for its Surent G480 ultrasonic gas meter, making it the first ultrasonic gas meter approved for use in New York State. The meter provides interval volume, pressure, and temperature data, remote shutoff, and flexible cellular, RF Mesh, and Wi-SUN connectivity, enabling utilities to strengthen gas-network safety and operational visibility.
- May 2026 : Honeywell expanded the positioning of its NXU Residential Smart Gas Meter around early anomaly detection and proactive gas-network management. The ultrasonic meter combines pressure sensing, an integrated controller, remote shutoff, and advanced analytics to help utilities identify abnormal conditions earlier and improve field-worker and network safety. The platform also supports cellular AMI connectivity and long battery life.
- March 2026 : Itron expanded its UtilityIQ Application Suite to support the Cellular 500G gas communication module, enabling a unified head-end platform across gas, water, and electric deployments. The solution supports multi-transport, multi-device, and multi-vendor interoperability, allowing utilities to combine cellular and mesh connectivity while extending AMI infrastructure and centralized meter-data management capabilities.
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
Methodology
The study involved major activities to estimate the current size of the smart gas meter market. Exhaustive secondary research was done to collect information on the peer and parent markets. The next step was to validate these findings, assumptions, and sizing with industry experts across the value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the total market size. Thereafter, market breakdown and data triangulation were used to estimate the market size of the segments and subsegments.
Secondary Research
This research study on the smart gas meter market involved the use of extensive secondary sources, directories, and databases, such as Hoover's, Bloomberg, Factiva, IRENA, International Energy Agency, and Statista Industry Journal, to collect and identify information useful for a technical, market-oriented, and commercial study of the market. The other secondary sources included annual reports, press releases & investor presentations of companies, white papers, certified publications, articles by recognized authors, manufacturer associations, trade directories, and databases, articles by recognized authors, manufacturer associations, trade directories, and databases.
Primary Research
The smart gas meter market comprises several stakeholders, such as equipment providers, service providers, and technical providers in the supply chain. The rising demand for smart gas meters of various types, such as smart ultrasonic gas meters and smart diaphragm gas meters, characterizes this market's demand side. The supply side is characterized by rising demand for contracts from the industrial sector and mergers & acquisitions among big players. Various primary sources from both the supply and demand sides of the market were interviewed to obtain qualitative and quantitative information.
In the complete market engineering process, the top-down and bottom-up approaches and several data triangulation methods were extensively used to perform the market size estimations and forecasts for all segments and subsegments listed in this report. Extensive qualitative and quantitative analyses were conducted to complete the market engineering process and list key information/insights throughout the report.
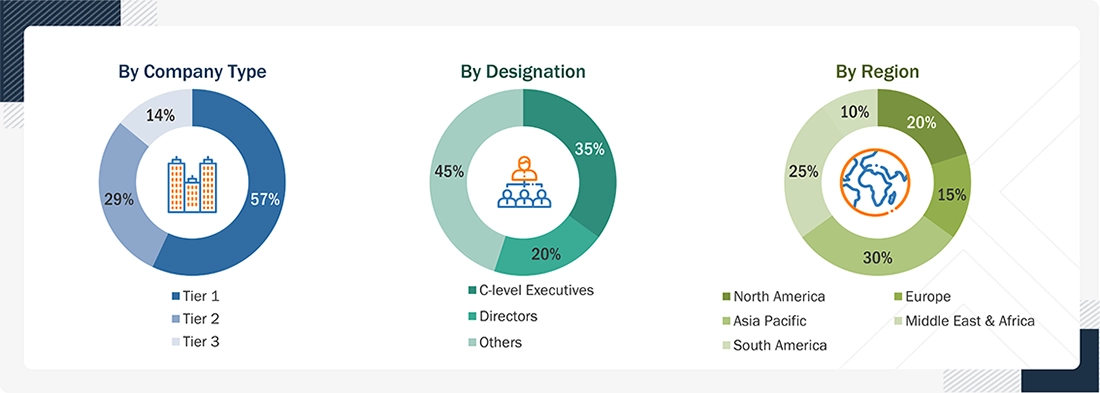
The following is the breakdown of primary respondents:
To know about the assumptions considered for the study, download the pdf brochure
Tier 1 Company Revenue> USD 5 billion, Tier 2 Company Revenue between USD 1 and USD 5 billion, and Tier 3 Company Revenue < USD 1 billion.
Note: Others include sales managers, engineers, and regional managers.
Market Size Estimation
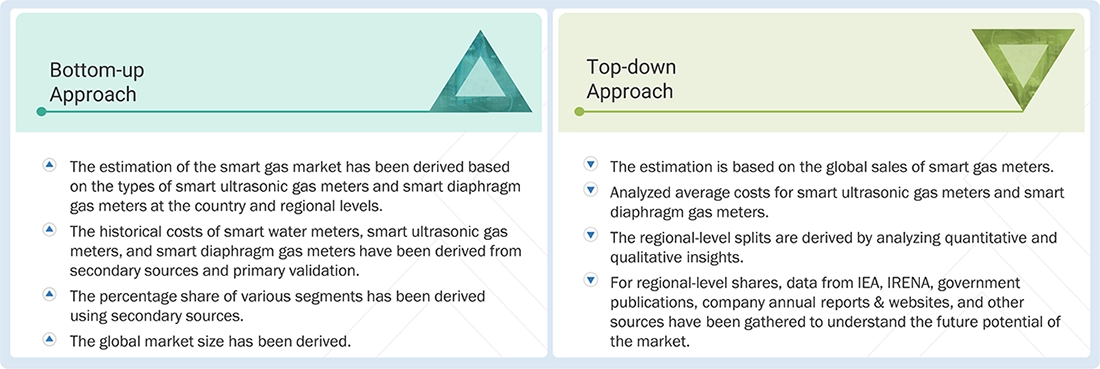
Both top-down and bottom-up approaches were used to estimate and validate the total size of the smart gas meter market. These methods were also used extensively to estimate the size of various subsegments in the market. The research methodology used to estimate the market size includes the following.
Bottom-up Approach
- The smart gas meter market estimation has been done at the country and regional level based on the types of smart gas meters, such as smart diaphragm gas meters and smart ultrasonic gas meters.
- The historical cost of smart gas meters, such as smart diaphragm gas meters and smart ultrasonic gas meters, has been obtained from secondary sources and verified through primary research.
- The market share of different types of smart gas meters, technologies, applications, and end users has been calculated based on secondary sources and primary research.
- To determine the market size for smart gas meters, estimates for the country and regional markets were consolidated.
Top-down Approach
- The estimation is based on the global sales of smart gas meters, considering the adoption of smart metering technologies in residential, commercial, and industrial gas applications.
- Average cost has been analyzed by type for smart gas meters, such as smart diaphragm gas meters and smart ultrasonic gas meters, to estimate the overall market value.
- Based on quantitative and qualitative information regarding the deployment of smart gas meters, adoption of AMR/AMI, communication technologies, utility modernization, and the replacement of traditional gas meters, the overall market has been segmented into its key components.
- Regional-level shares have been analyzed using data from the International Energy Agency (IEA), government sources, gas utilities, metering associations, company annual reports, company websites, and other credible sources to gain an understanding of how many smart gas meters could be expected to be installed in key regions and how big those numbers are.
Smart Gas Meter Market : Top-Down and Bottom-Up Approach
Data Triangulation
After arriving at the overall market size from the above estimation process, the total market has been split into several segments and subsegments. Data triangulation and market breakdown processes have been employed to complete the overall market engineering process and arrive at the exact statistics for all the segments and sub-segments, wherever applicable. The data has been triangulated by studying various factors and trends from both the demand and supply sides. Along with this, the market has been validated using both the top-down and bottom-up approaches.
Market Definition
A smart gas meter is equipment used for measuring the amount of gas consumed in intervals on an hourly or daily basis at homes, buildings, or industrial facilities. Smart gas meters are next-generation metering devices that allow remote data collection related to consumers' usage and periodic communication with the utility. They use wireless communication to connect to wide-area networks, allowing remote monitoring and automatic billing. Implementing smart gas meters in utilities helps increase energy efficiency and effectively monitor and integrate new utility resources. For consumers, smart gas meters offer a better understanding of their usage or consumption patterns and help with easier supplier switching, fault detection, and clearance. There are two major types of smart gas meter technologies: Automatic Meter Reading (AMR) and Advanced Metering Infrastructure (AMI). Smart gas meters are mainly implemented globally in the residential, commercial, and industrial sectors.
Key Stakeholders
- Government and research organizations
- Energy service providers (private/government)
- Utilities & retail gas suppliers
- Original equipment manufacturers (OEMs)
- Independent service providers (ISPs)
- Asset owners/operators
- Technology providers
- Spare parts suppliers & logistics
- Consultants/consultancies/advisory firms
- Environmental research institutes
- Private or investor-owned utilities
- State and national regulatory authorities
- Investors/shareholders
Report Objectives
- _Hlk18346556To define and describe the smart gas meter market, based on technology, type, component, and end user, in terms of value and volume
- To provide detailed information on the major factors influencing the growth of the smart gas meter market (drivers, restraints, opportunities, and challenges)
- To strategically analyze the smart gas meter market with respect to individual growth trends, prospects, and contribution of each segment to the market
- To analyze market opportunities for stakeholders and details of a competitive landscape for market leaders
- To forecast the growth of the smart gas meter market with respect to the major regions (Asia Pacific, Europe, North America, South America, the Middle East, & Africa), in terms of value
- To strategically profile key players and comprehensively analyze their market share and core competencies
- To track and analyze competitive developments, such as new product launches, contracts & agreements, investments & expansions, and mergers & acquisitions, in the smart gas meter market
Customization Options
MarketsandMarkets offers customizations according to the specific needs of the companies with the given market data.
The following customization options are available for the report:
Product Analysis
- Product matrix, which gives a detailed comparison of the product portfolio of each company
Regional Analysis
- Further breakdown of the energy as a service market, by country
Company Information
- Detailed analysis and profiling of additional market players (up to five)
Key Questions Addressed by the Report
What was the size of the smart gas meter market in 2026?
The smart gas meter market reached USD 2.55 Billion in 2026.
What are the major drivers for the smart gas meter market?
The smart gas meter is driven by factors such as the growing modernization of gas distribution infrastructure, replacement of conventional meters, and growing adoption of automated and connected metering solutions.
Which region will be the most lucrative region in the smart gas market during the forecast period?
Asia Pacific is projected to be the fastest-growing market during the forecast period due to the region's greenfield investments in chemical and oil & gas industries.
By technology, which segment is projected to be the fastest-growing segment in the smart gas meter market during the forecast period?
The AMI segment is projected to register the highest CAGR during the forecast period. The market for AMI is driven by the growing need for accurate meter readings and increasing spending on smart grid projects.
Who are the leading players in the global smart gas meter market?
Landis+Gyr (Switzerland), Itron Inc. (US), Honeywell International Inc. (US), and Diehl Stiftung & Co. KG (Germany). are the leading players in the smart gas meter market.


Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the Smart Gas Meter Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Custom Market Research Services
We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements
Get 10% Free CustomisationTESTIMONIALS
Kimberly Murphy
GLOBAL MARKETING DIRECTOR
Bently Nevada,
Leading Condition Monitoring & Asset Protectionwww.bakerhughesds.com/bently-nevada
MarketsandMarkets™ showed consistent rigor for success and relentlessly worked with Bently Nevada stakeholders to positively impact go-to-market strategy. Their proactiveness and flexibility has been instrumental in achieving the objectives to grow our sales pipeline in key industrial markets.
DARRICK HUEBER
Business Development Leader
Nexus Controls LLC,
Leading Manufacturer of Automation System & Electrical Panelswww.bakerhughesds.com/nexus-controls
We partnered with MarketsandMarkets to expand our business further by tapping into new industrial segments. It was critical for us to gather crucial business insights about specific markets to achieve this goal. MarketsandMarkets engagement model and client services helped us provide those insights, it was really impressive and valuable for my business. The team was extremely flexible and helpful.
Mike Schoff
Global Industrial Commercial Strategy Leader
Nexus Controls LLC
Leading Manufacturer of Automation System & Electrical Panelswww.bakerhughesds.com/nexus-controls
We consulted MarketsandMarkets for potential Partner Identification. Overall, it was a good experience. The insights provided through interviews conducted by the team helped us put together the questionnaire required for discussion with the selected partners. Their ability to provide insights through interviews with customers in a timely manner was quite impressive.
- Canada Smart Gas Meter Market
- Mexico Smart Gas Meter Market
- US Smart Gas Meter Market
- France Smart Gas Meter Market
- Germany Smart Gas Meter Market
- Italy Smart Gas Meter Market
- Poland Smart Gas Meter Market
- Spain Smart Gas Meter Market
- UK Smart Gas Meter Market
- Australia Smart Gas Meter Market
- China Smart Gas Meter Market
- India Smart Gas Meter Market
- Japan Smart Gas Meter Market
- South Korea Smart Gas Meter Market
- Saudi Arabia Smart Gas Meter Market
- UAE Smart Gas Meter Market
- Israel Smart Gas Meter Market
- South Africa Smart Gas Meter Market
- Turkey Smart Gas Meter Market
- Rest Of Europe Smart Gas Meter Market
- Rest Of Asia Pacific Smart Gas Meter Market
- GCC Smart Gas Meter Market





Growth opportunities and latent adjacency in Smart Gas Meter Market