Wearable Injectors Market by Product (On-body/Off-body), Technology (Spring, Motor Driven, Rotary Pump), Usage (Disposable, Reusable), Delivery Method (Bolus, Programmed Infusion), Therapeutic Application (Diabetes, Oncology) - Global Forecast to 2031

Market Size
$12.6B
MARKET SIZE, 2026
Projected Market Size
$21.0B
MARKET SIZE, 2031
CAGR
10.8%
CAGR (2026-2031)
Forecast Period
2026-2031
FORECAST PERIOD

WEARABLE INJECTORS MARKET SIZE, SHARE & GROWTH SNAPSHOT

wearable-injector-market Overview

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

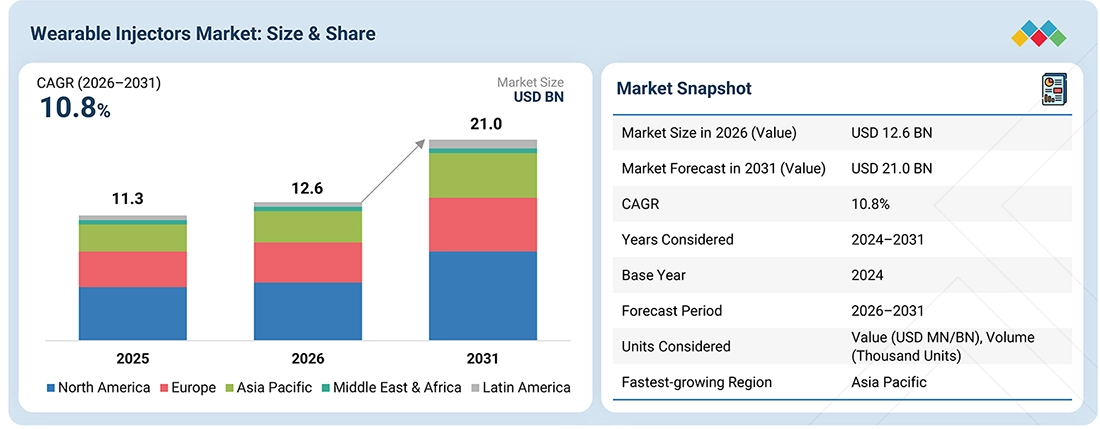
The global wearable injectors market is projected to grow from USD 12.6 billion in 2026 to USD 21.0 billion by 2031, at a CAGR of 10.8% during the forecast period. The market was valued at USD 11.3 billion in 2025. Wearable injectors refer to drug delivery devices that are designed to administer large-volume biologics or medications subcutaneously over an extended period, typically ranging from minutes to hours. These compact, lightweight, body-worn devices improve patient compliance by enabling self-administration outside clinical settings, particularly for chronic conditions such as diabetes, oncology, autoimmune disorders, and cardiovascular diseases. Wearable injectors are engineered to deliver high-viscosity drugs safely and accurately with minimal discomfort, reducing the need for frequent hospital visits and manual injections. The market encompasses a wide range of device types, including on-body and off-body injectors, bolus injectors, and patch pumps, powered by electromechanical or mechanical systems.

KEY TAKEAWAYS

  • MARKET SNAPSHOT:
    Base Year Market Size (2025): USD 11.3 Billion
    Current Market Size (2026): USD 12.6 Billion
    Forecast Market Size (2031): USD 21.0 Billion
    CAGR (2026–2031): 10.8%
  • SEGMENT LEADERSHIP:
    Regional Outlook: Asia Pacific is expected to have the highest CAGR from 2026 to 2031.
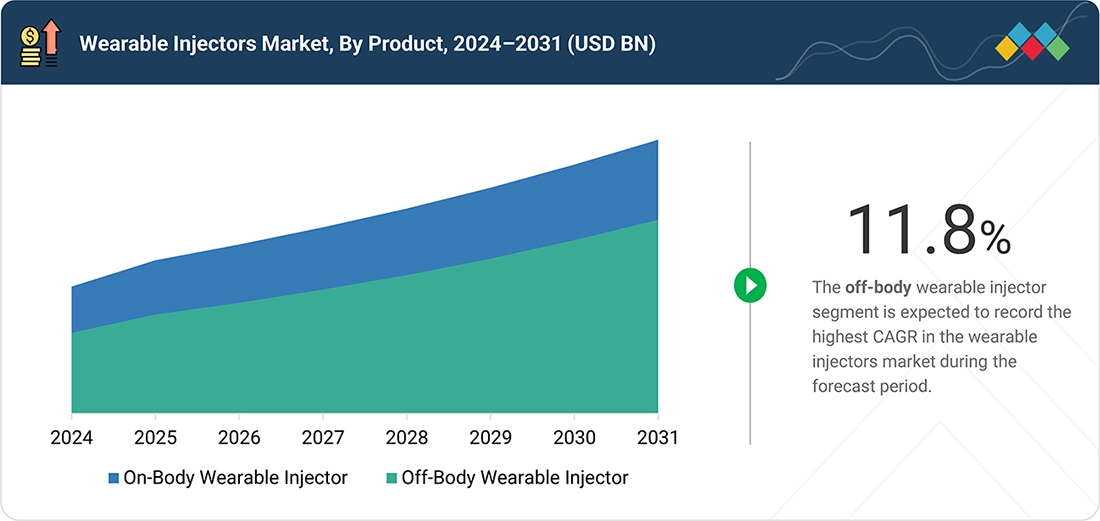
    Product Leader: On-body wearable injectors accounted for a 60.8% share of the market in 2025.
    Technology Leader: Spring-based technology accounted for a 41.8% share of the market in 2025.
    Fastest-Growing Usage: Reusable segment is expected to register the highest CAGR of 11.8% during the forecast period.
    Fastest-Growing Delivery Method: Programmed/continuous infusion is projected to witness the highest CAGR of 11.5% during 2026–2031.
    Fastest-Growing Therapeutic Application: Infectious disease segment is projected to witness the highest CAGR of 13.9% during 2026–2031.
    End User Leader: Formulation end user segment accounted for a 74.1% share of the market in 2025.
  • MARKET OUTLOOK & COMPETITIVE LANDSCAPE:
    Major players include Insulet Corporation (US), Medtronic (Ireland), BD (US), West Pharmaceutical Services, Inc. (US), and Gerresheimer AG (Germany). These companies offer a diverse portfolio of drug-device products and technologies and compete through product innovation, broad geographic presence, and applications across hospitals & clinics, home care settings, Specialty Infusion Centers / ASCs, pharmaceutical companies, biotechnology companies, and other end users.
    Emerging companies such as Enable Injections, Inc. (US), Subcuject ApS (Denmark), and CeQur (Switzerland), among others, have distinguished themselves among startups and SMEs by securing strong footholds in specialized niche areas, underscoring their potential as emerging market leaders.

The wearable injectors market is projected to grow rapidly over the next decade, supported by the rising burden of chronic diseases and the aging global population. These demographic shifts are pushing healthcare systems to adopt more patient-centric solutions. The growing preference for home healthcare and self-administration is further accelerating the adoption of wearable injectors, as they let patients manage conditions like diabetes, cancer, and autoimmune diseases independently and more conveniently.

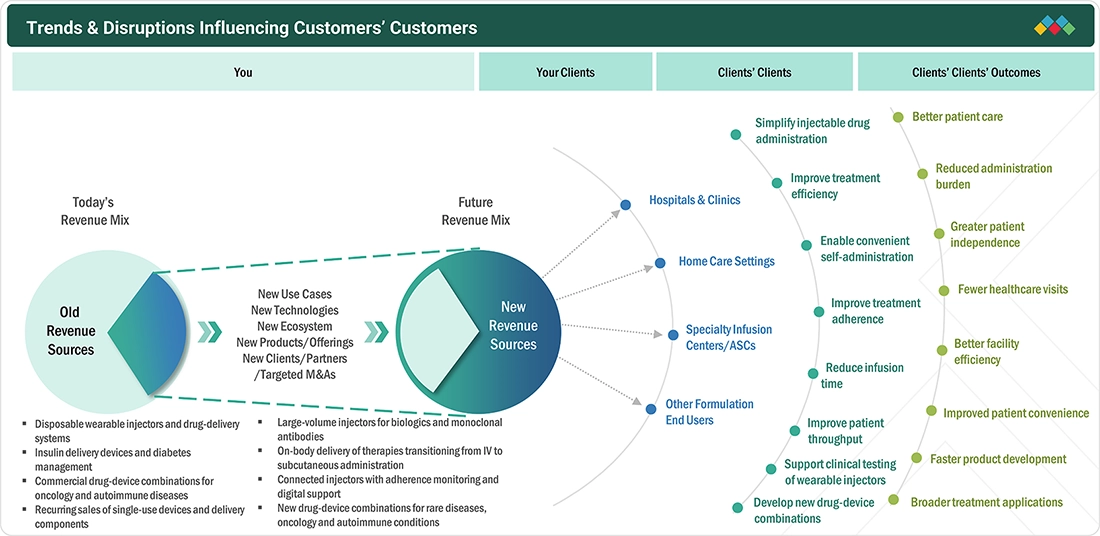
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS

The evolving landscape of the wearable injectors market highlights key trends and disruptions that are reshaping revenue sources and impacting end-user dynamics. As the industry transitions from traditional drug delivery systems to more patient-centric and technology-integrated solutions, new high-growth opportunities are emerging, particularly in self-administration and home-based care.

wearable-injector-market Disruptions

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

MARKET DYNAMICS

Drivers
Impact
Level
  • Rising burden of chronic diseases and aging population
  • Growing preference for home healthcare and self-administration
RESTRAINTS
Impact
Level
  • High cost of wearable injectors and lack of reimbursement plans in emerging economies
  • Stringent regulatory requirements for new product approval
OPPORTUNITIES
Impact
Level
  • Growth potential of emerging economies
  • Integration with digital health & remote monitoring
CHALLENGES
Impact
Level
  • Lack of training and education for using wearable injectors

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Driver: Rising burden of chronic diseases and aging population

The wearable injectors market is growing rapidly due to rising chronic disease prevalence and an expanding elderly population. Conditions like diabetes, cancer, and cardiovascular disorders require long-term therapy, making wearable injectors ideal for delivering large-volume drugs in a safe, convenient way. According to the WHO, chronic diseases cause over 70% of global deaths. Aging patients, often managing multiple conditions, benefit from at-home, minimally invasive solutions that reduce hospital visits and improve adherence. This aligns with the global shift toward outpatient and home-based care. Technological advances, such as Insulet’s FDA-cleared Omnipod 5 app for iOS and Android, further drive adoption with connected and automated delivery systems.

Restraint: High cost and limited reimbursement in emerging economies

High costs and weak reimbursement systems limit wearable injector adoption in emerging markets. Advanced technology, regulatory compliance, and manufacturing expenses drive up prices, making devices less accessible in cost-sensitive regions. In many developing countries, patients face out-of-pocket expenses as insurers hesitate to cover such devices without clear long-term cost-benefit data. This financial barrier restricts adoption and slows market expansion in high-growth but economically constrained geographies.

Opportunity: Growth potential of emerging economies

Emerging markets such as India, China, and Brazil present strong growth prospects for the wearable injectors industry, fueled by rising incidences of chronic and infectious diseases and evolving healthcare ecosystems. Ongoing infrastructure development, increasing R&D, and cost-efficient manufacturing in these regions are expected to attract global investments. Currently, most leading manufacturers maintain a limited presence in Asia Pacific and Latin America, relying heavily on imports from the US and Europe, creating untapped opportunities. In particular, growing demand for wearable insulin pumps, driven by rising diabetes prevalence, higher healthcare spending, and advancements in insulin patch technology, is set to accelerate market expansion.

Challenge: Lack of training and education for using wearable injectors

Adoption of wearable injectors is hindered by limited training among both patients and healthcare professionals. Although designed for simplicity, correct use still requires understanding steps such as application, dosing, and disposal. Inadequate training increases the risk of misuse or device malfunction, compromising patient safety. The challenge is more pronounced in low-resource healthcare settings where providers have limited time and tools for patient education. Elderly users or those with physical or cognitive difficulties also face barriers to self-administration. To overcome this, manufacturers must prioritize user-friendly designs, clear visual instructions, and structured training programs to ensure safe and effective usage.

WEARABLE INJECTORS MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES

COMPANY USE CASE DESCRIPTION BENEFITS
company logo
Develops the Libertas wearable injector platform for subcutaneous delivery of large-volume and high-viscosity biologics and biosimilars, with 2–5 mL and 5–10 mL configurations. Prefilled, ready-to-use design | Hands-free drug delivery | Simplified administration and reduced preparation errors
company logo
Offers the MiniMed 780G automated insulin delivery system, which integrates an insulin pump with continuous glucose monitoring to automatically adjust insulin delivery based on glucose levels. Automated insulin delivery | Continuous glucose monitoring integration | Improved diabetes management
company logo
Offers the Neulasta Onpro kit, an on-body injector that delivers pegfilgrastim after chemotherapy, allowing the dose to be administered approximately 27 hours after application. At-home drug administration | Reduced need for next-day clinic visits | Convenient post-chemotherapy treatment
company logo
Offers SKYRIZI with an on-body injector for subcutaneous administration of risankizumab for eligible patients with conditions including Crohn's disease and ulcerative colitis. Convenient biologic administration | Supports home-based treatment | Reduced administration burden
company logo
Develops the Omnipod range of tubeless, wearable insulin delivery systems, including Omnipod 5, which integrates automated insulin delivery technology for diabetes management. Tubeless, wearable insulin delivery | Automated diabetes management | Greater convenience for daily insulin therapy

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET ECOSYSTEM

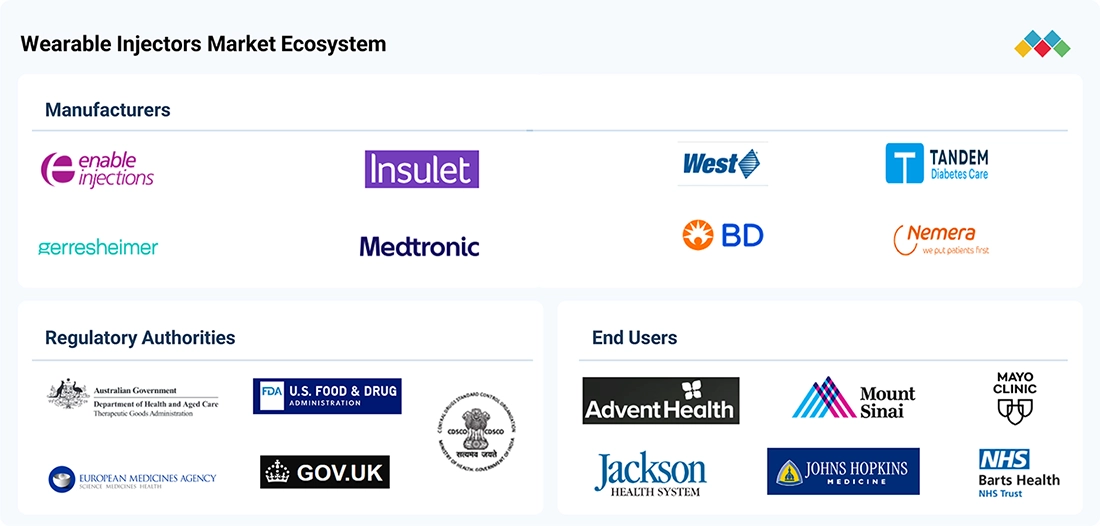
The wearable injectors market operates within a complex, interconnected ecosystem, which includes product innovation, regulatory oversight, manufacturing, distribution, and end-user adoption across multiple care settings. At the core of the ecosystem are manufacturers, including Insulet Corporation (US), Medtronic (Ireland), Tandem Diabetes Care, Inc. (US), BD (US), West Pharmaceutical Services, Inc. (US), Gerresheimer AG (Germany), Stevanato Group (Italy), and LTS Lohmann Therapie-Systeme AG (Germany). They are supported by academic institutes, clinical research bodies, and technology partners. Surrounding this network are regulatory agencies such as the Food and Drug Administration (FDA), European Medicines Agency (EMA), and national health authorities that enforce strict compliance with device safety, sterility, performance standards, and post-market surveillance. Downstream, the ecosystem culminates with diverse end users, including hospitals & clinics, home care settings, Specialty Infusion Centers / ASCs, pharmaceutical companies, biotechnology companies, and other end users, whose clinical needs, workflow requirements, and safety priorities directly shape product selection, adoption rates, and long-term technology evolution within the market.

wearable-injector-market Ecosystem

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET SEGMENTS

wearable-injector-market Segments

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Wearable Injectors Market, By Product

The on-body wearable injectors segment held the largest market share in 2025. These devices, attached directly to the patient's skin, provide hands-free, controlled subcutaneous drug delivery over a set duration. Their ability to deliver high-volume and viscous drugs conveniently, without disrupting daily activities, has driven widespread adoption. Rising use in managing chronic conditions such as cancer, diabetes, and autoimmune disorders, where frequent self-administration is common, further strengthens their market position. A growing preference for home healthcare, reduced hospital dependency, and improved patient comfort also support this dominance. Meanwhile, the off-body injectors segment is projected to record the fastest growth during the forecast period, propelled by innovations in connectivity and digital monitoring features.

Wearable Injectors Market, By Technology

The spring-based technology segment led the wearable injectors market in 2025. Known for its simplicity, reliability, and cost-effectiveness, this mechanism delivers consistent drug flow through mechanical springs, making it suitable for large-volume and viscous biologics. Widely adopted in chronic disease management, including cancer, diabetes, and autoimmune disorders, spring-based injectors are user-friendly and require minimal intervention, supporting safe self-administration in home care. Their straightforward design, broad drug compatibility, and adaptability across hospital and outpatient settings underpin their continued dominance in the market.

Wearable Injectors Market, By Usage

The disposable segment holds the largest share in the wearable injectors market by usage. These devices are widely preferred for biologics and chronic therapies requiring monthly or weekly subcutaneous dosing and are favored for their simplicity, sterility assurance, and reduced infection risk. One-step administration and minimal handling make them highly suitable for elderly and self-administering patient populations.

Wearable Injectors Market, By Delivery Method

The programmed or continuous infusion segment of the wearable injectors market is emerging as a high-growth frontier. It enables safe and sustained subcutaneous administration of drugs that traditionally required hospital-based intravenous infusions. This segment addresses critical challenges such as infusion site reactions, bioavailability concerns, and the growing demand for at-home administration of large-volume biologics.

Wearable Injectors Market, By Therapeutic Application

Therapeutic applications accounted for the largest share of the wearable injectors market in 2025. The rising prevalence of conditions like rheumatoid arthritis, psoriasis, and Crohn's disease requiring regular biologic administration has fueled demand for self-administered, non-invasive delivery systems. Wearable injectors enhance treatment adherence, reduce hospital visits, and improve quality of life. For example, AbbVie's Skyrizi, indicated for plaque psoriasis and Crohn's disease, reflects this patient-centric shift. Additionally, the increasing number of biologic approvals and pipeline therapies in autoimmune care is boosting demand for advanced drug delivery devices.

Wearable Injectors Market, By End User

Homecare settings accounted for the largest share of the wearable injectors market in 2025. The growing shift toward home-based treatment for chronic diseases such as diabetes, cancer, and autoimmune disorders has significantly boosted adoption. Wearable injectors enable patients to self-administer large-volume biologics and other therapies conveniently, reducing the need for frequent hospital visits while maintaining treatment adherence. Rising healthcare costs, coupled with the preference for outpatient and remote care, are further accelerating this trend. In developed markets like the US, Germany, and Japan, strong healthcare infrastructure, high patient awareness, and reimbursement support have strengthened the uptake of wearable injectors in homecare settings.

REGION

Asia Pacific to be fastest-growing region in global wearable injectors market during forecast period

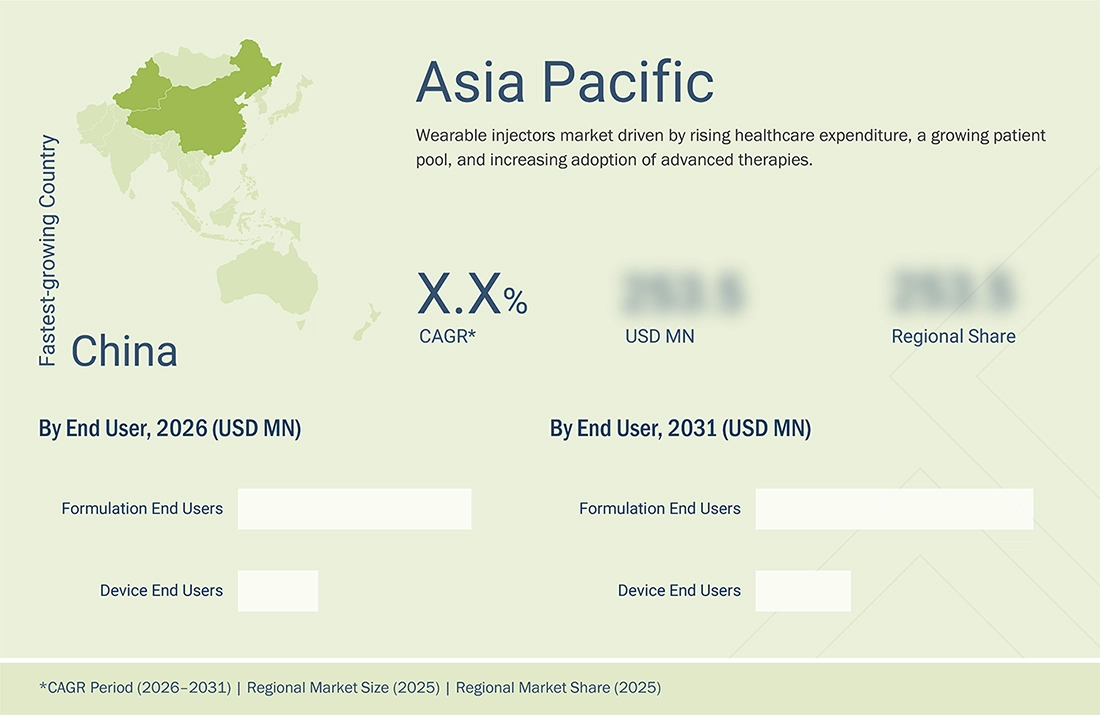
Asia Pacific is expected to grow at the highest CAGR globally during the forecast period. This growth is primarily driven by the increasing prevalence of chronic diseases such as diabetes, cancer, and cardiovascular conditions in the region. The aging population further contributes to this trend. Countries like China, India, and Southeast Asia are investing heavily in healthcare, which supports the development of hospitals, clinics, and other healthcare facilities. Supportive government policies and regulations also play a vital role in this regional segment's growth.

wearable-injector-market Region

WEARABLE INJECTORS MARKET: COMPANY EVALUATION MATRIX

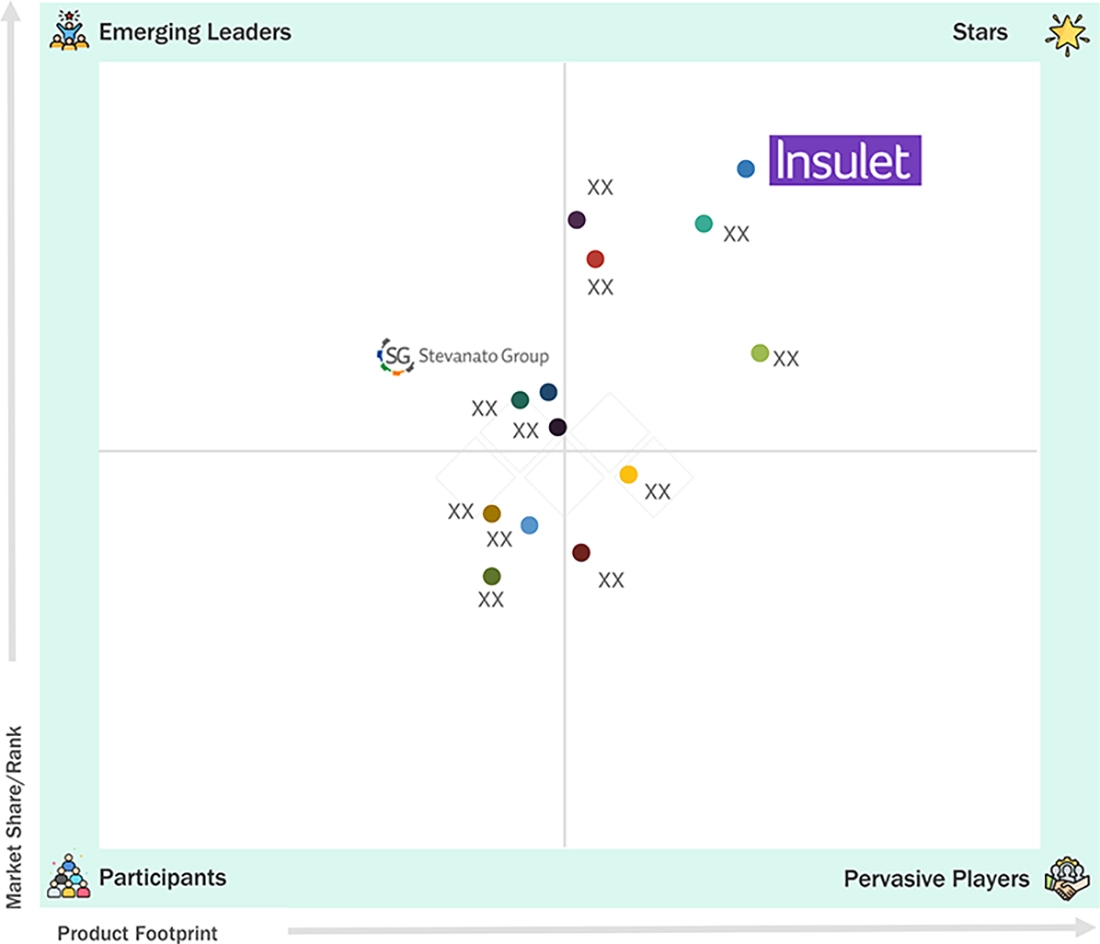
In the wearable injectors market matrix, Insulet (Star) leads with a strong market share and product footprint, driven by its advanced equipment and technologies. Stevanato Group (Emerging Leader) is gaining ground with innovative and cost-effective drug delivery solutions, strengthening its position through innovation and niche clinical applications.

wearable-injector-market Evaluation Metrics

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

KEY MARKET PLAYERS

MARKET SCOPE

REPORT METRIC DETAILS
Market Size in 2025 (Value) USD 11.3 Billion
Market Forecast in 2026 (Value) USD 12.6 Billion
Market Forecast in 2031 (Value) USD 21.0 Billion
Growth Rate 10.80%
Years Considered 2024-2031
Base Year 2025
Forecast Period 2026-2031
Units Considered Value (USD Million/Billion), Volume (Thousand Units)
Report Coverage Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments Covered
  • By Product:
    • On-Body Wearable Injector
    • Off-Body Wearable Injector
  • By Therapeutic Application:
    • Diabetes
    • Oncology
    • Autoimmune Diseases
    • Cardiovascular Diseases
    • Infectious Diseases
    • Rare/Orphan Diseases
    • Other Therapeutic Applications
  • By Delivery Method:
    • Bolus-Only
    • Programmed/Continuous Infusion
  • By Usage:
    • Disposable
    • Reusable
  • By Technology:
    • Spring-Based Technology
    • Motor-Driven Technology
    • Rotary Pump Technology
    • Expanding Battery Technology
    • Other Technologies
  • By End User:
    • Formulation End Users
    • Device End Users
Regions Covered North America, Asia Pacific, Europe, Latin America, the Middle East & Africa

WHAT IS IN IT FOR YOU: WEARABLE INJECTORS MARKET REPORT CONTENT GUIDE

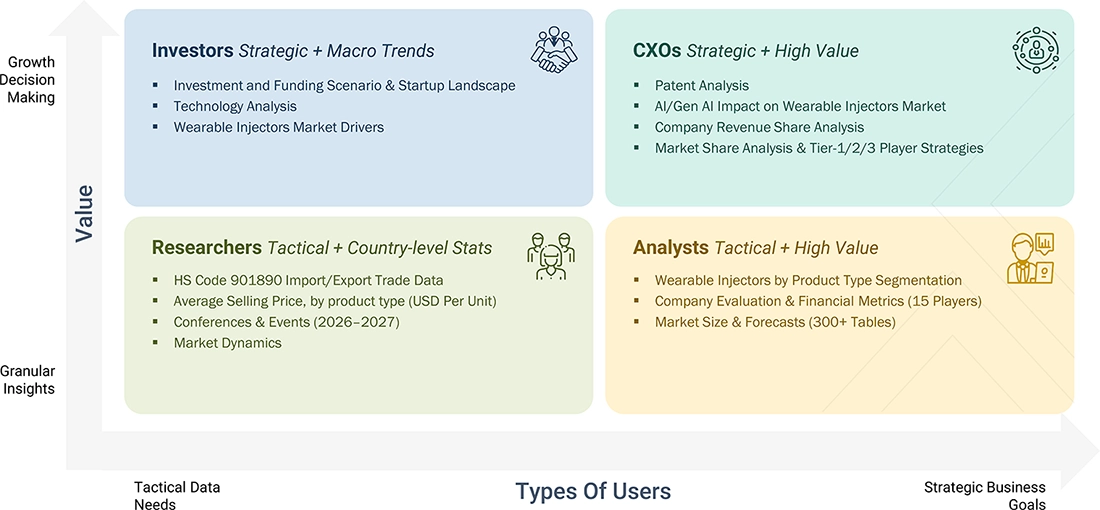
wearable-injector-market Content Guide

DELIVERED CUSTOMIZATIONS

We have successfully delivered the following deep-dive customizations:

CLIENT REQUEST CUSTOMIZATION DELIVERED VALUE ADDS
Product Analysis In-depth assessment of the wearable injectors market, by product (on-body wearable injectors and off-body wearable injectors), by therapeutic application (diabetes, oncology, autoimmune diseases, cardiovascular diseases, infectious diseases, rare/orphan diseases, and other therapeutic applications), by delivery method (bolus-only and programmed/continuous infusion), by usage (disposable and reusable), by technology (spring-based technology, motor-driven technology, rotary pump technology, expanding battery technology, and other technologies), and by end user (formulation end users and device end users), along with evaluation of drug-delivery efficiency, patient convenience, self-administration capabilities, and treatment adherence.
  • Identify interconnections and supply chain blind spots
  • Detect customer migration trends across industries.
Company Information Comprehensive profiles of leading global players such as Insulet Corporation (US), Medtronic (Ireland), Tandem Diabetes Care, Inc. (US), Amgen Inc. (US), AbbVie Inc. (US), and other partners. Insights on revenue shifts towards emerging therapeutic applications and device innovations.
Geographic Analysis Region- and country-level demand mapping across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa; evaluation of regulatory frameworks, biologics adoption, pricing dynamics, and healthcare infrastructure. Country-level demand mapping for product launches and localization strategy planning.

RECENT DEVELOPMENTS

  • January 2026 : In January 2026, West Pharmaceutical Services announced an agreement to transfer the manufacturing and supply rights for its SmartDose 3.5 mL on-body delivery system and associated facilities to AbbVie for USD 112.5 million. West completed the transaction in July 2026 and retained its development and manufacturing activities for other SmartDose configurations, including the 10 mL platform.
  • January 2026 : In January 2026, LTS Device Technologies collaborated with Stevanato Group and Datwyler to expand on-body delivery options for large-volume drugs. The collaboration combines LTS's wearable device technology with drug-containment and elastomer-component capabilities to support subcutaneous administration of higher-dose therapies, including monoclonal antibodies and anticancer treatments.
  • April 2025 : Medtronic received US FDA approval for the Simplera Sync sensor for use with the MiniMed 780G system. With this approval, the MiniMed 780G system offers more flexibility for users of the company's advanced insulin delivery system, featuring Meal Detection technology with the Guardian 4 sensor and the Simplera Sync sensor.


Table of Contents

checkmarkExclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.

TITLE
PAGE NO
1
INTRODUCTION


15
2
EXECUTIVE SUMMARY


3
PREMIUM INSIGHTS


4
MARKET OVERVIEW
Outlines emerging trends, technology impact, and regulatory signals affecting growth trajectory and stakeholder decisions.


4.1
INTRODUCTION


4.2
MARKET DYNAMICS


4.2.1
DRIVERS


4.2.2
RESTRAINTS


4.2.3
OPPORTUNITIES


4.2.4
CHALLENGES


4.3
UNMET NEEDS AND WHITE SPACES


4.4
INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES


4.5
STRATEGIC MOVES BY TIER-1/2/3 PLAYERS


5
INDUSTRY TRENDS
This section summarizes market dynamics, key shifts, and high-impact trends shaping demand outlook.


5.1
PORTER’S FIVE FORCES ANALYSIS


5.2
MACROECONOMIC INDICATORS


5.2.1
INTRODUCTION


5.2.2
GDP TRENDS AND FORECAST


5.2.3
TRENDS IN GLOBAL HEALTHCARE INDUSTRY


5.2.4
TRENDS IN GLOBAL MEDICAL DEVICE INDUSTRY


5.3
SUPPLY CHAIN ANALYSIS


5.4
VALUE CHAIN ANALYSIS


5.5
ECOSYSTEM ANALYSIS


5.6
PRICING ANALYSIS


5.6.1
AVERAGE SELLING PRICE TREND OF KEY PLAYERS, BY PRODUCT TYPE (2023-2025)


5.6.2
AVERAGE SELLING PRICE TREND, BY REGION (2023-2025)


5.7
TRADE ANALYSIS


5.7.1
IMPORT SCENARIO (HS CODE 901890)


5.7.2
EXPORT SCENARIO (HS CODE 901890)


5.8
KEY CONFERENCES AND EVENTS, 2026–2027


5.9
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS


5.10
INVESTMENT AND FUNDING SCENARIO


5.11
SUCCESS STORIES AND REAL-WORLD APPLICATIONS


5.12
IMPACT OF 2025 US TARIFF – WEARABLE INJECTORS MARKET


5.12.1
INTRODUCTION


5.12.2
KEY TARIFF RATES


5.12.3
PRICE IMPACT ANALYSIS


5.12.4
IMPACT ON COUNTRIES/REGIONS


5.12.5
IMPACT ON END-USE INDUSTRIES
 
 
6
TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS


6.1
KEY EMERGING TECHNOLOGIES


6.1.1
MICRO-MEMS AND BIO-MEMS IN WEARABLE INJECTORS


6.1.2
ELECTROMECHANICAL DRIVE SYSTEMS (MOTORIZED PUMPS)


6.2
COMPLEMENTARY TECHNOLOGIES


6.2.1
SMARTPHONE AND APP INTERFACES


6.2.2
IOT AND SMART ANALYTICS IN WEARABLE INJECTORS


6.3
ADJACENT TECHNOLOGIES


6.3.1
ELECTROCHEMICAL APTAMER BIOSENSORS


6.4
TECHNOLOGY/PRODUCT ROADMAP


6.5
PATENT ANALYSIS


6.6
FUTURE APPLICATIONS


6.7
IMPACT OF AI/GEN AI ON WEARABLE INJECTORS MARKET


6.7.1
TOP USE CASES AND MARKET POTENTIAL


6.7.2
BEST PRACTICES IN WEARABLE INJECTORS MARKET


6.7.3
CASE STUDIES OF AI IMPLEMENTATION IN WEARABLE INJECTORS MARKET


6.7.4
INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS


6.7.5
CLIENTS’ READINESS TO ADOPT GENERATIVE AI IN WEARABLE INJECTORS MARKET
 
 
7
SUSTAINABILITY AND REGULATORY FRAMEWORK


7.1
REGIONAL REGULATIONS AND COMPLIANCE


7.1.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


7.1.2
INDUSTRY STANDARDS


7.2
REGIONAL REIMBURSEMENT SCENARIO


7.2.1
REIMBURSEMENT SCENARIO FOR WEARABLE INJECTORS MARKET.


7.3
SUSTAINABILITY IMPACT AND REGULATORY POLICY INITIATIVES


7.4
CERTIFICATIONS, LABELING, ECO-STANDARDS


8
CUSTOMER LANDSCAPE & BUYER BEHAVIOR


8.1
DECISION-MAKING PROCESS


8.2
BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA


8.3
ADOPTION BARRIERS & INTERNAL CHALLENGES


8.4
UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES


8.5
MARKET PROFITABILITY


9
WEARABLE INJECTORS MARKET, BY PRODUCT (MARKET SIZE & FORECAST TO 2031 – IN VALUE, USD MILLION & VOLUME IN UNITS)


9.1
INTRODUCTION


9.2
ON-BODY WEARABLE INJECTORS


9.3
OFF-BODY WEARABLE INJECTORS


10
WEARABLE INJECTORS MARKET, BY DELIVERY METHOD (MARKET SIZE & FORECAST TO 2031 – IN VALUE, USD MILLION)


10.1
INTRODUCTION


10.2
PROGRAMMED/CONTINUOUS INFUSION


10.3
BOLUS-ONLY


11
WEARABLE INJECTORS MARKET, BY THERAPEUTIC APPLICATION (MARKET SIZE & FORECAST TO 2031 – IN VALUE, USD MILLION)


11.1
INTRODUCTION


11.2
AUTOIMMUNE DISEASES


11.3
DIABETES


11.4
ONCOLOGY


11.5
CARDIOVASCULAR DISEASES


11.6
INFECTIOUS DISEASES


11.7
RARE/ORPHAN DISEASES


11.8
OTHER THERAPEUTIC APPLICATIONS


NOTE: OTHER THERAPEUTIC APPLICATIONS INCLUDE PAIN MANAGEMENT, NEUROLOGICAL DISEASES SUCH AS PARKINSON’S DISEASE, ALZHEIMER'S DISEASE, BLOOD DISORDERS (THALASSEMIA, HEMOPHILIA) AND PRIMARY IMMUNODEFICIENCY DISORDERS.


12
WEARABLE INJECTORS MARKET, BY TECHNOLOGY (MARKET SIZE & FORECAST TO 2031 – IN VALUE, USD MILLION)


12.1
INTRODUCTION


12.2
SPRING-BASED TECHNOLOGY


12.3
MOTOR-DRIVEN TECHNOLOGY


12.4
ROTARY PUMP TECHNOLOGY


12.5
EXPANDING BATTERY TECHNOLOGY


12.6
OTHER TECHNOLOGIES


NOTE: OTHER TECHNOLOGIES INCLUDE OSMOTIC TECHNOLOGY AND GAS PUMP TECHNOLOGY.


13
WEARABLE INJECTORS MARKET, BY USAGE (MARKET SIZE & FORECAST TO 2031 – IN VALUE, USD MILLION)


13.1
INTRODUCTION


13.2
DISPOSABLE


13.3
REUSABLE


14
WEARABLE INJECTORS MARKET, BY END USER (MARKET SIZE & FORECAST TO 2031 – IN VALUE, USD MILLION)


14.1
INTRODUCTION


14.2
WEARABLE FORMULATION END USERS


14.2.1
HOME CARE SETTINGS


14.2.2
HOSPITALS & CLINICS


14.2.3
SPECIALTY INFUSION CENTERS/AMBULATORY SURGERY CENTERS


14.2.4
OTHER FORMULATION END USERS


14.3
WEARABLE INJECTOR DEVICE END USERS


14.3.1
PHARMACEUTICAL COMPANIES


14.3.1
BIOTECHNOLOGY COMPANIES


14.3.1
CONTRACT DEVELOPMENT & MANUFACTURING ORGANIZATIONS


NOTE: OTHER FORMULATION END USERS INCLUDE CLINICAL RESEARCH, ACADEMIC & RESEARCH INSTITUTIONS, AND OTHER HEALTHCARE PROVIDERS, AMONG OTHERS


15
WEARABLE INJECTORS MARKET, BY REGION (MARKET SIZE & FORECAST TO 2031 – IN VALUE, USD MILLION & VOLUME IN UNITS)


15.1
INTRODUCTION


15.2
NORTH AMERICA


15.2.1
NORTH AMERICA: VOLUME ANALYSIS, 2024–2031 (UNITS)


15.2.2
MACROECONOMIC OUTLOOK FOR NORTH AMERICA


15.2.3
US


15.2.4
CANADA


15.3
EUROPE


15.3.1
EUROPE: VOLUME ANALYSIS, 2024–2031 (UNITS)


15.3.2
MACROECONOMIC OUTLOOK FOR EUROPE


15.3.3
GERMANY


15.3.4
UK


15.3.5
FRANCE


15.3.6
ITALY


15.3.7
SPAIN


15.3.9
REST OF EUROPE


15.4
ASIA PACIFIC


15.4.1
ASIA PACIFIC: VOLUME ANALYSIS, 2024–2031 (UNITS)


15.4.2
MACROECONOMIC OUTLOOK FOR ASIA PACIFIC


15.4.3
JAPAN


15.4.4
CHINA


15.4.5
INDIA


15.4.6
AUSTRALIA


15.4.7
SOUTH KOREA


15.4.8
REST OF ASIA PACIFIC


15.5
LATIN AMERICA


15.5.1
LATIN AMERICA: VOLUME ANALYSIS, 2024–2031 (UNITS)


15.5.2
MACROECONOMIC OUTLOOK FOR LATIN AMERICA


15.5.3
BRAZIL


15.5.4
MEXICO


15.5.5
REST OF LATIN AMERICA


15.6
MIDDLE EAST & AFRICA


15.6.1
MIDDLE EAST & AFRICA: VOLUME ANALYSIS, 2024–2031 (UNITS)


15.6.2
MACROECONOMIC OUTLOOK FOR MIDDLE EAST & AFRICA


15.6.3
GCC COUNTRIES


15.6.3.1
KINGDOM OF SAUDI ARABIA (KSA)


15.6.3.2
UNITED ARAB EMIRATES (UAE)


15.6.3.3
OTHER GCC COUNTRIES


15.6.4
REST OF MIDDLE EAST & AFRICA


NOTE: REST OF EUROPE INCLUDES RUSSIA, PORTUGAL, POLAND, FINLAND, DENMARK, BELGIUM, AUSTRIA, ICELAND, IRELAND, NORWAY, AND LUXEMBOURG


NOTE: REST OF ASIA PACIFIC INCLUDES BANGLADESH, BHUTAN, NEPAL, SRI LANKA, PHILIPPINES, SINGAPORE, VIETNAM, TAIWAN, CAMBODIA, AND INDONESIA


NOTE: REST OF LATIN AMERICA INCLUDES COLOMBIA, ECUADOR, PERU, URUGUAY, CUBA, AND CHILE


NOTE: REST OF GCC INCLUDES BAHRAIN, KUWAIT, QATAR, AND OMAN


NOTE: REST OF MIDDLE EAST INCLUDES ISRAEL, IRAN, IRAQ, JORDAN, YEMEN, AND OTHER COUNTRIES


16
COMPETITIVE LANDSCAPE


16.1
OVERVIEW


16.2
KEY PLAYER STRATEGIES/RIGHT TO WIN


16.3
REVENUE SHARE ANALYSIS OF KEY PLAYERS (2021-2025)


16.4
GLOBAL WEARABLE INJECTORS MARKET SHARE ANALYSIS,


16.4.1
US MARKET SHARE ANALYSIS,


16.4.2
EUROPE MARKET SHARE ANALYSIS,


16.6
BRAND/PRODUCT COMPARISON


16.7
COMPANY EVALUATION MATRIX: KEY PLAYERS,


16.7.1
STARS


16.7.2
EMERGING LEADERS


16.7.3
PERVASIVE PLAYERS


16.7.4
PARTICIPANTS


16.7.5
COMPANY FOOTPRINT: KEY PLAYERS,


16.7.5.1
COMPANY FOOTPRINT


16.7.5.2
REGION FOOTPRINT


16.7.5.3
PRODUCT FOOTPRINT


16.7.5.4
MODALITY FOOTPRINT


16.7.5.5
USAGE FOOTPRINT
 
 
16.8
COMPANY EVALUATION MATRIX: STARTUPS/SMES,


16.8.1
PROGRESSIVE COMPANIES


16.8.2
RESPONSIVE COMPANIES


16.8.3
DYNAMIC COMPANIES


16.8.4
STARTING BLOCKS


16.8.5
COMPETITIVE BENCHMARKING: STARTUPS/SMES,


16.8.5.1
DETAILED LIST OF KEY STARTUPS/SMES


16.8.5.2
COMPETITIVE BENCHMARKING OF STARTUPS/SMES
 
 
16.9
COMPANY VALUATION AND FINANCIAL METRICS


16.10
COMPETITIVE SCENARIO


16.10.1
PRODUCT LAUNCHES


16.10.2
DEALS


16.10.3
EXPANSIONS


16.10.4
OTHER DEVELOPMENTS
 
 
17
COMPANY PROFILES


17.1
WEARABLE INJECTORS DEVICE MANUFACTURERS


17.2
KEY PLAYERS


17.2.1
INSULET CORPORATION


17.2.2
TANDEM DIABETES CARE, INC.


17.2.3
MEDTRONIC


17.2.4
BD


17.2.5
WEST PHARMACEUTICAL SERVICES, INC.


17.2.6
GERRESHEIMER AG


17.2.7
STEVANTO


17.2.8
LTS LOHMANN THERAPIE-SYSTEME AG


17.2.9
SONCEBOZ


17.2.10
NEMERA


17.2.11
MANKIND CORPORATION


17.2.12
ENABLE INJECTIONS, INC.


17.2.13
ELCAM MEDICAL


17.3
OTHER PLAYERS


17.3.1
DEVIOTECH SA


17.3.2
MEDTUM TECHNOLOGIES INC.


17.3.3
CEQUR SIMPLICITY


17.3.4
SUBCUJECT APS


17.3.5
MICROMED CO., LTD


17.4
WEARABLE INJECTORS WITH FORMULATION MANUFACTURERS


17.4.1
AMGEN INC.


17.4.2
ABBVIE INC.


17.4.3
UNITED THERAPEUTICS CORPORATION


17.4.4
APELLIS PHARMACEUTICAL, INC.


17.4.5
SUPERNUS PHARMACEUTICALS


17.4.6
COHERUS BIOSCIENCES, INC.


17.4.7
SCPHARMACEUTICALS, INC.


NOTE: WE WILL PROFILE A TOTAL OF 25 COMPANIES, INCLUDING KEY PLAYERS AND OTHER PLAYERS. THE DETAILS ON BUSINESS OVERVIEW, FINANCIAL INFORMATION, PRODUCT PORTFOLIO, RECENT DEVELOPMENTS, AND MARKETSANDMARKETS VIEW WILL BE PROVIDED FOR KEY PLAYERS. THESE DET


18
RESEARCH METHODOLOGY


18.1
RESEARCH DATA


18.1.1
SECONDARY DATA


18.1.1.1
KEY DATA FROM SECONDARY SOURCES


18.1.2
PRIMARY DATA


18.1.2.1
KEY DATA FROM PRIMARY SOURCES


18.1.2.2
KEY PRIMARY PARTICIPANTS


18.1.2.3
BREAKDOWN OF PRIMARY INTERVIEWS


18.1.2.4
KEY INDUSTRY INSIGHTS
 
 
18.2
MARKET SIZE ESTIMATION


18.2.1
APPROACH 1: COMPANY REVENUE ANALYSIS APPROACH


18.2.2
APPROACH 2: CUSTOMER-BASED MARKET ESTIMATION


18.2.3
APPROACH 3: BOTTOM-UP APPROACH


18.2.4
APPROACH 4: TOP-DOWN APPROACH


18.2.5
APPROACH 5: PRIMARY INTERVIEWS


18.2.6
APPROACH 6: DEMAND-SIDE APPROACH


18.2.7
APPROACH 7: VOLUME DATA ANALYSIS


18.3
MARKET FORECAST APPROACH


18.3.1
SUPPLY SIDE


18.3.2
DEMAND SIDE


18.4
DATA TRIANGULATION


18.5
FACTOR ANALYSIS


18.6
RESEARCH ASSUMPTIONS


18.7
RESEARCH LIMITATIONS AND RISK ASSESSMENT


19
APPENDIX


19.1
DISCUSSION GUIDE


19.2
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL


19.3
CUSTOMIZATION OPTIONS


19.3.1
PRODUCT ANALYSIS


19.3.2
COMPANY INFORMATION


19.3.3
GEOGRAPHIC ANALYSIS


19.3.4
REGIONAL/COUNTRY LEVEL MARKET SHARE ANALYSIS


19.3.5
COUNTRY LEVEL VOLUME ANALYSIS


19.3.6
BY PRODUCT MARKET SHARE ANALYSIS (TOP 5 PLAYERS)


19.3.7
ANY CONSULTS/CUSTOM REQUIREMENTS AS PER CLIENT REQUESTS


19.4
RELATED REPORTS


19.5
AUTHOR DETAILS



Methodology

This study used both primary and secondary sources extensively. The research examined factors affecting the industry to identify segmentation types, industry trends, key players, the competitive landscape, key market dynamics, and key players' strategies.

Secondary Research

This research study used comprehensive secondary sources: directories; databases such as Bloomberg Business, Factiva, and Dun & Bradstreet; white papers; annual reports; company house documents; investor presentations; and companies' SEC filings. Secondary research was used to identify and collect information useful for an extensive, technical, market-oriented, and commercial study of the wearable injectors market. It was also used to identify key market players and classify and segment the industry based on trends to the most detailed level. Additionally, significant developments related to market and technology perspectives were noted. A database of the primary industry leaders was also created using secondary research.

Primary Research

In the primary research process, various sources from both the supply and demand sides were interviewed to obtain qualitative and quantitative information for this report. Primary sources on the supply side include project/sales/marketing/business development managers; presidents; CEOs; vice presidents; chairpersons; chief operating officers; chief strategy officers; directors; chief information officers; and chief medical information officers related to the wearable injectors market. Primary demand-side sources include healthcare professionals from hospitals, nursing care facilities, long-term health centers, and ambulatory surgery centers.

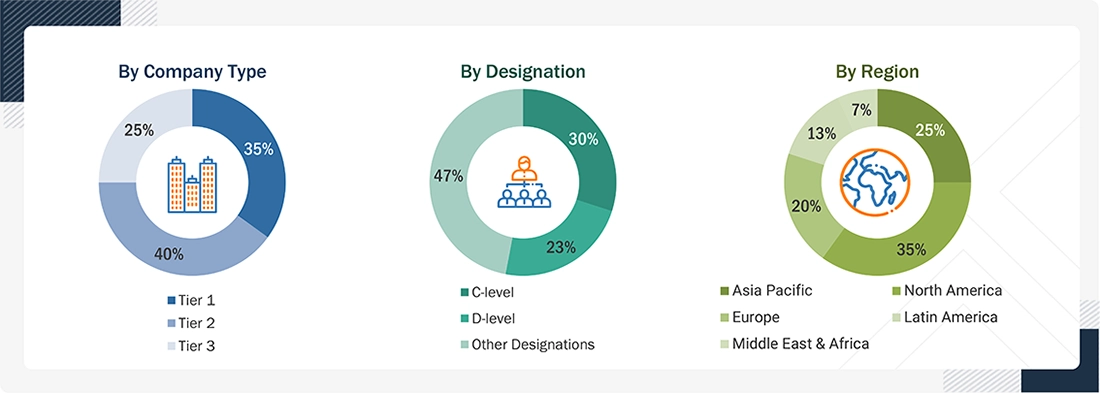
Wearable Injectors Market 
 Size, and Share

Note 1: C-level executives include CEOs, COOs, CTOs, and VPs.
Note 2: Other designations include sales, marketing, and product managers.

Note 3: Tiers are defined based on a company’s total revenue. As of 2024: Tier 1 = >USD 1 billion, Tier 2 = USD 500 million to USD 1 billion, and Tier 3 = <USD 500 million

To know about the assumptions considered for the study, download the pdf brochure

Market Size Estimation

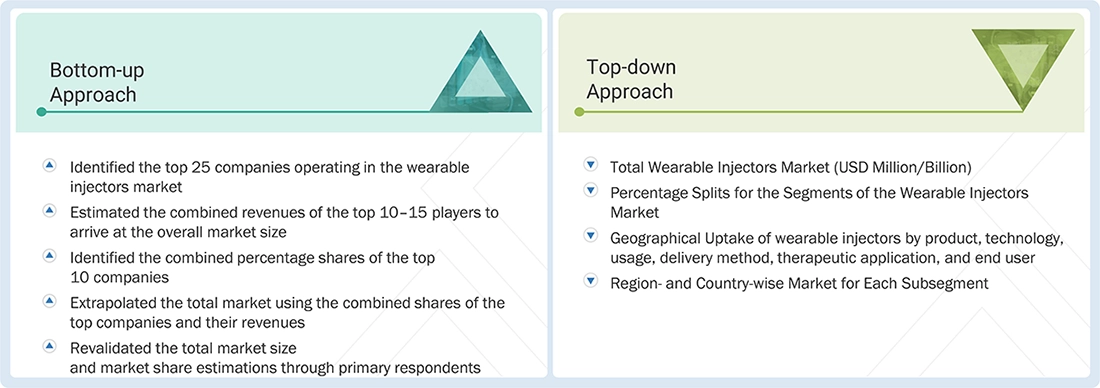
The total size of the wearable injectors market was determined by triangulating data from three approaches, as described below. After each approach, we calculated a weighted average of the three approaches based on the level of assumptions used in each.

Wearable Injectors Market Top Down and Bottom Up Approach

Data Triangulation

After arriving at the market size, the total market was divided into several segments and subsegments. Data triangulation and market breakdown procedures were used, where applicable, to complete the overall market engineering process and arrive at accurate statistics for all segments and subsegments.

Market Definition

The wearable injectors market refers to drug delivery devices that are designed to administer large-volume biologics or medications subcutaneously over an extended period, typically ranging from minutes to hours. These compact, lightweight, body-worn devices improve patient compliance by enabling self-administration outside clinical settings, particularly for chronic conditions such as diabetes, oncology, autoimmune disorders, and cardiovascular diseases. Wearable injectors are engineered to deliver high-viscosity drugs safely and accurately with minimal discomfort, reducing the need for frequent hospital visits and manual injections. The market encompasses a wide range of device types, including on-body and off-body injectors, bolus injectors, and patch pumps, powered by electromechanical or mechanical systems.

Key Stakeholders

  • Medical device manufacturers and distributors.
  • Wearable injector manufacturers
  • Wearable injectors finished formulation manufacturing companies
  • Suppliers and distributors of wearable injectors
  • Hospitals and clinics
  • Ambulatory surgery centers
  • Home healthcare agencies
  • Research and consulting firms
  • Contract manufacturing organizations
  • Venture capitalists

Report Objectives

  • To define, describe, segment, and forecast the wearable injectors market by product, technology, usage, delivery method, therapeutic application, end user, and region
  • To provide detailed information about the factors influencing market growth (such as drivers, restraints, opportunities, and challenges)
  • To analyze micromarkets with respect to individual growth trends, prospects, and contributions to the overall wearable injectors market
  • To analyze market opportunities for stakeholders and provide details of the competitive landscape for key players
  • To forecast the size of the wearable injectors market in five main regions (along with their respective key countries), namely, North America, Europe, the Asia Pacific, Latin America, and the Middle East & Africa
  • To profile the key players in the wearable injectors market and comprehensively analyze their core competencies and market shares
  • To track and analyze competitive developments such as acquisitions, product launches, expansions, collaborations, agreements, and partnerships

Available customizations:

Based on the provided market data, MarketsandMarkets offers customizations to meet your company’s specific needs. The following customization options are available for the report:

Company Information

  • Detailed analysis and profiling of additional market players (up to 5)

Geographic Analysis

  • Further breakdown of the Rest of European wearable injectors market into Austria, Finland, the Netherlands, Switzerland, and other countries
  • Further breakdown of the Rest of Latin American wearable injectors market into Colombia, Chile, and other countries

Competitive Landscape Assessment

  • Market share analysis for North America and Europe, which provides market shares of the top 3–5 key players in the wearable injectors market
  • Competitive leadership mapping for established players in the US


Key Questions Addressed by the Report

What are the opportunities in the wearable injectors market?

The wearable injectors market presents numerous opportunities, especially with the growing integration of digital health and remote monitoring technologies. Additionally, emerging markets such as China, India, and Brazil offer promising avenues for growth, attracting the interest of stakeholders and manufacturers.

Which segments have been included in this report?

This report includes several key segments based on product, technology, usage, delivery method, therapeutic application, end user, and region.

Which are the top players in the wearable injectors market?

The leading companies in the global wearable injectors market include Insulet Corporation, Medtronic, Tandem Diabetes Care, Inc., BD, and West Pharmaceutical Services.

What are the factors expected to pose a challenge to the growth of the wearable injectors market?

One of the main challenges anticipated to hinder market growth is the lack of proper training and education among users for operating wearable injectors effectively.

How big is the global wearable injectors market today?

The wearable injectors market is projected to grow from USD 11,332.6 million in 2025 to USD 18,916.4 million by 2030, registering a compound annual growth rate (CAGR) of 10.8% during the forecast period.

Personalize This Research

  • Triangulate with your Own Data
  • Get Data as per your Format and Definition
  • Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
  • Any level of Personalization
Request A Free Customisation

Let Us Help You

  • What are the Known and Unknown Adjacencies Impacting the Wearable Injectors Market
  • What will your New Revenue Sources be?
  • Who will be your Top Customer; what will make them switch?
  • Defend your Market Share or Win Competitors
  • Get a Scorecard for Target Partners
Customized Workshop Request

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements

Get 10% Free Customisation

TESTIMONIALS

Growth opportunities and latent adjacency in Wearable Injectors Market

avtar

Martin

Jun, 2022

How latest advancements in technologies impacting the revenue growth of Wearable Injectors Market?.

avtar

Micah

Jun, 2022

What are the key factors driving revenue opportunities in Wearable Injectors Market?.

avtar

Anthony

Jun, 2022

Can you give some more information on demand of wearable injectors in end-user industry?.

THIS REPORT TELLS YOU

How big the Wearable Injectors market is, and who leads it.

GROWTHIQ TELLS YOU NEW

Where your company should play next, and who is taking your share.

Get your company's view of this market. Free snapshot.

DMCA.com Protection Status
popup img