



Rolling Stock Market
Report Code
AT 3235
Published in
Oct, 2026, By MarketsandMarkets™
Rolling Stock Market by Product Type, Locomotive Type (Diesel Locomotives, Hydrogen Locomotives, Battery-electric Locomotives, Electro-diesel Locomotives), Application and Region (Asia Oceania, Europe, North America, MEA, RoW) - Global Forecast to 2033

USD 43.74 BN
MARKET SIZE, 2033

CAGR 4.7%
(2026-2033)

400
REPORT PAGES

240
MARKET TABLES
OVERVIEW
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
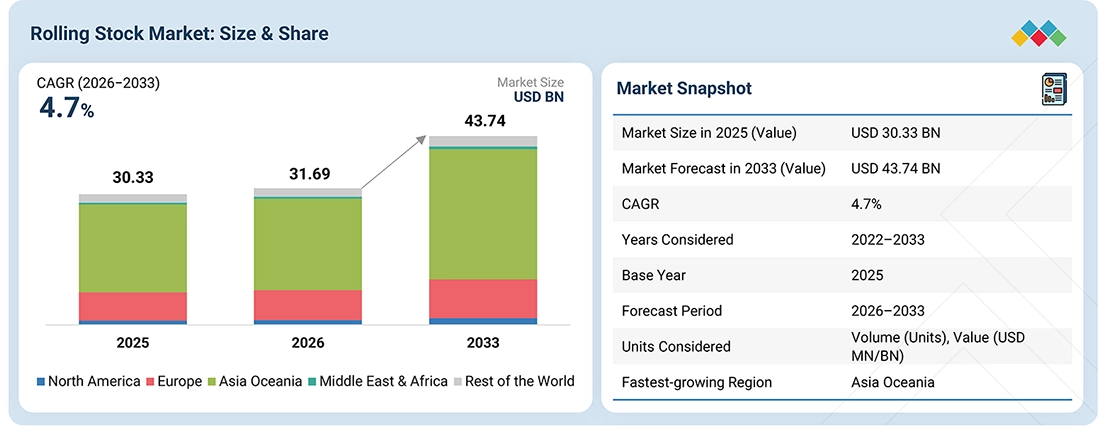
The rolling stock market is projected to grow from USD 31.69 billion in 2026 to USD 43.74 billion by 2033, at a 4.7% CAGR. Electro-diesel and full electrification are gaining traction as rail operators and governments seek to balance climate commitments, rising fuel costs, and service reliability. High-speed rail projects and urban transit expansion are increasingly being designed with electrified traction as the baseline, given its efficiency and sustainability advantages. Operators are phasing out diesel fleets not only due to emissions and air quality concerns but also to lower lifetime operating costs. Rather than a one-size-fits-all approach, the market is moving toward a multi-technology model, overhead electrification for high-density mainlines, hybrid or battery-electric solutions for regional routes, and hydrogen fuel-cell trains for non-electrified corridors. This shift marks a clear transition toward greener, more resilient rolling stock strategies that align with long-term transport modernization goals.
KEY TAKEAWAYS
-
BY PRODUCT TYPEThe rolling stock market by product type is segmented into locomotives, rapid transit, coaches, wagons, and others, with the rapid transit segment accounting for a dominant share due to rising urbanization and growing demand for metro and light rail systems worldwide.
-
BY COMPONENTRising demand for reliable, electrified rolling stock and digital maintenance solutions is driving growth in traction motors, pantographs, and train control systems, while aftermarket and refurbishment services provide steady revenue for component suppliers.
-
BY LOCOMOTIVE TECHNOLOGYAdvances in materials have made locomotive turbochargers more durable and efficient. Conventional locomotives remain popular for their reliability, cost-effectiveness, and ability to operate in areas with limited infrastructure.
-
BY APPLICATIONEconomic growth, urbanization, and industrial activities drive the demand for freight wagons. Commuter patterns, tourism, and urban planning shape demand for passenger coaches, which is further boosted by modern technologies such as Wi-Fi connectivity and real-time passenger information systems.
-
BY REGIONAsia Oceania is projected to see the fastest growth rate, driven by major investments in fleet modernization, expanded urban transit systems and a strong focus on electrification and advanced rolling stock technologies. Additionally, supportive government policies and funding for sustainable transportation further accelerate market growth in the region.
The decarbonization of non-electrified rail corridors is driving adoption of alternative traction technologies. Battery-electric trains are being deployed on short- to medium-distance routes where charging through electrified sections or fast-charge points is viable. Hydrogen fuel-cell trains offer a cost-effective solution for longer or low-traffic lines where overhead wires are impractical, provided green hydrogen supply is available. Meanwhile, hybrid diesel-battery systems and biofuels act as transitional options, enabling operators to cut emissions while moving toward fully sustainable rail operations.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
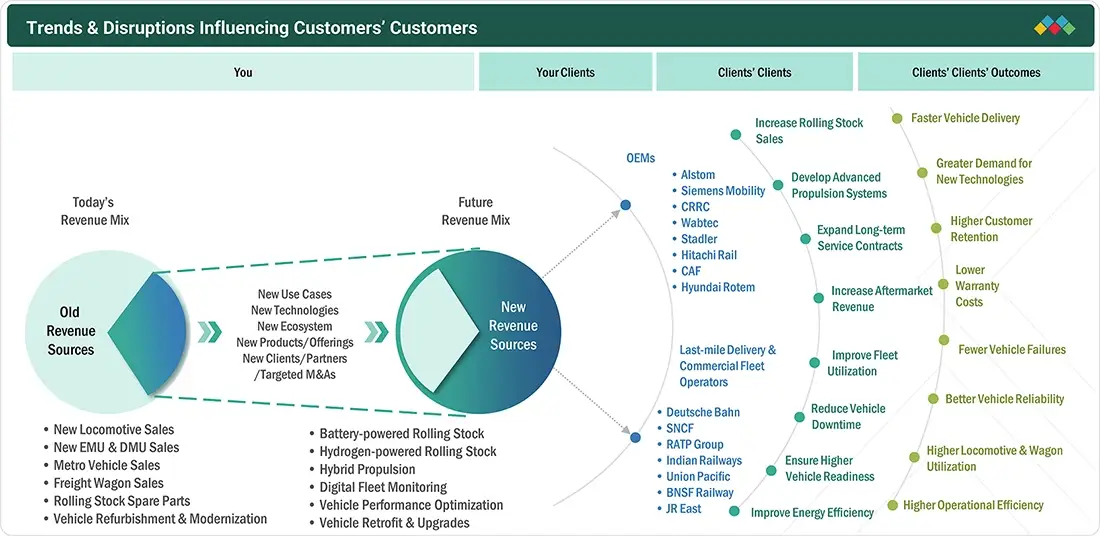
Trends and disruptions in the rolling stock market reveal the current and future trends. As the rolling stock market shifts from conventional diesel locomotives to electrified, battery-powered, and hydrogen-powered trains, new revenue pockets are emerging in alternative fuel technologies, advanced traction systems, and charging/refueling infrastructure. Growth in digital solutions, including predictive maintenance, real-time monitoring, and passenger information systems, also opens recurring service and aftermarket opportunities.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Drivers
Impact
Level
Level
-
Aging rolling stock fleets driving replacement and refurbishment demand

-
Accelerating demand for energy-efficient rolling stock


RESTRAINTS
Impact
Level
Level
-
Long procurement cycles and complex public tendering processes

-
Complex regulatory, safety, and interoperability requirements


OPPORTUNITIES
Impact
Level
Level
-
Rail electrification and AI integration creating demand for intelligent rolling stock

-
Increasing demand for driverless and automated metro trains


CHALLENGES
Impact
Level
Level
-
Navigating local content requirements and regionalized supply chains

-
Balancing customer-specific configuration with scale economies and platform standardization

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Aging rolling stock fleets driving replacement and refurbishment demand
Aging rolling stock fleets are increasing demand for fleet replacement and refurbishment, as operators seek to maintain reliability, improve efficiency, and extend vehicle service life. Investments in fleet renewal, modernization, and technology upgrades are driving demand for new trains and the refurbishment of existing locomotives, passenger vehicles, and freight wagons. The growing need to replace aging assets is supporting a sustained replacement cycle and creating new revenue opportunities across the global rolling stock market.
Restraint: Complex regulatory, safety, and interoperability requirements
Complex regulatory and interoperability requirements can increase development time and compliance costs for rolling stock manufacturers. Different technical standards, safety requirements, vehicle approval processes, and interoperability rules can complicate product development and cross-border deployment.
Opportunity: Rail electrification and AI integration creating demand for intelligent rolling stock
Rail electrification is driving demand for electric locomotives and electric multiple units as railway operators seek more efficient, modern rolling stock. The expansion of electrified networks is also encouraging fleet replacement and new procurement programs. AI and digital technologies are increasing demand for intelligent rolling stock with predictive maintenance, condition monitoring, remote diagnostics, and automated functions. This creates opportunities for manufacturers to increase vehicles' technology value and develop more advanced rolling stock solutions.
Challenge: Navigating local content requirements and regionalized supply chains
Local content requirements can increase complexity for rolling stock manufacturers, as operators and governments may expect greater local sourcing, manufacturing, and technology participation. Meeting these requirements can require manufacturers to adapt production strategies and establish local partnerships. Regionalized supply chains can also increase sourcing and coordination challenges, especially when manufacturers must manage suppliers across different markets. This can increase operational complexity and affect production timelines, making supply chain localization a key challenge for global rolling stock companies.
ROLLING STOCK MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Operates freight trains to transport automotive parts and manufactured goods across multiple European countries efficiently. | Reduces road congestion, lowers overall transport costs, and ensures timely delivery of goods across long distances. |
 |
Uses heavy-duty freight wagons to move large volumes of iron ore from remote mines to coastal ports for export. | Enables high-volume bulk transport efficiently, reduces reliance on road transport, and supports large-scale mining operations. |
 |
Operates electric multiple units (EMUs) to transport millions of daily commuters across the metropolitan area reliably. | Provides fast, energy-efficient, and reliable urban mobility while reducing traffic congestion and emissions. |
 |
Uses rail freight to transport large volumes of consumer goods from central warehouses to regional distribution hubs. | Accelerates delivery times, reduces carbon emissions compared to road transport, and optimizes long-distance logistics. |
 |
Transports chemicals and petrochemical products in specialized tank wagons safely across Europe. | Facilitates bulk movement while minimizing handling risks, ensuring safety, and maintaining product quality during transit. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
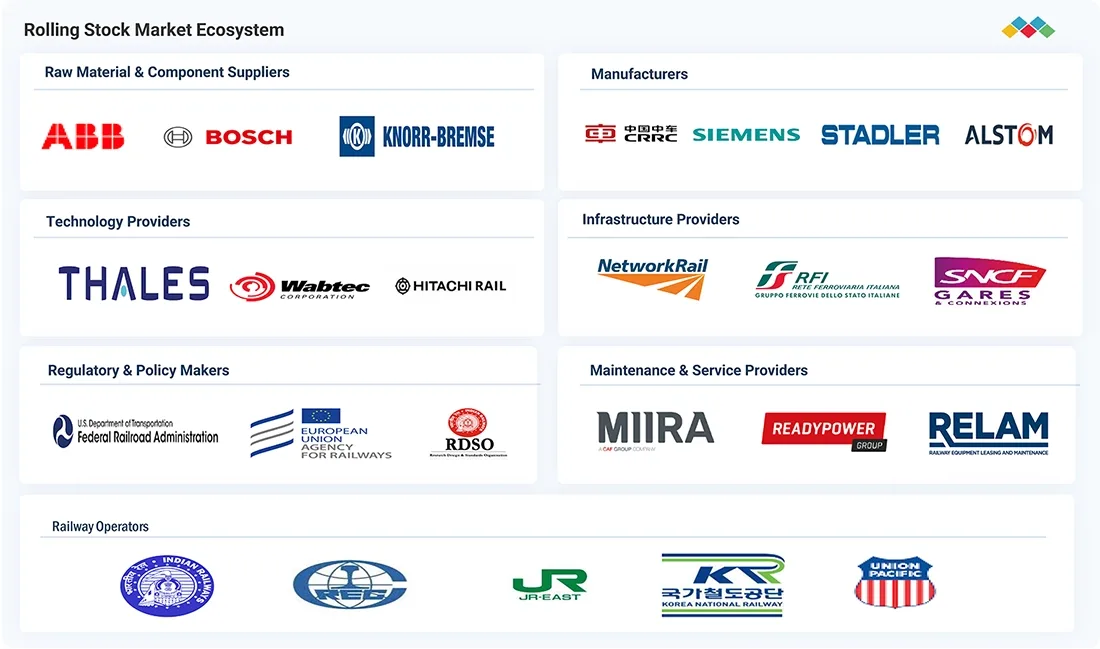
The rolling stock market ecosystem includes raw material and component suppliers, rolling stock manufacturers, technology providers, infrastructure providers, regulatory & policy makers, maintenance & service providers, and rail operators. Major rolling stock manufacturers include CRRC Corporation Limited (China), Siemens AG (Germany), Alstom SA (France), Stadler Rail AG (Switzerland), and Wabtec Corporation (US).
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
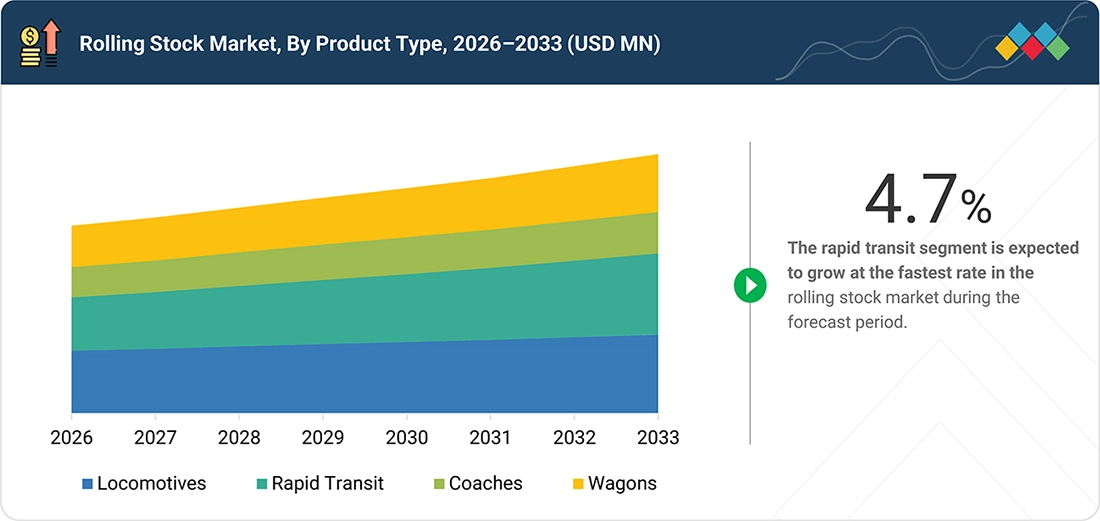
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Rolling Stock Market, By Product Type
Rapid transit is becoming an important revenue segment as cities increase metro capacity to meet rising urban passenger demand. New train procurement is being supported by metro fleet expansion, replacement of aging trainsets, and the need for higher-capacity services. At the same time, automated operation, efficient propulsion, and advanced onboard control technologies are raising the specification of rapid transit rolling stock.
Rolling Stock Market, By Locomotive Technology
Conventional locomotives dominate the market due to their reliability and compatibility with existing rail infrastructure. Electro-diesel models, such as Siemens’ Vectron Dual Mode, can operate on both electrified and non-electrified tracks and support sustainability goals with HVO fuel. Electric locomotives are increasingly adopted amid global electrification efforts.
Rolling Stock Market, By Application
The freight transportation application is expected to lead the rolling stock market. The development of dedicated freight corridors is driving demand for high-capacity locomotives and wagons, as these corridors require rolling stock built for heavier loads, longer hauls, and improved freight efficiency.
REGION
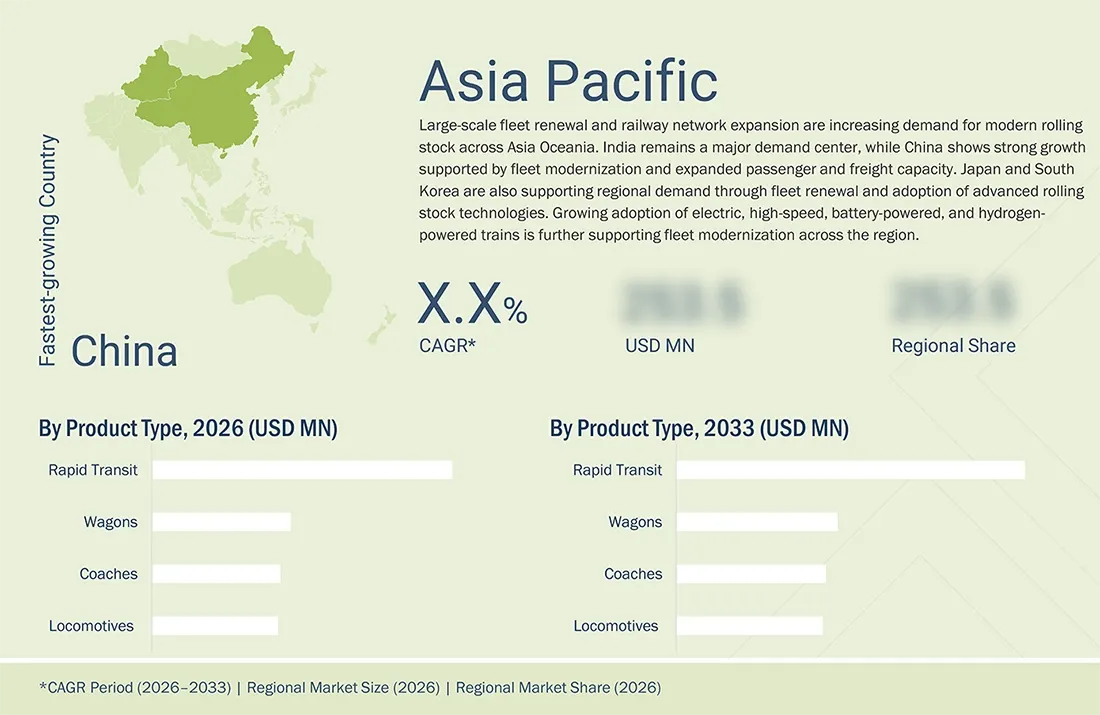
Asia Oceania to grow at fastest rate in global rolling stock market during forecast period
Asia Oceania is expected to be the major regional market for rolling stock, supported by fleet replacement, rising passenger volumes, metro procurement, and modernization of high speed and regional trains. Recent procurement activity supports this demand. India has planned to manufacture 260 Vande Bharat Sleeper trainsets, while China recorded 4.60 billion railway passenger trips in 2025, up 6.7%, supporting continued demand for modern passenger rolling stock. China has also begun delivering new fully automated metro trains for Shanghai Metro Line 22.
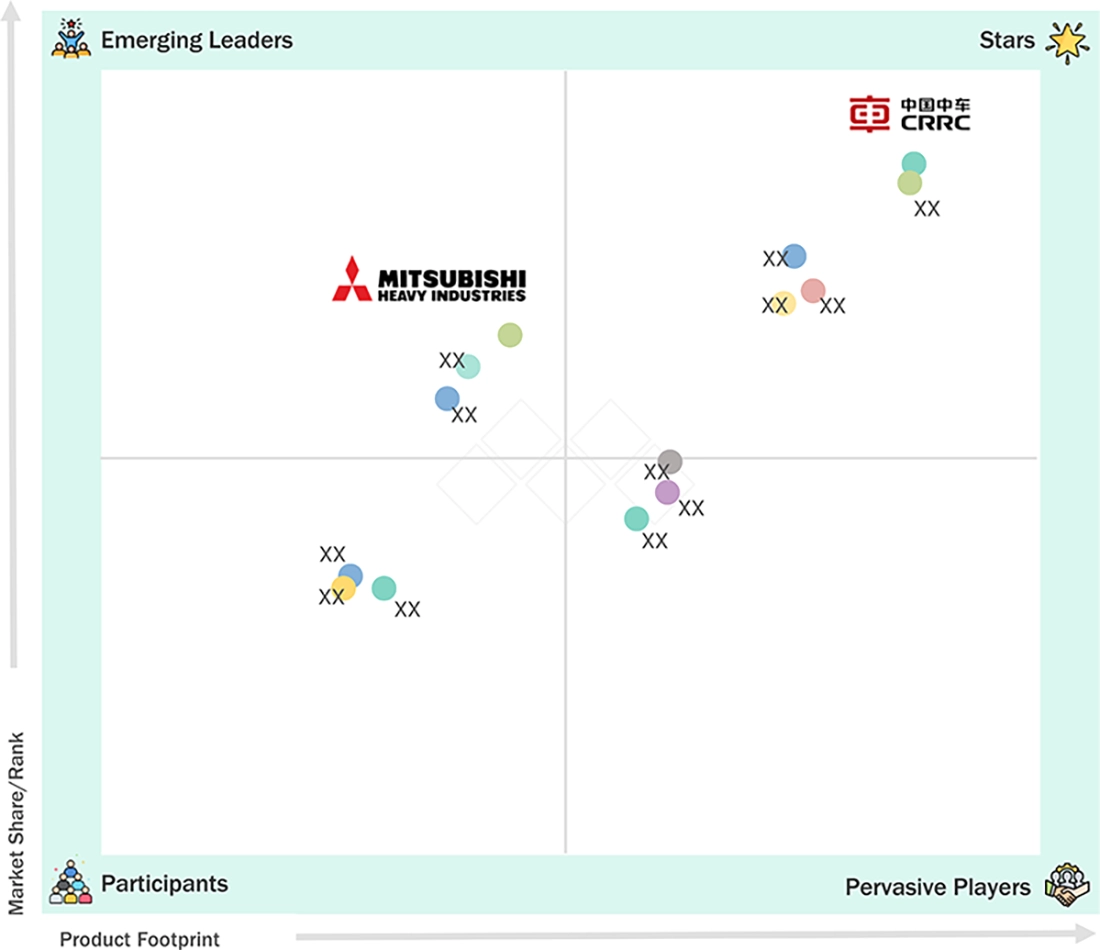
ROLLING STOCK MARKET: COMPANY EVALUATION MATRIX
In the rolling stock market matrix, CRRC Corporation Limited (Star) leads with a strong global presence and comprehensive rolling stock offerings, driving market expansion and revenue growth through strategic partnerships and supply contracts. MITSUBISHI HEAVY INDUSTRIES, LTD. (Emerging Leader) is gaining traction with advanced propulsion technologies and customized rolling stock solutions. The company shows strong growth potential to advance toward the leaders' quadrant.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- CRRC Corporation Limited (China)
- Siemens AG (Germany)
- Alstom SA (France)
- Stadler Rail AG (Switzerland)
- Wabtec Corporation (US)
- Kawasaki Heavy Industries, Ltd (Japan)
- CAF Group (Spain)
- HYUNDAI ROTEM COMPANY (South Korea)
- MITSUBISHI HEAVY INDUSTRIES, LTD. (Japan)
- Talgo (Spain)
- Transmashholding (Russia)
- Titagarh Rail Systems Limited (India)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2025 (Value) | USD 30.33 Billion |
| Market Forecast in 2026 (Value) | USD 31.69 Billion |
| Market Forecast in 2033 (Value) | USD 43.74 Billion |
| Growth Rate | CAGR of 4.7% from 2026–2033 |
| Actual Data | 2022–2033 |
| Base Year | 2025 |
| Forecast Period | 2026–2033 |
| Units Considered | Volume (Units) and Value (USD Million/Billion) |
| Report Coverage | Revenue Forecast, Company Ranking, Competitive Landscape, Growth Factors, and Trends |
| Segments Covered |
|
| Regional Scope | Asia Oceania, Europe, North America, Middle East & Africa, Rest of the World |
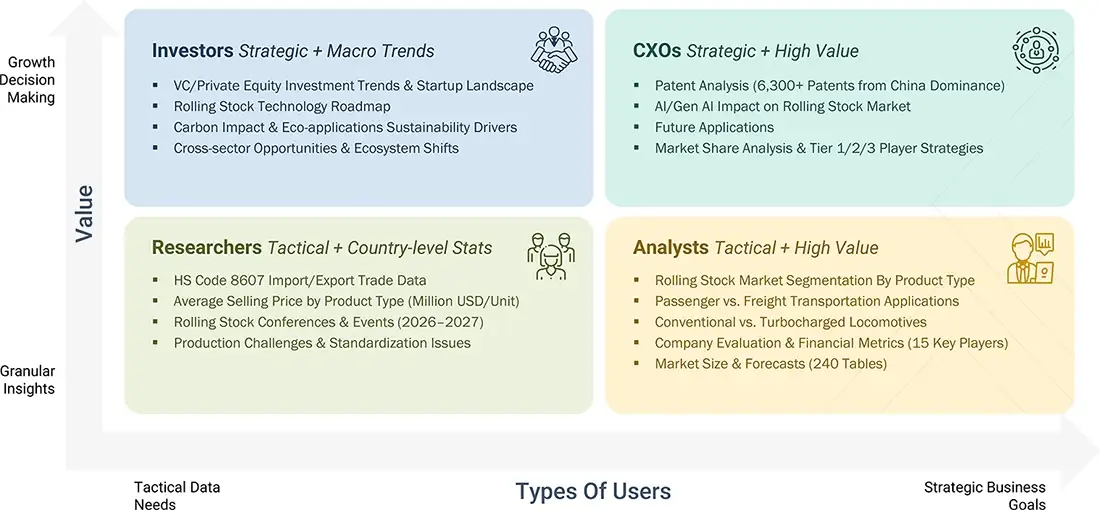
WHAT IS IN IT FOR YOU: ROLLING STOCK MARKET REPORT CONTENT GUIDE
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Global Rolling Stock OEM (Europe) | • Competitive benchmarking of CRRC, Alstom, Siemens Mobility • Product roadmap tracking for electric & hydrogen rolling stock | • Identify technology white spaces in zero-emission propulsion • Support R&D prioritization and investment strategy |
| Rail Operator (Asia Pacific) | • Fleet modernization analysis for passenger coaches and EMUs • Lifecycle cost analysis of refurbished vs. new rolling stock | • Optimize capital expenditure decisions • Extend service life and improve ROI |
| Tier-1 Component Supplier (North America) | • Partnership mapping with leading OEMs • Technology adoption study in braking, traction, and digital control systems | • Expand client base via targeted partnerships • Align product portfolio with next-gen rolling stock trends |
| Technology Provider (Global) | • Assessment of digitalization trends (IoT, predictive maintenance, CBTC) • Competitive positioning of major telematics and connectivity players | • Identify growth opportunities in smart train solutions • Build recurring revenue models through digital offerings |
RECENT DEVELOPMENTS
- June 2026 : CRRC Corporation Limited launched its Xuankun (VELFORCE) (New-energy Locomotive Platform), which covers 1,000–2,000 kW and offers diesel-battery hybrid, pure-battery, and hydrogen-fuel-cell powertrains for railway transportation applications.
- March 2026 : Siemens Mobility launched the Vectron Dual Mode Electric/Battery locomotive, a new battery-based development of the Vectron Dual Mode platform that can operate under overhead-line power and on non-electrified sections using traction batteries.
- February 2026 : Germany inaugurated its first Alstom battery trains, marking a milestone in deploying alternative-propulsion rolling stock. The battery-electric multiple units are intended to replace diesel trains on non-electrified lines and support rail decarbonization.
- September 2025 : San Bernardino County launched ZEMU, the first self-powered hydrogen-battery passenger train in the US, built by Stadler. It will enter zero-emission service on the Arrow Corridor, showcasing Stadler’s deployment of hydrogen multiple units in North America.
- July 2025 : Wabtec acquired Bloom Engineering, a company specializing in heat transfer and combustion technology, for USD 69 million. This acquisition expands Wabtec’s energy solutions portfolio, supporting more efficient and lower-emission power and heating systems applicable in rail manufacturing and maintenance facilities.
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
TITLE
PAGE NO
1
INTRODUCTION
15
2
EXECUTIVE SUMMARY
3
PREMIUM INSIGHTS
4
MARKET OVERVIEW
This section summarizes market dynamics, key shifts, and high-impact trends shaping demand outlook.
4.1
INTRODUCTION
4.2
MARKET DYNAMICS
4.2.1
DRIVERS
4.2.1.1
LIFECYCLE ECONOMICS SHIFTING ROLLING STOCK PROCUREMENT TOWARD PERFORMANCE-BASED MODELS
4.2.1.2
FREIGHT & PASSENGER CAPACITY EXPANSION DRIVING HIGHER-PERFORMANCE ROLLING STOCK
4.2.1.3
AGING ROLLING STOCK FLEETS DRIVING REPLACEMENT AND REFURBISHMENT DEMAND
4.2.1.4
ACCELERATING DEMAND FOR ENERGY-EFFICIENT ROLLING STOCK
4.2.2
RESTRAINTS
4.2.2.1
HIGH UPFRONT CAPITAL REQUIREMENTS AND LONG PAYBACK PERIODS
4.2.2.2
LONG PROCUREMENT CYCLES AND COMPLEX PUBLIC TENDERING PROCESSES
4.2.2.3
COMPLEX REGULATORY, SAFETY, AND INTEROPERABILITY REQUIREMENTS
4.2.3
OPPORTUNITIES
4.2.3.1
RAIL ELECTRIFICATION AND AI INTEGRATION CREATING DEMAND FOR INTELLIGENT ROLLING STOCK
4.2.3.2
EXPANSION OF LIFECYCLE AND AFTERMARKET SERVICES BEYOND NEW TRAIN SALES
4.2.3.3
INCREASING DEMAND FOR DRIVERLESS AND AUTOMATED METRO TRAINS
4.2.4
CHALLENGES
4.2.4.1
NAVIGATING LOCAL CONTENT REQUIREMENTS AND REGIONALIZED SUPPLY CHAINS
4.2.4.2
BALANCING CUSTOMER-SPECIFIC CONFIGURATION WITH SCALE ECONOMIES AND PLATFORM STANDARDIZATION
4.3
UNMET NEEDS & WHITE SPACES
4.4
INTERCONNECTED MARKETS & CROSS-SECTOR OPPORTUNITIES
4.5
STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5
INDUSTRY TRENDS
Provides a snapshot of current market scenario, value chain context, and factors impacting competitive intensity.
5.1
MACROECONOMIC INDICATORS
5.1.1.1
INTRODUCTION
5.1.1.2
GDP TRENDS & FORECAST
5.1.1.3
TRENDS IN RAIL INFRASTRUCTURE INDUSTRY
5.1.1.4
TRENDS IN GLOBAL RAILWAY INDUSTRY
5.2
SUPPLY CHAIN ANALYSIS
5.3
ECOSYSTEM ANALYSIS
5.4
PRICING ANALYSIS
5.4.1
INDICATIVE PRICING OF ROLLING STOCK OFFERED BY KEY PLAYERS
5.4.2
AVERAGE SELLING PRICE TREND, BY PRODUCT TYPE
5.4.3
AVERAGE SELLING PRICE TREND, BY REGION
5.5
TRADE ANALYSIS
5.5.1
IMPORT SCENARIO (HS CODE 8603)
5.5.2
EXPORT SCENARIO (HS CODE 8603)
5.6
KEY CONFERENCES & EVENTS, 2026–2027
5.7
TRENDS/DISRUPTIONS IMPACTING CUSTOMERS’ BUSINESSES
5.8
INVESTMENT & FUNDING SCENARIO
5.9
CASE STUDY ANALYSIS
5.9.1.1
LEASING BATTERY TRAINS TO REDUCE UPFRONT PROCUREMENT COSTS
5.9.1.2
DEPLOYING HYDROGEN TRAINS ON NON-ELECTRIFIED ROUTES
5.9.1.3
INTEGRATING FUEL CELLS FOR ZERO-EMISSION TRAIN OPERATIONS
5.9.1.4
DEPLOYING AUTOMATED METRO TRAINS AND DIGITAL SIGNALING
5.9.1.5
DEPLOYING HIGH-CAPACITY DOUBLE-DECK TRAINS FOR REGIONAL TRANSPORT
5.10
REGIONAL INVESTMENT HOTSPOTS: FLEET MODERNIZATION, LOCAL MANUFACTURING, AND ALTERNATIVE PROPULSION
5.10.1.1
FLEET MODERNIZATION INVESTMENT
5.10.1.2
LOCAL MANUFACTURING INVESTMENT
5.10.1.3
ALTERNATIVE PROPULSION INVESTMENT
5.10.1.4
REGIONAL INVESTMENT HOTSPOT COMPARISON
5.11
CAPEX OPTIMIZATION FOR OPERATORS: INVESTMENT IN NEW ROLLING STOCK VS. FLEET REFURBISHMENT
5.11.1
FLEET LIFECYCLE STAGE
5.11.1.1
NEW BUILD
5.11.1.2
MID-LIFE UPGRADE
5.11.1.3
REFURBISHMENT
5.11.1.4
LIFE EXTENSION
5.11.1.5
REPLACEMENT
5.11.2
CAPEX OPTIMIZATION
5.12
COMPETITIVE COMPARISON MATRIX: ROLLING STOCK OEM STRATEGIES
5.12.1.1
BY PROPULSION
5.12.1.2
BY APPLICATION
5.12.1.3
BY ROLLING STOCK PLATFORM ARCHITECTURE
5.13
DIGITALIZATION OF ROLLING STOCK: PREDICTIVE MAINTENANCE, CONDITION MONITORING, AND DIGITAL TWINS
5.13.1.1
CONDITION MONITORING
5.13.1.2
DIGITAL TWINS
5.13.1.3
DIGITAL CAPABILITIES OF MAJOR ROLLING STOCK OEMS
5.14
DIESEL TO LOW-EMISSION ROLLING STOCK TRANSITION
5.14.1.1
DIESEL FLEET REPLACEMENT
5.14.1.2
NON-ELECTRIFIED ROUTE DEMAND
5.14.1.3
LOW-EMISSION ROLLING STOCK PROCUREMENT
5.14.1.4
FLEET TRANSITION ECONOMICS
5.14.1.5
REPLACEMENT MARKET OPPORTUNITY
5.15
SHIFT TOWARD LIFECYCLE REVENUE: ROLLING STOCK MAINTENANCE & ASSET-AS-A-SERVICE MODELS
5.15.1.1
LONG-TERM ROLLING STOCK MAINTENANCE CONTRACTS
5.15.1.2
ROLLING STOCK AFTERMARKET REVENUE
5.15.1.3
ASSET-AS-A-SERVICE MODELS
5.15.1.4
LIFECYCLE REVENUE OPPORTUNITY
5.15.1.5
OEM AND SUPPLIER LIFECYCLE STRATEGIES
6
TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
6.1
KEY EMERGING TECHNOLOGIES
6.1.1.1
DIGITAL AUTOMATIC COUPLING (DAC)
6.1.1.2
DIGITAL TWIN-BASED FLEET OPTIMIZATION
6.1.1.3
AUTONOMOUS TRAINS
6.1.1.4
HYBRID AND DUAL-MODE TRACTION SYSTEMS
6.1.1.5
HYDROGEN FUEL-CELL PROPULSION
6.2
COMPLEMENTARY TECHNOLOGIES
6.2.1.1
AI-BASED FAULT DETECTION & HEALTH-STATE MODELING
6.2.1.2
INTELLIGENT RAIL TRANSIT
6.2.1.3
COLLISION AVOIDANCE SYSTEMS
6.3
ADJACENT TECHNOLOGIES
6.3.1.1
FUTURE RAILWAY MOBILE COMMUNICATION SYSTEM (FRMCS)
6.3.1.2
BIG DATA ANALYTICS
6.3.1.3
RENEWABLE ENERGY SYSTEMS
6.4
TECHNOLOGY/PRODUCT ROADMAP
6.5
PATENT ANALYSIS
6.6
FUTURE APPLICATIONS
6.7
IMPACT OF AI ON ROLLING STOCK MARKET
6.7.1
KEY AI USE CASES IN ROLLING STOCK
6.7.2
AI-ENABLED PREDICTIVE MAINTENANCE & FLEET OPTIMIZATION
6.7.3
CASE STUDIES OF AI DEPLOYMENT IN ROLLING STOCK
6.7.4
AI ECOSYSTEM: OEMS, OPERATORS, TECHNOLOGY PROVIDERS, AND DEPOTS
6.7.5
OPERATOR READINESS & BARRIERS TO AI ADOPTION
7
REGULATORY LANDSCAPE & SUSTAINABILITY INITIATIVES
7.1
REGIONAL REGULATIONS & COMPLIANCE
7.1.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
7.1.2
GLOBAL EMISSION & SAFETY REGULATIONS
7.1.2.1
EMISSION STANDARDS
7.1.2.2
QUALITY CONTROL & MANUFACTURING STANDARDS
7.1.2.3
FIRE SAFETY & MATERIAL STANDARDS
7.2
SUSTAINABILITY INITIATIVES
7.3
IMPACT OF REGULATORY POLICIES ON SUSTAINABILITY INITIATIVES
8
CUSTOMER LANDSCAPE & BUYER BEHAVIOR
8.1
DECISION-MAKING PROCESS
8.2
BUYER STAKEHOLDERS & BUYING EVALUATION CRITERIA
8.3
KEY STAKEHOLDERS IN BUYING PROCESS
8.4
BUYING CRITERIA
9
ROLLING STOCK MARKET, BY PRODUCT
Market Size, Volume & Forecast – USD Million
9.1
INTRODUCTION
9.2
LOCOMOTIVES
9.2.1.1
DIESEL LOCOMOTIVES
9.2.1.2
ELECTRIC LOCOMOTIVES
9.2.1.2.1
HYDROGEN LOCOMOTIVES
9.2.1.2.2
BATTERY-ELECTRIC LOCOMOTIVES
9.2.1.3
ELECTRO-DIESEL LOCOMOTIVES
9.3
RAPID TRANSIT
9.3.1.1
DIESEL MULTIPLE UNITS
9.3.1.2
ELECTRIC MULTIPLE UNITS
9.3.1.3
LIGHT RAILS/TRAMS
9.3.1.4
SUBWAYS/METROS
9.3.1.5
MONORAILS
9.4
COACHES
9.5
WAGONS
9.6
OTHER PRODUCT TYPES
9.7
KEY PRIMARY INSIGHTS
# NOTE: MARKET SIZE WILL BE PROVIDED AT THE REGIONAL LEVEL IN TERMS OF VALUE (USD BILLION)
10
ROLLING STOCK MARKET, BY LOCOMOTIVE TECHNOLOGY
Market Size, Volume & Forecast – USD Million
10.1
INTRODUCTION
10.2
CONVENTIONAL LOCOMOTIVES
10.3
TURBOCHARGED LOCOMOTIVES
10.4
MAGLEV
10.5
KEY PRIMARY INSIGHTS
# NOTE: MARKET SIZE WILL BE PROVIDED AT THE REGIONAL LEVEL IN TERMS OF VALUE (USD BILLION)
11
ROLLING STOCK MARKET, BY PROPULSION/TRACTION TYPE
Market Size, Volume & Forecast – USD Million
11.1
INTRODUCTION
11.2
DIESEL
11.3
ELECTRIC
11.4
ELECTRO-DIESEL
11.5
KEY PRIMARY INSIGHTS
# NOTE: MARKET SIZE WILL BE PROVIDED AT THE REGIONAL LEVEL IN TERMS OF VALUE (USD BILLION)
12
ROLLING STOCK MARKET, BY APPLICATION
Market Size, Volume & Forecast – USD Million
12.1
INTRODUCTION
12.2
PASSENGER TRANSPORTATION
12.2.1
URBAN
12.2.2
REGIONAL
12.2.3
INTERCITY
12.2.4
HSR
12.3
FREIGHT TRANSPORTATION
12.3.1
HAUL
12.3.2
MAINLINE
12.3.3
SHUNTING
12.4
KEY PRIMARY INSIGHTS
# NOTE: MARKET SIZE WILL BE PROVIDED AT THE REGIONAL LEVEL IN TERMS OF VALUE (USD BILLION)
13
ROLLING STOCK MARKET, BY COMPONENT
Market Size, Volume & Forecast – USD Million
13.1
INTRODUCTION
13.2
TRAIN CONTROL SYSTEMS
13.3
PANTOGRAPHS
13.4
AXLES
13.5
WHEELSET
13.6
TRACTION MOTORS
13.7
PASSENGER INFORMATION SYSTEMS
13.8
BRAKES
13.9
AIR CONDITIONING SYSTEMS
13.10
AUXILIARY POWER SYSTEMS
13.11
GEARBOXES
13.12
BAFFLE GEARS
13.13
COUPLERS
# NOTE: MARKET SIZE WILL BE PROVIDED AT THE REGIONAL LEVEL IN TERMS OF VALUE (USD BILLION)
14
ROLLING STOCK MARKET, BY REGION
Market Size, Volume & Forecast – USD Million
14.1
ASIA OCEANIA
14.1.1.1
CHINA
14.1.1.2
INDIA
14.1.1.3
JAPAN
14.1.1.4
SOUTH KOREA
14.1.1.5
AUSTRALIA
14.1.1.6
MALAYSIA
14.2
EUROPE
14.2.1.1
GERMANY
14.2.1.2
FRANCE
14.2.1.3
UK
14.2.1.4
ITALY
14.2.1.5
SPAIN
14.2.1.6
SWITZERLAND
14.2.1.7
AUSTRIA
14.2.1.8
SWEDEN
14.3
NORTH AMERICA
14.3.1.1
US
14.3.1.2
MEXICO
14.3.1.3
CANADA
14.4
MIDDLE EAST & AFRICA
14.4.1.1
SOUTH AFRICA
14.4.1.2
UAE
14.4.1.3
EGYPT
14.4.1.4
IRAN
14.5
REST OF THE WORLD
14.5.1.1
BRAZIL
14.5.1.2
RUSSIA
14.5.1.3
ARGENTINA
NOTE: MARKET SIZE WILL BE PROVIDED AT THE COUNTRY LEVEL IN TERMS OF VALUE (USD BILLION)
15
COMPETITIVE LANDSCAPE
15.1
OVERVIEW
15.2
KEY PLAYER STRATEGIES/RIGHT TO WIN
15.3
MARKET SHARE ANALYSIS,
15.4
REVENUE ANALYSIS OF TOP LISTED/PUBLIC PLAYERS,
15.5
BRAND/PRODUCT COMPARISON
15.6
COMPANY VALUATION & FINANCIAL METRICS
15.7
COMPANY EVALUATION MATRIX: KEY PLAYERS,
15.7.1.1
STARS
15.7.1.2
EMERGING LEADERS
15.7.1.3
PERVASIVE PLAYERS
15.7.1.4
PARTICIPANTS
15.7.1.5
COMPANY FOOTPRINT: KEY PLAYERS,
15.7.1.6
COMPANY FOOTPRINT
15.7.1.7
REGION FOOTPRINT
15.7.1.8
APPLICATION FOOTPRINT
15.7.1.9
PRODUCT TYPE FOOTPRINT
15.7.1.10
LOCOMOTIVE TECHNOLOGY FOOTPRINT
15.8
COMPANY EVALUATION MATRIX: START-UPS/SMES,
15.8.1.1
PROGRESSIVE COMPANIES
15.8.1.2
RESPONSIVE COMPANIES
15.8.1.3
DYNAMIC COMPANIES
15.8.1.4
STARTING BLOCKS
15.8.1.5
COMPETITIVE BENCHMARKING: START-UPS/SMES,
15.8.1.6
DETAILED LIST OF KEY START-UPS/SMES
15.8.1.7
COMPETITIVE BENCHMARKING OF KEY START-UPS/SMES
15.9
COMPETITIVE SCENARIO
15.9.1
PRODUCT LAUNCHES
15.9.2
DEALS
15.9.3
EXPANSIONS
15.9.4
OTHER DEVELOPMENTS
16
COMPANY PROFILES
16.1
OEMS
16.1.1
CRRC CORPORATION LIMITED
16.1.1.1
BUSINESS OVERVIEW
16.1.1.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED
16.1.1.3
NEW PRODUCT DEVELOPMENT/ENRICHMENT
16.1.1.4
DEALS
16.1.1.5
MNM VIEW
16.1.2
SIEMENS AG
16.1.3
ALSTOM SA
16.1.4
STADLER RAIL AG
16.1.5
WABTEC CORPORATION
16.1.6
KAWASAKI HEAVY INDUSTRIES, LTD.
16.1.7
CAF GROUP
16.1.8
HYUNDAI ROTEM COMPANY
16.1.9
MITSUBISHI HEAVY INDUSTRIES, LTD.
16.1.10
TALGO
16.1.11
TRANSMASHHOLDING
16.1.12
TITAGARH RAIL SYSTEMS LIMITED
(*COMPANY PROFILE WOULD COVER BUSINESS OVERVIEW, PRODUCTS OFFERED, DEALS, AND MNM VIEW)
*DETAILS ON BUSINESS OVERVIEW, PRODUCTS OFFERED, DEALS, AND MNM VIEW MIGHT NOT BE CAPTURED IN THE CASE OF UNLISTED COMPANIES.
16.2
OTHER KEY PLAYERS
(*QUALITATIVE WRITE-UP WOULD BE PROVIDED FOR OTHER KEY PLAYERS)
17
RESEARCH METHODOLOGY
17.1
RESEARCH DATA
17.1.1
SECONDARY DATA
17.1.1.1
KEY DATA FROM SECONDARY SOURCES
17.1.2
PRIMARY DATA
17.1.2.1
KEY DATA FROM PRIMARY SOURCES
17.1.2.2
KEY PRIMARY PARTICIPANTS
17.1.2.3
BREAKDOWN OF PRIMARY INTERVIEWS
17.1.2.4
KEY INDUSTRY INSIGHTS
17.2
MARKET SIZE ESTIMATION
17.2.1
TOP-DOWN APPROACH
17.2.2
BOTTOM-UP APPROACH
17.3
MARKET FORECAST APPROACH
17.3.1
SUPPLY SIDE
17.3.2
DEMAND SIDE
17.4
DATA TRIANGULATION
17.5
FACTOR ANALYSIS
17.6
RESEARCH ASSUMPTIONS
17.7
RESEARCH LIMITATIONS & RISK ASSESSMENT
18
APPENDIX
18.1
DISCUSSION GUIDE
18.2
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL
18.3
CUSTOMIZATION OPTIONS
18.4
RELATED REPORTS
18.5
AUTHOR DETAILS
Methodology
The study involved four major activities in estimating the current size of the rolling stock market. The team conducted extensive secondary research to gather information on the rolling stock market, related markets, and the broader rail transportation ecosystem. The team then validated the findings, assumptions, and market sizing through primary research with industry participants across the rolling stock value chain. We used both top-down and bottom-up approaches to estimate the overall market size. The team then performed market breakdown and data triangulation to estimate the size of individual segments and subsegments by product type, locomotive type, application, and region.
Secondary Research
Secondary sources referred to for this research study included rolling stock industry organizations, company annual reports, investor presentations, financial statements, industry databases, trade publications, technical reports, and publications from recognized railway associations and government sources. We collected and analyzed secondary data to assess market size, segment trends, regional developments, industry dynamics, and competitive activity in the rolling stock market. We then validated the findings through primary research.
Primary Research
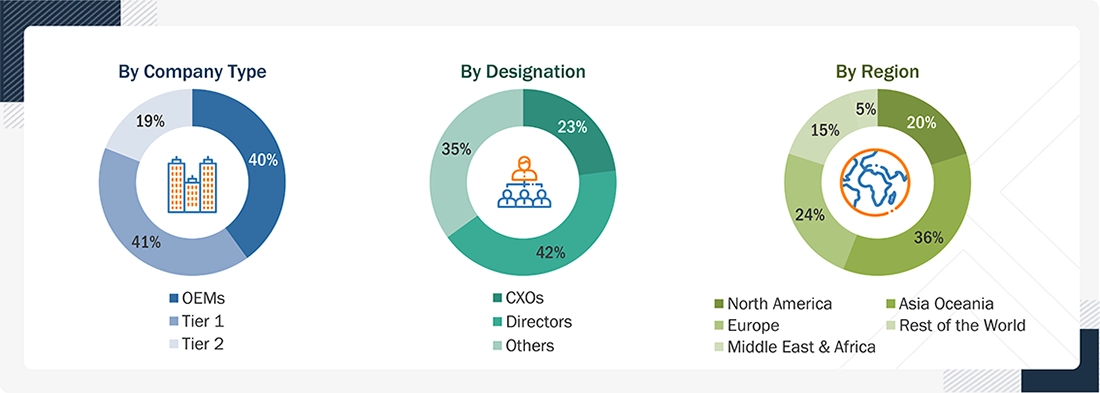
We conducted extensive primary research after understanding the rolling stock market through secondary research. Several primary interviews were conducted with market experts from both the demand (railway operators, system integrators, country-level government associations, and trade associations) and supply (OEMs and component manufacturers) sides across major regions, namely, North America, Europe, Asia Oceania, the Middle East & Africa, and the Rest of the World. We conducted approximately 40% of primary interviews from the demand side and 60% from the supply side. We collected primary data through questionnaires, emails, and telephonic interviews. When collecting primary data, we considered various departments within organizations, such as sales, operations, and administration, to provide a holistic viewpoint in this report.
We conducted brief sessions with highly experienced independent consultants to reinforce primary findings after consulting industry experts. This, along with the in-house subject matter experts’ opinions, led to the findings described in the remainder of this report.
In the primary research process, we interviewed various primary sources from both the supply and demand sides to obtain qualitative and quantitative information for the report. Supply-side primary sources included industry experts such as Chief Executive Officers (CEOs), Vice Presidents (VPs), marketing directors, technology and innovation directors, and other key executives from various companies and organizations. Primary sources on the demand side included end users such as Chief Information Officers (CIOs), consultants, service professionals, technicians and technologists, and managers at public and investor-owned utilities.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
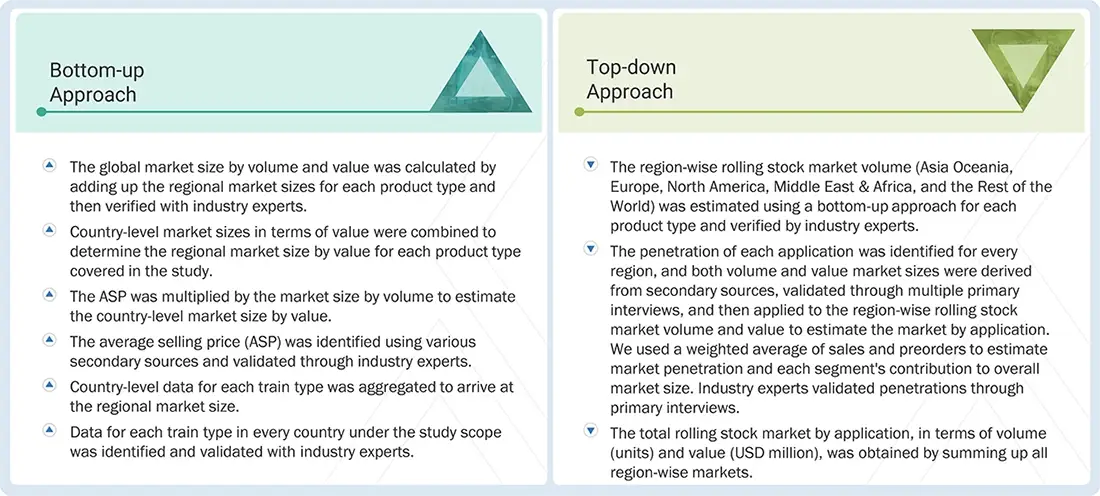
We used the bottom-up approach to estimate and validate the rolling stock market size. In this approach, we considered rolling stock fleet statistics for each vehicle type, including locomotives, passenger coaches, multiple units, and freight wagons, at the country level. We mapped rolling stock units for each country and vehicle type to determine market size by volume. The number of rolling stock units and procurement or replacement requirements varied by country. After analyzing the models, we classified the segments by vehicle type, propulsion type, application, and region. Using the model mapping, the study assessed market penetration by rolling stock segment using country-level fleet data, deliveries, production volumes, and replacement requirements, and provided the volume for each segment type. The country-level data was summed to arrive at regional-level volume data. Summing the country-level market sizes gave the regional market size, and further summing provided the global rolling stock market size.
The top-down approach estimates and validates the global rolling stock market size by vehicle type, propulsion type, application, and region, in terms of volume. This approach identifies key vehicle type, propulsion type, application, and rolling stock category segments at the regional level. The penetration of each identified segment has been multiplied by the total regional rolling stock market volume to derive total segment volume. The analysis considers rolling stock vehicles such as locomotives, passenger coaches, multiple units, and freight wagons, while excluding railway infrastructure and related markets. We derived the rolling stock market using a top-down approach to estimate key subsegments by vehicle type, propulsion type, and application. Using this method, we derived market size by volume at the regional level for each segment. We multiplied the total volume of the rolling stock market by the adoption rate, or segment penetration percentage, at the regional level across vehicle type, propulsion type, application, and other relevant classifications. The regional segment volumes were then aggregated to determine the overall rolling stock market size.
Data Triangulation
After arriving at the overall market size through the above-mentioned methodology, this market was split into several segments and subsegments. Where applicable, we used data triangulation and market-breakdown procedures to complete the overall market engineering process and arrive at exact market value data for the key segments and subsegments. The extrapolated market data was triangulated by studying various macro indicators and regional trends from both the demand- and supply-side participants.
Market Definitio
Rolling stock refers to railway vehicles. They include both powered and unpowered vehicles, such as locomotives, railroad cars, coaches, and wagons. Rolling stock is used for freight and passenger transport and plays a vital role in a city's or country's transport infrastructure. Rapid urbanization and industrialization, along with the increasing use of public transport to reduce traffic congestion, are the key factors driving growth in the rolling stock market.
Key Stakeholders
- Rolling stock manufacturers
- Rolling stock component & subsystem suppliers
- Rail technology providers
- Leasing companies & financial institutions
- Maintenance, repair, and overhaul (MRO) service providers
- Government bodies & regulatory authorities
- Rail infrastructure developers
- Investors & public-private partnerships (PPPs)
- Rail operators & service providers
Report Objectives
- To segment and forecast the size of the rolling stock market in terms of value (USD million) and volume (units)
- To define, describe, and forecast the market by product type, locomotive technology, application, component, and region
- To analyze regional markets for growth trends, prospects, and their contributions to the overall market
- To segment and forecast the market size by product type (locomotives, rapid transit, wagons, and coaches)
- To provide a qualitative analysis of other product types
- To segment and forecast the market size by locomotive technology (conventional locomotives and turbocharged locomotives)
- To segment and forecast the market size by application (passenger transportation and freight transportation)
- To provide a qualitative analysis of component segments (pantographs, axles, wheelsets, traction motors, passenger information systems, air conditioning systems, auxiliary power systems, train control systems, brakes, baffle gear, couplers, and gearboxes)
- To forecast the market size by region [North America, Europe, Asia Oceania, the Middle East & Africa (MEA), and the Rest of the World (RoW)]
- To analyze technological developments impacting the market
- To provide detailed information about the major factors influencing the market growth (drivers, challenges, restraints, and opportunities)
- To strategically analyze the market, considering individual growth trends, prospects, and contributions to the total market
- To study the following concerning the market:
- Supply Chain Analysis
- Ecosystem Analysis
- Technology Analysis
- Trade Analysis
- Case Study Analysis
- Patent Analysis
- Regulatory Landscape
- Impact of AI/Gen AI
- Trend & Disruption Impact
- Key Stakeholders & Buying Criteria
- Key Conferences & Events
- Investment & Funding Scenario
- Strategic Pathways for Alternative Propulsion Systems
- Rail Infrastructure Modernization Strategy
- Implementation Framework for Autonomous Train Technology
- Success Stories & Real-world Applications
- To strategically profile key players and comprehensively analyze their market shares and core competencies
- To track and analyze competitive developments such as deals (joint ventures, mergers & acquisitions, contracts, partnerships, collaborations), product developments & launches, and other activities conducted by key industry participants
Available customizations:
With the given market data, MarketsandMarkets offers customizations in line with company-specific needs.
- Rolling stock market, by technology type at the country level (for countries covered in the report)
- Rolling stock market, by product type at the country level (for countries covered in the report)
- Profiling of additional market players (up to five)
Key Questions Addressed by the Report
What is the current market size of the Rolling Stock Market, and how is it expected to grow?
The Rolling Stock Market is projected to grow from USD 30.94 billion in 2025 to USD 41.79 billion by 2032, at a CAGR of 4.4% during the forecast period.
What are the key factors driving the growth of the Rolling Stock Market?
The market is driven by increasing investments in railway modernization, growing adoption of electric and hydrogen-powered trains, expansion of metro rail networks, and rising demand for sustainable rail transportation.
Which region is expected to dominate the Rolling Stock Market during the forecast period?
Asia Oceania is expected to dominate the Rolling Stock Market due to rapid urbanization, large-scale rail infrastructure projects, expanding metro networks, and increasing government investments in railway modernization.
What are the latest trends shaping the Rolling Stock Market?
Key trends include the adoption of battery-electric and hydrogen-powered trains, smart rail technologies, predictive maintenance, AI-enabled fleet management, and digitalization of railway operations.
Who are the leading companies in the Rolling Stock Market, and what strategies are they adopting?
Leading companies are focusing on product innovation, strategic partnerships, capacity expansion, and the development of energy-efficient rolling stock solutions to strengthen their market position.
Fact checked
Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the Rolling Stock Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Custom Market Research Services
We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements
Get 10% Free CustomisationTESTIMONIALS
JIM NAAS
PRODUCT DIRECTOR, WEASLER
Weasler Engineering, a CentroMotion organization
Global Provider of Industrial Actuation & Control Solutionswww.weasler.com
Our organization was interested in learning more about the attractiveness of a particular market space. We contacted MarketsandMarkets to help us based on previous positive experiences we had with them. The results did not disappoint! We discussed our objectives with them, and the team at MarketsandMarkets developed and executed a proposal that met our needs precisely. We were very impressed by their level of expertise, the quality of the analysis and their insightful recommendations. We would not hesitate in working with them again in the future.

Matt Kardel,
Vice President
Aptiv,
A global technology company that develops safer, greener and more connected solutions.www.aptiv.com
We contracted with
MarketsandMarkets to evaluate the value chain and potential go-to-market partners related to our
interest in the Fleet Management space. The team successfully completed the work on time and at the
pricing agreed. MarketsandMarkets listened and understood our objectives and collaborated well with
us to help us get the visibility we needed to make an investment.
We have subsequently used
MarketsandMarkets again related to Smart Cities to good results.
- China Rolling Stock Market
- India Rolling Stock Market
- Japan Rolling Stock Market
- South Korea Rolling Stock Market
- Germany Rolling Stock Market
- France Rolling Stock Market
- UK Rolling Stock Market
- Italy Rolling Stock Market
- Spain Rolling Stock Market
- Mexico Rolling Stock Market
- Canada Rolling Stock Market
- South Africa Rolling Stock Market
- UAE Rolling Stock Market
- Egypt Rolling Stock Market
- Brazil Rolling Stock Market
- Russia Rolling Stock Market
- US Rolling Stock Market
Growth opportunities and latent adjacency in Rolling Stock Market






robert
May, 2022
what is the market size for rolling stock market and also want to more details about forecast year 2022 to 2027. .
Heidy
Jun, 2026
we are making business research for railway industry in Indonesia .
Wiwid
Jun, 2026
interest in rolling stock global markets and developments. .