Semiconductor Manufacturing Equipment Market by Front-End Equipment (Lithography, Wafer Surface Conditioning, Deposition, Wafer Cleaning), Back-End Equipment (Dicing, Assembly & Packaging, Metrology, Bonding), End User - Global Forecast to 2033

icon1
USD 371.58 BN
MARKET SIZE, 2033
icon2
CAGR 10.6%
(2026-2033)
icon3
300
REPORT PAGES
icon4
170
MARKET TABLES

Semiconductor Manufacturing Equipment Market OVERVIEW

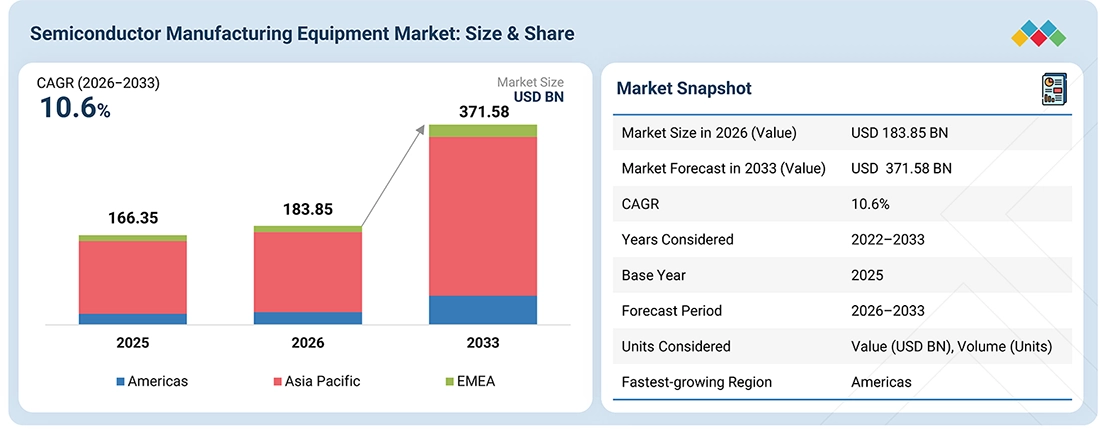
According to Marketsandmarkets, the semiconductor manufacturing equipment market size is projected to reach USD 371.58 billion by 2033 from USD 183.85 billion in 2026, registering at a CAGR of 10.6% from 2026 to 2033. Market growth is driven by increasing investments in semiconductor fabrication facilities and rising demand for advanced logic and memory chips. Additionally, growing adoption of AI processors, high-performance computing, and advanced packaging, along with advancements in lithography, deposition, etching, and inspection technologies, is further supporting market growth globally.

REPORT SCOPE

REPORT METRIC DETAILS
Market Size in 2025 (Value) USD 166.35 Billion
Market Forecast in 2026 (Value) USD 183.85 Billion
Market Forecast in 2033 (Value) USD 371.58 Billion
Growth Rate CAGR of 10.6% from 2026-2033
Years Considered 2022-2033
Base Year 2025
Forecast Period 2026-2033
Units Considered Value (USD Million/Billion), Volume (Units)
Report Coverage Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments Covered
  • By Manufacturing Phase:
    • Front-end Equipment
    • Back-end Equipment
    • Others
  • By Front-end Equipment:
    • Lithography
    • Deposition
    • Wafer Surface Conditioning
    • Wafer Cleaning
    • Metrology
    • Other Front-end Equipment
  • By Back-end Equipment:
    • Assembly & Packaging
    • Dicing
    • Bonding
    • Wafer Testing/IC Testing
    • Other Back-end Equipment
  • By End User:
    • Foundries
    • IDMs
    • OSAT Companies
    • Other End Users
Regions Covered Americas, Asia Pacific, EMEA

KEY TAKEAWAYS

  • BY REGION
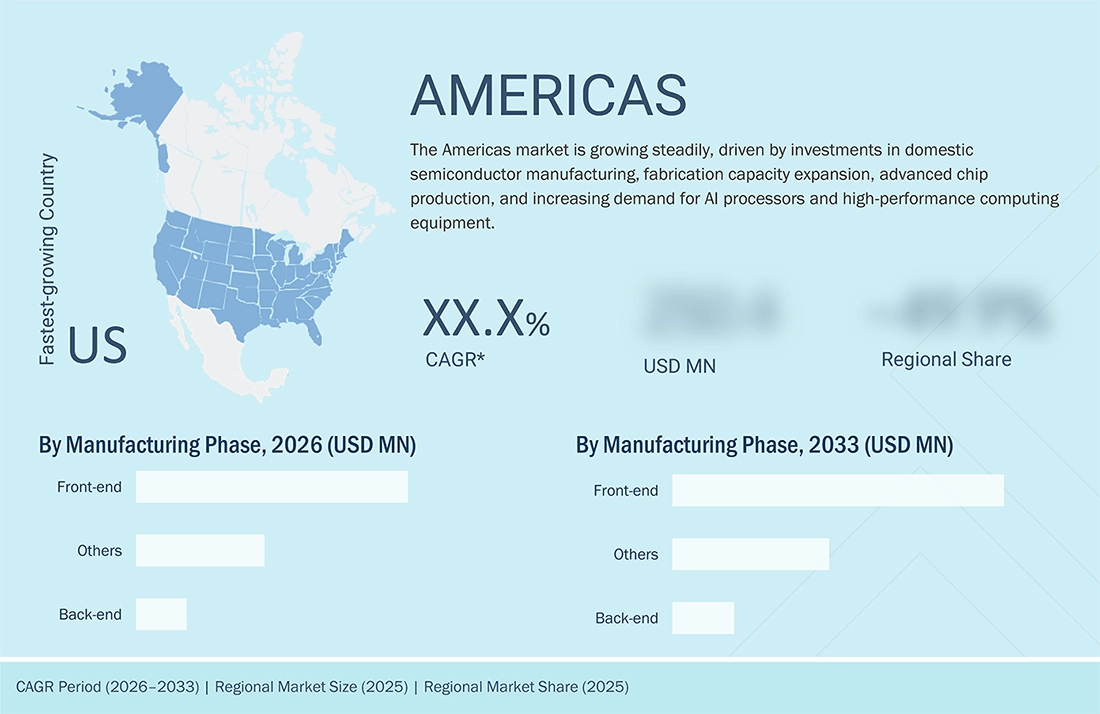
    The Americas is expected to register the highest CAGR of 12.6% during the forecast period, supported by rising investments in domestic semiconductor manufacturing, fabrication capacity expansion, and advanced chip production.
  • BY MANUFACTURING PHASE
    By manufacturing phase, front-end equipment accounted for the largest share of the semiconductor manufacturing equipment market in 2025, driven by increasing requirements for wafer processing, lithography, deposition, and etching across semiconductor fabrication facilities.
  • BY FRONT-END EQUIPMENT
    Based on front-end equipment, deposition equipment is projected to register the highest CAGR of 12.1% during the forecast period, supported by increasing adoption of advanced logic architectures, 3D NAND memory, and complex semiconductor structures requiring precise thin-film deposition.
  • BY BACK-END EQUIPMENT
    Based on back-end equipment, assembly & packaging equipment is projected to register the highest CAGR during the forecast period, supported by increasing demand for advanced packaging, chip integration, and high-performance semiconductor devices.
  • BY END USER
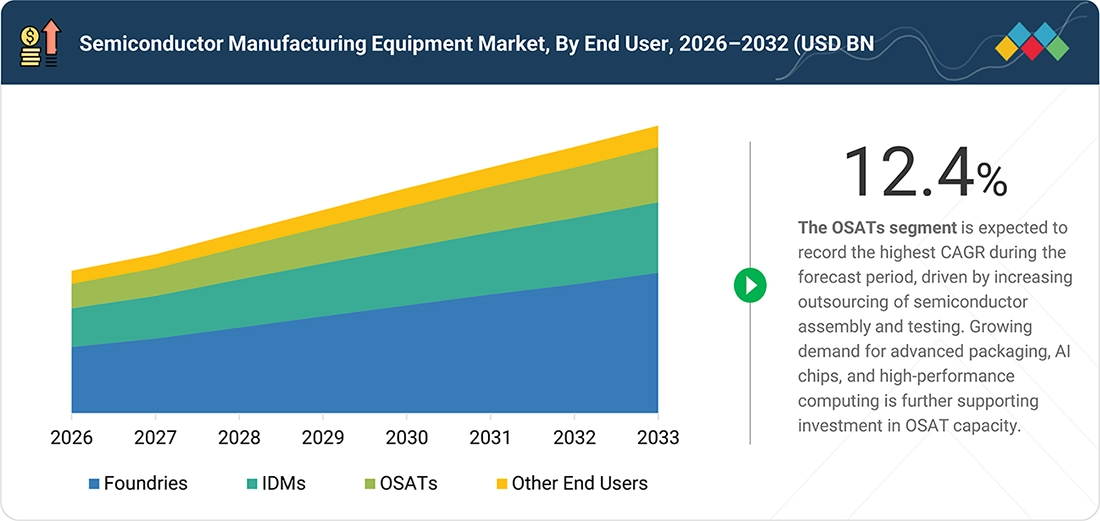
    By end user, foundries held the largest market share of ~47% in 2025, driven by growing demand for outsourced semiconductor manufacturing, advanced logic chips, AI processors, and high-performance computing applications.
  • COMPETITIVE LANDSCAPE (KEY PLAYERS)
    Major market players have adopted organic and inorganic strategies, including product launches, technology development, strategic partnerships, acquisitions, and investments, to strengthen their positions in the semiconductor manufacturing equipment market. Applied Materials, Inc. (US), ASML (Netherlands), Tokyo Electron Limited (Japan), Lam Research Corporation (US), KLA Corporation (US), SCREEN Holdings Co., Ltd. (Japan), Teradyne, Inc. (US), Advantest Corporation (Japan), Hitachi High-Tech Corporation (Japan), and Plasma-Therm, LLC (US) are among the leading participants offering semiconductor manufacturing and testing equipment.
  • COMPETITIVE LANDSCAPE (STARTUPS/SMEs)
    Emerging companies and specialized technology providers are strengthening their presence through innovations in semiconductor processing, advanced packaging, wafer inspection, and plasma-based technologies. Companies such as Trymax Semiconductor Equipment (Netherlands), NEXX (US), and Plasma-Therm, LLC (US) offer specialized equipment and technologies supporting wafer processing, deposition, etching, and advanced semiconductor manufacturing applications.

The semiconductor manufacturing equipment market is witnessing steady growth, driven by increasing demand for advanced semiconductor devices and expanding fabrication capacity. Rising investments in AI processors, high-performance computing, advanced memory, and semiconductor manufacturing facilities are supporting market expansion. Continuous advancements in lithography, deposition, etching, wafer cleaning, and inspection technologies are enabling the production of smaller and more complex chips. Additionally, growing investments in advanced packaging and next-generation semiconductor architectures are creating new opportunities across semiconductor manufacturing processes.

semiconductor-manufacturing-equipment-market Overview

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS

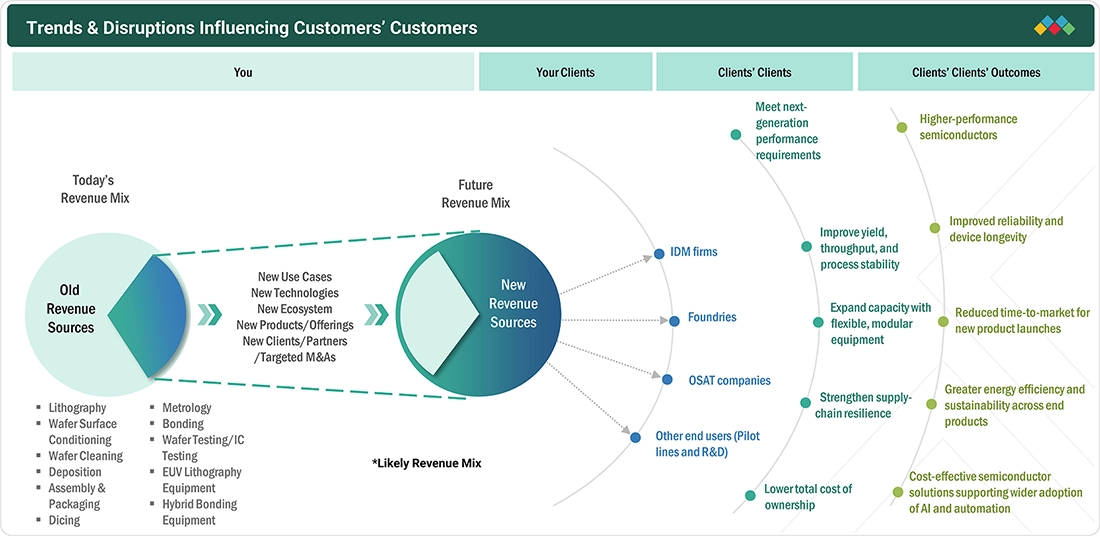
The semiconductor manufacturing equipment market is undergoing a major revenue shift from conventional wafer processing and assembly equipment toward advanced manufacturing and packaging technologies. The future revenue mix is increasingly centered around advanced lithography, atomic layer deposition, selective etching, EUV lithography, and hybrid bonding equipment, driven by growing demand for AI processors, high-performance computing, and advanced memory. This shift is encouraging equipment manufacturers to develop solutions that improve manufacturing precision, production yields, process stability, and chip integration to address increasingly complex semiconductor architectures.

semiconductor-manufacturing-equipment-market Disruptions

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

MARKET DYNAMICS

Drivers
Impact
Level
  • Increasing miniaturization and advanced node adoption
  • Rising autonomous vehicle adoption and digitalization
RESTRAINTS
Impact
Level
  • High capital and operational costs
  • Rising complexity of semiconductor manufacturing processes
OPPORTUNITIES
Impact
Level
  • Mounting adoption of advanced packaging technologies
  • Government-led initiatives to strengthen semiconductor manufacturing
CHALLENGES
Impact
Level
  • Complexities associated with transitioning to smaller geometries and higher transistor densities
  • Rising implementation of stringent environmental norms

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Driver: Increasing miniaturization and advanced node adoption

Increasing miniaturization and the adoption of advanced process nodes are driving demand for semiconductor manufacturing equipment. Chipmakers are developing smaller transistors and more complex chip architectures to improve performance, power efficiency, and integration density. These developments require advanced lithography, deposition, etching, and inspection systems capable of achieving greater precision and tighter process control. Growing production of AI processors, high-performance computing chips, and advanced memory is further increasing equipment requirements. Additionally, the transition toward gate-all-around transistors and other advanced device structures is encouraging investments in next-generation manufacturing technologies.

Restraint: High capital and operational costs

High capital and operational costs remain a major restraint for the semiconductor manufacturing equipment market. Advanced lithography, deposition, etching, and inspection systems require substantial upfront investment, specialized infrastructure, and controlled manufacturing environments. Installation, maintenance, equipment calibration, and technology upgrades further increase ownership costs. In addition, operating advanced equipment requires skilled personnel and continuous process optimization. These financial and operational requirements can delay capacity expansion and equipment upgrades, particularly for smaller manufacturers and facilities operating under tight investment budgets.

Opportunity: Mounting adoption of advanced packaging technologies

The growing adoption of advanced packaging technologies is creating new opportunities for semiconductor manufacturing equipment providers. Techniques such as 2.5D and 3D integration, chiplets, and hybrid bonding enable greater integration of multiple semiconductor dies within compact packages. These approaches are gaining importance as manufacturers address the performance and bandwidth requirements of AI processors and high-performance computing systems. Increasing adoption is driving demand for specialized bonding, deposition, inspection, metrology, and packaging equipment. Continued investment in advanced packaging capacity is expected to expand equipment opportunities across foundries, integrated device manufacturers, and outsourced semiconductor assembly and test providers.

Challenge: Complexities associated with transitioning to smaller geometries and higher transistor densities

Transitioning to smaller process geometries and higher transistor densities presents significant technical challenges for semiconductor manufacturing equipment providers. Advanced chip structures require increasingly precise patterning, material deposition, etching, and defect inspection. Maintaining uniformity and process control becomes more difficult as feature sizes shrink and three-dimensional structures become more complex. Equipment manufacturers must continuously improve accuracy, throughput, and defect detection while supporting new materials and manufacturing processes. These requirements increase research and development needs, extend equipment qualification cycles, and create challenges in achieving consistent yields during the adoption of advanced semiconductor technologies.

SEMICONDUCTOR MANUFACTURING EQUIPMENT MARKET SIZE, SHARE & TRENDS: COMMERCIAL USE CASES ACROSS INDUSTRIES

COMPANY USE CASE DESCRIPTION BENEFITS
company logo
Provides deposition, etching, materials modification, and inspection technologies for semiconductor fabrication and advanced packaging Enables precise material processing | Improves wafer yield | Supports advanced chip architectures | Enhances manufacturing productivity
company logo
Develops extreme ultraviolet (EUV) and deep ultraviolet (DUV) lithography systems for printing circuit patterns on semiconductor wafers Enables advanced node manufacturing | Supports higher transistor density | Improves patterning precision | Supports semiconductor scaling
company logo
Provides wafer fabrication equipment for deposition, etching, and cleaning processes used in logic, memory, and advanced packaging manufacturing Enables precise material removal | Supports complex three-dimensional structures | Improves process control | Enhances manufacturing yields
company logo
Supplies semiconductor production equipment for coating and developing, deposition, etching, cleaning, and other wafer processing steps Supports advanced wafer processing | Improves process uniformity | Enables higher production efficiency | Supports advanced semiconductor manufacturing
company logo
Provides inspection, metrology, and process control equipment to detect defects and monitor manufacturing processes across semiconductor production Enables early defect detection | Improves process control | Supports higher yields | Reduces manufacturing variability

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET ECOSYSTEM

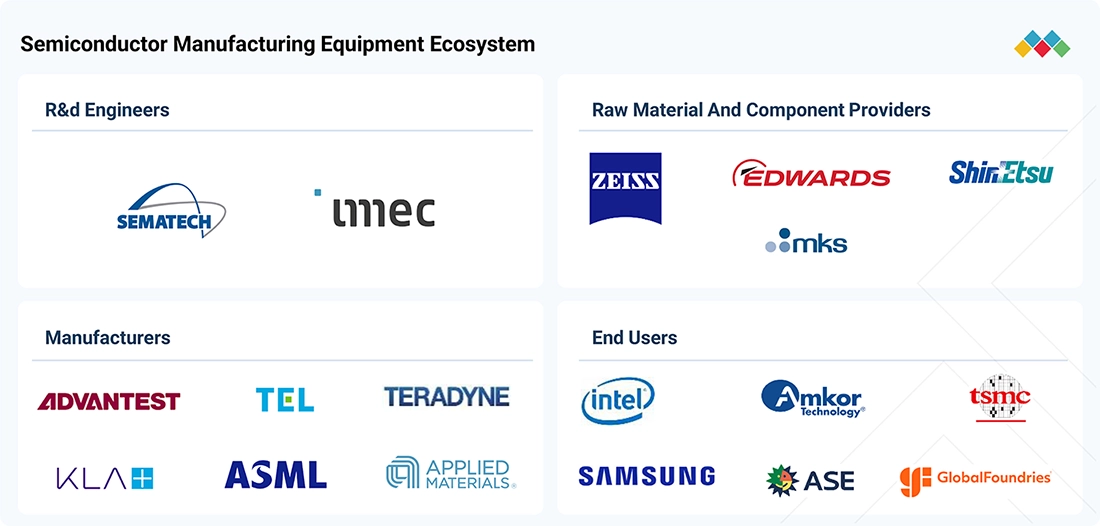
The semiconductor manufacturing equipment ecosystem comprises research institutions, raw material and component providers, equipment manufacturers, and semiconductor manufacturers. Organizations such as imec (Belgium) and SEMATECH (US) support semiconductor research and process development, while companies such as ZEISS (Germany), Edwards Vacuum (UK), Shin-Etsu Chemical (Japan), and MKS Inc. (US) supply optical systems, vacuum technologies, wafers, and process-control components. Equipment manufacturers, including Advantest Corporation (Japan), Tokyo Electron Limited (Japan), Teradyne, Inc. (US), KLA Corporation (US), ASML (Netherlands), and Applied Materials, Inc. (US), provide manufacturing, inspection, and testing solutions. End users such as Intel Corporation (US), ASE Technology Holding (Taiwan), Amkor Technology (US), TSMC (Taiwan), Samsung Electronics (South Korea), and GlobalFoundries (US) drive demand across semiconductor fabrication, assembly, packaging, and testing.

semiconductor-manufacturing-equipment-market Ecosystem

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET SEGMENTS

semiconductor-manufacturing-equipment-market Segments

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Semiconductor Manufacturing Equipment Market, By Manufacturing Phase

As of 2025, front-end equipment is expected to hold the largest share of the semiconductor manufacturing equipment market. Front-end equipment is essential for processing silicon wafers and forming integrated circuits through lithography, deposition, etching, and cleaning. Growing demand for advanced logic, memory, and AI processors is driving investments in front-end manufacturing technologies. Increasing adoption of advanced process nodes and complex transistor architectures is further strengthening demand for front-end equipment across semiconductor fabrication facilities.

Semiconductor Manufacturing Equipment Market, By Front-end Equipment

As of 2025, lithography equipment is expected to account for the largest share of the front-end equipment segment. Lithography systems transfer circuit patterns onto silicon wafers and are essential for manufacturing advanced semiconductor devices. Growing demand for smaller process nodes, higher transistor density, and complex chip architectures is driving adoption of advanced lithography technologies. Increasing use of extreme ultraviolet (EUV) lithography and continued improvements in deep ultraviolet (DUV) systems are further supporting demand for lithography equipment.

Semiconductor Manufacturing Equipment Market, By Back-end Equipment

Assembly and packaging equipment is projected to register the highest CAGR during the forecast period. Growing adoption of advanced packaging technologies is increasing demand for equipment used to integrate multiple semiconductor dies into compact, high-performance packages. Technologies such as 2.5D and 3D integration, chiplets, and hybrid bonding are gaining importance in AI processors and high-performance computing applications. Increasing requirements for higher bandwidth, improved power efficiency, and greater integration density are further supporting demand for advanced assembly and packaging equipment.

Semiconductor Manufacturing Equipment Market, By End User

OSATs are expected to record the highest CAGR among end users during the forecast period. Growing outsourcing of semiconductor assembly and testing, rising demand for advanced packaging, and increasing adoption of AI processors and high-performance computing chips are driving investments in OSAT capacity expansion and equipment upgrades.

Semiconductor Manufacturing Equipment Market, By Region

In 2025, Asia Pacific accounted for the largest share of the semiconductor manufacturing equipment market. The region benefits from an established semiconductor manufacturing ecosystem, supported by fabrication facilities, memory production, and semiconductor packaging and testing operations. Strong demand for consumer electronics, automotive semiconductors, and advanced computing devices is supporting equipment investments. Continued capacity expansion and process technology upgrades across major semiconductor manufacturing countries are further strengthening Asia Pacific's market position.

REGION

Americas to be fastest-growing region in global semiconductor manufacturing equipment market during forecast period

The Americas semiconductor manufacturing equipment market is likely to grow at the highest CAGR, driven by increasing investments in domestic semiconductor fabrication and advanced chip manufacturing. Expanding production capacity, government initiatives to strengthen regional semiconductor supply chains, and rising demand for AI processors and high-performance computing are accelerating equipment adoption across the US and Canada. Growing investments in advanced lithography, deposition, etching, and inspection technologies are further supporting market expansion. Additionally, increasing demand for leading-edge chips and advanced packaging is creating opportunities for semiconductor manufacturing equipment providers across the region.

semiconductor-manufacturing-equipment-market Region

SEMICONDUCTOR MANUFACTURING EQUIPMENT MARKET SIZE, SHARE & TRENDS: COMPANY EVALUATION MATRIX

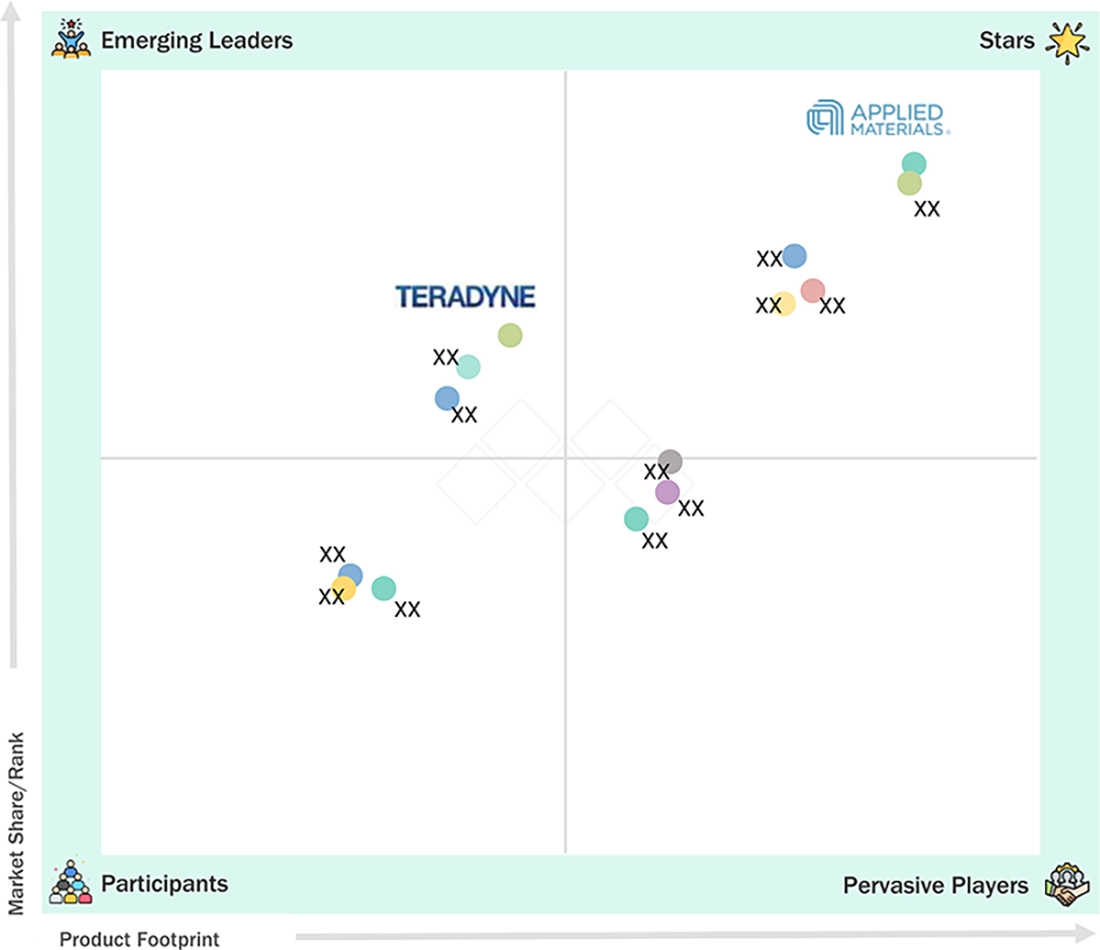
The semiconductor manufacturing equipment market matrix positions Applied Materials, Inc. (US) as a Star, supported by its broad portfolio of deposition, etching, materials modification, and inspection technologies. Other established players, including ASML (Netherlands) and Lam Research Corporation (US), strengthen their positions through advanced lithography and wafer processing solutions. Teradyne, Inc. (US) is positioned among Emerging Leaders, reflecting its semiconductor test equipment capabilities and market presence.

semiconductor-manufacturing-equipment-market Evaluation Metrics

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

KEY MARKET PLAYERS

WHAT IS IN IT FOR YOU: SEMICONDUCTOR MANUFACTURING EQUIPMENT MARKET SIZE, SHARE & TRENDS REPORT CONTENT GUIDE

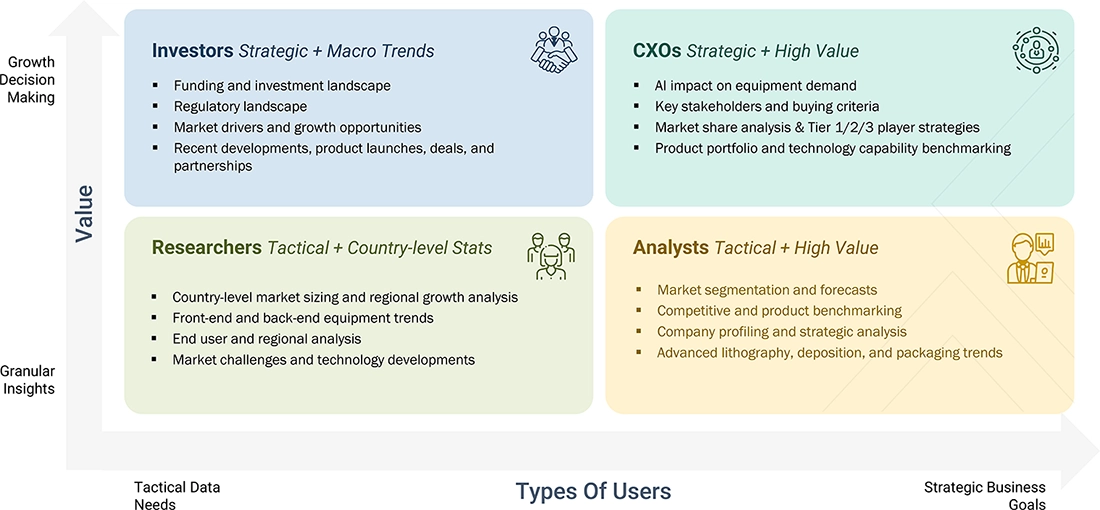
semiconductor-manufacturing-equipment-market Content Guide

DELIVERED CUSTOMIZATIONS

We have successfully delivered the following deep-dive customizations:

CLIENT REQUEST CUSTOMIZATION DELIVERED VALUE ADDS
Semiconductor Equipment Manufacturer
  • Competitive profiling of semiconductor equipment manufacturers, including product portfolios, process capabilities, and technology roadmaps
  • Benchmarking of lithography, deposition, etching, inspection, and metrology equipment
  • Analysis of customer segments and application focus
  • Identify technology differentiation opportunities
  • Benchmark product capabilities
  • Strengthen competitive positioning and product strategy
Foundry / IDM
  • Assessment of equipment adoption across advanced logic, memory, and wafer fabrication processes
  • Analysis of capacity expansion, process node transitions, and equipment requirements
  • Evaluation of manufacturing efficiency and yield improvement needs
  • Support equipment procurement and capacity planning
  • Identify process optimization opportunities
  • Improve manufacturing productivity
OSAT Provider
  • Assessment of demand for assembly, packaging, and testing equipment
  • Analysis of advanced packaging, chiplet integration, and hybrid bonding adoption
  • Evaluation of inspection and testing requirements
  • Identify high-growth packaging opportunities
  • Support equipment investment decisions
  • Strengthen advanced packaging capabilities
Semiconductor Equipment Investor
  • Analysis of market size, growth trends, and investment opportunities across manufacturing phases
  • Assessment of competitive positioning and technology differentiation
  • Evaluation of regional demand and capacity expansion plans
  • Identify attractive investment segments
  • Assess market potential and risks
  • Support investment prioritization
Semiconductor Industry Researcher / Analyst
  • Market sizing and forecasting by manufacturing phase, equipment type, end user, and region
  • Benchmarking of leading players and technology developments
  • Analysis of drivers, restraints, opportunities, and challenges
  • Identify high-growth segments
  • Strengthen market forecasts and competitive analysis
  • Support strategic decision-making

RECENT DEVELOPMENTS

  • February 2026 : Lam Research (US) expanded its collaboration with CEA-Leti (France) to develop advanced materials and manufacturing processes for specialty semiconductors. The collaboration covers MEMS, sensors, photonics, power management, and RF devices, supporting future equipment and process requirements.
  • April 2026 : Applied Materials, Inc. (US) introduced new deposition systems designed to support advanced logic chips using gate-all-around transistor architectures. The Precision Selective Nitride PECVD and Trillium ALD systems enable precise material deposition for 2 nm and beyond, supporting improved transistor performance and energy efficiency.
  • September 2026 : ASML (Netherlands) advanced its High-NA EUV lithography collaboration with Intel Foundry (US) and Samsung Electronics (South Korea). The companies reported progress in advanced lithography manufacturing readiness, including reticle stitching and larger-format photomasks, supporting the development of next-generation semiconductor production processes.
  • October 2026 : Teradyne (US) introduced the UltraFLEXplus S series of semiconductor test systems for edge AI applications. The platform is designed to improve space efficiency and testing economics for manufacturers handling varied product types and production volumes.


Table of Contents

checkmarkExclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.

TITLE
PAGE NO
1
INTRODUCTION


15
2
EXECUTIVE SUMMARY


3
PREMIUM INSIGHTS


4
MARKET OVERVIEW
Presents a concise view of industry direction, strategic priorities, and key indicators influencing market momentum.


4.1
INTRODUCTION


4.2
MARKET DYNAMICS


4.2.1
DRIVERS


4.2.2
RESTRAINTS


4.2.3
OPPORTUNITIES


4.2.4
CHALLENGES


4.3
INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES


4.4
STRATEGIC MOVES BY TIER 1/2/3 PLAYERS


5
INDUSTRY TRENDS
Covers the key developments, trend analysis, and actionable insights to support strategic planning and positioning.


5.1
INTRODUCTION


5.2
PORTER’S FIVE FORCES ANALYSIS


5.3
MACROECONOMIC OUTLOOK


5.3.1
INTRODUCTION


5.3.2
GDP TRENDS AND FORECAST


5.4
VALUE CHAIN ANALYSIS


5.5
ECOSYSTEM ANALYSIS


5.6
PRICING ANALYSIS


5.6.1
AVERAGE SELLING PRICE TREND OF FRONT-END LITHOGRAPHY EQUIPMENT, BY KEY PLAYERS (2022-2025)


5.6.2
AVERAGE SELLING PRICE TREND OF STANDARD LITHOGRAPHY EQUIPMENT, BY REGION (2022-2025)


5.7
TRADE ANALYSIS


5.7.1
IMPORT SCENARIO (HS CODE 848620)


5.7.2
EXPORT SCENARIO (HS CODE 848620)


5.8
KEY CONFERENCES AND EVENTS, 2026–2027


5.9
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS


5.10
INVESTMENT AND FUNDING SCENARIO


5.11
CASE STUDY ANALYSIS


5.12
IMPACT OF US TARIFF – SEMICONDUCTOR MANUFACTURING EQUIPMENT MARKET


5.12.1
INTRODUCTION


5.12.2
KEY TARIFF RATES


5.12.3
PRICE IMPACT ANALYSIS


5.12.4
IMPACT ON COUNTRIES/REGIONS


5.12.4.1
US


5.12.4.2
EUROPE


5.12.4.3
ASIA PACIFIC


5.12.5
IMPACT ON END USERS
 
 
6
TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, AND INNOVATIONS


6.1
KEY TECHNOLOGIES


6.1.1
EXTREME ULTRAVIOLET (EUV) LITHOGRAPHY


6.1.2
WAFER BONDING


6.2
COMPLEMENTARY TECHNOLOGIES


6.2.1
FLIP CHIP


6.3
TECHNOLOGY/PRODUCT ROADMAP


6.4
PATENT ANALYSIS


6.5
IMPACT OF GEN AI/AI ON THE SEMICONDUCTOR MANUFACTURING EQUIPMENT MARKET


6.5.1
TOP USE CASES AND MARKET POTENTIAL


6.5.2
BEST PRACTICES FOLLOWED BY IDMS/OSATS IN SEMICONDUCTOR MANUFACTURING EQUIPMENT MARKET


6.5.3
CASE STUDIES RELATED TO AI IMPLEMENTATION IN SEMICONDUCTOR MANUFACTURING EQUIPMENT


6.5.4
INTERCONNECTED/ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS


6.5.5
CLIENTS’ READINESS TO ADOPT GENERATIVE AI IN SEMICONDUCTOR MANUFACTURING EQUIPMENT MARKET
 
 
7
REGULATORY LANDSCAPE


7.1
REGIONAL REGULATIONS AND COMPLIANCE


7.1.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


7.1.2
INDUSTRY STANDARDS
 
 
8
CUSTOMER LANDSCAPE & BUYING BEHAVIOR


8.1
INTRODUCTION


8.2
DECISION-MAKING PROCESS


8.3
KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA


8.3.1
KEY STAKEHOLDERS IN BUYING PROCESS


8.3.2
BUYING CRITERIA


8.4
ADOPTION BARRIERS AND INTERNAL CHALLENGES


8.5
UNMET NEEDS OF VARIOUS END USERS


9
SEMICONDUCTOR MANUFACTURING EQUIPMENT MARKET, BY MANUFACTURING PHASE
Market Size, Volume & Forecast – USD Million


9.1
INTRODUCTION


9.2
FRONT-END EQUIPMENT


9.3
BACK-END EQUIPMENT


9.4
OTHERS


10
SEMICONDUCTOR MANUFACTURING EQUIPMENT MARKET, BY FRONT-END EQUIPMENT
Market Size, Volume & Forecast – USD Million


10.1
INTRODUCTION


10.2
LITHOGRAPHY


10.3
DEPOSITION


10.4
WAFER SURFACE CONDITIONING


10.5
WAFER CLEANING


10.6
METROLOGY


10.7
OTHER FRONT-END EQUIPMENT


11
SEMICONDUCTOR MANUFACTURING EQUIPMENT MARKET, BY BACK-END EQUIPMENT
Market Size, Volume & Forecast – USD Million


11.1
INTRODUCTION


11.2
ASSEMBLY & PACKAGING


11.3
DICING


11.4
BONDING


11.5
WAFER TESTING/IC TESTING


11.6
OTHER BACK-END EQUIPMENT


12
SEMICONDUCTOR MANUFACTURING EQUIPMENT MARKET, BY END USER
Market Size, Volume & Forecast – USD Million


12.1
INTRODUCTION


12.2
FOUNDRIES


12.3
IDMS


12.4
OSAT COMPANIES


12.5
OTHER END USERS


13
SEMICONDUCTOR MANUFACTURING EQUIPMENT MARKET, BY REGION
Market Size, Volume & Forecast – USD Million


13.1
INTRODUCTION


13.2
ASIA PACIFIC


13.2.1
CHINA


13.2.2
JAPAN


13.2.3
SOUTH KOREA


13.2.4
TAIWAN


13.2.5
REST OF ASIA PACIFIC


13.3
AMERICAS


13.3.1
US


13.3.2
CANADA


13.3.3
REST OF AMERICAS


13.4
EUROPE, MIDDLE EAST, AND AFRICA (EMEA)


13.4.1
UK


13.4.2
GERMANY


13.4.3
IRELAND


13.4.4
FRANCE


13.4.5
ITALY


13.4.6
NETHERLANDS


13.4.7
REST OF EMEA
 
 
14
SEMICONDUCTOR MANUFACTURING EQUIPMENT MARKET, COMPETITIVE LANDSCAPE


14.1
OVERVIEW


14.2
KEY PLAYER COMPETITIVE STRATEGIES/RIGHT TO WIN, 2023-2026


14.3
REVENUE ANALYSIS, 2022-2025


14.4
MARKET SHARE ANALYSIS, 2025 (TOP 5 PLAYERS)


14.5
PRODUCT/BRAND/TECHNOLOGY COMPARISON


14.6
COMPANY VALUATION AND FINANCIAL METRICS


14.7
COMPANY EVALUATION MATRIX: KEY PLAYERS,


14.7.1
STARS


14.7.2
EMERGING LEADERS


14.7.3
PERVASIVE PLAYERS


14.7.4
PARTICIPANTS


14.7.5
COMPANY FOOTPRINT: KEY PLAYERS,


14.7.5.1
COMPANY FOOTPRINT


14.7.5.2
REGION FOOTPRINT


14.7.5.3
FRONT-END EQUIPMENT FOOTPRINT


14.7.5.4
BACK-END EQUIPMENT FOOTPRINT


14.7.5.5
END USER FOOTPRINT
 
 
14.8
COMPANY EVALUATION MATRIX: STARTUPS/SMES,


14.8.1
PROGRESSIVE COMPANIES


14.8.2
RESPONSIVE COMPANIES


14.8.3
DYNAMIC COMPANIES


14.8.4
STARTING BLOCKS


14.8.5
COMPETITIVE BENCHMARKING: STARTUPS/SMES,


14.8.5.1
DETAILED LIST OF KEY STARTUPS/SMES


14.8.5.2
COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
 
 
14.9
COMPETITIVE SCENARIO


14.9.1
PRODUCT LAUNCHES


14.9.2
DEALS


14.9.3
EXPANSIONS


14.9.4
OTHER DEVELOPMENTS
 
 
15
SEMICONDUCTOR MANUFACTURING EQUIPMENT MARKET, COMPANY PROFILES


15.1
INTRODUCTION


15.2
KEY PLAYERS


15.2.1
APPLIED MATERIALS, INC.


15.2.2
ASML


15.2.3
TOKYO ELECTRON LIMITED


15.2.4
LAM RESEARCH CORPORATION


15.2.5
KLA CORPORATION


15.2.6
SCREEN HOLDINGS CO., LTD.


15.2.7
TERADYNE, INC.


15.2.8
ADVANTEST CORPORATION


15.2.9
HITACHI HIGH-TECH CORPORATION


15.2.10
PLASMA-THERM


15.3
OTHER PLAYERS


15.3.1
ASM INTERNATIONAL N.V.


15.3.2
EV GROUP (EVG)


15.3.3
ONTO INNOVATION


15.3.4
NORDSON CORPORATION


15.3.5
ADT


15.3.6
BENEQ


15.3.7
CVD EQUIPMENT CORPORATION


15.3.8
EUGENE TECHNOLOGY CO. LTD.


15.3.9
NIKON CORPORATION


15.3.10
SEMICONDUCTOR EQUIPMENT CORP.


15.3.11
SENTECH INSTRUMENTS GMBH


15.3.12
CANON INC.


15.3.13
KOKUSAI ELECTRIC CORPORATION


15.3.14
SEMES


15.3.15
FORMFACTOR
 
 
16
RESEARCH METHODOLOGY


16.1
RESEARCH DATA


16.1.1
SECONDARY DATA


16.1.1.1
KEY DATA FROM SECONDARY SOURCES


16.1.1.2
LIST OF KEY SECONDARY SOURCES


16.1.2
PRIMARY DATA


16.1.2.1
KEY DATA FROM PRIMARY SOURCES


16.1.2.2
KEY PRIMARY PARTICIPANTS


16.1.2.3
BREAKDOWN OF PRIMARY INTERVIEWS


16.1.2.4
KEY INDUSTRY INSIGHTS
 
 
16.2
MARKET SIZE ESTIMATION


16.2.1
BOTTOM-UP APPROACH


16.2.2
TOP-DOWN APPROACH


16.3
MARKET FORECAST APPROACH


16.3.1
SUPPLY SIDE


16.3.2
DEMAND SIDE


16.4
DATA TRIANGULATION


16.5
RESEARCH ASSUMPTIONS


16.6
RESEARCH LIMITATIONS


16.7
RISK ASSESSMENT


17
APPENDIX


17.1
DISCUSSION GUIDE


17.2
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL


17.3
CUSTOMIZATION OPTIONS


17.4
RELATED REPORTS


17.5
AUTHOR DETAILS


Methodology

The study involved major activities in estimating the current market size of the semiconductor manufacturing equipment market. Exhaustive secondary research was conducted to collect information on semiconductor manufacturing technologies, equipment categories, industry developments, and key market participants. The next step was to validate these findings and assumptions with industry experts across the value chain through primary research. Different approaches, including top-down and bottom-up methods, were employed to estimate the total market size. Following this, market breakdown and data triangulation procedures were used to determine the market sizes of segments and subsegments.

Secondary Research

Secondary research for this study involved gathering information from credible sources, including company annual reports, investor presentations, government publications, industry journals, technical papers, and semiconductor industry publications. This process helped understand the semiconductor manufacturing equipment value chain, identify key players, analyze market segmentation and regional trends, and track major technological developments and capacity expansion initiatives. The collected data was used to estimate the overall market size and segment-level revenues, which were subsequently validated through primary research.

Primary Research

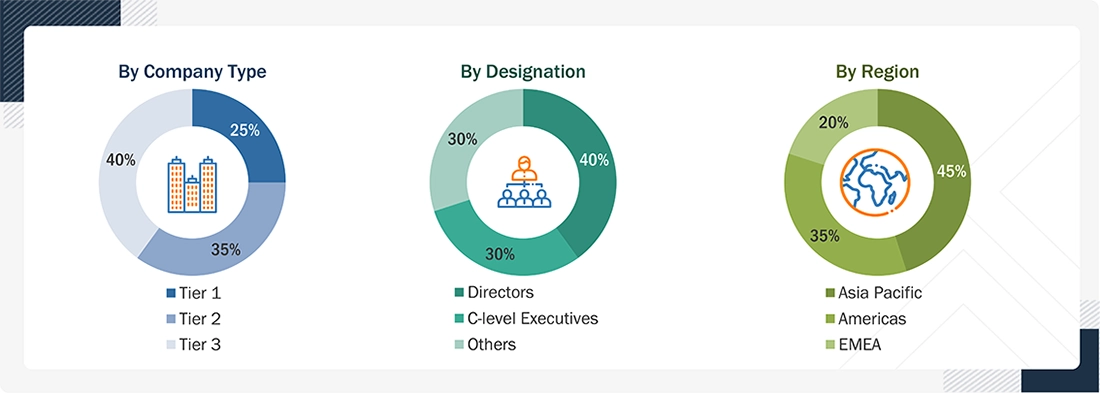
Extensive primary research was conducted after assessing the semiconductor manufacturing equipment market through secondary research. Interviews were conducted with experts from the demand and supply sides across four major regions: Americas, Asia Pacific, Europe, and the Middle East and Africa (MEA). Respondents included equipment manufacturers, semiconductor foundries, integrated device manufacturers (IDMs), outsourced semiconductor assembly and test (OSAT) providers, and industry experts. Primary data was collected through questionnaires, emails, and telephonic interviews to validate market estimates, growth trends, segmentation, and regional demand.

Semiconductor Manufacturing Equipment Market 
 Size, and Share

To know about the assumptions considered for the study, download the pdf brochure

Market Size Estimation

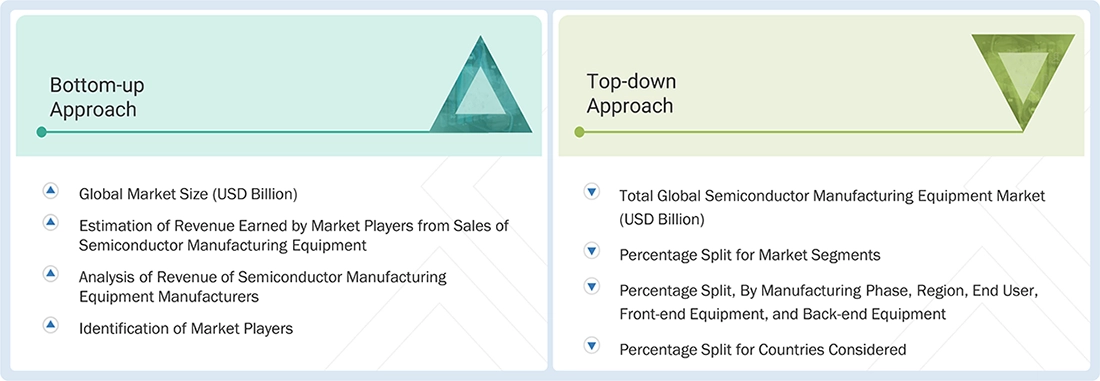
The bottom-up procedure was employed to arrive at the overall size of the semiconductor manufacturing equipment market.

  • Identifying semiconductor manufacturing equipment offered by key players across front-end and back-end manufacturing processes
  • Tracking major manufacturers and suppliers of lithography, deposition, etching, wafer cleaning, inspection, metrology, assembly, and testing equipment across different regions
  • Tracking ongoing and upcoming product launches, capacity expansions, acquisitions, partnerships, and collaborations among semiconductor equipment manufacturers
  • Estimating and forecasting the semiconductor manufacturing equipment market in each country and region based on equipment manufacturers' revenues, semiconductor fabrication investments, and relevant industry indicators
  • Conducting discussions with key opinion leaders to understand equipment demand across foundries, integrated device manufacturers (IDMs), and outsourced semiconductor assembly and test (OSAT) providers while analyzing the revenue contribution of major companies
  • Verifying and cross-checking estimates at every level through discussions with key opinion leaders, including company executives, directors, operations managers, and semiconductor industry experts.
  • Studying paid and unpaid information sources, including annual reports, investor presentations, press releases, technical papers, industry publications, and government documents

The top-down approach was used to estimate and validate the total size of the semiconductor manufacturing equipment market.

  • Analyzing global semiconductor manufacturing equipment market revenue and overall semiconductor industry investment trends
  • Calculating market size using revenue generated by major players through semiconductor manufacturing equipment sales
  • Segmenting the market by manufacturing phase, front-end equipment, back-end equipment, end user, and region to derive segment-level market estimates
  • Acquiring and analyzing information related to revenues generated by major players through their key equipment offerings
  • Conducting discussions with key opinion leaders involved in semiconductor fabrication, wafer processing, advanced packaging, and semiconductor testing equipment
  • Estimating geographic market distribution using secondary sources and factors such as semiconductor fabrication capacity, equipment installations, manufacturing investments, and the presence of major semiconductor manufacturers in each country and region.

The market size includes the following:

Semiconductor Manufacturing Equipment Market Top Down and Bottom Up Approach

Data Triangulation

After arriving at the overall market size using the market size estimation processes explained above, the semiconductor manufacturing equipment market has been divided into several segments and subsegments. Data triangulation and market breakdown procedures have been employed to complete the market engineering process and determine the market size of each segment and subsegment. The data has been triangulated by analyzing factors and trends from the demand and supply sides of the semiconductor manufacturing equipment market.

Market Definition

The semiconductor manufacturing equipment market comprises equipment used to manufacture, process, assemble, inspect, and test semiconductor devices. The market includes front-end equipment, such as lithography, deposition, etching, and wafer cleaning systems, and back-end equipment used for semiconductor assembly, packaging, and testing. These technologies support the production of logic, memory, analog, and other semiconductor devices. The equipment is used by foundries, integrated device manufacturers (IDMs), and outsourced semiconductor assembly and test (OSAT) providers. The market covers equipment sales used in semiconductor fabrication, wafer processing, assembly, packaging, inspection, and testing.

Key Stakeholders

  • Raw Material Suppliers
  • Component and Subsystem Suppliers
  • Semiconductor Equipment Manufacturers
  • Technology Solution Providers
  • IDMs (Integrated Device Manufacturers) and Foundries
  • Chip Designers
  • Software Developers
  • Third-party Service Providers
  • Distributors and Resellers
  • Service Providers
  • Regulatory Bodies
  • Research and Development Institutes
  • End Users

Report Objectives

  • To define, describe, and forecast the size of the semiconductor manufacturing equipment market, by manufacturing phase, front-end equipment, back-end equipment, end user, and region, in terms of value
  • To describe and forecast the size of the semiconductor manufacturing equipment market, by front-end equipment, in terms of volume
  • To forecast the market for various segments with respect to the main regions, namely, the Americas; Asia Pacific; and Europe, the Middle East, and Africa (EMEA), in terms of value
  • To provide global macroeconomic outlooks
  • To provide detailed information regarding the drivers, restraints, opportunities, and challenges influencing the market’s growth
  • To strategically analyze micromarkets with respect to individual growth trends, prospects, and contributions to the total market
  • To provide ecosystem analysis, value chain, unmet needs and white spaces, interconnected market and cross-sector opportunities, trends/disruptions impacting customer business, technology analysis, pricing analysis, key stakeholders and buying criteria, case study analysis, trade analysis, patent analysis, Porter’s five forces, key conferences and events, AI impact, impact of 2025 US tariff, and regulations related to the semiconductor manufacturing equipment market
  • To analyze the opportunities in the market for stakeholders by identifying high-growth segments and detailing the competitive landscape for market players
  • To strategically profile key players and comprehensively analyze their market rankings, core competencies, company valuation, and financial metrics, and product/brand comparison, along with detailing the competitive landscape for the market leaders
  • To analyze the competitive strategies, such as equipment launches, expansions, agreements, collaborations, and acquisitions, undertaken by market players
  • To benchmark players within the market using the competitive leadership mapping framework, which analyzes market players on various parameters within the broad categories of business strategy excellence and strength of product portfolio

Available customizations:

With the given market data, MarketsandMarkets offers customizations according to the company‘s specific needs. The following customization options are available for the report.

Company Information:

  • Detailed analysis and profiling of additional market players (up to five)


Key Questions Addressed by the Report

What is the projected market value of the Semiconductor Manufacturing Equipment market?

The Semiconductor Manufacturing Equipment market is projected to reach a substantial market value by the forecast period, driven by increasing demand for advanced chips across various industries.

Which region is expected to dominate the Semiconductor Manufacturing Equipment market?

Asia Pacific is expected to dominate the Semiconductor Manufacturing Equipment market due to the strong presence of semiconductor fabrication facilities in countries such as Taiwan, South Korea, China, and Japan.

What are the key segments of the Semiconductor Manufacturing Equipment market?

The market is segmented by equipment type, dimension, application, and region, with front-end equipment and integrated circuit manufacturing accounting for a major share.

Who are the major key players in the Semiconductor Manufacturing Equipment market?

Major key players in the Semiconductor Manufacturing Equipment market include ASML Holding NV, Applied Materials, Inc., Lam Research Corporation, Tokyo Electron Limited, and KLA Corporation.

What factors are driving the growth of the Semiconductor Manufacturing Equipment market?

The growth of the Semiconductor Manufacturing Equipment market is driven by rising demand for consumer electronics, expansion of data centers, advancements in AI and 5G technologies, and increasing investments in semiconductor fabrication plants.

Personalize This Research

  • Triangulate with your Own Data
  • Get Data as per your Format and Definition
  • Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
  • Any level of Personalization
Request A Free Customisation

Let Us Help You

  • What are the Known and Unknown Adjacencies Impacting the Semiconductor Manufacturing Equipment Market
  • What will your New Revenue Sources be?
  • Who will be your Top Customer; what will make them switch?
  • Defend your Market Share or Win Competitors
  • Get a Scorecard for Target Partners
Customized Workshop Request

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements

Get 10% Free Customisation

TESTIMONIALS

Growth opportunities and latent adjacency in Semiconductor Manufacturing Equipment Market

avtar

Ed

Jan, 2025

Is there a version of this report that focuses only on the front-end equipment market?.

THIS REPORT TELLS YOU

How big the Semiconductor Manufacturing Equipment market is, and who leads it.

GROWTHIQ TELLS YOU NEW

Where your company should play next, and who is taking your share.

Get your company's view of this market. Free snapshot.

DMCA.com Protection Status
popup img