Active Wound Care Market

Active Wound Care Market by Product Type (Biological Skin Substitutes (Human donor, Animal derived), Biosynthetic Skin Substitutes, Topical Agents), Wound Type (Diabetic Foot, Venous Leg Ulcers, Pressure Ulcers, Burns) & End User - Global Forecast to 2031


ACTIVE WOUND CARE MARKET SIZE, SHARE & GROWTH SNAPSHOT
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
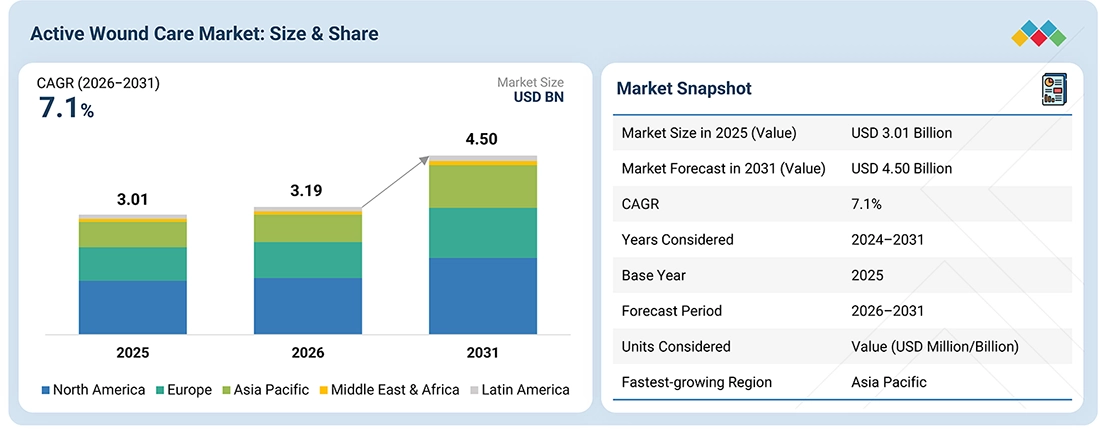
The global active wound care market is projected to grow from USD 3.19 billion in 2026 to USD 4.50 billion by 2031, at a CAGR of 7.1% during the forecast period. The market was valued at USD 3.01 billion in 2025. The market is expanding through the rising burden of diabetes, obesity, vascular disease, and aging-related chronic wounds; growing clinical use of regenerative products for hard-to-heal wounds; expansion of outpatient wound centers and specialist treatment pathways; and product innovation in burns, trauma, and complex surgical wounds. The market covers chronic wounds such as diabetic foot ulcers, venous leg ulcers, and pressure injuries, as well as acute wounds including surgical/dehisced wounds, traumatic wounds, and burns.
KEY TAKEAWAYS
-
MARKET SNAPSHOT:
Base Year Market Size (2025): USD 3.01 Billion
Current Market Size (2026): USD 3.19 Billion
Forecast Market Size (2031): USD 4.50 Billion
CAGR (2026–2031): 7.1% -
SEGMENT LEADERSHIP:
Regional Leader: North America accounted for the largest regional market share of 44.9% in 2025.
Product Leader: Biological skin substitutes accounted for the largest share of 56.8% in 2025.
Wound Type Leader: Chronic wounds accounted for the largest share in 2025.
End User Leader: Hospitals accounted for the largest end-user share in 2025. -
MARKET OUTLOOK & COMPETITIVE LANDSCAPE:
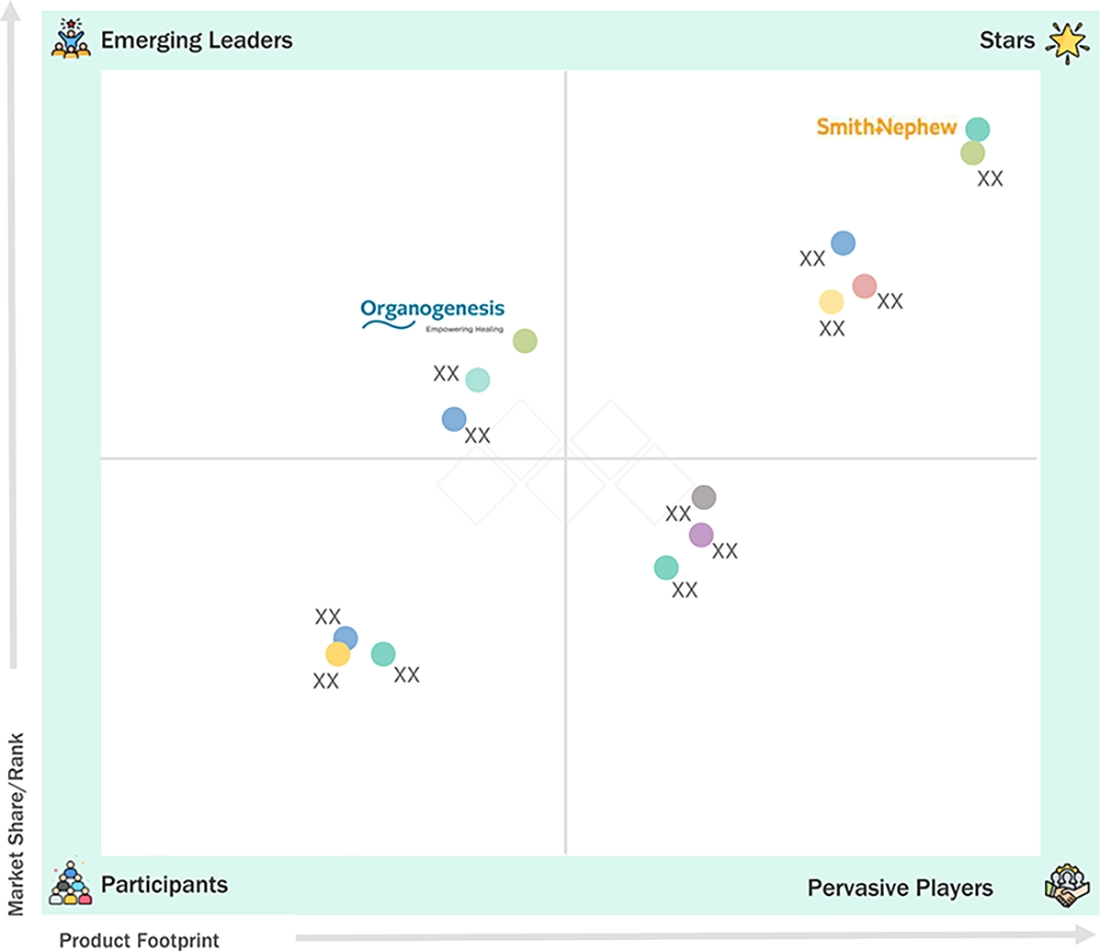
Smith+Nephew plc (UK), MIMEDX Group, Inc. (US), Integra LifeSciences Holdings Corporation (US), and Coloplast A/S (Denmark) were identified as key players in the global active wound care market, given their strong market share and product footprint.
StimLabs LLC (US) and VIVEX Biologics, Inc. (US) have distinguished themselves among startups and SMEs by establishing strong footholds in specialized niches, underscoring their potential as emerging market leaders.
The active wound care market is moving toward evidence-backed regenerative wound management, broader use of tissue and extracellular matrix technologies, and growing adoption of off-the-shelf synthetic/biosynthetic matrices. Revenue growth is increasingly linked to clinical outcomes, reimbursement durability, product handling and wastage economics, and expansion beyond chronic wounds into burns, trauma, dehisced wounds, and complex surgical wounds.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
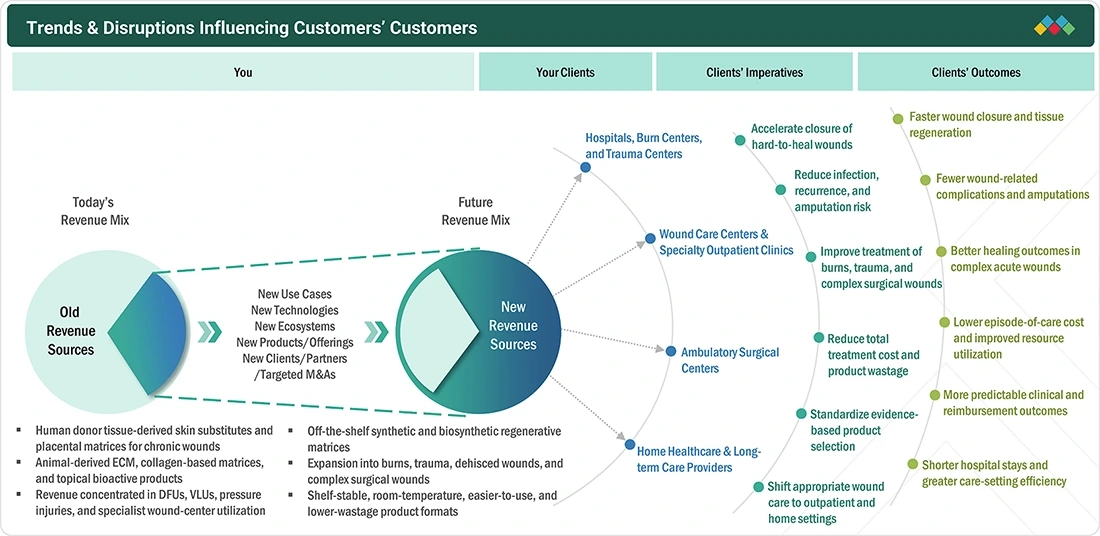
Active wound care is shifting from a market heavily centered on donor-tissue products and chronic-wound reimbursement toward a more diversified regenerative model built on evidence-backed biologic matrices, off-the-shelf synthetic/biosynthetic products, acute and surgical wound applications, and greater focus on total treatment economics. Direct customers—including hospitals, burn and trauma centers, wound care centers, specialty outpatient clinics, ambulatory surgical centers, and home/long-term-care providers—are seeking faster wound closure, consistent clinical outcomes, easier handling, lower product wastage, reliable supply, and clearer reimbursement pathways. These shifts ultimately affect patients and payers through fewer complications and amputations, shorter care episodes, more predictable outcomes, and broader access to advanced wound-healing therapies.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Level
-
Rising burden of diabetes, obesity, vascular disease, and aging-related chronic wounds

-
Growing clinical use of regenerative products for hard-to-heal wounds


Level
-
High acquisition cost and dependence on reimbursement


Level
-
Growing adoption of off-the-shelf synthetic and biosynthetic matrices

-
Expansion into burns, trauma, dehisced wounds, and complex surgical wounds


Level
-
Changing product classification, coding, coverage, and payment policies

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Rising burden of diabetes, obesity, vascular disease, and aging-related chronic wounds
The increasing prevalence of diabetes, obesity, vascular disease, immobility, and age-related comorbidities is expanding the pool of diabetic foot ulcers, venous leg ulcers, pressure injuries, and other hard-to-heal chronic wounds that may require active regenerative treatment.
Restraint: High acquisition cost and dependence on reimbursement
Many regenerative products have high acquisition costs, and utilization depends on coding, payer coverage, payment rates, provider economics, and documentation requirements, making demand sensitive to reimbursement changes.
Opportunity: Growing adoption of off-the-shelf synthetic and biosynthetic matrices
Synthetic and biosynthetic matrices can provide standardized manufacturing, predictable availability, simpler logistics, and potential room-temperature storage, reducing dependence on donor tissue while supporting tissue ingrowth and reconstruction.
Challenge: Changing product classification, coding, coverage, and payment policies
Active wound products span tissue, device, drug, and biologic pathways, and shifts in regulatory classification, coding rules, covered-product lists, and payment methodology can materially change commercialization economics.
ACTIVE WOUND CARE MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Through products such as GRAFIX, STRAVIX, and OASIS, the company provides placental tissue and extracellular matrix solutions for diabetic foot ulcers, venous leg ulcers, surgical wounds, and other difficult-to-heal wounds | Supports tissue regeneration and wound closure, provides advanced options for complex chronic wounds, and may help reduce prolonged treatment and wound-related complications |
 |
Provides regenerative wound care products such as Apligraf, PuraPly, NuShield, and Affinity for chronic and complex wounds, particularly diabetic foot ulcers and venous leg ulcers, across wound centers and outpatient care settings | Enables biologically active wound management, supports granulation and tissue repair, broadens treatment options for non-healing wounds, and supports specialist outpatient wound care pathways |
 |
Provides intact fish-skin regenerative matrices for diabetic foot ulcers, vascular ulcers, burns, surgical wounds, and other complex wounds through the Kerecis portfolio | Provides an off-the-shelf regenerative scaffold, supports tissue ingrowth and wound healing, offers differentiated animal-derived ECM technology, and expands treatment options across chronic and acute wounds |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
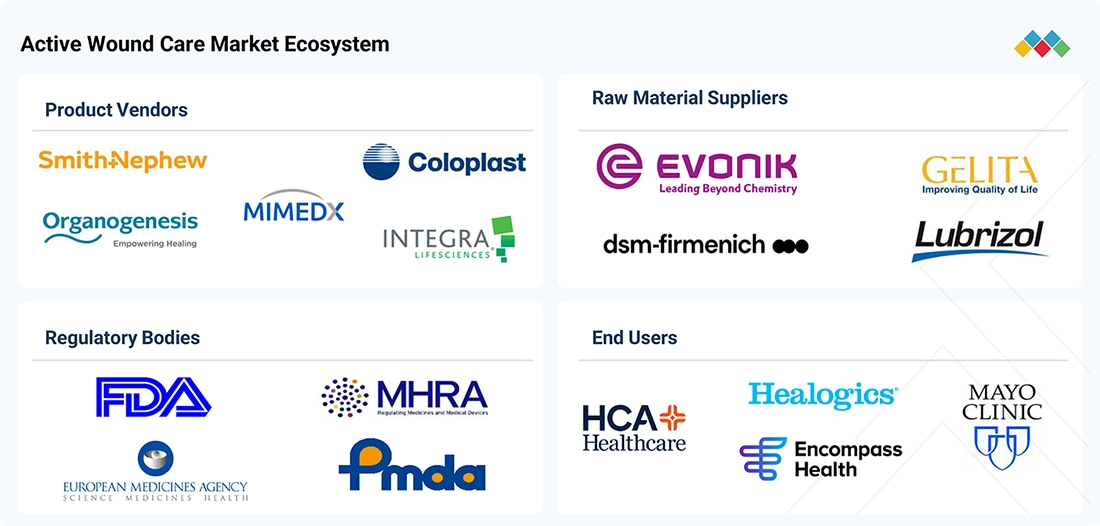
The global active wound care market is a specialized ecosystem involving skin substitute manufacturers, biotech and regenerative medicine firms, tissue banks, growth factor developers, biomaterial suppliers, contract manufacturers, hospitals, wound care centers, and regulatory authorities. These product providers develop cellular and acellular skin substitutes, ECM products, placental tissues, collagen matrices, and growth factor therapies to aid tissue regeneration and wound healing. Hospitals and wound clinics use these products where conventional methods fail. Tissue banks and biologic material suppliers provide human tissue, ECM, collagen, and other biological materials, while biotech firms contribute cell processing, tissue engineering, biomaterials, and growth factors. Manufacturers depend on CDMOs, sterilization, packaging, and distribution networks for product support. Regulatory and reimbursement bodies influence market adoption through standards on biologics, donor screening, manufacturing, clinical evidence, approval, and reimbursement. Healthcare providers and payers assess products by outcomes, healing rates, recurrence, cost-effectiveness, and total care costs. Advances in regenerative medicine, tissue engineering, ECM therapies, placental products, biomaterials, and growth factors drive the ecosystem, with rising demand for chronic wound solutions.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
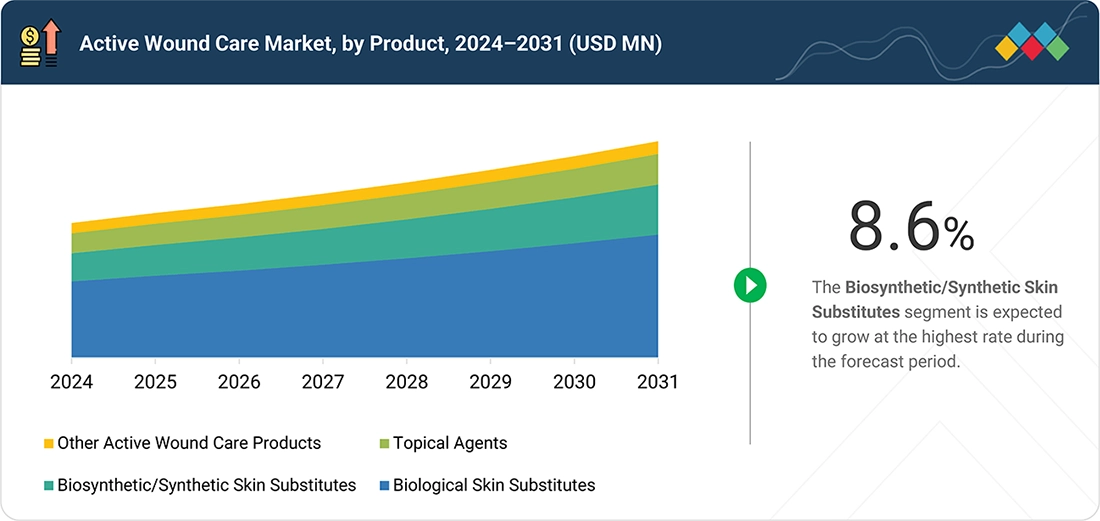
Global Active Wound Care Market, by Product Type
In 2025, biological skin substitutes held the largest share of the active wound care market, supported by their growing use in chronic and complex wounds and the availability of human donor tissue-derived and animal-derived products. Human donor products include cellular/viable and acellular tissue products, while animal-derived products include regenerative extracellular-matrix technologies. These products are increasingly used in diabetic foot ulcers, venous leg ulcers, pressure injuries, burns, and surgical wounds where conventional wound management may be insufficient. Biosynthetic/synthetic skin substitutes are expected to gain adoption due to standardized manufacturing, off-the-shelf availability, storage advantages, and expanding use in burns, trauma, and complex surgical wounds.
Global Active Wound Care Market, by Wound Type
In 2025, chronic wounds accounted for the largest share of the active wound care market because of the high and recurring burden of diabetic foot ulcers, venous leg ulcers, and pressure injuries. These wounds frequently require prolonged treatment and are associated with diabetes, vascular disease, neuropathy, immobility, and aging. Active regenerative products are increasingly used to stimulate tissue repair and wound closure in difficult-to-heal cases. Acute wounds, including surgical and dehisced wounds, traumatic wounds, burns, and donor/graft sites, are also gaining importance as regenerative matrices and skin substitutes expand into reconstructive and hospital-based applications.
Global Active Wound Care Market, by End User
In 2025, hospitals accounted for the largest end-user share, supported by the management of severe and complex chronic wounds, burns, trauma, surgical wound dehiscence, and patients requiring grafting or reconstructive procedures. Hospitals also provide access to multidisciplinary wound teams, surgeons, burn specialists, and advanced regenerative technologies. Wound care centers and specialty clinics represent another major segment because they provide recurring treatment for DFUs, VLUs, and other non-healing wounds. Ambulatory surgical centers and home healthcare settings are gaining importance as suitable wound-management procedures and follow-up care increasingly shift toward outpatient and post-acute settings.
REGION
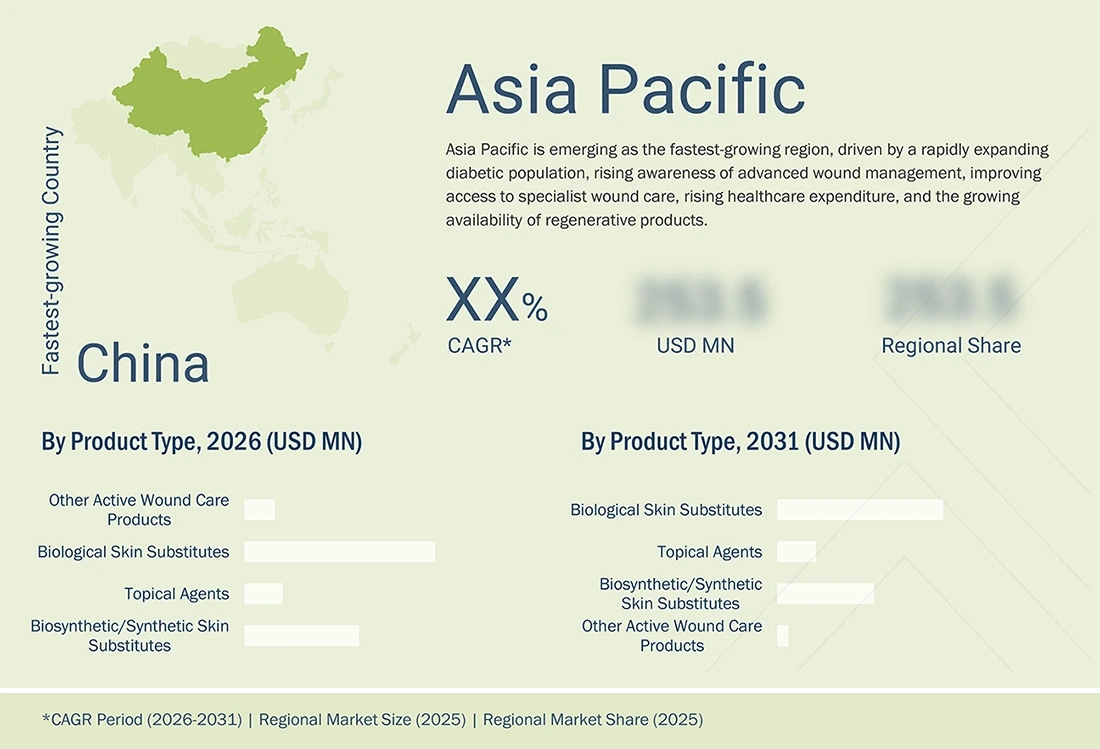
Asia Pacific to be fastest-growing region in market during forecast period
During the forecast period, Asia Pacific is expected to register the highest CAGR in the active wound care market, driven by a rapidly expanding diabetic population, rising chronic wound incidence, improving specialist wound-care infrastructure, and growing adoption of regenerative wound products. China is expanding hospital and specialty-care capacity, while Japan and South Korea benefit from comparatively advanced healthcare infrastructure and growing adoption of regenerative technologies. India is witnessing rising investment in private hospitals and diabetic-foot management, while Australia has an established burn, reconstructive, and advanced wound-care ecosystem. Regional growth is further supported by increasing healthcare expenditure, expanding surgical volumes, greater physician awareness, and growing availability of biological and synthetic wound matrices. North America is expected to retain the largest market share in 2025 because of its established wound-care infrastructure, high utilization of skin substitutes and regenerative matrices, strong specialist wound-center network, reimbursement availability, and concentration of leading active wound care manufacturers.
ACTIVE WOUND CARE MARKET: COMPANY EVALUATION MATRIX
Smith+Nephew plc is positioned as a Star in the active wound care market, supported by its leading market share and broad regenerative wound-care footprint. Its portfolio spans placental and umbilical tissue products, extracellular-matrix technologies, and other bioactive wound products through brands such as GRAFIX, STRAVIX, and OASIS. Its global hospital and wound-care commercial infrastructure, clinical evidence, reimbursement capabilities, and presence across chronic, surgical, and complex wounds strengthen its market leadership. Organogenesis Holdings Inc. is positioned as a strong Emerging Leader, supported by one of the industry's broadest dedicated regenerative wound portfolios, including Apligraf, PuraPly, Affinity, and NuShield. Its substantial market share, clinical evidence base, specialized wound-center presence, and strong US commercial position support its competitive standing, although its geographic footprint is comparatively more concentrated than that of Smith+Nephew.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2025 (Value) | USD 3.01 Billion |
| Market Forecast in 2026 (Value) | USD 3.19 Billion |
| Market Forecast in 2031 (Value) | USD 4.50 Billion |
| Growth Rate | CAGR of 7.1 from 2026-2031 |
| Years Considered | 2024–2031 |
| Base Year | 2025 |
| Forecast Period | 2026–2031 |
| Units Considered | Value (USD Million/Billion) |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered |
|
| Regions Covered | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
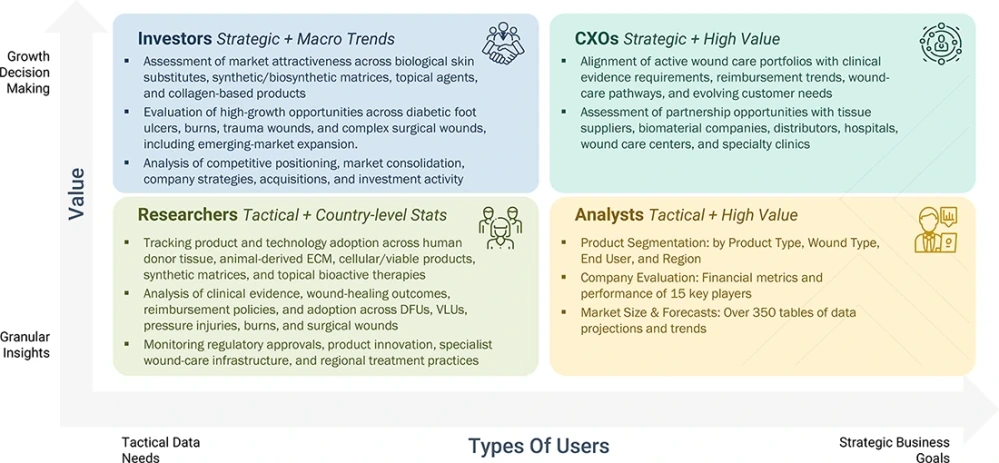
WHAT IS IN IT FOR YOU: ACTIVE WOUND CARE MARKET REPORT CONTENT GUIDE
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Evaluate the competitive positioning of key players in the active wound care market | Benchmarked leading companies across biological skin substitutes, human donor tissue-derived products, animal-derived ECM, biosynthetic/synthetic matrices, topical agents, and collagen-based products. The assessment considered estimated market share, product breadth, wound-type coverage, clinical evidence, regulatory status, reimbursement positioning, geographic presence, specialist commercial reach, manufacturing capabilities, and recent strategic developments. | Identifies competitive gaps, partnership and acquisition opportunities, portfolio differentiation strategies, and potential right-to-win areas across chronic wound management, burns, trauma, and complex surgical wound applications. |
| Assess high-growth product technologies and segment opportunities in active wound care | Evaluated growth potential across placental and human tissue-derived products, animal-derived ECM matrices, synthetic/biosynthetic skin substitutes, collagen-based regenerative matrices, and bioactive topical agents. The analysis also assessed adoption across diabetic foot ulcers, venous leg ulcers, pressure injuries, burns, traumatic wounds, and complex surgical wounds, along with differences by end user and geography. | Supports investment prioritization, product-development planning, clinical-evidence strategy, reimbursement planning, and geographic expansion decisions, particularly for off-the-shelf synthetic matrices, evidence-backed biologics, acute/surgical wound applications, and emerging-market opportunities. |
RECENT DEVELOPMENTS
- July 2026 : MIMEDX Group, Inc. entered into a definitive agreement to acquire Sanara MedTech Inc. in a cash-and-stock transaction with an enterprise value of approximately USD 350 million. The transaction is intended to substantially expand MIMEDX's surgical regenerative-medicine footprint and add Sanara's regenerative and collagen-based technologies, as well as its hospital/surgeon relationships.
- July 2026 : Organogenesis Holdings Inc. announced peer-reviewed randomized clinical trial results for Affinity in complex venous leg ulcers. The study demonstrated statistically significant improvements in wound closure at weeks 12 and 16 for Affinity plus standard of care compared with standard of care alone, strengthening the clinical evidence base for regenerative products in difficult-to-heal VLUs.
- March 2026 : MIMEDX launched CHORIOFIX, expanding its advanced wound care portfolio of placental allografts. CHORIOFIX consists of two chorion layers with an intact intermediate layer and is designed to provide greater thickness and improved handling during positioning and suturing, supporting its use in complex wound-care applications.
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
Methodology
This study involved four major activities in estimating the current size of the active wound care market. Exhaustive secondary research was conducted to collect information on the market, its peer markets, wound prevalence and incidence, treatment practices, reimbursement environment, product utilization, and the broader wound management ecosystem. The findings, assumptions, and market-sizing logic were subsequently validated through primary research with participants across the value chain. Both top-down and bottom-up approaches were used to estimate the complete market. Following this, data triangulation was applied to finalize the overall market size and the values of individual segments and subsegments.
Secondary Research
Secondary research was used to identify and gather information for this extensive technical, market-oriented, and commercial study. Public-sector and institutional sources included the US Food and Drug Administration (FDA), Centers for Medicare & Medicaid Services (CMS), Centers for Disease Control and Prevention (CDC), National Institutes of Health (NIH), Agency for Healthcare Research and Quality (AHRQ), World Health Organization (WHO), European Medicines Agency (EMA), European Commission, national health ministries, national reimbursement authorities, and relevant public health databases.
Clinical and professional sources included publications and guidance from organizations involved in diabetes, diabetic foot management, pressure injury prevention, vascular disease, burns, tissue repair, and wound management. These included wound care and tissue-repair associations, diabetic-foot working groups, pressure-injury organizations, vascular and surgical societies, and peer-reviewed clinical literature. Epidemiological data on diabetes, diabetic foot ulcers, venous leg ulcers, pressure injuries, burns, surgical wounds, and other chronic and acute wounds were also reviewed to understand the addressable patient population.
Company and industry sources included annual reports, SEC and other regulatory filings, investor presentations, earnings releases, product catalogs, regulatory databases, company websites, reimbursement documents, clinical-trial registries, scientific publications, peer-reviewed journals, and industry association publications. These sources were used to identify major participants, active wound care product portfolios, regulatory approvals, product indications, revenue exposure, geographic presence, commercial developments, reimbursement status, product launches, acquisitions, partnerships, and expansion activities.
Secondary data were analyzed to estimate the overall active wound care market and construct preliminary splits by product type, wound type, end user, and region. Key inputs included company revenues, product-level revenue exposure, addressable wound populations, treatment rates, utilization of active wound care products, product pricing, reimbursement levels, clinical practice patterns, and geographic adoption. The resulting estimates were subsequently validated and refined through primary research.
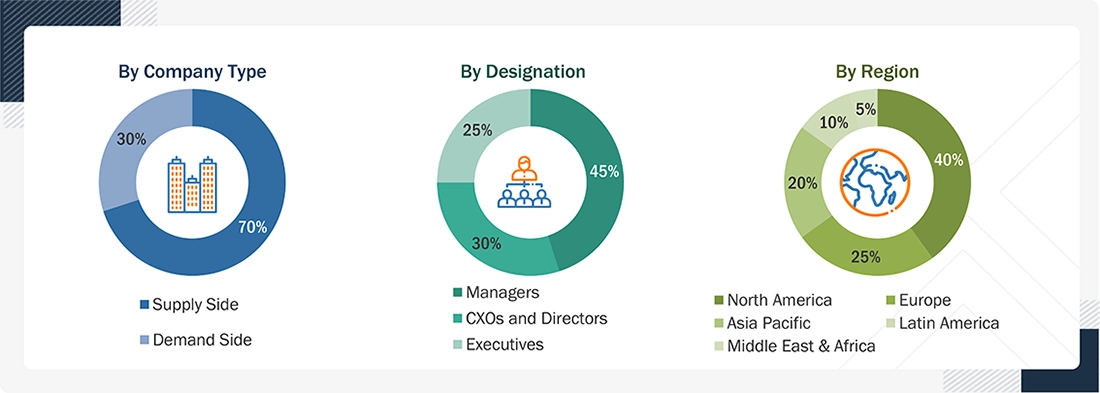
Primary Research
In-depth interviews were conducted with primary respondents across both the supply and demand sides of the active wound care ecosystem. Supply-side respondents included executives and managers from active wound care manufacturers, regenerative medicine companies, tissue-product manufacturers, biomaterials companies, distributors, product managers, commercial leaders, business-development professionals, regulatory specialists, and subject-matter experts.
Demand-side respondents included wound care physicians, podiatrists, vascular surgeons, plastic and reconstructive surgeons, dermatologists, burn-care specialists, wound care nurses, hospital procurement professionals, wound care center personnel, ambulatory care professionals, and other clinicians involved in chronic and acute wound management.
Primary interviews were used to validate market definitions, product inclusions and exclusions, adoption levels, average selling prices, reimbursement trends, patient and procedure volumes, product utilization rates, frequency of product application, treatment duration, product mix, regional variations, end-user behavior, competitive positioning, and market-growth assumptions.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
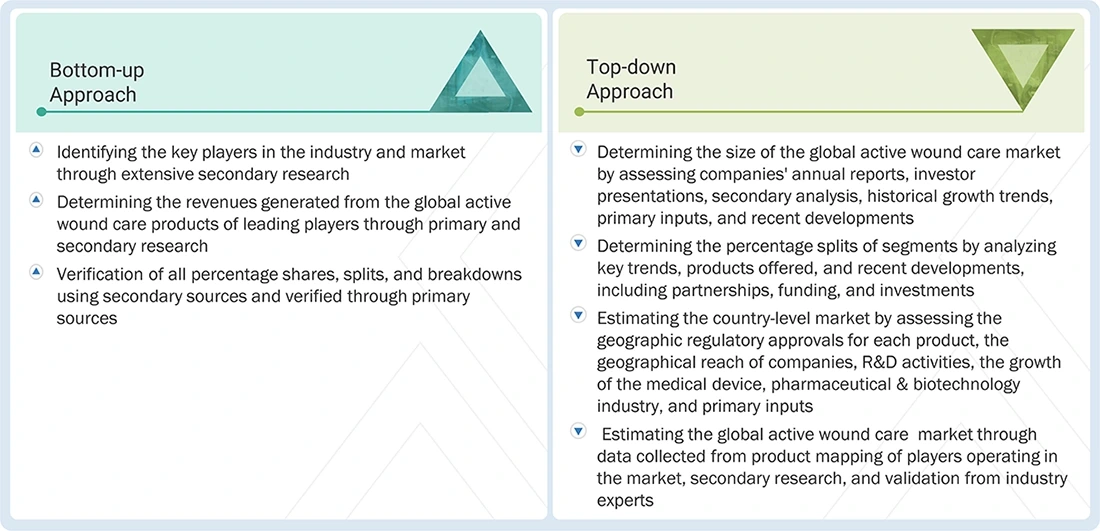
The global active wound care market was estimated through multiple complementary approaches. A detailed market-engineering model was used to estimate and validate the overall market and each segment. The process combined company-level revenue analysis, product portfolio mapping, wound prevalence and incidence assessment, eligible treated-patient estimation, product-utilization analysis, average selling price analysis, reimbursement assessment, end-user demand estimation, and regional adoption patterns. The research methodology used to estimate the market size included the following:
Active Wound Care Market : Top-Down and Bottom-Up Approach
Data Triangulation
After estimating the overall market through the market-size estimation process, the total market was split into the defined segments and subsegments. To complete the market-engineering process and arrive at the final statistics, data triangulation was employed. The process examined factors and trends from both the demand and supply sides and reconciled company revenues, active wound care product sales, wound prevalence and incidence, eligible treated-patient populations, product utilization rates, units per treatment episode, average selling prices, reimbursement levels, clinical practice patterns, end-user adoption, and regional market conditions.
The final estimates were checked for consistency across all dimensions. For example, the product totals were reconciled with wound type, end user, and regional totals. Company-share estimates were also compared with the independently derived global market size to ensure that no major revenue pools were omitted or double-counted.
Market Definition
Active wound care refers to products designed to actively support, stimulate, or modulate the biological wound-healing process rather than functioning solely as passive wound coverings. These products provide viable cells, extracellular matrix components, biological tissue scaffolds, bioengineered structures, synthetic regenerative matrices, collagen-based matrices, growth factors, cytokines, or other bioactive components intended to promote granulation, tissue regeneration, re-epithelialization, wound closure, and restoration of damaged tissue.
Key Stakeholders
- Manufacturers of active wound care products
- Manufacturers of biological skin substitutes
- Human donor tissue processors and tissue banks
- Manufacturers of animal-derived regenerative matrices
- Biosynthetic and synthetic skin substitute manufacturers
- Biomaterials and regenerative medicine companies
- Growth factor- and cytokine-based topical product manufacturers
- Collagen-based wound care product manufacturers
- Contract manufacturers and raw-material suppliers supporting active wound care products
- Distributors, wholesalers, and specialty wound care product suppliers
- Hospitals and health systems
- Wound care centers and specialty clinics
- Burn centers and trauma centers
- Ambulatory surgical centers
- Home healthcare providers
- Long-term care and community health centers
- Wound care physicians and wound management specialists
- Podiatrists, vascular surgeons, plastic surgeons, dermatologists, and burn specialists
- Wound care nurses and other allied healthcare professionals
- Government and private healthcare payers
- Reimbursement authorities and health technology assessment bodies
- Regulatory agencies
- Research institutes and academic centers
- Group purchasing organizations and hospital procurement organizations
- Market research and consulting firms
- Private equity firms, venture capitalists, and other investors
Report Objectives
- To define, describe, segment, and forecast the global active wound care market by product type, wound type, end user, and region
- To provide detailed information regarding the major factors influencing market growth, including drivers, restraints, opportunities, and challenges
- To analyze micromarkets with respect to individual growth trends, prospects, and contributions to the overall active wound care market
- To analyze market opportunities for stakeholders and provide details of the competitive landscape for key players
- To forecast the size of the market segments with respect to North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa
- To profile the key players and comprehensively analyze their product portfolios, market positions, and core competencies
- To track and analyze company developments such as product launches & approvals, partnerships, acquisitions, agreements, collaborations, expansions, and other developments
- To benchmark players within the market using the proprietary “Company Evaluation Matrix” framework, which analyzes market players on various parameters within the broad categories of business and product excellence strategy
Available customizations:
With the given market data, MarketsandMarkets offers customizations as per the company’s specific needs. The following customization options are available for the report:
Geographical Analysis
- Further breakdown of the Rest of Europe Active Wound Care Market, by country
- Further breakdown of the Rest of Asia Pacific Active Wound Care Market, by country
Company Information
- Detailed analysis and profiling of additional market players (up to five)
Segment Analysis
- Cross-segment analysis


Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the Active Wound Care Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Custom Market Research Services
We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements
Get 10% Free CustomisationTESTIMONIALS
JAYANT RAJPUROHIT
Director of Market Insights, Data and Analytics
SFI Health,
Leading Pharmaceutical Companywww.sfihealth.com/
We at SFI Health approached MarketsandMarkets for an Opportunity Assessment on "Incidence and Prevalence of Focus Indications" as we wanted to know the most attractive HCPs like Physician, Functional MD, Naturopath and Pharmacist. The project was critical for us to ensure our focus on the right target which would enable sustainable growth and profitability for SFI Health. The business insights provided exceeded our expectations and we were extremely impressed. The team at MarketsandMarkets is highly professional and detail oriented and very well understood our business needs. MarketsandMarkets offers a unique combination of expertise and dedicated engagement model. We identified 2 new products to be launched in coming months, based on the research findings provided by MarketsandMarkets. We are happy with the services and would strongly recommend MarketsandMarkets to my peers in the industry.
BEATRIZ DE LA CALLE
Head of Commercial Analytics
Qualicaps,
Leading Pharmaceutical Companywww.qualicaps.com/
We partnered with MarketsandMarkets for an assessment study on hard empty capsules. The team was extremely professional in understanding our business requirements and we received timely responses to all our queries. The market intelligence and the recommendations has met our business requirements. We were extremely impressed to see the final study results; it really exceeded our expectations. The market intelligence offered by MarketsandMarkets, and clarity on next steps will help us achieve our business objective for the Year 2021. We are happy with the services and would strongly recommend MarketsandMarkets to my peers in the industry.

Bob Williams,
Senior Director Business Development & Innovation
Bracco Diagnostics Inc.,
Italian Multinational in life sciences sector and a World Leader in imaging diagnosticsimaging.bracco.com/us-en
We were pleased with targeted insights that MarketsandMarkets identified from a custom study on the 'Radiation Dose Management Solutions Market'. Your team identified and characterized the market participants as well as underlying trends accurately. This study was useful to Bracco in formulating business strategies for our dose monitoring product lines and we thank MarketsandMarkets for the job well done.
Cody Coonradt,
Market Development and Strategy Manager
3M Health Information Systems,
Leader in Health care Coding, Payment & Analytics Solutions.www.3m.com/3M/en_US/health-information-systems-us
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarketsandMarkets, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer.
Their customer first approach and high value engagement model, have given us great analysis and excellent value for money





Growth opportunities and latent adjacency in Active Wound Care Market