



Biopesticides Market
Report Code
AGI 2716
Published in
Oct, 2026, By MarketsandMarkets™
Biopesticides Market by Type (Bioinsecticides, Biofungicides, Bionematicides), Crop Type (Cereals & Grains, Oilseeds & Pulses), Formulation (Liquid, Dry), Source (Microbials, Biochemicals), Mode of Application, and Region - Global Forecast To 2031

USD 20.32 Billion
MARKET SIZE, 2031

CAGR 14.5%
(2026-2031)

300+
REPORT PAGES

280+
MARKET TABLES
OVERVIEW
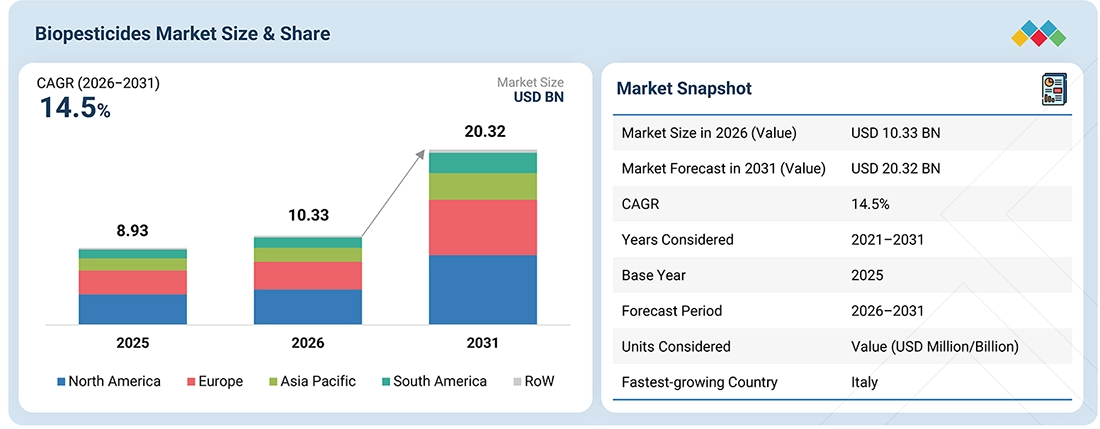
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
The global biopesticides market is estimated at USD 10.33 billion in 2026 and is projected to reach USD 20.32 billion by 2031, at a CAGR of 14.5%. The global biopesticides market is experiencing strong growth because people want sustainable crop protection solutions that do not leave any chemical residues behind. Market growth momentum also benefits from evolving regulatory requirements, which are encouraging the adoption of integrated pest management (IPM) systems, while scientists continue to create better microbial and biochemical products. Biopesticides have become a crucial growth driver for the global biological crop protection market because their use has expanded into specialty crops, fruit and vegetable farming, and row crop farming.
KEY TAKEAWAYS
-
BY REGIONEurope is projected to register a CAGR of 14.9% in the global biopesticides market during the forecast period.
-
BY TYPEBy type, the bionematicides segment is expected to register the highest CAGR of 15.7% between 2026 and 2031.
-
BY MODE OF APPLICATIONBy mode of application, the seed treatment segment is expected to register the highest CAGR.
-
BY FORMULATIONBy formulation type, the liquid segment is projected to grow at the fastest CAGR of 14.7% from 2026 to 2031.
-
BY CROP TYPEBy crop type, the fruits & vegetables segment is expected to dominate the market.
-
BY SOURCEBy source, the microbial segment is projected to grow at the fastest rate from 2026 to 2031.
-
COMPETITIVE LANDSCAPE - KEY PLAYERSCompanies such as Corteva Agriscience, Valent BioSciences, BASF, and Bayer CropScience were identified as some of the star players in the global biopesticides market, given their strong market share and product footprint.
-
COMPETITIVE LANDSCAPE - STARTUPS/SMESCompanies such as BioWorks Inc., Lallemand Plant Care, and AgBiome, among others, have distinguished themselves among startups and SMEs by securing strong footholds in specialized niche areas, underscoring their potential as emerging market leaders.
The global biopesticides market is estimated at USD 10.33 billion in 2026 and is projected to reach USD 20.32 billion by 2031, at a CAGR of 14.5%. The global biopesticides market experiences growth because farmers demand environmentally friendly methods for protecting their crops. The market shows faster expansion because new microbial and biochemical products enter the market and existing integrated pest management (IPM) systems gain wider acceptance from farmers. The agricultural industry identifies biopesticides as a highly promising growth sector because farmers now use biological products in their crop protection programs across all major crop categories, which include fruits, vegetables, and row crops.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
A primary trend in the global biopesticides market is the shift toward sustainable crop protection methods that produce minimal chemical residues. The combination of stricter pesticide regulations and growing consumer demand for safe, green products is driving both manufacturers and growers to select biological solutions as their preferred choice. Innovations in microbial and biochemical technologies enable the development of sustainable agricultural systems that increase system resilience when used with precision agriculture and integrated pest management (IPM) solutions.
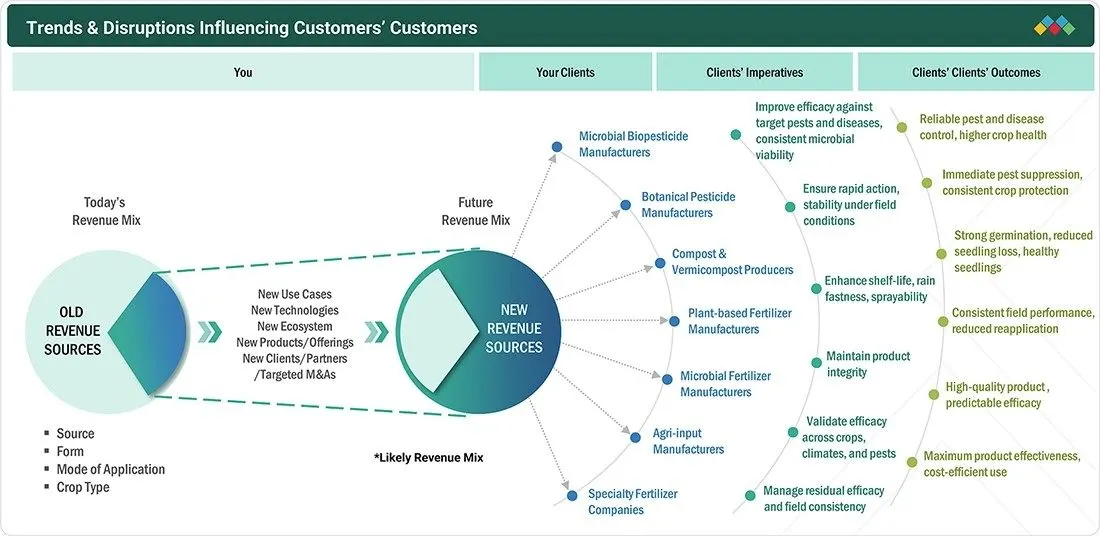
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Drivers
Impact
Level
Level
-
Stricter pesticide residue limits and sustainability-driven agricultural policies

-
Rising consumer demand for organic and chemical-free food


RESTRAINTS
Impact
Level
Level
-
Higher costs compared to conventional synthetic crop protection products

-
Variable efficacy under diverse climatic and pest conditions


OPPORTUNITIES
Impact
Level
Level
-
Expansion of organic farming and integrated pest management programs

-
Advancements in microbial formulations and precision application technologies


CHALLENGES
Impact
Level
Level
-
Fragmented regulatory standards across regions delaying product approvals

-
Limited farmer awareness and technical adoption capabilities

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Stricter pesticide residue limits and sustainability-driven agricultural policies
A key driver for the global biopesticides market is the growing emphasis on sustainable and low-residue crop protection solutions. With increasing regulation of synthetic chemicals and consumers demanding safer, eco-friendly food, both producers and growers are looking toward biological alternatives. Advances in microbial and biochemical technologies, as well as their incorporation into precision agriculture and integrated pest management systems, will further drive this trend. All of these converging trends will eventually lead to more resilient and eco-friendly farming practices worldwide.
Restraint: Higher costs compared to conventional synthetic crop protection products
A key restraint in the global biopesticides market is the cost gap between biopesticides and chemical pesticides, which is one of the most significant factors hindering market growth. Biopesticides require expert processing, fermentation, and cold chain distribution, leading to incrementally higher processing costs. Due to such cost variations, small and medium-scale farmers find it difficult to adopt these solutions, particularly in cost-conscious regions that demand an instant effect on pest control.
Opportunity: Expansion of organic farming and integrated pest management programs
A major opportunity for the global biopesticides market lies in the greater acceptance of organic farming and the growing implementation of integrated pest management (IPM) programs across regions. Governments, as well as certification bodies, are pushing for reduced chemical use. This drives further demand for biological products that comply with organic standards and residue limits, rather than synthetic products. As operations worldwide gear toward sustainable production systems, biopesticides will find their way into different components of IPM strategies, providing high long-term growth potential for microbial and biochemical products across key crop categories.
Challenge: Fragmented regulatory standards across regions delaying product approvals
A lack of consistency among the regulatory structures of various countries emerges as an issue for most biopesticide producers. Every country has its own registration processes and safety standards for biological crop protection agents. If consistency is not developed across regions, it will create hurdles for producers seeking to pursue large-scale opportunities in the global market. Addressing such issues will play an important role in the adoption of biopesticides worldwide.
BIOPESTICIDES MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Application of microbial bioinsecticides in corn and soybean farming | Enhances targeted pest control, minimizes residues, and supports sustainable row-crop systems |
 |
Use of Bacillus-based biofungicides in fruits and vegetables | Strengthens disease management, improves crop quality, and meets residue-free requirements |
 |
Integration of botanical and microbial biopesticides in specialty crops | Provides broad-spectrum protection and supports IPM while reducing synthetic pesticide use |
 |
Use of biofungicides and seed-applied biologicals in cereals and grains | Improves early-stage protection, enhances plant vigor, and promotes sustainable crop production |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
Some of the prominent companies in this market include well-established and financially sound manufacturers of biopesticide products. These companies have been operational in the market for over a decade and have diversified portfolios, the latest technologies, and excellent global sales and marketing networks. The global biopesticides ecosystem comprises manufacturers, regulatory bodies, and end users. Key manufacturers such as Corteva Agriscience, Valent BioSciences, Certis Biologicals, and BASF develop microbial, botanical, and biochemical solutions.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
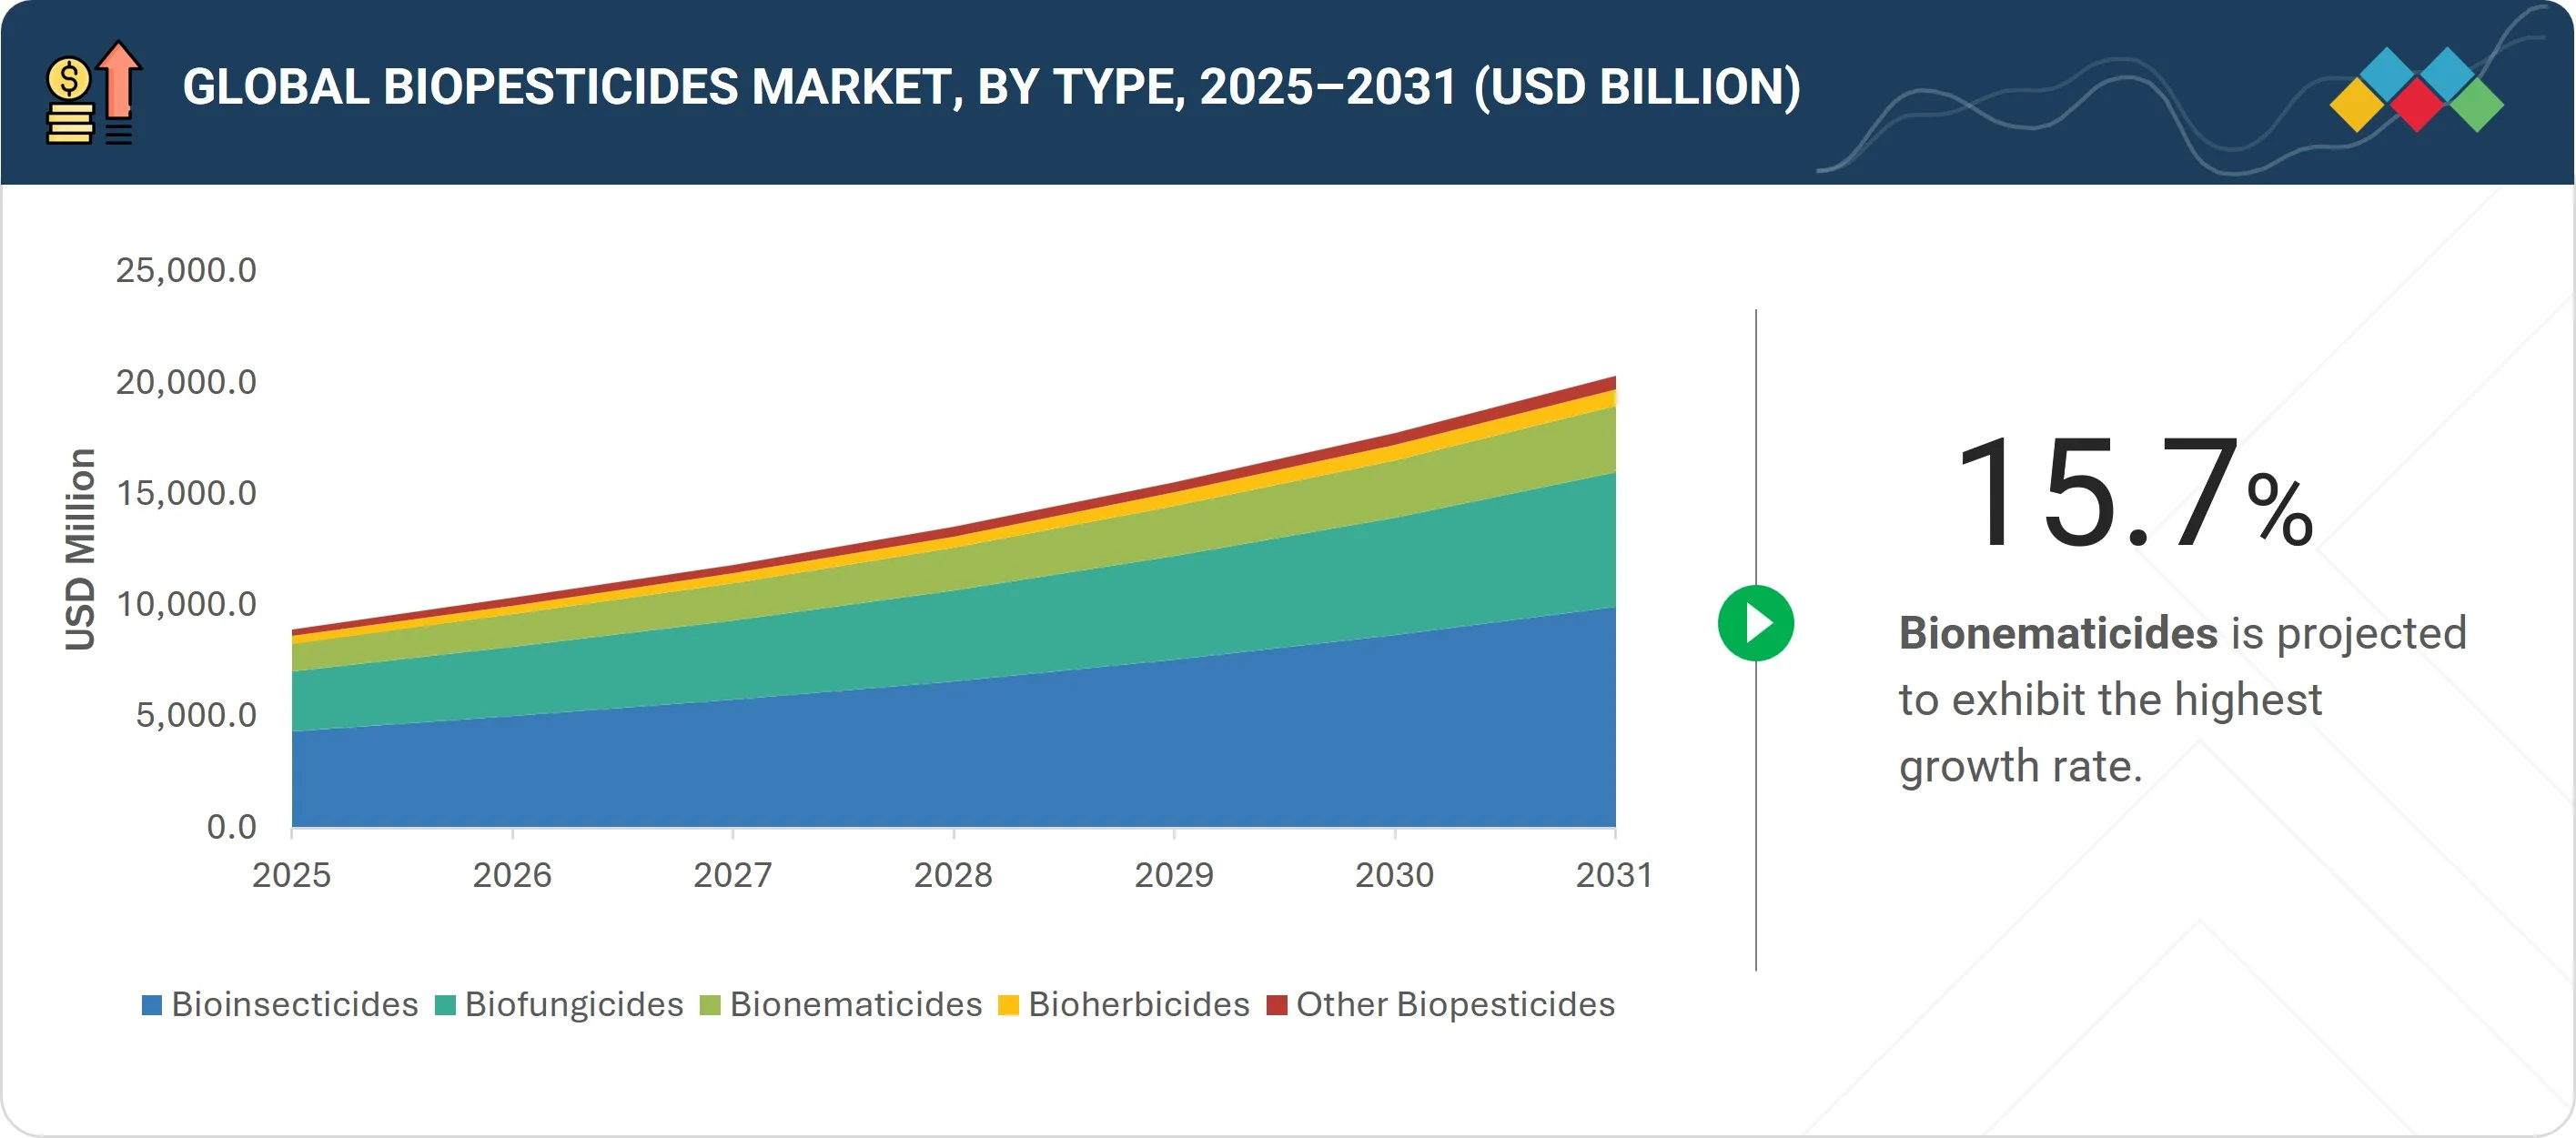
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Global Biopesticides Market, By Type
In the global biopesticides market, bioinsecticides hold the largest market share. They are being driven by a growing need for environmentally friendly substitutes for chemical insecticides, especially for fruits, vegetables, and high-value row crops. Bioinsecticides offer targeted insect pest management, lower pesticide residues in treated products, and compatibility with integrated pest management. Advances in microbial and biochemical formulation technology have also increased awareness of their advantages, enabling mass usage and securing their leadership in the type segment.
Global Biopesticides Market, By Mode of Application
In the global biopesticides market, seed treatment commands the largest share of the mode of application segment. The efficacy of seed-applied biopesticides in controlling pests, diseases, and nematodes during early crop growth stages remains uncontested. Seed treatment applications, therefore, help minimize dependency on chemical sprays, increase nutrient utilization, and fit well into various integrated pest management programs. Continuous developments in formulation stability, coating technologies, and microbial viability are promoting the adoption of biopesticides, with seed treatment as the preferred and most efficient mode of application.
Global Biopesticides Market, By Formulation
In the global biopesticides market, the liquid formulation segment holds the largest share. Factors favoring this segment include ease of application, uniform crop coverage, and compatibility with existing spraying equipment and integrated pest management programs. Liquid formulations of biopesticides provide greater stability, exhibiting higher efficacy and application flexibility across a large array of crops, including row crops, fruits, and vegetables. Continued developments in microbial and biochemical formulation technologies will further enhance product performance and drive wider acceptance, strengthening the dominance of liquid formulations in the marketplace.
Global Biopesticides Market, By Source
In the global biopesticides market, microbials represent the largest segment within the source category. Their high efficacy, specificity, and environmentally sustainable profile make them a preferred choice for managing pests, diseases, and nematodes. Widely applied across row crops, fruits, and vegetables, microbial biopesticides are compatible with integrated pest management programs and have minimal impact on non-target organisms. Ongoing advancements in strain development, formulation technologies, and delivery methods are further enhancing performance and adoption, reinforcing microbials as the dominant source in the global biopesticides market.
Global Biopesticides Market, By Crop Type
In the global biopesticides market, fruits and vegetables are the largest segment in this category due to the high economic value of these crops, strict regulations regarding pesticide residues, and increasing consumer preference for organically and sustainably grown foods. Growers are increasingly turning to microbial, biochemical, and botanical biopesticides for pest and disease management while ensuring crop quality and compliance with standards. Research advances in formulation technologies, seed treatments, and foliar applications, as well as integration into precision agriculture and integrated pest management programs, are further enhancing adoption, reinforcing fruits and vegetables as the dominant crop type segment in the global biopesticides market.
REGION
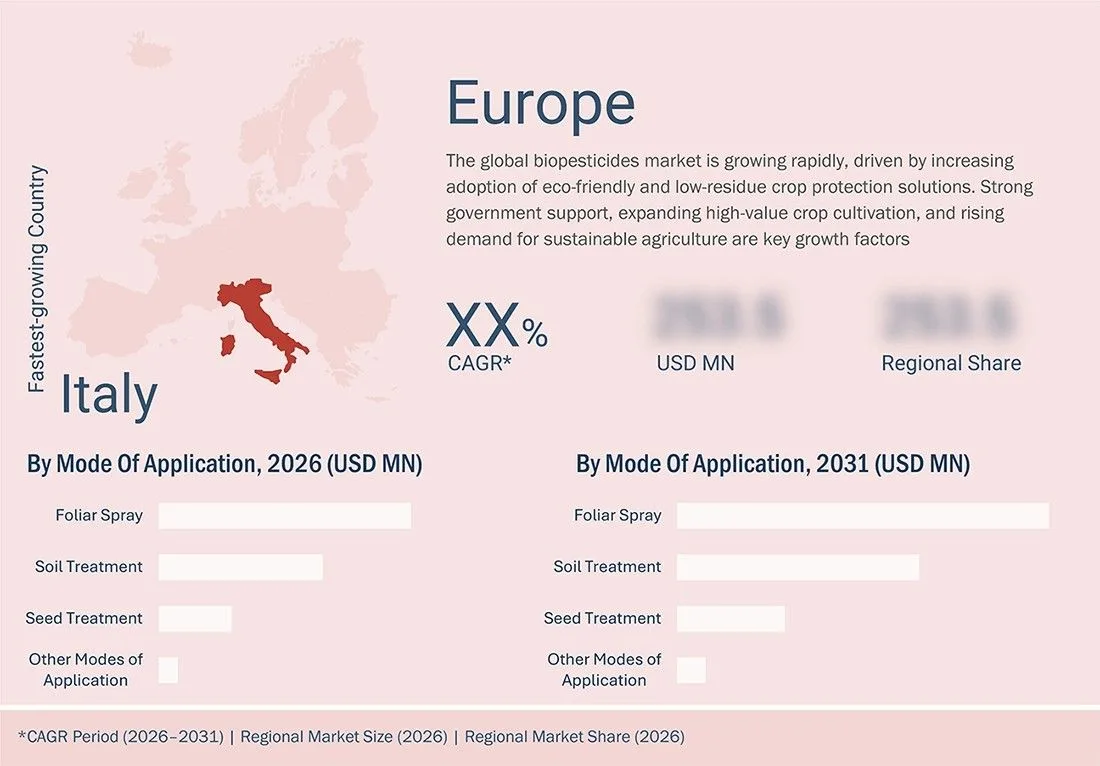
Europe to be the fastest-growing region in the global biopesticides market during the forecast period
Europe is emerging as the fastest-growing market for biopesticides globally, driven by strong government backing for sustainable farming and stricter rules on chemical pesticide use. Farmers growing fruits, vegetables, and specialty crops are increasingly turning to biological solutions to meet both safety standards and market demands. Local companies are ramping up production, investing in research, and making these products more accessible, while awareness among growers continues to grow. Together, these trends are positioning Europe as a key driver of biopesticide market growth.
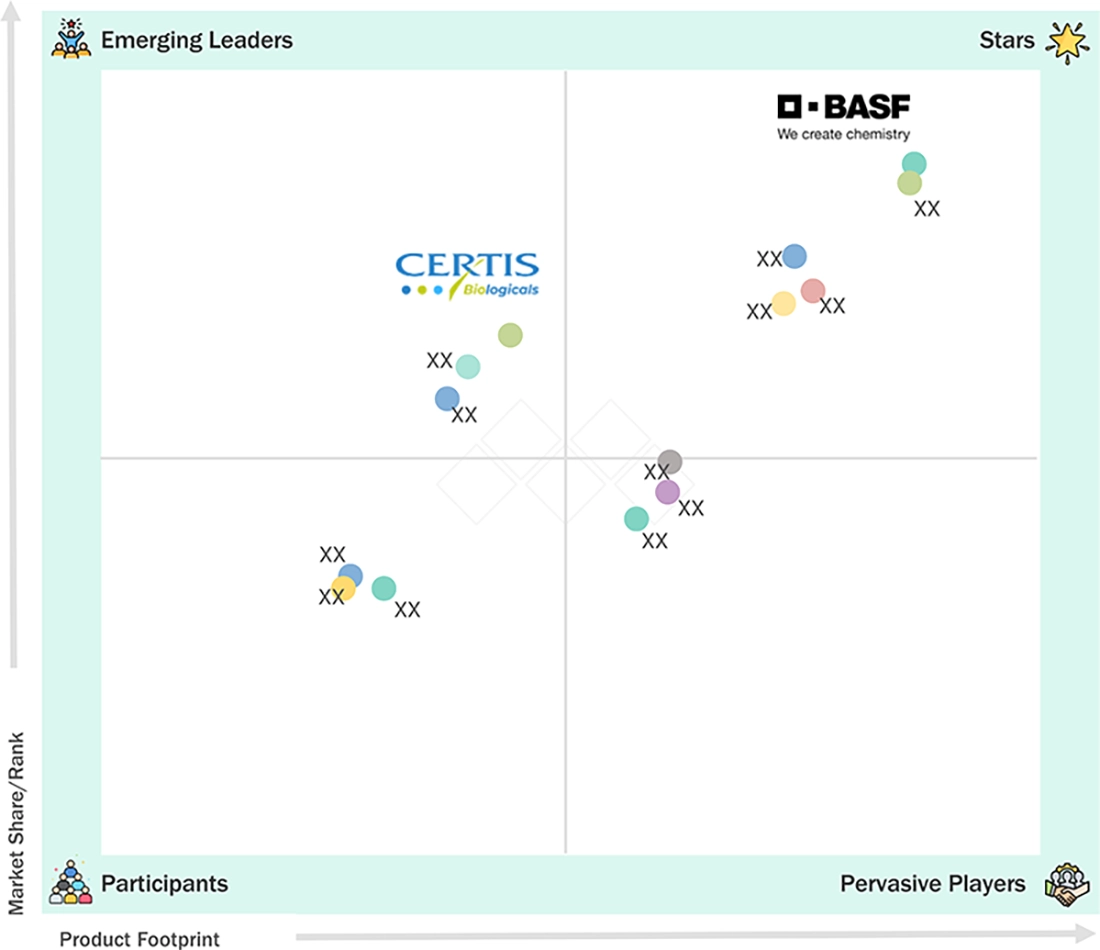
BIOPESTICIDES MARKET: COMPANY EVALUATION MATRIX
Star companies such as Corteva Agriscience, along with leading regional biopesticide manufacturers, possess broad and diversified portfolios, strong brand visibility, and significant market influence. Emerging Leaders such as AgBiome are expanding rapidly through innovative, eco-friendly biopesticides and integrated pest management solutions. Participants maintain steady operations, while Pervasive Players hold a moderate but growing market presence.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- Corteva Agriscience (US)
- Valent BioSciences (US)
- BASF (Germany)
- Bayer CropScience (Germany)
- Syngenta Group (Switzerland)
- FMC Corporation (US)
- UPL (India)
- Marrone Bio Innovations (US)
- Certis Biologicals (US)
- Koppert Biological Systems (Netherlands)
- AgBiome (US)
- Novonesis (Denmark)
- Andermatt Group AG (Switzerland)
- Lallemand Plant Care (Canada)
- BioWorks Inc. (US)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2026 (Value) | USD 10.33 Billion |
| Market Forecast in 2031 (Value) | USD 20.32 Billion |
| Growth Rate | CAGR of 14.5% during 2026-2031 |
| Years Considered | 2021-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million/Billion) |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered |
|
| Region Covered | North America, South America, Europe, Asia Pacific, Rest of the World |
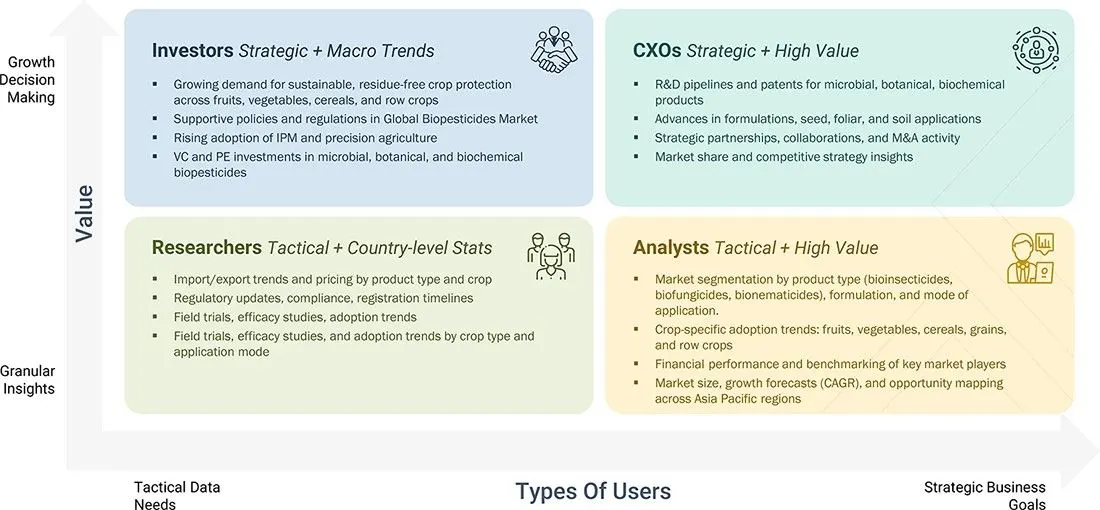
WHAT IS IN IT FOR YOU: BIOPESTICIDES MARKET REPORT CONTENT GUIDE
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Global Biopesticides Manufacturer |
|
|
| Globally focused Distributor |
|
|
| Global Agri-Biologicals Company |
|
|
| Investor/Private Equity Firm |
|
|
RECENT DEVELOPMENTS
- February 2025 : UPL launched Thiopron, a sulfur-based biofungicide aimed at sustainable powdery mildew control in specialty crops.
- January 2025 : Syngenta Group advanced its biologicals platform with the rollout of new nature-inspired microbial and biochemical solutions supported by expanded manufacturing capacity.
- January 2025 : Valent BioSciences entered a strategic partnership to commercialize Sweetsei and other Seipasa biostimulants in the US market.
- December 2024 : AgBiome transferred its biological fungicides Howler and Theia to Certis Biologicals, enabling expanded commercialization of these microbial solutions globally.
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
TITLE
PAGE NO
1
INTRODUCTION
33
2
EXECUTIVE SUMMARY
38
3
PREMIUM INSIGHTS
43
4
MARKET OVERVIEW
Sustainable practices and microbial advances drive biopesticides amidst regulatory and cost challenges.
47
4.1
INTRODUCTION
4.2
MARKET DYNAMICS
4.2.1
DRIVERS
4.2.1.1
GROWING EMPHASIS ON SUSTAINABLE AGRICULTURAL PRACTICES
4.2.1.2
GOVERNMENT RESTRICTIONS ON CHEMICAL PESTICIDES AND AWARENESS PROGRAMS
4.2.1.3
INCREASING ORGANIC FOOD SALES
4.2.2
RESTRAINTS
4.2.2.1
TECHNOLOGICAL AND ENVIRONMENTAL CONSTRAINTS
4.2.2.2
SLOW AND VARIABLE PERFORMANCE
4.2.2.3
LIMITED SHELF LIFE AND STORAGE STABILITY OF BIOLOGICAL PRODUCTS
4.2.3
OPPORTUNITIES
4.2.3.1
RAPID ADVANCES IN MICROBIAL RESEARCH
4.2.3.2
HIGH EMPHASIS ON INTEGRATED PEST MANAGEMENT (IPM) STRATEGIES
4.2.3.3
RISING RESIDUE-SENSITIVE AND EXPORT-ORIENTED CROP PRODUCTION
4.2.4
CHALLENGES
4.2.4.1
HIGHER COST OF BIOPESTICIDES THAN CHEMICAL COUNTERPARTS
4.2.4.2
LACK OF AWARENESS AND TECHNICAL KNOWLEDGE AMONG FARMERS
4.2.4.3
STRINGENT AND TIME-CONSUMING REGULATORY APPROVAL PROCESSES
4.3
UNMET NEEDS AND WHITE SPACES
4.3.1
UNMET NEEDS IN BIOPESTICIDES MARKET
4.3.2
WHITE SPACE OPPORTUNITIES
4.4
INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
4.4.1
CROSS-SECTOR OPPORTUNITIES
4.5
EMERGING BUSINESS MODELS AND ECOSYSTEM SHIFTS
4.6
STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5
INDUSTRY TRENDS
Navigate competitive pressures and seize growth opportunities in the evolving biopesticides market landscape.
59
5.1
PORTER’S FIVE FORCES ANALYSIS
5.1.1
THREAT OF NEW ENTRANTS
5.1.2
THREAT OF SUBSTITUTES
5.1.3
BARGAINING POWER OF SUPPLIERS
5.1.4
BARGAINING POWER OF BUYERS
5.1.5
INTENSITY OF COMPETITIVE RIVALRY
5.2
MACROECONOMIC OUTLOOK
5.2.1
GROWTH IN ORGANIC AGRICULTURAL PRACTICES
5.2.2
ADOPTION OF PESTICIDES FOR DEFENSE AGAINST PEST ATTACKS
5.3
VALUE CHAIN ANALYSIS
5.3.1
RAW MATERIAL & BIOLOGICAL INPUT SUPPLIERS
5.3.2
BIOLOGICAL R&D & ACTIVE INGREDIENT DEVELOPERS
5.3.3
BIOPESTICIDE MANUFACTURERS & FORMULATORS
5.3.4
DISTRIBUTION & SERVICE NETWORKS
5.3.5
END USERS
5.3.6
AFTER-SALES & TECHNICAL SERVICE PROVIDERS
5.4
ECOSYSTEM ANALYSIS
5.4.1
DEMAND SIDE
5.4.2
SUPPLY SIDE
5.5
PRICING ANALYSIS
PRICING RANGE OF BIOPESTICIDES OFFERED BY KEY PLAYERS,
AVERAGE SELLING PRICE TREND OF BIOPESTICIDES,
5.5.3
AVERAGE SELLING PRICE TREND OF BIOPESTICIDES, BY TYPE, 2023–2025
5.6
TRADE ANALYSIS
5.6.1
EXPORT SCENARIO (HS CODE 3808)
5.6.2
IMPORT SCENARIO (HS CODE 3808)
5.7
KEY CONFERENCES AND EVENTS, 2026
5.8
INVESTMENT AND FUNDING SCENARIO
5.9
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
5.10
CASE STUDY ANALYSIS
5.10.1
CORTEVA AGRISCIENCE: LAUNCH OF GOLTREVO MICROBIAL BIOINSECTICIDE
5.10.2
FMC: REGISTRATION OF SOFERO FALL PHEROMONE
5.10.3
BIOWORKS: LAUNCH OF PRINCIPLE WP BIOINSECTICIDE
5.11
IMPACT OF US TARIFFS – BIOPESTICIDES MARKET
5.11.1
INTRODUCTION
5.11.2
PRICE IMPACT ANALYSIS
5.11.3
KEY TARIFF RATES
5.11.4
IMPACT ON COUNTRIES/REGIONS
5.11.4.1
INDIA
5.11.4.2
CHINA
5.11.4.3
EUROPEAN UNION
5.11.4.4
JAPAN
5.11.5
IMPACT ON END-USE INDUSTRIES
6
TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
AI-driven biopesticides revolutionize precision agriculture, unlocking new market potential and transformative ecosystem impacts.
83
6.1
KEY EMERGING TECHNOLOGIES
6.1.1
MICROBIAL CONSORTIA AND NEXT-GENERATION MICROBIAL STRAINS
6.1.2
PRECISION FORMULATION AND ENCAPSULATION
6.1.3
RNA-BASED BIOPESTICIDES
6.2
COMPLEMENTARY TECHNOLOGIES
6.2.1
PRECISION AGRICULTURE AND DIGITAL PEST MONITORING
6.2.2
BIOLOGICAL SEED TREATMENT AND SEED COATING
6.2.3
SMART SPRAYING AND AUTONOMOUS APPLICATION
6.3
ADJACENT TECHNOLOGIES
6.3.1
BIOSTIMULANTS AND MICROBIAL BIOSTIMULANTS
6.3.2
BIOLOGICAL FERTILIZERS AND MICROBIAL SOIL AMENDMENTS
6.3.3
BIOCONTROL-BASED INTEGRATED PEST MANAGEMENT PLATFORMS
6.4
TECHNOLOGY/PRODUCT ROADMAP
6.4.1
SHORT-TERM (2025–2027) | FOUNDATION & EARLY COMMERCIALIZATION
6.4.2
MID-TERM (2027–2030) | EXPANSION & STANDARDIZATION
6.4.3
LONG-TERM (2030–2035+) | MASS COMMERCIALIZATION & DISRUPTION
6.5
PATENT ANALYSIS
6.6
FUTURE APPLICATIONS
6.7
IMPACT OF GENERATIVE AI ON BIOPESTICIDES MARKET
6.7.1
INTRODUCTION
6.7.2
TOP USE CASES AND MARKET POTENTIAL
6.7.3
BEST PRACTICES FOLLOWED BY OEMS IN BIOPESTICIDES MARKET
6.7.4
CASE STUDIES RELATED TO GEN AI IMPLEMENTATION IN BIOPESTICIDES MARKET
6.7.5
INTERCONNECTED ECOSYSTEM AND IMPACT ON MARKET PLAYERS
6.7.6
CLIENTS’ READINESS TO ADOPT GEN AI-INTEGRATED BIOPESTICIDES SOLUTIONS
6.8
SUCCESS STORIES AND REAL-WORLD APPLICATIONS
7
REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
Navigate complex regulations to enhance sustainability through global eco-standards and certifications.
110
7.1
REGIONAL REGULATIONS AND COMPLIANCE
7.1.1
INDUSTRY STANDARDS
7.2
SUSTAINABILITY INITIATIVES
7.3
IMPACT OF REGULATORY POLICIES ON SUSTAINABILITY INITIATIVES
7.4
CERTIFICATIONS, LABELING, AND ECO-STANDARDS
8
CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
Unlock key buyer insights and unmet needs driving agricultural sector decisions and profitability.
132
8.1
DECISION-MAKING PROCESS
8.2
KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
8.2.1
KEY STAKEHOLDERS IN BUYING PROCESS
8.2.2
BUYING CRITERIA
8.3
ADOPTION BARRIERS AND INTERNAL CHALLENGES
8.4
UNMET NEEDS OF VARIOUS END-USE INDUSTRIES
8.4.1
COMMERCIAL FARMING
8.4.2
AGRICULTURAL COOPERATIVES
8.4.3
AGRIBUSINESSES AND CONTRACT GROWERS
8.4.4
PLANTATION AND HORTICULTURAL PRODUCERS
8.4.5
ORGANIC FARMING
8.5
MARKET PROFITABILITY
9
BIOPESTICIDES MARKET, BY TYPE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million and Kilotons | 32 Data Tables
139
9.1
INTRODUCTION
9.2
BIOINSECTICIDES
9.2.1
BACILLUS THURINGIENSIS
9.2.1.1
WIDE-SCALE AVAILABILITY, TARGET-SPECIFICITY, AND EFFICIENCY TO BOOST SEGMENTAL GROWTH
9.2.1.2
AVAILABILITY IN VARIOUS FORMULATIONS TO CONTRIBUTE TO SEGMENTAL GROWTH
9.2.2
METARHIZIUM ANISOPLIAE
9.2.2.1
STRONG FOCUS ON PROLONGED INSECT PEST CONTROL TO EXPEDITE SEGMENTAL GROWTH
9.2.3
VERTICILLIUM LECANII
9.2.3.1
WIDE APPLICATIONS IN ORNAMENTALS, VEGETABLE CROPS, NURSERIES, LAWNS, AND VEGETABLE FIELD CROPS TO FUEL SEGMENTAL GROWTH
9.2.4
BACULOVIRUS
9.2.4.1
RAPID ADVANCES IN FORMULATION TECHNOLOGIES TO AUGMENT SEGMENTAL GROWTH
9.2.5
OTHER BIOINSECTICIDE MICROBIAL TYPES
9.3
BIOFUNGICIDES
9.3.1
TRICHODERMA
9.3.1.1
EASY AVAILABILITY AND LONG SHELF LIFE TO BOLSTER SEGMENTAL GROWTH
9.3.2
BACILLUS
9.3.2.1
ABILITY TO REPLICATE RAPIDLY AND RESIST ENVIRONMENTAL CONDITIONS TO FOSTER SEGMENTAL GROWTH
9.3.3
PSEUDOMONAS
9.3.3.1
HIGH EMPHASIS ON TREATING SEED-BORNE DISEASES TO CONTRIBUTE TO SEGMENTAL GROWTH
9.3.4
STREPTOMYCES
9.3.4.1
FOCUS ON ELIMINATING PLANT PATHOGENS BY SECRETING VOLATILE COMPOUNDS TO DRIVE MARKET
9.3.5
OTHER BIOFUNGICIDE MICROBIAL TYPES
9.4
BIONEMATICIDES
9.4.1
PAECILOMYCES LILACINUS
9.4.1.1
FOCUS ON CONTROLLING GROWTH OF ROOT-KNOT NEMATODES TO EXPEDITE SEGMENTAL GROWTH
9.4.2
BACILLUS FIRMUS
9.4.2.1
EFFECTIVENESS AGAINST LARVAE AND ADULT NEMATODES TO ACCELERATE SEGMENTAL GROWTH
9.4.3
PASTEURIA SPP.
9.4.3.1
NEED TO CONTROL PLANT-PARASITIC NEMATODES TO BOOST SEGMENTAL GROWTH
9.4.4
OTHER SPECIES
9.5
BIOHERBICIDES
9.5.1
FOCUS ON CONTROLLING FUNGAL PATHOGENS CAPABLE OF CAUSING SEVERE, TARGETED DAMAGE TO SINGLE PROBLEM WEED SPECIES TO DRIVE MARKET
9.6
OTHER BIOPESTICIDES
10
BIOPESTICIDES MARKET, BY SOURCE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 14 Data Tables
163
10.1
INTRODUCTION
10.2
MICROBIALS
10.2.1
BACTERIA
10.2.1.1
USE AS SUSTAINABLE APPROACH TO PEST CONTROL TO CONTRIBUTE TO SEGMENTAL GROWTH
10.2.2
FUNGI
10.2.2.1
EFFECTIVENESS IN ELIMINATING HARMFUL PESTS AND PATHOGENS IN AGRICULTURE TO BOLSTER SEGMENTAL GROWTH
10.2.3
VIRUS
10.2.3.1
ABILITY TO INFECT AGRICULTURAL PESTS BY DISRUPTING THEIR BIOLOGICAL PROCESSES TO FACILITATE SEGMENTAL GROWTH
10.2.4
PROTOZOA
10.2.4.1
ADOPTION AS SUSTAINABLE ALTERNATIVE TO CHEMICAL PESTICIDES TO AUGMENT SEGMENTAL GROWTH
10.3
BIOCHEMICALS
10.3.1
SEMIOCHEMICALS
10.3.1.1
ABILITY TO ATTRACT OR REPEL PESTS AND BENEFICIAL INSECTS TO CONTRIBUTE TO SEGMENTAL GROWTH
10.3.2
PLANT EXTRACTS
10.3.2.1
EFFECTIVE DISEASE CONTROL WHILE MAINTAINING LOW ENVIRONMENTAL IMPACT TO FOSTER SEGMENTAL GROWTH
10.3.3
ORGANIC ACIDS
10.3.3.1
PEST-REPELLENT AND FUNGICIDAL PROPERTIES TO ACCELERATE SEGMENTAL GROWTH
10.4
BENEFICIAL INSECTS
10.4.1
PREDATORS
10.4.1.1
USE TO ENHANCE CROP PROTECTION AND MAINTAIN ECOLOGICAL BALANCE TO AUGMENT SEGMENTAL GROWTH
10.4.2
PARASITOIDS
10.4.2.1
ABILITY TO TARGET HARMFUL PESTS WITHOUT IMPACTING BENEFICIAL ORGANISMS TO FUEL SEGMENTAL GROWTH
11
BIOPESTICIDES MARKET, BY FORMULATION
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 10 Data Tables
176
11.1
INTRODUCTION
11.2
LIQUID
11.2.1
EMULSIFIABLE CONCENTRATES
11.2.1.1
EASE OF HANDLING AND LESS AGITATION TO CONTRIBUTE TO SEGMENTAL GROWTH
11.2.2
SUSPENSION CONCENTRATES
11.2.2.1
SAFE FOR OPERATORS AND ENVIRONMENTS TO AUGMENT SEGMENTAL GROWTH
11.2.3
SOLUBLE LIQUID CONCENTRATES
11.2.3.1
LOWER VISCOSITIES THAN SUSPENSION CONCENTRATES TO FUEL SEGMENTAL GROWTH
11.3
DRY
11.3.1
DRY GRANULES
11.3.1.1
SUITABILITY FOR LONG-TERM STORAGE AND TRANSPORTATION WITHOUT SPECIAL CONDITIONS TO BOOST SEGMENTAL GROWTH
11.3.2
WATER-DISPERSIBLE GRANULES
11.3.2.1
DUST-FREE AND GOOD STORAGE VIABILITY TO AUGMENT SEGMENTAL GROWTH
11.3.3
WETTABLE POWDERS
11.3.3.1
EASE OF TRANSPORTATION, STORAGE, AND HANDLING TO FACILITATE SEGMENTAL GROWTH
12
BIOPESTICIDES MARKET, BY MODE OF APPLICATION
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 10 Data Tables
185
12.1
INTRODUCTION
12.2
SEED TREATMENT
12.2.1
EARLY-STAGE PROTECTION THROUGH PRECISE SEED PLACEMENT TO BOLSTER SEGMENTAL GROWTH
12.3
SOIL TREATMENT
12.3.1
TARGETED ROOT-ZONE DELIVERY FOR SOIL-BORNE PEST MANAGEMENT TO EXPEDITE SEGMENTAL GROWTH
12.4
FOLIAR SPRAY
12.4.1
CANOPY-LEVEL BIOLOGICAL PROTECTION THROUGH CONVENTIONAL SPRAY SYSTEMS TO FOSTER SEGMENTAL GROWTH
12.5
OTHER MODES OF APPLICATION
13
BIOPESTICIDES MARKET, BY CROP TYPE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 16 Data Tables
194
13.1
INTRODUCTION
13.2
CEREALS & GRAINS
13.2.1
CORN
13.2.1.1
INCREASING EXPORTS AND FOCUS ON IMPROVING YIELD TO ACCELERATE SEGMENTAL GROWTH
13.2.2
WHEAT
13.2.2.1
MOUNTING DEMAND FOR RELIABLE PEST MANAGEMENT SOLUTIONS TO MITIGATE DAMAGE TO CROPS TO FUEL SEGMENTAL GROWTH
13.2.3
RICE
13.2.3.1
HIGH EFFECTIVENESS AGAINST LEAF FOLDER AND STEM BORER TO CONTRIBUTE TO SEGMENTAL GROWTH
13.2.4
OTHER CEREALS & GRAINS
13.3
OILSEEDS & PULSES
13.3.1
SOYBEAN
13.3.1.1
SEVERE INFESTATION FROM ROOT-KNOT NEMATODES TO BOOST SEGMENTAL GROWTH
13.3.2
SUNFLOWER
13.3.2.1
PREFERENCE FOR SUNFLOWER OIL AND CONFECTIONERY VALUE OF SEED TO DRIVE MARKET
13.3.3
OTHER OILSEEDS & PULSES
13.4
FRUITS & VEGETABLES
13.4.1
ROOT & TUBER VEGETABLES
13.4.1.1
ECONOMIC LOSSES DUE TO PESTS, DISEASES, AND NEMATODES TO FOSTER SEGMENTAL GROWTH
13.4.2
LEAFY VEGETABLES
13.4.2.1
PREVALENCE OF ALTERNARIA LEAF BLIGHT AND OTHER DISEASES TO BOOST SEGMENTAL GROWTH
13.4.3
POME FRUITS
13.4.3.1
EFFECTIVENESS OF BIOCONTROL AGENTS ON POME FRUITS TO ACCELERATE SEGMENTAL GROWTH
13.4.4
BERRIES
13.4.4.1
AWARENESS ABOUT HEALTH BENEFITS TO CONTRIBUTE TO SEGMENTAL GROWTH
13.4.5
CITRUS FRUITS
13.4.5.1
FOCUS ON MINIMIZING ECONOMIC LOSSES TO EXPEDITE SEGMENTAL GROWTH
13.4.6
OTHER FRUITS & VEGETABLES
13.5
OTHER CROP TYPES
14
BIOPESTICIDES MARKET, BY REGION
Comprehensive coverage of 8 Regions with country-level deep-dive of 14 Countries | 112 Data Tables.
209
14.1
INTRODUCTION
14.2
NORTH AMERICA
14.2.1
US
14.2.1.1
RISING IMPLEMENTATION OF SUSTAINABLE AGRICULTURAL SOLUTIONS AND ORGANIC FARMING TO BOOST MARKET GROWTH
14.2.2
CANADA
14.2.2.1
HIGH EMPHASIS ON USAGE OF LOW-RISK PESTICIDES TO ACCELERATE MARKET GROWTH
14.2.3
MEXICO
14.2.3.1
STRONG FOCUS ON CLASSICAL AND AUGMENTATIVE BIOLOGICAL CONTROL TO EXPEDITE MARKET GROWTH
14.3
EUROPE
14.3.1
FRANCE
14.3.1.1
FAVORABLE LEGISLATIVE CHANGES FOR BIOCONTROL TO SUPPORT MARKET GROWTH
14.3.2
GERMANY
14.3.2.1
COMMITMENT TO REDUCING PESTICIDE USAGE AND PROMOTING SUSTAINABLE AGRICULTURAL PRACTICES TO FUEL MARKET GROWTH
14.3.3
SPAIN
14.3.3.1
RISING NEED FOR EFFECTIVE PEST MANAGEMENT SOLUTIONS THAT COMPLY WITH ORGANIC REGULATIONS TO DRIVE MARKET
14.3.4
ITALY
14.3.4.1
INCREASING ADOPTION OF ORGANIC FARMING PRACTICES TO EXPEDITE MARKET GROWTH
14.3.5
UK
14.3.5.1
CHANGING CONSUMER PREFERENCES FOR HEALTHY DIET TO CONTRIBUTE TO MARKET GROWTH
14.3.6
REST OF EUROPE
14.4
ASIA PACIFIC
14.4.1
CHINA
14.4.1.1
INCREASING AGRICULTURAL EXPORTS AND GOVERNMENT PUSH FOR SUSTAINABLE AGRICULTURE TO DRIVE MARKET
14.4.2
INDIA
14.4.2.1
INCREASING AREA UNDER ORGANIC FARMING TO AUGMENT MARKET GROWTH
14.4.3
JAPAN
14.4.3.1
STRONG FOCUS ON SUSTAINABILITY IN AGRICULTURE, FORESTRY, AND FISHERIES TO BOOST MARKET GROWTH
14.4.4
AUSTRALIA
14.4.4.1
GROWING EMPHASIS ON SUSTAINABLE AGRICULTURE TO BOLSTER MARKET GROWTH
14.4.5
REST OF ASIA PACIFIC
14.5
SOUTH AMERICA
14.5.1
BRAZIL
14.5.1.1
RISING POPULARITY OF BIOLOGICAL CROP PROTECTION SOLUTIONS TO FOSTER MARKET GROWTH
14.5.2
ARGENTINA
14.5.2.1
BURGEONING DEMAND FOR SUSTAINABLE AND ENVIRONMENTALLY FRIENDLY AGRICULTURAL INPUTS TO DRIVE MARKET
14.5.3
REST OF SOUTH AMERICA
14.6
ROW
14.6.1
AFRICA
14.6.1.1
CONCERNS ABOUT ECONOMIC IMPACT OF CROP INFECTION TO AUGMENT MARKET GROWTH
14.6.2
MIDDLE EAST
14.6.2.1
INITIATIVES TO PROMOTE ORGANIC FARMING AND SUSTAINABLE PRACTICES TO FUEL MARKET GROWTH
15
COMPETITIVE LANDSCAPE
Uncover key strategies and market dominance shifts among leading competitors and emerging players.
261
15.1
OVERVIEW
15.2
KEY PLAYER COMPETITIVE STRATEGIES/RIGHT TO WIN, 2023–2026
15.3
REVENUE ANALYSIS, 2021–2025
15.4
MARKET SHARE ANALYSIS, 2025
15.5
COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
15.5.1
STARS
15.5.2
EMERGING LEADERS
15.5.3
PERVASIVE PLAYERS
15.5.4
PARTICIPANTS
15.5.5
COMPANY FOOTPRINT: KEY PLAYERS, 2025
15.5.5.1
COMPANY FOOTPRINT
15.5.5.2
REGION FOOTPRINT
15.5.5.3
TYPE FOOTPRINT
15.5.5.4
FORMULATION FOOTPRINT
15.5.5.5
SOURCE FOOTPRINT
15.6
COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
15.6.1
PROGRESSIVE COMPANIES
15.6.2
RESPONSIVE COMPANIES
15.6.3
DYNAMIC COMPANIES
15.6.4
STARTING BLOCKS
15.6.5
COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
15.6.5.1
DETAILED LIST OF KEY STARTUPS/SMES
15.6.5.2
COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
15.7
COMPANY VALUATION AND FINANCIAL METRICS
15.8
BRAND/PRODUCT/SERVICE COMPARISON
15.9
COMPETITIVE SCENARIO
15.9.1
PRODUCT LAUNCHES
15.9.2
DEALS
15.9.3
EXPANSIONS
16
COMPANY PROFILES
In-depth Company Profiles of Leading Market Players with detailed Business Overview, Product and Service Portfolio, Recent Developments, and Unique Analyst Perspective (MnM View)
283
16.1
KEY PLAYERS
16.1.1
BASF
16.1.1.1
BUSINESS OVERVIEW
16.1.1.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED
16.1.1.3
RECENT DEVELOPMENTS
16.1.1.3.1
DEALS
16.1.1.3.2
OTHER DEVELOPMENTS
16.1.1.4
MNM VIEW
16.1.1.4.1
KEY STRENGTHS
16.1.1.4.2
STRATEGIC CHOICES
16.1.1.4.3
WEAKNESSES AND COMPETITIVE THREATS
16.1.2
BAYER AG
16.1.3
CORTEVA
16.1.4
SYNGENTA GROUP
16.1.5
FMC CORPORATION
16.1.6
UPL
16.1.7
SUMITOMO CHEMICAL CO., LTD.
16.1.8
NUFARM
16.1.9
NOVOZYMES A/S
16.1.10
BIOCERES CROP SOLUTIONS
16.1.11
KOPPERT
16.1.12
CERTIS USA L.L.C.
16.1.13
GOWAN COMPANY
16.1.14
BIOBEST
16.1.15
LALLEMAND INC.
16.2
OTHER PLAYERS (SMES/STARTUPS)
16.2.1
IPL BIOLOGICALS
16.2.2
ROVENSA NEXT
16.2.3
BIOCONTROL TECHNOLOGIES S.L
16.2.4
AGRILIFE (INDIA) PRIVATE LIMITED
16.2.5
STK BIO-AG TECHNOLOGIES
16.2.6
KAY BEE BIO ORGANICS PVT. LTD.
16.2.7
ANDERMATT GROUP AG
16.2.8
GÊNICA
16.2.9
SEIPASA, S.A.
16.2.10
BOTANOHEALTH LTD.
17
RESEARCH METHODOLOGY
360
17.1
RESEARCH DATA
17.1.1
SECONDARY DATA
17.1.1.1
LIST OF KEY SECONDARY SOURCES
17.1.1.2
KEY DATA FROM SECONDARY SOURCES
17.1.2
PRIMARY DATA
17.1.2.1
KEY DATA FROM PRIMARY SOURCES
17.1.2.2
KEY INDUSTRY INSIGHTS
17.1.2.3
BREAKDOWN OF PRIMARIES
17.2
MARKET SIZE ESTIMATION
17.2.1
BOTTOM-UP APPROACH
17.2.2
TOP-DOWN APPROACH
17.3
DATA TRIANGULATION
17.4
RESEARCH ASSUMPTIONS
17.5
RESEARCH LIMITATIONS AND RISK ASSESSMENT
18
ADJACENT AND RELATED MARKETS
372
18.1
INTRODUCTION
18.2
LIMITATIONS
18.3
AGRICULTURAL BIOLOGICALS MARKET
18.3.1
MARKET DEFINITION
18.3.2
MARKET OVERVIEW
18.4
BIORATIONAL PESTICIDES MARKET
18.4.1
MARKET DEFINITION
18.4.2
MARKET OVERVIEW
18.5
BIOCONTROL MARKET
18.5.1
MARKET DEFINITION
18.5.2
MARKET OVERVIEW
19
APPENDIX
378
19.1
DISCUSSION GUIDE
19.2
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL
19.3
AVAILABLE CUSTOMIZATION
19.4
RELATED REPORTS
19.5
AUTHOR DETAILS
LIST OF TABLES
TABLE 1
BIOPESTICIDES MARKET: INCLUSIONS & EXCLUSIONS
TABLE 2
USD EXCHANGE RATES CONSIDERED, 2021–2025
TABLE 3
INTERCONNECTED MARKETS
TABLE 4
KEY MOVES AND STRATEGIC FOCUS
TABLE 5
IMPACT OF PORTER’S FIVE FORCES
TABLE 6
ROLE OF COMPANIES IN BIOPESTICIDES ECOSYSTEM
TABLE 7
PRICING RANGE OF BIOPESTICIDES PROVIDED BY KEY PLAYERS, BY TYPE, 2025 (USD/KG)
TABLE 8
PRICING TREND OF BIOPESTICIDES, BY REGION, 2023–2025 (USD/KG)
TABLE 9
PRICING TREND OF BIOPESTICIDES, BY TYPE, 2023–2025 (USD/KG)
TABLE 10
EXPORT DATA FOR HS CODE 3808-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025 (USD THOUSAND)
TABLE 11
IMPORT DATA FOR HS CODE 3808-COMPLIANT PRODUCTS, BY KEY COUNTRY, 2021–2025 (USD THOUSAND)
TABLE 12
LIST OF KEY CONFERENCES AND EVENTS, 2026
TABLE 13
REGIONAL TARIFF IMPACT ON BIOPESTICIDE EXPORTS TO US
TABLE 14
LIST OF KEY PATENTS, 2016–2025
TABLE 15
AI-POWERED BIOPESTICIDE DISCOVERY
TABLE 16
ADVANCED BIOPESTICIDE COMBINATIONS
TABLE 17
PRECISION PEST-BASED APPLICATION
TABLE 18
SMART FORMULATION & CONTROLLED DELIVERY
TABLE 19
INTEGRATED DIGITAL BIOPESTICIDE MANAGEMENT
TABLE 20
USE CASES AND MARKET POTENTIAL
TABLE 21
BEST PRACTICES FOLLOWED BY COMPANIES
TABLE 22
CASE STUDIES RELATED TO GEN AI IMPLEMENTATION
TABLE 23
INTERCONNECTED ECOSYSTEM AND IMPACT ON BIOPESTICIDES MARKET PLAYERS
TABLE 24
NORTH AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
TABLE 25
EUROPE: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
TABLE 26
ASIA PACIFIC: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
TABLE 27
SOUTH AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
TABLE 28
ROW: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
TABLE 29
GLOBAL INDUSTRY STANDARDS
TABLE 30
KEY INDUSTRY STANDARDS
TABLE 31
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY MODE OF APPLICATION
TABLE 32
BUYING CRITERIA, BY MODE OF APPLICATION
TABLE 33
BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 34
BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 35
BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (KT)
TABLE 36
BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (KT)
TABLE 37
BIOINSECTICIDES: BIOPESTICIDES MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 38
BIOINSECTICIDES: BIOPESTICIDES MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 39
BIOINSECTICIDES: BIOPESTICIDES MARKET, BY REGION, 2021–2025 (KT)
TABLE 40
BIOINSECTICIDES: BIOPESTICIDES MARKET, BY REGION, 2026–2031 (KT)
TABLE 41
BIOINSECTICIDES: BIOPESTICIDES MARKET, BY MICROBIAL TYPE, 2021–2025 (USD MILLION)
TABLE 42
BIOINSECTICIDES: BIOPESTICIDES MARKET, BY MICROBIAL TYPE, 2026–2031 (USD MILLION)
TABLE 43
BIOFUNGICIDES: BIOPESTICIDES MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 44
BIOFUNGICIDES: BIOPESTICIDES MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 45
BIOFUNGICIDES: BIOPESTICIDES MARKET, BY REGION, 2021–2025 (KT)
TABLE 46
BIOFUNGICIDES: BIOPESTICIDES MARKET, BY REGION, 2026–2031 (KT)
TABLE 47
BIOFUNGICIDES: BIOPESTICIDES MARKET, BY MICROBIAL TYPE, 2021–2025 (USD MILLION)
TABLE 48
BIOFUNGICIDES: BIOPESTICIDES MARKET, BY MICROBIAL TYPE, 2026–2031 (USD MILLION)
TABLE 49
SECONDARY METABOLITES RELEASED BY TRICHODERMA SPP.
TABLE 50
DISEASES/TARGET PESTS CONTROLLED BY STREPTOMYCES SPP.
TABLE 51
BIONEMATICIDES: BIOPESTICIDES MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 52
BIONEMATICIDES: BIOPESTICIDES MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 53
BIONEMATICIDES: BIOPESTICIDES MARKET, BY REGION, 2021–2025 (KT)
TABLE 54
BIONEMATICIDES: BIOPESTICIDES MARKET, BY REGION, 2026–2031 (KT)
TABLE 55
BIONEMATICIDES: BIOPESTICIDES MARKET, BY MICROBIAL TYPE, 2021–2025 (USD MILLION)
TABLE 56
BIONEMATICIDES: BIOPESTICIDES MARKET, BY MICROBIAL TYPE, 2026–2031 (USD MILLION)
TABLE 57
BIOHERBICIDES: BIOPESTICIDES MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 58
BIOHERBICIDES: BIOPESTICIDES MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 59
BIOHERBICIDES: BIOPESTICIDES MARKET, BY REGION, 2021–2025 (KT)
TABLE 60
BIOHERBICIDES: BIOPESTICIDES MARKET, BY REGION, 2026–2031 (KT)
TABLE 61
OTHER BIOPESTICIDES: BIOPESTICIDES MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 62
OTHER BIOPESTICIDES: BIOPESTICIDES MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 63
OTHER BIOPESTICIDES: BIOPESTICIDES MARKET, BY REGION, 2021–2025 (KT)
TABLE 64
OTHER BIOPESTICIDES: BIOPESTICIDES MARKET, BY REGION, 2026–2031 (KT)
TABLE 65
BIOPESTICIDES MARKET, BY SOURCE, 2021–2025 (USD MILLION)
TABLE 66
BIOPESTICIDES MARKET, BY SOURCE, 2026–2031 (USD MILLION)
TABLE 67
MICROBIAL: BIOPESTICIDES MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 68
MICROBIAL: BIOPESTICIDES MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 69
MICROBIAL: BIOPESTICIDES MARKET, BY SUB-TYPE, 2021–2025 (USD MILLION)
TABLE 70
MICROBIAL: BIOPESTICIDES MARKET, BY SUB-TYPE, 2026–2031 (USD MILLION)
TABLE 71
BIOCHEMICALS: BIOPESTICIDES MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 72
BIOCHEMICALS: BIOPESTICIDES MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 73
BIOCHEMICALS: BIOPESTICIDES MARKET, BY SUB-TYPE, 2021–2025 (USD MILLION)
TABLE 74
BIOCHEMICALS: BIOPESTICIDES MARKET, BY SUB-TYPE, 2026–2031 (USD MILLION)
TABLE 75
BENEFICIAL INSECTS: BIOPESTICIDES MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 76
BENEFICIAL INSECTS: BIOPESTICIDES MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 77
BENEFICIAL INSECTS: BIOPESTICIDES MARKET, BY SUB-TYPE, 2021–2025 (USD MILLION)
TABLE 78
BENEFICIAL INSECTS: BIOPESTICIDES MARKET, BY SUB-TYPE, 2026–2031 (USD MILLION)
TABLE 79
BIOPESTICIDES MARKET, BY FORMULATION, 2021–2025 (USD MILLION)
TABLE 80
BIOPESTICIDES MARKET, BY FORMULATION, 2026–2031 (USD MILLION)
TABLE 81
LIQUID: BIOPESTICIDES MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 82
LIQUID: BIOPESTICIDES MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 83
LIQUID: BIOPESTICIDES MARKET, BY SUB-TYPE, 2021–2025 (USD MILLION)
TABLE 84
LIQUID: BIOPESTICIDES MARKET, BY SUB-TYPE, 2026–2031 (USD MILLION)
TABLE 85
DRY: BIOPESTICIDES MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 86
DRY: BIOPESTICIDES MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 87
DRY: BIOPESTICIDES MARKET, BY SUB-TYPE, 2021–2025 (USD MILLION)
TABLE 88
DRY: BIOPESTICIDES MARKET, BY SUB-TYPE, 2026–2031 (USD MILLION)
TABLE 89
BIOPESTICIDES MARKET, BY MODE OF APPLICATION, 2021–2025 (USD MILLION)
TABLE 90
BIOPESTICIDES MARKET, BY MODE OF APPLICATION, 2026–2031 (USD MILLION)
TABLE 91
SEED TREATMENT: BIOPESTICIDES MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 92
SEED TREATMENT: BIOPESTICIDES MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 93
SOIL TREATMENT: BIOPESTICIDES MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 94
SOIL TREATMENT: BIOPESTICIDES MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 95
FOLIAR SPRAY: BIOPESTICIDES MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 96
FOLIAR SPRAY: BIOPESTICIDES MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 97
OTHER MODES OF APPLICATION: BIOPESTICIDES MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 98
OTHER MODES OF APPLICATION: BIOPESTICIDES MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 99
BIOPESTICIDES MARKET, BY CROP TYPE, 2021–2025 (USD MILLION)
TABLE 100
BIOPESTICIDES MARKET, BY CROP TYPE, 2026–2031 (USD MILLION)
TABLE 101
CEREALS & GRAINS: BIOPESTICIDES MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 102
CEREALS & GRAINS: BIOPESTICIDES MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 103
CEREALS & GRAINS: BIOPESTICIDES MARKET, BY SUB-TYPE, 2021–2025 (USD MILLION)
TABLE 104
CEREALS & GRAINS: BIOPESTICIDES MARKET, BY SUB-TYPE, 2026–2031 (USD MILLION)
TABLE 105
OILSEEDS & PULSES: BIOPESTICIDES MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 106
OILSEEDS & PULSES: BIOPESTICIDES MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 107
OILSEEDS & PULSES: BIOPESTICIDES MARKET, BY SUB-TYPE, 2021–2025 (USD MILLION)
TABLE 108
OILSEEDS & PULSES: BIOPESTICIDES MARKET, BY SUB-TYPE, 2026–2031 (USD MILLION)
TABLE 109
FRUITS & VEGETABLES: BIOPESTICIDES MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 110
FRUITS & VEGETABLES: BIOPESTICIDES MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 111
FRUITS & VEGETABLES: BIOPESTICIDES MARKET, BY SUB-TYPE, 2021–2025 (USD MILLION)
TABLE 112
FRUITS & VEGETABLES: BIOPESTICIDES MARKET, BY SUB-TYPE, 2026–2031 (USD MILLION)
TABLE 113
OTHER CROP TYPES: BIOPESTICIDES MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 114
OTHER CROP TYPES: BIOPESTICIDES MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 115
BIOPESTICIDES MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 116
BIOPESTICIDES MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 117
BIOPESTICIDES MARKET, BY REGION, 2021–2025 (KT)
TABLE 118
BIOPESTICIDES MARKET, BY REGION, 2026–2031 (KT)
TABLE 119
NORTH AMERICA: BIOPESTICIDES MARKET, BY COUNTRY, 2021–2025 (USD MILLION)
TABLE 120
NORTH AMERICA: BIOPESTICIDES MARKET, BY COUNTRY, 2026–2031 (USD MILLION)
TABLE 121
NORTH AMERICA: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 122
NORTH AMERICA: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 123
NORTH AMERICA: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (KT)
TABLE 124
NORTH AMERICA: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (KT)
TABLE 125
NORTH AMERICA: BIOPESTICIDES MARKET, BY SOURCE, 2021–2025 (USD MILLION)
TABLE 126
NORTH AMERICA: BIOPESTICIDES MARKET, BY SOURCE, 2026–2031 (USD MILLION)
TABLE 127
NORTH AMERICA: BIOPESTICIDES MARKET, BY MODE OF APPLICATION, 2021–2025 (USD MILLION)
TABLE 128
NORTH AMERICA: BIOPESTICIDES MARKET, BY MODE OF APPLICATION, 2026–2031 (USD MILLION)
TABLE 129
NORTH AMERICA: BIOPESTICIDES MARKET, BY FORMULATION, 2021–2025 (USD MILLION)
TABLE 130
NORTH AMERICA: BIOPESTICIDES MARKET, BY FORMULATION, 2026–2031 (USD MILLION)
TABLE 131
NORTH AMERICA: BIOPESTICIDES MARKET, BY CROP TYPE, 2021–2025 (USD MILLION)
TABLE 132
NORTH AMERICA: BIOPESTICIDES MARKET, BY CROP TYPE, 2026–2031 (USD MILLION)
TABLE 133
US: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 134
US: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 135
CANADA: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 136
CANADA: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 137
MEXICO: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 138
MEXICO: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 139
EUROPE: BIOPESTICIDES MARKET, BY COUNTRY, 2021–2025 (USD MILLION)
TABLE 140
EUROPE: BIOPESTICIDES MARKET, BY COUNTRY, 2026–2031 (USD MILLION)
TABLE 141
EUROPE: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 142
EUROPE: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 143
EUROPE: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (KT)
TABLE 144
EUROPE: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (KT)
TABLE 145
EUROPE: BIOPESTICIDES MARKET, BY SOURCE, 2021–2025 (USD MILLION)
TABLE 146
EUROPE: BIOPESTICIDES MARKET, BY SOURCE, 2026–2031 (USD MILLION)
TABLE 147
EUROPE: BIOPESTICIDES MARKET, BY MODE OF APPLICATION, 2021–2025 (USD MILLION)
TABLE 148
EUROPE: BIOPESTICIDES MARKET, BY MODE OF APPLICATION, 2026–2031 (USD MILLION)
TABLE 149
EUROPE: BIOPESTICIDES MARKET, BY FORMULATION, 2021–2025 (USD MILLION)
TABLE 150
EUROPE: BIOPESTICIDES MARKET, BY FORMULATION, 2026–2031 (USD MILLION)
TABLE 151
EUROPE: BIOPESTICIDES MARKET, BY CROP TYPE, 2021–2025 (USD MILLION)
TABLE 152
EUROPE: BIOPESTICIDES MARKET, BY CROP TYPE, 2026–2031 (USD MILLION)
TABLE 153
FRANCE: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 154
FRANCE: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 155
GERMANY: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 156
GERMANY: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 157
SPAIN: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 158
SPAIN: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 159
ITALY: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 160
ITALY: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 161
UK: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 162
UK: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 163
REST OF EUROPE: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 164
REST OF EUROPE: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 165
ASIA PACIFIC: BIOPESTICIDES MARKET, BY COUNTRY, 2021–2025 (USD MILLION)
TABLE 166
ASIA PACIFIC: BIOPESTICIDES MARKET, BY COUNTRY, 2026–2031 (USD MILLION)
TABLE 167
ASIA PACIFIC: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 168
ASIA PACIFIC: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 169
ASIA PACIFIC: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (KT)
TABLE 170
ASIA PACIFIC: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (KT)
TABLE 171
ASIA PACIFIC: BIOPESTICIDES MARKET, BY SOURCE, 2021–2025 (USD MILLION)
TABLE 172
ASIA PACIFIC: BIOPESTICIDES MARKET, BY SOURCE, 2026–2031 (USD MILLION)
TABLE 173
ASIA PACIFIC: BIOPESTICIDES MARKET, BY MODE OF APPLICATION, 2021–2025 (USD MILLION)
TABLE 174
ASIA PACIFIC: BIOPESTICIDES MARKET, BY MODE OF APPLICATION, 2026–2031 (USD MILLION)
TABLE 175
ASIA PACIFIC: BIOPESTICIDES MARKET, BY FORMULATION, 2021–2025 (USD MILLION)
TABLE 176
ASIA PACIFIC: BIOPESTICIDES MARKET, BY FORMULATION, 2026–2031 (USD MILLION)
TABLE 177
ASIA PACIFIC: BIOPESTICIDES MARKET, BY CROP TYPE, 2021–2025 (USD MILLION)
TABLE 178
ASIA PACIFIC: BIOPESTICIDES MARKET, BY CROP TYPE, 2026–2031 (USD MILLION)
TABLE 179
CHINA: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 180
CHINA: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 181
INDIA: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 182
INDIA: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 183
JAPAN: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 184
JAPAN: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 185
AUSTRALIA: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 186
AUSTRALIA: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 187
REST OF ASIA PACIFIC: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 188
REST OF ASIA PACIFIC: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 189
SOUTH AMERICA: BIOPESTICIDES MARKET, BY COUNTRY, 2021–2025 (USD MILLION)
TABLE 190
SOUTH AMERICA: BIOPESTICIDES MARKET, BY COUNTRY, 2026–2031 (USD MILLION)
TABLE 191
SOUTH AMERICA: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 192
SOUTH AMERICA: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 193
SOUTH AMERICA: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (KT)
TABLE 194
SOUTH AMERICA: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (KT)
TABLE 195
SOUTH AMERICA: BIOPESTICIDES MARKET, BY SOURCE, 2021–2025 (USD MILLION)
TABLE 196
SOUTH AMERICA: BIOPESTICIDES MARKET, BY SOURCE, 2026–2031 (USD MILLION)
TABLE 197
SOUTH AMERICA: BIOPESTICIDES MARKET, BY MODE OF APPLICATION, 2021–2025 (USD MILLION)
TABLE 198
SOUTH AMERICA: BIOPESTICIDES MARKET, BY MODE OF APPLICATION, 2026–2031 (USD MILLION)
TABLE 199
SOUTH AMERICA: BIOPESTICIDES MARKET, BY FORMULATION, 2021–2025 (USD MILLION)
TABLE 200
SOUTH AMERICA: BIOPESTICIDES MARKET, BY FORMULATION, 2026–2031 (USD MILLION)
TABLE 201
SOUTH AMERICA: BIOPESTICIDES MARKET, BY CROP TYPE, 2021–2025 (USD MILLION)
TABLE 202
SOUTH AMERICA: BIOPESTICIDES MARKET, BY CROP TYPE, 2026–2031 (USD MILLION)
TABLE 203
BRAZIL: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 204
BRAZIL: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 205
ARGENTINA: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 206
ARGENTINA: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 207
REST OF SOUTH AMERICA: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 208
REST OF SOUTH AMERICA: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 209
ROW: BIOPESTICIDES MARKET, BY REGION, 2021–2025 (USD MILLION)
TABLE 210
ROW: BIOPESTICIDES MARKET, BY REGION, 2026–2031 (USD MILLION)
TABLE 211
ROW: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 212
ROW: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 213
ROW: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (KT)
TABLE 214
ROW: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (KT)
TABLE 215
ROW: BIOPESTICIDES MARKET, BY SOURCE, 2021–2025 (USD MILLION)
TABLE 216
ROW: BIOPESTICIDES MARKET, BY SOURCE, 2026–2031 (USD MILLION)
TABLE 217
ROW: BIOPESTICIDES MARKET, BY MODE OF APPLICATION, 2021–2025 (USD MILLION)
TABLE 218
ROW: BIOPESTICIDES MARKET, BY MODE OF APPLICATION, 2026–2031 (USD MILLION)
TABLE 219
ROW: BIOPESTICIDES MARKET, BY FORMULATION, 2021–2025 (USD MILLION)
TABLE 220
ROW: BIOPESTICIDES MARKET, BY FORMULATION, 2026–2031 (USD MILLION)
TABLE 221
ROW: BIOPESTICIDES MARKET, BY CROP TYPE, 2021–2025 (USD MILLION)
TABLE 222
ROW: BIOPESTICIDES MARKET, BY CROP TYPE, 2026–2031 (USD MILLION)
TABLE 223
AFRICA: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 224
AFRICA: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 225
MIDDLE EAST: BIOPESTICIDES MARKET, BY TYPE, 2021–2025 (USD MILLION)
TABLE 226
MIDDLE EAST: BIOPESTICIDES MARKET, BY TYPE, 2026–2031 (USD MILLION)
TABLE 227
BIOPESTICIDES MARKET: OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS, JANUARY 2023–AUGUST 2026
TABLE 228
BIOPESTICIDES MARKET: DEGREE OF COMPETITION, 2025
TABLE 229
BIOPESTICIDES MARKET: REGION FOOTPRINT
TABLE 230
BIOPESTICIDES MARKET: TYPE FOOTPRINT
TABLE 231
BIOPESTICIDES MARKET: FORMULATION FOOTPRINT
TABLE 232
BIOPESTICIDES MARKET: SOURCE FOOTPRINT
TABLE 233
BIOPESTICIDES MARKET: DETAILED LIST OF KEY STARTUPS/SMES
TABLE 234
BIOPESTICIDES MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES (1/2)
TABLE 235
BIOPESTICIDES MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES (2/2)
TABLE 236
BIOPESTICIDES MARKET: PRODUCT/SERVICE LAUNCHES, JANUARY 2023–AUGUST 2026
TABLE 237
BIOPESTICIDES MARKET: DEALS, JANUARY 2023–AUGUST 2026
TABLE 238
BIOPESTICIDES MARKET: EXPANSIONS, JANUARY 2023–AUGUST 2026
TABLE 239
BASF: COMPANY OVERVIEW
TABLE 240
BASF: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 241
BASF SE: DEALS
TABLE 242
BASF: OTHER DEVELOPMENTS
TABLE 243
BAYER AG: COMPANY OVERVIEW
TABLE 244
BAYER AG: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 245
BAYER AG: PRODUCT LAUNCHES
TABLE 246
BAYER AG: DEALS
TABLE 247
BAYER AG: EXPANSIONS
TABLE 248
CORTEVA: COMPANY OVERVIEW
TABLE 249
CORTEVA: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 250
CORTEVA: PRODUCT LAUNCHES
TABLE 251
CORTEVA: DEALS
TABLE 252
SYNGENTA GROUP: COMPANY OVERVIEW
TABLE 253
SYNGENTA GROUP: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 254
SYNGENTA GROUP: PRODUCT LAUNCHES
TABLE 255
SYNGENTA GROUP: DEALS
TABLE 256
SYNGENTA GROUP: EXPANSIONS
TABLE 257
FMC CORPORATION: COMPANY OVERVIEW
TABLE 258
FMC CORPORATION: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 259
FMC CORPORATION: PRODUCT LAUNCHES
TABLE 260
FMC CORPORATION: DEALS
TABLE 261
UPL: COMPANY OVERVIEW
TABLE 262
UPL: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 263
UPL: PRODUCT LAUNCHES
TABLE 264
SUMITOMO CHEMICAL CO., LTD: COMPANY OVERVIEW
TABLE 265
SUMITOMO CHEMICAL CO., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 266
SUMITOMO CHEMICAL CO., LTD.: DEALS
TABLE 267
NUFARM: COMPANY OVERVIEW
TABLE 268
NUFARM: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 269
NUFARM: PRODUCT LAUNCHES
TABLE 270
NOVOZYMES A/S: COMPANY OVERVIEW
TABLE 271
NOVOZYMES A/S: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 272
NOVOZYMES A/S: DEALS
TABLE 273
NOVOZYMES A/S: EXPANSIONS
TABLE 274
BIOCERES CROP SOLUTIONS: COMPANY OVERVIEW
TABLE 275
BIOCERES CROP SOLUTIONS: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 276
BIOCERES CROP SOLUTIONS: DEALS
TABLE 277
BIOCERES CROP SOLUTIONS: OTHER DEVELOPMENTS
TABLE 278
KOPPERT: COMPANY OVERVIEW
TABLE 279
KOPPERT: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 280
KOPPERT: DEALS
TABLE 281
KOPPERT: EXPANSIONS
TABLE 282
CERTIS USA L.L.C.: COMPANY OVERVIEW
TABLE 283
CERTIS USA L.L.C.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 284
CERTIS USA L.L.C.: PRODUCT LAUNCHES
TABLE 285
CERTIS USA L.L.C.: DEALS
TABLE 286
GOWAN COMPANY: COMPANY OVERVIEW
TABLE 287
GOWAN COMPANY: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 288
GOWAN COMPANY: DEALS
TABLE 289
BIOBEST: COMPANY OVERVIEW
TABLE 290
BIOBEST: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 291
BIOBEST: PRODUCT LAUNCHES
TABLE 292
BIOBEST: DEALS
TABLE 293
BIOBEST: EXPANSIONS
TABLE 294
LALLEMAND INC.: COMPANY OVERVIEW
TABLE 295
LALLEMAND INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 296
LALLEMAND INC: PRODUCT LAUNCHES
TABLE 297
IPL BIOLOGICALS: COMPANY OVERVIEW
TABLE 298
IPL BIOLOGICALS: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 299
IPL BIOLOGICALS: PRODUCT LAUNCHES
TABLE 300
IPL BIOLOGICALS: DEALS
TABLE 301
IPL BIOLOGICALS: EXPANSIONS
TABLE 302
IPL BIOLOGICALS: OTHER DEVELOPMENTS
TABLE 303
ROVENSA NEXT: COMPANY OVERVIEW
TABLE 304
ROVENSA NEXT: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 305
ROVENSA NEXT: PRODUCT LAUNCHES
TABLE 306
ROVENSA NEXT: DEALS
TABLE 307
ROVENSA NEXT: EXPANSIONS
TABLE 308
BIOCONTROL TECHNOLOGIES S.L.: COMPANY OVERVIEW
TABLE 309
BIOCONTROL TECHNOLOGIES S.L.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 310
BIOCONTROL TECHNOLOGIES S.L.: PRODUCT LAUNCHES
TABLE 311
BIOCONTROL TECHNOLOGIES S.L.: DEALS
TABLE 312
BIOCONTROL TECHNOLOGIES S.L: EXPANSIONS
TABLE 313
AGRILIFE (INDIA) PRIVATE LIMITED: COMPANY OVERVIEW
TABLE 314
AGRILIFE (INDIA) PRIVATE LIMITED: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 315
STK BIO-AG TECHNOLOGIES: COMPANY OVERVIEW
TABLE 316
STK BIO-AG TECHNOLOGIES: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 317
STK BIO-AG TECHNOLOGIES: EXPANSIONS
TABLE 318
KAY BEE BIO ORGANICS PVT. LTD.: COMPANY OVERVIEW
TABLE 319
ANDERMATT GROUP AG: COMPANY OVERVIEW
TABLE 320
GÊNICA: COMPANY OVERVIEW
TABLE 321
SEIPASA, S.A.: COMPANY OVERVIEW
TABLE 322
BOTANOHEALTH LTD.: COMPANY OVERVIEW
TABLE 323
MAJOR SECONDARY SOURCES
TABLE 324
ADJACENT MARKETS TO BIOPESTICIDES
TABLE 325
AGRICULTURAL BIOLOGICALS MARKET, BY TYPE, 2019–2023 (USD MILLION)
TABLE 326
AGRICULTURAL BIOLOGICALS MARKET, BY TYPE, 2024–2029 (USD MILLION)
TABLE 327
AGRICULTURAL BIOLOGICALS MARKET, BY TYPE, 2019–2023 (KT)
TABLE 328
AGRICULTURAL BIOLOGICALS MARKET, BY TYPE, 2024–2029 (KT)
TABLE 329
LIST OF PLANT PRODUCTS REGISTERED AS BIOPESTICIDES
TABLE 330
BIORATIONAL PESTICIDES MARKET, BY SOURCE, 2018–2022 (USD MILLION)
TABLE 331
BIORATIONAL PESTICIDES MARKET, BY SOURCE, 2023–2028 (USD MILLION)
TABLE 332
BIOCONTROL MARKET, BY TYPE, 2017–2021 (USD MILLION)
TABLE 333
BIOCONTROL MARKET, BY TYPE, 2022–2027 (USD MILLION)
TABLE 334
BIOCONTROL MARKET, BY TYPE, 2017–2021 (KT)
TABLE 335
BIOCONTROL MARKET, BY TYPE, 2022–2027 (KT)
LIST OF FIGURES
FIGURE 1
BIOPESTICIDES MARKET SEGMENTATION
FIGURE 2
BIOPESTICIDES MARKET: DURATION CONSIDERED
FIGURE 3
BIOPESTICIDES MARKET SCENARIO
FIGURE 4
GLOBAL BIOPESTICIDES MARKET, 2021–2031
FIGURE 5
MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN BIOPESTICIDES MARKET, 2023–2026
FIGURE 6
DISRUPTIVE TRENDS IMPACTING GROWTH OF BIOPESTICIDES MARKET
FIGURE 7
HIGH-GROWTH SEGMENTS IN BIOPESTICIDES MARKET, 2026–2031
FIGURE 8
EUROPE TO REGISTER HIGHEST GROWTH RATE DURING FORECAST PERIOD
FIGURE 9
MOUNTING DEMAND FOR HIGH-VALUE CROPS AND RISE IN ORGANIC FARMING TO CREATE GROWTH OPPORTUNITIES FOR MARKET PLAYERS
FIGURE 10
MICROBIAL SEGMENT AND NORTH AMERICA TO CAPTURE LARGEST MARKET SHARE IN 2026
FIGURE 11
LIQUID SEGMENT TO HOLD LARGER SHARE OF BIOPESTICIDES MARKET IN 2026
FIGURE 12
BIOINSECTICIDES SEGMENT TO CAPTURE LARGEST MARKET SHARE IN 2026
FIGURE 13
FRUITS & VEGETABLES SEGMENT TO ACCOUNT FOR LARGEST MARKET SHARE IN 2026
FIGURE 14
FOLIAR SPRAY SEGMENT TO HOLD LARGEST SHARE OF BIOPESTICIDES MARKET IN 2026
FIGURE 15
CHINA TO REGISTER HIGHEST CAGR IN GLOBAL MARKET BETWEEN 2026 AND 2031
FIGURE 16
DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
FIGURE 17
DISTRIBUTION OF GLOBAL ORGANIC PRODUCERS, BY REGION, 2023
FIGURE 18
TOTAL ORGANIC FOOD SALES IN US, 2013–2022
FIGURE 19
PORTER’S FIVE FORCES ANALYSIS
FIGURE 20
ORGANIC AGRICULTURAL LAND BY REGION, 2024
FIGURE 21
PESTICIDE CONSUMPTION, BY REGION
FIGURE 22
BIOPESTICIDES VALUE CHAIN
FIGURE 23
KEY PARTICIPANTS IN BIOPESTICIDES ECOSYSTEM
FIGURE 24
AVERAGE SELLING PRICE TREND OF BIOPESTICIDES, BY REGION, 2023–2025
FIGURE 25
AVERAGE SELLING PRICE TREND OF BIOPESTICIDES, BY TYPE, 2023–2025 (USD/KG)
FIGURE 26
EXPORT DATA FOR HS CODE 3808-COMPLIANT PRODUCTS FOR TOP FIVE COUNTRIES, 2021–2025
FIGURE 27
IMPORT DATA FOR HS CODE 3808-COMPLIANT PRODUCTS FOR TOP FIVE COUNTRIES, 2021–2025
FIGURE 28
INVESTMENT AND FUNDING SCENARIO
FIGURE 29
TRENDS/DISRUPTIONS INFLUENCING CUSTOMER BUSINESS
FIGURE 30
PATENTS APPLIED AND GRANTED, 2016–2025
FIGURE 31
FUTURE APPLICATIONS OF BIOPESTICIDES
FIGURE 32
REAL-WORLD APPLICATIONS
FIGURE 33
DECISION-MAKING FACTORS IN BIOPESTICIDES MARKET
FIGURE 34
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY MODE OF APPLICATION
FIGURE 35
KEY INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY MODE OF APPLICATION
FIGURE 36
BIOINSECTICIDES SEGMENT TO DOMINATE BIOPESTICIDES MARKET FROM 2026 TO 2031
FIGURE 37
MICROBIAL SEGMENT TO HOLD LARGEST SHARE OF BIOPESTICIDES MARKET IN 2026 AND 2031
FIGURE 38
LIQUID SEGMENT TO CAPTURE LARGER SHARE OF BIOPESTICIDES MARKET IN 2026 AND 2031
FIGURE 39
FOLIAR SPRAY SEGMENT TO HOLD LARGEST SHARE OF BIOPESTICIDES MARKET IN 2031
FIGURE 40
FRUITS & VEGETABLES SEGMENT TO CAPTURE LARGEST MARKET SHARE IN 2026 AND 2031
FIGURE 41
US HAS THE LARGEST MARKET SHARE IN BIOPESTICIDES MARKET IN 2025
FIGURE 42
NORTH AMERICA: BIOPESTICIDES MARKET SNAPSHOT
FIGURE 43
EUROPE: BIOPESTICIDES MARKET SNAPSHOT
FIGURE 44
BIOPESTICIDES MARKET: ANNUAL REVENUE ANALYSIS OF TOP FIVE PLAYERS, 2021–2025
FIGURE 45
MARKET SHARE ANALYSIS OF COMPANIES OFFERING BIOPESTICIDES, 2025
FIGURE 46
BIOPESTICIDES MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
FIGURE 47
BIOPESTICIDES MARKET: COMPANY FOOTPRINT
FIGURE 48
BIOPESTICIDES MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
FIGURE 49
COMPANY VALUATION
FIGURE 50
FINANCIAL METRICS (EV/EBITDA)
FIGURE 51
BRAND/PRODUCT/SERVICE COMPARATIVE ANALYSIS
FIGURE 52
BASF: COMPANY SNAPSHOT
FIGURE 53
BAYER AG: COMPANY SNAPSHOT
FIGURE 54
CORTEVA: COMPANY SNAPSHOT
FIGURE 55
SYNGENTA GROUP: COMPANY SNAPSHOT
FIGURE 56
FMC CORPORATION: COMPANY SNAPSHOT
FIGURE 57
UPL LTD: COMPANY SNAPSHOT
FIGURE 58
SUMITOMO CHEMICAL CO., LTD.: COMPANY SNAPSHOT
FIGURE 59
NUFARM: COMPANY SNAPSHOT
FIGURE 60
NOVOZYMES A/S: COMPANY SNAPSHOT
FIGURE 61
BIOCERES CROP SOLUTIONS: COMPANY SNAPSHOT
FIGURE 62
BIOPESTICIDES MARKET: RESEARCH DESIGN
FIGURE 63
DATA CAPTURED FROM SECONDARY SOURCES
FIGURE 64
DATA CAPTURED FROM PRIMARY SOURCES
FIGURE 65
CORE FINDINGS FROM INDUSTRY EXPERTS
FIGURE 66
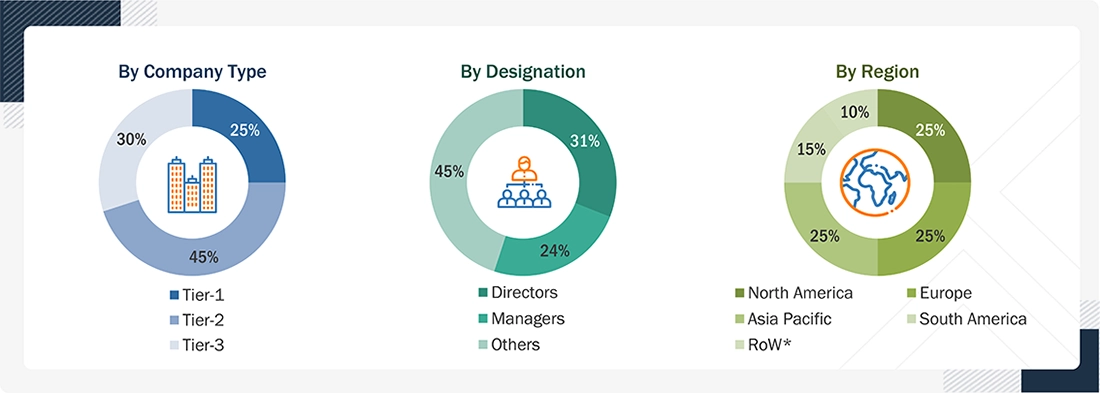
BREAKDOWN OF PRIMARY INTERVIEWS, BY COMPANY TYPE, DESIGNATION, AND REGION
FIGURE 67
BIOPESTICIDES MARKET: BOTTOM-UP APPROACH
FIGURE 68
BIOPESTICIDES MARKET: DEMAND-SIDE CALCULATION
FIGURE 69
BIOPESTICIDES MARKET SIZE ESTIMATION: SUPPLY SIDE
FIGURE 70
BIOPESTICIDES MARKET: SUPPLY-SIDE ANALYSIS
FIGURE 71
BIOPESTICIDES MARKET: DATA TRIANGULATION
FIGURE 72
BIOPESTICIDES MARKET: RESEARCH ASSUMPTIONS
FIGURE 73
BIOPESTICIDES MARKET: RESEARCH LIMITATIONS
Methodology
The study involved four major activities in estimating the current size of the biopesticides market. Exhaustive secondary research was done to collect information on the market, peer market, and parent market. The next step was to validate these findings, assumptions, and sizing with industry experts across the value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the complete market size. After that, market breakdown and data triangulation were used to estimate the market size of segments and subsegments.
Secondary Research
This research study involved the extensive use of secondary sources—directories and databases such as Bloomberg Businessweek and Factiva—to identify and collect information useful for a technical, market-oriented, and commercial study of the biopesticides market.
In the secondary research process, various sources such as annual reports, press releases & investor presentations of companies, white papers, certified publications, articles from recognized authors, gold & silver standard websites, directories, and databases were referred to identify and collect information. This research study involved the extensive use of secondary sources—directories and databases such as Bloomberg Businessweek and Factiva—to identify and collect information useful for a technical, market-oriented, and commercial study of the biopesticides market.
Secondary research was mainly used to obtain key information about the industry’s supply chain, the total pool of key players, and market classification and segmentation as per the industry trends to the bottom-most level, regional markets, and key developments from both market- and technology-oriented perspectives.
Primary Research
Extensive primary research was conducted after obtaining information regarding the global biopesticides market scenario through secondary research. Several primary interviews were conducted with market experts from both the demand and supply sides across major countries of North America, Europe, Asia Pacific, South America, and RoW. Primary data was collected through questionnaires, emails, and telephonic interviews. The primary sources from the supply side included various industry experts, such as Chief X Officers (CXOs), Vice Presidents (VPs), Directors from business development, marketing, research, and development teams, and key opinion leaders. Primary interviews were conducted to gather insights such as market statistics, data on revenue collected from the products and services, market breakdowns, market size estimations, market forecasting, and data triangulation. Primary research also helped in understanding the various trends related to global biopesticides core material, shell material, method, technology, and application. Stakeholders from the demand side, such as research institutions and universities, and third-party vendors, were interviewed to understand the buyer’s perspective on the service, and their current usage of encapsulation and the outlook of their business, which will affect the overall market.
To know about the assumptions considered for the study, download the pdf brochure
Note: The three tiers of the companies are defined based on their total revenues in 2023 or 2024, as per the availability of financial data: Tier 1: Revenue > USD 1 billion; Tier 2: USD 100 million ≤ Revenue ≤ USD 1 billion; Tier 3: Revenue < USD 100 million.
|
COMPANY NAME |
DESIGNATION |
|
Corteva Agriscience (US) |
R&D Expert |
|
BASF SE (Germany) |
Sales Manager |
|
Bayer CropSciences (Germany) |
Manager |
|
Syngenta Group (Switzerland) |
Sales Manager |
|
FMC Corporation (US) |
Marketing Manager |
Market Size Estimation
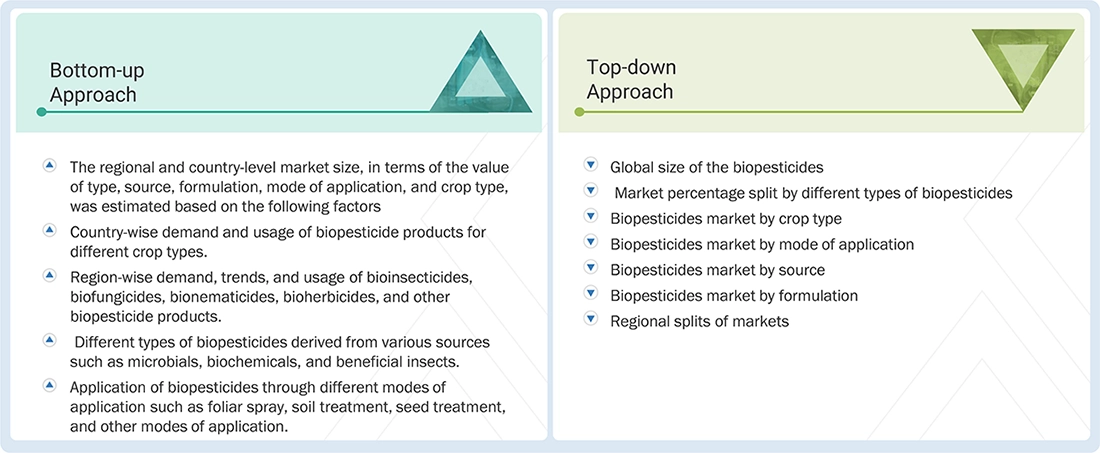
Both the top-down and bottom-up approaches were used to estimate and validate the total size of the biopesticides market. These approaches were also used extensively to determine the size of various subsegments in the market. The research methodology used to estimate the market size includes the following details:
- The key players in the industry and the overall markets were identified through extensive secondary research.
- All shares, splits, and breakdowns were determined using secondary sources and verified through primary sources.
- All possible parameters that affect the market covered in this research study were accounted for, viewed in extensive detail, verified through primary research, and analyzed to obtain final quantitative and qualitative data.
- The research included the study of reports, reviews, and newsletters of top market players, along with extensive interviews for opinions from leaders, such as CEOs, directors, and marketing executives.
Biopesticides Market : Top-Down and Bottom-Up Approach
Data Triangulation
After arriving at the overall market size from the estimation process explained above, the total market was split into several segments and subsegments. Data triangulation and market breakdown procedures were employed, wherever applicable, to estimate the overall biopesticides market and arrive at the exact statistics for all segments and subsegments. The data was triangulated by studying various factors and trends from the demand and supply sides. Along with this, the market size was validated using both the top-down and bottom-up approaches.
Market Definition
Biopesticides have pesticide properties originating from natural living organisms, including microorganisms, plants, and animals. Biopesticides are gaining prominence due to their safer and eco-friendly
ature.The Environmental Protection Agency has defined biopesticides as follows:
“Biopesticides include naturally occurring substances that control pests (biochemical pesticides), microorganisms that control pests (microbial pesticides), and pesticidal substances produced by plants containing added genetic material (plant-incorporated protectants) or PIPs.”
Key Stakeholders
- Agriculture pesticide manufacturers & suppliers
- Associations and industry bodies
- Biopesticide manufacturers & suppliers
- Biopesticide traders, retailers, and distributors
- Commercial research & development (R&D) institutions
- Venture capitalists and investors
- Government, regulatory bodies, and research organizations
- Technology providers to biopesticide & microbial companies
- Public hygiene organizations, government regulatory institutions, and food safety agencies
-
Associations and industry bodies:
- Food and Agriculture Organization (FAO)
- European Food Safety Authority (EFSA)
- British Pest Control Association (BPCA)
- National Pest Management Association (NPMA)
- National Pest Technicians Association
- Confederation of European Pest Management Association (CEPA)
- International associations and industry bodies such as Biopesticide Industry Alliance (BPIA) and the International Biocontrol Manufacturers Association (IBMA)
- Organisation for Economic Co-operation and Development (OECD)
Report Objectives
- Determining and projecting the size of the biopesticides market with respect to type, crop type, mode of application, source, formulation, and region
- Identifying the attractive opportunities in the market by determining the largest and fastest-growing segments
- Providing detailed information about the key factors influencing the market growth (drivers, restraints, opportunities, and industry-specific challenges)
- Providing the regulatory framework and market entry process related to the biopesticides market
- Analyzing the micro markets with respect to individual growth trends, prospects, and their contribution to the total market
Customization Options
With the given market data, MarketsandMarkets offers customizations according to company-specific scientific needs.
The following customization options are available for the report:
- Additional country-level analysis of the space sensors and actuators market
- Profiling of other market players (up to five)
Product Analysis
- Products Matrix, which gives a detailed comparison of the service portfolio of each company
Geographic Analysis
With the given market data, MarketsandMarkets offers customizations according to company-specific scientific needs
- Further breakdown of the Rest of Europe global biopesticides market into key countries
- Further breakdown of the Rest of Asia Pacific global biopesticides market into key countries
- Further breakdown of the Rest of South America global biopesticides market into key countries
Company Information
- Detailed analyses and profiling of additional market players (up to five)
Key Questions Addressed by the Report
What is the projected size of the biopesticides market by 2030?
The global biopesticides market is projected to grow from USD 8.94 billion in 2025 to USD 17.68 billion by 2030, registering a CAGR of 14.6% during the forecast period.
What factors are driving the growth of the biopesticides market?
The growth of the biopesticides market is driven by increasing demand for organic food products, stricter regulations on chemical pesticide residues, and the rising adoption of sustainable farming methods. Farmers are also increasingly implementing integrated pest management (IPM) and precision agriculture practices, which support the use of microbial and biochemical pest control solutions.
Why are farmers adopting biopesticides in modern agriculture?
Farmers are adopting biopesticides because they provide effective pest control without leaving harmful chemical residues. These products are considered safer for the environment, human health, and beneficial organisms. They also fit well into sustainable agriculture systems and help farmers meet regulatory requirements related to pesticide residues.
Which region holds a significant share in the global biopesticides market?
Europe holds a substantial share of the global biopesticides market. The region’s growth is supported by strict regulations on chemical pesticides, strong government support for sustainable agriculture, and increasing demand for environmentally friendly crop protection products.
Who are the key players in the global biopesticides market?
Key companies operating in the biopesticides market include Corteva Agriscience (US), Valent BioSciences (US), BASF (Germany), Bayer CropScience (Germany), Syngenta Group (Switzerland), FMC Corporation (US), UPL (India), Marrone Bio Innovations (US), Certis Biologicals (US), Koppert Biological Systems (Netherlands), AgBiome (US), Novonesis (Denmark), Lallemand Plant Care (Canada), BioWorks Inc. (US), and Andermatt Group AG (Switzerland).
Fact checked
Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the Biopesticides Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Custom Market Research Services
We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements
Get 10% Free CustomisationTESTIMONIALS

Business Innovation Director
US Based Leading Agribusiness,
Food and Ingredients ManufacturerI highly appreciate the team's efficiency for a well conducted study that helped us clarify some blind spots in food and agricultural niche markets. Although compiling information for B2B markets is very difficult, the MnM team pulled out the task successfully. The quality of research, level of insights, and responsiveness of team were commendable.
- US Biopesticides Market
- Canada Biopesticides Market
- Mexico Biopesticides Market
- France Biopesticides Market
- Germany Biopesticides Market
- Spain Biopesticides Market
- Italy Biopesticides Market
- UK Biopesticides Market
- Netherlands Biopesticides Market
- Russia Biopesticides Market
- China Biopesticides Market
- India Biopesticides Market
- Japan Biopesticides Market
- Australia Biopesticides Market
- Thailand Biopesticides Market
- Indonesia Biopesticides Market
- Brazil Biopesticides Market
- Argentina Biopesticides Market
- Chile Biopesticides Market
Growth opportunities and latent adjacency in Biopesticides Market





KORANGI
Jul, 2019
Looking for global biopesticides market and African share in consumption of biopesticides..
Giacomo
May, 2019
Want to develop an understanding regarding the global trend of Biopesticide - especially bacteria and microbials..
HyeGin
Aug, 2018
In addition to the sample report, I would like to know if you can provide the integrated table showing the market size of Beauveria Bassiana by soil treatment to berries in US..
User
Nov, 2019
Interested in the global biopesticide market.
Maitrayee
Jun, 2018
Want to know a detailed information about bio-insecticide..
Ricardo
Jun, 2019
By 2013/2014 Brazilian crop season a great amount of Dipel biospesticide was used against Helicoverpa armigera outbreaks. This represents a significant increase in Bacillus thuringiensis based biopesticides worldwide. I would like to know how important was this event to the whole biopesticide market..
David
Jan, 2019
Need information on the availability, mode of action and application of biopesticides in the UK..
David
Jan, 2019
Need information on the availability, mode of action and application of biopesticides in the UK..
Nguya
Feb, 2019
I would like to know the market outlook of microbial-based pesticides. .
MUJEEB
Nov, 2019
Looking for information regarding growth of global biopesticides market. .
Chen
Nov, 2019
Interested in the global biopesticide market.
Md
Oct, 2016
Looking for the bio pesticides (Bio-herbicides, Bio-insecticides, Bio-fungicides and others) details falong with bio pesticides list, explaining the active ingredient, doses, targeted crop, and targeted pest, mode of action, using methodology and price. .
Taufik
Sep, 2019
Interested in knowing the market potential for bio-oil from tobacco stem as biopesticide. .
Riley
Jul, 2026
Which regions are witnessing strong growth in the biopesticides market?.
Nicole
Jul, 2026
What future trends are shaping the biopesticides industry?.
Paisley
Jul, 2026
Biopesticides may not always act as quickly as chemical pesticides, but their environmental benefits are becoming increasingly important..
Emerson
Jul, 2026
Why are farmers increasingly adopting biopesticides despite slower action?.
Domenico
Jun, 2020
Very useful and interesting information. Thank you for your effort!.