Smart Glass Market

Smart Glass Market by Type (Tinted, Coated), Technology (Electrochromic, Suspended Particle Display [SPD], Liquid Crystal, Photochromic, Nanocrystalline), Control System (Voice-based, Building Automation System, Mobile-based) - Global Forecast to 2032


OVERVIEW
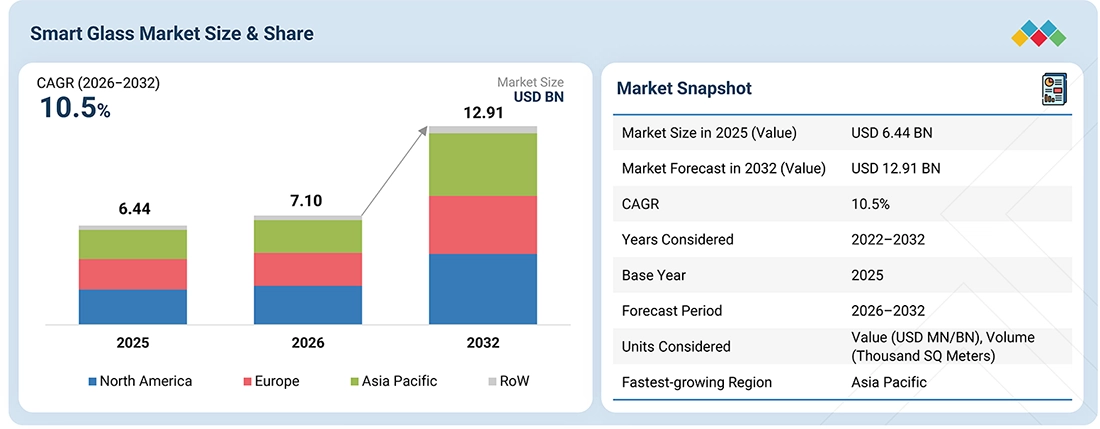
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
The smart glass market is projected to reach USD 12.91 billion by 2032 from USD 7.10 billion in 2026, growing at a CAGR of 10.5%. The market is witnessing steady growth due to increasing adoption of smart glass across architecture & construction, automotive & transportation, aerospace, healthcare, hospitality, and commercial applications. The growing demand for energy-efficient glazing, dynamic daylight and glare control, privacy, solar-heat management, and enhanced occupant comfort is accelerating the deployment of smart glass solutions. As industries focus on improving energy efficiency, sustainability, and user experience, the adoption of electrochromic, SPD, PDLC, and other smart glazing technologies is increasing across diverse applications. Additionally, advancements in functional coatings, switching technologies, mobile-based controls, and automated glazing systems are supporting market growth by improving optical performance, control flexibility, energy efficiency, and expanding smart glass into new applications.
KEY TAKEAWAYS
-
BY REGIONBy region, North America is expected to dominate the smart glass market with a share of ~35.7%, in terms of value, in 2025.
-
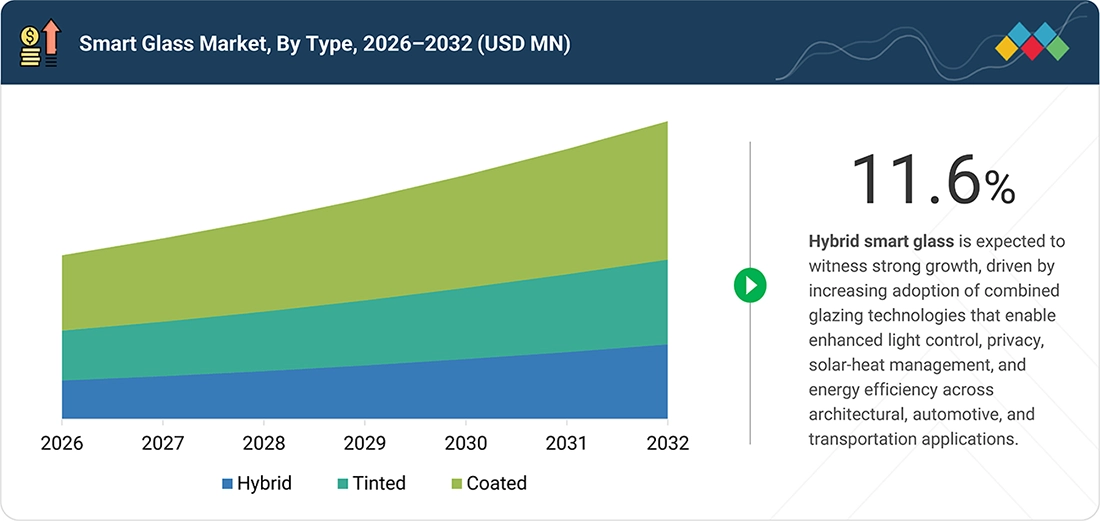
BY TYPEBy type, the hybrid segment is expected to record a CAGR of 11.6% during the forecast period.
-
BY TECHNOLOGYBy technology, the suspended particle display (SPD) segment is expected to register a CAGR of ~11.7% between 2026 and 2032.
-
BY MECHANISMBy mechanism, the active segment is expected to exhibit a CAGR of ~10.7% during the forecast period.
-
BY CONTROL SYSTEMBy control system, the mobile-based segment is expected to register a high growth rate during the forecast period.
-
BY END USEBy end use, the transportation segment is expected to capture the largest share in 2032.
-
COMPETITIVE LANDSCAPE (KEY PLAYERS)Saint-Gobain, AGC Inc., Gentex Corporation, Corning Incorporated, and Nippon Sheet Glass Co., Ltd. are identified as key players in the smart glass market due to their strong market presence, extensive glass and glazing portfolios, and advanced capabilities in electrochromic, SPD, PDLC, functional coatings, and specialty glass technologies.
-
COMPETITIVE LANDSCAPE (STARTUPS/SMES)Scienstry Inc. and Pro Display, among other startups and SMEs, have distinguished themselves through strong positions in specialized smart-glass applications, particularly switchable smart films, projection glazing, privacy glass, and retrofit solutions, highlighting their potential as emerging players in the global smart glass market.
The smart glass market is expected to grow significantly as industries increase investments in energy-efficient glazing, smart buildings, advanced automotive glazing, and intelligent transportation systems across architecture & construction, automotive & transportation, aerospace, healthcare, hospitality, and commercial applications. The market is further driven by rising demand for dynamic daylight and glare control, solar-heat management, privacy, occupant comfort, and improved energy efficiency. Product innovations and strategic developments by key players such as Saint-Gobain, AGC, Gentex, Corning, and NSG, including advancements in electrochromic, SPD, PDLC, hybrid glazing, functional coatings, and automated control systems, are further strengthening sustained market growth.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
Advanced electrochromic glazing, SPD and PDLC smart glass, automated tinting systems, mobile-based controls, and energy-efficient dynamic façades are transforming architecture & construction, automotive & transportation, aerospace, healthcare, hospitality, and commercial applications. These innovations enable dynamic daylight and glare control, privacy management, solar-heat reduction, improved occupant comfort, and enhanced energy efficiency. Advancements in functional coatings, switchable films, hybrid glazing, wireless connectivity, and intelligent control systems are improving switching performance, design flexibility, and integration across diverse applications. As building developers, automotive OEMs, and other end users increasingly adopt smart glass to improve energy performance, passenger comfort, and space functionality, these technologies are expected to support the shift toward higher-value glazing solutions and sustained growth of the global smart glass market.
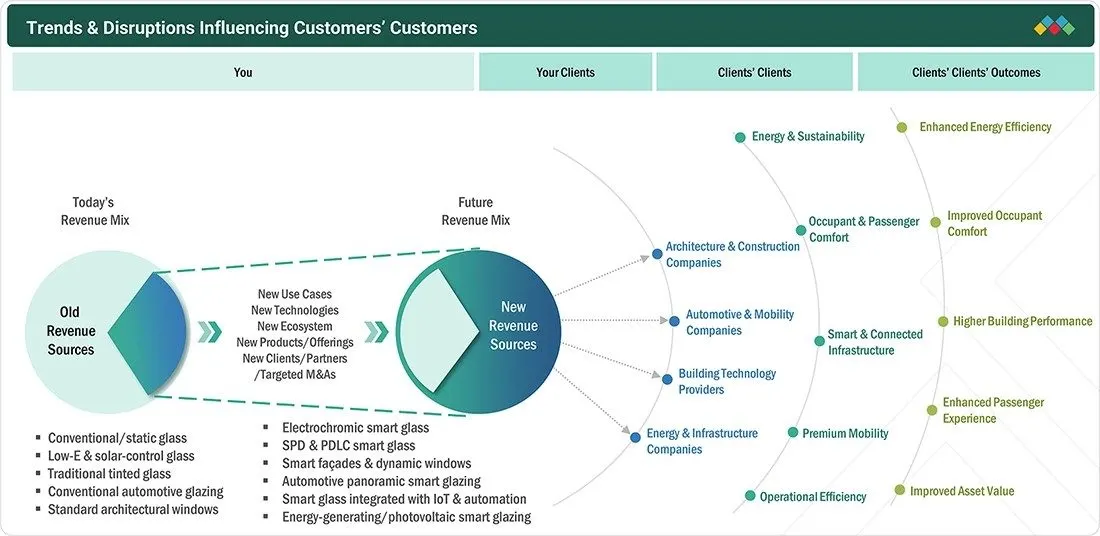
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Level
-
Increasing use of smart glass in modern luxury cars

-
Rising integration of electrochromic materials into smart glasses


Level
-
High initial investments and upfront costs

-
Operational and functional issues


Level
-
Growing trend of minimalist designs

-
Increasing demand for alternative power sources due to rising energy costs


Level
-
Lack of awareness about long-term benefits of smart glass technology

-
Complexities in maintaining compliance with building codes and regulations

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Increasing use of smart glass in modern luxury cars
The use of smart glass in modern luxury cars is growing rapidly due to its advanced functionalities, such as information projection, entertainment features, and window tinting. This technology has become integral to designing and developing modern luxury automobiles, enhancing privacy, entertainment, and safety within the vehicle.
Restraint: High initial investments and upfront costs
Smart glass technology was first introduced in the 1980s and commercialized after 2000. Over the years, there have been significant advancements in technology and applications. However, its adoption has been limited to the high-end and luxury sectors due to the high cost.
Opportunity: Growing trend of minimalist designs
Minimalist architecture, commonly known as minimalism, is a modern construction and design trend. This design philosophy prioritizes simplicity and essential elements over excessive decoration or ornamentation. The essence of minimalism is to simplify architectural concepts to their basic components, emphasizing the fundamental principles of design.
Challenge: Lack of awareness about long-term benefits of smart glass technology
The smart glass market is facing a significant challenge due to the lack of awareness about the long-term benefits of this innovative technology. Many potential users and stakeholders, including those in the consumer and business sectors, are unaware of the advantages and lasting impact that smart glass can have on various applications.
SMART GLASS MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Saint-Gobain offers SageGlass, an electrochromic smart glass that automatically or manually adjusts tint in response to changing sunlight conditions. It is used in façades, windows, skylights, and other architectural glazing applications. | Enables dynamic daylight and glare control | Reduces solar heat gain and cooling requirements | Enhances occupant comfort | Reduces reliance on blinds and shades | Supports energy-efficient building designs |
 |
AGC develops Smart Glazing Digital Curtain, which uses suspended particles within an interlayer to switch glazing between transparent and privacy states. The technology is particularly used in automotive roofs and other mobility applications. | Provides on-demand privacy and light control | Enables rapid switching between transparent and opaque states | Improves passenger comfort | Supports advanced automotive roof designs | Enhances control of natural light |
 |
Gentex develops electrochromic dimmable glass for automotive and aerospace applications, including self-dimming sunroofs, moonroofs, sun visors, HUDs, sensor shrouds, and electronically dimmable aircraft windows. | Reduces glare and solar load | Improves passenger and driver comfort | Enables automatic or on-demand dimming | Supports advanced vehicle and aircraft designs | Reduces dependence on conventional shades |
 |
Corning leverages its advanced glass and materials expertise in high-performance display and specialty glass, supporting applications requiring thin, durable, optically precise glass. Its display glass portfolio includes solutions for OLED and next-generation LCD technologies. | Enables high optical clarity and image quality | Supports thin and lightweight designs | Provides dimensional stability during processing | Enables integration into advanced display technologies | Supports next-generation electronic and display applications |
 |
NSG Group supports smart glazing through electrochromic and dynamic light-control glass solutions, including its collaboration with View for View Smart Glass. The group also develops value-added architectural glazing and technologies for energy-efficient buildings. | Enables dynamic control of visible light, UV, and solar radiation | Supports energy-efficient buildings | Reduces dependence on blinds and shades | Enhances daylight and thermal management | Expands smart glazing adoption in architectural applications |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
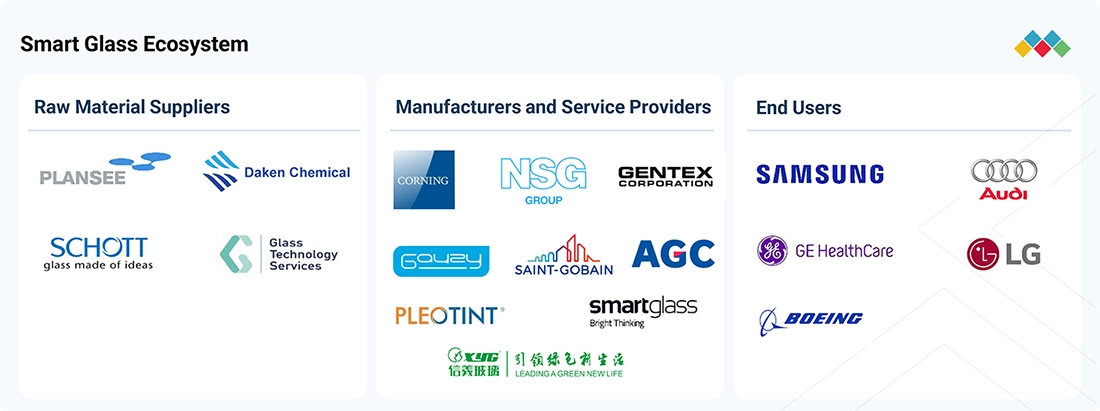
The smart glass ecosystem comprises raw material suppliers, smart glass manufacturers and suppliers, system integrators, and end users, forming an integrated value chain for dynamic glazing solutions. Raw material suppliers provide specialized glass substrates, coatings, chemicals, conductive materials, films, and other components required for smart glass production, while smart glass manufacturers and technology providers develop electrochromic, SPD, PDLC, thermochromic, and photochromic glazing solutions for diverse applications. Manufacturers and suppliers such as NSG Group, Gentex, AGC, Gauzy, Saint-Gobain, SmartGlass International, and Pleotint support the development and deployment of advanced smart glazing technologies. End users, including automotive OEMs, electronics manufacturers, healthcare organizations, aerospace companies, and building developers, drive demand for smart glass across automotive, architectural, aerospace, healthcare, hospitality, and commercial applications. Collaboration across the ecosystem supports technological innovation, improved optical performance, faster switching, enhanced energy efficiency, and integration with automated control systems, sensors, and smart-building platforms.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Smart Glass Market, by Type
Hybrid smart glass is expected to register the highest CAGR, driven by increasing adoption of combined smart-glazing technologies that offer enhanced flexibility in light control, privacy, glare reduction, and solar-heat management. The ability to integrate multiple technologies within a single glazing solution is expanding its use across architectural, automotive, transportation, and other advanced applications.
Smart Glass Market, by Technology
Electrochromic smart glass is expected to account for a significant market share due to its ability to dynamically adjust tint levels, control glare and solar heat, and improve energy efficiency. These systems are widely used in architectural façades, windows, skylights, automotive glazing, and transportation applications, supporting continued adoption across diverse smart glazing applications.
Smart Glass Market, by Mechanism
Active smart glass is anticipated to maintain a prominent position in the smart glass market due to its widespread use in applications requiring electrically controlled tinting, privacy, and light management. Its ability to provide on-demand control of transparency, glare, and solar heat supports continued adoption across architectural, automotive, transportation, and other advanced glazing applications.
Smart Glass Market, by Control System
Switch-based control is anticipated to maintain a prominent position in the smart glass market due to its simple operation, ease of installation, and reliable on-demand control of glass transparency and tint. Its widespread use in architectural windows, partitions, automotive glazing, and privacy applications supports continued adoption across diverse smart glass applications.
Smart Glass Market, by End Use
The transportation segment is anticipated to maintain a prominent position in the smart glass market due to increasing demand for advanced glazing solutions in automobiles, aircraft, trains, and other transportation applications. Rising adoption of smart glass in panoramic roofs, sunroofs, side windows, and aircraft windows, along with growing demand for enhanced passenger comfort, glare control, privacy, and solar-heat management, is further supporting segment growth.
REGION
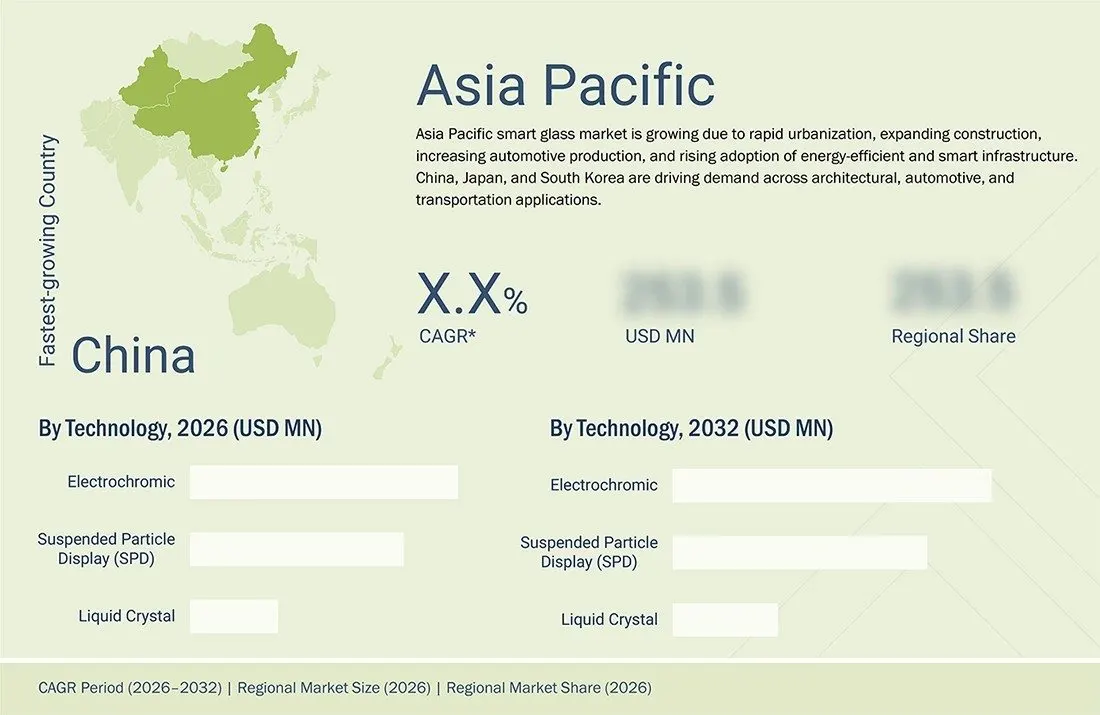
Asia Pacific to be fastest-growing region in smart glass market during forecast period
Asia Pacific is expected to grow at the fastest rate in the smart glass market during the forecast period due to rapid urbanization, expanding construction activities, increasing automotive production, and rising adoption of smart and energy-efficient infrastructure across China, Japan, and South Korea. Investments in green buildings, smart cities, electric vehicles, and advanced transportation are boosting the adoption of smart glass across architectural, automotive, and transportation applications. Furthermore, increasing demand for energy-efficient glazing, dynamic façades, panoramic roofs, privacy glass, and advanced passenger-comfort solutions, along with continuous technological advancements in electrochromic, SPD, and PDLC technologies, is expected to further strengthen regional market growth.
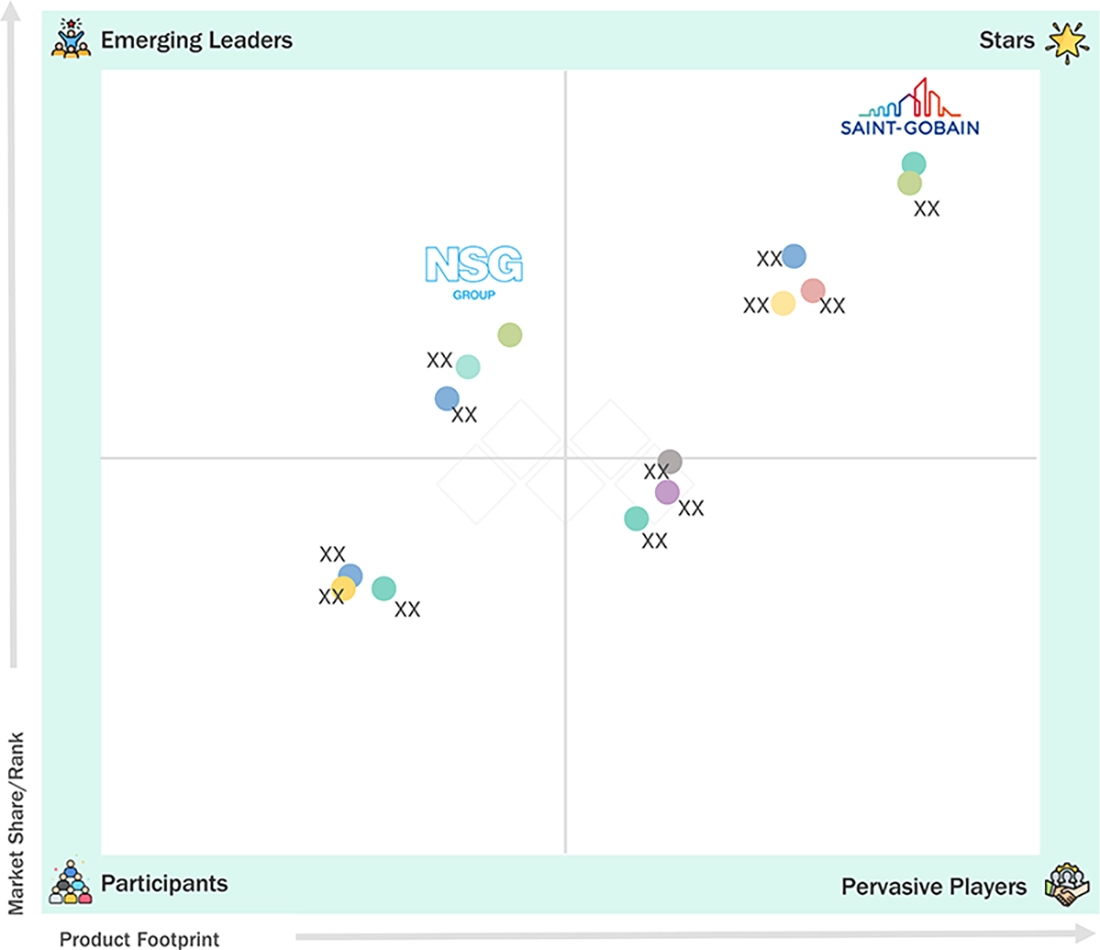
SMART GLASS MARKET: COMPANY EVALUATION MATRIX
In the smart glass market matrix, Saint-Gobain (Emerging Leader) holds a strong position due to its SageGlass portfolio of electrochromic smart glazing, which enables dynamic tinting, daylight and glare control, and improved building energy efficiency across commercial and institutional applications. Its broad architectural glass portfolio, global presence, and continued focus on intelligent glazing and automated control systems strengthen its competitive position. NSG Group (Emerging Leader) is strengthening its position through its portfolio of dynamic glazing solutions, including electrochromic smart glass and switchable glazing technologies for architectural and automotive applications. Its focus on next-generation dynamic glazing, energy-efficient glass, and advanced automotive glazing, combined with ongoing R&D in smart glass technologies, supports its competitiveness across high-value architectural and transportation applications.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- Saint-Gobain (France)
- AGC Inc. (Japan)
- Gentex Corporation (US)
- Corning Incorporated (US)
- Nippon Sheet Glass Co., Ltd (Japan)
- View, Inc. (US)
- Gauzy Ltd (Israel)
- Xinyi Glass Holdings Limited (China)
- Research Frontiers (US)
- Diamond Switchable Glass ltd (Ireland)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2025 (Value) | USD 6.44 Billion |
| Market Forecast in 2026 (Value) | USD 7.10 Billion |
| Market Forecast in 2032 (Value) | USD 12.91 Billion |
| Growth Rate | CAGR of 10.5% from 2026–2032 |
| Years Considered | 2022–2032 |
| Base Year | 2025 |
| Forecast Period | 2026–2032 |
| Units Considered | Value (USD Million/Billion), Volume (Thousand SQ Meters) |
| Report Coverage | Revenue Forecast, Company Ranking, Competitive Landscape, Growth Factors, and Trends |
| Segments Covered |
|
| Regions Covered | North America, Europe, Asia Pacific, and RoW |
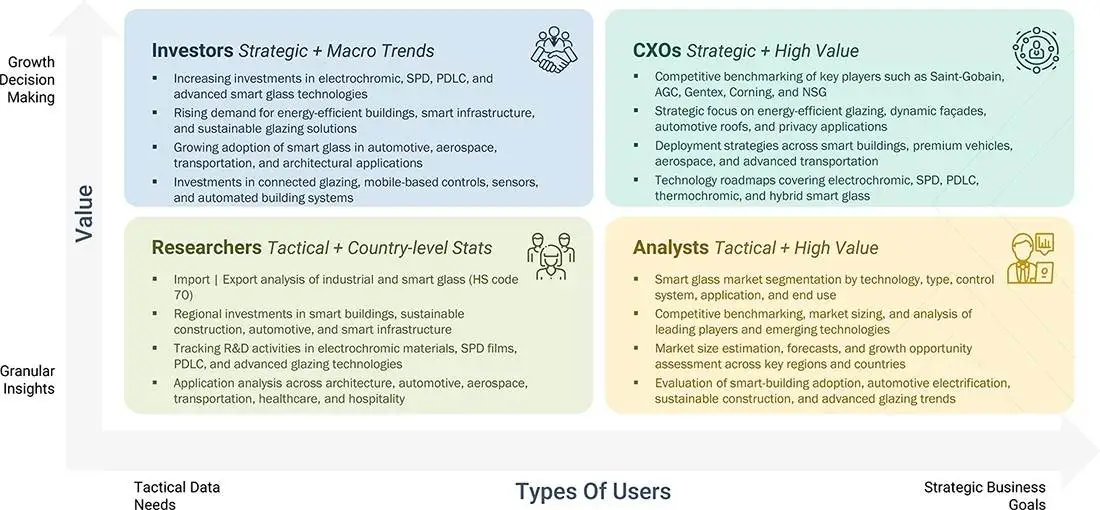
WHAT IS IN IT FOR YOU: SMART GLASS MARKET REPORT CONTENT GUIDE
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Smart Glass Manufacturer |
|
|
| Smart Glass Film / Technology Supplier |
|
|
| Architecture & Construction / System Integrator |
|
|
| Automotive & Transportation Enterprise |
|
|
| Private Equity / Investment Firm |
|
|
RECENT DEVELOPMENTS
- August 2026 : Saint-Gobain and AGC partnered to develop a large-scale, highly electrified flat glass furnace aimed at significantly reducing CO2 emissions from glass production. This initiative promotes more sustainable manufacturing of flat glass, which is essential for smart glass used in architectural and automotive applications.
- February 2026 : Saint-Gobain Glass launched COOL-LITE SKL 170, a selective solar control coating for laminated glass in complex façades. This product enhances energy efficiency and comfort in high-performance building envelopes and is suitable for advanced smart glazing solutions.
- February 2026 : Saint-Gobain Glass UK launched PLANITHERM NEO, a thermal insulation glass for double and triple glazing. This product meets evolving performance and aesthetic needs in windows and façades, supporting high-efficiency and potentially smart glazing systems in residential and commercial buildings.
- February 2025 : SageGlass, a Saint-Gobain subsidiary, introduced RealTone, an electrochromic glass solution known for its color neutrality and dynamic tinting. This product targets the architectural smart glass market, enhancing visual comfort and energy performance for façades and interiors.
- June 2024 : Research Frontiers launched a revolutionary retrofittable SPD-SmartGlass window: the Thermolite RetroWAL SPD system. This product was launched at the AIA Expo 2024 in Washington, DC, on June 6-7, 2024, at Booth 720.
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
Methodology
The study involved four major activities in estimating the current size of the global smart glass market. Extensive secondary research was conducted to gather information on the smart glass ecosystem, including smart glass manufacturers, technology providers, glass processors, film and material suppliers, automotive and architectural glazing companies, and system integrators. This was followed by primary research with industry stakeholders across the value chain, including smart glass manufacturers, technology developers, glass fabricators, component suppliers, distributors, architects, automotive companies, construction firms, and end users, to validate assumptions and market sizing. Both top-down and bottom-up approaches were used to estimate the overall market size. Market breakdowns and data triangulation techniques were then applied to determine the size of individual segments and subsegments by technology, type, mechanism, control system, end use, and region. Secondary and primary sources were jointly used to support a comprehensive technical, commercial, and competitive analysis of the global market.
Secondary Research
Various secondary sources were referred to during the secondary research process to identify and collect information relevant to the smart glass market. These sources included annual reports, company presentations, press releases, product catalogs, technical datasheets, patents, technical journals, industry publications, company websites, trade directories, and government databases. Secondary research was conducted to obtain key insights into the market’s supply chain, value chain, competitive landscape, and segmentation by technology, type, mechanism, control system, end use, and region. It also helped assess industry trends, adoption of dynamic glazing, energy-efficient windows, privacy glass, automotive smart glazing, and advancements in electrochromic, SPD, PDLC, thermochromic, and photochromic technologies. The collected information was further analyzed to estimate the overall market size and validate market assumptions, which were subsequently refined through primary research with industry experts and key stakeholders.
Primary Research
Extensive primary research was conducted after gaining knowledge about the current scenario of the smart glass market through secondary research. Several primary interviews were conducted with experts from the demand and supply sides across four major regions: North America, Europe, Asia Pacific, and RoW. This primary data was collected through questionnaires, emails, and telephonic interviews.
Breakdown of Primary Interviews
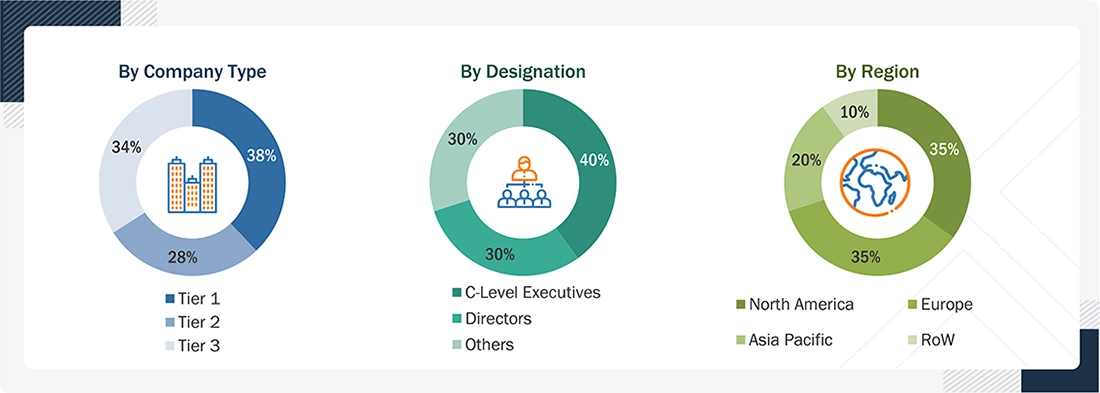
Note: The three tiers of the companies are defined based on their total revenue in 2025: Tier 1 - revenue greater than or equal to USD 1 billion; Tier 2 - revenue between USD 100 million and USD 1 billion; and Tier 3 revenue less than or equal to USD 100 million. Other designations include sales managers, marketing managers, and product managers.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
Both top-down and bottom-up approaches were used to estimate and validate the total size of the smart glass market. These methods have also been used extensively to estimate the size of various subsegments in the market. The following research methodology was used to estimate the market size:
- Major players in the smart glass market and related markets were identified through extensive secondary research.
- The industry’s value chain and market size (in terms of value) were determined through primary and secondary research processes.
- All percentage shares, splits, and segment-level breakdowns were determined using secondary sources and verified through primary sources.
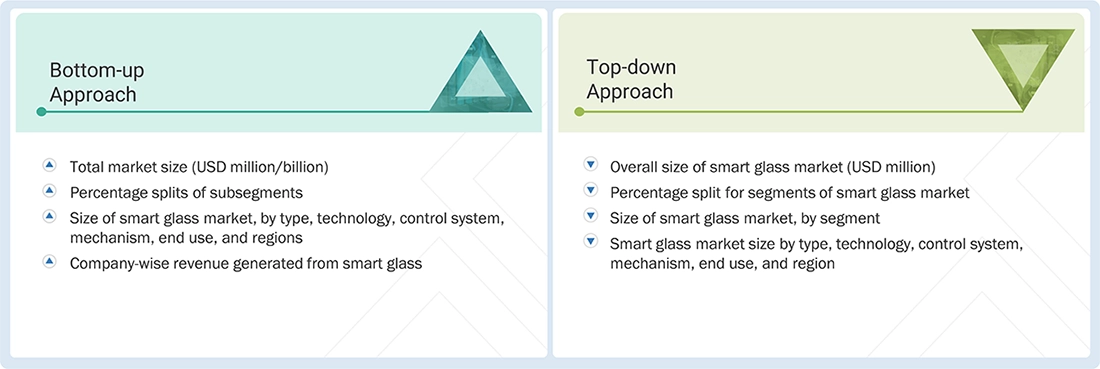
Data Triangulation
After arriving at the overall size of the smart glass market through the market size estimation process, the total market was divided into relevant segments and subsegments. Data triangulation and market breakdown procedures were employed, wherever applicable, to complete the market engineering process and derive the statistics for each segment and subsegment. The data was triangulated by evaluating factors and trends from the demand and supply sides, including technology adoption, product offerings, application requirements, manufacturing developments, and regional trends. The analysis considered key smart glass technologies such as electrochromic, PDLC, SPD, thermochromic, and photochromic, along with active, passive, and hybrid configurations. Along with this, the market size was validated using top-down and bottom-up approaches to ensure consistency across the overall market and individual segments.
Market Definition
Smart glass refers to advanced glazing that can change or control its optical properties, such as light transmission, tint, transparency, or opacity, in response to electrical signals, sunlight, temperature, or other environmental conditions. Smart glass enables dynamic control of daylight, glare, solar heat, and privacy and is used across a range of architectural, automotive, transportation, aerospace, and specialized applications. Depending on the technology and application requirements, smart glass can incorporate electrochromic, suspended particle device (SPD), polymer-dispersed liquid crystal (PDLC), thermochromic, and photochromic technologies.
Smart glass plays a crucial role across commercial and residential buildings, automotive and transportation, aerospace, healthcare, hospitality, and marine applications. These solutions help improve occupant comfort, manage solar heat and glare, provide on-demand privacy, and support energy-efficient building and vehicle designs. Smart glass is commonly integrated into windows, façades, partitions, skylights, sunroofs, side windows, aircraft windows, and other dynamic glazing systems. A typical smart glass system may consist of a glass substrate, functional film or coating, conductive layers, control electronics, and associated sensors or automation systems, with its configuration varying according to the technology, switching mechanism, optical requirements, application, and operating environment.
Key Stakeholders
- Smart glass manufacturers
- Building material suppliers
- Switchable (metal-oxide) film manufacturers
- Dimmable/smart glass film manufacturers
- Aerospace and automotive glass industry players
- Architects and building owners
- Smart glass-related technology investors
- Advanced glass and film technology researchers and developers
- End users
- Research institutes and organizations
- Market research and consulting firms
- Smart glass buyers
- Smart glass technology providers
Report Objectives
- To describe and forecast the smart glass market size, by type, technology, control system, mechanism, end use, and region in terms of value
- To describe and forecast the market for various segments across four main regions, namely North America, Europe, Asia Pacific, and RoW, in terms of value
- To describe and forecast the market, by technology and region in terms of volume
- To strategically analyze micromarkets with regard to individual growth trends, prospects, and contributions to the markets.
- To provide detailed information regarding drivers, restraints, opportunities, and challenges influencing market growth.
- To analyze opportunities for stakeholders by identifying high-growth segments in the market
- To provide a detailed overview of the smart glass value chain
- To strategically analyze key technologies, average selling price trends, trends impacting customer business, ecosystem, regulatory landscape, patent landscape, Porter’s five forces, import and export scenarios, trade landscape, key stakeholders and buying criteria, and case studies pertaining to the market under study
- To strategically profile key players in the smart glass market and comprehensively analyze their market share and core competencies
- To analyze competitive developments, such as partnerships, acquisitions, expansions, collaborations, and product launches, along with R&D, in the market
Available customizations:
With the given market data, MarketsandMarkets offers customizations according to the company’s specific needs. The following customization options are available for the report:
Company Information:
- Detailed analysis and profiling of additional market players (up to 5)
Key Questions Addressed by the Report
What is the current market size of the global Smart Glass market?
The global Smart Glass market was valued at USD 5.87 billion in 2024. Increasing demand for energy-efficient buildings, smart automotive solutions, and sustainable technologies is supporting market growth. (MarketsandMarkets)
What is the forecasted size of the Smart Glass market by 2030?
The Smart Glass market is projected to grow from USD 6.42 billion in 2025 to USD 10.42 billion by 2030. (MarketsandMarkets)
What is the expected CAGR of the Smart Glass market during 2025–2030?
The global Smart Glass market is expected to grow at a CAGR of 10.2% from 2025 to 2030, driven by adoption in construction, automotive, and smart infrastructure applications. (MarketsandMarkets)
What are the major growth drivers for the Smart Glass industry?
Key growth drivers include increasing demand for energy-efficient solutions, sustainable buildings, smart windows, privacy glass, luxury automotive applications, IoT integration, and low-carbon infrastructure solutions. (MarketsandMarkets)
What are the key trends shaping the Smart Glass market?
Major trends include adoption of electrochromic technology, AI and IoT-enabled glass systems, smart building automation, dynamic façades, switchable privacy glass, and integration with smart home systems. (MarketsandMarkets)
Which companies are the leading players in the Smart Glass market?
Major companies operating in the Smart Glass market include Saint-Gobain, AGC Inc., Gentex Corporation, Corning Incorporated, Nippon Sheet Glass Co. Ltd., Research Frontiers Inc., View Inc., Gauzy Ltd., and Polytronix Inc. (MarketsandMarkets)
Which industries are driving demand for Smart Glass?
The major end-use industries include construction and architecture, automotive and transportation, aerospace, marine, consumer electronics, and energy sectors. The construction sector remains a significant adopter due to demand for energy-efficient buildings. (MarketsandMarkets)
Which technology segment is expected to dominate the Smart Glass market?
Electrochromic smart glass is expected to hold a leading position due to its energy-saving capabilities, adjustable transparency, and suitability for buildings and automotive applications. (MarketsandMarkets)
Which region is expected to grow fastest in the Smart Glass market?
Asia Pacific is expected to register the fastest growth, with a projected CAGR of 12.5% during 2025–2030, driven by urbanization, smart infrastructure investments, automotive production, and construction growth. (MarketsandMarkets)
What regions and segments are covered in the Smart Glass market report?
The report covers North America, Europe, Asia Pacific, and Rest of the World (RoW). The market is analyzed by type (tinted, coated), technology (electrochromic, SPD, liquid crystal, photochromic, nanocrystalline), control system, mechanism, end use, and region. (MarketsandMarkets)


Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the Smart Glass Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Custom Market Research Services
We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements
Get 10% Free CustomisationTESTIMONIALS

Tetsuya Ohhira
Business Development Manager-Technology Business
Nikon Corporation,
Leading Japanese MNC specializing in optics and imaging productswww.nikon.com
MarketsandMarkets™ response
is quick. Their attitude is flexible and positive. Analyst Insights are globally considered and
significant. Client Services quickly respond to our inquiry and demand. Their wide range of global
surveys help us make our strategic plan.
We hope Knowledge Store will be easier to search
for a report.
VP - Marketing & Business Development
Leading Provider of Process Control Solutions
We engaged with MarketsandMarkets on a study to perform an analysis and recommend a Go-To-Market strategy for metrology and process control in the semiconductor market. The study was tailored to our targets and needs with well-defined milestones. Our overall experience with the MarketsandMarkets team was very good throughout the project in all aspects including the analysis methodologies used, the quality and depth of primary and secondary data sets, the professionalism and flexibility of the team and the ability to meet the target schedule and milestones. We want to thank MarketsandMarkets team for a job well done.
Growth opportunities and latent adjacency in Smart Glass Market





Darren
Sep, 2014
Do you have forecasts for the total glass market that would serve as the potential for retrofitting/replacement with Smart Glass?.
Randall
Apr, 2026
Is there a detailed value chain and ecosystem analysis to help identify investment opportunities across suppliers, manufacturers, and end users?.
Jack
Apr, 2026
Is it possible to add forecasts specifically for smart glass in electric vehicles and premium automotive segments?.
vishnu
Dec, 2015
Reasons why photochromic technology has not been incorporated for manufacturing of smart glass? Details such as it's cost, technological short comings, etc. .
kee
Sep, 2014
I want the list of manufacturers of smart glasses in US with their product prices, because I will sale the best one in KSA as representative of best products..
Lisa
Apr, 2017
I came across your report and the segments "Consumer Electronics" and "Power Generation Plant" really caught my eye. What we primarily do is manufacture these glasses for aircraft, vehicles and buildings. If you could explain what goes into consumer electronics and solar power generation, I could have a word with my manager and we could take this ahead. Looking forward to your timely response..
George
Apr, 2016
I am interested in Smart Glasses + Touched, separately. Information for the European and Middle East markets , if there are any import figures / country , and market shares among the producing companies , and any general marketing info's !.
George
Apr, 2016
I am interested in Smart Glasses + Touched, separately. Information for the European and Middle East markets , if there are any import figures / country , and market shares among the producing companies , and any general marketing info's !.
Gerard
Feb, 2017
I'm looking for data on enterprise use of smart glasses, to create a graphic to accompany a Wall Street Journal article..
Aurelio
Dec, 2017
I am only interested in the Automotive sector for smart glass report. So if you could customize it so we could reduce the whole report scope I'd appreciate a new quote, considering the actual price is way over my budget..
Yvonne
Dec, 2014
We have a client who is interested in the smart glass market. He is especially interested in data about installed square meter of facades, installed square meters of glass and installed square meter of smart glass in the following regions: World, Europe, Germany. Further he is interested in the potential of smart glass in the future. We would like to know if the study comprises such data? Furthermore which sources you used to get the data (in general)? Our client likes to purchase a study, but is uncertain about the quality of the data. I would very much appreciate your support. It is possible to get a sample?.
Mike
Oct, 2014
I am interested in penetration and growth rates of the major smart glass players (Sage, View, Gauzy, Scienstry, Pleating) .
CHNG
Jan, 2019
I want to know market trend of using smart glass in 10 years down the road; or any related information about smart glass..
Karen
Jul, 2014
Our company is interested in know more about Smart Glass applications in Aerospace industry, in order to start a pilot trial in our MRO..
Addison
May, 2017
I am interested in knowing the Architecture growth in North America, energy savings, renovation vs new construction. Also, which company has best technology?.
Yasuyuki
Oct, 2019
We are examining the needs of smart glass and the market price. Also, I would like to know why it is expanding in the West and not in Asia..