Railway Signaling Market by Train (Passenger, Freight), Technology (ABS, ETCS, CBTC, PTC & ATC), End-Use (Mainline, Freight), Offering (Hardware, Software), Component, Infrastructure, Deployment, Connectivity, and Region - Global Forecast to 2033

icon1
USD 32.60 BN
MARKET SIZE, 2033
icon2
CAGR 5.8%
(2026-2033)
icon3
301
REPORT PAGES
icon4
233
MARKET TABLES

OVERVIEW

railway-signaling-market Overview

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

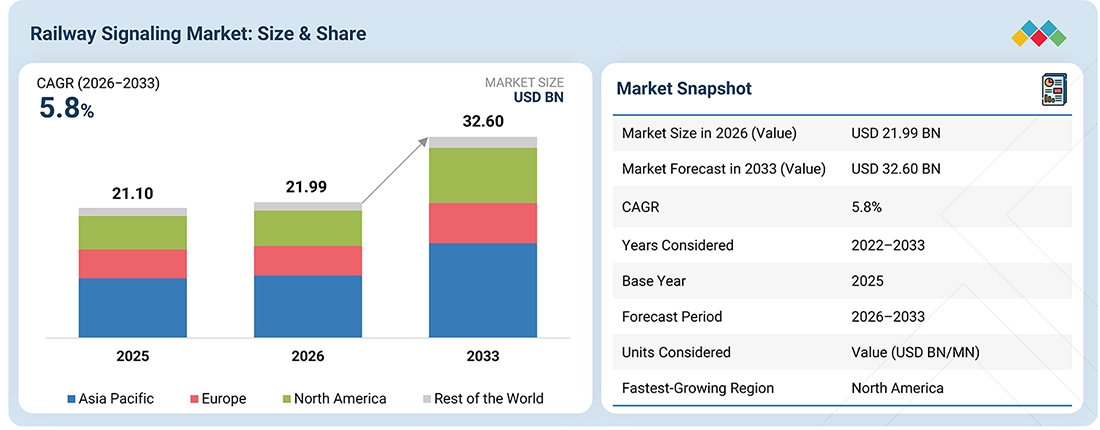
The railway signaling market is projected to reach USD 32.60 billion by 2033 from USD 21.99 billion in 2026, at a CAGR of 5.8%. The market is expanding as rail operators increase investments in network capacity enhancement, train automation, and modernization of aging signaling infrastructure. Deployment of advanced signaling technologies such as ETCS and CBTC is increasing across high-density mainline and urban rail networks, driven by the need to support higher train frequencies, improve operational control, and meet evolving safety requirements. At the same time, modernization of interlocking infrastructure, trackside signaling assets, and train detection systems is supporting replacement demand across brownfield networks. As signaling becomes more technology-intensive, suppliers with capabilities in system integration, interoperability, migration planning, and long-term asset support are better positioned to capture major modernization and network expansion programs.

KEY TAKEAWAYS

  • MARKET SNAPSHOT:
    Market Size (2025): USD 21.10 Billion
    Current Market Size (2026): USD 21.99 Billion
    Projected Market Size (2033): USD 32.60 Billion
    CAGR (2026–2033):  5.8%
  • BY REGION
    Asia Pacific is projected to account for the largest market share during the forecast period.
  • BY TCMS Train Type
    By TCMS train type, the light rail & metros (DMU & EMU) segment is expected to account for a significant share of 30.9% of the railway signaling market.
  • BY Technology
    Based on technology, CBTC is projected to register the highest CAGR of 9.0% during the forecast period.
  • BY End-use
    By end use, urban is projected to experience the highest growth rate of 7.2% during the forecast period.
  • COMPETITIVE LANDSCAPE (KEY PLAYERS)
    Alstom (France), Siemens Mobility (Germany), Hitachi Rail (UK), China Railway Signal & Communication (CRSC) (China), and Wabtec (US), among others, continue to strengthen their market positions through investments in ETCS and CBTC platforms.
  • COMPETITIVE LANDSCAPE (STARTUPS/SMES)
    Companies such as Traffic Control Technology (India) and UniTTEC (China) are expanding their footprint by offering cost-competitive signaling solutions.

Software-based signaling is becoming a cost-focused alternative to highly proprietary signaling architectures, as rail operators seek to reduce upgrade complexity and improve the reuse of existing infrastructure. The adoption of modular signaling architectures, standardized interfaces, and software-based control functions is gaining relevance, particularly in Europe, where EU Rail and EULYNX initiatives are supporting common interfaces, data models, and scalable signaling architectures for ETCS-based operations. This shift is encouraging suppliers to separate software functions from hardware platforms, allowing upgrades without replacing entire signaling installations. At the same time, the migration toward FRMCS and higher data requirements is creating pressure to design signaling systems that can support future communication architectures and greater levels of automation. These developments are likely to increase competition around software architecture, interoperability, cybersecurity, and upgradeability, while reducing the long-term advantage of closed proprietary signaling platforms.

TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS

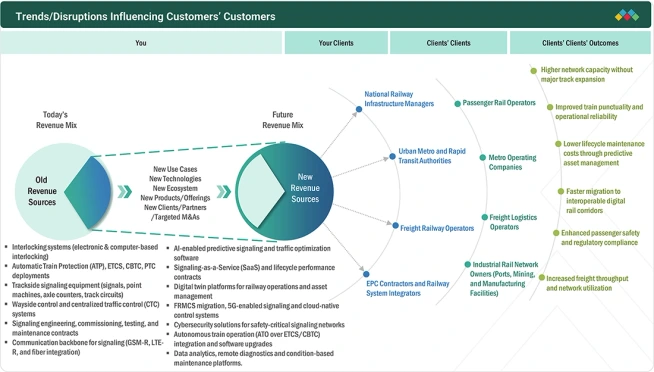
The railway signaling market is evolving from a project-based signaling equipment industry toward an integrated rail-control and lifecycle solutions ecosystem. While traditional revenue continues to come from interlocking systems, trackside signaling, train detection, onboard equipment, installation, and maintenance, future growth is increasingly supported by digital traffic management, signaling software, predictive asset management, remote diagnostics, cybersecurity, and data-driven network optimization. This transition is strengthening collaboration between signaling OEMs, railway infrastructure managers, metro and passenger rail operators, freight operators, and EPC/system integrators as operators prioritize higher network capacity, faster migration to interoperable digital corridors, improved punctuality, and reduced lifecycle costs without major track expansion. As railway operators increasingly shift toward outcome-based performance and asset availability, signaling suppliers are expanding beyond initial system deployment into remote monitoring, condition-based maintenance, software upgrades, traffic optimization, and integrated lifecycle contracts, creating recurring revenue opportunities while improving signaling availability, operational resilience, and network utilization.

railway-signaling-market Disruptions

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

MARKET DYNAMICS

Drivers
Impact
Level
  • Network capacity optimization through moving block signals and traffic digitalization
  • Increasing automation across metro and mainline rail network
RESTRAINTS
Impact
Level
  • Legacy signaling migration creating opportunity cost for operators
OPPORTUNITIES
Impact
Level
  • Transition from GSM-R to FRMCS and 5G railway communications
  • AI-driven traffic orchestration enabling autonomous freight rail operations
CHALLENGES
Impact
Level
  • Interoperability requirements reducing product differentiation

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Driver: Network capacity optimization through moving block signals and traffic digitalization

Capacity pressure is shifting signaling investment toward systems that extract more throughput from existing corridors. ETCS, CBTC, centralized traffic management, and digital interlocking are increasingly being combined with timetable optimization and real-time traffic control, allowing operators to improve network utilization without proportional civil infrastructure expansion. The commercial value is therefore moving toward integrated train control and traffic management architectures, rather than standalone signaling equipment. Siemens' 2026 Mexico ETCS project, for example, combines ETCS Level 1 with TPS.plan for timetable and network optimization.

Restraint: Legacy signaling migration creating opportunity cost for operators

Legacy replacement competes directly with other railway capacity and infrastructure investments, particularly where existing systems remain operational despite aging. The migration also requires service possessions, parallel system operation, application engineering, and extensive testing before cutover. Indian Railways' 2026 projects replacing relay-based interlocking across high-utilization routes illustrate the scale of this brownfield requirement, with INR 405 crore (USD 43.1 million) approved for 32 locations in June 2026.

Opportunity: AI-driven traffic orchestration enabling autonomous freight rail operations

AI is creating an additional software layer above conventional signaling by enabling predictive conflict detection, dynamic train sequencing, and disruption management. In 2026, Hitachi Rail demonstrated AI powered traffic management for mainline and high speed rail, while Siemens demonstrated AI supported traffic management and network optimization through its digital rail portfolio. This creates a new revenue pool for suppliers that can integrate AI decision support with existing signaling and traffic management systems, without requiring immediate replacement of safety-critical infrastructure.

Challenge: Interoperability requirements reducing product differentiation

Standardized signaling architectures are expanding addressable markets while making proprietary differentiation harder to sustain. ETCS is designed to replace multiple national train control systems with an interoperable framework, while current European requirements continue to address compatibility across train detection, onboard equipment, communications, and national rules. Suppliers therefore need to differentiate through certification efficiency, migration capability, open interfaces, integration speed, and system validation, rather than relying only on proprietary signaling hardware.

RAILWAY SIGNALING MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES

COMPANY USE CASE DESCRIPTION BENEFITS
company logo
Deploys digital interlocking, CBTC, and ERTMS solutions to modernize train-control architectures across urban and mainline networks Enables shorter headways, higher line capacity, and migration toward software-intensive automated signaling
company logo
Integrates ETCS, digital interlocking, and control systems for high-speed and mainline signaling modernization Supports higher train throughput and standardized digital control while reducing legacy-system dependency
company logo
Deploys electronic interlocking, ETCS, and CBTC platforms for large-scale network and station modernization Expands network capacity and enables centralized, real-time train movement management
company logo
Provides CBTC-based signaling and train-control solutions for metro and urban rail networks Supports high-frequency operations through reduced headways and automation-ready train control
company logo
Combines electronic train management, virtual-block signaling, precision positioning, and communications into integrated train-control systems Improves corridor capacity and operational visibility while enabling advanced train-control migration

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET ECOSYSTEM

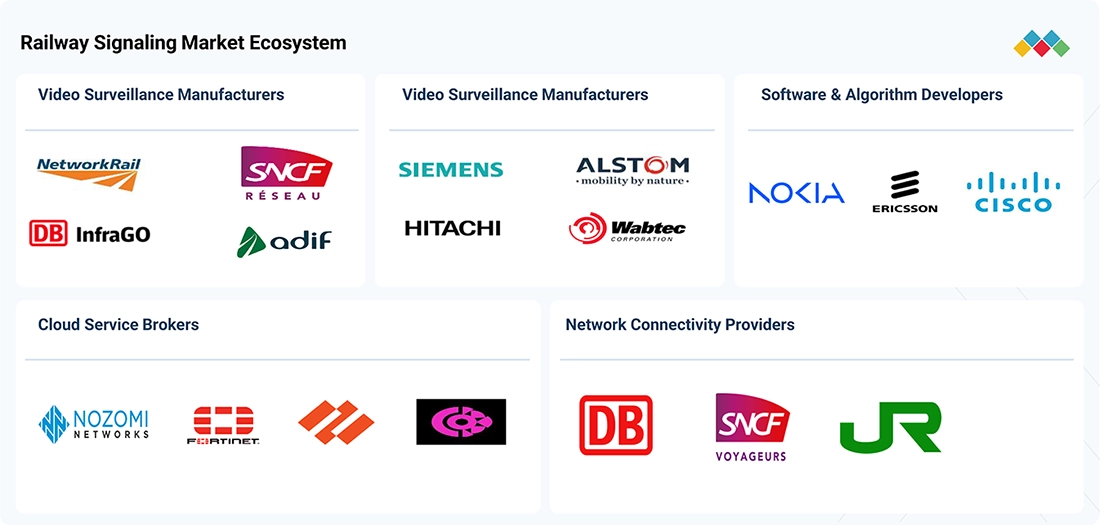
The railway signaling ecosystem is built on interdependent collaboration between rail infrastructure managers, signaling and rolling-stock OEMs, communications technology providers, cybersecurity specialists, and rail operators to deliver safety-critical and interoperable train-control systems. Infrastructure managers such as Network Rail, DB InfraGO, SNCF Réseau, and ADIF define network capacity, modernization, and interoperability requirements, while signaling OEMs including Siemens Mobility, Alstom, Hitachi Rail, and Wabtec integrate interlocking, train control, onboard systems, and wayside equipment into deployable architectures. Communications providers such as Nokia, Ericsson, and Cisco enable the connectivity required for real-time signaling and future digital rail networks, while cybersecurity and digital-asset specialists strengthen network protection, system resilience, and remote asset management. Rail operators ultimately translate these capabilities into higher capacity, improved punctuality, safer train movements, and lower disruption costs, making cross-layer integration a critical differentiator for signaling suppliers seeking long-term positions in modernization programs.

railway-signaling-market Ecosystem

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET SEGMENTS

railway-signaling-market Segments

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Railway Signaling Market, By Train Type

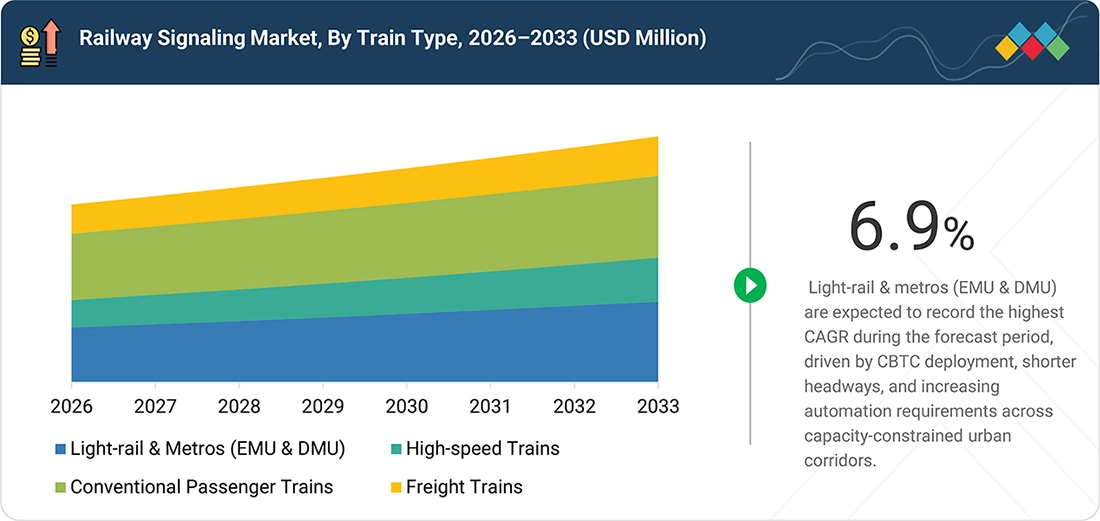
Light-rail & metros (EMU & DMU) are projected to remain the largest segment during the forecast period, supported by dense urban operations that require high-capacity, low-headway signaling. The segment has strong demand for CBTC, ATO, ATP, and centralized traffic management to maximize line capacity, operational reliability, and automation. The opportunity remains concentrated for OEMs and Tier-1 suppliers in CBTC modernization, automation-ready architectures, and integrated train-to-ground control solutions, particularly across high-density metro networks where incremental capacity gains can defer costly infrastructure expansion.

Railway Signaling Market, By Offering

Solutions are expected to remain the largest offering segment during the forecast period, as railway operators increasingly seek integrated signaling platforms that combine train control, traffic management, communications, and cybersecurity. The shift toward cloud-based interlocking, radio block center functions, AI-enabled traffic management, and predictive maintenance is increasing demand for scalable solutions that can support network upgrades without extensive infrastructure replacement. This is shifting supplier competition toward software capability, system integration, interoperability, and lifecycle scalability, with integrated solutions gaining an advantage in large modernization and network expansion programs.

Railway Signaling Market, By Component

Software is projected to be the fastest-growing component during the forecast period, as rail operators shift toward data-driven traffic management, real-time decision support, and predictive asset monitoring. This creates a strong opportunity for signaling suppliers to expand beyond hardware into traffic optimization, analytics, digital twins, and software-as-a-service capabilities, while open interfaces and standardized data architectures increasingly determine scalability across multi-vendor networks.

Railway Signaling Market, By Technology

European Train Control System (ETCS) is projected to remain the largest technology segment during the forecast period, supported by its role in standardizing train protection and enabling interoperability across diverse rail networks. Its adoption creates sustained demand for ETCS onboard and trackside integration, legacy-system migration, and interoperable control architectures, particularly as infrastructure managers modernize existing networks. For signaling OEMs and Tier-1 suppliers, competitive opportunities increasingly center on retrofit capability, cross-system compatibility, and scalable ETCS platforms that reduce migration complexity and lifecycle costs.

Railway Signaling Market, By End-use

Mainline is expected to remain the leading end-use segment during the forecast period, supported by the need to optimize capacity across long-distance passenger and freight corridors while improving interoperability and safety. Urban networks will remain a high-value application for capacity-intensive and automation-oriented signaling, whereas freight corridors will increasingly require systems that support higher axle loads, longer trains, mixed-traffic operations, and cross-border interoperability. For signaling OEMs and Tier-1 suppliers, the key opportunity lies in developing segment-specific architectures and scalable control systems that address the distinct operational requirements of mainline, urban, and freight networks rather than relying on one-size-fits-all solutions.

REGION

Asia Pacific to Lead Railway Signaling Market During Forecast Period

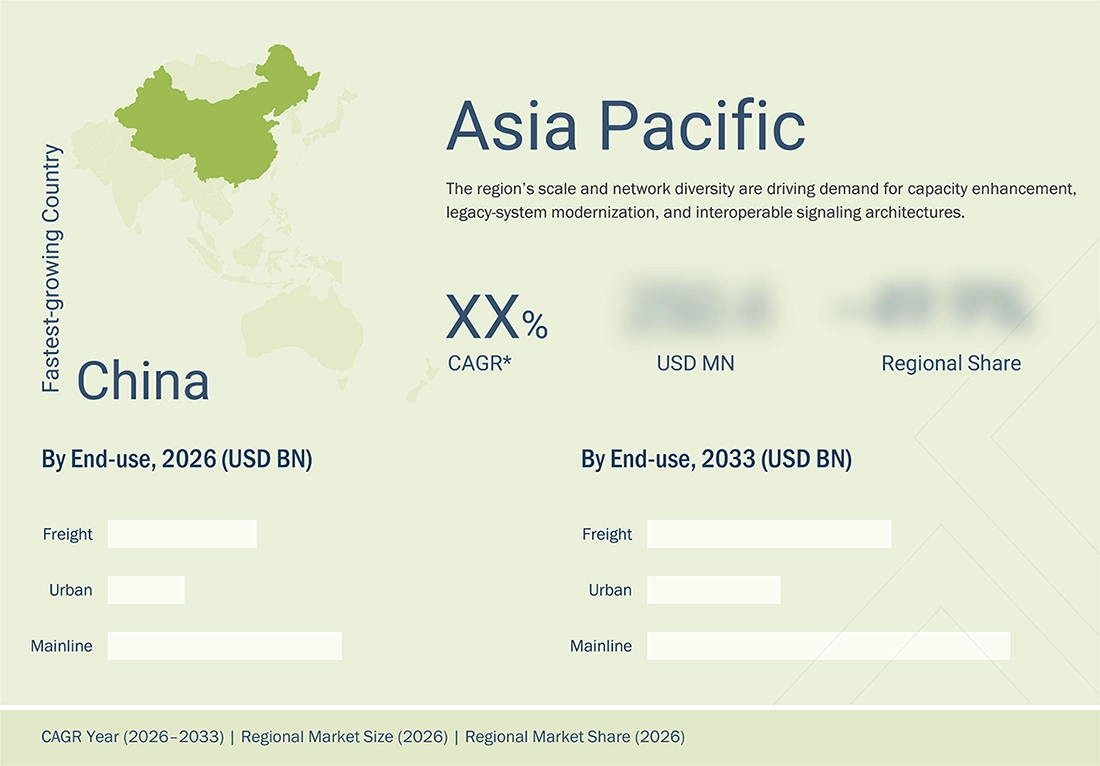
Asia Pacific is projected to remain the largest regional market for railway signaling during 2026–2033, underpinned by sustained investment in passenger, high-speed, urban, and freight rail infrastructure. The region’s scale and network diversity are driving demand for capacity enhancement, legacy-system modernization, and interoperable signaling architectures. For signaling OEMs and Tier 1 suppliers, the strongest opportunities lie in localized solutions, corridor-scale deployments, and scalable signaling platforms that can address diverse technical standards while supporting long-term network expansion and digitalization.

railway-signaling-market Region

RAILWAY SIGNALING MARKET: COMPANY EVALUATION MATRIX

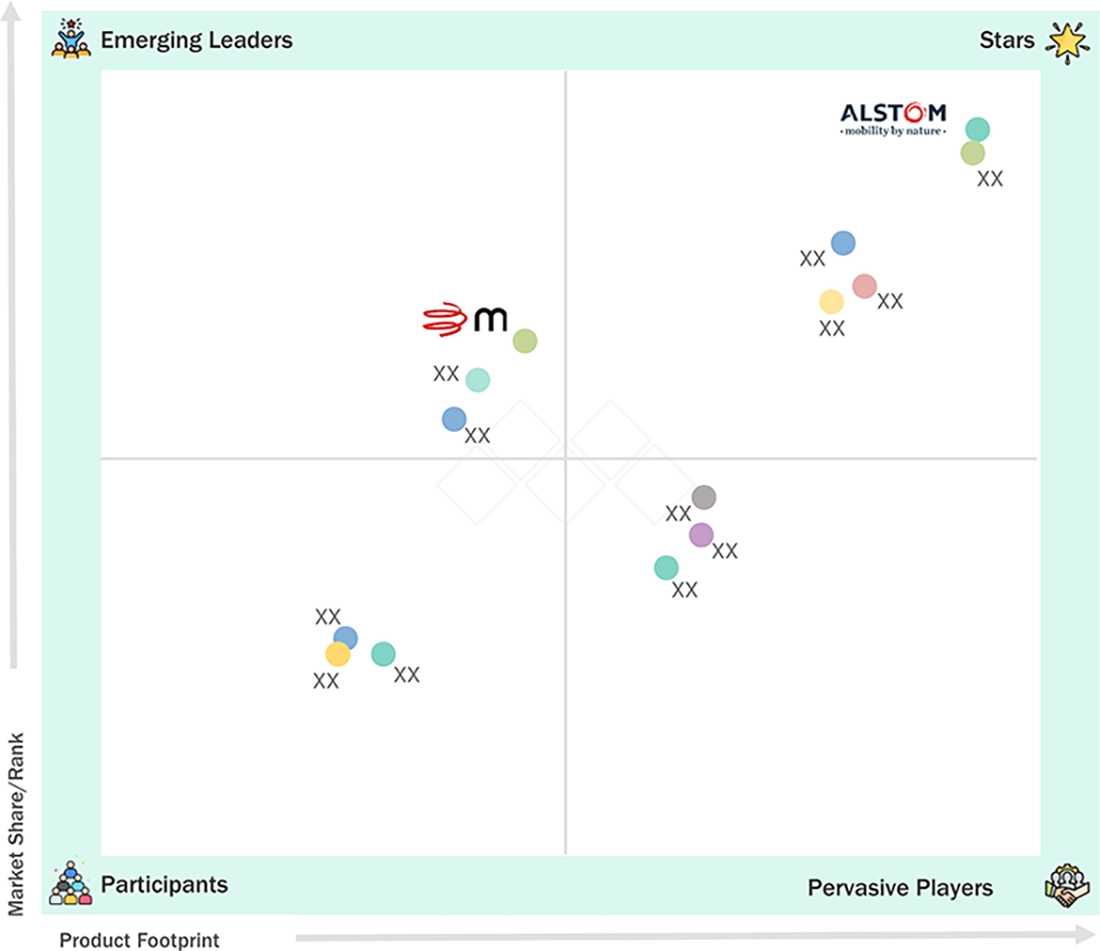
In the railway signaling market matrix, Alstom (Star) leads with a comprehensive portfolio spanning mainline, urban, freight, and digital signaling, supported by strong capabilities across ETCS, CBTC, interlocking, traffic management, and control systems. Its integrated signaling and digital rail ecosystem strengthens its position in large-scale network modernization and end-to-end system integration. MERMEC (Emerging Leader) is expanding its competitive position through a focused portfolio covering ETCS/ERTMS, radio block centers, interlocking, traffic control, lineside equipment, and diagnostic systems, enabling the company to address signaling modernization alongside railway monitoring and infrastructure intelligence. This positioning supports MERMEC’s progression toward the market leaders' quadrant by combining signaling expertise with measurement, diagnostics, and asset-monitoring capabilities, creating a differentiated proposition for integrated railway infrastructure projects.

railway-signaling-market Evaluation Metrics

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

KEY MARKET PLAYERS

MARKET SCOPE

REPORT METRIC DETAILS
Market Size in 2025 (Value) USD 21.10 BN
Market Size in 2026 (Value) USD 21.99 BN
Market Forecast in 2033 (Value) USD 32.60 BN
Growth Rate CAGR of 5.8% from 2026 to 2033
Years Considered 2022–2033
Base Year 2025
Forecast Period 2026–2033
Units Considered Value (USD BN/MN)
Report Coverage Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments Covered
  • TCMS Train Type:
    • Light Rail & Metros (DMU & EMU)
    • High-Speed Trains
    • Conventional Passenger Trains
    • Freight Trains
  • TCMS Offering:
    • Solutions (Hardware
    • Software)
    • Services (Consulting
    • Installation
    • Integration
    • Maintenance
    • Upgrades
    • Managed Services)
  • Component:
    • Hardware (Interlocking Systems
    • Track Circuits
    • Axle Counters
    • Point Machines
    • Signals
    • Balises
    • Train Detection Systems
    • Controllers
    • Communication Equipment
    • Onboard Equipment)
    • Software (Traffic Management Software
    • Control Center Software
    • Diagnostics Software)
  • Technology:
    • ABS
    • CBTC
    • ETCS
    • PTC
    • ATC
  • Infrastructure Foundations:
    • Electronic Interlocking
    • Digital Interlocking
  • End Use:
    • Mainline
    • Urban
    • Freight
  • Deployment:
    • Greenfield
    • Brownfield
  • Connectivity:
    • GSM-R
    • Wi-Fi
    • Tetra
    • Others
Regions Covered Asia Pacific, Europe, North America, Rest of the World

WHAT IS IN IT FOR YOU: RAILWAY SIGNALING MARKET REPORT CONTENT GUIDE

railway-signaling-market Content Guide

DELIVERED CUSTOMIZATIONS

We have successfully delivered the following deep-dive customizations:

CLIENT REQUEST CUSTOMIZATION DELIVERED VALUE ADDS
Global Railway Signaling OEM/Signaling Supplier (Europe) Competitive benchmarking of Alstom, Siemens Mobility, Hitachi Rail, Thales, Wabtec, and MERMEC across signaling technologies, regional presence, and solution portfolios Vendor positioning matrix, technology leadership assessment, regional opportunity mapping, and white-space analysis for expansion and partnership decisions
Railway Infrastructure Manager (Asia Pacific) Market sizing and demand analysis by technology (ETCS, CBTC, PTC, ATC, ABS), offering, deployment type, and end-use across mainline, urban, and freight networks Signaling modernization roadmap, technology-selection priorities, and corridor-level investment opportunity assessment aligned with capacity and interoperability requirements
Metro / Urban Rail Operator (Middle East & Africa) Assessment of signaling requirements for high-density metro networks, including CBTC, ATO, interlocking, train detection, and traffic management systems Headway and capacity-enhancement assessment, automation readiness evaluation, and brownfield migration strategy to minimize operational disruption
Rail Signaling Tier-1 Supplier (North America) Evaluation of demand for PTC, electronic interlocking, wayside systems, onboard signaling, communications, and centralized traffic management across passenger and freight applications Technology adoption roadmap, interoperability assessment, supplier ecosystem analysis, and market-entry priorities by application and region
Private Equity / Infrastructure Investor (Global) Identification and evaluation of high-growth signaling OEMs, software providers, rail technology specialists, and infrastructure-service companies Competitive attractiveness scoring, capability benchmarking, market-entry barriers, and investment opportunity assessment based on recurring service potential, installed base, and technology exposure

RECENT DEVELOPMENTS

  • July 2026 : Siemens Mobility secured three railway signaling modernization contracts in Romania covering approximately 560 km, 66 stations, 122 level crossings, and more than 2,000 signals, reinforcing the growing opportunity for integrated signaling and interlocking modernization across legacy mainline networks.
  • June 2026 : Alstom secured the first mainline ETCS contract under Queensland’s The Wave program, deploying ETCS Level 2 with integrated 5G connectivity. The development highlights the shift toward interoperable digital signaling and connectivity-enabled infrastructure in new and upgraded mainline corridors.
  • May 2026 : Siemens Mobility agreed to acquire key businesses of MERMEC, strengthening its signaling, diagnostics, telecommunications, and asset-intelligence capabilities. The transaction signals increasing industry consolidation around integrated signaling, infrastructure diagnostics, and data-driven rail solutions.
  • April 2026 : Siemens Mobility was selected to modernize New York City's Fulton-Liberty Lines with CBTC, covering 23 stations and 65 track kilometers, alongside a 25-year maintenance agreement. The project reinforces the commercial value of combining brownfield signaling modernization with long-term lifecycle services.
  • March 2026 : Siemens Mobility and Sonda won Mexico's first ETCS contract, covering more than 300 km and integrating ETCS Level 1, OCC, SCADA, and TPS.plan train-planning software. This demonstrates growing demand for bundled signaling and operational software rather than standalone train-control systems.


Table of Contents

checkmarkExclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.

TITLE
PAGE NO
1
INTRODUCTION


26
2
EXECUTIVE SUMMARY


34
3
PREMIUM INSIGHTS


39
4
MARKET OVERVIEW
Unlock rail efficiency with AI-driven automation and 5G communication advancements.


43
 
4.1
INTRODUCTION


4.2
MARKET DYNAMICS


4.2.1
DRIVERS


4.2.1.1
NETWORK CAPACITY OPTIMIZATION THROUGH MOVING BLOCK SIGNALING AND TRAFFIC DIGITALIZATION


4.2.1.2
INCREASING AUTOMATION ACROSS METRO AND MAINLINE RAIL NETWORKS


4.2.1.3
TRANSITION TOWARD INTELLIGENT, SOFTWARE-DEFINED RAIL OPERATIONS


4.2.2
RESTRAINTS


4.2.2.1
LEGACY SIGNALING MIGRATION CREATES OPPORTUNITY COSTS FOR OPERATORS


4.2.3
OPPORTUNITIES


4.2.3.1
TRANSITION FROM GSM-R TO FRMCS AND 5G-BASED RAILWAY COMMUNICATIONS


4.2.3.2
AI-DRIVEN TRAFFIC ORCHESTRATION ENABLES AUTONOMOUS FREIGHT RAIL OPERATIONS


4.2.4
CHALLENGES


4.2.4.1
INTEROPERABILITY REQUIREMENTS REDUCE PRODUCT DIFFERENTIATION


4.3
UNMET NEEDS AND WHITE SPACES


4.3.1
UNMET NEEDS IN RAILWAY SIGNALING MARKET


4.3.2
WHITE SPACE OPPORTUNITIES


4.4
INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES


4.4.1
INTERCONNECTED MARKETS


4.4.2
CROSS-SECTOR OPPORTUNITIES


4.5
STRATEGIC MOVES BY TIER-1/2/3 PLAYERS


5
INDUSTRY TRENDS
Explore transformative trends reshaping global rail industry through technology, trade, and strategic investments.


55
 
5.1
MACROECONOMIC OUTLOOK


5.1.1
GDP TRENDS AND FORECAST


5.1.2
TRENDS IN GLOBAL RAILWAY SIGNALING MARKET


5.1.3
TRENDS IN GLOBAL ROLLING STOCK INDUSTRY


5.2
ECOSYSTEM ANALYSIS


5.2.1
RAIL INFRASTRUCTURE MANAGERS


5.2.2
RAILWAY SIGNALING PROVIDERS


5.2.3
COMMUNICATION, CLOUD, & AI TECHNOLOGY PROVIDERS


5.2.4
CYBERSECURITY & DIGITAL ASSET MANAGEMENT PROVIDERS


5.2.5
RAIL OPERATORS


5.3
SUPPLY CHAIN ANALYSIS


5.4
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS


5.5
INVESTMENT AND FUNDING SCENARIO


5.6
TRADE ANALYSIS


5.6.1
IMPORT SCENARIO (HS CODE 8530)


5.6.2
EXPORT SCENARIO (HS CODE 8530)


5.7
KEY CONFERENCES AND EVENTS, 2026–2027


5.8
CASE STUDY ANALYSIS


5.8.1
DIGITAL SIGNALING FOR MUMBAI-AHMEDABAD HIGH-SPEED RAIL


5.8.2
DIGITAL RAIL TRANSFORMATION FOR WAVE PROGRAM


5.8.3
POSITIVE TRAIN CONTROL MODERNIZATION FOR VALE FREIGHT NETWORK


5.9
SUPPLIER ANALYSIS


5.9.1
SIEMENS MOBILITY


5.9.2
ALSTOM


5.9.3
HITACHI RAIL


5.9.4
WABTEC CORPORATION


5.10
EUROPE-INDIA TRADE DEALS: IMPACT ANALYSIS


5.10.1
INTRODUCTION


5.10.2
EU TARIFFS


5.10.3
IMPORTS TO INDIA


5.10.4
EXPORTS FROM INDIA


5.11
US-IRAN IMPACT ON RAILWAY SIGNALING MARKET


5.11.1
INTRODUCTION


5.11.2
DIRECT IMPACT


5.11.3
INDIRECT IMPACT


5.11.4
RISE IN FUEL PRICES


6
TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
Revolutionize rail systems with AI-driven traffic management and cloud-native signaling innovations.


74
 
6.1
KEY EMERGING TECHNOLOGIES


6.1.1
AI-BASED TRAFFIC MANAGEMENT & AUTONOMOUS DISPATCHING


6.1.2
CLOUD-NATIVE SIGNALING MANAGEMENT PLATFORMS


6.1.3
DIGITAL TWIN OF RAILWAY SIGNALING SYSTEMS


6.2
COMPLEMENTARY TECHNOLOGIES


6.2.1
FIBER OPTIC RAILWAY COMMUNICATION NETWORKS


6.2.2
ETCS LEVEL 3


6.3
ADJACENT TECHNOLOGIES


6.3.1
SMART RAIL INFRASTRUCTURE PLATFORMS


6.3.2
INTERNET OF THINGS (IOT) FOR RAIL ASSETS


6.4
PATENT ANALYSIS


6.5
RAILWAY DIGITALIZATION ROADMAP


6.5.1
DIGITAL RAILWAY


6.5.2
TRAFFIC MANAGEMENT SYSTEMS


6.5.3
AI-DISPATCHING


6.5.4
CLOUD-BASED SIGNALING


6.5.5
DIGITAL TWINS


6.5.6
EDGE COMPUTING


6.5.7
PREDICTIVE OPERATIONS


6.6
OEM TECHNOLOGY BENCHMARKING


6.6.1
ETCS ADOPTION


6.6.2
CBTC MIGRATION


6.6.3
POSITIVE TRAIN CONTROL


6.6.4
FRMCS READINESS


6.6.5
MULTI-VENDOR INTEROPERABILITY


6.7
FUTURE COMMUNICATION TECHNOLOGIES


6.7.1
GSM-R


6.7.2
FRMCS (5G)


6.7.3
PRIVATE LTE


6.7.4
SATELLITE COMMUNICATION


6.7.5
EDGE COMPUTING


6.8
IMPACT OF AI ON RAILWAY SIGNALING MARKET


6.8.1
TOP USE CASES AND MARKET POTENTIAL


6.8.1.1
AI-DRIVEN NETWORK OPTIMIZATION AND AUTONOMOUS TRAFFIC MANAGEMENT


6.8.1.2
INTELLIGENT ASSET MANAGEMENT AND PREDICTIVE INFRASTRUCTURE MAINTENANCE


6.8.1.3
DIGITAL VALIDATION, AI SIMULATION, AND SOFTWARE-DEFINED SIGNALING DEPLOYMENT


6.8.2
BEST PRACTICES FOLLOWED BY MANUFACTURERS IN RAILWAY SIGNALING MARKET


6.8.2.1
SAFETY ASSURANCE THROUGH CONTROLLED AI DEPLOYMENT


6.8.2.2
DATA QUALITY AND MODEL GOVERNANCE AS PROCUREMENT CRITERION


6.8.2.3
CYBERSECURITY BUILT AROUND AI AND DATA LIFECYCLE


6.8.2.4
HYBRID COMPUTING BASED ON FUNCTION CRITICALITY


6.8.2.5
AI MODEL VALIDATION USING OPERATIONAL EVIDENCE


6.8.3
INTERCONNECTED ECOSYSTEM AND IMPACT OF MARKET PLAYERS


6.8.4
CLIENTS' READINESS TO ADOPT AI IN RAILWAY SIGNALING MARKET


7
REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
Explore global regulatory impacts on sustainability with insights into regional compliance and eco-initiatives.


91
 
7.1
REGIONAL REGULATIONS AND COMPLIANCE


7.1.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


7.1.1.1
ASIA PACIFIC


7.1.1.2
EUROPE


7.1.1.3
NORTH AMERICA


7.1.1.4
REST OF THE WORLD


7.2
INDUSTRY STANDARDS


7.2.1
ASIA PACIFIC


7.2.2
EUROPE


7.2.3
NORTH AMERICA


7.2.4
REST OF THE WORLD


7.3
SUSTAINABILITY INITIATIVES


7.3.1
CARBON IMPACT AND ECO-APPLICATIONS


7.3.2
LIFECYCLE VS. OPERATION


7.3.3
ECO-APPLICATIONS


7.4
IMPACT OF REGULATORY POLICIES ON SUSTAINABILITY INITIATIVES


7.4.1
EUROPEAN UNION


7.4.2
US


7.4.3
CHINA


7.4.4
INDIA


8
CUSTOMER LANDSCAPE & BUYER BEHAVIOR
Identify critical unmet needs and stakeholder influences shaping train industry purchasing decisions.


100
 
8.1
DECISION-MAKING PROCESS


8.2
KEY STAKEHOLDERS AND BUYING CRITERIA


8.2.1
KEY STAKEHOLDERS IN BUYING PROCESS


8.2.2
BUYING CRITERIA


8.3
ADOPTION BARRIERS AND INTERNAL CHALLENGES


8.4
UNMET NEEDS OF VARIOUS END-USE INDUSTRIES


9
FUTURE REVENUE MODELS FOR RAILWAY SIGNALING INDUSTRY
Explore innovative revenue models transforming railway signaling with service-based and predictive maintenance contracts.


106
 
9.1
SIGNALING AS A SERVICE


9.2
SOFTWARE LICENSING


9.3
ANNUAL MAINTENANCE CONTRACTS


9.4
PREDICTIVE MAINTENANCE CONTRACTS


10
RAILWAY SIGNALING MARKET, BY TCMS TRAIN TYPE
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million | 11 Data Tables


112
 
10.1
INTRODUCTION


10.2
LIGHT RAIL & METROS (EMU & DMU)


10.2.1
EXPANDING URBAN METRO NETWORKS AND CAPACITY ENHANCEMENT TO DRIVE DEMAND


10.3
HIGH-SPEED TRAINS


10.3.1
EXPANDING HIGH-SPEED RAIL CORRIDORS AND ETCS DEPLOYMENT TO DRIVE SIGNALING DEMAND


10.4
CONVENTIONAL PASSENGER TRAINS


10.4.1
MODERNIZATION OF CONVENTIONAL RAIL NETWORKS AND DIGITAL INTERLOCKING DEPLOYMENT TO DRIVE SIGNALING DEMAND


10.5
FREIGHT TRAINS


10.5.1
INCREASING FREIGHT CORRIDOR DIGITALIZATION AND HEAVY-HAUL NETWORK MODERNIZATION TO DRIVE MARKET


10.6
KEY PRIMARY INSIGHTS


11
RAILWAY SIGNALING MARKET, BY TCMS OFFERING
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million | 22 Data Tables


121
 
11.1
INTRODUCTION


11.2
SOLUTIONS


11.2.1
HARDWARE


11.2.1.1
RAILWAY DIGITALIZATION AND HIGHER AUTOMATION TO DRIVE MARKET


11.2.2
SOFTWARE


11.2.2.1
AI-DRIVEN TRAFFIC MANAGEMENT AND PREDICTIVE OPERATIONS TO DRIVE MARKET


11.3
SERVICES


11.3.1
CONSULTING


11.3.1.1
STRATEGIC CONSULTING AND DIGITAL MODERNIZATION PLANNING TO DRIVE MARKET


11.3.2
INSTALLATION


11.3.2.1
PHASED DEPLOYMENT AND STANDARDIZED INSTALLATION TO DRIVE MARKET


11.3.3
INTEGRATION


11.3.3.1
AI, CLOUD-BASED OPERATIONS, AND DIGITAL TWINS TO PROPEL MARKET


11.3.4
MAINTENANCE


11.3.4.1
CONDITION-BASED AND PREDICTIVE MAINTENANCE TO SUPPORT MARKET GROWTH


11.3.5
UPGRADES


11.3.5.1
PHASED SIGNALING MODERNIZATION AND DIGITAL TECHNOLOGY READINESS TO DRIVE MARKET


11.3.6
MANAGED


11.3.6.1
REMOTE MONITORING AND AI-ENABLED ASSET MANAGEMENT TO DRIVE MARKET


11.4
KEY PRIMARY INSIGHTS


12
RAILWAY SIGNALING MARKET, BY COMPONENT
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million | 32 Data Tables


136
 
12.1
INTRODUCTION


12.2
HARDWARE


12.2.1
INTERLOCKING SYSTEMS


12.2.1.1
DIGITAL INTERLOCKING MIGRATION AND NETWORK CAPACITY EXPANSION TO PROPEL MARKET


12.2.2
TRACK CIRCUITS


12.2.2.1
DIGITAL TRACK CIRCUIT MODERNIZATION AND ADVANCED MONITORING TO DRIVE MARKET


12.2.3
AXLE COUNTERS


12.2.3.1
DIGITAL SIGNALING MIGRATION AND COMPLEX TRACK DEPLOYMENT TO SUPPORT MARKET GROWTH


12.2.4
POINT MACHINES


12.2.4.1
INTELLIGENT POINT MACHINE DEPLOYMENT AND CONDITION MONITORING TO DRIVE MARKET


12.2.5
SIGNALS


12.2.5.1
LED SIGNAL MODERNIZATION AND INTELLIGENT SIGNALING INTEGRATION TO PROPEL MARKET


12.2.6
BALISES


12.2.6.1
ETCS DEPLOYMENT AND AUTOMATED TRAIN PROTECTION TO DRIVE MARKET


12.2.7
TRAIN DETECTION SYSTEMS


12.2.7.1
MULTI-TECHNOLOGY TRAIN DETECTION AND CENTRALIZED MONITORING TO SUPPORT MARKET GROWTH


12.2.8
CONTROLLERS


12.2.8.1
HIGH-PERFORMANCE CONTROLLERS AND DISTRIBUTED SIGNALING ARCHITECTURE TO DRIVE MARKET


12.2.9
COMMUNICATION EQUIPMENT


12.2.9.1
FRMCS AND 5G RAILWAY COMMUNICATIONS TO DRIVE MARKET


12.2.10
ONBOARD EQUIPMENT


12.2.10.1
TRAIN AUTOMATION AND INTEROPERABLE FLEET MODERNIZATION TO DRIVE MARKET


12.3
SOFTWARE


12.3.1
TRAFFIC MANAGEMENT SOFTWARE


12.3.1.1
AI-DRIVEN TRAFFIC OPTIMIZATION AND PREDICTIVE SCHEDULING TO DRIVE MARKET


12.3.2
CONTROL CENTER SOFTWARE


12.3.2.1
REAL-TIME OPERATIONAL CONTROL AND INTEGRATED AUTOMATION TO DRIVE MARKET


12.3.3
DIAGNOSTICS SOFTWARE


12.3.3.1
AI-BASED FAULT PREDICTION AND CONDITION MONITORING TO DRIVE MARKET


12.4
KEY PRIMARY INSIGHTS


13
RAILWAY SIGNALING MARKET, BY TECHNOLOGY
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million | 13 Data Tables


156
 
13.1
INTRODUCTION


13.2
AUTOMATIC BLOCK SIGNALING


13.2.1
RISING CONVENTIONAL RAIL MODERNIZATION SUSTAINS DEMAND FOR AUTOMATIC BLOCK SIGNALING


13.3
COMMUNICATIONS-BASED TRAIN CONTROL


13.3.1
GROWING URBAN MOBILITY INVESTMENTS ACCELERATE SHIFT TOWARD ADVANCED CBTC SYSTEMS


13.4
EUROPEAN TRAIN CONTROL SYSTEM


13.4.1
ETCS STANDARDIZATION ACROSS INTERNATIONAL RAIL CORRIDORS TO ACCELERATE INTEROPERABLE SIGNALING DEPLOYMENT


13.5
POSITIVE TRAIN CONTROL


13.5.1
NEXT-GENERATION PTC SOLUTIONS ENABLE SAFER AND HIGH-CAPACITY RAIL OPERATIONS


13.6
AUTOMATIC TRAIN CONTROL


13.6.1
INTELLIGENT TRAIN AUTOMATION ADVANCES STRENGTHEN EVOLUTION OF ATC SYSTEMS


13.7
KEY PRIMARY INSIGHTS


14
RAILWAY SIGNALING MARKET, BY INFRASTRUCTURE FOUNDATION
| 2 Data Tables


167
 
14.1
INTRODUCTION


14.2
ELECTRONIC INTERLOCKING


14.3
DIGITAL INTERLOCKING


15
RAILWAY SIGNALING MARKET, BY END USE
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million | 8 Data Tables


170
 
15.1
INTRODUCTION


15.2
MAINLINE


15.2.1
ACCELERATING MAINLINE DIGITALIZATION TO EXPAND HIGH-CAPACITY SIGNALING DEPLOYMENT


15.3
URBAN


15.3.1
ACCELERATING URBAN RAIL AUTOMATION TO DRIVE NEXT-GENERATION SIGNALING DEMAND


15.4
FREIGHT


15.4.1
INTEGRATED FREIGHT CONTROL PLATFORMS TO DRIVE AUTONOMOUS HEAVY HAUL SIGNALING SOLUTIONS


15.5
PRIMARY INSIGHTS


16
RAILWAY SIGNALING MARKET, BY DEPLOYMENT
| 2 Data Tables


177
 
16.1
INTRODUCTION


16.2
GREENFIELD


16.3
BROWNFIELD


17
RAILWAY SIGNALING MARKET, BY CONNECTIVITY
Market Size & Growth Rate Forecast Analysis


181
 
17.1
INTRODUCTION


17.2
GSM-R


17.3
WI-FI


17.4
TETRA


17.5
OTHERS


18
RAILWAY SIGNALING MARKET, BY REGION
Comprehensive coverage of 5 Regions with country-level deep-dive of 14 Countries | 38 Data Tables.


183
 
18.1
INTRODUCTION


18.2
ASIA PACIFIC


18.2.1
CHINA


18.2.1.1
END-TO-END DOMESTIC RAIL TECHNOLOGY INTEGRATION TO ACCELERATE INTELLIGENT SIGNALING DEPLOYMENT


18.2.2
JAPAN


18.2.2.1
MODULAR SIGNALING ARCHITECTURE TO ACCELERATE LOW-DISRUPTION RAILWAY MODERNIZATION


18.2.3
SOUTH KOREA


18.2.3.1
URBAN RAILWAY OPTIMIZATION INITIATIVES TO DRIVE DEMAND FOR ADVANCED SIGNALING SYSTEMS


18.2.4
INDIA


18.2.4.1
EVOLVING RAILWAY PROCUREMENT STRATEGIES TO STRENGTHEN SIGNALING SOLUTION ADOPTION


18.3
EUROPE


18.3.1
GERMANY


18.3.1.1
EXISTING NETWORK CAPACITY OPTIMIZATION TO ACCELERATE ADVANCED SIGNALING DEPLOYMENT


18.3.2
FRANCE


18.3.2.1
INTEGRATED RAILWAY SYSTEM DEVELOPMENT TO STRENGTHEN SIGNALING COMPETITIVENESS


18.3.3
UK


18.3.3.1
PHASED DEPLOYMENT OF ADVANCED TRAIN CONTROL TECHNOLOGIES TO SUPPORT RAILWAY SIGNALING DEMAND


18.3.4
ITALY


18.3.4.1
GOVERNMENT SUPPORT FOR RAILWAY MODERNIZATION TO DRIVE MARKET


18.3.5
SPAIN


18.3.5.1
EXPANDING ADVANCED SIGNALING PROGRAMS TO STRENGTHEN RAILWAY CAPACITY AND INTEROPERABILITY


18.4
NORTH AMERICA


18.4.1
US


18.4.1.1
LIFECYCLE MODERNIZATION OF TRAIN CONTROL SYSTEMS TO DRIVE MARKET


18.4.2
CANADA


18.4.2.1
DEVELOPMENT OF HIGH-SPEED RAIL CORRIDORS TO CREATE NEW OPPORTUNITIES FOR INTEGRATED SIGNALING SYSTEMS


18.4.3
MEXICO


18.4.3.1
EXPANSION OF NATIONAL PASSENGER RAIL CORRIDORS TO DRIVE DEMAND FOR ADVANCED SIGNALING SYSTEMS


18.5
REST OF THE WORLD


18.5.1
SOUTH AFRICA


18.5.1.1
RAILWAY INFRASTRUCTURE REFORMS TO ENABLE PRIVATE OPERATOR PARTICIPATION AND DRIVE SIGNALING MODERNIZATION


18.5.2
BRAZIL


18.5.2.1
PRIVATE RAILWAY INVESTMENTS TO STRENGTHEN DEMAND FOR MODERN SIGNALING INFRASTRUCTURE


19
COMPETITIVE LANDSCAPE
Discover key players' strategies and market dominance in autonomous train technology by 2025.


211
 
19.1
OVERVIEW


19.2
KEY PLAYER STRATEGIES/RIGHT TO WIN, JANUARY 2022–AUGUST 2026


19.3
MARKET SHARE ANALYSIS, 2025


19.4
REVENUE ANALYSIS, 2021–2025


19.5
AUTONOMOUS TRAIN READINESS INDEX


19.5.1
GOA0


19.5.2
GOA1


19.5.3
GOA2


19.5.4
GOA3


19.5.5
GOA4


19.6
BRAND COMPARISON


19.7
COMPANY VALUATION AND FINANCIAL METRICS


19.8
COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025


19.8.1
STARS


19.8.2
EMERGING LEADERS


19.8.3
PERVASIVE PLAYERS


19.8.4
PARTICIPANTS


19.8.5
COMPANY FOOTPRINT: KEY PLAYERS, 2025


19.8.5.1
COMPANY FOOTPRINT


19.8.5.2
REGION FOOTPRINT


19.8.5.3
TECHNOLOGY FOOTPRINT


19.8.5.4
COMPONENT FOOTPRINT


19.9
COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025


19.9.1
PROGRESSIVE COMPANIES


19.9.2
RESPONSIVE COMPANIES


19.9.3
DYNAMIC COMPANIES


19.9.4
STARTING BLOCKS


19.9.5
COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025


19.9.5.1
DETAILED LIST OF STARTUPS/SMES


19.9.5.2
COMPETITIVE BENCHMARKING OF STARTUPS/SMES


19.10
COMPETITIVE SCENARIO


19.10.1
PRODUCT LAUNCHES


19.10.2
DEALS


19.10.3
EXPANSIONS


19.10.4
OTHER DEVELOPMENTS


20
COMPANY PROFILES
In-depth Company Profiles of Leading Market Players with detailed Business Overview, Product and Service Portfolio, Recent Developments, and Unique Analyst Perspective (MnM View)


233
 
20.1
KEY PLAYERS


20.1.1
ALSTOM SA


20.1.1.1
BUSINESS OVERVIEW


20.1.1.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


20.1.1.3
RECENT DEVELOPMENTS


20.1.1.3.1
DEALS


20.1.1.4
MNM VIEW


20.1.1.4.1
KEY STRENGTHS


20.1.1.4.2
STRATEGIC CHOICES


20.1.1.4.3
WEAKNESSES AND COMPETITIVE THREATS


20.1.2
SIEMENS MOBILITY


20.1.3
HITACHI RAIL


20.1.4
CHINA RAILWAY SIGNAL & COMMUNICATION CO., LTD. (CRSC)


20.1.5
WABTEC CORPORATION


20.1.6
PROGRESS RAIL


20.1.7
KNORR-BREMSE GLOBAL RAIL HOLDING GMBH


20.1.8
CAF S.A.


20.1.9
NIPPON SIGNAL CO., LTD.


20.1.10
KYOSAN ELECTRIC MFG. CO., LTD.


20.1.11
MER MEC S.P.A


20.1.12
MITSUBISHI ELECTRIC


20.2
OTHER PLAYERS


20.2.1
PINTSCH GMBH


20.2.2
SCHEIDT & BACHMANN GMBH


20.2.3
TRAFFIC CONTROL TECHNOLOGY CO., LTD.


20.2.4
AŽD PRAHA S.R.O


20.2.5
STADLER INC.


20.2.6
HIMA


20.2.7
TOSHIBA


20.2.8
UNITTEC


20.2.9
RAILTEL


20.2.10
CLEARSY


20.2.11
PILZ


21
RESEARCH METHODOLOGY


289
 
21.1
RESEARCH DATA


21.1.1
SECONDARY DATA


21.1.1.1
LIST OF SECONDARY SOURCES


21.1.1.2
KEY DATA FROM SECONDARY SOURCES


21.1.2
PRIMARY DATA


21.1.2.1
PRIMARY INTERVIEWS: DEMAND AND SUPPLY SIDES


21.1.2.2
BREAKDOWN OF PRIMARY INTERVIEWS


21.1.2.3
PRIMARY PARTICIPANTS


21.1.2.4
OBJECTIVES OF PRIMARY RESEARCH


21.2
MARKET SIZE ESTIMATION


21.2.1
TOP-DOWN APPROACH


21.3
DATA TRIANGULATION


21.4
FACTOR ANALYSIS


21.5
RESEARCH ASSUMPTIONS


21.6
RESEARCH LIMITATIONS


21.7
RISK ASSESSMENT


22
APPENDIX


301
 
22.1
DISCUSSION GUIDE


22.2
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL


22.3
CUSTOMIZATION OPTIONS


22.3.1
COMPANY PROFILE


22.3.2
RAILWAY SIGNALING MARKET, BY TCMS TRAIN TYPE, AT COUNTRY LEVEL


22.3.3
RAILWAY SIGNALING MARKET, BY END-USE, AT COUNTRY LEVEL


22.4
RELATED REPORTS


22.5
AUTHOR DETAILS


LIST OF TABLES


TABLE 1
RAILWAY SIGNALING MARKET DEFINITION, BY TCMS TRAIN TYPE


TABLE 2
RAILWAY SIGNALING MARKET DEFINITION, BY TCMS OFFERING


TABLE 3
RAILWAY SIGNALING MARKET DEFINITION, BY COMPONENT


TABLE 4
RAILWAY SIGNALING MARKET DEFINITION, BY TECHNOLOGY


TABLE 5
RAILWAY SIGNALING MARKET DEFINITION, BY INFRASTRUCTURE FOUNDATION


TABLE 6
RAILWAY SIGNALING MARKET DEFINITION, BY END USE


TABLE 7
RAILWAY SIGNALING MARKET DEFINITION, BY DEPLOYMENT


TABLE 8
RAILWAY SIGNALING MARKET DEFINITION, BY CONNECTIVITY


TABLE 9
CURRENCY EXCHANGE RATES (PER USD)


TABLE 10
KEY OEM STRATEGIES FOR NETWORK CAPACITY OPTIMIZATION


TABLE 11
RAILWAY TECHNOLOGY PROVIDER STRATEGIES FOR FRMCS TRANSITION


TABLE 12
IMPACT OF MARKET DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES


TABLE 13
STRATEGIC MOVES BY TIER 1/2/3 PLAYERS


TABLE 14
GDP PERCENTAGE CHANGE, BY COUNTRY, 2021–2030


TABLE 15
ROLE OF COMPANIES IN ECOSYSTEM


TABLE 16
IMPORT DATA FOR HS CODE 8530-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025 (USD BILLION)


TABLE 17
EXPORT DATA FOR HS CODE 8530-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025 (USD BILLION)


TABLE 18
KEY CONFERENCES AND EVENTS, 2026–2027


TABLE 19
SIEMENS MOBILITY: SUPPLIER ANALYSIS


TABLE 20
ALSTOM: SUPPLIER ANALYSIS


TABLE 21
HITACHI RAIL: SUPPLIER ANALYSIS


TABLE 22
WABTEC CORPORATION: SUPPLIER ANALYSIS


TABLE 23
IMPORT TARIFFS ON RAILWAY SIGNALING COMPONENTS AND ELECTRONIC SYSTEMS IN INDIA


TABLE 24
IMPACT OF TRADE LIBERALIZATION ON RAILWAY SIGNALING COMPONENT IMPORTS INTO INDIA


TABLE 25
IMPACT OF TRADE LIBERALIZATION ON RAILWAY SIGNALING COMPONENT EXPORTS FROM INDIA


TABLE 26
KEY PATENTS, MARCH 2022–JUNE 2026


TABLE 27
ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 28
EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 29
NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 30
REST OF THE WORLD: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 31
ASIA PACIFIC: INDUSTRY STANDARDS FOR RAILWAY SIGNALING


TABLE 32
EUROPE: INDUSTRY STANDARDS FOR RAILWAY SIGNALING


TABLE 33
NORTH AMERICA: INDUSTRY STANDARDS FOR RAILWAY SIGNALING


TABLE 34
REST OF THE WORLD: INDUSTRY STANDARDS FOR RAILWAY SIGNALING


TABLE 35
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY TRAIN TYPE


TABLE 36
KEY BUYING CRITERIA, BY TRAIN TYPE


TABLE 37
UNMET NEEDS IN RAILWAY SIGNALING MARKET, BY END-USE INDUSTRY


TABLE 38
COMMERCIAL REVENUE MODELS IN RAILWAY SIGNALING


TABLE 39
RAILWAY SIGNALING MARKET, BY TCMS TRAIN TYPE, 2022–2025 (USD MILLION)


TABLE 40
RAILWAY SIGNALING MARKET, BY TCMS TRAIN TYPE, 2026–2033 (USD MILLION)


TABLE 41
RAILWAY SIGNALING SOLUTION OFFERINGS BY KEY PLAYERS


TABLE 42
LIGHT-RAIL & METROS (EMU & DMU): RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 43
LIGHT-RAIL & METROS (EMU & DMU): RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 44
HIGH-SPEED TRAINS: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 45
HIGH-SPEED TRAINS: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 46
CONVENTIONAL PASSENGER TRAINS: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 47
CONVENTIONAL PASSENGER TRAINS: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 48
FREIGHT TRAINS: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 49
FREIGHT TRAINS: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 50
RAILWAY SIGNALING MARKET, BY TCMS OFFERING, 2022–2025 (USD MILLION)


TABLE 51
RAILWAY SIGNALING MARKET, BY TCMS OFFERING, 2026–2033 (USD MILLION)


TABLE 52
RAILWAY SIGNALING MARKET, BY SOLUTION, 2022–2025 (USD MILLION)


TABLE 53
RAILWAY SIGNALING MARKET, BY SOLUTION, 2026–2033 (USD MILLION)


TABLE 54
HARDWARE: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 55
HARDWARE: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 56
SOFTWARE: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 57
SOFTWARE: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 58
RAILWAY SIGNALING MARKET, BY SERVICE, 2022–2025 (USD MILLION)


TABLE 59
RAILWAY SIGNALING MARKET, BY SERVICE, 2026–2033 (USD MILLION)


TABLE 60
CONSULTING: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 61
CONSULTING: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 62
INSTALLATION: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 63
INSTALLATION: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 64
INTEGRATION: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 65
INTEGRATION: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 66
MAINTENANCE: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 67
MAINTENANCE: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 68
UPGRADES: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 69
UPGRADES: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 70
MANAGED: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 71
MANAGED: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 72
RAILWAY SIGNALING MARKET, BY COMPONENT, 2022–2025 (USD MILLION)


TABLE 73
RAILWAY SIGNALING MARKET, BY COMPONENT, 2026–2033 (USD MILLION)


TABLE 74
RAILWAY SIGNALING MARKET, BY HARDWARE TYPE, 2022–2025 (USD MILLION)


TABLE 75
RAILWAY SIGNALING MARKET, BY HARDWARE TYPE, 2026–2033 (USD MILLION)


TABLE 76
INTERLOCKING SYSTEMS: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 77
INTERLOCKING SYSTEMS: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 78
TRACK CIRCUITS: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 79
TRACK CIRCUITS: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 80
AXLE COUNTERS: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 81
AXLE COUNTERS: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 82
POINT MACHINES: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 83
POINT MACHINES: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 84
SIGNALS: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 85
SIGNALS: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 86
BALISES: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 87
BALISES: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 88
TRAIN DETECTION SYSTEMS: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 89
TRAIN DETECTION SYSTEMS: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 90
CONTROLLERS: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 91
CONTROLLERS: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 92
COMMUNICATION EQUIPMENT: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 93
COMMUNICATION EQUIPMENT: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 94
ONBOARD EQUIPMENT: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 95
ONBOARD EQUIPMENT: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 96
RAILWAY SIGNALING MARKET, BY SOFTWARE TYPE, 2022–2025 (USD MILLION)


TABLE 97
RAILWAY SIGNALING MARKET, BY SOFTWARE TYPE, 2026–2033 (USD MILLION)


TABLE 98
TRAFFIC MANAGEMENT SOFTWARE: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 99
TRAFFIC MANAGEMENT SOFTWARE: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 100
CONTROL CENTER SOFTWARE: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 101
CONTROL CENTER SOFTWARE: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 102
DIAGNOSTICS SOFTWARE: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 103
DIAGNOSTICS SOFTWARE: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 104
RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 105
RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2026–2033 (USD MILLION)


TABLE 106
RAILWAY SIGNALING TECHNOLOGY COMPARISON, BY KEY PLAYER


TABLE 107
AUTOMATIC BLOCK SIGNALING: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 108
AUTOMATIC BLOCK SIGNALING: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 109
COMMUNICATIONS-BASED TRAIN CONTROL: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 110
COMMUNICATIONS-BASED TRAIN CONTROL: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 111
EUROPEAN TRAIN CONTROL SYSTEM: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 112
EUROPEAN TRAIN CONTROL SYSTEM: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 113
POSITIVE TRAIN CONTROL: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 114
POSITIVE TRAIN CONTROL: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 115
AUTOMATIC TRAIN CONTROL: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 116
AUTOMATIC TRAIN CONTROL: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 117
INVESTMENT PRIORITIES DRIVING ELECTRONIC INTERLOCKING


TABLE 118
DIGITAL INTERLOCKING: ENABLEMENT OF NEXT-GENERATION RAILWAY OPERATIONS


TABLE 119
RAILWAY SIGNALING MARKET, BY END USE, 2022–2025 (USD MILLION)


TABLE 120
RAILWAY SIGNALING MARKET, BY END USE, 2026–2033 (USD MILLION)


TABLE 121
MAINLINE: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 122
MAINLINE: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 123
URBAN: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 124
URBAN: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 125
FREIGHT: RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 126
FREIGHT: RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 127
GREENFIELD RAILWAY SIGNALING PROJECTS, BY COUNTRY


TABLE 128
BROWNFIELD RAILWAY SIGNALING PROJECTS, BY COUNTRY


TABLE 129
RAILWAY SIGNALING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 130
RAILWAY SIGNALING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 131
ASIA PACIFIC: RAILWAY SIGNALING MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 132
ASIA PACIFIC: RAILWAY SIGNALING MARKET, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 133
CHINA: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 134
CHINA: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2026–2033 (USD MILLION)


TABLE 135
JAPAN: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 136
JAPAN: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2026–2033 (USD MILLION)


TABLE 137
SOUTH KOREA: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 138
SOUTH KOREA: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2026–2033 (USD MILLION)


TABLE 139
INDIA: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 140
INDIA: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2026–2033 (USD MILLION)


TABLE 141
EUROPE: RAILWAY SIGNALING MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 142
EUROPE: RAILWAY SIGNALING MARKET, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 143
GERMANY: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 144
GERMANY: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2026–2033 (USD MILLION)


TABLE 145
FRANCE: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 146
FRANCE: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2026–2033 (USD MILLION)


TABLE 147
UK: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 148
UK: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2026–2033 (USD MILLION)


TABLE 149
ITALY: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 150
ITALY: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2026–2033 (USD MILLION)


TABLE 151
SPAIN: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 152
SPAIN: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2026–2033 (USD MILLION)


TABLE 153
NORTH AMERICA: RAILWAY SIGNALING MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 154
NORTH AMERICA: RAILWAY SIGNALING MARKET, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 155
US: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 156
US: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2026–2033 (USD MILLION)


TABLE 157
CANADA: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 158
CANADA: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2026–2033 (USD MILLION)


TABLE 159
MEXICO: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 160
MEXICO: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2026–2033 (USD MILLION)


TABLE 161
REST OF THE WORLD: RAILWAY SIGNALING MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 162
REST OF THE WORLD: RAILWAY SIGNALING MARKET, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 163
SOUTH AFRICA: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 164
SOUTH AFRICA: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2026–2033 (USD MILLION)


TABLE 165
BRAZIL: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2022–2025 (USD MILLION)


TABLE 166
BRAZIL: RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2026–2033 (USD MILLION)


TABLE 167
KEY PLAYER STRATEGIES/RIGHT TO WIN, JANUARY 2022–AUGUST 2026


TABLE 168
MARKET SHARE ANALYSIS OF RAILWAY SIGNALING MARKET PLAYERS 2025


TABLE 169
GOA LEVELS: MARKET POSITION AND COMMERCIAL PRIORITIES, JANUARY 2022–AUGUST 2026


TABLE 170
RAILWAY SIGNALING MARKET: REGION FOOTPRINT


TABLE 171
RAILWAY SIGNALING MARKET: TECHNOLOGY FOOTPRINT


TABLE 172
RAILWAY SIGNALING MARKET: COMPONENT FOOTPRINT


TABLE 173
RAILWAY SIGNALING MARKET: DETAILED LIST OF KEY STARTUPS/SMES


TABLE 174
RAILWAY SIGNALING MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES


TABLE 175
RAILWAY SIGNALING MARKET: PRODUCT LAUNCHES/DEVELOPMENTS, JANUARY 2022–AUGUST 2026


TABLE 176
RAILWAY SIGNALING MARKET: DEALS, JANUARY 2022–AUGUST 2026


TABLE 177
RAILWAY SIGNALING MARKET: EXPANSIONS, JANUARY 2022–AUGUST 2026


TABLE 178
RAILWAY SIGNALING MARKET: OTHER DEVELOPMENTS, JANUARY 2022–AUGUST 2026


TABLE 179
ALSTOM SA: COMPANY OVERVIEW


TABLE 180
ALSTOM SA: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 181
ALSTOM SA: DEALS


TABLE 182
SIEMENS MOBILITY: COMPANY OVERVIEW


TABLE 183
SIEMENS MOBILITY: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 184
SIEMENS MOBILITY: PRODUCT LAUNCHES/DEVELOPMENTS


TABLE 185
SIEMENS MOBILITY: DEALS


TABLE 186
SIEMENS MOBILITY: OTHER DEVELOPMENTS


TABLE 187
HITACHI RAIL: COMPANY OVERVIEW


TABLE 188
HITACHI RAIL: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 189
HITACHI RAIL: PRODUCT LAUNCHES/DEVELOPMENTS


TABLE 190
HITACHI RAIL: DEALS


TABLE 191
CRSC: COMPANY OVERVIEW


TABLE 192
CRSC: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 193
CRSC: PRODUCT LAUNCHES/DEVELOPMENTS


TABLE 194
CRSC: DEALS


TABLE 195
CRSC: EXPANSIONS


TABLE 196
WABTEC CORPORATION: COMPANY OVERVIEW


TABLE 197
WABTEC CORPORATION: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 198
WABTEC CORPORATION: PRODUCT LAUNCHES/DEVELOPMENTS


TABLE 199
WABTEC CORPORATION: DEALS


TABLE 200
WABTEC CORPORATION: OTHER DEVELOPMENTS


TABLE 201
PROGRESS RAIL: COMPANY OVERVIEW


TABLE 202
PROGRESS RAIL: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 203
PROGRESS RAIL: DEALS


TABLE 204
PROGRESS RAIL: OTHER DEVELOPMENTS


TABLE 205
KNORR-BREMSE GLOBAL RAIL HOLDING GMBH: COMPANY OVERVIEW


TABLE 206
KNORR-BREMSE GLOBAL RAIL HOLDING GMBH: PRODUCTS/SOLUTIONS/ SERVICES OFFERED


TABLE 207
KNORR-BREMSE GLOBAL RAIL HOLDING GMBH: DEALS


TABLE 208
KNORR-BREMSE GLOBAL RAIL HOLDING GMBH: EXPANSIONS


TABLE 209
KNORR-BREMSE GLOBAL RAIL HOLDING GMBH: OTHER DEVELOPMENTS


TABLE 210
CAF S.A.: COMPANY OVERVIEW


TABLE 211
CAF S.A.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 212
CAF S.A.: OTHER DEVELOPMENTS


TABLE 213
NIPPON SIGNAL CO., LTD.: COMPANY OVERVIEW


TABLE 214
NIPPON SIGNAL CO., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 215
KYOSAN ELECTRIC MFG. CO., LTD.: COMPANY OVERVIEW


TABLE 216
KYOSAN ELECTRIC MFG. CO., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 217
MER MEC S.P.A.: COMPANY OVERVIEW


TABLE 218
MER MEC S.P.A.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 219
MER MEC S.P.A.: DEALS


TABLE 220
MER MEC S.P.A.: OTHER DEVELOPMENTS


TABLE 221
MITSUBISHI ELECTRIC: COMPANY OVERVIEW


TABLE 222
MITSUBISHI ELECTRIC: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 223
PINTSCH GMBH: COMPANY OVERVIEW


TABLE 224
SCHEIDT & BACHMANN: COMPANY OVERVIEW


TABLE 225
TRAFFIC CONTROL TECHNOLOGY CO., LTD.: COMPANY OVERVIEW


TABLE 226
AŽD PRAHA S.R.O: COMPANY OVERVIEW


TABLE 227
STADLER INC.: COMPANY OVERVIEW


TABLE 228
HIMA: COMPANY OVERVIEW


TABLE 229
TOSHIBA: COMPANY OVERVIEW


TABLE 230
UNITTEC: COMPANY OVERVIEW


TABLE 231
RAILTEL: COMPANY OVERVIEW


TABLE 232
CLEARSY: COMPANY OVERVIEW


TABLE 233
PILZ: COMPANY OVERVIEW


LIST OF FIGURES


FIGURE 1
RAILWAY SIGNALING MARKET SEGMENTATION AND REGIONAL SCOPE


FIGURE 2
MARKET SCENARIO


FIGURE 3
GLOBAL RAILWAY SIGNALING MARKET, 2022–2033


FIGURE 4
MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN RAILWAY SIGNALING MARKET, 2022–2026


FIGURE 5
DISRUPTIONS INFLUENCING GROWTH OF RAILWAY SIGNALING MARKET


FIGURE 6
HIGH-GROWTH SEGMENTS IN RAILWAY SIGNALING MARKET, 2026–2033


FIGURE 7
ASIA PACIFIC TO LEAD MARKET DURING FORECAST PERIOD


FIGURE 8
DIGITAL SIGNALING AND NETWORK MODERNIZATION TO ACCELERATE MARKET GROWTH


FIGURE 9
HIGH-SPEED TRAINS TO EXHIBIT FASTEST GROWTH DURING FORECAST PERIOD


FIGURE 10
SOLUTIONS TO ACCOUNT FOR LARGER MARKET SHARE DURING FORECAST PERIOD


FIGURE 11
HARDWARE SEGMENT TO SECURE LEADING POSITION DURING FORECAST PERIOD


FIGURE 12
AUTOMATIC TRAIN CONTROL SEGMENT TO DOMINATE MARKET IN 2033


FIGURE 13
MAINLINE TO BE LARGEST SEGMENT DURING FORECAST PERIOD


FIGURE 14
NORTH AMERICA TO BE FASTEST-GROWING MARKET FOR RAILWAY SIGNALING DURING FORECAST PERIOD


FIGURE 15
RAILWAY SIGNALING MARKET DYNAMICS


FIGURE 16
ECOSYSTEM ANALYSIS


FIGURE 17
RAILWAY SIGNALING MARKET: SUPPLY CHAIN ANALYSIS


FIGURE 18
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS


FIGURE 19
INVESTMENT AND FUNDING SCENARIO, 2024–2026


FIGURE 20
IMPORT DATA FOR HS CODE 8530-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025


FIGURE 21
EXPORT DATA FOR HS CODE 8530-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025


FIGURE 22
AVERAGE MONTHLY BRENT SPOT PRICE FREE ON BOARD (FOB), MAY 2024–JULY 2026


FIGURE 23
PATENT ANALYSIS, 2017–2026


FIGURE 24
ROADMAP OF RAILWAY DIGITALIZATION


FIGURE 25
OEM TECHNOLOGY BENCHMARKING - RAILWAY SIGNALING MARKET (2026)


FIGURE 26
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY TRAIN TYPE


FIGURE 27
KEY BUYING CRITERIA, BY TRAIN TYPE


FIGURE 28
FUTURE REVENUE MODELS FOR RAILWAY SIGNALING INDUSTRY


FIGURE 29
SIGNALING AS A SERVICE: RECURRING REVENUE STRUCTURE


FIGURE 30
SOFTWARE LICENSING: SOFTWARE REVENUE MODEL


FIGURE 31
ANNUAL MAINTENANCE CONTRACTS: LIFECYCLE COMMERCIAL MODEL


FIGURE 32
PREDICTIVE MAINTENANCE CONTRACTS: ANALYTICS-LED REVENUE MODEL


FIGURE 33
RAILWAY SIGNALING MARKET, BY TCMS TRAIN TYPE, 2026 VS. 2033


FIGURE 34
RAILWAY SIGNALING MARKET, BY TCMS OFFERING, 2026 VS. 2033


FIGURE 35
RAILWAY SIGNALING MARKET, BY COMPONENT, 2026 VS. 2033


FIGURE 36
RAILWAY SIGNALING MARKET, BY TECHNOLOGY, 2026 VS. 2033


FIGURE 37
RAILWAY SIGNALING MARKET, BY END USE, 2026 VS. 2033


FIGURE 38
RAILWAY SIGNALING MARKET, BY REGION, 2026 VS. 2033


FIGURE 39
ASIA PACIFIC: RAILWAY SIGNALING MARKET SNAPSHOT


FIGURE 40
EUROPE: RAILWAY SIGNALING MARKET, BY COUNTRY, 2026 VS. 2033


FIGURE 41
NORTH AMERICA: RAILWAY SIGNALING SNAPSHOT


FIGURE 42
REST OF THE WORLD: RAILWAY SIGNALING MARKET, BY COUNTRY, 2026 VS. 2033


FIGURE 43
RAILWAY SIGNALING MARKET SHARE ANALYSIS, 2025


FIGURE 44
REVENUE ANALYSIS OF KEY PLAYERS IN RAILWAY SIGNALING MARKET, 2021–2025


FIGURE 45
RAILWAY SIGNALING MARKET: BRAND COMPARISON


FIGURE 46
COMPANY VALUATION OF KEY PLAYERS


FIGURE 47
FINANCIAL METRICS OF KEY PLAYERS


FIGURE 48
RAILWAY SIGNALING MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025


FIGURE 49
RAILWAY SIGNALING MARKET: COMPANY FOOTPRINT


FIGURE 50
RAILWAY SIGNALING MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025


FIGURE 51
ALSTOM SA: COMPANY SNAPSHOT


FIGURE 52
SIEMENS MOBILITY: COMPANY SNAPSHOT


FIGURE 53
HITACHI RAIL: COMPANY SNAPSHOT


FIGURE 54
CRSC: COMPANY SNAPSHOT


FIGURE 55
WABTEC CORPORATION: COMPANY SNAPSHOT


FIGURE 56
KNORR-BREMSE GLOBAL RAIL HOLDING GMBH: COMPANY SNAPSHOT


FIGURE 57
CAF S.A.: COMPANY SNAPSHOT


FIGURE 58
NIPPON SIGNAL CO., LTD.: COMPANY SNAPSHOT


FIGURE 59
KYOSAN ELECTRIC MFG. CO., LTD.: COMPANY SNAPSHOT


FIGURE 60
MITSUBISHI ELECTRIC: COMPANY SNAPSHOT


FIGURE 61
RESEARCH DESIGN


FIGURE 62
RESEARCH DESIGN MODEL


FIGURE 63
RESEARCH METHODOLOGY: HYPOTHESIS BUILDING


FIGURE 64
TOP-DOWN APPROACH


FIGURE 65
DATA TRIANGULATION


FIGURE 66
GROWTH PROJECTIONS FROM DEMAND-SIDE DRIVERS


FIGURE 67
DEMAND- AND SUPPLY-SIDE FACTOR ANALYSIS


Methodology

The study involved four major activities in estimating the current size of the railway signaling market. Exhaustive secondary research was done to collect information on the market, the peer market, and the child markets. The next step was to validate these findings and assumptions and size them with industry experts across value chains through primary research. The top-down approaches were employed to estimate the complete market size. Thereafter, market breakdown and data triangulation processes were used to estimate the market size of segments and subsegments.

Secondary Research

In the secondary research process, various secondary sources such as company annual report/presentations, press releases, investor presentations of companies, white papers, certified publications, and articles from recognized authors have been used to identify and collect information useful for an extensive commercial study of the global machine tools market.

Primary Research

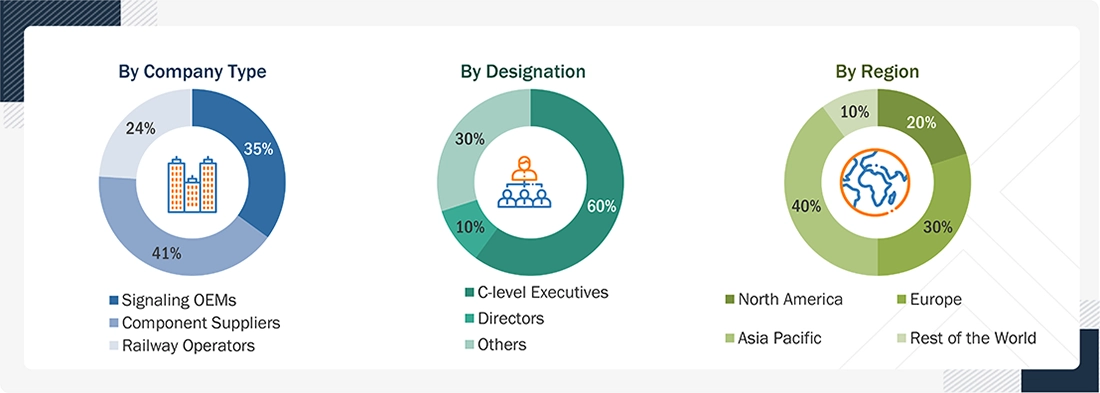
Extensive primary research was conducted after acquiring an understanding of the railway signaling market scenarios through secondary research. Several primary interviews were conducted with market experts from both the demand (railway infrastructure managers, passenger and freight operators, metro and high-speed rail authorities, government railway organizations, regulators, and signaling procurement teams) and supply (signaling OEMs, system integrators, technology and component suppliers, and signaling maintenance/service providers) sides across four major regions: North America, Europe, Asia Pacific, and the Rest of the World (RoW). Approximately 24% and 76% of primary interviews were conducted from the demand and supply sides, respectively. Primary data was collected through questionnaires, emails, and telephonic interviews.
In the canvassing of primaries, various departments within organizations, such as sales, operations, and administration, were covered to provide a holistic viewpoint in the report. After interacting with industry experts, brief sessions were conducted with highly experienced independent consultants to reinforce the findings from primaries. This, along with in-house subject-matter experts’ opinions, led to the findings described in the remainder of this report.

Railway Signaling Market Size, and Share

To know about the assumptions considered for the study, download the pdf brochure

Market Size Estimation

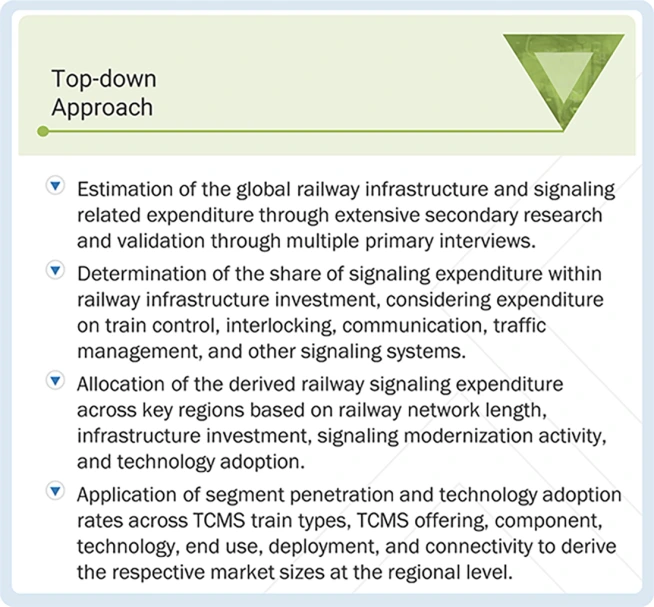
Only the top-down approach was used to estimate and validate the total size of the market. This method was also used extensively to estimate the size of various subsegments in the market. The research methodology used to estimate the market size includes the following:

Railway Signaling Market : Top-Down Approach

Railway Signaling Market Top Down and Bottom Up Approach

Data Triangulation

After arriving at the overall market size- using the market estimation processes as explained above- the market was split into several segments and subsegments. To complete the overall market engineering process and arrive at the exact statistics of each market segment and subsegment, data triangulation and market breakdown procedures were employed, wherever applicable. The data was triangulated by studying various factors and trends from both the demand and supply sides.

Market Defination

Railway signaling refers to the integrated systems used to control, supervise, and manage train movements while maintaining safe separation between trains. These systems combine train detection, interlocking, route control, train protection, onboard and wayside equipment, and signaling communications. Key technologies include ABS, CBTC, ETCS, PTC, and ATC, deployed across mainline, urban, high-speed, and freight rail networks. Modern signaling also supports continuous train localization and movement supervision, particularly in digitally controlled and automated railway operations. The market therefore covers signaling hardware, software, system integration, modernization, and associated lifecycle services used for new installations and upgrades of existing networks.

Key Stakeholders

  • Railway Operators & Infrastructure Managers
  • Signaling OEMs & System Integrators
  • Signaling Component Suppliers
  • Railway Infrastructure Contractors
  • Rolling Stock OEMs
  • Rail Regulators & Safety Authorities
  • Standards Organizations & Industry Associations
  • Testing, Certification, and Assessment Bodies

Report Objectives

  • To define, segment, and forecast the size of the railway signaling market in terms of value (USD billion) based on the following categories: TCMS train type, TCMS offering, component, technology, end-use, deployment, connectivity, and region
    • TCMS Train Type [Light-Rail & Metros (DMU & EMU), High Speed Trains, Conventional Passenger Trains, Freight Trains]
    • TCMS Offering (Solutions and Services)
    • Component (Hardware and Software)
    • Technology [Automatic Block Signaling (ABS), Communications-Based Train Control (CBTC), European Train Control System (ETCS), Positive Train Control (PTC), Automatic Train Control (ATC)]
    • End-use (Mainline, Urban, Freight)
    • Region [North America, Europe, Asia Pacific, and RoW]
  • To cover infrastructure foundations, deployment, and connectivity segments qualitatively
  • To evaluate the key market dynamics influencing the railway signaling market, including strategic drivers, restraints, opportunities, challenges, and emerging technology trends shaping future industry growth
  • To study the following with respect to the market:
    • Supply Chain Analysis
    • Ecosystem Analysis
    • Technology Analysis
    • Trade Analysis
    • Case Study Analysis
    • Supplier Analysis
    • Investment and Funding Scenario
    • Company Valuation and Financial Metrics
    • Brand/Product Comparison
    • Patent Analysis
    • Regulatory Landscape
    • Conferences and Events
    • Future Revenue Models for Railway Signaling Industry
    • Global Capex Pipeline Analysis
    • Future Communication Technologies
    • EU-India Trade Deal: Impact Analysis
    • Israel-Iran Impact on Railway Signaling Market

    • Railway Digitalization Roadmap
    • OEM Technology Benchmarking
  • To strategically analyze segments with respect to individual growth trends, prospects, and contributions to the total market
  • To assess the competitive landscape by profiling leading global market participants based on their business overview, product portfolio, geographic presence, financial performance, and recent strategic developments such as product launches, partnerships, acquisitions, and capacity expansions
  • To map the competitive ecosystem by categorizing market participants into Stars, Emerging Leaders, Pervasive Players, and Participants using a robust evaluation framework based on the strength of their product portfolio, business strategy, innovation capability, and market presence

Available customizations:

With the given market data, MarketsandMarkets offers customizations in line with company-specific needs.

  • Further breakdown for the railway signaling market, by TCMS train type, at the country level (for countries covered in the report)
  • Further breakdown for the railway signaling market, by end-use, at the country level (for countries covered in the report)

Company Profiles

  • Profiles of additional market players (up to five)

 

Personalize This Research

  • Triangulate with your Own Data
  • Get Data as per your Format and Definition
  • Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
  • Any level of Personalization
Request A Free Customisation

Let Us Help You

  • What are the Known and Unknown Adjacencies Impacting the Railway Signaling Market
  • What will your New Revenue Sources be?
  • Who will be your Top Customer; what will make them switch?
  • Defend your Market Share or Win Competitors
  • Get a Scorecard for Target Partners
Customized Workshop Request

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements

Get 10% Free Customisation

TESTIMONIALS

Growth opportunities and latent adjacency in Railway Signaling Market

avtar

Amey

Nov, 2019

Dear all, in which of your fields of train control system does the ETCS fit it – Train Control Solutions Market or Positive Train Control or Communication-Based Train Control or Integrated Train Control? Query180047242460889000637_1573815378507.

avtar

Amey

Nov, 2019

I am Interested in the report. Please share the sample of the report. It seems a good report. i would like to see the level of information you covered in the report. Thanks. .

DMCA.com Protection Status
popup img