



Enterprise Asset Management Market
Report Code
TC 3454
Published in
Sep, 2026, By MarketsandMarkets™
Enterprise Asset Management Market by Asset Class (Linear, Fleet & Mobile, Fixed Assets, Production Equipment), Application (Asset Lifecycle Management, Operations, Maintenance Management, Other Applications), Deployment Type, Region - Global Forecast to 2031

USD 12.55 BN
MARKET SIZE, 2031

CAGR 10.1%
(2026-2031)

320
REPORT PAGES

200
MARKET TABLES
OVERVIEW
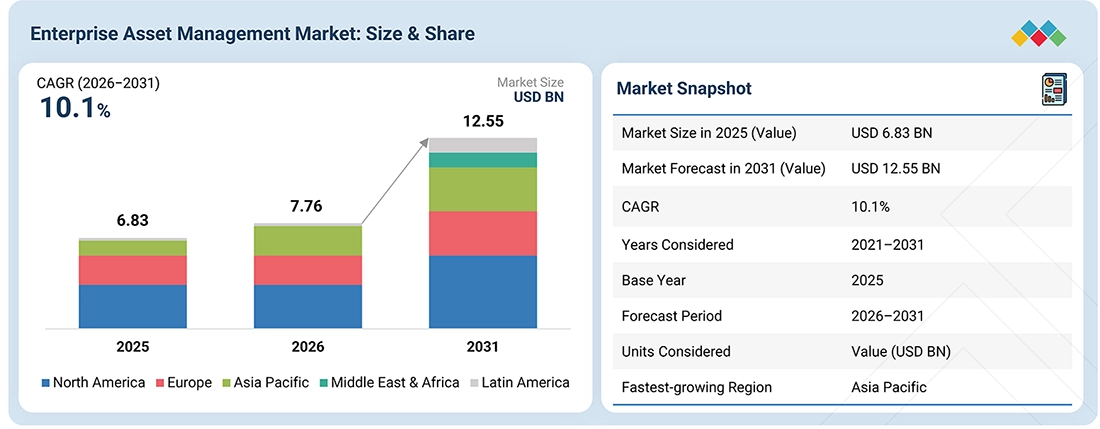
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
The enterprise asset management market is projected to grow from USD 7.76 billion in 2026 to USD 12.55 billion by 2031, at a CAGR of 10.1% during the forecast period. The enterprise asset management market is advancing as organizations prioritize intelligent asset lifecycle management, connected maintenance operations, and unified asset data architectures across distributed facilities. Vendors are differentiating through AI-enabled EAM software, predictive maintenance, embedded analytics, mobile workforce capabilities, and automation that strengthens asset reliability, optimizes maintenance scheduling, and supports enterprise-wide operational decision making.
KEY TAKEAWAYS
-
BY REGIONAsia Pacific is likely to be the fastest-growing market for enterprise asset management solutions and services, driven by rapid industrial digitalization, expanding connected asset networks, and increasing adoption of predictive maintenance requiring scalable, intelligent asset management platforms.
-
BY OFFERINGSolutions are expected to capture the largest share of the enterprise asset management market in 2031.
-
BY APPLICATIONBy application, the maintenance management segment is expected to record at the fastest rate of 10.8% during the forecast period in the enterprise asset management market.
-
BY ASSET CLASSLinear assets are expected to record the fastest growth rate of 10.8% of the global enterprise asset management market during the forecast period.
-
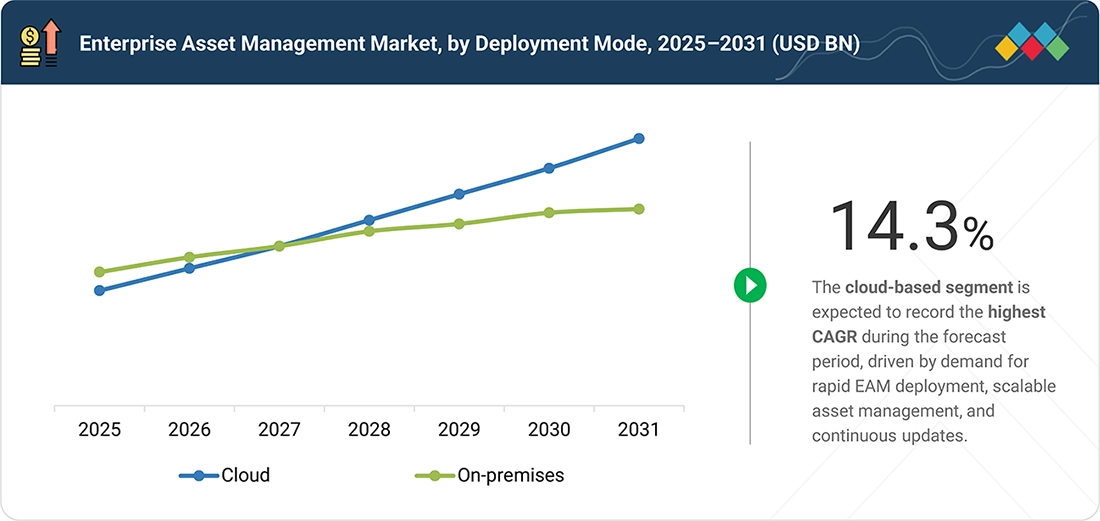
BY DEPLOYMENT TYPEBy deployment type, cloud is expected to witness the fastest growth rate 14.3% during the forecast period in the global enterprise asset management market.
-
BY ORGANIZATION SIZESMEs are likely to witness the fastest growth rate in the enterprise asset management market as expanding asset bases, limited maintenance resources, and tight budgets drive adoption of cloud-based EAM software and scalable, configurable asset management solutions.
-
BY VERTICALBy vertical, the manufacturing segment is expected to capture the largest market share as manufacturers expand connected asset networks, predictive maintenance programs, and enterprise-wide asset lifecycle management infrastructure.
-
COMPETITIVE LANDSCAPE - KEY PLAYERSIBM, SAP, Oracle, Siemens, and IFS are key players in the enterprise asset management market, delivering AI-enabled EAM software, predictive maintenance, asset performance management, mobile workforce solutions, and integrated asset lifecycle platforms for complex industrial operations.
-
COMPETITIVE LANDSCAPE - STARTUPS/SMEsAsset Panda, Asset Infinity, KloudGin have distinguished themselves among startups and SMEs through robust product portfolios and effective business strategies.
As asset data becomes increasingly distributed across maintenance, operations, supply chain, and enterprise systems, demand for Enterprise Asset Management (EAM) platforms that orchestrate connected asset lifecycle operations is accelerating. Vendors are embedding intelligent workflow automation, unified asset data models, and interoperable integration frameworks to improve operational agility, strengthen asset governance, and enable proactive maintenance and reliability interventions.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
Disruptions in enterprise asset management (EAM) are expected to reshape revenue sources of market players over the next 7–10 years by shifting demand from traditional on-premises EAM software, computerized maintenance and standalone work-order management systems toward cloud-native EAM and SaaS platforms, IoT- and sensor-enabled asset management, AI-powered maintenance planning, digital twins, and connected asset ecosystems. This transition is driven by the growing need for manufacturing companies to connect plant assets with maintenance data, minimize unplanned downtime, optimize maintenance and asset costs, and manage distributed and aging assets. In energy and utilities, EAM adoption is increasingly linked to asset-risk-based maintenance, integration of field and asset operations, and improved reliability and faster failure resolution. Similarly, transportation and logistics companies are prioritizing fleet and infrastructure availability, real-time asset visibility, and optimized field maintenance and resources. These client imperatives are expected to translate into measurable operational outcomes, including higher equipment availability and OEE, lower unplanned downtime and maintenance costs, standardized maintenance practices, extended asset life, greater infrastructure reliability, faster failure detection, and lower lifecycle costs. Consequently, new use cases, technologies, products and offerings, clients and partners, and targeted M&A are expected to expand the share of new revenue sources in the enterprise asset management market while gradually reducing reliance on legacy revenue streams.
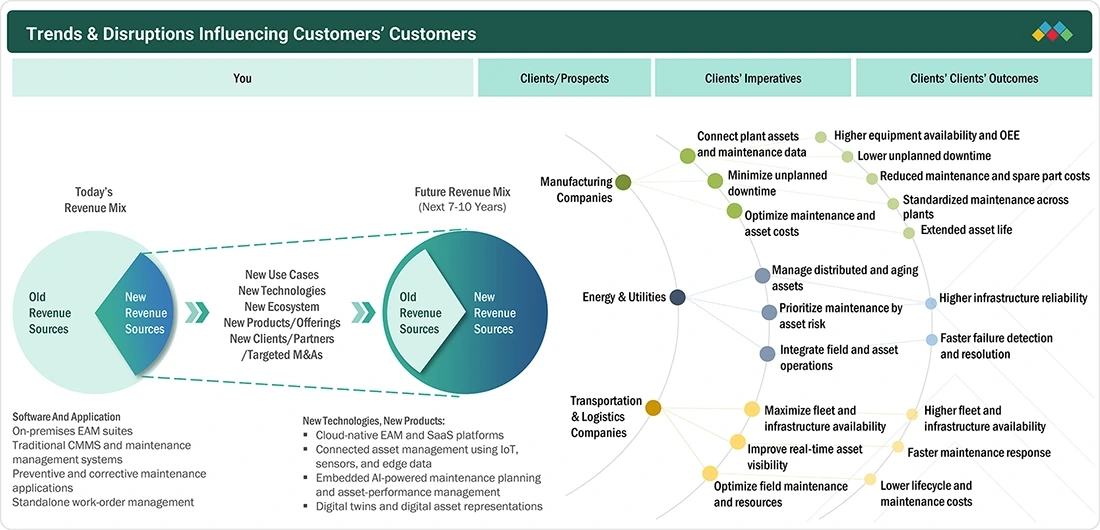
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Drivers
Impact
Level
Level
-
Rising demand for higher asset uptime

-
Pressing need for real-time asset insights


RESTRAINTS
Impact
Level
Level
-
High upfront implementation costs

-
Complex integration and system modernization requirements


OPPORTUNITIES
Impact
Level
Level
-
Expansion of digital twins and lifecycle simulation

-
Growing adoption of remote maintenance


CHALLENGES
Impact
Level
Level
-
Fragmented asset data and legacy systems

-
Shortage of skilled asset management professionals

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Accelerating adoption of AI-driven, connected asset operation
The growing demand for higher asset uptime, greater maintenance efficiency, and improved asset lifecycle value is accelerating the adoption of AI-powered EAM platforms. Organizations are increasingly leveraging predictive analytics, condition monitoring, generative AI, and automated workflows to enable predictive and prescriptive asset management. These capabilities help organizations identify potential failures earlier, optimize maintenance activities, reduce unplanned downtime, and improve overall asset reliability.
Restraint: Complex Integration and System Modernization Requirements
The complexity and cost of integrating EAM platforms with legacy ERP systems, operational technologies, asset databases, and existing maintenance systems can create significant implementation challenges. Large organizations may require extensive data migration, system integration, customization, process redesign, and user training to ensure seamless deployment. These requirements can increase implementation costs and timelines, create operational disruptions, and delay the realization of returns on EAM investments, thereby constraining the adoption of EAM solutions.
Opportunity: Expansion of digital twins and lifecycle simulation
The growing adoption of digital twins presents an opportunity for EAM vendors to expand beyond traditional maintenance management toward comprehensive asset lifecycle optimization. Digital twins integrate real-time asset data with engineering information, maintenance histories, and operational conditions, enabling organizations to continuously monitor asset performance, simulate operating scenarios, predict potential failures, and optimize maintenance and asset-management strategies throughout the asset lifecycle.
Challenge: Fragmented asset data and legacy systems
Dispersed asset information, along with complicated legacy systems, results in difficulties in upgrading EAM, especially for big companies, which utilize many custom technologies. The use of EAM technology to integrate with ERP, MES, inventory, engineering, and operational systems brings other burdens, such as the need to migrate data, standardize it, and implement the necessary actions, which makes the upgrade process more complicated and less speedy.
ENTERPRISE ASSET MANAGEMENT MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Hungrana Kft. modernized maintenance and safety with SAP EAM | Hungrana achieved significant cost savings, improved technician productivity, and reduced paperwork through digitalized maintenance. The solutions also enhanced workplace safety, ensured regulatory compliance, and supported long-term sustainability goals. |
 |
Riyadh Airports Company (RAC) transformed King Khalid International Airport’s maintenance operations by deploying IBM Maximo | RAC achieved major efficiency gains with an 80% reduction in paperwork, a 50% improvement in real-time insights, and contractor onboarding cut from 10 days to just 2–3. Inspector productivity rose by over 40%, while automated workflows and preventive maintenance minimized errors, reduced downtime, and optimized asset lifecycle costs. |
 |
Transdev Sweden rapidly deployed Hexagon’s HxGN EAM to take over the Mälartåg rail network | Transdev Sweden ensured uninterrupted passenger services with improved maintenance efficiency and seamless asset tracking across rail and bus fleets. The future-ready HxGN EAM platform also supports proactive strategies, system integration, and readiness for electric bus adoption. |
 |
L’Oréal implemented Maintenance Connection CMMS to enhance preventive maintenance, streamline workflows, and centralize asset data across its U.S. facilities. | L’Oréal achieved lower maintenance costs and fewer equipment breakdowns through preventive maintenance. The company also improved mechanic productivity and real-time asset visibility, enabling proactive downtime management. |
 |
Anderson Dahlen implemented Aptean EAM to centralize preventive maintenance, streamline work order tracking, and reduce reliance on costly outsourced contractors. | Anderson Dahlen cut maintenance costs by replacing outsourced services with an expanded in-house team and centralized preventive maintenance requests. This improved response speed, reduced downtime, and provided data-driven visibility for smarter decision-making. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
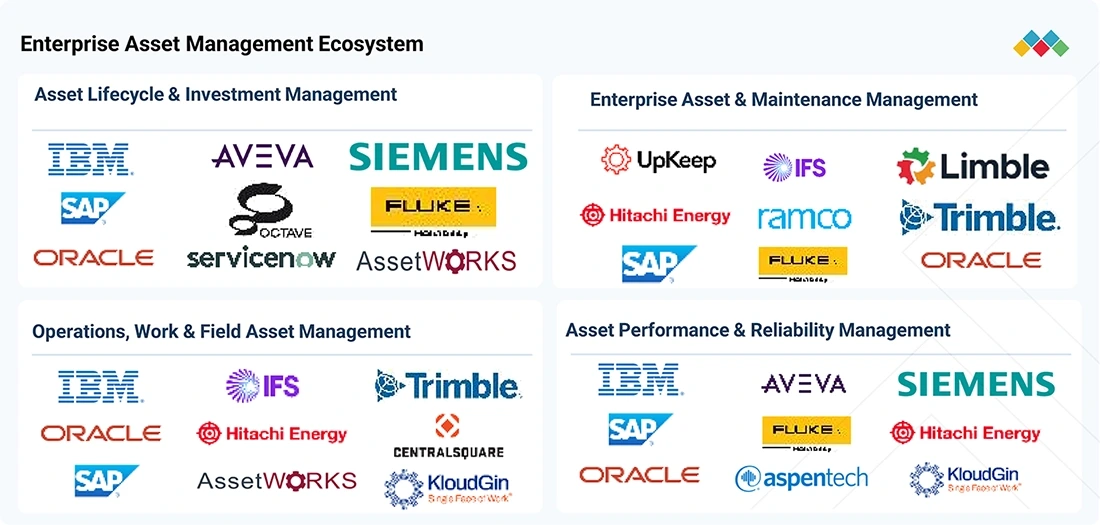
The EAM ecosystem comprises platforms that support asset investment planning and lifecycle management, enterprise asset and maintenance management solutions that streamline preventive maintenance, asset management, and work-order processes, operations, work, and field asset management platforms that improve workforce execution, and asset performance and reliability management solutions that enable predictive analytics, risk assessment, and asset optimization. Within this ecosystem, a core group of vendors, including IBM and SAP, offers capabilities spanning the entire asset lifecycle, from investment planning and asset acquisition to maintenance, field operations, and performance monitoring. Their broad portfolios indicate a competitive focus on end-to-end suite capabilities, integration, and lifecycle coverage rather than specialization in a single functional area. In the Asset Lifecycle & Investment Management category, Siemens and AVEVA stand out for their capabilities in engineering analytics, asset planning, and long-term capital investment management. The Enterprise Asset & Maintenance Management category includes specialized CMMS providers such as UpKeep and Limble, which primarily focus on day-to-day maintenance execution, work-order management, and technician productivity rather than broader capital planning. Similarly, the Operations, Work & Field Asset Management category includes suite providers such as ServiceNow and Trimble, reflecting the convergence of field service management, asset operations, and enterprise workflow capabilities. In contrast, the Asset Performance & Reliability Management category features specialized providers such as AspenTech and Fluke, with a stronger emphasis on condition monitoring, asset performance, and reliability analytics. Overall, the competitive landscape reflects a two-tier structure comprising diversified incumbents that compete through breadth, integration, and end-to-end lifecycle capabilities, alongside specialized vendors that differentiate through focused solutions for maintenance execution, field operations, asset performance, and reliability management.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Enterprise Asset Management (EAM) Market, By Offering
The services segment is growing rapidly as companies need special support in upgrading their asset management systems and maximizing their value. Demand is growing in areas such as training and consulting for asset strategy, process unification, and AI readiness; deployment and integration for legacy modernization, ERP, MES, IoT, APM, etc., and appropriate support for constant improvements and updates, cybersecurity, and performance of the base system.
Enterprise Asset Management (EAM) Market, By Application
By application, operations management is likely to capture the largest market share given that EAM will become the implementation layer that integrates asset condition with the maintenance schedules, work orders, field tasks and availability of resources. In the context of the transition to real time asset data, AI-based prioritization, and mobile work implementation, operations management is deemed to play a crucial role in enhancing uptime and maintenance efficiency.
Enterprise Asset Management (EAM) Market, By Asset Class
By asset class, it is anticipated that the production equipment sector will expand more quickly due to manufacturers moving toward highly mechanized production systems rich in sensors, where equipment malfunction has a direct impact on throughput and OEE. The more frequent application of condition data, digital twins, and AI-based failure prediction software will allow organizations to move from scheduled maintenance regimes to continuous equipment performance improvement and usage decisions related to the remaining life of equipment.
Enterprise Asset Management (EAM) Market, By Deployment Type
By deployment type, cloud is expected to witness the fastest growth, driven by the need to modernize fragmented EAM environments while minimizing disruption to heavily customized legacy systems. The increasing demand for AI-enabled capabilities, real-time asset visibility, and standardized integrations is further supporting cloud adoption, particularly among organizations with geographically dispersed assets undergoing phased EAM modernization.
Enterprise Asset Management (EAM) Market, By Organization Size
Large enterprises now regard EAM as an orchestration level in the relationship between operational technology and business applications, instead of viewing it just as a maintenance application. This is changing the demand for solutions that can continuously ingest assets and health data, and use AI to arrange jobs. In addition, the present customers expect that the vendors will lessen the integration friction and support the environments with various obsolete technologies.
Enterprise Asset Management (EAM) Market, By Vertical
Transportation and logistics will record the highest growth rate during the study period among all vertical segments. This is because sensor networks are being deployed in fleets, rail networks, airports, ports, and logistics infrastructure to make them increasingly interconnected and operational. The transformation from traditional maintenance to condition-based maintenance, and the use of AI-assisted tools for thorough fleet and infrastructure monitoring, will broaden the scope of enterprise asset management (EAM) from asset tracking processes to lifecycle management solutions.
REGION
Asia Pacific to be largest region in global enterprise asset management market during forecast period
According to forecasts, Asia Pacific is expected to register the highest growth in the enterprise asset management market, driven by rapid industrialization and the modernization of both newly digitized assets and aging legacy infrastructure. The increasing adoption of smart manufacturing, localized production, and infrastructure automation is creating strong demand for EAM solutions that integrate IoT data, maintenance operations, asset hierarchies, and lifecycle management across distributed facilities. As enterprises prioritize operational efficiency, asset visibility, and cost optimization, the need for integrated EAM platforms is expected to increase across the region.
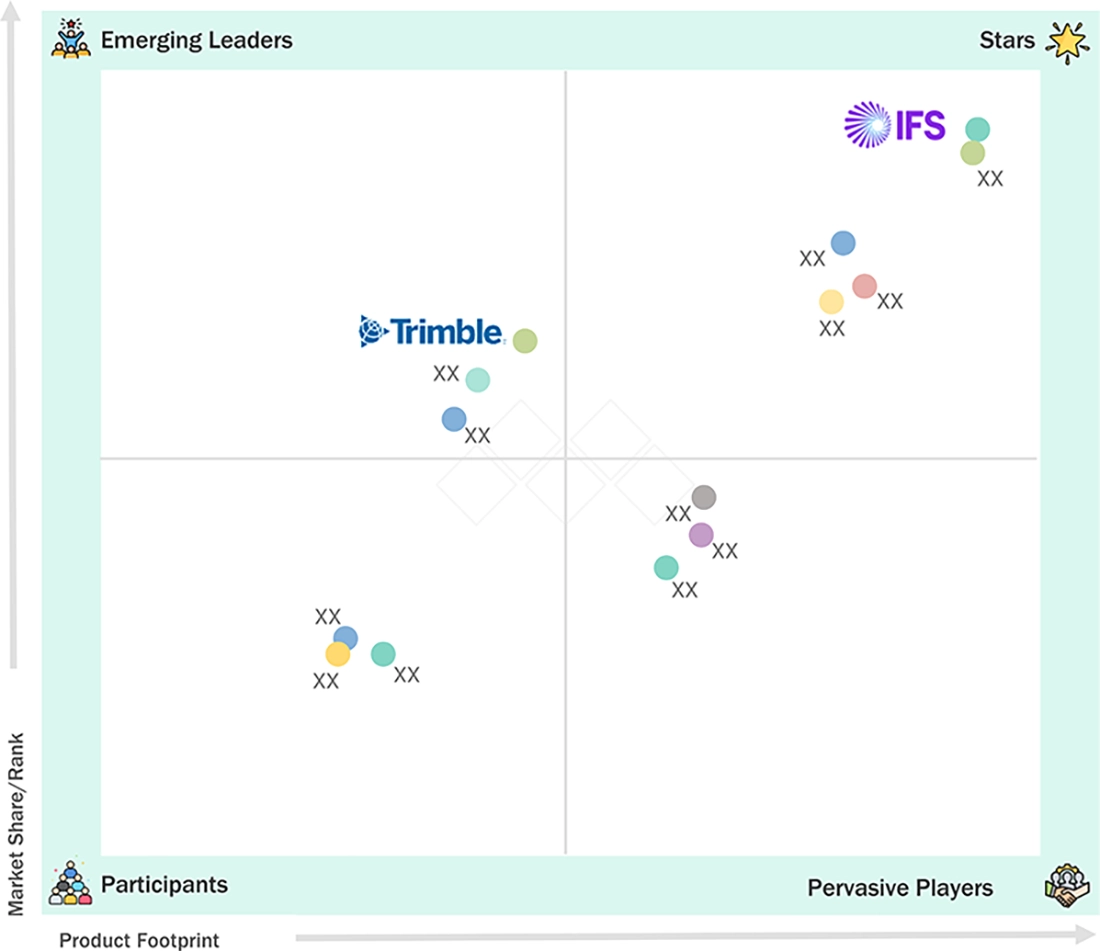
ENTERPRISE ASSET MANAGEMENT MARKET: COMPANY EVALUATION MATRIX
In the enterprise asset management market matrix, IFS (Star) lead with a strong market presence and comprehensive portfolio, enabling large-scale adoption across industries such as manufacturing, energy, and transportation. Trimble (Emerging Leader) is gaining traction with scalable, data-driven EAM solutions tailored for asset-intensive operations. While IFS dominates with scale and enterprise reach, other providers such as SAP and IBM show strong growth potential to advance toward the leaders’ quadrant.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- IBM (US)
- Oracle (US)
- SAP (Germany)
- Octave Intelligence (Ireland)
- IFS (Sweden)
- Aptean (US)
- Siemens (Germany)
- CGI (Canada)
- Trimble (US)
- ServiceNow (US)
- Eptura (US)
- Hitachi Energy (Switzerland)
- Ramco Systems (India)
- Accruent (US)
- MaintainX (US)
- ABS Group (US)
- Central Square Technologies (US)
- KloudGin (US)
- Assetworks (US)
- Limble CMMS (US)
- Upkeep (US)
- Asset Panda (US)
- emaint (US)
- Asset Infinity (India)
- Pragma (South Africa)
- EZmaintain (US)
- Llumin (US)
- IPS Intelligent Process Solutions (Germany)
- Ideagen (England)
- ePROMIS Solutions (US)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2025 (Value) | USD 6.83 Billion |
| Market Size in 2026 (Value) | USD 7.76 Billion |
| Market Forecast in 2031 (Value) | USD 12.55 Billion |
| CAGR | 10.1% |
| Years Considered | 2021-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Billion) |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered |
|
| Regions Covered | North America, Europe, Asia Pacific, Middle East & Africa, Latin America |
WHAT IS IN IT FOR YOU: ENTERPRISE ASSET MANAGEMENT MARKET REPORT CONTENT GUIDE
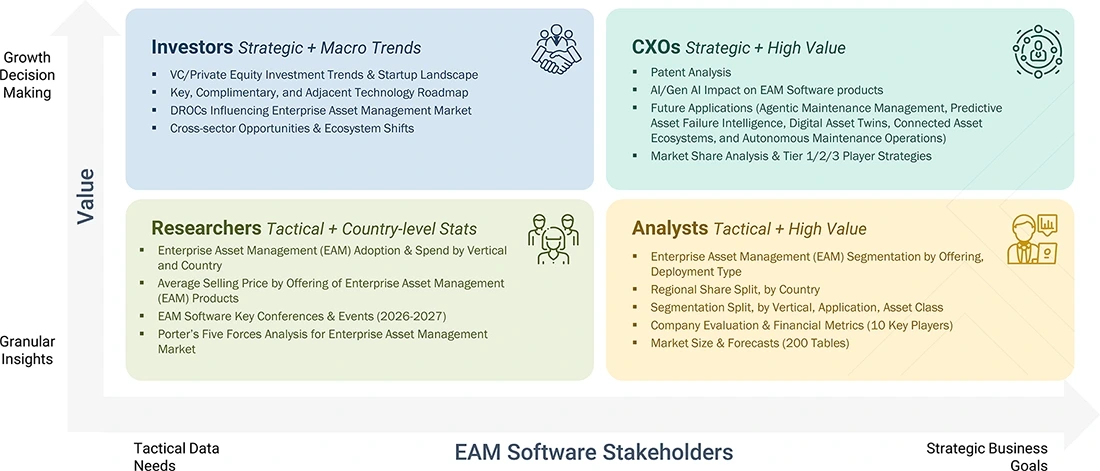
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Logistics Provider (US) | Regional Enterprise Asset Management (EAM) Market Assessment: Analysis of industrial asset modernization, smart manufacturing adoption, connected asset deployment, predictive maintenance initiatives, cloud and on-premises EAM preferences, legacy system integration, and AI-driven asset performance management across Asia Pacific asset-intensive industries. | Identifies high-growth asset management opportunities, prioritizes modernization and AI investments, aligns EAM capabilities with regional industrial transformation priorities, reduces deployment and integration risk, and supports region-specific market expansion strategies |
| Manufacturing & Industrial Enterprise (Asis Pacific) | Additional EAM Vendor Mapping: Identification and profiling of EAM providers across asset lifecycle management, maintenance management, work order management, asset performance management, predictive maintenance, mobile workforce management, IoT integration, digital twins, analytics, and AI-enabled maintenance solutions. | Expands qualified vendor options, strengthens competitive benchmarking, supports platform selection and partnership decisions, identifies capability gaps, reduces technology selection risk, and enables deployment of scalable EAM platforms aligned with evolving asset reliability and operational requirements |
RECENT DEVELOPMENTS
- August 2026 : Interloc Solutions launched interloc.ai, an agentic AI platform built specifically for IBM Maximo and Maximo Application Suite. The collaboration combines specialized AI agents with Maximo APIs, workflows, and security controls to analyze requests, create and update work orders, recommend assignments, retrieve knowledge, and execute approved maintenance actions.
- July 2026 : IFS and Chelsea Football Club expanded their partnership to deploy IFS technology across club operations. While the initial phase covers finance and procurement, future phases are planned to include asset management and facility operations. The agreement therefore represents a prospective EAM customer deployment, with Industrial AI intended to support asset and facility management activities.
- July 2026 : Octave Intelligence renewed a five-year strategic partnership with Veolia Environnement, expanding deployment of Octave Attune EAM to more than 10,000 users globally. The agreement supports digitalization of field operations, maintenance planning, and asset performance across Veolia’s water, waste, and energy activities, while integrating asset condition, regulatory requirements, and operational data through AWS Cloud.
- July 2026 : Siemens, through its owned company Brightly Software, partnered with AppyWay to integrate AppyWay’s Traffic Suite with Brightly’s Confirm asset management system. The collaboration connects digital traffic regulation and kerbside information with highway asset records, work programs, and operational activities, helping UK local authorities improve maintenance coordination and prepare for digital traffic-order compliance requirements.
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
TITLE
PAGE NO
1
INTRODUCTION
15
2
EXECUTIVE SUMMARY
3
PREMIUM INSIGHTS
4
MARKET OVERVIEW
Captures industry movement, adoption patterns, and strategic signals across key end-use segments and regions.
4.1
INTRODUCTION
4.2
MARKET DYNAMICS
4.2.1
DRIVERS
4.2.2
RESTRAINTS
4.2.3
OPPORTUNITIES
4.2.4
CHALLENGES
4.3
UNMET NEEDS AND WHITE SPACES
4.4
INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
4.5
STRATEGIC MOVES BY TIER 1/2/3
5
INDUSTRY TRENDS
Highlights the market structure, growth drivers, restraints, and near-term inflection points influencing performance.
5.1
PORTER’S FIVE FORCES ANALYSIS
5.2
MACROECONOMIC OUTLOOK
5.2.1
INTRODUCTION
5.2.2
GDP TRENDS AND FORECAST
5.2.3
TRENDS IN GLOBAL HUMAN CAPITAL MANAGEMENT INDUSTRY
5.2.4
TRENDS IN GLOBAL WORKFORCE MANAGEMENT INDUSTRY
5.3
VALUE CHAIN ANALYSIS
5.4
ECOSYSTEM ANALYSIS
5.5
PRICING ANALYSIS
5.5.1
AVERAGE SELLING PRICE TREND OF EAM OFFERINGS, BY KEY PLAYER, 2023-2025
5.5.2
AVERAGE SELLING PRICE TREND OF EAM OFFERINGS, BY REGION,
5.6
KEY CONFERENCES AND EVENTS, 2026-2027
5.7
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
5.8
INVESTMENT FUNDING SCENARIO
5.9
CASE STUDY ANALYSIS
5.10
IMPACT OF 2025 US TARIFF- ENTERPRISE ASSET MANAGEMENT MARKET
5.10.1
INTRODUCTION
5.10.2
KEY TARIFF RATES
5.10.3
PRICE IMPACT ANALYSIS
5.10.4
IMPACT ON REGIONS
5.10.4.1
NORTH AMERICA
5.10.4.2
ASIA PACIFIC
5.10.4.3
EUROPE
5.10.5
IMPACT ON END-USE INDUSTRIES
6
TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
6.1
KEY TECHNOLOGIES
6.2
COMPLEMENTARY TECHNOLOGIES
6.3
ADJACENT TECHNOLOGIES
6.4
TECHNOLOGY/PRODUCT ROADMAP
6.5
PATENT ANALYSIS
6.6
FUTURE APPLICATIONS
6.7
IMPACT OF AI/GEN AI ON ENTERPRISE ASSET MANAGEMENT (EAM) MARKET
6.7.1
TOP USE CASE AND MARKET POTENTIAL
6.7.2
BEST PRACTICES FOLLOWED BY PROVIDERS IN ENTERPRISE ASSET MANAGEMENT MARKET
6.7.3
CASE STUDIES RELATED TO AI IMPLEMENTATION IN THE ENTERPRISE ASSET MANAGEMENT MARKET
6.7.4
INTERCONNECTED ECOSYSTEM AND IMPACT OF MARKET PLAYERS
6.7.5
CLIENTS’ READINESS TO ADOPT AI-INTEGRATED ENTERPRISE ASSET MANAGEMENT
7
REGULATORY LANDSCAPE
7.1
REGIONAL REGULATIONS AND COMPLIANCE
7.1.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
7.1.2
INDUSTRY STANDARDS
8
CUSTOMER LANDSCAPE AND BUYING BEHAVIOR
8.1
INTRODUCTION
8.2
DECISION-MAKING PROCESS
8.3
KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND EVALUATION CRITERIA
8.3.1
KEY STAKEHOLDERS IN BUYING PROCESS
8.3.2
BUYING CRITERIA
8.3.3
ADOPTION BARRIERS AND INTERNAL CHALLENGES
8.3.4
UNMET NEEDS OF VARIOUS END-USE INDUSTRIES
9
ENTERPRISE ASSET MANAGEMENT MARKET, BY OFFERING (MARKET SIZE & GLOBAL FORECAST TO 2031 - IN VALUE USD MILLION) (COMPARATIVE ASSESSMENT OF KEY OFFERINGS, THEIR MARKET POTENTIAL, AND DEMAND PATTERNS BY VARIOUS SUPPLIER COMPANIES)
9.1
INTRODUCTION
9.1.1
OFFERING: ENTERPRISE ASSET MANAGEMENT MARKET DRIVERS
9.2
SOLUTIONS
9.3
SERVICES
9.3.1
TRAINING & CONSULTING
9.3.2
DEPLOYMENT & INTEGRATION
9.3.3
SUPPORT & MAINTENANCE
10
ENTERPRISE ASSET MANAGEMENT MARKET, BY APPLICATION (MARKET SIZE & GLOBAL FORECAST TO 2031 - IN VALUE USD MILLION) (APPLICATION-WISE DEMAND POTENTIAL AND GROWTH PATHWAYS SHAPING ENTERPRISE ASSET MANAGEMENT ADOPTION IN DIVERSE INDUSTRIES)
10.1
INTRODUCTION
10.1.1
APPLICATION: ENTERPRISE ASSET MANAGEMENT MARKET DRIVERS
10.2
ASSET LIFECYCLE MANAGEMENT
10.3
OPERATIONS MANAGEMENT
10.4
MAINTENANCE MANAGEMENT
10.5
COMPLIANCE & SAFETY
10.6
REPORTING & ANALYTICS
10.7
OTHER APPLICATIONS
11
ENTERPRISE ASSET MANAGEMENT MARKET, BY ASSET CLASS (MARKET SIZE & GLOBAL FORECAST TO 2031 - IN VALUE USD MILLION) (ASSET CLASS-WISE DEMAND POTENTIAL AND GROWTH PATHWAYS SHAPING ENTERPRISE ASSET MANAGEMENT ADOPTION IN DIVERSE INDUSTRIES)
11.1
INTRODUCTION
11.1.1
ASSET CLASS: ENTERPRISE ASSET MANAGEMENT MARKET DRIVERS
11.2
LINEAR ASSETS
11.3
PRODUCTION EQUIPMENT
11.4
FLEET & MOBILE ASSETS
11.5
FIXED/FACILITY ASSETS/INFRATSRUCTURE
12
ENTERPRISE ASSET MANAGEMENT MARKET, BY DEPLOYMENT TYPE (MARKET SIZE & GLOBAL FORECAST TO 2031 - IN VALUE USD MILLION) (DEPLOYMENT MODE-WISE DEMAND POTENTIAL AND GROWTH PATHWAYS SHAPING ENTERPRISE ASSET MANAGEMENT ADOPTION IN DIVERSE INDUSTRIES)
12.1
INTRODUCTION
12.1.1
DEPLOYMENT MODE: ENTERPRISE ASSET MANAGEMENT MARKET DRIVERS
12.2
CLOUD
12.3
ON-PREMISES
13
ENTERPRISE ASSET MANAGEMENT MARKET, BY ORGANIZATION SIZE (MARKET SIZE & GLOBAL FORECAST TO 2031 - IN VALUE USD MILLION) (ORGANIZATION SIZE-WISE DEMAND POTENTIAL AND GROWTH PATHWAYS SHAPING ENTERPRISE ASSET MANAGEMENT ADOPTION IN DIVERSE INDUSTRIES)
13.1
INTRODUCTION
13.1.1
ORGANIZATION SIZE: ENTERPRISE ASSET MANAGEMENT MARKET DRIVERS
13.2
SMALL AND MEDIUM-SIZED ENTERPRISES
13.3
LARGE ENTERPRISES
14
ENTERPRISE ASSET MANAGEMENT MARKET, BY VERTICAL (MARKET SIZE & GLOBAL FORECAST TO 2031 - IN VALUE USD MILLION) (SECTOR-SPECIFIC ADOPTION DRIVERS, DEMAND DYNAMICS AND MARKET POTENTIAL ACROSS EACH END USER)
14.1
INTRODUCTION
14.1.1
VERTICAL: ENTERPRISE ASSET MANAGEMENT MARKET DRIVERS
14.2
MANUFACTURING
14.3
ENERGY & UTILITIES
14.4
OIL & GAS
14.5
TRANSPORTATION & LOGISTICS
14.6
HEALTHCARE & LIFE SCIENCES
14.7
GOVVERNMENT & PUBLIC SECTOR
14.8
OTHER VERTICALS
15
ENTERPRISE ASSET MANAGEMENT MARKET, BY REGION (MARKET SIZE & GLOBAL FORECAST TO 2031 - IN VALUE USD MILLION) (ASSESSING GROWTH PATTERNS, INDUSTRY FORCES, REGULATORY LANDSCAPE, AND MARKET POTENTIAL ACROSS KEY GEOGRAPHIES AND COUNTRIES)
15.1
INTRODUCTION
15.2
NORTH AMERICA
15.2.1
US
15.2.2
CANADA
15.3
EUROPE
15.3.1
UK
15.3.2
GERMANY
15.3.3
FRANCE
15.3.4
ITALY
15.3.5
REST OF EUROPE
15.4
ASIA PACIFIC
15.4.1
CHINA
15.4.2
JAPAN
15.4.3
AUSTRALIA & NEW ZEALAND
15.4.4
REST OF ASIA PACIFIC
15.5
MIDDLE EAST & AFRICA
15.5.1
GULF COOPERATION COUNCIL (GCC)
15.5.1.1
UAE
15.5.1.2
SAUDI ARABIA
15.5.1.3
REST OF GCC (QATAR, BAHRAIN, OMAN, AND KUWAIT)
15.5.2
SOUTH AFRICA
15.5.3
REST OF MIDDLE EAST & AFRICA
15.6
LATIN AMERICA
15.6.1
BRAZIL
15.6.2
MEXICO
15.6.3
REST OF LATIN AMERICA
16
COMPETITIVE LANDSCAPE (STRATEGIC ASSESSMENT OF LEADING PLAYERS, MARKET SHARE, REVENUE ANALYSIS, COMPANY POSITIONING, AND COMPETITIVE BENCHMARKS INFLUENCING MARKET POTENTIAL
OVERVIEW)
16.1
KEY PLAYER COMPETITIVE STRATEGIES/RIGHT TO WIN (JANUARY 2024-SEPTEMBER 2026)
16.2
REVENUE ANALYSIS (2021-2025)
16.3
MARKET SHARE ANALYSIS,
16.4
PRODUCT COMPARISON
16.5
COMPANY EVALUATION MATRIX: KEY PLAYERS
16.5.1
STARS
16.5.2
EMERGING LEADERS
16.5.3
PERVASIVE PLAYERS
16.5.4
PARTICIPANTS
16.5.5
COMPANY FOOTPRINT: KEY PLAYERS,
16.5.5.1
COMPANY FOOTPRINT
16.5.5.2
REGION FOOTPRINT
16.5.5.3
OFFERING FOOTPRINT
16.5.5.4
DEPLOYMENT TYPE FOOTPRINT
16.5.5.5
ASSET CLASS FOOTPRINT
16.5.5.6
VERTICAL FOOTPRINT
16.6
COMPANY EVALUATION MATRIX: STARTUPS/SMES,
16.6.1
PROGRESSIVE COMPANIES
16.6.2
RESPONSIVE COMPANIES
16.6.3
DYNAMIC COMPANIES
16.6.4
STARTING BLOCKS
16.6.5
COMPETITIVE BENCHMARKING: STARTUPS/SMES,
16.6.5.1
DETAILED LIST OF KEY STARTUPS/SMES
16.6.5.2
COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
16.7
COMPANY VALUATION & FINANCIAL METRICS
16.8
COMPETITIVE SCENARIO
16.8.1
NEW LAUNCHES
16.8.2
DEALS
16.8.3
OTHER DEVELOPMENTS
17
COMPANY PROFILES (IN-DEPTH REVIEW OF COMPANIES, PRODUCTS, SERVICES, RECENT INITIATIVES, AND POSITIONING STRATEGIES IN THE ENTERPRISE ASSET MANAGEMENT (EAM) MARKET LANDSCAPE
17.1.1
IBM
17.1.2
IFS
17.1.3
SAP
17.1.4
HITACHI ENERGY
17.1.5
SERVICENOW
17.1.6
OCTAVE INTELLIGENCE
17.1.7
SIEMENS
17.1.8
TRIMBLE
17.1.9
ORACLE
17.1.10
CGI
17.1.11
ACCURENT
17.1.12
APTEAN
17.1.13
MAINTAINX
17.1.14
EPTURA
17.1.15
ABS GROUP
17.1.16
LIMBLE CMMS
17.1.17
ASSETWORKS
17.1.18
CENTRALSQUARE TECHNOLOGIES
17.1.19
PRAGMA
17.1.20
UPKEEP
17.1.21
RAMCO SYSTEMS
17.1.22
EMAINT
17.1.23
KLOUDGIN
17.1.24
IDEAGEN
17.1.25
IPS INTELLIGENT PROCESS SOLUTIONS
17.1.26
ASSET PANDA
17.1.27
LLUMIN
17.1.28
ASSET INFINITY
17.1.29
EZMAINTAIN
17.1.30
EPROMIS SOLUTIONS
18
RESEARCH METHODOLOGY
18.1
RESEARCH DATA
18.1.1
SECONDARY DATA
18.1.1.1
KEY DATA FROM SECONDARY SOURCES
18.1.1.2
LIST OF KEY SECONDARY SOURCES
18.1.2
PRIMARY DATA
18.1.2.1
KEY DATA FROM PRIMARY SOURCES
18.1.2.2
KEY PRIMARY PARTICIPANTS
18.1.2.3
BREAKDOWN OF PRIMARY INTERVIEWS
18.1.2.4
KEY INDUSTRY INSIGHTS
18.2
MARKET SIZE ESTIMATION
18.2.1
BOTTOM-UP APPROACH
18.2.2
TOP-DOWN APPROACH
18.2.3
MARKET SIZE CALCULATION FOR BASE YEAR
18.3
MARKET FORECAST APPROACH
18.3.1
SUPPLY SIDE
18.3.2
DEMAND SIDE
18.4
DATA TRIANGULATION
18.5
FACTOR ANALYSIS
18.6
RESEARCH ASSUMPTIONS
18.7
RESEARCH LIMITATIONS
18.8
RISK ASSESSMENT
19
APPENDIX
19.1
DISCUSSION GUIDE
19.2
KNOWLEDGE STORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL
19.3
CUSTOMIZATION OPTIONS
19.4
RELATED REPORTS
19.5
AUTHOR DETAILS
Methodology
This research study on the enterprise asset management market involved extensive secondary sources, including directories, IEEE Communication-Efficient: Algorithms and Systems, and the International Journal of Innovation and Technology Management, as well as paid databases. Primary sources were mainly industry experts from core and related industries, preferred enterprise asset management software providers, third-party service providers, consulting service providers, end users, and other commercial enterprises. In-depth interviews with primary respondents, including key industry participants and subject matter experts, were conducted to gather and verify critical qualitative and quantitative information, as well as assess the market’s prospects.
Secondary Research
In the secondary research process, various sources were referred to identify and collect information for this study. Secondary sources included annual reports, press releases, and investor presentations of companies; white papers, journals, and certified publications; and articles from recognized authors, directories, and databases. The data was also collected from other secondary sources, such as journals, government websites, blogs, and vendors’ websites. Additionally, the enterprise asset management spending of various countries was extracted from the respective sources.
Primary Research
In the primary research process, various sources from the supply and demand sides were interviewed to obtain qualitative and quantitative information on the market. The primary sources from the supply side included various industry experts, such as chief experience officers (CXOs), vice presidents (VPs), and directors specializing in business development, marketing, and enterprise asset management services. It also included key executives from enterprise asset management vendors, system integrators (SIs), professional service providers, industry associations, and other key opinion leaders.
Breakup of Primary Profiles:
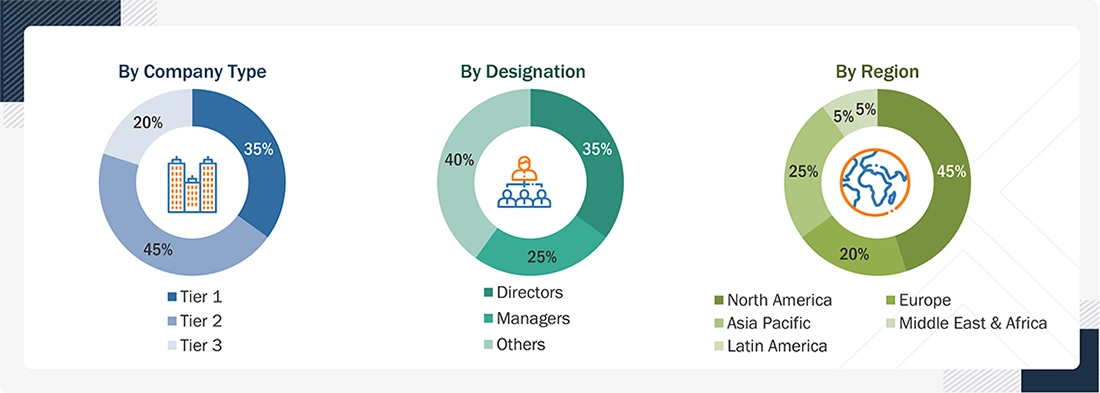
Note: Tier 1 companies’ revenues are more than USD 10 billion; tier 2 companies’ revenues range between USD 1 and 10 billion; and tier 3 companies’ revenues range between USD 500 million and USD 1 billion. Other designations include sales, marketing, and product managers.
Source: Industry Experts
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
Multiple approaches were adopted to estimate and forecast the enterprise asset management market. The first approach involved estimating the market size based on companies’ revenue from the sale of enterprise asset management products.
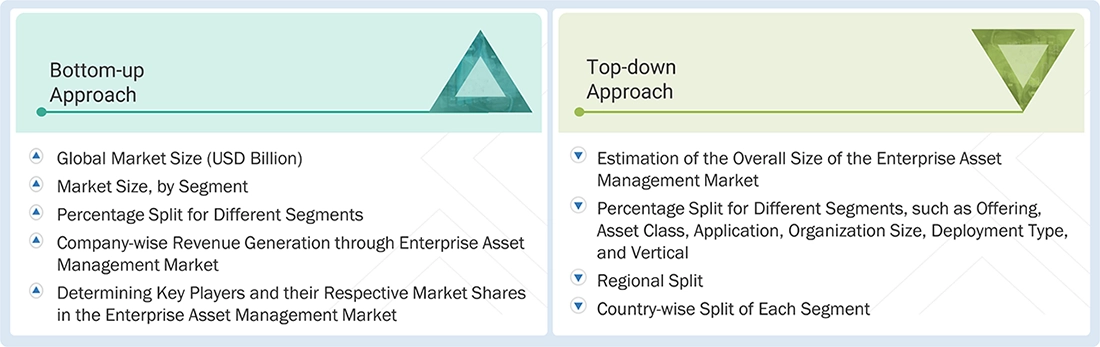
Market Size Estimation Methodology: Top-down Approach
The top-down approach prepared an exhaustive list of all the vendors offering products in the enterprise asset management market. The revenue contribution of the market vendors was estimated through annual reports, press releases, funding, investor presentations, paid databases, and primary interviews. Each vendor’s offerings were evaluated based on offering, platform module, technology, deployment mode, end user, and region. The markets were triangulated through primary and secondary research. The primary procedure included extensive interviews for key insights from industry leaders, such as CIOs, CEOs, VPs, directors, and marketing executives. The market numbers were further triangulated with the existing MarketsandMarkets repository for validation.
Market Size Estimation Methodology: Bottom-up Approach
The bottom-up approach identified the adoption rate of enterprise asset management products across different verticals in key countries, considering the regions that contribute the most to the market share. For cross-validation, the adoption of enterprise asset management products among enterprises and other use cases for their regions was identified and extrapolated. Use cases identified in different areas were weighed for the market size calculation.
Based on the market numbers, the regional split was determined by primary and secondary sources. The procedure included an analysis of the enterprise asset management market’s regional penetration. Based on secondary research, the regional spending on Information and Communications Technology (ICT), socioeconomic analysis of each country, strategic vendor analysis of major enterprise asset management service providers, and organic and inorganic business development activities of regional and global players were estimated.
Enterprise Asset Management Market : Top-Down and Bottom-Up Approach
Data Triangulation
After determining the overall market size using the market size estimation processes as explained above, the market was split into several segments and subsegments. Data triangulation and market breakup procedures were employed, wherever applicable, to complete the overall market engineering process and arrive at the exact statistics of each market segment and subsegment. The overall market size was then used in the top-down approach to estimate the size of other individual markets by applying percentage splits to the market segmentation.
Market Definition
The enterprise asset management market comprises software and services that enable organizations to systematically manage physical assets, including equipment, machinery, vehicles, infrastructure, and facilities, throughout their lifecycle. EAM solutions support asset planning, acquisition, operation, maintenance, performance optimization, and disposal, with capabilities designed to improve asset reliability, operational efficiency, safety, compliance, and lifecycle value.
Key Stakeholders
- Maintenance Managers
- Asset Managers
- Facility Managers
- Operations Managers
- Engineers (Mechanical, Electrical, and Civil)
- IT/Technology Teams
- Procurement Teams
- Safety & Compliance Officers
- Plant/Production Managers
- Service Technicians
- Inventory & Warehouse Managers
- Energy & Utilities Managers
- Project Managers
Report Objectives
- To define, describe, and forecast the enterprise asset management market based on offering (solutions and services), by application (asset lifecycle management, operation management, maintenance management, compliance & safety, reporting & analytics and other applications), by deployment type (cloud, on-premises), by asset class (linear asset, production equipment, fleet & mobility assets, fixed/facility assets/infrastructure, and others) by organization size (large enterprises, small and medium-sized enterprises), by vertical (manufacturing, energy & utilities, oil & gas, transportation & logistics, healthcare & life sciences, government & public sector, and other verticals)
- To provide detailed information on major factors influencing market growth (drivers, restraints, opportunities, and challenges) across enterprise asset management, asset lifecycle management, maintenance management, and aftermarket transformation
- To strategically analyze micro markets with respect to individual growth trends, adoption patterns, and their contribution to the overall enterprise asset management market
- To analyze market opportunities for stakeholders and present a comprehensive competitive landscape of leading enterprise asset management vendors, OEM aftermarket players, and service providers
- To project the market size and its submarkets in terms of value (USD million) across five key regions (North America, Europe, Asia Pacific, Middle East & Africa, Latin America), along with an analysis of their respective major countries
- To strategically profile leading companies and provide an in-depth evaluation of their core competencies, product portfolios, technology capabilities, and market positioning
- To examine competitive developments, including product launches, software upgrades, partnerships, integrations, strategic expansions, and mergers & acquisitions across the enterprise asset management ecosystem
Available customizations:
With the given market data, MarketsandMarkets offers customizations according to the company’s specific needs. The following customization options are available for the report:
Product Analysis
- The product matrix provides a detailed comparison of the product portfolio of each company.
Geographic Analysis based on feasibility
- Further breakup of the North American enterprise asset management market
- Further breakup of the European enterprise asset management market
- Further breakup of the Asia Pacific enterprise asset management market
- Further breakup of the Middle East & Africa enterprise asset management market
- Further breakup of the Latin American enterprise asset management market
Company Information
-
Detailed analysis and profiling of additional market players (up to five)
Key Questions Addressed by the Report
What is enterprise asset management?
Enterprise asset management (EAM) refers to the integrated software and processes used to manage the lifecycle of physical assets such as machinery, equipment, and infrastructure. It helps organizations optimize asset utilization, reduce downtime, and extend asset life.
What are the best strategies for EAM providers to optimize cloud-based solutions for scalability?
EAM providers should focus on developing cloud-based platforms with robust APIs, seamless integrations, and flexible architectures. This ensures scalability to handle growing asset portfolios, improves user adoption, and meets the demand for cost-effective, future-proof solutions across industries.
Which industries are the major adopters of EAM solutions?
Key industries adopting EAM include manufacturing, energy and utilities, transportation, healthcare, and government. These sectors rely heavily on asset-intensive operations where efficiency, safety, and compliance are critical.
What challenges do organizations face in implementing EAM?
Challenges include high upfront costs, complexity in integrating EAM with legacy systems, lack of skilled professionals, and organizational resistance to change. However, cloud-based solutions are helping reduce these barriers.
What steps can EAM providers take to reduce clients’ high upfront implementation costs?
Providers can offer subscription-based pricing, cloud-hosted solutions, and phased implementation plans. These strategies lower initial investment barriers, improve accessibility for SMEs, and drive wider market penetration.
Who are the key vendors in the enterprise asset management market?
The key vendors in the global enterprise asset management market include IBM, Oracle, SAP, Heaxgon, IFS, Aptean, Trimble, ServiceNow, Hitachi Energy, Ramco, Accruent, MaintainX, ABS Group, Central Square, KloudGin, Assetworks, Limble CMMS, Upkeep, Asset Panda, emaint, Asset Infinity, EZmaintain, Llumin, and IPS Intelligent Process Solutions.
Fact checked
Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the Enterprise Asset Management Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Custom Market Research Services
We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements
Get 10% Free CustomisationTESTIMONIALS
- US Enterprise Asset Management Market
- Canada Enterprise Asset Management Market
- UK Enterprise Asset Management Market
- Germany Enterprise Asset Management Market
- France Enterprise Asset Management Market
- Italy Enterprise Asset Management Market
- China Enterprise Asset Management Market
- Japan Enterprise Asset Management Market
- UAE Enterprise Asset Management Market
- Saudi Arabia Enterprise Asset Management Market
- South Africa Enterprise Asset Management Market
- Brazil Enterprise Asset Management Market
- Mexico Enterprise Asset Management Market
- Rest Of Europe Enterprise Asset Management Market
- Rest Of Asia Pacific Enterprise Asset Management Market
- GCC Countries Enterprise Asset Management Market





Growth opportunities and latent adjacency in Enterprise Asset Management Market