PFAS Testing Market by Product Type (Consumables: Columns, Reference Standards, Solvents, Reagents; Instrument, Software), Technology (LC-MS, GC-MS, MS, NMR, ELISA), Application (Wastewater, Potable Water, Food, Soil, Air, Blood) - Global Forecast to 2031

Market Size
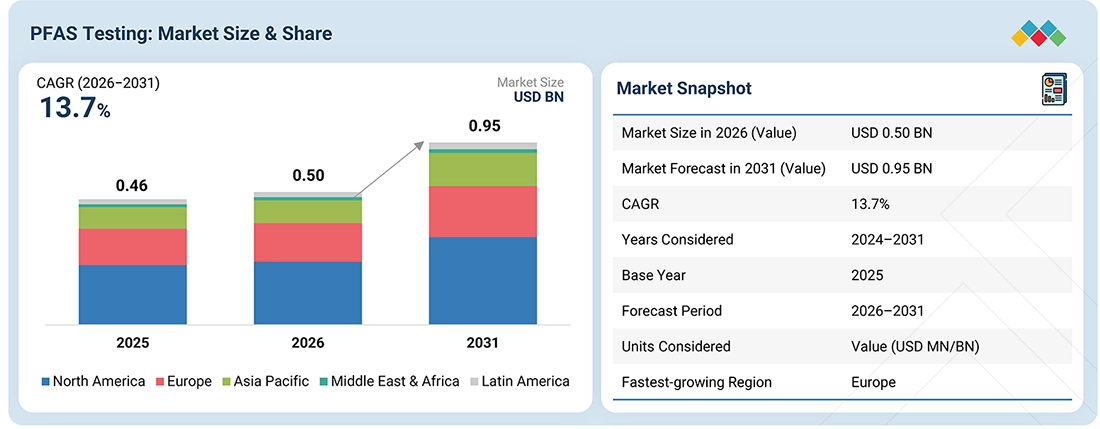
$0.50B
MARKET SIZE, 2026
Projected Market Size
$0.95B
MARKET SIZE, 2031
CAGR
13.7%
CAGR (2026-2031)
Forecast Period
2026-2031
FORECAST PERIOD

PFAS TESTING MARKET SIZE, SHARE & GROWTH SNAPSHOT
pfas-testing-market Overview

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

The global PFAS testing market is projected to grow from USD 0.50 billion in 2026 to USD 0.95 billion by 2031, at a CAGR of 13.7% during the forecast period. The market was valued at USD 0.46 billion in 2025. Investment in the PFAS testing market is increasing across high-sensitivity LC-MS/MS and high-resolution mass spectrometry (HRMS) systems, automated sample-preparation platforms, PFAS-specific chromatography columns, and integrated data-analysis software. This investment is being supported by stricter regulatory requirements, growing demand for lower detection limits, expansion of PFAS analyte panels, and the need to test complex environmental matrices. Laboratories are also investing in automation and high-throughput workflows to improve testing efficiency, reproducibility, and contamination control, creating further opportunities for instrument and consumable providers.

KEY TAKEAWAYS

  • MARKET SNAPSHOT:
    Base Year Market Size (2025): USD 0.46 Billion
    Current Market Size (2026): USD 0.50 Billion
    Forecast Market Size (2031): USD 0.95 Billion
    CAGR (2026–2031): 13.7%
  • SEGMENT LEADERSHIP:
    Regional Leader: North America accounted for the largest share of 47.4% in 2025.
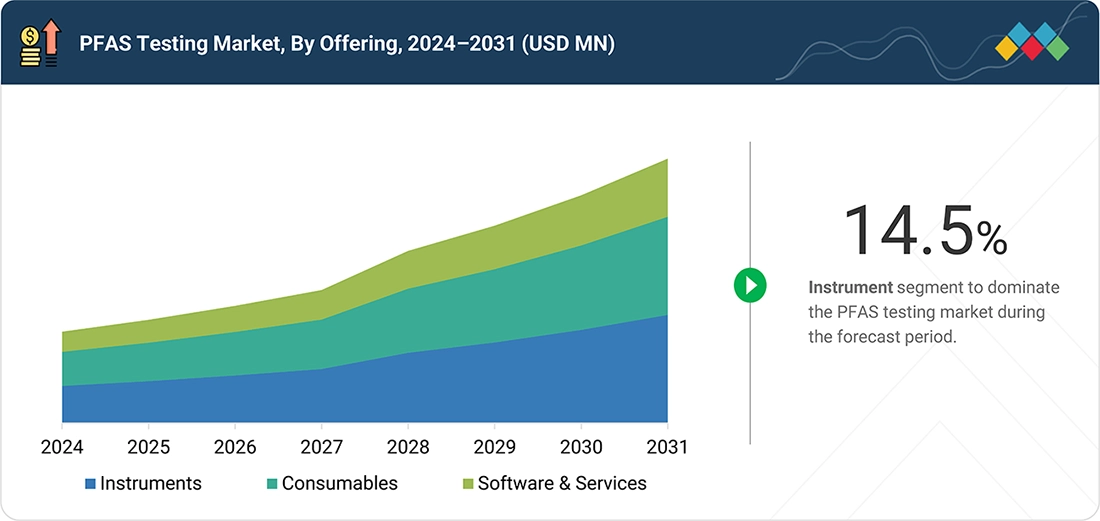
    Product Type Leader: Instruments segment is expected to register the highest CAGR of 14.5%.
    Technique Leader: Liquid chromatography with tandem mass spectrometry (LCMS/MS) is expected to register the highest CAGR of 15.0%.
    Method Leader: EPA segment is expected to grow the fastest.
    Application Leader: Water testing was the largest segment in 2025 with a share of 61.0%.
  • MARKET OUTLOOK & COMPETITIVE LANDSCAPE:
    Thermo Fisher Scientific, Danaher (SCIEX), Agilent Technologies, Waters Corporation, and Shimadzu Corporation are strengthening their positions in the PFAS testing market by offering high-sensitivity LC-MS/MS and high-resolution mass spectrometry platforms, PFAS-specific columns and consumables, automated sample preparation, and integrated data-analysis workflows.
    Absolute Standards, AccuStandard, LC Tech, and LANXESS are strengthening their presence in the PFAS testing market by focusing on specialized reference standards, certified reference materials (CRMs), PFAS-specific analytical consumables, and targeted laboratory solutions rather than competing directly with large analytical-instrument providers.

The PFAS testing market is increasingly driven by the adoption of high-sensitivity LC-MS/MS, automated sample-preparation systems, high-resolution mass spectrometry (HRMS), and integrated chromatography–data-analysis platforms. The expansion of regulatory methods is particularly important: EPA Method 1633A supports the analysis of 40 PFAS compounds across water, soil, biosolids, sediment, landfill leachate, and tissue, increasing demand for instruments capable of multi-compound analysis at very low detection levels. Automation of solid-phase extraction (SPE) is another major growth driver, as laboratories seek higher throughput, improved reproducibility, and reduced manual handling. Thermo Fisher, for example, combines automated SPE with LC-MS/MS for PFAS workflows.

TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS

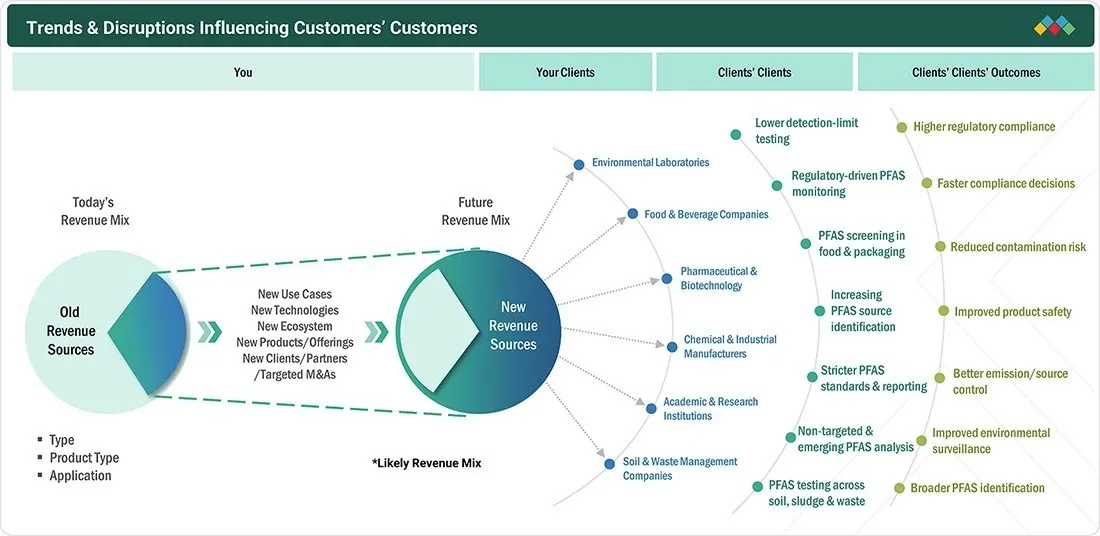
The PFAS testing market is being driven by growing demand from environmental laboratories, food and beverage companies, pharmaceutical and biotechnology organizations, chemical and industrial manufacturers, academic and research institutions, and soil and waste management companies. Key customer trends include the need for lower detection limits, regulatory-driven PFAS monitoring, PFAS screening in food and packaging, PFAS source identification, stricter PFAS standards and reporting, targeted and emerging PFAS analysis, and testing across soil, sludge, and waste. These trends are encouraging adoption of advanced analytical and automated testing solutions, resulting in higher regulatory compliance, faster compliance decisions, reduced contamination risk, improved product safety, better emission and source control, enhanced environmental surveillance, and broader PFAS identification. Overall, the market is shifting toward more sensitive, comprehensive, faster, and regulation-focused PFAS testing, creating opportunities for providers that can deliver reliable low-level detection, broader compound coverage, rapid turnaround, and efficient data reporting.
pfas-testing-market Disruptions

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

MARKET DYNAMICS

Drivers
Impact
Level
  • Increasing implementation of regulations governing PFAS contamination in drinking water and environmental samples
  • Growing investments in water treatment, environmental monitoring, and PFAS remediation programs
RESTRAINTS
Impact
Level
  • High cost of advanced analytical instruments, such as LC-MS/MS, and associated testing consumables
  • Complex sample preparation, testing procedures, and quality-control requirements
OPPORTUNITIES
Impact
Level
  • Increasing funding for PFAS testing and environmental monitoring programs
  • Rising demand for high-throughput, rapid, and non-targeted PFAS testing technologies
CHALLENGES
Impact
Level
  • Lack of harmonized PFAS testing standards and regulatory requirements across countries and regions
  • Continuous introduction and identification of new PFAS compounds creates difficulties in developing comprehensive analytical methods

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Driver: Increasing implementation of regulations governing PFAS contamination in drinking water and environmental samples

The PFAS testing market is primarily driven by the growing implementation of stringent regulations and monitoring requirements for per- and polyfluoroalkyl substances (PFAS) in drinking water, wastewater, groundwater, soil, and industrial environments. Growing awareness of the potential health and environmental risks associated with PFAS contamination is prompting governments, industries, and water utilities to conduct regular testing and monitoring.

Restraint: High cost of advanced analytical instruments, such as LC-MS/MS, and associated testing consumables

High testing costs remain a major restraint for the PFAS testing market. Advanced analytical techniques, particularly LC-MS/MS, require expensive instruments, specialized laboratory infrastructure, high-quality consumables, and skilled technicians. These requirements can increase the overall cost of PFAS analysis and limit adoption among smaller laboratories and organizations with restricted testing budgets.

Opportunity: Increasing funding for PFAS testing and environmental monitoring programs

Increasing government funding for PFAS testing and environmental monitoring is creating significant growth opportunities for the PFAS testing market. In May 2026, the US EPA announced nearly USD 1 billion through the Emerging Contaminants in Small or Disadvantaged Communities program to support PFAS-related drinking water testing, planning, and treatment. Additionally, in July 2026, the EPA allocated USD 30.7 million for training and technical assistance programs supporting PFAS contamination assessment in small and rural communities. These funding initiatives are expected to strengthen PFAS monitoring activities among water utilities, laboratories, and environmental agencies, driving the adoption of advanced analytical instruments and testing services.  

Challenge: Lack of harmonized PFAS testing standards and regulatory requirements across countries and regions

A key challenge is the lack of uniformity in PFAS testing standards and regulatory requirements across countries and regions. Differences in the PFAS compounds monitored, permissible limits, analytical methods, and reporting requirements can make testing procedures more complex. In addition, the continuous identification of new PFAS compounds creates difficulties for laboratories in developing testing methods that can provide comprehensive and reliable PFAS detection.

PFAS TESTING MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES

COMPANY USE CASE DESCRIPTION BENEFITS
company logo
High-resolution analysis for targeted PFAS quantification and screening across environmental and food samples Enables ultra-trace detection, retrospective data analysis, and flexible monitoring as PFAS regulations evolve
company logo
Quantification of PFAS in drinking water and environmental samples using regulatory analytical methods Provides high sensitivity, accuracy, and precision for reliable PFAS measurement and regulatory compliance
company logo
Specialized extraction and sample preparation of PFAS from water, soil, sediment, and wastewater before instrumental analysis Improves recovery, reduces contamination, and enhances consistency of PFAS test results
company logo
Trace-level PFAS detection and quantification across water, soil, consumer products, and environmental matrices Supports ultra-sensitive analysis, rapid multi-component testing, and high laboratory throughput

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET ECOSYSTEM

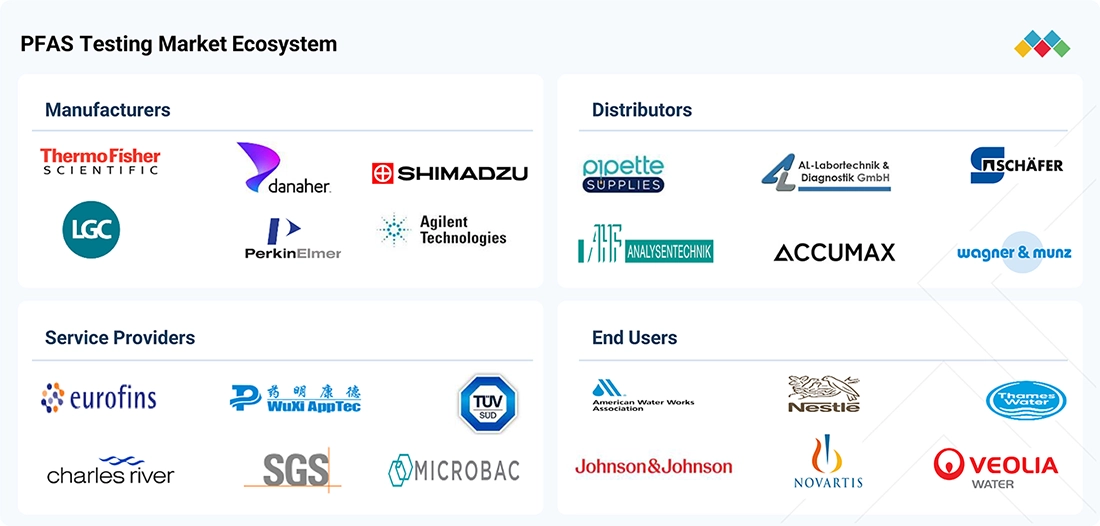
The PFAS testing market ecosystem comprises four key stakeholder groups: manufacturers, distributors, service providers, and end users. Major manufacturers, including Thermo Fisher Scientific, Agilent Technologies, PerkinElmer, Danaher, Shimadzu, and LGC, provide analytical instruments, laboratory technologies, and solutions for PFAS detection and quantification. Distributors, including Pipette Supplies, AL-Labortechnik & Diagnostik, Schäfer, LAB Analysentechnik, Accumax, and Wagner & Munz, support the supply and distribution of laboratory equipment and consumables. Service providers, such as Eurofins, WuXi AppTec, TÜV SÜD, Charles River, SGS, and Microbac, offer outsourced analytical and testing services for environmental, water, food, pharmaceutical, and industrial samples. Key end users include Veolia Water, American Water Works, Nestlé, Johnson & Johnson, Thames Water, and Novartis, representing sectors such as water and wastewater management, food and beverage, pharmaceuticals, and healthcare. Overall, the ecosystem reflects an integrated value chain in which manufacturers supply testing technologies, distributors facilitate access to laboratory solutions, service providers conduct PFAS analysis, and end users drive demand through regulatory compliance, environmental monitoring, contamination assessment, and product safety requirements.
pfas-testing-market Ecosystem

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET SEGMENTS
pfas-testing-market Segments

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

PFAS Testing Market, By Product Type

The PFAS testing instruments market is growing rapidly as laboratories increasingly adopt high-sensitivity LC-MS/MS, high-resolution mass spectrometry (HRMS), automated sample-preparation systems, and advanced chromatography platforms to meet stricter regulatory requirements and achieve lower detection limits. Demand is shifting toward instruments capable of analyzing larger PFAS panels, emerging PFAS compounds, and complex environmental matrices, including drinking water, wastewater, soil, sediment, and biosolids. At the same time, the adoption of automated SPE, high-throughput workflows, PFAS-specific columns, contamination-control components, and integrated data-analysis software is improving testing accuracy, reproducibility, and laboratory efficiency. These trends are expected to drive continued investment in advanced analytical instruments as regulatory monitoring expands globally.

PFAS Testing Market, By Technique

The liquid chromatography–tandem mass spectrometry (LC-MS/MS) segment is expected to remain a key growth driver in the PFAS testing market, supported by its high sensitivity, selectivity, and ability to quantify multiple PFAS compounds at trace levels. The increasing adoption of stringent regulatory methods and expanded PFAS analyte lists is prompting laboratories to upgrade to advanced triple-quadrupole LC-MS/MS systems with improved detection limits and faster analysis. Demand is also rising for automated sample preparation, high-throughput LC-MS/MS workflows, PFAS-specific columns, and integrated software, which help laboratories improve productivity, reproducibility, and data management. In addition, the growing need to analyze PFAS in complex matrices such as wastewater, soil, biosolids, food, and industrial samples is driving further adoption of LC-MS/MS platforms, supporting continued investment in the technology.

PFAS Testing Market, By Method

Methods such as EPA 533 and EPA 537.1 support PFAS analysis in drinking water, while EPA Method 1633/1633A expands testing across wastewater, surface water, groundwater, soil, sediment, biosolids, landfill leachate, and tissue matrices. The expansion from targeted drinking-water testing toward broader environmental monitoring is increasing demand for method-compliant LC-MS/MS systems, automated sample preparation, PFAS-specific columns and standards, and quality-control materials. In addition, ongoing regulatory developments and the need to monitor a broader range of PFAS compounds are encouraging laboratories to upgrade analytical capabilities, driving continued growth in EPA-method-based PFAS testing.

PFAS Testing Market, By Application

The water testing application is expected to remain a major growth driver in the PFAS testing market, supported by rising concerns about PFAS contamination in drinking water, groundwater, surface water, and wastewater. Stricter regulatory requirements and the expansion of PFAS monitoring programs are prompting municipalities, environmental agencies, water utilities, and industrial facilities to increase routine testing and adopt high-sensitivity LC-MS/MS methods capable of detecting PFAS at very low concentrations. Demand is also rising for automated sample preparation, PFAS-specific analytical columns, and standardized EPA methods, particularly as testing shifts from a limited set of regulated compounds to broader PFAS panels. The growing need to identify contamination sources, verify remediation effectiveness, and monitor industrial discharges is expected to further increase the frequency and volume of PFAS water testing.

REGION

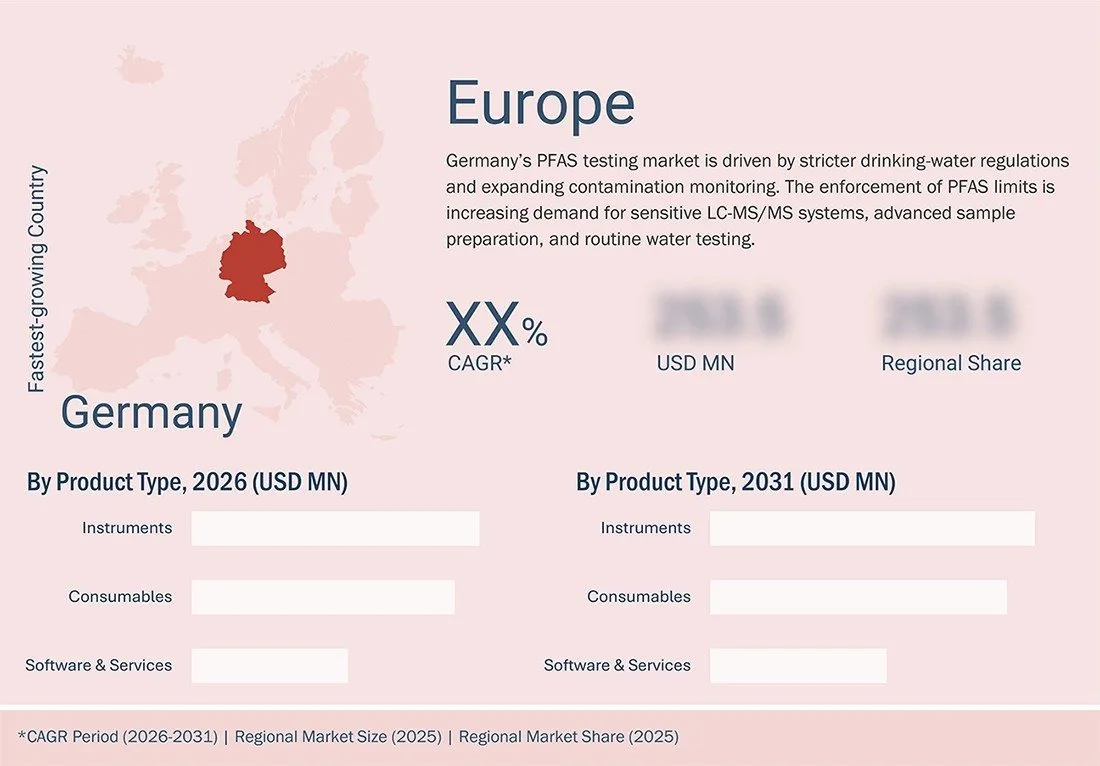
Europe to be fastest-growing region in PFAS testing market during forecast period

Europe’s PFAS water-testing market is witnessing growing demand due to stricter regulatory requirements, expanded environmental monitoring, and increasing concerns about PFAS contamination in drinking water, surface water, and groundwater. Since January 2026, EU Member States have been required to monitor PFAS levels in drinking water and meet regulatory limits for “PFAS Total” and “Sum of PFAS,” increasing the need for accurate and sensitive analytical testing. At the same time, broader monitoring initiatives are encouraging water utilities, environmental agencies, and laboratories to strengthen PFAS surveillance and identify contamination sources. These developments are driving the adoption of LC-MS/MS and high-resolution mass spectrometry, automated sample-preparation technologies, PFAS-specific analytical workflows, and expanded testing panels, creating sustained growth opportunities for PFAS water-testing instruments and services across Europe.
pfas-testing-market Region

PFAS TESTING MARKET: COMPANY EVALUATION MATRIX

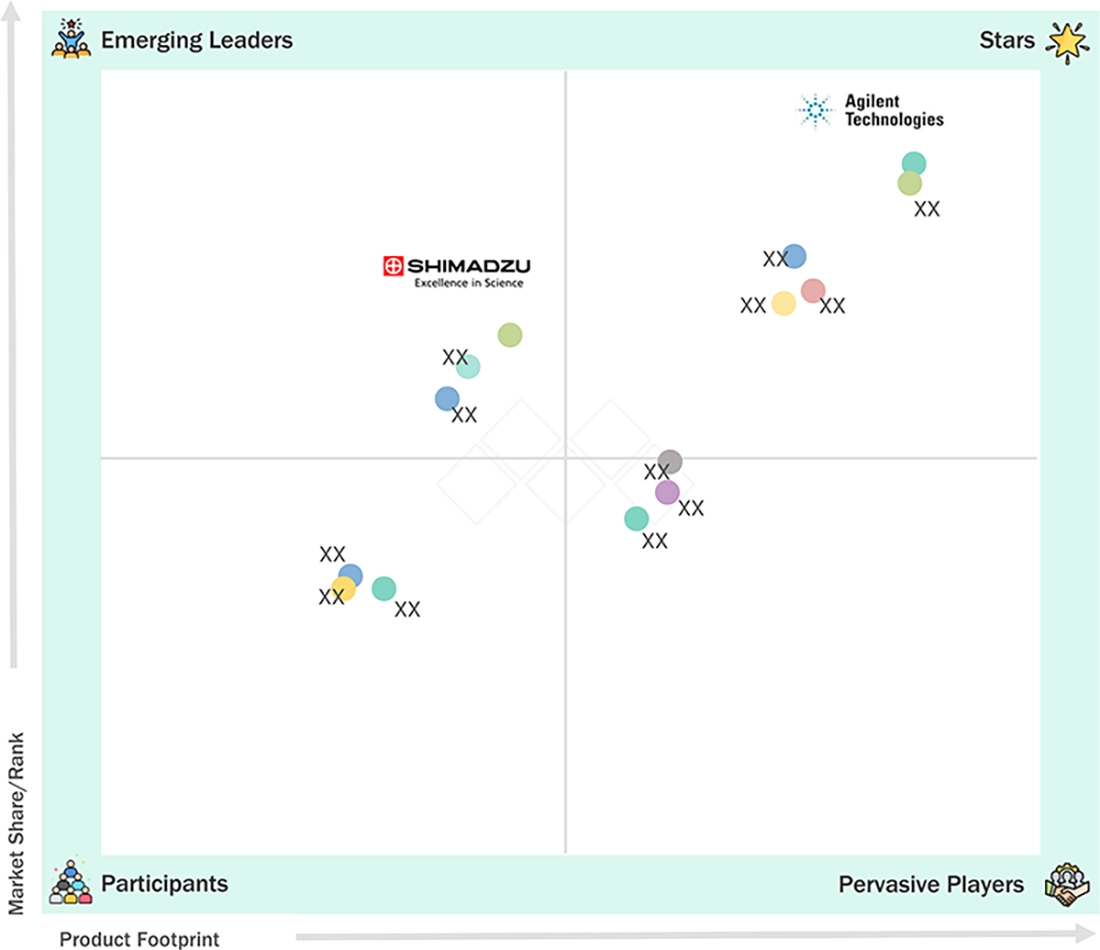
The PFAS testing market can be characterized by the competitive positioning shown in the figure, which divides market participants into Stars, Emerging Leaders, Pervasive Players, and Participants based on market share/rank and overall market presence. Agilent Technologies is positioned as a Star, reflecting a strong competitive position supported by its established analytical instrumentation portfolio and significant presence in PFAS testing solutions. Shimadzu is positioned as an Emerging Leader, reflecting its growing capabilities and increasing market relevance in PFAS analytical testing. Other companies represented in the matrix occupy emerging or participant positions, suggesting varying levels of market penetration, technological capabilities, and competitive strength. Overall, the positioning indicates that the PFAS testing market remains competitive and evolving, with established analytical technology providers maintaining strong positions while other participants continue to strengthen their capabilities in response to increasing PFAS regulations, environmental monitoring requirements, and demand for advanced analytical testing solutions.
pfas-testing-market Evaluation Metrics

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

KEY MARKET PLAYERS

MARKET SCOPE

REPORT METRIC DETAILS
Market Size in 2025 (Value) USD 0.46 Billion
Market Forecast in 2026 (Value) USD 0.50 Billion
Market Forecast in 2031 (Value) USD 0.95 Billion
Growth Rate CAGR of 13.7% from 2026-2031
Years Considered 2024-2031
Base Year 2025
Forecast Period 2026-2031
Units Considered Value (USD Million/Billion)
Report Coverage Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments Covered
  • By Product Type:
    • Instruments
    • Consumables
    • Software & Services
  • By Techniques:
    • Liquid Chromatography With Tandem Mass Spectrometry (LC-MS/MS)
    • Gas Chromatography-Mass Spectrometry (GC-MS)
    • Nuclear Magnetic Resonance Spectroscopy
    • Mass Spectrometry
    • Combustion Ion Chromatography
    • Enzyme-linked Immunosorbent Assay
    • Other Techniques
  • By Method:
    • EPA
    • DIN
    • ISO
    • ASTM
  • By Application:
    • Water Testing
    • Soil Testing
    • Food & Beverages Testing
    • Blood/Serum Testing
    • Air
    • Microbial Testing
    • Other Applications
Country Covered North America, Asia Pacific, Europe, Latin America, Middle East & Africa

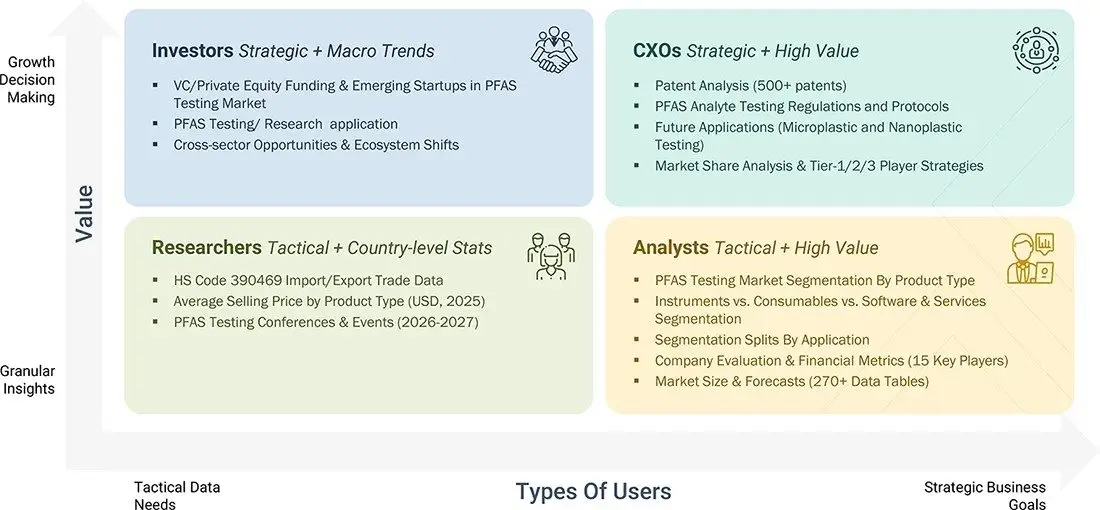
WHAT IS IN IT FOR YOU: PFAS TESTING MARKET REPORT CONTENT GUIDE
pfas-testing-market Content Guide

DELIVERED CUSTOMIZATIONS

We have successfully delivered the following deep-dive customizations:

CLIENT REQUEST CUSTOMIZATION DELIVERED VALUE ADDS
Flexibility in instrument configuration to match diverse research or diagnostic needs Modular and configurable instrument designs Tailored performance for specific applications

RECENT DEVELOPMENTS

  • June 2026 : Agilent Technologies Inc. and Sound Analytics, LLC announced a collaboration to provide an integrated LC/MS triple quadrupole workflow for supporting drug metabolism and pharmacokinetics (DMPK) laboratories in pharmaceutical and biopharmaceutical research.
  • June 2025 : Waters Corporation introduced a new analytical platform that was subsequently incorporated into its PFAS testing workflows, supporting improved sensitivity and longer calibration stability for PFAS analysis.
  • April 2025 : Shimadzu Corporation began local production of its high-end LCMS-8050RX and LCMS-8060RX liquid chromatography–mass spectrometry (LCMS) systems at its Suzhou factory, supporting the localization of advanced mass spectrometry products in China.


Table of Contents

checkmarkExclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.

TITLE
PAGE NO
1
INTRODUCTION


30
2
EXECUTIVE SUMMARY


34
3
PREMIUM INSIGHTS


39
4
MARKET OVERVIEW
Environmental reforms and investment boost water testing, but high costs and skill gaps hinder progress.


43
 
4.1
INTRODUCTION


4.2
MARKET DYNAMICS


4.2.1
DRIVERS


4.2.1.1
REGULATORY REFORMS ADDRESSING ENVIRONMENTAL POLLUTION


4.2.1.2
GROWING CONCERNS OVER PFAS CONTAMINATION IN WATER


4.2.1.3
FAVORABLE INVESTMENT CLIMATE DRIVING IMPROVEMENTS IN TESTING


4.2.1.4
INCREASING FINANCIAL SUPPORT FOR WASTEWATER TREATMENT PROJECTS AND PROGRAMS


4.2.2
RESTRAINTS


4.2.2.1
LIMITED ADOPTION DUE TO HIGH COST OF CONSUMABLES AND MAINTENANCE OF MS INSTRUMENTS


4.2.2.2
STRICT STORAGE REQUIREMENTS FOR PFAS TESTING REAGENTS AND ANALYTICAL STANDARDS


4.2.3
OPPORTUNITIES


4.2.3.1
GROWTH OPPORTUNITIES PRESENTED BY MAJOR MARKETS


4.2.3.2
GROWING FINANCIAL SUPPORT FOR TREATMENT PROJECTS AND PROGRAMS


4.2.3.3
HIGHER PUBLIC AWARENESS REGARDING POLLUTION LEVELS


4.2.4
CHALLENGES


4.2.4.1
LACK OF STANDARDIZED TESTING METHODS ACROSS REGIONS


4.2.4.2
LIMITED AVAILABILITY OF SKILLED LABOR


5
INDUSTRY TRENDS
Explore strategic shifts in PFAS testing driven by advanced technology adoption and market dynamics.


53
 
5.1
PORTER’S FIVE FORCES ANALYSIS


5.1.1
INTENSITY OF COMPETITIVE RIVALRY


5.1.2
BARGAINING POWER OF SUPPLIERS


5.1.3
BARGAINING POWER OF BUYERS


5.1.4
THREAT OF SUBSTITUTES


5.1.5
THREAT OF NEW ENTRANTS


5.2
MACROECONOMIC OUTLOOK


5.2.1
INTRODUCTION


5.2.2
GDP TRENDS AND FORECAST


5.2.3
TRENDS IN GLOBAL PFAS TESTING MARKET


5.2.3.1
GROWING ADOPTION OF ADVANCED LC-MS/MS TECHNOLOGIES


5.2.3.2
INCREASING ADOPTION OF HRMS FOR EMERGING PFAS ANALYSIS


5.2.3.3
GROWING AUTOMATION OF PFAS SAMPLE PREPARATION


5.2.3.4
EXPANSION OF PFAS TESTING ACROSS MULTIPLE SAMPLE MATRICES


5.2.3.5
INCREASING DEMAND FOR BROADER PFAS TESTING PANELS


5.3
VALUE CHAIN ANALYSIS


5.3.1
RESEARCH & DEVELOPMENT


5.3.2
RAW MATERIAL PROCUREMENT


5.3.3
MANUFACTURING


5.3.4
DISTRIBUTION


5.3.5
MARKETING & SALES


5.3.6
POST-SALES SERVICES


5.4
ECOSYSTEM ANALYSIS


5.5
PRICING ANALYSIS


5.5.1
AVERAGE SELLING PRICE TREND OF LC-MS INSTRUMENTS, BY KEY PLAYER, 2025


5.5.2
AVERAGE SELLING PRICE TREND OF PFAS INSTRUMENTS, BY TYPE, 2025


5.5.3
AVERAGE SELLING PRICE TREND, BY REGION, 2023–2025


5.6
TRADE DATA ANALYSIS


5.6.1
IMPORT DATA FOR HS CODE 390460)


5.6.2
EXPORT DATA FOR HS CODE 390460


5.7
KEY CONFERENCES & EVENTS, 2026–2027


5.8
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS


5.9
INVESTMENT & FUNDING SCENARIO


5.10
CASE STUDY ANALYSIS


5.10.1
BUILDING HIGH-SENSITIVITY PFAS TESTING CAPABILITY FOR DRINKING WATER


5.10.2
LARGE-SCALE PFAS MONITORING IN DRINKING WATER


5.10.3
EXPANDING PFAS ANALYSIS IN WASTEWATER AND BIOSOLIDS


5.11
IMPACT OF US TARIFF – PFAS TESTING MARKET


5.11.1
INTRODUCTION


5.11.2
KEY TARIFF RATES


5.11.3
PRICE IMPACT ANALYSIS


5.11.4
IMPACT ON COUNTRIES/REGIONS


5.11.4.1
US


5.11.4.2
EUROPE


5.11.4.3
ASIA PACIFIC


5.11.5
IMPACT ON END USERS


6
STRATEGIC DISRUPTION THROUGH TECHNOLOGY, PATENTS, AND AI ADOPTION
Harness AI and patent insights to revolutionize PFAS testing and environmental monitoring markets.


76
 
6.1
KEY TECHNOLOGIES


6.1.1
CHROMATOGRAPHY


6.1.2
MASS SPECTROMETRY


6.1.3
ION CHROMATOGRAPHY


6.2
COMPLEMENTARY TECHNOLOGIES


6.2.1
TOTAL ORGANIC FLUORINE (TOF) ANALYSIS


6.2.2
AI-BASED IMAGE PROCESSING AND DIAGNOSTIC SOFTWARE


6.3
ADJACENT TECHNOLOGIES


6.3.1
ENVIRONMENTAL MONITORING TECHNOLOGIES


6.3.2
WATER TREATMENT AND FILTRATION TECHNOLOGIES


6.4
PATENT ANALYSIS


6.5
IMPACT OF AI/GEN AI ON PFAS TESTING MARKET


6.5.1
TOP USE CASES AND MARKET POTENTIAL


6.5.2
BEST PRACTICES FOLLOWED BY COMPANIES IN PFAS TESTING MARKET


6.5.3
CASE STUDIES RELATED TO AI/GEN AI IMPLEMENTATION IN PFAS TESTING MARKET


6.5.4
INTERCONNECTED ECOSYSTEM AND IMPACT ON MARKET PLAYERS


6.5.5
CLIENT'S READINESS TO ADOPT AI/GEN AI IN PFAS TESTING MARKET


6.6
SUCCESS STORIES AND REAL-WORLD APPLICATIONS


7
REGULATORY LANDSCAPE
Navigate global regulatory complexities with insights into key agencies across major regions.


85
 
7.1
REGULATORY SCENARIO


7.1.1
REGULATORY LANDSCAPE


7.1.2
REGULATORY GUIDELINES


7.1.2.1
NORTH AMERICA


7.1.2.1.1
US


7.1.2.1.2
CANADA


7.1.2.2
EUROPE


7.1.2.2.1
UK


7.1.2.2.2
FRANCE


7.1.2.2.3
GERMANY


7.1.2.3
ASIA PACIFIC


7.1.2.3.1
CHINA


7.1.2.3.2
JAPAN


7.1.2.3.3
INDIA


7.1.2.4
LATIN AMERICA


7.1.2.4.1
BRAZIL


7.1.2.5
MIDDLE EAST & AFRICA


7.1.2.5.1
UAE
 
8
CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
Understand stakeholder dynamics and unmet needs to optimize PFAS testing adoption strategies.


96
 
8.1
DECISION MAKING PROCESS


8.2
BUYER STAKEHOLDERS & BUYING EVALUATION CRITERIA


8.2.1
KEY STAKEHOLDERS IN BUYING PROCESS


8.2.2
KEY BUYING CRITERIA


8.3
ADOPTION BARRIERS AND INTERNAL CHALLENGES


8.4
UNMET NEEDS FROM VARIOUS END USE CUSTOMERS


9
PFAS TESTING MARKET, BY PRODUCT TYPE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 64 Data Tables


101
 
9.1
INTRODUCTION


9.2
INSTRUMENTS


9.2.1
LIQUID CHROMATOGRAPHY-MASS SPECTROMETRY (LC-MS)


9.2.1.1
ADVANCEMENTS IN LC-MS TO BOOST MARKET


9.2.2
GAS CHROMATOGRAPHY-MASS SPECTROMETRY (GC-MS)


9.2.2.1
STRICT REGULATIONS, ENVIRONMENTAL CONCERNS, AND RISING DEMAND FOR PFAS TESTING TO DRIVE SEGMENTAL GROWTH


9.2.3
STANDALONE MASS SPECTROMETRY


9.2.3.1
STRINGENT REGULATIONS TO DRIVE ADOPTION OF MASS SPECTROMETRY


9.2.4
NUCLEAR MAGNETIC RESONANCE SPECTROSCOPY


9.2.4.1
ADVANCEMENTS IN DRUG DISCOVERY AND STRUCTURAL ANALYSIS TO DRIVE NMR INSTRUMENT GROWTH


9.2.5
OTHER INSTRUMENTS


9.3
CONSUMABLES


9.3.1
SAMPLE PREPARATION PRODUCTS


9.3.1.1
RISING DEMAND FOR HIGH-QUALITY ANALYTICAL RESULTS TO DRIVE GROWTH OF SAMPLE PREPARATION PRODUCTS


9.3.2
CHROMATOGRAPHY COLUMNS


9.3.2.1
INCREASING DEMAND FOR HIGH-PERFORMANCE SEPARATION IN CHROMATOGRAPHY TO DRIVE MARKET GROWTH


9.3.3
REFERENCE MATERIALS & ANALYTICAL STANDARDS


9.3.3.1
STRINGENT REGULATORY STANDARDS AND QUALITY CONTROL REQUIREMENTS TO DRIVE PROPEL GROWTH


9.3.4
SOLVENTS


9.3.4.1
GROWING DEMAND FOR HIGH-PURITY SOLVENTS IN ANALYTICAL TESTING TO FUEL GROWTH


9.3.5
MEMBRANE & SYRINGE FILTERS


9.3.5.1
INCREASING DEMAND FOR SAMPLE PURIFICATION AND CONTAMINATION CONTROL IN LABORATORIES TO BOOST MARKET


9.3.6
REAGENTS


9.3.6.1
RISING DEMAND FOR HIGH-QUALITY REAGENTS IN RESEARCH TO FAVOR GROWTH


9.3.7
OTHER CONSUMABLES


9.4
SOFTWARE & SERVICES


10
PFAS TESTING MARKET, BY TECHNIQUE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 9 Data Tables


139
 
10.1
INTRODUCTION


10.2
LIQUID CHROMATOGRAPHY WITH TANDEM MASS SPECTROMETRY (LC-MS/MS)


10.2.1
PREFERRED ANALYTICAL TECHNIQUE FOR DETECTION AND ANALYSIS OF PFAS COMPOUNDS TO DRIVE MARKET GROWTH


10.3
GAS CHROMATOGRAPHY-MASS SPECTROMETRY (GC-MS)


10.3.1
HIGH COST OF GC INSTRUMENTS AND CONSUMABLES TO LIMIT WIDESPREAD ADOPTION AMONG END USERS


10.4
NUCLEAR MAGNETIC RESONANCE SPECTROSCOPY (NMR SPECTROSCOPY)


10.4.1
DEMAND FOR HIGH-SPEED, ACCURATE, AND RELIABLE DETECTION CAPABILITIES TO FAVOR GROWTH


10.5
MASS SPECTROMETRY


10.5.1
AUTOMATED TECHNIQUES WITH MULTI-ANALYTE PFAS DETECTION CAPABILITIES TO CONTRIBUTE TO GROWTH


10.6
COMBUSTION ION CHROMATOGRAPHY


10.6.1
SHORTAGE OF TRAINED PROFESSIONALS TO OPERATE CHROMATOGRAPHY INSTRUMENTS TO RESTRAIN MARKET GROWTH


10.7
ENZYME-LINKED IMMUNOSORBENT ASSAYS (ELISA)


10.7.1
COST-EFFECTIVE SAMPLE PREPARATION AND USER-FRIENDLY METHODS TO DRIVE ADOPTION


10.8
OTHER TECHNIQUES


11
PFAS TESTING MARKET, BY METHOD
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 12 Data Tables


147
 
11.1
INTRODUCTION


11.2
EPA


11.2.1
GROWING NEED TO MONITOR AND LIMIT PFAS CONTAMINATION IN DRINKING WATER TO DRIVE MARKET GROWTH


11.3
DIN


11.3.1
GROWING CONCERNS ABOUT AIR AND WATER POLLUTION TO DRIVE MARKET GROWTH


11.4
ISO


11.4.1
INCREASING DISCHARGE OF INDUSTRIAL WASTEWATER AND EFFLUENTS TO BOOST GROWTH


11.5
ASTM


11.5.1
GOVERNMENT REGULATIONS AIMED AT CONTROLLING WATER POLLUTION TO FAVOR MARKET GROWTH


11.6
OTHER METHODS


12
PFAS TESTING MARKET, BY APPLICATION
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 11 Data Tables


154
 
12.1
INTRODUCTION


12.2
WATER TESTING


12.2.1
GROUND & POTABLE WATER TESTING


12.2.1.1
RISING DEMAND FOR WATER QUALITY TESTING DRIVEN BY PFAS CONTAMINATION TO BOOST MARKET


12.2.2
WASTEWATER TESTING


12.2.2.1
RISING DEMAND FOR WASTEWATER AND IRRIGATION WATER TESTING TO PROPEL MARKET


12.3
SOIL TESTING


12.3.1
GROWING DEMAND FOR SOIL TESTING TO DRIVE MARKET GROWTH


12.4
FOOD & BEVERAGE TESTING


12.4.1
GROWING DEMAND FOR ADVANCED ANALYTICAL METHODS IN FOOD & BEVERAGE INDUSTRY TO FUEL GROWTH


12.5
BLOOD/SERUM TESTING


12.5.1
EFFORTS BY REGULATORY AGENCIES TO MONITOR AND RESTRICT PFAS CONTAMINATION TO CREATE OPPORTUNITIES


12.6
AIR MONITORING


12.6.1
COLLABORATIVE REGULATORY ACTIONS DRIVING ENVIRONMENTAL REMEDIATION TO AID GROWTH


12.7
MICROBIAL TESTING


12.7.1
GROWING RESEARCH FUNDING TO DRIVE GROWTH


12.8
OTHER APPLICATIONS


13
PFAS TESTING MARKET, BY REGION
Comprehensive coverage of 8 Regions with country-level deep-dive of 14 Countries | 103 Data Tables.


164
 
13.1
INTRODUCTION


13.2
NORTH AMERICA


13.2.1
MACROECONOMIC OUTLOOK FOR NORTH AMERICA


13.2.2
US


13.2.2.1
US TO DOMINATE NORTH AMERICAN PFAS TESTING MARKET


13.2.3
CANADA


13.2.3.1
INCREASING GOVERNMENT FUNDING TO DRIVE ADOPTION OF PFAS TESTING INSTRUMENTS


13.3
EUROPE


13.3.1
MACROECONOMIC OUTLOOK FOR EUROPE


13.3.2
GERMANY


13.3.2.1
GERMANY TO DOMINATE MARKET FOR PFAS TESTING IN EUROPE


13.3.3
UK


13.3.3.1
FAVORABLE FUNDING & INVESTMENT SCENARIO TO DRIVE MARKET GROWTH.


13.3.4
FRANCE


13.3.4.1
RISING INDUSTRIAL CONTAMINANTS & POLLUTION DRIVE MARKET GROWTH


13.3.5
ITALY


13.3.5.1
HIGH LEVELS OF WATER POLLUTION TO OFFER GROWTH OPPORTUNITIES


13.3.6
SPAIN


13.3.6.1
STRICT FOOD REGULATIONS AND HIGH AGRICULTURAL IMPORTS TO DRIVE MARKET GROWTH IN SPAIN


13.3.7
REST OF EUROPE


13.4
ASIA PACIFIC


13.4.1
MACROECONOMIC OUTLOOK FOR ASIA PACIFIC


13.4.2
JAPAN


13.4.2.1
RISING AWARENESS ABOUT ANALYTICAL TECHNOLOGIES TO SUPPORT MARKET GROWTH


13.4.3
CHINA


13.4.3.1
INCREASING R&D EXPENDITURE TO DRIVE MARKET GROWTH


13.4.4
INDIA


13.4.4.1
RISING FUNDING PROGRAMS TO DRIVE MARKET


13.4.5
AUSTRALIA


13.4.5.1
GROWING GOVERNMENT REGULATION TO SUPPORT ADOPTION AND DEVELOPMENT OF ANALYTICAL TECHNOLOGIES


13.4.6
SOUTH KOREA


13.4.6.1
INCREASING ALLIANCES & INVESTMENTS IN RESEARCH TO DRIVE MARKET


13.4.7
REST OF ASIA PACIFIC


13.5
LATIN AMERICA


13.5.1
MACROECONOMIC OUTLOOK FOR LATIN AMERICA


13.5.2
BRAZIL


13.5.2.1
BRAZIL TO DOMINATE LATIN AMERICAN MARKET DURING FORECAST PERIOD


13.5.3
MEXICO


13.5.3.1
STRONG PHARMACEUTICAL INDUSTRY AND INCREASED GOVERNMENT SUPPORT TO AUGMENT MARKET


13.5.4
REST OF LATIN AMERICA


13.6
MIDDLE EAST & AFRICA


13.6.1
MACROECONOMIC OUTLOOK FOR MIDDLE EAST & AFRICA


13.6.2
GCC COUNTRIES


13.6.2.1
LACK OF REGULATIONS FOR PFAS SUBSTANCES TO RESTRICT MARKET GROWTH


13.6.3
REST OF MIDDLE EAST & AFRICA


14
COMPETITIVE LANDSCAPE
Uncover key strategies and market positions shaping PFAS testing industry leaders and emerging players.


226
 
14.1
INTRODUCTION


14.2
KEY PLAYER STRATEGIES/RIGHT TO WIN


14.2.1
OVERVIEW OF STRATEGIES ADOPTED BY PLAYERS IN PFAS TESTING MARKET


14.3
REVENUE ANALYSIS, 2022–2025


14.4
MARKET SHARE ANALYSIS, 2025


14.5
MARKET RANKING ANALYSIS, 2025


14.6
COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025


14.6.1
STARS


14.6.2
EMERGING LEADERS


14.6.3
PERVASIVE PLAYERS


14.6.4
PARTICIPANTS


14.6.5
COMPANY FOOTPRINT: KEY PLAYERS, 2025


14.6.5.1
COMPANY FOOTPRINT


14.6.5.2
REGION FOOTPRINT


14.6.5.3
PRODUCT TYPE FOOTPRINT


14.6.5.4
TECHNIQUE FOOTPRINT


14.6.5.5
METHOD FOOTPRINT


14.6.5.6
APPLICATION FOOTPRINT


14.7
COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025


14.7.1
PROGRESSIVE COMPANIES


14.7.2
RESPONSIVE COMPANIES


14.7.3
DYNAMIC COMPANIES


14.7.4
STARTING BLOCKS


14.7.5
COMPETITIVE BENCHMARKING OF STARTUPS/SMES, 2025


14.7.5.1
DETAILED LIST OF KEY STARTUPS/SMES


14.7.5.2
COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES


14.8
COMPETITIVE SCENARIO


14.8.1
PRODUCT LAUNCHES


14.8.2
DEALS


14.8.3
EXPANSIONS


14.9
COMPANY VALUATION & FINANCIAL METRICS


14.10
BRAND/PRODUCT COMPARISON


15
COMPANY PROFILES
In-depth Company Profiles of Leading Market Players with detailed Business Overview, Product and Service Portfolio, Recent Developments, and Unique Analyst Perspective (MnM View)


250
 
15.1
KEY PLAYERS


15.1.1
AGILENT TECHNOLOGIES, INC.


15.1.1.1
BUSINESS OVERVIEW


15.1.1.2
PRODUCTS OFFERED


15.1.1.3
RECENT DEVELOPMENTS


15.1.1.3.1
PRODUCT LAUNCHES


15.1.1.3.2
DEALS


15.1.1.3.3
EXPANSIONS


15.1.1.4
MNM VIEW


15.1.1.4.1
KEY STRENGTHS


15.1.1.4.2
STRATEGIC CHOICES


15.1.1.4.3
WEAKNESSES & COMPETITIVE THREATS


15.1.2
DANAHER CORPORATION


15.1.3
WATERS CORPORATION


15.1.4
THERMO FISHER SCIENTIFIC INC.


15.1.5
SHIMADZU CORPORATION


15.1.6
MERCK KGAA


15.1.7
PERKINELMER INC.


15.1.8
LGC LIMITED


15.1.9
BIOTAGE


15.1.10
MACHEREY-NAGEL GMBH & CO. KG


15.1.11
ACCUSTANDARD


15.1.12
WELLINGTON LABORATORIES INC.


15.1.13
CAMBRIDGE ISOTOPE LABORATORIES, INC.


15.1.14
CHIRON AS


15.1.15
METROHM INULA GMBH


15.2
OTHER COMPANIES


15.2.1
RESTEK CORPORATION


15.2.2
MICROSAIC


15.2.3
EVONIK


15.2.4
LCTECH


15.2.5
ABSOLUTE STANDARDS INC.


15.2.6
CYTIVA


15.2.7
AVANTOR, INC.


15.2.8
GREYHOUND CHROMATOGRAPHY AND ALLIED CHEMICALS LTD.


15.2.9
LANXESS


15.2.10
THE CHEMOURS COMPANY


16
RESEARCH METHODOLOGY


314
 
16.1
RESEARCH DATA


16.1.1
SECONDARY RESEARCH


16.1.1.1
KEY SECONDARY SOURCES


16.1.1.2
KEY DATA FROM SECONDARY SOURCES


16.1.2
PRIMARY RESEARCH


16.1.2.1
KEY PRIMARY SOURCES


16.1.2.2
KEY SUPPLY- AND DEMAND-SIDE PARTICIPANTS


16.1.2.3
BREAKDOWN OF PRIMARY INTERVIEWS


16.1.2.4
KEY PRIMARY INSIGHTS


16.2
MARKET SIZE ESTIMATION METHODOLOGY


16.2.1
REVENUE MAPPING-BASED MARKET ESTIMATION


16.2.2
END USER-BASED MAPPING MARKET ESTIMATION


16.3
GROWTH FORECASTING MODEL


16.4
DATA TRIANGULATION AND MARKET BREAKDOWN


16.5
RESEARCH ASSUMPTIONS


16.6
RESEARCH LIMITATIONS


16.7
RISK ANALYSIS


17
APPENDIX


327
 
17.1
DISCUSSION GUIDE


17.2
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL


17.3
CUSTOMIZATION OPTIONS


17.4
RELATED REPORTS


17.5
AUTHOR DETAILS


LIST OF TABLES


TABLE 1
PFAS TESTING MARKET: INCLUSIONS & EXCLUSIONS


TABLE 2
WASTEWATER, DRINKING WATER, AND WATER SUPPLY INFRASTRUCTURE: FEDERAL FUNDING FOR PROJECTS AND PROGRAMS


TABLE 3
RESEARCH GRANTS FOR PFAS UPTAKE AND BIOACCUMULATION IN PLANTS AND ANIMALS IN AGRICULTURAL, RURAL, AND TRIBAL COMMUNITIES


TABLE 4
PFAS TESTING MARKET: PORTER’S FIVE FORCES ANALYSIS


TABLE 5
PFAS TESTING MARKET: ROLE OF ECOSYSTEM


TABLE 6
AVERAGE SELLING PRICE TREND OF LC-MS INSTRUMENTS, BY KEY PLAYER, 2023–2025 (USD THOUSAND)


TABLE 7
AVERAGE SELLING PRICE OF INSTRUMENTS, BY REGION, 2023–2025, (USD THOUSAND)


TABLE 8
IMPORT DATA FOR HS CODE 390460-COMPLIANT PRODUCTS, BY COUNTRY, 2021−2025 (USD MILLION)


TABLE 9
EXPORT DATA FOR HS CODE 390460-COMPLIANT PRODUCTS, BY COUNTRY, 2021−2025 (USD THOUSAND)


TABLE 10
LIST OF KEY CONFERENCES AND EVENTS, 2026–2027


TABLE 11
US-ADJUSTED RECIPROCAL TARIFF RATES IN PFAS TESTING INDUSTRY


TABLE 12
ESTIMATED IMPACT OF US TARIFFS ON PRICES OF PFAS TESTING EQUIPMENT AND CONSUMABLES


TABLE 13
PFAS TESTING MARKET: KEY PATENTS, 2022–2026


TABLE 14
KEY COMPANIES IMPLEMENTING AI/GEN AI IN PFAS TESTING MARKET


TABLE 15
KEY APPLICATIONS AND CLINICAL OUTCOMES ENABLED BY PFAS TESTING


TABLE 16
NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 17
EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 18
ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 19
REST OF THE WORLD: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 20
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS (%)


TABLE 21
KEY BUYING CRITERIA FOR PFAS TESTING, BY PRODUCT TYPE


TABLE 22
PFAS TESTING MARKET: UNMET NEEDS


TABLE 23
PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 24
PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 25
PFAS TESTING INSTRUMENTS MARKET, BY REGION, 2024–2031 (USD MILLION)


TABLE 26
NORTH AMERICA: PFAS TESTING INSTRUMENTS MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 27
EUROPE: PFAS TESTING INSTRUMENTS MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 28
ASIA PACIFIC: PFAS TESTING INSTRUMENTS MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 29
PFAS TESTING INSTRUMENTS MARKET FOR LC-MS, BY REGION, 2024–2031 (USD MILLION)


TABLE 30
NORTH AMERICA: PFAS TESTING INSTRUMENTS MARKET FOR LC-MS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 31
EUROPE: PFAS TESTING INSTRUMENTS MARKET FOR LC-MS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 32
ASIA PACIFIC: PFAS TESTING INSTRUMENTS MARKET FOR LC-MS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 33
PFAS TESTING INSTRUMENTS MARKET FOR GC-MS, BY REGION, 2024–2031 (USD MILLION)


TABLE 34
NORTH AMERICA: PFAS TESTING INSTRUMENTS MARKET FOR GC-MS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 35
EUROPE: PFAS TESTING INSTRUMENTS MARKET FOR GC-MS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 36
ASIA PACIFIC: PFAS TESTING INSTRUMENTS MARKET FOR GC-MS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 37
PFAS TESTING INSTRUMENTS MARKET FOR STANDALONE MASS SPECTROMETRY, BY REGION, 2024–2031 (USD MILLION)


TABLE 38
NORTH AMERICA: PFAS TESTING INSTRUMENTS MARKET FOR STANDALONE MASS SPECTROMETRY, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 39
EUROPE: PFAS TESTING INSTRUMENTS MARKET FOR STANDALONE MASS SPECTROMETRY, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 40
ASIA PACIFIC: PFAS TESTING INSTRUMENTS MARKET FOR STANDALONE MASS SPECTROMETRY, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 41
PFAS TESTING INSTRUMENTS MARKET FOR NUCLEAR MAGNETIC RESONANCE SPECTROSCOPY, BY REGION, 2024–2031 (USD MILLION)


TABLE 42
NORTH AMERICA: PFAS TESTING INSTRUMENTS MARKET FOR NUCLEAR MAGNETIC RESONANCE SPECTROSCOPY, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 43
EUROPE: PFAS TESTING INSTRUMENTS MARKET FOR NUCLEAR MAGNETIC RESONANCE SPECTROSCOPY, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 44
ASIA PACIFIC: PFAS TESTING INSTRUMENTS MARKET FOR NUCLEAR MAGNETIC RESONANCE SPECTROSCOPY, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 45
OTHER PFAS TESTING INSTRUMENTS MARKET, BY REGION, 2 024–2031 (USD MILLION)


TABLE 46
NORTH AMERICA: OTHER PFAS TESTING INSTRUMENTS MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 47
EUROPE: OTHER PFAS TESTING INSTRUMENTS MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 48
ASIA PACIFIC: OTHER PFAS TESTING INSTRUMENTS MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 49
PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 50
PFAS TESTING CONSUMABLES MARKET, BY REGION, 2024–2031 (USD MILLION)


TABLE 51
NORTH AMERICA: PFAS TESTING CONSUMABLES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 52
EUROPE: PFAS TESTING CONSUMABLES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 53
ASIA PACIFIC: PFAS TESTING CONSUMABLES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 54
PFAS TESTING CONSUMABLES MARKET FOR SAMPLE PREPARATION PRODUCTS, BY REGION, 2024–2031 (USD MILLION)


TABLE 55
NORTH AMERICA: PFAS TESTING CONSUMABLES MARKET FOR SAMPLE PREPARATION PRODUCTS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 56
EUROPE: PFAS TESTING CONSUMABLES MARKET FOR SAMPLE PREPARATION PRODUCTS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 57
ASIA PACIFIC: PFAS TESTING CONSUMABLES MARKET FOR SAMPLE PREPARATION PRODUCTS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 58
PFAS TESTING CONSUMABLES MARKET FOR CHROMATOGRAPHY COLUMNS, BY REGION, 2024–2031 (USD MILLION)


TABLE 59
NORTH AMERICA: PFAS TESTING CONSUMABLES MARKET FOR CHROMATOGRAPHY COLUMNS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 60
EUROPE: PFAS TESTING CONSUMABLES MARKET FOR CHROMATOGRAPHY COLUMNS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 61
ASIA PACIFIC: PFAS TESTING CONSUMABLES MARKET FOR CHROMATOGRAPHY COLUMNS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 62
TOTAL NUMBER OF PFAS TESTS PERFORMED WORLDWIDE, BY REGION, 2024


TABLE 63
PFAS TESTING CONSUMABLES MARKET FOR REFERENCE MATERIALS & ANALYTICAL STANDARDS, BY REGION, 2024–2031 (USD MILLION)


TABLE 64
NORTH AMERICA: PFAS TESTING CONSUMABLES MARKET FOR REFERENCE MATERIALS & ANALYTICAL STANDARDS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 65
EUROPE: PFAS TESTING CONSUMABLES MARKET FOR REFERENCE MATERIALS & ANALYTICAL STANDARDS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 66
ASIA PACIFIC: PFAS TESTING CONSUMABLES MARKET FOR REFERENCE MATERIALS & ANALYTICAL STANDARDS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 67
PFAS TESTING CONSUMABLES MARKET FOR SOLVENTS, BY REGION, 2024–2031 (USD MILLION)


TABLE 68
NORTH AMERICA: PFAS TESTING CONSUMABLES MARKET FOR SOLVENTS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 69
EUROPE: PFAS TESTING CONSUMABLES MARKET FOR SOLVENTS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 70
ASIA PACIFIC: PFAS TESTING CONSUMABLES MARKET FOR SOLVENTS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 71
PFAS TESTING CONSUMABLES MARKET FOR MEMBRANE & SYRINGE FILTERS, BY REGION, 2024–2031 (USD MILLION)


TABLE 72
NORTH AMERICA: PFAS TESTING CONSUMABLES MARKET FOR MEMBRANE & SYRINGE FILTERS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 73
EUROPE: PFAS TESTING CONSUMABLES MARKET FOR MEMBRANE & SYRINGE FILTERS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 74
ASIA PACIFIC: PFAS TESTING CONSUMABLES MARKET FOR MEMBRANE & SYRINGE FILTERS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 75
PFAS TESTING CONSUMABLES MARKET FOR REAGENTS, BY REGION, 2024–2031 (USD MILLION)


TABLE 76
NORTH AMERICA: PFAS TESTING CONSUMABLES MARKET FOR REAGENTS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 77
EUROPE: PFAS TESTING CONSUMABLES MARKET FOR REAGENTS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 78
ASIA PACIFIC: PFAS TESTING CONSUMABLES MARKET FOR REAGENTS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 79
OTHER PFAS TESTING CONSUMABLES MARKET, BY REGION, 2024–2031 (USD MILLION)


TABLE 80
NORTH AMERICA: OTHER PFAS TESTING CONSUMABLES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 81
EUROPE: OTHER PFAS TESTING CONSUMABLES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 82
ASIA PACIFIC: OTHER PFAS TESTING CONSUMABLES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 83
PFAS TESTING SOFTWARE & SERVICES MARKET, BY REGION, 2024–2031 (USD MILLION)


TABLE 84
NORTH AMERICA: PFAS TESTING SOFTWARE & SERVICES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 85
EUROPE: PFAS TESTING SOFTWARE & SERVICES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 86
ASIA PACIFIC: PFAS TESTING SOFTWARE & SERVICES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 87
PFAS TESTING MARKET, BY TECHNIQUE, 2024–2031 (USD MILLION)


TABLE 88
PFAS TESTING TECHNIQUES MARKET, BY REGION, 2024–2031 (USD MILLION)


TABLE 89
PFAS TESTING MARKET FOR LC-MS/MS, BY REGION, 2024–2031 (USD MILLION)


TABLE 90
PFAS TESTING MARKET FOR GC-MS, BY REGION, 2024–2031 (USD MILLION)


TABLE 91
PFAS TESTING MARKET FOR NMR SPECTROSCOPY, BY REGION, 2024–2031 (USD MILLION)


TABLE 92
PFAS TESTING MARKET FOR MASS SPECTROMETRY, BY REGION, 2024–2031 (USD MILLION)


TABLE 93
PFAS TESTING MARKET FOR COMBUSTION ION CHROMATOGRAPHY, BY REGION, 2024–2031 (USD MILLION)


TABLE 94
PFAS TESTING MARKET FOR ELISA, BY REGION, 2024–2031 (USD MILLION)


TABLE 95
PFAS TESTING MARKET FOR OTHER TECHNIQUES, BY REGION, 2024–2031 (USD MILLION)


TABLE 96
PFAS TESTING MARKET, BY METHOD, 2024–2031 (USD MILLION)


TABLE 97
PFAS TESTING METHODS MARKET, BY REGION, 2024–2031 (USD MILLION)


TABLE 98
APPLICATIONS OF EPA METHODS FOR PFAS TESTING ACROSS VARIOUS SAMPLE TYPES


TABLE 99
PFAS TESTING MARKET FOR EPA METHODS, BY REGION, 2024–2031 (USD MILLION)


TABLE 100
APPLICATIONS OF DIN METHODS FOR PFAS TESTING ACROSS VARIOUS SAMPLE TYPES


TABLE 101
PFAS TESTING MARKET FOR DIN METHODS, BY REGION, 2024–2031 (USD MILLION)


TABLE 102
APPLICATIONS OF ISO METHODS FOR PFAS TESTING ACROSS VARIOUS SAMPLE TYPES


TABLE 103
PFAS TESTING MARKET FOR ISO METHODS, BY REGION, 2024–2031 (USD MILLION)


TABLE 104
APPLICATIONS OF ASTM METHODS FOR PFAS TESTING ACROSS VARIOUS SAMPLE TYPES


TABLE 105
PFAS TESTING MARKET FOR ASTM METHODS, BY REGION, 2024–2031 (USD MILLION)


TABLE 106
APPLICATIONS OF OTHER METHODS FOR PFAS TESTING ACROSS VARIOUS SAMPLE TYPES


TABLE 107
PFAS TESTING MARKET FOR OTHER METHODS, BY REGION, 2024–2031 (USD MILLION)


TABLE 108
PFAS TESTING MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 109
PFAS TESTING APPLICATIONS MARKET, BY REGION, 2024–2031 (USD MILLION)


TABLE 110
PFAS TESTING MARKET FOR WATER TESTING APPLICATIONS, BY TYPE, 2024–2031 (USD MILLION)


TABLE 111
PFAS TESTING MARKET FOR GROUND & POTABLE WATER TESTING APPLICATIONS, BY REGION, 2024–2031 (USD MILLION)


TABLE 112
PFAS TESTING MARKET FOR WASTEWATER TESTING APPLICATIONS, BY REGION, 2024–2031 (USD MILLION)


TABLE 113
PFAS TESTING MARKET FOR SOIL TESTING APPLICATIONS, BY REGION, 2024–2031 (USD MILLION)


TABLE 114
PFAS TESTING MARKET FOR FOOD & BEVERAGE TESTING APPLICATIONS, BY REGION, 2024–2031 (USD MILLION)


TABLE 115
PFAS TESTING MARKET FOR BLOOD/SERUM TESTING APPLICATIONS, BY REGION, 2024–2031 (USD MILLION)


TABLE 116
PFAS TESTING MARKET FOR AIR MONITORING APPLICATIONS, BY REGION, 2024–2031 (USD MILLION)


TABLE 117
PFAS TESTING MARKET FOR MICROBIAL TESTING APPLICATIONS, BY REGION, 2024–2031 (USD MILLION)


TABLE 118
PFAS TESTING MARKET FOR OTHER APPLICATIONS, BY REGION, 2024–2031 (USD MILLION)


TABLE 119
PFAS TESTING MARKET, BY REGION, 2024–2031 (USD MILLION)


TABLE 120
NORTH AMERICA: PFAS TESTING MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 121
NORTH AMERICA: PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 122
NORTH AMERICA: PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 123
NORTH AMERICA: PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 124
NORTH AMERICA: PFAS TESTING MARKET, BY TECHNIQUE, 2024–2031 (USD MILLION)


TABLE 125
NORTH AMERICA: PFAS TESTING MARKET, BY METHOD, 2024–2031 (USD MILLION)


TABLE 126
NORTH AMERICA: PFAS TESTING MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 127
NORTH AMERICA: PFAS TESTING MARKET FOR WATER TESTING APPLICATIONS, BY TYPE, 2024–2031 (USD MILLION)


TABLE 128
MACROECONOMIC OUTLOOK FOR NORTH AMERICA


TABLE 129
US: PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 130
US: PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 131
US: PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 132
CANADA: PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 133
CANADA: PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 134
CANADA: PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 135
EUROPE: PFAS TESTING MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 136
EUROPE: PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 137
EUROPE: PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 138
EUROPE: PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 139
EUROPE: PFAS TESTING MARKET, BY TECHNIQUE, 2024–2031 (USD MILLION)


TABLE 140
EUROPE: PFAS TESTING MARKET, BY METHOD, 2024–2031 (USD MILLION)


TABLE 141
EUROPE: PFAS TESTING MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 142
EUROPE: PFAS TESTING MARKET FOR WATER TESTING APPLICATIONS, BY TYPE, 2024–2031 (USD MILLION)


TABLE 143
MACROECONOMIC OUTLOOK FOR EUROPE


TABLE 144
GERMANY: PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 145
GERMANY: PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 146
GERMANY: PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 147
UK: PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 148
UK: PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 149
UK: PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 150
FRANCE: PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 151
FRANCE: PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 152
FRANCE: PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 153
ITALY: PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 154
ITALY: PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 155
ITALY: PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 156
SPAIN: PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 157
SPAIN: PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 158
SPAIN: PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 159
REST OF EUROPE: PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 160
REST OF EUROPE: PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 161
REST OF EUROPE: PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 162
ASIA PACIFIC: PFAS TESTING MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 163
ASIA PACIFIC: PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 164
ASIA PACIFIC: PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 165
ASIA PACIFIC: PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 166
ASIA PACIFIC: PFAS TESTING MARKET, BY TECHNIQUE, 2024–2031 (USD MILLION)


TABLE 167
ASIA PACIFIC: PFAS TESTING MARKET, BY METHOD, 2024–2031 (USD MILLION)


TABLE 168
ASIA PACIFIC: PFAS TESTING MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 169
ASIA PACIFIC: PFAS TESTING MARKET FOR WATER TESTING APPLICATIONS, BY TYPE, 2024–2031 (USD MILLION)


TABLE 170
MACROECONOMIC OUTLOOK FOR ASIA PACIFIC


TABLE 171
JAPAN: PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 172
JAPAN: PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 173
JAPAN: PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 174
CHINA: PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 175
CHINA: PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 176
CHINA: PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 177
INDIA: PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 178
INDIA: PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 179
INDIA: PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 180
AUSTRALIA: PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 181
AUSTRALIA: PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 182
AUSTRALIA: PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 183
SOUTH KOREA: PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 184
SOUTH KOREA: PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 185
SOUTH KOREA: PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 186
REST OF ASIA PACIFIC: PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 187
REST OF ASIA PACIFIC: PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 188
REST OF ASIA PACIFIC: PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 189
LATIN AMERICA: PFAS TESTING MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 190
LATIN AMERICA: PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 191
LATIN AMERICA: PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 192
LATIN AMERICA: PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 193
LATIN AMERICA: PFAS TESTING MARKET, BY TECHNIQUE, 2024–2031 (USD MILLION)


TABLE 194
LATIN AMERICA: PFAS TESTING MARKET, BY METHOD, 2024–2031 (USD MILLION)


TABLE 195
LATIN AMERICA: PFAS TESTING MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 196
LATIN AMERICA: PFAS TESTING MARKET FOR WATER TESTING APPLICATIONS, BY TYPE, 2024–2031 (USD MILLION)


TABLE 197
MACROECONOMIC OUTLOOK FOR LATIN AMERICA


TABLE 198
BRAZIL: PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 199
BRAZIL: PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 200
BRAZIL: PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 201
MEXICO: PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 202
MEXICO: PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 203
MEXICO: PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 204
REST OF LATIN AMERICA: PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 205
REST OF LATIN AMERICA: PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 206
REST OF LATIN AMERICA: PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 207
MIDDLE EAST & AFRICA: PFAS TESTING MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 208
MIDDLE EAST & AFRICA: PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 209
MIDDLE EAST & AFRICA: PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 210
MIDDLE EAST & AFRICA: PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 211
MIDDLE EAST & AFRICA: PFAS TESTING MARKET, BY TECHNIQUE, 2024–2031 (USD MILLION)


TABLE 212
MIDDLE EAST & AFRICA: PFAS TESTING MARKET, BY METHOD, 2024–2031 (USD MILLION)


TABLE 213
MIDDLE EAST & AFRICA: PFAS TESTING MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 214
MIDDLE EAST & AFRICA: PFAS TESTING MARKET FOR WATER TESTING APPLICATIONS, BY TYPE, 2024–2031 (USD MILLION)


TABLE 215
MACROECONOMIC OUTLOOK FOR MIDDLE EAST & AFRICA


TABLE 216
GCC COUNTRIES: PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 217
GCC COUNTRIES: PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 218
GCC COUNTRIES: PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 219
REST OF MIDDLE EAST & AFRICA: PFAS TESTING MARKET, BY PRODUCT TYPE, 2024–2031 (USD MILLION)


TABLE 220
REST OF MIDDLE EAST & AFRICA: PFAS TESTING INSTRUMENTS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 221
REST OF MIDDLE EAST & AFRICA: PFAS TESTING CONSUMABLES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 222
OVERVIEW OF STRATEGIES ADOPTED BY PLAYERS IN PFAS TESTING MARKET


TABLE 223
PFAS TESTING MARKET: DEGREE OF COMPETITION


TABLE 224
PFAS TESTING MARKET: REGION FOOTPRINT


TABLE 225
PFAS TESTING MARKET: PRODUCT TYPE FOOTPRINT


TABLE 226
PFAS TESTING MARKET: TECHNIQUE FOOTPRINT


TABLE 227
PFAS TESTING MARKET: METHOD FOOTPRINT


TABLE 228
PFAS TESTING MARKET: APPLICATION FOOTPRINT


TABLE 229
PFAS TESTING MARKET: DETAILED LIST OF KEYS STARTUPS/SMES


TABLE 230
PFAS TESTING MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES


TABLE 231
PFAS TESTING MARKET: PRODUCT LAUNCHES, JANUARY 2022–SEPTEMBER 2026


TABLE 232
PFAS TESTING MARKET: DEALS, JANUARY 2022–SEPTEMBER 2026


TABLE 233
PFAS TESTING MARKET: EXPANSIONS, JANUARY 2022–SEPTEMBER 2026


TABLE 234
AGILENT TECHNOLOGIES, INC.: COMPANY OVERVIEW


TABLE 235
AGILENT TECHNOLOGIES, INC.: PRODUCTS OFFERED


TABLE 236
AGILENT TECHNOLOGIES, INC.: PRODUCT LAUNCHES, JANUARY 2022–SEPTEMBER 2026


TABLE 237
AGILENT TECHNOLOGIES, INC.: DEALS, JANUARY 2022–SEPTEMBER 2026


TABLE 238
AGILENT TECHNOLOGIES, INC.: EXPANSIONS, JANUARY 2022–SEPTEMBER 2026


TABLE 239
DANAHER CORPORATION: COMPANY OVERVIEW


TABLE 240
PHENOMENEX INC.: PRODUCTS OFFERED


TABLE 241
SCIEX: PRODUCTS OFFERED


TABLE 242
DANAHER CORPORATION: PRODUCT LAUNCHES, JANUARY 2022–SEPTEMBER 2026


TABLE 243
DANAHER CORPORATION: DEALS, JANUARY 2022–SEPTEMBER 2026


TABLE 244
WATERS CORPORATION: COMPANY OVERVIEW


TABLE 245
WATERS CORPORATION: PRODUCTS OFFERED


TABLE 246
WATERS CORPORATION: PRODUCT LAUNCHES, JANUARY 2022–SEPTEMBER 2026


TABLE 247
THERMO FISHER SCIENTIFIC INC.: COMPANY OVERVIEW


TABLE 248
THERMO FISHER SCIENTIFIC INC.: PRODUCTS OFFERED


TABLE 249
THERMO FISHER SCIENTIFIC INC.: PRODUCT LAUNCHES, JANUARY 2022–SEPTEMBER 2026


TABLE 250
SHIMADZU CORPORATION: EXPANSIONS, JANUARY 2022–SEPTEMBER 2026


TABLE 251
SHIMADZU CORPORATION: COMPANY OVERVIEW


TABLE 252
SHIMADZU CORPORATION: PRODUCTS OFFERED


TABLE 253
SHIMADZU CORPORATION: PRODUCT LAUNCHES, JANUARY 2022–SEPTEMBER 2026


TABLE 254
SHIMADZU CORPORATION: EXPANSIONS, JANUARY 2022–SEPTEMBER 2026


TABLE 255
MERCK KGAA: COMPANY OVERVIEW


TABLE 256
MERCK KGAA: PRODUCTS OFFERED


TABLE 257
MERCK KGAA: DEALS, JANUARY 2022–SEPTEMBER 2026


TABLE 258
MERCK KGAA: EXPANSIONS, JANUARY 2022–SEPTEMBER 2026


TABLE 259
PERKINELMER INC.: COMPANY OVERVIEW


TABLE 260
PERKINELMER INC.: PRODUCTS OFFERED


TABLE 261
PERKINELMER INC: PRODUCT LAUNCHES, JANUARY 2022–SEPTEMBER 2026


TABLE 262
PERKINELMER INC: DEALS, JANUARY 2022–SEPTEMBER 2026


TABLE 263
LGC LIMITED: COMPANY OVERVIEW


TABLE 264
LGC LIMITED: PRODUCTS OFFERED


TABLE 265
LGC LIMITED: PRODUCT LAUNCHES, JANUARY 2022–SEPTEMBER 2026


TABLE 266
LGC LIMITED: DEALS, JANUARY 2022–SEPTEMBER 2026


TABLE 267
LGC LIMITED: EXPANSIONS, JANUARY 2022–SEPTEMBER 2026


TABLE 268
BIOTAGE: COMPANY OVERVIEW


TABLE 269
BIOTAGE: PRODUCTS OFFERED


TABLE 270
BIOTAGE: PRODUCT LAUNCHES, JANUARY 2022–SEPTEMBER 2026


TABLE 271
BIOTAGE: EXPANSIONS, JANUARY 2022–SEPTEMBER 2026


TABLE 272
MACHEREY-NAGEL GMBH & CO. KG: COMPANY OVERVIEW


TABLE 273
MACHEREY-NAGEL GMBH & CO. KG: PRODUCTS OFFERED


TABLE 274
MACHEREY-NAGEL GMBH & CO. KG: PRODUCT LAUNCHES, JANUARY 2022-SEPTEMBER 2026


TABLE 275
ACCUSTANDARD: COMPANY OVERVIEW


TABLE 276
ACCUSTANDARD: PRODUCTS OFFERED


TABLE 277
ACCUSTANDARD: PRODUCT LAUNCHES, JANUARY 2022–SEPTEMBER 2026


TABLE 278
WELLINGTON LABORATORIES INC.: COMPANY OVERVIEW


TABLE 279
WELLINGTON LABORATORIES INC.: PRODUCTS OFFERED


TABLE 280
WELLINGTON LABORATORIES INC.: PRODUCT LAUNCHES, JANUARY 2022–SEPTEMBER 2026


TABLE 281
CAMBRIDGE ISOTOPE LABORATORIES, INC.: COMPANY OVERVIEW


TABLE 282
CAMBRIDGE ISOTOPE LABORATORIES, INC.: PRODUCTS OFFERED


TABLE 283
CAMBRIDGE ISOTOPE LABORATORIES, INC.: EXPANSIONS, JANUARY 2022–SEPTEMBER 2026


TABLE 284
CHIRON AS: COMPANY OVERVIEW


TABLE 285
CHIRON AS: PRODUCTS OFFERED


TABLE 286
METROHM INULA GMBH: COMPANY OVERVIEW


TABLE 287
METROHM INULA GMBH: PRODUCTS OFFERED


TABLE 288
PFAS TESTING MARKET: RISK ANALYSIS


LIST OF FIGURES


FIGURE 1
PFAS TESTING MARKET SEGMENTATION AND REGIONAL SCOPE


FIGURE 2
PFAS TESTING MARKET: YEARS CONSIDERED


FIGURE 3
MARKET SCENARIO


FIGURE 4
GLOBAL PFAS TESTING MARKET, 2024–2031


FIGURE 5
MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN PFAS TESTING MARKET, 2022–2026


FIGURE 6
DISRUPTIONS INFLUENCING GROWTH OF PFAS TESTING MARKET


FIGURE 7
HIGH-GROWTH SEGMENTS IN PFAS TESTING MARKET, 2026–2031


FIGURE 8
ASIA PACIFIC TO REGISTER HIGHEST CAGR IN PFAS TESTING MARKET DURING FORECAST PERIOD


FIGURE 9
RISING PFAS CONTAMINATION CONCERNS IN WATER INCREASE DEMAND FOR SENSITIVE ANALYTICAL TESTING


FIGURE 10
INSTRUMENTS TO BE LARGEST SEGMENT IN 2031


FIGURE 11
US AND INSTRUMENTS ACCOUNTED FOR LARGEST MARKET SHARE IN NORTH AMERICA IN 2O25


FIGURE 12
JAPAN TO REGISTER HIGHEST GROWTH RATE DURING FORECAST PERIOD


FIGURE 13
ASIA PACIFIC TO DOMINATE MARKET DURING FORECAST PERIOD


FIGURE 14
PFAS TESTING MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES


FIGURE 15
PFAS TESTING MARKET: PORTER’S FIVE FORCES ANALYSIS


FIGURE 16
PFAS TESTING MARKET: VALUE CHAIN ANALYSIS


FIGURE 17
PFAS TESTING MARKET: ECOSYSTEM ANALYSIS


FIGURE 18
AVERAGE SELLING PRICE TREND OF PFAS INSTRUMENTS, BY TYPE, 2025 (USD THOUSAND)


FIGURE 19
AVERAGE SELLING PRICE TREND OF PFAS INSTRUMENTS, BY REGION, 2022–2024 (USD THOUSAND)


FIGURE 20
IMPORT DATA FOR HS CODE 390460-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025


FIGURE 21
EXPORT DATA FOR HS CODE 390460-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025


FIGURE 22
TRENDS/DISRUPTIONS INFLUENCING CUSTOMER BUSINESS


FIGURE 23
PFAS TESTING MARKET: INVESTMENT & FUNDING SCENARIO


FIGURE 24
PFAS TESTING MARKET: NUMBER OF INVESTOR DEALS, BY KEY PLAYER, 2019–2023 (USD MILLION)


FIGURE 25
VALUE OF INVESTOR DEALS IN PFAS TESTING MARKET, BY KEY PLAYER, 2019–2023 (USD MILLION)


FIGURE 26
PATENTS APPLIED AND GRANTED, 2016–2026


FIGURE 27
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS


FIGURE 28
KEY BUYING CRITERIA FOR PFAS TESTING MARKET


FIGURE 29
NORTH AMERICA: PFAS TESTING MARKET SNAPSHOT


FIGURE 30
ASIA PACIFIC: PFAS TESTING MARKET SNAPSHOT


FIGURE 31
REVENUE ANALYSIS OF TOP FIVE PLAYERS IN PFAS TESTING MARKET, 2022–2025


FIGURE 32
PFAS TESTING MARKET SHARE ANALYSIS OF KEY PLAYERS, 2025


FIGURE 33
RANKING OF KEY PLAYERS IN PFAS TESTING MARKET FOR TOTAL MARKET, 2025


FIGURE 34
PFAS TESTING MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025


FIGURE 35
PFAS TESTING MARKET: COMPANY FOOTPRINT


FIGURE 36
PFAS TESTING MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025


FIGURE 37
EV/EBITDA OF KEY VENDORS


FIGURE 38
YEAR-TO-DATE (YTD) PRICE TOTAL RETURN AND 5-YEAR STOCK BETA OF KEY VENDORS


FIGURE 39
PFAS TESTING MARKET: BRAND/PRODUCT COMPARISON


FIGURE 40
AGILENT TECHNOLOGIES, INC.: COMPANY SNAPSHOT (2025)


FIGURE 41
DANAHER CORPORATION: COMPANY SNAPSHOT (2025)


FIGURE 42
WATERS CORPORATION: COMPANY SNAPSHOT (2025)


FIGURE 43
THERMO FISHER SCIENTIFIC INC.: COMPANY SNAPSHOT (2025)


FIGURE 44
SHIMADZU CORPORATION: COMPANY SNAPSHOT (2025)


FIGURE 45
MERCK KGAA: COMPANY SNAPSHOT (2025)


FIGURE 46
LGC LIMITED: COMPANY SNAPSHOT (2025)


FIGURE 47
BIOTAGE: COMPANY SNAPSHOT (2024)


FIGURE 48
PFAS TESTING MARKET: RESEARCH DESIGN


FIGURE 49
PFAS TESTING MARKET: KEY SECONDARY SOURCES


FIGURE 50
PFAS TESTING MARKET: KEY DATA FROM SECONDARY SOURCES


FIGURE 51
PFAS TESTING MARKET: KEY PRIMARY SOURCES (DEMAND AND SUPPLY SIDES)


FIGURE 52
PFAS TESTING MARKET: KEY SUPPLY- AND DEMAND-SIDE PARTICIPANTS


FIGURE 53
BREAKDOWN OF PRIMARY INTERVIEWS: BY COMPANY TYPE, DESIGNATION, AND REGION


FIGURE 54
PFAS TESTING MARKET: KEY INSIGHTS FROM PRIMARY EXPERTS


FIGURE 55
RESEARCH METHODOLOGY: HYPOTHESIS BUILDING


FIGURE 56
PFAS TESTING MARKET: COMPANY REVENUE ESTIMATION, 2025


FIGURE 57
PFAS TESTING MARKET: MARKET SIZE ESTIMATION METHODOLOGY


FIGURE 58
DATA TRIANGULATION


Methodology

The study involved four major activities to estimate the current size of the PFAS testing market. Extensive secondary research was conducted to gather information on the PFAS testing market, related analytical testing markets, and adjacent environmental and food safety testing markets. The findings, assumptions, and market estimates were then validated through primary research with industry experts across the PFAS testing value chain, including testing laboratories, analytical instrument and technology providers, environmental consultants, regulatory bodies, and end users. Both top-down and bottom-up approaches were used to estimate the overall PFAS testing market size. This was followed by market segmentation and data triangulation to estimate the size of key segments and subsegments by testing method, sample type, application, end user, and region.

Secondary Research

The secondary research process relied extensively on industry databases, company websites, annual reports, investor presentations, SEC filings, regulatory publications, scientific and technical papers, white papers, financial reports, trade publications, and commercial databases such as Bloomberg Businessweek, Factiva, and D&B Hoovers. The research gathered comprehensive technical, market-oriented, regulatory, and commercial information on PFAS testing, including analytical methods and technologies used to detect and quantify PFAS compounds in various matrices. The research covered PFAS testing applications across drinking water and wastewater, environmental samples, soil and sediment, food and beverages, consumer products, industrial samples, and biological samples.

Secondary research was also used to identify key market players, testing laboratories, technology providers, and other stakeholders; establish detailed market classification and segmentation; assess PFAS regulatory developments, testing standards, analytical technology trends, emerging PFAS compounds, and testing requirements; and identify key market developments, demand drivers, challenges, and growth opportunities. A database of key industry participants and stakeholders in the PFAS testing ecosystem was also developed through secondary research.

Primary Research

During the primary research, supply- and demand-side stakeholders in the PFAS testing ecosystem were interviewed to gather qualitative and quantitative insights for the study. Supply-side respondents included industry experts such as CEOs, vice presidents, marketing and sales directors, product managers, technology and innovation directors, laboratory directors, and other senior executives from leading PFAS testing laboratories, analytical instrument manufacturers, testing technology providers, environmental testing companies, and laboratory service providers. Demand-side respondents included professionals from environmental monitoring agencies, water and wastewater treatment organizations, environmental consulting firms, food and beverage companies, pharmaceutical and biotechnology companies, chemical and manufacturing companies, government and regulatory bodies, research institutions, and other organizations that require PFAS testing services.

Primary research was conducted to validate market segmentation and market size estimates, identify and assess key market participants, and gain insights into PFAS testing technology adoption, analytical methods, sample and matrix testing requirements, regulatory and compliance requirements, testing frequency, purchasing criteria, laboratory capabilities, competitive dynamics, and key market drivers and challenges shaping the PFAS testing market.

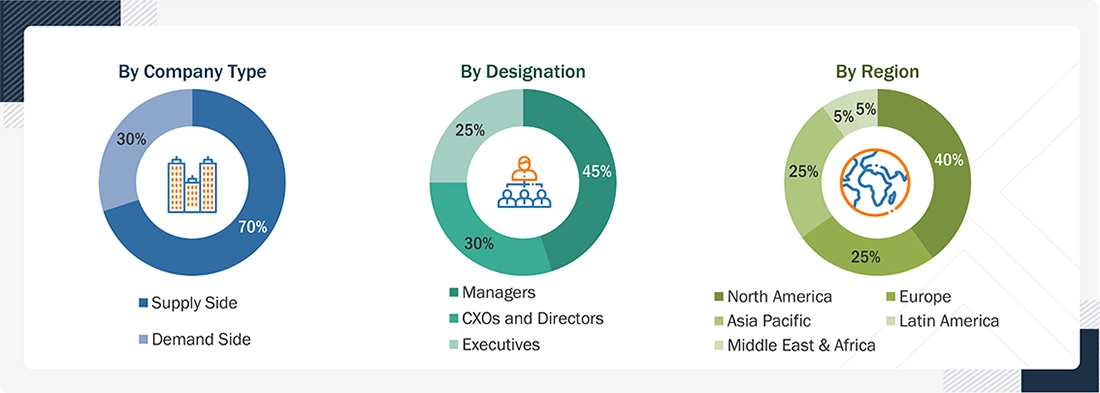
A breakdown of the primary respondents is provided below:
PFAS Testing Market 
 Size, and Share

Others include sales managers, marketing managers, business development managers, product managers, distributors, and suppliers.

Note: Companies are classified into tiers based on their total revenue. Tier 1 = >USD 400 million, Tier 2 = USD 200 million, and Tier 3 = <USD 100 million.

To know about the assumptions considered for the study, download the pdf brochure

Market Size Estimation

In this report, the size of the PFAS testing market was determined using a revenue share analysis of leading players. To this end, key players in the market were identified, and their revenues from market-related business were determined through insights gathered during the primary and secondary research phases. Secondary research included the study of the annual and financial reports of the top market players. In contrast, primary research included extensive interviews with key opinion leaders, such as CEOs, directors, and key marketing executives at hospital procurement and biobanking divisions.

Segmental revenue was calculated using the revenue mapping of major solution and product providers to estimate the global PFAS testing market value. This process involved the following steps:

  • Generating a list of major global players operating in the PFAS testing market
  • Mapping annual revenue generated by major global players from the PFAS testing storage consumables segment (or nearest reported business unit/product category)
  • Revenue mapping of major players to cover a major share of the global market, as of 2025
  • Extrapolating the global value of the PFAS testing market, with specific attention to the healthcare end-user segment
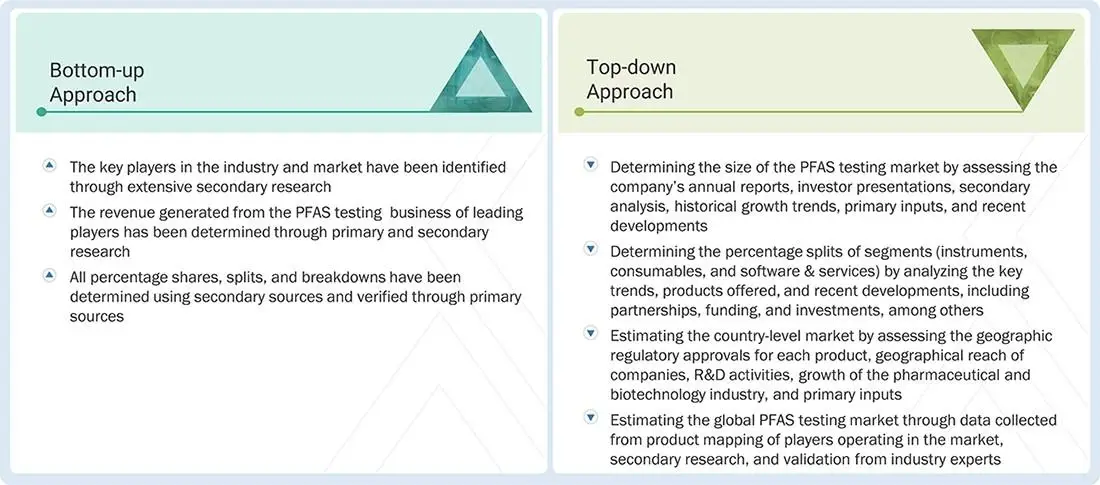
PFAS Testing Market Top Down and Bottom Up Approach

Data Triangulation

After determining the overall market size through the market size estimation process described above, the PFAS testing market was segmented into segments and subsegments. Data triangulation and market breakdown procedures were used to complete the overall market engineering process and arrive at precise statistics for all segments and subsegments, including the end-user category. Data was triangulated by analyzing various factors and trends from both the demand and supply sides. Additionally, the PFAS testing market was validated using top-down and bottom-up approaches.

Market Definition

The PFAS testing market comprises analytical technologies and services for detecting, identifying, quantifying, and characterizing per- and polyfluoroalkyl substances (PFAS) in environmental, industrial, food, and other sample matrices. PFAS are synthetic chemicals known for their resistance to heat, oil, grease, and water, and are often referred to as “forever chemicals” because of their persistence in the environment. The market includes technologies such as chromatography, mass spectrometry, and nuclear magnetic resonance (NMR) spectroscopy, which enable the separation, identification, quantification, and structural analysis of PFAS compounds. These technologies are widely used to monitor PFAS contamination, determine concentration levels, support regulatory compliance, and assess environmental pollution across applications including water, soil, wastewater, food, and industrial samples.

Key Stakeholders

  • Suppliers & distributors of PFAS testing consumables
  • PFAS testing consumable manufacturing companies
  • Food & beverage manufacturing companies
  • Pharmaceutical companies
  • Environmental protection agencies and institutes
  • Agricultural analysis companies
  • Pollution monitoring manufacturers
  • Clinical research organizations (CROs)
  • Market research and consulting firms
  • Research and development companies

Report Objectives

  • To define, describe, and forecast the size of the PFAS testing market based on product type, technique, method, application, end user, and region
  • To provide detailed information regarding the major factors influencing the growth potential of the global PFAS testing market (drivers, restraints, opportunities, challenges, and trends) from a healthcare industry perspective
  • To analyze micromarkets with respect to individual growth trends, prospects, and contributions to the global PFAS testing market
  • To analyze key growth opportunities in the global PFAS testing market for key stakeholders and provide details of the competitive landscape for market leaders
  • To forecast the size of market segments and/or subsegments with respect to five major regions, namely, North America, Europe, Asia Pacific, Latin America, and Middle East & Africa
  • To profile key players in the PFAS testing market and comprehensively analyze their market share and core competencies
  • To analyze the competitive developments undertaken in the global PFAS testing market, such as product launches; agreements; expansions; and mergers & acquisitions

Available customizations:

Based on the provided market data, customizations are offered to meet the company's specific needs. The following customization options are available for the current global PFAS testing market report:

Product Analysis

  • Product matrix, which gives a detailed comparison of the product portfolios of the top five companies.

Company Information

  • Detailed analysis and profiling of additional market players (up to five).

Geographic Analysis

  • Further breakdown of the Rest of Europe PFAS testing market into Russia, Belgium, the Netherlands, Switzerland, Austria, Finland, Sweden, Poland, and Portugal, among others.
  • Further breakdown of the Rest of Asia Pacific PFAS testing market into Singapore, Taiwan, New Zealand, Philippines, Malaysia, and other APAC countries.
  • Further breakdown of the Latin American PFAS testing market into Colombia, Chile, Argentina, and Peru, among others.

 

Personalize This Research

  • Triangulate with your Own Data
  • Get Data as per your Format and Definition
  • Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
  • Any level of Personalization
Request A Free Customisation

Let Us Help You

  • What are the Known and Unknown Adjacencies Impacting the PFAS Testing Market
  • What will your New Revenue Sources be?
  • Who will be your Top Customer; what will make them switch?
  • Defend your Market Share or Win Competitors
  • Get a Scorecard for Target Partners
Customized Workshop Request

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements

Get 10% Free Customisation

TESTIMONIALS

Growth opportunities and latent adjacency in PFAS Testing Market

DMCA.com Protection Status
popup img