Data Center Chillers Market by Product Type (Scroll Chillers, Screw Chillers, Centrifugal Chillers), Condenser Type (Air-Cooled Chillers, Water-Cooled Chillers), Cooling Capacity, and Region - Global Forecast to 2033

icon1
USD 8.81 BN
MARKET SIZE, 2033
icon2
CAGR 15.6%
(2026-2033)
icon3
346
REPORT PAGES
icon4
313
MARKET TABLES

OVERVIEW

data-center-chillers-market Overview

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

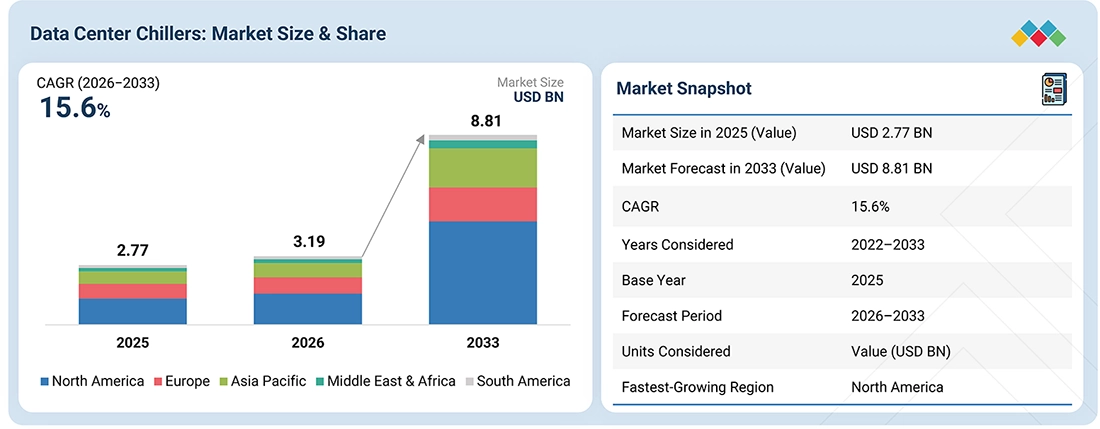
The global data center chillers market is projected to grow from USD 3.19 billion in 2026 to USD 8.81 billion in 2033, at a CAGR of 15.6% during the forecast period. Data center chillers are extremely important cooling solutions that provide support for the cooling factors of the new digital infrastructure by providing cooling capability by removing heat produced from servers, storage systems, and networking equipment. Depending on the facility’s cooling capacity, a majority of facilities utilize one of three types of chillers to maintain a proper temperature and operate with no interruptions, including air-cooled and water-cooled chillers. In addition, facilities will employ multiple chiller product types including scroll, screw, and centrifugal chillers, based on the type of facility (size, air flow, water flow, load characteristics) and amount of heat produced by their IT operations. As more and more data centers develop to accommodate higher computing loads, the cooling capabilities of these systems have transitioned from being primarily to support utility functions and facilities to being an integral part of the design of the facility. Current market conditions are being driven by the growth of cloud computing platforms, digitalization of businesses through technology, use of artificial intelligence, and use of high-performance computing (HPC). Each of these technologies produces a significant amount of heat and requires more sophisticated methods of controlling the cooling of the data. In addition, as demand grows for reliability, increasing rack densities, and more energy-efficient operations, investments in new-generation chillers are increasing. Growing demand resulting from the rapid expansion of hyperscape data centers, edge computing infrastructures, and sustainable facilities is further increasing the use of data center chillers as a critical component in the global digital economy.

KEY TAKEAWAYS

  • BY REGION
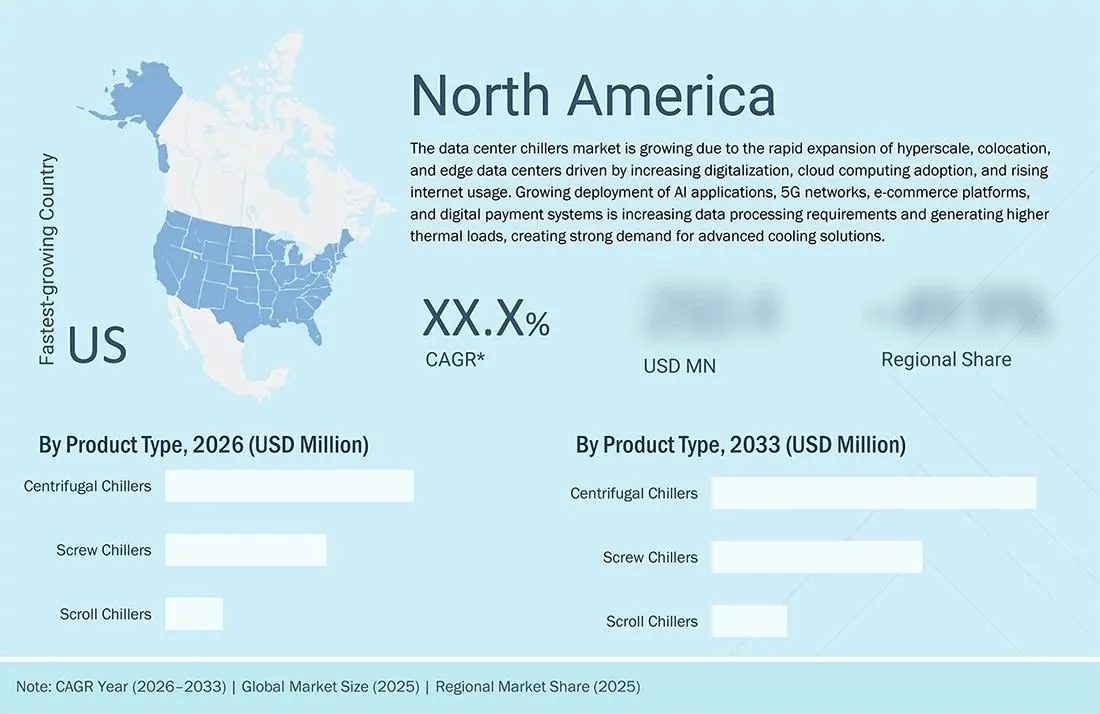
    North America is expected to register the highest CAGR (18.7%) during the forecast period.
  • BY PRODUCT TYPE
    By product type, the centrifugal chillers segment is projected to grow at the highest CAGR (17.3%) during the forecast period.
  • BY CONDENSER TYPE
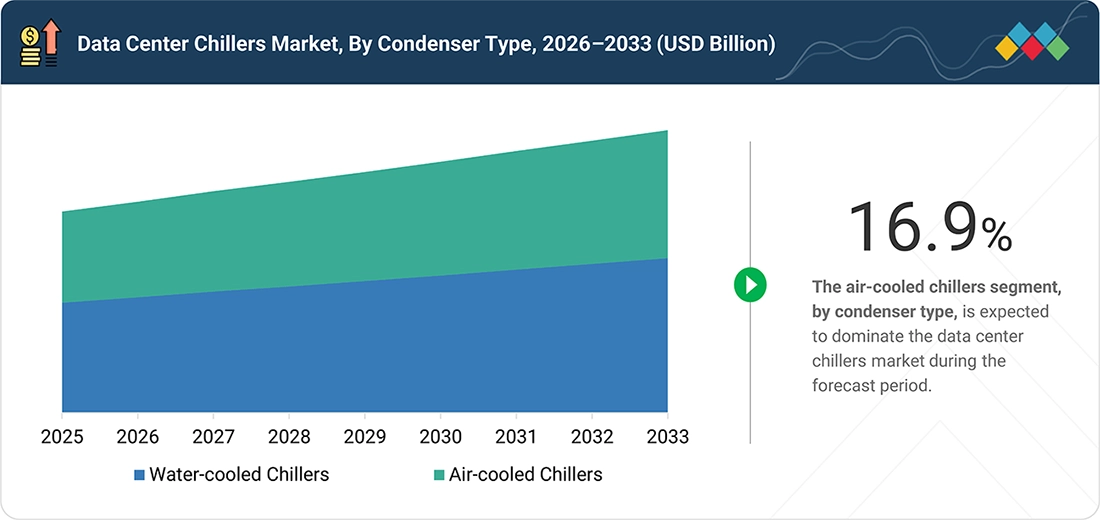
    By condenser type, the air-cooled chillers segment is projected to grow at the highest CAGR (16.9%) during the forecast period.
  • BY COOLING CAPACITY
    By cooling capacity, the 700–3,000 RT segment will dominate the market during the forecast period.
  • Competitive Landscape - Key Players
    Johnson Controls (US), Trane (Ireland), Carrier (US), Daikin (Japan), and Vertiv Group Corp. (US) were identified as leading players in the data center chillers market, given their strong market share and product portfolios.
  • Competitive Landscape - Startups
    Multistack (China), and AERMEC S.P.A. (Italy), among others,have distinguished themselves among startups and SMEs by securing strong footholds in specialized niche areas, underscoring their potential emerging market leaders.

Data center chillers form the backbone of thermal management systems in modern data centers, ensuring that critical IT equipment operates within safe temperature ranges despite continuously increasing computing loads. The market encompasses a range of cooling solutions, including air-cooled chillers and water-cooled chillers, each designed to meet specific operational and efficiency requirements. Product types such as screw chillers, centrifugal chillers, and scroll chillers further enable data center operators to optimize cooling performance across facilities ranging from edge installations to hyperscale campuses. As organizations accelerate digital transformation initiatives, demand for data storage, cloud services, and real-time data processing continues to expand, increasing the need for reliable cooling infrastructure. The growing deployment of artificial intelligence, machine learning, and high-performance computing applications is placing additional pressure on thermal management systems due to rising server densities and heat generation. At the same time, data center operators are prioritizing energy efficiency, operational reliability, and sustainability, driving investment in advanced chiller technologies. The continued expansion of hyperscale, colocation, and edge data centers across key regions is further strengthening demand, making data center chillers an essential component of next-generation digital infrastructures.

TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS

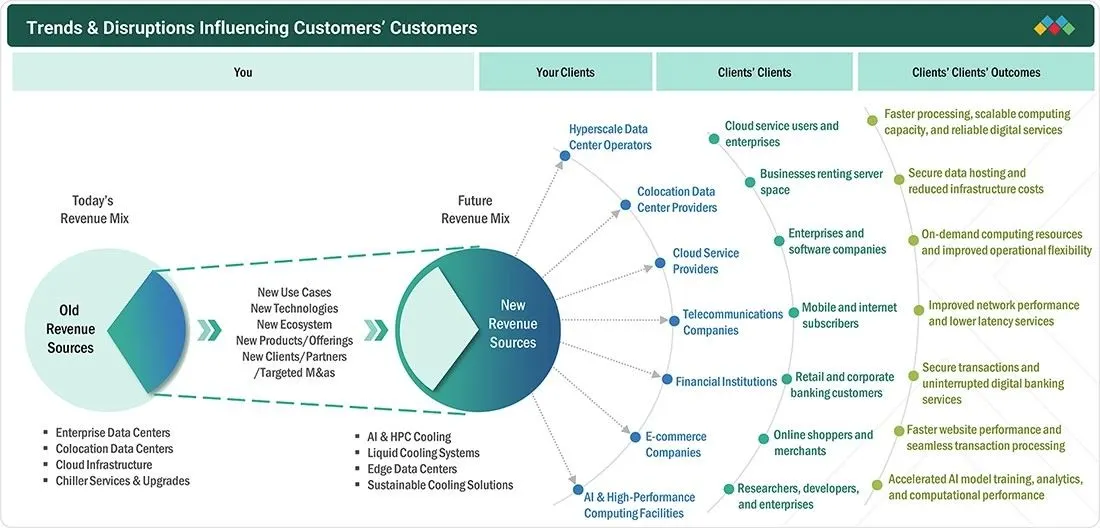
The impact on consumers' businesses arises from evolving customer trends or market disruptions. Megatrends such as sustainability and digital transformation, alongside disruptions such as AI, supply chain localization, and the energy transition, are significantly reshaping customer priorities and business models. Traditionally, revenue mixes were dominated by legacy products and processes focused on volume and cost. Today, customers are shifting toward high-margin, innovation-driven, and sustainable solutions to remain competitive and future-proof. This transition is prompting businesses to adapt quickly, invest in cleaner technologies, and enhance agility, with suppliers expected to deliver compliant, efficient, and tech-enabled offerings that align with evolving market demands.

data-center-chillers-market Disruptions

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

MARKET DYNAMICS

Drivers
Impact
Level
  • Rising AI and high-performance computing workloads
  • Growing focus on energy efficiency and lower PUE
RESTRAINTS
Impact
Level
  • High capital and installation costs
  • High water consumption of water-cooled chiller systems
OPPORTUNITIES
Impact
Level
  • Integration of chillers with AI-ready liquid-cooling architectures
  • Development of low-GWP and ultra-low-GWP chillers
CHALLENGES
Impact
Level
  • Transition from conventional air cooling to hybrid cooling architectures
  • Refrigerant regulations and technology transition

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Driver: Rising AI and high-performance computing workloads

The fast adoption of artificial intelligence (AI) and high-performance computing (HPC) applications represents one of the key factors driving the global data center chillers market, as they require more powerful chips that produce higher heat loads. In addition, according to the International Energy Agency (IEA), the electricity usage of AI-specific data centers grew by 50% in 2025, while the power density of AI servers increased around 11 times from 2020 to 2025 and will increase further by 4 times by 2027. Moreover, the increasing power density levels force traditional air cooling to operate at its performance limits, pushing operators to implement advanced thermal management solutions, such as the combination of liquid cooling, chillers, and chilled water. Hence, the growth in the development of AI infrastructure and high-density computing requires continuous, scalable, and reliable heat rejection systems, creating a growing demand for large-capacity centrifugal and screw chillers, air and water-cooled systems, free cooling systems, and combined cooling plant solutions. Thus, the further adoption of AI facilities and high-density computing will promote investments in data center cooling facilities and boost the data center chillers market growth.

Restraint: High capital and installation costs

The considerable cost of investment in chillers and their installations is one of the major restraints in the global data center chillers market. Chillers entail a considerable upfront investment in not only the chillers themselves but also cooling towers, pumps, piping, controls, electrical systems, water treatment systems, and their installation and commissioning, which gets even more costly when the system needs redundancy (N+1 or 2N). With the increase in the need for large capacity and complex cooling of facilities for artificial intelligence and HPC, which require increasingly complex thermal architecture, mechanical and cooling systems may make a considerable portion of the total data center construction costs, especially with high density. Moreover, the installation of the chillers in the existing facilities might require costly modification to piping, electrical distribution, structure systems, and controls infrastructure. For small and medium data centers and enterprise facilities, these considerable investments might cause delays in cooling system upgrades or the shift towards alternative technologies that would not require high upfront investments.

Opportunity: Integration of chillers with AI-ready liquid-cooling architectures

Chillers coupled with AI-ready liquid-cooling designs are among the key opportunities for the global data center chillers market, as the fast proliferation of AI and high-performance computing (HPC) systems increases rack power density and prompts the use of various liquid-cooling approaches, including direct-to-chip cooling. Liquid-cooling systems do not replace chillers but allow them to be used as an important heat rejection device at the facility level by delivering cold water to coolant distribution units (CDUs), heat exchangers, and technology cooling system loops. Contemporary AI-friendly data center designs often incorporate efficient chillers along with CDUs, fan coil walls, CRACs, and intelligent thermal management systems for both air- and liquid-cooled IT infrastructure. The application of warm-water liquid cooling opens up additional opportunities to use chillers operating on higher chilled-water temperature and thus improves overall cooling plant efficiency and reduces the number of chillers required. With growing rack power densities driven by AI workloads and transformation to hybrid air- and liquid-cooling designs, the need for high-capacity chillers, chilled water systems running on higher chilled water temperature, CDUs, heat exchangers, sophisticated control systems, and thermal management solutions is likely to grow.

Challenge: Transition from conventional air cooling to hybrid cooling architectures

The shift from traditional air cooling solutions to hybrid cooling systems is one of the biggest issues for the global data center chillers market due to the growing popularity of hybrid cooling systems that combine legacy air cooling technologies and direct-to-chip liquid cooling, rear-door heat exchangers, and other liquid-cooling solutions to provide cooling for increased rack density. Hybrid cooling architectures offer more opportunities for chillers for heat rejection at the facility level; however, the implementation of such cooling architectures raises certain difficulties regarding cooling design as operators have to coordinate such components as chilled-water loops, CDUs, liquid-cooling loops, CRAH/CRACs, piping, controls, heat rejection equipment. According to ASHRAE, it is important to keep legacy air-cooling architecture in use for residual heat and implement direct-to-chip liquid cooling for high-density AI racks. The retrofitting of an existing facility for liquid cooling infrastructure is quite costly and difficult, and there may be such obstacles as lack of space, lack of mechanical design for piping capacity, and lack of standardized designs. In addition, different cooling requirements for legacy servers, networking equipment, and high-density AI racks create additional difficulties with chiller capacity and temperature settings for the entire facility. Thus, data center operators should be very careful with air and liquid cooling capacity, redundancy, efficiency, water usage, costs, and scalability of cooling solutions, which complicates the situation for the chiller manufacturer.

DATA CENTER CHILLERS MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES

COMPANY USE CASE DESCRIPTION BENEFITS
company logo
Cooling of hyperscale and enterprise data centers requiring centralized thermal management | Support for colocation facilities with varying cooling loads | Management of high-density server environments | Modernization of existing data center infrastructure Cooling of hyperscale and enterprise data centers requiring centralized thermal management | Support for colocation facilities with varying cooling loads | Management of high-density server environments | Modernization of existing data center infrastructure
company logo
Thermal management for cloud computing facilities | Cooling support for AI and high-performance computing workloads | Large-scale enterprise data center deployments | Mission-critical applications requiring consistent uptime Thermal management for cloud computing facilities | Cooling support for AI and high-performance computing workloads | Large-scale enterprise data center deployments | Mission-critical applications requiring consistent uptime
company logo
Cooling solutions for colocation and enterprise data centers | Deployment in edge and regional data center facilities | Support for digital infrastructure expansion projects | Applications requiring dependable and efficient temperature control Cooling solutions for colocation and enterprise data centers | Deployment in edge and regional data center facilities | Support for digital infrastructure expansion projects | Applications requiring dependable and efficient temperature control
company logo
Cooling infrastructure for hyperscale and cloud data centers | Support for sustainability-focused facility developments | High-capacity cooling applications | Data centers seeking advanced energy management capabilities Cooling infrastructure for hyperscale and cloud data centers | Support for sustainability-focused facility developments | High-capacity cooling applications | Data centers seeking advanced energy management capabilities
company logo
Precision cooling for edge and modular data centers | Support for AI-ready and high-density computing environments | Thermal management for colocation facilities | Rapid deployment data center projects requiring scalable cooling solutions Precision cooling for edge and modular data centers | Support for AI-ready and high-density computing environments | Thermal management for colocation facilities | Rapid deployment data center projects requiring scalable cooling solutions

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET ECOSYSTEM

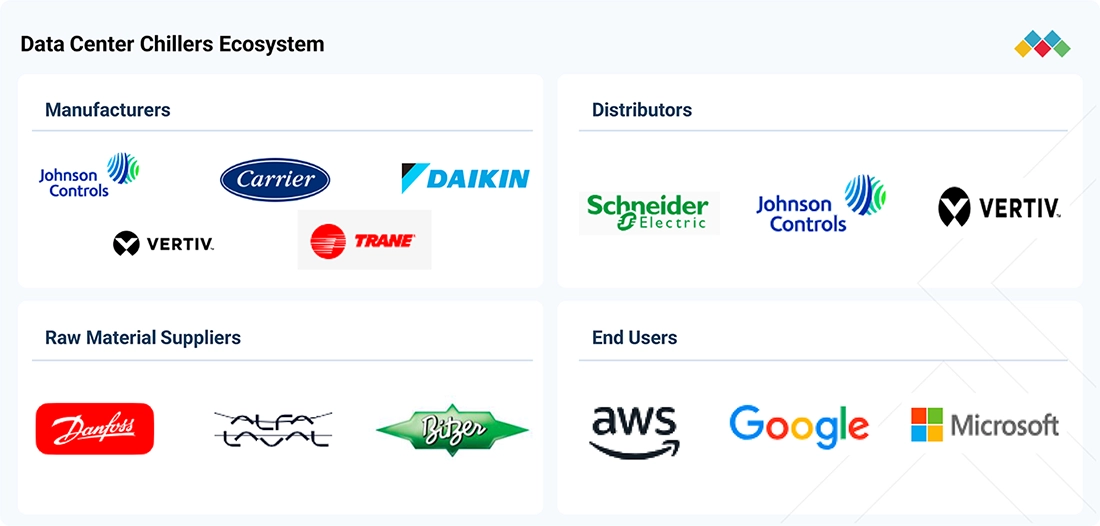
The data center chillers market ecosystem consists of raw material suppliers (e.g. Danfoss, ALFA LAVAL, and BITZER), Manufacturer (e.g., Johnson Controls, Trane, Carrier, Daikin, and Vertiv Group Corp.), distributors (e.g., Johnson Controls, Vertiv Group Corp., and Schneider Electric), and end users (e.g. Amazon Web Services, Inc., Microsoft, and Google).

data-center-chillers-market Ecosystem

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET SEGMENTS

data-center-chillers-market Segments

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Data Center Chillers Market, By Product Type

By product type segments, the centrifugal chillers segment is projected to witness the highest growth rate in the global data center chillers market during the forecast period owing to rising cooling needs of hyperscale, AI, and HPC data centers. High density of GPU servers being deployed is increasing thermal load and thereby increasing the need for chiller systems capable of providing efficient and reliable cooling in both full and partial load conditions. High energy efficiency and low maintenance are the key features of centrifugal chillers with the use of oil-free magnetic-bearing compressors, variable speed drives, intelligent controls, and free cooling options. According to research studies, magnetic bearing centrifugal chillers have been found to provide significantly better efficiency compared to traditional centrifugal and scroll chillers especially during partial load operations, and also decrease energy consumption by around 10% to 40% in some cases of data center operations. Leading companies are coming up with specific centrifugal chillers for AI and hyperscale data centers; for instance, the Magnitude line of Daikin offers capacity up to 3,000 tons, whereas YORK YDAM from Johnson Controls provides 3.5 MW of cooling capacity per unit in high-density data centers. Also, the introduction of new centrifugal magnetic bearing chiller products by Trane, Mitsubishi Electric, and Vertiv companies shows the ongoing advancements in this product segment. In light of rising preferences for energy efficiency, high cooling capacity, scalability, reliability, low maintenance, and low operating costs, centrifugal chillers are likely to post the fastest growth in the product type segments in the forecast period.

Data Center Chillers Market, By Condenser Type

The air-cooled chillers segment, according to the condenser type, is expected to witness the highest growth rate in the global data center chillers market during the forecast period due to the rapid growth in the construction of hyperscale, AI, HPC, and edge data centers, along with the rising focus on water savings. Since air-cooled chillers require no cooling towers and condenser water systems, they help achieve low water use onsite, simpler infrastructure, and lesser maintenance as compared to water-cooled chiller systems. Johnson Controls’ 2026 air-cooled chiller reference design for gigawatt-scale AI data centers, for instance, showcases the benefits of zero-water cooling, no cooling towers, and substantial energy savings. Further technological improvements in oil-free compressors, variable-speed drives, free cooling, ability to work in high ambient temperatures, and smart controls are improving the efficiency and reliability of air-cooled chillers; the data center-focused air-cooled chiller from Mitsubishi Electric, for example, shows great part-load efficiency. The practical applications of air-cooled chillers are rising, and the implementation of Trane’s air-cooled free-cooling system at a hyperscale data center in India is saving up to 18% of annual energy, which translates into 33,000 tons of CO2e reduction. While there may be higher energy consumption with air-cooled chillers compared to water-cooled ones in some operating scenarios, the combination of lower water use, easier installation process, easy scalability, and the ability to support free-cooling and hybrid liquid-cooling architectures will contribute to quick adoption of air-cooled chillers, making air-cooled chillers the fastest-growing condenser type in the data center chillers market.

REGION

Asia Pacific to be fastest-growing region in data center chillers market during forecast period

In terms of regions, North America is anticipated to be the leading region in the growth of the global data center chillers market during the forecast period owing to the rapid deployment of hyperscale, colocation, cloud, AI and high performance computing data centers in the United States and Canada. The rapid deployment of AI infrastructure leads to increase in rack power density and heat loads, thus driving demand for high capacity centrifugal and screw chillers, air-cooled and water-cooled equipment, free cooling solutions, and chilled water systems. Major US hubs, such as Northern Virginia, Dallas-Fort Worth, Atlanta, Phoenix, and others have been active in building out new data centers, where, for instance, Northern Virginia saw 4,496.5 MW of data center inventory in H1 2026 and Atlanta – 2,882 MW of under-construction data centers. Furthermore, the adoption of liquid cooling systems in GPU infrastructure is providing the opportunities for chillers, which can be used as part of facility-level heat rejection and coolant distribution systems, not for replacement of chiller-based cooling system. Moreover, increased attention to efficiency, water savings, reliability, scalability and reduction of operational costs drive operators to implement advanced chillers equipped with magnetic-bearing compressors, variable speed drives, free cooling capabilities and intelligent controls. Thus, the combination of rapidly growing demand for data center cooling due to deployment of AI, record high construction rates of data centers, power densities increase, and investments in advanced thermal management infrastructure will contribute to positioning North America as the leader in growth rate of data center chillers market during the forecast period.

data-center-chillers-market Region

DATA CENTER CHILLERS MARKET: COMPANY EVALUATION MATRIX

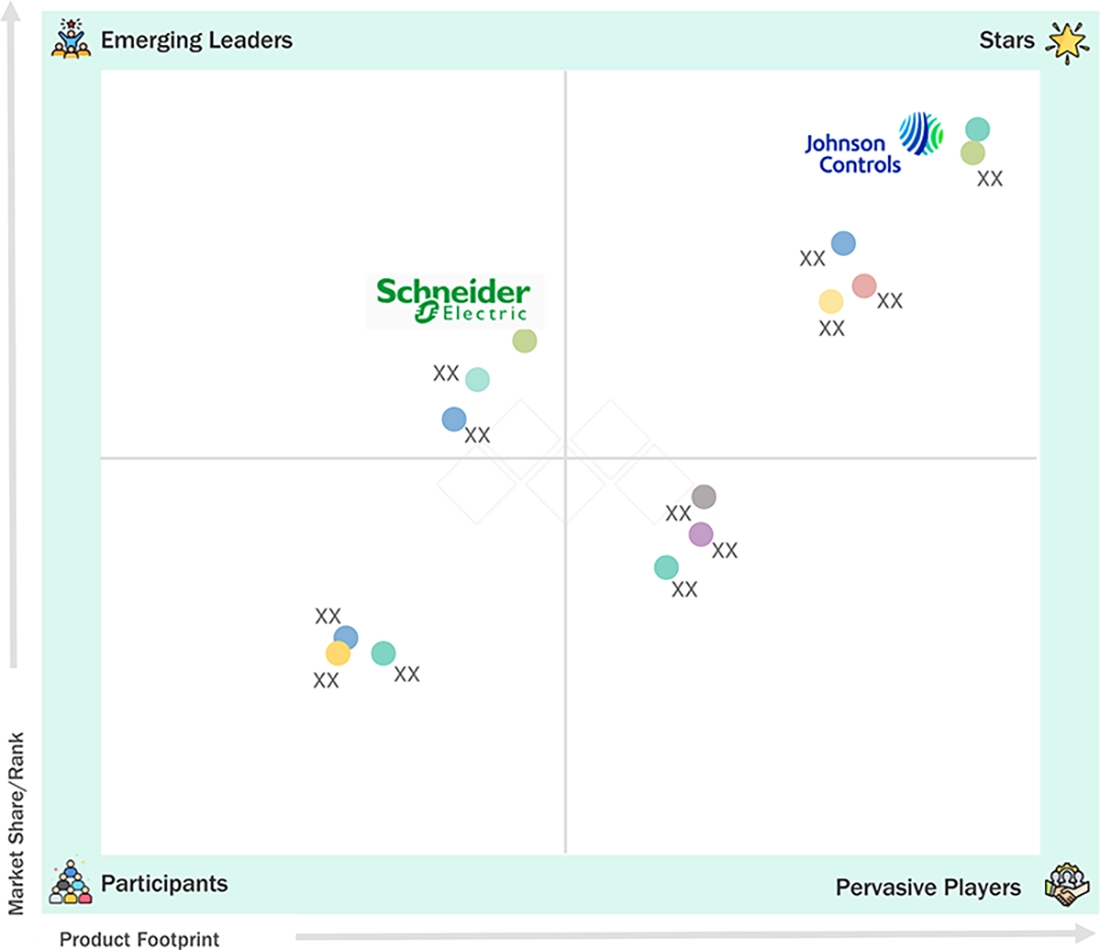
Johnson Controls is widely regarded as one of the leading players/star players in the data center chillers market due to its extensive portfolio of high-capacity cooling solutions, strong global presence, and established expertise in data center thermal management. In contrast, Schneider Electric is emerging as a notable player through its growing focus on integrated data center infrastructure, energy-efficient cooling solutions, and intelligent digital management platforms. While Johnson Controls benefits from a mature market position and broad deployment across large-scale facilities, Schneider Electric is strengthening its presence by capitalizing on increasing demand for sustainable, AI-ready, and energy-optimized data center environments.

data-center-chillers-market Evaluation Metrics

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

KEY MARKET PLAYERS

  • Johnson Controls (US)
  • Trane (Ireland)
  • Carrier (US)
  • Daikin (Japan)
  • Vertiv Group Corp. (US)
  • Modine (US)
  • Schneider Electric (France)
  • Munters (Sweden)
  • Mitsubishi Electric (Japan)
  • Lennox International Inc. (US)
  • Danfoss (Denmark)
  • STULZ GMBH (Germany)
  • GEA Group Aktiengesellschaft (Germany)
  • Rittal GmbH & Co. KG (Germany)
  • Thermax Limited (India)
  • Blue Star Limited (India)
  • Kirloskar (India)
  • LG Electronics (South Korea)
  • Thermal Care (US)
  • GD MIDEA HEATING & VENTILATING EQUIPMENT CO., LTD (China)
  • Delta Electronics, Inc. (Taiwan)

MARKET SCOPE

REPORT METRIC DETAILS
Market Size in 2025 (Value) USD 2.77 BN
Market Size in 2026 (Value) USD 3.19 BN
Market Size in 2033 (Value) USD 8.81 BN
CAGR% (2026–2033) 15.6
Years Considered 2022–2033
Base Year 2025
Forecast Period 2026–2033
Units Considered Value (USD Billion)
Report Coverage Revenue forecast, competitive landscape, growth factors, and trends
Segments Covered By Product Type: Scroll Chillers, Screw Chillers, and Centrifugal Chillers
Regions Covered North America, Europe, Asia Pacific, Middle East & Africa, and South America

WHAT IS IN IT FOR YOU: DATA CENTER CHILLERS MARKET REPORT CONTENT GUIDE

data-center-chillers-market Content Guide

DELIVERED CUSTOMIZATIONS

We have successfully delivered the following deep-dive customizations:

CLIENT REQUEST CUSTOMIZATION DELIVERED VALUE ADDS
Assessment of data center chiller demand across regions and facility types Customized market sizing and forecast analysis segmented by product type (air-cooled, water-cooled, liquid coolant chillers), technology, cooling capacity, data center type, and key regional markets, along with demand mapping based on data center construction activity and digital infrastructure investments Enabled the client to prioritize high-potential market segments, optimize resource allocation, identify attractive investment areas, and develop targeted growth strategies based on future demand patterns
Evaluation of growth potential for liquid coolant chillers and AI-driven cooling applications In-depth assessment of liquid cooling adoption trends, AI and high-performance computing cooling requirements, technology readiness, adoption barriers, and future demand outlook, including opportunity analysis across hyperscale and enterprise facilities Helped the client identify emerging technology opportunities, align product development with future market needs, strengthen innovation roadmaps, and gain a first-mover advantage in high-growth applications
Competitive benchmarking of leading chiller manufacturers Detailed comparison of major market participants covering product portfolios, technology capabilities, cooling capacity offerings, strategic developments, regional presence, customer focus, and competitive positioning within the data center cooling ecosystem Provided actionable insights into competitor strengths and weaknesses, supported differentiation strategies, identified market gaps, and improved strategic decision-making for product positioning and business expansion
Analysis of customer requirements and end-user adoption trends Customized evaluation of cooling requirements across hyperscale, colocation, enterprise, and edge data centers, including purchasing criteria, energy-efficiency priorities, sustainability goals, and evolving thermal management needs driven by AI workloads Improved understanding of customer purchasing behavior, enabled development of customer-centric solutions, enhanced value proposition design, and supported more effective sales and marketing strategies
Identification of regional expansion opportunities and investment hotspots Region- and country-level analysis of data center investments, cloud infrastructure growth, hyperscale expansion plans, regulatory environment, energy-efficiency trends, and cooling technology adoption patterns to identify the most attractive target markets Reduced market entry risks, supported expansion planning, identified favorable business environments, and enabled the client to c

RECENT DEVELOPMENTS

  • February 2026 : Johnson Controls announced its newest innovation in data center thermal management, the YORK YDAM air-cooled magnetic bearing centrifugal chiller. The innovative chiller is purpose-built to overcome the complex space and site challenges in high-density, multistory data centers. Built around the company's award-winning YORK YVAM chiller technology, YDAM delivers best-in-class cooling capacity within a compact footprint, helping data centers scale faster and more efficiently without consuming water.
  • April 2025 : Daikin expanded its data center cooling portfolio with the launch of the Pro-C CRAH range. This unit is available in two configurations: for hard floors and for raised floor. In the case of hard floors, either the split or compact configuration can be chosen. For raised floors, only the split configuration is available, which includes an optimized heat exchanger with high energy efficiency that recovers heat from the expelled air and transfers it to the inlet air. This reduces energy consumption.


Table of Contents

checkmarkExclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.

TITLE
PAGE NO
1
INTRODUCTION


26
2
EXECUTIVE SUMMARY


30
3
PREMIUM INSIGHTS


34
4
MARKET OVERVIEW
AI-driven liquid cooling revolutionizes energy efficiency in data centers amidst high installation costs.


37
 
4.1
INTRODUCTION


4.2
MARKET DYNAMICS


4.2.1
DRIVERS


4.2.1.1
RISING AI AND HIGH-PERFORMANCE COMPUTING WORKLOADS


4.2.1.2
GROWING FOCUS ON ENERGY EFFICIENCY AND LOWER PUE


4.2.1.3
INCREASING ADOPTION OF RELIABLE AND REDUNDANT LIQUID COOLING INFRASTRUCTURE


4.2.2
RESTRAINTS


4.2.2.1
HIGH CAPITAL AND INSTALLATION COSTS


4.2.2.2
HIGH WATER CONSUMPTION OF WATER-COOLED CHILLER SYSTEMS


4.2.3
OPPORTUNITIES


4.2.3.1
INTEGRATION OF CHILLERS WITH AI-READY LIQUID-COOLING ARCHITECTURE


4.2.3.2
DEVELOPMENT OF LOW-GWP AND ULTRA-LOW-GWP CHILLERS


4.2.3.3
SMART AND AI-ENABLED CHILLER OPTIMIZATION


4.2.4
CHALLENGES


4.2.4.1
TRANSITION FROM CONVENTIONAL AIR COOLING TO HYBRID COOLING ARCHITECTURES


4.2.4.2
REFRIGERANT REGULATIONS AND TECHNOLOGY TRANSITION


4.3
UNMET NEEDS AND WHITE SPACES


4.3.1
UNMET NEEDS IN DATA CENTER CHILLERS MARKET


4.3.2
WHITE SPACE OPPORTUNITIES


4.4
INTERCONNECTED MARKETS AND CROSS SECTOR OPPORTUNITIES


4.4.1
INTERCONNECTED MARKETS


4.4.2
CROSS-SECTOR OPPORTUNITIES


4.5
EMERGING BUSINESS MODELS AND ECOSYSTEM SHIFTS


4.5.1
EMERGING BUSINESS MODELS


4.5.2
ECOSYSTEM SHIFTS


4.6
STRATEGIC MOVES BY TIER 1/2/3 PLAYERS


4.6.1
KEY MOVES AND STRATEGIC FOCUS


5
INDUSTRY TRENDS
Uncover how AI and macroeconomic shifts redefine competitive dynamics in data center cooling.


50
 
5.1
PORTER’S FIVE FORCES ANALYSIS


5.1.1
BARGAINING POWER OF SUPPLIERS


5.1.2
THREAT OF NEW ENTRANTS


5.1.3
THREAT OF SUBSTITUTES


5.1.4
BARGAINING POWER OF BUYERS


5.1.5
INTENSITY OF COMPETITIVE RIVALRY


5.2
GLOBAL MACROECONOMIC OUTLOOK


5.2.1
GDP TRENDS


5.2.2
TRENDS IN GLOBAL ARTIFICIAL INTELLIGENCE INDUSTRY


5.3
VALUE CHAIN ANALYSIS


5.3.1
DATA CENTER CHILLERS VALUE CHAIN COMPRISES THE FOLLOWING STAGES:


5.4
ECOSYSTEM ANALYSIS


5.5
KEY CONFERENCES AND EVENTS, 2026–2027


5.6
TRENDS AND DISRUPTIONS IMPACTING CUSTOMER BUSINESS


5.7
INVESTMENT AND FUNDING SCENARIO


5.8
CASE STUDY ANALYSIS


5.8.1
CARRIER: INNOVATIVE HVAC SOLUTION TURNS DATA CENTERS INTO DISTRICT HEATING SOURCES


5.8.2
DANFOSS: 1,400-TON CHILLERS IMPROVE EFFICIENCY AND LOWER COSTS


6
TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
AI-driven adaptive controls and scalable chiller systems revolutionize efficiency and resilience in cooling technology.


63
 
6.1
KEY TECHNOLOGIES


6.1.1
SCREW CHILLERS


6.1.2
CENTRIFUGAL CHILLERS


6.1.3
SCROLL CHILLERS


6.2
ADJACENT TECHNOLOGIES


6.2.1
COOLING TOWERS


6.2.2
DRY COOLERS/FLUID COOLERS


6.3
COMPLEMENTARY TECHNOLOGIES


6.3.1
CHILLER PLANT CONTROLS


6.3.2
BUILDING MANAGEMENT SYSTEM (BMS)


6.4
PATENT ANALYSIS


6.4.1
INTRODUCTION


6.4.2
METHODOLOGY


6.4.3
DOCUMENT TYPE


6.4.4
INSIGHTS


6.4.5
LEGAL STATUS OF PATENTS


6.4.6
JURISDICTION ANALYSIS


6.4.7
TOP APPLICANTS


6.4.8
MAJOR PATENTS


6.5
FUTURE APPLICATIONS


6.5.1
AI-DRIVEN ADAPTIVE CHILLER CONTROL: REAL-TIME TEMPERATURE-BASED CONTROLS DYNAMICALLY ADJUST CHILLER AND AC OPERATION FOR HIGHER EFFICIENCY AND THERMAL ACCURACY


6.5.2
MODULAR & SCALABLE CHILLER ARCHITECTURES: PLUG-AND-PLAY COOLING MODULES ENABLE INCREMENTAL CAPACITY EXPANSION WITHOUT MAJOR INFRASTRUCTURE CHANGES


6.5.3
CASCADE & HYBRID MULTI-CHILLER SYSTEMS: HYBRID SYSTEMS OPTIMIZE PART-LOAD EFFICIENCY BY SWITCHING BETWEEN FREE COOLING AND MECHANICAL CHILLING BASED ON OUTDOOR TEMPERATURE


6.5.4
THERMAL STORAGE & EMERGENCY RESILIENCE SYSTEMS: BUFFER TANKS AND BACKUP CHILLERS ENSURE CONTINUOUS COOLING DURING OUTAGES AND DEMAND SPIKES


6.5.5
PRE-COOLING & IN-ROW DISTRIBUTED COOLING: PRE-COOLING CHILLERS WITH IN-ROW ACS ENABLE EFFICIENT, LOCALIZED COOLING FOR HIGH-DENSITY RACKS


6.6
IMPACT OF AI ON DATA CENTER CHILLERS MARKET


6.6.1
TOP USE CASES AND MARKET POTENTIAL


6.6.2
BEST PRACTICES: COMPANIES/INSTITUTIONS USE CASES


6.6.3
CASE STUDIES OF DATA CENTER CHILLERS MARKET


6.6.4
INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS


6.6.5
CLIENTS’ READINESS TO ADOPT GENERATIVE AI IN DATA CENTER CHILLERS MARKET


6.6.5.1
TRANE: 9,600 RT INTEGRATED CHILLER PLANT IN BEIJING, CHINA


6.6.5.2
CARRIER: IRON MOUNTAIN DATA CENTER, PENNSYLVANIA, US


7
SUSTAINABILITY AND REGULATORY LANDSCAPE
Navigate evolving eco-regulations and standards to optimize data center sustainability strategies.


82
 
7.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


7.1.1
INDUSTRY STANDARDS


7.2
SUSTAINABILITY INITIATIVES


7.2.1
CARBON IMPACT AND ECO APPLICATIONS OF DATA CENTER CHILLERS


7.3
SUSTAINABILITY IMPACT AND REGULATORY POLICY INITIATIVES


7.4
CERTIFICATIONS, LABELLING, AND ECO STANDARDS


8
CUSTOMER LANDSCAPE & BUYER BEHAVIOUR
Unlock revenue by targeting unmet needs and stakeholder influence in data center buying decisions.


95
 
8.1
DECISION-MAKING PROCESS


8.2
KEY STAKEHOLDERS AND BUYING CRITERIA


8.2.1
KEY STAKEHOLDERS IN BUYING PROCESS


8.2.2
BUYING CRITERIA


8.3
ADOPTION BARRIERS & INTERNAL CHALLENGES


8.4
UNMET NEEDS IN VARIOUS DATA CENTER TYPES


8.5
MARKET PROFITABILITY


8.5.1
REVENUE POTENTIAL


8.5.2
COST DYNAMICS


8.5.3
MARGIN OPPORTUNITIES IN KEY DATA CENTER TYPES


9
DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million | 8 Data Tables


108
 
9.1
INTRODUCTION


9.2
SCROLL CHILLERS


9.2.1
RISING DEPLOYMENT OF EDGE, ENTERPRISE, AND DISTRIBUTED DATA CENTERS FUELING DEMAND


9.3
SCREW CHILLERS


9.3.1
INCREASING MEDIUM-TO-HIGH RACK DENSITIES AND ADOPTION OF HYBRID AIR/LIQUID COOLING DRIVING DEMAND FOR FLEXIBLE SCREW CHILLERS


9.4
CENTRIFUGAL CHILLERS


9.4.1
RAPID EXPANSION OF HYPERSCALE AND AI DATA CENTERS WITH MULTI-MEGAWATT COOLING REQUIREMENTS TO FUEL GROWTH


10
DATA CENTER CHILLERS MARKET, BY CONDENSER TYPE
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million | 6 Data Tables


114
 
10.1
INTRODUCTION


10.2
AIR-COOLED CHILLERS


10.2.1
GROWING DATA CENTER DEPLOYMENT IN WATER-STRESSED REGIONS DRIVING DEMAND FOR AIR-COOLED


10.3
WATER-COOLED CHILLERS


10.3.1
RAPID EXPANSION OF HYPERSCALE AND AI DATA CENTERS WITH MULTI-MEGAWATT COOLING LOADS DRIVING DEMAND


11
DATA CENTER CHILLERS MARKET, BY COOLING CAPACITY
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million | 10 Data Tables


119
 
11.1
INTRODUCTION


11.2
BELOW 150 RT


11.2.1
EXPANSION OF EDGE, MICRO, TELECOM, AND SMALL ENTERPRISE DATA CENTERS DRIVING DEMAND FOR COMPACT AND MODULAR CHILLERS


11.3
150–700 RT


11.3.1
GROWING COLOCATION AND ENTERPRISE DATA CENTERS WITH RISING RACK DENSITIES DRIVING DEMAND FOR MEDIUM-CAPACITY CHILLERS


11.4
700–3,000 RT


11.4.1
INCREASING DEVELOPMENT OF LARGE HYPERSCALE, CLOUD, AND AI DATA CENTERS FUELING MARKET GROWTH


11.5
ABOVE 3,000 RT


11.5.1
RAPID SCALING OF HYPERSCALE AND AI DATA CENTER CAMPUSES DRIVING DEMAND FOR ULTRA-HIGH-CAPACITY CENTRIFUGAL CHILLER SYSTEMS


12
DATA CENTER CHILLERS MARKET, BY REGION
Comprehensive coverage of 8 Regions with country-level deep-dive of 21 Countries | 94 Data Tables.


126
 
12.1
INTRODUCTION


12.2
NORTH AMERICA


12.2.1
US


12.2.1.1
AI/HPC EXPANSION, HYPERSCALE CAMPUSES, HIGH RACK POWER DENSITY, CLOUD INVESTMENT, AND REPLACEMENT OF LEGACY CHILLERS BOOSTING DEMAND


12.2.2
CANADA


12.2.3
GROWING AI-COMPUTE TO SUPPORT MARKET GROWTH


12.2.4
MEXICO


12.2.4.1
NEARSHORING, CLOUD AND COLOCATION GROWTH, PROXIMITY TO US DIGITAL INFRASTRUCTURE, AND INDUSTRIAL DIGITALIZATION DRIVING GROWTH


12.3
EUROPE


12.3.1
GERMANY


12.3.2
FRANKFURT’S EXPANDING HYPERSCALE & COLOCATION MARKET, WASTE-HEAT RECOVERY REQUIREMENTS, AND GROWING AI WORKLOADS DRIVING MARKET GROWTH


12.3.3
UK


12.3.3.1
AI ADOPTION AND CRITICAL NATIONAL INFRASTRUCTURE STATUS FUELING DEMAND FOR DATA CENTER CHILLERS


12.3.4
FRANCE


12.3.4.1
GROWING AI INFRASTRUCTURE FUELING MARKET GROWTH


12.3.5
ITALY


12.3.5.1
MILAN DATA CENTER EXPANSION AND INCREASING CLOUD ADOPTION TO DRIVE MARKET


12.3.6
SPAIN


12.3.6.1
MADRID’S HYPERSCALE GROWTH FUELING MARKET EXPANSION


12.3.7
RUSSIA


12.3.7.1
RISING DEMAND FOR MODULAR AND LOCALLY SERVICEABLE COOLING SYSTEMS TO INCREASE ADOPTION


12.3.8
REST OF EUROPE


12.4
ASIA PACIFIC


12.4.1
CHINA


12.4.1.1
ADOPTION OF AI STRATEGY AND HYPERSCALE/CLOUD EXPANSION CREATING DEMAND


12.4.2
INDIA


12.4.2.1
GROWING AI INFRASTRUCTURE AND HYPERSCALE EXPANSION & CLOUD ADOPTION DRIVING DEMAND


12.4.3
JAPAN


12.4.3.1
DATA CENTER CONCENTRATION DUE TO LAND SCARCITY, ENERGY COSTS, AND ADVANCED AUTOMATION FUELING DEMAND


12.4.4
SOUTH KOREA


12.4.4.1
SEMICONDUCTOR & AI ECOSYSTEM FOR HYPERSCALE DEVELOPMENT SUPPORTING MARKET GROWTH


12.4.5
MALAYSIA


12.4.5.1
RAPID DATA CENTER EXPANSION DRIVING DEMAND FOR CHILLER SYSTEMS


12.4.6
THAILAND


12.4.6.1
GROWING DATA CENTER HUB IN BANGKOK AND EASTERN ECONOMIC CORRIDORS FUELING DEMAND


12.4.7
INDONESIA


12.4.7.1
GROWING DIGITAL ECONOMY, CLOUD ADOPTION, AND DATA-LOCALIZATION REQUIREMENTS TO DRIVE MARKET


12.4.8
REST OF ASIA PACIFIC


12.5
MIDDLE EAST & AFRICA


12.5.1
GCC COUNTRIES


12.5.1.1
UAE


12.5.1.1.1
G42/MICROSOFT INVESTMENT, STARGATE AI INFRASTRUCTURE, AND EXTREME TEMPERATURES TO DRIVE MARKET


12.5.1.2
SAUDI ARABIA


12.5.1.2.1
VISION 2030, ADOPTION OF SOVEREIGN AI, AND HYPERSCALE INVESTMENT TO SUPPORT MARKET GROWTH


12.5.1.3
REST OF GCC COUNTRIES


12.5.2
SOUTH AFRICA


12.5.2.1
ESTABLISHED COLOCATION MARKET, CLOUD ADOPTION, AND ENERGY-EFFICIENCY REQUIREMENTS TO FUEL MARKET


12.5.3
REST OF MIDDLE EAST & AFRICA


12.6
SOUTH AMERICA


12.6.1
BRAZIL


12.6.1.1
SÃO PAULO HYPERSCALE GROWTH, AI INFRASTRUCTURE, AND CLOUD ADOPTION FUELING DEMAND


12.6.2
CHILE


12.6.2.1
STRONG SUBMARINE CONNECTIVITY AND SANTIAGO’S EMERGENCE AS A REGIONAL DATA CENTER HUB TO SUPPORT GROWTH


12.6.3
REST OF SOUTH AMERICA


13
COMPETITIVE LANDSCAPE
Analyze strategic moves and revenue dominance of top market players shaping future competition.


165
 
13.1
INTRODUCTION


13.2
KEY PLAYERS’ STRATEGIES/RIGHT TO WIN


13.3
REVENUE ANALYSIS


13.3.1
TOP PLAYERS’ REVENUE ANALYSIS


13.4
MARKET SHARE ANALYSIS, 2025


13.4.1
RANKING ANALYSIS OF KEY MARKET PLAYERS


13.4.2
MARKET SHARE ANALYSIS, 2025


13.5
BRAND/PRODUCT COMPARISON


13.5.1
STULZ


13.5.2
VERTIV


13.5.3
TRANE


13.5.4
MUNTERS


13.5.5
DAIKIN


13.6
COMPANY VALUATION AND FINANCIAL METRICS


13.7
COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025


13.7.1
STARS


13.7.2
EMERGING LEADERS


13.7.3
PERVASIVE PLAYERS


13.7.4
PARTICIPANTS


13.7.5
COMPANY FOOTPRINT: KEY PLAYERS, 2025


13.7.5.1
COMPANY FOOTPRINT


13.7.6
REGION FOOTPRINT


13.7.7
CONDENSER TYPE FOOTPRINT


13.7.8
COOLING CAPACITY FOOTPRINT


13.7.9
PRODUCT TYPE FOOTPRINT


13.8
COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025


13.8.1
PROGRESSIVE COMPANIES


13.8.2
RESPONSIVE COMPANIES


13.8.3
DYNAMIC COMPANIES


13.8.4
STARTING BLOCKS


13.8.5
COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025


13.8.5.1
DETAILED LIST OF KEY STARTUPS/SMES


13.8.6
COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES


13.9
COMPETITIVE SCENARIO


13.9.1
PRODUCT LAUNCHES


13.9.2
DEALS


14
COMPANY PROFILE


187
 
14.1
KEY PLAYERS


14.1.1
JOHNSON CONTROLS


14.1.1.1
BUSINESS OVERVIEW


14.1.1.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.1.3
RECENT DEVELOPMENTS


14.1.1.3.1
PRODUCT LAUNCHES


14.1.1.4
MNM VIEW


14.1.1.4.1
KEY STRENGTHS


14.1.1.4.2
STRATEGIC CHOICES


14.1.1.4.3
WEAKNESSES AND COMPETITIVE THREATS


14.1.2
TRANE


14.1.2.1
BUSINESS OVERVIEW


14.1.2.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.2.3
RECENT DEVELOPMENTS


14.1.2.3.1
PRODUCT LAUNCHES


14.1.2.3.2
DEALS


14.1.2.4
MNM VIEW


14.1.2.4.1
KEY STRENGTHS


14.1.2.4.2
STRATEGIC CHOICES


14.1.2.4.3
WEAKNESSES AND COMPETITIVE THREATS


14.1.3
CARRIER


14.1.3.1
BUSINESS OVERVIEW


14.1.3.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.3.3
RECENT DEVELOPMENTS


14.1.3.3.1
PRODUCT LAUNCHES


14.1.3.3.2
DEALS


14.1.3.4
MNM VIEW


14.1.3.4.1
KEY STRENGTHS


14.1.3.4.2
STRATEGIC CHOICES


14.1.3.4.3
WEAKNESSES AND COMPETITIVE THREATS


14.1.4
DAIKIN APPLIED


14.1.4.1
BUSINESS OVERVIEW


14.1.4.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.4.3
RECENT DEVELOPMENTS


14.1.4.3.1
PRODUCT LAUNCHES


14.1.4.3.2
DEALS


14.1.4.3.3
EXPANSIONS


14.1.4.4
MNM VIEW


14.1.4.4.1
KEY STRENGTHS


14.1.4.4.2
STRATEGIC CHOICES


14.1.4.4.3
WEAKNESSES AND COMPETITIVE THREATS


14.1.5
VERTIV GROUP CORP.


14.1.5.1
BUSINESS OVERVIEW


14.1.5.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.5.3
RECENT DEVELOPMENTS


14.1.5.3.1
PRODUCT LAUNCHES


14.1.5.3.2
DEALS


14.1.5.3.3
EXPANSIONS


14.1.5.4
MNM VIEW


14.1.5.4.1
KEY STRENGTHS


14.1.5.4.2
STRATEGIC CHOICES


14.1.5.4.3
WEAKNESSES AND COMPETITIVE THREATS


14.1.6
MODINE


14.1.6.1
BUSINESS OVERVIEW


14.1.6.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.6.3
RECENT DEVELOPMENTS


14.1.6.3.1
PRODUCT LAUNCHES


14.1.6.3.2
DEALS


14.1.6.3.3
EXPANSIONS


14.1.7
SCHNEIDER ELECTRIC


14.1.7.1
BUSINESS OVERVIEW


14.1.7.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.7.3
RECENT DEVELOPMENTS


14.1.7.3.1
PRODUCT LAUNCHES


14.1.7.3.2
DEALS


14.1.8
MUNTERS


14.1.8.1
BUSINESS OVERVIEW


14.1.8.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.9
MITSUBISHI ELECTRIC CORPORATION


14.1.9.1
BUSINESS OVERVIEW


14.1.9.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.9.3
RECENT DEVELOPMENTS


14.1.9.3.1
PRODUCT LAUNCHES


14.1.9.3.2
EXPANSIONS


14.1.10
LENNOX INTERNATIONAL INC.


14.1.10.1
BUSINESS OVERVIEW


14.1.10.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.11
DANFOSS


14.1.11.1
BUSINESS OVERVIEW


14.1.11.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.12
STULZ GMBH


14.1.12.1
BUSINESS OVERVIEW


14.1.12.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.13
GEA GROUP AKTIENGESELLSCHAFT


14.1.13.1
BUSINESS OVERVIEW


14.1.13.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.14
RITTAL GMBH & CO. KG


14.1.14.1
BUSINESS OVERVIEW


14.1.14.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.15
BLUE STAR LIMITED


14.1.15.1
BUSINESS OVERVIEW


14.1.15.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.16
KIRLOSKAR CHILLERS PRIVATE LIMITED


14.1.16.1
BUSINESS OVERVIEW


14.1.16.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.17
LG ELECTRONICS


14.1.17.1
BUSINESS OVERVIEW


14.1.17.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.17.3
RECENT DEVELOPMENTS


14.1.17.3.1
DEALS


14.1.18
PANASONIC HOLDINGS CORPORATION


14.1.18.1
BUSINESS OVERVIEW


14.1.18.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.18.3
RECENT DEVELOPMENTS


14.1.18.3.1
EXPANSIONS


14.1.19
THERMAL CARE


14.1.19.1
BUSINESS OVERVIEW


14.1.19.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.20
GD MIDEA HEATING & VENTILATING EQUIPMENT CO., LTD.


14.1.20.1
BUSINESS OVERVIEW


14.1.20.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.20.3
RECENT DEVELOPMENTS


14.1.20.3.1
PRODUCT LAUNCHES


14.1.21
DELTA ELECTRONICS, INC.


14.1.21.1
BUSINESS OVERVIEW


14.1.21.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.22
THERMAX LIMITED


14.1.22.1
BUSINESS OVERVIEW


14.1.22.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.2
OTHER PLAYERS


14.2.1
MULTISTACK


14.2.2
AERMEC S.P.A.


14.2.3
VOLTAS LIMITED


15
RESEARCH METHODOLOGY


260
 
15.1
RESEARCH DATA


15.1.1
SECONDARY DATA


15.1.1.1
LIST OF KEY SECONDARY SOURCES


15.1.2
PRIMARY DATA


15.1.2.1
LIST OF PARTICIPATING COMPANIES FOR PRIMARY RESEARCH


15.2
MARKET SIZE ESTIMATION


15.2.1
TOP-DOWN APPROACH


15.2.2
BOTTOM-UP APPROACH


15.3
MARKET FORECAST APPROACH


15.3.1
DEMAND-SIDE ANALYSIS


15.3.2
SUPPLY-SIDE ANALYSIS


15.3.3
CALCULATION FOR SUPPLY-SIDE ANALYSIS


15.4
GROWTH FORECAST


15.5
DATA TRIANGULATION


15.6
FACTOR ANALYSIS


16
APPENDIX


270
 
16.1
DISCUSSION GUIDE


16.2
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL


16.3
CUSTOMIZATION OPTIONS


16.4
RELATED REPORTS


16.5
AUTHOR DETAILS


LIST OF TABLES


TABLE 1
DATA CENTER CHILLERS MARKET: INCLUSIONS AND EXCLUSIONS


TABLE 2
DATA CENTER CHILLERS MARKET: IMPACT OF PORTER’S FIVE FORCES


TABLE 3
REAL GDP GROWTH (ANNUAL PERCENTAGE CHANGE), BY COUNTRY, 2021–2025


TABLE 4
UNEMPLOYMENT RATE, BY COUNTRY, 2021–2025 (%)


TABLE 5
INFLATION RATE (AVERAGE CONSUMER PRICES), BY COUNTRY, 2021–2025 (%)


TABLE 6
FOREIGN DIRECT INVESTMENT, 2022 VS. 2023 (USD BILLION)


TABLE 7
DATA CENTER CHILLERS MARKET: ROLE OF COMPANIES IN ECOSYSTEM


TABLE 8
DATA CENTER CHILLERS MARKET: LIST OF KEY CONFERENCES AND EVENTS, 2026–2027


TABLE 9
DATA CENTER CHILLERS MARKET: TOTAL NUMBER OF PATENTS, 2015–2025


TABLE 10
TOP USE CASES AND MARKET POTENTIAL


TABLE 11
BEST PRACTICES: COMPANIES IMPLEMENTING USE CASES


TABLE 12
DATA CENTER CHILLERS MARKET: CASE STUDIES RELATED TO GEN AI IMPLEMENTATION


TABLE 13
INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS


TABLE 14
NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 15
EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 16
ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 17
ROW: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 18
STANDARDS FOR DATA CENTER COOLING


TABLE 19
MAJOR REGULATORY POLICY INITIATIVES:


TABLE 20
CERTIFICATIONS, LABELING, AND ECO STANDARDS IN DATA CENTER CHILLERS MARKET


TABLE 21
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR DATA CENTER TYPES (%)


TABLE 22
KEY BUYING CRITERIA, BY DATA CENTER TYPE


TABLE 23
DATA CENTER CHILLERS MARKET: UNMET NEEDS IN KEY DATA CENTER TYPES


TABLE 24
DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 25
DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 26
SCROLL CHILLERS: DATA CENTER CHILLERS MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 27
SCROLL CHILLERS: DATA CENTER CHILLERS MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 28
SCREW CHILLERS: DATA CENTER CHILLERS MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 29
SCREW CHILLERS: DATA CENTER CHILLERS MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 30
CENTRIFUGAL CHILLERS: DATA CENTER CHILLERS MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 31
CENTRIFUGAL CHILLERS: DATA CENTER CHILLERS MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 32
DATA CENTER CHILLERS MARKET, BY CONDENSER TYPE, 2022–2025 (USD MILLION)


TABLE 33
DATA CENTER CHILLERS MARKET, BY CONDENSER TYPE, 2026–2033 (USD MILLION)


TABLE 34
AIR-COOLED CHILLERS: DATA CENTER CHILLERS MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 35
AIR-COOLED CHILLERS: DATA CENTER CHILLERS MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 36
WATER-COOLED CHILLERS: DATA CENTER CHILLERS MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 37
WATER-COOLED CHILLERS: DATA CENTER CHILLERS MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 38
DATA CENTER CHILLERS MARKET, BY COOLING CAPACITY, 2022–2025 (USD MILLION)


TABLE 39
DATA CENTER CHILLERS MARKET, BY COOLING CAPACITY, 2026–2033 (USD MILLION)


TABLE 40
BELOW 150 RT: DATA CENTER CHILLERS MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 41
BELOW 150 RT: DATA CENTER CHILLERS MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 42
150–700 RT: DATA CENTER CHILLERS MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 43
150–700 RT: DATA CENTER CHILLERS MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 44
700–3,000 RT: DATA CENTER CHILLERS MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 45
700–3,000 RT: DATA CENTER CHILLERS MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 46
ABOVE 3,000 RT: DATA CENTER CHILLERS MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 47
ABOVE 3,000 RT: DATA CENTER CHILLERS MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 48
DATA CENTER CHILLERS MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 49
DATA CENTER CHILLERS MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 50
NORTH AMERICA: DATA CENTER CHILLERS MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 51
NORTH AMERICA: DATA CENTER CHILLERS MARKET, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 52
NORTH AMERICA: DATA CENTER CHILLERS MARKET, BY CONDENSER TYPE, 2022–2025 (USD MILLION)


TABLE 53
NORTH AMERICA: DATA CENTER CHILLERS MARKET, BY CONDENSER TYPE, 2026–2033 (USD MILLION)


TABLE 54
NORTH AMERICA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 55
NORTH AMERICA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 56
NORTH AMERICA: DATA CENTER CHILLERS MARKET, BY COOLING CAPACITY, 2022–2025 (USD MILLION)


TABLE 57
NORTH AMERICA: DATA CENTER CHILLERS MARKET, BY COOLING CAPACITY, 2026–2033 (USD MILLION)


TABLE 58
US: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 59
US: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 60
CANADA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 61
CANADA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 62
MEXICO: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 63
MEXICO: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 64
EUROPE: DATA CENTER CHILLERS MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 65
EUROPE: DATA CENTER CHILLERS MARKET, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 66
EUROPE: DATA CENTER CHILLERS MARKET, BY CONDENSER TYPE, 2022–2025 (USD MILLION)


TABLE 67
EUROPE: DATA CENTER CHILLERS MARKET, BY CONDENSER TYPE, 2026–2033 (USD MILLION)


TABLE 68
EUROPE: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 69
EUROPE: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 70
EUROPE: DATA CENTER CHILLERS MARKET, BY COOLING CAPACITY, 2022–2025 (USD MILLION)


TABLE 71
EUROPE: DATA CENTER CHILLERS MARKET, BY COOLING CAPACITY, 2026–2033 (USD MILLION)


TABLE 72
GERMANY: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 73
GERMANY: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 74
UK: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 75
UK: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 76
FRANCE: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 77
FRANCE: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 78
ITALY: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 79
ITALY: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 80
SPAIN: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 81
SPAIN: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 82
RUSSIA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 83
RUSSIA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 84
REST OF EUROPE: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 85
REST OF EUROPE: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 86
ASIA PACIFIC: DATA CENTER CHILLERS MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 87
ASIA PACIFIC: DATA CENTER CHILLERS MARKET, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 88
ASIA PACIFIC: DATA CENTER CHILLERS MARKET, BY CONDENSER TYPE, 2022–2025 (USD MILLION)


TABLE 89
ASIA PACIFIC: DATA CENTER CHILLERS MARKET, BY CONDENSER TYPE, 2026–2033 (USD MILLION)


TABLE 90
ASIA PACIFIC: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 91
ASIA PACIFIC: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 92
ASIA PACIFIC: DATA CENTER CHILLERS MARKET, BY COOLING CAPACITY, 2022–2025 (USD MILLION)


TABLE 93
ASIA PACIFIC: DATA CENTER CHILLERS MARKET, BY COOLING CAPACITY, 2026–2033 (USD MILLION)


TABLE 94
CHINA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 95
CHINA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 96
INDIA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 97
INDIA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 98
JAPAN: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 99
JAPAN: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 100
SOUTH KOREA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 101
SOUTH KOREA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 102
MALAYSIA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 103
MALAYSIA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 104
THAILAND: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 105
THAILAND: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 106
INDONESIA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 107
INDONESIA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 108
REST OF ASIA PACIFIC: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 109
REST OF ASIA PACIFIC: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 110
MIDDLE EAST & AFRICA: DATA CENTER CHILLERS MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 111
MIDDLE EAST & AFRICA: DATA CENTER CHILLERS MARKET, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 112
MIDDLE EAST & AFRICA: DATA CENTER CHILLERS MARKET, BY CONDENSER TYPE, 2022–2025 (USD MILLION)


TABLE 113
MIDDLE EAST & AFRICA: DATA CENTER CHILLERS MARKET, BY CONDENSER TYPE, 2026–2033 (USD MILLION)


TABLE 114
MIDDLE EAST & AFRICA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 115
MIDDLE EAST & AFRICA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 116
MIDDLE EAST & AFRICA: DATA CENTER CHILLERS MARKET, BY COOLING CAPACITY, 2022–2025 (USD MILLION)


TABLE 117
MIDDLE EAST & AFRICA: DATA CENTER CHILLERS MARKET, BY COOLING CAPACITY, 2026–2033 (USD MILLION)


TABLE 118
UAE: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 119
UAE: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 120
SAUDI ARABIA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 121
SAUDI ARABIA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 122
REST OF GCC COUNTRIES: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 123
REST OF GCC COUNTRIES: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 124
SOUTH AFRICA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 125
SOUTH AFRICA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 126
REST OF MIDDLE EAST & AFRICA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 127
REST OF MIDDLE EAST & AFRICA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 128
SOUTH AMERICA: DATA CENTER CHILLERS MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 129
SOUTH AMERICA: DATA CENTER CHILLERS MARKET, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 130
SOUTH AMERICA: DATA CENTER CHILLERS MARKET, BY CONDENSER TYPE, 2022–2025 (USD MILLION)


TABLE 131
SOUTH AMERICA: DATA CENTER CHILLERS MARKET, BY CONDENSER TYPE, 2026–2033 (USD MILLION)


TABLE 132
SOUTH AMERICA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 133
SOUTH AMERICA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 134
SOUTH AMERICA: DATA CENTER CHILLERS MARKET, BY COOLING CAPACITY, 2022–2025 (USD MILLION)


TABLE 135
SOUTH AMERICA: DATA CENTER CHILLERS MARKET, BY COOLING CAPACITY, 2026–2033 (USD MILLION)


TABLE 136
BRAZIL: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 137
BRAZIL: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 138
CHILE: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 139
CHILE: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 140
REST OF SOUTH AMERICA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2022–2025 (USD MILLION)


TABLE 141
REST OF SOUTH AMERICA: DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE, 2026–2033 (USD MILLION)


TABLE 142
DATA CENTER CHILLERS MARKET: OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS, 2021–2026


TABLE 143
DATA CENTER CHILLERS MARKET: DEGREE OF COMPETITION, 2025


TABLE 144
DATA CENTER CHILLERS MARKET: REGION FOOTPRINT


TABLE 145
DATA CENTER CHILLERS MARKET: CONDENSER TYPE FOOTPRINT


TABLE 146
DATA CENTER CHILLERS MARKET: COOLING CAPACITY FOOTPRINT


TABLE 147
DATA CENTER CHILLERS MARKET: PRODUCT TYPE FOOTPRINT


TABLE 148
DATA CENTER CHILLERS MARKET: DETAILED LIST OF KEY STARTUPS/SMES


TABLE 149
DATA CENTER CHILLERS MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES (1/2)


TABLE 150
DATA CENTER CHILLERS MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES (2/2)


TABLE 151
DATA CENTER CHILLERS MARKET: PRODUCT LAUNCHES, JANUARY 2021–AUGUST 2026


TABLE 152
DATA CENTER CHILLERS MARKET: DEALS, JANUARY 2021–AUGUST 2026


TABLE 153
JOHNSON CONTROLS: COMPANY OVERVIEW


TABLE 154
JOHNSON CONTROLS: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 155
JOHNSON CONTROLS: PRODUCT LAUNCHES


TABLE 156
TRANE: COMPANY OVERVIEW


TABLE 157
TRANE: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 158
TRANE: PRODUCT LAUNCHES


TABLE 159
TRANE: DEALS


TABLE 160
CARRIER: COMPANY OVERVIEW


TABLE 161
CARRIER: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 162
CARRIER: PRODUCT LAUNCHES


TABLE 163
CARRIER: DEALS


TABLE 164
DAIKIN APPLIED: COMPANY OVERVIEW


TABLE 165
DAIKIN APPLIED: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 166
DAIKIN APPLIED: PRODUCT LAUNCHES


TABLE 167
DAIKIN APPLIED: DEALS


TABLE 168
DAIKIN APPLIED: EXPANSIONS


TABLE 169
VERTIV GROUP CORP.: COMPANY OVERVIEW


TABLE 170
VERTIV GROUP CORP.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 171
VERTIV GROUP CORP.: PRODUCT LAUNCHES


TABLE 172
VERTIV GROUP CORP.: DEALS


TABLE 173
VERTIV GROUP CORP.: EXPANSIONS


TABLE 174
MODINE: COMPANY OVERVIEW


TABLE 175
MODINE: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 176
MODINE: PRODUCT LAUNCHES


TABLE 177
MODINE: DEALS


TABLE 178
MODINE: EXPANSIONS


TABLE 179
SCHNEIDER ELECTRIC: COMPANY OVERVIEW


TABLE 180
SCHNEIDER ELECTRIC: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 181
SCHNEIDER ELECTRIC: PRODUCT LAUNCHES


TABLE 182
SCHNEIDER ELECTRIC: DEALS


TABLE 183
MUNTERS: COMPANY OVERVIEW


TABLE 184
MUNTERS: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 185
MITSUBISHI ELECTRIC CORPORATION: COMPANY OVERVIEW


TABLE 186
MITSUBISHI ELECTRIC CORPORATION: PRODUCTS/SOLUTIONS/ SERVICES OFFERED


TABLE 187
MITSUBISHI ELECTRIC CORPORATION: PRODUCT LAUNCHES


TABLE 188
MITSUBISHI ELECTRIC CORPORATION: EXPANSIONS


TABLE 189
LENNOX INTERNATIONAL INC.: COMPANY OVERVIEW


TABLE 190
LENNOX INTERNATIONAL INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 191
DANFOSS: COMPANY OVERVIEW


TABLE 192
DANFOSS: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 193
STULZ GMBH: COMPANY OVERVIEW


TABLE 194
STULZ GMBH: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 195
GEA GROUP AKTIENGESELLSCHAFT: COMPANY OVERVIEW


TABLE 196
GEA GROUP AKTIENGESELLSCHAFT: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 197
RITTAL GMBH & CO. KG: COMPANY OVERVIEW


TABLE 198
RITTAL GMBH & CO. KG: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 199
BLUE STAR LIMITED: COMPANY OVERVIEW


TABLE 200
BLUE STAR LIMITED: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 201
KIRLOSKAR CHILLERS PRIVATE LIMITED: COMPANY OVERVIEW


TABLE 202
KIRLOSKAR CHILLERS PRIVATE LIMITED: PRODUCTS/SOLUTIONS/ SERVICES OFFERED


TABLE 203
LG ELECTRONICS: COMPANY OVERVIEW


TABLE 204
LG ELECTRONICS: PRODUCTS OFFERED


TABLE 205
LG ELECTRONICS: DEALS


TABLE 206
PANASONIC HOLDINGS CORPORATION: COMPANY OVERVIEW


TABLE 207
PANASONIC HOLDINGS CORPORATION: PRODUCTS/SOLUTIONS/ SERVICES OFFERED


TABLE 208
PANASONIC HOLDINGS CORPORATION: EXPANSIONS


TABLE 209
THERMAL CARE: COMPANY OVERVIEW


TABLE 210
THERMAL CARE: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 211
GD MIDEA HEATING & VENTILATING EQUIPMENT CO., LTD.: COMPANY OVERVIEW


TABLE 212
GD MIDEA HEATING & VENTILATING EQUIPMENT CO., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 213
GD MIDEA HEATING & VENTILATING EQUIPMENT CO., LTD.: PRODUCT LAUNCHES


TABLE 214
DELTA ELECTRONICS, INC.: COMPANY OVERVIEW


TABLE 215
DELTA ELECTRONICS, INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 216
THERMAX LIMITED: COMPANY OVERVIEW


TABLE 217
THERMAX LIMITED: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 218
MULTISTACK: COMPANY OVERVIEW


TABLE 219
AERMEC S.P.A.: COMPANY OVERVIEW


TABLE 220
VOLTAS LIMITED: COMPANY OVERVIEW


LIST OF FIGURES


FIGURE 1
DATA CENTER CHILLERS MARKET: SEGMENTATION AND REGIONAL SCOPE


FIGURE 2
KEY INSIGHTS AND MARKET HIGHLIGHTS


FIGURE 3
GLOBAL DATA CENTER CHILLERS MARKET, 2026–2033


FIGURE 4
MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN DATA CENTER CHILLERS MARKET (2020–2025)


FIGURE 5
DISRUPTIVE TRENDS IMPACTING GROWTH OF DATA CENTER CHILLERS MARKET


FIGURE 6
HIGH-GROWTH SEGMENTS IN DATA CENTER CHILLERS MARKET


FIGURE 7
NORTH AMERICA TO EXHIBIT FASTEST GROWTH DURING FORECAST PERIOD


FIGURE 8
RAPID ADOPTION OF AI, ML, AND BLOCKCHAIN TECHNOLOGIES TO CREATE LUCRATIVE OPPORTUNITIES FOR MARKET PLAYERS


FIGURE 9
AIR-COOLED CHILLERS TO BE LARGEST SEGMENT DURING FORECAST PERIOD


FIGURE 10
CENTRIFUGAL CHILLERS TO SECURE LEADING POSITION DURING FORECAST PERIOD


FIGURE 11
700–3,000 RT TO ACCOUNT FOR LARGEST MARKET SHARE DURING FORECAST PERIOD


FIGURE 12
NORTH AMERICA TO DOMINATE GLOBAL DATA CENTER CHILLERS MARKET


FIGURE 13
US TO BE FASTEST-GROWING MARKET DURING FORECAST PERIOD


FIGURE 14
DATA CENTER CHILLERS MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES


FIGURE 15
DATA CENTER COOLING TECHNOLOGIES, BY SERVER RACK POWER DENSITY


FIGURE 16
GLOBAL DATA CENTER POWER USAGE EFFECTIVENESS


FIGURE 17
DATA CENTER CHILLERS MARKET: PORTER’S FIVE FORCES ANALYSIS


FIGURE 18
GROWTH IN AI MARKET 2023 TO 2033


FIGURE 19
DATA CENTER CHILLERS MARKET: VALUE CHAIN ANALYSIS


FIGURE 20
DATA CENTER CHILLERS MARKET: ECOSYSTEM MAPPING


FIGURE 21
TRENDS/DISRUPTIONS IMPACTING CUSTOMERS’ BUSINESSES


FIGURE 22
INVESTMENT AND FUNDING SCENARIO, 2021–2026


FIGURE 23
PATENT ANALYSIS, BY DOCUMENT TYPE, 2015–2025


FIGURE 24
PATENT PUBLICATION TRENDS, 2015–2025


FIGURE 25
LEGAL STATUS OF PATENTS, JANUARY 2015–DECEMBER 2025


FIGURE 26
JURISDICTION OF CHINA REGISTERED HIGHEST SHARE OF PATENTS, 2015–2025


FIGURE 27
TOP PATENT APPLICANTS, 2015–2025


FIGURE 28
FUTURE APPLICATIONS OF DATA CENTER CHILLERS


FIGURE 29
SUCCESS STORIES AND REAL-WORLD APPLICATIONS


FIGURE 30
DATA CENTER CHILLERS MARKET: DECISION MAKING FACTORS


FIGURE 31
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR DATA CENTER TYPES


FIGURE 32
KEY BUYING CRITERIA, BY DATA CENTER TYPE


FIGURE 33
ADOPTION BARRIERS AND INTERNAL CHALLENGES


FIGURE 34
CENTRIFUGAL CHILLERS SEGMENT TO REGISTER HIGHER CAGR DURING FORECAST PERIOD


FIGURE 35
AIR-COOLED CHILLERS SEGMENT TO REGISTER HIGHER CAGR DURING FORECAST PERIOD


FIGURE 36
700–3,000 RT SEGMENT TO ACCOUNT FOR LARGEST MARKET SHARE DURING FORECAST PERIOD


FIGURE 37
NORTH AMERICA TO RECORD HIGHEST CAGR IN DATA CENTER CHILLERS MARKET DURING FORECAST PERIOD


FIGURE 38
NORTH AMERICA: DATA CENTER CHILLERS MARKET SNAPSHOT


FIGURE 39
EUROPE: DATA CENTER CHILLERS MARKET SNAPSHOT


FIGURE 40
ASIA PACIFIC: DATA CENTER CHILLERS MARKET SNAPSHOT


FIGURE 41
DATA CENTER CHILLERS MARKET: REVENUE ANALYSIS OF KEY COMPANIES, 2021–2025


FIGURE 42
DATA CENTER CHILLERS MARKET: RANKING OF TOP FIVE PLAYERS, 2025


FIGURE 43
DATA CENTER CHILLERS MARKET SHARE ANALYSIS, 2025


FIGURE 44
DATA CENTER CHILLERS MARKET: BRAND/PRODUCT COMPARISON


FIGURE 45
DATA CENTER CHILLERS MARKET: EV/EBITDA


FIGURE 46
DATA CENTER CHILLERS MARKET: EV/REVENUE


FIGURE 47
DATA CENTER CHILLERS MARKET: YEAR-TO-DATE (YTD) PRICE TOTAL RETURN AND FIVE-YEAR STOCK BETA OF KEY MANUFACTURERS


FIGURE 48
DATA CENTER CHILLERS MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025


FIGURE 49
DATA CENTER CHILLERS MARKET: COMPANY FOOTPRINT


FIGURE 50
DATA CENTER CHILLERS MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025


FIGURE 51
JOHNSON CONTROLS: COMPANY SNAPSHOT


FIGURE 52
TRANE: COMPANY SNAPSHOT


FIGURE 53
CARRIER: COMPANY SNAPSHOT


FIGURE 54
DAIKIN APPLIED: COMPANY SNAPSHOT


FIGURE 55
VERTIV GROUP CORP.: COMPANY SNAPSHOT


FIGURE 56
MODINE: COMPANY SNAPSHOT


FIGURE 57
SCHNEIDER ELECTRIC: COMPANY SNAPSHOT


FIGURE 58
MUNTERS: COMPANY SNAPSHOT


FIGURE 59
MITSUBISHI ELECTRIC CORPORATION: COMPANY SNAPSHOT


FIGURE 60
LENNOX INTERNATIONAL INC.: COMPANY SNAPSHOT


FIGURE 61
DANFOSS: COMPANY SNAPSHOT


FIGURE 62
GEA GROUP AKTIENGESELLSCHAFT: COMPANY SNAPSHOT


FIGURE 63
BLUE STAR LIMITED: COMPANY SNAPSHOT


FIGURE 64
LG ELECTRONICS: COMPANY SNAPSHOT


FIGURE 65
PANASONIC HOLDINGS CORPORATION: COMPANY SNAPSHOT


FIGURE 66
GD MIDEA HEATING & VENTILATING EQUIPMENT CO., LTD.: COMPANY SNAPSHOT


FIGURE 67
DELTA ELECTRONICS, INC.: COMPANY SNAPSHOT


FIGURE 68
THERMAX LIMITED: COMPANY SNAPSHOT


FIGURE 69
DATA CENTER CHILLERS MARKET: RESEARCH DESIGN


FIGURE 70
KEY DATA FROM SECONDARY SOURCES


FIGURE 71
KEY DATA FROM PRIMARY SOURCES


FIGURE 72
KEY INDUSTRY INSIGHTS


FIGURE 73
BREAKDOWN OF PRIMARY INTERVIEWS


FIGURE 74
MARKET SIZE ESTIMATION: TOP-DOWN APPROACH


FIGURE 75
MARKET SIZE ESTIMATION: BOTTOM-UP APPROACH


FIGURE 76
MAIN MATRIX CONSIDERED TO ASSESS DEMAND FOR DATA CENTER CHILLERS


FIGURE 77
STEPS CONSIDERED TO ANALYZE SUPPLY OF DATA CENTER CHILLERS


FIGURE 78
DATA TRIANGULATION: DATA CENTER CHILLERS MARKET


FIGURE 79
RESEARCH ASSUMPTIONS


FIGURE 80
RESEARCH LIMITATIONS


FIGURE 81
RISK ASSESSMENT


FIGURE 82
FACTOR ANALYSIS


Methodology

The study involved four major activities in estimating the current size of the data center chillers market. Exhaustive secondary research was done to collect information on the market, peer markets, and the parent market. The next step was to validate these findings, assumptions, and sizing with industry experts across the data center chillers value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the complete market size. Thereafter, market breakdown and data triangulation were used to estimate the market size of segments and subsegments.

Secondary Research

Secondary sources for this research study include annual reports, press releases, and investor presentations of companies; white papers; certified publications; and articles by recognized authors; gold- and silver-standard websites; data center chiller manufacturing companies, regulatory bodies, trade directories, and databases. The secondary research was mainly used to obtain key information about the industry's supply chain, the total pool of key players, market classification, and segmentation according to industry trends to the bottom-most level and regional markets. It has also been used to obtain information about key developments from a market-oriented perspective.

Primary Research

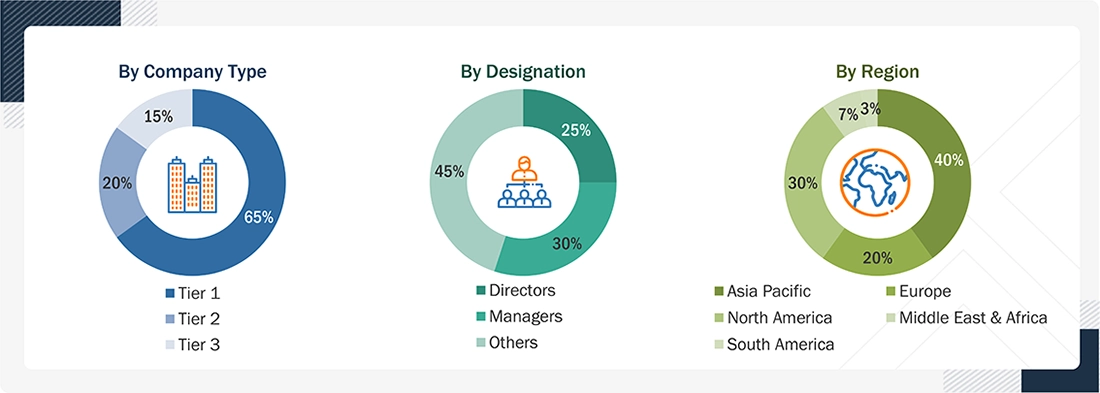
The data center chillers market comprises several stakeholders, such as raw material suppliers, technology support providers, and regulatory organizations in the supply chain. Various primary sources from both the supply and demand sides of the market were interviewed to obtain qualitative and quantitative information. Primary sources from the supply side included industry experts such as Chief Executive Officers (CEOs), vice presidents, marketing directors, technology and innovation directors, and related key executives from various key companies and organizations operating in the data center chillers market. Primary sources from the demand side included directors, marketing heads, and purchase managers from various sourcing industries. The following is the breakdown of the primary respondents:

Data Center Chillers Market 
 Size, and Share

To know about the assumptions considered for the study, download the pdf brochure

Market Size Estimation

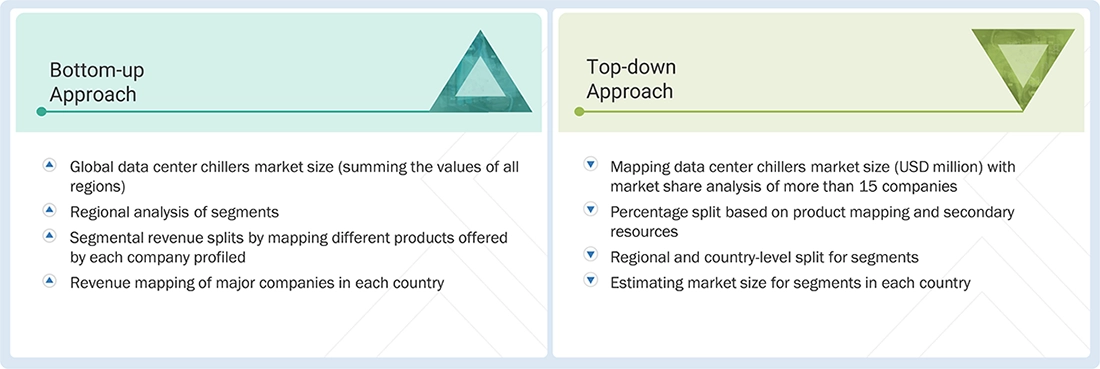
The top-down and bottom-up approaches have been employed to estimate and validate the total size of the data center chillers market. These approaches have also been used extensively to estimate the size of various dependent market subsegments. The research methodology used to estimate the market size included the following:
The following segments provide details about the overall market size estimation process employed in this study:

  • Extensive primary and secondary research was done to identify the key players.
  • The value chain and market size of the data center chillers market, in terms of value, were determined through primary and secondary research.
  • All percentage shares, splits, and breakdowns were collected through secondary sources and verified through primary sources.
  • All possible parameters that affect the market were covered in this research study and are viewed in extensive detail, verified through primary research, and analyzed to obtain the final quantitative and qualitative data.
  • The study of reports, reviews, and newsletters of top market players, along with extensive interviews for opinions from key leaders, such as CEOs, directors, and marketing executives, is included in this research.

Global Data Center Chillers  Market Size: Bottom-Up & Top-Down Approach

Data Center Chillers Market Top Down and Bottom Up Approach

Data Triangulation

After arriving at the overall market size using the market size estimation processes as explained above, the market was split into several segments and sub-segments. To complete the overall market engineering process and arrive at the exact statistics of each market segment and subsegment, the data triangulation and market breakdown procedures were employed, wherever applicable. The data was triangulated by studying various factors and trends from both the demand and supply sides.

Market Definition

Data center chillers are specialized cooling systems designed to remove and manage the heat generated by servers, storage systems, networking equipment, and other IT infrastructure within data centers. They operate by circulating a cooling medium, such as chilled water or liquid coolant, to absorb heat from critical equipment and transfer it away from the facility, thereby maintaining optimal operating temperatures. Data center chillers play a crucial role in ensuring equipment reliability, preventing overheating, improving energy efficiency, and supporting the continuous operation of data centers, particularly as computing workloads become more intensive and server densities continue to increase.

Key Stakeholders

  • Data Center Chiller Manufacturers, Data Center Operators, Engineering and System Integration Companies, and Component Suppliers.
  • Research Institutions, Standards Organizations, and Regulatory Agencies such as ASTM, EDQM, and Others
  • NGOs, Governments, Investment Banks, Venture Capitalists, and Private Equity Firms

Report Objectives

  • To define, describe, and forecast the market size of data center chillers in terms of value
  • To provide detailed information regarding the key factors, such as drivers, restraints, opportunities, and industry-specific challenges, influencing the growth of the data center chillers  market
  • To analyze and forecast the global data center chillers market based on product type, condenser type, cooling capacity, and region
  • To analyze the opportunities in the market for stakeholders and provide details of a competitive landscape for market leaders
  • To forecast the size of various market segments based on five major regions: North America, Asia Pacific, Europe, Middle East & Africa, and South America along with their respective key countries
  • To track and analyze the competitive developments, such as acquisitions, partnerships, collaborations, agreements, and expansions in the market
  • To strategically profile the key players and comprehensively analyze their market shares and core competencies

Available customizations:

With the given market data, MarketsandMarkets offers customizations according to the client-specific needs.

The following customization options are available for the report:

  • Additional country-level analysis of the data center chillers market
  • Profiling of additional market players (up to 5)

Product Analysis

  • Product matrix, which provides a detailed comparison of each company's product portfolio.


Personalize This Research

  • Triangulate with your Own Data
  • Get Data as per your Format and Definition
  • Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
  • Any level of Personalization
Request A Free Customisation

Let Us Help You

  • What are the Known and Unknown Adjacencies Impacting the Data Center Chillers Market
  • What will your New Revenue Sources be?
  • Who will be your Top Customer; what will make them switch?
  • Defend your Market Share or Win Competitors
  • Get a Scorecard for Target Partners
Customized Workshop Request

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements

Get 10% Free Customisation

TESTIMONIALS

Growth opportunities and latent adjacency in Data Center Chillers Market

DMCA.com Protection Status
popup img