Dental Sutures Market by Type (Absorbable, Non-absorbable), Material (Synthetic (Polyglactin 910, PGA, PTFE, Nylon), Natural (Silk, Gut)), Filament Type (Monofilament, Multifilament), & End User (Dental Clinics, Hospitals & ASCs) - Global Forecast to 2031

Market Size
$0.28B
MARKET SIZE, 2026
Projected Market Size
$0.37B
MARKET SIZE, 2031
CAGR
6.2%
CAGR (2026-2031)
Forecast Period
2026-2031
FORECAST PERIOD

DENTAL SUTURES MARKET SIZE, SHARE & GROWTH SNAPSHOT

dental-sutures-market Overview

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

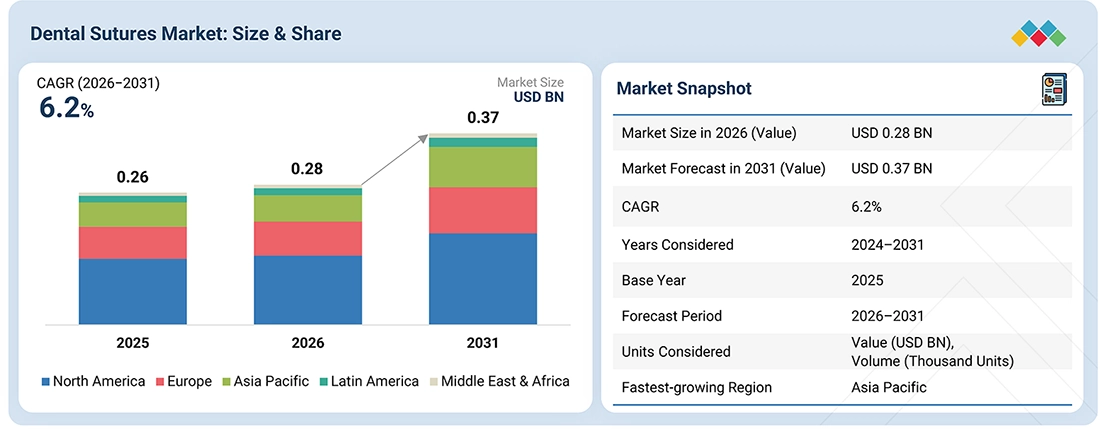
The global dental sutures market is projected to grow from USD 0.28 billion in 2026 to USD 0.37 billion by 2031, at a CAGR of 6.2% during the forecast period. The market was valued at USD 0.26 billion in 2025. Growth in the market is supported by the rising volume of dental surgical procedures, including tooth extractions, periodontal surgeries, dental implant placement, bone grafting, and other oral and maxillofacial procedures, which require effective wound closure and tissue approximation. Increasing adoption of synthetic absorbable, monofilament, PTFE, and other advanced suture materials is further improving handling, tissue compatibility, and healing outcomes. In addition, the growing prevalence of periodontal disease and tooth loss, rising demand for dental implants, expansion of specialty dental clinics and oral surgery centers, increasing awareness of oral healthcare, and improving access to advanced dental treatment in emerging markets are driving demand for dental sutures globally.

KEY TAKEAWAYS

  • MARKET SNAPSHOT:
    Base Year Market Size (2025): USD 0.26 Billion
    Current Market Size (2026): USD 0.28 Billion
    Forecast Market Size (2031): USD 0.37 Billion
    CAGR (2026–2031): 6.2%
  • SEGMENT LEADERSHIP:
    Regional Leader: North America accounted for the largest share of ~28–32% of the dental sutures market in 2025.
    Type Leader: Non-absorbable dental sutures are expected to register the highest CAGR of 6–7% in the market.
    Material Leader: Synthetic dental sutures are expected to garner the highest share of 85–90% of the dental sutures market.
    Filament Type Leader: Multifilament dental sutures are expected to dominate the market.
    End User Leader: Dental clinics & specialty dental centers are expected to dominate the market.
  • MARKET OUTLOOK & COMPETITIVE LANDSCAPE:
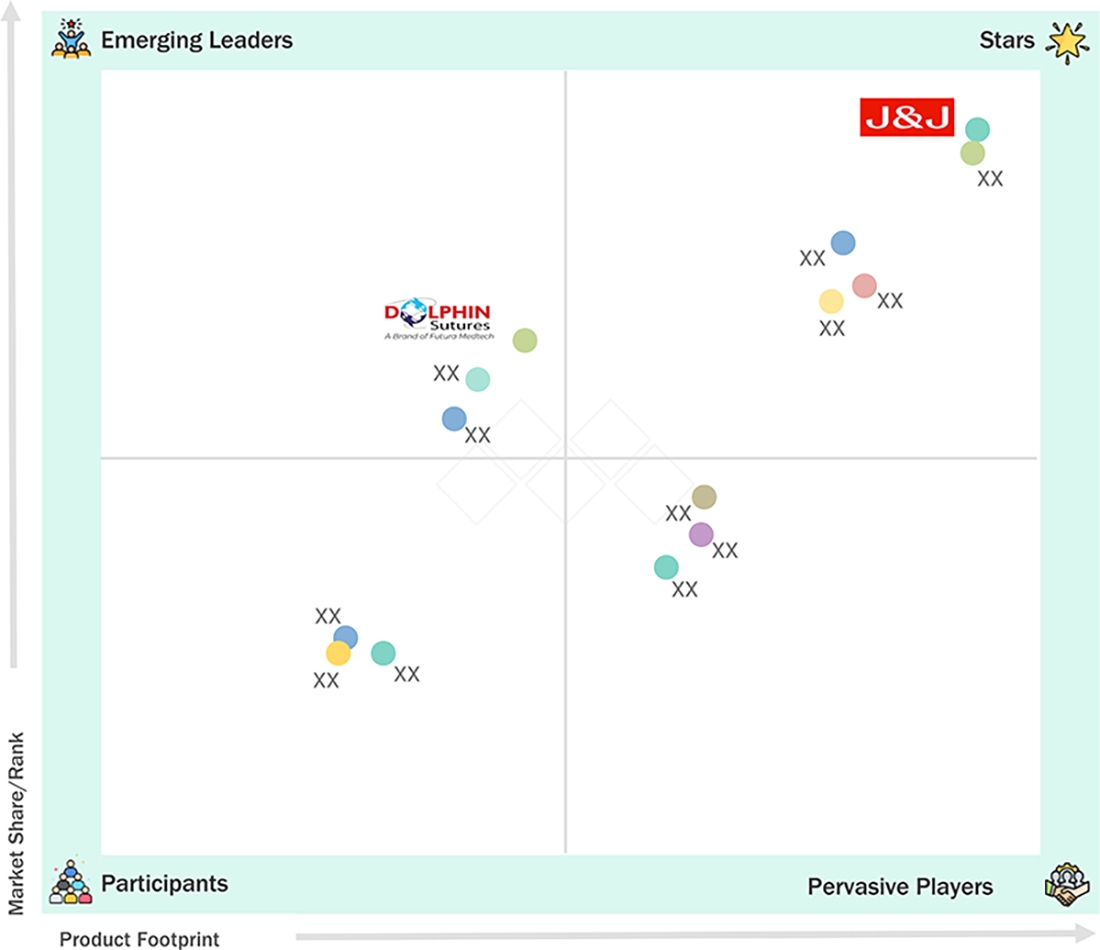
    Johnson & Johnson (US), Advanced Medical Solutions Group plc (UK), and Hu-Friedy Mfg. Co., LLC (US) were identified as some of the star players in the global dental sutures market, given their strong market share and product footprint.
    Qubix Medicare Private Limited (India), among others, has distinguished itself among startups and SMEs by securing strong footholds in specialized niche areas, underscoring their potential as emerging market leaders.

The global dental sutures market is witnessing steady growth, driven by the increasing number of dental surgical procedures and the rising burden of periodontal disease, tooth loss, and other oral health conditions. Growing adoption of dental implants, periodontal surgeries, bone grafting, tooth extractions, and oral and maxillofacial procedures is increasing the need for reliable wound closure and tissue approximation products. In addition, advancements in suture materials, including synthetic absorbable sutures, monofilament sutures, PTFE sutures, and other low-tissue-reactivity materials, are improving handling, wound healing, and clinical outcomes. Expansion of specialty dental clinics and oral surgery centers, increasing awareness of oral healthcare, a growing elderly population, and improving access to advanced dental treatment in emerging markets are further supporting the growth of the dental sutures market globally.

TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS

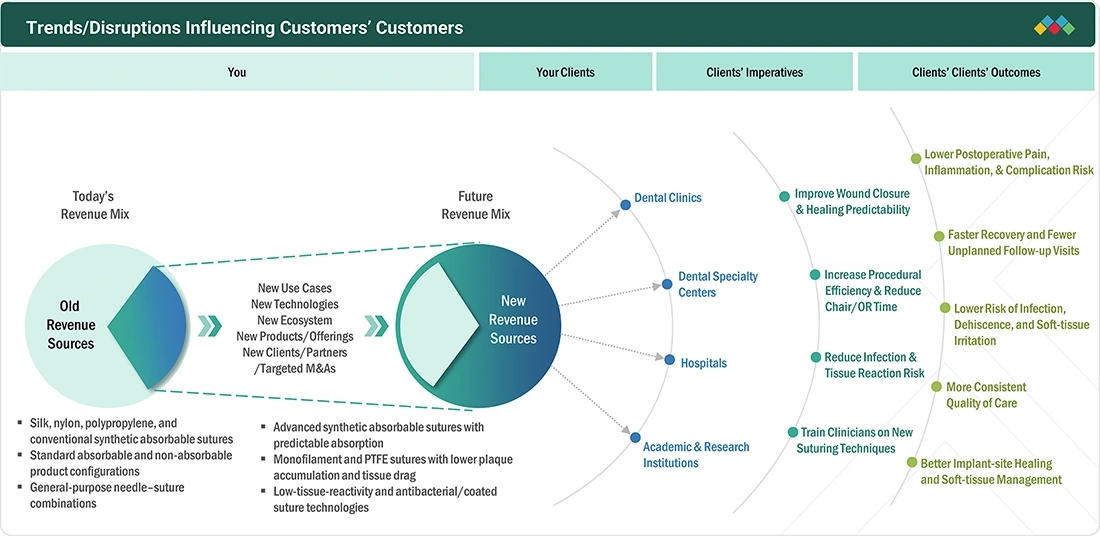
The dental sutures market is undergoing steady transformation with the growing adoption of advanced synthetic, monofilament, and PTFE sutures that offer improved handling, lower tissue reactivity, and more predictable wound support compared with conventional materials. Increasing use of dental implants, periodontal reconstruction, bone grafting, and other regenerative procedures is accelerating demand for procedure-specific sutures, atraumatic needle–suture combinations, and low-plaque-retentive materials designed to support precise soft-tissue closure and healing. In addition, the growing focus on infection prevention and postoperative outcomes is encouraging the use of antibacterial or coated sutures and materials with reduced bacterial wicking. The expansion of dental chains and specialty clinics is also promoting greater product standardization and procurement of premium suturing solutions, creating new growth opportunities for manufacturers offering differentiated, clinically focused dental suture portfolios.

dental-sutures-market Disruptions

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

MARKET DYNAMICS

Drivers
Impact
Level
  • Increasing patient pool for dental treatments
  • Rising demand for advanced cosmetic dental procedures
RESTRAINTS
Impact
Level
  • Need for post-operative removal and follow-up for non-absorbable sutures
  • Pricing pressure and commoditization of conventional dental sutures
OPPORTUNITIES
Impact
Level
  • Continued expansion of dental service organizations
  • Rising dental tourism activity
CHALLENGES
Impact
Level
  • Dearth of trained dental practitioners

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Driver: Increasing patient pool for dental treatments

The expanding patient pool requiring dental and oral surgical treatment is a major driver of the dental sutures market. According to the WHO’s March 2025 update, oral diseases affect nearly 3.7 billion people globally, while severe periodontal diseases account for more than 1 billion cases worldwide. The high burden of periodontal disease, dental caries, tooth loss, and related oral conditions is supporting a growing volume of tooth extractions, periodontal procedures, implant placement, bone grafting, and other oral surgeries where sutures are required for tissue approximation and wound closure. Population ageing, improving access to dental care, and greater willingness to undergo restorative and implant-based treatments are further expanding the addressable patient base and supporting recurring demand for dental sutures.

Restraint: Need for post-operative removal and follow-up for non-absorbable sutures

The requirement for postoperative removal and follow-up associated with non-absorbable dental sutures can restrain their adoption in certain procedures. Materials such as silk, nylon, polypropylene, and PTFE generally require patients to return to the dental clinic for suture removal after an appropriate healing period, adding an additional clinical visit and increasing both patient inconvenience and chair-time requirements for dental professionals. Missed or delayed follow-up appointments may also increase the risk of plaque accumulation, local irritation, or prolonged retention of the suture. This is encouraging greater preference for absorbable alternatives in procedures where extended wound support from non-absorbable sutures is not clinically necessary.

Opportunity: Continued expansion of dental service organizations

The continued expansion of dental service organizations presents an important commercial opportunity for dental suture manufacturers, as larger dental networks increasingly aggregate general dentistry and specialties such as periodontics and oral surgery under organized practice platforms. For example, Heartland Dental reported that its supported network expanded to more than 1,900 practices across 39 states and Washington, D.C. in 2025, completing approximately 11.5 million patient visits during the year. The company also added practices through de novo openings, affiliations, and its acquisition of the 60-practice Smile Design Dentistry network. Such large multi-site networks create opportunities for suture suppliers to pursue centralized procurement agreements, preferred-vendor relationships, standardized product formularies, and broader roll-out of procedure-specific or premium sutures across multiple locations, potentially improving account penetration and recurring consumables revenue.

Challenge: Dearth of trained dental practitioners

The shortage and uneven distribution of trained dentists and dental specialists remain an important challenge for the dental sutures market, particularly in developing and underserved regions. Advanced procedures such as dental implant placement, periodontal reconstruction, bone grafting, and oral and maxillofacial surgery require specialized clinical skills, including appropriate suture-material selection and precise soft-tissue closure techniques. Limited availability of trained professionals can restrict the number of complex dental surgeries performed and consequently reduce utilization of advanced dental sutures. Addressing this gap will require continued investment in dental education, specialist training, and access to advanced clinical techniques.

DENTAL SUTURES MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES

COMPANY USE CASE DESCRIPTION BENEFITS
company logo
VICRYL and VICRYL RAPIDE polyglactin 910 sutures are used for intraoral soft-tissue approximation and wound closure in oral and maxillofacial procedures. VICRYL RAPIDE is particularly suited to fast-healing oral mucosal wounds where only short-term wound support is required, making it relevant for procedures such as dental extractions and other minor oral surgical interventions. Provides predictable absorbability and reliable early wound support, while good handling and knot security facilitate precise closure in confined intraoral sites | The rapidly absorbable option can also reduce the need for suture-removal visits, improving postoperative convenience for both clinicians and patients
company logo
Perma Sharp sutures are specifically designed for dental procedures, including dental implant surgery, oral surgery, periodontal surgery, osseous surgery, and crown lengthening. Dental-specific needle configurations facilitate precise soft-tissue closure, while finer point geometry and laser-drilled needles are designed to reduce tissue disruption and drag
company logo
Cytoplast PTFE sutures are specifically positioned for dental implant and bone-grafting procedures, where secure closure around regenerative sites and graft materials is important. Monofilament PTFE prevents bacterial wicking; biologically inert material, softness, handling characteristics, and knot security support closure of sensitive regenerative sites
company logo
TEFLENE PTFE sutures are used for dental surgery, implant surgery, bone-graft surgery, and oral & maxillofacial surgery. Low-friction PTFE facilitates smooth tissue passage and minimizes tissue drag; monofilament construction limits bacterial wicking and provides prolonged wound support
company logo
SMI's dedicated dental range includes Surgicryl 910, Surgicryl PGA, Surgicryl Rapid, Surgicryl Monofast, and non-absorbable dental sutures, allowing clinicians to select different absorption and wound-support profiles. Provides multiple absorption profiles and material options | Synthetic products are designed for predictable absorption, limited tissue reaction, and controlled wound support.

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET ECOSYSTEM

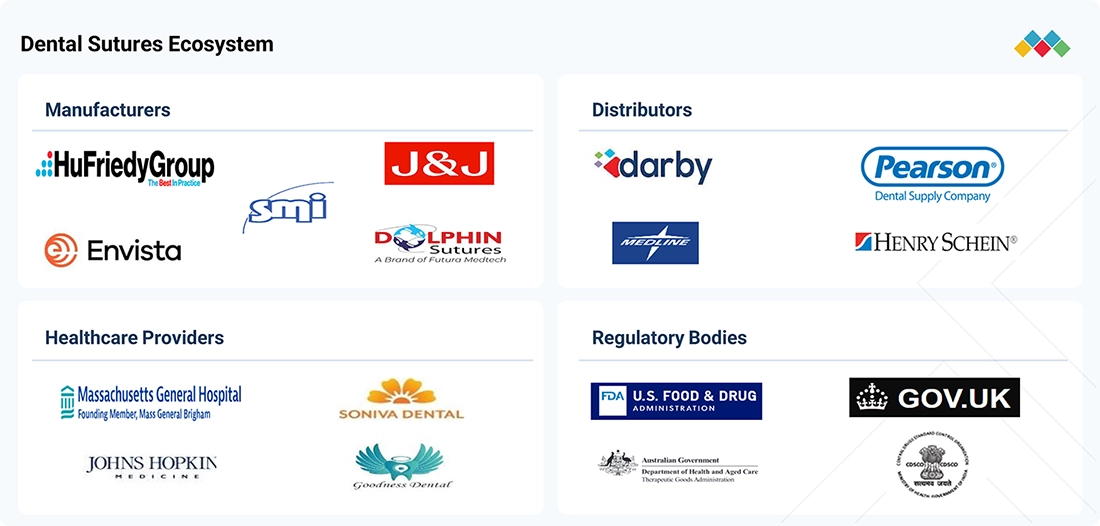
The dental sutures market ecosystem comprises key stakeholders, including raw material suppliers, suture manufacturers, distributors, dental care providers, regulatory authorities, and end users, all of which contribute to product development, commercialization, adoption, and compliance. Manufacturers develop a broad range of absorbable and non-absorbable sutures using materials such as polyglactin 910, PGA, PDO, nylon, polypropylene, silk, and PTFE, along with specialized needle–suture combinations designed for oral surgical applications. Distributors and dental supply companies play an important role in ensuring product availability across dental clinics, specialty dental centers, hospitals, ambulatory surgical centers, and academic institutions. Dental professionals, including periodontists, implantologists, oral and maxillofacial surgeons, and general dentists, act as key decision-makers by selecting sutures based on tissue response, tensile strength, absorption profile, handling characteristics, knot security, and procedure requirements. Regulatory authorities oversee product approvals, sterility, biocompatibility, labeling, quality standards, and post-market compliance. Together, these stakeholders influence product innovation, clinical adoption, distribution reach, pricing, and the overall growth of the global dental sutures market.

dental-sutures-market Ecosystem

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET SEGMENTS

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Dental Sutures Market, By Type

By type, the dental sutures market is categorized into absorbable and non-absorbable sutures. Non-absorbable sutures held a larger market share in 2025, reflecting their continued preference in procedures where extended tissue approximation and clinician-controlled removal are required. These sutures are commonly selected for implant-related surgeries, periodontal procedures, bone grafting, and other oral interventions in which the wound needs to remain securely supported during the early healing phase. Their ability to retain strength for a longer duration makes them suitable for complex surgical sites where premature loss of support may affect healing. In addition, materials such as silk, nylon, polypropylene, and PTFE offer different handling, biocompatibility, and surface characteristics, giving dental professionals flexibility in product selection. Broad product availability across multiple suture sizes and needle designs further reinforces the strong use of non-absorbable sutures in dental and oral surgical practice.

Dental Sutures Market, By Material

By material, the dental sutures market is segmented into synthetic and natural dental sutures. Synthetic dental sutures accounted for a larger market share in 2025, supported by their predictable performance, lower tissue reactivity, and availability across both absorbable and non-absorbable product categories. Materials such as polyglactin 910, polyglycolic acid (PGA), PTFE, nylon, polypropylene, and other synthetic polymers are widely used across dental implantology, periodontal surgery, bone grafting, tooth extractions, and other oral surgical procedures. Compared to natural sutures, synthetic materials generally provide more consistent tensile-strength retention, controlled absorption characteristics, and improved handling, enabling clinicians to select products according to specific wound-healing requirements. The growing preference for advanced monofilament and synthetic absorbable sutures, particularly in procedures where reduced tissue reaction and predictable wound support are important, further strengthens the dominance of the synthetic dental sutures segment.

Dental Sutures Market, By Filament Type

By filament type, the dental sutures market is classified into monofilament and multifilament sutures. Multifilament sutures are expected to exhibit a faster growth rate during the forecast period, largely because braided constructions offer good pliability, easier handling, and reliable knot performance, which remain important in many dental and oral surgical procedures. Their availability across both absorbable and non-absorbable categories also allows clinicians to select products according to different tissue-healing and wound-support requirements. At the same time, the higher surface area and interstices of braided sutures can promote greater plaque and bacterial accumulation than monofilament alternatives, particularly in the oral cavity. As a result, clinical preference depends on balancing handling and knot security with infection-control considerations, tissue response, and the expected duration of suture placement.

Dental Sutures Market, By End User

By end user, the dental sutures market is segmented into dental clinics & dental specialty centers, hospitals & ambulatory surgical centers, and academic & research institutions. Dental clinics & dental specialty centers accounted for the largest share of the market in 2025, supported by the high volume of tooth extractions, periodontal surgeries, dental implant procedures, bone grafting, and other routine and advanced oral surgical procedures performed in these settings. The growing number of private dental practices, implantology and periodontology centers, and oral surgery clinics, together with the increasing shift of dental procedures toward outpatient settings, continues to support suture consumption in this segment. In addition, specialist dental centers generally perform a higher concentration of implant, regenerative, and soft-tissue procedures that require reliable wound closure, further strengthening their share of the dental sutures market.

REGION

Asia Pacific to be fastest-growing region in global dental sutures market during forecast period

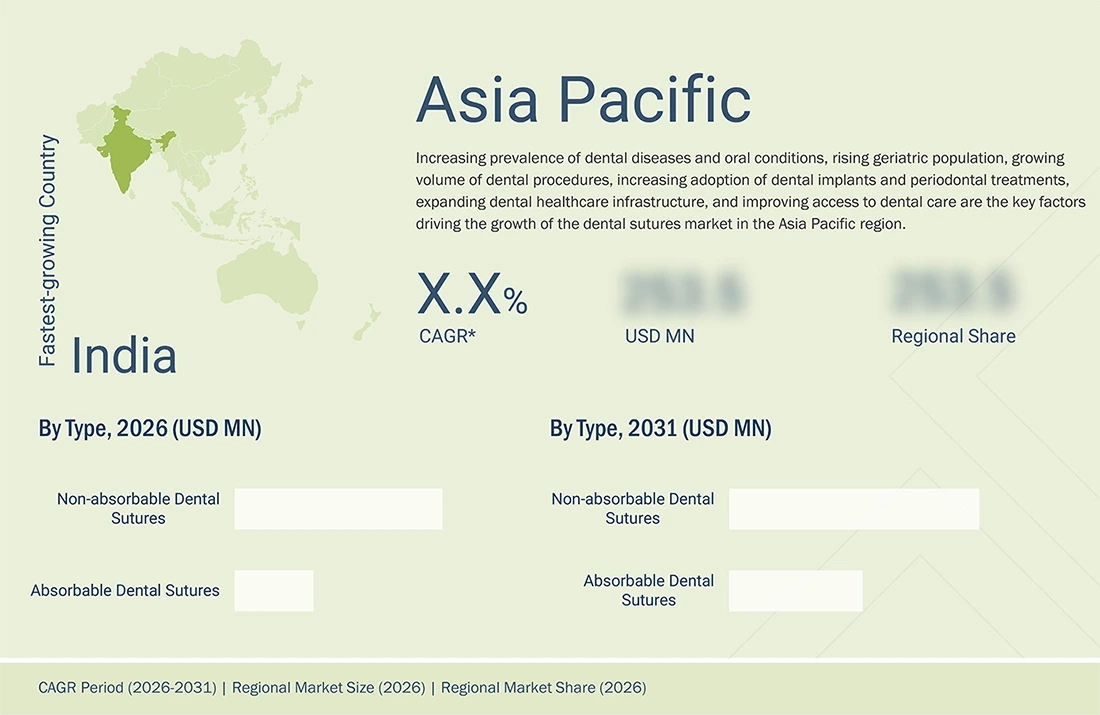
The Asia Pacific region is expected to witness the highest CAGR in the dental sutures market during the forecast period. Market growth is being supported by the region’s large patient pool, rising burden of periodontal disease and tooth loss, and increasing demand for dental implants, tooth extractions, periodontal procedures, and other oral surgeries. Countries such as China, India, Japan, and South Korea are witnessing expanding access to dental care, growth in specialty dental clinics, and increasing adoption of advanced implantology and regenerative dental procedures. Rising disposable incomes, greater awareness of oral health, expanding dental insurance coverage in selected markets, and increasing dental tourism in countries such as India and Thailand are further supporting procedure volumes. In addition, continued investment in healthcare infrastructure, growth in the number of dental professionals, and increasing availability of advanced synthetic, absorbable, and monofilament sutures are expected to strengthen the adoption of dental sutures across the region.

dental-sutures-market Region

DENTAL SUTURES MARKET: COMPANY EVALUATION MATRIX

In the dental sutures market matrix, Johnson & Johnson MedTech (Ethicon) (Star) holds a leading position due to its strong global presence, established wound-closure expertise, extensive distribution network, and widely recognized suture brands such as VICRYL, VICRYL RAPIDE, MONOCRYL, PDS II, and PROLENE, several of which are relevant to oral and soft-tissue surgical closure applications. The company benefits from strong clinician familiarity, broad adoption across surgical specialties, and a well-established reputation for product quality, handling, and predictable absorption characteristics, supporting its leadership position in the market. Dolphin Sutures (Emerging Leader) is gaining traction through its expanding portfolio of dental and oral surgery sutures, including TEFLENE PTFE sutures used in dental, implant, bone-graft, and oral & maxillofacial procedures. With its focus on specialty suture materials, growing international presence, and increasing relevance in advanced dental procedures, Dolphin Sutures is well positioned to strengthen its competitive position as demand for procedure-specific, monofilament, PTFE, and low-tissue-reactivity sutures continues to grow.

dental-sutures-market Evaluation Metrics

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

KEY MARKET PLAYERS

MARKET SCOPE

REPORT METRIC DETAILS
Market Size Value in 2025 (Value) USD 0.26 BN
Market Size Value in 2026 (Value) USD 0.28 BN
Market Forecast in 2031 (Value) USD 0.37 BN
Growth Rate CAGR of 6.2% from 2026–2031
Years Considered 2024–2031
Base Year 2025
Forecast Period 2026–2031
Units Considered Value (USD BN), Volume (Thousands Units)
Report Coverage Revenue Forecast, Company Ranking, Competitive Landscape, Growth Factors, and Trends
Segments Covered By Type: Absorbable, Non-absorbable I By Material: Synthetic Dental Sutures, Natural Dental Sutures I By Filament type: Monofilament Dental Sutures, Multifilament Dental Sutures I By End User: Dental Clinics & Specialty Dental Centers, Hospitals & ASCs, and Academic & Research Institutions
Regions Covered North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa

WHAT IS IN IT FOR YOU: DENTAL SUTURES MARKET REPORT CONTENT GUIDE

dental-sutures-market Content Guide

DELIVERED CUSTOMIZATIONS

We have successfully delivered the following deep-dive customizations:

CLIENT REQUEST CUSTOMIZATION DELIVERED VALUE ADDS
Volume Analysis Market assessment by volume (units) for dental sutures used in dental clinics
  • Insights on product demand by volume
  • YOY growth (%) and demand for key categories
Company Information Key players: include Johnson & Johnson (US), Advanced Medical Solutions Group plc (UK), and Hu-Friedy Mfg. Co., LLC (US). Top 3-5 players market share analysis at APAC and the European country level Insights on revenue shifts toward emerging innovations
Disease Prevalence    

RECENT DEVELOPMENTS

  • July 2026 : Hu-Friedy Mfg. Co., LLC (US) opened a new Northbrook campus in Illinois, US, combining advanced manufacturing capabilities with expanded capacity and technology to support the company's future growth and American-made dental product manufacturing.
  • July 2024 : Advanced Medical Solutions Group plc (UK) completed the acquisition of Peters Surgical (France) for an initial cash consideration of USD 143.2 Million (€ 132.5 million), adding Peters Surgical’s specialty sutures, haemostatic clips, clamps, and surgical glue portfolio.


Table of Contents

checkmarkExclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.

TITLE
PAGE NO
1
INTRODUCTION


28
2
EXECUTIVE SUMMARY


33
3
PREMIUM INSIGHTS


38
2025
(USD MILLION)


40
4
MARKET OVERVIEW
Growing demand for innovative dental solutions driven by aging demographics and evolving treatment practices.


42
 
4.1
INTRODUCTION


4.2
MARKET DYNAMICS


4.2.1
DRIVERS


4.2.1.1
INCREASING PATIENT POOL FOR DENTAL TREATMENTS


4.2.1.1.1
GERIATRIC POPULATION AND EDENTULISM


4.2.1.1.2
PERIODONTAL DISEASES


4.2.1.1.3
CHANGING LIFESTYLES AND UNHEALTHY FOOD HABITS


4.2.1.2
INCREASING ADOPTION OF PERIODONTAL PLASTIC SURGERY AND SOFT-TISSUE GRAFTING PROCEDURES


4.2.1.3
EXPANDING DENTAL CARE INFRASTRUCTURE AND SPECIALIST PRACTICES


4.2.2
RESTRAINTS


4.2.2.1
NEED FOR POST-OPERATIVE REMOVAL AND FOLLOW-UP FOR NON-ABSORBABLE SUTURES


4.2.2.2
PRICING PRESSURE AND COMMODITIZATION OF CONVENTIONAL DENTAL SUTURES


4.2.3
OPPORTUNITIES


4.2.3.1
CONTINUED GROWTH OF DENTAL SERVICE ORGANIZATIONS


GROWING FOCUS ON EMERGING ECONOMIES AND RISING DISPOSABLE


4.2.4
CHALLENGES


4.2.4.1
SHORTAGE AND UNEVEN DISTRIBUTION OF SKILLED DENTAL PROFESSIONALS


4.3
UNMET NEEDS & WHITE SPACES


4.3.1
UNMET NEEDS IN DENTAL SUTURES MARKET


4.3.2
WHITE SPACE OPPORTUNITIES


4.4
INTERCONNECTED MARKETS & CROSS-SECTOR OPPORTUNITIES


4.4.1
INTERCONNECTED MARKETS


4.4.2
CROSS-SECTOR OPPORTUNITIES


4.5
STRATEGIC MOVES BY TIER-1/2/3 PLAYERS


5
INDUSTRY TRENDS
Navigate competitive dynamics and macroeconomic shifts to leverage growth in the surgical sutures market.


52
 
5.1
PORTER’S FIVE FORCES ANALYSIS


5.1.1
THREAT OF NEW ENTRANTS


5.1.2
INTENSITY OF COMPETITIVE RIVALRY


5.1.3
BARGAINING POWER OF BUYERS


5.1.4
BARGAINING POWER OF SUPPLIERS


5.1.5
THREAT OF SUBSTITUTES


5.2
MACROECONOMIC OUTLOOK


5.2.1
INTRODUCTION


5.2.2
GDP TRENDS & FORECAST


5.2.3
TRENDS IN SURGICAL SUTURES INDUSTRY


5.3
VALUE CHAIN ANALYSIS


5.4
ECOSYSTEM ANALYSIS


5.5
PRICING ANALYSIS


AVERAGE SELLING PRICE OF DENTAL SUTURE PRODUCTS,


AVERAGE SELLING PRICE TREND OF NON-ABSORBABLE DENTAL


5.6
TRADE ANALYSIS


5.6.1
IMPORT DATA FOR DENTAL SUTURES (HS CODE: 300610), 2021–2025


5.6.2
EXPORT DATA FOR DENTAL SUTURES (HS CODE: 300610), 2021–2025


5.7
KEY CONFERENCES & EVENTS, 2026–2027


5.8
TRENDS/DISRUPTIONS IMPACTING CUSTOMERS’ BUSINESSES


5.9
CASE STUDY ANALYSIS


5.9.1
CASE STUDY 1: STRATAFIX KNOTLESS BARBED PDS SUTURE REDUCES INTRAORAL CLOSURE TIME IN MAXILLOFACIAL SURGERY


5.9.2
CASE STUDY 2: B. BRAUN DAFILON® DEMONSTRATES SAFE AND EFFECTIVE MUCOSAL CLOSURE IN ROUTINE ORAL SURGERY.


5.9.3
CASE STUDY 3: SMI DACLON SHOWS LOWER BACTERIAL COLONIZATION AND MILDER TISSUE REACTION IN THIRD-MOLAR SURGERY


5.10
IMPACT OF 2025 US TARIFFS ON DENTAL SUTURES MARKET


5.10.1
INTRODUCTION


5.10.2
KEY TARIFF RATES


5.10.3
PRICE IMPACT ANALYSIS


5.10.4
IMPACT ON COUNTRIES/REGIONS


5.10.4.1
US


5.10.4.2
EUROPE


5.10.4.3
ASIA PACIFIC


5.10.5
IMPACT ON END-USE INDUSTRIES


TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT,


6.1
KEY EMERGING TECHNOLOGIES


6.2
COMPLEMENTARY TECHNOLOGIES


6.2.1
ANTIMICROBIAL & BIOACTIVE COATING TECHNOLOGIES


6.3
TECHNOLOGY/PRODUCT ROADMAP


6.3.1
SHORT-TERM (2025–2027) | FOUNDATION & EARLY COMMERCIALIZATION


6.3.2
MID-TERM (2027–2030) | EXPANSION & STANDARDIZATION


6.3.3
LONG-TERM (2030–2035+) | MASS COMMERCIALIZATION & DISRUPTION


6.4
PATENT ANALYSIS


6.4.1
PATENT PUBLICATION TRENDS FOR DENTAL SUTURES MARKET


6.4.2
TOP APPLICANTS (COMPANIES) OF DENTAL SUTURE PATENTS


6.4.3
JURISDICTION ANALYSIS: TOP APPLICANTS (COUNTRIES) FOR PATENTS IN DENTAL SUTURES MARKET


6.5
IMPACT OF AI/GEN AI ON DENTAL SUTURES MARKET


6.5.1
TOP USE CASES & MARKET POTENTIAL


6.5.2
INTERCONNECTED ADJACENT ECOSYSTEMS & IMPACT ON MARKET PLAYERS


6.6
SUCCESS STORIES & REAL-WORLD APPLICATIONS


6.6.1
ENVISTA/OSTEOGENICS: CYTOPLAST PTFE SUTURES – DENTAL-SPECIFIC MONOFILAMENT CLOSURE FOR BONE GRAFTING AND IMPLANT SURGERY


JOHNSON & JOHNSON MEDTECH/ETHICON: VICRYL RAPIDE –


6.6.3
HUFRIEDYGROUP: PERMA SHARP SUTURES – DENTAL-SPECIFIC NEEDLE-SUTURE CONFIGURATIONS FOR PRECISE SOFT-TISSUE CLOSURE


7
REGULATORY LANDSCAPE
Navigate complex global regulations with insights into key regional compliance and certification standards.


78
 
7.1
REGIONAL REGULATIONS & COMPLIANCE


7.1.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


7.1.2
INDUSTRY STANDARDS


7.1.2.1
NORTH AMERICA


7.1.2.1.1
US


7.1.2.1.2
CANADA


7.1.2.2
EUROPE


7.1.2.3
ASIA PACIFIC


7.1.2.3.1
CHINA


7.1.2.3.2
JAPAN


7.1.2.4
LATIN AMERICA


7.1.2.4.1
BRAZIL


7.1.2.4.2
MEXICO


7.1.2.5
MIDDLE EAST


7.1.2.6
AFRICA


7.2
CERTIFICATIONS, LABELING, AND ECO-STANDARDS


CERTIFICATIONS, LABELING, AND ECO-STANDARDS IN DENTAL


8
CUSTOMER LANDSCAPE & BUYER BEHAVIOR
Unlock unmet needs and maximize revenue by understanding key buying criteria and stakeholder influence.


85
 
8.1
DECISION-MAKING PROCESS


8.2
BUYER STAKEHOLDERS & BUYING EVALUATION CRITERIA


8.2.1
KEY STAKEHOLDERS IN BUYING PROCESS


8.2.2
KEY BUYING CRITERIA


8.3
ADOPTION BARRIERS & INTERNAL CHALLENGES


8.4
UNMET NEEDS


8.5
MARKET PROFITABILITY


8.5.1
REVENUE POTENTIAL


8.5.2
COST DYNAMICS


8.5.3
MARGIN OPPORTUNITIES IN KEY APPLICATIONS


9
DENTAL SUTURES MARKET, BY TYPE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million and Units | 5 Data Tables


91
 
9.1
INTRODUCTION


9.2
ABSORBABLE DENTAL SUTURES


9.2.1
ELIMINATION OF POSTOPERATIVE SUTURE REMOVAL TO SUPPORT MARKET GROWTH


9.3
NON-ABSORBABLE DENTAL SUTURES


9.3.1
GROWING ADOPTION OF NON-ABSORBABLE SUTURES IN IMPLANT AND PERIODONTAL PROCEDURES TO DRIVE GROWTH


10
DENTAL SUTURES MARKET, BY MATERIAL
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 13 Data Tables


97
 
10.1
INTRODUCTION


10.2
SYNTHETIC DENTAL SUTURES


10.2.1
POLYGLACTIN 910 DENTAL SUTURES


10.2.1.1
EXCELLENT HANDLING CHARACTERISTICS AND KNOT SECURITY OF POLYGLACTIN 910 DENTAL SUTURES TO SUPPORT ADOPTION


10.2.2
POLYGLYCOLIC ACID (PGA) DENTAL SUTURES


10.2.2.1
SUITABILITY OF POLYGLYCOLIC ACID (PGA) DENTAL SUTURES FOR BROAD RANGE OF ROUTINE AND ADVANCED DENTAL PROCEDURES TO FUEL GROWTH


10.2.3
POLYTETRAFLUOROETHYLENE (PTFE) DENTAL SUTURES


10.2.3.1
ADVANTAGES SUCH AS LOW BACTERIAL RETENTION AND PROLONGED WOUND-SUPPORT CHARACTERISTICS TO DRIVE DEMAND FOR PTFE DENTAL SUTURES


10.2.4
NYLON (POLYAMIDE) DENTAL SUTURES


10.2.4.1
HIGH TENSILE STRENGTH AND SMOOTH TISSUE PASSAGE OF NYLON TO DRIVE DEMAND IN PROCEDURES REQUIRING PRECISE TISSUE APPROXIMATION


10.2.5
OTHER SYNTHETIC DENTAL SUTURES


10.3
NATURAL DENTAL SUTURES


10.3.1
SILK DENTAL SUTURES


10.3.1.1
FAVORABLE HANDLING CHARACTERISTICS, CLINICIAN FAMILIARITY, AND BROAD AVAILABILITY TO CONTINUE TO DRIVE DEMAND FOR SILK DENTAL SUTURES


10.3.2
PLAIN GUT DENTAL SUTURES


10.3.2.1
WIDE USAGE OF PLAIN GUT SUTURES IN ORAL MUCOSAL CLOSURE AND OTHER SHORT-HEALING PROCEDURES TO SUPPORT GROWTH


10.3.3
CHROMIC GUT DENTAL SUTURES


GROWING USE OF CHROMIC GUT DENTAL SUTURES IN TOOTH EXTRACTIONS


11
DENTAL SUTURES MARKET, BY FILAMENT TYPE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 3 Data Tables


114
 
11.1
INTRODUCTION


11.2
MONOFILAMENT DENTAL SUTURES


LOW CAPILLARITY AND BACTERIAL RETENTION TO DRIVE ADOPTION


11.3
MULTIFILAMENT DENTAL SUTURES


11.3.1
FLEXIBILITY AND EASE OF HANDLING TO DRIVE USE OF MULTIFILAMENT DENTAL SUTURES


12
DENTAL SUTURES MARKET, BY APPLICATION
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 6 Data Tables


119
 
12.1
INTRODUCTION


12.2
ORAL SURGERY & TOOTH EXTRACTION


12.2.1
HIGH VOLUME OF TOOTH EXTRACTIONS PERFORMED FOR DENTAL CARIES AND OTHER DENTAL CONDITIONS TO BOOST MARKET


12.3
PERIODONTAL SURGERY


12.3.1
GROWING CLINICAL EMPHASIS ON ESTHETIC PERIODONTAL TREATMENT TO SUPPORT GROWTH


12.4
DENTAL IMPLANTOLOGY


12.4.1
GROWTH IN IMPLANT-SUPPORTED DENTAL REHABILITATION TO SUPPORT DEMAND FOR DENTAL SUTURES IN THIS APPLICATION


12.5
MAXILLOFACIAL SURGERY


12.5.1
GROWTH IN CORRECTIVE MAXILLOFACIAL PROCEDURES TO SUSTAIN DEMAND FOR SPECIALIZED SUTURES


12.6
OTHER APPLICATIONS


13
DENTAL SUTURES MARKET, BY END USER
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 4 Data Tables


127
 
13.1
INTRODUCTION


13.2
DENTAL CLINICS & SPECIALTY DENTAL CENTERS


13.2.1
INCREASING VOLUME OF TOOTH EXTRACTIONS, PERIODONTAL SURGERIES, AND OTHER OUTPATIENT DENTAL PROCEDURES TO DRIVE SUTURE UTILIZATION


13.3
HOSPITALS & AMBULATORY SURGICAL CENTERS


RISING NUMBER OF COMPLEX ORAL AND MAXILLOFACIAL SURGERIES


13.4
ACADEMIC & RESEARCH INSTITUTIONS


13.4.1
GROWING DENTAL EDUCATION, SURGICAL TRAINING, AND RESEARCH ACTIVITIES TO SUPPORT DEMAND


14
DENTAL SUTURES MARKET, BY REGION
Comprehensive coverage of 8 Regions with country-level deep-dive of 14 Countries | 190 Data Tables.


133
 
14.1
INTRODUCTION


14.2
EUROPE


14.2.1
MACROECONOMIC OUTLOOK FOR EUROPE


14.2.2
GERMANY


14.2.2.1
FAVORABLE GOVERNMENT POLICIES FOR REIMBURSEMENT TO DRIVE DEMAND FOR DENTAL SUTURES


14.2.3
UK


14.2.3.1
HIGH DENTAL PROCEDURE VOLUMES AND ORAL DISEASE BURDEN TO DRIVE MARKET


14.2.4
FRANCE


14.2.4.1
LARGE DENTAL WORKFORCE AND EXTENSIVE HEALTH-INSURANCE COVERAGE TO SUPPORT DEMAND FOR DENTAL SURGICAL PROCEDURES AND ASSOCIATED SUTURES


14.2.5
SPAIN


14.2.5.1
PRESENCE OF WELL-ESTABLISHED DENTAL HEALTHCARE INFRASTRUCTURE TO PROPEL MARKET


14.2.6
ITALY


14.2.6.1
PREDOMINANTLY PRIVATE DENTAL-CARE FINANCING TO SUPPORT PROCEDURAL BASE FOR DENTAL SUTURES


14.2.7
REST OF EUROPE


14.3
NORTH AMERICA


14.3.1
MACROECONOMIC OUTLOOK FOR NORTH AMERICA


14.3.2
US


14.3.2.1
HIGH PER CAPITA INCOME AND HIGH QUALITY OF TREATMENT TO SUPPORT MARKET GROWTH


14.3.3
CANADA


14.3.3.1
RISING HEALTHCARE EXPENDITURE TO DRIVE MARKET


14.4
ASIA PACIFIC


14.4.1
MACROECONOMIC OUTLOOK FOR ASIA PACIFIC


14.4.2
JAPAN


14.4.2.1
RISING GERIATRIC POPULATION AND FAVORABLE REIMBURSEMENT SCENARIO TO SUPPORT MARKET GROWTH


14.4.3
CHINA


14.4.3.1
GROWING PREVALENCE OF DENTAL DISEASES AND INCREASING GERIATRIC POPULATION TO DRIVE MARKET


14.4.4
INDIA


14.4.4.1
GROWING DENTAL TOURISM TO SUPPORT MARKET GROWTH


14.4.5
AUSTRALIA


GROWING NUMBER OF REGISTERED DENTAL PRACTITIONERS TO SUPPORT


14.4.6
SOUTH KOREA


14.4.6.1
HIGH SENIOR POPULATION TO SUPPORT MARKET DEMAND


14.4.7
REST OF ASIA PACIFIC


14.5
LATIN AMERICA


14.5.1
MACROECONOMIC OUTLOOK FOR LATIN AMERICA


14.5.2
BRAZIL


14.5.2.1
IMPROVING ACCESS AND AFFORDABILITY TO DRIVE MARKET


14.5.3
MEXICO


14.5.3.1
FOCUS ON IMPROVING HEALTHCARE INFRASTRUCTURE AND AVAILABILITY OF SKILLED DENTISTS TO DRIVE THE MARKET


14.5.4
REST OF LATIN AMERICA


14.6
MIDDLE EAST & AFRICA


14.6.1
MACROECONOMIC OUTLOOK FOR MIDDLE EAST & AFRICA


14.6.2
GCC COUNTRIES


14.6.3
REST OF MIDDLE EAST & AFRICA


15
COMPETITIVE LANDSCAPE
Discover strategic shifts and market dominance of key players in dental sutures by 2025.


211
 
15.1
INTRODUCTION


15.2
KEY PLAYER STRATEGY/RIGHT TO WIN


15.2.1
OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS IN DENTAL SUTURES MARKET


15.3
REVENUE ANALYSIS, 2021–2025


15.4
MARKET SHARE ANALYSIS, 2025


15.5
COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025


15.5.1
STARS


15.5.2
EMERGING LEADERS


15.5.3
PERVASIVE PLAYERS


15.5.4
PARTICIPANTS


15.5.5
COMPANY FOOTPRINT: KEY PLAYERS, 2025


15.5.5.1
COMPANY FOOTPRINT


15.5.5.2
REGION FOOTPRINT


15.5.5.3
TYPE FOOTPRINT


15.5.5.4
MATERIAL FOOTPRINT


15.5.5.5
FILAMENT TYPE FOOTPRINT


15.6
COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025


15.6.1
PROGRESSIVE COMPANIES


15.6.2
RESPONSIVE COMPANIES


15.6.3
DYNAMIC COMPANIES


15.6.4
STARTING BLOCKS


15.6.5
COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025


15.6.5.1
DETAILED LIST OF STARTUPS/SMES


15.6.5.2
COMPETITIVE BENCHMARKING OF STARTUPS/SMES


15.7
BRAND/PRODUCT COMPARISON


15.8
COMPANY VALUATION & FINANCIAL METRICS


15.8.1
FINANCIAL METRICS


15.8.2
COMPANY VALUATION


15.9
COMPETITIVE SCENARIO


15.9.1
DEALS


15.9.2
EXPANSIONS


15.9.3
OTHER DEVELOPMENTS


16
COMPANY PROFILES
In-depth Company Profiles of Leading Market Players with detailed Business Overview, Product and Service Portfolio, Recent Developments, and Unique Analyst Perspective (MnM View)


232
 
16.1
KEY PLAYERS


16.1.1
JOHNSON & JOHNSON


16.1.1.1
BUSINESS OVERVIEW


16.1.1.2
PRODUCTS OFFERED


16.1.1.3
RECENT DEVELOPMENTS


16.1.1.3.1
DEALS


16.1.1.3.2
OTHER DEVELOPMENTS


16.1.1.4
MNM VIEW


16.1.1.4.1
KEY STRENGTHS


16.1.1.4.2
STRATEGIC CHOICES


16.1.1.4.3
WEAKNESSES & COMPETITIVE THREATS


16.1.2
B. BRAUN SE


16.1.3
ADVANCED MEDICAL SOLUTIONS GROUP PLC


16.1.4
DEMETECH CORPORATION


16.1.5
HU-FRIEDY MFG. CO., LLC


16.1.6
ENVISTA


16.1.7
HENRY SCHEIN


16.1.8
FUTURA SURGICARE PVT. LTD.


16.1.9
MANI, INC.


16.1.10
CORZA MEDICAL


16.1.11
SMI AG


16.1.12
YOUNG INNOVATIONS, INC.


16.1.13
ASSUT EUROPE


16.1.14
KATSAN KATGÜT SANAYI VE TIC. A.S.


16.1.15
DOGSAN TIBBI MALZEME SANAYI A.S.


16.2
OTHER PLAYERS


16.2.1
HYGITECH


16.2.2
ZIMVIE INC.


16.2.3
MEDIPAC SA


16.2.4
LUX SUTURES


16.2.5
BENTLEY HEALTHCARE PVT. LTD.


16.2.6
BOZ MEDICAL


16.2.7
DSI LTD.


16.2.8
GDT DENTAL IMPLANTS


16.2.9
GOLNIT


16.2.10
QUBIX MEDICARE PRIVATE LIMITED


17
RESEARCH METHODOLOGY


282
 
17.1
RESEARCH DATA


17.1.1
SECONDARY DATA


17.1.1.1
KEY DATA FROM SECONDARY SOURCES


17.1.2
PRIMARY DATA


17.1.2.1
KEY DATA FROM PRIMARY SOURCES


17.1.2.2
KEY INDUSTRY INSIGHTS


17.2
MARKET SIZE ESTIMATION


17.2.1
BOTTOM-UP APPROACH


17.2.2
TOP-DOWN APPROACH


17.2.3
BASE NUMBER ESTIMATION


17.2.3.1
SUPPLY-SIDE ANALYSIS (REVENUE SHARE ANALYSIS)


17.2.3.2
COMPANY PRESENTATIONS & PRIMARY INTERVIEWS


17.3
MARKET FORECAST APPROACH


MARKET SEGMENT ASSESSMENT (BY TYPE, MATERIAL, FILAMENT TYPE,


17.5
GEOGRAPHIC MARKET ASSESSMENT (BY REGION AND COUNTRY)


17.6
DATA TRIANGULATION


17.7
MARKET SHARE ESTIMATION


17.8
STUDY ASSUMPTIONS


17.9
FACTOR ANALYSIS


17.10
RESEARCH LIMITATIONS


17.10.1
SCOPE-RELATED LIMITATIONS


17.10.2
METHODOLOGY-RELATED LIMITATIONS


17.11
RISK ASSESSMENT


18
APPENDIX


295
 
18.1
DISCUSSION GUIDE


18.2
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL


18.3
CUSTOMIZATION OPTIONS


18.4
RELATED REPORTS


18.5
AUTHOR DETAILS


LIST OF TABLES


TABLE 1
STANDARD CURRENCY CONVERSION RATES


TABLE 2
PROJECTED INCREASE IN NUMBER OF PEOPLE AGED OVER 65 YEARS, BY REGION, 2019 VS. 2050 (MILLION)


TABLE 3
DENTAL SUTURES MARKET: PORTER’S FIVE FORCES ANALYSIS


TABLE 4
GDP PERCENTAGE CHANGE, BY KEY COUNTRY, 2021–2030


TABLE 5
AVERAGE SELLING PRICE OF DENTAL SUTURE PRODUCTS, BY KEY PLAYER, 2025


TABLE 6
AVERAGE SELLING PRICE TREND OF NON-ABSORBABLE DENTAL SUTURES, BY REGION, 2023–2025


TABLE 7
IMPORT DATA FOR DENTAL SUTURES (HS CODE: 300610), BY COUNTRY, 2021–2025 (USD THOUSAND)


TABLE 8
EXPORT DATA FOR DENTAL SUTURES (HS CODE: 300610), BY COUNTRY, 2021–2025 (USD THOUSAND)


TABLE 9
DENTAL SUTURES MARKET: LIST OF KEY CONFERENCES & EVENTS, 2026–2027


TABLE 10
CASE STUDY 1: STRATAFIX KNOTLESS BARBED PDS SUTURE REDUCES INTRAORAL CLOSURE TIME IN MAXILLOFACIAL SURGERY


TABLE 11
CASE STUDY 2: B. BRAUN DAFILON® DEMONSTRATES SAFE AND EFFECTIVE MUCOSAL CLOSURE IN ROUTINE ORAL SURGERY.


TABLE 12
CASE STUDY 3: SMI DACLON SHOWS LOWER BACTERIAL COLONIZATION AND MILDER TISSUE REACTION IN THIRD-MOLAR SURGERY


TABLE 13
US-ADJUSTED RECIPROCAL TARIFF RATES


TABLE 14
KEY PRODUCT-RELATED TARIFFS EFFECTIVE FOR ADHESIVE BARRIER PRODUCTS


TABLE 15
TOP USE CASES & MARKET POTENTIAL


TABLE 16
INTERCONNECTED ADJACENT ECOSYSTEMS & IMPACT ON MARKET PLAYERS


TABLE 17
NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 18
EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 19
ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 20
LATIN AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 21
MIDDLE EAST & AFRICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 22
INFLUENCE OF KEY STAKEHOLDERS ON BUYING PROCESS OF END USERS


TABLE 23
KEY BUYING CRITERIA FOR END USERS


TABLE 24
ADOPTION BARRIERS & INTERNAL CHALLENGES


TABLE 25
DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 26
ABSORBABLE DENTAL SUTURES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 27
ABSORBABLE DENTAL SUTURES MARKET, BY REGION, 2024–2031 (THOUSANDS UNITS)


TABLE 28
NON-ABSORBABLE DENTAL SUTURES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 29
NON-ABSORBABLE DENTAL SUTURES MARKET, BY REGION, 2024–2031 (THOUSANDS UNITS)


TABLE 30
DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 31
SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 32
SYNTHETIC DENTAL SUTURES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 33
POLYGLACTIN 910 DENTAL SUTURES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 34
POLYGLYCOLIC ACID (PGA) DENTAL SUTURES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 35
POLYTETRAFLUOROETHYLENE (PTFE) DENTAL SUTURES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 36
NYLON (POLYAMIDE) DENTAL SUTURES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 37
OTHER SYNTHETIC DENTAL SUTURES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 38
NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 39
NATURAL DENTAL SUTURES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 40
SILK DENTAL SUTURES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 41
PLAIN GUT DENTAL SUTURES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 42
CHROMIC GUT DENTAL SUTURES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 43
DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 44
MONOFILAMENT DENTAL SUTURES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 45
MULTIFILAMENT DENTAL SUTURES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 46
DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 47
DENTAL SUTURES MARKET FOR ORAL SURGERY & TOOTH EXTRACTION, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 48
DENTAL SUTURES MARKET FOR PERIODONTAL SURGERY, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 49
DENTAL SUTURES MARKET FOR DENTAL IMPLANTOLOGY, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 50
DENTAL SUTURES MARKET FOR MAXILLOFACIAL SURGERY, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 51
DENTAL SUTURES MARKET FOR OTHER APPLICATIONS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 52
DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 53
DENTAL SUTURES MARKET FOR DENTAL CLINICS & SPECIALTY DENTAL CENTERS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 54
DENTAL SUTURES MARKET FOR HOSPITALS & AMBULATORY SURGICAL CENTERS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 55
DENTAL SUTURES MARKET FOR ACADEMIC & RESEARCH INSTITUTIONS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 56
DENTAL SUTURES MARKET, BY REGION, 2024–2031 (USD MILLION)


TABLE 57
EUROPE: DENTAL SUTURES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 58
EUROPE: DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 59
EUROPE: DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 60
EUROPE: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 61
EUROPE: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 62
EUROPE: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 63
EUROPE: DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 64
EUROPE: DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 65
GERMANY: KEY MACROINDICATORS


TABLE 66
GERMANY: DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 67
GERMANY: DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 68
GERMANY: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 69
GERMANY: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 70
GERMANY: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 71
GERMANY: DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 72
GERMANY: DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 73
UK: KEY MACROINDICATORS


TABLE 74
UK: DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 75
UK: DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 76
UK: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 77
UK: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 78
UK: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 79
UK: DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 80
UK: DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 81
FRANCE: KEY MACROINDICATORS


TABLE 82
FRANCE: DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 83
FRANCE: DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 84
FRANCE: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 85
FRANCE: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 86
FRANCE: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 87
FRANCE: DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 88
FRANCE: DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 89
SPAIN: KEY MACROINDICATORS


TABLE 90
SPAIN: DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 91
SPAIN: DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 92
SPAIN: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 93
SPAIN: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 94
SPAIN: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 95
SPAIN: DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 96
SPAIN: DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 97
ITALY: KEY MACROINDICATORS


TABLE 98
ITALY: DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 99
ITALY: DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 100
ITALY: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 101
ITALY: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 102
ITALY: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 103
ITALY: DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 104
ITALY: DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 105
REST OF EUROPE: DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 106
REST OF EUROPE: DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 107
REST OF EUROPE: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 108
REST OF EUROPE: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 109
REST OF EUROPE: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 110
REST OF EUROPE: DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 111
REST OF EUROPE: DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 112
NORTH AMERICA: DENTAL SUTURES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 113
NORTH AMERICA: DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 114
NORTH AMERICA: DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 115
NORTH AMERICA: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 116
NORTH AMERICA: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 117
NORTH AMERICA: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 118
NORTH AMERICA: DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 119
NORTH AMERICA: DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 120
US: MACROECONOMIC INDICATORS


TABLE 121
US: DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 122
US: DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 123
US: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 124
US: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 125
US: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 126
US: DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 127
US: DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 128
CANADA: KEY MACROINDICATORS


TABLE 129
CANADA: DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 130
CANADA: DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 131
CANADA: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 132
CANADA: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 133
CANADA: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 134
CANADA: DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 135
CANADA: DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 136
ASIA PACIFIC: DENTAL SUTURES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 137
ASIA PACIFIC: DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 138
ASIA PACIFIC: DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 139
ASIA PACIFIC: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 140
ASIA PACIFIC: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 141
ASIA PACIFIC: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 142
ASIA PACIFIC: DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 143
ASIA PACIFIC: DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 144
JAPAN: KEY MACROINDICATORS


TABLE 145
JAPAN: DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 146
JAPAN: DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 147
JAPAN: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 148
JAPAN: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 149
JAPAN: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 150
JAPAN: DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 151
JAPAN: DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 152
CHINA: KEY MACROINDICATORS


TABLE 153
CHINA: DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 154
CHINA: DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 155
CHINA: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 156
CHINA: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 157
CHINA: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 158
CHINA: DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 159
CHINA: DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 160
INDIA: KEY MACROINDICATORS


TABLE 161
INDIA: DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 162
INDIA: DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 163
INDIA: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 164
INDIA: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 165
INDIA: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 166
INDIA: DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 167
INDIA: DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 168
AUSTRALIA: ORAL HEALTH STATUS OF CHILDREN AND ADULTS


TABLE 169
AUSTRALIA: MACROECONOMIC INDICATORS


TABLE 170
AUSTRALIA: DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 171
AUSTRALIA: DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 172
AUSTRALIA: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 173
AUSTRALIA: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 174
AUSTRALIA: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 175
AUSTRALIA: DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 176
AUSTRALIA: DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 177
SOUTH KOREA: NUMBER OF FOREIGN PATIENTS VISITING DENTAL FACILITIES, 2017–2021


TABLE 178
SOUTH KOREA: KEY MACROINDICATORS


TABLE 179
SOUTH KOREA: DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 180
SOUTH KOREA: DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 181
SOUTH KOREA: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 182
SOUTH KOREA: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 183
SOUTH KOREA: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 184
SOUTH KOREA: DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 185
SOUTH KOREA: DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 186
REST OF ASIA PACIFIC: DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 187
REST OF ASIA PACIFIC: DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 188
REST OF ASIA PACIFIC: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 189
REST OF ASIA PACIFIC: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 190
REST OF ASIA PACIFIC: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 191
REST OF ASIA PACIFIC: DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 192
REST OF ASIA PACIFIC: DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 193
LATIN AMERICA: DENTAL SUTURES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 194
LATIN AMERICA: DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 195
LATIN AMERICA: DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 196
LATIN AMERICA: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 197
LATIN AMERICA: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 198
LATIN AMERICA: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 199
LATIN AMERICA: DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 200
LATIN AMERICA: DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 201
BRAZIL: KEY MACROINDICATORS


TABLE 202
BRAZIL: DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 203
BRAZIL: DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 204
BRAZIL: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 205
BRAZIL: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 206
BRAZIL: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 207
BRAZIL: DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 208
BRAZIL: DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 209
MEXICO: KEY MACROINDICATORS


TABLE 210
MEXICO: DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 211
MEXICO: DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 212
MEXICO: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 213
MEXICO: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 214
MEXICO: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 215
MEXICO: DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 216
MEXICO: DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 217
REST OF LATIN AMERICA: DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 218
REST OF LATIN AMERICA: DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 219
REST OF LATIN AMERICA: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 220
REST OF LATIN AMERICA: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 221
REST OF LATIN AMERICA: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 222
REST OF LATIN AMERICA: DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 223
REST OF LATIN AMERICA: DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 224
MIDDLE EAST & AFRICA: DENTAL SUTURES MARKET, BY REGION, 2024–2031 (USD MILLION)


TABLE 225
MIDDLE EAST & AFRICA: DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 226
MIDDLE EAST & AFRICA: DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 227
MIDDLE EAST & AFRICA: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 228
MIDDLE EAST & AFRICA: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 229
MIDDLE EAST & AFRICA: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 230
MIDDLE EAST & AFRICA: DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 231
MIDDLE EAST & AFRICA: DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 232
GCC COUNTRIES: DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 233
GCC COUNTRIES: DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 234
GCC COUNTRIES: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 235
GCC COUNTRIES: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 236
GCC COUNTRIES: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 237
GCC COUNTRIES: DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 238
GCC COUNTRIES: DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 239
REST OF MIDDLE EAST & AFRICA: DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 240
REST OF MIDDLE EAST & AFRICA: DENTAL SUTURES MARKET, BY MATERIAL, 2024–2031 (USD MILLION)


TABLE 241
REST OF MIDDLE EAST & AFRICA: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 242
REST OF MIDDLE EAST & AFRICA: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 243
REST OF MIDDLE EAST & AFRICA: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024–2031 (USD MILLION)


TABLE 244
REST OF MIDDLE EAST & AFRICA: DENTAL SUTURES MARKET, BY APPLICATION, 2024–2031 (USD MILLION)


TABLE 245
REST OF MIDDLE EAST & AFRICA: DENTAL SUTURES MARKET, BY END USER, 2024–2031 (USD MILLION)


TABLE 246
OVERVIEW OF STRATEGIES DEPLOYED BY KEY PLAYERS IN DENTAL SUTURES MARKET


TABLE 247
DENTAL SUTURES MARKET: DEGREE OF COMPETITION


TABLE 248
DENTAL SUTURES MARKET: REGION FOOTPRINT


TABLE 249
DENTAL SUTURES MARKET: TYPE FOOTPRINT


TABLE 250
DENTAL SUTURES MARKET: MATERIAL FOOTPRINT


TABLE 251
DENTAL SUTURES MARKET: FILAMENT TYPE FOOTPRINT


TABLE 252
DENTAL SUTURES MARKET: DETAILED LIST OF KEY STARTUPS/SMES


TABLE 253
DENTAL SUTURES MARKET: COMPETITIVE BENCHMARKING OF STARTUPS/SMES


TABLE 254
DENTAL SUTURES MARKET: DEALS, JANUARY 2022–JULY 2026


TABLE 255
DENTAL SUTURES MARKET: EXPANSIONS, JANUARY 2022–JULY 2026


TABLE 256
DENTAL SUTURES MARKET: OTHER DEVELOPMENTS, JANUARY 2022–JULY 2026


TABLE 257
JOHNSON & JOHNSON: COMPANY OVERVIEW


TABLE 258
JOHNSON & JOHNSON: PRODUCTS OFFERED


TABLE 259
JOHNSON & JOHNSON: DEALS, JANUARY 2022–JULY 2026


TABLE 260
JOHNSON & JOHNSON: OTHER DEVELOPMENTS, JANUARY 2022–JULY 2026


TABLE 261
B. BRAUN SE: COMPANY OVERVIEW


TABLE 262
B. BRAUN SE: PRODUCTS OFFERED


TABLE 263
ADVANCED MEDICAL SOLUTIONS GROUP PLC: COMPANY OVERVIEW


TABLE 264
ADVANCED MEDICAL SOLUTIONS GROUP PLC: PRODUCTS OFFERED


TABLE 265
ADVANCED MEDICAL SOLUTIONS GROUP PLC: DEALS, JANUARY 2022–JULY 2026


TABLE 266
DEMETECH CORPORATION: COMPANY OVERVIEW


TABLE 267
DEMETECH CORPORATION: PRODUCTS OFFERED


TABLE 268
HU-FRIEDY MFG. CO., LLC: COMPANY OVERVIEW


TABLE 269
HU-FRIEDY MFG. CO., LLC: PRODUCTS OFFERED


TABLE 270
HU-FRIEDY MFG. CO., LLC: DEALS, JANUARY 2022–JULY 2026


TABLE 271
HU-FRIEDY MFG. CO., LLC: EXPANSIONS, JANUARY 2022–JULY 2026


TABLE 272
ENVISTA: COMPANY OVERVIEW


TABLE 273
ENVISTA: PRODUCTS OFFERED


TABLE 274
ENVISTA: DEALS, JANUARY 2022–JUNE 2025


TABLE 275
HENRY SCHEIN: COMPANY OVERVIEW


TABLE 276
HENRY SCHEIN: PRODUCTS OFFERED


TABLE 277
HENRY SCHEIN: DEALS, JANUARY 2022–JULY 2026


TABLE 278
HENRY SCHEIN, INC.: EXPANSIONS, JANUARY 2022–JULY 2026


TABLE 279
HENRY SCHEIN, INC.: OTHER DEVELOPMENTS, JANUARY 2022–JULY 2026


TABLE 280
FUTURA SURGICARE PVT. LTD.: COMPANY OVERVIEW


TABLE 281
FUTURA SURGICARE PVT. LTD.: PRODUCTS OFFERED


TABLE 282
FUTURA SURGICARE PVT. LTD.: DEALS, JANUARY 2022–JULY 2026


TABLE 283
MANI, INC.: COMPANY OVERVIEW


TABLE 284
MANI, INC.: PRODUCTS OFFERED


TABLE 285
MANI, INC.: OTHER DEVELOPMENTS, JANUARY 2022–JULY 2026


TABLE 286
CORZA MEDICAL: COMPANY OVERVIEW


TABLE 287
CORZA MEDICAL: PRODUCTS OFFERED


TABLE 288
CORZA MEDICAL: EXPANSIONS, JANUARY 2022–JULY 2026


TABLE 289
CORZA MEDICAL: OTHER DEVELOPMENTS, JANUARY 2022–JULY 2026


TABLE 290
SMI AG: COMPANY OVERVIEW


TABLE 291
SMI AG: PRODUCTS OFFERED


TABLE 292
YOUNG INNOVATIONS, INC.: COMPANY OVERVIEW


TABLE 293
YOUNG INNOVATIONS, INC.: PRODUCTS OFFERED


TABLE 294
YOUNG INNOVATIONS, INC.: DEALS, JANUARY 2022–JULY 2026


TABLE 295
ASSUT EUROPE: COMPANY OVERVIEW


TABLE 296
ASSUT EUROPE: PRODUCTS OFFERED


TABLE 297
KATSAN KATGÜT SANAYI VE TIC. A.S.: COMPANY OVERVIEW


TABLE 298
KATSAN KATGÜT SANAYI VE TIC. A.S.: PRODUCTS OFFERED


TABLE 299
KATSAN KATGÜT SANAYI VE TIC. A.S: OTHER DEVELOPMENTS, JANUARY 2022–JULY 2026


TABLE 300
DOGSAN TIBBI MALZEME SANAYI A.S.: COMPANY OVERVIEW


TABLE 301
DOGSAN TIBBI MALZEME SANAYI A.S.: PRODUCTS OFFERED


TABLE 302
DOGSAN TIBBI MALZEME SANAYI A.S.: OTHER DEVELOPMENTS, JANUARY 2022–JULY 2026


TABLE 303
RISK ASSESSMENT: DENTAL SUTURES MARKET


LIST OF FIGURES


FIGURE 1
DENTAL SUTURES MARKET SEGMENTATION & REGIONAL SCOPE


FIGURE 2
KEY INSIGHTS & MARKET HIGHLIGHTS


FIGURE 3
DENTAL SUTURES MARKET, 2024–2031 (USD MILLION)


FIGURE 4
MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN DENTAL SUTURES MARKET


FIGURE 5
DISRUPTIVE TRENDS IMPACTING GROWTH OF DENTAL SUTURES MARKET


FIGURE 6
HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS IN DENTAL SUTURES MARKET, 2025


FIGURE 7
ASIA PACIFIC TO REGISTER HIGHEST GROWTH DURING FORECAST PERIOD


FIGURE 8
INCREASING VOLUME OF DENTAL SURGERIES AND EXPANDING DENTAL CARE ACCESS TO DRIVE MARKET GROWTH


FIGURE 9
ASIA PACIFIC DENTAL SUTURES MARKET TO REGISTER HIGHEST GROWTH RATE DURING STUDY PERIOD


FIGURE 10
CHINA TO ACCOUNT FOR LARGEST MARKET SHARE IN 2025


FIGURE 11
INDIA TO REGISTER HIGHEST CAGR FROM 2026 TO 2031


FIGURE 12
EMERGING MARKETS TO REGISTER HIGHEST GROWTH DURING FORECAST PERIOD


FIGURE 13
DENTAL SUTURES MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES


FIGURE 14
UK: PROJECTED NUMBER OF ADULTS 16 YEARS AND OLDER WITH DENTAL CARIES, 2020 VS. 2035 VS. 2050


FIGURE 15
DENTAL SUTURES MARKET: PORTER’S FIVE FORCES ANALYSIS


FIGURE 16
DENTAL SUTURES MARKET: VALUE CHAIN ANALYSIS


FIGURE 17
DENTAL SUTURES MARKET: ECOSYSTEM ANALYSIS


FIGURE 18
DENTAL SUTURES MARKET: TRENDS/DISRUPTIONS IMPACTING CUSTOMERS’ BUSINESSES


FIGURE 19
TOP PATENT APPLICANTS AND OWNERS (COMPANIES/INSTITUTES) IN DENTAL SUTURES MARKET (JANUARY 2015–DECEMBER 2025)


FIGURE 20
JURISDICTION ANALYSIS: TOP APPLICANT COUNTRIES FOR DENTAL SUTURES PATENTS, 2015–2025


FIGURE 21
INFLUENCE OF KEY STAKEHOLDERS ON BUYING PROCESS OF DENTAL SUTURES, BY END USER


FIGURE 22
KEY BUYING CRITERIA FOR END USERS


FIGURE 23
DENTAL SUTURES MARKET: GEOGRAPHIC GROWTH OPPORTUNITIES


FIGURE 24
NORTH AMERICA: DENTAL SUTURES MARKET SNAPSHOT


FIGURE 25
ASIA PACIFIC: DENTAL SUTURES MARKET SNAPSHOT


FIGURE 26
REVENUE ANALYSIS OF KEY PLAYERS IN DENTAL SUTURES MARKET (2021−2025)


FIGURE 27
MARKET SHARE ANALYSIS OF KEY PLAYERS IN DENTAL SUTURES MARKET (2025)


FIGURE 28
DENTAL SUTURES MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025


FIGURE 29
DENTAL SUTURES MARKET: COMPANY FOOTPRINT


FIGURE 30
DENTAL SUTURES MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025


FIGURE 31
DENTAL SUTURES MARKET: BRAND/PRODUCT COMPARISON


FIGURE 32
EV/EBITDA OF KEY VENDORS


FIGURE 33
YEAR-TO-DATE (YTD) PRICE TOTAL RETURN AND 5-YEAR STOCK BETA OF KEY VENDOR


FIGURE 34
JOHNSON & JOHNSON: COMPANY SNAPSHOT (2025)


FIGURE 35
B. BRAUN SE: COMPANY SNAPSHOT (2025)


FIGURE 36
COMPANY SNAPSHOT: ADVANCED MEDICAL SOLUTIONS GROUP PLC (2025)


FIGURE 37
ENVISTA: COMPANY SNAPSHOT (2025)


FIGURE 38
HENRY SCHEIN: COMPANY SNAPSHOT (2025)


FIGURE 39
MANI, INC.: COMPANY SNAPSHOT (2025)


FIGURE 40
RESEARCH DESIGN


FIGURE 41
PRIMARY SOURCES


FIGURE 42
BOTTOM-UP APPROACH


FIGURE 43
TOP-DOWN APPROACH


FIGURE 44
DENTAL SUTURES MARKET SIZE ESTIMATION: REVENUE SHARE ANALYSIS (SUPPLY SIDE)


FIGURE 45
REVENUE SHARE ANALYSIS ILLUSTRATION: JOHNSON & JOHNSON


FIGURE 46
DENTAL SUTURES MARKET: SUPPLY-SIDE ANALYSIS (2025)


FIGURE 47
CAGR PROJECTIONS: SUPPLY-SIDE ANALYSIS


FIGURE 48
DATA TRIANGULATION METHODOLOGY


Methodology

The study involved four major activities to estimate the current size of the dental sutures market. Exhaustive secondary research was done to collect information on the market and its different subsegments. The next step was to validate these findings, assumptions, and sizing with industry experts across the value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the complete market size. Thereafter, market breakdown and data triangulation procedures were used to estimate the market size of the segments and subsegments.

Secondary Research

Secondary sources referred to for this research study include financial statements of companies offering adhesion barrier and information from various trade, business, and professional associations. The secondary data was collected and analyzed to arrive at the overall size of the dental sutures market, which was validated by primary respondents.

Primary Research

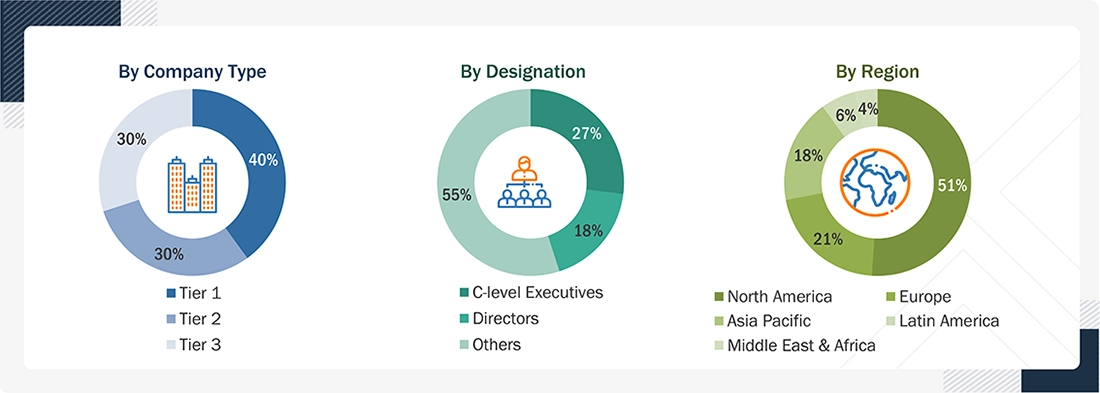
Extensive primary research was conducted after obtaining information regarding the dental sutures market scenario through secondary research. Several primary interviews were conducted with market experts from both the demand and supply sides across major countries of North America, Europe, Asia Pacific,  Latin America and the Middle East & Africa. Primary data was collected through questionnaires, emails, and telephonic interviews. The primary sources from the supply side included various industry experts, such as Chief X Officers (CXOs), Vice Presidents (VPs), and Directors, from business development, marketing, product development/innovation teams, and related key executives from dental suture manufacturers; distributors; and key opinion leaders.

Primary interviews were conducted to gather insights such as market statistics, data of revenue collected from the products and services, market breakdowns, market size estimations, market forecasting, and data triangulation. Primary research also helped in understanding the various trends related to technology, application, vertical, and region. Stakeholders from the demand side, customer/end users who are using dental sutures, were interviewed to understand the buyer’s perspective on the suppliers, products, and their current usage of dental sutures and future outlook of their business, which will affect the overall market.

Breakdown of Primary Interviews: Supply-Side Participants, By Company Type, Designation, and Region

Dental Sutures Market Size, and Share

Note: C-level executives include CEOs, COOs, CTOs, and VPs.
Other designations include sales managers, marketing managers, and product managers.
Companies are classified into tiers based on their total revenue. As of 2025: Tier 1 => USD 1 billion, Tier 2=USD 500 million to USD 1 billion, Tier 3=<USD 500 million.

To know about the assumptions considered for the study, download the pdf brochure

Market Size Estimation

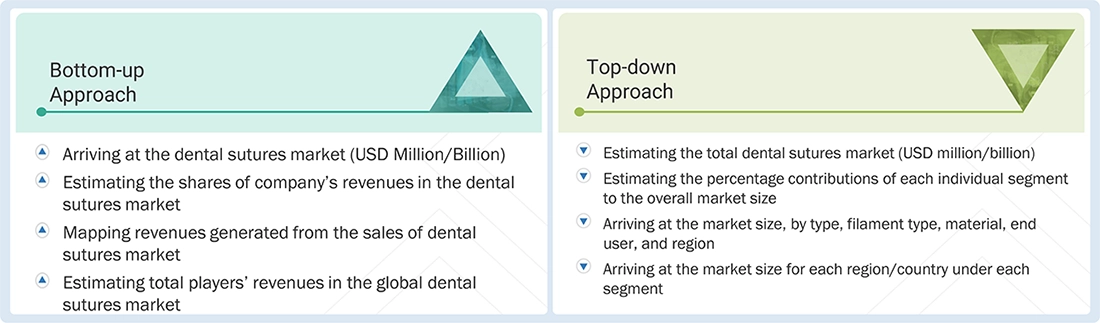
For the global market value, annual revenues were calculated based on the revenue mapping of major product manufacturers and OEMs active in the global dental sutures market. All the major product manufacturers were identified at the global and/or country/regional level. Revenue mapping of the respective business segments/subsegments was done for the major players. Also, the global dental sutures market was split into various segments and sub-segments based on:

  • List of major players operating in the dental sutures market at the regional and/or country level
  • Product mapping of various dental sutures manufacturers at the regional and/or country level
  • Mapping of annual revenue generated by listed major players from dental sutures (or the nearest reported business unit/product category)
  • Revenue mapping of major players to covered
  • Extrapolation of the revenue mapping of the listed major players to derive the global market value of the respective segments/subsegments
  • Summation of the market value of all segments/subsegments to arrive at the global dental sutures market

Dental Sutures Market : Top-Down and Bottom-Up Approach

Dental Sutures Market Top Down and Bottom Up Approach

Data Triangulation

The market was split into several segments and subsegments after arriving at the overall market size—using the market size estimation processes. Data triangulation and market breakdown procedures were employed to complete the overall market engineering process and arrive at the exact statistics of each market segment and subsegment. The data was triangulated by studying various factors and trends from both the demand and supply sides in the dental sutures market.

Market Definition

Dental sutures are sterile medical devices consisting of surgical threads used to approximate and secure tissues following dental and oral surgical procedures. They are used to close surgical wounds, control tissue positioning, and support healing after procedures such as tooth extraction, periodontal surgery, dental implant placement, bone grafting, and other oral surgical interventions.

Key Stakeholders

  • Dental suture manufacturers, vendors, and distributors
  • Hospitals
  • Dental clinics
  • Dental specialty centers
  • Ambulatory surgery centers
  • Market research and consulting firms
  • Venture capitalists
  • Research institutes and government organizations

Report Objectives

  • To describe, analyze, and forecast the dental sutures market by type, material, filament type, end user, and region
  • To provide detailed information regarding the drivers, restraints, opportunities, and challenges influencing the growth of the dental sutures market
  • To strategically analyze micromarkets1 with respect to individual growth trends, prospects, and contributions to the overall dental sutures market
  • To forecast the size of the dental sutures market with respect to five main regions (along with countries), namely, North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa
  • To profile key players and comprehensively analyze their market shares and core competencies2   in the dental sutures market
  • To analyze competitive developments such as partnerships, collaborations, agreements & acquisitions, expansions, and R&D activities in the dental sutures market
  • To benchmark players within the market using the proprietary Company Evaluation Matrix framework, which analyzes market players on various parameters within the broad categories of business and product strategy

Available customizations:

With the given market data, MarketsandMarkets offers customizations based on the company’s specific needs. The following customization options are available for the report:

Geographic Analysis

  • Further breakdown of the Rest of European dental sutures market into the Netherlands, Austria, Belgium, and others

  • Further breakdown of the Rest of Asia Pacific dental sutures market into Singapore, Malaysia, and others

Company Information

  • Detailed analysis and profiling of additional market players.


Personalize This Research

  • Triangulate with your Own Data
  • Get Data as per your Format and Definition
  • Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
  • Any level of Personalization
Request A Free Customisation

Let Us Help You

  • What are the Known and Unknown Adjacencies Impacting the Dental Sutures Market
  • What will your New Revenue Sources be?
  • Who will be your Top Customer; what will make them switch?
  • Defend your Market Share or Win Competitors
  • Get a Scorecard for Target Partners
Customized Workshop Request

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements

Get 10% Free Customisation

TESTIMONIALS

Growth opportunities and latent adjacency in Dental Sutures Market

DMCA.com Protection Status
popup img