



Digital X-ray Market
Report Code
MD 2562
Published in
Jan, 2026, By MarketsandMarkets™
Digital X-ray Market By Portability (Fixed, Portable), Applications (General, Dental, Mammography, Cancer, Fluoroscopy), Technology (Direct, Computed), System (Retrofit, New), End Users, Price Range, Type, and Region - Global Forecast to 2031

$5.76B
MARKET SIZE, 2025
$7.50B
MARKET SIZE, 2031

4.5%
CAGR (2025-2031)

2025-2031
FORECAST PERIOD
OVERVIEW
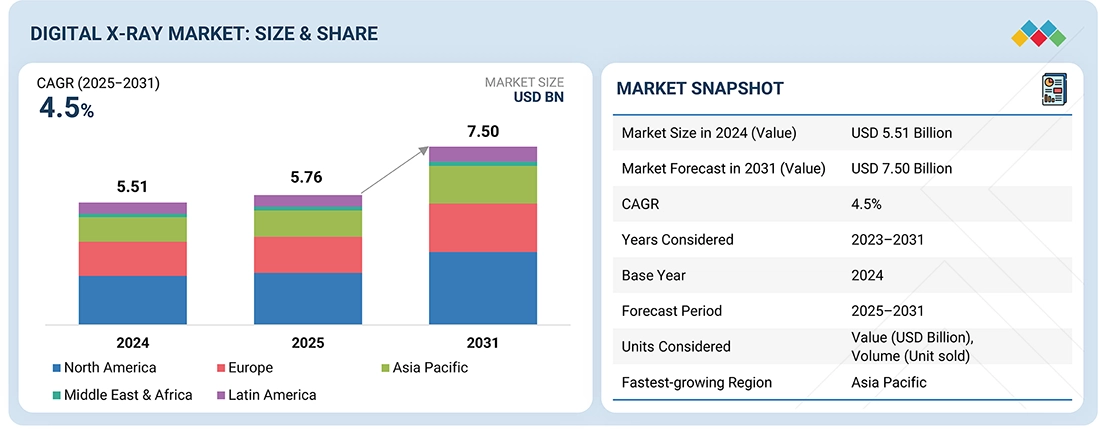
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
The global digital X-ray market, valued at USD 5.51 billion in 2024, stood at USD 5.76 billion in 2025 and is projected to advance at a resilient CAGR of 4.5% from 2025 to 2031, culminating in a forecasted valuation of USD 7.50 billion by the end of the period. The global digital X-ray market is experiencing steady growth due to the ongoing shift from analog to digital radiography. Digital X-ray technology has become essential in the diagnostic field owing to its ability to provide faster image capture, enhanced image quality, reduced radiation exposure, and optimized workflow processes. This market is further supported by continuously improving diagnostic imaging procedures, an aging population at higher risk of cancers and orthopedic disorders, rising prevalence of chronic diseases and orthopedic disorders, and increasing cases of trauma and emergencies. Additionally, developing medical infrastructure, such as diagnostic centers and multi-specialty hospitals, continues to support demand for the digital X-ray market.
KEY TAKEAWAYS
-
MARKET SNAPSHOT:
Base Year Market Size (2024): USD 5.51 Billion
Current Market Size (2025): USD 5.76 Billion
Forecast Market Size (2031): USD 7.50 Billion
CAGR (2025–2031): 4.5% -
SEGMENT LEADERSHIP:
Type Leader: Digital X-ray systems accounted for a 88.0% revenue share of the digital X-ray market in 2025.
Technology Leader: Direct radiography is expected to register the highest CAGR of 5.2% during the forecast period.
System Type Leader: Retrofit digital X-ray systems accounted for a 59.5% revenue share of the digital X-ray market in 2025.
Portability Leader: Fixed digital X-ray systems accounted for the major revenue share of the digital X-ray market in 2025.
Application Leader: Chest imaging held 36.1% of the digital X-ray market in 2025.
Price Range Leader: Low-end digital X-ray systems accounted for a 39.2% revenue share of the digital X-ray market in 2025.
End User Leader: Hospitals accounted for the major revenue share of the digital X-ray market in 2025. -
MARKET OUTLOOK & COMPETITIVE LANDSCAPE:
Siemens Healthineers, GE Healthcare, Canon, and Philips were identified as some of the key players in the US digital X-ray market. Growth in digital X-ray is driven by expanding healthcare infrastructure, rising diagnostic demand, and rapid adoption of advanced digital and portable imaging technologies.
Companies such as JPI Healthcare Solutions, IBIS S.R.L, and BPL Technologies have established a presence among small players in the digital X-ray market. These players serve the growing demand for cost-effective digital imaging solutions and localized manufacturing by emerging healthcare facilities.
One of the most dominant trends in the digital X-ray market is the growing preference for direct digital radiography systems over computed radiography systems. This, in turn, reflects a broader shift toward a comprehensive digital environment. Healthcare facilities are now looking for systems that enable faster processing, fewer retakes, and a more efficient interface with hospital information systems. Another significant trend in this segment is the rising demand for optimized workflows and user-centric systems that minimize procedure downtime and maximize productivity. There is also a rise in technically advanced systems capable of delivering consistent image quality across a variety of applications. Additionally, innovations such as FPDs, AI integration with workflow management and image analysis, a rising preference for portable and mobile X-ray units, and integration with digital health networks (PACS/EHR) are facilitating greater adoption of digital X-ray systems.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
Healthcare providers are under pressure to balance diagnostic accuracy with operational efficiency and cost containment. This has driven a shift toward digital X-ray systems that support higher patient throughput, standardized imaging protocols, and reduced dependence on consumables. The increasing integration of digital X-ray systems with enterprise imaging platforms is transforming how imaging departments manage data, collaborate across care teams, and deliver diagnostic outcomes. Meanwhile, procurement decisions are increasingly based on total cost of ownership rather than system pricing in isolation. These dynamics compel customers to reassess vendor selection, service contracts, and long-term technology roadmaps, leading to disruption through traditional purchasing and upgrade cycles.
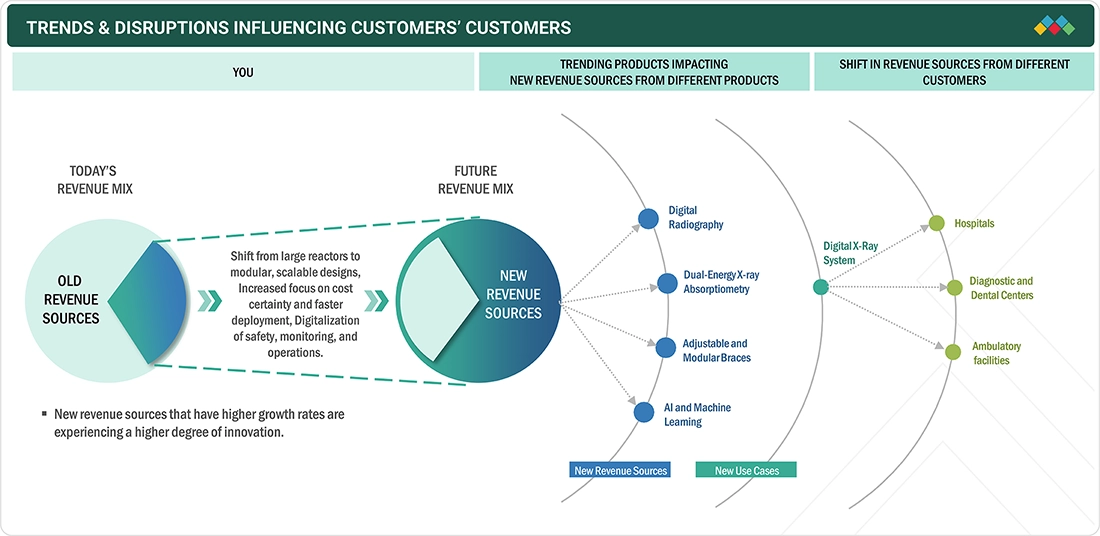
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Drivers
Impact
Level
Level
-
Rising aging population and prevalence of chronic diseases.

-
Advantages of digital X-ray systems over conventional analog imaging


RESTRAINTS
Impact
Level
Level
-
High upfront and installation costs

-
Radiation exposure and related safety risks


OPPORTUNITIES
Impact
Level
Level
-
Advancement of AI-enabled digital X-ray technologies

-
Expansion of portable digital X-ray systems for remote and emergency care


CHALLENGES
Impact
Level
Level
-
Reduced healthcare spending and budget constraints in hospitals

-
Growing preference for refurbished and pre-owned imaging systems

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Rising volume of X-ray scans at hospitals & imaging centers
The growth of the global digital X-ray market is driven by increased diagnostic imaging at hospitals and diagnostic centers. Rising chronic diseases, musculoskeletal disorders, and trauma boost the need for radiographic exams. Digital X-ray systems' technological benefits, lower radiation, faster images, and better diagnostic confidence promote adoption. Government efforts to enhance healthcare access and infrastructure also boost demand. Market growth is further supported by replacing old analog systems with modern ones and the push toward healthcare digitization.
Restraint: Radiation exposure and related safety risks
A major barrier to widespread X-ray use is radiation safety risks. Repeated or high doses raise health concerns for patients and staff. Safety regulations, patient awareness, and regulatory oversight compel healthcare providers to carefully manage radiation doses while maintaining diagnostic accuracy. This leads to increased spending on dose optimization, equipment calibration, and staff training, which improve safety but also raise costs and complicate operations. Consequently, radiation management is crucial in deploying digital X-ray systems.
Opportunity: Advancement of AI-enabled digital X-ray technologies
AI-driven digital X-ray systems are transforming diagnostic imaging to be more precise and faster. They improve image quality, boost lesion detection, and assist decision-making, enabling faster, more accurate diagnoses despite rising imaging volumes. AI algorithms now quickly examine X-ray images, detect abnormalities, flag urgent cases, and reduce errors. This relieves radiologists and clinicians from repetitive imaging and allows them to verify work quality and safety. AI devices also offer prediction, planning, and optimization features crucial for modern healthcare, such as early device failure alerts and workflow automation. Innovations like dose modulation and remote controls reduce patient stress. Providers aim to shift from reactive to proactive roles, lowering turnaround times, costs, and variability in diagnostics, while supporting AI market growth in medical imaging.
Challenge: Growing preference for refurbished and pre-owned imaging systems
Hospitals face tough choices between digital X-ray investments and other priorities due to limited budgets and high equipment costs. Without clear reimbursement, they often buy refurbished devices resold 40-60% cheaper than new, supporting demand for affordable, quality systems from independent suppliers. Many equipment makers, such as Siemens and Philips, have launched refurbishing programs, such as Siemens' Ecoline and Philips' Diamond Select, to tap into this market. Smaller manufacturers find the high demand challenging. To stay competitive, companies must either reduce prices or develop innovative, advanced technologies that meet unmet clinical and operational needs.
DIGITAL X-RAY MARKET: GROWTH, SIZE, SHARE, AND TRENDS: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Siemens Healthineers offers advanced x-ray systems used in both diagnostic and interventional applications. Their digital radiography solutions are designed to provide high-quality imaging, particularly in urgent care and outpatient settings. | Excellent image quality for faster, more accurate diagnoses | Reduced radiation dose and high patient throughput | Integration with other Siemens systems for seamless workflow in medical environments |
 |
GE Healthcare's x-ray detectors are employed in a variety of healthcare settings, including hospitals, outpatient clinics, and imaging centers. They specialize in providing both analog and digital imaging solutions. | High-resolution imaging with advanced image processing capabilities | Enhanced diagnostic confidence with faster image acquisition | Cost-effective solutions for healthcare providers with flexible system integration |
 |
Fujifilm provides digital x-ray detectors that support a broad spectrum of clinical examinations, including digital radiography (DR), fluoroscopy, and mobile imaging solutions. | Superior image quality with low radiation doses | High-speed image capture for better workflow efficiency | Enhanced diagnostic accuracy with reliable, scalable systems |
 |
Canon Medical's digital x-ray detectors are used in a variety of diagnostic imaging applications, from emergency care to long-term outpatient monitoring, delivering precise and detailed images for various clinical procedures | High-quality images with reduced radiation dose | Fast workflow and seamless integration into existing hospital systems | Improved diagnostic confidence with advanced image processing and clarity |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
The players in the digital X-ray market ecosystem include component suppliers, system manufacturers, software providers, distributors, service providers, and end users. Detector manufacturers and imaging software developers are crucial to system performance and differentiation. Original equipment manufacturers integrate these components into complete imaging solutions, with installation, training, and after-sales services. Distributors and channel partners provide access to regional markets, especially in emerging economies. End users include hospitals, diagnostic imaging centers, specialty clinics, and ambulatory care facilities, each with distinct purchasing and utilization dynamics.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
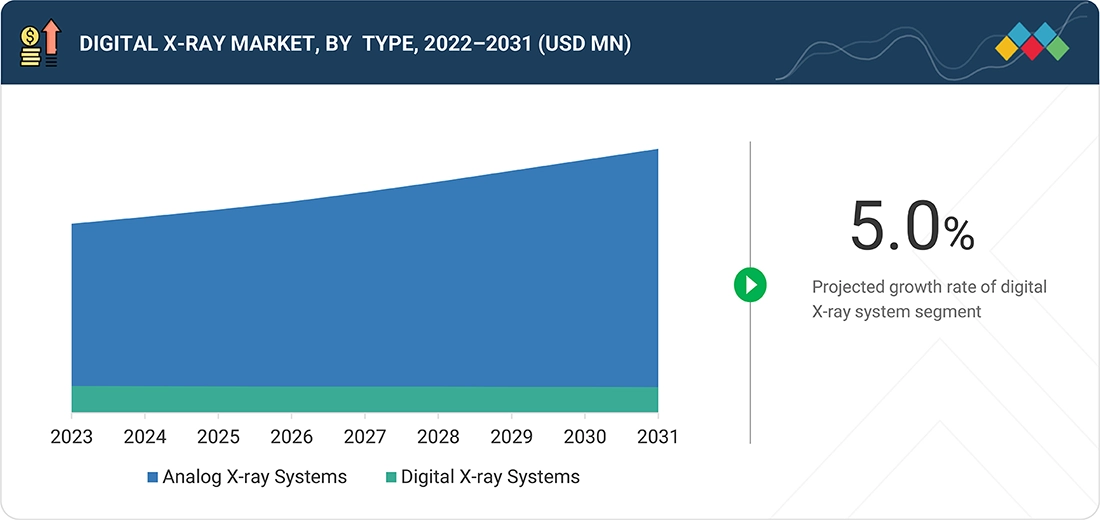
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Digital X-ray Market, By Type
The digital X-ray market is divided into analog and digital systems; the latter segment projected to grow due to the shift from traditional to digital imaging, especially in hospitals and diagnostic centers. Digital systems offer fast image capture, real-time processing, eliminate film workflows, and reduce patient wait times. These advantages boost efficiency, patient throughput, and support quicker clinical decisions. Digital images can be stored, retrieved, and shared easily via electronic platforms, enabling seamless integration with electronic health records (EHR) and picture archiving and communication systems (PACS). This facilitates tele-radiology, remote consultations, and information exchange among healthcare providers.
Digital X-ray Market, By Technology
The digital X-ray market is divided into direct and computed radiography, with the direct radiography segment leading in 2025. Its growth is driven by the demand for fast, high-quality diagnostic images that improve diagnosis efficiency. Direct radiography provides immediate imaging, higher resolution, lower doses than traditional methods, and easy integration with hospital IT systems such as PACS and EHRs. Its quick and efficient diagnostic capabilities make it the preferred choice in hospitals.
Digital X-ray Market, By System Type
The digital X-ray market is segmented into retrofit and new digital systems, with the latter dominating in 2025. Healthcare providers favor new digital X-ray due to its advanced, efficient, and accurate imaging capabilities needed for increasing patient loads. Modern equipment offers higher resolution, faster capture, lower patient doses, and better integration with hospital systems. Emerging AI-based imaging, portable devices, and advanced detectors are prompting upgrades from older X-ray systems to modern digital solutions.
Digital X-ray Market, By Application
The digital X-ray market by end user includes hospitals, diagnostic centers, and dental care centers, with hospitals holding the largest share in 2025. Hospitals in the US are a major demand segment, focusing on upgrading diagnostic imaging for efficiency and patient care. They are shifting from analog to digital X-ray systems to benefit from quick image acquisition, high quality, low radiation, and integrated electronic health records (EHR) and PACS. This transition streamlines workflows and reduces turnaround times. Factors like increased patient load, demand for accurate diagnostics, government healthcare initiatives, and support for advanced clinical applications have driven US hospitals to adopt digital X-ray technology.
Digital X-ray Market, By End User
The digital X-ray market's end users include hospitals, diagnostic, and dental centers, with hospitals holding the largest share. Hospitals are a major demand segment due to their focus on upgrading diagnostic infrastructure to enhance efficiency and patient care. They are shifting from analog to digital X-ray systems to benefit from quick imaging, high quality, low radiation, and integrated electronic health records (EHR) and PACS, streamlining workflows and reducing turnaround times. Factors like increased patient volume, demand for fast, accurate diagnostics, government healthcare initiatives, and the need for advanced clinical applications drive hospitals to adopt digital X-ray technologies.
REGION
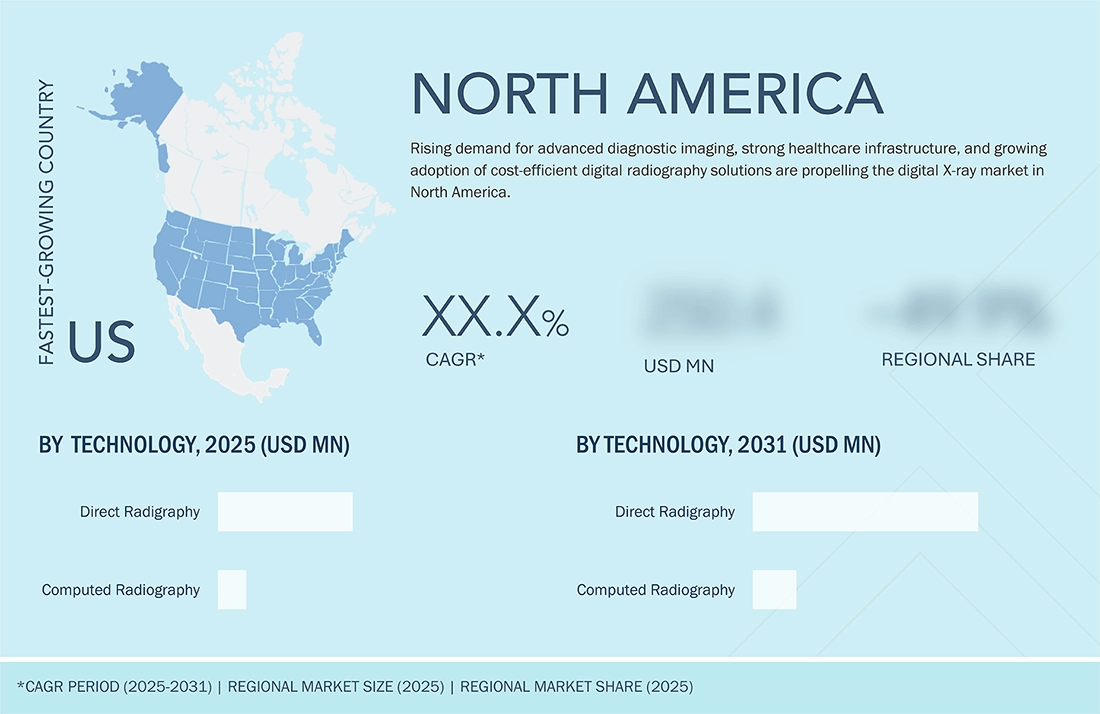
North America accounted for the largest share of the digital X-ray systems market
North America is the largest region in the global digital X-ray market, given its well-established healthcare infrastructure, high utilization rates of diagnostic imaging, and early adoption of digital technologies. Strong healthcare spending, favorable reimbursement frameworks, and a presence of leading imaging manufacturers further support the leadership.
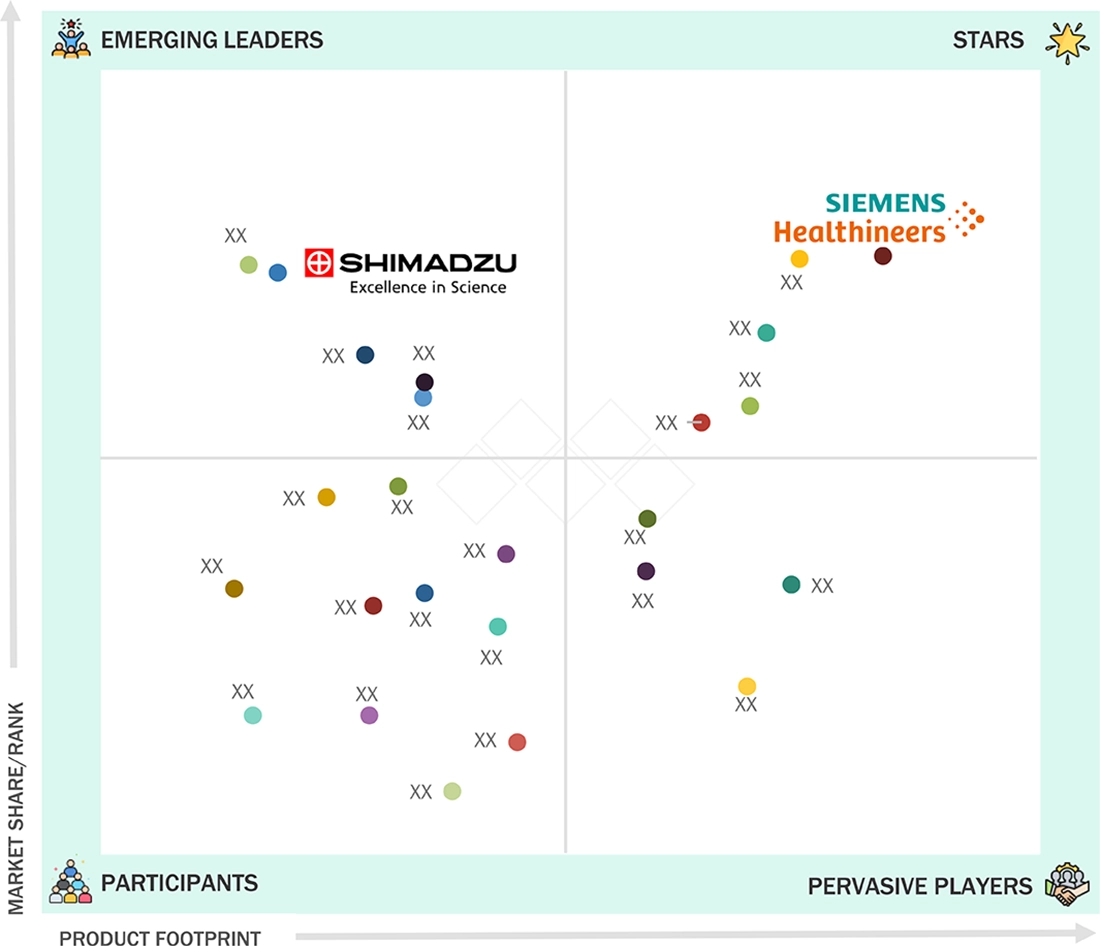
DIGITAL X-RAY MARKET: GROWTH, SIZE, SHARE, AND TRENDS: COMPANY EVALUATION MATRIX
Competition in the global digital X-ray market is dominated by established MNCs with strong portfolios and distribution channels worldwide. The best way for these companies to differentiate themselves is to innovate, emphasize reliability, and provide comprehensive services. Mid-market companies will focus on cost-effective, localized solutions, while smaller companies will concentrate on niches. The intensity of competition in this industry is high, and new product development, collaborations, and expansion are the major focal points of competition.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- Siemens Healthineers AG (US)
- Konica Minolta, Inc (Japan)
- GE HealthCare (US)
- Shimadzu Corporation (Japan)
- Agfa-Gevaert Group (Belgium)
- Canon Medical Systems Coproation (Japan)
- Carestream Health (US)
- FUJIFILM Corporation (Japan)
- JPI Healthcare Solution (Germany)
- Shanghai United Imaging Healthcare Co., LTD (China)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2024 (Value) | USD 5.51 Billion |
| Market Forecast in 2031 (value) | USD 7.50 Billion |
| Growth Rate | CAGR of 4.5% from 2025–2031 |
| Years Considered | 2023–2031 |
| Base Year | 2024 |
| Forecast Period | 2025–2031 |
| Units Considered | Value (USD Million/Billion) |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered |
|
| Regions Covered | North America, Europe, Asia-Pacific, Middle East & Africa |
WHAT IS IN IT FOR YOU: DIGITAL X-RAY MARKET: GROWTH, SIZE, SHARE, AND TRENDS REPORT CONTENT GUIDE
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Imaging OEM - MNC |
|
|
| Imaging OEM - MNC |
|
Installed base and unit sales of various digital X-ray system categories at regional level |
RECENT DEVELOPMENTS
- November 2025 : Canon Medical Systems Corporation began sales of Mobirex i9 / Smart Edition, a high-end mobile X-ray system with enhanced radiographic support functions.
- July 2025 : Canon Medical announced the release of Radrex i5 / Flex Edition, a general radiography system with high image quality and ease of use, designed with intelligent features for patient-friendly examination.
- July 2025 : GE HealthCare launched the Definium Pace Select ET, a novel floor-mounted digital X-ray system that enables access to cost-effective, high-quality medical imaging technology while easing workflow challenges in high-volume settings.
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
TITLE
PAGE NO
1
INTRODUCTION
26
2
EXECUTIVE SUMMARY
30
3
PREMIUM INSIGHTS
35
4
MARKET OVERVIEW
AI-driven digital X-ray systems revolutionize imaging amidst aging demographics and evolving healthcare demands.
38
4.1
INTRODUCTION
4.2
MARKET DYNAMICS
4.2.1
DRIVERS
4.2.1.1
RISING AGING POPULATION AND ASSOCIATED INCREASE IN PREVALENCE OF CHRONIC AND AGE-RELATED DISEASES
4.2.1.2
ADVANTAGES OF DIGITAL X-RAY SYSTEMS OVER CONVENTIONAL ANALOG IMAGING
4.2.1.3
RISING ADOPTION IN EMERGENCY, TRAUMA, AND POINT-OF-CARE IMAGING
4.2.2
RESTRAINTS
4.2.2.1
HIGH UPFRONT AND INSTALLATION COSTS
4.2.2.2
CONCERNS REGARDING RADIATION EXPOSURE AND RELATED SAFETY RISKS
4.2.2.3
SHORTAGE OF SKILLED RADIOLOGY PROFESSIONALS AND DIGITAL IMAGING SPECIALISTS
4.2.3
OPPORTUNITIES
4.2.3.1
ADVANCEMENT OF AI-ENABLED DIGITAL X-RAY TECHNOLOGIES
4.2.3.2
EXPANSION OF PORTABLE DIGITAL X-RAY SYSTEMS FOR REMOTE AND EMERGENCY CARE
4.2.3.3
INCREASING INTEGRATION OF AI-ASSISTED IMAGE ANALYSIS WITH DIGITAL X-RAY SYSTEMS
4.2.4
CHALLENGES
4.2.4.1
INTEGRATION WITH HOSPITAL IT INFRASTRUCTURE AND CYBERSECURITY REQUIREMENTS
4.2.4.2
GROWING PREFERENCE FOR REFURBISHED AND PRE-OWNED IMAGING SYSTEMS
4.3
INTERCONNECTED MARKETS & CROSS-SECTOR OPPORTUNITIES
4.4
STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5
INDUSTRY TRENDS
AI-driven digital X-ray systems revolutionize market dynamics amid shifting competitive forces.
44
5.1
PORTER’S FIVE FORCES ANALYSIS
5.1.1
INTENSITY OF COMPETITIVE RIVALRY
5.1.2
BARGAINING POWER OF SUPPLIERS
5.1.3
BARGAINING POWER OF BUYERS
5.1.4
THREAT OF SUBSTITUTES
5.1.5
THREAT OF NEW ENTRANTS
5.2
MACROECONOMIC OUTLOOK
5.2.1
INTRODUCTION
5.2.2
GDP TRENDS AND FORECAST
5.2.3
TRENDS IN GLOBAL DIGITAL X-RAY MARKET
5.2.3.1
GROWING ADOPTION OF AI-ENABLED DIGITAL X-RAY SYSTEMS
5.2.3.2
INCREASING DEMAND FOR PORTABLE AND MOBILE DIGITAL X-RAY SYSTEMS
5.2.3.3
TRANSITION FROM COMPUTED RADIOGRAPHY (CR) TO DIRECT DIGITAL RADIOGRAPHY (DR)
5.2.3.4
TRANSITION FROM COMPUTED RADIOGRAPHY (CR) TO DIRECT DIGITAL RADIOGRAPHY (DR)
5.2.3.5
INTEGRATION OF CLOUD CONNECTIVITY AND DIGITAL IMAGING WORKFLOW SOLUTIONS
5.3
VALUE CHAIN ANALYSIS
5.3.1
RESEARCH & DEVELOPMENT
5.3.2
RAW MATERIAL PROCUREMENT
5.3.3
MANUFACTURING
5.3.4
DISTRIBUTION
5.3.5
MARKETING & SALES
5.3.6
POST-SALES SERVICES
5.4
ECOSYSTEM ANALYSIS
5.5
PRICING ANALYSIS
5.5.1
AVERAGE SELLING PRICE TREND, BY REGION
5.6
TRADE DATA ANALYSIS
5.6.1
IMPORT DATA FOR HS CODE 902214)
5.6.2
EXPORT DATA FOR HS CODE 902214
5.7
KEY CONFERENCES & EVENTS, 2026–2027
5.8
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
5.9
INVESTMENT & FUNDING SCENARIO
5.10
CASE STUDY ANALYSIS
5.10.1
TRANSFORMING RURAL DIAGNOSTIC IMAGING THROUGH ADVANCED IMAGING TECHNOLOGIES
5.10.2
LOW-DOSE DIGITAL RADIOGRAPHY SOLUTIONS FOR ENHANCED CLINICAL WORKFLOW AND PATIENT CARE
5.10.3
DIGITAL X-RAY FOR IMPROVED DIAGNOSIS, PATIENT ENGAGEMENT, AND TREATMENT COMPLIANCE
5.11
IMPACT OF US TARIFF – DIGITAL X-RAY MARKET
5.11.1
INTRODUCTION
5.11.2
KEY TARIFF RATES
5.11.3
PRICE IMPACT ANALYSIS
5.11.4
IMPACT ON COUNTRIES/REGIONS
5.11.4.1
US
5.11.4.2
EUROPE
5.11.4.3
ASIA PACIFIC
5.11.5
IMPACT ON END USERS
6
STRATEGIC DISRUPTION THROUGH TECHNOLOGY, PATENTS, AND AI ADOPTIONS
Unlock market potential with AI-driven digital X-ray innovations and strategic patent insights.
65
6.1
KEY TECHNOLOGIES
6.1.1
ADVANCED DIGITAL X-RAY SYSTEMS
6.1.2
PORTABLE DIGITAL X-RAY SYSTEMS
6.1.3
AI-ENABLED IMAGE PROCESSING AND CLINICAL DECISION SUPPORT
6.2
COMPLEMENTARY TECHNOLOGIES
6.2.1
FLAT-PANEL DETECTORS (FPDS)
6.2.2
AI-BASED IMAGE PROCESSING AND DIAGNOSTIC SOFTWARE
6.2.3
PACS, RIS, AND CLOUD-BASED IMAGING INTEGRATION
6.3
ADJACENT TECHNOLOGIES
6.3.1
ARTIFICIAL INTELLIGENCE (AI) AND MACHINE LEARNING (ML)
6.3.2
INTERNET OF MEDICAL THINGS (IOMT)
6.3.3
ADVANCED VISUALIZATION AND 3D IMAGING TECHNOLOGIES
6.4
PATENT ANALYSIS
6.5
IMPACT OF AI/GEN AI ON DIGITAL X-RAY MARKET
6.5.1
TOP USE CASES AND MARKET POTENTIAL
6.5.2
BEST PRACTICES FOLLOWED BY COMPANIES IN DIGITAL X-RAY MARKET
6.5.3
CASE STUDIES RELATED TO AI/GEN AI IMPLEMENTATION IN DIGITAL X-RAY MARKET
6.5.4
INTERCONNECTED ECOSYSTEM AND IMPACT ON MARKET PLAYERS
6.5.5
CLIENT'S READINESS TO ADOPT AI/GEN AI IN DIGITAL X-RAY MARKET
6.6
SUCCESS STORIES AND REAL-WORLD APPLICATIONS
7
REGULATORY LANDSCAPE
Navigate global regulatory complexities with insights on regional trends and key governmental bodies.
74
7.1
REGULATORY SCENARIO
7.1.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
7.1.2
REGULATORY TRENDS
7.1.2.1
NORTH AMERICA
7.1.2.1.1
US
7.1.2.2
EUROPE
7.1.2.3
ASIA PACIFIC
7.1.2.4
REST OF THE WORLD
8
CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
Identify key influencers and unmet needs driving digital X-ray purchasing decisions.
78
8.1
DECISION-MAKING PROCESS
8.2
KEY STAKEHOLDERS & BUYING CRITERIA
8.2.1
KEY STAKEHOLDERS IN BUYING PROCESS
8.2.2
KEY BUYING CRITERIA
8.3
ADOPTION BARRIERS AND INTERNAL CHALLENGES
8.4
UNMET NEEDS OF VARIOUS APPLICATIONS
9
DIGITAL X-RAY MARKET, BY PRICE RANGE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 4 Data Tables
82
9.1
INTRODUCTION
9.2
AFFORDABLE/ LOW-END DIGITAL X-RAY SYSTEMS
9.2.1
COST-EFFECTIVE SOLUTIONS TO DRIVE ADOPTION ACROSS RESOURCE-CONSTRAINED HEALTHCARE FACILITIES
9.3
MID-RANGE DIGITAL X-RAY SYSTEMS
9.3.1
HIGH IMAGING AND WORKFLOW CAPABILITIES TO AUGMENT DEMAND
9.4
PREMIUM/HIGH-END DIGITAL X-RAY SYSTEMS
9.4.1
ADVANCED AUTOMATION AND HIGH-PERFORMANCE IMAGING TO DRIVE ADOPTION IN HIGH-VOLUME FACILITIES
10
DIGITAL X-RAY MARKET, BY TECHNOLOGY
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 3 Data Tables
86
10.1
INTRODUCTION
10.2
DIRECT RADIOGRAPHY
10.2.1
TECHNOLOGICAL ADVANCEMENTS AND EXPANDING DIGITAL HEALTHCARE INFRASTRUCTURE TO DRIVE ADOPTION
10.3
COMPUTED RADIOGRAPHY
10.3.1
HEALTHCARE MODERNIZATION TO SHIFT INVESTMENT FROM CR TOWARD FLAT-PANEL DR
11
DIGITAL X-RAY MARKET, BY SYSTEM TYPE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 3 Data Tables
90
11.1
INTRODUCTION
11.2
RETROFIT DIGITAL X-RAY SYSTEMS
11.2.1
HOSPITAL EXPANSION AND AI-ENABLED WORKFLOW AUTOMATION TO DRIVE ADOPTION
11.3
NEW DIGITAL X-RAY SYSTEMS
11.3.1
EFFORTS BY MAJOR PLAYERS TO BOOST ADOPTION
12
DIGITAL X-RAY MARKET, BY PORTABILITY
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 9 Data Tables
94
12.1
INTRODUCTION
12.2
FIXED
12.2.1
FLOOR-TO-CEILING-MOUNTED SYSTEMS
12.2.1.1
COST-EFFECTIVE INSTALLATION, FLEXIBLE POSITIONING, AND WORKFLOW AUTOMATION TO DRIVE ADOPTION
12.2.2
CEILING-MOUNTED SYSTEMS
12.2.2.1
SUPERIOR POSITIONING FLEXIBILITY AND WORKFLOW AUTOMATION TO SUPPORT ADOPTION
12.3
PORTABLE
12.3.1
MOBILE X-RAY SYSTEMS
12.3.1.1
POINT-OF-CARE IMAGE AVAILABILITY TO SUPPORT GROWTH
12.3.2
HANDHELD X-RAY SYSTEMS
12.3.2.1
PRODUCT MINIATURIZATION AND EXPANDING DENTAL AND ORTHOPEDIC APPLICATIONS TO ACCELERATE GROWTH
13
DIGITAL X-RAY MARKET, BY TYPE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 3 Data Tables
102
13.1
INTRODUCTION
13.2
ANALOG X-RAY SYSTEMS
13.2.1
DIGITAL MODERNIZATION OF HEALTHCARE FACILITIES TO CONSTRAIN ANALOG X-RAY SYSTEM DEMAND
13.3
DIGITAL X-RAY
13.3.1
TECHNOLOGICAL ADVANTAGES AND PUBLIC/PRIVATE COLLABORATIONS TO SUPPORT GROWTH
14
DIGITAL X-RAY MARKET, BY APPLICATION
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 8 Data Tables
106
14.1
INTRODUCTION
14.2
CHEST IMAGING
14.2.1
RISING CHEST IMAGING VOLUMES TO DRIVE MARKET GROWTH
14.3
ORTHOPEDICS
14.3.1
RISING OSTEOPOROSIS AND FRAGILITY-FRACTURE BURDEN TO DRIVE ADOPTION
14.4
CARDIOVASCULAR IMAGING
14.4.1
CARDIOVASCULAR DISEASE BURDEN AND EXPANSION OF IMAGE-GUIDED INTERVENTIONS TO DRIVE DEMAND
14.5
DENTAL APPLICATIONS
14.5.1
HIGH DENTAL-TREATMENT VOLUMES AND GLOBAL CARIES BURDEN TO SUPPORT ADOPTION
14.6
PEDIATRIC IMAGING
14.6.1
EXPANSION OF NEONATAL AND PEDIATRIC CRITICAL CARE TO DRIVE DEMAND
14.7
CANCER DIAGNOSIS & TREATMENT
14.7.1
INCREASING GLOBAL CANCER CASES TO EXPAND DEMAND FOR DIAGNOSTIC AND TREATMENT-SUPPORT IMAGING
14.8
OTHER APPLICATIONS
15
DIGITAL X-RAY MARKET, BY END USER
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 4 Data Tables
116
15.1
INTRODUCTION
15.2
HOSPITALS
15.2.1
ADOPTION OF AI-ENABLED, MOBILE, AND ENTERPRISE-INTEGRATED DIGITAL X-RAY SYSTEMS TO DRIVE SEGMENT GROWTH
15.3
DIAGNOSTIC CENTERS
15.3.1
RISING OUTPATIENT IMAGING VOLUMES AND ADOPTION OF HIGH-THROUGHPUT, CLOUD-CONNECTED SYSTEMS TO DRIVE GROWTH
15.4
DENTAL CARE CENTERS
15.4.1
HIGH BURDEN OF DENTAL DISEASES AND SHIFT FROM FILM-BASED IMAGING TO DIGITAL SENSORS TO DRIVE ADOPTION
16
DIGITAL X-RAY MARKET, BY REGION
Comprehensive coverage of 8 Regions with country-level deep-dive of 14 Countries | 65 Data Tables.
121
16.1
INTRODUCTION
16.2
NORTH AMERICA
16.2.1
US
16.2.1.1
RISING DIAGNOSTIC WORKLOADS TO ACCELERATE INVESTMENT IN AI-ENABLED AND WORKFLOW-OPTIMIZED X-RAY SYSTEMS
16.2.2
CANADA
16.2.2.1
AGING POPULATION, RURAL IMAGING NEEDS, AND REPLACEMENT OF END-OF-LIFE EQUIPMENT TO DRIVE MARKET
16.3
EUROPE
16.3.1
GERMANY
16.3.1.1
HIGH X-RAY UTILIZATION, AGING DEMOGRAPHICS, AND EXPANDING HOSPITAL ACTIVITY TO DRIVE AUTOMATED DR REPLACEMENT
16.3.2
UK
16.3.2.1
GOVERNMENT CAPITAL FUNDING AND CDC DEVELOPMENT TO EXPAND DIGITAL RADIOGRAPHY CAPACITY
16.3.3
FRANCE
16.3.3.1
HOSPITAL IMAGING DEMAND AND GOVERNMENT-SUPPORTED RIS UPGRADES TO STRENGTHEN MARKET
16.3.4
ITALY
16.3.4.1
AGING POPULATION, RISING CANCER INCIDENCE, AND HEALTHCARE MODERNIZATION TO ACCELERATE MARKET GROWTH
16.3.5
SPAIN
16.3.5.1
INCREASE IN EMERGENCY AND ORTHOPEDIC EXAMINATIONS, EXPANSION OF COMMUNITY-BASED IMAGING – MARKET DRIVERS
16.3.6
REST OF EUROPE
16.4
ASIA PACIFIC
16.4.1
CHINA
16.4.1.1
GROWTH IN DISPOSABLE INCOME AND HEALTHCARE EXPENDITURE TO DRIVE MARKET
16.4.2
JAPAN
16.4.2.1
RISING CANCER AND CARDIOVASCULAR BURDEN BOOSTS MARKET
16.4.3
INDIA
16.4.3.1
AI-ENABLED TB SCREENING AND COMMUNITY HEALTHCARE EXPANSION TO ACCELERATE DIGITAL X-RAY ADOPTION
16.4.4
AUSTRALIA
16.4.4.1
PEDIATRIC SYSTEM MODERNIZATION AND REMOTE-CARE NEEDS TO SUSTAIN DIGITAL X-RAY DEMAND
16.4.5
SOUTH KOREA
16.4.5.1
SUPER-AGING, HIGH IMAGING UTILIZATION, AND RAPID AI INTEGRATION TO DRIVE MARKET
16.4.6
REST OF ASIA PACIFIC
16.5
LATIN AMERICA
16.5.1
BRAZIL
16.5.1.1
GOVERNMENT PROCUREMENT AND EXPANDING ONCOLOGY IMAGING DEMAND TO ACCELERATE ADOPTION
16.5.2
MEXICO
16.5.2.1
GOVERNMENT-LED HOSPITAL MODERNIZATION, EXPANDING DIGITAL IMAGING CAPACITY, AND RISING CANCER BURDEN TO DRIVE MARKET
16.5.3
REST OF LATIN AMERICA
16.6
MIDDLE EAST & AFRICA
16.6.1
GCC
16.6.1.1
INFRASTRUCTURE EXPANSION TO ACCELERATE DIGITAL X-RAY MODERNIZATION ACROSS REGION
16.6.2
REST OF MIDDLE EAST & AFRICA
16.6.2.1
HIGH TB BURDEN, AI-ENABLED SCREENING, AND DECENTRALIZED CARE TO ACCELERATE PORTABLE DIGITAL X-RAY DEPLOYMENT
17
COMPETITIVE LANDSCAPE
Uncover strategic moves and market rankings shaping the digital X-ray industry's future landscape.
166
17.1
INTRODUCTION
17.2
KEY PLAYER STRATEGY/RIGHT TO WIN
17.2.1
OVERVIEW OF STRATEGIES DEPLOYED BY KEY PLAYERS IN DIGITAL X-RAY MARKET
17.3
REVENUE ANALYSIS, 2021-2025
17.4
MARKET SHARE ANALYSIS, 2025
17.4.1
MARKET RANKING OF KEY PLAYERS, 2025
17.5
COMPANY VALUATION AND FINANCIAL METRICS
17.6
BRAND/PRODUCT COMPARISON
17.7
COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
17.7.1
STARS
17.7.2
EMERGING LEADERS
17.7.3
PERVASIVE PLAYERS
17.7.4
PARTICIPANTS
17.7.5
COMPANY FOOTPRINT: KEY PLAYERS, 2025
17.7.5.1
REGION FOOTPRINT
17.7.5.2
TECHNOLOGY FOOTPRINT
17.7.5.3
TYPE FOOTPRINT
17.7.5.4
SYSTEM TYPE FOOTPRINT
17.7.5.5
PORTABILITY FOOTPRINT
17.7.5.6
PRICE RANGE FOOTPRINT
17.7.5.7
APPLICATION FOOTPRINT
17.7.5.8
END USER FOOTPRINT
17.8
COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
17.8.1
PROGRESSIVE COMPANIES
17.8.2
RESPONSIVE COMPANIES
17.8.3
DYNAMIC COMPANIES
17.8.4
STARTING BLOCKS
17.8.5
COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
17.9
COMPETITIVE SCENARIO
17.9.1
PRODUCT LAUNCHES & APPROVALS
17.9.2
DEALS
17.9.3
EXPANSIONS
18
COMPANY PROFILES
In-depth Company Profiles of Leading Market Players with detailed Business Overview, Product and Service Portfolio, Recent Developments, and Unique Analyst Perspective (MnM View)
185
18.1
KEY PLAYERS
18.1.1
SIEMENS HEALTHINEERS
18.1.1.1
BUSINESS OVERVIEW
18.1.1.2
PRODUCTS OFFERED
18.1.1.3
RECENT DEVELOPMENTS
18.1.1.3.1
PRODUCT LAUNCHES & APPROVALS
18.1.1.3.2
DEALS
18.1.1.3.3
EXPANSIONS
18.1.1.4
MNM VIEW
18.1.1.4.1
RIGHT TO WIN
18.1.1.4.2
STRATEGIC CHOICES
18.1.1.4.3
WEAKNESSES & COMPETITIVE THREATS
18.1.2
KONINKLIJKE PHILIPS N.V.
18.1.3
GE HEALTHCARE
18.1.4
SHIMADZU CORPORATION
18.1.5
CANON MEDICAL SYSTEMS
18.1.6
CARESTREAM HEALTH
18.1.7
FUJIFILM CORPORATION
18.1.8
AGFA-GEVAERT GROUP
18.1.9
SHANGHAI UNITED IMAGING HEALTHCARE CO., LTD.
18.1.10
SAMSUNG ELECTRONIC CO., LTD.
18.1.11
ACTEON
18.1.12
SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD
18.1.13
MINXRAY, INC.
18.1.14
BPL MEDICAL TECHNOLOGIES
18.1.15
KONICA MINOLTA
18.2
OTHER PLAYERS
18.2.1
CONTROL-X MEDICAL LTD.
18.2.2
ALLENGERS MEDICAL SYSTEMS LTD.
18.2.3
OEHM UND REHBEIN GMBH
18.2.4
VISARIS
18.2.5
KUB TECHNOLOGIES
18.2.6
JPI HEALTHCARE SOLUTIONS
18.2.7
IBIS S.R.L.
18.2.8
NEW MEDICAL IMAGING CO., LTD.
18.2.9
STERNMED GMBH
18.2.10
NP JSC AMICO
19
RESEARCH METHODOLOGY
236
19.1
RESEARCH DATA
19.1.1
SECONDARY RESEARCH
19.1.1.1
KEY SECONDARY SOURCES
19.1.1.2
KEY DATA FROM SECONDARY SOURCES
19.1.2
PRIMARY RESEARCH
19.1.2.1
KEY PRIMARY SOURCES
19.1.2.2
KEY SUPPLY- AND DEMAND-SIDE PARTICIPANTS
19.1.2.3
BREAKDOWN OF PRIMARY INTERVIEWS
19.1.2.4
KEY PRIMARY INSIGHTS
19.2
MARKET SIZE ESTIMATION METHODOLOGY
19.2.1
REVENUE MAPPING-BASED MARKET ESTIMATION
19.2.2
END-USER-BASED MAPPING MARKET ESTIMATION
19.3
GROWTH FORECASTING MODEL
19.4
DATA TRIANGULATION AND MARKET BREAKDOWN
19.5
RESEARCH ASSUMPTIONS
19.6
RESEARCH LIMITATIONS
19.7
RISK ANALYSIS
20
APPENDIX
248
20.1
DISCUSSION GUIDE
20.2
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL
20.3
CUSTOMIZATION OPTIONS
20.4
RELATED REPORTS
20.5
AUTHOR DETAILS
LIST OF TABLES
TABLE 1
DIGITAL X-RAY MARKET: INCLUSIONS AND EXCLUSIONS OF STUDY
TABLE 2
DIGITAL X-RAY MARKET: PORTER’S FIVE FORCES ANALYSIS
TABLE 3
DIGITAL X-RAY MARKET: ROLE OF ECOSYSTEM
TABLE 4
AVERAGE SELLING PRICE OF DIGITAL X-RAY, BY REGION, 2023–2025
TABLE 5
IMPORT DATA FOR HS CODE 902214-COMPLIANT PRODUCTS, BY COUNTRY, 2021−2025 (USD THOUSAND)
TABLE 6
EXPORT DATA FOR HS CODE 902214-COMPLIANT PRODUCTS, BY COUNTRY, 2021−2025 (USD THOUSAND)
TABLE 7
DIGITAL X-RAY MARKET: KEY CONFERENCES AND EVENTS, 2026–2027
TABLE 8
US-ADJUSTED RECIPROCAL TARIFF RATES IN DIGITAL X-RAY INDUSTRY
TABLE 9
DIGITAL X-RAY MARKET: KEY PATENTS, 2022–2026
TABLE 10
KEY COMPANIES IMPLEMENTING AI/GEN AI IN DIGITAL X-RAY MARKET
TABLE 11
KEY APPLICATIONS AND CLINICAL OUTCOMES ENABLED BY DIGITAL X-RAY SYSTEMS
TABLE 12
NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
TABLE 13
EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
TABLE 14
ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
TABLE 15
LATIN AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
TABLE 16
MIDDLE EAST & AFRICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
TABLE 17
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS OF DIGITAL X-RAY MARKET
TABLE 18
KEY BUYING CRITERIA FOR DIGITAL X-RAY SYSTEMS
TABLE 19
DIGITAL X-RAY MARKET: UNMET NEED ANALYSIS
TABLE 20
DIGITAL X-RAY MARKET, BY PRICE RANGE, 2024–2031 (USD MILLION)
TABLE 21
AFFORDABLE/LOW-END DIGITAL X-RAY MARKET, BY REGION, 2024–2031 (USD MILLION)
TABLE 22
MID-RANGE DIGITAL X-RAY MARKET, BY REGION, 2024–2031 (USD MILLION)
TABLE 23
PREMIUM/HIGH-END DIGITAL X-RAY MARKET, BY REGION, 2024–2031 (USD MILLION)
TABLE 24
DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 25
DIGITAL X-RAY MARKET FOR DIRECT RADIOGRAPHY, BY REGION, 2024–2031 (USD MILLION)
TABLE 26
DIGITAL X-RAY MARKET FOR COMPUTED RADIOGRAPHY, BY REGION, 2024–2031 (USD MILLION)
TABLE 27
DIGITAL X-RAY MARKET, BY SYSTEM TYPE, 2024–2031 (USD MILLION)
TABLE 28
RETROFIT DIGITAL X-RAY MARKET, BY REGION, 2024–2031 (USD MILLION)
TABLE 29
NEW DIGITAL X-RAY MARKET, BY REGION, 2024–2031 (USD MILLION)
TABLE 30
DIGITAL X-RAY MARKET, BY PORTABILITY, 2024–2031 (USD MILLION)
TABLE 31
FIXED DIGITAL X-RAY MARKET, BY TYPE, 2024–2031 (USD MILLION)
TABLE 32
FIXED DIGITAL X-RAY MARKET, BY REGION, 2024–2031 (USD MILLION)
TABLE 33
FLOOR-TO-CEILING-MOUNTED X-RAY SYSTEMS MARKET, BY REGION, 2024–2031 (USD MILLION)
TABLE 34
CEILING-MOUNTED X-RAY SYSTEMS MARKET, BY REGION, 2024–2031 (USD MILLION)
TABLE 35
PORTABLE DIGITAL X-RAY MARKET, BY TYPE, 2024–2031 (USD MILLION)
TABLE 36
PORTABLE DIGITAL X-RAY MARKET, BY REGION, 2024–2031 (USD MILLION)
TABLE 37
MOBILE X-RAY SYSTEMS MARKET, BY REGION, 2024–2031 (USD MILLION)
TABLE 38
HANDHELD X-RAY SYSTEMS MARKET, BY REGION, 2024–2031 (USD MILLION)
TABLE 39
DIGITAL X-RAY MARKET, BY TYPE, 2024–2031 (USD MILLION)
TABLE 40
ANALOG X-RAY MARKET, BY REGION, 2024–2031 (USD MILLION)
TABLE 41
DIGITAL X-RAY MARKET, BY REGION, 2024–2031 (USD MILLION)
TABLE 42
DIGITAL X-RAY MARKET, BY APPLICATION, 2024–2031 (USD MILLION)
TABLE 43
DIGITAL X-RAY MARKET FOR CHEST IMAGING, BY REGION, 2024–2031 (USD MILLION)
TABLE 44
DIGITAL X-RAY MARKET FOR ORTHOPEDICS, BY REGION, 2024–2031 (USD MILLION)
TABLE 45
DIGITAL X-RAY MARKET FOR CARDIOVASCULAR IMAGING, BY REGION, 2024–2031 (USD MILLION)
TABLE 46
DIGITAL X-RAY MARKET FOR DENTAL APPLICATIONS, BY REGION, 2024–2031 (USD MILLION)
TABLE 47
DIGITAL X-RAY MARKET FOR PEDIATRIC IMAGING, BY REGION, 2024–2031 (USD MILLION)
TABLE 48
DIGITAL X-RAY MARKET FOR CANCER DIAGNOSIS & TREATMENT, BY REGION, 2024–2031 (USD MILLION)
TABLE 49
DIGITAL X-RAY MARKET FOR OTHER APPLICATIONS, BY REGION, 2024–2031 (USD MILLION)
TABLE 50
DIGITAL X-RAY MARKET, BY END USER, 2024–2031 (USD MILLION)
TABLE 51
DIGITAL X-RAY MARKET FOR HOSPITALS, BY REGION, 2024–2031 (USD MILLION)
TABLE 52
DIGITAL X-RAY MARKET FOR DIAGNOSTIC CENTERS, BY REGION, 2024–2031 (USD MILLION)
TABLE 53
DIGITAL X-RAY MARKET FOR DENTAL CARE CENTERS, BY REGION, 2024–2031 (USD MILLION)
TABLE 54
DIGITAL X-RAY MARKET, BY REGION, 2024–2031 (USD MILLION)
TABLE 55
NORTH AMERICA: DIGITAL X-RAY MARKET, BY COUNTRY, 2024–2031 (USD MILLION)
TABLE 56
NORTH AMERICA: DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 57
NORTH AMERICA: DIGITAL X-RAY MARKET, BY SYSTEM TYPE, 2024–2031 (USD MILLION)
TABLE 58
NORTH AMERICA: DIGITAL X-RAY MARKET, BY PORTABILITY, 2024–2031 (USD MILLION)
TABLE 59
NORTH AMERICA: FIXED DIGITAL X-RAY MARKET, BY TYPE, 2024–2031 (USD MILLION)
TABLE 60
NORTH AMERICA: PORTABLE DIGITAL X-RAY MARKET, BY TYPE, 2024–2031 (USD MILLION)
TABLE 61
NORTH AMERICA: PORTABLE DIGITAL X-RAY MARKET, BY PRICE RANGE, 2024–2031 (USD MILLION)
TABLE 62
NORTH AMERICA: DIGITAL X-RAY MARKET, BY APPLICATION, 2024–2031 (USD MILLION)
TABLE 63
NORTH AMERICA: DIGITAL X-RAY MARKET, BY END USER, 2024–2031 (USD MILLION)
TABLE 64
US: DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 65
CANADA: DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 66
EUROPE: DIGITAL X-RAY MARKET, BY COUNTRY, 2024–2031 (USD MILLION)
TABLE 67
EUROPE: DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 68
EUROPE: DIGITAL X-RAY MARKET, BY SYSTEM TYPE, 2024–2031 (USD MILLION)
TABLE 69
EUROPE: DIGITAL X-RAY MARKET, BY PORTABILITY, 2024–2031 (USD MILLION)
TABLE 70
EUROPE: FIXED DIGITAL X-RAY MARKET, BY TYPE, 2024–2031 (USD MILLION)
TABLE 71
EUROPE: PORTABLE DIGITAL X-RAY MARKET, BY TYPE, 2024–2031 (USD MILLION)
TABLE 72
EUROPE: PORTABLE DIGITAL X-RAY MARKET, BY PRICE RANGE, 2024–2031 (USD MILLION)
TABLE 73
EUROPE: DIGITAL X-RAY MARKET, BY APPLICATION, 2024–2031 (USD MILLION)
TABLE 74
EUROPE: DIGITAL X-RAY MARKET, BY END USER, 2024–2031 (USD MILLION)
TABLE 75
GERMANY: DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 76
UK: DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 77
FRANCE: DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 78
ITALY: DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 79
SPAIN: DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 80
REST OF EUROPE: DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 81
ASIA PACIFIC: DIGITAL X-RAY MARKET, BY COUNTRY, 2024–2031 (USD MILLION)
TABLE 82
ASIA PACIFIC: DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 83
ASIA PACIFIC: DIGITAL X-RAY MARKET, BY SYSTEM TYPE, 2024–2031 (USD MILLION)
TABLE 84
ASIA PACIFIC: DIGITAL X-RAY MARKET, BY PORTABILITY, 2024–2031 (USD MILLION)
TABLE 85
ASIA PACIFIC: FIXED DIGITAL X-RAY MARKET, BY TYPE, 2024–2031 (USD MILLION)
TABLE 86
ASIA PACIFIC: PORTABLE DIGITAL X-RAY MARKET, BY TYPE, 2024–2031 (USD MILLION)
TABLE 87
ASIA PACIFIC: PORTABLE DIGITAL X-RAY MARKET, BY PRICE RANGE, 2024–2031 (USD MILLION)
TABLE 88
ASIA PACIFIC: DIGITAL X-RAY MARKET, BY APPLICATION, 2024–2031 (USD MILLION)
TABLE 89
ASIA PACIFIC: DIGITAL X-RAY MARKET, BY END USER, 2024–2031 (USD MILLION)
TABLE 90
CHINA: DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 91
JAPAN: DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 92
INDIA: DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 93
AUSTRALIA: DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 94
SOUTH KOREA: DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 95
REST OF ASIA PACIFIC: DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 96
LATIN AMERICA: DIGITAL X-RAY MARKET, BY COUNTRY, 2024–2031 (USD MILLION)
TABLE 97
LATIN AMERICA: DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 98
LATIN AMERICA: DIGITAL X-RAY MARKET, BY SYSTEM TYPE, 2024–2031 (USD MILLION)
TABLE 99
LATIN AMERICA: DIGITAL X-RAY MARKET, BY PORTABILITY, 2024–2031 (USD MILLION)
TABLE 100
LATIN AMERICA: FIXED DIGITAL X-RAY MARKET, BY TYPE, 2024–2031 (USD MILLION)
TABLE 101
LATIN AMERICA: PORTABLE DIGITAL X-RAY MARKET, BY TYPE, 2024–2031 (USD MILLION)
TABLE 102
LATIN AMERICA: PORTABLE DIGITAL X-RAY MARKET, BY PRICE RANGE, 2024–2031 (USD MILLION)
TABLE 103
LATIN AMERICA: DIGITAL X-RAY MARKET, BY APPLICATION, 2024–2031 (USD MILLION)
TABLE 104
LATIN AMERICA: DIGITAL X-RAY MARKET, BY END USER, 2024–2031 (USD MILLION)
TABLE 105
BRAZIL: DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 106
MEXICO: DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 107
REST OF LATIN AMERICA: DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 108
MIDDLE EAST & AFRICA: DIGITAL X-RAY MARKET, BY COUNTRY, 2024–2031 (USD MILLION)
TABLE 109
MIDDLE EAST & AFRICA: DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 110
MIDDLE EAST & AFRICA: DIGITAL X-RAY MARKET, BY SYSTEM TYPE, 2024–2031 (USD MILLION)
TABLE 111
MIDDLE EAST & AFRICA: DIGITAL X-RAY MARKET, BY PORTABILITY, 2024–2031 (USD MILLION)
TABLE 112
MIDDLE EAST & AFRICA: FIXED DIGITAL X-RAY MARKET, BY TYPE, 2024–2031 (USD MILLION)
TABLE 113
MIDDLE EAST & AFRICA: PORTABLE DIGITAL X-RAY MARKET, BY TYPE, 2024–2031 (USD MILLION)
TABLE 114
MIDDLE EAST & AFRICA: PORTABLE DIGITAL X-RAY MARKET, BY PRICE RANGE, 2024–2031 (USD MILLION)
TABLE 115
MIDDLE EAST & AFRICA: DIGITAL X-RAY MARKET, BY APPLICATION, 2024–2031 (USD MILLION)
TABLE 116
MIDDLE EAST & AFRICA: DIGITAL X-RAY MARKET, BY END USER, 2024–2031 (USD MILLION)
TABLE 117
GCC COUNTRIES: DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 118
REST OF MIDDLE EAST & AFRICA: DIGITAL X-RAY MARKET, BY TECHNOLOGY, 2024–2031 (USD MILLION)
TABLE 119
OVERVIEW OF STRATEGIES DEPLOYED BY KEY PLAYERS IN DIGITAL X-RAY MARKET, 2023–2026
TABLE 120
DIGITAL X-RAY MARKET: DEGREE OF COMPETITION
TABLE 121
DIGITAL X-RAY MARKET: REGION FOOTPRINT
TABLE 122
DIGITAL X-RAY MARKET: TECHNOLOGY FOOTPRINT
TABLE 123
DIGITAL X-RAY MARKET: TYPE FOOTPRINT
TABLE 124
DIGITAL X-RAY MARKET: SYSTEM TYPE FOOTPRINT
TABLE 125
DIGITAL X-RAY MARKET: PORTABILITY FOOTPRINT
TABLE 126
DIGITAL X-RAY MARKET: PRICE RANGE FOOTPRINT
TABLE 127
DIGITAL X-RAY MARKET: APPLICATION FOOTPRINT
TABLE 128
DIGITAL X-RAY MARKET: END USER FOOTPRINT
TABLE 129
DIGITAL X-RAY MARKET: DETAILED LIST OF STARTUPS/SMES
TABLE 130
DIGITAL X-RAY MARKET: REGIONAL FOOTPRINT OF STARTUPS/SMES
TABLE 131
DIGITAL X-RAY MARKET: PORTABILITY FOOTPRINT OF STARTUPS/SMES
TABLE 132
DIGITAL X-RAY MARKET: PRODUCT LAUNCHES & APPROVALS, JANUARY 2023–JULY 2026
TABLE 133
DIGITAL X-RAY MARKET: DEALS, JANUARY 2023–JULY 2026
TABLE 134
DIGITAL X-RAY MARKET: EXPANSIONS, JANUARY 2023–JULY 2026
TABLE 135
SIEMENS HEALTHINEERS: COMPANY OVERVIEW
TABLE 136
SIEMENS HEALTHINEERS: PRODUCTS OFFERED
TABLE 137
SIEMENS HEALTHINEERS: PRODUCT LAUNCHES & APPROVALS
TABLE 138
SIEMENS HEALTHINEERS: DEALS
TABLE 139
SIEMENS HEALTHINEERS: EXPANSIONS
TABLE 140
KONINKLIJKE PHILIPS N.V.: COMPANY OVERVIEW
TABLE 141
KONINKLIJKE PHILIPS N.V.: PRODUCTS OFFERED
TABLE 142
KONINKLIJKE PHILIPS N.V.: PRODUCT LAUNCHES & APPROVALS
TABLE 143
KONINKLIJKE PHILIPS N.V.: DEALS
TABLE 144
KONINKLIJKE PHILIPS N.V.: EXPANSIONS
TABLE 145
GE HEALTHCARE: COMPANY OVERVIEW
TABLE 146
GE HEALTHCARE: PRODUCTS OFFERED
TABLE 147
GE HEALTHCARE: PRODUCT LAUNCHES & APPROVALS
TABLE 148
GE HEALTHCARE: DEALS
TABLE 149
GE HEALTHCARE: EXPANSIONS
TABLE 150
SHIMADZU CORPORATION: COMPANY OVERVIEW
TABLE 151
SHIMADZU CORPORATION: PRODUCTS OFFERED
TABLE 152
SHIMADZU CORPORATION: PRODUCT LAUNCHES
TABLE 153
SHIMADZU CORPORATION: DEALS
TABLE 154
CANON MEDICAL SYSTEMS: COMPANY OVERVIEW
TABLE 155
CANON MEDICAL SYSTEMS: PRODUCTS OFFERED
TABLE 156
CANON MEDICAL SYSTEMS: PRODUCT LAUNCHES & APPROVALS
TABLE 157
CARESTREAM HEALTH : COMPANY OVERVIEW
TABLE 158
CARESTREAM HEALTH: PRODUCTS OFFERED
TABLE 159
CARESTREAM HEALTH: PRODUCT LAUNCHES
TABLE 160
CARESTREAM HEALTH: DEALS
TABLE 161
FUJIFILM CORPORATION: COMPANY OVERVIEW
TABLE 162
FUJIFILM CORPORATION: PRODUCTS OFFERED
TABLE 163
FUJIFILM CORPORATION: PRODUCT LAUNCHES & APPROVALS
TABLE 164
AGFA-GEVAERT GROUP: COMPANY OVERVIEW
TABLE 165
AGFA-GEVAERT GROUP: PRODUCTS OFFERED
TABLE 166
SHANGHAI UNITED IMAGING HEALTHCARE CO., LTD.: COMPANY OVERVIEW
TABLE 167
SHANGHAI UNITED IMAGING HEALTHCARE CO., LTD.: PRODUCTS OFFERED
TABLE 168
SHANGHAI UNITED IMAGING HEALTHCARE CO., LTD.: DEALS, JANUARY 2023–MAY 2026
TABLE 169
SHANGHAI UNITED IMAGING HEALTHCARE CO., LTD.: EXPANSIONS
TABLE 170
SAMSUNG ELECTRONICS CO., LTD.: COMPANY OVERVIEW
TABLE 171
SAMSUNG ELECTRONICS CO., LTD.: PRODUCTS OFFERED
TABLE 172
SAMSUNG ELECTRONICS CO., LTD.: DEALS, JANUARY 2023–MAY 2026
TABLE 173
ACTEON: COMPANY OVERVIEW
TABLE 174
ACTEON : PRODUCTS OFFERED
TABLE 175
TIME MEDICAL HOLDING: PRODUCT LAUNCHES & APPROVALS, JANUARY 2023–MAY 2026
TABLE 176
TIME MEDICAL HOLDING: EXPANSIONS, JANUARY 2023–MAY 2026
TABLE 177
SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD.: COMPANY OVERVIEW
TABLE 178
SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD.: PRODUCTS OFFERED
TABLE 179
MINXRAY, INC.: COMPANY OVERVIEW
TABLE 180
MINXRAY, INC.: PRODUCTS OFFERED
TABLE 181
BPL MEDICAL TECHNOLOGIES: COMPANY OVERVIEW
TABLE 182
BPL MEDICAL TECHNOLOGIES: PRODUCTS OFFERED
TABLE 183
KONICA MINOLTA: COMPANY OVERVIEW
TABLE 184
KONICA MINOLTA : PRODUCTS OFFERED
TABLE 185
CONTROL-X MEDICAL LTD. : COMPANY OVERVIEW
TABLE 186
ALLENGERS MEDICAL SYSTEMS LTD: COMPANY OVERVIEW
TABLE 187
OEHM UND REHBEIN GMBH: COMPANY OVERVIEW
TABLE 188
VISARIS: COMPANY OVERVIEW
TABLE 189
KUB TECHNOLOGIES: COMPANY OVERVIEW
TABLE 190
JPI HEALTHCARE SOLUTIONS: COMPANY OVERVIEW
TABLE 191
IBIS S.R.L.: COMPANY OVERVIEW
TABLE 192
NEW MEDICAL IMAGING CO., LTD.: COMPANY OVERVIEW
TABLE 193
STERNMED GMBH: COMPANY OVERVIEW
TABLE 194
NP JSC AMICO: COMPANY OVERVIEW
TABLE 195
DIGITAL X-RAY MARKET: RISK ANALYSIS
LIST OF FIGURES
FIGURE 1
DIGITAL X-RAY MARKET SEGMENTATION AND REGIONAL SCOPE
FIGURE 2
DIGITAL X-RAY MARKET: YEARS CONSIDERED
FIGURE 3
MARKET SCENARIO
FIGURE 4
GLOBAL DIGITAL X-RAY MARKET, 2024–2031
FIGURE 5
MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN DIGITAL X-RAY MARKET, 2023–2025
FIGURE 6
DISRUPTIONS INFLUENCING GROWTH OF DIGITAL X-RAY MARKET
FIGURE 7
HIGH-GROWTH SEGMENTS IN DIGITAL X-RAY MARKET, 2026–2031
FIGURE 8
ASIA PACIFIC TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD
FIGURE 9
INCREASED DEMAND FOR PREVENTIVE DIAGNOSTIC X-RAY SCANS TO GROW MARKET
FIGURE 10
DIRECT RADIOGRAPHY SEGMENT ACCOUNTED FOR LARGEST MARKET SHARE IN 2025
FIGURE 11
CHINA TO REGISTER HIGHEST CAGR FROM 2026 TO 2031
FIGURE 12
DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES IN DIGITAL X-RAY MARKET
FIGURE 13
DIGITAL X-RAY MARKET: PORTER’S FIVE FORCES ANALYSIS
FIGURE 14
DIGITAL X-RAY MARKET: VALUE CHAIN ANALYSIS
FIGURE 15
DIGITAL X-RAY MARKET: ECOSYSTEM ANALYSIS
FIGURE 16
AVERAGE SELLING PRICE TREND OF DIGITAL X-RAY SYSTEMS, BY PORTABILITY, 2023–2025 (USD)
FIGURE 17
AVERAGE SELLING PRICE TREND OF DIGITAL X-RAY SYSTEMS, BY REGION, 2023–2025 (USD)
FIGURE 18
IMPORT DATA FOR HS CODE 902214-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025
FIGURE 19
EXPORT DATA FOR HS CODE 902214-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025
FIGURE 20
TRENDS/DISRUPTIONS INFLUENCING CUSTOMER BUSINESS
FIGURE 21
DIGITAL X-RAY MARKET: INVESTMENT & FUNDING SCENARIO
FIGURE 22
DIGITAL X-RAY MARKET: NUMBER OF INVESTOR DEALS, BY KEY PLAYER, 2019–2023 (USD MILLION)
FIGURE 23
VALUE OF INVESTOR DEALS IN DIGITAL X-RAY MARKET, BY KEY PLAYER, 2021–2025 (USD MILLION)
FIGURE 24
PATENTS APPLIED AND GRANTED, 2016–2026
FIGURE 25
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR DIGITAL X-RAY SYSTEMS
FIGURE 26
KEY BUYING CRITERIA FOR DIGITAL X-RAY
FIGURE 27
NORTH AMERICA: DIGITAL X-RAY MARKET SNAPSHOT
FIGURE 28
ASIA PACIFIC: DIGITAL X-RAY MARKET SNAPSHOT
FIGURE 29
REVENUE ANALYSIS OF KEY PLAYERS IN DIGITAL X-RAY MARKET, 2021–2025 (USD MILLION)
FIGURE 30
MARKET SHARE ANALYSIS OF KEY PLAYERS (2025)
FIGURE 31
RANKING OF KEY PLAYERS IN DIGITAL X-RAY MARKET, 2025
FIGURE 32
EV/EBITDA OF KEY VENDORS
FIGURE 33
FIVE-YEAR STOCK BETA OF KEY VENDORS
FIGURE 34
DIGITAL X-RAY MARKET: BRAND/PRODUCT COMPARISON (2025)
FIGURE 35
DIGITAL X-RAY MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
FIGURE 36
DIGITAL X-RAY MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
FIGURE 37
SIEMENS HEALTHINEERS: COMPANY SNAPSHOT (2025)
FIGURE 38
KONINKLIJKE PHILIPS N.V.: COMPANY SNAPSHOT (2025)
FIGURE 39
GE HEALTHCARE: COMPANY SNAPSHOT (2025)
FIGURE 40
SHIMADZU CORPORATION: COMPANY SNAPSHOT (2025)
FIGURE 41
CANON MEDICAL SYSTEMS: COMPANY SNAPSHOT (2025)
FIGURE 42
FUJIFILM CORPORATION: COMPANY SNAPSHOT (2025)
FIGURE 43
AGFA-GEVAERT GROUP: COMPANY SNAPSHOT (2025)
FIGURE 44
SHANGHAI UNITED IMAGING HEALTHCARE CO., LTD.: COMPANY SNAPSHOT (2025)
FIGURE 45
SAMSUNG ELECTRONICS CO., LTD.: COMPANY SNAPSHOT (2025)
FIGURE 46
SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD.: COMPANY SNAPSHOT (2025)
FIGURE 47
KONICA MINOLTA: COMPANY SNAPSHOT (2025)
FIGURE 48
DIGITAL X-RAY MARKET: RESEARCH DATA
FIGURE 49
DIGITAL X-RAY MARKET: RESEARCH DESIGN
FIGURE 50
DIGITAL X-RAY MARKET: KEY SECONDARY SOURCES
FIGURE 51
DIGITAL X-RAY MARKET: KEY DATA FROM SECONDARY SOURCES
FIGURE 52
DIGITAL X-RAY MARKET: KEY PRIMARY SOURCES (DEMAND AND SUPPLY SIDES)
FIGURE 53
DIGITAL X-RAY MARKET: KEY SUPPLY- AND DEMAND-SIDE PARTICIPANTS
FIGURE 54
BREAKDOWN OF PRIMARY INTERVIEWS: BY COMPANY TYPE, DESIGNATION, AND REGION
FIGURE 55
DIGITAL X-RAY MARKET: KEY INSIGHTS FROM PRIMARY EXPERTS
FIGURE 56
RESEARCH METHODOLOGY: HYPOTHESIS BUILDING
FIGURE 57
DIGITAL X-RAY MARKET: COMPANY REVENUE ESTIMATION, 2025
FIGURE 58
DIGITAL X-RAY MARKET: MARKET SIZE ESTIMATION METHODOLOGY
FIGURE 59
DIGITAL X-RAY MARKET: GROWTH PROJECTIONS BASED ON REVENUE IMPACT OF KEY MACRO INDICATORS
FIGURE 60
DATA TRIANGULATION
Methodology
The study involved four major activities in estimating the current size of the global digital X-ray market. Exhaustive secondary research was done to collect information on the market, peer, and parent markets. The next step was to validate these findings, assumptions, and sizing with industry experts across the value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the complete market size. After that, market breakdown and data triangulation were used to estimate the market size of segments and subsegments.
Secondary Research
The secondary research process involves the widespread use of secondary sources, directories, databases (such as Bloomberg Businessweek, Factiva, and D&B Hoovers), white papers, annual reports, company house documents, investor presentations, and SEC filings of companies. Secondary research was used to identify and collect information useful for the extensive, technical, market-oriented, and commercial digital X-ray market study. It was also used to obtain important information about the key players and market classification & segmentation according to industry trends to the bottom-most level, and key developments related to market and technology perspectives. A database of the key industry leaders was also prepared using secondary research.
Primary Research
In the primary research process, various supply and demand sources were interviewed to obtain qualitative and quantitative information for this report. The primary sources from the supply side include industry experts such as CEOs, vice presidents, marketing and sales directors, technology & innovation directors, and related key executives from various key companies and organizations in the digital X-ray market. The primary sources from the demand side include hospitals, orthopedic clinics, diagnostic centers, dental clinics and other end users. Primary research was conducted to validate the market segmentation, identify key players, and gather insights on key industry trends & key market dynamics.
A breakdown of the primary respondents is provided below:
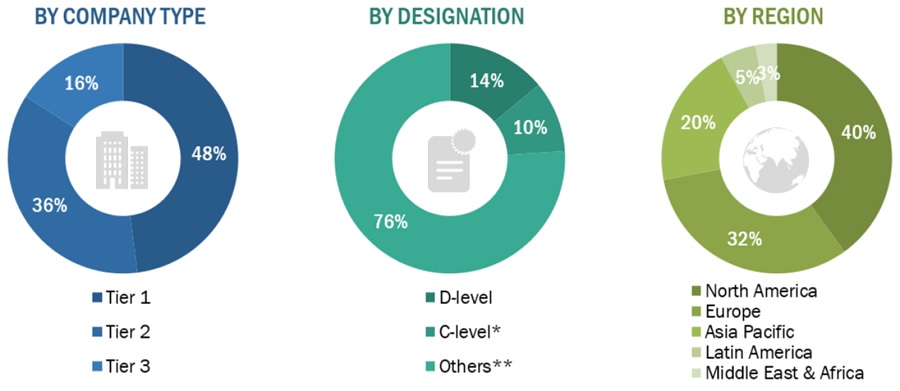
*Others include sales managers, marketing managers, business development managers, product managers, distributors, and suppliers.
The tiers of the companies are defined based on their total revenue. As of 2023: Tier 1 => USD 1 billion, Tier 2 = USD 500 million to USD 1 billion, and Tier 3 =< USD 500 million
To know about the assumptions considered for the study, download the pdf brochure
Market Estimation Methodology
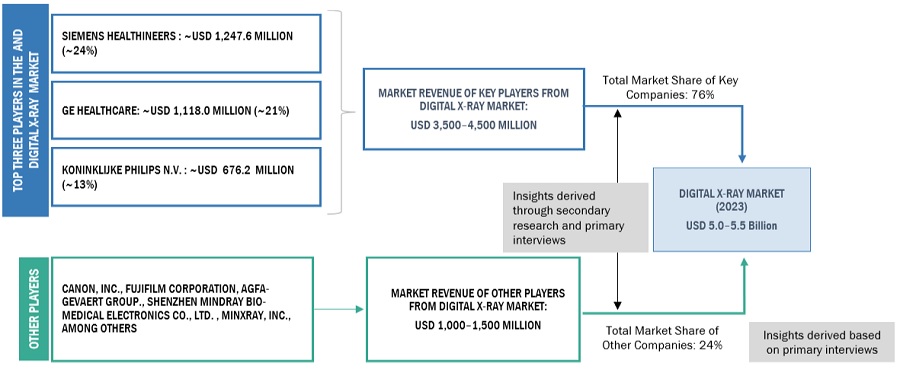
In this report, the digital X-ray market’s size was determined using the revenue share analysis of leading players. For this purpose, key players in the market were identified, and their revenues from the market business were determined through various insights gathered during the primary and secondary research phases. Secondary research included the study of the annual and financial reports of the top market players. In contrast, primary research included extensive interviews with key opinion leaders, such as CEOs, directors, and key marketing executives.
Segmental revenues were calculated based on the revenue mapping of major solution/service providers to calculate the global market value. This process involved the following steps:
- Generating a list of major global players operating in the digital X-ray market.
- Mapping annual revenues generated by major global players from the product segment (or nearest reported business unit/product category)
- Revenue mapping of major players to cover a major share of the global market share, as of 2023
- Extrapolating the global value of the digital X-ray market industry
Bottom-up approach
In this report, the size of the global digital X-ray market was determined using the revenue share analysis of leading players. For this purpose, key players in the market were identified, and their revenues from the digital X-ray business were determined through various insights gathered during the primary and secondary research phases. Secondary research included the study of the annual and financial reports of the top market players. In contrast, primary research included extensive interviews with key opinion leaders, such as CEOs, directors, and marketing executives.
Approach 1: Company revenue estimation approach
Segmental revenues were calculated based on the revenue mapping of major solution/product providers to calculate the global market value. This process involved the following steps:
- Generating a list of major global players operating in the digital X-ray market
- Mapping the annual revenues generated by major global players from the digital X-ray segment (or the nearest reported business unit/product category)
- Mapping the revenues of major players to cover at least 80–85% of the global market share as of 2022
- Extrapolating the global value of the digital X-ray industry
Market Size Estimation For Digital X-Ray: Approach 1 (Company Revenue Estimation)I
To know about the assumptions considered for the study, Request for Free Sample Report
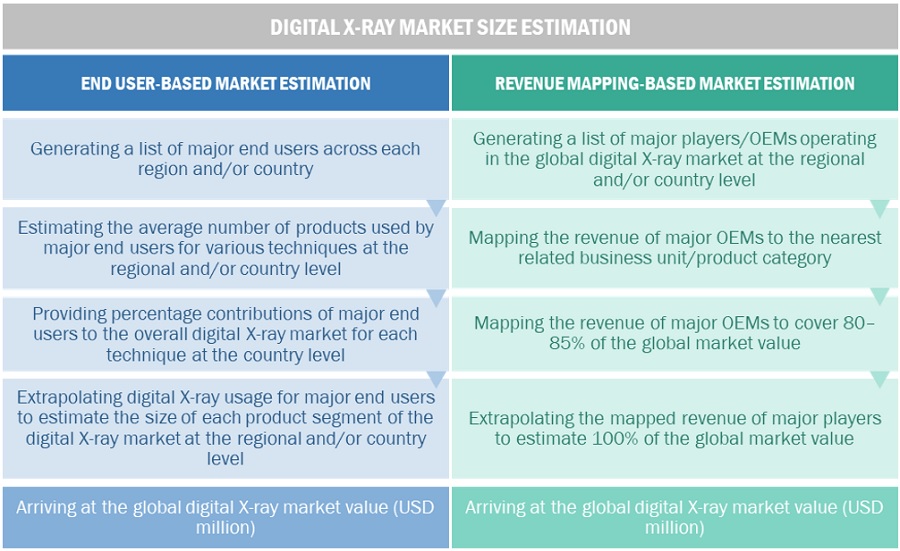
Approach 2: Customer-based market estimation
During preliminary secondary research, the total sales revenue of digital X-ray was estimated and validated at the regional and country level, triangulated, and validated to estimate the global market value. This process involved the following steps:
- Generating a list of major customer facilities across each region and country
- Identifying the average number of digital X-ray product supplies used by major customer facilities across each product type at the regional/country level, annually
- Identifying the percentage contribution of major customer facilities to the overall digital X-ray expenditure and usage at the regional/country level, annually
- Extrapolating the annual usage patterns for various products across major customer facilities to estimate the size of each product segment at the regional/country level, annually
- Identifying the percentage contributions of individual market segments and subsegments to the overall digital X-ray market at the regional/country level
Digital X-Ray Market Size Estimation: Bottom-Up Approach
Source: MarketsandMarkets Analysis
Data Triangulation
After arriving at the overall market size from the market size estimation process explained above, the global digital X-ray market was split into segments and subsegments. Data triangulation and market breakdown procedures were employed to complete the overall market engineering process and arrive at the exact statistics for all segments and subsegments. The data was triangulated by studying various factors and trends from both the demand and supply sides. Additionally, the digital X-ray market was validated using top-down and bottom-up approaches.
Market Definition
The digital X-ray market encompasses a diverse range of medical devices designed to provide external support, stabilization, and relief for musculoskeletal conditions. These products include braces, supports, and orthoses tailored for various anatomical areas such as the knee, ankle, spine, wrist, and shoulder. The market addresses the growing demand for solutions related to orthopedic injuries, post-surgical recovery, and chronic musculoskeletal disorders, driven by factors such as an aging population, increased awareness of preventive healthcare, and advancements in materials and technology. With a focus on enhancing patient comfort and mobility, the digital X-ray market plays a crucial role in promoting non-invasive treatment options and comprehensive musculoskeletal care within healthcare settings.
Key Stakeholders
- Digital X-ray product manufacturers
- Original equipment manufacturers (OEMs)
- Suppliers, distributors, and channel partners
- Healthcare service providers
- Hospitals and academic medical centers
- Radiologists
- Research laboratories
- Health insurance providers
- Government bodies/organizations
- Regulatory bodies
- Medical research institutes
- Business research and consulting service providers
- Venture capitalists and other public-private funding agencies
- Market research and consulting firms
Objectives of the Study
- To define, describe, and forecast the digital X-ray market based on technology, systems, portability, price range, type, application, end user, and region
- To provide detailed information regarding the major factors influencing the growth of the market (drivers, restraints, opportunities, and challenges)
- To strategically analyze micro markets with respect to individual growth trends, prospects, and contributions to the total market
- To analyze opportunities in the market for stakeholders and provide details of the competitive landscape for market leaders
- To forecast the revenue of the market segments with respect to five regions, namely, North America, Europe, the Asia Pacific, Latin America, Middle East and Africa
- To profile the key players and comprehensively analyze their market ranking and core competencies
- To benchmark players within the market using a proprietary competitive leadership mapping framework, which analyzes market players on various parameters within the broad categories of market share and product footprint
Available Customizations
With the given market data, MarketsandMarkets offers customizations per the company’s specific needs. The following customization options are available for the present global digital X-ray market report:
Product Analysis
- Product matrix, which gives a detailed comparison of the product portfolios of the top five companies
Company Information
- Detailed analysis and profiling of additional market players (up to five)
Geographic Analysis
- Further breakdown of the Rest of Europe digital X-ray market into Russia, Belgium, the Netherlands, Switzerland, Austria, Finland, Sweden, Poland, and Portugal, among others
- Further breakdown of the Rest of Asia Pacific digital X-ray market into Singapore, Taiwan, New Zealand, Philippines, Malaysia, and other APAC countries
- Further breakdown of the Rest of Latin America (RoLATAM), which comprises Argentina, Chile, Peru, Colombia, and Cuba
- Further breakdown of the RoW market into Latin America and MEA regions
Fact checked
Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the Digital X-ray Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Custom Market Research Services
We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements
Get 10% Free CustomisationTESTIMONIALS
JAYANT RAJPUROHIT
Director of Market Insights, Data and Analytics
SFI Health,
Leading Pharmaceutical Companywww.sfihealth.com/
We at SFI Health approached MarketsandMarkets for an Opportunity Assessment on "Incidence and Prevalence of Focus Indications" as we wanted to know the most attractive HCPs like Physician, Functional MD, Naturopath and Pharmacist. The project was critical for us to ensure our focus on the right target which would enable sustainable growth and profitability for SFI Health. The business insights provided exceeded our expectations and we were extremely impressed. The team at MarketsandMarkets is highly professional and detail oriented and very well understood our business needs. MarketsandMarkets offers a unique combination of expertise and dedicated engagement model. We identified 2 new products to be launched in coming months, based on the research findings provided by MarketsandMarkets. We are happy with the services and would strongly recommend MarketsandMarkets to my peers in the industry.
BEATRIZ DE LA CALLE
Head of Commercial Analytics
Qualicaps,
Leading Pharmaceutical Companywww.qualicaps.com/
We partnered with MarketsandMarkets for an assessment study on hard empty capsules. The team was extremely professional in understanding our business requirements and we received timely responses to all our queries. The market intelligence and the recommendations has met our business requirements. We were extremely impressed to see the final study results; it really exceeded our expectations. The market intelligence offered by MarketsandMarkets, and clarity on next steps will help us achieve our business objective for the Year 2021. We are happy with the services and would strongly recommend MarketsandMarkets to my peers in the industry.

Bob Williams,
Senior Director Business Development & Innovation
Bracco Diagnostics Inc.,
Italian Multinational in life sciences sector and a World Leader in imaging diagnosticsimaging.bracco.com/us-en
We were pleased with targeted insights that MarketsandMarkets identified from a custom study on the 'Radiation Dose Management Solutions Market'. Your team identified and characterized the market participants as well as underlying trends accurately. This study was useful to Bracco in formulating business strategies for our dose monitoring product lines and we thank MarketsandMarkets for the job well done.
Cody Coonradt,
Market Development and Strategy Manager
3M Health Information Systems,
Leader in Health care Coding, Payment & Analytics Solutions.www.3m.com/3M/en_US/health-information-systems-us
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarketsandMarkets, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer.
Their customer first approach and high value engagement model, have given us great analysis and excellent value for money
- Canada Digital X-ray Market
- US Digital X-ray Market
- France Digital X-ray Market
- Germany Digital X-ray Market
- Italy Digital X-ray Market
- UK Digital X-ray Market
- Spain Digital X-ray Market
- China Digital X-ray Market
- Japan Digital X-ray Market
- India Digital X-ray Market
- Australia Digital X-ray Market
- South Korea Digital X-ray Market
- Brazil Digital X-ray Market
- Mexico Digital X-ray Market
Growth opportunities and latent adjacency in Digital X-ray Market





Richard
Jun, 2026
After reviewing the Digital X-ray market report, I found the breakdown of detector technologies and adoption trends across hospitals and diagnostic centers especially useful for evaluating future imaging infrastructure investments..
Joseph
Jun, 2026
I went through the Digital X-ray analysis to better understand how AI-enabled imaging workflows and portable systems are reshaping radiology efficiency in both developed and emerging healthcare markets..
Thomas
Jun, 2026
The report gave me a clearer perspective on competitive positioning, reimbursement dynamics, and demand growth drivers influencing long-term opportunities within the Digital X-ray industry..