Drone Composites Market

Drone Composites Market by Composite Type (CFRP, GFRP, Other Composites), Manufacturing Process, Platform Type (Fixed, Rotary, VTOL/Hybrid), Component, Application (Military & Defense, Civil & Commercial, Consumer), and Region - Global Forecast to 2031


OVERVIEW
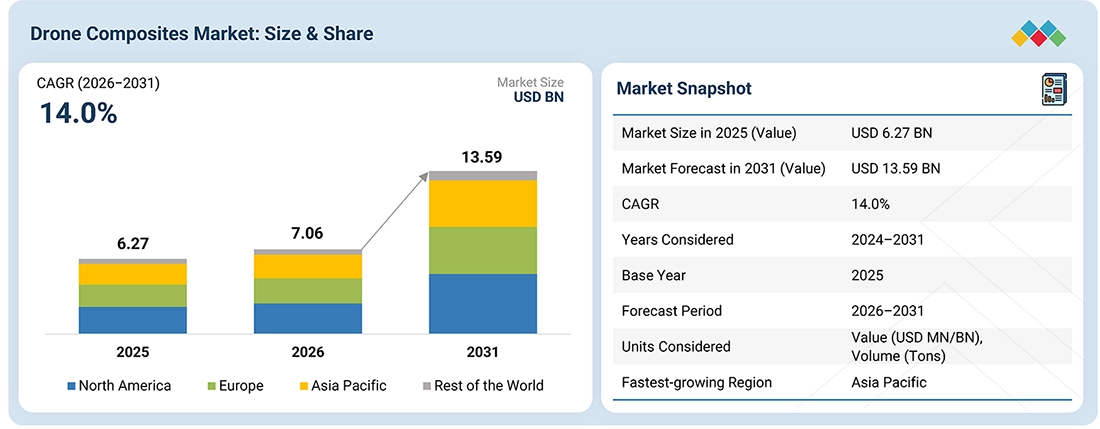
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
The drone composites market is expected to reach USD 13.59 billion by 2031 from USD 7.06 billion in 2026, at a CAGR of 14.0%. Market growth is supported by rising demand for lightweight composite structures across military & defense, civil & commercial, and consumer drone applications. The need to improve flight endurance, payload capacity, structural strength, and aerodynamic efficiency is encouraging the adoption of CFRP, GFRP, and other advanced composites. Key growth drivers include increasing procurement of military UAVs, expanding commercial drone use in agriculture, surveying, infrastructure inspection, and logistics, and the development of fixed-wing, rotary-wing, and VTOL/hybrid platforms. Key technology trends include advanced resin systems, thermoplastic composites, automated fiber placement (AFP), automated tape laying (ATL), and resin transfer molding (RTM), which support lightweight designs and manufacturing efficiency. North America is expected to remain a key regional market, supported by defense spending, established aerospace capabilities, and growing investment in unmanned systems, while Asia Pacific is expected to record strong growth as drone manufacturing and adoption expand across the region.
KEY TAKEAWAYS
-
By RegionAsia Pacific is projected to grow at the highest CAGR of 14.4% during the forecast period.
-
By Composite TypeCFRP segment dominated the global drone composites market with a share of 92.3% in 2025.
-
By Manufacturing ProcessThe AFP/ATL segment accounts for the largest share in the global drone composites market.
-
By Platform TypeThe fixed wing segment held the largest share in the global drone composites market, in terms of value, in 2025.
-
By ComponentThe fuselage segment dominated the global drone composites market in 2025.
-
By ApplicationThe military & defense segment held the largest share, at 76.1%, in 2025.
-
Competitive Landscape-Key PlayersToray Industries, Inc., Hexcel Corporation, SGL Carbon, Syensqo, and Teijin Limited are star players in the drone composites market, given their broad industry coverage and strong operational & financial strength.
-
Competitive Landscape- StartupsCRP Technology S.r.l., Clearwater Composites, LLC , and CUMI Aerospace & Defence have distinguished themselves among startups and SMEs due to their well-developed marketing channels and extensive funding to build their product portfolios.
The global drone composites market is gaining momentum as UAV manufacturers increasingly prioritize weight reduction, flight endurance, and structural efficiency. CFRP is expected to remain a key material, supported by its high strength-to-weight ratio, while advancements in manufacturing processes such as automated fiber placement (AFP) and automated tape laying (ATL) are improving production precision and material utilization. Military & defense applications continue to drive demand for high-performance composite structures, while civil & commercial drone adoption is expanding opportunities across agriculture, surveying, logistics, and infrastructure inspection. VTOL/hybrid platforms and next-generation fixed-wing UAVs are creating additional requirements for optimized composite airframes and wings. Regionally, North America remains a significant market due to its defense and aerospace capabilities, while Asia Pacific offers strong growth potential through expanding UAV manufacturing and adoption.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
The impact on consumers’ business emerges from customer trends or disruptions. Shifts, such as changing trends or disruptions, will affect end-user revenue. The revenue impact on end users will affect the revenue of hot bets, which will further affect the revenue of drone composite manufacturers.
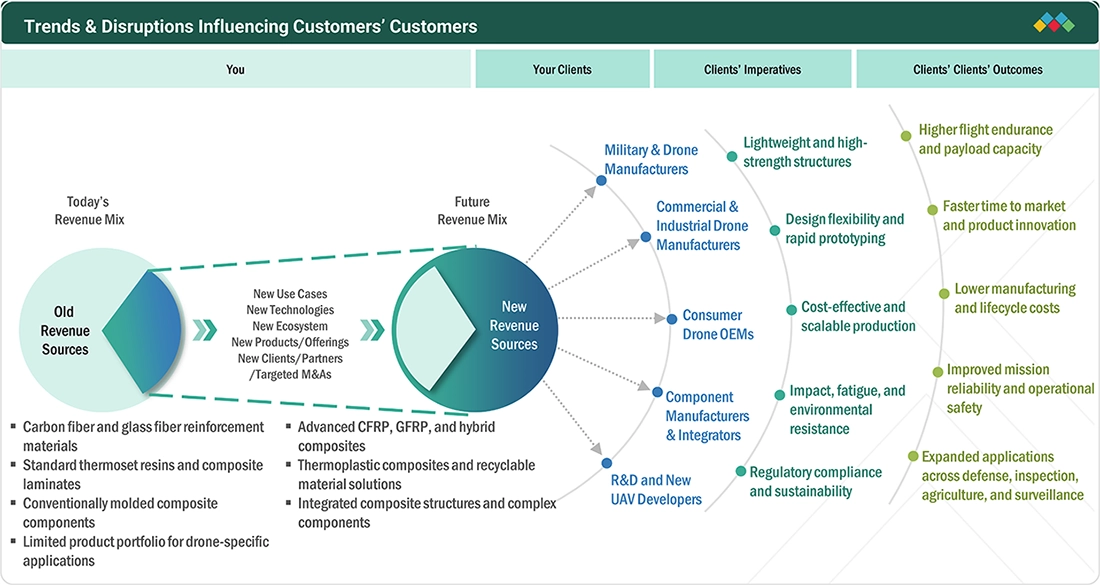
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Level
-
Increasing Integration of Engineered Composite Structures in Drone Airframes

-
Growing Requirement for Composite Structures in Military and High-Performance UAVs


Level
-
High Cost of Composite Prototyping and Transition to Economical Production

-
Specialized Engineering and Manufacturing Requirements for Complex Drone Airframes


Level
-
Expansion of Specialized Composite Component Manufacturing for UAVs

-
Adoption of Fiber-Reinforced Thermoplastics in Drone Components


Level
-
Achieving Reliable Propeller Performance and Consistent Composite Quality

-
Scaling Composite Drone Parts While Maintaining Dimensional Accuracy and Repeatability

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Growing Requirement for Composite Structures in Military and High-Performance UAVs
Military and high-performance UAVs require lightweight, high-stiffness composite materials to support mission-specific payloads, aerodynamic efficiency, and reliable operation. CFRP composites, including carbon-epoxy prepregs and engineered laminates, are used in load-bearing structures, airframes, and propulsion-related components. Blue Force Technologies’ Fury aircraft and the LR2M carbon drone airframe developed by AERONEFS SERVICES with COMPOSITE DISTRIBUTIONS illustrate the application of carbon fiber composites in specialized UAV structures. Hexcel’s HexPly carbon-epoxy prepreg is used in lightweight drone airframe designs, highlighting the role of advanced composite materials in UAV manufacturing. These developments demonstrate that market growth is driven by the integration and production of engineered composite components tailored to specific drone platforms.
Restraint: High Cost of Composite Prototyping and Transition to Economical Production
The adoption of composite materials in drone manufacturing involves significant development costs beyond raw material prices, including specialized tooling, design iterations, testing, and process optimization. These expenses can limit adoption in cost-sensitive drone segments, particularly when production volumes are insufficient to recover initial investments. A project by JR Proto for Suzhou Lan Yue Drone Technology demonstrated the use of carbon fiber composites and rapid tooling to develop a quadcopter airframe through multiple design iterations before production. This highlights the importance of aligning composite material selection and manufacturing processes with production volumes, target prices, and performance requirements.
Opportunity: Development of Multifunctional Composites for RF Transparency and Electromagnetic Shielding
Drone composites offer opportunities for integrating structural performance with electromagnetic properties to support GPS antennas, sensors, telemetry, and communication systems. Glass fiber composites are suitable for RF-transparent radomes and antenna covers, while carbon fiber composites can provide structural strength and, in certain designs, electromagnetic interference shielding. For example, Skydio X2 uses glass fiber in the upper section of its composite structure to support GPS signal reception while incorporating carbon fiber for structural performance. These applications highlight the need to balance electromagnetic characteristics, weight, durability, and mechanical strength when designing multifunctional composite components for drones.
Challenge: Repairability, Damage Inspection, and End-of-Life Management of Composite Drone Structures
Repairing composite drone structures is challenging because impact damage, delamination, and fiber breakage may occur beneath the surface, requiring specialized inspection, controlled repairs, and post-repair validation. These processes can increase maintenance costs and operational downtime, while component replacement may sometimes be more practical than repair. End-of-life management presents further challenges because thermoset composites are difficult to recycle, and recovered fibers may not retain the properties required for high-performance applications. These issues are encouraging drone manufacturers and composite suppliers to improve damage detection, develop repairable structures, reduce manufacturing waste, and explore more effective recycling solutions.
DRONE COMPOSITES MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Composite airframes and structural components in military reconnaissance and tactical UAVs | High strength-to-weight ratio | Extended endurance | Improved maneuverability |
 |
Fiber-reinforced composite structural components and propellers in selected commercial and enterprise drones | Lightweight construction | Structural stiffness | Improved flight efficiency |
 |
Composite airframe structures in tactical and unmanned combat aerial vehicles | Reduced structural weight | Improved aerodynamic performance | Increased mission endurance |
 |
Carbon-fiber and glass-fiber composite structural components in autonomous drones | Reduced weight | Improved stiffness | Enhanced durability |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
The drone composites market ecosystem involves identifying and analyzing interconnected relationships among raw material suppliers, composite material manufacturers, component fabricators, drone OEMs, and end users. This analysis outlines the flow of materials, technologies, and value across the ecosystem, highlighting dependencies, collaborations, and potential supply chain constraints. Raw material suppliers provide key inputs, including carbon fibers, glass fibers, resin systems, and reinforcement materials, which are processed into composite laminates, prepregs, molded structures, and sandwich panels. Composite manufacturers and component fabricators convert these inputs into drone airframes, wings, fuselages, propellers, frames, and other structural components, while UAV manufacturers integrate these components into fixed-wing, rotary-wing, and VTOL/hybrid platforms. End users deploy composite-based drones across military & defense, civil & commercial, and consumer applications, including surveillance, agriculture, infrastructure inspection, surveying, and logistics.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
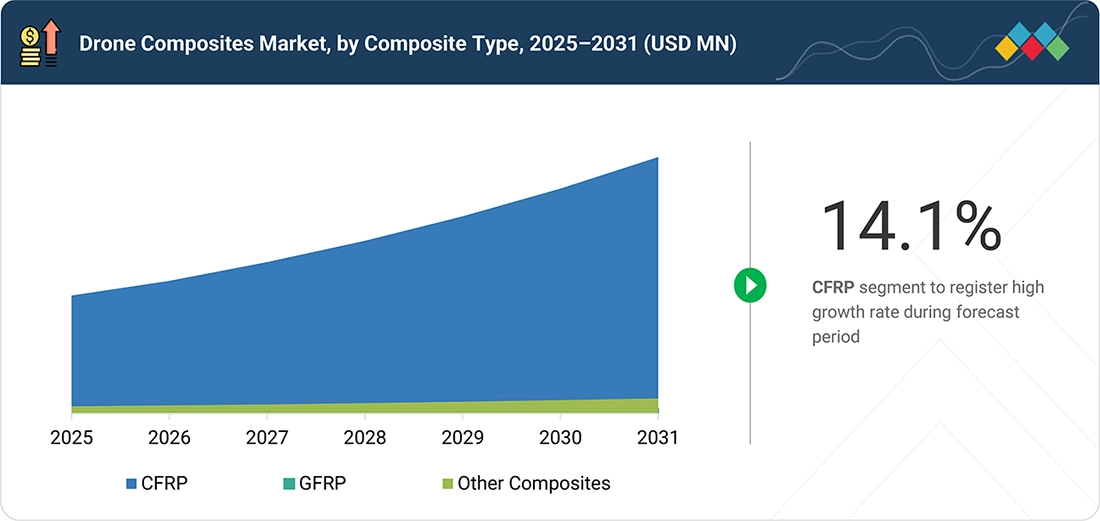
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Drone Composites Market, By Composite Type
Carbon fiber-reinforced polymer (CFRP) accounts for the largest share of the global drone composites market due to its high strength-to-weight ratio, stiffness, and fatigue resistance. These properties make CFRP suitable for lightweight UAV structures that require high structural performance without increasing overall weight. Its adoption is supported by demand for improved flight endurance, payload capacity, and aerodynamic efficiency. Military & defense UAVs particularly benefit from CFRP structures designed for demanding operational conditions. Continued development of advanced carbon fibers, resin systems, and composite manufacturing technologies is further supporting the segment's market position.
Drone Composites Market, By Platform Type
Fixed-wing drones account for the largest share of the global drone composites market, supported by their use in long-endurance missions and applications requiring extended flight range. Their wing and fuselage structures benefit from composite materials that reduce weight while maintaining stiffness and aerodynamic performance. Military surveillance, reconnaissance, mapping, and agricultural monitoring contribute to demand for fixed-wing UAVs. Composite structures enable manufacturers to optimize airframe weight and improve operational efficiency. Continued adoption of long-range and high-performance fixed-wing platforms supports demand for advanced drone composites.
Drone Composites Market, By Component
The fuselage accounts for the largest share of the global drone composites market by component, reflecting its role as the primary structural body of a UAV. Composite fuselages provide the strength required to support payloads, propulsion systems, onboard electronics, and other integrated equipment while minimizing structural weight. CFRP is particularly relevant where stiffness, durability, and weight reduction are critical. Increasing demand for high-performance military and commercial drones is supporting the use of composites in fuselage construction. Advances in molding and integrated manufacturing techniques are further enabling optimized fuselage designs and improved production efficiency.
Drone Composites Market, By Application
Military & defense accounts for the largest share of the global drone composites market by application, driven by demand for UAVs used in surveillance, reconnaissance, intelligence gathering, and tactical operations. These platforms require lightweight and durable structures to support mission-specific payloads, extended flight endurance, and reliable performance. Composite materials help reduce airframe weight while maintaining the structural strength required under demanding operating conditions. Increasing investments in unmanned defense systems and next-generation UAV development are supporting composite adoption. The need for high-performance airframes and structural components continues to strengthen demand across military drone programs.
REGION
Asia Pacific to be the fastest-growing market for drone composites during the forecast period
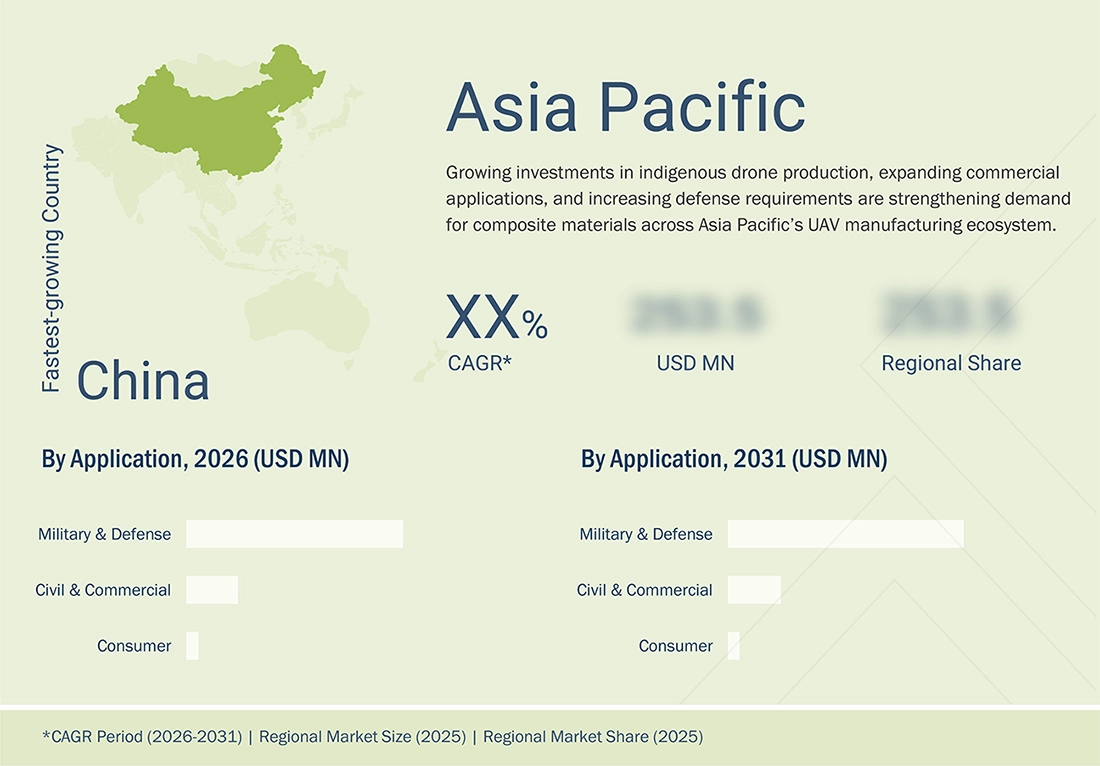
Asia Pacific is projected to be the fastest-growing region in the global drone composites market, supported by expanding UAV manufacturing, rising defense investments, and increasing adoption of commercial drones across China, India, Japan, and South Korea. Growing production of military and civilian UAVs is generating demand for lightweight composite materials used in airframes, wings, fuselages, and other structural components. The region's expanding drone manufacturing ecosystem and government initiatives supporting domestic UAV production are strengthening demand for advanced composites. Increasing use of drones in agricultural monitoring, infrastructure inspection, surveying, and logistics is creating additional opportunities for composite-intensive platforms. Investments in next-generation UAV technologies and advanced manufacturing capabilities are further supporting regional market growth.
DRONE COMPOSITES MARKET: COMPANY EVALUATION MATRIX
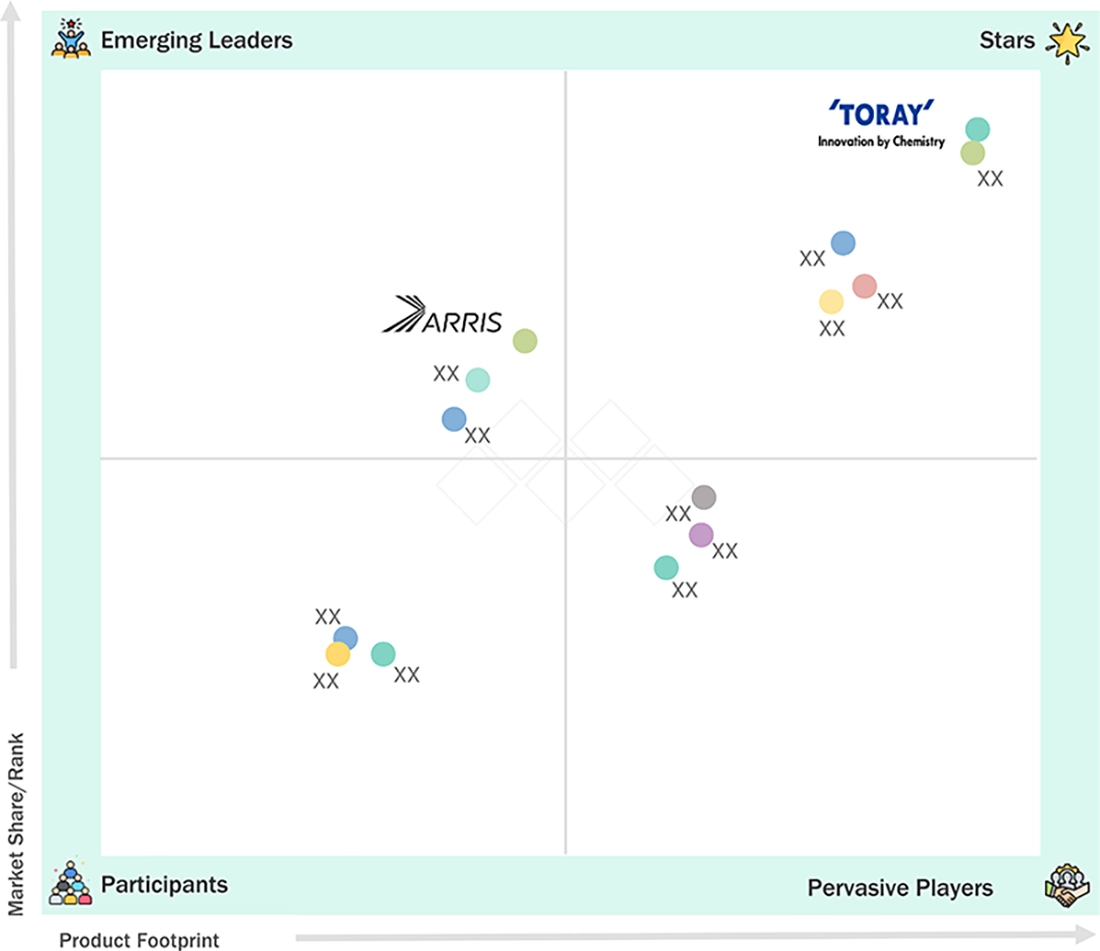
For the global drone composites market, Toray Industries, Inc. (Star) maintains a strong position through its extensive carbon fiber portfolio, advanced composite material technologies, established aerospace expertise, and global manufacturing capabilities. ARRIS Composites (Emerging Leader) is strengthening its market position through its proprietary composite manufacturing technologies, integrated structural components, and focus on scalable production of lightweight, high-performance structures. While Toray benefits from its broad advanced-materials portfolio, established aerospace relationships, and extensive production capabilities, ARRIS Composites demonstrates strong potential through its differentiated manufacturing approach and application-specific composite solutions. Growing demand for lightweight UAV structures, improved flight endurance, and efficient component manufacturing creates opportunities for both companies to strengthen their positions as the global drone composites market expands.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- Toray Industries, Inc.
- Hexcel Corporation
- SGL Carbon
- Teijin Limited
- Syensqo
- Gurit Services AG
- Mitsubishi Chemical Group Corporation
- Park Aerospace Corp.
- Exel Composites
- Kordsa
- RAMPF Holding GmbH & Co. KG
- Connova AG
- Piran Advanced Composites
- ARRIS Composites, Inc.
- Rock West Composites, Inc.
- ACP Composites, Inc.
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2025 (Value) | USD 6.27 Billion |
| Market Size in 2026 (Value) | USD 7.06 Billion |
| Market Forecast in 2031 (Value) | USD 13.59 Billion |
| CAGR | CAGR of 14.0% from 2026–2031 |
| Years Considered | 2024–2031 |
| Base Year | 2025 |
| Forecast Period | 2026–2031 |
| Units Considered | Value (USD Million/Billion), Volume (Tons) |
| Report Coverage | Revenue Forecast, Company Ranking, Competitive Landscape, Growth Factors, and Trends |
| Segments Covered |
|
| Regions Covered | North America, Europe, Asia Pacific, Rest of the World |
WHAT IS IN IT FOR YOU: DRONE COMPOSITES MARKET REPORT CONTENT GUIDE
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Raw Material Suppliers (Carbon fiber, glass fiber, resins, prepregs, reinforcement materials, and core materials) |
|
|
| Drone Composites Manufacturers |
|
|
| Drone OEMs and Component Manufacturers |
|
|
| End-Use Industries (Military & Defense, Civil & Commercial, Consumer) |
|
|
RECENT DEVELOPMENTS
- August 2026 : Toray Advanced Composites entered into a collaboration with IGCS International and Lacks Carbon Fiber to support the U.S. Drone Dominance Program, supplying carbon- and glass-fiber reinforced prepreg materials for the rapid and on-demand fabrication of military drones and UAS components.
- April 2025 : Hexcel collaborated with Hybron to support high-rate production of aerospace and defense composite structures, including the Pentagon's attritable drone programs. The collaboration combines Hybron's manufacturing processes designed to reduce composite production cycle times with Hexcel's domestically produced composite materials, supporting scalable and cost-efficient production of attritable UAVs.
- May 2025 : Syensqo collaborated with Boeing to demonstrate the potential of its CYCOM 5250-4HT high-temperature prepreg as a lightweight alternative to titanium in the exhaust-nozzle structure of the MQ-25 Stingray unmanned aerial refueling aircraft. The collaboration highlights the potential of advanced composite materials to reduce structural weight while meeting the demanding thermal and performance requirements of military UAV applications.
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
Methodology
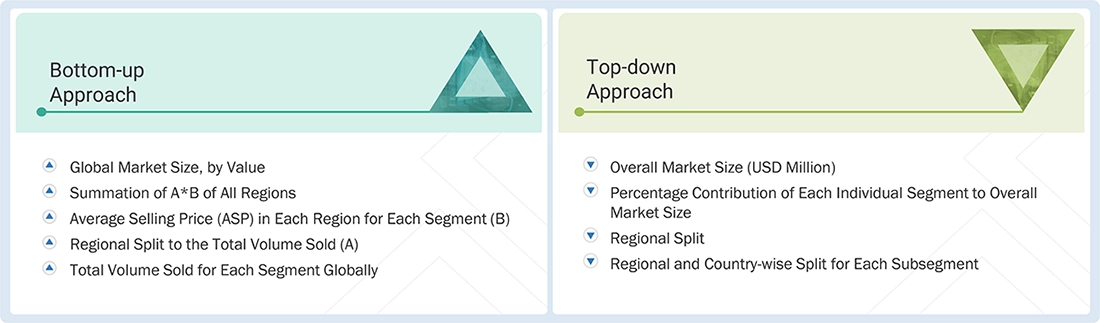
The study involves two major activities in estimating the current market size for the drone composites market. Exhaustive secondary research was done to collect information on the market, peer market, and parent market. The next step was to validate these findings, assumptions, and sizing with industry experts across the value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the complete market size. After that, market breakdown and data triangulation were used to estimate the market size of segments and subsegments.
Secondary Research
Secondary sources referred to for this research study include financial statements of companies offering drone composites and information from various trade, business, and professional associations. Secondary research has been used to obtain critical information about the industry’s value chain, the total pool of key players, market classification, and segmentation according to industry trends to the bottom-most level and regional markets. The secondary data was collected and analyzed to arrive at the overall size of the drone composites market, which was validated by primary respondents.
Primary Research
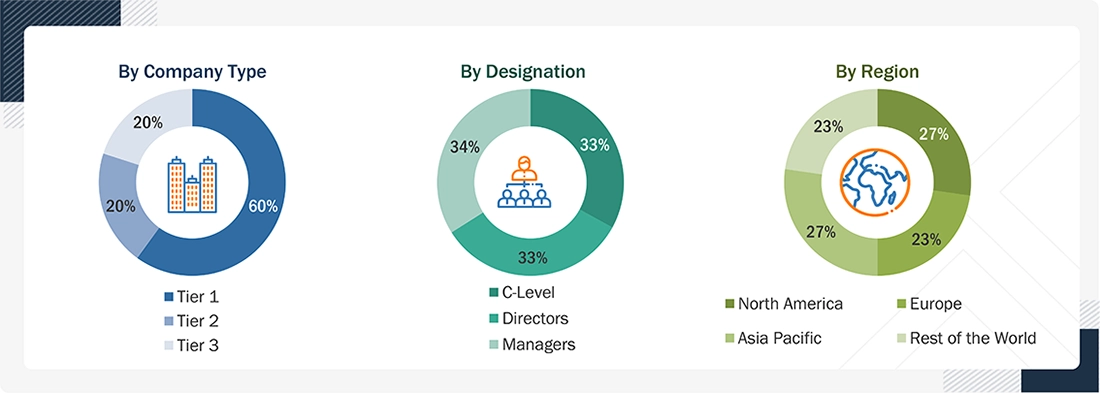
Extensive primary research was conducted after obtaining information regarding the drone composites market scenario through secondary research. Several primary interviews were conducted with market experts from both the demand and supply sides across major countries of North America, Europe, Asia Pacific, and Rest of the World. Primary data was collected through questionnaires, emails, and telephonic interviews. The primary sources from the supply side included various industry experts, such as chief experience officers (CXOs), vice presidents (VPs), business development/marketing directors, product development/innovation teams, related key executives from the drone composites industry, system integrators, component providers, distributors, and key opinion leaders. Primary interviews were conducted to gather insights such as market statistics, data on revenue collected from the products and services, market breakdowns, market size estimations, market forecasting, and data triangulation. Primary research helped in understanding the various trends related to composite type, manufacturing process, platform type, component, application, and region. Stakeholders from the demand side, such as CIOs, CTOs, CSOs, and installation teams of the customers/end users who are seeking drone composite services, were interviewed to understand the buyer’s perspective on the suppliers, products, component providers, and their current usage of drone composites and future outlook of their business, which will affect the overall market.
Breakup of Primary Research
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
The research methodology used to estimate the size of the drone composites market includes the following details. The market size was estimated from the demand side. The market was upsized based on the demand for drone composites in different applications at the regional level. Such procurements provide information on the demand aspects of the drone composites industry for each application. For each application, all possible segments of the drone composites market were integrated and mapped.
Drone Composites Market: Top-Down and Bottom-Up Approach
Data Triangulation
After arriving at the overall size from the market size estimation process explained above, the total market was split into several segments and subsegments. The data triangulation and market breakdown procedures explained below were implemented, wherever applicable, to complete the overall market engineering process and arrive at the exact statistics for various market segments and subsegments. The data were triangulated by studying various factors and trends from the demand and supply sides. Along with this, the market size was validated using both the top-down and bottom-up approaches.
Market Definition
Drone composites refer to advanced composite materials used in the manufacturing of unmanned aerial vehicles (UAVs), commonly known as drones, to enhance structural strength, reduce weight, and improve flight performance. These materials primarily include carbon fiber-reinforced polymers (CFRP), glass fiber-reinforced polymers (GFRP), and other fiber-reinforced composites, which offer high strength-to-weight ratios, stiffness, and resistance to environmental conditions. They are used in key drone components such as fuselages, wings, rotor blades, propellers, and structural frames. The adoption of composites enables longer flight endurance, higher payload capacity, improved maneuverability, and greater operational efficiency across military & defense, civil & commercial, and consumer drone applications.
Key Stakeholders
- Drone composite manufacturers
- Raw material manufacturers
- Government and research organizations
- R&D institutions
- National and local government organizations
- Institutional investors
- Drone composite suppliers
- End users
Report Objectives
- To define, describe, and forecast the drone composites market size in terms of volume and value
- To provide detailed information regarding the key factors, such as drivers, restraints, opportunities, and challenges influencing market growth
- To analyze and project the global drone composites market by composite type, manufacturing process, platform type, component, application, and region
- To forecast the market size concerning four main regions (along with country-level data), namely, North America, Europe, Asia Pacific, and Rest of the World, and analyze the significant region-specific trends
- To strategically analyze micromarkets with respect to individual growth trends, prospects, and contributions of the submarkets to the overall market
- To analyze the market opportunities and the competitive landscape for stakeholders and market leaders
- To assess recent market developments and competitive strategies, such as agreements, contracts, acquisitions, and product developments/product launches, to draw the competitive landscape
- To strategically profile the key market players and comprehensively analyze their core competencies
Available customizations:
MarketsandMarkets offers the following customizations for this market report:
- Additional country-level analysis of the drone composites market
Product Analysis
- Product matrix, which provides a detailed comparison of the product portfolio of each company in the market


Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the Drone Composites Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Custom Market Research Services
We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements
Get 10% Free CustomisationTESTIMONIALS
We at Nissan Chemicals Corporation have been clients of MarketsandMarkets for more than a year now. We recently consulted MarketsandMarkets for a study, the team at MarketsandMarkets was extremely professional and organized. The business insights were very detailed and aligned well with our expectations that really helped us formulate the Business Plans and device new strategies for development themes. MarketsandMarkets offers a unique combination of expertise and dedicated engagement model. Their research findings have helped us in designing our Pricing Strategy which will make it easier for us to predict the future sales and profits for the next ten years. We look forward to working with MarketsandMarkets in the future.
VP of Strategy & New Business Development
Leading Specialty Chemical Company
The MarketsandMarkets Engagement Model, composed of both the Knowledge Store and advisory custom research, has greatly helped us in understanding our markets and making strategic decisions. The Knowledge Store is a fast way to allow everyone in our organization to understand more about most any market they are interested in. The ability to then get custom research done and get answers to specific strategic questions and market insight has been spectacular. The Markets and Markets team feel more like colleagues than vendors and their services have helped us change our culture where statements of things like growth opportunities and competitive position are always backed by industry research.

Rich Gibson,
Director, Corporate Strategy
Milliken & Company,
Leading Industrial Manufacturer of specialty chemical, floor covering, performance and protective textile materials, and healthcaremilliken.com
MarketsandMarkets is a trusted resource that helps us to better understand markets that are near-adjacencies-whether its technology, value chain or geography. Their Knowledge Store platform provides a dashboard of markets and their characteristics which is easy to use and saves us time.
Adam Shaw,
Market Development and Strategy Manager
AdvanSix Inc. USA,
An American Leader in Chemicalswww.advansix.com
The Knowledge Store from MarketsandMarkets is a valuable tool which has helped my team acquire greater insight in to the end markets that our business serves. This has enabled us to help our company build stronger strategies throughout our planning process.
TOSHIO KINOSHITA
Senior Chif Consultion Research & Consulting Division
Mitsubishi Chemical Research Corporation,
Leading Manufacturer of Chemical Productswww.mitsubishichem-res.co.jp/en/

We recently engaged with MarketsandMarkets for a study, the team not only clearly understood our business objectives but was also extremely professional in the way they handled the entire project. The study was efficiently conducted in a phase-wise manner, and the engagement model furnished us with high-quality business insights that far exceeded our expectations at each phase. We were especially happy that MarketsandMarkets could provide us with both, an English as well as a Japanese version of the study. A special thanks to the Analyst Team and Client Services Team, whose fluency in Japanese enhanced our comfort level, as we could converse with them in our preferred language.
Independent entrepreneurs
Arrow Precision
We approached MarketsandMarkets for study on Proppants Market, and their work exceeded our expectations. The study conducted was comprehensive and enabled us to view the market through the various dimensions. In addition, the team was extraordinarily responsive throughout the process and resolved our queries on time. I strongly recommend MarketsandMarkets and will certainly consider them for additional market assessments we will need in the future.
Global engineering company, Japan
Deputy Manager,
Strategic Planning OfficeThe high-quality insights shared by the MarketsandMarkets team helped us understand the pharmaceutical plant designers in a specific geography. It also captured the risks that we may likely face in communicating with our potential partners. The study would enable us identify partners, which would impact our future growth.





Growth opportunities and latent adjacency in Drone Composites Market