UK Cloud FinOps Market (2025-2030)
The UK Cloud FinOps Market was valued at $555.8 Million in 2025 and projected to reach to $960.6 Million by 2030, representing a compound annual growth rate of 11.6%. The UK Cloud FinOps market is positioned for sustained growth as enterprises recognize the critical importance of managing cloud costs in an increasingly complex multi-cloud landscape.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
UK Cloud FinOps Market Trends and Insights
- The UK's digital transformation initiatives and increasing cloud adoption across enterprises are driving demand for financial operations solutions that optimize cloud spending and resource allocation.
- UK organizations are increasingly recognizing the need to manage multi-cloud environments efficiently, positioning the UK as a key growth market within Europe. During the 2025–2030 forecast period, the UK Cloud FinOps market will grow at a compound annual growth rate (CAGR) of 11.6%, reflecting strong investment in cost optimization and governance frameworks.
- The UK's mature financial services sector, combined with regulatory pressures and competitive pressures to reduce operational costs, is accelerating FinOps adoption.
- UK enterprises across banking, insurance, and technology sectors are prioritizing cloud cost visibility and automation, creating sustained demand for specialized FinOps platforms and consulting services..
Key Market Statistics
- CAGR (2025-2030) 11.6% CAGR
- Market Size, 2025 ~USD 555.8 Million
- Forecast, 2030 ~USD 960.6 Million
- Country UK
UK Cloud FinOps Market Overview
Market Valuation Growth :
The UK Cloud FinOps market is valued at $555.8 million in 2025, with a projected CAGR of 11.6%, reaching $960.6 million by 2030, reflecting strong enterprise investment in cloud cost optimization.
Digital Transformation Catalyst :
UK enterprises are accelerating cloud adoption as part of broader digital transformation strategies, creating urgent demand for FinOps solutions to manage and optimize escalating cloud expenditures across multi-cloud environments.
Enterprise Cost Optimization Focus :
UK organizations are increasingly prioritizing cloud financial management to control spending, improve resource allocation efficiency, and maximize ROI on cloud infrastructure investments amid economic pressures.
Competitive Market Dynamics :
The UK market is witnessing growing competition among FinOps vendors, with enterprises seeking comprehensive solutions that integrate cost monitoring, forecasting, and automated optimization capabilities.
UK Cloud FinOps Market Dynamics
- Financial pressures and the need for operational efficiency are compelling UK organizations to adopt dedicated FinOps platforms that provide real-time visibility into cloud spending and enable proactive cost management.
- The market will be driven by expanding cloud adoption, regulatory compliance requirements, and the maturation of FinOps practices across sectors including financial services, healthcare, and retail.
- By 2030, FinOps solutions will become essential infrastructure for UK enterprises seeking competitive advantage through optimized cloud economics and improved financial governance..
Market Ecosystem
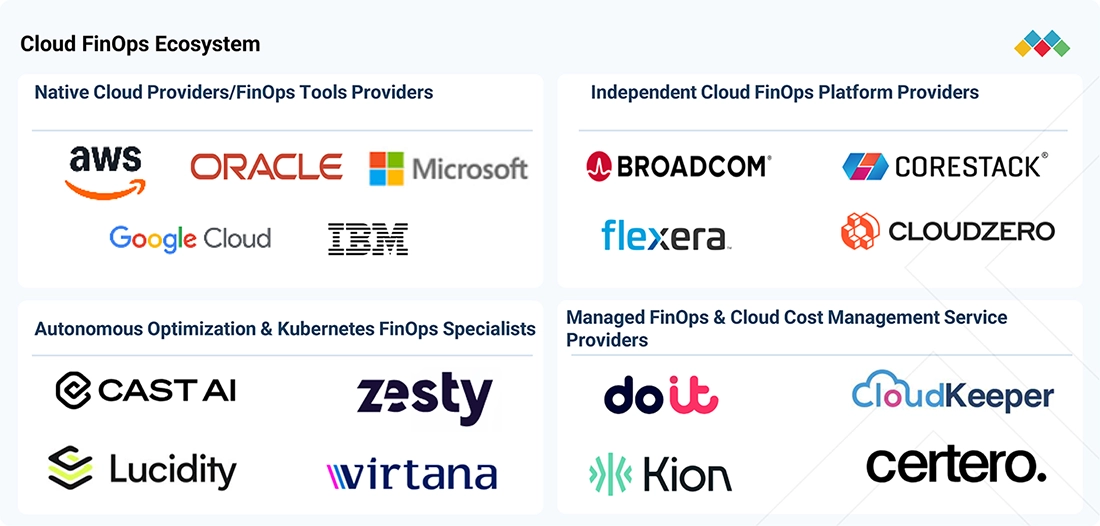
CLOUD FINOPS MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
PicPay linked cloud expenses across 20 business units to accountable engineering teams and business performance metrics using CloudZero's cost intelligence platform. | USD 18.6 million in annualized cloud savings across 2024–2025 | 350+ monthly engineering users | Reduced waste through rightsizing, early intervention, and rate optimization |
 |
InCred Finance deployed CAST AI's automated Kubernetes rebalancing, workload autoscaling, and instance selection capabilities within an already optimized cloud environment. | Approximately 30% monthly compute savings | Operational tasks shortened from seven to three–four days | Additional savings from automated Spot selection |
 |
A major North American financial institution used an AWS FinOps acceleration workshop to translate cost visibility into repeatable team-level optimization actions. | More than USD 1.4 million in annual recurring savings reported | Demonstrates the operational benefit of standardized execution across extensive account estates |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Cloud Computing
- Software as A Service (SaaS)
- Natural Language Processing (NLP)
- Platform as A Service (PaaS)
- Machine Learning
- Supply Chain Management
- International Business Machines Corporation
- MICROSOFT CORPORATION
- Oracle Corporation
- Amazon.com, Inc.
Software And Services
- Natural Language Processing (NLP)
- Machine Learning
- Supply Chain Management
- Predictive Analytics
- Image Sensors
- International Business Machines Corporation
- MICROSOFT CORPORATION
- Oracle Corporation
- SAP SE
- Amazon.com, Inc.
Key Takeaways
- The UK Cloud FinOps market is valued at $555.8 million in 2025 and will reach $960.6 million by 2030, representing a 11.6% CAGR.
- UK enterprises are increasingly adopting FinOps solutions to optimize multi-cloud spending and improve cost governance across digital operations.
- The UK's regulated financial services and technology sectors are primary drivers of FinOps platform adoption and investment.
- UK organizations prioritize cloud cost visibility, automation, and resource allocation efficiency as core strategic objectives through 2030.
Cloud FinOps Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | HYBRID (Deployment Mode) |
| Forecast Period | 2025–2030 |
| Growth Rate | CAGR of 12.57% from 2025 to 2030 |
| Largest Segment | SOLUTIONS (Offering) |
| Market Size Base Year (Billions) | ~USD 14.89 (2025) |
| Revenue Forecast (Billions) | ~USD 26.91 (2030) |
| Segments Covered | Offering, Solution, Service, Professional Service, Application/Capability, Deployment Environment, Deployment Mode, Service Model, Organization Size, Vertical, Application |
UK Cloud FinOps Market Report Segmentation
11 segment dimensions are covered across the global market.
By Offering
- Services
- Solutions
By Solution
- Native Solutions
- Third-Party Solutions
By Service
- Managed Services
- Professional Services
By Professional Service
- Finops Advisory & Strategy Services
- Implementation & Integration
- Support & Maintenance
By Application/Capability
- Budgeting & Forecasting
- Cost Allocation & Chargeback
- Cost Management & Optimization
- Other Applications
- Reporting & Analytics
- Workload Management & Optimization
By Deployment Environment
- Multi Cloud
- Single Cloud
By Deployment Mode
- Hybrid
- Private
- Public
By Service Model
- IaaS
- PaaS
- SaaS
By Organization Size
- Large Enterprise
- Large Enterprises
- Smes
By Vertical
- Bfsi
- Government & Public Sector
- Healthcare & Life Sciences
- It & Ites
- Manufacturing
- Media & Entertainment
- Other Verticals
- Retail & Consumer Goods
- Telecommunications
By Application
- Budgeting & Forecasting
- Cost Allocation & Chargeback
- Cost Management & Optimization
- Other Applications
- Reporting & Analytics
- Workload Management & Optimization
Target Audience
- FinOps Solution Vendors : UK-based and international FinOps vendors need market intelligence to assess growth potential, identify customer segments, benchmark competitive positioning, and develop localized go-to-market strategies for British enterprises.
- Enterprise IT & Finance Leaders : UK CIOs, CFOs, and cloud operations managers require market insights to justify FinOps investments, evaluate vendor solutions, understand industry best practices, and optimize cloud spending across their organizations.
- Cloud Service Resellers & Integrators : UK-based cloud consultants and system integrators need market data to identify FinOps service opportunities, develop complementary offerings, and position solutions to enterprise clients seeking cost optimization expertise.
- Investment & Strategy Consultants : Management consulting firms and investment advisors serving UK clients require detailed market analysis to support strategic recommendations, M&A assessments, and investment decisions in the FinOps sector.
- Technology Investors & PE Firms : UK and international investors evaluating FinOps market opportunities need comprehensive market sizing, growth forecasts, and competitive analysis to assess investment returns and portfolio company potential in this sector.
Key Companies in the UK Cloud FinOps Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| MICROSOFT | United States | Public Company | Intelligent Cloud (Azure, server products, GitHub, Nuance, enterprise services),Productivity and Business Processes (Microsoft 365, LinkedIn, Dynamics),Personal Computing (Windows, devices, gaming, search and news advertising), |
| United States | Public Company | Search & Other Ads,YouTube Ads & Subscriptions,Google Cloud (incl. Workspace), | |
| ORACLE | United States | Public Company | Cloud applications (Fusion ERP/EPM/SCM/HCM, NetSuite, Oracle Health, CX),Database and infrastructure technologies (Oracle Database, MySQL, autonomous DB, middleware, Java),Cloud infrastructure (compute, storage, networking, AI/ML, digital assistant, IoT, blockchain), |
| IBM | United States | Public Company | Software (Hybrid Cloud and AI Platforms),Consulting (Strategy, Technology, Managed Services),Infrastructure (Servers, Storage, Lifecycle Services), |
| HITACHI | Japan | Public Company | Digital Systems & Services (IT, cloud, integration),Green Energy & Mobility (power grids, energy, rail),Connective Industries (industrial, automotive, e-mobility), |
| VMWARE | United States | Private Company | Compute & Core Virtualization (vSphere),Hyperconverged & Private Cloud Platform (vSAN, VxRail, VMware Cloud Foundation),Networking & Security (NSX, SASE, Carbon Black), |
| SERVICENOW | United States | Public Company | IT Service & Operations Management,Customer & Field Service Management,Risk, Security & OT / Mission-Critical Operations, |
| DATADOG | United States | Public Company | Infrastructure & APM observability core,Log management & observability pipelines,Digital experience & app analytics (synthetics, RUM, product analytics), |
| NUTANIX | United States | Public Company | Nutanix Cloud Infrastructure (AOS, AHV, core HCI),Nutanix Cloud Manager & Central (operations, cost, security),Data & Storage Services (Unified Storage, Files, Objects, Volumes, Data Lens), |
| AMDOCS | United States | Public Company | CES25 and Customer Engagement / CRM,Monetization and Charging Suites,Intelligent Networking and eSIM / Network Services, |
| BMC SOFTWARE | United States | Private Company | Enterprise Service Management (ITSM, ITOM, ITAM),Mainframe Service Management,Control-M and Enterprise Workload Automation, |
| HCL | India | Public Company | IT and Business Services,Engineering and R&D Services,HCL Software and IP-led Offerings, |
MICROSOFT
Microsoft is a public company founded in 1975 in the United States and employs 228,000 people.
Google is a public company founded in 1998 in the United States with 194,668 employees.
ORACLE
Oracle is a public company founded in 1977 in the United States and has 141,000 employees.
IBM
IBM is a public company founded in 1911 in the United States with 264,300 employees.
HITACHI
Hitachi is a public company founded in 1910 in Japan and employs 287,901 people.
VMWARE
VMware is a private company founded in 1998 in the United States with 38,300 employees.
SERVICENOW
ServiceNow is a public company founded in 2004 in the United States and has 29,187 employees.
DATADOG
Datadog is a public company founded in 2010 in the United States with 8,100 employees.
NUTANIX
Nutanix is a public company founded in 2009 in the United States with 7,800 employees.
AMDOCS
Amdocs is a public company founded in 1982 in the United States and has 26,969 employees.
BMC SOFTWARE
BMC Software is a private company founded in 1980 in the United States with 6,700 employees.
HCL
HCL is a public company founded in 1976 and headquartered in India.
Reasons to Buy this Report
- UK-Specific Market Sizing : Obtain precise valuation data for the UK Cloud FinOps market with accurate 2025-2030 forecasts, enabling confident investment decisions and resource allocation tailored to the British market opportunity.
- Competitive Landscape Intelligence : Understand the competitive positioning of FinOps vendors within the UK market, identify key players, and assess market consolidation trends specific to British enterprises and their procurement preferences.
- Growth Driver Analysis : Gain insights into UK-specific factors driving FinOps adoption, including digital transformation initiatives, regulatory requirements, and enterprise cloud strategies unique to the British business environment.
- Sector-Specific Opportunities : Identify high-growth segments within the UK market across financial services, healthcare, retail, and public sector, with tailored insights for targeting specific industry verticals with FinOps solutions.
- Strategic Planning & Forecasting : Leverage detailed UK market projections and trend analysis to develop informed go-to-market strategies, product roadmaps, and partnership approaches aligned with British enterprise requirements and market dynamics.
Frequently asked questions
What is the current size of the UK Cloud FinOps market?
The UK Cloud FinOps market is estimated at $555.8 million in 2025 and is projected to grow to $960.6 million by 2030.
What is the growth rate of the UK Cloud FinOps market?
The UK Cloud FinOps market is expected to grow at a compound annual growth rate (CAGR) of 11.6% from 2025 to 2030.
Which sectors are driving Cloud FinOps adoption in the UK?
The UK's financial services, banking, insurance, and technology sectors are the primary drivers of Cloud FinOps adoption due to regulatory requirements and cost optimization pressures.
Why is the UK Cloud FinOps market growing faster than other regions?
The UK's mature digital infrastructure, strong regulatory environment, and enterprise focus on cost optimization are accelerating Cloud FinOps adoption compared to emerging markets.
What are the key challenges for Cloud FinOps implementation in the UK?
UK organizations face challenges including multi-cloud complexity, skills gaps in FinOps expertise, and the need to balance cost optimization with compliance and governance requirements.
RESEARCH METHODOLOGY
This research study on the cloud FinOps market incorporates extensive secondary research, structured market sizing, and primary research validation. Secondary sources include company annual reports, regulatory filings, investor presentations, earnings transcripts, product documentation, pricing disclosures, acquisition announcements, technical publications, government sources, and industry associations. Research also examines cloud expenditure patterns, FinOps adoption, commitment utilization, AI infrastructure costs, and enterprise financial governance requirements. The primary research framework covers cloud service providers, independent FinOps platform vendors, managed service providers, technology consultants, and enterprise cloud consumers. Supply- and demand-side research is designed to validate market boundaries, revenue attribution, pricing models, adoption patterns, competitive positioning, and growth assumptions. Top-down and bottom-up approaches are used to assess market revenue, followed by data triangulation across offerings, applications, service models, deployment environments, organization sizes, verticals, and geographic markets.
Secondary Research
During the secondary research process, multiple authoritative sources were reviewed to establish the cloud FinOps market's competitive structure, revenue potential, and technology landscape. These sources include company annual reports, regulatory filings, investor presentations, earnings transcripts, product portfolios, subscription pricing, customer case studies, acquisition announcements, partnership disclosures, and official technical documentation. Additional information was gathered from cloud service providers, the FinOps Foundation, FOCUS specifications, government publications, and recognized technology standards organizations. Research examined cloud cost management adoption, enterprise cloud expenditure, multi-cloud financial governance, Reserved Instance and Savings Plan utilization, Kubernetes optimization, AI infrastructure economics, and managed FinOps service delivery. Product-level analysis distinguished native cloud financial management functionality from independently monetized FinOps software and directly associated professional and managed services. Secondary research established the vendor universe, market inclusion and exclusion criteria, revenue estimation assumptions, competitive benchmarks, regional demand indicators, and the initial market-sizing framework.
Primary Research
The primary research framework incorporates supply- and demand-side participants to validate qualitative and quantitative assumptions concerning the cloud FinOps market. Supply-side participants include product directors, FinOps practice leaders, cloud economics specialists, engineering managers, solution architects, business development executives, and commercial strategy professionals. Target organizations include hyperscale cloud providers, independent FinOps software vendors, Kubernetes optimization specialists, managed cloud service providers, system integrators, and technology consulting firms. Demand-side participants include enterprise FinOps practitioners, cloud infrastructure managers, platform engineering leaders, financial planning professionals, IT procurement managers, cloud architects, and technology finance decision-makers. Primary discussions examine purchasing criteria, software pricing, managed service engagement models, commitment optimization, cloud cost allocation, automation maturity, and measurable savings realization. Findings are used to assess customer adoption, vendor differentiation, market segmentation, geographic demand, and the reasonableness of revenue and growth assumptions. Interview-derived findings should be incorporated into the final study only after the corresponding primary interviews are completed and documented.
Breakup of Primary Profiles:
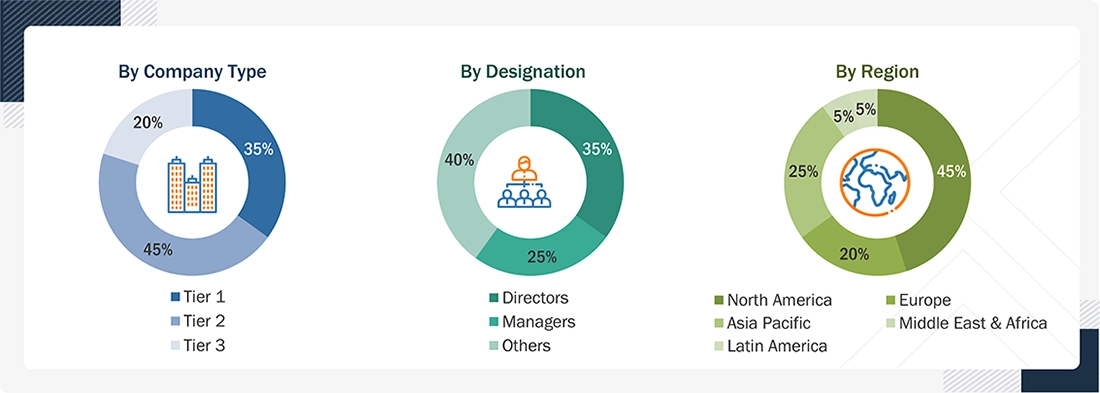
Note: Tier 1 companies have annual revenues of more than USD 1 billion; Tier 2 companies have annual revenues between USD 100 million and USD 1 billion; and Tier 3 companies have annual revenues below USD 100 million. Other designations include professionals working across sales, marketing, engineering, product management, operations, research, cloud architecture, and storage infrastructure.
Source: Industry Experts
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
Multiple approaches were used to develop the cloud FinOps market-sizing framework. The bottom-up approach evaluated revenue attributable to cloud financial management software, native and third-party FinOps solutions, managed FinOps services, and associated professional services. Company revenues were assessed using financial disclosures, product-level monetization models, customer references, pricing information, and relevant business segment performance. Revenue estimates were allocated based on supported FinOps capabilities, deployment characteristics, target customers, and geographic exposure. Broader cloud infrastructure consumption, general observability, unrelated IT management software, cloud resale pass-through revenue, and savings delivered to customers were excluded to avoid market overstatement. Estimates were evaluated against cloud expenditure, enterprise FinOps adoption, addressable workloads, provider pricing structures, commitment management requirements, and regional cloud consumption patterns. Market growth assumptions were further assessed using increasing AI infrastructure demand, financial governance requirements, adoption of automated optimization, and the expansion of managed FinOps services.
Market Size Estimation Methodology: Top-down Approach
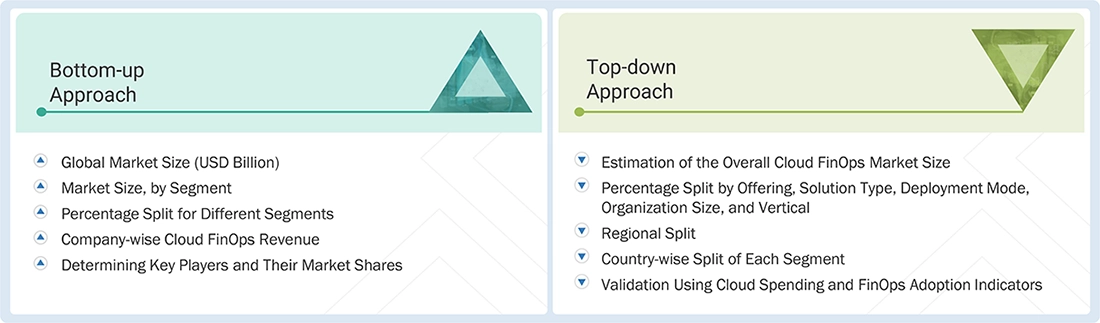
The top-down approach began by establishing the addressable revenue opportunity for cloud financial management software and directly related services. Global cloud infrastructure expenditure, enterprise software investments, vendor financial disclosures, and cloud financial management adoption indicators were analyzed to identify the portion associated with commercially monetized FinOps capabilities. Particular attention was given to cloud cost visibility, financial planning, anomaly management, commitment optimization, workload rightsizing, and business-value measurement. FinOps spending was distinguished from the underlying cloud consumption it manages, ensuring that cloud infrastructure revenue was not directly classified as FinOps market revenue. The resulting market envelope was assessed using enterprise adoption rates, pricing and licensing structures, managed service penetration, workload complexity, and geographic cloud maturity. The estimates were then distributed across offerings, applications, service models, deployment environments, deployment modes, organization sizes, verticals, regions, and countries. Results were cross-validated against company-level revenue estimates and available evidence on customer adoption and commercial contracts.
Market Size Estimation Methodology: Bottom-up Approach
The bottom-up approach involved developing a comprehensive universe of companies providing cloud FinOps solutions, cloud cost intelligence platforms, as well as commitment optimization, workload optimization, and directly associated managed and professional services. Each company's attributable revenue was assessed using annual reports, regulatory filings, investor disclosures, pricing information, product documentation, customer deployments, acquisition disclosures, and other official sources. For diversified vendors, relevant product and segmental revenues were identified before applying FinOps-specific revenue attribution assumptions. Pure-play vendors were assessed using available revenue disclosures, subscription pricing, customer adoption, product penetration, and estimated contract values. Native cloud provider tools were evaluated separately to distinguish monetized functionality from free capabilities bundled within cloud infrastructure services.
Company-level estimates were aggregated to establish the addressable supply-side revenue pool, with adjustments for reseller pass-through, overlapping product portfolios, acquisitions, and potential revenue duplication. Software and services were separated according to the underlying commercial transaction, while revenue attributable to unrelated infrastructure, general IT management, and non-FinOps services was excluded. The resulting estimates were allocated across applications, service models, deployment categories, customer sizes, verticals, and geographic markets. Regional allocations were assessed using vendor customer distribution, enterprise cloud maturity, purchasing patterns, financial governance requirements, and demand for advanced optimization capabilities.
Cloud FinOps Market: Top-Down and Bottom-Up Approach
Data Triangulation
After establishing the preliminary market size through top-down and bottom-up approaches, data triangulation was applied to reconcile supply-side estimates with demand-side indicators. Company-level FinOps revenues, product portfolios, subscription pricing, customer deployments, managed service penetration, cloud expenditure patterns, and regional adoption indicators were compared to identify inconsistencies. Particular attention was given to preventing double counting between native cloud platforms, third-party solutions, managed service engagements, and cloud resale arrangements. Revenue from acquired products was attributed to the appropriate economic owner, while customer savings, purchasing commitments, and cloud consumption were distinguished from FinOps vendor revenue.
The market estimates were further assessed against cloud infrastructure consumption, enterprise FinOps adoption, AI workload expansion, commitment utilization, cost management maturity, and financial governance requirements. Revenue allocations were reconciled across offerings, applications, service models, deployment environments, organization sizes, verticals, and geographic markets. Historical trends and forecast assumptions were evaluated for consistency with technology adoption, changes in monetization, and increasing automation. Final market figures were established through reconciliation of available evidence and model assumptions, ensuring consistency between global, regional, country-level, and segment estimates.
Market Definition
The cloud FinOps market comprises software solutions and directly associated services that enable organizations to manage, allocate, forecast, govern, and optimize expenditure across cloud-based technology environments. It includes native cloud financial management solutions, independent FinOps platforms, managed FinOps services, and professional services supporting financial visibility, operational efficiency, and cloud spending accountability. Core capabilities include cost and usage reporting, allocation and tagging, budgeting and forecasting, anomaly detection, commitment optimization, workload rightsizing, Kubernetes cost optimization, automated governance, chargeback, and business-value measurement.
Cloud FinOps capabilities support financial management across IaaS, PaaS, and SaaS consumption, including cloud-native applications, distributed infrastructure, and AI workloads. The market excludes underlying cloud infrastructure consumption, cloud resale pass-through revenue, free native billing functionality without separate attributable monetization, unrelated observability and IT management products, customer cost savings, and general consulting services without a direct FinOps component. Revenue is included only where it is attributable to commercial FinOps functionality or directly associated service delivery.
Key Stakeholders
- Hyperscale cloud service providers
- Native cloud financial management solution providers
- Independent and third-party FinOps platform vendors
- Cloud cost visibility and allocation software providers
- Cloud budgeting and forecasting solution providers
- Cloud cost anomaly detection and governance vendors
- Reserved Instance and Savings Plan optimization providers
- Cloud commitment and discount management specialists
- Kubernetes and container cost optimization vendors
- AI infrastructure and GPU cost optimization providers
- Automated workload rightsizing and scheduling vendors
- Managed cloud FinOps service providers
- Cloud financial management consulting firms
- Cloud system integrators and technology service providers
- Enterprise FinOps practitioners and cloud centers of excellence
- Enterprise cloud infrastructure and platform engineering teams
- IT financial management and enterprise procurement teams
Report Objectives
- To define and describe the cloud FinOps market by offering, application, service model, deployment environment, deployment mode, organization size, vertical, and region
- To provide detailed information on major factors influencing market growth, including drivers, restraints, opportunities, and challenges across the cloud FinOps ecosystem
- To strategically analyze micro-markets based on cloud spending patterns, FinOps adoption maturity, workload optimization requirements, and their contribution to overall market growth
- To assess market opportunities for stakeholders and evaluate the competitive landscape across native cloud providers, third-party FinOps platforms, automated optimization specialists, and managed FinOps service providers
- To estimate market size and forecast revenue across North America, Europe, Asia Pacific, Middle East & Africa, and Latin America
- To analyze major countries within each region based on enterprise cloud expenditure, multi-cloud adoption, AI infrastructure investments, financial governance requirements, and FinOps platform adoption
- To strategically profile leading companies and evaluate their FinOps product portfolios, optimization capabilities, geographic presence, business strategies, and competitive positioning
- To examine competitive developments, including product launches, AI-driven optimization capabilities, strategic partnerships, platform integrations, acquisitions, and geographic expansions
- To assess the impact of AI infrastructure spending, Kubernetes adoption, automated cost governance, commitment optimization, and evolving cloud pricing models on market development
Available customizations:
Based on the market data provided, customization can be tailored to specific research requirements. The following customization options can be offered for the cloud FinOps market report.
Product Analysis
-
A detailed product comparison matrix covering native and third-party FinOps solutions, financial management capabilities, commitment optimization, Kubernetes cost management, AI workload cost attribution, automation maturity, pricing structures, deployment models, and geographic availability.
Geographic Analysis Based On Feasibility
- Further breakdown of the North American cloud FinOps market
- Further breakdown of the European cloud FinOps market
- Further breakdown of the Asia Pacific cloud FinOps market
- Further breakdown of the Middle Eastern & African cloud FinOps market
- Further breakdown of the Latin American cloud FinOps market
Company Information
- Detailed analysis and profiling of additional market players (up to five)
Get the Full Cloud FinOps Market Report
Full forecast, segment splits, and company analysis for all Cloud FinOps Market.
- US Cloud FinOps Market
- Canada Cloud FinOps Market
- Germany Cloud FinOps Market
- France Cloud FinOps Market
- Italy Cloud FinOps Market
- China Cloud FinOps Market
- India Cloud FinOps Market
- Japan Cloud FinOps Market
- Saudi Arabia Cloud FinOps Market
- UAE Cloud FinOps Market
- South Africa Cloud FinOps Market
- Brazil Cloud FinOps Market
- Mexico Cloud FinOps Market
- Rest Of Europe Cloud FinOps Market
- Rest Of Apac Cloud FinOps Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report