–Rest Of GCC Monomaterial Packaging Films Market (2025-2030)
The –Rest Of GCC Monomaterial Packaging Films Market was valued at $4.3 Million in 2025 and projected to reach to $4.8 Million by 2030, representing a compound annual growth rate of CAGR 2.3%. Rest Of GCC's monomaterial packaging films market is positioned for steady expansion as regional manufacturers and brand owners increasingly prioritize sustainable packaging solutions.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
–Rest Of GCC Monomaterial Packaging Films Market Trends and Insights
- –Rest Of GCC's modest market size reflects the region's emerging demand for sustainable and cost-effective packaging solutions, driven by increasing consumer awareness and regulatory pressures toward circular economy practices.
- The growth trajectory in –Rest Of GCC remains steady but conservative compared to global benchmarks, indicating a developing market with untapped potential in food, beverage, and consumer goods sectors. –Rest Of GCC's monomaterial packaging films sector is characterized by limited local production capacity and reliance on imports from neighboring GCC nations and international suppliers.
- The region's growth is constrained by lower industrial activity and smaller manufacturing bases relative to major GCC economies, yet opportunities exist as multinational brands expand distribution networks and local enterprises adopt sustainable packaging standards.
- By 2030, –Rest Of GCC is expected to see incremental adoption of monomaterial films as cost competitiveness improves and supply chain infrastructure strengthens..
Key Market Statistics
- CAGR (2025-2030) CAGR 2.3%
- Market Size, 2025 ~USD 4.3 Million
- Forecast, 2030 ~USD 4.8 Million
- Country –Rest Of GCC
–Rest Of GCC Monomaterial Packaging Films Market Overview
Modest Market Valuation :
Rest Of GCC's monomaterial packaging films market is valued at USD 4.3 million in 2025, reflecting an emerging market with significant growth potential as regional industries adopt sustainable packaging practices.
Steady Growth Trajectory :
The market is projected to reach USD 4.8 million by 2030 with a CAGR of 2.3%, demonstrating consistent demand driven by regulatory compliance and consumer preference for environmentally responsible packaging solutions.
Sustainability-Driven Demand :
Rest Of GCC's market growth is primarily fueled by increasing consumer awareness of environmental issues and stringent regulatory pressures mandating the adoption of monomaterial packaging films over multi-layer alternatives.
Cost-Effective Solutions :
Monomaterial packaging films offer Rest Of GCC manufacturers a cost-competitive alternative to traditional multi-layer films, enabling improved profit margins while meeting sustainability and regulatory requirements in the region.
–Rest Of GCC Monomaterial Packaging Films Market Dynamics
- The 2.3% CAGR reflects a maturing market transitioning from conventional multi-layer films to single-material alternatives, driven by regulatory frameworks and consumer demand for recyclable packaging.
- Growing awareness among food, beverage, and consumer goods companies in the region is accelerating adoption rates. The forecast period through 2030 will see Rest Of GCC benefit from regional supply chain development and increased investment in recycling infrastructure.
- While growth remains modest compared to global benchmarks, the market's trajectory indicates strengthening fundamentals.
- Key drivers include compliance with emerging GCC environmental standards, cost advantages of monomaterial solutions, and rising brand commitments to circular economy principles, positioning Rest Of GCC as an emerging hub for sustainable packaging innovation..
Market Ecosystem

MONOMATERIAL PACKAGING FILMS MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Developed an all-PP recyclable laminate using a solvent-free adhesive and three key layers: an outer BOPP film, a polypropylene tie layer, and a recyclable inner BOPP sealing layer. The design solves compatibility issues of traditional multilayer laminates with PP recycling streams | Provides strong seal integrity, thermal resistance, and full compatibility with industrial PP recycling. The solution reduces environmental impact compared to multi-material laminates while maintaining barrier and print performance |
 |
Created an all-PE monomaterial laminate for mozzarella packaging that preserves barrier strength, sealing performance, and machine runnability at high speeds, while adhering to recyclability guidelines | Reduces puncture risk, improves heat seal performance, and lowers non-renewable energy use by up to 35%. Allows brands to meet retailer and regulatory recyclable-ready requirements without changing filling lines |
 |
Co-developed a mono-PE base web and lidding film for 1kg and 2kg cheese blocks to replace traditional multilayer films, improving recyclability while maintaining protection against oxygen and moisture | Enhances recyclability, delivers strong barrier and seal integrity, and maintains product shelf-life. Supports circularity goals by using a fully recyclable monomaterial structure compatible with polyolefin recycling streams |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Bulk Chemicals And Inorganics
- Corrosion Inhibitors
- Glycol Ethers
- Acetic Acid
- Acetone
- Ammonium Nitrate
- Basf se
- DOW CHEMICAL COMPANY
- Exxon Mobil Corporation
- AZELIS HOLDINGS SA
- Sinopec limited
Packaging
- Ampoules
- Gravure Process
- Rigid Packaging
- Aerosols
- Aseptic Filling and Sealing Equipment
- Amcor plc
- Essentra plc
- Berry Global Group, Inc.
- Mondi plc
- SEALED AIR CORPORATION
Key Takeaways
- –Rest Of GCC's monomaterial packaging films market is valued at USD 4.3 million in 2025 with a projected value of USD 4.8 million by 2030.
- The region exhibits a conservative 2.3% CAGR, reflecting emerging market dynamics and limited industrial infrastructure compared to larger GCC economies.
- –Rest Of GCC relies heavily on imports, presenting opportunities for regional supply chain development and local manufacturing initiatives.
- Sustainability regulations and multinational brand expansion are key drivers positioning –Rest Of GCC for gradual market growth through 2030.
Monomaterial Packaging Films Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | PP (POLYPROPYLENE) (Type) |
| Forecast Period | 2025–2030 |
| Growth Rate | CAGR of 6.7% from 2025 to 2030 |
| Largest Segment | FOOD & BEVERAGE (End-Use Industry) |
| Market Size Base Year (Billions) | ~USD 6.35 (2025) |
| Revenue Forecast (Billions) | ~USD 8.78 (2030) |
| Segments Covered | Packaging Format, Type, End-Use Industry |
–Rest Of GCC Monomaterial Packaging Films Market Report Segmentation
3 segment dimensions are covered across the global market.
By Packaging Format
- Bags
- Films & Wraps
- Other Packaging Formats
- Pouches
- Roll Stock & Sheets
- Rollstock & Sheets
By Type
- Other Types
- Pe (Polyethylene)
- Pet (Polyethylene Terephthalate)
- Pp (Polypropylene)
- Pvc (Polyvinyl Chloride)
By End-Use Industry
- Food & Beverage
- Household Products
- Other End-Use Industries
- Personal Care & Cosmetics
- Pharmaceuticals & Medical
Target Audience
- Packaging Film Manufacturers : Rest Of GCC-focused producers need regional market data to optimize production capacity, develop localized product portfolios, and identify growth opportunities in the emerging monomaterial segment.
- Brand Owners & FMCG Companies : Consumer goods and food/beverage companies operating in Rest Of GCC require market intelligence to source sustainable packaging solutions, ensure regulatory compliance, and meet corporate sustainability commitments.
- Packaging Converters & Distributors : Regional converters and distributors need Rest Of GCC-specific market forecasts to plan inventory, negotiate supplier contracts, and identify customer acquisition opportunities in the growing monomaterial segment.
- Investment & Private Equity Firms : Investors evaluating Rest Of GCC packaging opportunities require detailed market sizing and growth projections to assess investment viability, portfolio company performance, and exit potential in the region.
- Regulatory & Sustainability Consultants : Consultants advising Rest Of GCC organizations on packaging compliance and circular economy initiatives need market data to benchmark regional adoption rates and develop evidence-based sustainability strategies.
Key Companies in the –Rest Of GCC Monomaterial Packaging Films Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| AMCOR PLC | Switzerland | Public Company | Global Flexible Packaging Solutions,Global Rigid Packaging Solutions, |
| MONDI | United Kingdom | Public Company | Corrugated Packaging,Flexible Packaging,Uncoated Fine Paper, |
| TOPPAN HOLDINGS INC. | Japan | Public Company | Information & Communication (security, cards, BPO, publications),Lifestyle & Industry (packaging, containers, inks, building materials),Electronics (LCD color filters, films, photomasks, semiconductor packaging), |
| SABIC | Saudi Arabia | Public Company | Commodity polymers (PE, PP, PVC, PS, PET),Basic chemicals & intermediates (olefins, methanol, aromatics, glycols, MTBE, CO2),Specialties (NORYL, ULTEM, EXTEM, SILTEM and related compounds), |
| HUHTAMAKI | Finland | Public Company | Foodservice Packaging (beverage-to-go, food-to-go, Chinet, vending cups),Flexible Packaging (stickpacks, sachets, pouches for food, beverage, pet food, HPC, healthcare),Fiber Packaging (egg trays, cartons, fruit trays, wine separators, dairy and snack paper-based), |
| CONSTANTIA FLEXIBLES | Austria | Private Company | Consumer, Personal Care, and Home Care Packaging,Pharmaceutical Packaging,Food and Beverage (Coffee, Tea, Pet Food, Confectionery, Dairy), |
| SEALED AIR | United States | Private Company | Food segment – CRYOVAC, LIQUIBOX, trays and films,Protective segment – inflatable and foam packaging (SEALED AIR, BUBBLE WRAP, Instapak, Korrvu),Protective segment – AUTOBAG and automated bagging systems, |
| TRANSCONTINENTAL INC. | Canada | Public Company | Flexible Packaging (rollstock, pouches, films, coatings),Retail Services and Printing,Media (print and digital publishing), |
| UFLEX LIMITED | India | Public Company | Films (BOPET, BOPP, CPP, metallized, alox and special effects),Flexible packaging materials and laminates,Inks, coatings and adhesives, |
| TORAY INDUSTRIES, INC. | Japan | Public Company | Fibers and Textiles (filament, staple, nonwovens, apparel),Performance Chemicals (resins, films, fine chemicals, electronic materials),Carbon Fiber Composite Materials, |
AMCOR PLC
Amcor PLC is a Swiss packaging company founded in 1926 that operates as a public company with 77,000 employees. The company is a global leader in responsible packaging solutions across flexible and rigid packaging formats.
MONDI
Mondi is a United Kingdom-based public company founded in 2007 with 24,040 employees. The company specializes in packaging and paper products serving diverse industries worldwide.
TOPPAN HOLDINGS INC.
Toppan Holdings Inc. is a Japanese public company founded in 1900 with 54,371 employees. The company operates in printing, packaging, and related advanced technologies.
SABIC
SABIC is a Saudi Arabian public company founded in 1976 with 35,000 employees. The company is a global leader in diversified chemicals and petrochemicals.
HUHTAMAKI
Huhtamaki is a Finnish public company founded in 1920 with 17,417 employees. The company manufactures food packaging and foodservice products for global markets.
CONSTANTIA FLEXIBLES
Constantia Flexibles is an Austrian private company founded in 2009 with 9,835 employees. The company specializes in flexible packaging solutions for food, beverage, and pharmaceutical industries.
SEALED AIR
Sealed Air is a United States-based private company founded in 1960 with 16,100 employees. The company develops protective packaging and food safety solutions globally.
TRANSCONTINENTAL INC.
Transcontinental Inc. is a Canadian public company founded in 1976 with 7,600 employees. The company operates in packaging and printing services across North America.
UFLEX LIMITED
Uflex Limited is an Indian public company founded in 1983 with 7,619 employees. The company manufactures flexible packaging films and related products.
TORAY INDUSTRIES, INC.
Toray Industries, Inc. is a Japanese public company founded in 1926 with 46,294 employees. The company operates in advanced materials, chemicals, and fibers across multiple industries.
Reasons to Buy this Report
- Regional Market Sizing : Obtain precise market valuation data specific to Rest Of GCC, enabling accurate budget allocation and investment decisions for packaging film suppliers and manufacturers targeting this emerging market segment.
- Growth Trajectory Insights : Understand Rest Of GCC's 2.3% CAGR and USD 4.3M-to-USD 4.8M growth projection to identify optimal entry timing and market penetration strategies for the 2025-2030 period.
- Regulatory & Compliance Intelligence : Gain actionable insights into Rest Of GCC's regulatory pressures and sustainability mandates driving monomaterial adoption, enabling compliant product development and market positioning strategies.
- Competitive Landscape Analysis : Benchmark Rest Of GCC market dynamics against global trends (6.7% CAGR) to identify competitive advantages, differentiation opportunities, and underserved customer segments in the region.
- Strategic Planning Support : Leverage Rest Of GCC-specific forecasts and market drivers to develop targeted go-to-market strategies, partnership opportunities, and long-term business plans aligned with regional growth patterns.
Frequently asked questions
What is the current market size of monomaterial packaging films in –Rest Of GCC?
–Rest Of GCC's monomaterial packaging films market is estimated at USD 4.3 million in 2025.
What is the projected market size for –Rest Of GCC by 2030?
–Rest Of GCC's monomaterial packaging films market is forecast to reach USD 4.8 million by 2030.
What is the CAGR for monomaterial packaging films in –Rest Of GCC?
–Rest Of GCC's monomaterial packaging films market is expected to grow at a CAGR of 2.3% from 2025 to 2030.
Why is –Rest Of GCC's growth rate lower than the global average?
–Rest Of GCC has limited local manufacturing capacity, smaller industrial bases, and lower consumption volumes compared to major GCC economies, resulting in a more conservative 2.3% CAGR versus the global 6.7% CAGR.
What are the main drivers of growth in –Rest Of GCC's monomaterial packaging films market?
Key drivers in –Rest Of GCC include increasing sustainability regulations, multinational brand expansion, growing consumer awareness of eco-friendly packaging, and gradual improvements in supply chain infrastructure.
RESEARCH METHODOLOGY
The study involved four major activities to estimate the current size of the global monomaterial packaging films market. Exhaustive secondary research was conducted to gather information on the market, the peer product market, and the parent product group market. The next step was to validate these findings, assumptions, and sizes with the industry experts across the value chain of monomaterial packaging films through primary research. The top-down and bottom-up approaches were employed to estimate the overall size of the monomaterial packaging films market. Following this, market breakdown and data triangulation procedures were employed to determine the size of various market segments.
Secondary Research
The market for companies offering monomaterial packaging films was determined by analyzing secondary data from paid and unpaid sources, examining the product portfolios of major companies in the ecosystem, and evaluating companies based on their performance and quality. Various secondary sources, including Business Standard, Bloomberg, the World Bank, and Factiva, were consulted to identify and collect information for this study on the monomaterial packaging films market. During the secondary research process, various secondary sources were consulted to identify and collect information relevant to the study. Secondary sources included annual reports, press releases, investor presentations, monomaterial packaging film vendors, forums, certified publications, and white papers. The secondary research was utilized to gather critical information on the industry’s value chain, the total pool of key players, market classification, and segmentation from both market- and technology-oriented perspectives.
Primary Research
In the primary research process, various primary sources from both the supply and demand sides were interviewed to obtain qualitative and quantitative information for this report. The primary sources from the supply side included industry experts, such as chief executive officers (CEOs), vice presidents (VPs), marketing directors, technology and innovation directors, and related key executives from several key companies and organizations operating in the monomaterial packaging films market. After the complete market engineering (calculations for market statistics, market breakdown, market size estimations, market forecasting, and data triangulation), extensive primary research was conducted to gather information and verify and validate the critical numbers arrived at. Primary research was also conducted to identify the segmentation types, industry trends, and competitive landscape of monomaterial packaging films offered by various market players, as well as key market dynamics, including drivers, restraints, opportunities, challenges, industry trends, and key player strategies. In the complete market engineering process, the top-down and bottom-up approaches and several data triangulation methods were extensively used to perform the market estimation and market forecasting for the overall market segments and subsegments listed in this report. Extensive qualitative and quantitative analysis was performed on the complete market engineering process to list the key information/insights throughout the report.
The following is the breakdown of primary respondents:
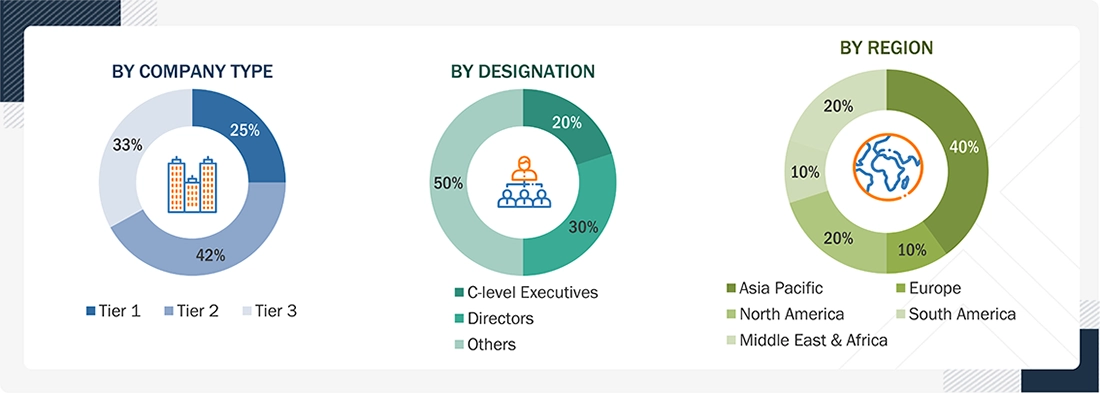
Notes: Other designations include sales, marketing, and product managers.
Tier 1: >USD 1 Billion; Tier 2: USD 500 million–1 Billion; and Tier 3: <USD 500 million
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
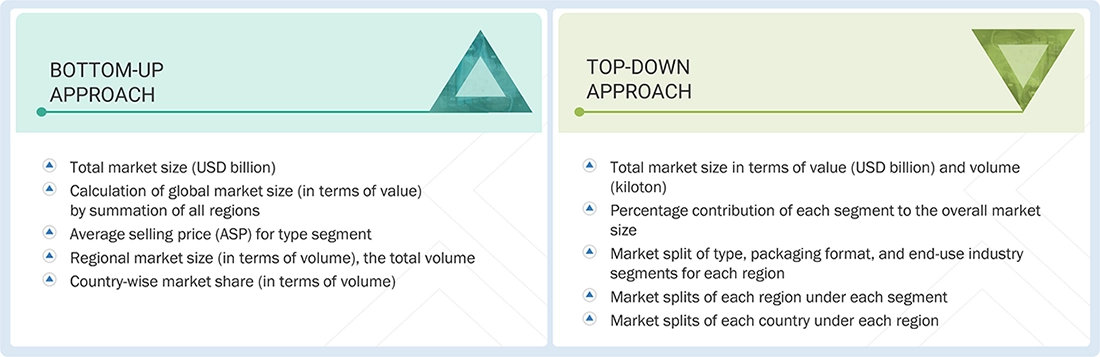
The top-down and bottom-up approaches were used to estimate and validate the size of the global monomaterial packaging films market. These approaches were also used extensively to estimate the size of various dependent market segments. The research methodology used to estimate the market size included the following.
Data Triangulation
After arriving at the overall market size using the market size estimation processes, the market was split into several segments and subsegments. The data triangulation and market breakup procedures were employed, wherever applicable, to complete the overall market engineering process and arrive at the exact statistics of each market segment and subsegment. The data was triangulated by studying various factors and trends from both the demand and supply sides.
Market Definition
Monomaterial packaging film refers to a flexible packaging structure made primarily from a single type of polymer, such as polyethylene (PE), polypropylene (PP), or polyethylene terephthalate (PET), rather than multiple laminated layers of different materials. By using one polymer family, these films offer improved compatibility with existing recycling systems, enabling higher-quality material recovery and supporting circular economy goals. Monomaterial films can be engineered to deliver the required performance attributes, such as barrier protection, sealing strength, clarity, and printability, through advanced coatings and polymer modifications. Their simplified structure reduces environmental impact, lowers production complexity, and helps brands meet increasingly stringent sustainability and recyclability requirements.
Key Stakeholders
- Raw Material Suppliers
- Regulatory Bodies
- Government and Consulting Firms
- End Users
- Research and Development Organizations
- Monomaterial Packaging Film Manufacturers, Dealers, Traders, and Suppliers
Report Objectives
- To define, describe, and forecast the size of the global monomaterial packaging film market based on type, packaging format, end-use industry, and region in terms of value and volume
- To provide detailed information on the significant drivers, restraints, opportunities, and challenges influencing the market
- To analyze and forecast the market based on type, packaging format, and end-use industry
- To strategically analyze micromarkets concerning individual growth trends, prospects, and their contribution to the market
- To assess the growth opportunities in the market for stakeholders and provide details on the competitive landscape for market leaders
- To forecast the market size of segments for North America, Europe, Asia Pacific, South America, and the Middle East & Africa
- To strategically profile key players and comprehensively analyze their market shares and core competencies
- To analyze competitive developments such as product launches, expansions, partnerships, and acquisitions in the monomaterial packaging films market
- To provide the impact of AI on the market.
Available customizations:
With the given market data, MarketsandMarkets offers customizations according to client-specific needs.
The following customization options are available for the monomaterial packaging film report:
Product Analysis
- A product matrix that gives a detailed comparison of the product portfolio of each company
Regional Analysis
- A further breakdown of the monomaterial packaging film market for additional countries
Company Information
- Detailed analysis and profiling of additional market players (up to five)
Get the Full Monomaterial Packaging Films Market Report
Full forecast, segment splits, and company analysis for all Monomaterial Packaging Films Market.
- Rest Of Asia Pacific Monomaterial Packaging Films Market
- GCC Countries Monomaterial Packaging Films Market
- Rest Of Mea Monomaterial Packaging Films Market
- Rest Of South America Monomaterial Packaging Films Market
- US Monomaterial Packaging Films Market
- Canada Monomaterial Packaging Films Market
- Mexico Monomaterial Packaging Films Market
- Germany Monomaterial Packaging Films Market
- UK Monomaterial Packaging Films Market
- France Monomaterial Packaging Films Market
- Russia Monomaterial Packaging Films Market
- Spain Monomaterial Packaging Films Market
- Italy Monomaterial Packaging Films Market
- China Monomaterial Packaging Films Market
- India Monomaterial Packaging Films Market
- Japan Monomaterial Packaging Films Market
- South Korea Monomaterial Packaging Films Market
- Indonesia Monomaterial Packaging Films Market
- South Africa Monomaterial Packaging Films Market
- Turkey Monomaterial Packaging Films Market
- Brazil Monomaterial Packaging Films Market
- Argentina Monomaterial Packaging Films Market
- Rest Of Europe Monomaterial Packaging Films Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report