Australia Observability Tools & Platforms Market (2026-2031)

The Australia Observability Tools & Platforms Market was valued at $232.4 Million in 2026 and projected to reach to $441.5 Million by 2031, representing a compound annual growth rate of 13.7%. Australia's observability tools and platforms market is positioned for sustained growth as enterprises increasingly prioritize system visibility and performance optimization.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Australia Observability Tools & Platforms Market Trends and Insights
- This expansion reflects Australia's increasing digital transformation initiatives and the growing complexity of cloud-native architectures across enterprises.
- Australia's market growth rate of 13.7% CAGR demonstrates strong demand for real-time monitoring, analytics, and operational intelligence solutions among Australian organizations. The observability market in Australia is driven by heightened adoption of microservices, containerization, and distributed systems across financial services, telecommunications, and technology sectors.
- Australia's enterprises are investing heavily in observability platforms to enhance system reliability, reduce downtime, and improve customer experience.
- Between 2026 and 2031, Australia is expected to see accelerated vendor competition and innovation, with both established players and emerging startups targeting the region's growing need for comprehensive monitoring and observability capabilities..
Key Market Statistics
- CAGR (2026-2031) 13.7% CAGR
- Market Size, 2026 ~USD 232.4 Million
- Forecast, 2031 ~USD 441.5 Million
- Country Australia
Australia Observability Tools & Platforms Market Overview
Market Valuation Growth :
Australia's observability tools market is valued at USD 232.4 million in 2026 and is projected to grow to USD 441.5 million by 2031, representing a 90% increase over the five-year forecast period.
Strong CAGR Performance :
Australia's market is growing at 13.7% CAGR, slightly below the global average of 14.1%, indicating steady and sustainable expansion driven by local digital transformation initiatives.
Cloud-Native Adoption :
Increasing complexity of cloud-native architectures across Australian enterprises is driving demand for advanced observability solutions to monitor distributed systems and microservices environments.
Digital Transformation Catalyst :
Australia's robust digital transformation initiatives across financial services, healthcare, and government sectors are accelerating the adoption of observability platforms for enhanced system visibility and performance management.
Australia Observability Tools & Platforms Market Dynamics
- The shift toward cloud-native architectures and containerized deployments is creating strong demand for comprehensive monitoring and observability solutions across Australian organizations.
- Financial services, healthcare, and technology sectors are leading adoption, with enterprises investing in tools to manage complex distributed systems and ensure operational excellence. The market outlook remains positive through 2031, supported by growing awareness of observability's business value, increasing regulatory compliance requirements, and the need for real-time insights into application performance.
- Australian organizations are recognizing observability as critical infrastructure for digital transformation, driving investment in integrated platforms that combine metrics, logs, and traces for holistic system understanding..
Market Ecosystem
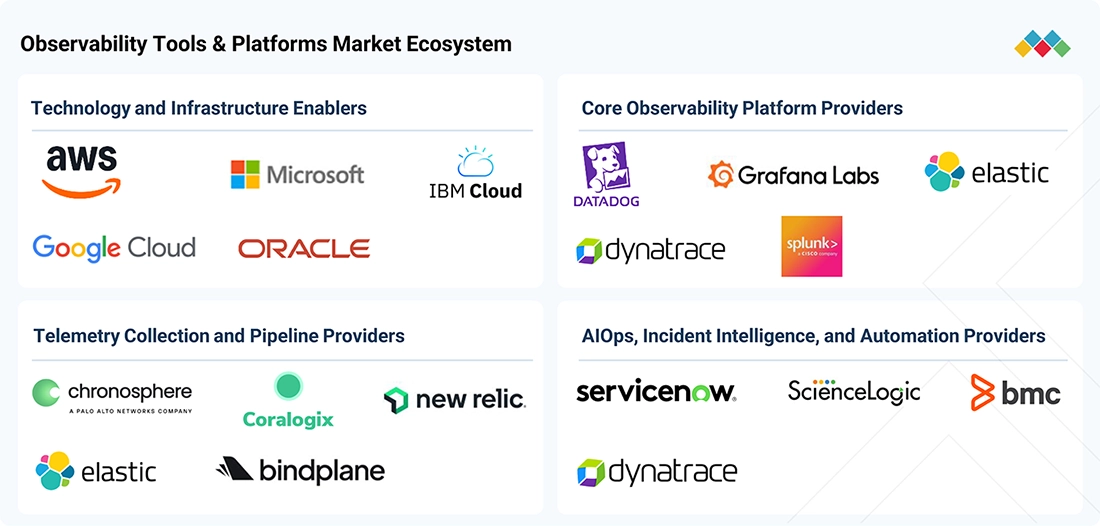
OBSERVABILITY TOOLS AND PLATFORMS MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Dynatrace Enabled National Grid To Modernize Observability Across Its Hybrid Multicloud Environment | Reduced observability TCO by 18% | Improved MTTR by more than 50% | Completed SaaS migration within six months | Enabled secure, real-time collaboration with vendors and partners |
 |
Elastic Enabled Comcast To Unify Observability Across Its Complex Technology Infrastructure | Processes around 400 TB of telemetry daily | Supports more than 50,000 software builds each day | Enables earlier issue detection and faster engineering feedback | Reduces observability ownership costs |
 |
Datadog Enabled Forbes To Improve Cloud Performance And Digital Experience Reliability | Reduced cloud spending by 2–3% through workload right-sizing | Maintained more than 99.5% uptime | Improved root-cause analysis time by 10% | Strengthened visibility and collaboration across engineering teams |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Software And Services
- Natural Language Processing (NLP)
- Machine Learning
- Supply Chain Management
- Predictive Analytics
- Image Sensors
- International Business Machines Corporation
- MICROSOFT CORPORATION
- Oracle Corporation
- SAP SE
- Amazon.com, Inc.
Key Takeaways
- Australia's observability market will nearly double from USD 232.4M (2026) to USD 441.5M (2031), representing a 13.7% CAGR.
- Australia's financial services and telecommunications sectors are primary drivers of observability platform adoption and investment.
- Australia's enterprises are prioritizing real-time monitoring and analytics to support cloud-native and distributed system architectures.
- Australia's market is attracting both global vendors and regional players, intensifying competition and accelerating innovation through 2031.
Observability Tools & Platforms Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2026 |
| Fastest Growing Segment | AIOPS & INCIDENT INTELLIGENCE (Solution) |
| Forecast Period | 2026-2031 |
| Growth Rate | CAGR of 14.1% from 2026 to 2031 |
| Largest Segment | SOLUTIONS (Offering) |
| Market Size Base Year (Billions) | ~USD 11.89 (2026) |
| Revenue Forecast (Billions) | ~USD 22.99 (2031) |
| Segments Covered | Offering, Solution, Service, Telemetry Type, Deployment Mode, Organization Size, Vertical |
Australia Observability Tools & Platforms Market Report Segmentation
7 segment dimensions are covered across the global market.
By Offering
- Services
- Solutions
By Solution
- Aiops & Incident Intelligence
- Application Performance Monitoring (Apm)
- Distributed Tracing
- Infrastructure Observability
- Log Management & Analytics
- Other Solutions
By Service
- Managed Services
- Professional Services
By Telemetry Type
- Logs
- Metrics
- Other Telemetry Types
By Deployment Mode
- Hybrid
- SaaS/Cloud-Hosted
- Self-Managed (On-Premises)
By Organization Size
- Large Enterprises
- Smes
By Vertical
- Bfsi
- Energy & Utilities
- Government & Public Sector
- Healthcare & Life Sciences
- It & Ites
- Manufacturing
- Media & Entertainment
- Other Vertical
- Other Verticals
- Retail & Ecommerce
- Telecommunications
- Transportation & Logistics
Target Audience
- Enterprise IT Leaders : CIOs and IT directors in Australia need market data to justify observability investments, understand competitive offerings, and align technology strategies with organizational digital transformation goals.
- Software & SaaS Vendors : Observability platform providers require Australia-specific market insights to develop localized go-to-market strategies, identify customer segments, and forecast revenue potential in the region.
- Management Consultants : Consulting firms advising Australian enterprises on digital transformation need credible market data to support recommendations for observability tool adoption and vendor selection.
- Investment & Private Equity Firms : Investors evaluating opportunities in Australian tech infrastructure need market sizing, growth forecasts, and trend analysis to assess investment viability and portfolio company potential.
- System Integrators & Resellers : Australian systems integrators and technology resellers need market intelligence to identify growth opportunities, develop service offerings, and position observability solutions to enterprise clients.
Reasons to Buy this Report
- Localized Market Intelligence : Gain Australia-specific insights into market size, growth trajectories, and regional dynamics that differ from global trends, enabling informed strategic decisions tailored to the local market.
- Competitive Positioning Strategy : Understand the Australian competitive landscape, identify key market players, and benchmark your offerings against local and international competitors operating in the region.
- Investment & Expansion Planning : Access detailed forecasts through 2031 to support investment decisions, market entry strategies, and resource allocation for Australian operations and expansion initiatives.
- Sector-Specific Opportunities : Identify high-growth segments within Australia's financial services, healthcare, and technology sectors where observability adoption is accelerating and demand is strongest.
- Risk Mitigation & Compliance : Understand regulatory drivers and compliance requirements specific to Australia that are influencing observability adoption, helping you align solutions with local market demands.
Frequently asked questions
What is the current size of Australia's observability tools market?
Australia's observability tools and platforms market is valued at USD 232.4 million in 2026 and is expected to grow to USD 441.5 million by 2031.
What is the projected growth rate for Australia's observability market?
Australia's observability market is projected to grow at a compound annual growth rate (CAGR) of 13.7% from 2026 to 2031.
Which industries in Australia are driving observability platform adoption?
Australia's financial services, telecommunications, and technology sectors are the primary drivers of observability platform adoption and investment.
What factors are contributing to growth in Australia's observability market?
Australia's market growth is driven by digital transformation initiatives, adoption of microservices and containerization, and the need for enhanced system reliability and real-time monitoring capabilities.
How competitive is Australia's observability tools market?
Australia's observability market is becoming increasingly competitive, with both established global vendors and emerging regional players competing for market share through innovation and localized solutions.
RESEARCH METHODOLOGY
This research study on the observability tools & platforms market involved extensive secondary and primary research. Secondary sources included company annual reports, SEC filings, investor presentations, product documentation, press releases, white papers, technology journals, government publications, cloud adoption databases, CNCF resources, OpenTelemetry documentation, and paid databases. Primary sources included industry experts from observability software vendors, cloud service providers, managed service providers, system integrators, consulting organizations, enterprise users, and related technology companies. In-depth interviews with market participants and subject-matter experts were conducted to gather and validate critical qualitative and quantitative information and assess the market’s growth prospects.
Secondary Research
During the secondary research process, multiple sources were reviewed to identify and collect information relevant to the study. These sources included annual reports, regulatory filings, investor presentations, earnings transcripts, press releases, product portfolios, acquisition announcements, pricing pages, and technology documentation from observability vendors. Additional information was gathered from recognized journals, industry associations, cloud provider publications, CNCF resources, OpenTelemetry materials, government websites, technical blogs, and certified publications. Data relating to cloud spending, application modernization, Kubernetes adoption, DevOps maturity, telemetry generation, artificial intelligence adoption, and observability software expenditure across major countries was also extracted from relevant secondary sources.
Primary Research
During the primary research process, respondents from the supply and demand sides were interviewed to obtain qualitative and quantitative information about the market. Supply-side participants included chief executive officers, vice presidents, directors, product managers, engineering leaders, business development executives, marketing executives, and observability specialists. Interviews also covered executives from observability platform vendors, hyperscalers, managed service providers, system integrators, professional service providers, telemetry pipeline providers, cloud consulting firms, industry associations, and other key opinion leaders. Demand-side participants included CIOs, CTOs, application owners, DevOps leaders, Site Reliability Engineering teams, platform engineering teams, cloud operations teams, security operations teams, and enterprise IT decision-makers.
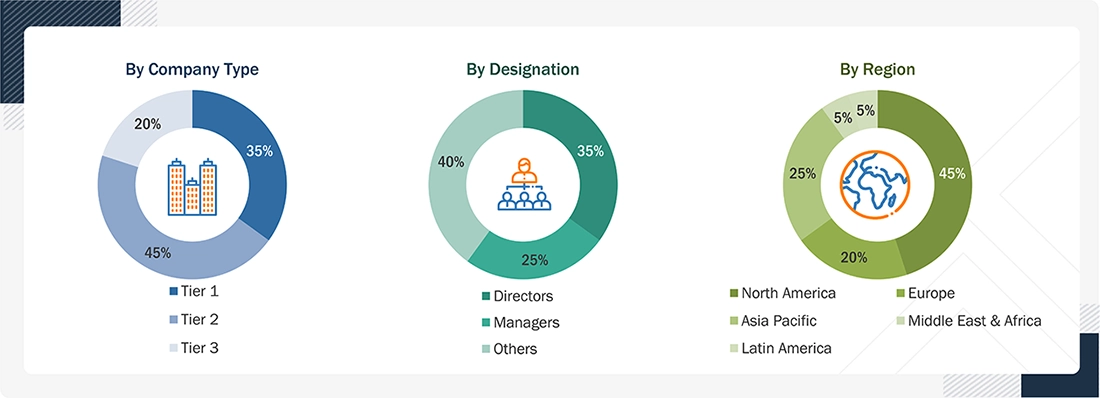
Note: Tier 1 companies’ revenues are more than USD 1 billion; tier 2 companies’ revenues range between USD 500 million and 100 million; and tier 3 companies’ revenues range between USD 10 million and USD 100 million. Other designations include sales, marketing, engineering, product, operations, and research managers.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
Multiple approaches were used to estimate and forecast the observability tools & platforms market. The first approach involved estimating the market size based on revenues generated by companies from observability software products, related platform capabilities, and associated services. Vendor revenues were allocated across relevant market segments based on product functionality, deployment models, customer profiles, vertical exposure, telemetry coverage, and regional presence. The estimates were then validated using adoption indicators, enterprise technology spending, cloud infrastructure growth, telemetry volumes, customer deployments, product pricing, and primary interviews.
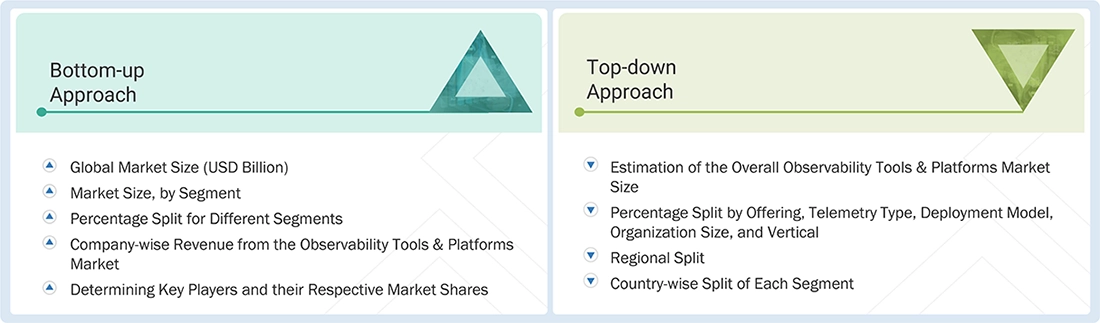
Market Size Estimation Methodology: Top-down Approach
The top-down approach involved preparing an exhaustive list of vendors offering observability platforms, monitoring tools, telemetry management capabilities, and related services. Vendor revenue contributions were estimated using annual reports, regulatory filings, investor presentations, press releases, funding information, acquisition disclosures, paid databases, product pricing, customer references, and primary interviews. Each vendor’s offerings were evaluated across offering, solution, telemetry type, deployment model, organization size, vertical, and region. The market estimates were triangulated through secondary and primary research. Primary validation included interviews with CIOs, CTOs, vice presidents, directors, engineering leaders, product executives, and marketing professionals. The resulting market estimates were further cross-validated against the existing MarketsandMarkets repository and related ICT market databases.
Market Size Estimation Methodology: Bottom-up Approach
The bottom-up approach assessed the adoption of observability platforms across major verticals and countries contributing significantly to the market. Enterprise deployments were evaluated across application performance monitoring, infrastructure observability, log management, distributed tracing, digital experience monitoring, AIOps, incident intelligence, and AI observability use cases. Adoption levels across large enterprises and SMEs were estimated and extrapolated using cloud maturity, application complexity, telemetry volumes, monitored hosts, containers, services, users, and digital workloads.
Regional splits were determined through primary and secondary sources. The process included analysis of regional observability penetration, cloud infrastructure spending, enterprise software expenditure, DevOps adoption, Kubernetes deployment, OpenTelemetry usage, cybersecurity investment, and application modernization activity. Strategic analysis of major global and regional observability vendors, together with their organic and inorganic developments, was also incorporated into the market estimates.
Data Triangulation
After determining the overall market size using the top-down and bottom-up estimation processes, the market was divided into segments and subsegments. Data triangulation and market breakup procedures were applied to validate each market segment and subsegment. Vendor revenues, customer adoption patterns, deployment models, telemetry coverage, regional indicators, pricing structures, and primary interview findings were compared to identify inconsistencies. The final market size was then used to estimate individual segments by applying validated percentage splits across the market segmentation. The resulting figures were cross-checked against supply-side revenues, demand-side adoption indicators, technology spending, and regional economic conditions.
Market Definition
The observability tools & platforms market comprises software solutions and associated services that enable organizations to collect, process, correlate, visualize, and analyze telemetry generated across applications, infrastructure, networks, databases, cloud platforms, containers, Kubernetes environments, digital experiences, and artificial intelligence workloads. These platforms ingest and analyze metrics, logs, traces, events, and profiles to provide visibility into system performance, service dependencies, application behavior, infrastructure health, user experience, and operational incidents.
Observability platforms include capabilities such as application performance monitoring, infrastructure observability, log management and analytics, distributed tracing, digital experience monitoring, AIOps, incident intelligence, service-level monitoring, telemetry pipelines, anomaly detection, root-cause analysis, workflow automation, and AI/LLM observability. The market includes SaaS/cloud-hosted, self-managed, and hybrid deployment models and supports enterprises operating cloud-native, multi-cloud, hybrid-cloud, on-premises, and edge environments.
Key Stakeholders
- Observability platform providers
- Application performance monitoring providers
- Infrastructure monitoring and observability vendors
- Log management and analytics providers
- Distributed tracing solution providers
- Digital experience monitoring providers
- AIOps and incident intelligence platform providers
- AI and LLM observability providers
- Telemetry pipeline and OpenTelemetry solution providers
- Cloud infrastructure providers and hyperscalers
- Kubernetes, container, network, and database monitoring providers
- Managed observability service providers and system integrators
- Cloud consulting and professional service providers
- DevOps, Site Reliability Engineering, and platform engineering teams
- Enterprise software and IT operations management vendors
- Large enterprises, SMEs, and digital-native businesses
Report Objectives
- To define and describe the observability tools & platforms market by offering, solution, telemetry type, deployment model, organization size, vertical, and region
- To provide detailed information on major factors influencing market growth, including drivers, restraints, opportunities, and challenges across the observability ecosystem
- To strategically analyze micro-markets with respect to individual growth trends, adoption patterns, and their contribution to the overall observability tools & platforms market
- To analyze market opportunities for stakeholders and present the competitive landscape of observability platform vendors, hyperscalers, enterprise software providers, and service providers
- To project the market size and its submarkets in terms of value across North America, Europe, Asia Pacific, the Middle East & Africa, and Latin America
- To analyze major countries within each region based on cloud adoption, enterprise IT spending, digital maturity, telemetry volumes, and observability deployment
- To strategically profile leading companies and evaluate their product portfolios, platform capabilities, geographic presence, growth strategies, and market positioning
- To examine competitive developments, including product launches, platform enhancements, partnerships, integrations, acquisitions, funding activities, and regional expansions
- To assess the impact of OpenTelemetry, artificial intelligence, cloud-native applications, Kubernetes, microservices, DevOps, and Site Reliability Engineering on market development
- To analyze market adoption across application performance monitoring, infrastructure observability, log management, distributed tracing, digital experience monitoring, AIOps, and AI observability
- To evaluate the market by telemetry type, including logs, metrics, and others comprising traces, events, and profiles
- To assess deployment trends across SaaS/cloud-hosted, self-managed, and hybrid environments
- To identify high-growth segments, emerging use cases, and evolving technology requirements across the observability tools & platforms market
Available customizations:
With the given market data, MarketsandMarkets offers customizations as per the company’s specific needs. The following customization options are available for the report:
Product Analysis
- The product matrix provides a detailed comparison of the product portfolios, platform capabilities, deployment models, telemetry coverage, and integrations of each company.
Geographic Analysis based on feasibility
- Further breakup of the North American observability tools & platforms market
- Further breakup of the European observability tools & platforms market
- Further breakup of the Asia Pacific observability tools & platforms market
- Further breakup of the Middle East & African observability tools & platforms market
- Further breakup of the Latin American observability tools & platforms market
Company Information
- Detailed analysis and profiling of additional market players (up to five)
Get the Full Observability Tools & Platforms Market Report
Full forecast, segment splits, and company analysis for all Observability Tools & Platforms Market.
- Rest Of Latin America Observability Tools & Platforms Market
- GCC Countries Observability Tools & Platforms Market
- Rest Of GCC Countries Observability Tools & Platforms Market
- US Observability Tools & Platforms Market
- Canada Observability Tools & Platforms Market
- UK Observability Tools & Platforms Market
- Germany Observability Tools & Platforms Market
- France Observability Tools & Platforms Market
- Italy Observability Tools & Platforms Market
- China Observability Tools & Platforms Market
- Japan Observability Tools & Platforms Market
- India Observability Tools & Platforms Market
- Saudi Arabia Observability Tools & Platforms Market
- UAE Observability Tools & Platforms Market
- South Africa Observability Tools & Platforms Market
- Brazil Observability Tools & Platforms Market
- Mexico Observability Tools & Platforms Market
- Rest Of Europe Observability Tools & Platforms Market
- Rest Of Asia Pacific Observability Tools & Platforms Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
