Medical Polymer Market by Type (Medical Plastics, Medical Elastomers), Application (Medical Disposables, Medical Instruments and Devices, Prosthetics, Diagnostics Instruments and Tools), Manufacturing Technology, and Region - Global Forecast to 2031

icon1
USD 71.92 BN
MARKET SIZE, 2031
icon2
CAGR 8.3%
(2026-2031)
icon3
270
REPORT PAGES
icon4
260
MARKET TABLES

OVERVIEW

medical-polymer-market Overview

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

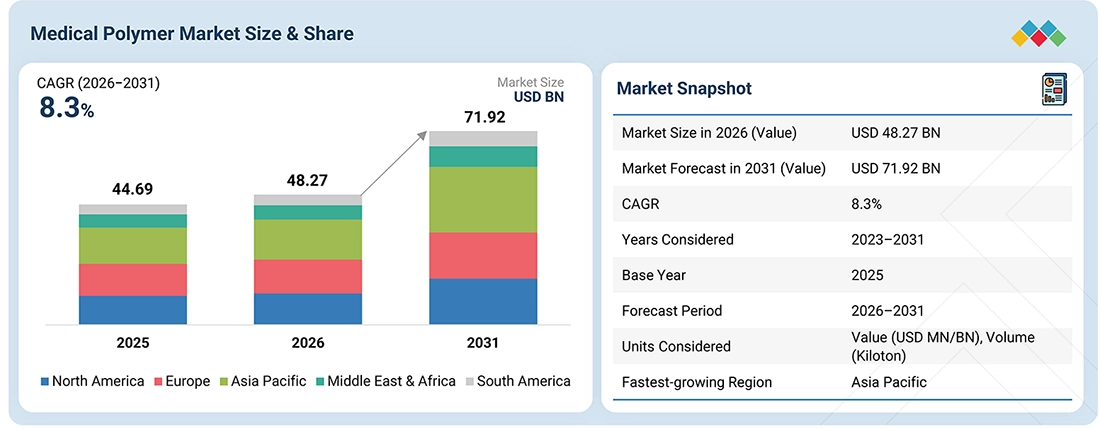
The medical polymer market is estimated to reach USD 71.92 billion by 2031 from USD 48.27 billion in 2026, registering a CAGR of 8.3% during the forecast period. Many factors contribute to the medical polymer market's growth, reflecting advances in healthcare, technology, material science and patient needs. One of the most prominent is the rising demand for lightweight, durable, and biocompatible materials for devices like catheters, implants, surgical instruments and diagnostic devices. As healthcare continues to expand globally, particularly in developing regions, demand is increasing for high-performance materials that do not sacrifice cost. An aging population and rising chronic health issues are driving demand for long-term, implantable solutions and specialized polymer approaches.

KEY TAKEAWAYS

  • By Region
    By region, Asia Pacific accounted for 30.3% of the medical polymer market in 2025, supported by expanding healthcare infrastructure, growing medical device manufacturing, rising healthcare expenditure, and rising demand for medical devices and healthcare products across China, India, Japan, and South Korea.
  • By Manufacturing Technology
    By manufacturing technology, the extrusion tubing segment is estimated to grow at a CAGR of 8.5% between 2026 and 2031, supported by its ability to produce continuous, precise, and dimensionally consistent polymer components. Increasing demand for medical tubing in catheters, fluid management systems, drug delivery devices, and other minimally invasive applications is contributing to segment growth.
  • By Type
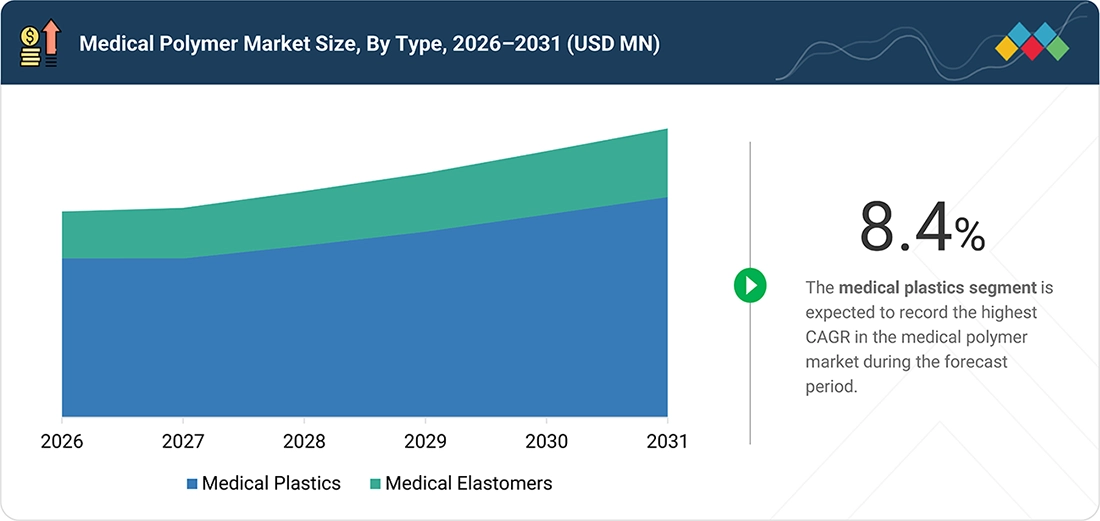
    By type, the medical Plastics segment is estimated to grow at a CAGR of 8.4% between 2026 and 2031, owing to their lightweight nature, durability, chemical resistance, flexibility, and suitability for sterilization. Their increasing use in medical instruments, devices, packaging, consumables, and other healthcare applications is supporting demand.
  • By Application
    By application, the medical instruments & devices segment is anticipated to record a CAGR of 8.9% during the forecast period, driven by the increasing use of medical polymers in surgical instruments, diagnostic devices, drug delivery systems, catheters, and other healthcare equipment. Growing adoption of minimally invasive procedures and increasing demand for lightweight, durable, and biocompatible components are further supporting segment growth.
  • Competitive Landscape - Key Players
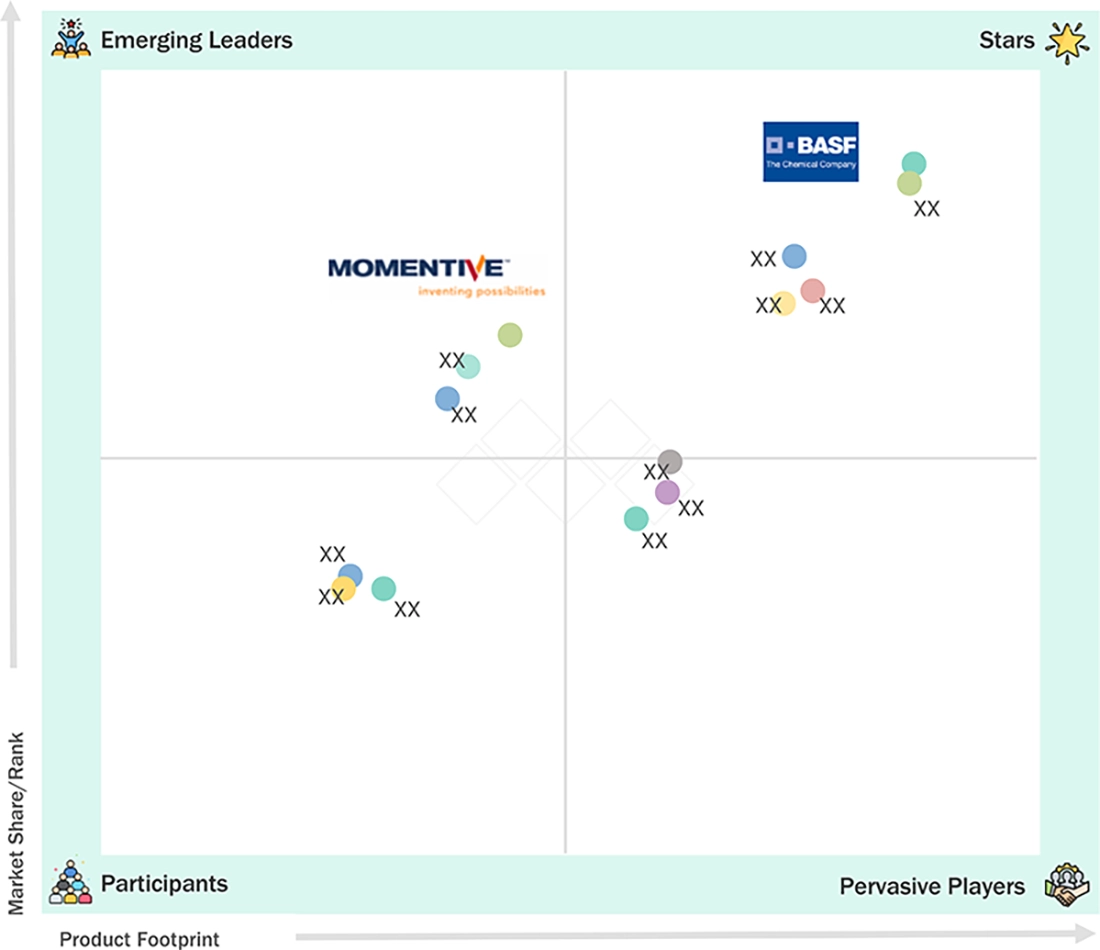
    BASF SE (Germany), SABIC (Saudi Arabia), and Covestro AG (Germany) were identified as key players in the medical polymer market, given their strong market share and product footprint.
  • Competitive Landscape - Startups/SMEs
    Trinseo, Kraton Corporation, and Mitsubishi Chemical Advanced Materials , among others, have distinguished themselves among startups and SMEs by securing strong footholds in specialized niche areas, underscoring their potential as emerging market leaders.

The global medical polymer market is growing due to increasing demand for advanced medical devices, minimally invasive procedures, drug delivery systems, medical consumables, and biocompatible and high-performance polymer materials. The market in Asia Pacific is supported by expanding healthcare infrastructure, increasing medical device manufacturing, rising healthcare expenditure, growing patient populations, and investments in pharmaceutical and healthcare manufacturing across China, India, Japan, South Korea, and Southeast Asia. In Europe, the market is supported by established healthcare systems, stringent medical device regulations, increasing demand for advanced medical technologies, and the adoption of specialty and high-performance polymers in medical applications. North America is witnessing steady growth, supported by technological advancements in medical devices, adoption of minimally invasive and implantable devices, demand for high-performance medical materials, and investments in healthcare and medical device manufacturing. Meanwhile, South America and the Middle East & Africa are experiencing gradual market development, supported by improving healthcare infrastructure, increasing healthcare expenditure, expanding access to medical devices and healthcare products, and investments in healthcare and medical manufacturing capabilities.

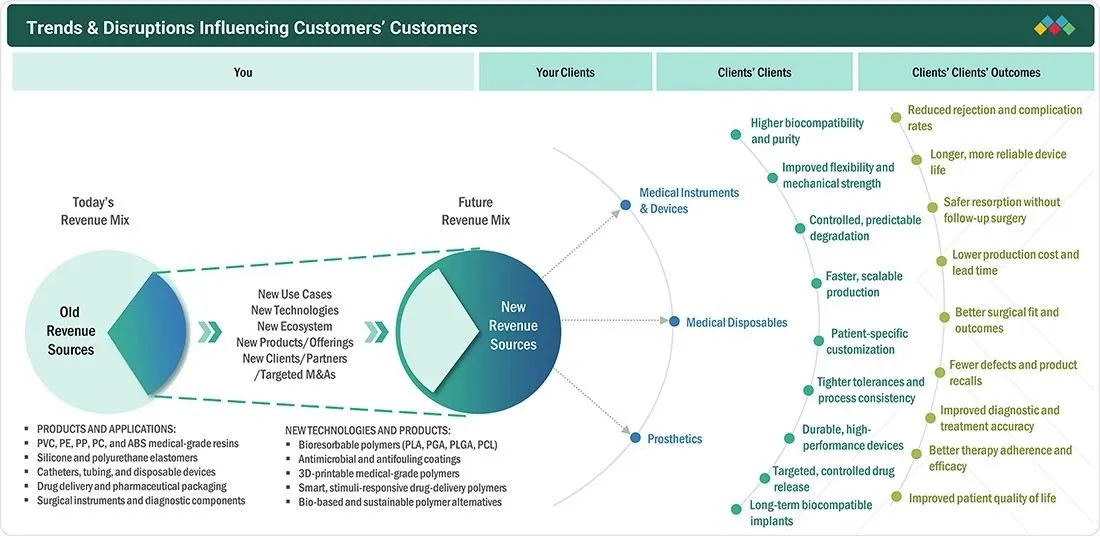
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS

Growing demand for minimally invasive procedures, advanced medical devices, drug delivery systems, and single-use healthcare products is driving significant advancements in medical polymer technologies across medical instruments and devices, healthcare packaging, drug delivery, surgical applications, and other healthcare applications. Greater emphasis is being placed on biocompatibility, sterilizability, lightweight materials, chemical resistance, durability, and improved patient safety. The transition from conventional materials toward advanced thermoplastics, elastomers, biodegradable polymers, and high-performance specialty polymers with enhanced mechanical properties, processing efficiency, sterilization resistance, and application-specific performance is influencing the competitive landscape. Increasing demand for customized material solutions and medical-grade polymer formulations is also encouraging manufacturers to invest in advanced processing technologies, material development, and application-specific solutions.

medical-polymer-market Disruptions

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

MARKET DYNAMICS

Drivers
Impact
Level
  • Increasing demand for biocompatible materials
  • Surge in global aging population
RESTRAINTS
Impact
Level
  • Environmental sustainability concerns
  • Regulatory complexities and approvals
OPPORTUNITIES
Impact
Level
  • Demand for minimally invasive devices
  • Growth in regenerative medicine
CHALLENGES
Impact
Level
  • Long term durability and degradation control
  • Cost constraints for novel materials

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Driver: Increasing demand for biocompatible materials

The growing need for biocompatible materials is a major driver of the medical polymer market. Biocompatible materials are compatible with living tissues and organisms and do not cause adverse effects, such as inflammation and rejection. The healthcare industry now demands biocompatible materials in medical devices, implants, and drug delivery systems. Patients and medical professionals pay close attention to materials that are compatible with the human body, their potential to cause complications, and the efficiency of the treatment. The increase in demand is partly due to the increase in chronic diseases and age-related illnesses across the globe. The demand for medical devices and implants is met with biocompatible materials that are functional, durable, and compatible with biological systems, driven by rising incidences of diseases like orthopedic injury, diabetes, and cardiovascular disease. Biocompatible polymers such as polylactic acid (PLA), polyethylene glycol (PEG), and polyvinyl alcohol (PVA) have been approved because of their low toxicity, biocompatibility, and ability to emulate natural tissues. Also, with material science and polymer engineering ongoing advancing, biocompatible polymers are becoming increasingly advanced and have mutable properties, such as better mechanical strength, controlled degradation rates, and saturation levels.

Restraint: Environmental sustainability concerns

Concerns about environmental sustainability are a major constraint in the medical polymer market, affecting all phases of the life cycle of polymer-based medical products, including creation, use, and disposal. Growing awareness of environmental stewardship, resource conservation and waste has drawn more attention to the environmental impact of medical polymers. A major concern for environmentally sustainable sourcing is the reliance on petroleum-based polymers such as polyethylene, polypropylene, and PVC, which are non-biodegradable and contribute to plastic pollution. These polymers all derive from fossil fuel-based feedstocks. Carbon emissions, energy consumption and environmental impacts arise during the extraction and processing of these materials. Also, the disposal of medical devices and packaging ultimately associated with these polymers can result in landfill and environmental contamination. Moreover, additives, fillers and processing aids in medical polymers may also raise environmental toxicity concerns. Plasticizers, flame-retardants, and antimicrobial agents can all have environmental consequences. Regulations governing the use of 'hazardous' substances also exist, such as REACH regulations in Europe and FDA guidelines in the United States. This adds complexity to material selection and product development.

Opportunity: Demand for minimally invasive devices

The development of minimally invasive devices creates a substantial opportunity in the medical polymer market. Minimally invasive procedures typically rely on medical polymers in most of the devices used for these procedures. Another consideration for using polymers in minimally invasive devices is their relative ease of molding into complex shapes, small components, and catheter systems that fit through narrow anatomical structures. Generally, medical polymers used in catheter-based devices include polyurethane, polyethylene, and PEEK (polyether ether ketone), if permissible for patient considerations. Each medical polymer type provides low friction, high strength and compatibility with imaging technologies. Advances in polymer manufacturing technologies such as extrusion, injection molding, and additive manufacturing (3D printing) enable customization and mass production of minimally invasive devices with specific dimensions, surface textures, and functionalities. Additionally, new manufacturing technologies enable rapid prototyping, iterative design, and scaling up of device designs.

Challenge: Long term durability and degradation control

Maintaining durability and controlling degradation is a major challenge in the medical polymer space, as the performance, reliability, and safety of medical devices and implants change over time. Medical polymers are selected to withstand physiological and environmental conditions and mechanical loads while maintaining biocompatibility, molecular weight, and physical properties over a predetermined period. However, maintaining durability and controlling degradation involves multiple challenges that require proper materials selection, design optimization, and regulatory considerations. One of the most pertinent challenges in long-term durability is predicting and controlling the degradation kinetics of biodegradable polymers used in devices such as implants and drug delivery systems. Biodegradable polymers such as polylactic acid (PLA), polyglycolic acid (PGA) or their copolymers (PLGA) are highly susceptible to hydrolytic and enzymatic degradation in vivo, and once implemented in a medical device, changes in mechanical properties, degradation rates and degradation by products is an incredibly difficult challenge. Using biodegradable medical polymers requires balancing degradation rates, tissue integration, and the device's therapeutic release profile to achieve desired performance and safety outcomes. In addition to considering durability and degradation, companies need to think about long term durability past the shelf life of a product, which includes remediation, testing, validation, and market surveillance or post-marketing activities to determine material stability, degradation characteristics and biocompatibility in real-world situations over time.

MEDICAL POLYMER MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES

COMPANY USE CASE DESCRIPTION BENEFITS
company logo
BASF supplies Ultrason polyarylsulfone (PSU, PPSU, PESU) grades for healthcare applications, including respiratory devices, fluid collection containers, sterilization trays, diagnostic equipment, and orthopedic sizing components. It also offers custom-colored, USP Class V/VI and ISO 10993-compliant Ultrason grades, developed with partner Techmer PM, to remove the in-house color-blending step for device makers. High-temperature resistance | Repeated steam/EtO sterilization tolerance | Custom-colorable, biocompatible grades reduce development cycles | Transparency retained after repeated sterilization | Chemical resistance exceeding polyamide/PC/POM/PBT
company logo
SABIC's LNP portfolio (ELCRES/ELCRIN CRX copolymers, EXL copolymers, LUBRILOY, SLX, ULTEM HU, SILTEM HU) serves device housings, insulin pumps, diagnostic imaging equipment, drug-delivery autoinjectors, surgical robot components, and medical tubing. The company backs this with a Healthcare Product Policy, management-of-change processes, and Centers of Excellence for OEM co-development. High chemical resistance to aggressive disinfectants | Thin-wall, miniaturized device design enablement | Non-PFAS/non-fluorine compliant options | Biocompatible per ISO 10993 | Reduced carbon footprint on bio-based grades
company logo
Covestro provides Makrolon and Makroblend polycarbonate resins, Baymedix polyurethane adhesives/foams, Platilon TPU films, and Texin Rx TPU resins for drug-delivery devices, IV/luer components, on-body devices, wound care, and surgical instruments. It supports customers with design and material-selection guidance through final regulatory approval. Biocompatibility per ISO 10993-1/USP Class IV | Gamma/e-Beam/ETO sterilization compatibility | High-flow grades for thin-wall, intricate designs | Chemical and oncology-drug resistance to prevent cracking | Renewable-content grades lower carbon footprint
company logo
Celanese supplies Hostaform/Celcon POM, Zytel nylon, GUR UHMW-PE, VitalDose EVA, and Vectra LCP for drug-delivery devices (inhalers, insulin pens, auto-injectors), orthopedic implants (hips/knees), and ventilator/respirator components. Its Hostaform MT SlideX grade is formulated specifically for low-friction mechanical drug-delivery devices. Low friction/wear for patient comfort in wearables | Gold-standard biocompatibility for load-bearing implants | Vitamin E-stabilized grades resist implant oxidation | High impact and dimensional stability | Expanded portfolio via 2022 DuPont M&M acquisition

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET ECOSYSTEM

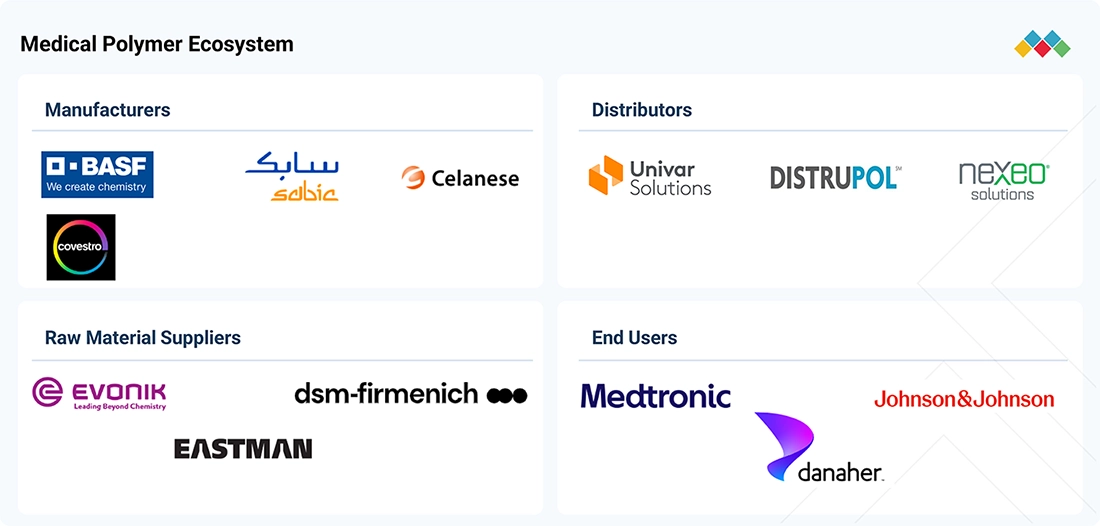
The medical polymer ecosystem comprises a complex network of component suppliers, technology partners, manufacturers, system integrators, service providers, and end users. The ecosystem of the medical polymer market involves an analysis of the ecosystem of the medical polymer market, which ranges from raw material suppliers to polymer converters, medical device companies, regulatory agencies, and ultimately end users such as hospitals and clinics. All of these players must continue to work together in an innovative environment and be compliant with regulations. Regulatory agencies such as the FDA and EMA use various processes to establish acceptable safety and performance standards. Emerging technologies, patient-centered healthcare, and sustainable initiatives also affect the ecosystem of the medical polymers market and provide demand for biocompatible, high-performance, and recyclable medical polymers used in diagnostic, therapeutic, and surgical applications.

medical-polymer-market Ecosystem

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET SEGMENTS

medical-polymer-market Segments

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Medical Polymer Market, By Type

Medical plastics represent the fastest-growing segment in the medical polymer market because of their versatility, cost-effectiveness, and performance properties designed for medical use. Medical plastics commonly include polyethylene, polypropylene, PVC, and polycarbonate, and they suit medical applications because of their chemical resistance, biocompatibility, lightweight nature, and ease of sterilization. Medical plastics can be molded into complex forms, allowing manufacturers to design syringes, catheters, IV bags, surgical tools, and diagnostic materials with high precision and produce them reliably. Because medical plastics are comparatively inexpensive, they support the production of single-use devices, which help reduce the risk of cross-contamination and improve infection control in clinical settings. The growing focus on patient-centric care, supported by minimally invasive procedures and home-based healthcare services, has increased the use of compact, solution-based, flexible plastic medical products. Protections and medical plastics with antimicrobial and biodegradable formulations are key drivers that can help to grow this market segment. Medical plastics offer unique processing innovation and a rapid transition through polymer chemistries to the envisioned production process. Most medical plastics replace traditional materials such as glass and metal. Medical plastics are driving the market's rapid growth and evolution toward safer, more efficient, patient-focused medical products.

Medical Polymer Market, By Manufacturing Technology

By manufacturing technology, extrusion tubing is estimated to be the largest segment of the overall medical polymer market because it enables versatile production of flexible, strong, precise parts for medical devices. The extrusion process suits manufacturers of medical-grade tubing used in catheters, IV lines, dialysis devices, and infusion systems. Through the extrusion process, tubes are produced continuously, consistently rounded in cross-section, of precise dimensions, and with a smooth surface that is required for transporting all kinds of fluids to protect patient safety. Extrusion technology is used in producing many different polymers, including polyvinyl chloride (PVC), polyethylene, polyurethane, and silicone, which have made it widely adopted for a variety of medical tube applications. In addition, extrusion technology can create multilayer or co-extruded tubes that combine the properties of different materials in a single tube for improved performance. The growing demand for non-invasive medical procedures, along with the rise of sophisticated diagnostic and therapeutic devices, has fueled increased demand for precision tubing. Considering the low cost, low risk, ease of scaling, and compatibility with automation and consistent quality, extrusion technology will prevail in the medical polymer market.

Medical Polymer Market, By Application

The medical instruments & devices segment dominates the medical polymers market. The many products physicians rely on every day are made from polymer materials. Examples include surgical instruments, catheters, medical implants, diagnostic devices, tubing, and even medical equipment housings. Demand for medical-grade polymers is driven by the need for precise, durable, biocompatible medical devices. Polymers also enable miniaturization and lightweight vaccine distribution, which is essential for modern portable and wearable medical devices. As the trend toward single-use (disposable) medical instruments accelerates because of hygiene concerns, so does polymer consumption. With the global rise in surgical procedures and the ever-increasing volumes of diagnostic testing, demand is rising for reliable, high-performance materials that comply with strict regulatory and safety standards. Emerging polymer science also advances in-device functionality, including drug delivery, antimicrobial surfaces, and improved flexibility. Together, these factors reinforce the dominance of medical instruments and devices as the largest segment of the medical polymers market and drive growth and innovation.

REGION

Asia Pacific to be fastest-growing region in medical polymer market during forecast period

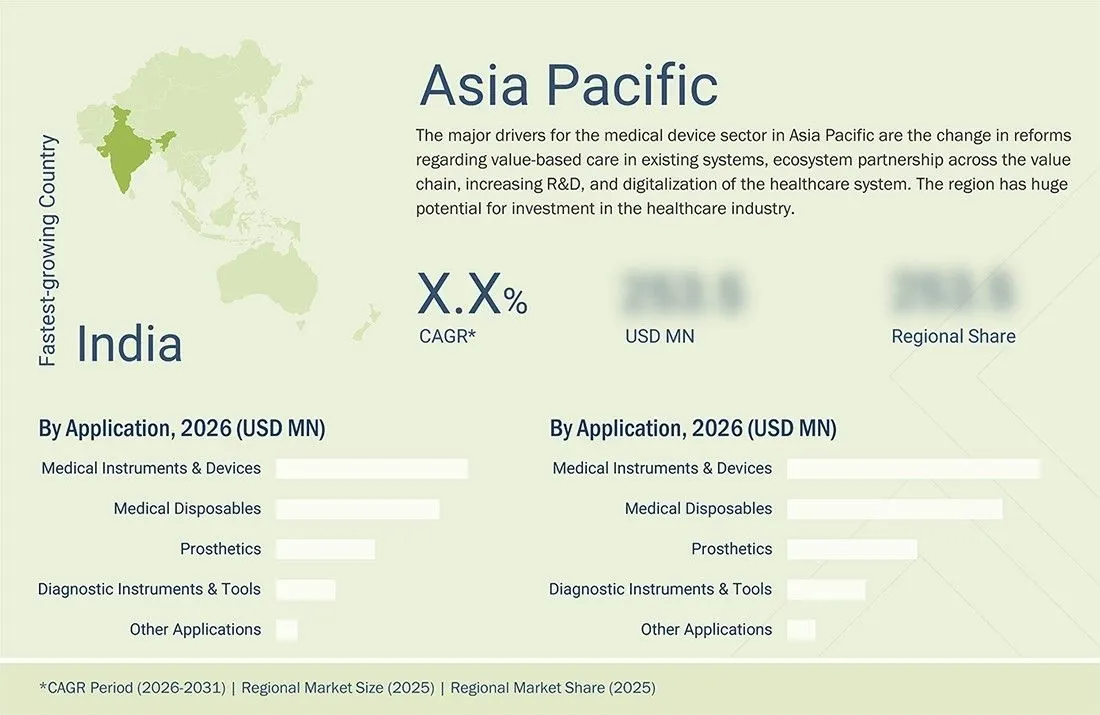
Asia Pacific is the fastest-growing market during the forecast period. This growth is driven by improvements in healthcare infrastructure, rising demand for medical devices, and increased investment in production capacity. A growing population, increased urbanization, and rising middle-class incomes in countries such as China, India, and Southeast Asia are supporting the large increase in healthcare spending and access to specialty medical treatments. This is increasing demand for medical polymers in diagnostics, implants, surgical tools, and drug delivery systems. These countries also offer low production costs, making them an appealing location for both domestic and international medical device manufacturers. Recent government programs focused on increasing access to healthcare, supporting local production, and developing innovation in medical technologies are accelerating the medical polymers market in the area. The growing number of chronic diseases and an aging population continue to drive demand for more effective, lighter-weight, biocompatible solutions. The medical polymer market will benefit from the current shift toward higher-quality, patient-friendly, and sustainable solutions in the Asia Pacific region.

medical-polymer-market Region

MEDICAL POLYMER MARKET: COMPANY EVALUATION MATRIX

BASF SE (Star), a Germany-based company in the medical polymer market, has emerged as a market leader thanks to its broad portfolio of high-performance and specialty polymers used in medical devices, healthcare packaging, drug delivery systems, and other healthcare applications. The company's medical-grade materials offer biocompatibility, chemical resistance, durability, flexibility, and sterilization compatibility, supporting the development of reliable, high-performance medical components and devices. Momentive Performance Materials Inc. (Emerging Leader), a US-based company, is strengthening its position in the medical polymer market through its portfolio of specialized silicone materials and technologies developed for medical and healthcare applications. The company's medical-focused offerings include StatSil antimicrobial silicone, Addisil UV-curable silicone, and ReliaSil silicone technologies for long-term implantable applications. Its focus on medical-specific product innovation and specialized processing capabilities supports the development of application-specific polymer solutions and strengthens its presence in the medical polymer market.

medical-polymer-market Evaluation Metrics

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

KEY MARKET PLAYERS

MARKET SCOPE

REPORT METRIC DETAILS
Market Size in 2025 (Value) USD 44.69 Billion
Market Size in 2026 (Value) USD 48.27 Billion
Market Forecast in 2031 (Value) USD 71.92 Billion
Growth Rate CAGR of 8.3% from 2026-2031
Years Considered 2023-2031
Base Year 2025
Forecast Period 2026-2031
Units Considered Value (USD Million/Billion), Volume (Kiloton)
Report Coverage Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments Covered
  • By Type:
    • Medical Plastics
    • Medical Elastomers
  • By Manufacturing Technology:
    • Extrusion Tubing
    • Compression Moulding
    • Injection Moulding
    • Other Technologies
  • By Application:
    • Medical Disposables
    • Medical Instruments & Devices
    • Prosthetics
    • Diagnostic Instruments & Tools
    • Other Applications
Regions Covered North America, Asia Pacific, Europe, South America, and Middle East & Africa

WHAT IS IN IT FOR YOU: MEDICAL POLYMER MARKET REPORT CONTENT GUIDE

medical-polymer-market Content Guide

DELIVERED CUSTOMIZATIONS

We have successfully delivered the following deep-dive customizations:

CLIENT REQUEST CUSTOMIZATION DELIVERED VALUE ADDS
Leading Medical Polymer Supplier Competitive profiling of key medical polymer suppliers (financials, polymer portfolio, technologies, applications, and strategic developments) Supported go-to-market strategy and competitive positioning
Country-level insights for high-growth regions
  • Provided detailed market sizing and forecasts for Asia Pacific and North America markets
  • Identified country-level demand drivers for drug delivery and implantable devices
  • Helped the client identify regional growth hotspots and investment opportunities
Enabled prioritized market entry and resource allocation across high-growth geographies
Identify emerging medical polymer technologies Conducted technology scouting and feasibility analysis for bioresorbable polymers, high-performance PEEK/PAEK grades, antimicrobial and low-friction compounds Supported investment decisions and innovation roadmaps for clients
Evaluate regulatory compliance for new market entry Compiled country-level medical device regulations, biocompatibility standards (ISO 10993, USP Class VI), and sterilization compliance requirements relevant to medical-grade polymers Ensured smoother market entry and minimized regulatory and compliance risks

RECENT DEVELOPMENTS

  • February 2026 : Kuraray America Inc. launched CERABIEN MiLai, an aesthetic micro-layering ceramic system at LMT LAB DAY 2026. This material is intended for high-aesthetic dental restorations, supporting Kuraray’s range of advanced dental ceramics used in crowns and prosthetics.
  • June 2025 : BASF opened a GMP manufacturing facility in Wyandotte, Michigan, to supply bioprocessing ingredients and related solutions. Operating under pharmaceutical-grade Good Manufacturing Practice standards, the site enhances BASF’s role as a supplier of critical inputs to biopharma and medical manufacturing.
  • January 2025 : Covestro expanded its Hebron, Ohio facility with a low triple-digit million-euro investment, significantly increasing its manufacturing capabilities. This expansion focuses on enhancing the production of customized polycarbonate compounds and blends to meet evolving customer and market needs.
  • March 2024 : SABIC, one of the world's largest chemical companies, has explored new market opportunities to recycle medical plastics back into the medical materials stream with the dialysis department at Jessa Hospital, one of the largest non-university medical clusters in Limburg, Flanders, Belgium. As a pilot proof of concept, medical plastic from Jessa’s hospitals was processed through an advanced recycling process into pyrolysis oil, providing circular feedstock for SABIC to make TRUCIRCLE polymers, each product manufactured to medical-grade specifications, with equal or superior performance, purity, and physiological safety compared with virgin-based medical-grade polymers.
  • October 2023 : Covestro put its first mechanical recycling (MCR) compounding line dedicated to polycarbonates into operation at its integrated site in Shanghai, China. The compounding line will produce more than 25,000 tons of polycarbonates and blends containing mechanically recycled materials every year in response to sustainability commitments, especially for post-consumer recycled (PCR) plastics used in electrical/electronic products, automotive, healthcare, and consumer goods applications.
  • October 2023 : Covestro increased production capacities associated with thermoplastic polyurethane (TPU) films in the Platilon product range and associated infrastructure and logistics in Bomlitz, Lower Saxony, Germany.


Table of Contents

checkmarkExclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.

TITLE
PAGE NO
1
INTRODUCTION


28
2
EXECUTIVE SUMMARY


32
3
PREMIUM INSIGHTS


39
4
MARKET OVERVIEW
Surging demand for biocompatible materials drives innovation amidst regulatory and sustainability challenges.


43
 
4.1
INTRODUCTION


4.2
MARKET DYNAMICS


4.2.1
DRIVERS


4.2.1.1
INCREASING DEMAND FOR BIOCOMPATIBLE AND HIGH-PERFORMANCE MATERIALS


4.2.1.2
GROWING AGING POPULATION AND HEALTHCARE EXPENDITURE


4.2.1.3
ADVANCEMENTS IN MEDICAL DEVICES AND MINIMALLY INVASIVE PROCEDURES


4.2.1.4
RISE IN CHRONIC DISEASES


4.2.1.5
INCREASING ADOPTION OF STRINGENT MEDICAL-GRADE MATERIAL AND BIOCOMPATIBILITY REQUIREMENTS


4.2.2
RESTRAINTS


4.2.2.1
STRINGENT REGULATORY AND MATERIAL QUALIFICATION REQUIREMENTS


4.2.2.2
HIGH COMPETITION FROM ALTERNATIVE POLYMERS AND MATERIALS


4.2.2.3
ENVIRONMENTAL SUSTAINABILITY AND CHEMICAL REGULATORY CONCERNS


4.2.3
OPPORTUNITIES


4.2.3.1
GROWTH IN REGENERATIVE MEDICINE AND TISSUE ENGINEERING


4.2.3.2
ADVANCEMENTS IN BIODEGRADABLE AND BIORESORBABLE POLYMERS


4.2.3.3
GROWING ADOPTION OF 3D-PRINTED AND PATIENT-SPECIFIC MEDICAL DEVICES


4.2.3.4
INCREASING DEMAND FOR MINIMALLY INVASIVE AND PATIENT-SPECIFIC DEVICES


4.2.4
CHALLENGES


4.2.4.1
HIGH COST AND LENGTHY QUALIFICATION OF NOVEL MEDICAL-GRADE MATERIALS


4.2.4.2
BALANCING SUSTAINABILITY WITH DURABILITY, STERILIZATION, AND BIOCOMPATIBILITY


4.2.4.3
EVOLVING RESTRICTIONS ON PFAS AND OTHER CHEMICALS USED IN MEDICAL POLYMER APPLICATIONS


4.3
UNMET NEEDS IN MEDICAL POLYMER MARKET


4.3.1
WHITE SPACE OPPORTUNITIES


4.4
INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES


4.5
STRATEGIC MOVES BY TIER-1/2/3 PLAYERS


4.5.1
KEY MOVES AND STRATEGIC FOCUS


5
INDUSTRY TRENDS
Discover emerging revenue opportunities and competitive dynamics shaping the medical polymer industry landscape.


55
 
5.1
PORTER’S FIVE FORCES ANALYSIS


5.1.1
THREAT FROM NEW ENTRANTS


5.1.2
THREAT OF SUBSTITUTES


5.1.3
BARGAINING POWER OF BUYERS


5.1.4
BARGAINING POWER OF SUPPLIERS


5.1.5
INTENSITY OF COMPETITIVE RIVALRY


5.2
MACROECONOMIC INDICATORS


5.2.1
GLOBAL GDP TRENDS


5.2.2
HEALTHCARE INDUSTRY TRENDS


5.3
VALUE CHAIN ANALYSIS


5.3.1
RAW MATERIAL SUPPLIERS


5.3.2
MANUFACTURERS


5.3.3
DISTRIBUTION


5.3.4
END USERS


5.4
ECOSYSTEM


5.5
PRICING ANALYSIS


5.5.1
AVERAGE SELLING PRICE TREND, BY REGION


5.5.2
AVERAGE SELLING PRICE TREND, BY APPLICATION


5.6
TRADE ANALYSIS


5.6.1
IMPORT SCENARIO


5.6.2
EXPORT SCENARIO


5.7
KEY CONFERENCES & EVENTS


5.8
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS


5.8.1
REVENUE SHIFT AND NEW REVENUE POCKETS FOR MEDICAL POLYMER MANUFACTURERS


5.9
INVESTMENT AND FUNDING SCENARIO


5.10
CASE STUDY ANALYSIS


5.10.1
EVONIK INDUSTRIES PROVIDES MEDICAL POLYMERS TO JENACELL GMBH FOR WOUND DRESSINGS, IMPLANTABLE MATERIALS, AND DRUG DELIVERY SYSTEMS


5.10.2
ENSINGER OFFERS HIGH-PERFORMANCE, MEDICAL-GRADE POLYMERS FOR HIGH-FREQUENCY SURGERY


5.11
IMPACT OF 2025 US TARIFF ON MEDICAL POLYMER MARKET


5.11.1
INTRODUCTION


5.11.2
KEY TARIFF RATES


5.11.3
PRICE IMPACT ANALYSIS


5.11.4
IMPACT ON KEY COUNTRIES/REGIONS


5.11.4.1
NORTH AMERICA


5.11.4.2
EUROPE


5.11.4.3
ASIA PACIFIC


5.11.5
IMPACT ON END-USE INDUSTRIES


6
TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
AI-driven innovations in medical polymers revolutionize sustainable, high-performance materials and smart manufacturing.


76
 
6.1
TECHNOLOGY ANALYSIS


6.1.1
KEY TECHNOLOGIES


6.1.1.1
BIOCOMPATIBLE AND MEDICAL-GRADE POLYMERS


6.1.1.2
MEDICAL-GRADE THERMOPLASTIC ELASTOMERS


6.1.1.3
HIGH-PERFORMANCE MEDICAL POLYMER ENGINEERING


6.1.2
COMPLEMENTARY TECHNOLOGIES


6.1.2.1
POLYMER-BASED ADDITIVE MANUFACTURING


6.1.2.2
MEDICAL POLYMER SURFACE MODIFICATION TECHNIQUES


6.1.2.3
ADVANCED POLYMER COMPOUNDING AND PROCESSING


6.2
TECHNOLOGY/PRODUCT ROADMAP


6.2.1
SHORT TERM (2025-2027) | MEDICAL-GRADE MATERIAL INNOVATION & PERFORMANCE OPTIMIZATION


6.2.2
MID-TERM (2027-2030) | ADVANCED MATERIALS, SMART MANUFACTURING & APPLICATION INTEGRATION


6.2.3
LONG TERM (2030-2035+) | SUSTAINABLE HIGH-PERFORMANCE POLYMERS & INTELLIGENT MANUFACTURING


6.3
PATENT ANALYSIS


6.3.1
LEGAL STATUS OF PATENTS


6.3.2
JURISDICTION ANALYSIS


6.4
FUTURE APPLICATIONS


6.4.1
HIGH-PERFORMANCE POLYMERS FOR MEDICAL INSTRUMENTS & DEVICES


6.4.2
SUSTAINABLE, BIORESORBABLE & BIO-BASED MEDICAL POLYMERS


6.4.3
ADDITIVE MANUFACTURING & PATIENT-SPECIFIC MEDICAL POLYMERS


ADVANCED POLYMER PROCESSING, SURFACE ENGINEERING &


6.5
IMPACT OF AI/GEN AI ON MEDICAL POLYMER MARKET


6.5.1
TOP USE CASES AND MARKET POTENTIAL OF MEDICAL POLYMERS


6.5.2
BEST PRACTICES IN MEDICAL POLYMER PROCESSING


6.5.3
CASE STUDIES OF AI IMPLEMENTATION IN MEDICAL POLYMER MARKET


6.5.4
INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS


CLIENTS' READINESS TO ADOPT GENERATIVE AI IN MEDICAL


7
SUSTAINABILITY AND REGULATORY LANDSCAPE
Navigate complex global regulations to leverage sustainability in the medical polymer market.


90
 
7.1
REGIONAL REGULATIONS AND COMPLIANCE


7.1.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


7.1.2
INDUSTRY STANDARDS


7.2
IMPACT OF REGULATORY POLICIES AND SUSTAINABILITY INITIATIVES


7.3
CERTIFICATIONS, LABELING, AND ECO-STANDARDS


8
CUSTOMER LANDSCAPE & BUYING BEHAVIOUR
Unlock revenue by understanding stakeholder influence and unmet needs in key industries.


100
 
8.1
INTRODUCTION


8.2
DECISION-MAKING PROCESS


8.3
KEY STAKEHOLDERS & BUYING CRITERIA


8.3.1
KEY STAKEHOLDERS IN BUYING PROCESS


8.3.2
BUYING CRITERIA


8.4
ADOPTION BARRIERS & INTERNAL CHALLENGES


8.5
UNMET NEEDS IN VARIOUS END-USE INDUSTRIES


8.6
MARKET PROFITABILITY


8.6.1
REVENUE POTENTIAL


8.6.2
COST DYNAMICS


8.6.3
MARGIN OPPORTUNITIES IN KEY END-USE INDUSTRIES


9
MEDICAL POLYMER MARKET, BY APPLICATION
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million and Kilotons | 4 Data Tables


109
 
9.1
INTRODUCTION


9.2
MEDICAL DISPOSABLES


9.2.1
INCREASING DEMAND FOR CATHETERS AND SYRINGES TO DRIVE MARKET


9.2.2
GLOVES


9.2.3
SYRINGES


9.2.4
MEDICAL BAGS


9.2.5
OTHER MEDICAL DISPOSABLES


9.3
MEDICAL INSTRUMENTS & DEVICES


9.3.1
INCREASING USE OF ADVANCED AND MINIMALLY INVASIVE MEDICAL DEVICES TO DRIVE MARKET


9.3.2
MEDICAL TUBES


9.3.3
CATHETERS


9.3.4
DRUG DELIVERY INSTRUMENTS


9.3.5
OTHER MEDICAL INSTRUMENTS & DEVICES


9.4
PROSTHETICS


9.4.1
RISING DEMAND FOR ADVANCED LIMB PROSTHESES AND IMPLANTS TO DRIVE MARKET


9.4.2
IMPLANTS


9.4.3
LIMB PROSTHESIS


9.4.4
OTHER PROSTHETICS APPLICATIONS


9.5
DIAGNOSTIC INSTRUMENTS & TOOLS


9.5.1
INCREASING DEMAND IN SURGICAL AND PROCEDURAL APPLICATIONS TO DRIVE MARKET


9.5.2
DENTAL TOOLS


9.5.3
SURGICAL INSTRUMENTS


9.5.4
OTHER DIAGNOSTIC INSTRUMENTS & TOOLS


9.6
OTHER APPLICATIONS


10
MEDICAL POLYMER MARKET, BY TYPE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million and Kilotons | 4 Data Tables


122
 
10.1
INTRODUCTION


10.2
MEDICAL PLASTICS


10.2.1
ADVANCEMENTS IN MATERIAL SCIENCE AND MANUFACTURING TECHNOLOGIES TO DRIVE MARKET


10.2.2
POLYPROPYLENE


10.2.3
POLYVINYL CHLORIDE


10.2.4
POLYETHYLENE


10.2.5
POLYSTYRENE


10.2.6
ENGINEERING & HIGH-PERFORMANCE PLASTICS


10.2.6.1
POLYETHER ETHER KETONE


10.2.6.2
NYLON/POLYAMIDE


10.2.6.3
POLYPHENYLSULFONE


10.2.6.4
POLYSULFONES


10.2.6.5
POLYMETHYL METHACRYLATE


10.2.6.6
POLYCARBONATE


10.2.6.7
ACRYLONITRILE BUTADIENE STYRENE


10.2.6.8
OTHER ENGINEERING & HIGH-PERFORMANCE PLASTICS


10.2.7
OTHER MEDICAL PLASTICS


10.3
MEDICAL ELASTOMERS


10.3.1
FLEXIBILITY, DURABILITY, AND BIOCOMPATIBILITY TO DRIVE MARKET


10.3.2
SILICONE


10.3.3
THERMOPLASTIC ELASTOMERS


10.3.3.1
THERMOPLASTIC POLYURETHANE


10.3.3.2
THERMOPLASTIC VULCANIZATES


10.3.3.3
THERMOPLASTIC STYRENIC ELASTOMERS


10.3.3.3.1
POLY (STYRENE-BUTADIENE-STYRENE)


10.3.3.3.2
STYRENE-ETHYLENE-BUTYLENE-STYRENE


10.3.3.4
THERMOPLASTIC COPOLYESTER ELASTOMERS


10.3.4
OTHER MEDICAL ELASTOMERS


11
MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million and Kilotons | 4 Data Tables


136
 
11.1
INTRODUCTION


11.2
EXTRUSION TUBING


11.2.1
INCREASING USE IN INTRAVENOUS DELIVERY SYSTEMS, CATHETERS, AND SURGICAL INSTRUMENTS TO DRIVE MARKET


11.3
COMPRESSION MOLDING


11.3.1
RISING USE IN PROSTHETIC AND ORTHOPEDIC COMPONENTS TO FUEL DEMAND


11.4
INJECTION MOLDING


11.4.1
INCREASING USE IN SYRINGES, SURGICAL INSTRUMENTS, AND MEDICAL DEVICE COMPONENTS TO SUPPORT MARKET GROWTH


11.5
OTHER MANUFACTURING TECHNOLOGIES


12
MEDICAL POLYMER MARKET, BY REGION
Comprehensive coverage of 8 Regions with country-level deep-dive of 18 Countries | 268 Data Tables.


141
 
12.1
INTRODUCTION


12.2
NORTH AMERICA


12.2.1
US


12.2.1.1
STRONG MEDICAL R&D AND DEVICE INNOVATION TO SUPPORT DEMAND


12.2.2
CANADA


12.2.2.1
EXPANDING MEDICAL DEVICE MANUFACTURING AND HEALTHCARE DEMAND TO SUPPORT MARKET


12.2.3
MEXICO


12.2.3.1
EXPANSION OF MEDICAL-DEVICE MANUFACTURING TO SUPPORT MARKET GROWTH


12.3
ASIA PACIFIC


12.3.1
CHINA


12.3.1.1
ESTABLISHMENT OF MEDICAL DEVICE MANUFACTURING UNITS AND INVESTMENT IN HEALTHCARE-RELATED SECTORS TO DRIVE MARKET


12.3.2
INDIA


12.3.2.1
EXPANSION OF DOMESTIC MEDICAL DEVICE MANUFACTURING TO DRIVE DEMAND


12.3.3
SOUTH KOREA


12.3.3.1
ADVANCED MEDICAL DEVICE MANUFACTURING AND TECHNOLOGY DEVELOPMENT TO DRIVE MARKET


12.3.4
JAPAN


12.3.4.1
AGING POPULATION AND ADVANCED MEDICAL-DEVICE TECHNOLOGIES TO SUPPORT MARKET GROWTH


12.3.5
AUSTRALIA


12.3.5.1
STRONG MEDICAL DEVICE MANUFACTURING AND REGULATORY STANDARDS TO SUPPORT MARKET GROWTH


12.3.6
REST OF ASIA PACIFIC


12.4
EUROPE


12.4.1
GERMANY


12.4.1.1
ADVANCED MEDICAL DEVICE MANUFACTURING AND AGING POPULATION TO SUPPORT MARKET GROWTH


12.4.2
FRANCE


12.4.2.1
AGING POPULATION AND ADVANCED MEDICAL-DEVICE MANUFACTURING TO SUPPORT MARKET GROWTH


12.4.3
UK


12.4.3.1
GROWING MEDICAL DEVICE INDUSTRY AND GOVERNMENT SUPPORT FOR INNOVATION TO DRIVE MARKET


12.4.4
ITALY


12.4.4.1
STRONG PRODUCTION FACILITIES WITH PRESENCE OF GLOBAL PLAYERS TO PROPEL MARKET GROWTH


12.4.5
SPAIN


12.4.5.1
GROWING MEDICAL TECHNOLOGY INDUSTRY AND GOVERNMENT SUPPORT TO DRIVE MARKET


12.4.6
REST OF EUROPE


12.5
SOUTH AMERICA


12.5.1
BRAZIL


12.5.1.1
AGING POPULATION AND EXPANDING MEDICAL DEVICE INDUSTRY TO DRIVE MARKET


12.5.2
ARGENTINA


12.5.2.1
HIGH IMPORT DEPENDENCE AND EVOLVING MEDICAL DEVICE REGULATIONS TO SUPPORT MARKET


12.5.3
REST OF SOUTH AMERICA


12.6
MIDDLE EAST & AFRICA


12.6.1
GCC COUNTRIES


12.6.1.1
SAUDI ARABIA


12.6.1.1.1
HEALTHCARE TRANSFORMATION AND MEDICAL DEVICE LOCALIZATION TO SUPPORT MARKET GROWTH


12.6.1.2
UAE


12.6.1.2.1
MODERNIZATION OF HEALTHCARE INDUSTRY TO DRIVE MARKET


12.6.1.3
REST OF GCC


12.6.2
SOUTH AFRICA


12.6.2.1
LOCALIZATION OF MEDICAL DEVICE PRODUCTION TO SUPPORT MARKET


12.6.3
REST OF MIDDLE EAST & AFRICA


13
COMPETITIVE LANDSCAPE
Discover strategic shifts and emerging leaders shaping the competitive landscape through 2025.


386
 
13.1
OVERVIEW


13.2
KEY PLAYERS' STRATEGIES


13.3
REVENUE ANALYSIS, 2022–2025


13.4
MARKET SHARE ANALYSIS, 2025


13.5
COMPANY VALUATION AND FINANCIAL METRICS


13.6
BRAND/PRODUCT COMPARISON ANALYSIS


13.7
COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025


13.7.1
STARS


13.7.2
EMERGING LEADERS


13.7.3
PERVASIVE PLAYERS


13.7.4
PARTICIPANTS


13.7.5
COMPANY FOOTPRINT: KEY PLAYERS, 2025


13.7.5.1
COMPANY FOOTPRINT


13.7.5.2
REGION FOOTPRINT


13.7.5.3
TYPE FOOTPRINT


13.7.5.4
MANUFACTURING TECHNOLOGY FOOTPRINT


13.7.5.5
APPLICATION FOOTPRINT


13.8
COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025


13.8.1
PROGRESSIVE COMPANIES


13.8.2
RESPONSIVE COMPANIES


13.8.3
DYNAMIC COMPANIES


13.8.4
STARTING BLOCKS


13.8.5
COMPETITIVE BENCHMARKING: KEY STARTUPS/SMES, 2025


13.8.5.1
DETAILED LIST OF KEY STARTUPS/SMES


13.8.5.2
COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES


13.9
COMPETITIVE SCENARIO


13.9.1
PRODUCT LAUNCHES


13.9.2
DEALS


13.9.3
EXPANSIONS


14
COMPANY PROFILES
In-depth Company Profiles of Leading Market Players with detailed Business Overview, Product and Service Portfolio, Recent Developments, and Unique Analyst Perspective (MnM View)


414
 
14.1
MAJOR PLAYERS


14.1.1
BASF SE


14.1.1.1
BUSINESS OVERVIEW


14.1.1.2
PRODUCTS/SERVICES/SOLUTIONS OFFERED


14.1.1.3
RECENT DEVELOPMENTS


14.1.1.3.1
PRODUCT LAUNCHES


14.1.1.3.2
EXPANSIONS


14.1.1.4
MNM VIEW


14.1.1.4.1
KEY STRENGTHS


14.1.1.4.2
STRATEGIC CHOICES


14.1.1.4.3
WEAKNESSES AND COMPETITIVE THREATS


14.1.2
SABIC


14.1.3
COVESTRO AG


14.1.4
CELANESE CORPORATION


14.1.5
EVONIK INDUSTRIES


14.1.6
ARKEMA


14.1.7
SOLVAY


14.1.8
KURARAY CO., LTD.


14.1.9
MOMENTIVE PERFORMANCE MATERIALS INC.


14.1.10
DUPONT


14.2
OTHER PLAYERS


14.2.1
TRINSEO


14.2.2
KRATON CORPORATION


14.2.3
TOTAL PLASTICS


14.2.4
SIMONA AMERICA


14.2.5
DSM


14.2.6
INVIBIO


14.2.7
AVIENT CORPORATION


14.2.8
RTP COMPANY


14.2.9
TEKNI-PLEX, INC.


14.2.10
TEKNOR APEX


14.2.11
MITSUBISHI CHEMICAL ADVANCED MATERIALS


14.2.12
WACKER CHEMIE


14.2.13
HARDIE POLYMERS


14.2.14
ELIX POLYMERS


14.2.15
INNOVATIVE POLYMER COMPOUNDS LTD.


15
RESEARCH METHODOLOGY


478
 
15.1
RESEARCH DATA


15.1.1
SECONDARY DATA


15.1.1.1
LIST OF MAJOR SECONDARY SOURCES


15.1.1.2
KEY DATA FROM SECONDARY SOURCES


15.1.2
PRIMARY DATA


15.1.2.1
KEY DATA FROM PRIMARY SOURCES


15.1.2.2
LIST OF PRIMARY INTERVIEW PARTICIPANTS—DEMAND AND SUPPLY SIDE


15.1.2.3
KEY INDUSTRY INSIGHTS


15.1.2.4
BREAKDOWN OF PRIMARY INTERVIEWS


15.2
MARKET SIZE ESTIMATION


15.2.1
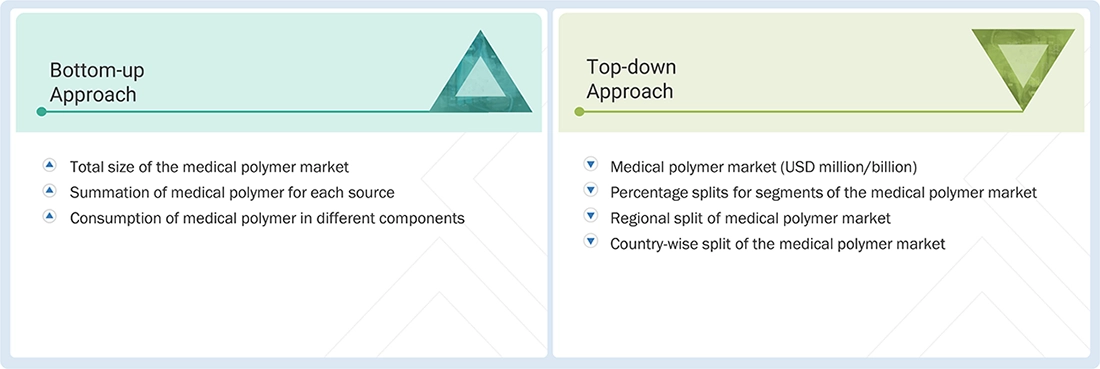
BOTTOM-UP APPROACH


15.2.2
TOP-DOWN APPROACH


15.3
BASE NUMBER CALCULATION


15.3.1
DEMAND-SIDE APPROACH


15.3.2
SUPPLY-SIDE APPROACH


15.4
MARKET FORECAST APPROACH


15.4.1
SUPPLY SIDE


15.4.2
DEMAND SIDE


15.5
DATA TRIANGULATION


15.6
FACTOR ANALYSIS


15.7
ASSUMPTIONS


15.8
LIMITATIONS AND RISKS


16
APPENDIX


488
 
16.1
DISCUSSION GUIDE


16.2
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL


16.3
CUSTOMIZATION OPTIONS


16.4
RELATED REPORTS


16.5
AUTHOR DETAILS


LIST OF TABLES


TABLE 1
MEDICAL POLYMER MARKET: INCLUSIONS AND EXCLUSIONS


TABLE 2
MEDICAL POLYMER MARKET: IMPACT OF PORTER’S FIVE FORCES


TABLE 3
PROJECTED REAL GDP GROWTH (ANNUAL PERCENTAGE CHANGE) OF KEY COUNTRIES, 2018–2025


TABLE 4
GDP TRENDS AND FORECAST OF MAJOR ECONOMIES, 2023–2030 (USD BILLION, CURRENT PRICES)


TABLE 5
U.S. NATIONAL HEALTH EXPENDITURE (NHE) TRENDS, 2022–2033


TABLE 6
MEDICAL POLYMER MARKET: ROLE OF COMPANIES IN ECOSYSTEM


TABLE 7
MEDICAL POLYMER MARKET: CONFERENCES & EVENTS, 2026−2027


TABLE 8
US-ADJUSTED RECIPROCAL TARIFF RATES


TABLE 9
TOP USE CASES AND MARKET POTENTIAL


TABLE 10
BEST PRACTICES: NOTABLE INDUSTRY PRACTICES BY LEADING COMPANIES


TABLE 11
INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS


TABLE 12
NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 13
EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 14
ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 15
SOUTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 16
MIDDLE EAST & AFRICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 17
GLOBAL STANDARDS IN MEDICAL POLYMER MARKET


TABLE 18
CERTIFICATIONS, LABELING, AND ECO-STANDARDS IN MEDICAL POLYMER MARKET


TABLE 19
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP FOUR APPLICATIONS


TABLE 20
KEY BUYING CRITERIA IN MAJOR APPLICATIONS


TABLE 21
MEDICAL POLYMER MARKET: UNMET NEEDS IN KEY END-USE INDUSTRIES


TABLE 22
MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 23
MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 24
MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 25
MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 26
MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 27
MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 28
MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 29
MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 30
MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2023–2025 (USD MILLION)


TABLE 31
MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2026–2031 (USD MILLION)


TABLE 32
MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2023–2025 (KILOTON)


TABLE 33
MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2026–2031 (KILOTON)


TABLE 34
MEDICAL POLYMER MARKET, BY REGION, 2023–2025 (USD MILLION)


TABLE 35
MEDICAL POLYMER MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 36
MEDICAL POLYMER MARKET, BY REGION, 2023–2025 (KILOTON)


TABLE 37
MEDICAL POLYMER MARKET, BY REGION, 2026–2031 (KILOTON)


TABLE 38
NORTH AMERICA: MEDICAL POLYMER MARKET, BY COUNTRY, 2023–2025 (USD MILLION)


TABLE 39
NORTH AMERICA: MEDICAL POLYMER MARKET, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 40
NORTH AMERICA: MEDICAL POLYMER MARKET, BY COUNTRY, 2023–2025 (KILOTON)


TABLE 41
NORTH AMERICA: MEDICAL POLYMER MARKET, BY COUNTRY, 2026–2031 (KILOTON)


TABLE 42
NORTH AMERICA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 43
NORTH AMERICA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 44
NORTH AMERICA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 45
NORTH AMERICA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 46
NORTH AMERICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 47
NORTH AMERICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 48
NORTH AMERICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 49
NORTH AMERICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 50
NORTH AMERICA: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2023–2025 (USD MILLION)


TABLE 51
NORTH AMERICA: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2026–2031 (USD MILLION)


TABLE 52
NORTH AMERICA: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2023–2025 (KILOTON)


TABLE 53
NORTH AMERICA: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2026–2031 (KILOTON)


TABLE 54
US: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 55
US: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 56
US: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 57
US: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 58
US: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 59
US: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 60
US: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 61
US: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 62
CANADA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 63
CANADA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 64
CANADA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 65
CANADA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 66
CANADA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 67
CANADA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 68
CANADA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 69
CANADA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 70
MEXICO: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 71
MEXICO: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 72
MEXICO: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 73
MEXICO: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 74
MEXICO: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 75
MEXICO: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 76
MEXICO: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 77
MEXICO: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 78
ASIA PACIFIC: MEDICAL POLYMER MARKET, BY COUNTRY, 2023–2025 (USD MILLION)


TABLE 79
ASIA PACIFIC: MEDICAL POLYMER MARKET, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 80
ASIA PACIFIC: MEDICAL POLYMER MARKET, BY COUNTRY, 2023–2025 (KILOTON)


TABLE 81
ASIA PACIFIC: MEDICAL POLYMER MARKET, BY COUNTRY, 2026–2031 (KILOTON)


TABLE 82
ASIA PACIFIC: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 83
ASIA PACIFIC: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 84
ASIA PACIFIC: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 85
ASIA PACIFIC: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 86
ASIA PACIFIC: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 87
ASIA PACIFIC: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 88
ASIA PACIFIC: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 89
ASIA PACIFIC: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 90
ASIA PACIFIC: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2023–2025 (USD MILLION)


TABLE 91
ASIA PACIFIC: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2026–2031 (USD MILLION)


TABLE 92
ASIA PACIFIC: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2023–2025 (KILOTON)


TABLE 93
ASIA PACIFIC: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2026–2031 (KILOTON)


TABLE 94
CHINA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 95
CHINA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 96
CHINA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 97
CHINA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 98
CHINA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 99
CHINA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 100
CHINA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 101
CHINA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 102
INDIA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 103
INDIA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 104
INDIA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 105
INDIA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 106
INDIA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 107
INDIA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 108
INDIA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 109
INDIA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 110
SOUTH KOREA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 111
SOUTH KOREA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 112
SOUTH KOREA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 113
SOUTH KOREA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 114
SOUTH KOREA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 115
SOUTH KOREA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 116
SOUTH KOREA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 117
SOUTH KOREA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 118
JAPAN: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 119
JAPAN: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 120
JAPAN: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 121
JAPAN: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 122
JAPAN: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 123
JAPAN: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 124
JAPAN: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 125
JAPAN: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 126
AUSTRALIA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 127
AUSTRALIA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 128
AUSTRALIA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 129
AUSTRALIA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 130
AUSTRALIA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 131
AUSTRALIA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 132
AUSTRALIA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 133
AUSTRALIA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 134
REST OF ASIA PACIFIC: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 135
REST OF ASIA PACIFIC: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 136
REST OF ASIA PACIFIC: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 137
REST OF ASIA PACIFIC: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 138
REST OF ASIA PACIFIC: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 139
REST OF ASIA PACIFIC: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 140
REST OF ASIA PACIFIC: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 141
REST OF ASIA PACIFIC: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 142
EUROPE: MEDICAL POLYMER MARKET, BY COUNTRY, 2023–2025 (USD MILLION)


TABLE 143
EUROPE: MEDICAL POLYMER MARKET, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 144
EUROPE: MEDICAL POLYMER MARKET, BY COUNTRY, 2023–2025 (KILOTON)


TABLE 145
EUROPE: MEDICAL POLYMER MARKET, BY COUNTRY, 2026–2031 (KILOTON)


TABLE 146
EUROPE: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 147
EUROPE: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 148
EUROPE: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 149
EUROPE: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 150
EUROPE: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 151
EUROPE: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 152
EUROPE: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 153
EUROPE: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 154
EUROPE: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2023–2025 (USD MILLION)


TABLE 155
EUROPE: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2026–2031 (USD MILLION)


TABLE 156
EUROPE: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2023–2025 (KILOTON)


TABLE 157
EUROPE: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2026–2031 (KILOTON)


TABLE 158
GERMANY: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 159
GERMANY: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 160
GERMANY: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 161
GERMANY: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 162
GERMANY: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 163
GERMANY: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 164
GERMANY: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 165
GERMANY: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 166
FRANCE: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 167
FRANCE: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 168
FRANCE: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 169
FRANCE: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 170
FRANCE: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 171
FRANCE: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 172
FRANCE: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 173
FRANCE: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 174
UK: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 175
UK: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 176
UK: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 177
UK: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 178
UK: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 179
UK: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 180
UK: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 181
UK: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 182
ITALY: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 183
ITALY: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 184
ITALY: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 185
ITALY: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 186
ITALY: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 187
ITALY: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 188
ITALY: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 189
ITALY: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 190
SPAIN: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 191
SPAIN: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 192
SPAIN: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 193
SPAIN: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 194
SPAIN: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 195
SPAIN: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 196
SPAIN: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 197
SPAIN: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 198
REST OF EUROPE: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 199
REST OF EUROPE: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 200
REST OF EUROPE: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 201
REST OF EUROPE: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 202
REST OF EUROPE: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 203
REST OF EUROPE: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 204
REST OF EUROPE: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 205
REST OF EUROPE: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 206
SOUTH AMERICA: MEDICAL POLYMER MARKET, BY COUNTRY, 2023–2025 (USD MILLION)


TABLE 207
SOUTH AMERICA: MEDICAL POLYMER MARKET, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 208
SOUTH AMERICA: MEDICAL POLYMER MARKET, BY COUNTRY, 2023–2025 (KILOTON)


TABLE 209
SOUTH AMERICA: MEDICAL POLYMER MARKET, BY COUNTRY, 2026–2031 (KILOTON)


TABLE 210
SOUTH AMERICA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 211
SOUTH AMERICA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 212
SOUTH AMERICA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 213
SOUTH AMERICA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 214
SOUTH AMERICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 215
SOUTH AMERICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 216
SOUTH AMERICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 217
SOUTH AMERICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 218
SOUTH AMERICA: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2023–2025 (USD MILLION)


TABLE 219
SOUTH AMERICA: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2026–2031 (USD MILLION)


TABLE 220
SOUTH AMERICA: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2023–2025 (KILOTON)


TABLE 221
SOUTH AMERICA: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2026–2031 (KILOTON)


TABLE 222
BRAZIL: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 223
BRAZIL: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 224
BRAZIL: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 225
BRAZIL: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 226
BRAZIL: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 227
BRAZIL: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 228
BRAZIL: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 229
BRAZIL: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 230
ARGENTINA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 231
ARGENTINA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 232
ARGENTINA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 233
ARGENTINA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 234
ARGENTINA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 235
ARGENTINA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 236
ARGENTINA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 237
ARGENTINA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 238
REST OF SOUTH AMERICA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 239
REST OF SOUTH AMERICA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 240
REST OF SOUTH AMERICA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 241
REST OF SOUTH AMERICA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 242
REST OF SOUTH AMERICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 243
REST OF SOUTH AMERICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 244
REST OF SOUTH AMERICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 245
REST OF SOUTH AMERICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 246
MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY COUNTRY, 2023–2025 (USD MILLION)


TABLE 247
MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 248
MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY COUNTRY, 2023–2025 (KILOTON)


TABLE 249
MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY COUNTRY, 2026–2031 (KILOTON)


TABLE 250
MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 251
MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 252
MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 253
MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 254
MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 255
MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 256
MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 257
MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 258
MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2023–2025 (USD MILLION)


TABLE 259
MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2026–2031 (USD MILLION)


TABLE 260
MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2023–2025 (KILOTON)


TABLE 261
MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2026–2031 (KILOTON)


TABLE 262
SAUDI ARABIA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 263
SAUDI ARABIA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 264
SAUDI ARABIA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 265
SAUDI ARABIA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 266
SAUDI ARABIA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 267
SAUDI ARABIA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 268
SAUDI ARABIA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 269
SAUDI ARABIA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 270
UAE: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 271
UAE: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 272
UAE: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 273
UAE: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 274
UAE: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 275
UAE: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 276
UAE: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 277
UAE: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 278
REST OF GCC: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 279
REST OF GCC: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 280
REST OF GCC: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 281
REST OF GCC: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 282
REST OF GCC: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 283
REST OF GCC: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 284
REST OF GCC: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 285
REST OF GCC: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 286
SOUTH AFRICA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 287
SOUTH AFRICA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 288
SOUTH AFRICA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 289
SOUTH AFRICA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 290
SOUTH AFRICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 291
SOUTH AFRICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 292
SOUTH AFRICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 293
SOUTH AFRICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 294
REST OF MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 295
REST OF MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 296
REST OF MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 297
REST OF MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 298
REST OF MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 299
REST OF MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 300
REST OF MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 301
REST OF MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 302
OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS IN MEDICAL POLYMER MARKET BETWEEN 2023 AND 2026


TABLE 303
MEDICAL POLYMER MARKET: DEGREE OF COMPETITION


TABLE 304
MEDICAL POLYMER MARKET: REGION FOOTPRINT


TABLE 305
MEDICAL POLYMER MARKET: TYPE FOOTPRINT


TABLE 306
MEDICAL POLYMER MARKET: MANUFACTURING TECHNOLOGY FOOTPRINT


TABLE 307
MEDICAL POLYMER MARKET: APPLICATION FOOTPRINT


TABLE 308
MEDICAL POLYMER MARKET: DETAILED LIST OF KEY STARTUPS/SMES


TABLE 309
MEDICAL POLYMER MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES (1/2)


TABLE 310
MEDICAL POLYMER MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES (2/2)


TABLE 311
MEDICAL POLYMER MARKET: PRODUCT LAUNCHES, JANUARY 2023–AUGUST 2026


TABLE 312
MEDICAL POLYMER MARKET: DEALS, JANUARY 2023–AUGUST 2026


TABLE 313
MEDICAL POLYMER MARKET: EXPANSIONS, JANUARY 2023–AUGUST 2026


TABLE 314
BASF SE: COMPANY OVERVIEW


TABLE 315
BASF SE: PRODUCTS/SERVICES/SOLUTIONS OFFERED


TABLE 316
BASF SE: PRODUCT LAUNCHES, JANUARY 2023–AUGUST 2026


TABLE 317
BASF SE: EXPANSIONS, JANUARY 2023–AUGUST 2026


TABLE 318
SABIC: COMPANY OVERVIEW


TABLE 319
SABIC: PRODUCTS/SERVICES/SOLUTIONS OFFERED


TABLE 320
SABIC: PRODUCT LAUNCHES, JANUARY 2023–AUGUST 2026


TABLE 321
SABIC: DEALS, JANUARY 2023–AUGUST 2026


TABLE 322
COVESTRO AG: COMPANY OVERVIEW


TABLE 323
COVESTRO AG: PRODUCTS/SERVICES/SOLUTIONS OFFERED


TABLE 324
COVESTRO AG: PRODUCT LAUNCHES, JANUARY 2023–AUGUST 2026


TABLE 325
COVESTRO AG: EXPANSIONS, JANUARY 2023–AUGUST 2026


TABLE 326
CELANESE CORPORATION: COMPANY OVERVIEW


TABLE 327
CELANESE CORPORATION: PRODUCTS/SERVICES/SOLUTIONS OFFERED


TABLE 328
CELANESE CORPORATION: DEALS, JANUARY 2023–AUGUST 2026


TABLE 329
CELANESE CORPORATION: EXPANSIONS, JANUARY 2023–AUGUST 2026


TABLE 330
EVONIK INDUSTRIES: COMPANY OVERVIEW


TABLE 331
EVONIK INDUSTRIES: PRODUCTS/SERVICES/SOLUTIONS OFFERED


TABLE 332
EVONIK INDUSTRIES: PRODUCT LAUNCHES, JANUARY 2023–AUGUST 2026


TABLE 333
EVONIK INDUSTRIES: DEALS, JANUARY 2023–AUGUST 2026


TABLE 334
EVONIK INDUSTRIES: EXPANSIONS, JANUARY 2023–AUGUST 2026


TABLE 335
ARKEMA: COMPANY OVERVIEW


TABLE 336
ARKEMA: PRODUCTS/SERVICES/SOLUTIONS OFFERED


TABLE 337
ARKEMA: DEALS, JANUARY 2023–AUGUST 2026


TABLE 338
ARKEMA: EXPANSIONS, JANUARY 2023–AUGUST 2026


TABLE 339
SOLVAY: COMPANY OVERVIEW


TABLE 340
SOLVAY: PRODUCTS/SERVICES/SOLUTIONS OFFERED


TABLE 341
SOLVAY: PRODUCT LAUNCHES, JANUARY 2023–AUGUST 2026


TABLE 342
KURARAY CO., LTD.: COMPANY OVERVIEW


TABLE 343
KURARAY CO., LTD.: PRODUCTS/SERVICES/SOLUTIONS OFFERED


TABLE 344
KURARAY CO., LTD.: EXPANSIONS, JANUARY 2023–AUGUST 2026


TABLE 345
MOMENTIVE PERFORMANCE MATERIALS INC.: COMPANY OVERVIEW


TABLE 346
MOMENTIVE PERFORMANCE MATERIALS INC.: PRODUCTS/SERVICES/ SOLUTIONS OFFERED


TABLE 347
MOMENTIVE PERFORMANCE MATERIALS INC.: PRODUCT LAUNCHES, JANUARY 2023–AUGUST 2026


TABLE 348
MOMENTIVE PERFORMANCE MATERIALS INC.: EXPANSIONS, JANUARY 2023–AUGUST 2026


TABLE 349
DUPONT: COMPANY OVERVIEW


TABLE 350
DUPONT: PRODUCTS/SERVICES/SOLUTIONS OFFERED


TABLE 351
DUPONT: PRODUCT LAUNCHES, JANUARY 2023–AUGUST 2026


TABLE 352
DUPONT: DEALS, JANUARY 2023–AUGUST 2026


TABLE 353
DUPONT: EXPANSIONS, JANUARY 2023–AUGUST 2026


TABLE 354
TRINSEO: COMPANY OVERVIEW


TABLE 355
KRATON CORPORATION: COMPANY OVERVIEW


TABLE 356
TOTAL PLASTICS: COMPANY OVERVIEW


TABLE 357
SIMONA AMERICA: COMPANY OVERVIEW


TABLE 358
DSM: COMPANY OVERVIEW


TABLE 359
INVIBIO: COMPANY OVERVIEW


TABLE 360
AVIENT CORPORATION: COMPANY OVERVIEW


TABLE 361
RTP COMPANY: COMPANY OVERVIEW


TABLE 362
TEKNI-PLEX, INC.: COMPANY OVERVIEW


TABLE 363
TEKNOR APEX: COMPANY OVERVIEW


TABLE 364
MITSUBISHI CHEMICAL ADVANCED MATERIALS: COMPANY OVERVIEW


TABLE 365
WACKER CHEMIE: COMPANY OVERVIEW


TABLE 366
HARDIE POLYMERS: COMPANY OVERVIEW


TABLE 367
ELIX POLYMERS: COMPANY OVERVIEW


TABLE 368
INNOVATIVE POLYMER COMPOUNDS LTD.: COMPANY OVERVIEW


LIST OF FIGURES


FIGURE 1
MEDICAL POLYMER MARKET SEGMENTATION


FIGURE 2
KEY INSIGHTS AND MARKET HIGHLIGHTS


FIGURE 3
MEDICAL POLYMER MARKET, 2025–2031


FIGURE 4
MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN MEDICAL POLYMER MARKET (2020–2026)


FIGURE 5
DISRUPTIVE TRENDS IMPACTING GROWTH OF MEDICAL POLYMER MARKET DURING FORECAST PERIOD


FIGURE 6
HIGH-GROWTH SEGMENTS AND EMERGING FRONTIERS IN MEDICAL POLYMER MARKET, 2026–2031


FIGURE 7
ASIA PACIFIC TO REGISTER HIGHEST GROWTH DURING FORECAST PERIOD


FIGURE 8
HIGH DEMAND FOR MEDICAL POLYMER SECTOR TO CREATE LUCRATIVE OPPORTUNITIES FOR MARKET PLAYERS


FIGURE 9
CHINA ACCOUNTED FOR LARGEST MARKET SHARE IN 2025


FIGURE 10
EXTRUSION TUBING DOMINATED MEDICAL POLYMER MARKET IN 2025


FIGURE 11
MEDICAL INSTRUMENTS & DEVICES SEGMENT ACCOUNTED FOR LARGEST SHARE OF MEDICAL POLYMER MARKET IN 2025


FIGURE 12
INDIA TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD


FIGURE 13
MEDICAL POLYMER MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES


FIGURE 14
PORTER’S FIVE FORCES ANALYSIS: MEDICAL POLYMER MARKET


FIGURE 15
MEDICAL POLYMER MARKET: VALUE CHAIN ANALYSIS


FIGURE 16
MEDICAL POLYMER MARKET: ECOSYSTEM ANALYSIS


FIGURE 17
AVERAGE SELLING PRICE TREND OF MEDICAL POLYMER, BY REGION, 2023-2025


FIGURE 18
AVERAGE SELLING PRICE TREND OF APPLICATION, BY APPLICATION (2023–2025)


FIGURE 19
IMPORT OF MEDICAL POLYMERS, BY COUNTRY, 2021–2025


FIGURE 20
EXPORT OF MEDICAL POLYMERS, BY COUNTRY, 2021–2025


FIGURE 21
REVENUE SHIFT AND NEW REVENUE POCKETS FOR MEDICAL POLYMER MANUFACTURERS


FIGURE 22
INVESTMENT AND FUNDING SCENARIO, 2021−2025


FIGURE 23
LIST OF MAJOR PATENTS FOR MEDICAL POLYMER, 2016–2025


FIGURE 24
PATENT ANALYSIS, BY LEGAL STATUS


FIGURE 25
TOP JURISDICTION, BY DOCUMENT


FIGURE 26
MEDICAL POLYMER MARKET: DECISION-MAKING FACTORS


FIGURE 27
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP FOUR APPLICATIONS


FIGURE 28
KEY BUYING CRITERIA IN MAJOR APPLICATIONS


FIGURE 29
ADOPTION BARRIERS & INTERNAL CHALLENGES


FIGURE 30
MEDICAL INSTRUMENTS & DEVICES TO ACCOUNT FOR LARGEST MARKET SHARE DURING FORECAST PERIOD


FIGURE 31
MEDICAL PLASTICS SEGMENT TO LEAD MARKET DURING FORECAST PERIOD


FIGURE 32
EXTRUSION TUBING SEGMENT TO LEAD MARKET DURING FORECAST PERIOD


FIGURE 33
MEDICAL POLYMER MARKET SNAPSHOT


FIGURE 34
NORTH AMERICA: MEDICAL POLYMER MARKET SNAPSHOT


FIGURE 35
ASIA PACIFIC: MEDICAL POLYMER MARKET SNAPSHOT


FIGURE 36
EUROPE: MEDICAL POLYMER MARKET SNAPSHOT


FIGURE 37
REVENUE ANALYSIS OF KEY COMPANIES IN MEDICAL POLYMER MARKET, 2022–2025


FIGURE 38
SHARES OF TOP FIVE COMPANIES IN MEDICAL POLYMER MARKET, 2025


FIGURE 39
VALUATION OF KEY COMPANIES IN MEDICAL POLYMER MARKET, 2025


FIGURE 40
FINANCIAL METRICS OF KEY COMPANIES IN MEDICAL POLYMER MARKET, 2025


FIGURE 41
MEDICAL POLYMER MARKET: BRAND/PRODUCT COMPARISON


FIGURE 42
MEDICAL POLYMER MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025


FIGURE 43
MEDICAL POLYMER MARKET: COMPANY FOOTPRINT


FIGURE 44
MEDICAL POLYMER MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025


FIGURE 45
BASF SE: COMPANY SNAPSHOT


FIGURE 46
SABIC: COMPANY SNAPSHOT


FIGURE 47
COVESTRO AG: COMPANY SNAPSHOT


FIGURE 48
CELANESE CORPORATION: COMPANY SNAPSHOT


FIGURE 49
EVONIK INDUSTRIES: COMPANY SNAPSHOT


FIGURE 50
ARKEMA: COMPANY SNAPSHOT


FIGURE 51
SOLVAY: COMPANY SNAPSHOT


FIGURE 52
KURARAY CO., LTD.: COMPANY SNAPSHOT


FIGURE 53
DUPONT: COMPANY SNAPSHOT


FIGURE 54
MEDICAL POLYMER MARKET: RESEARCH DESIGN


FIGURE 55
MEDICAL POLYMER MARKET: BOTTOM-UP APPROACH


FIGURE 56
MEDICAL POLYMER MARKET: TOP-DOWN APPROACH


FIGURE 57
MEDICAL POLYMER MARKET: APPROACH 1


FIGURE 58
MEDICAL POLYMER MARKET: APPROACH 2


FIGURE 59
MEDICAL POLYMER MARKET: DATA TRIANGULATION


Methodology

The study involved four major activities for estimating the current size of the global medical polymer market. Exhaustive secondary research was conducted to collect information on the market, the peer product market, and the parent product group market. The next step was to validate these findings, assumptions, and sizes with industry experts across the value chain of medical polymers through primary research. Both the top-down and bottom-up approaches were employed to estimate the overall size of the medical polymer market. After that, market breakdown and data triangulation procedures were used to determine the size of different segments and sub-segments of the market.

Secondary Research

In the secondary research process, various secondary sources such as Hoovers, Factiva, Bloomberg BusinessWeek, and Dun & Bradstreet were referred to identify and collect information for this study on the medical polymer market. These secondary sources included annual reports, press releases & investor presentations of companies; white papers; certified publications; articles by recognized authors; regulatory bodies, trade directories, and databases.

Primary Research

The medical polymer market comprises several stakeholders in the supply chain, which include raw material suppliers, distributors, end-product manufacturers, buyers, and regulatory organizations. Various primary sources from the supply and demand sides of the market have been interviewed to obtain qualitative and quantitative information. The primary participants from the demand side include key opinion leaders, executives, vice presidents, and CEOs of companies in the medical polymer market. Primary sources from the supply side include associations and institutions involved in the medical polymer market, key opinion leaders, and processing players.

Medical Polymer Market 
 Size, and Share

To know about the assumptions considered for the study, download the pdf brochure

Market Size Estimation

The bottom-up and top-down approaches have been used to estimate the medical polymer market by type, application, manufacturing technology, and region. The research methodology used to calculate the market size includes the following steps:

  • The key players in the industry were identified through extensive secondary research.
  • In terms of value, the industry’s supply chain and market size were determined through primary and secondary research processes.
  • All percentage shares, splits, and breakdowns were determined using secondary sources and verified through primary sources.
  • All possible parameters that affect the markets covered in this research study were accounted for, viewed in extensive detail, verified through primary research, and analyzed to obtain the final quantitative and qualitative data.
  • The research included studying reports, reviews, and newsletters of top market players and extensive interviews with leaders such as directors and marketing executives to obtain opinions.

The following figure illustrates the overall market size estimation process employed for this study.

Medical Polymer Market Top Down and Bottom Up Approach

Data Triangulation

After arriving at the overall size of the medical polymer market from the estimation process explained above, the total market was split into several segments and sub-segments. The data triangulation and market breakdown procedures were employed, wherever applicable, to complete the overall market engineering process and arrive at the exact statistics for all segments and subsegments. The data was triangulated by studying various factors and trends from both the demand and supply sides. Along with this, the market size was validated using both the top-down and bottom-up approaches.

Market Definition

The medical polymer market represents the industry that develops and implements polymer materials intended for medical and healthcare purposes. In the medical sector, these polymers must adhere to strict specifications related to biocompatibility, durability, elasticity and sterilization or aseptic requirements. Various medical products, like surgical instruments, implants, diagnostic devices, drug delivery systems, and disposables, including syringes and gloves, use medical polymers. The market includes many different types of polymers, including medical plastics, elastomer polymers, and biodegradable polymers. The medical polymer market is an important institutional component in the advancement of modern health care through affordable, safe, efficient medical solutions.

Key Stakeholders

  • Medical Polymer Manufacturers
  • Raw Material Suppliers
  • Regulatory Bodies and Government Agencies
  • Distributors and Suppliers
  • End-Use Industries
  • Associations and Industrial Bodies
  • Market Research and Consulting Firms

Report Objectives

  • To define, describe, and forecast the size of the medical polymer market in terms of value and volume
  • To provide detailed information regarding the key factors influencing the growth of the market (drivers, restraints, opportunities, and challenges)
  • To forecast the market size based on type, application, manufacturing technology, and region
  • To forecast the market size for the five main regions—North America, Europe, Asia Pacific (APAC), South America, and the Middle East & Africa (MEA)—along with their key countries
  • To strategically analyze micro markets with respect to individual growth trends, prospects, and contributions to the total market
  • To analyze the opportunities in the market for stakeholders and provide details of the competitive landscape for the market leaders
  • To strategically profile leading players and comprehensively analyze their key developments such as new product launches, expansions, and deals in the medical polymer market
  • To strategically profile key players and comprehensively analyze their market shares and core competencies
  • To study the impact of AI/Gen AI on the market under study, along with the macroeconomic outlook

Available customizations:

With the given market data, MarketsandMarkets offers customizations per the specific needs of companies.

The following customization options are available for the report:

PRODUCT ANALYSIS

  • Product matrix, which provides a detailed comparison of the market for different sources of medical polymer.

REGIONAL ANALYSIS

  • Further breakdown of a country with respect to the medical polymer market.

COMPANY INFORMATION

  • Detailed analysis and profiling of additional market players


Key Questions Addressed by the Report

Which factors are propelling the growth of the medical polymer market?

Increasing demand for minimally invasive surgical procedures, technological advancements in medical devices, the rise in chronic diseases, and the expanding geriatric population requiring healthcare are the primary factors propelling the growth of the medical polymer market.

Which are the key applications driving the medical polymer market?

The key applications driving demand include medical disposables, prosthetics, medical instruments and devices, and others.

Who are the major manufacturers?

Major manufacturers include BASF SE (Germany), SABIC (Saudi Arabia), Covestro AG (Germany), Celanese Corporation (US), and Evonik Industries (Germany).

What will be the growth prospects of the medical polymer market?

The market is expected to witness robust growth due to rising global healthcare needs, advancements in polymer technology, increasing demand for biocompatible materials, and expanding applications such as drug delivery systems and implants.

What will be the growth prospects of the medical polymer market in terms of CAGR in the next five years?

The CAGR of the medical polymer market is expected to be between 8–9% over the next five years.

Personalize This Research

  • Triangulate with your Own Data
  • Get Data as per your Format and Definition
  • Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
  • Any level of Personalization
Request A Free Customisation

Let Us Help You

  • What are the Known and Unknown Adjacencies Impacting the Medical Polymer Market
  • What will your New Revenue Sources be?
  • Who will be your Top Customer; what will make them switch?
  • Defend your Market Share or Win Competitors
  • Get a Scorecard for Target Partners
Customized Workshop Request

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements

Get 10% Free Customisation

TESTIMONIALS

Growth opportunities and latent adjacency in Medical Polymer Market

DMCA.com Protection Status
popup img