Laser Processing Market by Laser Type (Solid Lasers, Gas Lasers, Liquid Lasers), Configuration (Fixed Beam, Moving Beam, Hybrid Beam), Application (Cutting, Welding, Drilling), End User, and Region - Global Forecast to 2033

icon1
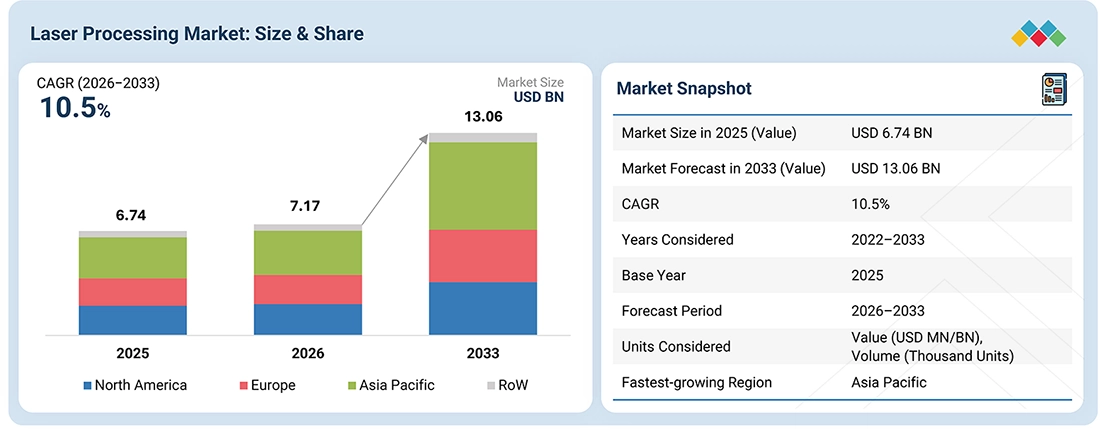
USD 13.06 BN
MARKET SIZE, 2033
icon2
CAGR 10.5%
(2026-2033)
icon3
300
REPORT PAGES
icon4
180
MARKET TABLES

OVERVIEW

Laser-Cutting-Boring-and-Engraving-Machines-Market Overview

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

The laser processing market is projected to reach USD 13.06 billion by 2033 from USD 7.17 billion in 2026, at a CAGR of 10.5% from 2026 to 2033. The market is driven by increasing demand for high-precision manufacturing, rising adoption of automation and robotics across industries, and advancements in laser technology supporting efficient and flexible material processing applications.

KEY TAKEAWAYS

  • BY LASER TYPE
    By laser type, the solid lasers segment is expected to account for the largest share of the laser processing market in 2033 due to their efficiency, reliability, high beam quality, and versatility across industrial applications.
  • BY CONFIGURATION
    The hybrid beam segment is expected to hold a 40.6% share of the laser processing market in 2026, driven by its ability to provide greater processing flexibility and support multiple laser-based operations.
  • BY APPLICATION
    By application, the cutting segment is expected to account for a market share of 30.1% in 2026, driven by its widespread use for high-precision and efficient material processing.
  • BY END-USE INDUSTRY
    By end-use industry, the microelectronics & semiconductors segment accounts for the largest share of the laser processing market due to the increasing demand for precision manufacturing and miniaturization.
  • BY REGION
    By region, Asia Pacific is expected to record a CAGR of 12.0% in the laser processing market from 2026 to 2033.
  • COMPETITIVE LANDSCAPE - KEY PLAYERS
    The laser processing market is characterized by the presence of established players with broad laser source, laser system, and photonics portfolios. Coherent Corp., TRUMPF, Han's Laser Technology Industry Group Co., Ltd., IPG Photonics Corporation, and JENOPTIK AG are among the key players, supported by strong technology capabilities, product innovation, geographic presence, and strategic partnerships, acquisitions, and product launches.
  • COMPETITIVE LANDSCAPE - STARTUPS/SMES
    The laser processing market includes specialized and SME players focusing on niche laser sources, photonics technologies, laser processing equipment, and application-specific solutions. ALPHALAS GmbH, Applied Laser Technology, Inc., Arima Lasers Corp., Focuslight Technologies Inc., Inno Laser Technology Co., Ltd., Photonics Industries International, Inc., SFX, and TOPTICA Photonics AG are among the specialized players addressing targeted industrial, scientific, and high-precision laser processing applications.

The laser processing market is driven by rising demand for advanced manufacturing, miniaturized electronics, and industrial automation. Its applications span medical, automotive, and aerospace sectors for precision material processing. Technological innovations in laser systems and software continue to enhance efficiency and expand adoption across high-tech industries

TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS

The laser processing market is undergoing a shift from traditional toward emerging technologies, driving a new revenue mix across industries. Advancements in solid, liquid, and gas lasers are fueling adoption in sectors such as microelectronics, automotive, aerospace, and medical devices. These innovations align with broader trends such as Industrial IoT (IIoT), AI, cloud computing, and predictive maintenance, which are transforming manufacturing efficiency and precision. As digitalization accelerates, emerging technologies are becoming central to clients’ strategic imperatives and long-term growth outcomes.
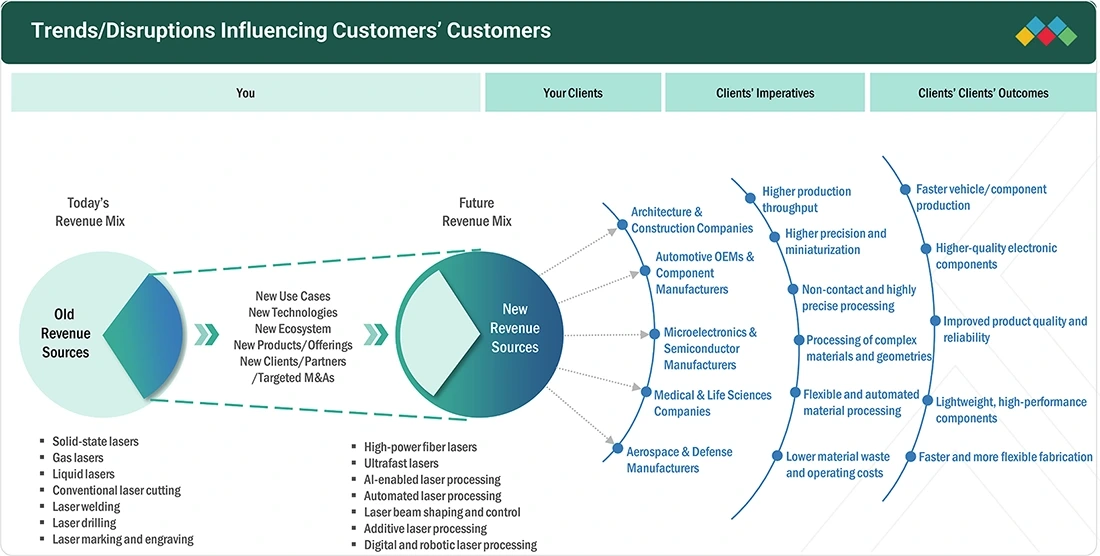
Laser-Cutting-Boring-and-Engraving-Machines-Market Disruptions

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

MARKET DYNAMICS

Drivers
Impact
Level
  • Rising integration of laser technologies in precision healthcare and tailored treatments
  • Rapid transition from traditional material processing methods to advanced laser-based solutions
RESTRAINTS
Impact
Level
  • Significant R&D investment and initial deployment costs
  • Limited availability of skilled laser technicians
OPPORTUNITIES
Impact
Level
  • Expanding use of laser technologies in automotive sector
  • Strong focus on enhancing design, functionality, and personalization of consumer goods
CHALLENGES
Impact
Level
  • Environmental concerns due to reliance on rare-earth elements
  • Technical limitations in high-power laser integration

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Driver: Rising integration of laser technologies in precision healthcare and tailored treatments

Laser processing is a highly valuable tool in the medical industry due to its precision, versatility, and minimally invasive nature. This technique is crucial in the medical industry for offering precise and minimally invasive solutions. Lasers have unique properties, such as focusing on specific tissues, high precision, and minimal collateral damage, making them perfect for medical procedures.

Restraint: Significant R&D investment and initial deployment costs

Research & development investments to advance laser technologies and ensure compliance with safety standards contribute to the high upfront costs. Quality assurance procedures, infrastructure requirements, and the need for customization to suit specific applications contribute to the overall financial commitment associated with deploying laser technology. The applications of lasers are increasing in various industries, such as automotive, semiconductor, industrial, medical, research, and defense.

Opportunity: Expanding use of laser technologies in automotive sector

Laser processing has become a fundamental technology in the automotive industry, improving manufacturing processes and product quality. One of the most crucial applications is laser welding, which allows for the precise and efficient joining of automotive components, including body panels and exhaust systems, resulting in strong and durable bonds. Laser cutting is pivotal in shaping metal sheets for body panels and other intricate parts with unparalleled precision and speed, reducing production time and material waste.

Challenge: Environmental concerns due to reliance on rare-earth elements

The use of rare earth elements (REEs) in laser processing is causing environmental concerns due to the potential negative impacts associated with their extraction, processing, and disposal. Rare earth elements, such as neodymium and dysprosium, are critical in producing certain types of lasers, particularly solid-state lasers used in various applications.

LASER PROCESSING MARKET SIZE, SHARE & TRENDS, 2025 TO 2032: COMMERCIAL USE CASES ACROSS INDUSTRIES

COMPANY USE CASE DESCRIPTION BENEFITS
company logo
High-power fiber lasers for cutting and welding in automotive and electronics manufacturing Precise material processing | Reduced thermal distortion | Increased throughput speeds | Lower operating costs
company logo
Laser systems for sheet metal fabrication and 3D printing (additive manufacturing) in industrial applications High cutting speeds | Exceptional edge quality | Reduced material waste | Flexibility in complex geometries
company logo
UV laser marking and engraving systems for consumer electronics and semiconductor packaging Ultra-fine precision marking | Minimal heat-affected zone | Permanent traceability | High-speed processing
company logo
High-power fiber lasers for metal cutting, welding, and additive manufacturing in aerospace and heavy industry Superior beam quality | Energy efficiency up to 40% better than CO2 lasers | Reduced maintenance | Longer operational life
company logo
Laser material processing systems for micro-machining in medical device manufacturing and photonics Extreme precision at microscale | Minimal material damage | Clean processing without contamination | High repeatability

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET ECOSYSTEM

The laser processing ecosystem comprises raw material suppliers, laser processing system manufacturers, laser processing system distributors, and end-use industries. The ecosystem identifies end-use Industries, such as microelectronics & semiconductors, automotive, medical & life sciences, aerospace, and architecture & construction.
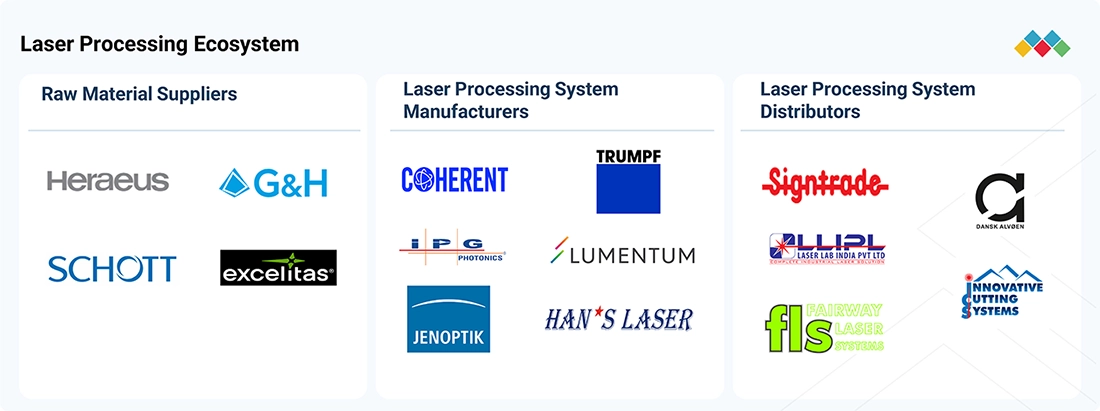
Laser-Cutting-Boring-and-Engraving-Machines-Market Ecosystem

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET SEGMENTS
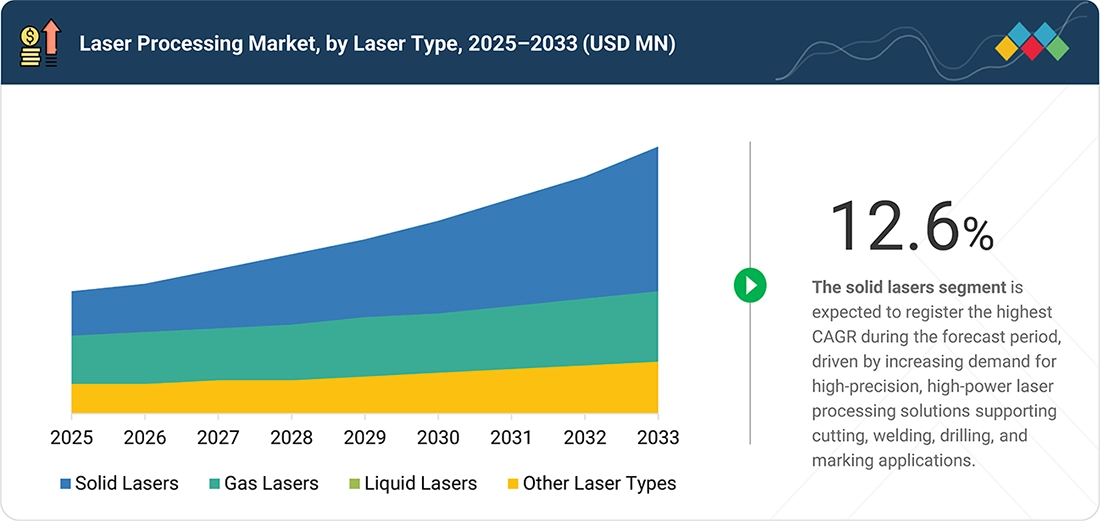
Laser-Cutting-Boring-and-Engraving-Machines-Market Segments

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Laser Processing Market, By Laser Type

The laser processing market encompasses a range of laser types, each tailored for specific industrial, medical, and research applications. This chapter provides a comprehensive overview of the key laser types, including solid lasers, gas lasers, liquid lasers, and other laser types. Solid lasers are further divided into fiber lasers, RUBY lasers, YAG lasers, semiconductor lasers, and thin-disk lasers. Gas lasers are further categorized into CO: lasers, excimer lasers, helium-neon lasers, argon lasers, and chemical lasers, which offer versatile capabilities for cutting, engraving, and medical treatments.

Laser Processing Market, By Configuration

Laser processing is widely used across various industries for applications such as welding, drilling, marking, engraving, and advanced material processing. These processes benefit from high precision, repeatability, and minimal material distortion. Depending on the motion and control of the laser beam relative to the material, laser systems are configured into three main types: fixed beams, moving beams, and hybrid beams. These setups are typically based on movements along the X-axis, Y-axis, and, in some cases, the Z-axis, especially in multi-axis CNC operations. The choice of configuration directly impacts processing speed, efficiency, and quality, making it essential to align the system setup with the specific requirements of the manufacturing process.

Laser Processing Market, By Application

Laser technology has become integral across various industrial applications due to its precision, speed, and versatility. Key applications include cutting, welding, drilling, marking & engraving, advanced processing, and other applications such as ablation, annealing, soldering, and microstructuring, Industries such as automotive, aerospace, electronics, medical devices, and manufacturing are increasingly adopting laser systems to enhance production efficiency, product quality, and customization capabilities. The market growth is driven by rising demand for miniaturized components, increasing automation across sectors, and advancements in laser technology, including ultrafast and fiber lasers.

Laser Processing Market, By End-use Industry

Laser processing has become a vital manufacturing tool across various industries for cutting, welding, engraving, marking, and drilling with high accuracy and minimal material waste. In the machine tools and microelectronics & semiconductors sectors, laser systems support high-speed fabrication and miniaturization. The automotive and medical & life sciences Industries benefit from precision welding and marking for safety and traceability. The aerospace and architecture & construction sectors use laser processing for advanced material handling and complex design implementations. Other end-use industries, such as defense, nuclear, consumer goods, and food & beverages, are increasingly integrating laser solutions for marking, packaging, and clean processing. Laser processing technologies are key in advancing production capabilities as these industries evolve.

REGION

Asia Pacific to register highest CAGR in laser processing market during forecast period.

Asia Pacific is projected to record the highest CAGR in the global laser processing market during the forecast period, driven by its strong manufacturing base in China, Japan, South Korea, and India. The growth is supported by expanding electronics, automotive, and semiconductor industries, along with government-backed automation and R&D initiatives. Emerging hubs such as Vietnam and Thailand are attracting global investments, while digital transformation and smart factory adoption further boost the demand for advanced laser systems.
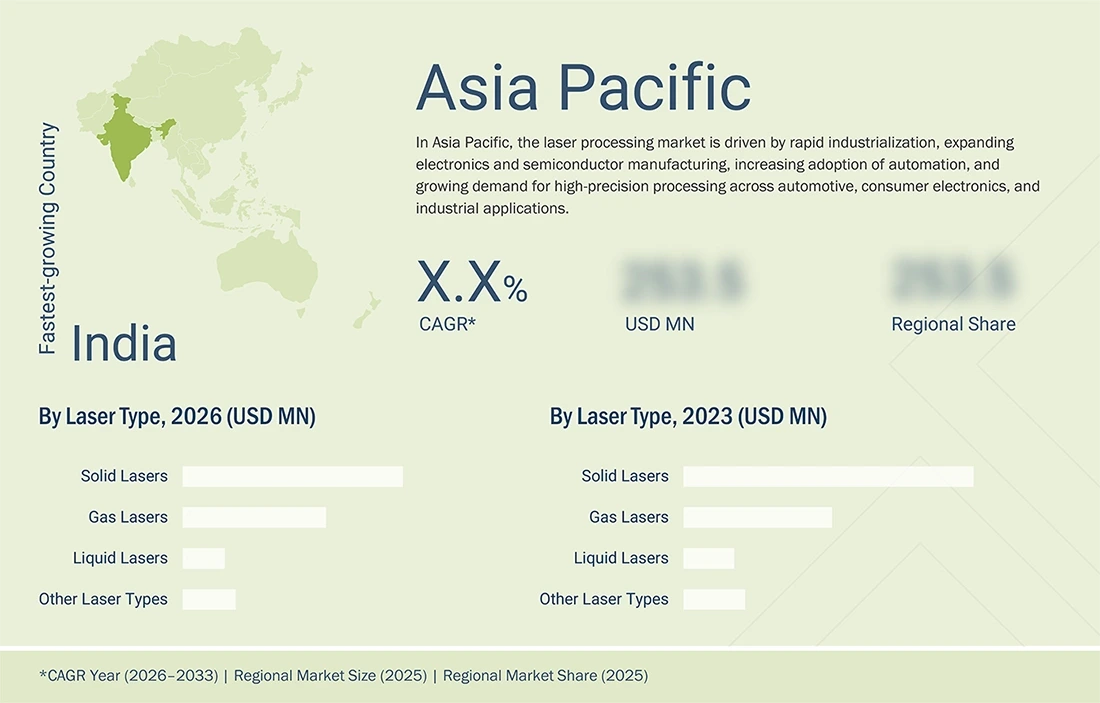
Laser-Cutting-Boring-and-Engraving-Machines-Market Region

LASER PROCESSING MARKET SIZE, SHARE & TRENDS, 2025 TO 2032: COMPANY EVALUATION MATRIX

In the laser processing market, Coherent Corp. (US) and TRUMPF (Germany) are star players with strong portfolios, broad market reach, and strategic innovations driving global adoption. MKS Instruments (US) stands as an emerging leader, leveraging its focused, advanced laser technologies to enhance competitiveness despite a smaller market share.
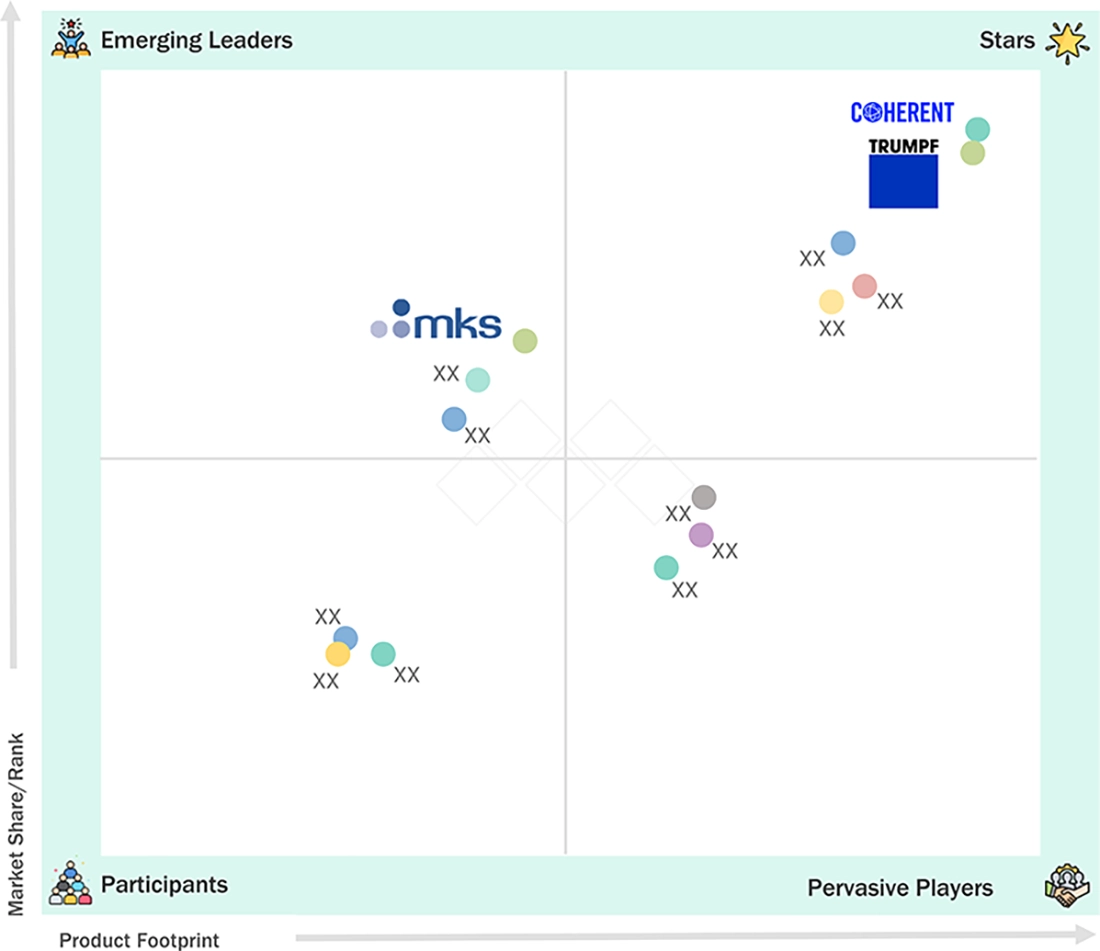
Laser-Cutting-Boring-and-Engraving-Machines-Market Evaluation Metrics

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

KEY MARKET PLAYERS

MARKET SCOPE

REPORT METRIC DETAILS
Market Size in 2025 (Value) USD 6.74 Billion
Market Forecast in 2026 (Value) USD 7.17 Billion
Market Forecast in 2033 (Value) USD 13.06 Billion
CAGR 10.5%
Years Considered 2022–2033
Base Year 2025
Forecast Period 2026–2033
Units Considered Value (USD Billion/Million), Volume (Thousand Units)
Report Coverage Revenue Forecast, Company Ranking, Competitive Landscape, Growth Factors, and Trends
Segments Covered
  • By Laser Type:
    • Solid Lasers (Fiber
    • Ruby
    • YAG
    • Semiconductor
    • Thin-disk Lasers)
    • Gas Lasers (CO2 Lasers
    • Excimer Lasers
    • Helium Neon Lasers
    • Argon Lasers
    • Chemical Lasers)
    • Liquid Lasers
    • Other Laser Types
  • By Configuration:
    • Fixed Beam
    • Moving Beam
    • Hybrid Beam
  • By Application:
    • Cutting
    • Welding
    • Drilling
    • Marking & Engraving
    • Advanced Processing
    • Other Applications
  • By End-use Industry:
    • Microelectronics & Semiconductors
    • Automotive
    • Medical & Life Sciences
    • Aerospace
    • Architecture & Construction
    • Other End-use Industries
Regions Covered North America, Europe, Asia Pacific and RoW

WHAT IS IN IT FOR YOU: LASER PROCESSING MARKET SIZE, SHARE & TRENDS, 2025 TO 2032 REPORT CONTENT GUIDE
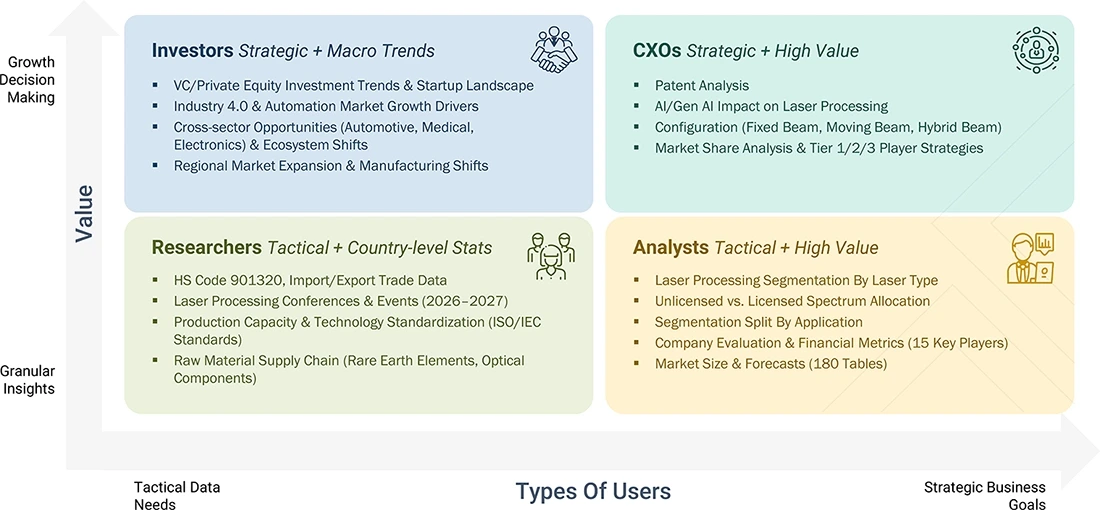
Laser-Cutting-Boring-and-Engraving-Machines-Market Content Guide

DELIVERED CUSTOMIZATIONS

We have successfully delivered the following deep-dive customizations:

CLIENT REQUEST CUSTOMIZATION DELIVERED VALUE ADDS
Laser Equipment OEM
  • Market adoption benchmarking across end-use industries (automotive, aerospace, electronics, medical devices, heavy machinery)
  • Competitive positioning analysis of fiber vs. CO2 vs. solid-state laser technologies
  • Technology roadmap for ultra-short pulse lasers and green/blue wavelength capabilities
  • Regional demand analysis by laser power range (low, medium, high-power systems)
  • Insights on industry-specific adoption drivers and barriers
  • Pinpoint high-growth application segments (EV battery welding, additive manufacturing)
  • Enable targeting of strategic partnerships with system integrators and automation providers
Asia Pacific Laser Processing Startup
  • Competitive landscape mapping of established players (TRUMPF, IPG, Coherent, Han's Laser) and emerging startups
  • Go-to-market strategy benchmarking across direct sales, distributor networks, and online channels
  • Customer acquisition analysis by application segment (micro-machining, marking, welding, cutting)
  • Partnership opportunity mapping with industrial robot manufacturers and CNC machine builders
  • Funding landscape and investor sentiment analysis for laser technology ventures
  • Accelerate market entry with validated use cases
  • Identify whitespace opportunities in underserved applications (textile processing, food packaging)
  • Support Series A/B fundraising with market validation data
  • Enable strategic partnerships for rapid scaling
  • Benchmark against competition for differentiated positioning
Laser Processing System Provider
  • Competitive landscape analysis of complete system providers
  • Technology differentiation mapping across laser source integration, automation levels, and software capabilities
  • Market share analysis by application type (cutting, welding, marking/engraving, cleaning, additive manufacturing)
  • Pricing strategy benchmarking across equipment tiers and service contracts
  • Identify competitive positioning gaps and market whitespace
  • Support product portfolio optimization decisions
  • Enable targeted go-to-market strategies by customer segment
  • Optimize pricing and bundling strategies for maximum market penetration
Laser Processing System Integrator
  • End-user industry demand analysis across automotive, aerospace, electronics, medical devices, and job shops
  • Application-specific use case repository with ROI models and payback period calculations
  • Vendor ecosystem mapping (laser source suppliers, beam delivery systems, motion control, vision systems, safety interlocks)
  • Technology stack benchmarking for modular system design
  • Material processing capability matrix (metals, plastics, ceramics, composites, multi-material)
  • Strengthen technical capabilities for complex custom applications
  • Identify high-value vertical markets for specialization (battery manufacturing, semiconductor packaging)
  • Build strategic vendor relationships for preferred pricing and co-development
  • Develop turnkey solution packages for faster deployment
  • Position for recurring revenue through maintenance contracts and process optimization services
US Based Solid State Laser Provider
  • Competitive benchmarking against fiber laser adoption and technology substitution trends
  • Application-specific market sizing for solid-state laser advantages (ultrafast processing, precision micro-machining, medical applications)
  • Customer segmentation analysis across defense/aerospace, semiconductor, medical device, and research sectors
  • Technology roadmap assessment for diode-pumped solid-state (DPSS) and disk laser innovations
  • Regional market penetration analysis (North America dominance vs. Europe/Asia expansion opportunities)
  • Identify niche application segments where solid-state technology outperforms fiber/CO2 alternatives
  • Support strategic positioning against lower-cost fiber laser competition
  • Enable international expansion strategy with market entry priorities
  • Strengthen value proposition for high-precision, high-quality processing applications
  • Assess vertical integration opportunities vs. partnership models
  • Optimize R&D investment decisions based on emerging application trends

RECENT DEVELOPMENTS

  • September 2026 : TRUMPF introduced the TruLaser Weld 3000, a compact robotic laser welding cell with artificial intelligence (AI)-supported programming. The system uses AI to accelerate programming, while compact welding optics enable access to difficult-to-reach areas. The solution is designed for flexible, automated welding applications and small-batch production.
  • January 2026 : IPG Photonics Corporation showcased a novel 8 kW compact single-mode laser source with high beam quality at SPIE Photonics West 2026. The laser was subsequently recognized with the 2026 SPIE Prism Award in the Lasers category and is designed to deliver higher precision while enabling new industrial processing applications.


Table of Contents

checkmarkExclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.

TITLE
PAGE NO
1
INTRODUCTION


30
2
EXECUTIVE SUMMARY


35
3
PREMIUM INSIGHTS


40
4
MARKET OVERVIEW
Laser technologies drive innovation across sectors, despite cost and skill barriers.


43
 
4.1
INTRODUCTION


4.2
MARKET DYNAMICS


4.2.1
DRIVERS


4.2.1.1
GROWING INTEGRATION OF LASER TECHNOLOGIES IN PRECISION HEALTHCARE AND TAILORED TREATMENTS


4.2.1.2
TRANSITION FROM TRADITIONAL MATERIAL PROCESSING METHODS TO ADVANCED LASER-BASED SOLUTIONS


4.2.1.3
INCREASING DEPENDENCE ON LASER TECHNOLOGIES FOR NANO- AND MICRO-SCALE MANUFACTURING


4.2.1.4
EXPANDING LASER APPLICATIONS IN MARKING AND CODING OPERATIONS


4.2.2
RESTRAINTS


4.2.2.1
SIGNIFICANT R&D INVESTMENT AND INITIAL DEPLOYMENT COSTS


4.2.2.2
LIMITED AVAILABILITY OF SKILLED LASER TECHNICIANS


4.2.3
OPPORTUNITIES


4.2.3.1
EXPANDING USE OF LASER TECHNOLOGIES IN AUTOMOTIVE SECTOR


4.2.3.2
GROWING ADOPTION TO ENHANCE DESIGN, FUNCTIONALITY, AND PERSONALIZATION OF CONSUMER GOODS


4.2.3.3
EXPANDING ROLE IN SCIENTIFIC RESEARCH AND INNOVATION


4.2.4
CHALLENGES


4.2.4.1
ENVIRONMENTAL CONCERNS DUE TO USE OF RARE-EARTH ELEMENTS


4.2.4.2
TECHNICAL LIMITATIONS IN HIGH-POWER LASER INTEGRATION


4.3
UNMET NEEDS AND WHITE SPACES


4.4
INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES


4.5
STRATEGIC MOVES BY TIER 1/2/3 PLAYERS


5
INDUSTRY TRENDS
Navigate industry shifts with strategic insights from Porter’s Five Forces and macroeconomic trends.


56
 
5.1
INTRODUCTION


5.2
PORTER’S FIVE FORCES ANALYSIS


5.2.1
THREAT OF NEW ENTRANTS


5.2.2
THREAT OF SUBSTITUTES


5.2.3
BARGAINING POWER OF SUPPLIERS


5.2.4
BARGAINING POWER OF BUYERS


5.2.5
INTENSITY OF COMPETITIVE RIVALRY


5.3
MACROECONOMIC OUTLOOK


5.3.1
INTRODUCTION


5.3.2
GDP TRENDS AND FORECAST


5.3.3
TRENDS IN GLOBAL MANUFACTURING INDUSTRY


5.3.4
TRENDS IN GLOBAL AUTOMOTIVE AND ELECTRIC VEHICLE INDUSTRY


5.4
SUPPLY CHAIN ANALYSIS


5.5
ECOSYSTEM ANALYSIS


5.6
PRICING ANALYSIS


5.6.1
AVERAGE SELLING PRICE TREND OF LASER TYPE, 2022–2025


5.6.2
AVERAGE SELLING PRICE TREND OF LASER PROCESSING SOLUTIONS, BY REGION, 2022–2025


5.7
TRADE ANALYSIS


5.7.1
IMPORT SCENARIO (HS CODE 901320)


5.7.2
EXPORT SCENARIO (HS CODE 901320)


5.8
KEY CONFERENCES AND EVENTS, 2026–2027


5.9
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS


5.10
INVESTMENT AND FUNDING SCENARIO


5.11
CASE STUDY ANALYSIS


5.12
IMPACT OF US TARIFFS – LASER PROCESSING MARKET


5.12.1
INTRODUCTION


5.12.2
KEY TARIFF RATES


5.12.3
PRICE IMPACT ANALYSIS


5.12.4
IMPACT ON COUNTRIES/REGIONS


5.12.4.1
US


5.12.4.2
EUROPE


5.12.4.3
ASIA PACIFIC


5.12.5
IMPACT ON END-USE INDUSTRIES


6
TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, AND INNOVATIONS
AI-driven innovations revolutionize laser processing, unlocking market potential and transforming industry practices.


79
 
6.1
KEY TECHNOLOGIES


6.1.1
MACHINE LEARNING & ARTIFICIAL INTELLIGENCE


6.1.2
ADDITIVE MANUFACTURING


6.2
COMPLEMENTARY TECHNOLOGIES


6.2.1
LIDAR


6.3
ADJACENT TECHNOLOGIES


6.3.1
FIBER OPTICS


6.4
PATENT ANALYSIS


6.5
IMPACT OF AI ON LASER PROCESSING MARKET


6.5.1
TOP USE CASES AND MARKET POTENTIAL


6.5.2
BEST PRACTICES FOLLOWED BY MANUFACTURERS/OEMS IN LASER PROCESSING MARKET


6.5.3
CASE STUDIES RELATED TO AI IMPLEMENTATION IN LASER PROCESSING MARKET


6.5.4
INTERCONNECTED/ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS


6.5.5
CLIENTS’ READINESS TO ADOPT AI IN LASER PROCESSING MARKET


6.6
REGULATORY LANDSCAPE


6.6.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


6.6.2
STANDARDS


6.6.2.1
IEC 60825-1:2014


6.6.2.2
ANSI Z136.1


6.6.2.3
FEDERAL LASER PRODUCT PERFORMANCE STANDARD (FLPPS)


6.6.2.4
INTERNATIONAL COMMISSION ON NON-IONIZING RADIATION PROTECTION (ICNIRP) (2013)


6.6.2.5
EN 60825 – SAFETY OF LASER PRODUCTS


7
CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
Unlock buyer behavior insights by understanding stakeholder influence and unmet needs across key industries.


95
 
7.1
DECISION-MAKING PROCESS


7.2
KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR BUYING CRITERIA


7.2.1
KEY STAKEHOLDERS IN BUYING PROCESS


7.2.2
BUYING CRITERIA


7.3
ADOPTION BARRIERS AND INTERNAL CHALLENGES


7.4
UNMET NEEDS OF VARIOUS END-USE INDUSTRIES


8
COMPONENTS OF LASER PROCESSING DEVICES
Explore the pivotal components driving efficiency and precision in advanced laser processing systems.


100
 
8.1
INTRODUCTION


8.2
LASERS


8.3
LASER SYSTEMS


9
LASER PROCESSING MARKET, BY LASER TYPE
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million and Units | 16 Data Tables


102
 
9.1
INTRODUCTION


9.2
SOLID LASERS


9.2.1
FIBER LASERS


9.2.1.1
RISING ADOPTION IN CUTTING, WELDING, AND MARKING APPLICATIONS TO DRIVE SEGMENTAL GROWTH


9.2.2
RUBY LASERS


9.2.2.1
SUSTAINED DEMAND IN DERMATOLOGY AND SCIENTIFIC RESEARCH TO SUPPORT SEGMENTAL GROWTH


9.2.3
YAG LASERS


9.2.3.1
GROWING USE IN HIGH-PRECISION WELDING AND CUTTING TO PROPEL SEGMENTAL GROWTH


9.2.4
SEMICONDUCTOR LASERS


9.2.4.1
INCREASING DEPLOYMENT IN ADDITIVE MANUFACTURING AND COMPACT LASER SYSTEMS TO BOOST SEGMENTAL GROWTH


9.2.5
THIN-DISK LASERS


9.2.5.1
RISING NEED FOR HIGH-POWER, HIGH-BEAM QUALITY PROCESSING TO ACCELERATE SEGMENTAL GROWTH


9.3
GAS LASERS


9.3.1
CO2 LASERS


9.3.1.1
RISING DEMAND FOR CONTACTLESS PROCESSING OF NON-METALLIC MATERIALS TO DRIVE SEGMENTAL GROWTH


9.3.2
EXCIMER LASERS


9.3.2.1
EXPANDING USE IN SEMICONDUCTOR PHOTOLITHOGRAPHY AND VISION CORRECTION TO PROPEL SEGMENTAL GROWTH


9.3.3
HELIUM-NEON LASERS


9.3.3.1
SUSTAINED NEED FOR PRECISION ALIGNMENT AND MEASUREMENT TOOLS TO SUPPORT SEGMENTAL GROWTH


9.3.4
ARGON LASERS


9.3.4.1
CONTINUED ADOPTION IN OPHTHALMIC PROCEDURES AND SCIENTIFIC RESEARCH TO BOOST SEGMENTAL GROWTH


9.3.5
CHEMICAL LASERS


9.3.5.1
GROWING INVESTMENTS IN DEFENSE AND HIGH-ENERGY RESEARCH TO SUSTAIN SEGMENTAL GROWTH


9.4
LIQUID LASERS


9.4.1
ELEVATING DEPLOYMENT IN VEGETATION AND LAND COVER STUDIES TO DRIVE MARKET


9.5
OTHER LASER TYPES


10
LASER PROCESSING MARKET, BY CONFIGURATION
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million | 9 Data Tables


116
 
10.1
INTRODUCTION


10.2
FIXED BEAMS


10.2.1
EVOLUTION OF MOTION CONTROL AND CNC SYSTEMS TO SUPPORT MARKET EXPANSION


10.3
MOVING BEAMS


10.3.1
GOVERNMENT INVESTMENTS SUPPORTING SMART MANUFACTURING INITIATIVES TO FUEL MARKET GROWTH


10.4
HYBRID BEAMS


10.4.1
RISING FOCUS ON REDUCING PRODUCTION CYCLE TIMES AND IMPROVING PRODUCT QUALITY TO ACCELERATE DEMAND


11
LASER PROCESSING MARKET, BY APPLICATION
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million | 2 Data Tables


123
 
11.1
INTRODUCTION


11.2
CUTTING


11.2.1
ADVANCEMENTS IN MANUFACTURING SECTOR TO DRIVE SEGMENTAL GROWTH


11.3
WELDING


11.3.1
GROWTH IN ELECTRIC VEHICLE AND BATTERY PRODUCTION TO SUPPORT MARKET GROWTH


11.4
DRILLING


11.4.1
GROWING DEMAND FOR HIGH-PRECISION MICROFABRICATION TO FUEL MARKET GROWTH


11.5
MARKING & ENGRAVING


11.5.1
RISING USE OF LASER ENGRAVING IN MEDICAL DEVICE PRODUCTION FOR PRECISION AND STERILITY TO PROPEL MARKET


11.6
ADVANCED PROCESSING


11.6.1
ADVANCEMENTS IN ADDITIVE MANUFACTURING IN INDUSTRIAL AND HEALTHCARE SECTORS TO FOSTER MARKET GROWTH


11.7
OTHER APPLICATIONS


12
LASER PROCESSING MARKET, BY END-USE INDUSTRY
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million | 87 Data Tables


129
 
12.1
INTRODUCTION


12.1.1
KEY COMPETITORS


12.2
MICROELECTRONICS & SEMICONDUCTORS


12.2.1
MINIATURIZATION AND RISING CIRCUIT COMPLEXITY TO ACCELERATE DEMAND FOR ADVANCED LASER PROCESSING


12.2.2
CASE STUDY ANALYSIS


12.2.3
PCB DRILLING & CUTTING


12.2.4
WAFER DICING


12.2.5
OLED DISPLAY PATTERNING


12.2.5.1
LIST OF CLIENTS IN MICROELECTRONICS & SEMICONDUCTORS INDUSTRY


12.3
AUTOMOTIVE


12.3.1
SHIFT TOWARD LIGHTWEIGHT MATERIALS, ELECTRIC VEHICLES, AND AUTOMATED MANUFACTURING TO DRIVE MARKET


12.3.2
CASE STUDY ANALYSIS


12.3.3
BODY PANEL WELDING


12.3.4
BATTERY WELDING


12.3.5
PLASTIC COMPONENT MARKING


12.3.5.1
LIST OF CLIENTS IN AUTOMOTIVE INDUSTRY


12.4
MEDICAL & LIFE SCIENCES


12.4.1
ACCELERATED DEMAND FOR PRECISION AND MINIATURIZATION IN MEDICAL DEVICES TO FUEL MARKET GROWTH


12.4.2
CASE STUDY ANALYSIS


12.4.3
MEDICAL DEVICE MANUFACTURING


12.4.4
LASER MICROMACHINING FOR STENTS


12.4.5
DNA AND CELL MANIPULATION


12.4.5.1
LIST OF CLIENTS IN MEDICAL & LIFE SCIENCES INDUSTRY


12.5
AEROSPACE


12.5.1
RISING FOCUS ON REDUCING MATERIAL WASTE AND EXPEDITING PRODUCTION TO STIMULATE DEMAND


12.5.2
CASE STUDY ANALYSIS


12.5.3
AIRCRAFT COMPONENT WELDING


12.5.4
COMPOSITE MATERIAL PROCESSING


12.5.5
LASER RANGE FINDERS & TARGETING SYSTEMS


12.5.5.1
LIST OF CLIENTS IN AEROSPACE INDUSTRY


12.6
ARCHITECTURE & CONSTRUCTION


12.6.1
HEIGHTENED USE OF AUTOMATED AND DIGITALLY CONTROLLED FABRICATION TO SUPPORT MARKET EXPANSION


12.6.2
CASE STUDY ANALYSIS


12.6.3
DECORATIVE LASER CUTTING


12.6.4
INTERIOR & FACADE ENGRAVING


12.6.4.1
LIST OF CLIENTS IN ARCHITECTURE & CONSTRUCTION INDUSTRY


12.7
OTHER END-USE INDUSTRIES


12.7.1
CASE STUDY ANALYSIS


12.7.1.1
LIST OF CLIENTS IN OTHER END-USE INDUSTRIES


13
LASER PROCESSING MARKET, BY REGION
Comprehensive coverage of 8 Regions with country-level deep-dive of 22 Countries | 90 Data Tables.


175
 
13.1
INTRODUCTION


13.2
NORTH AMERICA


13.2.1
US


13.2.1.1
GROWING NEED FOR MICRO-PROCESSING IN ELECTRONICS MANUFACTURING TO DRIVE MARKET GROWTH


13.2.2
CANADA


13.2.2.1
GOVERNMENT-BACKED INNOVATIONS IN OPTICS AND PHOTONICS SEGMENT TO SUPPORT MARKET GROWTH


13.2.3
MEXICO


13.2.3.1
DEVELOPMENT OF SMART MANUFACTURING HUBS TO FOSTER MARKET EXPANSION


13.3
EUROPE


13.3.1
UK


13.3.1.1
INCREASING INVESTMENTS IN PHOTONICS AND LASER RESEARCH AND DEVELOPMENT TO PROPEL MARKET GROWTH


13.3.2
GERMANY


13.3.2.1
STRONG INDUSTRIAL FOUNDATION AND INVESTMENTS IN ADVANCED MANUFACTURING TECHNOLOGIES TO FACILITATE DEMAND


13.3.3
FRANCE


13.3.3.1
EXPANDING MEDICAL, PHARMACEUTICALS, AND TEXTILES SECTORS TO CREATE GROWTH OPPORTUNITIES


13.3.4
ITALY


13.3.4.1
EXPANSION OF LOCAL DISTRIBUTION NETWORK THROUGH INTERNATIONAL COLLABORATIONS TO SUPPORT MARKET GROWTH


13.3.5
SPAIN


13.3.5.1
INVESTMENTS IN AUTOMATION AND SMART MANUFACTURING TO CONTRIBUTE TO MARKET GROWTH


13.3.6
NETHERLANDS


13.3.6.1
GROWTH IN HIGH-TECH AND PRECISION MANUFACTURING INDUSTRIES TO SUPPORT MARKET GROWTH


13.3.7
SWITZERLAND


13.3.7.1
STRONG FOUNDATION AND INNOVATION IN PRECISION ENGINEERING AND PHOTONICS TO CONTRIBUTE TO MARKET GROWTH


13.3.8
POLAND


13.3.8.1
GROWING DEMAND FOR PRECISION MANUFACTURING IN ELECTRONICS AND SEMICONDUCTORS TO DRIVE MARKET


13.3.9
NORDICS


13.3.9.1
EMPHASIS ON ADVANCED MANUFACTURING, HEALTHCARE INNOVATION, AND SUSTAINABILITY TO FUEL DEMAND


13.3.10
REST OF EUROPE


13.4
ASIA PACIFIC


13.4.1
CHINA


13.4.1.1
EXPANSION OF WAFER FABRICATION, ADVANCED PACKAGING, AND SEMICONDUCTOR EQUIPMENT MANUFACTURING TO PROPEL MARKET


13.4.2
JAPAN


13.4.2.1
PRESENCE OF WELL-ESTABLISHED MANUFACTURING SECTOR TO OFFER LUCRATIVE GROWTH OPPORTUNITIES


13.4.3
SOUTH KOREA


13.4.3.1
ADVANCEMENT IN ADDITIVE MANUFACTURING AND 3D PRINTING TECHNOLOGIES TO ANTICIPATE POSITIVE MARKET GROWTH


13.4.4
INDIA


13.4.4.1
GROWING PRESENCE OF INTERNATIONAL LASER TECHNOLOGY PROVIDERS TO CONTRIBUTE TO MARKET GROWTH


13.4.5
AUSTRALIA


13.4.5.1
STRATEGIC PARTNERSHIPS STRENGTHENING SOVEREIGN MANUFACTURING CAPABILITIES TO SUPPORT MARKET GROWTH


13.4.6
INDONESIA


13.4.6.1
GOVERNMENT FOCUS ON SEMICONDUCTOR INDUSTRY DEVELOPMENT TO FUEL MARKET GROWTH


13.4.7
MALAYSIA


13.4.7.1
THRIVING SEMICONDUCTOR INDUSTRY TO CREATE LUCRATIVE GROWTH OPPORTUNITIES


13.4.8
THAILAND


13.4.8.1
TECHNOLOGY TRANSFER FROM SOUTH KOREAN CHIPMAKER TO SUPPORT MARKET GROWTH


13.4.9
VIETNAM


13.4.9.1
INCREASING DEMAND FOR LASER PROCESSING SOLUTIONS FROM BATTERY MANUFACTURERS TO FUEL MARKET GROWTH


13.4.10
REST OF ASIA PACIFIC


13.5
ROW


13.5.1
MIDDLE EAST


13.5.1.1
BAHRAIN


13.5.1.1.1
STRATEGIC FOCUS ON INDUSTRIAL MODERNIZATION TO SPUR DEMAND FOR LASER PROCESSING


13.5.1.2
KUWAIT


13.5.1.2.1
POLICIES UNDER KUWAIT VISION 2035 STRATEGY TO SUPPORT MARKET GROWTH


13.5.1.3
OMAN


13.5.1.3.1
RISING IMPORTANCE OF LASER-BASED SOLUTIONS IN COMMERCIAL AND INDUSTRIAL APPLICATIONS TO SUPPORT MARKET GROWTH


13.5.1.4
QATAR


13.5.1.4.1
INVESTMENT IN ADVANCED MANUFACTURING AND CLEAN ENERGY TRANSITION TO CONTRIBUTE TO MARKET GROWTH


13.5.1.5
SAUDI ARABIA


13.5.1.5.1
EXPANSION OF DOMESTIC MANUFACTURING CAPABILITIES USING ADVANCED TECHNOLOGIES TO FUEL MARKET GROWTH


13.5.1.6
UAE


13.5.1.6.1
INVESTMENT IN ADVANCED BATTERY MANUFACTURING TECHNOLOGIES TO FACILITATE MARKET GROWTH


13.5.1.7
REST OF MIDDLE EAST


13.5.2
SOUTH AMERICA


13.5.2.1
MAJOR INDUSTRIAL TRADE FAIRS PROMOTING TECHNOLOGY AWARENESS TO STRENGTHEN MARKET EXPANSION


13.5.3
AFRICA


13.5.4
SOUTH AFRICA


13.5.4.1
RISING VENTURE CAPITAL INVESTMENT IN ICT SECTOR TO BOOST ADOPTION


13.5.5
OTHER AFRICAN COUNTRIES


14
COMPETITIVE LANDSCAPE
Uncover strategic moves and market dominance tactics shaping the competitive landscape through 2026.


226
 
14.1
OVERVIEW


14.2
KEY PLAYER COMPETITIVE STRATEGIES, RIGHT TO WIN, 2024–2026


14.3
MARKET SHARE ANALYSIS, 2025


14.4
REVENUE ANALYSIS


14.5
COMPANY VALUATION AND FINANCIAL METRICS


14.6
BRAND/PRODUCT COMPARISON


14.7
COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025


14.7.1
STARS


14.7.2
EMERGING LEADERS


14.7.3
PERVASIVE PLAYERS


14.7.4
PARTICIPANTS


14.7.5
COMPANY FOOTPRINT: KEY PLAYERS, 2025


14.7.5.1
COMPANY FOOTPRINT


14.7.5.2
REGION FOOTPRINT


14.7.5.3
LASER TYPE FOOTPRINT


14.7.5.4
APPLICATION FOOTPRINT


14.7.5.5
END-USE INDUSTRY FOOTPRINT


14.8
COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025


14.8.1
PROGRESSIVE COMPANIES


14.8.2
RESPONSIVE COMPANIES


14.8.3
DYNAMIC COMPANIES


14.8.4
STARTING BLOCKS


14.8.5
COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025


14.8.5.1
DETAILED LIST OF ADDITIONAL START UPS/SMES


14.8.5.2
COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES


14.9
COMPETITIVE SCENARIO


14.9.1
PRODUCT LAUNCHES


14.9.2
DEALS


14.9.3
EXPANSIONS


15
COMPANY PROFILES
In-depth Company Profiles of Leading Market Players with detailed Business Overview, Product and Service Portfolio, Recent Developments, and Unique Analyst Perspective (MnM View)


248
 
15.1
KEY PLAYERS


15.1.1
COHERENT CORP.


15.1.1.1
BUSINESS OVERVIEW


15.1.1.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


15.1.1.3
RECENT DEVELOPMENTS


15.1.1.3.1
PRODUCT LAUNCHES


15.1.1.4
MNM VIEW


15.1.1.4.1
KEY STRENGTHS/RIGHT TO WIN


15.1.1.4.2
STRATEGIC CHOICES


15.1.1.4.3
WEAKNESSES/COMPETITIVE THREATS


15.1.2
TRUMPF


15.1.3
HAN’S LASER TECHNOLOGY INDUSTRY GROUP CO., LTD.


15.1.4
IPG PHOTONICS CORPORATION


15.1.5
JENOPTIK AG


15.1.6
FIVES


15.1.7
AXBIS


15.1.8
LUMENTUM OPERATIONS LLC


15.1.9
GRAVOTECH, INC.


15.1.10
LASER STAR TECHNOLOGIES


15.1.11
LUMIBIRD


15.1.12
EPILOG LASER


15.1.13
MKS INSTRUMENTS


15.1.14
NOVANTA INC.


15.1.15
EUROLASER GMBH


15.2
OTHER PLAYERS


15.2.1
600 GROUP PLC


15.2.2
BYSTRONIC GROUP


15.2.3
ALPHALAS GMBH


15.2.4
APPLIED LASER TECHNOLOGY, INC.


15.2.5
ARIMA LASERS CORP.


15.2.6
FOCUSLIGHT TECHNOLOGIES INC.


15.2.7
INNO LASER TECHNOLOGY CO., LTD.


15.2.8
NKT PHOTONICS A/S


15.2.9
PHOTONICS INDUSTRIES INTERNATIONAL. INC.


15.2.10
SFX


15.2.11
TOPTICA PHOTONICS AG


15.2.12
UNIVERSAL LASER SYSTEMS, INC.


16
RESEARCH METHODOLOGY


315
 
16.1
RESEARCH DATA


16.1.1
SECONDARY DATA


16.1.1.1
MAJOR SECONDARY SOURCES


16.1.1.2
KEY DATA FROM SECONDARY SOURCES


16.1.2
PRIMARY DATA


16.1.2.1
PARTICIPANTS IN PRIMARY INTERVIEWS


16.1.2.2
KEY DATA FROM PRIMARY SOURCES


16.1.2.3
KEY INDUSTRY INSIGHTS


16.1.2.4
BREAKDOWN OF PRIMARIES


16.1.3
SECONDARY AND PRIMARY RESEARCH


16.2
MARKET SIZE ESTIMATION


16.2.1
BOTTOM-UP APPROACH


16.2.1.1
APPROACH TO ESTIMATE MARKET SIZE THROUGH BOTTOM-UP ANALYSIS (DEMAND SIDE)


16.2.2
TOP-DOWN APPROACH


16.2.2.1
APPROACH TO ESTIMATE MARKET SIZE THROUGH TOP-DOWN ANALYSIS (SUPPLY SIDE)


16.2.2.2
APPROACH TO ESTIMATE MARKET SIZE FROM SUPPLY SIDE (APPROACH 1)


16.2.2.3
APPROACH TO ESTIMATE MARKET SIZE FROM SUPPLY SIDE (APPROACH 2)


16.3
DATA TRIANGULATION


16.4
RESEARCH ASSUMPTIONS


16.5
PARAMETERS CONSIDERED TO ANALYZE RECESSION IMPACT ON LASER PROCESSING MARKET


16.6
RISK ASSESSMENT


16.7
RESEARCH LIMITATIONS


17
APPENDIX


329
 
17.1
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL


17.2
CUSTOMIZATION OPTIONS


17.3
RELATED REPORTS


17.4
AUTHOR DETAILS


LIST OF TABLES


TABLE 1
INCLUSIONS AND EXCLUSIONS


TABLE 2
SUMMARY OF CHANGES IMPLEMENTED IN UPDATED REPORT VERSION


TABLE 3
KEY STRATEGIC FOCUS OF TIER 1/2/ 3 PLAYERS


TABLE 4
IMPACT OF PORTER’S FIVE FORCES ANALYSIS


TABLE 5
GDP PERCENTAGE CHANGE, BY COUNTRY, 2021–2030


TABLE 6
ROLE OF COMPANIES IN LASER PROCESSING ECOSYSTEM


TABLE 7
AVERAGE SELLING PRICE TREND OF LASER TYPE, 2022–2025 (USD)


TABLE 8
AVERAGE SELLING PRICE TREND OF LASER PROCESSING SOLUTIONS, BY REGION, 2022–2025 (USD)


TABLE 9
IMPORT DATA FOR HS CODE 901320-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025 (USD MILLION)


TABLE 10
EXPORT DATA FOR HS CODE 901320-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025 (USD MILLION)


TABLE 11
LIST OF KEY CONFERENCES AND EVENTS, 2026–2027


TABLE 12
ENHANCING COPPER LASER WELDING WITH CANUNDA-HP AT INSTITUT MAUPERTUIS


TABLE 13
TRANSITIONING FROM GRIT BLASTING TO LASER TEXTURING WITH LASERAX


TABLE 14
ENHANCING ENGINEERING EDUCATION WITH HPC LASER CUTTER AT UNIVERSITY OF MANCHESTER


TABLE 15
ENHANCING CHIMNEY & BOILER MANUFACTURING WITH LASER ISSE'S FULLY AUTOMATED LASER WELDING LINE


TABLE 16
IMPROVING BIOMEDICAL RESEARCH WITH VORTRAN LASER’S LIFE CANVAS TECHNOLOGY


TABLE 17
US-ADJUSTED RECIPROCAL TARIFF RATES


TABLE 18
EVOLUTION OF LASER PROCESSING TECHNOLOGIES


TABLE 19
LASER PROCESSING MARKET: LIST OF MAJOR PATENTS, 2021–2024


TABLE 20
KEY USE CASES AND MARKET POTENTIAL


TABLE 21
BEST PRACTICES ADOPTED BY MARKET PLAYERS, BY USE CASE


TABLE 22
LASER PROCESSING MARKET: CASE STUDIES RELATED TO AI IMPLEMENTATION


TABLE 23
INTERCONNECTED/ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS


TABLE 24
NORTH AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 25
EUROPE: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 26
ASIA PACIFIC: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 27
ROW: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 28
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP 3 END-USE INDUSTRIES (%)


TABLE 29
KEY BUYING CRITERIA FOR TOP 3 END-USE INDUSTRIES


TABLE 30
UNMET NEEDS IN LASER PROCESSING MARKET, BY END USER


TABLE 31
LASER PROCESSING MARKET, BY LASER TYPE, 2022–2025 (USD MILLION)


TABLE 32
LASER PROCESSING MARKET, BY LASER TYPE, 2026–2033 (USD MILLION)


TABLE 33
LASER PROCESSING MARKET, BY LASER TYPE, 2022–2025 (THOUSAND UNITS)


TABLE 34
LASER PROCESSING MARKET, BY LASER TYPE, 2026–2033 (THOUSAND UNITS)


TABLE 35
SOLID LASERS: LASER PROCESSING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 36
SOLID LASERS: LASER PROCESSING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 37
SOLID LASERS: LASER PROCESSING MARKET, BY TYPE, 2022–2025 (USD MILLION)


TABLE 38
SOLID LASERS: LASER PROCESSING MARKET, BY TYPE, 2026–2033 (USD MILLION)


TABLE 39
GAS LASERS: LASER PROCESSING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 40
GAS LASERS: LASER PROCESSING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 41
GAS LASERS: LASER PROCESSING MARKET, BY TYPE, 2022–2025 (USD MILLION)


TABLE 42
GAS LASERS: LASER PROCESSING MARKET, BY TYPE, 2026–2033 (USD MILLION)


TABLE 43
LIQUID LASERS: LASER PROCESSING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 44
LIQUID LASERS: LASER PROCESSING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 45
OTHER LASER TYPES: LASER PROCESSING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 46
OTHER LASER TYPES: LASER PROCESSING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 47
LASER PROCESSING MARKET, BY CONFIGURATION, 2022–2025 (USD MILLION)


TABLE 48
LASER PROCESSING MARKET, BY CONFIGURATION, 2026–2033 (USD MILLION)


TABLE 49
FIXED BEAMS: LASER PROCESSING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 50
FIXED BEAMS: LASER PROCESSING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 51
MOVING BEAMS: LASER PROCESSING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 52
MOVING BEAMS: LASER PROCESSING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 53
HYBRID BEAMS: LASER PROCESSING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 54
HYBRID BEAMS: LASER PROCESSING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 55
COMPARISON OF LASER PROCESSING CONFIGURATIONS


TABLE 56
LASER PROCESSING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)


TABLE 57
LASER PROCESSING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)


TABLE 58
LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 59
LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 60
KEY COMPETITORS OFFERING LASER PROCESSING SYSTEMS


TABLE 61
MICROELECTRONICS & SEMICONDUCTORS: LASER PROCESSING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 62
MICROELECTRONICS & SEMICONDUCTORS: LASER PROCESSING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 63
MICROELECTRONICS & SEMICONDUCTORS: LASER PROCESSING MARKET IN NORTH AMERICA, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 64
MICROELECTRONICS & SEMICONDUCTORS: LASER PROCESSING MARKET IN NORTH AMERICA, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 65
MICROELECTRONICS & SEMICONDUCTORS: LASER PROCESSING MARKET IN EUROPE, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 66
MICROELECTRONICS & SEMICONDUCTORS: LASER PROCESSING MARKET IN EUROPE, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 67
MICROELECTRONICS & SEMICONDUCTORS: LASER PROCESSING MARKET IN ASIA PACIFIC, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 68
MICROELECTRONICS & SEMICONDUCTORS: LASER PROCESSING MARKET IN ASIA PACIFIC, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 69
MICROELECTRONICS & SEMICONDUCTORS: LASER PROCESSING MARKET IN ROW, BY REGION, 2022–2025 (USD MILLION)


TABLE 70
MICROELECTRONICS & SEMICONDUCTORS: LASER PROCESSING MARKET IN ROW, BY REGION, 2026–2033 (USD MILLION)


TABLE 71
ENHANCING WAFER DOWNSIZING WITH PRECISION LASER MICROJET TECHNOLOGY


TABLE 72
PRECISION SINGULATION OF ULTRA-THIN SILICON WAFERS USING WATER-GUIDED LASERS


TABLE 73
ENHANCING PRECISION AND EFFICIENCY IN DICING OF HIGH-DENSITY CIRCUITS


TABLE 74
COST REDUCTION AND QUALITY IMPROVEMENT IN WAFER DICING


TABLE 75
CLIENTS IN MICROELECTRONICS & SEMICONDUCTORS INDUSTRY


TABLE 76
AUTOMOTIVE: LASER PROCESSING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 77
AUTOMOTIVE: LASER PROCESSING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 78
AUTOMOTIVE: LASER PROCESSING MARKET IN NORTH AMERICA, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 79
AUTOMOTIVE: LASER PROCESSING MARKET IN NORTH AMERICA, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 80
AUTOMOTIVE: LASER PROCESSING MARKET IN EUROPE, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 81
AUTOMOTIVE: LASER PROCESSING MARKET IN EUROPE, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 82
AUTOMOTIVE: LASER PROCESSING MARKET IN ASIA PACIFIC, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 83
AUTOMOTIVE: LASER PROCESSING MARKET IN ASIA PACIFIC, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 84
AUTOMOTIVE: LASER PROCESSING MARKET IN ROW, BY REGION, 2022–2025 (USD MILLION)


TABLE 85
AUTOMOTIVE: LASER PROCESSING MARKET IN ROW, BY REGION, 2026–2033 (USD MILLION)


TABLE 86
ENHANCING TRACEABILITY IN HARSH DIE CASTING ENVIRONMENTS WITH LASER MARKING


TABLE 87
PRECISION E-COATING REMOVAL FOR AUTOMOTIVE SEAT RAIL WELDING


TABLE 88
IMPROVING PRODUCTIVITY AND PRECISION IN 3D LASER CUTTING FOR AUTOMOTIVE MANUFACTURING


TABLE 89
LIST OF CLIENTS IN AUTOMOTIVE INDUSTRY


TABLE 90
MEDICAL & LIFE SCIENCES: LASER PROCESSING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 91
MEDICAL & LIFE SCIENCES: LASER PROCESSING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 92
MEDICAL & LIFE SCIENCES: LASER PROCESSING MARKET IN NORTH AMERICA, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 93
MEDICAL & LIFE SCIENCES: LASER PROCESSING MARKET IN NORTH AMERICA, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 94
MEDICAL & LIFE SCIENCES: LASER PROCESSING MARKET IN EUROPE, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 95
MEDICAL & LIFE SCIENCES: LASER PROCESSING MARKET IN EUROPE, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 96
MEDICAL & LIFE SCIENCES: LASER PROCESSING MARKET IN ASIA PACIFIC, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 97
MEDICAL & LIFE SCIENCES: LASER PROCESSING MARKET IN ASIA PACIFIC, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 98
MEDICAL & LIFE SCIENCES: LASER PROCESSING MARKET IN ROW, BY REGION, 2022–2025 (USD MILLION)


TABLE 99
MEDICAL & LIFE SCIENCES: LASER PROCESSING MARKET IN ROW, BY REGION, 2026–2033 (USD MILLION)


TABLE 100
PRECISION CUTTING OF SILICON BLADES FOR OPHTHALMIC SURGERY


TABLE 101
ENHANCING STENT MANUFACTURING WITH LASER MICROJET TECHNOLOGY


TABLE 102
ACHIEVING DURABLE AND PRECISE MARKINGS FOR MEDICAL DEVICES


TABLE 103
PRECISION LASER MARKING AND CUTTING FOR NEUROSURGICAL IMPLANTS


TABLE 104
CLIENTS IN MEDICAL & LIFE SCIENCES INDUSTRY


TABLE 105
AEROSPACE: LASER PROCESSING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 106
AEROSPACE: LASER PROCESSING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 107
AEROSPACE: LASER PROCESSING MARKET IN NORTH AMERICA, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 108
AEROSPACE: LASER PROCESSING MARKET IN NORTH AMERICA, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 109
AEROSPACE: LASER PROCESSING MARKET IN EUROPE, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 110
AEROSPACE: LASER PROCESSING MARKET IN EUROPE, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 111
AEROSPACE: LASER PROCESSING MARKET IN ASIA PACIFIC, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 112
AEROSPACE: LASER PROCESSING MARKET IN ASIA PACIFIC, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 113
AEROSPACE: LASER PROCESSING MARKET IN ROW, BY REGION, 2022–2025 (USD MILLION)


TABLE 114
AEROSPACE: LASER PROCESSING MARKET IN ROW, BY REGION, 2026–2033 (USD MILLION)


TABLE 115
PRECISION DRILLING, MILLING, AND CUTTING OF AERO-ENGINE PARTS WITH LMJ TECHNOLOGY


TABLE 116
ADVANCING CMC MACHINING WITH WATER-JET GUIDED LASER SOLUTIONS


TABLE 117
PRECISION WELDING SOLUTIONS FOR COMPLEX AEROSPACE COMPONENTS


TABLE 118
CLIENTS IN AEROSPACE INDUSTRY


TABLE 119
ARCHITECTURE & CONSTRUCTION: LASER PROCESSING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 120
ARCHITECTURE & CONSTRUCTION: LASER PROCESSING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 121
ARCHITECTURE & CONSTRUCTION: LASER PROCESSING MARKET IN NORTH AMERICA, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 122
ARCHITECTURE & CONSTRUCTION: LASER PROCESSING MARKET IN NORTH AMERICA, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 123
ARCHITECTURE & CONSTRUCTION: LASER PROCESSING MARKET IN EUROPE, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 124
ARCHITECTURE & CONSTRUCTION: LASER PROCESSING MARKET IN EUROPE, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 125
ARCHITECTURE & CONSTRUCTION: LASER PROCESSING MARKET IN ASIA PACIFIC, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 126
ARCHITECTURE & CONSTRUCTION: LASER PROCESSING MARKET IN ASIA PACIFIC, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 127
ARCHITECTURE & CONSTRUCTION: LASER PROCESSING MARKET IN ROW, BY REGION, 2022–2025 (USD MILLION)


TABLE 128
ARCHITECTURE & CONSTRUCTION: LASER PROCESSING MARKET IN ROW, BY REGION, 2026–2033 (USD MILLION)


TABLE 129
PRECISION MODELING FOR HIGH-COMPLEXITY INFRASTRUCTURE PROJECTS


TABLE 130
LIENTS IN ARCHITECTURE & CONSTRUCTION INDUSTRY


TABLE 131
OTHER END-USE INDUSTRIES: LASER PROCESSING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 132
OTHER END-USE INDUSTRIES: LASER PROCESSING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 133
OTHER END-USE INDUSTRIES: LASER PROCESSING MARKET IN NORTH AMERICA, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 134
OTHER END-USE INDUSTRIES: LASER PROCESSING MARKET IN NORTH AMERICA, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 135
OTHER END-USE INDUSTRIES: LASER PROCESSING MARKET IN EUROPE, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 136
OTHER END-USE INDUSTRIES: LASER PROCESSING MARKET IN EUROPE, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 137
OTHER END-USE INDUSTRIES: LASER PROCESSING MARKET IN ASIA PACIFIC, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 138
OTHER END-USE INDUSTRIES: LASER PROCESSING MARKET IN ASIA PACIFIC, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 139
OTHER END-USE INDUSTRIES: LASER PROCESSING MARKET IN ROW, BY REGION, 2022–2025 (USD MILLION)


TABLE 140
OTHER END-USE INDUSTRIES: LASER PROCESSING MARKET IN ROW, BY REGION, 2026–2033 (USD MILLION)


TABLE 141
MEETING MILITARY MARKING STANDARDS WITH LASER TECHNOLOGY


TABLE 142
ENHANCING TIME EFFICIENCY AND DESIGN PRECISION WITH LASER TECHNOLOGY


TABLE 143
IMPLEMENTING SUSTAINABLE MARKING TECHNOLOGIES FOR FOOD PACKAGING


TABLE 144
CLIENTS IN OTHER END-USE INDUSTRIES


TABLE 145
LASER PROCESSING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 146
LASER PROCESSING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 147
NORTH AMERICA: LASER PROCESSING MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 148
NORTH AMERICA: LASER PROCESSING MARKET, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 149
NORTH AMERICA: LASER PROCESSING MARKET, BY LASER TYPE, 2022–2025 (USD MILLION)


TABLE 150
NORTH AMERICA: LASER PROCESSING MARKET, BY LASER TYPE, 2026–2033 (USD MILLION)


TABLE 151
NORTH AMERICA: LASER PROCESSING MARKET, BY CONFIGURATION, 2022–2025 (USD MILLION)


TABLE 152
NORTH AMERICA: LASER PROCESSING MARKET, BY CONFIGURATION, 2026–2033 (USD MILLION)


TABLE 153
NORTH AMERICA: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 154
NORTH AMERICA: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 155
US: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 156
US: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 157
CANADA: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 158
CANADA: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 159
MEXICO: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 160
MEXICO: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 161
EUROPE: LASER PROCESSING MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 162
EUROPE: LASER PROCESSING MARKET, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 163
EUROPE: LASER PROCESSING MARKET, BY LASER TYPE, 2022–2025 (USD MILLION)


TABLE 164
EUROPE: LASER PROCESSING MARKET, BY LASER TYPE, 2026–2033 (USD MILLION)


TABLE 165
EUROPE: LASER PROCESSING MARKET, BY CONFIGURATION, 2022–2025 (USD MILLION)


TABLE 166
EUROPE: LASER PROCESSING MARKET, BY CONFIGURATION, 2026–2033 (USD MILLION)


TABLE 167
EUROPE: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 168
EUROPE: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 169
UK: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 170
UK: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 171
GERMANY: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 172
GERMANY: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 173
FRANCE: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 174
FRANCE: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 175
ITALY: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 176
ITALY: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 177
SPAIN: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 178
SPAIN: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 179
NETHERLANDS: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 180
NETHERLANDS: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 181
SWITZERLAND: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 182
SWITZERLAND: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 183
POLAND: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 184
POLAND: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 185
NORDICS: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 186
NORDICS: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 187
REST OF EUROPE: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 188
REST OF EUROPE: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 189
ASIA PACIFIC: LASER PROCESSING MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 190
ASIA PACIFIC: LASER PROCESSING MARKET, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 191
ASIA PACIFIC: LASER PROCESSING MARKET, BY LASER TYPE, 2022–2025 (USD MILLION)


TABLE 192
ASIA PACIFIC: LASER PROCESSING MARKET, BY LASER TYPE, 2026–2033 (USD MILLION)


TABLE 193
ASIA PACIFIC: LASER PROCESSING MARKET, BY CONFIGURATION, 2022–2025 (USD MILLION)


TABLE 194
ASIA PACIFIC: LASER PROCESSING MARKET, BY CONFIGURATION, 2026–2033 (USD MILLION)


TABLE 195
ASIA PACIFIC: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 196
ASIA PACIFIC: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 197
CHINA: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 198
CHINA: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 199
JAPAN: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 200
JAPAN: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 201
SOUTH KOREA: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 202
SOUTH KOREA: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 203
INDIA: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 204
INDIA: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 205
AUSTRALIA: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 206
AUSTRALIA: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 207
INDONESIA: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 208
INDONESIA: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 209
MALAYSIA: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 210
MALAYSIA: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 211
THAILAND: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 212
THAILAND: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 213
VIETNAM: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 214
VIETNAM: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 215
REST OF ASIA PACIFIC: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 216
REST OF ASIA PACIFIC: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 217
ROW: LASER PROCESSING MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 218
ROW: LASER PROCESSING MARKET, BY REGION, 2026–2033 (USD MILLION)


TABLE 219
ROW: LASER PROCESSING MARKET, BY LASER TYPE, 2022–2025 (USD MILLION)


TABLE 220
ROW: LASER PROCESSING MARKET, BY LASER TYPE, 2026–2033 (USD MILLION)


TABLE 221
ROW: LASER PROCESSING MARKET, BY CONFIGURATION, 2022–2025 (USD MILLION)


TABLE 222
ROW: LASER PROCESSING MARKET, BY CONFIGURATION, 2026–2033 (USD MILLION)


TABLE 223
ROW: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 224
ROW: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 225
MIDDLE EAST: LASER PROCESSING MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 226
MIDDLE EAST: LASER PROCESSING MARKET, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 227
MIDDLE EAST: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 228
MIDDLE EAST: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 229
SOUTH AMERICA: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 230
SOUTH AMERICA: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 231
AFRICA: LASER PROCESSING MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 232
AFRICA: LASER PROCESSING MARKET, BY COUNTRY, 2026–2033 (USD MILLION)


TABLE 233
AFRICA: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2022–2025 (USD MILLION)


TABLE 234
AFRICA: LASER PROCESSING MARKET, BY END-USE INDUSTRY, 2026–2033 (USD MILLION)


TABLE 235
LASER PROCESSING MARKET: OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS, JANUARY 2023–JUNE 2026


TABLE 236
LASER PROCESSING MARKET: DEGREE OF COMPETITION, 2025


TABLE 237
LASER PROCESSING MARKET: REGION FOOTPRINT


TABLE 238
LASER PROCESSING MARKET: LASER TYPE FOOTPRINT


TABLE 239
LASER PROCESSING MARKET: APPLICATION FOOTPRINT


TABLE 240
LASER PROCESSING MARKET: END-USE INDUSTRY FOOTPRINT


TABLE 241
LASER PROCESSING MARKET: LIST OF KEY STARTUPS/SMES


TABLE 242
LASER PROCESSING MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES


TABLE 243
LASER PROCESSING MARKET: PRODUCT LAUNCHES, JANUARY 2024–SEPTEMBER 2026


TABLE 244
LASER PROCESSING MARKET: DEALS, JANUARY 2024–SEPTEMBER 2026


TABLE 245
LASER PROCESSING MARKET: EXPANSIONS, JANUARY 2024–SEPTEMBER 2026


TABLE 246
COHERENT CORP.: COMPANY OVERVIEW


TABLE 247
COHERENT CORP.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 248
COHERENT CORP.: PRODUCT LAUNCHES


TABLE 249
TRUMPF: COMPANY OVERVIEW


TABLE 250
TRUMPF: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 251
TRUMPF: PRODUCT LAUNCHES


TABLE 252
TRUMPF: DEALS


TABLE 253
HAN’S LASER TECHNOLOGY INDUSTRY GROUP CO., LTD.: COMPANY OVERVIEW


TABLE 254
HAN’S LASER TECHNOLOGY INDUSTRY GROUP CO., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 255
HAN’S LASER TECHNOLOGY INDUSTRY GROUP CO., LTD.: PRODUCT LAUNCHES


TABLE 256
IPG PHOTONICS CORPORATION: COMPANY OVERVIEW


TABLE 257
IPG PHOTONICS CORPORATION: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 258
IPG PHOTONICS CORPORATION: PRODUCT LAUNCHES


TABLE 259
IPG PHOTONICS CORPORATION: DEALS


TABLE 260
JENOPTIK AG: COMPANY OVERVIEW


TABLE 261
JENOPTIK AG: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 262
JENOPTIK AG: PRODUCT LAUNCHES


TABLE 263
FIVES: COMPANY OVERVIEW


TABLE 264
FIVES: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 265
FIVES: EXPANSIONS


TABLE 266
AXBIS: COMPANY OVERVIEW


TABLE 267
AXBIS: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 268
LUMENTUM OPERATIONS LLC: COMPANY OVERVIEW


TABLE 269
LUMENTUM OPERATIONS LLC: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 270
LUMENTUM OPERATIONS LLC: DEALS


TABLE 271
LUMENTUM OPERATIONS LLC: EXPANSIONS


TABLE 272
GRAVOTECH, INC.: COMPANY OVERVIEW


TABLE 273
GRAVOTECH, INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 274
GRAVOTECH, INC.: PRODUCT LAUNCHES


TABLE 275
LASER STAR TECHNOLOGIES: COMPANY OVERVIEW


TABLE 276
LASER STAR TECHNOLOGIES: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 277
LUMIBIRD: COMPANY OVERVIEW


TABLE 278
LUMIBIRD: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 279
LUMIBIRD: DEALS


TABLE 280
EPILOG LASER: COMPANY OVERVIEW


TABLE 281
EPILOG LASER: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 282
EPILOG LASER: PRODUCT LAUNCHES


TABLE 283
MKS INSTRUMENTS: COMPANY OVERVIEW


TABLE 284
MKS INSTRUMENTS: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 285
MKS INSTRUMENTS: PRODUCT LAUNCHES


TABLE 286
NOVANTA INC.: COMPANY OVERVIEW


TABLE 287
NOVANTA INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 288
NOVANTA INC.: PRODUCT LAUNCHES


TABLE 289
EUROLASER GMBH: COMPANY OVERVIEW


TABLE 290
EUROLASER GMBH: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 291
600 GROUP PLC: COMPANY OVERVIEW


TABLE 292
BYSTRONIC GROUP: COMPANY OVERVIEW


TABLE 293
ALPHALAS GMBH: COMPANY OVERVIEW


TABLE 294
APPLIED LASER TECHNOLOGY, INC.: COMPANY OVERVIEW


TABLE 295
ARIMA LASERS CORP.: COMPANY OVERVIEW


TABLE 296
FOCUSLIGHT TECHNOLOGIES INC.: COMPANY OVERVIEW


TABLE 297
INNO LASER TECHNOLOGY CO., LTD.: COMPANY OVERVIEW


TABLE 298
NKT PHOTONICS A/S: COMPANY OVERVIEW


TABLE 299
PHOTONICS INDUSTRIES INTERNATIONAL. INC.: COMPANY OVERVIEW


TABLE 300
SFX: COMPANY OVERVIEW


TABLE 301
TOPTICA PHOTONICS AG: COMPANY OVERVIEW


TABLE 302
UNIVERSAL LASER SYSTEMS, INC.: COMPANY OVERVIEW


TABLE 303
KEY SECONDARY SOURCES


TABLE 304
KEY PRIMARY INTERVIEW PARTICIPANTS


LIST OF FIGURES


FIGURE 1
MARKETS COVERED AND REGIONAL SCOPE


FIGURE 2
DURATION COVERED


FIGURE 3
MARKET SCENARIO


FIGURE 4
LASER PROCESSING MARKET, 2022–2033


FIGURE 5
MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN LASER PROCESSING MARKET (JANUARY 2024–SEPTEMBER 2026)


FIGURE 6
DISRUPTIVE TRENDS IMPACTING GROWTH OF LASER PROCESSING MARKET


FIGURE 7
HIGH-GROWTH SEGMENTS IN LASER PROCESSING MARKET, 2026-2033


FIGURE 8
ASIA PACIFIC TO EXHIBIT HIGHEST CAGR DURING FORECAST PERIOD


FIGURE 9
RISING DEMAND FOR ADVANCED MANUFACTURING, AUTOMATION, AND PRECISION TO DRIVE MARKET


FIGURE 10
SOLID LASERS TO ACCOUNT FOR MAJORITY OF MARKET SHARE IN 2033


FIGURE 11
MOVING BEAMS TO RECORD HIGHEST CAGR IN LASER PROCESSING MARKET DURING FORECAST PERIOD


FIGURE 12
ADVANCED PROCESSING TO BE FASTEST-GROWING APPLICATION IN LASER PROCESSING MARKET DURING FORECAST PERIOD


FIGURE 13
MICROELECTRONICS & SEMICONDUCTORS TO ACCOUNT FOR LARGEST MARKET SHARE IN 2033


FIGURE 14
INDIA TO RECORD HIGHEST CAGR IN GLOBAL LASER PROCESSING MARKET DURING FORECAST PERIOD


FIGURE 15
LASER PROCESSING MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES


FIGURE 16
IMPACT ANALYSIS: DRIVERS


FIGURE 17
IMPACT ANALYSIS: RESTRAINTS


FIGURE 18
IMPACT ANALYSIS: OPPORTUNITIES


FIGURE 19
IMPACT ANALYSIS: CHALLENGES


FIGURE 20
PORTER’S FIVE FORCES ANALYSIS


FIGURE 21
LASER PROCESSING MARKET SUPPLY CHAIN ANALYSIS


FIGURE 22
LASER PROCESSING ECOSYSTEM ANALYSIS


FIGURE 23
AVERAGE SELLING PRICE TREND OF DIFFERENT TYPES OF LASERS, 2022–2025


FIGURE 24
AVERAGE SELLING PRICE TREND OF LASER PROCESSING SOLUTIONS, BY REGION, 2022–2025


FIGURE 25
IMPORT DATA FOR HS CODE 901320-COMPLIANT PRODUCTS FOR TOP 5 COUNTRIES, 2021−2025


FIGURE 26
EXPORT DATA FOR HS CODE 901320-COMPLIANT PRODUCTS FOR TOP 5 COUNTRIES, 2021−2025


FIGURE 27
TRENDS/DISRUPTIONS INFLUENCING CUSTOMER BUSINESS


FIGURE 28
INVESTMENT AND FUNDING SCENARIO, 2022–2025


FIGURE 29
PATENTS APPLIED AND GRANTED, 2016–2025


FIGURE 30
DECISION-MAKING FACTORS IN LASER PROCESSING MARKET


FIGURE 31
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP 3 END-USE INDUSTRIES


FIGURE 32
KEY BUYING CRITERIA FOR TOP 3 END-USE INDUSTRIES


FIGURE 33
ADOPTION BARRIERS AND INTERNAL CHALLENGES


FIGURE 34
SOLID LASERS TO DOMINATE LASER PROCESSING MARKET THROUGHOUT FORECAST PERIOD


FIGURE 35
HYBRID BEAMS TO ACCOUNT FOR LARGEST SHARE OF LASER PROCESSING MARKET IN 2033


FIGURE 36
CUTTING APPLICATION TO ACCOUNT FOR LARGEST SHARE OF LASER PROCESSING MARKET IN 2033


FIGURE 37
MICROELECTRONICS & SEMICONDUCTORS TO ACCOUNT FOR LARGEST SHARE OF LASER PROCESSING MARKET IN 2033


FIGURE 38
LASER PROCESSING MARKET: GEOGRAPHIC SNAPSHOT


FIGURE 39
NORTH AMERICA: LASER PROCESSING MARKET SNAPSHOT


FIGURE 40
EUROPE: LASER PROCESSING MARKET SNAPSHOT


FIGURE 41
ASIA PACIFIC: LASER PROCESSING MARKET SNAPSHOT


FIGURE 42
MARKET SHARE ANALYSIS OF COMPANIES OFFERING LASER PROCESSING SOLUTIONS, 2025


FIGURE 43
LASER PROCESSING MARKET: REVENUE ANALYSIS OF TOP 5 PLAYERS, 2021–2025


FIGURE 44
COMPANY VALUATION


FIGURE 45
FINANCIAL METRICS (EV/EBITDA)


FIGURE 46
BRAND/PRODUCT COMPARATIVE ANALYSIS


FIGURE 47
LASER PROCESSING MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025


FIGURE 48
LASER PROCESSING MARKET: COMPANY FOOTPRINT


FIGURE 49
LASER PROCESSING MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025


FIGURE 50
COHERENT CORP.: COMPANY SNAPSHOT


FIGURE 51
TRUMPF: COMPANY SNAPSHOT


FIGURE 52
HAN’S LASER TECHNOLOGY INDUSTRY GROUP CO., LTD.: COMPANY SNAPSHOT


FIGURE 53
IPG PHOTONICS CORPORATION: COMPANY SNAPSHOT


FIGURE 54
JENOPTIK AG: COMPANY SNAPSHOT


FIGURE 55
FIVES: COMPANY SNAPSHOT


FIGURE 56
LUMENTUM OPERATIONS LLC: COMPANY SNAPSHOT


FIGURE 57
LUMIBIRD: COMPANY SNAPSHOT


FIGURE 58
MKS INSTRUMENTS: COMPANY SNAPSHOT


FIGURE 59
NOVANTA INC.: COMPANY SNAPSHOT


FIGURE 60
LASER PROCESSING MARKET: RESEARCH DESIGN


FIGURE 61
DATA OBTAINED FROM SECONDARY SOURCES


FIGURE 62
DATA OBTAINED FROM PRIMARY SOURCES


FIGURE 63
KEY FINDINGS FROM INDUSTRY EXPERTS


FIGURE 64
BREAKDOWN OF PRIMARY PARTICIPANTS: BY COMPANY TYPE, DESIGNATION, AND REGION


FIGURE 65
PRIMARY RESEARCH AND SECONDARY RESEARCH APPROACH


FIGURE 66
RESEARCH FLOW OF MARKET SIZE ESTIMATION


FIGURE 67
MARKET SIZE ESTIMATION METHODOLOGY: BOTTOM-UP APPROACH


FIGURE 68
MARKET SIZE ESTIMATION METHODOLOGY: TOP-DOWN APPROACH


FIGURE 69
DATA TRIANGULATION


Methodology

The research process for this technical, market-oriented, and commercial study of the laser processing market included systematic gathering, recording, and analysis of data about companies operating in the market. It involved the extensive use of secondary sources, directories, and databases to identify and collect relevant information. In-depth interviews were conducted with various primary respondents, including experts from core and related industries and preferred manufacturers, to obtain and verify critical qualitative and quantitative information as well as to assess the growth prospects of the market. Key players were identified through secondary research, and their market rankings were determined through primary and secondary research. This included studying annual reports of top players and interviewing key industry experts, such as CEOs, directors, and marketing executives.

Secondary Research

In the secondary research process, various secondary sources have been referred to for identifying and collecting information relevant to this study. Secondary sources include annual reports, press releases, and investor presentations of companies; white papers, certified publications, and articles from recognized authors; directories; and databases. Secondary research has been mainly conducted to obtain key information about the supply of the laser processing industry; a total pool of key players; segmentation of the market according to laser type, configuration, end users, geographic markets, and key developments from market- and technology-oriented perspectives.

Primary Research

In the primary research process, primary sources from the supply and demand sides have been interviewed to obtain qualitative and quantitative information for this report. Primary sources from the supply side include experts, such as CEOs, vice presidents, marketing directors, technology and innovation directors, subject-matter experts, consultants, and related key executives from major companies and organizations operating in the laser processing market.

After the complete market engineering process (market statistics calculations, market breakdown, market size estimations, market forecasting, and data triangulation), extensive primary research has been conducted to gather information and verify and validate the critical market numbers.

Several primary interviews have been conducted with experts from the demand and supply sides across four major regions - North America, Europe, Asia Pacific, and RoW. Approximately 25% of the primary interviews were conducted with the demand side and 75% with the supply side. This primary data has been collected through questionnaires, emails, and telephonic interviews.

Breakdown Of Primary Interview Participants
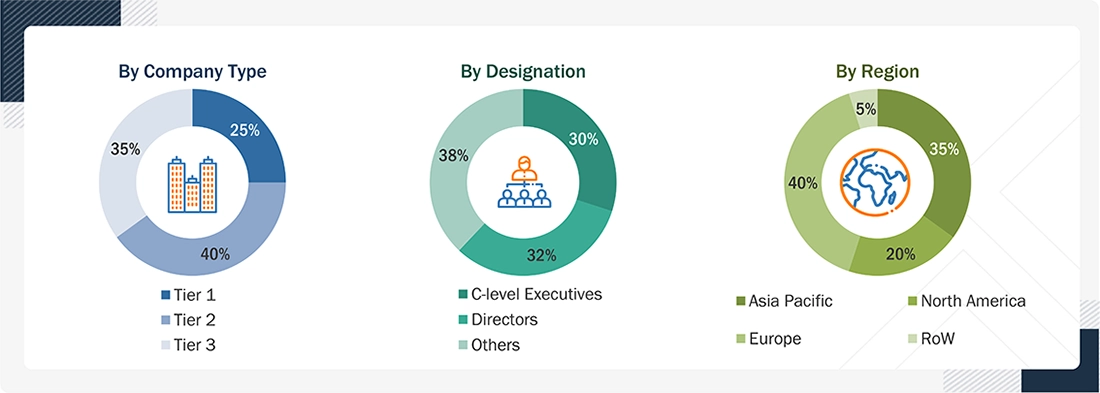
Laser Processing Market Size, and Share

Note: Other designations include sales, marketing specialists, and product managers.
RoW mainly includes the Middle East & Africa and South America.
The 3 tiers of the companies have been defined based on their total revenue as of 2023; tier 1: revenue greater than USD 1 billion, tier 2: revenue between USD 500 million and USD 1 billion, and tier 3: revenue less than USD 500 million.

To know about the assumptions considered for the study, download the pdf brochure

Market Size Estimation

In the complete market estimation process, the top-down and bottom-up approaches have been used, along with several data triangulation methods, to estimate and forecast the size of the market and its segments and subsegments listed in the report. Extensive qualitative and quantitative analyses have been carried out on the complete market engineering process to list the key information/insights pertaining to the laser processing market.

Key players in the laser processing market have been identified through secondary research, and their rankings in the respective regions have been determined through primary and secondary research. This entire procedure involved the study of the annual and financial reports of top players and interviews with industry experts, such as chief executive officers, vice presidents, directors, and marketing executives, for quantitative and qualitative insights. All percentage shares, splits, and breakdowns have been determined using secondary sources and verified through primary sources. All parameters that affect the markets covered in this research study have been accounted for, viewed in extensive detail, verified through primary research, and analyzed to obtain the final quantitative and qualitative data. This data has been consolidated and enhanced with detailed inputs and analysis from MarketsandMarkets and presented in this report.

Bottom-Up Approach

  • The first step involved identifying companies that offer laser processing solutions, followed by mapping their products according to various parameters, such as laser type, configuration, application, end-use industries, and region.
  • The size of the laser processing market has been calculated based on the demand from various end users and the revenue generated by companies within the laser processing ecosystem.
  • To confirm the global market size, primary interviews have been conducted with a few major players in the market.
  • The market size has also been cross-checked using secondary sources, which included Springer Nature Limited, Laser Focus World, Spectrum Plastics Group, Universal Laser Systems, Inc., Resonetics, and the Journal of Laser Applications. Other secondary sources comprised company websites, press releases, and research journals.
  • To determine the compound annual growth rate (CAGR) of the market, both historical and projected market trends have been analyzed by examining the industry’s penetration rate, as well as the supply and demand from various verticals.
  • All estimates at each stage have been confirmed through discussions with key opinion leaders, including corporate executives (CXOs), directors, and sales heads, as well as industry experts from MarketsandMarkets.
  • Several paid and unpaid information sources, such as annual reports, press releases, white papers, and databases, have also been reviewed during the research process.

Top-Down Approach

  • To estimate the global size of the laser processing market, revenue information from leading manufacturers and providers of laser processing systems and solutions has been gathered and analyzed.
  • The laser processing market is projected to exhibit a steady growth trend during the forecast period, reflecting its maturity and the presence of numerous well-established players across various sectors.
  • The revenues, geographic footprints, key market sectors, and product offerings of all identified players in the laser processing market have been studied to estimate the percentage distribution of different market segments.
  • Major players in each category (laser type, application, and end-use industry) within the laser processing market have been identified through secondary research, and information has been confirmed through brief discussions with industry experts.
  • Several discussions with key opinion leaders from leading companies involved in developing laser processing systems have been conducted to validate the market segmentation based on laser type, configuration, application, end user, and region.
  • The geographic segmentation has been done using secondary research, considering factors such as the presence and concentration of companies offering laser processing solutions across different countries and regions.

Laser Processing Market : Top-Down and Bottom-Up Approach
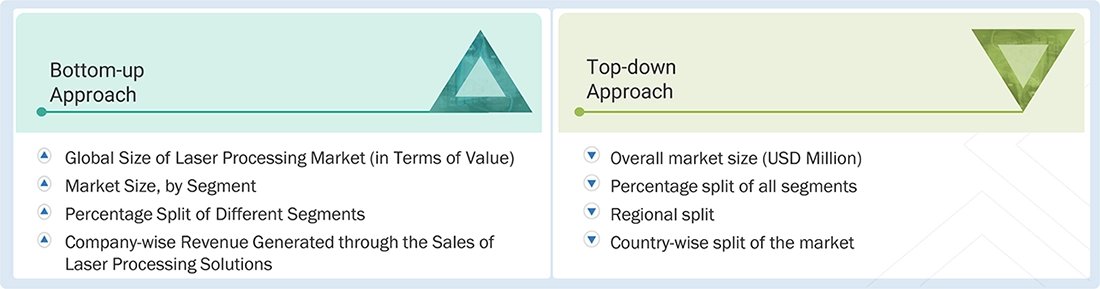
Laser Processing Market Top Down and Bottom Up Approach

Data Triangulation

After arriving at the overall market size from the market size estimation process explained in the previous section, the total market was split into several segments and subsegments. Market breakdown and data triangulation procedures have been employed, wherever applicable, to complete the overall market engineering process and arrive at the exact statistics for all segments and subsegments. The data have been triangulated by studying various factors and trends from the demand and supply sides. Along with this, the laser processing market has been validated using both top-down and bottom-up approaches.      

Market Definition

The laser processing market includes a range of systems used for precision cutting, welding, drilling, marking, and surface treatment. These systems are classified by laser type as solid lasers (fiber, ruby, YAG, semiconductor, thin-disk), gas lasers (CO2, excimer, helium-neon, argon, chemical), liquid lasers, and other laser types. Laser processing enables high-speed, contactless operations with superior accuracy and minimal material distortion, making it essential for applications requiring fine detail and high quality. It plays a critical role in industries such as microelectronics & semiconductors, automotive, medical and life sciences, aerospace, and architecture & construction.

The market is driven by the rising demand for advanced manufacturing solutions, miniaturized electronic components, and increased automation. In medical settings, lasers are used for surgical procedures and device fabrication. In the automotive and aerospace sectors, they support lightweight material processing and structural integrity. Ongoing innovations in laser sources, beam control, cooling systems, and integrated software have enhanced energy efficiency and precision, expanding their adoption. These advancements continue to open new opportunities for the adoption of laser processing in industrial and high-tech sectors.

Key Stakeholders

  • Microelectronics manufacturers
  • Aerospace companies
  • Medical & life sciences companies
  • Automotive companies
  • Architecture firms
  • Machine tool manufacturers
  • Lasers and systems manufacturers
  • Laser processing solution providers
  • Engineering and manufacturing companies
  • Technology providers  

Report Objectives

  • To estimate and forecast the size of the laser processing market, by laser type, configuration, application, end-use industry, and region, in terms of value
  • To provide qualitative information about the components of laser processing
  • To describe and forecast the market size for four major regions: North America, Europe, Asia Pacific, and RoW, in terms of value
  • To provide detailed information regarding the major factors, such as drivers, restraints, opportunities, and challenges, influencing the market growth
  • To provide a detailed overview of the laser processing value chain
  • To strategically analyze micromarkets regarding individual market trends, growth prospects, and contributions to the total market
  • To strategically profile key players and comprehensively analyze their market position in terms of ranking and core competencies, along with a detailed competitive landscape for the market leaders
  • To analyze major growth strategies such as product launches/developments and acquisitions adopted by the key market players to enhance their market position
  • To analyze the impact of the macroeconomic factors impacting the laser processing market.

Available customizations:

With the given market data, MarketsandMarkets offers customizations according to the company’s specific needs. The following customization options are available for the report:

Company Information

  • Detailed analysis and profiling of up to five additional market players


Key Questions Addressed by the Report

Which are the major companies in the laser processing market? What are their significant strategies to strengthen their market presence?

The major companies in the laser processing market are Coherent Corp. (US), TRUMPF (Germany), Han's Laser Technology Industry Group Co., Ltd. (China), IPG Photonics Corporation (US), and JENOPTIK AG (Germany). These players adopt major strategies, including product launches and developments, collaborations, acquisitions, and expansions.

Which region is expected to dominate the laser processing market?

The Asia Pacific region is expected to dominate the laser processing market due to the growth in automation and smart manufacturing and increased adoption in renewable energy projects.

What are the opportunities for new market entrants?

There are significant opportunities for start-up companies in the laser processing market. These companies provide innovative and diverse product portfolios.

What are the drivers and opportunities for the laser processing market?

Expanding use of laser technologies in the automotive sector and growing adoption of laser processing for enhanced design, functionality, and personalization in consumer goods are fueling market growth.

What are the major laser processing technologies expected to drive the market's growth in the next five years?

Major laser processing technologies, such as fiber lasers, CO2 lasers, and diode lasers, are expected to drive market growth through their diverse applications in cutting, welding, and marking across industries.

Personalize This Research

  • Triangulate with your Own Data
  • Get Data as per your Format and Definition
  • Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
  • Any level of Personalization
Request A Free Customisation

Let Us Help You

  • What are the Known and Unknown Adjacencies Impacting the Laser Processing Market
  • What will your New Revenue Sources be?
  • Who will be your Top Customer; what will make them switch?
  • Defend your Market Share or Win Competitors
  • Get a Scorecard for Target Partners
Customized Workshop Request

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements

Get 10% Free Customisation

TESTIMONIALS

Growth opportunities and latent adjacency in Laser Processing Market

avtar

Kevin

Apr, 2015

How dot peen marking affect adoption of laser for marketing and engraving application?.

avtar

Sébastien

Jan, 2019

Dear Sir/Madam, I am working on a project involving femtosecond pulsed lasers for my master's thesis. The project focuses on laser microprocessing of silicon. Thus I would be really interested by having any information on the laser microprocessing market of silicon or the market of silicon in general. Unfortunately we don't have enough funding now to purchase your book without being sure we can find what we are looking for. This is why I am requesting a free sample report. .

avtar

Georg

Mar, 2014

Dear Market research Team, Before buying I would like to have a summary of the study..

avtar

Chiara

Jun, 2013

Hi, I am interested in evaluate the US laser processing market and their applications that best fit the using of small-medium Fiber laser machines, which have an high precision and can work for small/medium metal pieces. .

avtar

Mark

Sep, 2014

Currently selling Nitrogen Gas generators throughout Eastern Europe and CIS and would be interested in what this report has to say, in relation to Laser Cutting..

avtar

Naoki

Jan, 2015

Interested in each of the applications by the market size of Laser Diode, DPSSL, and Fiber Laser. We especially would like to make sure the application..

avtar

Jinan

Aug, 2015

Will increase in adoption of fiber laser will affect demand of CO2 laser?.

avtar

Joanna

Dec, 2018

I am a polish student and involved in some project about ultrafast lasers. I have found that they are commonly used in micromachining so I am also really interested in this market. Can you share the summary for this market study?.

avtar

chirag

Dec, 2014

I am specially interested in fiber laser latest developments. And market opportunity for high power cutting machine in South Asia and Middle East regions. .

avtar

Juan

Apr, 2019

Trying to understand the market for ultra-short pulse lasers for the processing of ultra-hard materials ..

avtar

Jack

Jul, 2015

Hard to tell what your definition of "Laser Processing Market" is - seems like this includes more than just annual system sales. Can you please define it a bit further - what the study covers in this $17.4 billion market by 2020?.

avtar

Mahesh

Dec, 2015

I need to know which companies you have considered for the study, are these companies produces laser machines or the user of the machines?.

avtar

John

Oct, 2014

Interested in laser marking and engraving applications as it relates to tooling and tube identification specifically in aerospace and automotive industry segments. .

avtar

Jensen

Oct, 2014

Can you provide the qualitative and quantitative data for laser marking and engraving applications particularly for growth in the fiber and decline in CO2 and other solid state lasers?.

avtar

Aaron

Jul, 2017

I'm one of the co-founders in a startup focused on distributed manufacturing. I've been struggling to find a decent total addressable market number, and I'm pretty sure you guys have some of the data I need in your report. We don't have the funds to buy the full report. I'm wondering if you would be willing to sell part of the data so I can build a market case for investors. We are focused specifically on the laser fabrication market for metals and non-metals. For the time being out customers are mainly prototyping parts. I appreciate any help or advice you can offer. .

Show More
DMCA.com Protection Status
popup img