India Healthcare Indoor Location Market (2026-2031)
The India Healthcare Indoor Location Market was valued at $114.99 Million in 2026 and projected to reach to $622.34 Million by 2031, representing a compound annual growth rate of 32.5%. India's healthcare indoor location market is poised for exceptional growth, driven by rapid digital transformation in the healthcare sector and increasing adoption of IoT-enabled solutions.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
India Healthcare Indoor Location Market Trends and Insights
- This represents a compound annual growth rate of 32.5%, significantly outpacing global trends.
- India's healthcare sector is increasingly adopting indoor positioning technologies to enhance patient tracking, asset management, and operational efficiency across hospitals and medical facilities. The growth trajectory in India reflects rising healthcare infrastructure investments, digital transformation initiatives, and growing demand for real-time location services in clinical environments.
- India's expanding middle class and increasing healthcare expenditure are driving adoption of advanced technologies in hospitals and diagnostic centers.
- By 2031, India is expected to become a major hub for healthcare indoor location solutions, supported by government initiatives promoting healthcare digitalization and smart hospital development. India's market growth is fueled by the need for improved patient safety, staff coordination, and inventory management in increasingly complex healthcare settings.
- The country's large patient population and growing number of multi-specialty hospitals create substantial opportunities for indoor location technology providers targeting India's healthcare sector..
Key Market Statistics
- CAGR (2026-2031) 32.5% CAGR
- Market Size, 2026 ~USD 114.99 Million
- Forecast, 2031 ~USD 622.34 Million
- Country India
India Healthcare Indoor Location Market Overview
Exceptional Growth Trajectory :
India's healthcare indoor location market is projected to grow from USD 114.99 million in 2026 to USD 622.34 million by 2031, representing a robust 32.5% CAGR that significantly exceeds the global average of 27.8%.
Digital Healthcare Transformation :
Indian hospitals and healthcare facilities are rapidly modernizing operations through indoor positioning technologies, driven by government initiatives like Digital India and increasing investments in smart hospital infrastructure across urban and emerging metros.
Patient Safety & Asset Optimization :
Healthcare providers in India are leveraging indoor location solutions for real-time patient tracking, reducing medical errors, optimizing staff workflows, and improving asset management efficiency across multi-floor hospital complexes.
Rising Healthcare Infrastructure Demand :
With India's expanding middle class and increasing healthcare spending, new hospital constructions and facility upgrades are creating substantial demand for integrated indoor positioning systems to enhance operational efficiency and patient experience.
India Healthcare Indoor Location Market Dynamics
- Government support through healthcare digitalization initiatives and rising investments in smart hospital infrastructure are accelerating market expansion across major metropolitan areas and tier-2 cities.
- The market's 32.5% CAGR reflects strong momentum as healthcare providers prioritize patient safety, operational efficiency, and real-time asset tracking capabilities. Looking ahead to 2031, India's market is expected to mature significantly as indoor positioning technologies become standard in modern healthcare facilities.
- Increasing smartphone penetration, affordable 5G deployment, and growing awareness of location-based healthcare benefits will drive widespread adoption.
- The convergence of AI, cloud computing, and indoor positioning systems will enable advanced applications in patient management, staff coordination, and emergency response, positioning India as a key growth engine in the global healthcare indoor location market..
Market Ecosystem

HEALTHCARE INDOOR LOCATION MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Zebra deployed its MotionWorks RTLS solution at Hull University Teaching Hospitals NHS Trust to track and trace medical equipment across its two clinical campuses. The deployment uses RFID to provide visibility of equipment and support inventory and operational workflows. The Trust has labelled more than 72,000 assets and continues to track sterile trays across its facilities. | Real-time asset visibility | Reduced equipment search time | Improved asset utilization | Better operational efficiency |
 |
RWJBarnabas Health deployed Securitas Healthcare's RTLS across seven hospitals to improve visibility of medical assets and support operational workflows. The solution enables healthcare teams to locate and manage tagged assets through the RTLS platform, supporting clinicians, biomedical teams, and other hospital stakeholders. | Improved asset utilization | Reduced unnecessary purchases | Enhanced operational efficiency | Improved patient and staff safety |
 |
Kontakt.io deployed location-aware BLE smart badges across Northeast Georgia Health System to protect healthcare staff. The badges enable employees to send silent duress alerts, with their location transmitted in real time to security and designated responders. NGHS deployed the solution for approximately 10,000 staff members, with the platform also supporting expansion into other clinical and operational workflows. | Faster emergency response | Improved staff safety | Real-time staff visibility | Automated security workflows |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Key Takeaways
- India's healthcare indoor location market will grow from USD 114.99 million in 2026 to USD 622.34 million by 2031, representing a 32.5% CAGR.
- India's rapid adoption is driven by digital healthcare transformation, government smart hospital initiatives, and increasing multi-specialty hospital infrastructure.
- Real-time patient tracking and asset management solutions are becoming critical operational requirements in India's expanding healthcare facilities.
- India's large patient population and rising healthcare expenditure create significant market opportunities for indoor location technology providers through 2031.
Healthcare Indoor Location Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2026 |
| Fastest Growing Segment | ACCESS CONTROL & SECURITY (Application) |
| Forecast Period | 2026-2031 |
| Growth Rate | CAGR of 27.8% from 2026 to 2031 |
| Largest Segment | HOSPITALS & HEALTHCARE FACILITIES (Facility Type) |
| Market Size Base Year (Billions) | ~USD 3.17 (2026) |
| Revenue Forecast (Billions) | ~USD 10.82 (2031) |
| Segments Covered | Offering, Hardware, Type, Technology, Application, Facility Type, Service |
India Healthcare Indoor Location Market Report Segmentation
7 segment dimensions are covered across the global market.
By Offering
- Hardware
- Services
- Software
By Hardware
- Other Hardware
- Readers/Trackers /Access Point
- Readers/Trackers/Access Point
- Tags/Badges
By Type
- Consulting
- Deployment & Integration
- Support & Maintenance
By Technology
- Ble
- Infrared
- Other Technologies
- Rfid
- Ultrasound
- Uwb
- Wi-Fi
By Application
- Access Control & Security
- Environmental Monitoring
- Inventory/Asset Tracking & Management
- Other Applications
- Personnel Locating & Monitoring
- Supply Chain Management & Automation
By Facility Type
- Hospitals & Healthcare Facilities
- Senior Living Facilities
By Service
- Consulting
- Deployment & Integration
- Support & Maintenance
Target Audience
- Healthcare Technology Vendors : Indoor positioning system providers and healthcare IT companies need India-specific market data to develop localized solutions, identify distribution channels, and prioritize resource allocation in this high-growth market.
- Hospital & Healthcare Operators : Hospital chains and healthcare facility managers require market insights to evaluate indoor location technology investments, benchmark adoption rates, and understand competitive offerings for operational modernization.
- Private Equity & Investors : Investment firms and venture capitalists need detailed India market analysis to identify acquisition targets, assess portfolio company growth potential, and evaluate healthcare technology investment opportunities.
- Government & Policy Bodies : Healthcare regulators and government agencies need market intelligence to inform digital health policies, infrastructure development initiatives, and technology adoption frameworks aligned with national healthcare goals.
- Consulting & Strategy Firms : Management consultants and strategic advisors require India market data to support client engagements, develop market entry strategies, and provide competitive positioning recommendations for healthcare technology clients.
Reasons to Buy this Report
- Market Size & Growth Validation : Access precise market valuation data for India's healthcare indoor location sector with detailed CAGR analysis (32.5%), enabling accurate investment decisions and competitive benchmarking against global trends.
- India-Specific Growth Drivers : Understand unique factors propelling India's market expansion including government healthcare digitalization policies, hospital modernization trends, and regional adoption patterns across metropolitan and emerging healthcare centers.
- Strategic Market Positioning : Identify high-potential segments within India's healthcare system, including patient tracking, asset management, and operational optimization, to develop targeted product strategies and market entry approaches.
- Competitive Intelligence : Gain insights into India's competitive landscape, emerging players, technology adoption rates, and market consolidation trends to inform partnership strategies and differentiation opportunities.
- Investment & Expansion Planning : Leverage comprehensive India market forecasts through 2031 to support business case development, funding proposals, and expansion roadmaps for healthcare technology solutions and services.
Frequently asked questions
What is the projected size of India's healthcare indoor location market by 2031?
India's healthcare indoor location market is projected to reach USD 622.34 million by 2031, growing from USD 114.99 million in 2026.
What is the CAGR for India's healthcare indoor location market?
India's healthcare indoor location market is expected to grow at a compound annual growth rate of 32.5% between 2026 and 2031.
What are the primary drivers of growth in India's healthcare indoor location market?
Key drivers include digital healthcare transformation, government smart hospital initiatives, increasing multi-specialty hospital infrastructure, and rising demand for patient safety and asset management solutions in India.
Which healthcare applications are driving adoption of indoor location technology in India?
Real-time patient tracking, staff coordination, medical equipment asset management, and operational efficiency improvements are the primary applications driving adoption across India's healthcare facilities.
How does India's market growth compare to global trends?
India's healthcare indoor location market CAGR of 32.5% significantly exceeds the global CAGR of 27.8%, positioning India as a high-growth market within the Asia Pacific region.
RESEARCH METHODOLOGY
This research study involved four major activities in estimating the healthcare indoor location market size. Exhaustive secondary research was conducted to collect important information about the market and peer markets. The next step involved validating these findings and assumptions and sizing them with the help of primary research with industry experts across the value chain. Both top-down and bottom-up approaches were used to estimate the market size. After which, the market breakdown and data triangulation were adopted to estimate the market sizes of segments and sub-segments.
Secondary Research
The market size of companies offering healthcare indoor location hardware, software, and services for various subscribers was estimated based on the secondary data available through paid and unpaid sources and by analyzing the different components (hardware, solutions, and services) of major companies in the ecosystem and rating them based on their performance and quality. In the secondary research process, various sources were referred to for identifying and collecting information for this study. The secondary sources included annual reports, press releases and investor presentations of companies, white papers, journals, and certified publications and articles from recognized authors, directories, and databases.
Secondary research was mainly used to obtain key information about the industry’s supply chain, the total pool of key players, market classification, and segmentation according to industry trends to the bottommost level, regional markets, and key developments from both market- and technology-oriented perspectives, all of which were further validated by primary sources.
Primary Research
In the primary research process, various primary sources from both the supply and demand sides were interviewed to obtain qualitative and quantitative information for the report. The primary sources from the supply side included industry experts, such as Chief Executive Officers (CEOs), Vice Presidents (VPs), marketing directors, technology and innovation directors, and related key executives from various key companies and organizations providing healthcare indoor location solutions. The primary sources from the demand side included end users, such as Chief Information Officers (CIOs), consultants, service professionals, technicians and technologists, and managers at public and investor-owned utilities.
In the market engineering process, top-down and bottom-up approaches were extensively used, along with several data triangulation methods, to perform market estimation and market forecasting for the overall market segments and subsegments listed in the report. Extensive qualitative and quantitative analyses were performed on the complete market engineering process to list key information/insights throughout the report.
After the complete market engineering (including calculations for market statistics, market breakup, market size estimations, market forecasting, and data triangulation), extensive primary research was conducted to gather information. Primary research was conducted to identify the segmentation, industry trends, key players, competitive landscape, and key market dynamics, such as drivers, restraints, opportunities, challenges, industry trends, and key strategies.
BREAKDOWN OF PRIMARIES
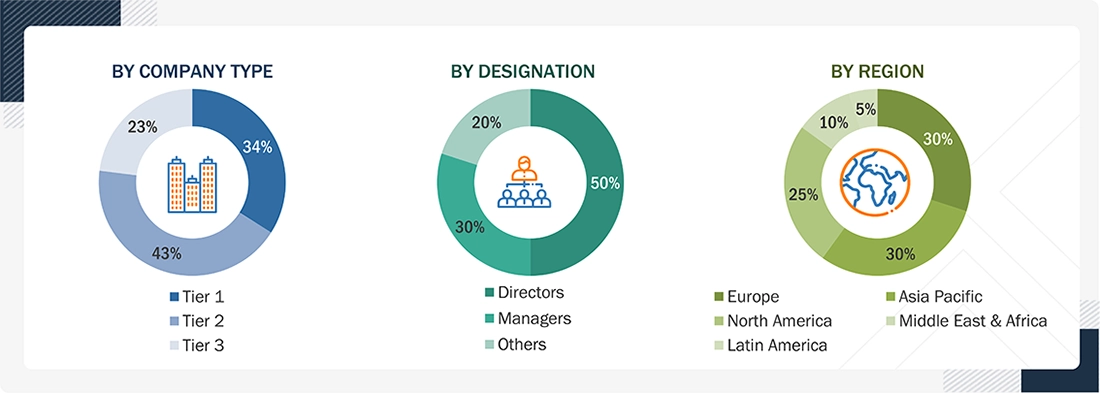
Note: Tier 1 companies have revenues of more than USD 10 billion; tier 2 companies’ revenue ranges from USD 1 billion to USD 10 billion; and tier 3 companies’ revenue ranges from USD 500 million to USD 1 billion.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
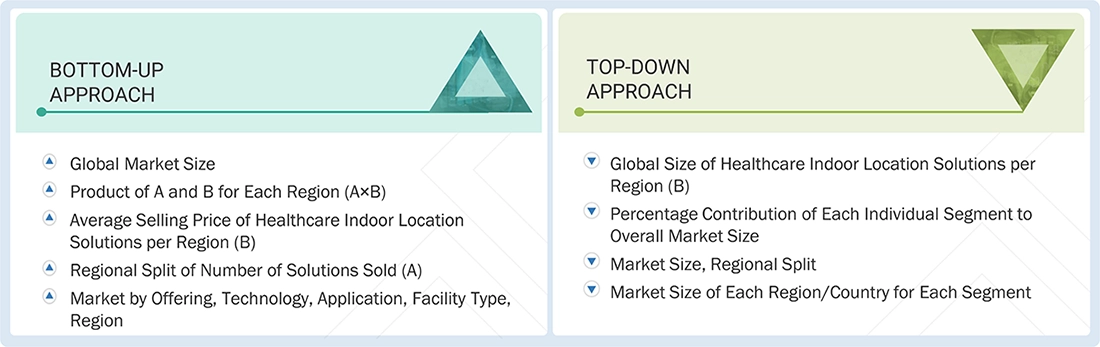
In the market engineering process, the top-down and bottom-up approaches were used along with multiple data triangulation methods to estimate and validate the size of the healthcare indoor location market, as well as other dependent submarkets. The research methodology used to estimate the market sizes includes the following:
- Initially, MarketsandMarkets focuses on top-line investments and spending in the ecosystem. Further, significant developments in the critical market area were considered.
- Tracking recent and upcoming developments in the healthcare indoor location market that include investments, R&D activities, product launches, collaborations, mergers and acquisitions, and partnerships, as well as forecasting the market size based on these developments and other critical parameters.
- Conducting multiple discussions with key opinion leaders to learn about the diverse types of authentications and brand protection offerings used and the applications for which they are used to analyze the breakdown of the scope of work carried out by major companies.
- Segmenting the market based on technology types concerning applications wherein the types are to be used and deriving the size of the global healthcare indoor location market.
- Segmenting the overall market into various market segments
- Validating the estimates at every level through discussions with key opinion leaders, such as chief executives (CXOs), directors, and operations managers, and finally with the domain experts at MarketsandMarkets
Healthcare Indoor Location : Top-Down and Bottom-Up Approach
Data Triangulation
After arriving at the overall market size from the above estimation process, the healthcare indoor location market was split into several segments and sub-segments. To complete the overall market engineering process and arrive at the exact statistics for all segments and sub-segments, data triangulation and market breakdown procedures were used, wherever applicable. The data was triangulated by studying various factors and trends from both the demand and supply sides.
The healthcare indoor location market size was validated using top-down and bottom-up approaches.
Market Definition
Healthcare indoor location refers to the use of indoor positioning and location-tracking technologies to identify, monitor, and determine the real-time or near-real-time location of patients, healthcare staff, medical assets, equipment, and other resources within healthcare facilities.
The technologies used include Bluetooth Low Energy (BLE), RFID, Ultra-Wideband (UWB), Wi-Fi, and infrared (IR) to provide location visibility within hospitals and other healthcare environments. The resulting location information is used for applications such as medical asset tracking, patient and staff tracking, patient flow management, staff safety, infant protection, equipment utilization, indoor navigation, and workflow optimization.
Key Stakeholders
- Healthcare Indoor Location Solution Providers
- Independent Software Vendors (ISVs)
- Investors and Venture Capitalists (VCs)
- Managed Service Providers
- Support and Maintenance Service Providers
- System Integrators (SIs)/Migration Service Providers
- Value-added Resellers (VARs) and Distributors
Report Objectives
- To determine, segment, and forecast the healthcare indoor location market based on offering (hardware, software, and services), technology, application, facility type, and region in terms of value
- To forecast the size of the market segments with respect to five main regions: North America, Europe, Asia Pacific, Middle East & Africa, and Latin America
- To provide detailed information about the major factors (drivers, restraints, opportunities, and challenges) influencing the growth of the market
- To study the complete value chain and related industry segments and perform a value chain analysis of the market landscape
- To strategically analyze the macro and micromarkets with respect to individual growth trends, prospects, and contributions to the total market
- To analyze the industry trends, pricing data, patents, and innovations related to the market
- To analyze the opportunities for stakeholders by identifying the high-growth segments of the market
- To profile the key players in the market and comprehensively analyze their market share/ranking and core competencies
- To track and analyze competitive developments, such as mergers & acquisitions, product launches & developments, partnerships, agreements, collaborations, business expansions, and R&D activities
Available customizations:
With the given market data, MarketsandMarkets offers customizations per the company’s specific needs. The following customization options are available for the report:
Geographic Analysis
- Further break-up of the Asia Pacific market into countries contributing 75% to the regional market size
- Further break-up of the North America market into countries contributing 75% to the regional market size
- Further break-up of the Latin America market into countries contributing 75% to the regional market size
- Further break-up of the Middle East & Africa market into countries contributing 75% to the regional market size
- Further break-up of the Europe market into countries contributing 75% to the regional market size.
Company Information
- Detailed analysis and profiling of additional market players (up to 5)
Get the Full Healthcare Indoor Location Market Report
Full forecast, segment splits, and company analysis for all Healthcare Indoor Location Market.
- UAE Healthcare Indoor Location Market
- South Africa Healthcare Indoor Location Market
- Brazil Healthcare Indoor Location Market
- Mexico Healthcare Indoor Location Market
- Rest Of Europe Healthcare Indoor Location Market
- Rest Of Asia Pacific Healthcare Indoor Location Market
- Rest Of Latin America Healthcare Indoor Location Market
- Ksa Healthcare Indoor Location Market
- Canada Healthcare Indoor Location Market
- US Healthcare Indoor Location Market
- UK Healthcare Indoor Location Market
- Germany Healthcare Indoor Location Market
- France Healthcare Indoor Location Market
- China Healthcare Indoor Location Market
- Japan Healthcare Indoor Location Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report