Italy Laboratory Filtration Market (2024-2029)

The Italy Laboratory Filtration Market was valued at $44 Million in 2024 and projected to reach to $56.5 Million by 2029, representing a compound annual growth rate of 5.1%. Italy's laboratory filtration market is poised for steady expansion through 2029, supported by the country's established pharmaceutical manufacturing base and growing biotechnology sector.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Italy Laboratory Filtration Market Trends and Insights
- This steady expansion reflects Italy's robust pharmaceutical, biotechnology, and clinical research sectors, which increasingly rely on advanced filtration technologies for quality assurance and regulatory compliance.
- Italy's position within the European healthcare landscape drives demand for specialized filtration solutions across diagnostic laboratories, research institutions, and manufacturing facilities. The growth trajectory in Italy is supported by rising investments in healthcare infrastructure and stringent European Union regulatory standards that mandate high-quality filtration in laboratory operations.
- Italy's pharmaceutical industry, a significant contributor to the European market, continues to adopt innovative filtration systems to enhance product purity and safety.
- Between 2024 and 2029, Italy's laboratory filtration market will benefit from increased R&D spending and modernization of laboratory facilities across the country's leading research centers and hospitals..
Key Market Statistics
- CAGR (2024-2029) 5.1% CAGR
- Market Size, 2024 ~USD 44 Million
- Forecast, 2029 ~USD 56.5 Million
- Country Italy
Italy Laboratory Filtration Market Overview
Market Valuation :
Italy's laboratory filtration market is valued at $44.0 million in 2024, with projected growth to $56.5 million by 2029, driven by increasing demand from pharmaceutical and biotechnology sectors.
Steady Growth Trajectory :
The Italian market demonstrates a compound annual growth rate of 5.1%, reflecting consistent investment in quality assurance and regulatory compliance across clinical research and manufacturing facilities.
Pharmaceutical & Biotech Dominance :
Italy's robust pharmaceutical and biotechnology industries are primary drivers of laboratory filtration adoption, with stringent EU regulatory requirements mandating advanced filtration technologies for product quality.
Regulatory Compliance Focus :
Italian laboratories increasingly prioritize filtration solutions to meet EU GMP standards and ISO certifications, positioning advanced filtration as essential for maintaining competitive advantage in European markets.
Italy Laboratory Filtration Market Dynamics
- The 5.1% CAGR reflects moderate but consistent demand as Italian laboratories modernize equipment to meet evolving EU regulatory standards and quality assurance requirements.
- Investment in research infrastructure and clinical diagnostics will continue to drive filtration technology adoption across hospitals, contract research organizations, and manufacturing facilities. The Italian market benefits from its strategic position within the European Union, where harmonized regulations create standardized demand for filtration solutions.
- Emerging opportunities in personalized medicine, vaccine development, and advanced biologics manufacturing present growth catalysts.
- However, market expansion remains measured compared to global rates, suggesting opportunities for suppliers to penetrate underserved segments through localized solutions and technical support tailored to Italian regulatory frameworks..
Market Ecosystem
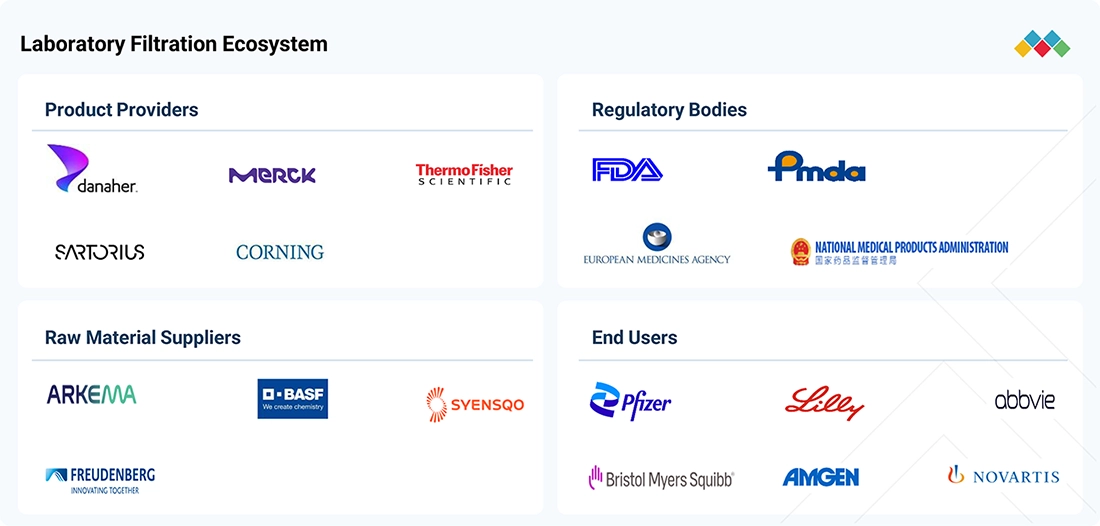
LABORATORY FILTRATION MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Pfizer researchers collaborated with Pennsylvania State University to evaluate commercial 0.2/0.22 µm sterilizing-grade membrane filters for a four-serotype glycoconjugate vaccine formulation. The study compared single-layer and dual-layer membranes to assess filtration capacity, membrane fouling, and prefiltration effectiveness. | The highly asymmetric Millipore Express membrane demonstrated substantially higher filtration capacity than more homogeneous membranes. Its supporting structure acted as an internal prefilter, reducing fouling of the selective membrane layer and providing insights into improving sterile filtration performance. |
 |
Regeneron researchers evaluated PES membrane filters in small-scale sterile filtration studies involving concentrated monoclonal antibody formulations. The study compared pleated and non-pleated membrane configurations to assess polysorbate 80 adsorption-related analytical responses, potential leachable, and filter-flushing performance. | The study demonstrated differences between pleated and non-pleated PES membrane configurations. A secondary analytical peak appeared with the pleated filter but not the non-pleated configuration, highlighting limitations in small-scale model selection and the importance of representative filters for process development. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Biotechnology
- Reagents
- Polymerase Chain Reaction (PCR)
- Stem Cells
- Assay Kits
- Flow Cytometers
- Thermo Fisher Scientific Inc.
- Merck KGaA
- Danaher Corporation
- Agilent Technologies, Inc.
- Bio-Rad Laboratories, Inc.
Key Takeaways
- Italy's laboratory filtration market is valued at $44.0 million in 2024 and will reach $56.5 million by 2029, growing at a 5.1% CAGR.
- Italy's pharmaceutical and biotechnology sectors drive demand for advanced filtration solutions to meet EU regulatory compliance standards.
- Healthcare infrastructure investments and modernization of research facilities support sustained market growth in Italy through 2029.
- Italy's position as a European pharmaceutical hub creates opportunities for specialized filtration technology adoption across clinical and research laboratories.
Laboratory Filtration Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2024 |
| Fastest Growing Segment | MEMBRANE FILTERS (Type) |
| Forecast Period | 2024–2029 |
| Growth Rate | CAGR of 8.3% from 2024 to 2029 |
| Largest Segment | FILTERS & FILTER MEDIA (Product) |
| Market Size Base Year (Billions) | ~USD 4.09 (2024) |
| Revenue Forecast (Billions) | ~USD 6.1 (2029) |
| Segments Covered | Product, Type, Material |
Italy Laboratory Filtration Market Report Segmentation
3 segment dimensions are covered across the global market.
By Product
- Filters & Filter Media
- Filtration Accessories
- Filtration Assemblies
By Type
- Capsule Filters
- Depth Filters
- Filter Dispensers
- Filter Flasks
- Filter Funnels
- Filter Holders
- Filter Housings
- Filter Media
- Membrane Filters
- Membrane Sheets & Discs
- Microfiltration Assemblies
- Mixed Cellulose Ester & Cellulose Acetate (Mce & Ca)
- Nanofiltration Assemblies
- Nylon
- Other Filters
- Other Filtration Accessories
- Other Filtration Assemblies
- Other Filtration Membranes
- Other Membrane Filters
- Polycarbonate Track-Etched (Pcte)
- Polyethersulfone (Pes)
- Polytetrafluoroethylene (Ptfe)
- Polyvinylidene Difluoride (Pvdf)
- Seals
- Syringe Filters
- Syringeless Filters
- Ultrafiltration Assemblies
- Vacuum Pumps
By Material
- Filtration Media
- Filtration Membranes
ITALY: LABORATORY FILTRATION MARKET, BY END USER, 2022–2029
| Segment | 2022 | 2023 | 2024 | 2025 | 2026 | 2027 | 2028 | 2029 | CAGR (%) |
|---|---|---|---|---|---|---|---|---|---|
| ACADEMIC & RESEARCH INSTITUTES | 9.5 | 9.7 | 10 | 10.4 | 10.8 | 11.3 | 11.8 | 12.3 | 4.1 |
| HOSPITALS & CLINICAL LABORATORIES | 4.2 | 4.2 | 4.3 | 4.4 | 4.6 | 4.7 | 4.9 | 5 | 3 |
| PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES | 45.1 | 46.4 | 48.3 | 50.5 | 53.1 | 55.8 | 58.6 | 61.7 | 5 |
| TOTAL | 58.8 | 60.4 | 62.7 | 65.4 | 68.5 | 71.8 | 75.3 | 79 | 4.7 |
Target Audience
- Pharmaceutical Manufacturers : Italian and multinational pharma companies operating in Italy need market intelligence to optimize filtration procurement strategies, ensure regulatory compliance, and evaluate supplier performance in a competitive landscape.
- Biotechnology Companies : Italian biotech firms and research organizations require detailed market data to benchmark filtration technology investments, plan facility upgrades, and align purchasing decisions with industry growth trends.
- Filtration Equipment Suppliers : Manufacturers and distributors of laboratory filtration systems need Italy-specific market insights to identify growth opportunities, refine go-to-market strategies, and understand customer requirements in this regional market.
- Clinical Research Organizations : CROs and diagnostic laboratories in Italy need market analysis to justify capital expenditures on filtration infrastructure, stay competitive, and ensure compliance with evolving quality and regulatory standards.
- Investment & Consulting Firms : Private equity, venture capital, and management consultants require Italy market data to evaluate investment opportunities, assess portfolio company performance, and develop growth strategies in the healthcare filtration sector.
Key Companies in the Italy Laboratory Filtration Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| ALLERGAN PLC | Ireland | Private Company | Medical aesthetics and dermatology,Eye care,Neuroscience and CNS, |
| TECHNICOLOR SA | France | Public Company | Broadband CPE (fiber gateways, routers, extenders, Wi-Fi XL, FWA including Falcon 5G),Video CPE (set-top boxes, dongles, smart media devices, media servers),Software, Platforms, and Service Management (navigate, HomeSight, service management solutions), |
| GENERAL ELECTRIC | United States | Public Company | Commercial Engines & OE Sales,Commercial MRO & Spare Parts,Defense & Propulsion OE, |
| GE HEALTHCARE | United States | Public Company | Imaging,Advanced Visualization Solutions (AVS),Patient Care Solutions (PCS), |
| MERCK KGAA | Germany | Public Company | Life Science (tools, reagents, bioprocessing, CDMO),Healthcare (oncology, neurology, fertility, rare diseases),Electronics (semiconductor and display materials, gases, equipment), |
| DANAHER CORPORATION | United States | Public Company | Biotechnology (bioprocessing and bioproduction solutions),Life Sciences (research tools, genomic and analytical systems),Diagnostics (clinical instruments, consumables, software, services), |
| SARTORIUS AG | Germany | Public Company | Bioprocess solutions (bioreactors, fermenters, filtration, process chromatography, fluid management),Lab products and services (lab filtration, water systems, weighing, pipettes, microbiological testing, OEM),Advanced analytical and cell-based solutions (BLI, cytometry, live-cell imaging, SPR, cell selection, microtissue), |
| THERMO FISHER SCIENTIFIC INC. | United States | Public Company | Life Sciences Solutions,Analytical Instruments,Specialty Diagnostics, |
| 3M COMPANY | United States | Public Company | Safety and Industrial,Transportation and Electronics,Consumer, |
| AGILENT TECHNOLOGIES, INC. | United States | Public Company | Life Sciences and Diagnostics Markets,Agilent CrossLab,Applied Markets, |
| EATON CORPORATION PLC | Ireland | Public Company | Electrical Americas,Electrical Global,Aerospace, |
| GEA GROUP | Germany | Public Company | Separation & Flow Technologies (separators, decanters, valves, pumps),Liquid & Power Technologies (brewing, liquid processing, thermal, carbon capture),Food & Health Technologies (meat, poultry, vegan, pharma processing), |
| AVANTOR, INC. | United States | Public Company | Materials and consumables,Equipment and instrumentation,Services and specialty procurements, |
| STERIS PLC | United States | Public Company | Healthcare (hospitals and providers),Applied Sterilization Technologies (contract sterilization),Life Sciences (pharma and biopharma solutions), |
| AHLSTROM | Finland | Private Company | Filtration and Life Sciences,Food and Consumer Packaging,Protective and Industrial Materials, |
| GVS S.P.A. | Italy | Public Company | Healthcare & Life Sciences Filtration,Health & Safety PPE and Industrial Filtration,Energy & Mobility Components, |
ALLERGAN PLC
Allergan PLC is an Ireland-based private company founded in 1983 with 17,400 employees. The company operates in the pharmaceutical and specialty healthcare sectors.
TECHNICOLOR SA
Technicolor SA is a French public company established in 1985 with 1,552 employees. The company provides media and entertainment technology services.
GENERAL ELECTRIC
General Electric is a United States-based public company founded in 1892 with 57,000 employees. The company operates across multiple industrial and technology sectors.
GE HEALTHCARE
GE Healthcare is a United States-based public company founded in 2022 with 54,000 employees. The company provides healthcare technology and medical imaging solutions.
MERCK KGAA
Merck KGaA is a German public company with roots dating back to 1668 and 59,077 employees. The company operates in pharmaceuticals, life sciences, and performance materials.
DANAHER CORPORATION
Danaher Corporation is a United States-based public company founded in 1969 with 59,000 employees. The company operates across diagnostics, life sciences, and environmental solutions.
SARTORIUS AG
Sartorius AG is a German public company founded in 1870 with 14,242 employees. The company specializes in laboratory and bioprocess technologies.
THERMO FISHER SCIENTIFIC INC.
Thermo Fisher Scientific Inc. is a United States-based public company founded in 1956 with 125,000 employees. The company is a global leader in life sciences, analytical instruments, and laboratory services.
3M COMPANY
3M Company is a United States-based public company founded in 1902 with 60,500 employees. The company manufactures diversified products across industrial, healthcare, safety, and consumer segments.
AGILENT TECHNOLOGIES, INC.
Agilent Technologies, Inc. is a United States-based public company founded in 1999 with 18,000 employees. The company provides analytical instruments, software, and services for life sciences and diagnostics.
EATON CORPORATION PLC
Eaton Corporation PLC is an Ireland-based public company founded in 1911 with 97,303 employees. The company operates in electrical, hydraulic, and industrial power management solutions.
GEA GROUP
GEA Group is a German public company founded in 1881 with 19,670 employees. The company provides process technology and equipment for the food, beverage, and pharmaceutical industries.
AVANTOR, INC.
Avantor, Inc. is a United States-based public company founded in 1904 with 13,500 employees. The company supplies specialty chemicals, materials, and equipment for research and manufacturing.
STERIS PLC
Steris PLC is a United States-based public company founded in 1985 with 17,937 employees. The company provides sterilization, contamination control, and surgical support solutions.
AHLSTROM
Ahlstrom is a Finland-based private company founded in 1851 with 6,883 employees. The company produces fiber-based materials for various industrial applications.
GVS S.P.A.
GVS S.P.A. is an Italy-based public company founded in 1979 with 3,952 employees. The company manufactures filtration and separation products for healthcare and industrial markets.
Reasons to Buy this Report
- Italy-Specific Market Sizing : Obtain precise valuation data for Italy's laboratory filtration market with detailed 2024-2029 forecasts, enabling accurate budget allocation and market entry strategies tailored to Italian pharmaceutical and biotech sectors.
- Regulatory Landscape Insights : Understand how EU GMP standards and Italian regulatory requirements drive filtration technology adoption, helping suppliers align product offerings with compliance mandates specific to Italian laboratories and manufacturers.
- Competitive Positioning : Benchmark your market presence against competitors in Italy's 5.1% CAGR growth environment, identifying gaps in the Italian market and opportunities to capture share from pharmaceutical, biotech, and clinical research segments.
- Sector-Specific Demand Analysis : Access detailed insights into filtration demand across Italian pharmaceutical manufacturing, biotechnology research, and clinical diagnostics, enabling targeted sales strategies for each vertical market.
- Strategic Investment Planning : Make informed decisions about market expansion, partnerships, or acquisitions in Italy by understanding growth drivers, market maturity, and emerging opportunities in advanced biologics and personalized medicine sectors.
Frequently asked questions
What is the current size of Italy's laboratory filtration market?
Italy's laboratory filtration market is valued at $44.0 million in 2024 and is expected to grow to $56.5 million by 2029.
What is the projected growth rate for Italy's laboratory filtration market?
Italy's laboratory filtration market is projected to grow at a compound annual growth rate (CAGR) of 5.1% from 2024 to 2029.
What factors are driving growth in Italy's laboratory filtration market?
Growth in Italy is driven by increased pharmaceutical R&D investments, EU regulatory compliance requirements, modernization of laboratory infrastructure, and expansion of biotechnology research facilities.
Which sectors in Italy are the primary consumers of laboratory filtration products?
Italy's pharmaceutical manufacturing, biotechnology companies, clinical diagnostic laboratories, and academic research institutions are the primary consumers of laboratory filtration solutions.
How does Italy's market compare to the broader European laboratory filtration market?
Italy represents a significant segment of the European laboratory filtration market, with its 5.1% CAGR reflecting steady growth aligned with the region's healthcare modernization and regulatory compliance initiatives.
RESEARCH METHODOLOGY
This study relied heavily on secondary sources, directories, and databases to identify and collect information for analyzing the global laboratory filtration market. The study conducted in-depth interviews with primary respondents, including key industry participants, subject-matter experts (SMEs), C-level executives at major market players, and industry consultants, to gather and validate critical qualitative and quantitative information and assess the market's growth prospects. The global market size estimated through secondary research was then triangulated with primary research inputs to arrive at the final market size.
Secondary Research
Secondary research was used mainly to identify and collect information for the extensive, technical, market-oriented, and commercial study of the laboratory filtration market. The secondary sources used for this study include the International Association of Laboratory Schools (IALS), International Federation of Pharmaceutical Manufacturers & Associations (IFPMA), National Science Foundation (NSF), American Society for Clinical Laboratory Science (ASCLS), American Filtration and Separations Society (AFS), European Federation of Clinical Chemistry and Laboratory Medicine (EFLM), Canadian Association for Laboratory Accreditation (CALA), American Membrane Technology Associations (AMTA), European Membrane Society (EMS), National Center for Biotechnology Information (NCBI), Food and Drug Administration (FDA), European Medicines Agency (EMA), Health Canada, World Health Organization (WHO), International Society for Pharmaceutical Engineering (ISPE), BioPlan Associates, Eurostat, Factiva; corporate & regulatory filings such as annual reports, SEC filings, investor presentations, and financial statements; press releases; and trade, business, and professional associations, among others. These sources were also used to obtain key information on major players, market classification and segmentation aligned with industry trends, regional/country-level markets, market developments, laboratory filtration practices, biopharmaceutical manufacturing trends, and technological perspectives.
Primary Research
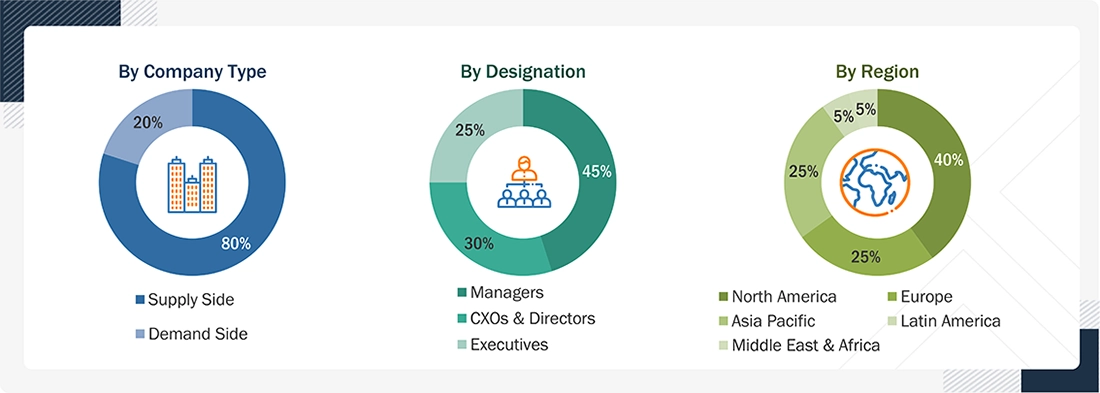
We conducted in-depth interviews with primary respondents, including key industry participants, subject-matter experts (SMEs), C-level executives at key market players, and industry consultants, among others, to gather and validate critical qualitative and quantitative information and assess the market's prospects. We interviewed various primary sources from both the supply and demand sides of the market to gather qualitative and quantitative information. The following is a breakdown of the primary respondents:
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
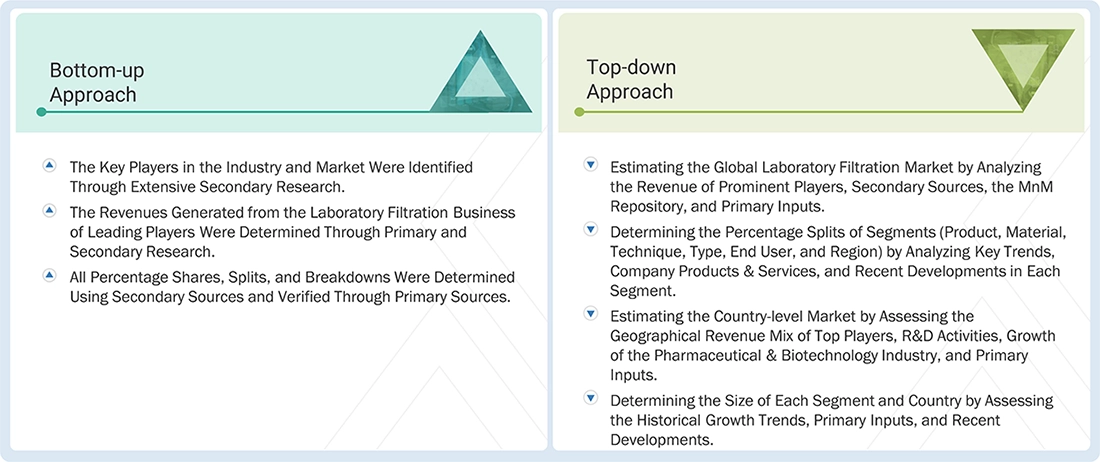
Both top-down and bottom-up approaches were used to estimate and validate the total size of the laboratory filtration market. These methods were also used extensively to estimate the size of various market subsegments. The research methodology used to estimate the market size includes the following:
Data Triangulation
After estimating the market size as described above, the total market was divided into several segments and subsegments. To complete the overall market engineering process and obtain accurate statistics for all segments and subsegments, we employed data triangulation and market breakdown procedures where applicable. We triangulated the data by examining factors and trends from both the demand and supply sides.
Market Definition
Laboratory filtration refers to the separation of solid particles from liquids or gases using a filter medium in a controlled laboratory setting. Laboratory filtration products include filters & filter media, filtration assemblies, and filtration accessories used for laboratory-scale physical and chemical processes. This market includes laboratory filtration products that are utilized by pharmaceutical & biopharmaceutical companies, academic & research institutes, and hospitals & diagnostic laboratories.
This report covers laboratory filtration products used for separation, clarification, purification, and sterile filtration. These include membrane filters, membrane sheets and discs, filter media, depth filters, filtration assemblies, and filtration accessories used across research, sample preparation, analytical testing, and biopharmaceutical manufacturing.
Key Stakeholders
- Laboratory filtration equipment and accessory manufacturing companies
- Laboratory filtration equipment and accessory distributors
- Pharmaceutical and biotechnology companies
- Hospitals and clinical laboratories
- Academic and research institutes
- Life science companies
- Market research and consulting firms
- Venture capitalists and investors
- Contract research organizations (CROs)
- Government organizations
- Private research firms
Report Objectives
- To define, describe, and forecast the laboratory filtration market based on product, material, technique, type, end user, and region
- To provide detailed information regarding the factors influencing market growth such as drivers, opportunities, restraints, and challenges
- To strategically analyze micromarkets with respect to individual growth trends, prospects, and contributions to the overall laboratory filtration market
- To analyze key market opportunities for stakeholders and provide details of the competitive landscape for key players
- To profile the key players in the global laboratory filtration market, as well as comprehensively analyze their core competencies and market rankings
- To forecast the size of the market segments for six regions: North America (US and Canada), Europe (Germany, France, UK, Italy, Spain, and the Rest of Europe), Asia Pacific (Japan, China, India, Australia, South Korea, and Rest of Asia Pacific), Latin America (Brazil, Mexico, and Rest of Latin America), Middle East (GCC and Rest of Middle East), and Africa
- To analyze competitive developments, such as product launches, expansions, acquisitions, partnerships, collaborations, and agreements in the laboratory filtration market
- To benchmark players within the market using the proprietary “Company Evaluation Matrix” framework, which analyzes market players on various parameters within the broad categories of business and product excellence strategies
Available customizations:
Based on the market data provided, MarketsandMarkets offers customization to meet the company’s specific needs. The following customization options are available for this report:
Portfolio Assessment
- Product Matrix, which gives a detailed comparison of the product portfolios of the top four companies.
Company Information
- Detailed analysis and profiling of additional market players (up to five).
Geographical Analysis
- A further breakdown of the Rest of Europe laboratory filtration market, by country
- A further breakdown of the Rest of Asia Pacific laboratory filtration market, by country
- A further breakdown of the Rest of Latin America laboratory filtration market, by country
Get the Full Laboratory Filtration Market Report
Full forecast, segment splits, and company analysis for all Laboratory Filtration Market.
- Canada Laboratory Filtration Market
- US Laboratory Filtration Market
- Germany Laboratory Filtration Market
- UK Laboratory Filtration Market
- France Laboratory Filtration Market
- Spain Laboratory Filtration Market
- China Laboratory Filtration Market
- Japan Laboratory Filtration Market
- India Laboratory Filtration Market
- South Korea Laboratory Filtration Market
- Australia Laboratory Filtration Market
- Brazil Laboratory Filtration Market
- Mexico Laboratory Filtration Market
- Saudi Arabia Laboratory Filtration Market
- UAE Laboratory Filtration Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
