UK Onshore Wind Market (2026-2031)
The UK Onshore Wind Market was valued at $2104.2 Million in 2026 and projected to reach to $6084 Million by 2031, representing a compound annual growth rate of 12.5%. The UK onshore wind market is positioned for exceptional growth, expanding from $2,104.2 million in 2026 to $6,084 million by 2031.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
UK Onshore Wind Market Trends and Insights
- The UK's commitment to renewable energy targets and net-zero ambitions is driving substantial investment in onshore wind capacity.
- The UK's favorable wind resources, combined with supportive government policies and declining turbine costs, position the country as a key growth market within Europe's renewable energy transition. Between 2026 and 2031, the UK onshore wind sector is expected to grow at a compound annual growth rate of 12.5%, significantly outpacing global averages.
- The UK's expansion is underpinned by increased grid connectivity, technological advancements, and competitive auction mechanisms that attract both domestic and international developers.
- The UK's strategic focus on energy security and decarbonization ensures sustained momentum in onshore wind deployment throughout the forecast period..
Key Market Statistics
- CAGR (2026-2031) 12.5% CAGR
- Market Size, 2026 ~USD 2104.2 Million
- Forecast, 2031 ~USD 6084 Million
- Country UK
UK Onshore Wind Market Overview
Strong CAGR Growth :
The UK onshore wind market is projected to grow at a 12.5% CAGR from 2026 to 2031, outpacing the global average of 10.3%, reflecting accelerating domestic investment and capacity expansion.
Net-Zero Policy Support :
The UK government's commitment to achieving net-zero emissions by 2050 and renewable energy targets is driving substantial policy support, subsidies, and regulatory frameworks favoring onshore wind development.
Declining Turbine Costs :
Technological advancements and supply chain maturation have significantly reduced onshore wind turbine costs in the UK, improving project economics and attracting private and institutional investment.
Optimal Wind Resources :
The UK's geographic location and coastal regions provide exceptional wind resources, enabling high capacity factors and making onshore wind projects economically viable across multiple regions.
UK Onshore Wind Market Dynamics
- This trajectory reflects the UK's strategic pivot toward renewable energy independence and climate commitments, supported by streamlined planning processes and competitive auction mechanisms that attract major developers.
- Increasing grid modernization investments and energy storage integration further enhance market viability. Key drivers include rising electricity demand, corporate renewable energy procurement commitments, and declining financing costs for wind projects.
- The UK's skilled workforce and established supply chain provide competitive advantages.
- However, challenges such as grid connection delays and planning constraints may moderate growth rates.
- Overall, the market presents substantial opportunities for developers, investors, and technology providers aligned with the UK's energy transition agenda..
Market Ecosystem
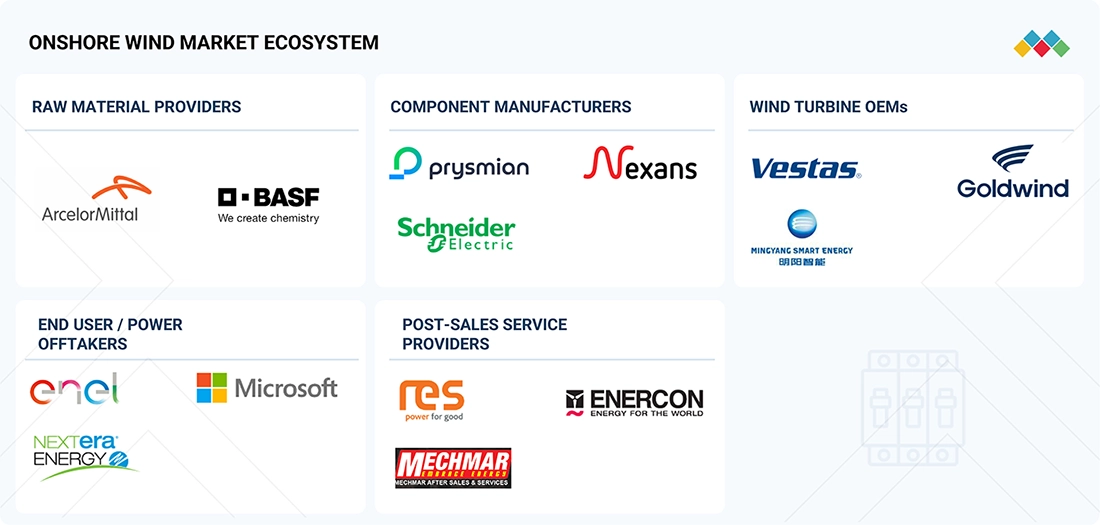
ONSHORE WIND MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Whitelee Wind Farm, one of the UK’s largest onshore wind facilities, required modernization to improve energy output and operational efficiency while supporting the country’s renewable energy targets. Aging assets and evolving grid requirements made repowering and digital optimization increasingly important. | Modernization enhanced annual energy production, reduced maintenance-related downtime, extended asset life, and improved overall project economics. It also supported lower lifecycle costs and increased reliability, enabling the wind farm to continue supplying renewable electricity efficiently. |
 |
The 372 MW Björnberget project in Sweden was developed to strengthen renewable electricity generation in the Nordic region while taking advantage of favorable wind resources and modern high-capacity turbine technology | The project achieved higher energy capture, improved operational efficiency, and enhanced reliability, contributing substantial clean electricity to the regional grid while reducing the levelized cost of energy over the project lifetime. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Decarbonization
- Battery Electric Vehicle (BEV)
- Energy Management Systems
- Fuel Cell
- Fuel Cell Electric Vehicle (FCEV)
- Geographical Information System (GIS)
- TotalEnergies SE
- Siemens ag
- Mitsui & Co., Ltd.
- General Electric Company
- Thyssenkrupp ag
Key Takeaways
- The UK onshore wind market will nearly triple from $2,104.2M (2026) to $6,084M (2031), representing a 12.5% CAGR.
- The UK's net-zero commitments and renewable energy targets are primary catalysts for accelerated onshore wind investment.
- The UK benefits from superior wind resources and established supply chains, attracting major global wind developers.
- The UK's competitive auction framework and grid modernization initiatives support sustained market growth through 2031.
Onshore Wind Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2026 |
| Fastest Growing Segment | ABOVE 5 MW (Turbine Rating) |
| Forecast Period | 2026-2031 |
| Growth Rate | CAGR of 10.3% from 2026 to 2031 |
| Largest Segment | TURBINES (Component) |
| Market Size Base Year (Billions) | ~USD 132.9 (2026) |
| Revenue Forecast (Billions) | ~USD 216.97 (2031) |
| Segments Covered | Component, Turbine Rating |
UK Onshore Wind Market Report Segmentation
2 segment dimensions are covered across the global market.
By Component
- Electrical Infrastructure
- Turbines
By Turbine Rating
- 2-3 Mw
- 4-5 Mw
- Above 5 Mw
- Below 2 Mw
Target Audience
- Wind Energy Developers : UK-based and international developers need market sizing, growth forecasts, and policy insights to identify pipeline opportunities, secure financing, and plan capacity expansion across UK regions.
- Institutional Investors : Infrastructure funds, pension funds, and private equity firms require validated market data and growth projections to evaluate UK wind portfolio investments, assess risk-return profiles, and allocate capital strategically.
- Equipment & Turbine Manufacturers : OEMs and component suppliers need UK market forecasts and cost trend analysis to optimize production capacity, plan supply chain investments, and identify demand drivers for turbine sales and services.
- Utility & Energy Companies : UK utilities and energy majors require market intelligence to guide renewable energy procurement strategies, assess competitive threats, and plan grid integration and capacity investments.
- Policy & Regulatory Bodies : Government agencies and regulatory authorities use market data to evaluate policy effectiveness, forecast capacity targets, and design incentive mechanisms aligned with net-zero commitments and energy security goals.
Reasons to Buy this Report
- Market Size & Growth Validation : Obtain precise UK market valuation ($2,104.2M in 2026) and verified forecast data ($6,084M by 2031) to support investment decisions, business planning, and competitive positioning in the UK wind sector.
- Policy & Regulatory Intelligence : Understand UK-specific net-zero policies, government incentives, planning frameworks, and auction mechanisms that directly impact project viability, timelines, and return on investment for onshore wind developments.
- Competitive Landscape Analysis : Identify key UK market players, emerging developers, and competitive dynamics to benchmark performance, identify partnership opportunities, and develop targeted market entry or expansion strategies.
- Investment & Financing Insights : Access data on UK financing trends, capital allocation patterns, and investor sentiment to optimize funding strategies, identify growth segments, and evaluate risk-adjusted returns for wind projects.
- Technology & Cost Benchmarking : Leverage UK-specific turbine cost trends, technology adoption rates, and supply chain developments to optimize procurement strategies, improve project economics, and maintain technological competitiveness.
Frequently asked questions
What is the projected size of the UK onshore wind market by 2031?
The UK onshore wind market is projected to reach $6,084 million by 2031, growing from $2,104.2 million in 2026.
What is the CAGR for the UK onshore wind market?
The UK onshore wind market is expected to grow at a compound annual growth rate of 12.5% between 2026 and 2031.
What are the main drivers of growth in the UK onshore wind sector?
Key growth drivers for the UK include net-zero policy commitments, renewable energy targets, favorable wind resources, declining turbine costs, and competitive auction mechanisms.
How does the UK onshore wind market compare to global trends?
The UK's 12.5% CAGR significantly exceeds the global onshore wind market CAGR of 10.3%, reflecting the UK's accelerated renewable energy transition.
What infrastructure investments support UK onshore wind expansion?
The UK is investing in grid modernization, transmission capacity upgrades, and enhanced connectivity to accommodate increased onshore wind generation through 2031.
RESEARCH METHODOLOGY
The study involved major activities in estimating the current size of the onshore wind market. Exhaustive secondary research was done to collect information on the peer and parent markets. The next step was to validate these findings, assumptions, and sizing with industry experts across the value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the complete market size. Thereafter, market breakdown and data triangulation were used to estimate the market size of the segments and subsegments.
Secondary Research
This research study on the onshore wind market involved the use of extensive secondary sources, directories, and databases, such as D&B Hoovers, Bloomberg, Businessweek, Factiva, International Energy Agency, and BP Statistical Review of World Energy, to identify and collect valuable information for a technical, market-oriented, and commercial study of the global onshore wind market. The other secondary sources included companies' annual reports, press releases, and investor presentations; white papers; certified publications; articles by recognized authors; manufacturer associations; trade directories; and databases.
Primary Research
The onshore wind market comprises stakeholders across the value chain, including onshore wind turbine manufacturers, component suppliers, onshore cable manufacturers, onshore substation providers, EPC contractors, project developers, utilities, transmission system operators, engineering consultants, digital technology providers, and operations & maintenance service providers. On the demand side, the market is driven by the increasing deployment of onshore wind projects across key regions, including Europe, Asia Pacific, and North America, supported by growing investments from utilities, independent power producers (IPPs), governments, and industrial energy consumers seeking large-scale renewable energy solutions. On the supply side, turbine manufacturers, foundation suppliers, electrical infrastructure providers, and onshore service companies are benefiting from increasing project awards, long-term supply agreements, and investments in onshore renewable energy infrastructure. Various primary sources from both the supply and demand sides of the market were interviewed to obtain qualitative and quantitative information. The following is the breakdown of primary respondents:
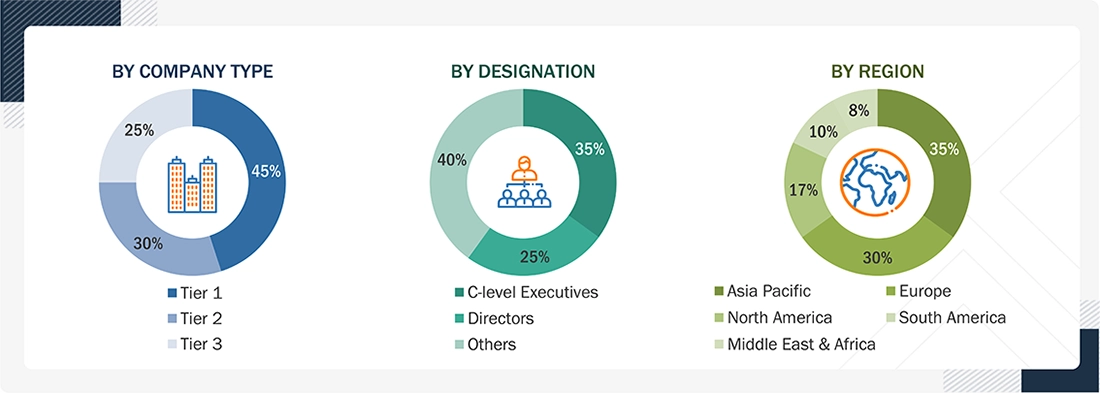
Note: Others include sales managers, engineers, and regional managers.
The tiers of the companies are defined by their total revenue as of 2024: Tier 1: > USD 1 billion; Tier 2: USD 500 million–1 billion; and Tier 3: < USD 500 million.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
Both top-down and bottom-up approaches were employed to estimate and validate the size of the onshore wind market and its dependent submarkets. The key players in the market were identified through secondary research, and their market share in the respective regions was determined through a combination of primary and secondary research. The research methodology involves analyzing the annual and financial reports of leading market players and conducting interviews with industry experts, including chief executive officers, vice presidents, directors, sales managers, and marketing executives, to gather key quantitative and qualitative insights into the onshore wind market.
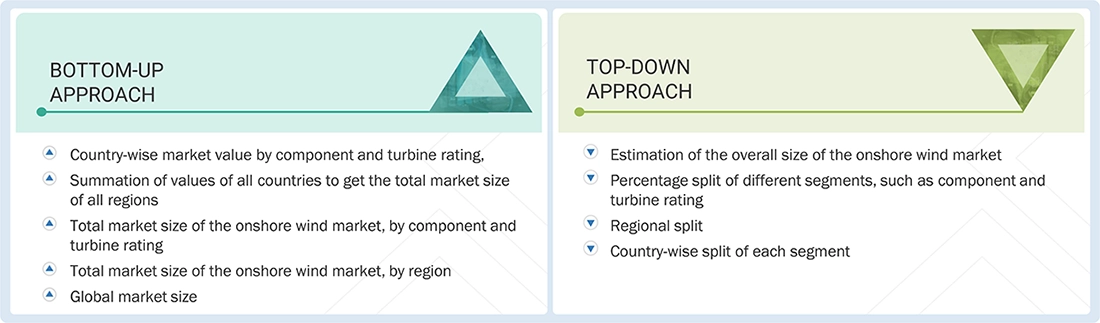
Data Triangulation
After determining the overall market size through the estimation process explained above, the total market has been divided into several segments and subsegments. To complete the overall market engineering process and obtain exact statistics for all segments and subsegments, data triangulation and market breakdown have been employed where applicable. The data has been triangulated by studying various factors and trends from both the demand and supply sides. Additionally, the market has been validated using both top-down and bottom-up approaches.
Market Definition
The onshore wind market encompasses the development, manufacturing, and installation of land-based wind energy systems that generate electricity from wind. It includes key components such as wind turbines, nacelles, rotors and blades, towers, and supporting electrical infrastructure, including wires and cables, substations, and related balance-of-plant equipment. The market covers turbine capacity segments ranging from up to 2 MW to above 5 MW and serves utility-scale, commercial, industrial, and government-backed renewable energy projects. Market growth is driven by decarbonization initiatives, favorable regulatory policies, technological advancements in turbine design, declining electricity generation costs, and increasing investments in sustainable and energy-secure power infrastructure.
Key Stakeholders
- Project Developers & Owners
- Turbine Manufacturers
- EPC Contractors & Marine Engineering Firms
- Mooring, Anchoring, & Subsea System Providers
- Electrical Infrastructure & Grid Connection Providers
- Governments & Regulatory Authorities
- Investors & Financial Institutions
- Research Institutions & Certification Bodies
- Energy Associations
- Environmental Associations
- Energy Efficiency Consultants
Report Objectives
- To describe and forecast the onshore wind market, by turbine rating and component, in terms of value
- To describe and forecast the onshore wind market for various segments with respect to five main regions: North America, Europe, Asia Pacific, South America, and Middle East & Africa, along with their country-level analysis, in terms of value
- To provide detailed information regarding the major drivers, restraints, opportunities, and challenges influencing the growth of the onshore wind market
- To analyze market opportunities for stakeholders and provide a detailed competitive landscape for market leaders
- To strategically analyze micromarkets about individual growth trends, prospects, and contributions to the total market
- To strategically profile the key players and comprehensively analyze their market shares and core competencies
- To provide a detailed overview of the unmet needs and white spaces, interconnected markets and cross-sector opportunities, strategic moves by tier-1/2/3 players, onshore wind market value chain analysis, ecosystem analysis, key conferences and events, key stakeholders and buying criteria, patent analysis, trends/disruptions impacting customer business, trade analysis, tariff analysis, investment and funding scenario, technology analysis, technology/product roadmap, case study analysis, regulations, future applications, macroeconomic outlook, pricing analysis, Porter’s five forces analysis, sustainability initiatives, adoption barriers and internal challenges, market profitability, impact of regulatory policies on sustainability initiatives, certifications, labeling and eco-standards, decision making process, impact of gen AI, and the 2024 US tariff impact
- To analyze competitive developments, such as agreements, product launches, expansions, contracts, investments, partnerships, collaborations, announcements, and acquisitions in the market
Available customizations:
MarketsandMarkets offers customizations tailored to the specific needs of companies using the given market data.
The following customization options are available for the report:
Product Analysis
- Product matrix, which gives a detailed comparison of the product portfolio of each company
Regional Analysis
- Further breakdown of the onshore wind systems, by country
Company Information
- Detailed analysis and profiling of additional market players (up to five)
Get the Full Onshore Wind Market Report
Full forecast, segment splits, and company analysis for all Onshore Wind Market.
- China Onshore Wind Market
- India Onshore Wind Market
- Australia Onshore Wind Market
- Vietnam Onshore Wind Market
- Canada Onshore Wind Market
- US Onshore Wind Market
- Germany Onshore Wind Market
- Spain Onshore Wind Market
- France Onshore Wind Market
- Italy Onshore Wind Market
- Sweden Onshore Wind Market
- Saudi Arabia Onshore Wind Market
- South Africa Onshore Wind Market
- Brazil Onshore Wind Market
- Rest Of Europe Onshore Wind Market
- Rest Of Asia Pacific Onshore Wind Market
- Rest Of South America Onshore Wind Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report