UK Video as a Sensor Market (2024-2029)

The UK Video as a Sensor Market was valued at $2449.2 Million in 2024 and projected to reach to $3246 Million by 2029, representing a compound annual growth rate of 5.8%. The UK video as a sensor market is positioned for sustained growth through 2029, driven by digital transformation initiatives across manufacturing, retail, and security sectors.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
UK Video as a Sensor Market Trends and Insights
- The UK market is expanding at a compound annual growth rate of 5.8%, driven by increasing adoption of computer vision technologies across manufacturing, retail, and security sectors.
- The UK's strong semiconductor and electronics infrastructure supports the deployment of advanced imaging sensors and AI-powered video analytics solutions. In 2024, the UK market reflects growing investment in smart surveillance systems, autonomous vehicles, and industrial automation.
- By 2029, the UK is expected to see accelerated adoption as enterprises integrate video sensing capabilities into IoT ecosystems and edge computing platforms.
- The UK's regulatory environment and emphasis on data privacy are shaping how video sensor technologies are deployed across public and private sectors. The UK market benefits from a mature technology ecosystem and skilled workforce, positioning the country as a key hub for video sensor innovation in Europe.
- Demand from healthcare, transportation, and smart city initiatives continues to drive market expansion throughout the forecast period..
Key Market Statistics
- CAGR (2024-2029) 5.8% CAGR
- Market Size, 2024 ~USD 2449.2 Million
- Forecast, 2029 ~USD 3246 Million
- Country UK
UK Video as a Sensor Market Overview
Market Valuation :
The UK video as a sensor market is valued at £2,449.2 million in 2024, with projections to reach £3,246 million by 2029, representing a steady CAGR of 5.8%.
Key Growth Drivers :
Manufacturing automation, retail analytics, and security surveillance are the primary sectors driving adoption of computer vision technologies across the UK, supported by strong semiconductor infrastructure.
Regional Competitiveness :
The UK market grows at 5.8% CAGR, slightly below the global average of 7.9%, reflecting a mature but stable market with established technology adoption patterns.
Industry Infrastructure :
The UK's robust semiconductor and electronics ecosystem provides a competitive advantage, with established supply chains and technical expertise supporting video sensor innovation and deployment.
UK Video as a Sensor Market Dynamics
- Investment in Industry 4.0 technologies and smart retail solutions continues to accelerate adoption of computer vision systems.
- The UK's established semiconductor manufacturing base and strong R&D capabilities provide a foundation for innovation in video sensor applications. Looking ahead, the market will benefit from increasing integration of AI and machine learning with video sensing technologies, particularly in predictive maintenance and customer analytics.
- Government support for digital infrastructure and cybersecurity standards will further encourage adoption.
- However, growth rates remain moderate compared to global markets, reflecting the UK's mature technology landscape and competitive pressures from international players..
Market Ecosystem
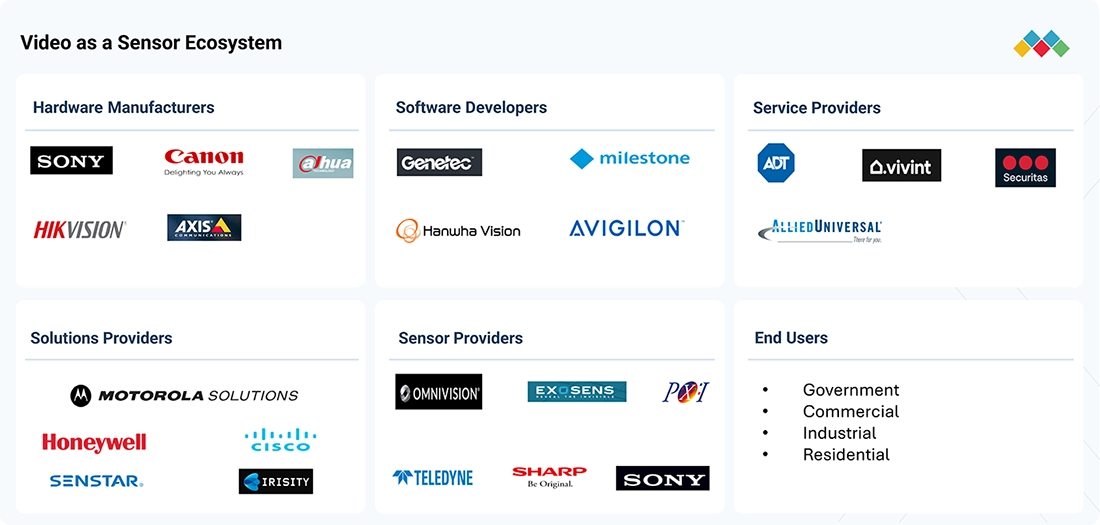
VIDEO AS A SENSOR MARKET SIZE, SHARE AND TRENDS: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Hikvision offers AI-enabled video sensing solutions that combine intelligent cameras, deep-learning algorithms, edge computing, and cloud-based analytics. Its AI technologies enable automatic detection, classification, and analysis of people, vehicles, and objects, while its AIoT architecture integrates video with IoT data for security, traffic management, retail, manufacturing, and smart-city applications. | Enables real-time intelligent detection | Reduces false alarms | Supports automated monitoring | Improves situational awareness and operational efficiency |
 |
Dahua Technology provides AI-based video sensing through its WizMind portfolio, integrating deep-learning algorithms across network cameras, PTZ cameras, NVRs, thermal cameras, and software platforms. Its solutions support human and vehicle detection, video metadata, people counting, ANPR, parking management, PPE detection, and behavioral analysis across transportation, retail, energy, finance, and other verticals. | Enables accurate object and behavior detection | Supports real-time business analytics | Improves traffic and security management | Enables automated decision-making |
 |
Honeywell provides intelligent video surveillance solutions incorporating AI analytics, smart motion detection, people counting, object detection, license plate recognition, vehicle tracking, heat mapping, and occupancy monitoring. Its AI-enabled cameras and video management platforms transform surveillance footage into actionable intelligence for commercial, industrial, critical infrastructure, and perimeter-security applications. | Enhances security and situational awareness | Reduces nuisance alarms | Enables occupancy and behavior monitoring | Improves incident response and facility management |
 |
Bosch integrates AI-driven video analytics directly into its cameras to detect and classify objects, monitor predefined areas, and identify events such as loitering or intrusion. Its Intelligent Insights platform converts video analytics metadata into actionable information such as people counting, occupancy, crowd detection, object counting, and object positioning for security and operational applications. | Enables proactive threat detection | Improves situational awareness | Supports operational efficiency | Converts video data into actionable insights |
 |
Cisco, through its Meraki MV smart camera portfolio, combines onboard processing, AI-powered analytics, cloud management, and video intelligence. Its smart cameras provide person and vehicle detection, people counting, heat maps, object detection, motion and audio analytics, and cloud-based remote management, enabling video to function as a data source for physical security and business intelligence. | Reduces infrastructure complexity | Enables real-time video intelligence | Supports remote monitoring and management | Improves security and data-driven decision-making |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Sensors And Control
- Sensors
- Temperature Sensors
- Image Sensors
- Pressure Sensors
- Flow Sensors
- BAUMER ELECTRIC AG
- HONEYWELL INTERNATIONAL INC.
- Stmicroelectronics
- Lenovo
- Texas Instruments Incorporated
Automotive Advance Technologies
- Battery Electric Vehicle (BEV)
- Light Commercial Vehicles (LCVs)
- Fuel Cell Electric Vehicle (FCEV)
- Hybrid Electric Vehicle (HEV)
- Internal Combustion Engine (ICE)
- BOSCH LIMITED
- Continental ag
- Visteon Corporation
- DENSO Corporation
- ZF FRIEDRICHSHAFEN AG
Industrial Automation
- Sensors
- Image Sensors
- Manufacturing Execution System (MES)
- Actuators
- Flow Sensors
- Siemens ag
- ABB India Limited
- Emerson Electric Co.
- HONEYWELL INTERNATIONAL INC.
- SCHNEIDER ELECTRIC SE
Key Takeaways
- The UK video as a sensor market is valued at £2,449.2 million in 2024 and will grow to £3,246 million by 2029 at a 5.8% CAGR.
- The UK market is driven by adoption of computer vision in manufacturing, retail, security, and autonomous vehicle applications.
- The UK's regulatory focus on data privacy and GDPR compliance shapes video sensor deployment strategies across industries.
- The UK's mature semiconductor ecosystem and skilled workforce position it as a European leader in video sensor innovation.
Video as a Sensor Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2024 |
| Fastest Growing Segment | HYPERSPECTRAL IMAGING (Product Type) |
| Forecast Period | 2024-2029 |
| Growth Rate | CAGR of 7.9% from 2024 to 2029 |
| Largest Segment | VIDEO SURVEILLANCE (Product Type) |
| Market Size Base Year (Billions) | ~USD 69.67 (2024) |
| Revenue Forecast (Billions) | ~USD 101.89 (2029) |
| Segments Covered | Offering, Type, Camera Type, Camera Component, Product Type, End User, Application |
UK Video as a Sensor Market Report Segmentation
7 segment dimensions are covered across the global market.
By Offering
- Hardware
- Services
- Software
By Type
- Accessories
- AI And Machine Learning Algorithms
- Cameras
- Dvrs
- Image Sensor
- Infrared Sensor
- Installation & Maintenance Services
- Integration Software
- Intelligent Video Analytics Software
- Monitors
- Motion Sensor
- Nvrs
- Storage Devices
- Video Management Software
- Vsaas
By Camera Type
- Hyperspectral Imaging Cameras
- Ip Cameras
- Machine Vision Cameras
- Thermal Cameras
By Camera Component
- Camera Sensors
- Other Components
- Processors
By Product Type
- Hyperspectral Imaging
- Machine Vision And Monitoring
- Thermal Imaging
- Video Surveillance
By End User
- Commercial
- Government
- Industrial
- Residential
By Application
- Healthcare
- Manufacturing
- Mapping
- Retail Analytics
- Security & Surveillance
- Traffic Management
Target Audience
- UK Electronics Manufacturers : Manufacturers need detailed market sizing and sector adoption data to identify growth opportunities in video sensor technology and plan product development roadmaps aligned with UK demand.
- Retail & Security Solution Providers : UK-based retailers and security firms require market insights to understand computer vision adoption trends, competitive positioning, and investment priorities for analytics and surveillance solutions.
- Investment & Private Equity Firms : Investors targeting the UK semiconductor and electronics sector need precise market valuations, growth forecasts, and sector analysis to evaluate acquisition targets and portfolio opportunities.
- Technology Consultants & Systems Integrators : UK consultants advising manufacturing and retail clients need market data and adoption trends to recommend video sensor solutions and justify technology investments to stakeholders.
- Government & Policy Bodies : UK government agencies and policy makers require market intelligence to inform digital infrastructure investments, industry support programs, and competitiveness initiatives in semiconductor technology.
Reasons to Buy this Report
- UK-Specific Market Sizing : Access precise valuation data for the UK market (£2,449.2M in 2024) with detailed forecasts through 2029, enabling accurate budget allocation and investment planning for UK operations.
- Sector-Focused Insights : Understand growth dynamics across UK manufacturing, retail, and security sectors with tailored analysis of how computer vision adoption varies by industry vertical and regional deployment patterns.
- Competitive Landscape Analysis : Benchmark UK market performance against global trends (5.8% vs 7.9% CAGR) and identify competitive positioning opportunities within the UK's established semiconductor and electronics ecosystem.
- Strategic Investment Guidance : Make informed decisions on UK market entry, expansion, or partnership strategies with comprehensive analysis of growth drivers, infrastructure advantages, and technology adoption readiness.
- Regulatory & Infrastructure Context : Leverage insights into the UK's semiconductor infrastructure, supply chain dynamics, and digital transformation initiatives to align product development and go-to-market strategies with local market conditions.
Frequently asked questions
What is the current size of the UK video as a sensor market?
The UK video as a sensor market was valued at £2,449.2 million in 2024 and is projected to reach £3,246 million by 2029.
What is the growth rate of the UK video as a sensor market?
The UK market is growing at a compound annual growth rate (CAGR) of 5.8% from 2024 to 2029.
Which industries are driving the UK video as a sensor market?
The UK market is driven by manufacturing, retail, security, healthcare, transportation, and smart city applications that leverage computer vision and AI-powered video analytics.
How does UK regulation impact video sensor deployment?
The UK's GDPR compliance requirements and data privacy regulations shape how organizations implement video sensing technologies, requiring robust data protection and consent mechanisms.
What competitive advantages does the UK market offer?
The UK benefits from a mature semiconductor ecosystem, skilled technical workforce, strong R&D capabilities, and established technology infrastructure supporting video sensor innovation.
RESEARCH METHODOLOGY
The study involved four major activities to estimate the current size of the global Video as a Sensor market. Extensive secondary research was conducted to gather information on the Video as a Sensor ecosystem, including camera manufacturers, video analytics providers, AI and computer vision companies, image sensor and semiconductor companies, component suppliers, distributors, system integrators, technology providers, and end users. This was followed by primary research with industry stakeholders across the value chain, including video surveillance manufacturers, AI analytics providers, technology developers, component suppliers, distributors, OEMs, system integrators, commercial enterprises, industrial companies, transportation operators, and end users, to validate assumptions and market sizing. Both top-down and bottom-up approaches were used to estimate the overall market size. Market breakdowns and data triangulation techniques were then applied to determine the size of individual segments and subsegments by component, technology, deployment, application, end-use industry, and region. Secondary and primary sources were used together to support a comprehensive technical, commercial, and competitive analysis of the global video as a sensor market.
Secondary Research
Secondary research drew on a range of sources to identify and collect information relevant to the Video as a Sensor market. These sources included annual reports, company presentations, press releases, product catalogs, technical datasheets, patents, technical journals, industry publications, company websites, trade directories, and government databases. The research provided key insights into the market’s supply chain, value chain, competitive landscape, and segmentation by component, technology, deployment, application, end-use industry, and region. It also helped assess industry trends, adoption of Video as a Sensor solutions across commercial, industrial, transportation, retail, smart city, critical infrastructure, healthcare, and public safety applications, and advancements in AI-powered cameras, computer vision, edge computing, deep-learning video analytics, IoT-enabled cameras, cloud-based video platforms, and multi-sensor technologies. The collected information was further analyzed to estimate the overall market size and validate market assumptions, which were subsequently refined through primary research with industry experts and key stakeholders.
Primary Research
Extensive primary research was conducted after secondary research provided insight into the current state of the video as a sensor market. Several primary interviews were conducted with experts from the demand and supply sides across four major regions: North America, Europe, Asia Pacific, and RoW. This primary data was collected through questionnaires, emails, and telephone interviews.
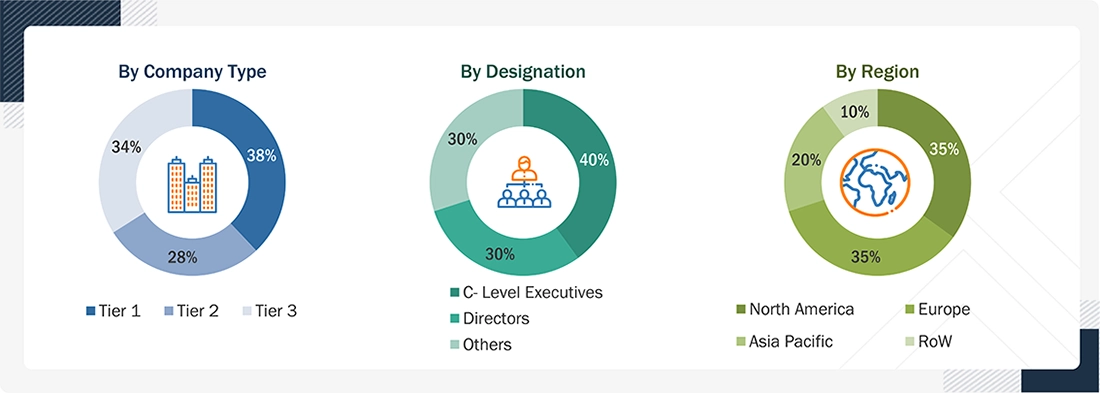
Note: The three tiers of the companies are defined based on their total revenue in 2025: Tier 1 - revenue greater than or equal to USD 1 billion; Tier 2 - revenue between USD 100 million and USD 1 billion; and Tier 3 revenue less than or equal to USD 100 million. Other designations include sales managers, marketing managers, and product managers.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
Both top-down and bottom-up approaches were used to estimate and validate the total size of the video as a sensor market. These methods have also been used extensively to estimate the size of various market subsegments. The following research methodology was used to estimate the market size:
- Major players in the video as a sensor market and related markets were identified through extensive secondary research.
- The industry’s value chain and market size in terms of value and volume were determined through primary and secondary research processes.
- All percentage shares, splits, and segment-level breakdowns were determined using secondary sources and verified through primary research and data triangulation.
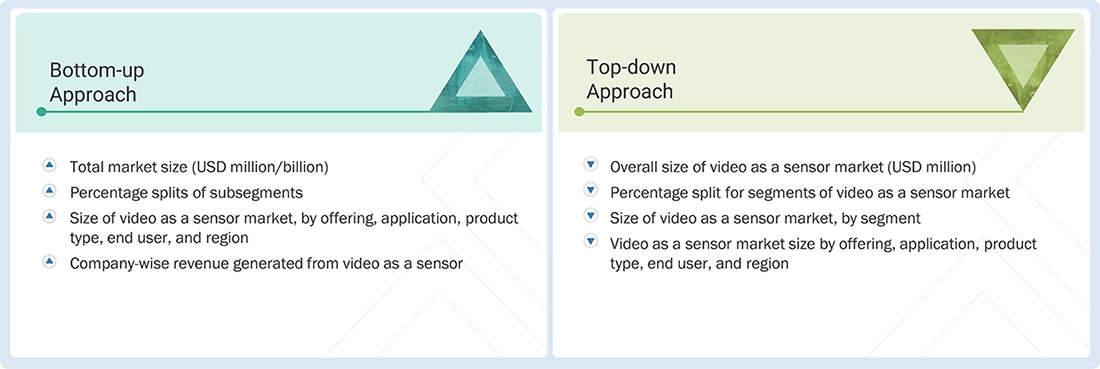
Data Triangulation
After determining the overall size of the Video as a Sensor market through the market size estimation process, the total market was divided into relevant segments and subsegments. Data triangulation and market breakdown procedures were employed, wherever applicable, to complete the market engineering process and derive statistics for each segment and subsegment. Data was triangulated by evaluating factors and trends from the demand and supply sides, including AI adoption, video analytics capabilities, camera technologies, edge computing, cloud deployment, IoT integration, application requirements, smart-city development, industrial automation, and regional trends. The analysis considered key Video as a Sensor technologies, such as AI-enabled cameras, computer vision, edge-based analytics, cloud-based video platforms, IoT-enabled cameras, and multi-sensor systems, along with applications such as security and surveillance, traffic management, industrial monitoring, retail analytics, smart buildings, and public safety. The market size was also validated using top-down and bottom-up approaches to ensure consistency across the overall market and individual segments.
Market Definition
Video as a sensor refers to using cameras, computer vision, and video analytics to detect, identify, track, and measure people, objects, activities, and environmental conditions, converting visual information into actionable data for monitoring, decision-making, control, or automation. Video-as-a-sensor solutions can incorporate AI-enabled cameras, edge-based video analytics, cloud-based platforms, IoT connectivity, and multi-sensor systems, supporting real-time and historical analysis across diverse applications.
Video as a sensor solutions play a crucial role across commercial facilities, manufacturing and industrial automation, transportation, smart cities, retail, critical infrastructure, healthcare, and public safety. These solutions enable intelligent surveillance, object detection and classification, people and vehicle counting, traffic monitoring, occupancy analysis, behavioral detection, process monitoring, and automated response. Video sensors are commonly integrated into security systems, access control, traffic management systems, industrial equipment, smart building platforms, retail analytics, and city infrastructure. A typical Video as a Sensor system may consist of a camera or imaging device, an image sensor, a processing/AI engine, video analytics software, a connectivity interface, and an associated management or control platform. Its configuration varies according to the sensing technology, analytics requirements, application, and operating environment.
Key Stakeholders
- Raw material vendors
- Component providers
- Video as a sensor software developers
- Video surveillance as a service (VSaaS) provider s
- Video surveillance cameras and other hardware manufacturers
- Original equipment manufacturers (OEMs)
- Video as a sensor system integrators
- Video surveillance service providers
- Technology standards organizations, forums, alliances, and associations
- Governments, financial institutions, and investment communities
- Research organizations
- Analysts and strategic business planners
- Venture capitalists, private equity firms, and startups
- Distributors
- Commercial, government, industrial, and residential end users
Report Objectives
- To define, describe, segment, and forecast the size of the video as a sensor market, by offering, product type, application, and end user, in terms of value
- To describe and forecast the market size for camera type in terms of volume
- To forecast the market size for various segments with respect to four main regions—North America, Europe, Asia Pacific, and the Rest of the World (RoW) in terms of value
- To provide detailed information regarding drivers, restraints, opportunities, and challenges influencing the growth of video as a sensor market
- To study the complete value chain analysis of the video as a sensor market landscape
- To strategically analyze macro and micromarkets with respect to growth trends, prospects, and their contributions to the overall market
- To provide a detailed overview of the ecosystem analysis, case study analysis, patent analysis, trade analysis, technology analysis, average selling price (ASP) analysis, AI impact analysis, Porter’s Five Forces analysis, macroeconomic outlook, and regulations pertaining to the market
- To analyze opportunities in the market for stakeholders and provide a detailed competitive landscape
- To strategically profile key players in the market and comprehensively analyze their market share/ranking and core competencies
- To analyze competitive developments by players in the video as a sensor market, such as contracts, product launches/developments, expansions, and research and development (R&D) activities.
Available customizations:
Based on the provided market data, MarketsandMarkets offers customizations to meet the company’s specific needs. The following customization options are available for the report:
Company Information:
- Detailed analysis and profiling of additional market players (up to 5)
Get the Full Video as a Sensor Market Report
Full forecast, segment splits, and company analysis for all Video as a Sensor Market.
- Canada Video as a Sensor Market
- Mexico Video as a Sensor Market
- US Video as a Sensor Market
- Germany Video as a Sensor Market
- France Video as a Sensor Market
- Italy Video as a Sensor Market
- China Video as a Sensor Market
- India Video as a Sensor Market
- Japan Video as a Sensor Market
- South Korea Video as a Sensor Market
- Rest Of Europe Video as a Sensor Market
- Rest Of Asia Pacific Video as a Sensor Market
- Africa Video as a Sensor Market
- Middle East Video as a Sensor Market
- South America Video as a Sensor Market
- GCC Countries Video as a Sensor Market
- Rest Of Middle East Video as a Sensor Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
