Healthcare Supply Chain Management Market

Healthcare Supply Chain Management Market by Offering (Suite, Analytics, RFID), Function (Procurement, Sourcing, Order Management, Warehouse, Transportation), Managed (Vaccines, CGT), End User (Medical Devices, Pharma), and Region - Global Forecast to 2031


HEALTHCARE SUPPLY CHAIN MANAGEMENT MARKET SIZE, SHARE & GROWTH SNAPSHOT
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
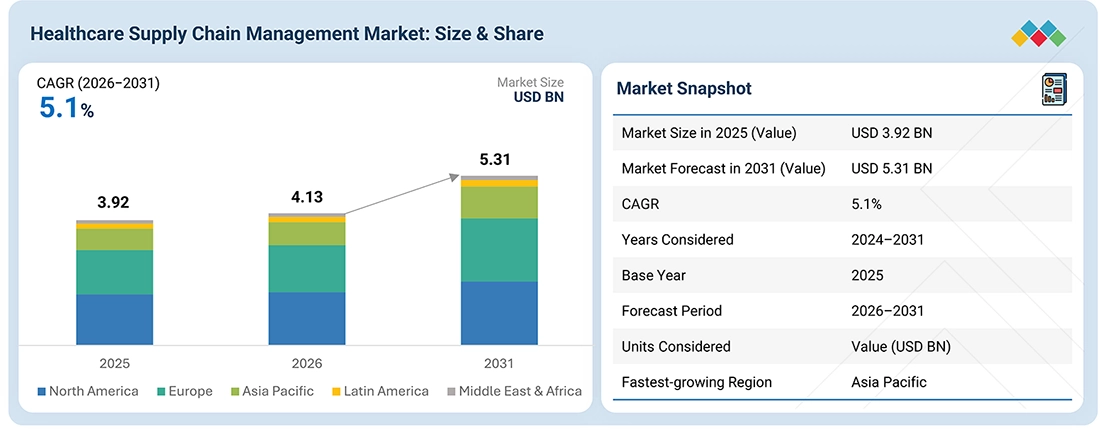
The global healthcare supply chain management market is projected to grow from USD 4.13 billion in 2026 to USD 5.31 billion by 2031, at a CAGR of 5.1% during the forecast period. The market was valued at USD 3.92 billion in 2025. The market is driven by growing pressure on healthcare organizations to improve operational efficiency, reduce supply chain costs, and ensure adequate availability of medical products and supplies. Healthcare organizations, manufacturers, distributors and other participants are adopting supply chain management solutions to enable efficient procurement, optimize inventory and improve demand forecasting and logistics operations. Increased demand for real-time supply chain visibility, product tracking, supplier collaboration and disruption management are other factors boosting market growth. Furthermore, the adoption of cloud computing solutions, AI-based analytics, automation and integrated supply chain solutions has enabled organizations to move from fragmented, manual operations to efficient, intelligent healthcare supply chains.
KEY TAKEAWAYS
-
MARKET SNAPSHOT:
Base Year Market Size (2025): USD 3.92 Billion
Current Market Size (2026): USD 4.13 Billion
Forecast Market Size (2031): USD 5.31 Billion
CAGR (2026–2031): 5.1% -
SEGMENT LEADERSHIP:
Regional Leader: North America dominates the market, with a share of 40.6% of the global healthcare supply chain management market in 2025.
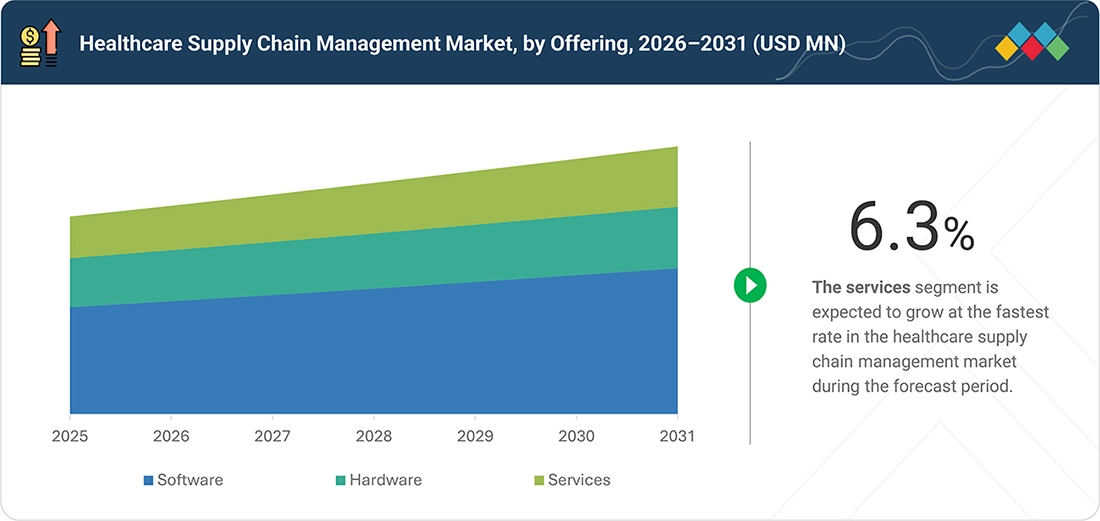
Offering Leader: Services is projected to grow at the highest rate of 6.3% from 2026 to 2031.
Function Leader: Purchasing management held the largest share of the healthcare supply chain management market.
Product Managed Leader: Pharmaceutical & biotechnology is projected to register the highest CAGR of 5.4% from 2026 to 2031.
Deployment Model Leader: On-premises held the largest share in 2025.
End User Leader: Healthcare provider segment is growing at the fastest rate. -
MARKET OUTLOOK & COMPETITIVE LANDSCAPE:
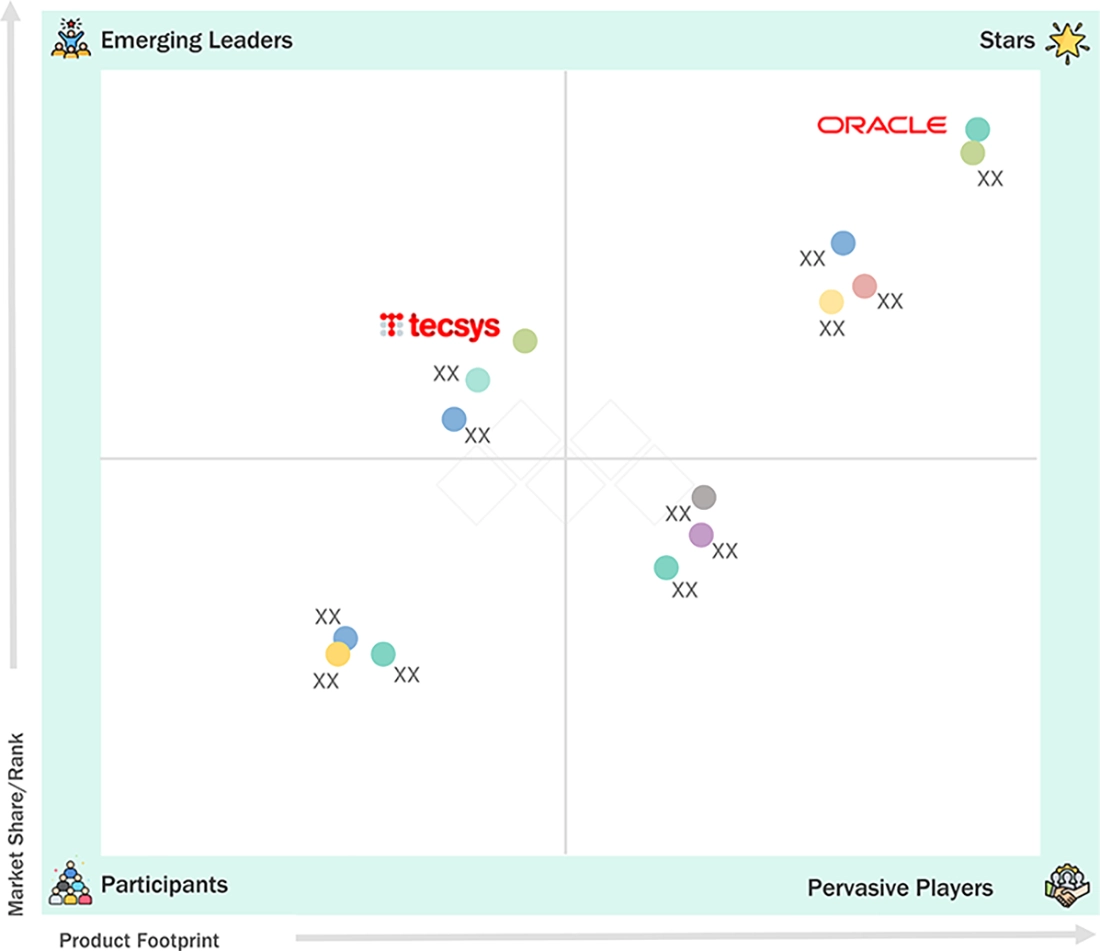
SAP SE, Oracle, IBM, Cardinal Health, and Infor, among others, were identified as some of the star players in the healthcare supply chain management market (global), given their strong market share and product footprint.
Jump Technologies, Inc., Medical Tracking Solutions, Inc., Promedeo, and Procurement Partners, among others, have distinguished themselves among startups and SMEs by securing strong footholds in specialized niche areas, underscoring their potential as emerging market leaders.
The healthcare supply chain management market is fueled by the growing need for effective procurement, inventory management, supply chain visibility and cost reduction. In addition, rising healthcare demand, expanding pharmaceutical and medical device manufacturing, and the adoption of cloud-based supply chain automation are driving market growth.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
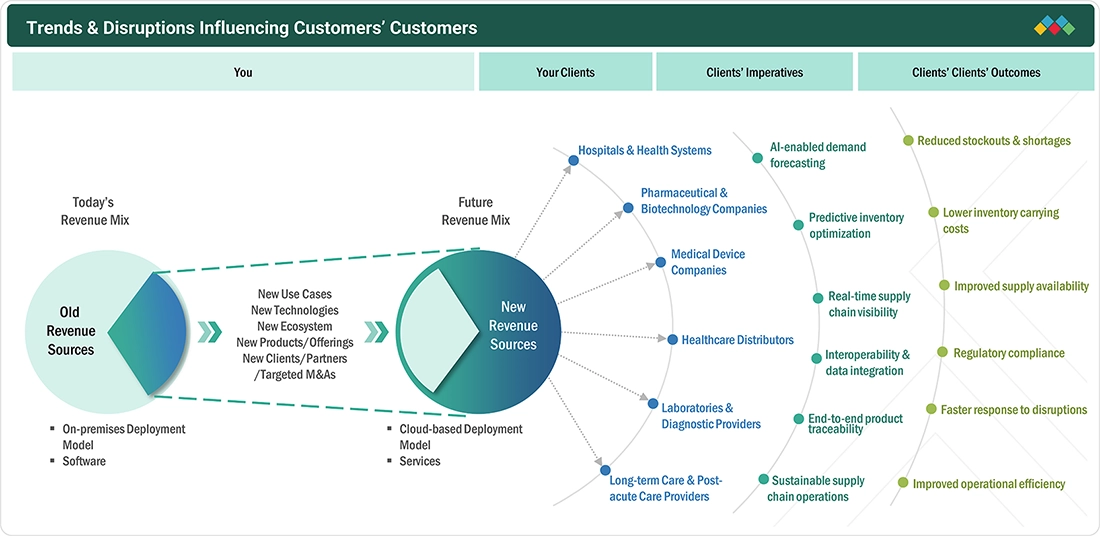
The healthcare supply chain management industry is transforming as organizations integrate advanced cloud computing, artificial intelligence, automation, and real-time supply chain systems. Such systems may assist in addressing challenges arising from the complexities of supply chain systems and improve their procurement processes, inventory management, forecasting, and operations management. Focusing on increased supply chain visibility, resilience, traceability, and cost reduction would enable firms to move away from isolated systems to more integrated, connected systems.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Level
-
Focus on reducing supply chain costs

-
Demand for transparency and traceability


Level
-
High implementation costs for advanced technologies

-
Data security and privacy concerns


Level
-
Increasing use of AI-powered solutions

-
Expansion into emerging markets with growing healthcare demands


Level
-
Complex and varying regulatory requirements across regions

-
Shortage of skilled professionals to manage sophisticated systems

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Focus on reducing supply chain costs
Healthcare institutions, increasingly challenged to control their operational costs, are working to cut costs across procurement, inventory, warehousing, and logistics. Inefficiencies in procurement, inventory waste, stockouts, product waste, and fragmented supply chain management processes tend to raise overall operating costs. Healthcare supply chain management systems help optimize purchasing, maximize inventory use, automate restocking, improve logistics, and identify cost-reduction opportunities. Real-time data and analytics from the supply chain also enable better tracking of expenditures, demand forecasting, and inventory matching.
Restraint: High implementation costs for advanced technologies
Healthcare organizations implement technologies such as AI, cloud computing, automation, and real-time supply chain management. However, the high costs of implementation could hinder adoption, particularly for small-scale organizations. Adopting these technologies requires significant investment in software, hardware, integration, data migration, security measures, and employee training. Organizations would also need to upgrade their systems and integrate their solutions into existing procurement, inventory, and enterprise systems. The costs of these investments and ongoing maintenance could be a significant burden for organizations with limited budgets.
Opportunity: Increasing use of AI-powered solutions
As the complexity of the healthcare supply chain process increases, it is becoming necessary to integrate more applications that use AI, which is helping to improve the processes of planning, decision-making, and operations. With the use of AI technology, it is now possible to analyze supply chain data to forecast demand, optimize inventories, purchasing plans, and risk factors. Moreover, due to advances in the field of artificial intelligence, automation can be achieved for routine procedures and supplier management.
Challenge: Complex and varying regulatory requirements across regions
Healthcare supply chains are managed across different regions, where regulations governing procurement, quality, safety, traceability, data management, and reporting vary. These variations can make it difficult for an organization to achieve uniformity in managing its supply chain processes. This may require modifying the company's processes, documentation, and systems to align with the regulations of specific countries or regions. Managing these changes to systems and processes can also add to the complexities and costs associated with supply chain management.
HEALTHCARE SUPPLY CHAIN MANAGEMENT MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Integrated healthcare and life sciences supply chain and procurement solutions that support supply planning, sourcing, inventory management, supplier collaboration, warehouse management, transportation, and clinical supply management. | Improves supply-chain visibility and inventory utilization, supports efficient procurement and supplier collaboration, reduces inventory waste and expiration risk, and improves planning and distribution of healthcare and clinical supplies. |
 |
Healthcare supply chain solutions supporting procurement, inventory management, pharmacy and perioperative inventory, point-of-use supply management, replenishment, and product recall management. | Improves inventory visibility and availability, helps prevent stockouts and excess inventory, automates replenishment and procurement workflows, improves supply utilization, and supports cost control and operational efficiency. |
 |
Healthcare supply chain solutions support inventory visibility, order orchestration, supplier collaboration, procurement, supply-chain transparency, and disruption management. They provide real-time inventory visibility, order orchestration, and supplier collaboration. | Enhances supply-chain visibility and transparency, improves inventory and order management, strengthens supplier collaboration and resilience, reduces disruption-related risks, and supports more responsive decision-making across the supply chain. |
 |
Integrated healthcare supply chain and inventory solutions supporting medical product distribution, inventory management, product tracking, automated ordering and replenishment, RFID-enabled workflows, and supply chain analytics. | Improves product availability and inventory visibility, reduces stockouts and excess inventory, automates ordering and replenishment, supports product traceability, and enables data-driven optimization of healthcare supply workflows. |
 |
Healthcare-specific supply chain management through support for inventory and item management, contract and procurement management, GPO integration, supply planning, EHR integration, automated replenishment, and product recall workflows. | Improves system-wide supply-chain visibility, reduces stockouts, waste, expirations, and carrying costs, streamlines procurement and contract management, improves procedure-level supply planning, and supports faster recall execution and greater supply-chain resilience. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
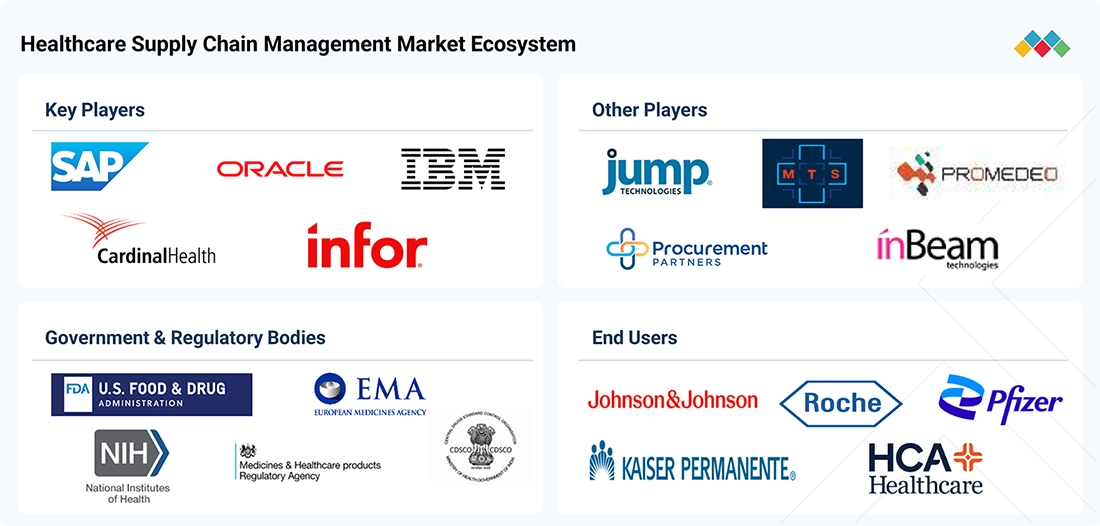
The healthcare supply chain management market ecosystem comprises key players (SAP SE, Oracle, IBM, Cardinal Health, Infor) that provide supply chain management, procurement, inventory, and digital supply chain solutions across healthcare organizations. Other players, including Jump Technologies, Inc., Medical Tracking Solutions, Inc., Promedeo, Procurement Partners, and Inbeam Technologies, contribute specialized solutions for healthcare inventory management, procurement, tracking, and supply chain operations. Government and regulatory bodies (US FDA, European Medicines Agency (EMA), Medicines and Healthcare products Regulatory Agency (MHRA), and Central Drugs Standard Control Organisation (CDSCO)) influence healthcare product regulation, supply chain standards, safety, and compliance. The ecosystem also includes end users (Johnson & Johnson, F. Hoffmann-La Roche Ltd, Pfizer Inc, Kaiser Foundation Health Plan, Inc., and HCA Inc) that rely on healthcare supply chain solutions to support procurement, inventory management, distribution, and operational efficiency.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Healthcare Supply Chain Management Market, By Offering
In 2025, the software segment held the largest market share within the healthcare supply chain management market. It is driven by the growing need for organizations to improve procurement, inventory management, supply planning and supply chain visibility. Healthcare providers, manufacturers and distributors are increasingly using supply chain software to automate purchasing, replenishment, optimize inventory levels, forecast demand, manage suppliers and track products across the supply chain. The integration of cloud-based platforms, AI-powered analytics and real-time data capabilities is further enhancing the ability of organizations to make data-driven decisions. As healthcare supply chains become more complex and organizations focus on improving operational efficiency, demand for integrated software solutions is expected to remain strong.
Healthcare Supply Chain Management Market, By Function
In 2025, purchasing management held the largest market share within the healthcare supply chain management market. This share is driven by healthcare organizations' need to streamline procurement processes, control spending and ensure the timely availability of medical products and supplies. Purchasing management solutions enable healthcare organizations to automate procurement processes, manage suppliers and contracts, compare procurement needs, and make procurement decisions. Integrating these solutions with inventory management and enterprise systems helps healthcare organizations procure based on demand and inventory levels.
Healthcare Supply Chain Management Market, By Product Managed
In 2025, the pharmaceutical and biotechnology segment held the largest market share within the healthcare supply chain management market. This segment is propelled by the need to manage complex product flows, ensure product quality, and maintain the availability of medicines. Healthcare supply chain management solutions assist pharmaceutical and biotechnology companies with demand forecasting, procurement, inventory management, warehousing, distribution, and product tracking. Increased complexity in pharmaceutical supply chains, the need for temperature-controlled logistics, product traceability, regulatory requirements, and inventory management further add fuel to the fire. Moreover, increased production and transparency in the supply chain network would continue to drive demand in this segment.
Healthcare Supply Chain Management Market, By Deployment Model
In 2025, the on-premises deployment model held the largest market share within the healthcare supply chain management market. This is because many healthcare institutions prefer greater control over their supply chain data, systems, and infrastructure. On-premises solutions allow organizations to carry out procurement, inventory, and supply chain processes using their own IT infrastructure, providing more control over data access, cybersecurity, and system configuration. Such a solution can also be integrated with the institution's existing enterprise, procurement, inventory, and hospital management systems. The need to comply with the organization's security policies and to meet regulatory requirements, especially when handling healthcare and supply chain data, makes on-premises solutions even more relevant.
Healthcare Supply Chain Management Market, By End User
In 2025, the manufacturers segment held the largest market share within the healthcare supply chain management market. The need for supply chain management solutions arises from the requirement to manage the processes associated with procurement, production, inventory, warehousing and logistics. Manufacturers in the pharmaceutical, biotech and medical devices industry rely on supply chain management solutions in forecasting demand, managing inventories, suppliers and managing movements of goods/materials through different stages of the supply chain. The solutions of supply chain management are utilized to improve the visibility of material availability, manufacturing needs, and logistics processes to ensure that manufacturers do not experience any delay or surplus inventories in the supply chain.
REGION
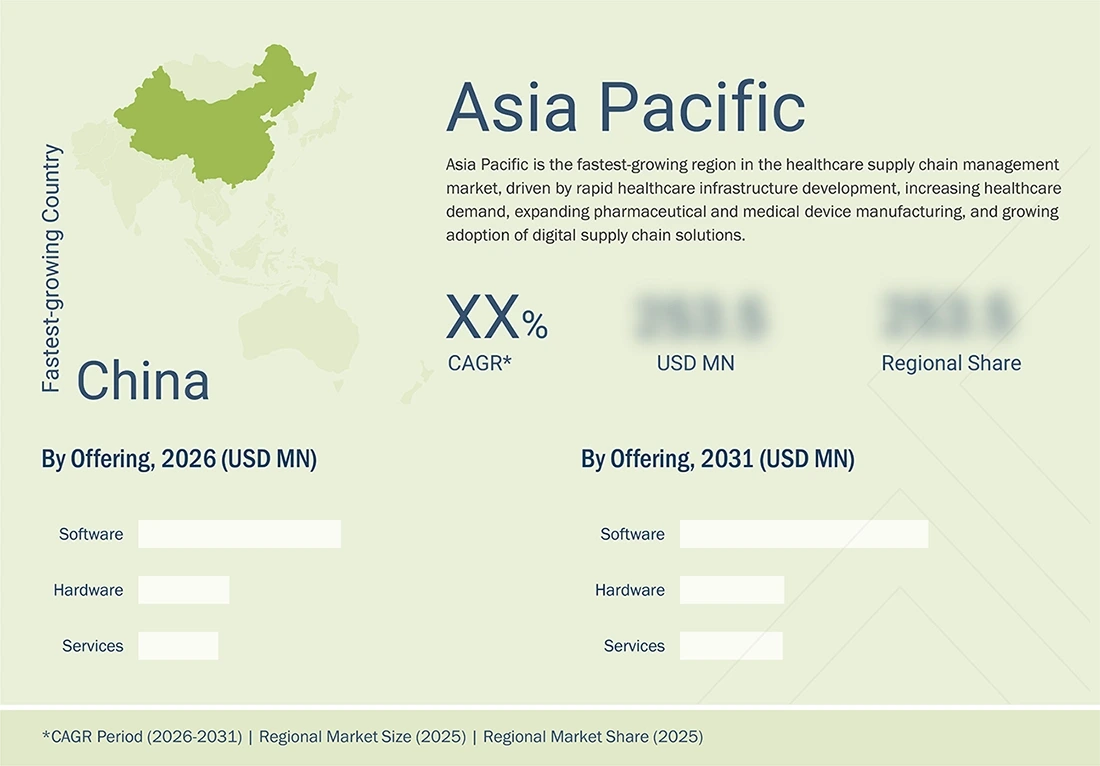
Asia Pacific to be the fastest-growing region in the healthcare supply chain management market during the forecast period
The Asia Pacific region is set to be the fastest-growing region in the healthcare supply chain management market over the forecast period. Growing demand for healthcare, developing healthcare infrastructure and increasing investments in pharmaceutical and medical device manufacturing across the region have contributed to this growth. The adoption of cloud-based platforms, artificial intelligence-driven analytics, automation, and digital procurement platforms has been aiding healthcare organizations in better managing inventory and optimizing their supply chain. The growing requirement for real-time monitoring, traceability, demand forecasting, and resilient supply chains has also contributed to the adoption of digital technologies. Moreover, healthcare digitalization efforts led by governments and the upgrading of healthcare and pharmaceutical supply chains in countries like China, India, and Japan have also been driving the adoption of healthcare supply chain management solutions in the region.
HEALTHCARE SUPPLY CHAIN MANAGEMENT MARKET: COMPANY EVALUATION MATRIX
In the healthcare supply chain management market matrix, Oracle (Star) maintains a strong market position. Its broad supply chain portfolio, established healthcare customer base, and global presence support this position, along with strong supply chain execution capabilities. Its healthcare solutions provide real-time visibility and help organizations improve supply availability, automate workflows, and control costs. Tecsys (Emerging Leader) is gaining momentum through its strong focus on healthcare-specific supply chain management. Its solutions support inventory management, demand planning, supplier collaboration, procurement, warehouse management, point-of-use tracking, and product traceability, with increasing integration of AI-driven intelligence. Its expanding capabilities across hospitals, pharmacies, medical distribution, and life sciences further strengthen its position in the healthcare supply chain management market.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- SAP SE (Germany)
- Oracle (US)
- IBM (US)
- Cardinal Health (US)
- Infor (US)
- Manhattan Associates (US)
- Tecsys (Canada)
- McKesson (US)
- Medline (US)
- Global Healthcare Exchange, LLC. (US)
- Epicor Software Corporation (US)
- Corcentric, Inc. (US)
- Coupa (US)
- Blue Yonder Group, Inc. (US)
- Logitag Systems (US)
- Workday, Inc. (US)
- Arvato Systems (Germany)
- Cencora, Inc. (US)
- GEP (US)
- Vizient, Inc. (US)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2025 (Value) | USD 3.92 BN |
| Market Size in 2026 (Value) | USD 4.13 BN |
| Market Forecast in 2031 (value) | USD 5.31 BN |
| Growth Rate | 5.10% |
| Years Considered | 2024-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Billion) |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered |
|
| Regions Covered | North America, Asia Pacific, Europe, Latin America, Middle East & Africa |
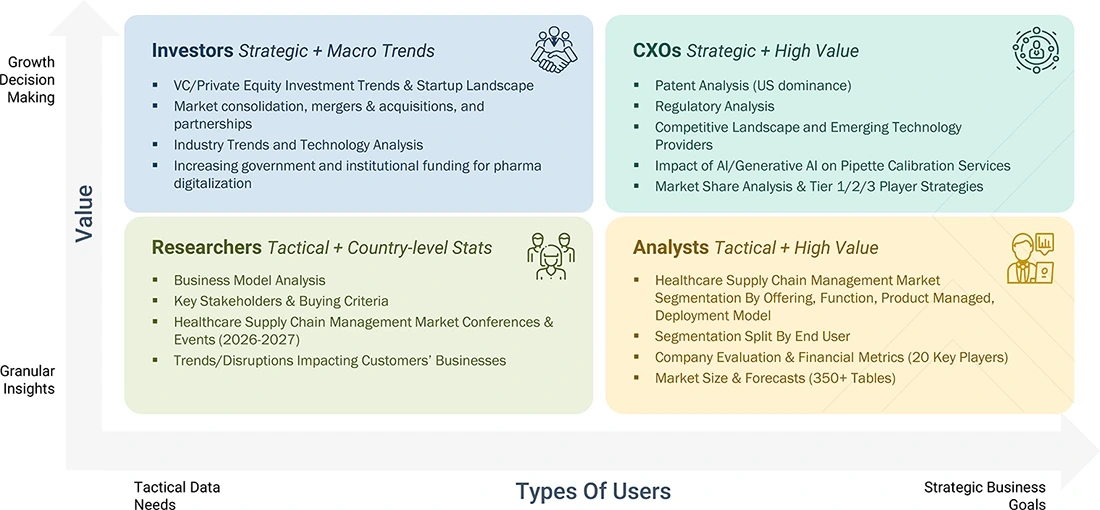
WHAT IS IN IT FOR YOU: HEALTHCARE SUPPLY CHAIN MANAGEMENT MARKET REPORT CONTENT GUIDE
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Local Competitive Landscape | Profiling of leading healthcare supply chain management companies based on product portfolio, technology capabilities, market presence, partnerships, and supply chain solutions. | Enables competitive benchmarking, vendor evaluation, and differentiation strategies. |
| Regional Market Entry Strategy | Assessment of regional adoption, healthcare infrastructure, digitalization, regulatory environment, and market maturity across key geographies. | Supports localization, reduces entry risk, and identifies high-growth markets. |
| Local Risk & Opportunity Assessment | Analysis of supply chain disruptions, regulatory requirements, technology adoption, implementation barriers, and growth opportunities. | Strengthens risk mitigation and supports investment decisions. |
| Technology Adoption by Region | Mapping adoption of AI-enabled supply chain solutions, cloud platforms, predictive analytics, inventory optimization, automation, and real-time supply chain visibility across end users. | Identifies technology trends and supports product development and market expansion. |
RECENT DEVELOPMENTS
- June 2026 : Tecsys introduced new AI and agentic capabilities through TecsysIQ to address healthcare supply chain challenges, including drug shortages, inventory waste, compliance risk, and point-of-care documentation. New capabilities include inventory visibility, image capture, and AI agents for warehouse execution, 340B compliance, and managing inventory expiry.
- June 2026 : Oracle announced new Fusion Agentic Applications and inventory optimization capabilities within Oracle Fusion Cloud Supply Chain & Manufacturing. The AI-powered capabilities are designed to improve inventory visibility, address supplier and operational risks, and support supply chain execution across areas including logistics, sourcing, warehouse operations, and inventory management.
- May 2026 : Medline officially launched Mpower, an AI-powered digital control tower for healthcare supply chains. Developed with Microsoft, the cloud-based platform combines supply and demand data, predictive analytics, real-time visibility, and workflow automation to help healthcare providers identify supply risks, evaluate product substitutions, and respond to potential disruptions.
- May 2026 : Global Healthcare Exchange, LLC launched a new AI-powered orchestration layer that connects data, intelligence, and workflow automation across healthcare providers and suppliers. The platform is intended to help organizations identify disruptions earlier, coordinate decisions, and improve supply chain resilience through capabilities including industry data alignment and bill-only automation.
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
Methodology
The study involved several key activities to estimate the current size of the healthcare supply chain management market. Extensive secondary research was conducted to gather information on this market. The next step was to validate the findings, assumptions, and size estimates by consulting industry experts throughout the value chain through primary research. We employed various methods, including top-down and bottom-up approaches, to estimate the overall market size. Following this, we utilized market segmentation and data triangulation techniques to determine the size of specific segments and subsegments within the healthcare supply chain management market.
Secondary Research
This research study relied heavily on secondary sources, including directories and databases such as Dun & Bradstreet, Bloomberg Businessweek, and Factiva; white papers, annual reports, and companies’ house documents; investor presentations; and companies' SEC filings. Secondary research was used to identify and collect information useful for an extensive, technical, market-oriented, and commercial study of the healthcare supply chain management market. It was also used to obtain key information on the key players and market classification & segmentation, aligned with industry trends to the most granular level, and key developments from market and technology perspectives. A database of the key industry leaders was also prepared using secondary research.
Some of the key secondary sources referred to for this study include:
- US Food and Drug Administration (FDA)
- US Department of Health and Human Services (HHS)
- US Centers for Medicare & Medicaid Services (CMS)
- European Medicines Agency (EMA)
- World Health Organization (WHO)
- Organisation for Economic Co-operation and Development (OECD)
- Healthcare Supply Chain Association (HSCA)
- Association for Health Care Resource & Materials Management (AHRMM)
- US Securities and Exchange Commission (SEC)
- Investor Presentations, SEC Filings, and Company Annual Reports
- White Papers, Industry Reports, Trade Publications, and News Articles
- Paid Databases, such as Factiva, D&B Hoovers, and Bloomberg
Primary Research
In the primary research process, various sources from both the supply and demand sides were interviewed to obtain qualitative and quantitative information for this report. Primary sources mainly include industry experts from core and related industries, as well as preferred suppliers, manufacturers, distributors, technology developers, researchers, and organizations across all segments of this industry’s value chain. In-depth interviews were conducted with various primary respondents, including key industry participants, subject-matter experts (SMEs), executives of key market players, and industry consultants, among others, to obtain and verify critical qualitative and quantitative information and assess prospects.
Primary research was conducted to identify segmentation types, industry trends, key players, and key market dynamics such as drivers, restraints, opportunities, challenges, and strategies adopted by key players.
Breakdown of Primary Respondents:
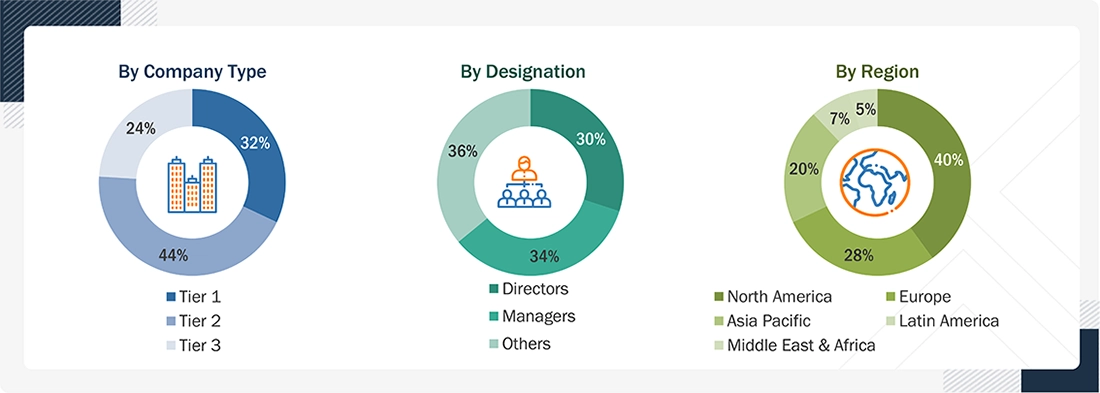
Note: Tiers are defined based on a company’s total revenue, as of 2025: Tier 1 = >USD 1 billion, Tier 2 = USD 500 million to USD 1 billion, and Tier 3 = <USD 500 million.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
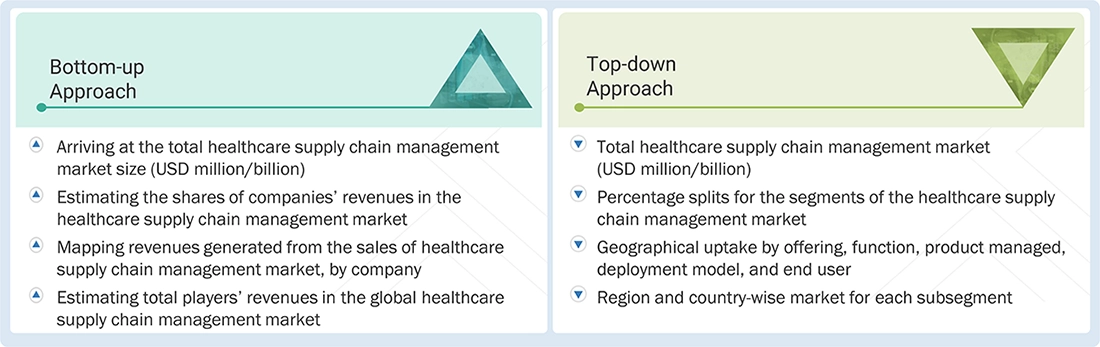
The market size estimates and forecasts in this study are derived through a mix of the bottom-up approach (revenue share analysis of leading players) and the top-down approach (assessment of utilization/adoption/penetration trends by offering, function, product managed, deployment model, end user, and region).
Healthcare Supply Chain Management Market : Top-Down and Bottom-Up Approach
Data Triangulation
After arriving at the overall market size using the market size estimation processes, the market was split into several segments and subsegments. To complete the overall market engineering process and arrive at the exact statistics of each market segment and sub-segment, the data triangulation and market breakdown procedures were employed, wherever applicabe. The data was triangulated by examining factors and trends from both the demand and supply sides of the healthcare supply chain management market.
Market Definition
Healthcare supply chain management encompasses the processes, technologies, and services used to procure, manage, track, and distribute medical products, supplies, and related resources across healthcare organizations. It includes activities such as purchasing, inventory management, supplier management, demand planning, warehousing, and logistics, aiming to improve supply chain visibility and operational efficiency, ensure product availability and traceability, and reduce costs while maintaining quality and compliance.
Key Stakeholders
- Healthcare IT service providers
- Healthcare institutions/providers (hospitals, clinics, ambulatory surgical centers, pharmacies, physicians, nursing homes, integrated delivery networks)
- Healthcare medical device manufacturers
- Healthcare ERP solution providers
- Venture capitalists
- Pharmaceutical & Biotechnology companies
- Medical device companies
- Private equity funds
- Investors
- Investment banks
- Government bodies/Municipal corporations
- Corporate entities
- Research and consulting firms
Report Objectives
- To define, describe, and forecast the global healthcare supply chain management market based on offering, function, products managed, deployment model, end user, and region.
- To provide detailed information regarding the major factors influencing the growth of the market (drivers, restraints, opportunities, and challenges)
- To strategically analyze micro markets with respect to individual growth trends, prospects, and contributions to the overall market
- To analyze the opportunities in the market for stakeholders and provide details of the competitive landscape for market leaders
- To forecast the size of the market segments with respect to five main regions, namely, North America, Europe, Asia, Latin America, and the Middle East & Africa
- To profile key market players and comprehensively analyze their product portfolios, market positions, and core competencies
- To track and analyze competitive developments such as acquisitions; product launches and upgrades; expansions; agreements, partnerships, and acquisitions; and R&D activities in the healthcare supply chain management market
Available customizations:
With the provided market data, MarketsandMarkets offers customizations to meet your company’s specific needs. The following customization options are available for the report:
Company Information
- Detailed analysis and profiling of additional market players (up to 5)
Geographic Analysis
- Further breakdown of the Rest of Asian healthcare supply chain management market into Vietnam, New Zealand, and others
Key Questions Addressed by the Report
- Software
- Hardware
- Services
- Manufacturers
- Distributors
- Providers


Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the Healthcare Supply Chain Management Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Custom Market Research Services
We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements
Get 10% Free CustomisationTESTIMONIALS
JAYANT RAJPUROHIT
Director of Market Insights, Data and Analytics
SFI Health,
Leading Pharmaceutical Companywww.sfihealth.com/
We at SFI Health approached MarketsandMarkets for an Opportunity Assessment on "Incidence and Prevalence of Focus Indications" as we wanted to know the most attractive HCPs like Physician, Functional MD, Naturopath and Pharmacist. The project was critical for us to ensure our focus on the right target which would enable sustainable growth and profitability for SFI Health. The business insights provided exceeded our expectations and we were extremely impressed. The team at MarketsandMarkets is highly professional and detail oriented and very well understood our business needs. MarketsandMarkets offers a unique combination of expertise and dedicated engagement model. We identified 2 new products to be launched in coming months, based on the research findings provided by MarketsandMarkets. We are happy with the services and would strongly recommend MarketsandMarkets to my peers in the industry.
BEATRIZ DE LA CALLE
Head of Commercial Analytics
Qualicaps,
Leading Pharmaceutical Companywww.qualicaps.com/
We partnered with MarketsandMarkets for an assessment study on hard empty capsules. The team was extremely professional in understanding our business requirements and we received timely responses to all our queries. The market intelligence and the recommendations has met our business requirements. We were extremely impressed to see the final study results; it really exceeded our expectations. The market intelligence offered by MarketsandMarkets, and clarity on next steps will help us achieve our business objective for the Year 2021. We are happy with the services and would strongly recommend MarketsandMarkets to my peers in the industry.

Bob Williams,
Senior Director Business Development & Innovation
Bracco Diagnostics Inc.,
Italian Multinational in life sciences sector and a World Leader in imaging diagnosticsimaging.bracco.com/us-en
We were pleased with targeted insights that MarketsandMarkets identified from a custom study on the 'Radiation Dose Management Solutions Market'. Your team identified and characterized the market participants as well as underlying trends accurately. This study was useful to Bracco in formulating business strategies for our dose monitoring product lines and we thank MarketsandMarkets for the job well done.
Cody Coonradt,
Market Development and Strategy Manager
3M Health Information Systems,
Leader in Health care Coding, Payment & Analytics Solutions.www.3m.com/3M/en_US/health-information-systems-us
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarketsandMarkets, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer.
Their customer first approach and high value engagement model, have given us great analysis and excellent value for money





Growth opportunities and latent adjacency in Healthcare Supply Chain Management Market