Automotive Transmission Market

Automotive Transmission Market by Transmission Type (MT, AT, CVT, DCT, AMT), EV Transmission (Single-speed and Multi-speed), Integration Level of EV Transmission, Motor Configuration (1-Motor, 2-Motor and 3-Motor), Fuel Type, Vehicle Type, Forward Gears, and Region - Global Forecast to 2033




OVERVIEW
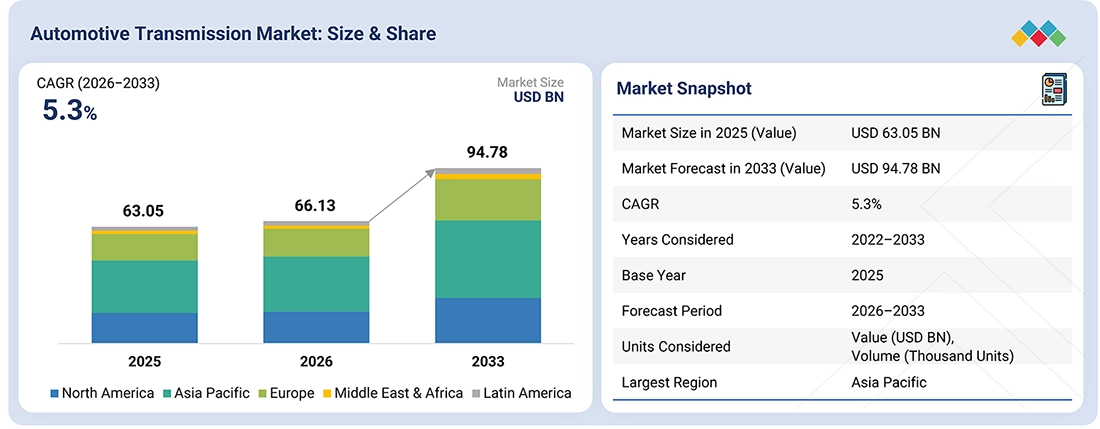
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
The automotive transmission market is estimated to grow from USD 66.13 billion in 2026 to USD 94.78 billion by 2033 at a CAGR of 5.3%. The automotive transmission market is evolving through the adoption of advanced automatic transmissions, 8–10-speed gearboxes, dual-clutch transmissions (DCTs), continuously variable transmissions (CVTs), and dedicated hybrid transmissions (DHTs) that optimize torque delivery, fuel efficiency, and powertrain performance. The growing penetration of hybrid electric vehicles is accelerating demand for e-CVTs and integrated motor-transmission architectures, while software-based shift control and low-friction gear designs improve drivetrain efficiency. Asia Pacific, led by China, remains a strategic hub for transmission manufacturing and electrified powertrain development, while Europe and North America continue to invest in hybrid-ready automatics and high-torque transmissions for SUVs and commercial vehicles. In India, rising automatic-transmission adoption is driving localization and capacity investments by suppliers such as AISIN. However, transmission manufacturers must manage parallel investments in ICE, hybrid, and electric drivetrains while controlling system costs, engineering complexity, and returns on technology investments.
KEY TAKEAWAYS
-
AUTOMOTIVE TRANSMISSION MARKET, BY REGIONAsia Pacific leads the regional automotive transmission market, accounting for >45% share in the global transmission market in 2026 due to high vehicle production, broad ICE and hybrid powertrain demand, and localized transmission manufacturing.
-
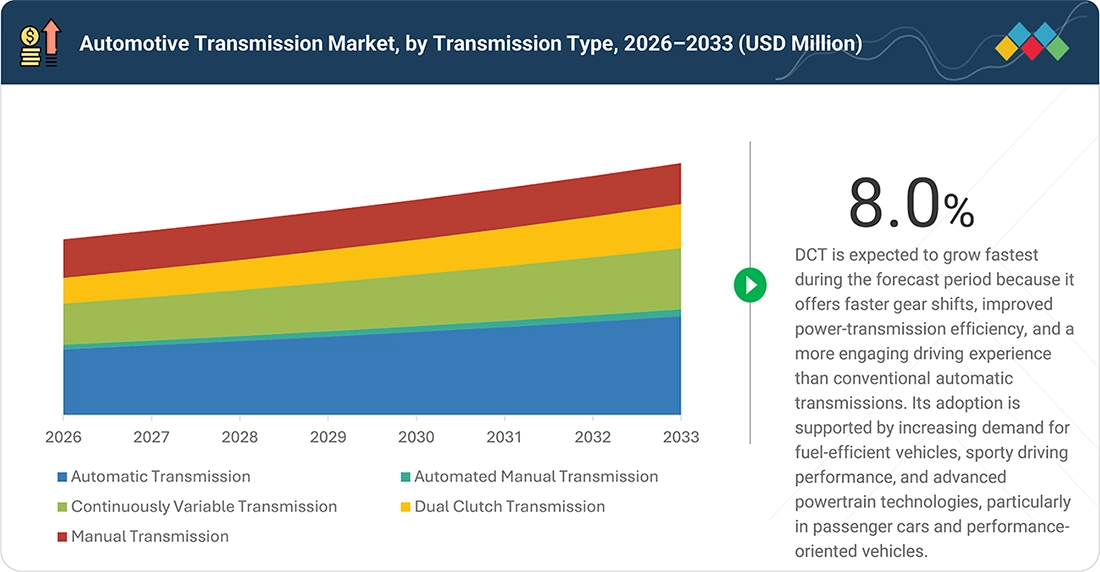
BY TRANSMISSION TYPEDCT is expected to register the highest CAGR of 8.0% in terms of value in the automotive transmission market due to rapid gear shifts, reduced shift interruption, and efficient power transfer in compact vehicles.
-
BY VEHICLE TYPEThe passenger car segment is expected to dominate the market due to high production volumes and widespread use of ATs, CVTs, DCTs and hybrid transmissions.
-
BY FUEL TYPEThe gasoline segment is projected to hold a larger market share due to its large installed vehicle base and continued production of gasoline-powered passenger cars.
-
BY FORWARD GEARSThe 6 to 8 forward gears segment is expected to dominate the automotive transmission market due to balance acceleration, cruising efficiency, engine operating range and transmission complexity.
-
EV TRANSMISSION, BY TRANSMISSION TYPEMulti-speed transmission is expected to grow at the fastest rate in the EV transmission market during the forecast period.
-
COMPETITIVE LANDSCAPEMajor market players have adopted both organic and inorganic strategies, including partnerships and investments. Key players include AISIN Corporation (Japan), ZF Friedrichshafen AG (Germany), Magna International Inc. (Canada), Hyundai Transys (South Korea), and BorgWarner Inc. (USA).
In the automotive transmission market, product innovation increasingly focuses on improving power-transfer efficiency, reducing energy losses, and integrating mechanical components with electronic controls without compromising durability, performance, or cost efficiency. The market is witnessing greater adoption of electronically controlled shifting, advanced transmission control units, optimized gear ratios, and integrated motor, inverter, and gearbox systems. For hybrid and plug-in hybrid vehicles, dedicated hybrid transmissions and power split architectures are being developed to coordinate engine and electric motor operation across varying driving conditions, improving energy utilization and drivability. In battery electric vehicles, innovation is centered on compact reduction gearboxes, integrated electric drive units, and e-axles that combine transmission, electric motor, and power electronics to reduce packaging requirements and improve drivetrain efficiency. At the same time, manufacturers are developing higher torque density gear systems, advanced lubrication technologies, and software-enabled transmission controls to support higher power outputs, quieter operation, and improved vehicle responsiveness. The growing adoption of electrified powertrains and software-controlled vehicle architectures is shifting automotive transmission development from standalone mechanical gear systems toward integrated, electronically managed power delivery solutions.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
The automotive transmission market is undergoing a shift as OEMs move from conventional gearbox designs toward powertrain-specific architectures that improve efficiency, performance, and energy management. The growth of hybrid and electric vehicles is driving demand for dedicated hybrid transmissions, integrated electric drive units, and e-axles, while software-controlled shifting and advanced transmission control systems are improving torque delivery and driving performance. At the same time, demand for compact designs, higher torque density, and reduced mechanical losses is accelerating the integration of gearboxes with electric motors and power electronics. These trends are reshaping supplier strategies, encouraging transmission manufacturers to expand beyond standalone gear systems and develop integrated drivetrain solutions tailored to ICE, hybrid, and electric vehicle platforms.
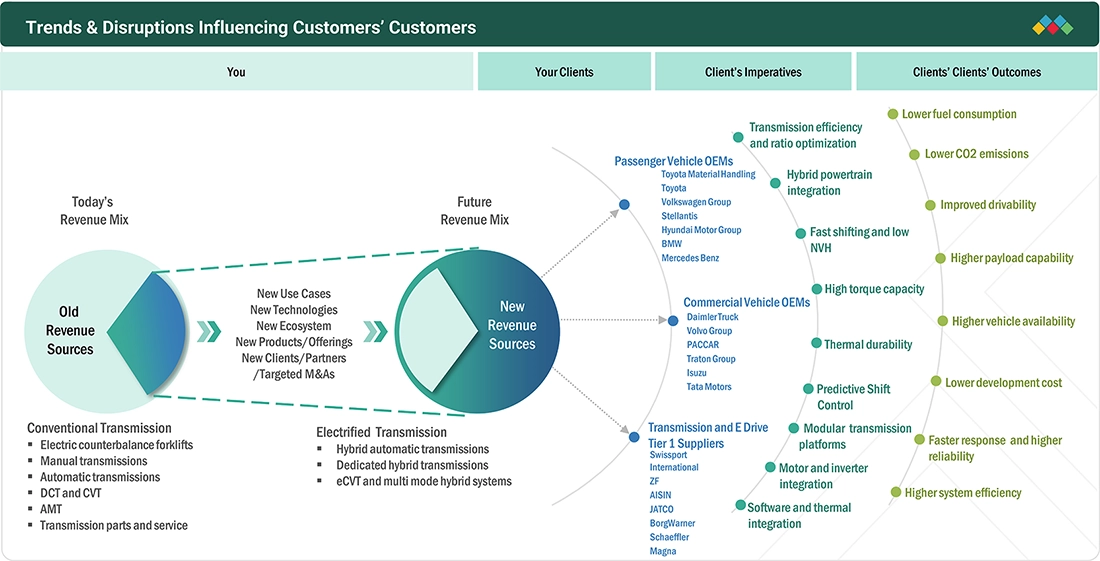
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Level
-
Hybridization transforming transmission from mechanical gearbox into integrated electrified powertrain module

-
Rising demand for higher torque density and multi-mode drivability driving advanced transmission architectures and intelligent control


Level
-
High system complexity and development cost of next-generation transmissions


Level
-
Hybrid-specific and modular transmission platforms

-
Integrated e-Drive/e-Transmission systems for BEV and next-generation hybrid vehicles


Level
-
Electrification of mechanical auxiliaries expanding across ICE, 48V and EV platforms

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Hybridization transforming transmission from mechanical gearbox into integrated electrified powertrain module
Growing adoption of electrified mechanical transmissions is driven by the expansion of hybrid vehicles and increasing demand for higher electric torque, improved energy efficiency, and flexible transmission architectures. Transmission suppliers are integrating electric motors, disconnect clutches, power electronics, and electronic controls into established multi-speed gearsets, enabling electric, series, and parallel driving modes while retaining existing transmission platforms. In November 2025, ZF introduced its 8HP evo for 48 V mild hybrid and 400 V full hybrid and plug-in hybrid applications, offering up to 28% lower input shaft losses in its PHEV version. In April 2026, Schaeffler announced volume production of its hybrid transmission, reflecting the shift toward modular e-drive transmission systems that support multiple electrification levels and improve vehicle efficiency.
Restraint: High system complexity and development cost of next-generation transmissions
High system complexity and development costs of next-generation transmissions restrain market growth, as P2, DHT, and hybrid DCT architectures require substantial investment in engineering, software calibration, testing, tooling, and manufacturing. Integrating electric motors, power electronics, clutch systems, thermal management, and electronic controls increases system integration and validation requirements. For example, BorgWarner’s P2 module and ZF’s 8HP hybrid architecture combine multiple mechanical and electronic functions, increasing development costs, particularly for smaller suppliers and low volume vehicle programs. While scalable platforms help larger suppliers distribute costs across multiple vehicle models, high upfront investment remains a barrier to wider adoption.
Opportunity: Hybrid-specific and modular transmission platforms
Growing demand for hybrid-specific and modular transmission platforms creates opportunities for suppliers to develop scalable architectures that support 48 V MHEV, HEV, and PHEV applications. With over 200 hybrid vehicle models globally in 2025, representing more than 10% growth, demand for adaptable transmission solutions is rising across vehicle segments and regions. Platforms such as ZF’s 8HP evo and BorgWarner’s P2 module integrate electric motors, clutches, power electronics, and control systems while supporting multiple transmission configurations. This modular approach enables OEMs and suppliers to reuse components, software, and manufacturing assets across vehicle programs, reducing incremental development costs and accelerating hybrid transmission deployment.
Challenge: Electrification of mechanical auxiliaries expanding across ICE, 48V and EV platforms
Increasing integration complexity from electrified mechanical auxiliaries challenges transmission and powertrain suppliers as electric steering, coolant pumps, compressors, and other auxiliaries expand across 12 V, 48 V, and high-voltage platforms. These systems increase electrical loads and require additional thermal management, wiring, control integration, and software calibration. Suppliers must develop reliable, compatible components that operate across different voltage architectures while meeting performance and functional safety requirements, increasing system integration and validation demands.
AUTOMOTIVE TRANSMISSION MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
In August 2026, AISIN and its partners introduced a two-motor hybrid drive module selected for the new Jeep Cherokee, combining a high-torque transaxle with coordinated motor and boost-converter control. The system manages engine and electric-motor output across hybrid driving conditions. | Improves fuel efficiency and acceleration by coordinating motor output and increasing system voltage. Integrated torque management supports responsive power delivery across hybrid driving modes. The architecture can optimize motor operating points during launch and regenerative braking. |
 |
In June 2025, ZF developed its fourth-generation 8HP eight-speed automatic transmission platform for conventional, mild hybrid, and plug-in hybrid vehicles. Its modular design accommodates different levels of electrification within a shared transmission architecture. | Improves transmission efficiency, supports higher electrical performance, and enables automakers to adapt existing vehicle platforms for hybridization while reducing the need for major powertrain redesigns. |
 |
In July 2026, Magna secured an 800 V, 250 kW two-speed eDrive programme with Chery, with production planned at its Wuhu facility in China. The system combines two-speed gearing with a high-voltage electric drive for the vehicle programme. | Combines high power output with two-speed gearing to support acceleration and high-speed efficiency. The additional ratio helps maintain motor efficiency across a wider vehicle-speed range. The 800 V architecture supports high-power operation with lower current for a given power level. |
 |
In 2025, Hyundai Transys advanced its next-generation e²AT hybrid transmission for Hyundai Motor Group hybrid platforms, integrating a P1+P2 motor configuration with a six-speed automatic transmission. The arrangement coordinates engine and motor output within a single hybrid drive system. | Improves fuel efficiency and acceleration compared with the previous hybrid transmission, while integrating key components to reduce packaging requirements and improve power delivery. P1+P2 motor placement enables engine starting, torque assist, and regenerative energy recovery. Coordinated motor control also supports smoother transitions between operating modes. |
 |
In October 2025, BorgWarner secured a programme to supply a 7-in-1 integrated drive module for a Chinese OEM’s hybrid SUV, with production planned for 2026. The module consolidates electric-drive and power-management functions into one assembly. | Reduces packaging requirements and simplifies vehicle integration by consolidating multiple components. The integrated architecture supports scalable hybrid powertrain design and efficient power delivery. Consolidating power electronics and drive components can shorten high-voltage interconnections and simplify thermal-management integration. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
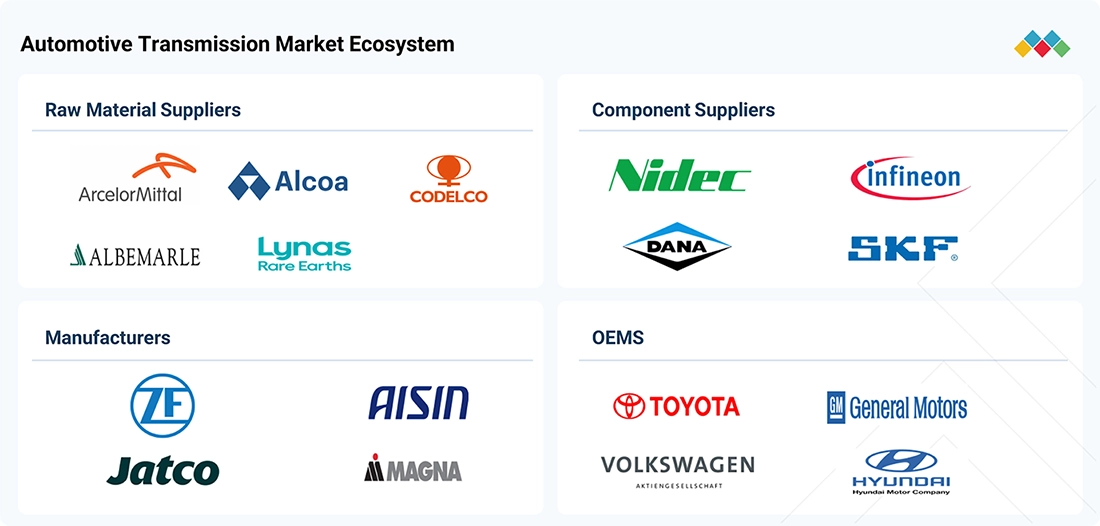
The automotive transmission ecosystem includes raw material suppliers, component suppliers, transmission manufacturers, and vehicle OEMs that work together to develop and integrate efficient power-transmission systems. Raw material suppliers provide steel, aluminum, and specialized alloys, while component suppliers manufacture gears, shafts, bearings, clutches, torque converters, and electronic control units. Transmission manufacturers such as AISIN, ZF, Magna, Hyundai Transys, and BorgWarner integrate these components into manual, automatic, hybrid, and electric transmission systems. OEMs then integrate these systems into vehicle platforms, with growing collaboration across the value chain to develop compact, energy-efficient, and application-specific transmission architectures for ICE, hybrid, and electric vehicles.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
BY TRANSMISSION TYPE
DCT is expected to register the fastest growth by value in the automotive transmission market during the forecast period, driven by demand for faster gear shifts, improved powertrain efficiency, and enhanced driving performance across passenger cars, particularly in performance-oriented and premium vehicles.
BY VEHICLE TYPE
Passenger cars are expected to dominate the automotive transmission market in 2026, driven by their high share of global vehicle production and widespread adoption of manual, automatic, and electrified transmission systems across economy, mid-range, and premium vehicle segments.
BY FUEL TYPE
Gasoline vehicles are projected to hold the largest share of the automotive transmission market in terms of value, driven by their substantial presence in the global vehicle parc and continued demand across passenger cars and light commercial vehicles, particularly in emerging markets.
BY FORWARD GEARS
The 6 to 8 speed transmission segment is expected to dominate the automotive transmission market, as it offers an effective balance of fuel efficiency, smooth gear shifting, driving performance, and manufacturing cost, supporting widespread adoption across passenger cars and commercial vehicles.
EV TRANSMISSION, BY TRANSMISSION TYPE
Multi-speed transmissions are expected to grow at the fastest rate in the EV transmission market during the forecast period, driven by demand for improved high-speed efficiency, extended driving range, and enhanced acceleration in performance-oriented and commercial electric vehicles.
REGION
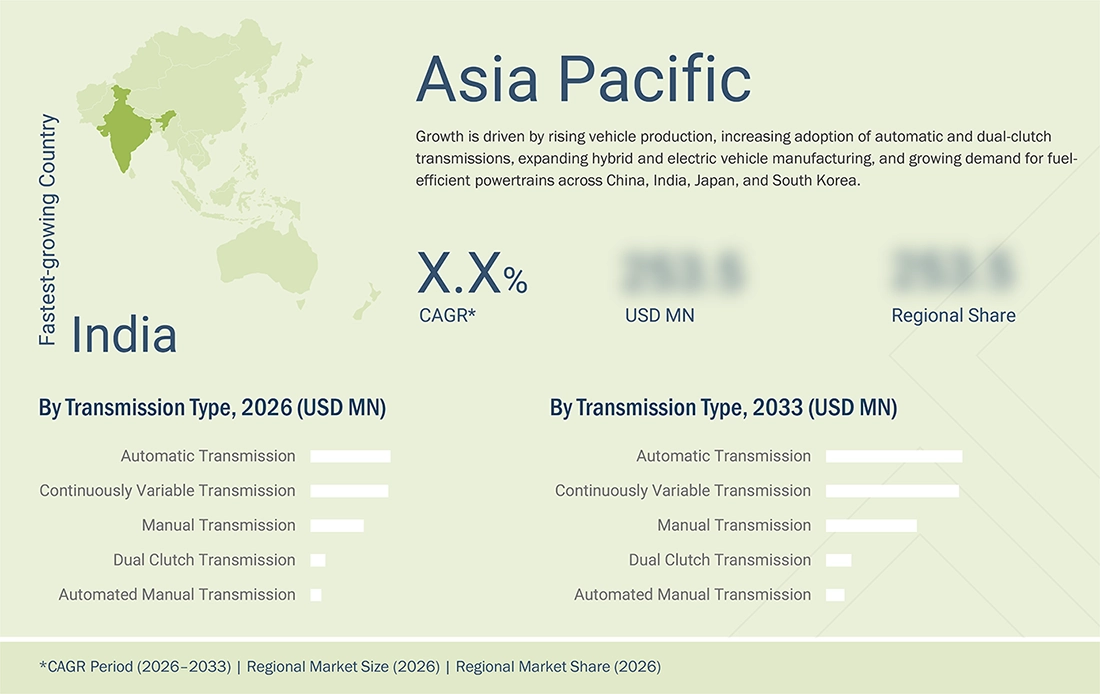
Asia Pacific is the largest region in global automotive transmission market in 2026.
Asia Pacific’s automotive transmission market is supported by high vehicle production, rising adoption of automatic transmissions, and rapid expansion of hybrid and electric vehicle manufacturing. Growing domestic OEM capabilities in China, Japan, South Korea, and India are driving demand for locally developed transmission systems, while increasing adoption of DCTs, dedicated hybrid transmissions, and integrated electric drives is accelerating the shift toward advanced transmission technologies across vehicle segments.
AUTOMOTIVE TRANSMISSION MARKET: COMPANY EVALUATION MATRIX
AISIN Corporation (Star) focuses on a broad portfolio of automatic transmissions, hybrid transmission systems, and drivetrain components, leveraging its manufacturing scale and OEM relationships to strengthen its position as a leading transmission system supplier. Schaeffler AG (Emerging) focuses on transmission components, hybrid modules, electric drive systems, and precision technologies, expanding its presence in electrified powertrains through engineering capabilities and integrated solutions for hybrid and electric vehicles.
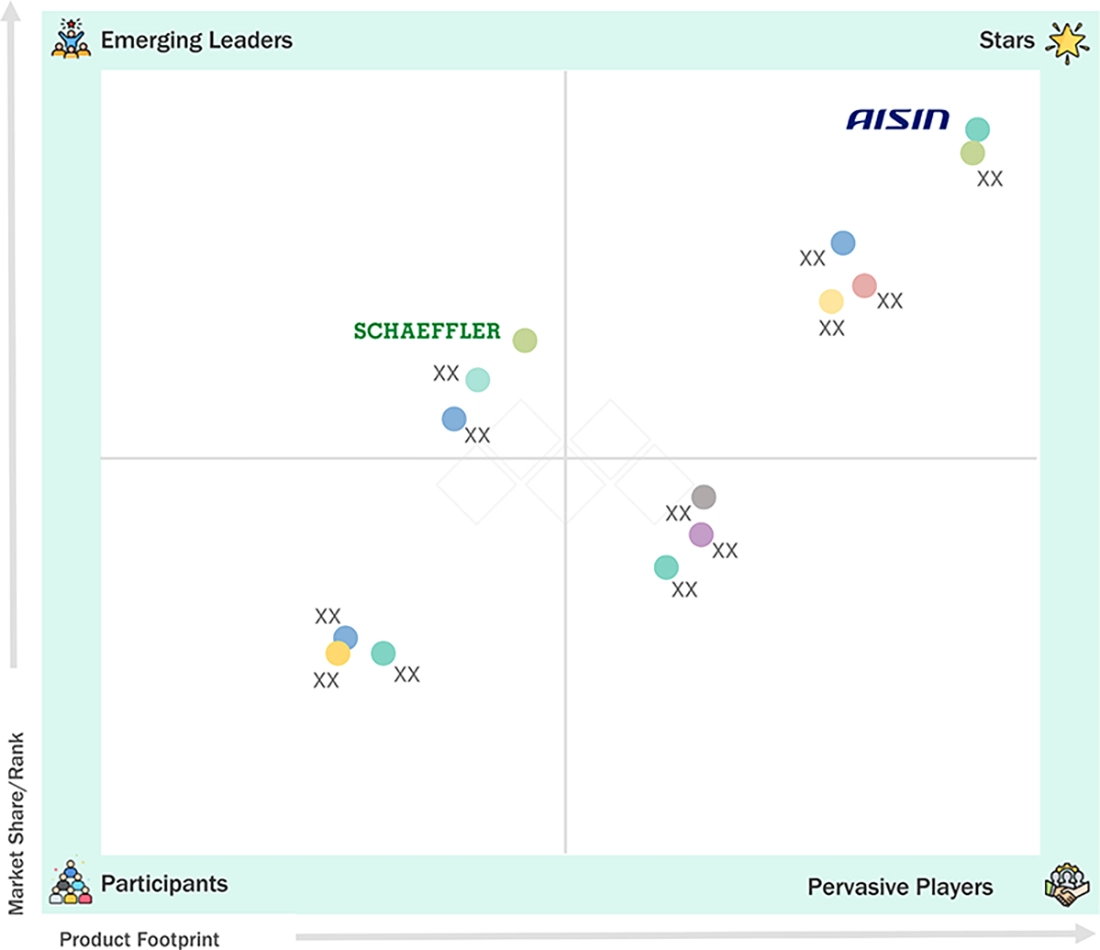
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2026 (Value) | USD 66.13 Billion |
| Market Forecast in 2033 (Value) | USD 94.78 Billion |
| Growth Rate | CAGR of 5.3% from 2026-2033 |
| Years Considered | 2022-2033 |
| Base Year | 2025 |
| Estimate Year | 2026 |
| Forecast Period | 2026-2033 |
| Units Considered | Value (USD Million), Volume (Thousand Units) |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered | By transmission type, fuel type, number of forward gears, vehicle type, EV by transmission type, integration level, and motor configuration |
| Regions Covered | Asia Pacific, Europe, North America, Latin America, and Middle East & Africa |
WHAT IS IN IT FOR YOU: AUTOMOTIVE TRANSMISSION MARKET REPORT CONTENT GUIDE
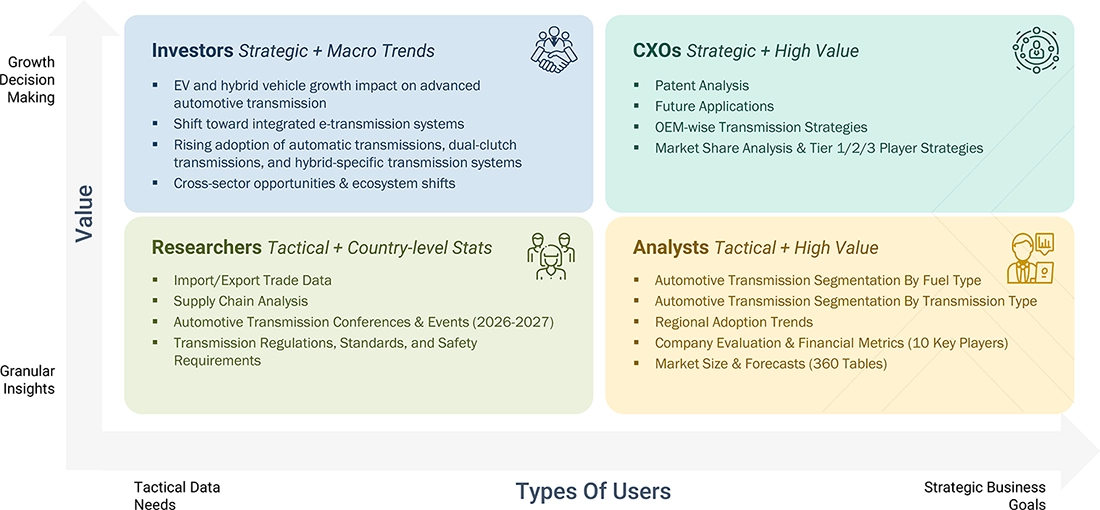
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Benchmark transmission supplier capabilities across ICE, hybrid, and electric vehicle technologies. | Conduct competitive benchmarking of leading transmission suppliers across AT, AMT, CVT, DCT, dedicated hybrid transmissions, and electric drive systems, including technology capabilities, OEM relationships, and vehicle platform adoption | Identifies technology leaders and competitive gaps, helping prioritize transmission technologies with strong OEM adoption potential |
| Assess the impact of EV architectures on transmission design and integration | Evaluate BEV transmission architectures, including single-speed reduction gearboxes, two-speed transmissions, integrated electric drives, and e-axles, considering packaging, efficiency, weight, and performance requirements | Supports technology and architecture decisions by identifying trade-offs between drivetrain efficiency, vehicle range, packaging, and system integration |
| Identify opportunities for advanced transmission technologies across vehicle segments | Assess the adoption of DCTs, advanced automatic transmissions, dedicated hybrid transmissions, and multi-speed EV transmissions across passenger cars, LCVs, trucks, and buses, considering performance requirements and cost implications | Identifies opportunities to expand advanced transmission technologies across vehicle segments and prioritizes applications based on performance, efficiency, and commercial feasibility |
| Evaluate transmission efficiency and lightweighting approaches without compromising durability or performance | Benchmark gear design optimization, lightweight materials, advanced lubrication, friction reduction, and compact transmission architectures across leading suppliers, considering torque capacity, energy losses, and durability | Identifies practical approaches to reduce transmission weight and power losses while maintaining torque delivery, reliability, and operating performance |
| Identify emerging transmission technologies and software enabled powertrain solutions | Assess developments in electronically controlled shifting, transmission control software, integrated motor and gearbox systems, predictive control strategies, and coordinated energy management in hybrid and electric powertrains | Helps align transmission portfolios with evolving OEM requirements and identifies opportunities for differentiation through control software, system integration, and improved powertrain efficiency |
RECENT DEVELOPMENTS
- October 2026 : AISIN, BluE Nexus, and DENSO developed a two-motor hybrid drive module adopted for the new Jeep Cherokee. The system combines a high-efficiency transmission with coordinated motor and power electronics control, while AISIN manufactures the transaxle and motors in North America. Benefit: strengthens AISIN’s hybrid transmission content through localized production and integrated torque management.
- September 2026 : ZF introduced its TraXon 2 automated manual transmission with integrated Intarder on HINO’s new S’elega premium coach in Japan. The transmission combines automated shifting with integrated hydraulic retarding for smooth operation, braking support and improved efficiency in long-distance passenger transport. This extends TraXon 2 from truck applications into the premium coach segment and strengthens ZF’s regional transmission portfolio. Benefit: improves drivability, braking integration and fuel efficiency while reducing the need for separate retarder packaging.
- July 2026 : BorgWarner secured an integrated dual-clutch transmission program in China for motorcycle and four-wheeled vehicle applications above 500 cc. The integrated DCT system expands BorgWarner’s role from clutch technology toward transmission system supply. Benefit: increases drivetrain content and supports faster, smoother torque transfer with improved transmission efficiency.
- July 2026 : Magna is establishing production of its 250 kW 800 V two-speed eDrive system at its new Wuhu facility for Chery. The site strengthens Magna’s localized electric drive manufacturing capability in China and is positioned to support additional Chinese OEM programs. The expansion increases local capacity for high-voltage transmission and eDrive architectures. Benefit: reduces regional supply distance and increases Magna’s ability to scale 800 V electric drive programs for Chinese OEMs.
- April 2026 : AISIN began contract manufacturing Mazda’s six-speed automatic transmission at AISIN Drivetrain in Indiana, United States. The arrangement uses AISIN’s transmission production technology and quality management capabilities to support Mazda’s regional supply requirements. Benefit: improves North American supply responsiveness and reduces logistics exposure through localized transmission production.
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
Methodology
The research study involved extensive use of secondary sources, such as company annual reports/presentations, industry association publications, automotive magazine articles, directories, technical handbooks, the World Economic Outlook, trade websites, technical articles, and databases, to identify and collect information on the automotive transmission market. Primary interviews have been conducted to obtain and verify critical qualitative and quantitative information as well as assess the prospects of the industry. Primary sources include experts from core and related industries, suppliers, manufacturers, distributors, service providers, technology developers, and organizations related to various segments of the automotive transmission market value chain. Detailed interviews have been conducted with various primary respondents, including key industry participants, Subject Matter Experts (SMEs), C-level executives of key market players, and industry consultants.
Secondary Research
Secondary sources referred to for this research study include automotive industry organizations such as the International Organization of Motor Vehicle Manufacturers (OICA), United Nations Economic Commission for Europe (UNECE), European Automobile Manufacturers' Association (ACEA), China Association of Automobile Manufacturers (CAAM), National Highway Traffic Safety Administration (NHTSA), Society of Indian Automobile Manufacturers (SIAM), among others; corporate filings such as annual reports, investor presentations, and financial statements; and trade, business, and automotive associations. Secondary data has been collected and analyzed to arrive at the overall market size, which is further validated by primary research.
Primary Research
Extensive primary research was conducted after acquiring an understanding of the automotive transmission market scenario through secondary research. Several primary interviews were conducted with market experts from the automotive OEMs and automotive transmission providers across four major regions, namely, Asia Pacific, Europe, North America, and Middle East & Africa. Approximately 70% and 30% of the primary interviews were conducted with the automotive transmission manufacturers and OEMs, respectively. Primary data was collected through questionnaires, emails, and telephonic interviews. Various departments within organisations, including sales, operations, and administration, were contacted to provide a holistic viewpoint in reports while canvassing primary data. After interacting with industry participants, some brief sessions were conducted with experienced independent consultants to reinforce the findings from the primary interviews. This, along with the opinions of in-house subject matter experts, led to the findings delineated in the rest of this report.
Primary interviews have been conducted to gather insights, including automotive transmission market sizing estimation and forecast, future trends, and upcoming technologies in the automotive transmission market. Data triangulation of all these points was done using the information gathered from secondary research and model mapping. Stakeholders from the demand and supply sides have been interviewed to understand their views on the aforementioned points.
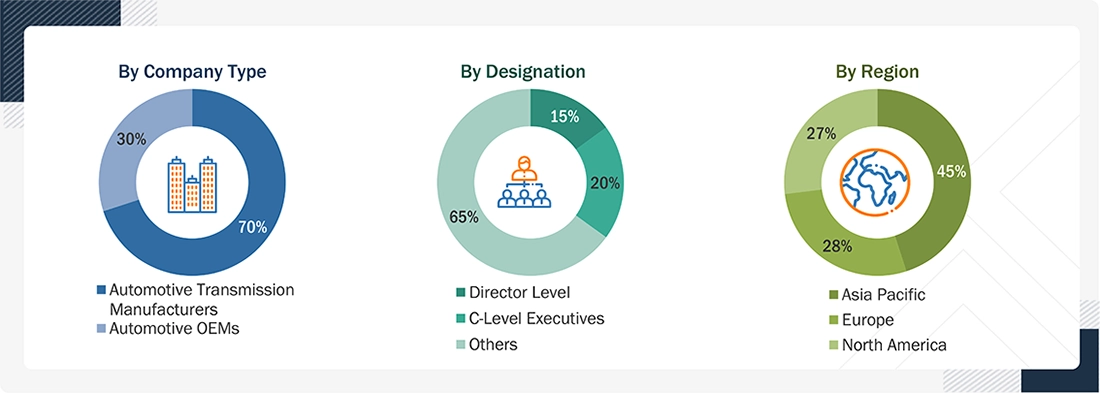
Note: Others include sales, marketing, and product managers.
Company tiers are based on the value chain; revenue of the company is not considered.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
A detailed market estimation approach was followed to estimate and validate the value and volume of the automotive transmission market and other dependent submarkets, as mentioned below:
- The bottom-up and top-down approaches have been used to estimate and validate the size of the automotive transmission market. The automotive transmission market, by transmission type, in terms of value and volume, is derived by identifying the country-level production numbers of each vehicle type (PC, LCV, Trucks, and buses). Forecasts are based on the expected penetration of transmission type across vehicle segments, considering OEM adoption plans, vehicle electrification, premiumization, safety and fuel-efficiency requirements, and increasing integration of advanced transmission systems.
- The market size was derived using parameters such as production of vehicle types (passenger cars, LCVs, heavy trucks, and buses) and corresponding penetration of the transmission type considered under the scope. Forecasts are based on expected vehicle production by country and vehicle type, considering OEM production plans, regional demand trends, economic conditions, electrification, and capacity expansion or rationalization.
- Transmission volume is calculated by multiplying vehicle production by the penetration of each transmission type, including automatic, manual, CVT, DCT, and AMT, across the respective vehicle segments. Transmission penetration is derived through country-level vehicle model mapping using OEM specifications, official product pages, brochures, and available transmission configurations.
- The market value for each transmission type is calculated by multiplying the corresponding transmission volume by its average selling price (ASP). ASPs are estimated for each transmission type and vehicle segment at the country level using supplier websites, product brochures, company disclosures, secondary sources, and industry expert validation.
- Country-level vehicle production and transmission penetration are forecast through 2033, considering historical production trends, OEM manufacturing plans, capacity expansions, vehicle electrification, domestic demand, export trends, economic conditions, government policies, and changes in vehicle mix. Country-level market estimates are aggregated to derive regional and global market sizes in terms of value and volume.
- Key players in the automotive transmission market were identified through secondary research, and their global market rankings were determined through primary and secondary research.
- The research methodology included the study of annual and quarterly financial reports, regulatory filings of major market players, and interviews with industry experts to gain detailed market insights.
- All major penetration rates, percentage shares, splits, and breakdowns for the automotive transmission market were determined through secondary sources and verified through primary sources.
- All key macro indicators affecting the revenue growth of the market segments and subsegments have been accounted for, viewed in extensive detail, verified through primary research, and analyzed to obtain validated and verified quantitative & qualitative data.
- The market data gathered was consolidated and added with detailed inputs, analyzed, and presented in this report.
Automotive Transmission Market: Top-Down and Bottom-Up Approach

Data Triangulation
All percentage shares, splits, and breakdowns were determined using secondary sources and verified by primary sources. All parameters that are said to affect the markets covered in this research study were accounted for, viewed in extensive detail, and analyzed to obtain the final quantitative and qualitative data.
Market Definition
- Manual Transmission (MT): A manual transmission uses a driver-operated clutch and gear lever to select fixed gear ratios. The driver controls gear changes according to vehicle speed, engine load, and driving conditions, while the mechanically simple architecture offers lower manufacturing and maintenance costs.
- Automated Manual Transmission (AMT): An AMT automates clutch operation and gear selection in a conventional manual gearbox using electronic control units and electromechanical or hydraulic actuators. It reduces driver effort while retaining much of the manual transmission's hardware, making it suitable for cost-sensitive passenger cars and commercial vehicles.
- Automatic Transmission (AT): An automatic transmission changes gear ratios without requiring driver-operated clutch control. Conventional ATs typically use planetary gearsets, a torque converter and electronically controlled hydraulic clutches to transfer engine torque across different driving conditions. Multiple gear ratios support smooth acceleration, high torque delivery and lower engine speeds during cruising, making ATs suitable for SUVs, passenger cars and heavy-duty vehicles.
- Dual Clutch Transmission (DCT): A DCT uses two independently controlled clutches to manage odd and even gear sets, allowing the next gear to be preselected before the current gear disengages. This enables rapid gear changes with minimal torque interruption, although clutch temperature management, low-speed smoothness and system cost influence adoption.
- Continuously Variable Transmission (CVT): A CVT varies the transmission ratio continuously, commonly through a belt or chain operating between variable-diameter pulleys. By adjusting the ratio to keep the engine within an efficient operating range, it supports smooth acceleration and fuel efficiency, particularly in small and mid-size passenger cars.
Key Stakeholders
- Automotive Transmission Manufacturers
- Automotive Original Equipment Manufacturers
- Automotive Transmission Component and Raw Material Suppliers
- Automotive Powertrain and Electric Drive System Suppliers
- Automotive Transmission Control Systems and Electronics Suppliers
- Automotive Transmission Testing, Certification, and Standards Organizations
- Regional Transmission Manufacturer Associations and Automobile Associations
- Traders, Distributors, and Suppliers of Automotive Transmission Systems
- Automotive Regulatory Bodies and Government Agencies
Report Objectives
-
To segment and forecast the size of the automotive transmission market by volume (million units) and value (USD billion/million) from 2026 to 2033.
- By transmission type (manual transmission, automatic transmission, continuously variable transmission (CVT), dual clutch transmission (DCT), automated manual transmission (AMT), at the regional level
- By vehicle type (passenger cars, light commercial vehicles, Trucks and Buses,), at the regional level
- By fuel type (diesel, gasoline, CNG/Alternate fuel), at the regional level
- By number of forward gears (up to 5, 6 to 8, 9 to 10, above 10 and CVT), at the regional level
- EV transmission, by transmission type (single-speed transmission and multi-speed transmission) at the regional level
- EV transmission, by integration level (reducer, e-transmission, integrated e-drive, e-axle) at the regional level
- Hybrid transmission market, by motor configuration (1 Motor Hybrid, 2 Motor Hybrid, 3 Motor Hybrid) at the regional level
- By region (Asia Pacific, Europe, North America, Latin America and Middle East & Africa)
- To comprehensively evaluate the key market dynamics, including growth drivers, restraints, opportunities, and challenges, shaping the evolution of the Automotive Transmission Market
- To strategically assess market segments based on their growth potential, emerging trends, future opportunities, and contribution to overall market revenue
- To analyze the competitive leadership mapping of the global automotive transmission manufacturers in the market and understand their market position with the help of a company evaluation matrix
- To track and analyze competitive developments, such as joint ventures, collaborations, partnerships, mergers & acquisitions, new product developments, and expansions, in the automotive transmission market
-
To study the following with respect to the market:
- Supply Chain Analysis
- Ecosystem Analysis
- Technology Analysis
- Trade Analysis
- Case Study Analysis
- Patent Analysis
- Regulatory Landscape
- Pricing Analysis
- Investment Scenario
- Key Stakeholders and Buying Criteria
- To analyze opportunities for stakeholders and the competitive landscape for market leaders
Available customizations:
MarketsandMarkets offers the following customisations for this market report:
Key Questions Addressed by the Report


Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the Automotive Transmission Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Custom Market Research Services
We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements
Get 10% Free CustomisationTESTIMONIALS
JIM NAAS
PRODUCT DIRECTOR, WEASLER
Weasler Engineering, a CentroMotion organization
Global Provider of Industrial Actuation & Control Solutionswww.weasler.com
Our organization was interested in learning more about the attractiveness of a particular market space. We contacted MarketsandMarkets to help us based on previous positive experiences we had with them. The results did not disappoint! We discussed our objectives with them, and the team at MarketsandMarkets developed and executed a proposal that met our needs precisely. We were very impressed by their level of expertise, the quality of the analysis and their insightful recommendations. We would not hesitate in working with them again in the future.

Matt Kardel,
Vice President
Aptiv,
A global technology company that develops safer, greener and more connected solutions.www.aptiv.com
We contracted with
MarketsandMarkets to evaluate the value chain and potential go-to-market partners related to our
interest in the Fleet Management space. The team successfully completed the work on time and at the
pricing agreed. MarketsandMarkets listened and understood our objectives and collaborated well with
us to help us get the visibility we needed to make an investment.
We have subsequently used
MarketsandMarkets again related to Smart Cities to good results.
- China Automotive Transmission Market
- India Automotive Transmission Market
- Japan Automotive Transmission Market
- South Korea Automotive Transmission Market
- Thailand Automotive Transmission Market
- Germany Automotive Transmission Market
- France Automotive Transmission Market
- Italy Automotive Transmission Market
- Russia Automotive Transmission Market
- UK Automotive Transmission Market
- Spain Automotive Transmission Market
- Canada Automotive Transmission Market
- Mexico Automotive Transmission Market
- US Automotive Transmission Market
- Brazil Automotive Transmission Market
- Argentina Automotive Transmission Market
- Iran Automotive Transmission Market
- South Africa Automotive Transmission Market
- Rest Of Europe Automotive Transmission Market
- Turkey Automotive Transmission Market
- Rest Of Asia Pacific Automotive Transmission Market
- Rest Of Latin America Automotive Transmission Market
Growth opportunities and latent adjacency in Automotive Transmission Market






Danial
Jun, 2022
Who are the top vendors in the Automotive Transmission Market? What is the competitive scenario among them?.
User
Nov, 2019
Pls send TOC and can it be customised for 2W AMT market for India and for ASEAN region including after market requirement for 2W AMT for a Bolt on design of AMT for 2W.
User
Nov, 2019
I am looking for commercial vehicle transmission data at a global level with deep dive into India, China, Brazil, Russia and South Africa. In this database, I am looking for Tier-1 and Tier-2 transmission suppliers mapping by different OEMs and models for the mentioned countries..
User
Nov, 2019
I am interested in new technologies relevance in commercial vehicles in developing countries context. Request if you can send me the free sample report portion relevant to only commercial vehicle regions covering other than Europe and North America.
User
Nov, 2019
I am interested to know just in the Automotive Transmission Market by vehicle and transmission type just in Mexico..
User
Nov, 2019
Looking for opportunities to exploit new technologies in the automotive industry in particular for smaller engines and related industries..
User
Nov, 2019
Ideally would like to see Program and/or Platform included. Also EVT/Reduction breakouts if possible..
User
Nov, 2019
Market share, past, present, forecast (2008-2018) with splits for: Supplier OEM Vehicle Class Technology Type Global Region.
User
Nov, 2019
LOW CARBON TRANSPORT – 16.67 Co2e g/km Transport, Automotive, Rail, Ship, Missile, JET Plane. Technology: Double Speed, 1/3 Fuel for same Ton-HP-Vehicle. 6 x kmpl; 16.67 Co2e g/km; g/t-km. .
User
Aug, 2019
Architecture,Transmission,Motor Output,final drive,Drive Type, Power Electronics, Vehicle type, Region-Global Forecast to 2025.