SCADA in Data Center Market Size, Share & Growth Report

SCADA in Data Center Market Size, Share & Trends by Offering (PLCs, RTUs, HMIs, I/O Modules, Gateways; Software; Services), Data Center Type (Hyperscale, Colocation, Enterprise, Edge & Micro), Facility Size (<5 MW, 5-20 MW, 20-100 MW, >100 MW) - Global Forecast to 2032


SCADA IN DATA CENTER MARKET OVERVIEW
According to MarketsandMarkets, SCADA in data center market size is projected to grow from USD 0.88 billion in 2026 to USD 2.01 billion by 2032, registering a CAGR of 14.7% during the forecast period. Growth is driven by increasing investments in hyperscale and colocation data centers as operators prioritize infrastructure reliability, real-time monitoring, and operational efficiency. The rising deployment of artificial intelligence workloads, cloud infrastructure, and high-performance computing is increasing demand for advanced SCADA solutions. Advancements in SCADA software, industrial control hardware, data acquisition, and supervisory monitoring are enhancing infrastructure visibility, enabling faster fault detection, and supporting reliable data center operations across major regions.
MARKET REPORT SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2025 (Value) | USD 0.78 Billion |
| Market Size in 2026 (Value) | USD 0.88 Billion |
| Market Forecast in 2032 (Value) | USD 2.01 Billion |
| CAGR | CAGR of 14.7% |
| Years Considered | 2022–2032 |
| Base Year | 2025 |
| Forecast Period | 2026–2032 |
| Units Considered | Value (USD Billion), Volume (Thousand Units) |
|
Top Companies
|
|
| Report Coverage | Revenue Forecast, Company Ranking, Competitive Landscape, Growth Factors, and Trends |
| Growth Drivers |
|
| Segments Covered |
|
| Regions Covered | North America, Europe, Asia Pacific, RoW |
KEY TAKEAWAYS
-
BY REGIONAsia Pacific is expected to register the highest CAGR of 15–17% in the SCADA in data center market during the forecast period, driven by expanding data center infrastructure and growing demand for digital and AI computing capacity.
-
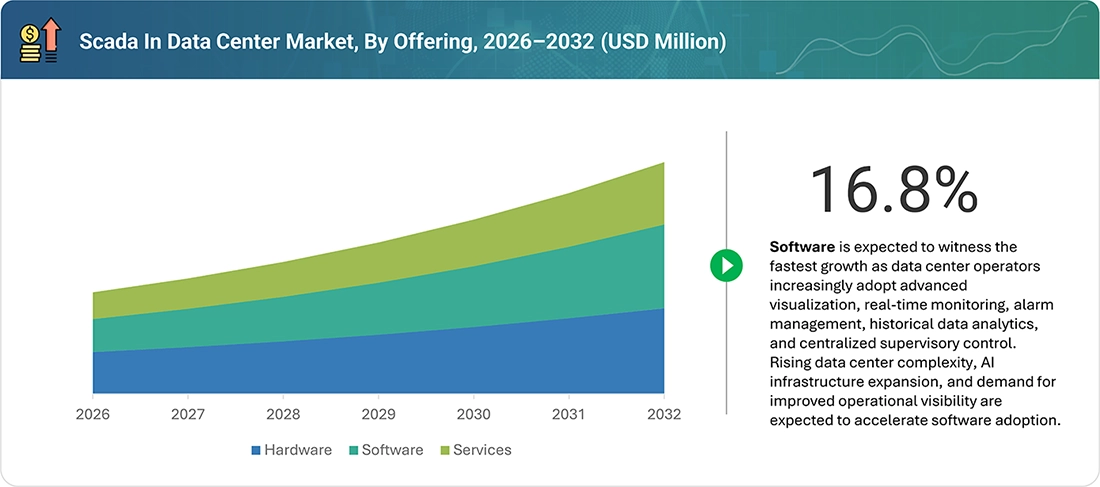
BY OFFERINGSoftware is expected to register the highest CAGR of 16.8% in the SCADA in data center market during the forecast period, supported by increasing adoption of real-time monitoring, visualization, alarm management, and supervisory control platforms.
-
BY APPLICATIONElectrical power distribution monitoring and control accounted for approximately 35–37% of the SCADA in data center market growth in 2025, reflecting the importance of monitoring critical electrical infrastructure, power distribution, and operational conditions.
-
BY DATA CENTER TYPEHyperscale data centers are expected to register the highest CAGR during 2026–2032.
-
BY FACILITY SIZEMega/campus data centers with IT capacity above 100 MW accounted for the largest share of the market in 2025, making them the largest facility size segment. Their demand for centralized monitoring and control of critical infrastructure supports continued market growth.
-
COMPETITIVE LANDSCAPE (KEY PLAYERS)Schneider Electric (France), Siemens (Germany), ABB (Switzerland), Emerson Electric Co. (US), and Honeywell International Inc. (US), among others, are identified as key players in the SCADA in data center market Analysis .
-
COMPETITIVE LANDSCAPE (STARTUPS/SMES)Inductive Automation (US) and Vertech (US), among others, provide SCADA software, system integration, and automation solutions relevant to data center infrastructure, highlighting their role as specialized technology providers in the SCADA in data center market.
The SCADA in data center industry is witnessing strong growth as operators invest in automation and real-time monitoring to improve infrastructure reliability and operational efficiency. Demand is supported by the expansion of hyperscale and colocation data centers, increasing deployment of AI workloads, and growing complexity of critical power and utility infrastructure. Advancements in SCADA software, industrial control hardware, data acquisition, and supervisory monitoring are enabling faster fault detection, centralized visibility, and improved operational control. Rising investments in large and mega campus facilities are further strengthening demand for SCADA solutions across data center applications and regions.
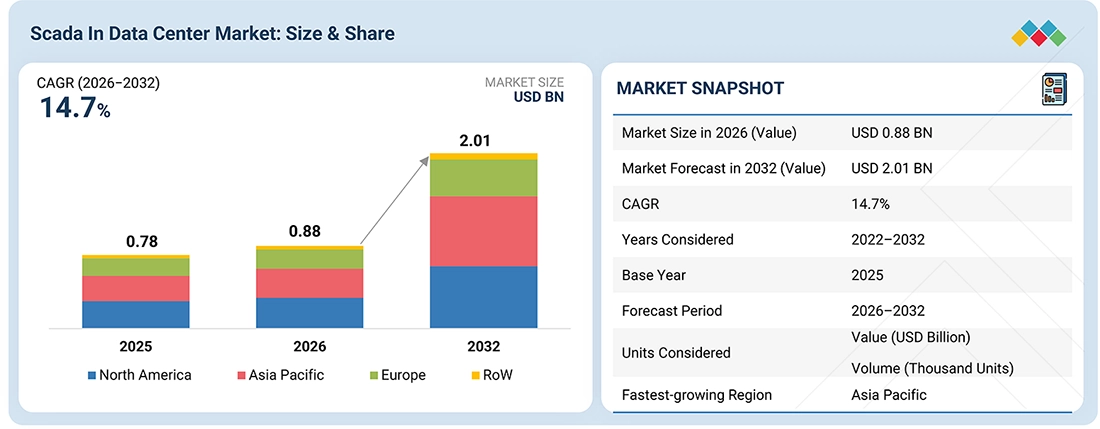
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
The figure highlights the growing shift in the SCADA in data center market trends toward advanced supervisory monitoring, real-time data acquisition, and intelligent infrastructure control. Data center operators are adopting SCADA hardware, software, and services to monitor critical power distribution, backup power systems, cooling utilities, and other essential facility operations. Increasing deployment of hyperscale and colocation data centers, alongside rising AI and high-performance computing workloads, is driving demand for enhanced operational visibility and reliable infrastructure monitoring. Advancements in SCADA software, AI-enabled analytics, anomaly detection, and centralized monitoring are creating opportunities to improve fault identification and operational response. This transition supports greater infrastructure reliability, reduced downtime, improved operational efficiency, and scalable monitoring across modern data center facilities.
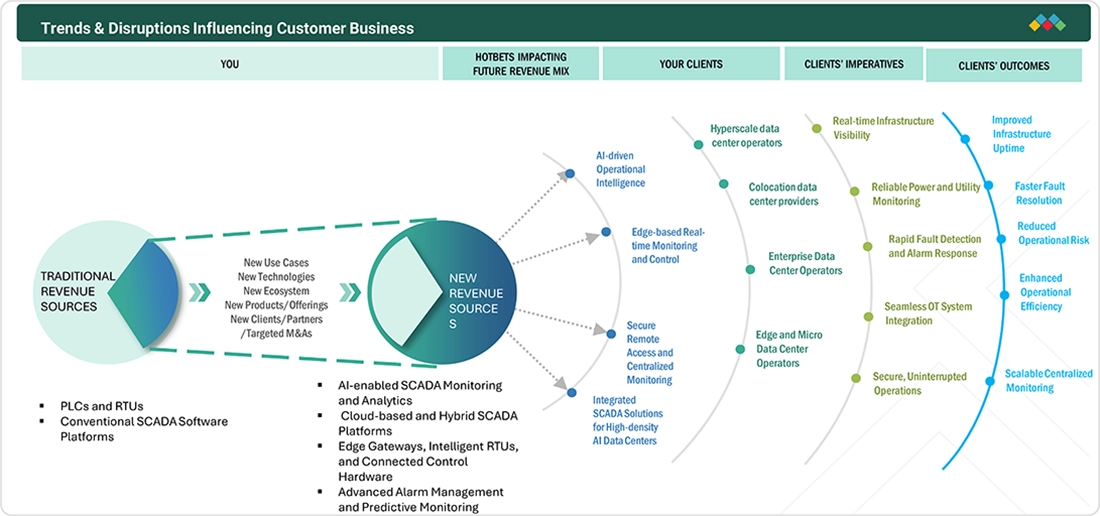
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
SCADA IN DATA CENTER MARKET DYNAMICS

Level
-
Expansion of hyperscale and colocation data centers to support growing cloud computing and digital infrastructure demand

-
Increasing deployment of AI and high-performance computing workloads, driving demand for real-time monitoring and control of critical power and cooling systems


Level
-
High initial costs of SCADA deployment and system integration

-
Complexity of integrating SCADA with legacy infrastructure and existing control systems


Level
-
Adoption of AI-enabled monitoring, analytics, and anomaly detection

-
SCADA modernization and centralized monitoring across multi-site data center operations


Level
-
Cybersecurity risks across connected OT systems and critical infrastructure

-
Interoperability challenges across equipment, protocols, and automation platforms

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Expansion of hyperscale and colocation data centers to support growing cloud computing and digital infrastructure demand
Increasing investments in hyperscale and colocation data centers are driving demand for SCADA solutions that enable centralized monitoring and supervisory control of critical infrastructure. As facilities expand in scale and complexity, operators require reliable data acquisition, equipment visibility, and alarm management to support efficient operations.
Restraint: High initial costs of SCADA deployment and system integration
SCADA implementation requires investment in software platforms, industrial control hardware, communication infrastructure, engineering, and commissioning. Integration and customization costs can increase the initial investment, particularly for large facilities with complex infrastructure and extensive monitoring requirements.
Opportunity: Adoption of AI-enabled monitoring, analytics, and anomaly detection
Growing interest in intelligent infrastructure operations creates opportunities for SCADA platforms incorporating advanced analytics, anomaly detection, and enhanced alarm management. These capabilities can help operators identify unusual equipment behavior, improve operational visibility, and support faster decision making.
Challenge: Interoperability challenges across equipment, protocols, and automation platforms
Data centers may use equipment and control technologies from multiple vendors, with different communication protocols and system architectures. Ensuring reliable data exchange and compatibility across SCADA software, PLCs, RTUs, and existing infrastructure can complicate integration and ongoing system maintenance.
SCADA IN DATA CENTER MARKET SIZE, SHARE & GROWTH REPORT: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Provides SCADA software, automation hardware, RTUs, gateways, and supervisory monitoring solutions for critical data center power and utility infrastructure. | Improves real time infrastructure visibility, supports centralized monitoring, enables faster alarm response, and strengthens operational reliability. |
 |
Offers SCADA platforms, including SIMATIC WinCC, for data acquisition, visualization, alarm management, and supervisory monitoring of data center infrastructure. | Enhances operational visibility, enables timely fault detection, supports centralized control, and improves monitoring of critical facility systems. |
 |
Supplies industrial automation, control, and monitoring technologies applicable to data center electrical and utility systems, including SCADA related applications. | Supports reliable data acquisition, improves process monitoring, enables faster response to abnormal conditions, and strengthens operational continuity. |
 |
Provides SCADA and automation technologies, including control systems, RTUs, and communication solutions for monitoring and controlling critical electrical infrastructure serving data centers. | Improves power infrastructure visibility, supports remote monitoring, enhances fault detection, and strengthens reliability across critical electrical systems. |
 |
Offers automation, supervisory monitoring, and control technologies applicable to data center facility operations, including qualifying SCADA deployments across critical infrastructure. | Supports centralized monitoring, improves alarm management, enables faster operational response, and enhances visibility across connected infrastructure systems. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
SCADA IN DATA CENTER MARKET ECOSYSTEM
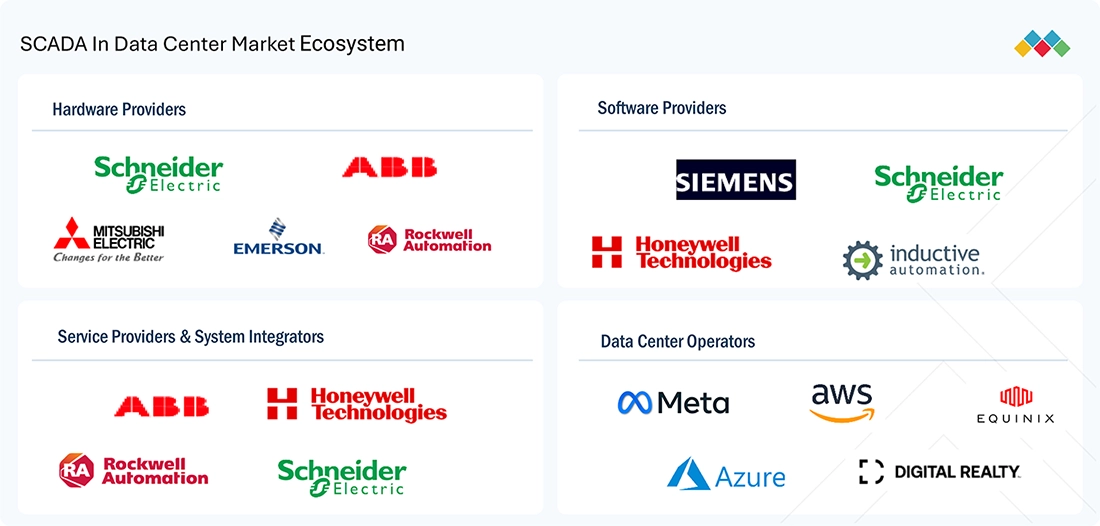
The SCADA in data center market ecosystem is structured across SCADA hardware and component providers, software platform providers, system integrators, and data center operators, collectively enabling real-time monitoring, supervisory control, and reliable infrastructure operations. Hardware providers supply PLCs, RTUs, HMIs, I/O modules, communication gateways, and other components required for data acquisition and control. Software providers develop SCADA platforms that support equipment visualization, alarm management, historical data recording, and centralized monitoring of critical infrastructure. System integrators combine hardware and software with existing data center systems to ensure seamless deployment, interoperability, and operational reliability. Data center operators deploy SCADA solutions to monitor power distribution, backup power, cooling utilities, and other critical facility systems, helping improve operational visibility, support faster fault detection, and maintain infrastructure availability across hyperscale, colocation, and other data center facilities.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
SCADA IN DATA CENTER MARKET SEGMENTS
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
SCADA in Data Center Market, by Offering
Software is expected to register the highest CAGR of 16.8% during the forecast period, driven by increasing adoption of real-time monitoring, data visualization, alarm management, and supervisory control platforms. Growing demand for centralized monitoring, advanced analytics, and SCADA modernization is accelerating software adoption across data center infrastructure.
SCADA in Data Center Market, by Application
Electrical power distribution monitoring and control is expected to account for a significant share of the SCADA in data center market in 2026, supported by the critical need to monitor electrical infrastructure and maintain operational reliability.
SCADA in Data Center Market, by Data Center Type
Hyperscale data centers are expected to account for a significant share of the SCADA in data center market, supported by investments in large-scale cloud infrastructure and AI computing capacity. Increasing infrastructure complexity and the need for centralized monitoring of critical power, cooling, and utility systems are driving SCADA adoption.
SCADA in Data Center Market, by Facility Size
Mega/campus data centers with IT capacity above 100 MW are expected to register the highest CAGR during the forecast period, reflecting growing investment in large-scale facilities that require centralized monitoring and control of critical infrastructure.
SCADA IN DATA CENTER MARKET BY REGION
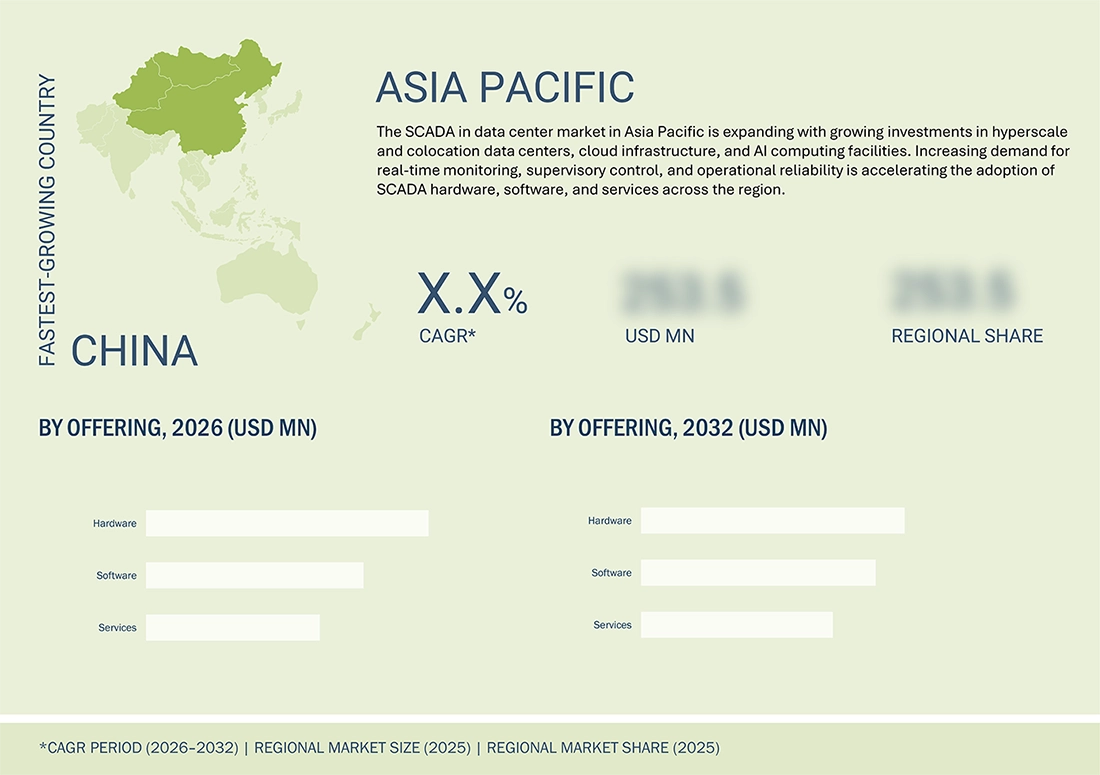
Asia Pacific to be the fastest-growing region in the SCADA in data center market during the forecast period
Asia Pacific is expected to be the fastest-growing region in the SCADA in data center market, driven by the expansion of hyperscale and colocation data centers across China, India, Japan, Australia, and Southeast Asia. Increasing investments in cloud computing, AI infrastructure, and digital services are creating demand for reliable infrastructure monitoring and automation. The growing complexity of power distribution, backup power, and cooling systems is accelerating the adoption of SCADA hardware, software, and services. Rising emphasis on operational efficiency, infrastructure reliability, and centralized monitoring is further supporting regional market growth.
SCADA IN DATA CENTER MARKET SIZE, SHARE & GROWTH REPORT: COMPANY EVALUATION MATRIX
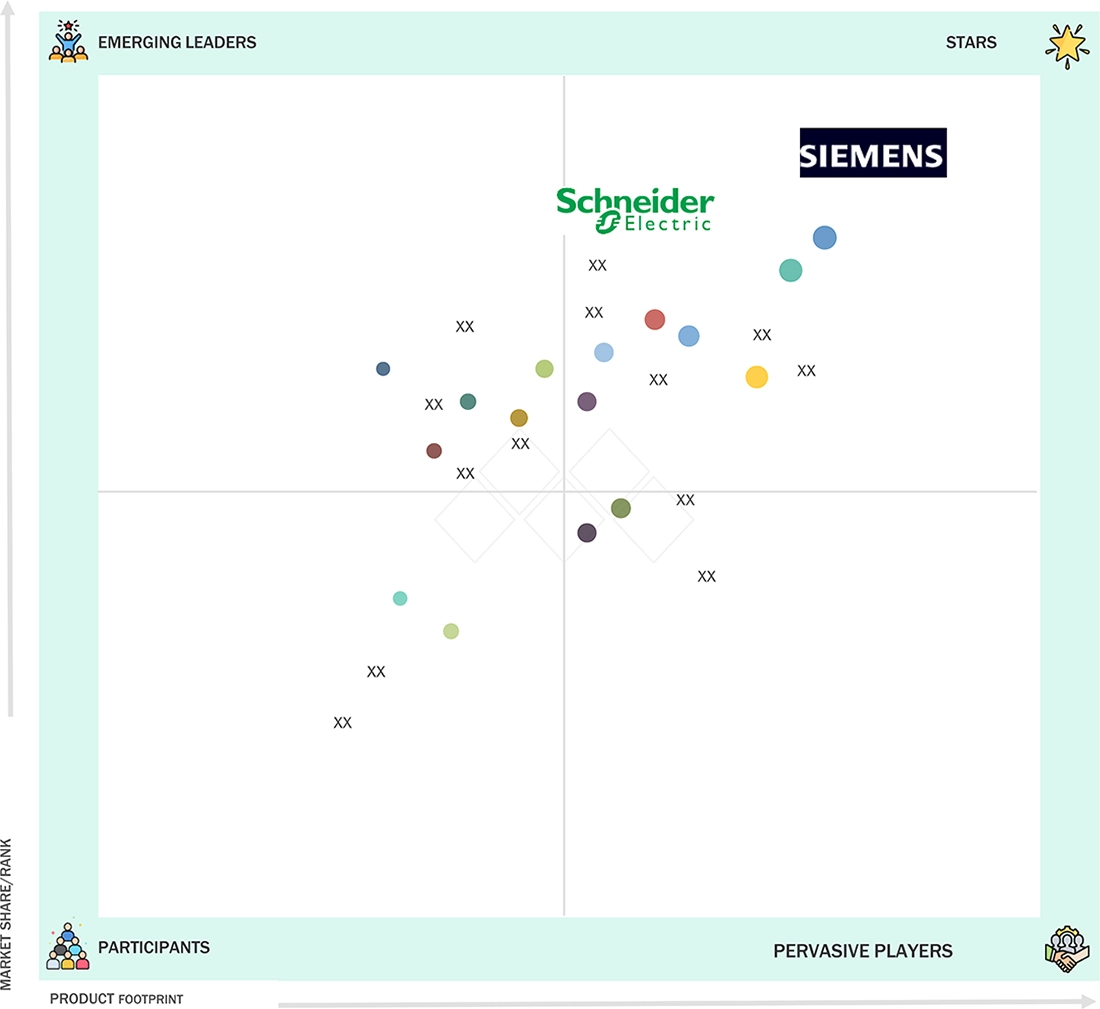
In the SCADA in data center companies matrix, Siemens (Germany) is positioned as a key player, supported by its extensive industrial automation portfolio, SIMATIC WinCC SCADA software, and capabilities in real-time data acquisition, visualization, and supervisory control. Its expertise in industrial control hardware, software platforms, and system integration strengthens its position in monitoring critical data center infrastructure. Schneider Electric (France) is also positioned as a key player, driven by its SCADA software, automation hardware, and EcoStruxure portfolio supporting critical infrastructure monitoring and control. Its capabilities in power distribution monitoring, industrial connectivity, and integrated automation solutions support data center operators in improving operational visibility and infrastructure reliability. Continued investments in digital technologies, software development, and advanced automation solutions reinforce the positions of both companies in the evolving SCADA in data center market.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- Rockwell Automation (US)
- ABB (Switzerland)
- Schneider Electric (France)
- Emerson Electric Co. (US)
- Siemens (Germany)
- Honeywell International Inc. (US)
- Mitsubishi Electric Corporation (Japan)
- OMRON Corporation (Japan)
- Yokogawa Electric Corporation (Japan)
WHAT IS IN IT FOR YOU: SCADA IN DATA CENTER MARKET SIZE, SHARE & GROWTH REPORT REPORT CONTENT GUIDE
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| SCADA Solution Providers |
|
|
| SCADA Component & Technology Providers |
|
|
RECENT DEVELOPMENTS
- October 2026 : Schneider Electric, AVEVA, Nscale, and Start Campus announced a pilot deployment of an end-to-end digital twin at the SINES Data Campus in Portugal. The initiative combines engineering and operational data with power and cooling simulations to help optimize AI data center performance. The development highlights growing adoption of integrated monitoring, simulation, and operational intelligence technologies relevant to SCADA-enabled data center environments.
- January 2026 : Schneider Electric highlighted software-defined SCADA as an emerging approach for remote operations, with its EcoStruxure Geo SCADA Expert supporting scalable monitoring and control, live configuration changes, Python-based automation, and management of geographically dispersed assets.
- June 2025 : Siemens partnered with Cadolto Datacenter and Legrand to introduce a modular edge data center solution, with Siemens providing and integrating energy and building automation systems. The solution is designed to support scalable deployment, efficient infrastructure management, and workloads ranging from standard data processing to high-performance AI applications. The development highlights the growing demand for integrated automation and monitoring capabilities in modular data center environments.
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
Methodology
The study involved four major activities in estimating the current size of the SCADA in data center market. Exhaustive secondary research has been done to collect information on the market, peer market, and parent market. To validate these findings, assumptions, and sizing with industry experts across the value chain through primary research has been the next step. Both top-down and bottom-up approaches have been employed to estimate the complete market size. After that, market breakdown and data triangulation methods have been used to estimate the market size of segments and subsegments. Two sources of information, secondary and primary, have been used to identify and collect information for an extensive technical and commercial study of the SCADA in data center market.
Secondary Research
Various secondary sources have been referred to during the research process to identify and collect information relevant to the SCADA in data center market. These sources include company annual reports, press releases, investor presentations, official product documentation, technical white papers, industry journals, certified publications, research articles, company websites, industry directories, and relevant market research databases. Secondary research has been conducted to obtain key information on the industry's supply chain, market value chain, leading market participants, SCADA product portfolios, data center applications, market segmentation, regional markets, and key developments from market and technology perspectives. The research has also examined relevant SCADA hardware, software, and service offerings, along with adoption trends, technology developments, and competitive dynamics specific to data center environments. The collected secondary data has been analyzed to support market sizing, segmentation, and forecasting, with key findings and assumptions further assessed through primary research wherever applicable.
Primary Research
Extensive primary research has been conducted after gaining an understanding of the current state of the SCADA in data center market through secondary research. Several primary interviews have been conducted with experts from the demand and supply sides across four major regions: North America, Europe, Asia Pacific and RoW. This primary data has been collected through questionnaires, emails, and telephonic interviews.
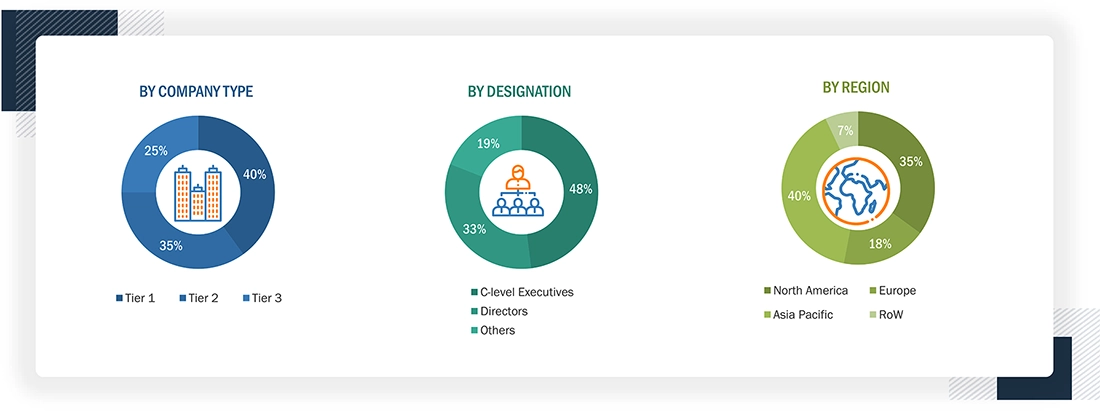
Following is the breakdown of primary respondents:
To know about the assumptions considered for the study, download the pdf brochure
Note: Other designations include product, sales, and marketing managers.
Three tiers of companies have been defined based on their total revenue as of 2025: tier 3: revenue less than USD 500 million; tier 2: revenue between USD 500 million and USD 5 billion; and tier 1: revenue more than USD 5 billion.
RoW mainly includes South America, Africa, and the Middle East.
Market Size Estimation
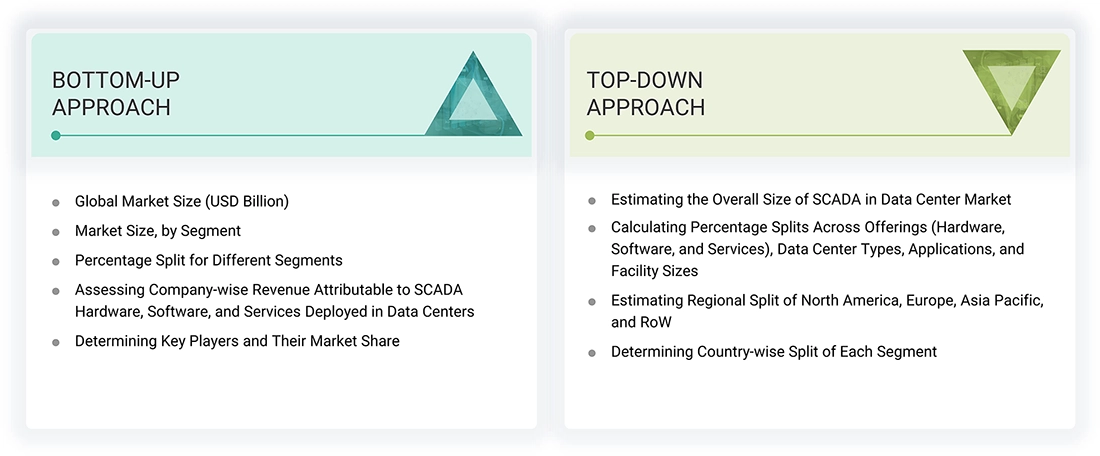
Both top-down and bottom-up approaches have been used to estimate and validate the total size of the SCADA in data center market. These methods have also been used extensively to estimate the size of various market subsegments. The following research methodology has been used to estimate the market size:
- Major players in the industry and markets have been identified through extensive secondary research.
- The industry’s value chain and market size (in terms of value) have been determined through primary and secondary research processes.
- All percentage shares, splits, and breakdowns have been determined using secondary sources and verified through primary sources.
Data Triangulation
After arriving at the overall size of the SCADA in data center market from the market size estimation process explained above, the total market has been split into several segments and subsegments. Data triangulation and market breakdown procedures have been employed, where applicable, to complete the overall market engineering process and derive the exact statistics for all market segments and subsegments. The data has been triangulated by studying various factors and trends from both the demand and supply sides. Additionally, the market size has been validated using both top-down and bottom-up approaches.
Market Definition
The SCADA in data center market comprises supervisory control and data acquisition hardware, software, and services deployed to monitor, collect, visualize, and control operational data across data center infrastructure. These solutions enable real-time monitoring of connected equipment, alarm and event management, historical data recording, and supervisory control to support operational reliability and infrastructure performance. The market includes qualifying programmable logic controllers (PLCs), remote terminal units (RTUs), human-machine interfaces (HMIs), industrial communication equipment, SCADA software platforms, and associated engineering, integration, commissioning, modernization, and maintenance services. These solutions support applications involving electrical power infrastructure, backup power systems, cooling and thermal management, environmental monitoring, critical utilities, and on-site energy systems where genuine SCADA functionality is deployed. SCADA solutions play an important role in improving operational visibility, identifying abnormal conditions, coordinating supervisory control, and supporting timely responses to infrastructure disruptions. As data centers expand in scale and complexity to accommodate cloud computing, artificial intelligence, and high-performance computing workloads, SCADA technologies are becoming increasingly relevant to managing critical operations and maintaining reliable infrastructure performance.
Key Stakeholders
- Data center operators
- Cloud service providers and hyperscale operators
- Colocation service providers
- Enterprise organizations and end users
- SCADA software and platform providers
- Industrial automation hardware manufacturers
- Programmable logic controller (PLC) and remote terminal unit (RTU) manufacturers
- Human machine interface (HMI) and industrial communication equipment providers
- Data center electrical infrastructure and power equipment providers
- Cooling and thermal management equipment providers
- System integrators and SCADA solution providers
- Engineering, procurement, and construction (EPC) contractors
- Data center developers and construction companies
- Industrial cybersecurity and operational technology (OT) security providers
- Energy management and power monitoring solution providers
- Building automation and infrastructure management technology providers
- Government bodies, investors, and private equity firms
- Industry associations related to data centers, industrial automation, and digital infrastructure
- Research institutions and technology organizations
- Standards organizations and regulatory authorities
Report Objectives
- To define, describe, and forecast the SCADA in data center market based on offering, data center type, application, facility size, and region, in terms of value
- To describe and forecast the size of the SCADA in data center market across four regions: North America, Europe, Asia Pacific, and the Rest of the World (RoW), along with their respective countries, in terms of value
- To provide detailed information regarding the drivers, restraints, opportunities, and challenges influencing the growth of the SCADA in data center market
- To strategically analyze micromarkets with respect to individual growth trends, prospects, and contributions to the overall market size
- To study the complete value chain of the SCADA in data center market
- To analyze opportunities for stakeholders by identifying high-growth segments of the SCADA in data center market
- To strategically profile the key players and comprehensively analyze their market positions in terms of their ranking and core competencies
- To analyze competitive developments, such as product launches, acquisitions, collaborations, and partnerships, in the SCADA in data center market
- To provide ecosystem analysis, case study analysis, patent analysis, technology analysis, the impact of AI/Gen AI, the impact of 2025 US tariffs, key conferences and events, Porter's five forces analysis, and regulations pertaining to the SCADA in data center market
Available Customizations:
With the given market data, MarketsandMarkets offers customizations according to the company’s specific needs. The following customization options are available for the report:
Company Information:
- Detailed analysis and profiling of additional market players (up to 5)


Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the SCADA in Data Center Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Custom Market Research Services
We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements
Get 10% Free CustomisationTESTIMONIALS

Tetsuya Ohhira
Business Development Manager-Technology Business
Nikon Corporation,
Leading Japanese MNC specializing in optics and imaging productswww.nikon.com
MarketsandMarkets™ response
is quick. Their attitude is flexible and positive. Analyst Insights are globally considered and
significant. Client Services quickly respond to our inquiry and demand. Their wide range of global
surveys help us make our strategic plan.
We hope Knowledge Store will be easier to search
for a report.
VP - Marketing & Business Development
Leading Provider of Process Control Solutions
We engaged with MarketsandMarkets on a study to perform an analysis and recommend a Go-To-Market strategy for metrology and process control in the semiconductor market. The study was tailored to our targets and needs with well-defined milestones. Our overall experience with the MarketsandMarkets team was very good throughout the project in all aspects including the analysis methodologies used, the quality and depth of primary and secondary data sets, the professionalism and flexibility of the team and the ability to meet the target schedule and milestones. We want to thank MarketsandMarkets team for a job well done.





Growth opportunities and latent adjacency in SCADA in Data Center Market