Ventilators Market by Mobility (Intensive Care Ventilators, Transportable Ventilators), Type (Adult & Pediatric Ventilators), Interface (Invasive Ventilation), Mode (Combined Mode Ventilation), Care Setting (Hospitals & Clinics)- Global Forecast to 2031

Market Size
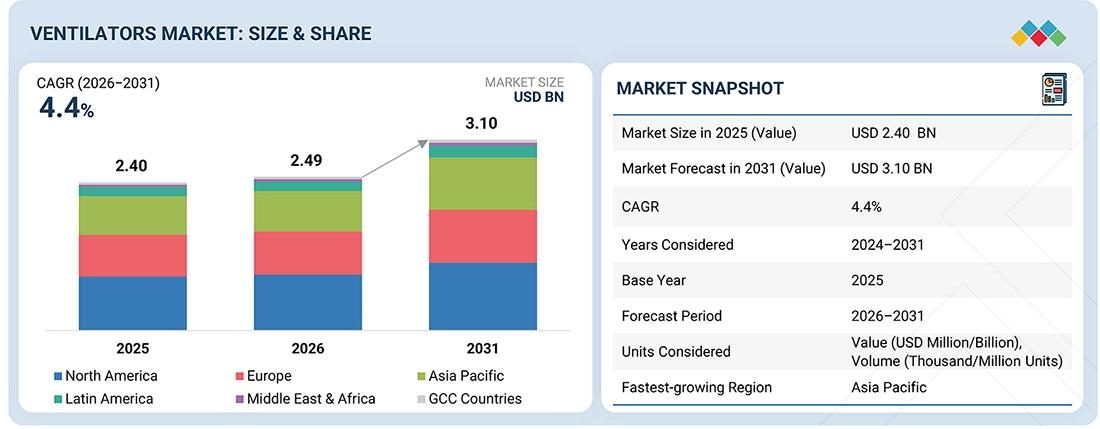
$2.49B
MARKET SIZE, 2026
Projected Market Size
$3.10B
MARKET SIZE, 2031
CAGR
4.4%
CAGR (2026-2031)
Forecast Period
2026-2031
FORECAST PERIOD

VENTILATORS MARKET SIZE, SHARE & GROWTH SNAPSHOT
ventilators-market Overview

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

The global ventilators market is projected to grow from USD 2.49 billion in 2026 to USD 3.10 billion by 2031, at a CAGR of 4.4% during the forecast period. The market was valued at USD 2.40 billion in 2025. Market growth is supported by rising respiratory and critical-care admissions, aging populations, continued ICU and NICU capacity upgrades, and stronger emergency preparedness. Demand is also shifting toward portable and transport systems, neonatal-capable platforms, dual invasive/non-invasive devices, and connected ventilators with automated or closed-loop decision support. High acquisition and lifecycle costs, long hospital replacement cycles, complex regulatory requirements, and shortages of trained respiratory-care personnel restrain adoption. Vendor exits and portfolio consolidation since 2024 are accelerating replacement opportunities for active global suppliers.

KEY TAKEAWAYS

  • MARKET SNAPSHOT:
    Base Year Market Size (2025): USD 2.40 Billion
    Current Market Size (2026): USD 2.49 Billion
    Forecast Market Size (2031): USD 3.10 Billion
    CAGR (2026–2031): 4.4%
  • SEGMENT LEADERSHIP:
    Product Type Leader: Portable and transportable ventilators are projected to grow at a CAGR of 5.5% and are expected to reach USD 857.1 million by 2031.
    Patient Type Leader: Adult & pediatric ventilators account for the largest share.
    Capability Leader: Dual-capability ventilators hold the largest share.
    Ventilation Mode Leader: Combined-mode ventilation represents the largest segment.
    End User Leader: Hospitals and clinics dominate the market.
    Regional Leader: North America holds the largest market share, while Asia Pacific is expected to record the fastest growth.
  • MARKET OUTLOOK & COMPETITIVE LANDSCAPE:
    Dräger, Getinge, Mindray, Hamilton Medical, and ZOLL are the key players in the ventilators market, supported by broad portfolios, global reach, strong clinical credibility, and robust financial strength.
    CorVent Medical, Noccarc, Magnamed, and Ventinova have distinguished themselves through portable solutions, specialized ventilation technologies, local manufacturing, and lower lifecycle costs.

The ventilators market is being reshaped by ICU modernization, rising respiratory disease burden, expansion of neonatal and emergency-care capacity, and a growing preference for connected, versatile ventilation platforms. Capital-budget constraints, long device replacement cycles, regulatory complexity, and workforce shortages remain key restraints. Growth opportunities are concentrated in portable and transport ventilation, emerging markets, dual invasive/non-invasive systems, automated modes, and the replacement demand created by supplier exits and industry consolidation.

TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS

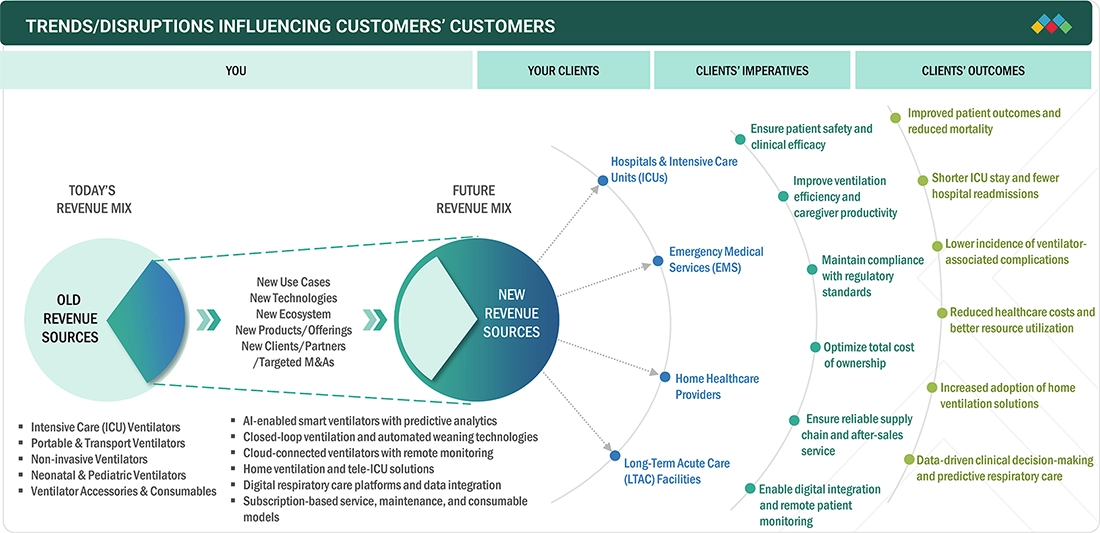
The ventilators market is undergoing a structural transition driven by supplier consolidation and rapid technology evolution. Medtronic's decision to wind down its ventilator product line and Philips' contraction in parts of its hospital and home respiratory portfolio created replacement opportunities, while ZOLL's acquisition of selected Vyaire product lines preserved and consolidated the Bellavista, LTV, Fabian, and 3100 HFOV platforms. Active manufacturers are responding with broader universal platforms, neonatal options, compact transport systems, remote software updates, interoperable data exchange, and automated lung-protective or weaning functions. Hospitals are increasingly evaluating vendors on installed-base support, cybersecurity, service continuity, consumable availability, and integration with patient monitoring and clinical information systems. The result is a shift from stand-alone breathing machines toward connected respiratory-care ecosystems that support ICU, transport, emergency, and step-down workflows.
ventilators-market Disruptions

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

MARKET DYNAMICS

Drivers
Impact
Level
  • Rising incidence of respiratory failure and critical-care admissions
  • Aging population and higher surgical volumes
RESTRAINTS
Impact
Level
  • High acquisition, maintenance, and training costs
  • Long replacement cycles and constrained hospital capital budgets
OPPORTUNITIES
Impact
Level
  • Replacement opportunities created by vendor exits and portfolio consolidation
  • Rapid growth of portable, transport, and neonatal ventilation
CHALLENGES
Impact
Level
  • Shortage of respiratory therapists and critical-care professionals
  • Interoperability, software validation, and cybersecurity requirements

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Driver: Rising incidence of respiratory failure and critical-care admissions

The rising burden of acute respiratory failure, pneumonia, COPD exacerbations, sepsis, trauma, and complex surgical cases is increasing the need for mechanical ventilation. Hospitals are expanding ICU and NICU capacity and strengthening emergency preparedness, while ambulance and air-medical providers are investing in portable systems. These trends support demand for high-performance ventilators capable of serving multiple patient types and care pathways.

Restraint:High acquisition, maintenance, and training costs

Ventilators require substantial upfront investment as well as expenditure for preventive maintenance, calibration, staff training, accessories, and service contracts. Hospitals often operate ventilators for many years, extending replacement cycles when budgets are constrained. These factors slow fleet renewal, particularly in public hospitals and lower-income markets, even when newer systems offer better automation and connectivity.

Opportunity: Replacement opportunities created by vendor exits and portfolio consolidation

The withdrawal or contraction of established suppliers has created opportunities for active manufacturers to replace legacy fleets, secure multi-year hospital contracts, and standardize customers on new platforms. Getinge, Dräger, Mindray, Hamilton Medical, ZOLL, and selected home-ventilation specialists can benefit by offering migration support, clinical training, compatible workflows, and reliable long-term service.

Challenge: Shortage of respiratory therapists and critical-care professionals

Advanced ventilators can only deliver their full value when clinicians are trained to configure modes, interpret waveforms, manage alarms, and implement lung-protective protocols. Shortages of respiratory therapists and critical-care staff, variation in clinical practice, and the need to retrain teams when switching vendors can delay adoption and reduce utilization of sophisticated features.

VENTILATORS MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES

COMPANY USE CASE DESCRIPTION BENEFITS
company logo
Deploys ICU and neonatal ventilators within connected acute-care environments, integrating ventilation data with patient monitoring and clinical workflow systems Supports standardized critical-care workflows | Remote visibility | Lung-protective ventilation | Long-term fleet serviceability
company logo
Provides Servo ventilators for adult, pediatric, and neonatal care, with advanced synchrony, monitoring, and automated support across high-acuity settings Improves patient-ventilator interaction | Enables one-platform use across patient groups | Supports efficient ICU standardization
company logo
Combines ventilators with patient monitors, infusion systems, anesthesia equipment, and digital ICU solutions for hospital-wide critical-care deployments Enables bundled procurement | Competitive lifecycle economics | Integrated data and alarm management across care areas
company logo
Offers ventilation-focused platforms for ICU, neonatal, MRI, emergency, and transport settings with automated modes and compact mobility options Reduces clinician workload | Supports consistent therapy during transport | Enables fleet continuity from prehospital to ICU care
company logo
Provides a broad respiratory portfolio spanning critical-care, transport, neonatal, and high-frequency ventilation following the acquisition of selected Vyaire product lines Maintains continuity for legacy fleets | Expands patient-range coverage | Supports hospitals and EMS providers with multiple ventilation technologies

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET ECOSYSTEM

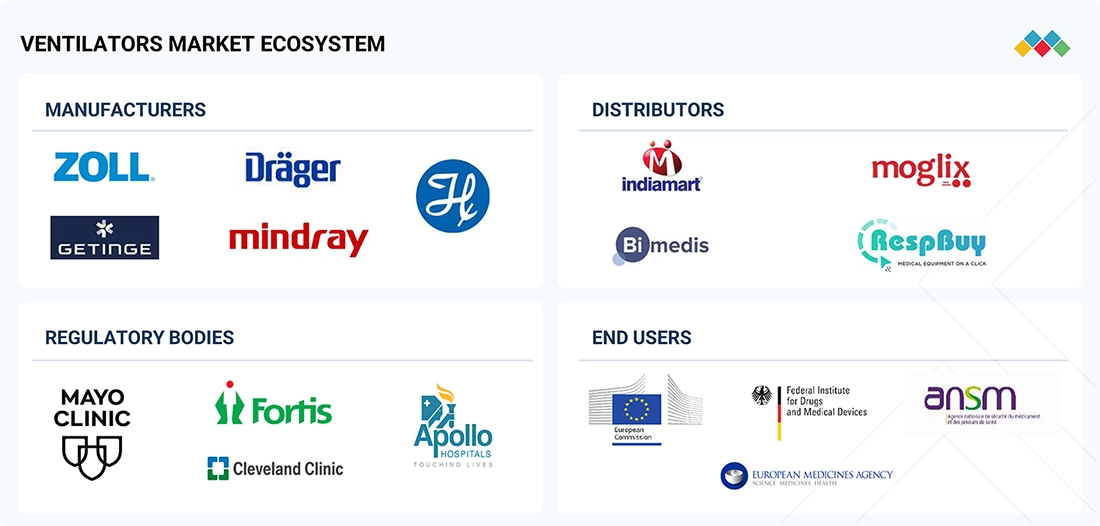
The ventilators market ecosystem begins with suppliers of blowers and turbines, flow and pressure sensors, valves, oxygen-control modules, microprocessors, displays, batteries, humidification components, breathing-circuit interfaces, and embedded software. Global manufacturers such as Dräger, Getinge, Mindray, Hamilton Medical, ZOLL, Löwenstein Medical, GE HealthCare, Nihon Kohden, and Air Liquide Medical Systems integrate these components into ICU, neonatal, transport, emergency, and home life-support ventilators. Products reach customers through direct hospital sales organizations, specialist respiratory distributors, government tenders, group purchasing organizations, and emergency-care channels. Clinical engineering teams, respiratory therapists, service partners, software providers, and consumable suppliers support the installed base throughout the device lifecycle. Key end users include hospitals and clinics, ambulatory care centers, ambulance and air-medical services, long-term care providers, and selected home-care programs.
ventilators-market Ecosystem

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET SEGMENTS
ventilators-market Segments

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Ventilators Market, By Mobility

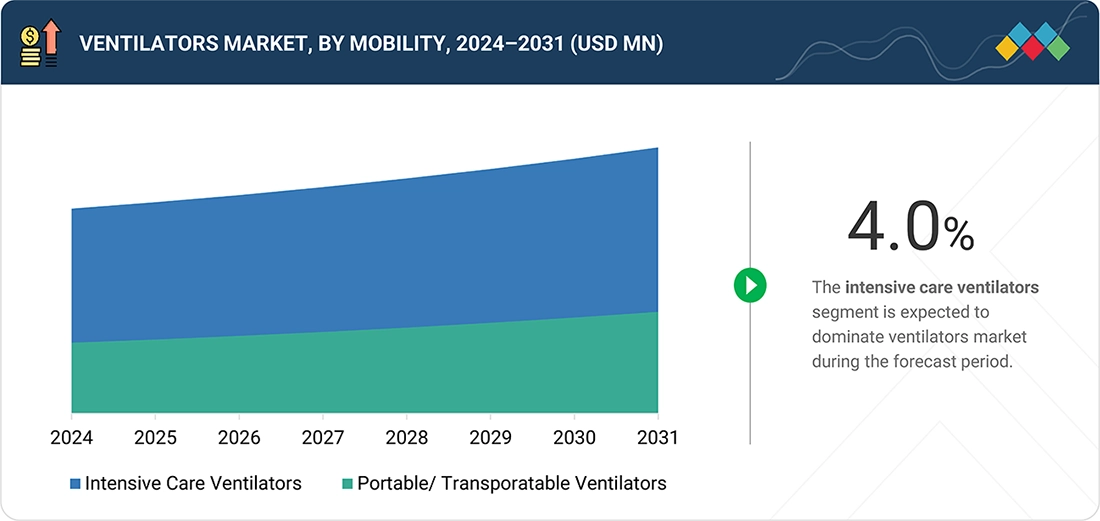
Intensive care ventilators hold the largest share due to their high selling prices, broad use across ICUs and NICUs, and advanced clinical capabilities. High-end and mid-end ICU systems provide integrated monitoring, multiple modes, automated support, and connectivity. Portable and transportable ventilators are expected to grow faster as hospitals, EMS providers, air ambulances, and disaster-response organizations expand mobile respiratory-care capacity.

Ventilators Market, By Patient Type

Adult & pediatric ventilators dominate revenue because adult critical-care admissions represent the largest treatment volume and require a wide range of invasive and non-invasive support. Neonatal and infant systems remain a specialized high-value segment, driven by premature births, NICU investment, and the need for precise low-volume, low-pressure ventilation.

Ventilators Market, By Interface Capability

Dual-capability ventilation holds the largest share because modern ICU and transport platforms generally support both invasive and non-invasive interfaces. This versatility allows hospitals to use the same device during escalation, stabilization, and weaning, improving utilization and lowering the need for separate equipment fleets.

Ventilators Market, By Mode

Combined-mode ventilation leads the market as contemporary systems integrate volume, pressure, assisted, spontaneous, and automated ventilation modes. The ability to switch between modes or apply hybrid targeting helps clinicians personalize therapy and respond to changing lung mechanics, while dedicated pressure and volume modes remain important for defined protocols.

Ventilators Market, By Care Setting

Hospitals and clinics account for most revenue because ventilators are essential in ICUs, NICUs, emergency departments, recovery areas, and high-dependency units. Emergency medical services are expected to expand rapidly with demand for rugged, portable, battery-powered ventilators, while ambulatory centers use ventilation primarily for procedural and short-duration respiratory support.

REGION

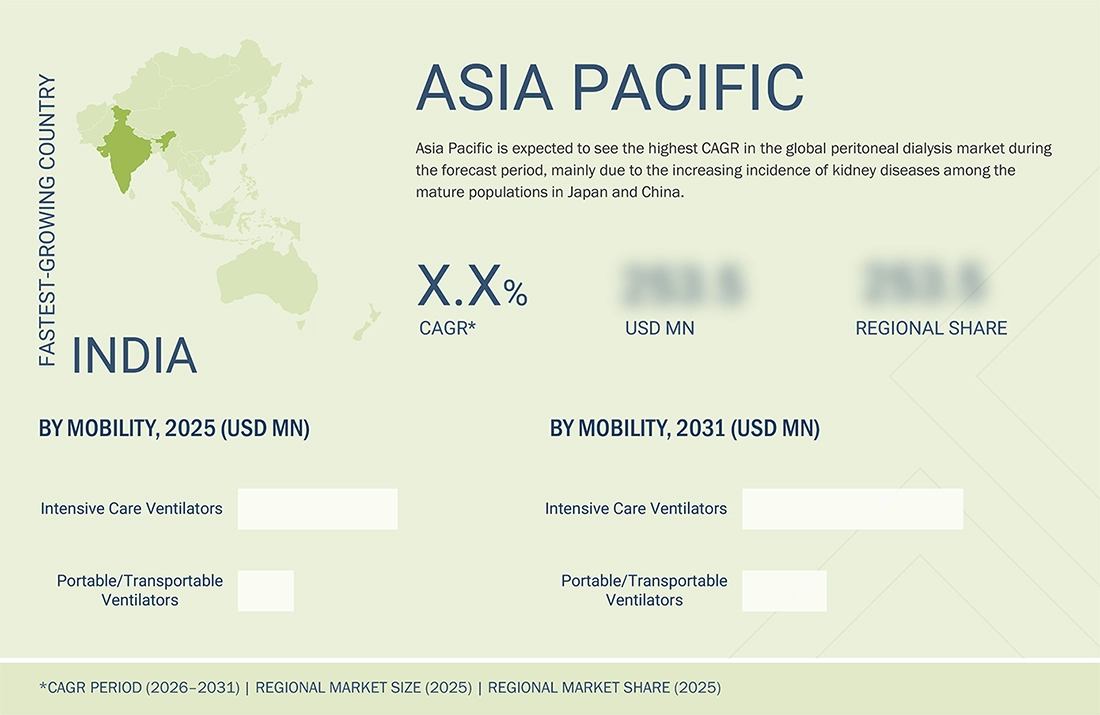
Asia Pacific to be the fastest-growing region in the global ventilators market during the forecast period

Asia Pacific is projected to register the fastest growth in the global ventilators market during the forecast period. Expansion of hospital and ICU infrastructure, government investment in emergency preparedness, increasing critical-care admissions, and rising local production are supporting adoption across China, India, Southeast Asia, and other developing markets. Regional manufacturers are improving affordability, while global suppliers are expanding localized sales, service, and manufacturing capabilities. North America is expected to remain the largest market by value due to its high installed base, advanced clinical infrastructure, premium product mix, and ongoing replacement of legacy ventilator fleets.
ventilators-market Region

VENTILATORS MARKET: COMPANY EVALUATION MATRIX

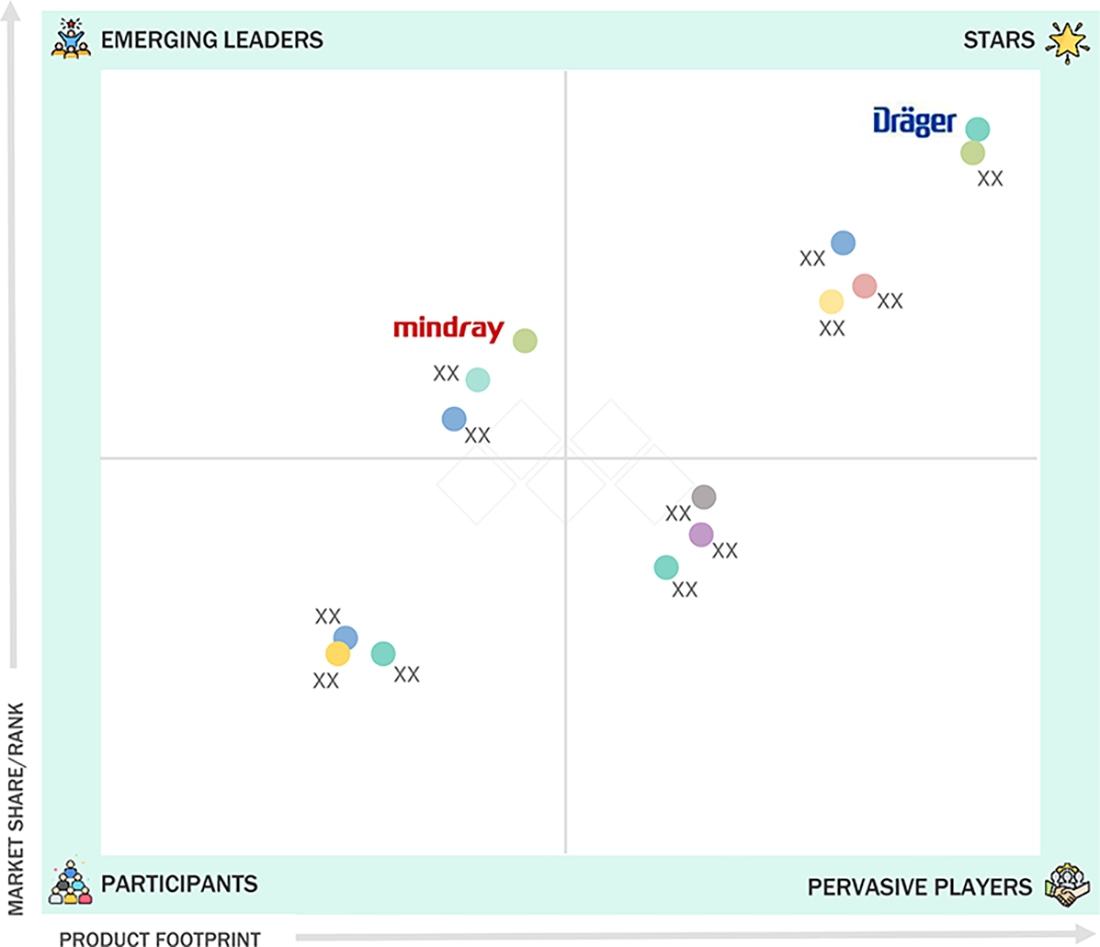
In the ventilators market matrix, Dräger is positioned as a Star Player due to its broad ICU, neonatal, transport, and connected acute-care portfolio, established global service network, and strong hospital installed base. Mindray is positioned as an Emerging Leader, supported by rapid international expansion, competitive pricing, integrated ICU solutions, and growing penetration of high-end hospitals.
ventilators-market Evaluation Metrics

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

KEY MARKET PLAYERS

MARKET SCOPE

REPORT METRIC DETAILS
Market Size Value in 2026 (Value) USD 2.49 BN
Revenue Forecast in 2031 (Value) USD 3.10 BN
Growth Rate CAGR of 4.4%
Years Considered 2024–2031
Base Year 2025
Forecast Period 2026-2031
Units Considered Value (USD Million/Billion), Volume (Thousand Units)
Report Coverage Revenue and Volume Forecast, Company Ranking, Competitive Landscape, Growth Factors, Market Dynamics, Technology Trends, and Recent Developments
Segments Covered Modality, Patient Type, Interface Capability, Mode, Care Settings, and Region
Country Region North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa

WHAT IS IN IT FOR YOU: VENTILATORS MARKET REPORT CONTENT GUIDE
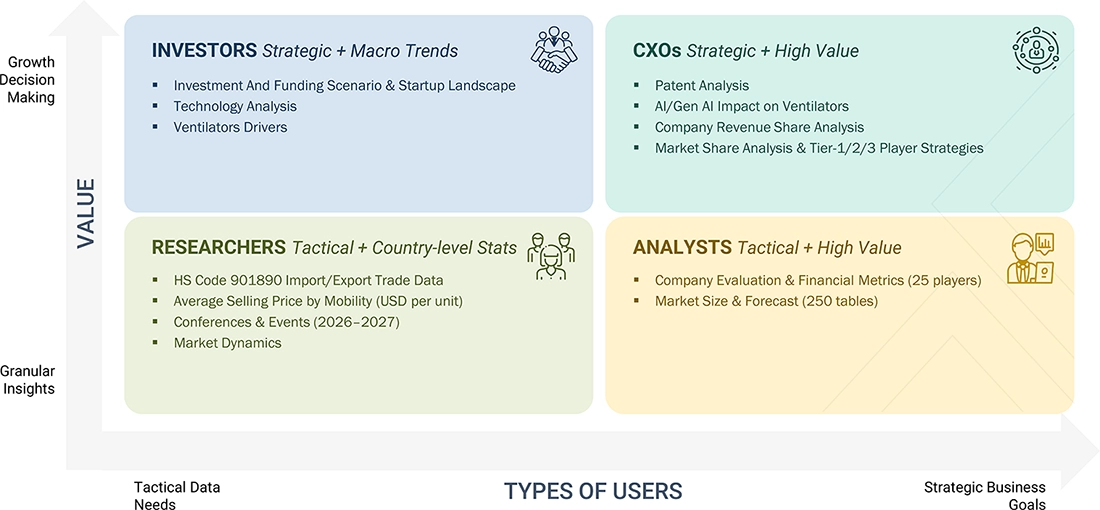
ventilators-market Content Guide

DELIVERED CUSTOMIZATIONS

We have successfully delivered the following deep-dive customizations:

CLIENT REQUEST CUSTOMIZATION DELIVERED VALUE ADDS
Product and Segment Analysis
  • Comparative assessment across intensive-care and portable/transportable ventilators; adult/pediatric and neonatal systems; invasive, non-invasive, and dual-capability interfaces; combined, volume, and pressure modes; and key care settings
  • Analysis includes ASPs, volume trends, replacement cycles, technology adoption, and product positioning
Supports prioritization of high-value and high-growth product categories, portfolio planning, pricing strategy, and identification of underserved clinical applications
Company Information
  • Profiles of major manufacturers including Dräger, Getinge, Mindray, Hamilton Medical, ZOLL, Löwenstein Medical, ResMed, GE HealthCare, and Nihon Kohden
  • Coverage includes product portfolios, financial segment allocation, market-share estimates, service capabilities, partnerships, acquisitions, and product developments
Provides visibility into competitive positioning and helps assess which suppliers are capturing demand following vendor exits and industry consolidation
Geographic Analysis Regional analysis covering North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, with emphasis on ICU/NICU infrastructure, installed-base replacement, local manufacturing, procurement models, and emergency-care investment Supports market-entry and channel planning, identifies high-growth countries, and helps prioritize distribution, service, and localization investments

RECENT DEVELOPMENTS

  • July 2025 : Dräger introduced a new software version for the Connectivity Converter CC300, enabling selected therapeutic devices including Evita ventilators to connect with the SDC ecosystem and hospital information systems.
  • June 2025 : Getinge expanded the Servo-c platform with a neonatal option, increasing its ability to serve adult, pediatric, and neonatal patients on a universal ventilator platform.
  • April 2025 : Air Liquide Medical Systems' Monnal TEO critical-care ventilator received the Red Dot Award for Product Design 2025, supporting the company's positioning in modern ICU ventilation.
  • October 2024 : ZOLL completed the acquisition of selected Vyaire ventilator product lines, including bellavista, fabian, LTV, and 3100 HFOV, and continued their commercial availability.
  • April 2024 : A US federal court entered a consent decree restricting Philips Respironics from manufacturing and distributing certain devices until specified quality-system conditions are met, materially affecting the respiratory-care competitive environment.
  • February 2024 : Medtronic announced that it would wind down and exit its ventilator product line while continuing service and support obligations for the installed base.


Table of Contents

checkmarkExclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.

TITLE
PAGE NO
1
INTRODUCTION


26
2
EXECUTIVE SUMMARY


31
3
PREMIUM INSIGHTS


37
4
MARKET OVERVIEW
Urbanization and pollution drive respiratory market growth, yet skilled workforce shortages pose challenges.


41
 
4.1
INTRODUCTION


4.2
MARKET DYNAMICS


4.2.1
DRIVERS


4.2.1.1
RISE IN RESPIRATORY DISEASES


4.2.1.1.1
INCREASING INCIDENCE OF COPD AND ASTHMA


4.2.1.1.2
GROWING TOBACCO CONSUMPTION


4.2.1.2
URBANIZATION AND RISING POLLUTION LEVELS


4.2.1.3
RISING OBESITY DUE TO SEDENTARY LIFESTYLES


4.2.1.4
GROWING GERIATRIC POPULATION WORLDWIDE


4.2.1.5
INCREASING PREFERENCE FOR HOME CARE SETTINGS


4.2.1.6
RISING NUMBER OF PRETERM BIRTHS


4.2.1.7
OUTBREAK OF INFECTIOUS RESPIRATORY DISEASES


4.2.2
RESTRAINTS


4.2.2.1
SHORTAGE OF SKILLED MEDICAL WORKERS


4.2.2.2
EXCESSIVE PURCHASE OF VENTILATORS DURING COVID-19


4.2.2.3
REIMBURSEMENT CONCERNS


4.2.3
OPPORTUNITIES


4.2.3.1
COST-EFFICIENCY OF HOME CARE SERVICES


4.2.3.2
GROWTH OPPORTUNITIES IN EMERGING ECONOMIES


4.2.4
CHALLENGES


4.2.4.1
LOW AWARENESS AND INADEQUATE RESOURCES IN EMERGING ECONOMIES


4.2.4.2
HARMFUL EFFECTS OF RESPIRATORY DEVICES ON NEONATES


4.2.4.3
SUPPLY CHAIN DISRUPTIONS


4.2.4.4
GLOBAL DEMAND FLUCTUATIONS


4.3
UNMET NEEDS & WHITE SPACES


4.3.1
UNMET NEEDS IN VENTILATORS MARKET


4.3.2
WHITE SPACE OPPORTUNITIES


4.4
INTERCONNECTED MARKETS & CROSS-SECTOR OPPORTUNITIES


4.4.1
INTERCONNECTED MARKETS


4.4.2
CROSS-SECTOR OPPORTUNITIES


4.5
STRATEGIC MOVES BY TIER-1/2/3 PLAYERS


5
INDUSTRY TRENDS
Navigate industry shifts with strategic insights into global ventilator market dynamics and competitive forces.


53
 
5.1
PORTER’S FIVE FORCES ANALYSIS


5.1.1
THREAT OF NEW ENTRANTS


5.1.2
THREAT OF SUBSTITUTES


5.1.3
BARGAINING POWER OF SUPPLIERS


5.1.4
BARGAINING POWER OF BUYERS


5.1.5
INTENSITY OF COMPETITIVE RIVALRY


5.2
MACROECONOMIC OUTLOOK


5.2.1
INTRODUCTION


5.2.2
GDP TRENDS & FORECAST


5.2.3
TRENDS IN GLOBAL VENTILATORS INDUSTRY


5.2.4
TRENDS IN GLOBAL HEALTHCARE & CRITICAL CARE INDUSTRY


5.3
SUPPLY CHAIN ANALYSIS


5.4
VALUE CHAIN ANALYSIS


5.5
ECOSYSTEM ANALYSIS


5.6
PRICING ANALYSIS


5.6.1
INDICATIVE PRICING OF VENTILATORS, BY KEY PLAYER, 2025


5.6.2
AVERAGE SELLING PRICE TREND OF VENTILATORS, BY REGION, 2023–2025


5.7
TRADE ANALYSIS


5.7.1
IMPORT SCENARIO (HS CODE 9018)


5.7.2
EXPORT DATA (HS CODE 9018)


5.8
KEY CONFERENCES & EVENTS, 2026–2027


5.9
TRENDS/DISRUPTIONS IMPACTING CUSTOMERS’ BUSINESSES


5.10
INVESTMENT & FUNDING SCENARIO


5.11
CASE STUDY ANALYSIS


5.11.1
CASE STUDY 1: SCALING AI-ENABLED CRITICAL CARE VENTILATION


5.11.2
CASE STUDY2: EXPANDING HOME RESPIRATORY CARE THROUGH CONNECTED VENTILATION


5.11.3
CASE STUDY 3: ENHANCING ICU RESPIRATORY CARE WITH INTEGRATED VENTILATION


5.12
IMPACT OF 2025 US TARIFFS ON VENTILATORS MARKET


5.12.1
INTRODUCTION


5.12.2
KEY TARIFF RATES


5.12.3
PRICE IMPACT ANALYSIS


5.12.4
IMPACT ON COUNTRIES/REGIONS


5.12.4.1
NORTH AMERICA


5.12.4.2
EUROPE


5.12.4.3
ASIA PACIFIC


5.12.5
END-USE INDUSTRY IMPACT


6
TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
AI-driven innovations revolutionize ventilator systems, paving the way for predictive care and market disruption.


74
 
6.1
KEY EMERGING TECHNOLOGIES


6.1.1
INTELLIGENT & CLOSED-LOOP VENTILATION SYSTEMS


6.2
COMPLEMENTARY TECHNOLOGIES


6.2.1
REMOTE MONITORING SYSTEMS


6.3
TECHNOLOGY/PRODUCT ROADMAP


6.3.1
SHORT-TERM (2025–2027) | FOUNDATION & EARLY COMMERCIALIZATION


6.3.2
1.16.2 MID-TERM (2027–2030) | EXPANSION & STANDARDIZATION


6.3.3
1.16.3 LONG-TERM (2030–2035+) | MASS COMMERCIALIZATION & DISRUPTION


6.4
PATENT ANALYSIS


6.4.1
INSIGHTS: JURISDICTION & TOP APPLICANT ANALYSIS


6.5
FUTURE APPLICATIONS


6.5.1
AI-ENABLED REMOTE VENTILATION MANAGEMENT & PREDICTIVE CARE


6.5.2
SMART RESPIRATORY CARE ECOSYSTEMS


6.5.3
ADVANCED VENTILATOR CONSUMABLES & LUNG-PROTECTIVE SOLUTIONS


6.6
IMPACT OF AI/GEN AI ON VENTILATORS MARKET


6.6.1
TOP USE CASES & MARKET POTENTIAL


6.6.2
CASE STUDIES OF AI IMPLEMENTATION IN VENTILATORS MARKET


6.6.3
INTERCONNECTED ADJACENT ECOSYSTEMS & IMPACT ON MARKET PLAYERS


6.6.4
CLIENTS’ READINESS TO ADOPT GENERATIVE AI IN VENTILATORS MARKET


7
REGULATORY LANDSCAPE
Navigate complex global regulations and standards with region-specific compliance insights.


83
 
7.1
REGIONAL REGULATIONS & COMPLIANCE


7.1.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


7.1.2
INDUSTRY STANDARDS


8
CUSTOMER LANDSCAPE & BUYER BEHAVIOR
Unlock profitability by understanding unmet needs and key buying criteria in ventilator markets.


87
 
8.1
DECISION-MAKING PROCESS


8.2
BUYER STAKEHOLDERS & BUYING EVALUATION CRITERIA


8.2.1
KEY STAKEHOLDERS IN BUYING PROCESS


8.2.2
BUYING CRITERIA


8.3
ADOPTION BARRIERS & INTERNAL CHALLENGES


8.4
UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES


8.5
MARKET PROFITABILITY


8.5.1
REVENUE POTENTIAL


8.5.2
COST DYNAMICS


8.5.3
MARGIN OPPORTUNITIES IN KEY APPLICATIONS


9
VENTILATORS MARKET, BY MOBILITY
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million and Units | 16 Data Tables


92
 
9.1
INTRODUCTION


9.2
INTENSIVE CARE VENTILATORS


9.2.1
HIGH-END ICU VENTILATORS


9.2.1.1
RISING HEALTHCARE EXPENDITURE AND IMPROVING INFRASTRUCTURE IN EMERGING ECONOMIES TO DRIVE MARKET


9.2.2
MID-END ICU VENTILATORS


9.2.2.1
HIGHER AFFORDABILITY AND ACCESSIBILITY TO DRIVE MARKET


9.2.3
BASIC ICU VENTILATORS


9.2.3.1
GROWING USE IN AMBULATORY CARE CENTERS TO DRIVE MARKET


9.3
PORTABLE/TRANSPORTABLE VENTILATORS


9.3.1
INCREASING DEMAND FOR COMPACT DEVICES FOR MECHANICAL VENTILATION TO DRIVE MARKET


10
VENTILATORS MARKET, BY TYPE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 5 Data Tables


104
 
10.1
INTRODUCTION


10.2
ADULT & PEDIATRIC VENTILATORS


10.2.1
GROWING GERIATRIC POPULATION TO DRIVE MARKET


10.3
NEONATAL & INFANT VENTILATORS


10.3.1
TECHNOLOGICAL ADVANCEMENTS IN NEONATAL MONITORS TO DRIVE MARKET


11
VENTILATORS MARKET, BY INTERFACE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 4 Data Tables


108
 
11.1
INTRODUCTION


11.2
DUAL-CAPABILITY VENTILATION


11.2.1
RISING PREVALENCE OF COPD & ARDS TO DRIVE MARKET GROWTH


11.3
NON-INVASIVE VENTILATION


11.3.1
RELIABILITY OF MECHANICAL DESIGNS TO SUPPORT MARKET GROWTH


11.4
INVASIVE VENTILATION


11.4.1
RISING PREVALENCE OF RESPIRATORY DISEASES TO DRIVE MARKET


12
VENTILATORS MARKET, BY MODE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 7 Data Tables


113
 
12.1
INTRODUCTION


12.2
COMBINED-MODE VENTILATORS


12.2.1
COMBINED BENEFITS OF VOLUME-TARGETED AND PRESSURE-TARGETED VENTILATORS TO DRIVE MARKET


12.3
VOLUME-MODE VENTILATORS


12.3.1
INCREASING DEMAND FOR ADVANCED RESPIRATORY SUPPORT SYSTEMS IN HEALTHCARE SETTINGS TO DRIVE MARKET


12.4
PRESSURE-MODE VENTILATORS


12.4.1
PRESET INSPIRATORY PRESSURE MAINTENANCE AND BETTER PATIENT COMFORT TO DRIVE MARKET


12.5
OTHER VENTILATOR MODES


13
VENTILATORS MARKET, BY CARE SETTING
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 5 Data Tables


120
 
13.1
INTRODUCTION


13.2
HOSPITALS & CLINICS


13.2.1
RISING DEMAND FOR VENTILATORS IN PRIVATE HOSPITALS TO DRIVE MARKET


13.3
AMBULATORY CARE CENTERS


13.3.1
INCREASING NUMBER OF OUTPATIENT VISITS TO DRIVE MARKET


13.4
EMERGENCY MEDICAL SERVICES


13.4.1
HIGH INCIDENCE OF TRAUMA INJURIES TO DRIVE MARKET


13.5
HOME CARE SETTINGS


13.5.1
EMERGENCE OF REMOTE PATIENT MONITORING DEVICES TO DRIVE MARKET


14
VENTILATORS MARKET, BY REGION
Comprehensive coverage of 8 Regions with country-level deep-dive of 15 Countries | 149 Data Tables.


126
 
14.1
INTRODUCTION


14.2
NORTH AMERICA


14.2.1
US


14.2.1.1
HIGH PREVALENCE OF COPD TO DRIVE THE MARKET


14.2.2
CANADA


14.2.2.1
INCREASING INCIDENCE OF ASTHMA TO DRIVE MARKET GROWTH


14.3
EUROPE


14.3.1
GERMANY


14.3.1.1
RISING HEALTHCARE SPENDING TO INCREASE DEMAND FOR HIGH-END VENTILATORS


14.3.2
FRANCE


14.3.2.1
HIGHLY ADVANCED HEALTHCARE SYSTEM TO DRIVE ADOPTION OF VENTILATORS IN HOSPITALS


14.3.3
UK


14.3.3.1
INCREASING HEALTHCARE EXPENDITURE TO DRIVE MARKET GROWTH


14.3.4
ITALY


14.3.4.1
HIGH GROWTH IN GERIATRIC POPULATION AND SUBSEQUENT RISE IN AGE-RELATED RESPIRATORY DISEASES TO DRIVE MARKET


14.3.5
SPAIN


14.3.5.1
HIGH BURDEN ON STATE-RUN HEALTH INSURANCE SYSTEM AND POOR HEALTHCARE INFRASTRUCTURE TO RESTRAIN MARKET GROWTH


14.3.6
NETHERLANDS


14.3.6.1
RISING PREVALENCE OF RESPIRATORY DISEASES TO DRIVE MARKET


14.3.7
REST OF EUROPE


14.4
ASIA PACIFIC


14.4.1
JAPAN


14.4.1.1
ESTABLISHED HEALTHCARE SYSTEM TO INCREASE ADOPTION OF RESPIRATORY CARE DEVICES


14.4.2
CHINA


14.4.2.1
HIGH PREVALENCE OF COPD AND LUNG CANCER TO PROPEL DEMAND


14.4.3
INDIA


14.4.3.1
RISING FOCUS OF GLOBAL PLAYERS ON INDIAN MARKET TO DRIVE ADOPTION OF ADVANCED VENTILATORS


14.4.4
AUSTRALIA


14.4.4.1
HIGH PREVALENCE OF CHRONIC LUNG DISEASES TO DRIVE DEMAND FOR VENTILATORS


14.4.5
REST OF ASIA PACIFIC


14.5
LATIN AMERICA


14.5.1
BRAZIL


14.5.1.1
HEALTHCARE INFRASTRUCTURE IMPROVEMENT TO SUPPORT MARKET GROWTH


14.5.2
MEXICO


14.5.2.1
RISING OBESITY RATE TO INCREASE INCIDENCE OF RESPIRATORY DISEASES


14.5.3
ARGENTINA


14.5.3.1
INCIDENCE OF SEVERE ACUTE RESPIRATORY INFECTIONS TO DRIVE MARKET


14.5.4
REST OF LATIN AMERICA


14.6
MIDDLE EAST & AFRICA


14.6.1
RISING HEALTHCARE SPENDING AND PRESENCE OF MEDICAL DEVICE MANUFACTURING COMPANIES TO DRIVE MARKET


14.7
GCC COUNTRIES


14.7.1
HIGHER DISPOSABLE INCOME AND INCREASED GOVERNMENT HEALTHCARE EXPENDITURE TO PROPEL MARKET GROWTH


15
COMPETITIVE LANDSCAPE
Discover top players and emerging stars shaping the ventilators market's competitive dynamics.


187
 
15.1
OVERVIEW


15.1.1
OVERVIEW OF STRATEGIES ADOPTED BY PLAYERS IN VENTILATORS MARKET


15.2
REVENUE ANALYSIS, 2021–2025


15.3
MARKET SHARE ANALYSIS, 2025


15.4
COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025


15.4.1
STARS


15.4.2
EMERGING LEADERS


15.4.3
PERVASIVE PLAYERS


15.4.4
PARTICIPANTS


15.4.5
COMPANY FOOTPRINT: KEY PLAYERS, 2025


15.4.5.1
COMPANY FOOTPRINT


15.4.5.2
COMPANY FOOTPRINT


15.4.5.3
MOBILITY FOOTPRINT


15.4.5.4
TYPE FOOTPRINT


15.4.5.5
INTERFACE FOOTPRINT


15.4.5.6
MODE FOOTPRINT


15.5
COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025


15.5.1
PROGRESSIVE COMPANIES


15.5.2
RESPONSIVE COMPANIES


15.5.3
DYNAMIC COMPANIES


15.5.4
STARTING BLOCKS


15.5.5
COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025


15.5.5.1
DETAILED LIST OF KEY STARTUPS/SMES


15.5.5.2
COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES


15.6
R&D EXPENDITURE


15.7
COMPANY VALUATION & FINANCIAL METRICS


15.7.1
FINANCIAL METRICS


15.7.2
COMPANY VALUATION


15.8
BRAND/PRODUCT COMPARISON


15.9
COMPETITIVE SCENARIO


15.9.1
PRODUCT LAUNCHES


15.9.2
DEALS


15.9.3
OTHER DEVELOPMENTS


16
COMPANY PROFILES
In-depth Company Profiles of Leading Market Players with detailed Business Overview, Product and Service Portfolio, Recent Developments, and Unique Analyst Perspective (MnM View)


210
 
16.1
KEY PLAYERS


16.1.1
DRÄGERWERK AG & CO. KGAA


16.1.1.1
BUSINESS OVERVIEW


16.1.1.2
PRODUCTS OFFERED


16.1.1.3
RECENT DEVELOPMENTS


16.1.1.3.1
PRODUCT LAUNCHES


16.1.1.3.2
DEALS


16.1.1.3.3
OTHER DEVELOPMENTS


16.1.1.4
MNM VIEW


16.1.1.4.1
KEY STRENGTHS


16.1.1.4.2
STRATEGIC CHOICES


16.1.1.4.3
WEAKNESSES & COMPETITIVE THREATS


16.1.2
GETINGE AB


16.1.3
SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD.


16.1.4
ASAHI KASEI CORPORATION


16.1.5
RESMED INC.


16.1.6
KONINKLIJKE PHILIPS N.V.


16.1.7
ICU MEDICAL INC.


16.1.8
AIR LIQUIDE


16.1.9
FLEXICARE (GROUP) LIMITED


16.1.10
NIHON KOHDEN CORPORATION


16.1.11
GE HEALTHCARE


16.1.12
HAMILTON MEDICAL


16.1.13
LÖWENSTEIN MEDICAL TECHNOLOGY GMBH & CO. KG


16.2
OTHER PLAYERS


16.2.1
SKANRAY TECHNOLOGIES, LTD.


16.2.2
METRAN CO., LTD.


16.2.3
MAGNAMED


16.2.4
LEISTUNG INGENIERÍA SRL


16.2.5
AIRON CORPORATION


16.2.6
TRITON ELECTRONIC SYSTEMS LTD.


16.2.7
BIO-MED DEVICES, INC.


16.2.8
HEYER MEDICAL AG


16.2.9
AGVA HEALTHCARE


16.2.10
SCHILLER AG


16.2.11
AVI HEALTHCARE LIMITED


16.2.12
MAGNAMEDIA B.V.


16.2.13
BREAS MEDICAL AB


16.2.14
BEIJING AEONMED CO., LTD


16.2.15
SHENZHEN COMEN MEDICAL INSTRUMENTS CO., LTD


16.2.16
REACT HEALTH


16.2.17
MICOMME MEDICAL TECHNOLOGY DEVELOPMENT CO., LTD


16.2.18
CHIRANA MEDICAL, A.S.


17
RESEARCH METHODOLOGY


270
 
17.1
RESEARCH DATA


17.1.1
SECONDARY RESEARCH


17.1.2
PRIMARY RESEARCH


17.2
MARKET SIZE ESTIMATION


17.3
MARKET BREAKDOWN & DATA TRIANGULATION


17.4
RESEARCH ASSUMPTIONS


17.5
RESEARCH LIMITATIONS


17.5.1
SCOPE-RELATED LIMITATIONS


17.5.2
METHODOLOGY-RELATED LIMITATIONS


17.6
RISK ASSESSMENT


18
APPENDIX


285
 
18.1
DISCUSSION GUIDE


18.2
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL


18.3
CUSTOMIZATION OPTIONS


18.4
RELATED REPORTS


18.5
AUTHOR DETAILS


LIST OF TABLES


TABLE 1
STANDARD CURRENCY CONVERSION RATES (USD)


TABLE 2
DISORDERS AND DEATHS CAUSED BY SMOKING, 2024


TABLE 3
VENTILATORS MARKET: PORTER’S FIVE FORCES ANALYSIS


TABLE 4
GDP PERCENTAGE CHANGE, BY KEY COUNTRY, 2021–2030


TABLE 5
INDICATIVE PRICING OF VENTILATORS, BY KEY PLAYER, 2025 (USD)


TABLE 6
AVERAGE SELLING PRICE TREND OF HIGH-END VENTILATORS, BY REGION, 2023–2025 (USD)


TABLE 7
IMPORT DATA FOR VENTILATOR PRODUCTS UNDER HS CODE 9018, BY COUNTRY, 2021–2025 (USD THOUSAND)


TABLE 8
EXPORT DATA FOR VENTILATOR PRODUCTS UNDER HS CODE 9018, BY COUNTRY, 2021–2025 (USD THOUSAND)


TABLE 9
VENTILATORS MARKET: DETAILED LIST OF KEY CONFERENCES & EVENTS (2026–2027)


TABLE 10
US-ADJUSTED RECIPROCAL TARIFF RATES “RECIPROCAL TARIFF, ADJUSTED" FOR THE TOP 20 TRADE PARTNERS


TABLE 11
KEY PRODUCT-RELATED TARIFF EFFECTIVE FOR VENTILATORS


TABLE 12
VENTILATORS MARKET: CASE STUDIES RELATED TO AI IMPLEMENTATION


TABLE 13
INTERCONNECTED ADJACENT ECOSYSTEMS & IMPACT ON MARKET PLAYERS


TABLE 14
NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 15
EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 16
ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 17
LATIN AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 18
MIDDLE EAST & AFRICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 19
GLOBAL STANDARDS IN VENTILATORS MARKET


TABLE 20
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR VENTILATORS


TABLE 21
KEY BUYING CRITERIA FOR VENTILATORS


TABLE 22
VENTILATORS MARKET: UNMET NEEDS/END-USER EXPECTATIONS


TABLE 23
VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 24
INTENSIVE CARE VENTILATORS: KEY PRODUCTS


TABLE 25
INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 26
INTENSIVE CARE VENTILATORS MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 27
INTENSIVE CARE VENTILATORS MARKET, BY REGION, 2024–2031 (THOUSAND UNITS)


TABLE 28
HIGH-END ICU VENTILATORS: KEY PRODUCTS


TABLE 29
HIGH-END ICU VENTILATORS MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 30
HIGH-END ICU VENTILATORS MARKET, BY REGION, 2024–2031 (THOUSAND UNITS)


TABLE 31
MID-END ICU VENTILATORS: KEY PRODUCTS


TABLE 32
MID-END ICU VENTILATORS MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 33
MID-END ICU VENTILATORS MARKET, BY REGION, 2024–2031 (THOUSAND UNITS)


TABLE 34
BASIC ICU VENTILATORS MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 35
BASIC ICU VENTILATORS MARKET, BY REGION, 2024–2031 (THOUSAND UNITS)


TABLE 36
PORTABLE/TRANSPORTABLE VENTILATORS: KEY PRODUCTS


TABLE 37
PORTABLE/TRANSPORTABLE VENTILATORS MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 38
PORTABLE/TRANSPORTABLE VENTILATORS MARKET, BY REGION, 2024–2031 (THOUSAND UNITS)


TABLE 39
VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 40
ADULT & PEDIATRIC VENTILATORS: KEY PRODUCTS


TABLE 41
ADULT & PEDIATRIC VENTILATORS MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 42
NEONATAL & INFANT VENTILATORS: KEY PRODUCTS


TABLE 43
NEONATAL & INFANT VENTILATORS MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 44
VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 45
DUAL-CAPABILITY VENTILATION MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 46
NON-INVASIVE VENTILATION MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 47
INVASIVE VENTILATION MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 48
VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION)


TABLE 49
COMBINED-MODE VENTILATORS: KEY PRODUCTS


TABLE 50
COMBINED-MODE VENTILATORS MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 51
VOLUME-MODE VENTILATORS MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 52
PRESSURE-MODE VENTILATORS: KEY PRODUCTS


TABLE 53
PRESSURE-MODE VENTILATORS MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 54
OTHER VENTILATOR MODES MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 55
VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 56
VENTILATORS MARKET FOR HOSPITALS & CLINICS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 57
VENTILATORS MARKET FOR AMBULATORY CARE CENTERS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 58
VENTILATORS MARKET FOR EMERGENCY MEDICAL SERVICES, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 59
VENTILATORS MARKET FOR HOME CARE SETTINGS, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 60
VENTILATORS MARKET, BY REGION, 2024–2031 (USD MILLION)


TABLE 61
NORTH AMERICA: VENTILATORS MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 62
NORTH AMERICA: VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 63
NORTH AMERICA: INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 64
NORTH AMERICA: VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 65
NORTH AMERICA: VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 66
NORTH AMERICA: VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION)


TABLE 67
NORTH AMERICA: VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 68
US: VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 69
US: INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 70
US: VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 71
US: VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 72
US: VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION)


TABLE 73
US: VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 74
CANADA: VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 75
CANADA: INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 76
CANADA: VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 77
CANADA: VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 78
CANADA: VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION)


TABLE 79
CANADA: VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 80
EUROPE: VENTILATORS MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 81
EUROPE: VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 82
EUROPE: INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 83
EUROPE: VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 84
EUROPE: VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 85
EUROPE: VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION)


TABLE 86
EUROPE: VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 87
GERMANY: VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 88
GERMANY: INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 89
GERMANY: VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 90
GERMANY: VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 91
GERMANY: VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION)


TABLE 92
GERMANY: VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 93
FRANCE: VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 94
FRANCE: INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 95
FRANCE: VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 96
FRANCE: VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 97
FRANCE: VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION)


TABLE 98
FRANCE: VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 99
UK: VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 100
UK: INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 101
UK: VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 102
UK: VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 103
UK: VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION)


TABLE 104
UK: VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 105
ITALY: VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 106
ITALY: INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 107
ITALY: VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 108
ITALY: VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 109
ITALY: VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION)


TABLE 110
ITALY: VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 111
SPAIN: VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 112
SPAIN: INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 113
SPAIN: VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 114
SPAIN: VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 115
SPAIN: VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION)


TABLE 116
SPAIN: VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 117
NETHERLANDS: VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 118
NETHERLANDS: INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 119
NETHERLANDS: VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 120
NETHERLANDS: VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 121
NETHERLANDS: VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION)


TABLE 122
NETHERLANDS: VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 123
REST OF EUROPE: VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 124
REST OF EUROPE: INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 125
REST OF EUROPE: VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 126
REST OF EUROPE: VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 127
REST OF EUROPE: VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION)


TABLE 128
REST OF EUROPE: VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 129
ASIA PACIFIC: VENTILATORS MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 130
ASIA PACIFIC: VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 131
ASIA PACIFIC: INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 132
ASIA PACIFIC: VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 133
ASIA PACIFIC: VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 134
ASIA PACIFIC: VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION)


TABLE 135
ASIA PACIFIC: VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 136
JAPAN: VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 137
JAPAN: INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 138
JAPAN: VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 139
JAPAN: VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 140
JAPAN: VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION)


TABLE 141
JAPAN: VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 142
CHINA: VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 143
CHINA: INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 144
CHINA: VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 145
CHINA: VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 146
CHINA: VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION).


TABLE 147
CHINA: VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 148
INDIA: VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 149
INDIA: INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 150
INDIA: VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 151
INDIA: VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 152
INDIA: VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION)


TABLE 153
INDIA: VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 154
AUSTRALIA: VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 155
AUSTRALIA: INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 156
AUSTRALIA: VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 157
AUSTRALIA: VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 158
AUSTRALIA: VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION)


TABLE 159
AUSTRALIA: VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 160
REST OF ASIA PACIFIC: VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 161
REST OF ASIA PACIFIC: INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 162
REST OF ASIA PACIFIC: VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 163
REST OF ASIA PACIFIC: VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 164
REST OF ASIA PACIFIC: VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION)


TABLE 165
REST OF ASIA PACIFIC: VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 166
LATIN AMERICA: VENTILATORS MARKET, BY COUNTRY, 2024–2031 (USD MILLION)


TABLE 167
LATIN AMERICA: VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 168
LATIN AMERICA: INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 169
LATIN AMERICA: VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 170
LATIN AMERICA: VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 171
LATIN AMERICA: VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION)


TABLE 172
LATIN AMERICA: VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 173
BRAZIL: VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 174
BRAZIL: INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 175
BRAZIL: VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 176
BRAZIL: VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 177
BRAZIL: VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION)


TABLE 178
BRAZIL: VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 179
MEXICO: VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 180
MEXICO: INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 181
MEXICO: VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 182
MEXICO: VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 183
MEXICO: VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION)


TABLE 184
MEXICO: VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 185
ARGENTINA: VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 186
ARGENTINA: INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 187
ARGENTINA: VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 188
ARGENTINA: VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 189
ARGENTINA: VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION)


TABLE 190
ARGENTINA: VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 191
REST OF LATIN AMERICA: VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 192
REST OF LATIN AMERICA: INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 193
REST OF LATIN AMERICA: VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 194
REST OF LATIN AMERICA: VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 195
REST OF LATIN AMERICA: VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION)


TABLE 196
REST OF LATIN AMERICA: VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 197
MIDDLE EAST & AFRICA: VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 198
MIDDLE EAST & AFRICA: INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 199
MIDDLE EAST & AFRICA: VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 200
MIDDLE EAST & AFRICA: VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 201
MIDDLE EAST & AFRICA: VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION)


TABLE 202
MIDDLE EAST & AFRICA: VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 203
GCC COUNTRIES: VENTILATORS MARKET, BY MOBILITY, 2024–2031 (USD MILLION)


TABLE 204
GCC COUNTRIES: INTENSIVE CARE VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 205
GCC COUNTRIES: VENTILATORS MARKET, BY TYPE, 2024–2031 (USD MILLION)


TABLE 206
GCC COUNTRIES: VENTILATORS MARKET, BY INTERFACE, 2024–2031 (USD MILLION)


TABLE 207
GCC COUNTRIES: VENTILATORS MARKET, BY MODE, 2024–2031 (USD MILLION)


TABLE 208
GCC COUNTRIES: VENTILATORS MARKET, BY CARE SETTING, 2024–2031 (USD MILLION)


TABLE 209
VENTILATORS MARKET: DEGREE OF COMPETITION


TABLE 210
VENTILATORS MARKET: REGION FOOTPRINT


TABLE 211
VENTILATORS MARKET: MOBILITY FOOTPRINT


TABLE 212
VENTILATORS MARKET: TYPE FOOTPRINT


TABLE 213
VENTILATORS MARKET: INTERFACE FOOTPRINT


TABLE 214
VENTILATORS MARKET: MODE FOOTPRINT


TABLE 215
VENTILATORS MARKET: DETAILED LIST OF KEY STARTUPS/SMES


TABLE 216
VENTILATOR MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES


TABLE 217
VENTILATORS MARKET: PRODUCT LAUNCHES, JANUARY 2021–JUNE 2026


TABLE 218
VENTILATORS MARKET: DEALS, JANUARY 2021–JUNE 2026


TABLE 219
VENTILATORS MARKET: OTHER DEVELOPMENTS, JANUARY 2021–JUNE 2026


TABLE 220
DRÄGERWERK AG & CO. KGAA: COMPANY OVERVIEW


TABLE 221
DRÄGERWERK AG & CO. KGAA: PRODUCTS OFFERED


TABLE 222
DRÄGERWERK AG & CO. KGAA: PRODUCT LAUNCHES, JANUARY 2021–JUNE 2026


TABLE 223
DRÄGERWERK AG & CO. KGAA: DEALS, JANUARY 2021–JUNE 2026


TABLE 224
DRÄGERWERK AG & CO. KGAA: OTHER DEVELOPMENTS, JANUARY 2021–JUNE 2026


TABLE 225
GETINGE AB: COMPANY OVERVIEW


TABLE 226
GETINGE AB: PRODUCTS OFFERED


TABLE 227
GETINGE AB: PRODUCT LAUNCHES, JANUARY 2021–JUNE 2026


TABLE 228
GETINGE AB: DEALS, JANUARY 2021–JUNE 2026


TABLE 229
GETINGE AB: OTHER DEVELOPMENTS, JANUARY 2021–JUNE 2026


TABLE 230
SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD.: COMPANY OVERVIEW


TABLE 231
SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD.: PRODUCTS OFFERED


TABLE 232
SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD.: PRODUCT LAUNCHES, JANUARY 2021–JUNE 2026


TABLE 233
SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD.: OTHER DEVELOPMENTS, JANUARY 2021–JUNE 2026


TABLE 234
ASAHI KASEI CORPORATION: COMPANY OVERVIEW


TABLE 235
ASAHI KASEI CORPORATION: PRODUCTS OFFERED


TABLE 236
ASAHI KASEI CORPORATION: DEALS, JANUARY 2021–JUNE 2026


TABLE 237
RESMED INC.: COMPANY OVERVIEW


TABLE 238
RESMED INC.: PRODUCTS OFFERED


TABLE 239
RESMED INC.: PRODUCT LAUNCHES, JANUARY 2021–JUNE 2026


TABLE 240
RESMED INC.: DEALS, JANUARY 2021–JUNE 2026


TABLE 241
RESMED INC.: OTHER DEVELOPMENTS, JANUARY 2021–JUNE 2026


TABLE 242
KONINKLIJKE PHILIPS N.V.: COMPANY OVERVIEW


TABLE 243
KONINKLIJKE PHILIPS N.V.: PRODUCTS OFFERED


TABLE 244
KONINKLIJKE PHILIPS N.V.: OTHER DEVELOPMENTS, JANUARY 2021–JUNE 2026


TABLE 245
ICU MEDICAL INC.: COMPANY OVERVIEW


TABLE 246
ICU MEDICAL INC.: PRODUCTS OFFERED


TABLE 247
ICU MEDICAL INC.: DEALS, JANUARY 2021–JUNE 2026


TABLE 248
AIR LIQUIDE: COMPANY OVERVIEW


TABLE 249
AIR LIQUIDE: PRODUCTS OFFERED


TABLE 250
FLEXICARE (GROUP) LIMITED: COMPANY OVERVIEW


TABLE 251
FLEXICARE (GROUP) LIMITED: PRODUCTS OFFERED


TABLE 252
FLEXICARE (GROUP) LIMITED: DEALS, JANUARY 2021–JUNE 2026


TABLE 253
NIHON KOHDEN CORPORATION: COMPANY OVERVIEW


TABLE 254
NIHON KOHDEN CORPORATION: PRODUCTS OFFERED


TABLE 255
NIHON KOHDEN CORPORATION: PRODUCT LAUNCHES, JANUARY 2021–JUNE 2026


TABLE 256
GE HEALTHCARE: COMPANY OVERVIEW


TABLE 257
GE HEALTHCARE: PRODUCTS OFFERED


TABLE 258
HAMILTON MEDICAL: COMPANY OVERVIEW


TABLE 259
HAMILTON MEDICAL: PRODUCTS OFFERED


TABLE 260
HAMILTON MEDICAL: PRODUCT UPGRADES, JANUARY 2021–JUNE 2026


TABLE 261
HAMILTON MEDICAL: DEALS, JANUARY 2021–JUNE 2026


TABLE 262
HAMILTON MEDICAL: OTHER DEVELOPMENTS, JANUARY 2021–JUNE 2026


TABLE 263
RISK ASSESSMENT


LIST OF FIGURES


FIGURE 1
VENTILATORS MARKET SEGMENTATION & REGIONS COVERED


FIGURE 2
KEY INSIGHTS & MARKET HIGHLIGHTS


FIGURE 3
VENTILATORS MARKET, 2024–2031


FIGURE 4
MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN VENTILATORS MARKET


FIGURE 5
DISRUPTIVE TRENDS IMPACTING GROWTH OF VENTILATORS MARKET


FIGURE 6
HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS IN VENTILATORS MARKET, 2026


FIGURE 7
ASIA PACIFIC TO REGISTER HIGHEST GROWTH DURING FORECAST PERIOD


FIGURE 8
RISING PREVALENCE OF CHRONIC RESPIRATORY DISEASES TO DRIVE MARKET


FIGURE 9
INTENSIVE CARE VENTILATORS SEGMENT ACCOUNTED FOR LARGEST SHARE IN 2025


FIGURE 10
INDIA TO REGISTER HIGHEST GROWTH DURING FORECAST PERIOD


FIGURE 11
NORTH AMERICA WILL DOMINATE MARKET TILL 2031


FIGURE 12
EMERGING ECONOMIES TO REGISTER HIGHER GROWTH RATES OVER FORECAST PERIOD


FIGURE 13
VENTILATORS MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES


FIGURE 14
ANNUAL DEATHS CAUSED BY HOUSEHOLD AND AMBIENT AIR POLLUTION, BY DISEASE TYPE, 2024


FIGURE 15
GLOBAL GERIATRIC POPULATION, BY COUNTRY, 2015 VS. 2020 VS. 2023


FIGURE 16
VENTILATORS MARKET: PORTER’S FIVE FORCES ANALYSIS


FIGURE 17
VENTILATORS MARKET: SUPPLY CHAIN ANALYSIS


FIGURE 18
VENTILATORS MARKET: VALUE CHAIN ANALYSIS


FIGURE 19
VENTILATORS MARKET: ECOSYSTEM ANALYSIS


FIGURE 20
AVERAGE SELLING PRICE TREND OF HIGH-END VENTILATORS, BY REGION, 2023–2025 (USD)


FIGURE 21
TRENDS/DISRUPTIONS IMPACTING CUSTOMERS’ BUSINESSES


FIGURE 22
VENTILATORS MARKET: INVESTMENT & FUNDING SCENARIO


FIGURE 23
NUMBER OF PATENTS PUBLISHED (JANUARY 2016-JULY 2026)


FIGURE 24
TOP APPLICANT COUNTRIES/REGIONS FOR VENTILATORS (JANUARY 2016− JULY 2026)


FIGURE 25
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR VENTILATORS


FIGURE 26
KEY BUYING CRITERIA FOR VENTILATORS


FIGURE 27
NORTH AMERICA: VENTILATORS MARKET SNAPSHOT


FIGURE 28
ASIA PACIFIC: VENTILATORS MARKET SNAPSHOT


FIGURE 29
OVERVIEW OF STRATEGIES DEPLOYED BY KEY COMPANIES


FIGURE 30
REVENUE ANALYSIS OF KEY PLAYERS OPERATING IN VENTILATORS MARKET, 2021–2025


FIGURE 31
MARKET SHARE ANALYSIS OF KEY PLAYERS IN VENTILATORS MARKET, 2025


FIGURE 32
VENTILATORS MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025


FIGURE 33
VENTILATORS MARKET: COMPANY FOOTPRINT


FIGURE 34
VENTILATORS MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025


FIGURE 35
R&D EXPENDITURE OF KEY PLAYERS IN VENTILATORS MARKET (2024 VS. 2025)


FIGURE 36
EV/EBITDA OF KEY VENDORS


FIGURE 37
YEAR-TO-DATE (YTD) PRICE TOTAL RETURN AND 5-YEAR STOCK BETA OF KEY VENDORS


FIGURE 38
BRAND/PRODUCT COMPARATIVE ANALYSIS


FIGURE 39
DRÄGERWERK AG & CO. KGAA: COMPANY SNAPSHOT (2025)


FIGURE 40
GETINGE AB: COMPANY SNAPSHOT (2025)


FIGURE 41
SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD.: COMPANY SNAPSHOT (2025)


FIGURE 42
ASAHI KASEI CORPORATION: COMPANY SNAPSHOT (2025)


FIGURE 43
RESMED INC.: COMPANY SNAPSHOT (2025)


FIGURE 44
KONINKLIJKE PHILIPS N.V.: COMPANY SNAPSHOT (2025)


FIGURE 45
SMITHS GROUP PLC: COMPANY SNAPSHOT (2025)


FIGURE 46
AIR LIQUIDE: COMPANY SNAPSHOT (2025)


FIGURE 47
NIHON KOHDEN CORPORATION: COMPANY SNAPSHOT (2025)


FIGURE 48
GE HEALTHCARE: COMPANY SNAPSHOT (2025)


FIGURE 49
RESEARCH DESIGN


FIGURE 50
KEY DATA FROM SECONDARY SOURCES


FIGURE 51
PRIMARY SOURCES


FIGURE 52
KEY DATA FROM PRIMARY SOURCES


FIGURE 53
KEY INDUSTRY INSIGHTS


FIGURE 54
BREAKDOWN OF PRIMARY INTERVIEWS: SUPPLY-SIDE & DEMAND-SIDE PARTICIPANTS


FIGURE 55
BREAKDOWN OF PRIMARY INTERVIEWS (SUPPLY SIDE): BY COMPANY TYPE, DESIGNATION, AND REGION


FIGURE 56
BREAKDOWN OF PRIMARY INTERVIEWS (DEMAND SIDE): BY CARE SETTING, DESIGNATION, AND REGION


FIGURE 57
SUPPLY-SIDE MARKET SIZE ESTIMATION: REVENUE SHARE ANALYSIS


FIGURE 58
REVENUE SHARE ANALYSIS ILLUSTRATION: DRÄGERWERK AG & CO. KGAA (GERMANY) (2025)


FIGURE 59
SUPPLY-SIDE MARKET SIZE ESTIMATION


FIGURE 60
DEMAND-SIDE MARKET SIZE ESTIMATION


FIGURE 61
CAGR PROJECTIONS FROM ANALYSIS OF DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES FOR VENTILATORS MARKET (2026–2031)


FIGURE 62
CAGR PROJECTIONS: SUPPLY-SIDE ANALYSIS


FIGURE 63
TOP-DOWN APPROACH


FIGURE 64
DATA TRIANGULATION METHODOLOGY


Methodology

This research study involved the extensive use of both primary and secondary sources. It examined various factors affecting the industry to identify segmentation types, industry trends, key players, the competitive landscape of market players, and key market dynamics such as drivers, opportunities, challenges, restraints, and key player strategies.

Secondary Research

This research study involved the wide use of secondary sources, directories, databases such as Dun & Bradstreet, Bloomberg Businessweek, and Factiva, white papers, and companies’ in-house documents. Secondary research was undertaken to identify and collect information for this extensive, technical, market-oriented, and commercial study of the ventilators market. It was also used to obtain important information about the top players, market classification, and segmentation according to industry trends to the bottom-most level, geographic markets, and key developments related to the market. A database of the key industry leaders was also prepared using secondary research.

Primary Research

In the primary research process, various supply-side and demand-side sources were interviewed to obtain qualitative and quantitative information for this report. Primary sources from the supply side included industry experts such as CEOs, vice presidents, marketing and sales directors, technology & innovation directors, engineers, and related key executives from various companies and organizations operating in the ventilators market. Primary sources from the demand side included hospitals, clinics, researchers, lab technicians, purchase managers, and stakeholders in corporate & government bodies.

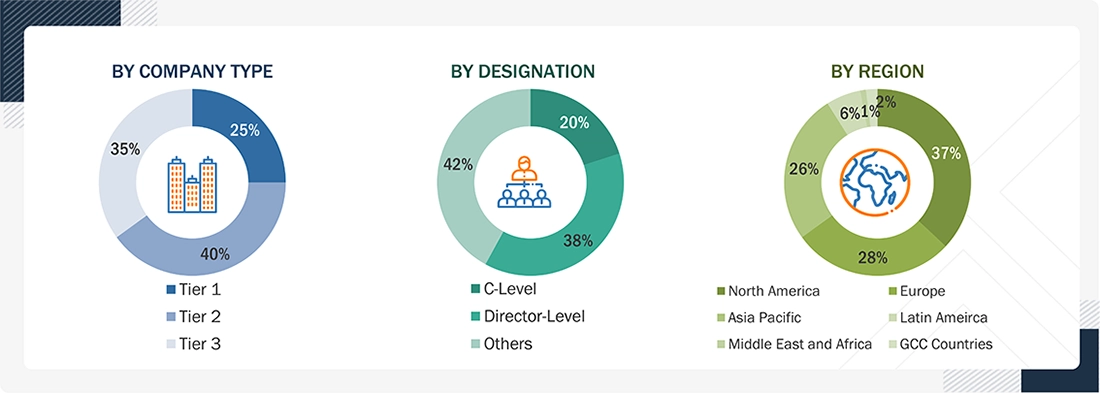
The following is a breakdown of the primary respondents:
Ventilators Market Size, and Share

Note 1: Companies are classified into tiers based on their total revenue. As of 2025: Tier 1 = >USD 1 billion, Tier 2 = USD 500 million to USD 1 billion, and Tier 3 = <USD 500 million.
Note 2: C-level executives include CEOs, COOs, CTOs, and VPs.
Note 3: Other primaries include sales managers, marketing managers, and product managers.

To know about the assumptions considered for the study, download the pdf brochure

Market Size Estimation

Both top-down and bottom-up approaches were used to estimate and validate the total size of the ventilators market. These methods were also used extensively to estimate the size of various subsegments in the market. The research methodology used to estimate the market size includes the following:

Ventilators Market: Top-Down and Bottom-Up Approach
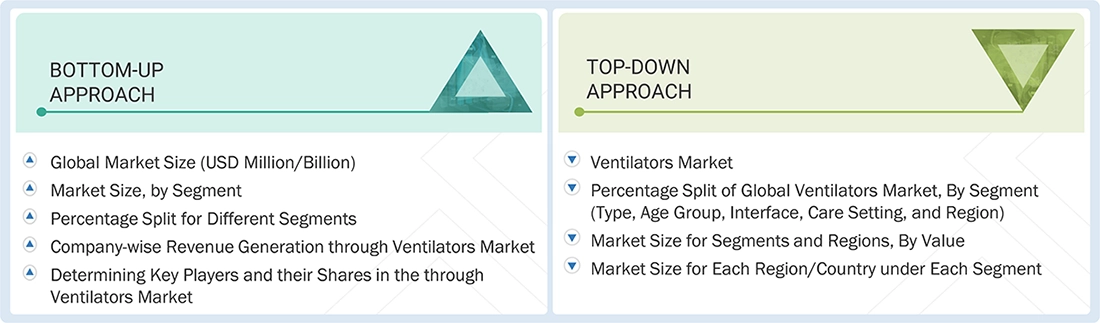
Ventilators Market Top Down and Bottom Up Approach

Data Triangulation

The entire market was split up into five segments when the market size was determined. Data triangulation and market breakdown processes were used, wherever necessary, to complete the entire market engineering process and arrive at the precise statistics for all segments.

Approach to derive the market size and estimate market growth.

Using secondary data from both paid and unpaid sources, the market rankings for the major players were determined following a thorough analysis of their sales of ventilators. Due to data restrictions, the revenue share in certain cases was determined after a thorough analysis of the product portfolio of big corporations and their individual sales performance. This information was verified at each stage by in-depth interviews with professionals in the field.

Market Definition

Ventilators are medical devices that assist or replace spontaneous breathing in patients with respiratory failure by mechanically delivering air and oxygen to the lungs. They can operate invasively—via intubation—or non-invasively using masks, and are essential in settings like intensive care units, emergency departments, and home care for improving patient oxygenation and respiratory support.

Key Stakeholders

  • Manufacturers of ventilators
  • Original equipment manufacturing companies
  • Suppliers and distributors of ventilators  
  • Healthcare service providers
  • Teaching hospitals and academic medical centers
  • Health insurance players
  • Government bodies/Municipal corporations
  • Regulatory bodies
  • Business research and consulting service providers
  • Authorities framing reimbursement policies for ventilators
  • Venture capitalists
  • Market research and consulting firms

Report Objectives

  • To define, describe, and forecast the ventilators market based on mobility, type, age group, interface, mode, care setting, and region
  • To provide detailed information about the major factors influencing the market growth (such as drivers, restraints, challenges, and opportunities)
  • To strategically analyze micromarkets with respect to individual growth trends, prospects, and contributions to the overall ventilators market
  • To analyze market opportunities for stakeholders and provide details of the competitive landscape for key players
  • To forecast the size of the ventilator market in North America, Europe, the Asia Pacific, Latin America, Middle East & Africa, and GCC countries
  • To profile the key players and comprehensively analyze their market shares and core competencies in the ventilators market
  • To track and analyze competitive developments such as partnerships, expansions, acquisitions, collaborations, product launches, agreements, and other developments in the ventilators market
  • To benchmark players within the ventilators market using the Company Evaluation Quadrant framework, which analyzes market players on various parameters within the broad categories of business strategy, market share, and product offerings

Available customizations:

With the given market data, MarketsandMarkets offers customizations as per your company’s specific needs. The following customization options are available for the report:

Company Information

  • Detailed analysis and profiling of additional market players (up to 5)

Geographic Analysis

  • Further breakdown of the Rest of Europe ventilators market  into Denmark, Norway, and others

  • Further breakdown of the Rest of Asia Pacific ventilators market into Vietnam and others


Key Questions Addressed by the Report

Who are the leading industry players in the ventilators market?
The key players in this market are ResMed (US), Getinge AB (Sweden), Koninklijke Philips N.V. (Netherlands), Drägerwerk AG & CO. KGAA (Germany), and ICU Medical, Inc. (US).
Which interface type segments have been included in the ventilators market report?
The report contains the following product segments: Invasive Ventilation, Non-invasive Ventilation, and Hybrid Ventilation.
Which region dominated the ventilators market in 2024?
In 2024, North America accounted for the largest share of the ventilators market.
What are the emerging trends in the ventilators market?
Emerging trends include the incorporation of AI, machine learning, and IoT for real-time monitoring, hybrid ventilators that switch between invasive and non-invasive modes, and a focus on portable, affordable, and easy-to-use designs for patient-centric care.
What is the total CAGR expected for the ventilators market during 2024−2029?
The ventilators market is expected to grow at a CAGR of 4.7% during the forecast period.

Personalize This Research

  • Triangulate with your Own Data
  • Get Data as per your Format and Definition
  • Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
  • Any level of Personalization
Request A Free Customisation

Let Us Help You

  • What are the Known and Unknown Adjacencies Impacting the Ventilators Market
  • What will your New Revenue Sources be?
  • Who will be your Top Customer; what will make them switch?
  • Defend your Market Share or Win Competitors
  • Get a Scorecard for Target Partners
Customized Workshop Request

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements

Get 10% Free Customisation

TESTIMONIALS

Growth opportunities and latent adjacency in Ventilators Market

DMCA.com Protection Status
popup img