Data Center Colocation Market

Data Center Colocation Market by Service Type (Traditional, Managed), Service Scale (Retail, Wholesale), Workload Type (General Purpose IT, HPC & AI), End User (Enterprises and Hyperscalers) with Impact of AI/GenAI - Global Forecast to 2031


OVERVIEW
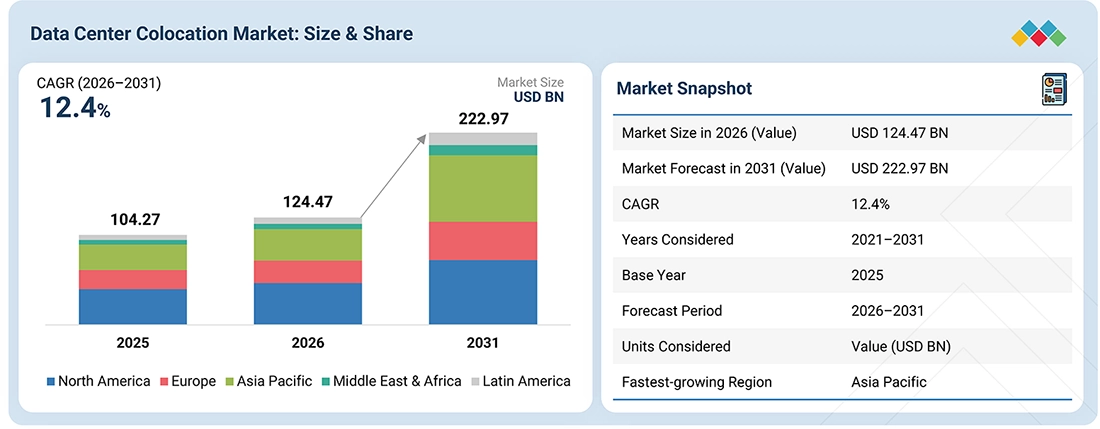
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
The global data center colocation market is projected to grow from USD 124.47 billion in 2026 to USD 222.97 billion by 2031, registering a CAGR of 12.4% during the forecast period. Growth is driven by increasing cloud adoption, AI and high-performance computing workloads, enterprise migration to hybrid IT environments, and rising demand for scalable and reliable data center capacity. Hyperscalers and enterprises are increasingly using colocation facilities to access power, connectivity, physical infrastructure, and geographic scalability without developing and operating their own facilities. The expansion of AI workloads is further increasing demand for high-density capacity, advanced cooling, and power availability. Growing requirements for interconnection, low-latency connectivity, workload distribution, and data sovereignty are also supporting demand for colocation across major and emerging data center markets.
KEY TAKEAWAYS
-
BY REGIONNorth America is expected to account for the largest market value of USD 48,453.2 million in 2026.
-
BY SERVICE TYPEBy service type, managed colocation is expected to register the highest CAGR of 18.0% during the forecast period.
-
BY SERVICE SCALEBy service scale, retail colocation is expected to account for the largest market value of USD 86,390.3 million in 2026.
-
BY WORKLOAD TYPEBy workload type, HPC is expected to register the highest CAGR, driven by AI, machine learning, analytics, and other compute-intensive workloads.
-
BY ORGANIZATION SIZEBy organization size, large enterprises are expected to account for the largest market share, supported by increasing requirements for scalable infrastructure, hybrid IT, business continuity, and geographic redundancy.
-
BY END USERBy end user, hyperscalers are expected to represent a major demand segment, supported by continued cloud expansion, AI infrastructure requirements, and large-scale capacity deployments.
-
COMPETITIVE LANDSCAPE - Key PlayersKey players such as Equinix, Digital Realty, NTT DATA, QTS Data Centers, and KDDI have established strong positions through extensive data center footprints, connectivity ecosystems, hyperscale capacity, and colocation offerings.
-
COMPETITIVE LANDSCAPE - Startups/SMEsProviders such as CyrusOne, EdgeConneX, Flexential, TierPoint, Cologix, and DataBank compete through regional capacity, enterprise colocation, connectivity, and specialized infrastructure offerings across key markets.
The data center colocation market is expanding as enterprises, cloud providers, and hyperscalers seek scalable infrastructure, reliable power, and connectivity without the capital requirements of owning and operating facilities. Increasing AI workloads, hybrid IT adoption, cloud migration, and demand for interconnection are supporting colocation deployments across major data center markets. Providers are also expanding capacity through new campuses, acquisitions, and partnerships, while increasing focus on high-density infrastructure to accommodate AI and HPC workloads.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
Key trends and disruptions in the data center colocation market include rapid growth in AI and high-performance computing workloads, rising power-density requirements, and the expansion of hybrid IT architectures. AI deployments are driving demand for higher-capacity facilities, advanced cooling, and dedicated power infrastructure, while enterprises continue to use colocation to connect on-premises systems with cloud platforms and network providers. The expansion of hyperscale and AI campuses is also increasing demand for large-scale wholesale capacity, while enterprises continue to require retail colocation for flexible and geographically distributed deployments. Increasing power constraints, land availability, sustainability requirements, and data sovereignty considerations are influencing site selection and facility development. At the same time, greater demand for direct cloud connectivity, interconnection, and low-latency infrastructure is strengthening the role of colocation facilities within hybrid and multicloud environments.
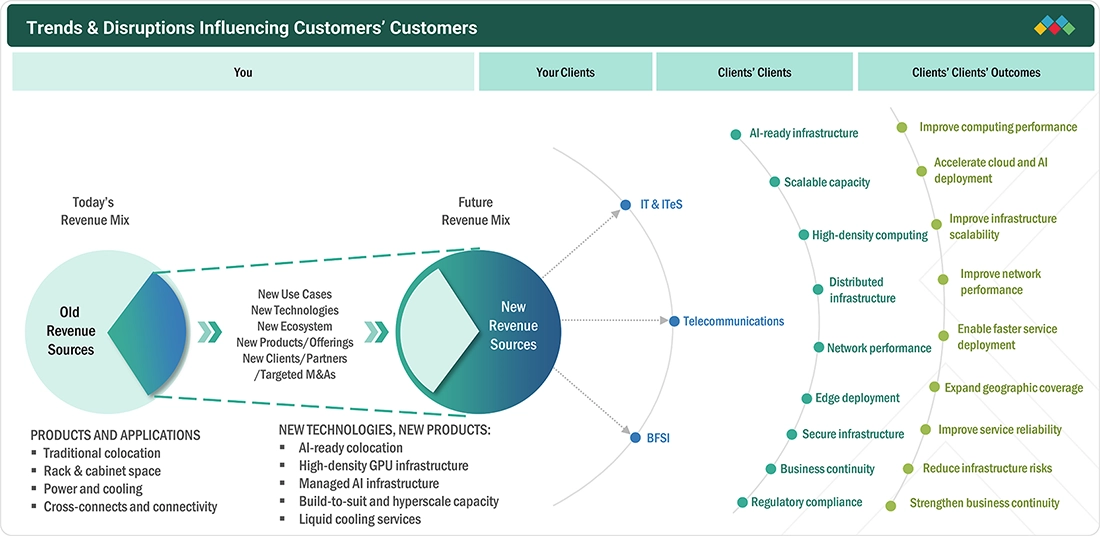
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Level
-
Growing adoption of AI and high-density data centers

-
Surge in use of hybrid-multicloud interconnected ecosystems


Level
-
Long lead times for critical electrical and mechanical equipment

-
High up-front capital costs


Level
-
Integrating sustainability into data center colocation

-
Managed AI-Infrastructure-as-a-Service


Level
-
Transforming legacy facilities for liquid cooling

-
Skilled labor shortage

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Growing adoption of AI and high-density data centers
AI and high-performance computing workloads are increasing power and thermal density requirements across data centers, supporting demand for high-density colocation capacity. Colocation providers are expanding facilities with higher power availability, advanced cooling, and infrastructure designed for GPU-intensive workloads. Hyperscalers and enterprises are increasingly seeking liquid-cooled and high-density environments for AI deployments. Providers such as Digital Realty and Equinix are expanding AI-ready capacity and supporting larger power blocks. This shift is increasing demand for wholesale and specialized colocation facilities that can support high-density workloads.
Restraint: Long lead times for critical electrical and mechanical equipment
Extended lead times for transformers, switchgear, UPS systems, generators, chillers, and other critical equipment are slowing data center construction and capacity expansion. Increasing demand for power infrastructure is placing additional pressure on equipment manufacturers and supply chains. Delays in equipment delivery can postpone facility energization and revenue-generating capacity. Colocation providers are responding through advance procurement, supplier partnerships, and longer-term equipment planning. However, continued supply constraints can increase project costs and create uncertainty around expansion timelines.
Opportunity: Integrating sustainability into data center colocation
Sustainability is becoming an important consideration in data center site selection and colocation procurement as customers seek to reduce the environmental impact of digital infrastructure. Colocation providers are increasing the use of renewable energy, power purchase agreements, energy-efficient cooling, and improved facility design. Operators can differentiate their services by offering renewable energy options and greater visibility into energy performance. Sustainability initiatives can also help meet evolving environmental requirements and customer targets. This creates opportunities for providers to position energy efficiency and renewable power as part of their colocation offering.
Challenge: Transforming legacy facilities for liquid cooling
The rapid adoption of AI is creating a challenge for legacy data centers that were designed for lower-density air-cooled workloads. Existing facilities may require upgrades to power distribution, cooling systems, floor structures, and rack infrastructure to support liquid-cooled deployments. Retrofitting operating facilities can also require temporary capacity reductions and increase project costs. Colocation providers therefore need to balance retrofit investments with customer demand for AI-ready capacity. The ability to integrate liquid cooling into existing facilities is becoming increasingly important as high-density workloads expand.
DATA CENTER COLOCATION MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
SAP partnered with Digital Realty to scale its global cloud infrastructure through PlatformDIGITAL and interconnection services. The deployment addressed the need for faster infrastructure expansion across multiple countries while supporting SAP’s hybrid cloud strategy, sustainability requirements, and growing generative AI workloads. | Digital Realty’s colocation infrastructure enabled SAP to accelerate infrastructure scaling and reduce deployment time from 18 months to 3 months. The solution provided access to interconnected facilities, improved operational flexibility, and supported SAP’s cloud expansion and sustainability goals through energy-efficient, green-certified facilities. |
 |
BMW Group partnered with NTT DATA to modernize and operate its global network and data center infrastructure. The solution combined managed enterprise networks, Infrastructure as a Service, and automation to support BMW’s cloud-first strategy while managing its large-scale server and network environment across global operations. | NTT DATA helped BMW improve network and infrastructure reliability while reducing manual operations. Automation enabled faster server deployments and improved issue diagnosis, while integrating cloud-ready infrastructure let BMW focus internal IT resources on strategic transformation and innovation. |
 |
CBS Interactive deployed Iron Mountain’s high-density colocation infrastructure to address increasing server, storage, power, and cooling requirements associated with rapidly growing digital traffic. The solution was designed to provide scalable infrastructure, reliable uptime, and improved energy efficiency while supporting high-density workloads. | Iron Mountain provided CBS Interactive with high-density colocation capacity, improved cooling and energy efficiency, and a 100% uptime SLA. The deployment reduced previous colocation costs by approximately two-thirds and provided greater flexibility to scale infrastructure while supporting performance and reliability requirements. |
 |
Nestlé Japan used Equinix IBX data centers and siteROCK monitoring services to modernize its infrastructure and support migration toward a hybrid cloud environment. The deployment addressed the need to replace aging EDI infrastructure, improve cloud connectivity, and maintain visibility across cloud and on-premises environments. | Equinix enabled Nestlé Japan to improve infrastructure visibility and support its hybrid cloud environment. Monitoring provided continuous performance visibility, real-time alerts, and historical analysis, helping reduce operational workloads and improve incident response, system stability, and disaster recovery capabilities. |
 |
Exabeam migrated its quality assurance environment to Evoactive’s colocation infrastructure after its existing data center provider announced the facility's closure. The deployment consolidated servers and racks while providing remote access, transition support, and network connectivity to maintain operational continuity during the migration. | Evoactive completed the migration, including racking, stacking, cabling, and decommissioning, within one week. Exabeam consolidated hundreds of servers into fewer than 20 racks and achieved approximately 35% cost savings. The deployment also improved remote access, simplified network architecture, and reduced the need for on-site infrastructure support. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
The data center colocation ecosystem includes colocation providers, hyperscalers, cloud service providers, enterprises, network carriers, internet service providers, infrastructure developers, utilities, and technology vendors. Colocation providers operate facilities and offer space, power, cooling, connectivity, and related infrastructure to customers. Hyperscalers and cloud providers are major users of large-scale capacity, while enterprises use colocation for hybrid IT, business continuity, connectivity, and workload distribution. Network and connectivity providers support interconnection between customers, cloud platforms, and internet exchanges. Utilities and infrastructure partners are increasingly important as power availability becomes a key factor in data center development. Together, these participants support the development, operation, and expansion of interconnected data center ecosystems.
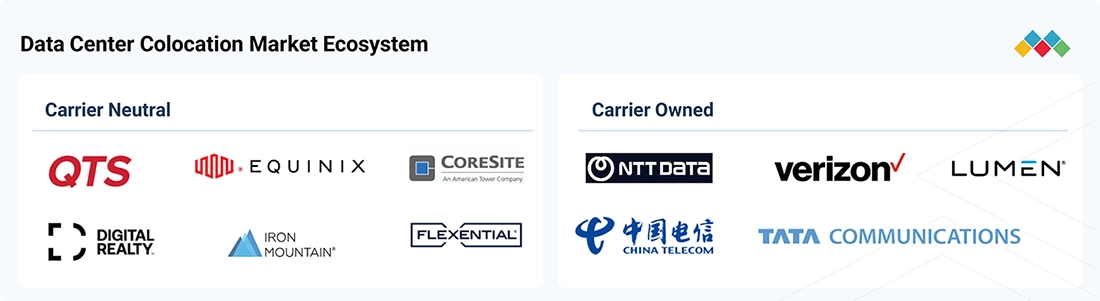
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Data Center Colocation Market, By Service Type
Managed colocation is expected to register the highest CAGR during the forecast period, driven by increasing demand for flexible infrastructure, operational support, and managed data center capabilities. Managed colocation allows enterprises to outsource selected infrastructure and operational activities while maintaining access to dedicated data center resources. Growing adoption of hybrid IT and multicloud environments is increasing demand for services that simplify infrastructure management and reduce the operational burden on internal IT teams. Enterprises are also seeking scalable solutions that can support changing workload requirements without significant investments in owned facilities. Increasing deployment of AI, cloud, and distributed workloads is further creating demand for managed colocation services that combine data center capacity with operational and infrastructure support.
Data Center Colocation Market, By Service Scale
Retail colocation is expected to capture the largest market share during the forecast period, supported by demand from enterprises and organizations that need flexible, scalable data center capacity. Retail colocation typically provides individual racks, cabinets, cages, or smaller dedicated spaces, making it suitable for organizations with moderate infrastructure requirements. Increasing cloud migration, hybrid IT adoption, business continuity requirements, and demand for reliable connectivity are supporting deployments across enterprise and regional markets. Retail colocation also enables organizations to access established data center infrastructure without developing their own facilities. Growing requirements for connectivity to cloud platforms, network providers, and internet exchanges are further supporting demand for retail colocation across major data center markets.
Data Center Colocation Market, By Workload Type
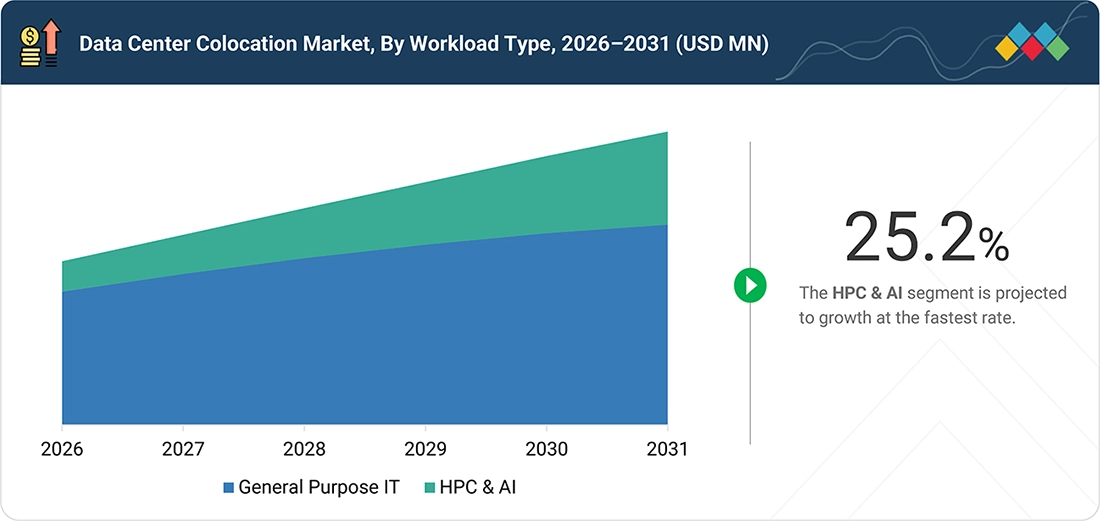
High Performance Computing (HPC) is expected to register the highest CAGR during the forecast period, driven by increasing adoption of artificial intelligence, machine learning, advanced analytics, scientific computing, and other compute-intensive applications. These workloads require high processing capacity, greater power availability, and infrastructure that can support higher rack densities than conventional IT environments. Colocation providers are therefore expanding their facilities to accommodate higher-density deployments and increasing their power and cooling capabilities. The growth of AI infrastructure is also encouraging customers to seek facilities with suitable power availability, advanced cooling, and strong network connectivity. As organizations increasingly deploy compute-intensive applications, HPC-focused colocation is expected to create new capacity requirements across major data center markets.
Data Center Colocation Market, By Organization Size
Large enterprises are expected to hold the largest market share during the forecast period, supported by their extensive infrastructure needs and growing adoption of hybrid IT environments. Large organizations use colocation facilities to support critical applications, disaster recovery, business continuity, geographic expansion, and connectivity to cloud and network providers. Colocation also allows enterprises to access scalable power, cooling, physical security, and connectivity without making large investments in owned data center infrastructure. Increasing digital workloads and cloud migration are encouraging large enterprises to distribute infrastructure across multiple locations. Demand is further supported by requirements for reliable infrastructure, lower latency, operational flexibility, and the ability to scale capacity as business and technology requirements change.
Data Center Colocation Market, By End User
Hyperscalers represent a major end-user segment in the data center colocation market, supported by continued expansion of cloud services, digital platforms, and AI infrastructure. Hyperscalers require large amounts of data center capacity to support growing computing, storage, and networking requirements across multiple geographic markets. Colocation enables these companies to access power and facility capacity while expanding infrastructure closer to customers and major connectivity hubs. The increasing deployment of AI and high-performance computing is further raising requirements for high-density facilities, large power allocations, and advanced cooling infrastructure. Hyperscalers are also increasingly using wholesale and build-to-suit arrangements to secure dedicated capacity for large-scale deployments, supporting continued expansion of the colocation market.
REGION
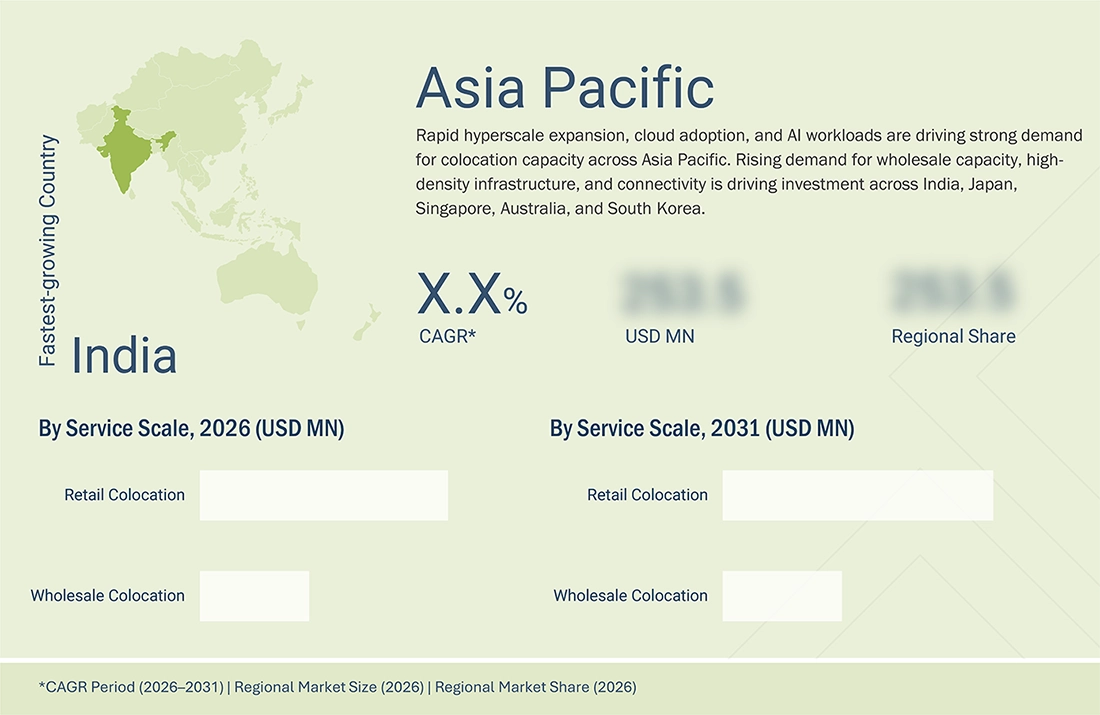
Asia Pacific is expected to register the fastest growth in the data center colocation market during the forecast period
Asia Pacific (APAC) is expected to register the fastest growth during the forecast period, driven by rapid data center capacity expansion, cloud adoption, digital transformation, and increasing investment in AI infrastructure. Countries such as India, China, Japan, Singapore, Australia, and South Korea are witnessing growing demand for colocation capacity from hyperscalers, cloud service providers, and enterprises. The expansion of AI and high-performance computing workloads is increasing requirements for high-density infrastructure, reliable power, and advanced cooling. Rising internet usage, digital services, and data localization requirements are also encouraging organizations to deploy infrastructure closer to end users. In addition, investments in new data center campuses and connectivity infrastructure are supporting the expansion of colocation services across emerging and established APAC markets.
DATA CENTER COLOCATION MARKET: COMPANY EVALUATION MATRIX
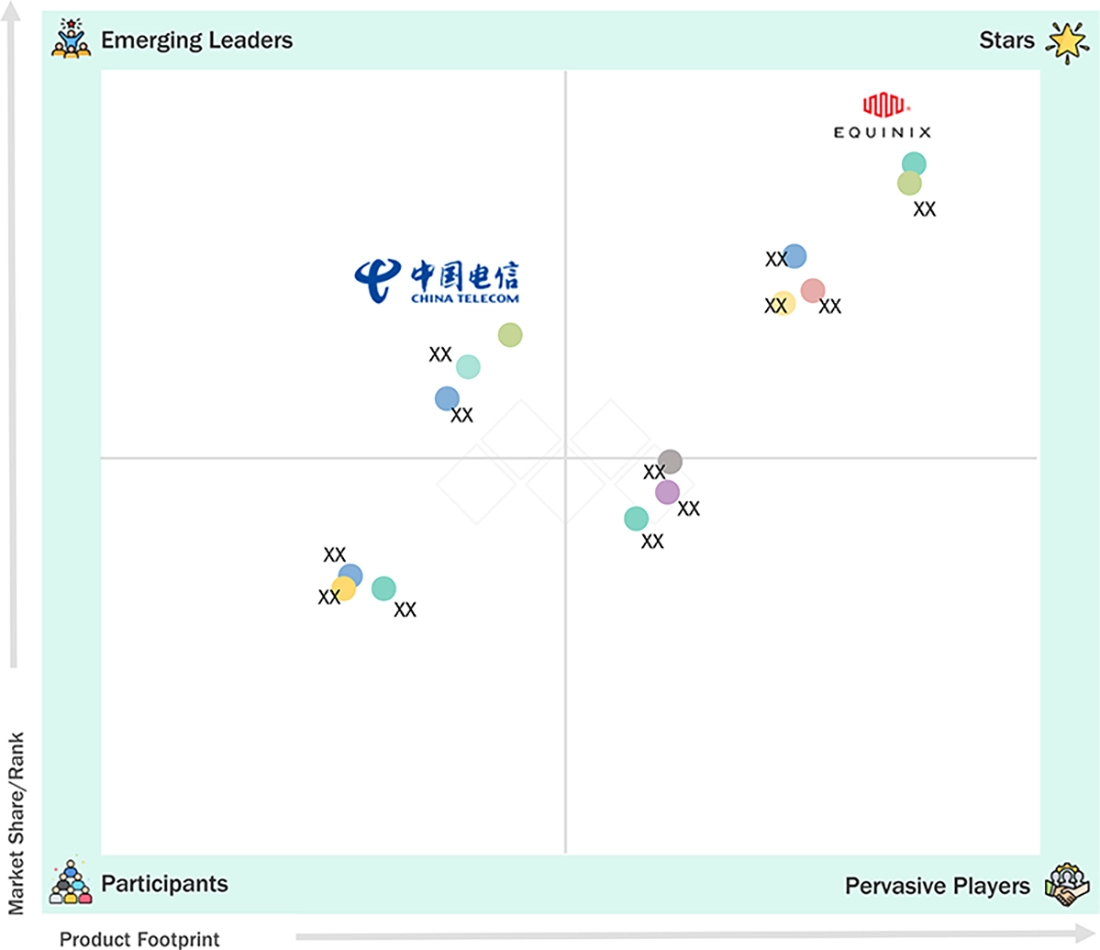
In the data center colocation market, Equinix is positioned as a Star, supported by its extensive global colocation footprint, strong interconnection ecosystem, broad customer base, and continued investment in AI-ready and high-density data center capacity. China Telecom is positioned as an Emerging Leader, supported by its large data center and telecommunications infrastructure, strong presence in China, and growing capabilities to support cloud, enterprise, and high-performance computing workloads. The competitive positioning of these companies is influenced by geographic coverage, data center capacity, power availability, connectivity, interconnection capabilities, scalability, and ability to support growing AI and cloud infrastructure requirements.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- Equinix (US)
- Digital Realty (US)
- NTT DATA (Japan)
- QTS Data Centers (US)
- KDDI Corporation (Japan)
- Iron Mountain (US)
- China Telecom Corporation Ltd. (China)
- CyrusOne (US)
- Centersquare (CSquare) (US)
- Vantage Data Centers (US)
- DataBank (US)
- EdgeConneX (US)
- Switch (US)
- CoreSite (US)
- Aligned Data Centers (US)
- Flexential (US)
- TierPoint (US)
- Cologix (US)
- TRG Data Centers (US)
- ScaleMatrix (US)
- AT&T (US)
- Global Data Systems (US)
- Verne Global (UK)
- 365 Data Centers US)
- BDX Data Centers (Singapore)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2025 (Value) | USD 104.27 Billion |
| Market Size in 2026 (Value) | USD 124.47 Billion |
| Market Forecast in 2031 (Value) | USD 222.97 Billion |
| Growth Rate | 12.4% |
| Years Considered | 2021–2031 |
| Base Year | 2025 |
| Forecast Period | 2026–2031 |
| Units Considered | Value (USD Billion) |
| Report Coverage | Revenue Forecast, Company Ranking, Competitive Landscape, Growth Factors, Trends, and Developments |
| Segments Covered |
|
| Regional Scope | North America, Europe, Asia Pacific, Middle East & Africa, Latin America |
WHAT IS IN IT FOR YOU: DATA CENTER COLOCATION MARKET REPORT CONTENT GUIDE
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Leading Colocation Provider (US) | In-depth segmentation of the North American Data Center Colocation Market Extended regional breakdowns for: • US • Canada | Identifies high-growth opportunities across AI infrastructure, cloud adoption, and enterprise colocation demand Supports market-entry and capacity expansion decisions across key North American markets Enables evaluation of demand by service type, service scale, workload, organization size, and end user |
| Leading Colocation Provider (Europe) | Detailed profiling of additional colocation market players (up to 5 vendors), including facility footprint, colocation offerings, expansion initiatives, and regional presence | Enhances competitive intelligence for strategic planning and market expansion Identifies competitive gaps and opportunities across key European colocation markets Supports targeted capacity expansion and customer acquisition strategies based on regional demand and competitor presence |
RECENT DEVELOPMENTS
- September 2026 : Equinix and CPP Investments completed the acquisition of atNorth, expanding their presence in the Nordic data center market. atNorth operates eight data centers across the five Nordic countries, with additional projects under development, strengthening high-density colocation and build-to-suit capacity. (Equinix, Inc.)
- August 2026 : Vantage Data Centers and Nebius announced an agreement to deploy high-density AI infrastructure at Vantage's CWL1 campus in Newport, Wales. The deployment will provide capacity for AI training, inference, agentic AI, and enterprise AI workloads. (Vantage Data Centers)
- August 2026 : NTT announced plans to expand its global data center capacity to approximately 4 GW by FY2030, compared with approximately 2 GW as of June 2026. The expansion will support cloud and AI infrastructure demand across its global footprint. (NTT)
- June 2026 : Digital Realty announced the purchase of a 64% interest in three fully leased Northern Virginia data centers, representing 288 MW of IT capacity and a gross asset value of approximately USD 7.80 billion. The transaction increases Digital Realty's exposure to hyperscale capacity in a major US data center market. (Digital Realty Trust)
- June 2026 : Equinix opened HK6 in Hong Kong, with an initial investment of USD 124 million and 1,000 cabinets in the first phase, expandable to 3,550 cabinets. The facility incorporates liquid cooling and is designed to support AI workloads and high-density infrastructure. (Equinix Newsroom)
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
Methodology
This research study on the data center colocation market used extensive secondary sources, including directories, IEEE Communications-Efficient: Algorithms and Systems, the International Journal of Innovation and Technology Management, and paid databases. Primary sources included industry experts from core and related industries, preferred data center colocation service providers, third-party service providers, consulting service providers, end users, and other commercial enterprises. In-depth interviews were conducted with primary respondents, including key industry participants and subject matter experts, to obtain and verify critical qualitative and quantitative information and assess the market’s prospects.
Secondary Research
In the secondary research process, various sources were referred to identify and collect information for this study. Secondary sources included annual reports, press releases, and investor presentations of companies; white papers, journals, and certified publications; and articles from recognized authors, directories, and databases. The data was also collected from other secondary sources, such as journals, government websites, blogs, and vendors’ websites. Additionally, the data center colocation spending of various countries was extracted from the respective sources.
Primary Research
In the primary research process, various primary sources from the supply and demand sides were interviewed to obtain qualitative and quantitative information on the market. Supply-side primary sources included industry experts such as Chief Experience Officers (CXOs), Vice Presidents (VPs), and directors specializing in business development, marketing, and data center colocation service providers. It also included key executives from data center colocation vendors, system integrators (SIs), professional service providers, industry associations, and other key opinion leaders.
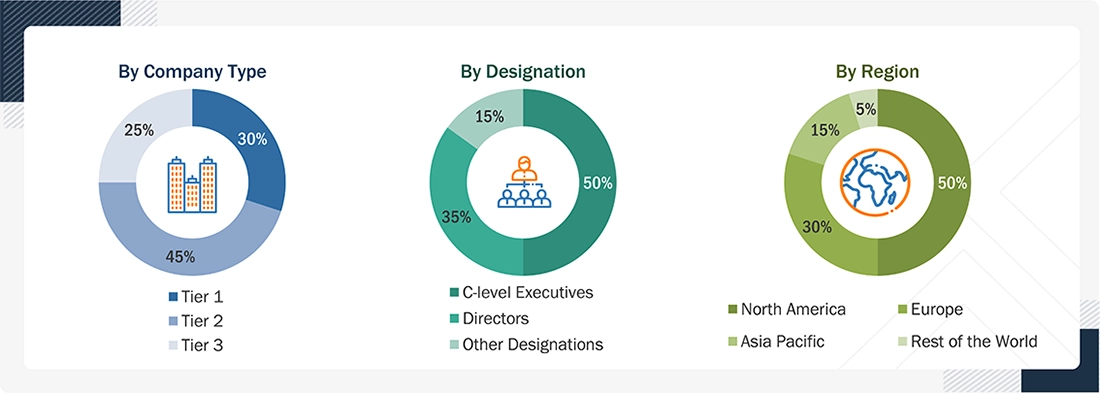
Note: Tier 1 companies’ revenues are more than USD 10 billion; tier 2 companies’ revenues range between USD 1 and 10 billion; and tier 3 companies’ revenues range between USD 500 million and USD 1 billion. Other designations include sales managers, marketing managers, and product managers.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
Multiple approaches were adopted to estimate and forecast the data center colocation market. The first approach estimated market size based on companies’ revenue generated from the sale of data center colocation services.
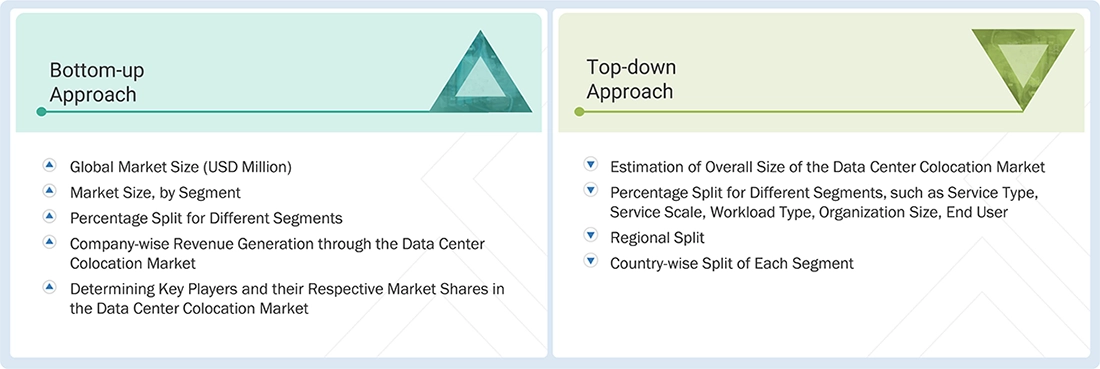
Market Size Estimation Methodology: Top-down Approach
The top-down approach prepared an exhaustive list of all the vendors offering products in the data center colocation market. The market vendors' revenue contribution was estimated using annual reports, press releases, funding announcements, investor presentations, paid databases, and primary interviews. Each vendor’s offerings were evaluated based on platform, degree of customization, type, application, end user, and region. The markets were triangulated through primary and secondary research. The primary procedure included extensive interviews with industry leaders, such as CIOs, CEOs, VPs, directors, and marketing executives, to capture key insights. The market numbers were further triangulated with the existing MarketsandMarkets’ repository for validation.
Market Size Estimation Methodology: Bottom-up Approach
In the bottom-up approach, the adoption rate of data center colocation services among different verticals in key countries, concerning their regions contributing the most to the market share, was identified. For cross-validation, the adoption of data center colocation services among enterprises, along with different use cases for their regions, was identified and extrapolated. Weightage was given to use cases identified in different areas for the market size calculation.
Based on the market numbers, the regional split was determined by primary and secondary sources. The procedure included an analysis of regional penetration in the data center colocation market. Based on secondary research, the regional spending on Information and Communications Technology (ICT), socioeconomic analysis of each country, strategic vendor analysis of major data center colocation providers, and organic and inorganic business development activities of regional and global players were estimated.
Data Triangulation
After determining the overall market size using the market size estimation processes as explained above, the market was split into several segments and subsegments. Data triangulation and market breakup procedures were employed, wherever applicable, to complete the overall market engineering process and arrive at the exact statistics of each market segment and subsegment. The overall market size was then used in the top-down procedure to estimate the size of other individual markets via percentage splits of the market segmentation.
Market Definition
The data center colocation market refers to the segment where businesses rent space, power, cooling, and connectivity within third-party data center facilities to host their own servers, storage, and networking equipment. Colocation providers offer physical security, redundant power and cooling systems, and access to multiple network carriers, allowing different enterprises to operate in a shared yet secure environment while maintaining control over their infrastructure. This model enables companies to reduce capital expenditures, improve uptime and scalability, and meet compliance requirements more effectively. The market is expanding as cloud computing, big data analytics, and IoT adoption rise, along with growing emphasis on modular infrastructure and sustainable operations.
Key Stakeholders
- Data center colocation service providers
- Hyperscalers & cloud service providers
- Networking companies
- Information technology (IT) infrastructure providers
- Consultants/Consultancies/Advisory firms
- Component providers
- Telecom service providers
- System integrators (SIs)
- Support and maintenance service providers
- Support service providers
- Third-party providers
- Government organizations and standardization bodies
- Datacenter providers
- Regional associations
- Independent hardware and software vendors
- Value-added resellers and distributors
Report Objectives
- To define, describe, and forecast the data center colocation market based on service type, service scale, workload type, organization size, end user, and region
- To forecast the market size of the five major regional segments: North America, Europe, Asia Pacific, Middle East & Africa, and Latin America
- To provide detailed information related to the major factors influencing the growth of the market (drivers, restraints, opportunities, and challenges)
- To strategically analyze macro and micro markets concerning growth trends, prospects, and their contribution to the overall market
- To analyze industry trends, patents and innovations, and pricing data related to the market
- To analyze the opportunities in the market for stakeholders and provide details of the competitive landscape for major players
- To profile key players in the market and comprehensively analyze their market share/ranking and core competencies
- To track and analyze competitive developments, such as mergers & acquisitions, product developments, and partnerships & collaborations in the market
Available customizations:
With the given market data, MarketsandMarkets offers customizations to meet the company’s specific needs. The following customization options are available for the report:
Product Analysis
- The product matrix provides a detailed comparison of each company’s product portfolio.
Geographic Analysis based on feasibility
- Further breakdown of the North American data center colocation market
- Further breakdown of the European data center colocation market
- Further breakdown of the Asia Pacific data center colocation market
- Further breakdown of the Middle East & African data center colocation market
- Further breakdown of the Latin American data center colocation market
Company Information
- Detailed analysis and profiling of additional market players (up to five)
Key Questions Addressed by the Report
What is data center colocation?
According to the International Telecommunication Union (ITU), a colocation center is a commercial data center where businesses install and operate their own servers and networking equipment within a shared facility, using the provider’s infrastructure for power, cooling, and connectivity. This model allows enterprises to avoid the high capital and operational costs of building private data centers while ensuring access to carrier-neutral networks, physical security, and scalability. Colocation supports hybrid IT environments, edge computing deployments, and regulatory compliance needs. It enables businesses to maintain control over their hardware while benefiting from enhanced resilience, operational efficiency, and geographic flexibility across interconnected ecosystems.
What are the colocation services offered by the data center providers based on the scale of colocation?
Data center colocation providers primarily offer two key service types: retail colocation and wholesale colocation. Retail colocation is designed for businesses that need limited space, such as single racks or cabinets, and prefer shared environments with standard power and cooling. It is ideal for small to mid-sized enterprises seeking cost-effective, scalable solutions without managing full data center operations. In contrast, wholesale colocation targets large organizations with high-density IT needs, offering dedicated suites or entire data halls. This model provides greater control, customization, and efficiency in terms of space, power, and cooling infrastructure. Both types enable businesses to outsource physical infrastructure while maintaining control over their hardware and applications.
What are the major factors driving the growth of the data center colocation industry?
The growth of the data center colocation industry is being driven by a surge in demand for AI, cloud computing, and big data workloads, prompting hyperscalers and enterprises to expand infrastructure rapidly. Hybrid and edge computing models are also gaining traction, with businesses colocating infrastructure closer to end users to ensure low-latency and seamless cloud integration. Sustainability is another key driver, as providers such as Equinix and Digital Realty adopt green energy solutions, liquid cooling technologies, and HVO-powered generators to reduce environmental impact. Additionally, innovations such as software-defined power, lithium-ion UPS systems, and AI-powered monitoring are enhancing operational efficiency and uptime. These advancements, along with rising digital transformation efforts across sectors such as BFSI, healthcare & life sciences, retail & e-commerce, manufacturing, and media & entertainment, are making colocation a strategic choice for enterprises seeking scalability, compliance, and high-performance infrastructure.
What challenges are hindering the widespread adoption of data center colocation?
Enterprises face several challenges that hinder the widespread adoption of data center colocation. Increasing concerns over energy and water consumption have prompted public backlash and stricter zoning rules, particularly in regions such as Virginia and California, where local resistance has delayed new projects. Grid limitations present a challenge as the rapid expansion of data centers puts pressure on existing power infrastructure, leading to concerns about potential outages and rising electricity expenses. Moreover, complexity in operations continues to be a barrier; manual processes across different facilities can lead to inefficiencies and delays, and colocation services may restrict infrastructure customization for unique workloads. These factors, environmental impact, power reliability challenges, and limited operational control, are slowing colocation’s broader deployment despite its benefits.
Who are the key vendors in the data center colocation market?
The key vendors in the global data center colocation market include Equinix (US), Digital Realty (US), NTT Data Corporation (Japan), QTS Data Centers (US), KDDI Corporation (Japan), Iron Mountain (US), China Telcom (China), and CyrusOne (Texas).

Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the Data Center Colocation Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Custom Market Research Services
We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements
Get 10% Free CustomisationTESTIMONIALS
- Canada Data Center Colocation Market
- US Data Center Colocation Market
- UK Data Center Colocation Market
- Germany Data Center Colocation Market
- France Data Center Colocation Market
- Italy Data Center Colocation Market
- China Data Center Colocation Market
- Japan Data Center Colocation Market
- India Data Center Colocation Market
- Hong Kong Data Center Colocation Market
- UAE Data Center Colocation Market
- South Africa Data Center Colocation Market
- Brazil Data Center Colocation Market
- Mexico Data Center Colocation Market
- Eastern Europe Data Center Colocation Market
- Northern Europe Data Center Colocation Market
- Southern Europe Data Center Colocation Market
- Rest Of Asia Pacific Data Center Colocation Market
- Rest Of Latin America Data Center Colocation Market
- GCC Countries Data Center Colocation Market
- Rest Of Southern Europe Data Center Colocation Market
- Ksa Data Center Colocation Market
- Rest Of GCC Countries Data Center Colocation Market



Growth opportunities and latent adjacency in Data Center Colocation Market