Caps & Closures Market by Raw Material (Plastic, Metal), Type (Plastic Caps & Closures, Metal Caps & Closures), End-use Industry (Food, Beverage, Healthcare, Cosmetics & Toiletries, Other End-use Industries), Region - Global Forecast to 2031

icon1
USD 103.96 BN
MARKET SIZE, 2031
icon2
CAGR 3.89%
(2026-2031)
icon3
300
REPORT PAGES
icon4
200
MARKET TABLES

OVERVIEW

caps-closures-market Overview

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

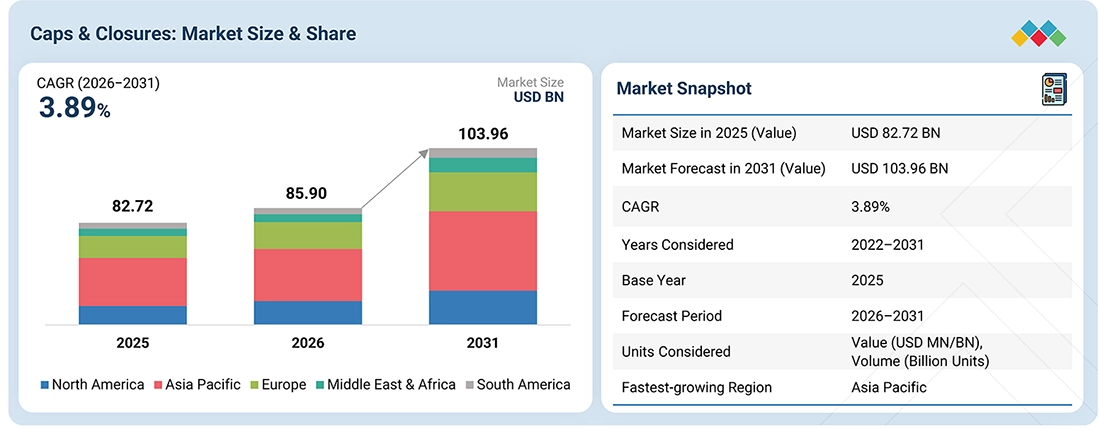
The caps & closures market is projected to grow from USD 85.90 billion in 2026 to USD 103.96 billion by 2031, reflecting a compound annual growth rate of 3.89% over the forecast period. The caps & closures market is driven by rising consumption of packaged beverages, food, pharmaceuticals, cosmetics, and personal care products, supported by global population growth, urbanization, and increasing demand for convenient packaging. According to the United Nations World Population Prospects 2024, the global population reached 8.2 billion in 2024 and is projected to reach around 8.5 billion by 2030, expanding the consumer base for packaged products. Rising beverage consumption is creating particularly strong opportunities for closure manufacturers. According to the International Bottled Water Association (IBWA), US bottled water consumption reached 16.4 billion gallons in 2024, increasing 2.9% and marking a new volume record. Carbonated soft drinks reached 11.9 billion gallons, while energy drinks grew 1.6%, further supporting demand for beverage closures. These trends are increasing demand for lightweight, tamper-evident, tethered, dispensing, and recyclable closures, while growing sustainability requirements are encouraging the adoption of PCR materials, mono-material designs, and lightweighting technologies.

KEY TAKEAWAYS

  • By Region
    Asia Pacific's caps & closures market dominated, accounting for 39.0% in 2025.
  • By Type
    The plastic caps & closures segment is expected to register the highest CAGR of 4.22% from 2026 to 2031, in terms of value.
  • By Raw Material
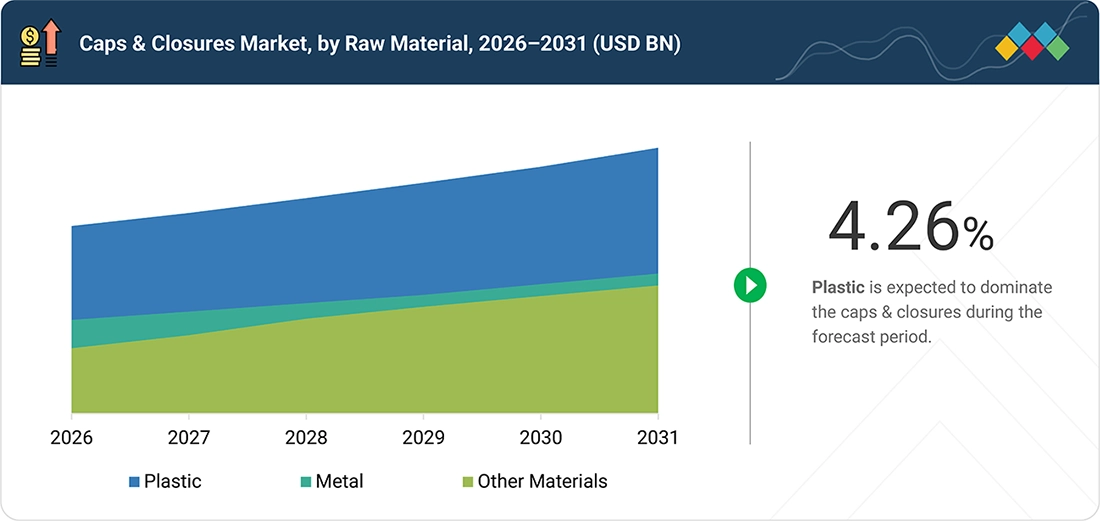
    The plastic segment is expected to register the highest CAGR of 4.26% from 2026 to 2031, in terms of value.
  • By Application
    Food is expected to dominate the market, growing at the highest CAGR of 4.92%.
  • Competitive Landscape - Key Players
    Amcor plc, Crown Holdings, Ind., Silgan Holdings Inc., BERICAP, and Guala Closures S.p.A were identified as Star players in the caps & closures market, as they have focused on innovation, have broad industry coverage, and have strong operational & financial strength.
  • Competitive Landscape- Startups
    TriMas, PHEONIX, and MRP Solutions, among others, have distinguished themselves among startups and SMEs through their strong product portfolios and business strategies.

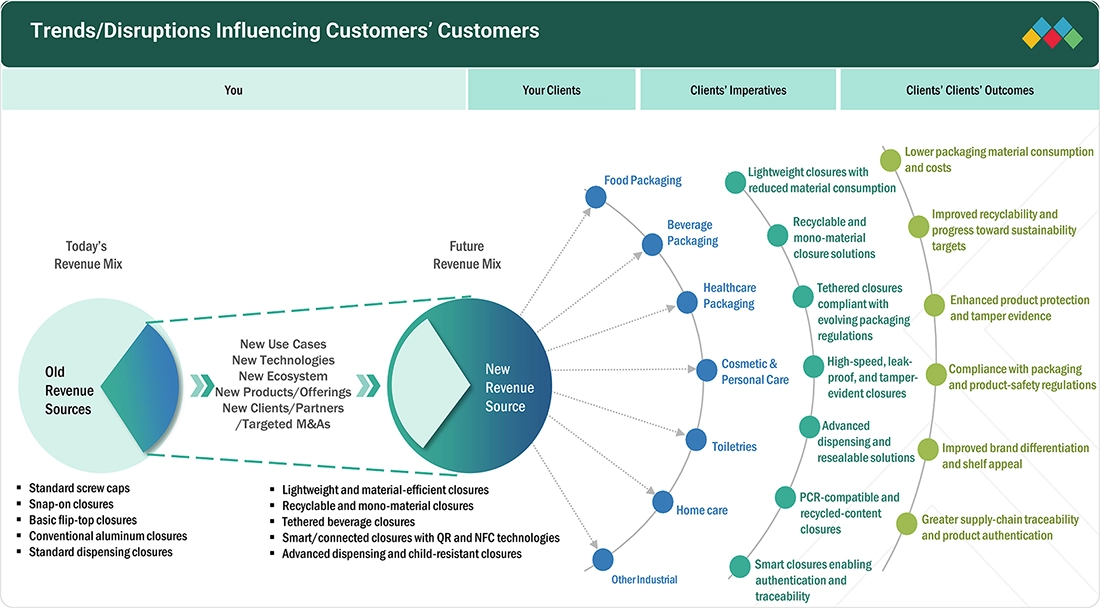
The caps & closures market is expanding as packaging manufacturers and brand owners seek to reduce material consumption, improve product protection, and meet growing sustainability requirements. Rising demand for packaged beverages, food products, pharmaceuticals, cosmetics, and personal care products is supporting consumption of plastic, metal, dispensing, tethered, and specialty closures. Increasing regulatory focus on recyclability and recycled content is further encouraging the adoption of lightweight, PCR-based, mono-material, and recyclable closure solutions. These trends are driving investments in advanced closure designs, lightweighting technologies, high-performance materials, smart closures, and automated manufacturing and inspection systems, enabling improved functionality, greater production efficiency, lower material usage, and enhanced recyclability.

TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS

The caps & closures market is driven by growing demand for convenient, sustainable, lightweight, and high-performance packaging across beverage, food, cosmetics & toiletries, and healthcare applications. Caps and closures provide product protection, leak prevention, tamper evidence, dispensing control, and consumer convenience across diverse packaging formats. To improve material efficiency and meet sustainability requirements, manufacturers are adopting lightweight designs, tethered closures, mono-material structures, PCR materials, and recyclable and bio-based resins. Moreover, advanced technologies such as smart closures, dispensing systems, automated inspection, and digital quality-control solutions are gaining importance, helping manufacturers improve production efficiency, closure performance, traceability, and recyclability while reducing material consumption and manufacturing costs.

caps-closures-market Disruptions

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

MARKET DYNAMICS

Drivers
Impact
Level
  • Growth in bottled water and packaged beverages consumption
  • Rising RTDs, coffee & functional drink demand is scaling caps and closures volumes globally
RESTRAINTS
Impact
Level
  • Volatility in PP, HDPE, and other polymer prices
  • Pressure to reduce virgin plastic and improve packaging circularity
OPPORTUNITIES
Impact
Level
  • Manufacturers of caps and closures focus on sustainable caps & closures
  • Emerging economies provide lucrative opportunities for market growth
CHALLENGES
Impact
Level
  • Stringent environmental regulations
  • Mature markets in developed regions

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Driver: Growth in bottled water and packaged beverages consumption

The expansion of packaged beverages is a major volume driver for the caps and closures market, as most single-use bottles and containers require closures. Rising consumption of bottled water, carbonated soft drinks, sports and energy drinks, juices, and ready-to-drink beverages directly increases demand for closures. Growth is particularly strong in emerging markets, supported by urbanization, rising disposable incomes, improving retail infrastructure, and increasing adoption of single-serve and on-the-go formats. Bottled water remains a key growth category, with changing lifestyles, higher per capita consumption, and demand for premium products supporting tamper-evident and differentiated closure solutions. According to the International Bottled Water Association (IBWA), US bottled water consumption reached 16.4 billion gallons in 2024, growing 2.9% and remaining the country’s leading beverage by volume for the ninth consecutive year. Carbonated soft drinks reached 11.9 billion gallons, while energy drinks grew 1.6%, further supporting demand for caps and closures across packaged beverage applications.

Restraint: Volatility in PP, HDPE and other polymer prices

Raw material cost volatility remains a key constraint for the caps & closures market, particularly for plastic closures that rely heavily on polypropylene (PP) and HDPE. Crude oil and natural gas prices, petrochemical capacity, energy costs, and supply-demand fluctuations influence these polymer prices. The impact is significant because closures are manufactured in high volumes and operate under strong cost pressures, especially in beverage packaging. Even a small increase in resin prices per closure can substantially increase procurement costs for beverage and consumer goods companies purchasing millions or billions of units. Manufacturers must therefore balance higher input costs with customer price expectations while protecting margins. Lightweighting, material optimization, recycled resin adoption, and improved production efficiency can partially mitigate cost pressures, but sustained raw material volatility continues to affect profitability and pricing strategies across the industry.

Opportunity: Manufacturers of caps and closures focus on sustainable caps & closures

Caps and closures manufacturers are increasingly adopting lightweighting, recyclable materials, and PCR resins to reduce plastic consumption while maintaining product integrity and performance. Greater collaboration across the packaging value chain is supporting sustainability goals through improved material selection, design optimization, and recycling compatibility. Lightweight closures require less raw material and can reduce processing, transportation, and overall packaging impacts. High-performance plastics enable manufacturers to further reduce closure weight without compromising sealing strength, safety, or functionality. Companies such as Berry Global and O. Berk Company offer PCR-based caps and closures for various packaging applications, supporting the transition toward more circular packaging solutions.

Challenge: Stringent environmental regulations

Increasing concerns over packaging waste and plastic pollution are driving governments to introduce stricter regulations on packaging design, recycling, and material use. Caps and closures, predominantly made from plastics, are increasingly subject to requirements for recyclability, recycled content, extended producer responsibility (EPR), and packaging waste reduction. Europe has implemented several measures to improve packaging circularity, while developing economies are also strengthening regulations to promote sustainable packaging. Manufacturers must adapt closure designs and material choices to meet evolving regulatory requirements and reduce environmental impacts. Compliance can increase costs through investments in recyclable materials, PCR content, redesigned tooling, and recycling-compatible technologies. In addition, restrictions on certain raw materials and sourcing practices may increase input costs, potentially affecting manufacturing margins and overall market economics.

CAPS & CLOSURES MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES

COMPANY USE CASE DESCRIPTION BENEFITS
company logo
Developed TetherSafe, a lightweight, mono-material polypropylene tethered closure with an integrated tether, tamper-evident band, and ergonomic grip to address regulatory and consumer demand for recyclable, lightweight, and accessible packaging | The design supported PCR and bio-renewable materials and was compatible with kerbside recycling systems in Australia and New Zealand and EU Directive 2019/904 requirements Reduced material use and packaging weight | Minimized litter from detached caps and plastic fragments | Supported recyclability |Improved opening and resealing convenience | Enabled recyclability communication through the Australasian Recycling Label (ARL) system
company logo
Collaborated with Califia Farms to develop a customized dispensing closure for its 750-ml creamer bottle, using a four-phase process covering planning, development, testing, and commercialization | The closure was designed to integrate with the bottle shape while addressing dispensing precision, consumer usability, cost, and production requirements Improved dispensing control and consumer usability, achieved targeted budget and launch requirements, provided shelf differentiation, and enhanced the overall consumer experience.
company logo
Collaborated with Militec Inc. to develop customized packaging solutions for specialty lubricants and greases used across sportsmen, military, law enforcement, automotive, and marine applications | Bernard used a standard cap with a ½-oz plastic bottle for liquid lubricants and sourced a specialty needle-tip applicator paired with a ½-oz grease tube to enable precise dispensing of thicker formulations Enabled accurate product application | Reduced packaging costs | Supported handling of both liquid and semi-solid formulations | Provided tailored dispensing solutions | Packaging and turnkey filling, packaging, and distribution capabilities supported Militec’s international market expansion and business growth

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET ECOSYSTEM

The caps & closures market ecosystem comprises raw material suppliers, closure manufacturers, packaging converters, brand owners, distributors, retailers, and recyclers. Raw material suppliers provide plastics, resins, metals, and recycled materials, which are processed by closure manufacturers into screw, dispensing, tethered, and specialty closures. Packaging converters integrate closures with bottles, jars, tubes, and other packaging formats, while brand owners across beverage, food, cosmetics & toiletries, and healthcare applications drive product specifications and demand. Distributors and retailers facilitate market reach, while recyclers support material recovery and circular packaging initiatives.

caps-closures-market Ecosystem

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET SEGMENTS

caps-closures-market Segments

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Caps & Closures Market, By Raw Material

Based on raw material, the plastic segment accounted for the largest share of the global caps & closures market in 2025. Plastic is widely used in caps and closures due to its lightweight nature, cost-effectiveness, design flexibility, and compatibility with high-speed manufacturing processes. Materials such as polypropylene (PP) and high-density polyethylene (HDPE) are extensively used across beverage, food, healthcare, and personal care packaging. The segment is supported by growing demand for lightweight packaging, single-serve beverages, dispensing solutions, and recyclable closures. In addition, advancements in PCR resins, bio-based materials, mono-material designs, and lightweighting technologies are enabling manufacturers to reduce material consumption while maintaining sealing performance and durability. The broad availability of plastic processing technologies and the ability to produce customized closure designs further support the continued dominance of plastic in the caps & closures market

Caps & Closures Market, By Type

Based on type, plastic caps & closures accounted for the largest share of the global caps & closures market in 2025. Plastic caps & closures are widely adopted across beverage, food, healthcare, and cosmetics packaging because of their lightweight construction, lower manufacturing costs, and versatility in design and functionality. Screw caps, dispensing closures, flip-top closures, and tethered caps are increasingly used to provide leak prevention, tamper evidence, controlled dispensing, and consumer convenience. The segment is further supported by investments in lightweighting, recyclable and mono-material structures, PCR content, and advanced closure designs. Growing demand for sustainable packaging is encouraging manufacturers to develop plastic closures that maintain performance while improving recyclability and reducing material consumption.

Caps & Closures Market, By End-use Industry

Based on end-use industry, the beverage segment accounted for the largest share of the global caps & closures market in 2025. High consumption of bottled water, carbonated soft drinks, juices, sports and energy drinks, and other ready-to-drink beverages generates substantial demand for caps and closures. The segment is supported by rising urbanization, changing consumer lifestyles, increasing adoption of single-serve and on-the-go packaging, and expanding packaged beverage consumption in emerging markets. Beverage manufacturers are also adopting lightweight, tamper-evident, tethered, and dispensing closures to improve product safety, convenience, and sustainability. Increasing demand for recyclable and PCR-based closures, along with the expansion of premium and functional beverage packaging, is further supporting the growth of caps and closures in the beverage industry.

REGION

Asia Pacific to be the fastest-growing region in the caps & closures market during the forecast period

Asia Pacific is expected to be the fastest-growing region in the caps & closures market during the forecast period, supported by its large and increasingly urbanized consumer base, expanding packaged food and beverage consumption, and rising demand for pharmaceutical and personal care packaging. Asia had a population of approximately 4.84 billion in 2025, providing a substantial consumer base for packaged products. China alone had 1.40 billion people in 2025, with its urbanization rate reaching 67.89%, while urban residents increased by 10.3 million during the year (Source: National Bureau of Statistics of China). Rising urbanization and modern retail penetration are supporting greater consumption of packaged beverages, processed foods, and convenience-oriented products, increasing demand for caps and closures. The region is also witnessing growing adoption of lightweight, recyclable, tethered, PCR-based, and dispensing closures as manufacturers respond to sustainability requirements and evolving packaging regulations. These demographic, consumption, and packaging trends are expected to strengthen caps and closures demand across Asia Pacific.

caps-closures-market Region

CAPS & CLOSURES MARKET: COMPANY EVALUATION MATRIX

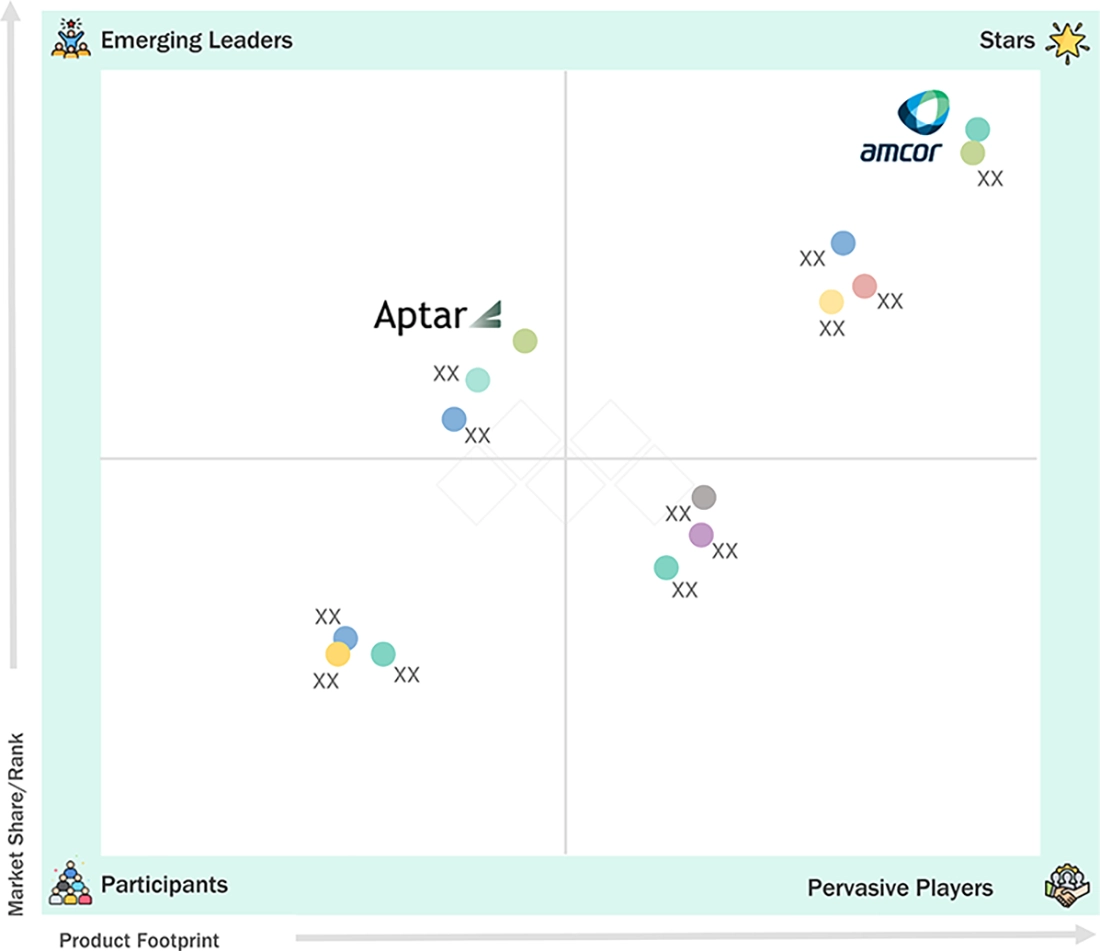
Amcor plc (Star) is a leading player in the caps & closures market, supported by its broad packaging portfolio, global manufacturing footprint, extensive customer base, and capabilities in sustainable and lightweight closure solutions. AptarGroup, Inc. (Emerging Leader) is strengthening its position through innovative dispensing and specialty closure technologies, supported by its expertise in pharmaceutical, beauty, food, and consumer packaging applications and its focus on functionality, convenience, and sustainability.

caps-closures-market Evaluation Metrics

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

KEY MARKET PLAYERS

MARKET SCOPE

REPORT METRIC DETAILS
Market Size in 2025 (Value) (Base Year) USD 82.72 BN
Market Size in 2026 (Value) (Estimated Year) USD 85.90 BN
Market Forecast in 2031 (Value) (Forecast Year) USD 103.96 BN
CAGR 3.89% from 2026-2031
Years Considered 2022–2031
Base Year 2025
Forecast Period 2026–2031
Units Considered Value (USD MN/BN) Volume (Billion Units)
Report Coverage Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments Covered
  • By Type:
    • Plastic Caps & Closures
    • Metal Caps & Closures
    • Other Caps & Closures
  • By Raw Material:
    • Plastic
    • Metal
    • Others
  • By End-use Industry:
    • Food Packaging
    • Beverage Packaging
    • Healthcare Packaging
    • Cosmetics & Toiletries
    • Other End-use Industries
Regions Covered North America, Europe, Asia Pacific, South America, and Middle East & Africa

WHAT IS IN IT FOR YOU: CAPS & CLOSURES MARKET REPORT CONTENT GUIDE

caps-closures-market Content Guide

DELIVERED CUSTOMIZATIONS

We have successfully delivered the following deep-dive customizations:

CLIENT REQUEST CUSTOMIZATION DELIVERED VALUE ADDS
US-based Cap & Closure Manufacturers
  • Comprehensive assessment of US-based cap and closure manufacturers serving food & beverage, pharmaceutical, personal care, and household chemical applications
  • Evaluation of manufacturing footprint, product portfolio, and material capabilities across plastic, metal, and composite closures
  • Assessment of closure types including screw caps, dispensing closures, child-resistant closures, and tamper-evident seals
  • Analysis of production capacity, automation levels, and regional distribution network
  • Analysis of sustainability initiatives, client base, and supply agreements with major brand owners
  • Identification of leading US-based cap and closure manufacturers and their market positioning
  • Benchmarking based on manufacturing footprint, product breadth, and end-use industry coverage
  • Insights into innovation capabilities around sustainable packaging, barrier technologies, and closure functionality
  • Assessment of opportunities driven by reshoring trends, e-commerce packaging demand, and regulatory shifts toward recyclable materials
Plastic Cap & Closure Manufacturers
  • In-depth assessment of manufacturers and technology providers offering plastic caps and closures across polymer types (PE, PP, PET)
  • Evaluation of closure formats including screw caps, flip-top closures, dispensing pumps, and child-resistant designs
  • Assessment of applications across beverages, food, pharmaceuticals, cosmetics, and household products
  • Analysis of injection molding and compression molding capabilities, tooling expertise, and production scalability
  • Assessment of lightweighting, mono-material design, and recycled content initiatives
  • Identification of leading plastic cap and closure manufacturers and competitive positioning
  • Benchmarking based on polymer expertise, molding technology, design innovation, and production scale
  • Insights into technologies enabling recyclability, lightweighting, and closure-liner compatibility
  • Assessment of growth opportunities driven by sustainable packaging mandates, beverage industry demand, and e-commerce-driven closure innovation
Metal Cap & Closures Manufacturers
  • Comprehensive evaluation of manufacturers and technology providers offering metal caps and closures including crowns, screw caps (ROPP), and lug closures
  • Assessment of substrate types (tinplate, aluminum), coating and lining technologies, and tamper-evidence features
  • Evaluation of applications across beverages (beer, wine, spirits), food jars, and specialty/pharmaceutical packaging
  • Analysis of stamping, forming, and finishing capabilities, along with production automation and capacity
  • Analysis of recyclability positioning, barrier performance, and closure integrity/safety systems
  • Identification of leading metal cap and closure manufacturers and technology differentiation
  • Benchmarking based on substrate capability, forming technology, capacity, and application footprint
  • Insights into tamper-evidence, barrier, and recyclability innovations supporting premium and sustainable packaging
  • Strategic assessment of opportunities driven by premiumization in beverages, glass-to-metal packaging shifts, and demand for infinitely recyclable closures

RECENT DEVELOPMENTS

  • July 2026 : Aptar introduced Harmonic, a liner-less flip-top sport cap designed for hot-fill beverage applications.
  • April 2026 : Amcor launched the Flava Flip Top Closure 38/400, a lightweight next-generation closure designed for sauce applications such as mayonnaise, ketchup, and sweet sauces.
  • April 2026 : BERICAP acquired Ireland-based Embankment Plastics, strengthening its local manufacturing presence and expanding access to dairy, food, and technical closure applications.
  • December 2025 : Crown Holdings expanded its longstanding partnership with Gallo through packaging support for the launch of High Noon Vodka Iced Tea and the reintroduction of Montucky Cold Snacks craft beer.
  • April 2025 : Amcor completed its merger with Berry Global, combining Berry Global’s packaging operations with Amcor to create a larger global packaging company.

Table of Contents

checkmarkExclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.

TITLE
PAGE NO
1
INTRODUCTION


30
2
EXECUTIVE SUMMARY


35
3
PREMIUM INSIGHTS


41
4
MARKET OVERVIEW
Explore growth potential in sustainable, high-value closures amid evolving beverage consumption and packaging trends.


45
 
4.1
INTRODUCTION


4.2
MARKET DYNAMICS


4.2.1
DRIVERS


4.2.1.1
GROWTH IN BOTTLED WATER AND PACKAGED BEVERAGES CONSUMPTION


4.2.1.2
RISING RTDS, COFFEE & FUNCTIONAL DRINK DEMAND SCALING UP DEMAND GLOBALLY


4.2.1.3
INCREASING DEMAND FOR FUNCTIONAL AND HIGHER-VALUE CLOSURES


4.2.1.4
PRODUCT DIFFERENTIATION AND DECREASING PACKAGE SIZES


4.2.2
RESTRAINTS


4.2.2.1
VOLATILITY IN PP, HDPE, AND OTHER POLYMER PRICES


4.2.2.2
PRESSURE TO REDUCE VIRGIN PLASTIC AND IMPROVE PACKAGING CIRCULARITY


4.2.3
OPPORTUNITIES


4.2.3.1
MANUFACTURERS OF CAPS AND CLOSURES FOCUS ON SUSTAINABLE CAPS & CLOSURES


4.2.3.2
EMERGING ECONOMIES PROVIDE LUCRATIVE OPPORTUNITIES FOR MARKET GROWTH


4.2.3.3
PRODUCT INNOVATION


4.2.4
CHALLENGES


4.2.4.1
STRINGENT ENVIRONMENTAL REGULATIONS


4.2.4.2
MATURE MARKETS IN DEVELOPED REGIONS


4.3
UNMET NEEDS AND WHITE SPACES


4.3.1
UNMET NEEDS IN CAPS & CLOSURES MARKET


4.3.2
WHITE SPACE OPPORTUNITIES


4.4
INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES


4.4.1
INTERCONNECTED MARKETS


4.4.2
CROSS-SECTOR OPPORTUNITIES


4.5
STRATEGIC MOVES BY TIER-1/2/3 PLAYERS


4.5.1
KEY MOVES AND STRATEGIC FOCUS


5
INDUSTRY TRENDS
Navigate industry dynamics with insights from competitive forces, pricing trends, and trade disruptions.


54
 
5.1
PORTER’S FIVE FORCES ANALYSIS


5.1.1
THREAT OF NEW ENTRANTS


5.1.2
THREAT OF SUBSTITUTES


5.1.3
BARGAINING POWER OF SUPPLIERS


5.1.4
BARGAINING POWER OF BUYERS


5.1.5
INTENSITY OF COMPETITIVE RIVALRY


5.2
MACROECONOMIC ANALYSIS


5.2.1
INTRODUCTION


5.2.2
GDP TRENDS AND FORECASTS


5.3
VALUE CHAIN ANALYSIS


5.4
ECOSYSTEM ANALYSIS


5.5
PRICING ANALYSIS


5.5.1
PRICING ANALYSIS BASED ON TYPE


5.5.2
PRICING ANALYSIS BASED ON REGION


5.6
TRADE ANALYSIS


5.6.1
EXPORT SCENARIO (HS CODE 392350)


5.6.2
IMPORT SCENARIO (HS CODE 392350)


5.7
KEY CONFERENCES AND EVENTS, 2026–2027


5.8
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS


5.9
INVESTMENT AND FUNDING SCENARIO


5.10
CASE STUDY ANALYSIS


5.10.1
CAPS AND CLOSURES PTY LTD: DEVELOPING SUSTAINABLE TETHERED CLOSURES WITH TETHERSAFEXX


5.10.2
PHOENIX CLOSURES: ENHANCING CONSUMER EXPERIENCE THROUGH CUSTOMIZED DISPENSING CLOSURES


5.10.3
CUSTOMIZED DISPENSING PACKAGING FOR SPECIALTY LUBRICANTS AND GREASES


5.11
IMPACT OF 2025 US TARIFF: CAPS & CLOSURES MARKET


5.11.1
INTRODUCTION


5.11.2
KEY TARIFF RATES


5.11.3
PRICE IMPACT ANALYSIS


5.11.4
IMPACT ON COUNTRY/REGION


5.11.4.1
US


5.11.4.2
CHINA


5.11.4.3
EUROPE


5.11.4.4
MEXICO AND CANADA


5.11.5
IMPACT ON END-USE INDUSTRIES


STRATEGIC DISRUPTION THROUGH TECHNOLOGY, PATENTS, DIGITAL,


6.1
KEY TECHNOLOGIES


6.1.1
SMART AND CONNECTED CLOSURES


6.1.2
TETHERED CLOSURE TECHNOLOGY


6.1.3
ADVANCED LIGHTWEIGHTING AND MATERIAL OPTIMIZATION


6.2
COMPLEMENTARY TECHNOLOGIES


6.2.1
RECYCLABLE AND MONO-MATERIAL CLOSURE TECHNOLOGIES


6.3
ADJACENT TECHNOLOGIES


6.3.1
AI-ENABLED QUALITY INSPECTION AND VISION SYSTEMS


6.4
TECHNOLOGY/PRODUCT ROADMAP


6.4.1
SHORT-TERM (2025–2027) |LIGHTWEIGHTING, TETHERED CAPS & RECYCLED CONTENT


6.4.2
MID-TERM (2027–2030) | MONO-MATERIAL, SMART & HIGH-PERFORMANCE CLOSURES


6.4.3
LONG-TERM (2030–2035+) | INTELLIGENT, CIRCULAR & MULTIFUNCTIONAL CLOSURES


6.5
PATENT ANALYSIS


6.5.1
INTRODUCTION


6.5.2
METHODOLOGY


6.5.3
CAPS & CLOSURES MARKET, PATENT ANALYSIS, 2016–2025


6.6
FUTURE APPLICATIONS


6.6.1
SMART & CONNECTED CLOSURES FOR PRODUCT AUTHENTICATION AND TRACEABILITY


6.6.2
SUSTAINABLE & MONO-MATERIAL CLOSURES FOR RECYCLABLE PACKAGING


6.6.3
ADVANCED DISPENSING & DOSING CLOSURES FOR CONTROLLED PRODUCT DELIVERY


6.6.4
RECYCLING-FRIENDLY & CIRCULAR CLOSURES FOR SUSTAINABLE PACKAGING SYSTEMS


6.7
IMPACT OF AI/GEN AI ON CAPS & CLOSURES MARKET


6.7.1
TOP USE CASES AND MARKET POTENTIAL


6.7.2
BEST PRACTICES IN CAPS & CLOSURES PROCESSING


6.7.3
CASE STUDIES OF AI IMPLEMENTATION IN THE CAPS & CLOSURES MARKET


6.7.4
INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS


6.7.5
CLIENTS’ READINESS TO ADOPT GENERATIVE AI IN THE CAPS & CLOSURES MARKET


6.8
SUCCESS STORIES AND REAL-WORLD APPLICATIONS


6.8.1
ALPLA: INTEGRATED DOSING CLOSURE FOR HOUSEHOLD CLEANING PRODUCTS


6.8.2
APTAR: SIMPLISQUEEZE® VALVE TRANSFORMS SOUR CREAM PACKAGING


6.8.3
CAPS & CLOSURES: BLACK-CF ENABLES RECYCLABLE BLACK CLOSURE PACKAGING


7
SUSTAINABILITY AND REGULATORY LANDSCAPE
Navigate complex global regulations to drive sustainable packaging innovations and compliance success.


91
 
7.1
REGIONAL REGULATIONS AND COMPLIANCE


7.1.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


7.1.2
INDUSTRY STANDARDS


7.2
SUSTAINABILITY INITIATIVES


7.2.1
LIGHTWEIGHTING AND MATERIAL REDUCTION


7.2.2
RECYCLED AND RENEWABLE MATERIAL ADOPTION


7.2.3
TETHERED AND RECYCLABLE CLOSURE DESIGNS


7.2.4
CIRCULAR ECONOMY AND CLOSURE RECYCLING


7.2.5
EPR AND SUSTAINABLE PACKAGING PROGRAMS


7.2.6
LOW-CARBON MANUFACTURING AND RENEWABLE ENERGY


7.3
IMPACT OF REGULATORY POLICY ON SUSTAINABILITY INITIATIVES


8
CUSTOMER LANDSCAPE & BUYER BEHAVIOR
Unlock hidden revenue by addressing unmet needs and aligning with key stakeholder criteria.


102
 
8.1
DECISION-MAKING PROCESS


8.2
BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA


8.2.1
KEY STAKEHOLDERS IN THE BUYING PROCESS


8.2.2
BUYING CRITERIA


8.3
ADOPTION BARRIERS & INTERNAL CHALLENGES


8.4
UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES


8.5
MARKET PROFITABILITY


8.5.1
REVENUE POTENTIAL


8.5.2
COST DYNAMICS


8.5.3
MARGIN OPPORTUNITIES BY END-USE INDUSTRY


9
CAPS & CLOSURES MARKET, BY RAW MATERIAL
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million and Units | 4 Data Tables


110
 
9.1
INTRODUCTION


9.2
PLASTIC


9.2.1
POLYPROPYLENE


9.2.2
POLYETHYLENE


9.2.3
PVC


9.2.4
OTHER PLASTICS


9.3
METALS


9.3.1
ALUMINUM


9.3.2
STAINLESS STEEL


9.4
OTHERS


9.4.1
GLASS


9.4.2
WOOD


9.4.3
RUBBER & ELASTOMERS


9.4.4
PAPERBOARD


9.4.5
PAPER


10
CAPS & CLOSURES MARKET, BY TYPE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million and Units | 4 Data Tables


116
 
10.1
INTRODUCTION


10.2
PLASTIC CAPS & CLOSURES


10.2.1
SCREW CAPS


10.2.2
DISPENSING CAPS


10.2.2.1
FLIP-TOP CAPS


10.2.2.2
DISC-TOP CLOSURES


10.2.2.3
TRIGGER CAPS & CLOSURES


10.2.3
LIQUID CARTON CLOSURES


10.2.4
PLASTIC LOTION PUMPS


10.2.5
PLASTIC AEROSOL SPRAYS


10.2.6
OTHER PLASTIC CAPS & CLOSURES


10.2.6.1
CHILD-RESISTANT CLOSURES


10.2.6.2
TAMPER-EVIDENT CLOSURES


10.2.6.3
OVERCAPS


10.3
METAL CAPS & CLOSURES


10.3.1
SCREW & LUG CAPS


10.3.2
CAN ENDS


10.3.3
CROWN CAPS


10.3.4
OTHER METAL CLOSURES


10.4
OTHER CAPS & CLOSURES


10.4.1
CORKS


10.4.2
GLASS STOPPERS


10.4.3
RUBBER & ELASTOMER STOPPERS


10.4.4
OTHERS


11
CAPS & CLOSURES MARKET, BY END-USE INDUSTRY
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million and Units | 4 Data Tables


123
 
11.1
INTRODUCTION


11.2
FOOD PACKAGING


11.2.1
RISING DEMAND FOR PROCESSED AND PACKAGED FOODS


11.3
BEVERAGE PACKAGING


11.3.1
INCREASING CONSUMPTION OF PACKAGED BEVERAGES


11.4
HEALTHCARE PACKAGING


11.4.1
EXPANDING PHARMACEUTICAL AND HEALTHCARE INDUSTRY TO DRIVE DEMAND


11.5
COSMETIC & TOILETRIES


11.5.1
GROWING GLOBAL BEAUTY AND PERSONAL CARE MARKET TO BOOST DEMAND


11.6
OTHER END-USE INDUSTRIES


12
CAPS & CLOSURES MARKET, BY REGION
Comprehensive coverage of 8 Regions with country-level deep-dive of 16 Countries | 260 Data Tables.


129
 
12.1
INTRODUCTION


12.2
ASIA PACIFIC


12.2.1
CHINA


12.2.1.1
EXPANSION OF FOOD PROCESSING, PREPARED MEALS, E-COMMERCE, AND HEALTHCARE TO ACCELERATE CLOSURE DEMAND


12.2.2
JAPAN


12.2.2.1
STRONG FOOD PROCESSING, CONVENIENCE RETAIL, AND E-COMMERCE ACTIVITY TO SUPPORT CLOSURE ADOPTION


12.2.3
INDIA


12.2.3.1
EXPANSION OF ORGANIZED RETAIL, QUICK COMMERCE, FOOD PROCESSING, AND HEALTHCARE TO BOOST CLOSURE DEMAND


12.2.4
AUSTRALIA


12.2.4.1
HIGH DISPOSABLE INCOME AND STRONG FOOD & BEVERAGE CONSUMPTION TO SUPPORT CLOSURE ADOPTION


12.2.5
REST OF ASIA PACIFIC


12.3
EUROPE


12.3.1
GERMANY


12.3.1.1
STRONG FOOD, BEVERAGE, HEALTHCARE, AND COSMETICS INDUSTRIES SUPPORTING DEMAND


12.3.2
UK


12.3.2.1
E-COMMERCE, AND LOGISTICS EXPANSION DRIVING CLOSURE DEMAND


12.3.3
FRANCE


12.3.3.1
RISING DEMAND FOR CAPS & CLOSURES FROM FOOD PROCESSING, AND FOODSERVICE SECTOR


12.3.4
SPAIN


12.3.4.1
GROWING FOOD AND BEVERAGE EXPORTS DRIVING DEMAND


12.3.5
REST OF EUROPE


12.4
NORTH AMERICA


12.4.1
US


12.4.1.1
GROWING FROZEN FOOD, FOODSERVICE, HEALTHCARE, AND E-COMMERCE ACTIVITY DRIVING CLOSURE DEMAND


12.4.2
CANADA


12.4.2.1
INCREASE IN DEMAND FOR CONVENIENT PACKAGING TO DRIVE THE CAPS & CLOSURES MARKET


12.4.3
MEXICO


12.4.3.1
HIGH GROWTH POTENTIAL OF PACKAGING INDUSTRY DUE TO INCREASING DISPOSABLE INCOME AND RISING POPULATION


12.5
MIDDLE EAST & AFRICA


12.5.1
GCC COUNTRIES


12.5.1.1
SAUDI ARABIA


12.5.1.1.1
RETAIL EXPANSION, AND HEALTHCARE INVESTMENT SUPPORTING CLOSURE DEMAND


12.5.1.2
UAE


12.5.1.2.1
FOOD PROCESSING, IMPORTED FOOD, AND BEAUTY PRODUCTS EXPANDING CLOSURE APPLICATIONS


12.5.1.3
REST OF GCC COUNTRIES


12.5.2
SOUTH AFRICA


12.5.2.1
EXPANDING FOOD RETAIL AND AGRICULTURAL EXPORTS SUPPORTING CAPS & CLOSURES DEMAND


12.5.3
REST OF MIDDLE EAST & AFRICA


12.6
SOUTH AMERICA


12.6.1
BRAZIL


12.6.1.1
EXPANDING SUPERMARKET AND E-COMMERCE CHANNELS TO DRIVE THE MARKET


12.6.2
ARGENTINA


12.6.2.1
PACKAGED FOOD CONSUMPTION, AND HEALTHCARE SPENDING TO DRIVE DEMAND


12.6.3
REST OF SOUTH AMERICA


13
COMPETITIVE LANDSCAPE
Discover market leaders' strategies, revenue insights, and emerging competitors shaping the industry's future.


225
 
13.1
OVERVIEW


13.2
KEY PLAYERS’ STRATEGIES/RIGHT TO WIN


13.3
REVENUE ANALYSIS


13.4
MARKET SHARE ANALYSIS


13.5
COMPANY VALUATION AND FINANCIAL METRICS


13.5.1
COMPANY VALUATION


13.5.2
FINANCIAL METRICS


13.6
BRAND/PRODUCT COMPARISON


13.7
COMPANY EVALUATION MATRIX


13.7.1
STARS


13.7.2
EMERGING LEADERS


13.7.3
PERVASIVE PLAYERS


13.7.4
PARTICIPANTS


13.7.5
COMPANY FOOTPRINT: KEY PLAYERS, 2025


13.7.5.1
COMPANY FOOTPRINT


13.7.5.2
REGION FOOTPRINT


13.7.5.3
RAW MATERIAL FOOTPRINT


13.7.5.4
TYPE FOOTPRINT


13.7.5.5
END-USE INDUSTRY FOOTPRINT


13.8
COMPANY EVALUATION MATRIX: STARTUPS/SMES


13.8.1
PROGRESSIVE COMPANIES


13.8.2
RESPONSIVE COMPANIES


13.8.3
DYNAMIC COMPANIES


13.8.4
STARTING BLOCKS


13.8.5
COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025


13.8.5.1
DETAILED LIST OF KEY STARTUPS/SMES


13.8.5.2
COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES


13.9
COMPETITIVE SCENARIO


13.9.1
PRODUCT LAUNCHES


13.9.2
DEALS


13.9.3
EXPANSIONS


14
COMPANY PROFILES
In-depth Company Profiles of Leading Market Players with detailed Business Overview, Product and Service Portfolio, Recent Developments, and Unique Analyst Perspective (MnM View)


251
 
14.1
KEY PLAYERS


14.1.1
AMCOR PLC


14.1.1.1
BUSINESS OVERVIEW


14.1.1.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.1.3
RECENT DEVELOPMENTS


14.1.1.3.1
PRODUCT LAUNCHES


14.1.1.3.2
DEALS


14.1.1.4
EXPANSIONS


14.1.1.5
MNM VIEW


14.1.1.5.1
RIGHT TO WIN


14.1.1.5.2
STRATEGIC CHOICES


14.1.1.5.3
WEAKNESSES AND COMPETITIVE THREATS


14.1.2
CROWN HOLDINGS, INC.


14.1.3
SILGAN HOLDINGS INC.


14.1.4
APTARGROUP, INC.


14.1.5
BERICAP


14.1.6
GUALA CLOSURES S.P.A


14.1.7
ALPLA GROUP


14.1.8
CLOSURE SYSTEMS INTERNATIONAL


14.1.9
UNITED CAPS


14.1.10
ALCOPACK GROUP


14.2
OTHER PLAYERS


14.2.1
TRIMAS


14.2.2
CORAL PRODUCTS PLC


14.2.3
HERTI JSC


14.2.4
PANO CAP CANADA LTD.


14.2.5
PHOENIX


14.2.6
MRP SOLUTIONS


14.2.7
PRECISION CONCEPTS INTERNATIONAL LLC


14.2.8
CAPRITE AUSTRALIA


14.2.9
CAPS AND CLOSURES PTY LTD


14.2.10
PRETIUM PACKAGING


14.2.11
TECNOCAP S.P.A.


14.2.12
PURV GROUP


14.2.13
AGLO


14.2.14
SECURE INDUSTRIES PVT. LTD.


14.2.15
ORIGIN MATERIALS


15
RESEARCH METHODOLOGY


313
 
15.1
RESEARCH DATA


15.1.1
SECONDARY DATA


15.1.1.1
KEY DATA FROM SECONDARY SOURCES


15.1.2
PRIMARY DATA


15.1.2.1
KEY DATA FROM PRIMARY SOURCES


15.1.2.2
KEY INDUSTRY INSIGHTS


15.2
MARKET SIZE ESTIMATION


15.3
BASE NUMBER CALCULATION


15.4
MARKET FORECAST APPROACH


15.4.1
SUPPLY SIDE


15.4.2
DEMAND SIDE


15.5
DATA TRIANGULATION


15.6
RESEARCH ASSUMPTIONS


15.7
RESEARCH LIMITATIONS AND RISK ASSESSMENT


16
APPENDIX


322
 
16.1
DISCUSSION GUIDE


16.2
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL


16.3
CUSTOMIZATION OPTIONS


16.4
RELATED REPORTS


16.5
AUTHOR DETAILS


LIST OF TABLES


TABLE 1
CAPS & CLOSURES MARKET: PORTER’S FIVE FORCES ANALYSIS


TABLE 2
WORLD REAL GDP (ANNUAL PERCENTAGE CHANGE), 2023–2027


TABLE 3
ROLES OF COMPANIES IN CAPS & CLOSURES ECOSYSTEM


TABLE 4
PRICE RANGE BY TYPE, BY KEY PLAYERS, 2025 (USD/THOUSAND UNITS)


TABLE 5
AVERAGE SELLING PRICE TREND OF KEY PLAYERS, BY REGION, 2022–2025 (USD/THOUSAND UNITS)


TABLE 6
EXPORT DATA FOR HS CODE 392350-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025 (USD MILLION)


TABLE 7
IMPORT DATA FOR HS CODE 392350-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025 (USD MILLION)


TABLE 8
CAPS & CLOSURES MARKET: DETAILED LIST OF CONFERENCES AND EVENTS, 2026–2027


TABLE 9
KEY TARIFF RATES IMPOSED ON VARIOUS COUNTRIES AS PER RECENT RECIPROCAL TARIFFS ANNOUNCED UNDER TRUMP ADMINISTRATION (2025)


TABLE 10
CAPS & CLOSURES MARKET: LIST OF KEY PATENTS, 2023–2025


TABLE 11
TOP USE CASES AND MARKET POTENTIAL


TABLE 12
BEST PRACTICES: COMPANIES IMPLEMENTING USE CASES


TABLE 13
CAPS & CLOSURES MARKET: CASE STUDIES RELATED TO GEN AI IMPLEMENTATION


TABLE 14
NORTH AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, INDUSTRY ASSOCIATIONS, AND OTHER ORGANIZATIONS


TABLE 15
EUROPE: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, INDUSTRY ASSOCIATIONS, AND OTHER ORGANIZATIONS


TABLE 16
ASIA PACIFIC: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, INDUSTRY ASSOCIATIONS, AND OTHER ORGANIZATIONS


TABLE 17
MIDDLE EAST & AFRICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, INDUSTRY ASSOCIATIONS, AND OTHER ORGANIZATIONS


TABLE 18
SOUTH AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, INDUSTRY ASSOCIATIONS, AND OTHER ORGANIZATIONS


TABLE 19
GLOBAL INDUSTRY STANDARDS IN CAPS & CLOSURES MARKET


TABLE 20
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY END-USE INDUSTRY (%)


TABLE 21
KEY BUYING CRITERIA, BY END-USE INDUSTRY


TABLE 22
UNMET NEEDS IN CAPS & CLOSURES MARKET BY END-USE INDUSTRY


TABLE 23
CAPS & CLOSURES MARKET, BY RAW MATERIAL, 2022–2024 (USD MILLION)


TABLE 24
CAPS & CLOSURES MARKET, BY RAW MATERIAL, 2025–2031 (USD MILLION)


TABLE 25
CAPS & CLOSURES MARKET, BY RAW MATERIAL, 2022–2024 (BILLION UNITS)


TABLE 26
CAPS & CLOSURES MARKET, BY RAW MATERIAL, 2025–2031 (BILLION UNITS)


TABLE 27
CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 28
CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 29
CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 30
CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 31
CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 32
CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 33
CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 34
CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 35
CAPS & CLOSURES MARKET, BY REGION, 2022–2024 (USD MILLION)


TABLE 36
CAPS & CLOSURES MARKET, BY REGION, 2025–2031 (USD MILLION)


TABLE 37
CAPS & CLOSURES MARKET, BY REGION, 2022–2024 (BILLION UNITS)


TABLE 38
CAPS & CLOSURES MARKET, BY REGION, 2025–2031 (BILLION UNITS)


TABLE 39
ASIA PACIFIC: CAPS & CLOSURES MARKET, BY COUNTRY, 2022–2024 (USD MILLION)


TABLE 40
ASIA PACIFIC: CAPS & CLOSURES MARKET, BY COUNTRY, 2025–2031 (USD MILLION)


TABLE 41
ASIA PACIFIC: CAPS & CLOSURES MARKET, BY COUNTRY, 2022–2024 (BILLION UNITS)


TABLE 42
ASIA PACIFIC: CAPS & CLOSURES MARKET, BY COUNTRY, 2025–2031 (BILLION UNITS)


TABLE 43
ASIA PACIFIC: CAPS & CLOSURES MARKET, BY RAW MATERIAL, 2022–2024 (USD MILLION)


TABLE 44
ASIA PACIFIC: CAPS & CLOSURES MARKET, BY RAW MATERIAL, 2025–2031 (USD MILLION)


TABLE 45
ASIA PACIFIC: CAPS & CLOSURES MARKET, BY RAW MATERIAL, 2022–2024 (BILLION UNITS)


TABLE 46
ASIA PACIFIC: CAPS & CLOSURES MARKET, BY RAW MATERIAL, 2025–2031 (BILLION UNITS)


TABLE 47
ASIA PACIFIC: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 48
ASIA PACIFIC: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 49
ASIA PACIFIC: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 50
ASIA PACIFIC: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 51
ASIA PACIFIC: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 52
ASIA PACIFIC: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 53
ASIA PACIFIC: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 54
ASIA PACIFIC: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 55
CHINA: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 56
CHINA: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 57
CHINA: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 58
CHINA: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 59
CHINA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 60
CHINA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 61
CHINA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 62
CHINA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 63
JAPAN: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 64
JAPAN: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 65
JAPAN: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 66
JAPAN: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 67
JAPAN: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 68
JAPAN: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 69
JAPAN: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 70
JAPAN: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 71
INDIA: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 72
INDIA: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 73
INDIA: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 74
INDIA: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 75
INDIA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 76
INDIA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 77
INDIA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 78
INDIA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 79
AUSTRALIA: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 80
AUSTRALIA: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 81
AUSTRALIA: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 82
AUSTRALIA: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 83
AUSTRALIA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 84
AUSTRALIA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 85
AUSTRALIA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 86
AUSTRALIA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 87
REST OF ASIA PACIFIC: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 88
REST OF ASIA PACIFIC: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 89
REST OF ASIA PACIFIC: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 90
REST OF ASIA PACIFIC: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 91
REST OF ASIA PACIFIC: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 92
REST OF ASIA PACIFIC: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 93
REST OF ASIA PACIFIC: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 94
REST OF ASIA PACIFIC: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 95
EUROPE: CAPS & CLOSURES MARKET, BY COUNTRY, 2022–2024 (USD MILLION)


TABLE 96
EUROPE: CAPS & CLOSURES MARKET, BY COUNTRY, 2025–2031 (USD MILLION)


TABLE 97
EUROPE: CAPS & CLOSURES MARKET, BY COUNTRY, 2022–2024 (BILLION UNITS)


TABLE 98
EUROPE: CAPS & CLOSURES MARKET, BY COUNTRY, 2025–2031 (BILLION UNITS)


TABLE 99
EUROPE: CAPS & CLOSURES MARKET, BY RAW MATERIAL, 2022–2024 (USD MILLION)


TABLE 100
EUROPE: CAPS & CLOSURES MARKET, BY RAW MATERIAL, 2025–2031 (USD MILLION)


TABLE 101
EUROPE: CAPS & CLOSURES MARKET, BY RAW MATERIAL, 2022–2024 (BILLION UNITS)


TABLE 102
EUROPE: CAPS & CLOSURES MARKET, BY RAW MATERIAL, 2025–2031 (BILLION UNITS)


TABLE 103
EUROPE: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 104
EUROPE: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 105
EUROPE: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 106
EUROPE: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 107
EUROPE: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 108
EUROPE: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 109
EUROPE: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 110
EUROPE: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 111
GERMANY: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 112
GERMANY: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 113
GERMANY: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 114
GERMANY: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 115
GERMANY: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 116
GERMANY: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 117
GERMANY: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 118
GERMANY: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 119
UK: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 120
UK: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 121
UK: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 122
UK: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 123
UK: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 124
UK: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 125
UK: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 126
UK: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 127
FRANCE: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 128
FRANCE: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 129
FRANCE: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 130
FRANCE: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 131
FRANCE: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 132
FRANCE: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 133
FRANCE: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 134
FRANCE: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 135
SPAIN: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 136
SPAIN: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 137
SPAIN: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 138
SPAIN: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 139
SPAIN: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 140
SPAIN: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 141
SPAIN: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 142
SPAIN: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 143
REST OF EUROPE: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 144
REST OF EUROPE: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 145
REST OF EUROPE: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 146
REST OF EUROPE: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 147
REST OF EUROPE: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 148
REST OF EUROPE: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 149
REST OF EUROPE: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 150
REST OF EUROPE: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 151
NORTH AMERICA: CAPS & CLOSURES MARKET, BY COUNTRY, 2022–2024 (USD MILLION)


TABLE 152
NORTH AMERICA: CAPS & CLOSURES MARKET, BY COUNTRY, 2025–2031 (USD MILLION)


TABLE 153
NORTH AMERICA: CAPS & CLOSURES MARKET, BY COUNTRY, 2022–2024 (BILLION UNITS)


TABLE 154
NORTH AMERICA: CAPS & CLOSURES MARKET, BY COUNTRY, 2025–2031 (BILLION UNITS)


TABLE 155
NORTH AMERICA: CAPS & CLOSURES MARKET, BY RAW MATERIAL, 2022–2024 (USD MILLION)


TABLE 156
NORTH AMERICA: CAPS & CLOSURES MARKET, BY RAW MATERIAL, 2025–2031 (USD MILLION)


TABLE 157
NORTH AMERICA: CAPS & CLOSURES MARKET, BY RAW MATERIAL, 2022–2024 (BILLION UNITS)


TABLE 158
NORTH AMERICA: CAPS & CLOSURES MARKET, BY RAW MATERIAL, 2025–2031 (BILLION UNITS)


TABLE 159
NORTH AMERICA: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 160
NORTH AMERICA: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 161
NORTH AMERICA: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 162
NORTH AMERICA: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 163
NORTH AMERICA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 164
NORTH AMERICA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 165
NORTH AMERICA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 166
NORTH AMERICA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 167
US: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 168
US: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 169
US: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 170
US: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 171
US: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 172
US: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 173
US: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 174
US: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 175
CANADA: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 176
CANADA: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 177
CANADA: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 178
CANADA: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 179
CANADA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 180
CANADA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 181
CANADA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 182
CANADA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 183
MEXICO: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 184
MEXICO: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 185
MEXICO: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 186
MEXICO: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 187
MEXICO: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 188
MEXICO: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 189
MEXICO: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 190
MEXICO: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 191
MIDDLE EAST & AFRICA: CAPS & CLOSURES MARKET, BY COUNTRY, 2022–2024 (USD MILLION)


TABLE 192
MIDDLE EAST & AFRICA: CAPS & CLOSURES MARKET, BY COUNTRY, 2025–2031 (USD MILLION)


TABLE 193
MIDDLE EAST & AFRICA: CAPS & CLOSURES MARKET, BY COUNTRY, 2022–2024 (BILLION UNITS)


TABLE 194
MIDDLE EAST & AFRICA: CAPS & CLOSURES MARKET, BY COUNTRY, 2025–2031 (BILLION UNITS)


TABLE 195
MIDDLE EAST & AFRICA: CAPS & CLOSURES MARKET, BY RAW MATERIAL, 2022–2024 (USD MILLION)


TABLE 196
MIDDLE EAST & AFRICA: CAPS & CLOSURES MARKET, BY RAW MATERIAL, 2025–2031 (USD MILLION)


TABLE 197
MIDDLE EAST & AFRICA: CAPS & CLOSURES MARKET, BY RAW MATERIAL, 2022–2024 (BILLION UNITS)


TABLE 198
MIDDLE EAST & AFRICA: CAPS & CLOSURES MARKET, BY RAW MATERIAL, 2025–2031 (BILLION UNITS)


TABLE 199
MIDDLE EAST & AFRICA: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 200
MIDDLE EAST & AFRICA: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 201
MIDDLE EAST & AFRICA: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 202
MIDDLE EAST & AFRICA: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 203
MIDDLE EAST & AFRICA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 204
MIDDLE EAST & AFRICA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 205
MIDDLE EAST & AFRICA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 206
MIDDLE EAST & AFRICA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 207
GCC COUNTRIES: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 208
GCC COUNTRIES: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 209
GCC COUNTRIES: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 210
GCC COUNTRIES: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 211
GCC COUNTRIES: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 212
GCC COUNTRIES: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 213
GCC COUNTRIES: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 214
GCC COUNTRIES: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 215
SAUDI ARABIA: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 216
SAUDI ARABIA: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 217
SAUDI ARABIA: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 218
SAUDI ARABIA: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 219
SAUDI ARABIA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 220
SAUDI ARABIA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 221
SAUDI ARABIA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 222
SAUDI ARABIA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 223
UAE: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 224
UAE: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 225
UAE: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 226
UAE: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 227
UAE: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 228
UAE: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 229
UAE: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 230
UAE: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 231
REST OF GCC COUNTRIES: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 232
REST OF GCC COUNTRIES: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 233
REST OF GCC COUNTRIES: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 234
REST OF GCC COUNTRIES: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 235
REST OF GCC COUNTRIES: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 236
REST OF GCC COUNTRIES: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 237
REST OF GCC COUNTRIES: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 238
REST OF GCC COUNTRIES: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 239
SOUTH AFRICA: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 240
SOUTH AFRICA: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 241
SOUTH AFRICA: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 242
SOUTH AFRICA: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 243
SOUTH AFRICA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 244
SOUTH AFRICA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 245
SOUTH AFRICA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 246
SOUTH AFRICA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 247
REST OF MIDDLE EAST & AFRICA: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 248
REST OF MIDDLE EAST & AFRICA: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 249
REST OF MIDDLE EAST & AFRICA: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 250
REST OF MIDDLE EAST & AFRICA: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 251
REST OF MIDDLE EAST & AFRICA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 252
REST OF MIDDLE EAST & AFRICA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 253
REST OF MIDDLE EAST & AFRICA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 254
REST OF MIDDLE EAST & AFRICA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 255
SOUTH AMERICA: CAPS & CLOSURES MARKET, BY COUNTRY, 2022–2024 (USD MILLION)


TABLE 256
SOUTH AMERICA: CAPS & CLOSURES MARKET, BY COUNTRY, 2025–2031 (USD MILLION)


TABLE 257
SOUTH AMERICA: CAPS & CLOSURES MARKET, BY COUNTRY, 2022–2024 (BILLION UNITS)


TABLE 258
SOUTH AMERICA: CAPS & CLOSURES MARKET, BY COUNTRY, 2025–2031 (BILLION UNITS)


TABLE 259
SOUTH AMERICA: CAPS & CLOSURES MARKET, BY RAW MATERIAL, 2022–2024 (USD MILLION)


TABLE 260
SOUTH AMERICA: CAPS & CLOSURES MARKET, BY RAW MATERIAL, 2025–2031 (USD MILLION)


TABLE 261
SOUTH AMERICA: CAPS & CLOSURES MARKET, BY RAW MATERIAL, 2022–2024 (BILLION UNITS)


TABLE 262
SOUTH AMERICA: CAPS & CLOSURES MARKET, BY RAW MATERIAL, 2025–2031 (BILLION UNITS)


TABLE 263
SOUTH AMERICA: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 264
SOUTH AMERICA: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 265
SOUTH AMERICA: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 266
SOUTH AMERICA: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 267
SOUTH AMERICA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 268
SOUTH AMERICA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 269
SOUTH AMERICA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 270
SOUTH AMERICA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 271
BRAZIL: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 272
BRAZIL: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 273
BRAZIL: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 274
BRAZIL: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 275
BRAZIL: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 276
BRAZIL: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 277
BRAZIL: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 278
BRAZIL: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 279
ARGENTINA: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 280
ARGENTINA: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 281
ARGENTINA: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 282
ARGENTINA: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 283
ARGENTINA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 284
ARGENTINA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 285
ARGENTINA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 286
ARGENTINA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 287
REST OF SOUTH AMERICA: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (USD MILLION)


TABLE 288
REST OF SOUTH AMERICA: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (USD MILLION)


TABLE 289
REST OF SOUTH AMERICA: CAPS & CLOSURES MARKET, BY TYPE, 2022–2024 (BILLION UNITS)


TABLE 290
REST OF SOUTH AMERICA: CAPS & CLOSURES MARKET, BY TYPE, 2025–2031 (BILLION UNITS)


TABLE 291
REST OF SOUTH AMERICA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (USD MILLION)


TABLE 292
REST OF SOUTH AMERICA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (USD MILLION)


TABLE 293
REST OF SOUTH AMERICA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2022–2024 (BILLION UNITS)


TABLE 294
REST OF SOUTH AMERICA: CAPS & CLOSURES MARKET, BY END-USE INDUSTRY, 2025–2031 (BILLION UNITS)


TABLE 295
CAPS & CLOSURES MARKET: OVERVIEW OF MAJOR STRATEGIES ADOPTED BY KEY PLAYERS, JANUARY 2024–AUGUST 2026


TABLE 296
CAPS & CLOSURES MARKET: DEGREE OF COMPETITION


TABLE 297
CAPS & CLOSURES MARKET: REGION FOOTPRINT


TABLE 298
CAPS & CLOSURES MARKET: RAW MATERIAL FOOTPRINT


TABLE 299
CAPS & CLOSURES MARKET: TYPE FOOTPRINT


TABLE 300
CAPS & CLOSURES MARKET: END-USE INDUSTRY FOOTPRINT


TABLE 301
CAPS & CLOSURES MARKET: DETAILED LIST OF KEY STARTUPS/SMES


TABLE 302
CAPS & CLOSURES MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES, 2025


TABLE 303
CAPS & CLOSURES MARKET: PRODUCT LAUNCHES, JANUARY 2024–AUGUST 2026


TABLE 304
CAPS & CLOSURES MARKET: DEALS, JANUARY 2024–AUGUST 2026


TABLE 305
CAPS & CLOSURES MARKET: EXPANSIONS, JANUARY 2024–AUGUST 2026


TABLE 306
AMCOR PLC: COMPANY OVERVIEW


TABLE 307
AMCOR PLC: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 308
AMCOR PLC: PRODUCT LAUNCHES, JANUARY 2024–AUGUST 2026


TABLE 309
AMCOR PLC: DEALS, JANUARY 2024–AUGUST 2026


TABLE 310
AMCOR PLC: EXPANSIONS, JANUARY 2024–AUGUST 2026


TABLE 311
CROWN HOLDINGS, INC.: COMPANY OVERVIEW


TABLE 312
CROWN HOLDINGS, INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 313
CROWN HOLDINGS, INC.: DEALS, JANUARY 2024–AUGUST 2026


TABLE 314
CROWN HOLDINGS, INC.: EXPANSIONS, JANUARY 2024–AUGUST 2026


TABLE 315
SILGAN HOLDINGS INC.: COMPANY OVERVIEW


TABLE 316
SILGAN HOLDINGS INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 317
SILGAN HOLDINGS INC.: PRODUCT LAUNCHES, JANUARY 2024–AUGUST 2026


TABLE 318
SILGAN HOLDINGS INC.: DEALS, JANUARY 2024–AUGUST 2026


TABLE 319
APTARGROUP, INC.: COMPANY OVERVIEW


TABLE 320
APTARGROUP, INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 321
APTARGROUP, INC.: PRODUCT LAUNCHES, JANUARY 2024–AUGUST 2026


TABLE 322
APTARGROUP, INC.: DEALS, JANUARY 2024–AUGUST 2026


TABLE 323
BERICAP: COMPANY OVERVIEW


TABLE 324
BERICAP: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 325
BERICAP: DEALS, JANUARY 2024–AUGUST 2026


TABLE 326
BERICAP: EXPANSIONS, JANUARY 2024–AUGUST 2026


TABLE 327
GUALA CLOSURES S.P.A: COMPANY OVERVIEW


TABLE 328
GUALA CLOSURES S.P.A: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 329
GUALA CLOSURES S.P.A: PRODUCT LAUNCHES, JANUARY 2024–AUGUST 2026


TABLE 330
GUALA CLOSURES S.P.A: DEALS, JANUARY 2024–AUGUST 2026


TABLE 331
GUALA CLOSURES S.P.A: EXPANSIONS, JANUARY 2024–AUGUST 2026


TABLE 332
ALPLA GROUP: COMPANY OVERVIEW


TABLE 333
ALPLA GROUP: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 334
ALPLA GROUP: DEALS, JANUARY 2024–AUGUST 2026


TABLE 335
ALPLA GROUP: EXPANSIONS, JANUARY 2024–AUGUST 2026


TABLE 336
CLOSURE SYSTEMS INTERNATIONAL: COMPANY OVERVIEW


TABLE 337
CLOSURE SYSTEMS INTERNATIONAL: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 338
CLOSURE SYSTEMS INTERNATIONAL: PRODUCT LAUNCHES, JANUARY 2024–AUGUST 2026


TABLE 339
CLOSURE SYSTEMS INTERNATIONAL: DEALS, JANUARY 2024–AUGUST 2026


TABLE 340
UNITED CAPS: COMPANY OVERVIEW


TABLE 341
UNITED CAPS: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 342
UNITED CAPS: PRODUCT LAUNCHES, JANUARY 2024–AUGUST 2026


TABLE 343
ALCOPACK GROUP: COMPANY OVERVIEW


TABLE 344
ALCOPACK GROUP: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 345
TRIMAS: COMPANY OVERVIEW


TABLE 346
CORAL PRODUCTS PLC: COMPANY OVERVIEW


TABLE 347
HERTI JSC: COMPANY OVERVIEW


TABLE 348
PANO CAP CANADA LTD.: COMPANY OVERVIEW


TABLE 349
PHOENIX: COMPANY OVERVIEW


TABLE 350
MRP SOLUTIONS: COMPANY OVERVIEW


TABLE 351
PRECISION CONCEPTS INTERNATIONAL LLC: COMPANY OVERVIEW


TABLE 352
CAPRITE AUSTRALIA: COMPANY OVERVIEW


TABLE 353
CAPS AND CLOSURES PTY LTD: COMPANY OVERVIEW


TABLE 354
PRETIUM PACKAGING: COMPANY OVERVIEW


TABLE 355
TECNOCAP S.P.A.: COMPANY OVERVIEW


TABLE 356
PURV GROUP: COMPANY OVERVIEW


TABLE 357
AGLO: COMPANY OVERVIEW


TABLE 358
SECURE INDUSTRIES PVT. LTD.: COMPANY OVERVIEW


TABLE 359
ORIGIN MATERIALS: COMPANY OVERVIEW


LIST OF FIGURES


FIGURE 1
CAPS & CLOSURES MARKET SEGMENTATION AND REGIONAL SCOPE


FIGURE 2
KEY INSIGHTS AND MARKET HIGHLIGHTS


FIGURE 3
CAPS & CLOSURES MARKET, 2022–2031


FIGURE 4
MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN CAPS & CLOSURES MARKET (2020-2025)


FIGURE 5
DISRUPTIVE TRENDS IMPACTING GROWTH OF CAPS & CLOSURES MARKET DURING FORECAST PERIOD


FIGURE 6
HIGH-GROWTH SEGMENTS AND EMERGING FRONTIERS IN CAPS & CLOSURES MARKET, 2026-2031


FIGURE 7
ASIA PACIFIC TO REGISTER HIGHEST GROWTH DURING FORECAST PERIOD


FIGURE 8
GROWING DEMAND FOR SUSTAINABLE AND CONVENIENT PACKAGING TO CREATE LUCRATIVE OPPORTUNITIES FOR MARKET PLAYERS


FIGURE 9
PLASTIC AND CHINA ACCOUNTED FOR LARGEST MARKET SHARES IN 2025


FIGURE 10
PLASTIC SEGMENT DOMINATED CAPS & CLOSURES MARKET IN 2025


FIGURE 11
PLASTIC CAPS & CLOSURES SEGMENT DOMINATED CAPS & CLOSURES MARKET IN 2025


FIGURE 12
BEVERAGE PACKAGING DOMINATED CAPS & CLOSURES MARKET IN 2025


FIGURE 13
INDIA TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD


FIGURE 14
CAPS & CLOSURES MARKET DYNAMICS


FIGURE 15
US BOTTLED WATER MARKET


FIGURE 16
TOP BOTTLED WATER CONSUMING COUNTRIES


FIGURE 17
BEVERAGE BOOM IN INDIA


FIGURE 18
PORTER’S FIVE FORCES ANALYSIS OF CAPS & CLOSURES MARKET


FIGURE 19
CAPS & CLOSURES MARKET: VALUE CHAIN ANALYSIS


FIGURE 20
CAPS & CLOSURES MARKET: ECOSYSTEM ANALYSIS


FIGURE 21
PRICE RANGE BY TYPE, BY KEY PLAYERS, 2025 (USD/THOUSAND UNITS)


FIGURE 22
CAPS & CLOSURES MARKET: AVERAGE SELLING PRICE TREND, BY REGION, (2022-2025) (USD/THOUSAND UNITS)


FIGURE 23
EXPORT DATA FOR HS CODE 392350-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025 (USD MILLION)


FIGURE 24
IMPORT DATA FOR HS CODE 392350-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025 (USD MILLION)


FIGURE 25
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS


FIGURE 26
INVESTMENT AND FUNDING SCENARIO, 2020–2025


FIGURE 27
LIST OF MAJOR PATENTS FOR CAPS & CLOSURES, 2016–2025


FIGURE 28
MAJOR PATENTS APPLIED AND GRANTED RELATED TO CAPS & CLOSURES, BY COUNTRY/REGION, 2016–2025


FIGURE 29
CAPS & CLOSURES MARKET DECISION-MAKING FACTORS


FIGURE 30
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY END-USE INDUSTRY


FIGURE 31
KEY BUYING CRITERIA, BY END-USE INDUSTRY


FIGURE 32
ADOPTION BARRIERS & INTERNAL CHALLENGES


FIGURE 33
PLASTIC SEGMENT TO REGISTER HIGHEST GROWTH RATE THROUGH 2031


FIGURE 34
PLASTIC CAPS & CLOSURES SEGMENT TO REGISTER HIGHEST GROWTH THROUGH 2031


FIGURE 35
BEVERAGE PACKAGING INDUSTRY TO BE LARGEST CONSUMER OF CAPS & CLOSURES


FIGURE 36
ASIA PACIFIC PROJECTED TO BE FASTEST-GROWING OF CAPS & CLOSURES MARKET DURING FORECAST PERIOD


FIGURE 37
INDIA PROJECTED TO BE FASTEST-GROWING COUNTRY OF CAPS & CLOSURES MARKET DURING FORECAST PERIOD


FIGURE 38
ASIA PACIFIC: PLASTIC CAPS & CLOSURES MARKET SNAPSHOT


FIGURE 39
EUROPE: CAPS & CLOSURES MARKET SNAPSHOT


FIGURE 40
REVENUE ANALYSIS OF KEY PLAYERS IN CAPS & CLOSURES MARKET, 2021–2025


FIGURE 41
CAPS & CLOSURES MARKET SHARE ANALYSIS, 2025


FIGURE 42
COMPANY VALUATION, 2025 (USD BILLION)


FIGURE 43
FINANCIAL MATRIX: EV/EBITDA RATIO


FIGURE 44
YEAR-TO-DATE PRICE AND FIVE-YEAR STOCK BETA


FIGURE 45
CAPS & CLOSURES MARKET: BRAND/PRODUCT COMPARISON


FIGURE 46
CAPS & CLOSURES MARKET: COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025


FIGURE 47
CAPS & CLOSURES MARKET: COMPANY FOOTPRINT


FIGURE 48
COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025


FIGURE 49
AMCOR PLC: COMPANY SNAPSHOT


FIGURE 50
CROWN HOLDINGS, INC.: COMPANY SNAPSHOT


FIGURE 51
SILGAN HOLDINGS INC.: COMPANY SNAPSHOT


FIGURE 52
APTARGROUP, INC.: COMPANY SNAPSHOT


FIGURE 53
GUALA CLOSURES S.P.A: COMPANY SNAPSHOT


FIGURE 54
CAPS & CLOSURES MARKET: RESEARCH DESIGN


FIGURE 55
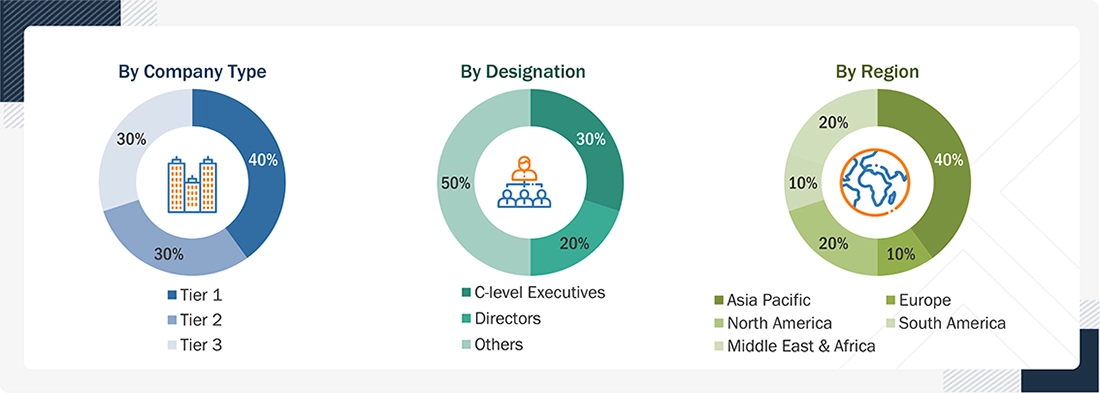
BREAKDOWN OF INTERVIEWS WITH EXPERTS


FIGURE 56
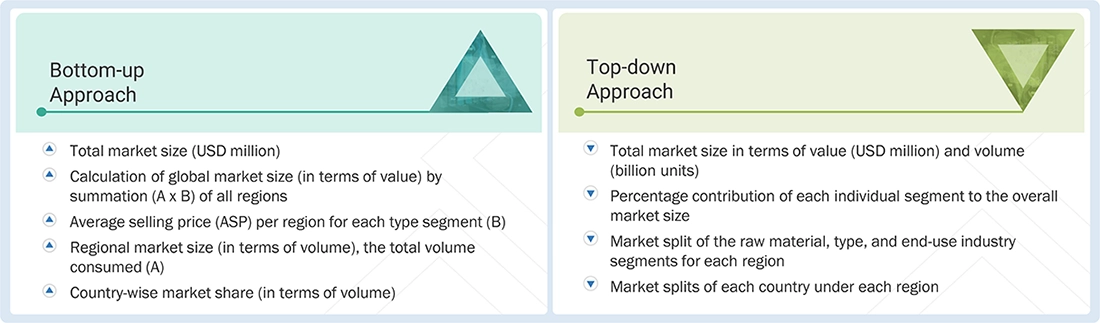
MARKET SIZE ESTIMATION: BOTTOM-UP APPROACH


FIGURE 57
MARKET SIZE ESTIMATION: TOP-DOWN APPROACH


FIGURE 58
APPROACH 1: SUPPLY-SIDE APPROACH


FIGURE 59
CAPS & CLOSURES MARKET: DATA TRIANGULATION


Methodology

The study involved four major activities to estimate the current size of the global caps & closures market. Exhaustive secondary research was carried out to collect information on the market, the peer product market, and the parent product group market. The next step was to validate these findings, assumptions, and sizes with industry experts across the caps & closures value chain through primary research. The top-down and bottom-up approaches were employed to estimate the overall size of the caps & closures market. After that, market breakdown and data triangulation procedures were used to determine the size of different segments and sub-segments of the market.

Secondary Research

The market for companies offering caps & closures was determined using secondary data available through paid and unpaid sources, analyzing the product portfolios of the major companies in the ecosystem, and rating the companies by their performance and quality. Various secondary sources, such as Business Standard, Bloomberg, World Bank, and Factiva, were referred to identify and collect information for this study on the caps & closures market. In the secondary research process, various secondary sources were referred to identify and collect information related to the study. Secondary sources included annual reports, press releases, and investor presentations of door vendors, forums, certified publications, and whitepapers. The secondary research was used to obtain critical information on the industry’s value chain, the total pool of key players, market classification, and segmentation from market- and technology-oriented perspectives.

Primary Research

In the primary research process, various primary sources from both the supply and demand sides were interviewed to obtain qualitative and quantitative information for this report. The primary sources from the supply side included industry experts, such as Chief Executive Officers (CEOs), Vice Presidents (VPs), marketing directors, technology and innovation directors, and related key executives from several key companies and organizations operating in the caps & closures market. After the complete market engineering (calculations for market statistics, market breakdown, market size estimations, market forecasting, and data triangulation), extensive primary research was conducted to gather information and verify and validate the critical numbers arrived at. Primary research was also conducted to identify the segmentation types, industry trends, competitive landscape of caps & closures offered by various market players, and key market dynamics, such as drivers, restraints, opportunities, challenges, industry trends, and key player strategies. In the complete market engineering process, the top-down and bottom-up approaches and several data triangulation methods were extensively used to perform the market estimation and market forecasting for the overall market segments and subsegments listed in this report. Extensive qualitative and quantitative analysis was performed on the complete market engineering process to list the key information/insights throughout the report.

The following is the breakdown of primary respondents:

Caps & Closures Market Size, and Share

Notes: Other designations include sales, marketing, and product managers.
Tier 1: >USD 1 Billion; Tier 2: USD 500 Million–1 Billion; and Tier 3: <USD 500 Million.

To know about the assumptions considered for the study, download the pdf brochure

Market Size Estimation

The top-down and bottom-up approaches were used to estimate and validate the size of the global caps & closures market. These approaches were also used extensively to estimate the size of various dependent market segments. The research methodology used to estimate the market size included the following:

Caps & Closures Market: Top-Down and Bottom-Up Approach

Caps & Closures Market Top Down and Bottom Up Approach

Data Triangulation

After arriving at the overall market size using the market size estimation processes, the market was split into several segments and subsegments. The data triangulation and market breakup procedures were employed, wherever applicable, to complete the overall market engineering process and arrive at the exact statistics of each market segment and subsegment. The data was triangulated by studying various factors and trends from both the demand and supply sides.

Market Definition

Caps & closures are components used to seal and secure containers, protecting packaged products from contamination, leakage, moisture, oxygen, and other external factors. They are widely used across bottles, jars, jugs, tubes, and other packaging formats to preserve product quality and enable controlled dispensing. Caps and closures include screw caps, snap-on caps, flip-top closures, dispensing closures, tamper-evident closures, child-resistant closures, sports closures, and overcaps. Depending on the application, they are manufactured from materials such as plastic, metal, and rubber or elastomers. Caps and closures play an important role in extending product shelf life, ensuring package integrity, improving convenience, and supporting product differentiation through design, functionality, and printability.

Key Stakeholders

  • Caps & closures manufacturers
  • Raw material suppliers
  • Converters & processors
  • Distributors and traders
  • Industry associations and regulatory bodies
  • End users

Report Objectives

  • To define, describe, and forecast the size of the global caps & closures market, based on raw material, type, end-use industry, and region in terms of value
  • To provide detailed information on the significant drivers, restraints, opportunities, and challenges influencing the market
  • To strategically analyze micromarkets concerning individual growth trends, prospects, and their contribution to the market
  • To assess the growth opportunities in the market for stakeholders and provide details on the competitive landscape for market leaders
  • To forecast the market size of segments and subsegments for North America, Europe, Asia Pacific, South America, and Middle East & Africa.
  • To strategically profile key players and comprehensively analyze their market shares and core competencies
  • To analyze competitive developments such as product launches, acquisitions, expansions, partnerships, and agreements in the caps & closures market
  • To provide the impact of AI/Gen AI on the market

Available customizations:

With the given market data, MarketsandMarkets offers customizations according to client-specific needs.
The following customization options are available for the caps & closures market report:

Product Analysis

  • A product matrix that gives a detailed comparison of the product portfolio of each company

Regional Analysis

  • A further breakdown of the caps & closures market for additional countries

Company Information

  • Detailed analysis and profiling of additional market players (up to five)

Personalize This Research

  • Triangulate with your Own Data
  • Get Data as per your Format and Definition
  • Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
  • Any level of Personalization
Request A Free Customisation

Let Us Help You

  • What are the Known and Unknown Adjacencies Impacting the Caps & Closures Market

  • What will your New Revenue Sources be?
  • Who will be your Top Customer; what will make them switch?
  • Defend your Market Share or Win Competitors
  • Get a Scorecard for Target Partners
Customized Workshop Request

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements

Get 10% Free Customisation

TESTIMONIALS

Growth opportunities and latent adjacency in Caps & Closures Market

DMCA.com Protection Status
popup img