North America Data Center Busways Market (2026-2031)
The North America Data Center Busways Market was valued at $2033.7 Million in 2026 and projected to reach to $3992.5 Million by 2031, representing a compound annual growth rate of 11.9%. North America's data center busways market is positioned for sustained expansion through 2031, driven by accelerating digital transformation initiatives, cloud migration strategies, and AI infrastructure buildout across the region.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
North America Data Center Busways Market Trends and Insights
- This expansion reflects North America's critical role as a global hub for cloud computing, artificial intelligence, and enterprise data infrastructure.
- North America's market growth is driven by accelerating digital transformation initiatives and substantial investments in hyperscale data center facilities across the United States and Canada. The 11.9% compound annual growth rate (CAGR) through 2031 underscores North America's leadership in adopting advanced power distribution solutions within data centers.
- North America's demand for efficient, scalable busway systems is intensifying as operators prioritize energy efficiency and operational reliability.
- North America continues to attract major technology investments, positioning the region as a cornerstone market for data center infrastructure innovation and modernization..
Key Market Statistics
- CAGR (2026-2031) 11.9% CAGR
- Market Size, 2026 ~USD 2033.7 Million
- Forecast, 2031 ~USD 3992.5 Million
- Geography North America
North America Data Center Busways Market Overview
Market Valuation & Growth Trajectory :
North America's data center busways market is valued at $2,033.7 million in 2026 and is projected to reach $3,992.5 million by 2031, representing a robust 11.9% CAGR. This growth significantly outpaces many global regions and underscores North America's strategic importance in data infrastructure investment.
Cloud & AI Infrastructure Expansion :
The region's dominance in cloud computing and artificial intelligence deployment is driving substantial demand for advanced power distribution solutions. Major tech hubs across the US, Canada, and Mexico are investing heavily in next-generation data center facilities to support AI workloads and enterprise cloud migration.
US Market Leadership :
The United States commands the largest share of North America's busways market at $3,641.2 million, reflecting its position as the global epicenter for hyperscale data center development. US investments in edge computing and 5G infrastructure continue to fuel busway system adoption.
Regional Infrastructure Modernization :
Canada ($263.5 million) and Mexico ($87.8 million) are emerging as secondary growth drivers, with increasing investments in data center capacity to support regional digital transformation and nearshoring trends from North American enterprises.
North America Data Center Busways Market Dynamics
- The market's 11.9% CAGR reflects strong capital expenditure from hyperscalers, enterprise data centers, and colocation providers investing in efficient power distribution systems. The region benefits from established technology ecosystems, regulatory frameworks supporting data center development, and significant venture capital funding for infrastructure modernization.
- As organizations prioritize energy efficiency and operational reliability, busway systems—offering superior thermal management and scalability—are becoming essential components of next-generation data center designs across North America..
Market Ecosystem
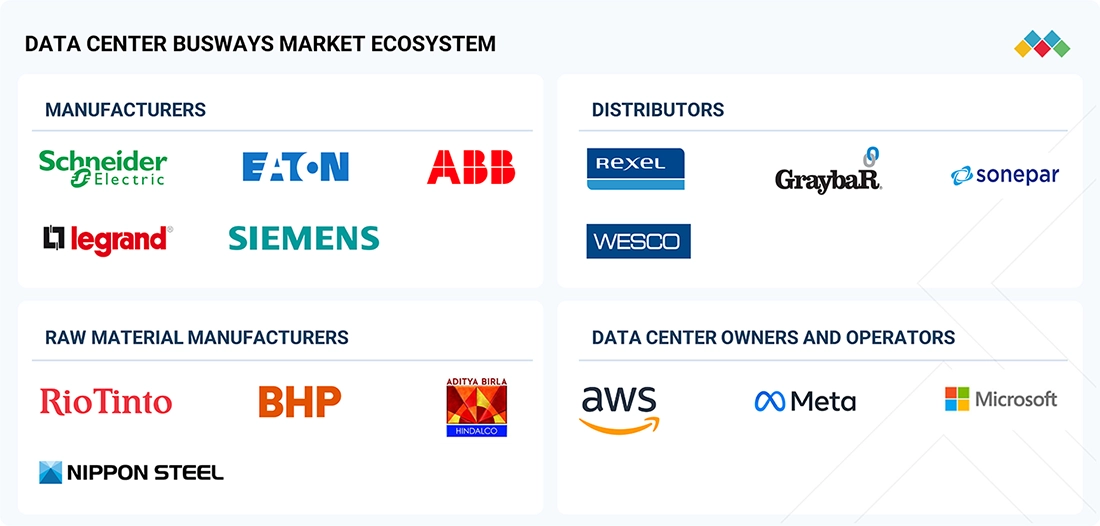
DATA CENTER BUSWAYS MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Provides modular and scalable power distribution solutions for hyperscale cloud, colocation, enterprise, and AI-ready data centers | Supports rapid deployment and expansion of high-density computing environments through flexible electrical distribution architectures | Enables faster deployment of IT infrastructure | Simplifies power distribution reconfiguration | Reduces installation complexity compared to traditional cabling | Supports increasing power demands associated with AI and HPC workloads |
 |
Delivers overhead power distribution systems used across hyperscale, colocation, enterprise, and high-performance computing facilities | Supports dynamic rack layouts and changing power requirements through flexible plug-and-play power distribution architectures | Enhances operational flexibility | Reduces downtime during infrastructure modifications | Improves space utilization | Supports evolving compute requirements in cloud and AI-driven environments |
 |
Provides configurable power distribution solutions for mission-critical facilities, cloud campuses, enterprise data centers, and colocation environments | Supports scalable electrical infrastructure capable of adapting to changing capacity requirements and facility expansions | Enhances power infrastructure scalability | Expedites capacity expansion | Simplifies maintenance requirements | Improves operational efficiency through flexible and configurable power distribution architectures |
 |
Supplies modular electrical distribution solutions for hyperscale, enterprise, and colocation data centers requiring reliable and efficient power delivery | Supports long-term infrastructure growth through scalable and expandable power architectures | Increases power distribution reliability | Enables modular facility expansion | Improves electrical efficiency | Minimizes operational disruption during infrastructure upgrades and expansions |
 |
Provides busbar power distribution systems designed to meet the demand of enterprise facilities, cloud campuses, large data centers and other mission-critical locations | Enables the high efficiency power transmission and meet the demand for future capacity growth and upgrade of the facility | Reduces cable complexity | Improves installation efficiency | Supports future scalability requirements | Enhances reliability of mission-critical electrical infrastructure |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Equipment Machine And Tooling
- Wastewater Treatment
- Air Cooled Heat Exchangers
- Diaphragm Pumps
- Fiberglass
- HVAC System
- Alfa Laval Corporate AB
- Johnson Controls International plc
- Daikin Industries,Ltd.
- Veolia
- Carrier Global Corporation
Key Takeaways
- North America's data center busways market will nearly double from $2,033.7M (2026) to $3,992.5M (2031), reflecting strong infrastructure investment momentum.
- North America's 11.9% CAGR demonstrates sustained demand for efficient power distribution solutions in hyperscale and enterprise data centers.
- North America's market leadership is fueled by cloud adoption, AI workloads, and digital transformation across enterprise and technology sectors.
- North America's focus on energy efficiency and operational reliability drives adoption of advanced busway technologies in new and retrofitted facilities.
Data Center Busways Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2026 |
| Fastest Growing Segment | DC (Power Source) |
| Forecast Period | 2026-2031 |
| Growth Rate | CAGR of 15.1% from 2026 to 2031 |
| Largest Segment | AC (Power Source) |
| Market Size Base Year (Billions) | ~USD 3.7 (2026) |
| Revenue Forecast (Billions) | ~USD 7.47 (2031) |
| Segments Covered | It Load, Conductor Type, Power Source, Data Center Type, Power Ampacity |
North America Data Center Busways Market Report Segmentation
5 segment dimensions are covered across the global market.
By It Load
- AI
- Non-AI
By Conductor Type
- Aluminum & Hybrid
- Copper
By Power Source
- Ac
- Dc
By Data Center Type
- Colocation
- Enterprise
- Hyperscale
By Power Ampacity
- High Ampacity (1250A To 2000A)
- Low Ampacity (Up To 600A)
- Medium Ampacity (800A To 1000A)
- Very High Ampacity (>2000A)
Target Audience
- Data Center Operators & Hyperscalers : Require detailed market insights to optimize busway procurement strategies, plan facility upgrades, and allocate capital across North American data center portfolios experiencing rapid expansion.
- Electrical Equipment Manufacturers : Need regional market data to guide product development, manufacturing capacity planning, and sales strategy for busway systems targeting North American data center customers.
- Infrastructure Investment Firms : Utilize market forecasts and growth projections to evaluate investment opportunities in North American data center infrastructure, including busway technology providers and facility operators.
- System Integrators & Engineering Firms : Require market intelligence to identify client demand trends, justify technology recommendations, and develop competitive proposals for data center power distribution solutions across North America.
- Enterprise IT & Procurement Leaders : Need insights into busway market evolution and vendor landscape to make informed decisions on data center infrastructure upgrades and colocation partnerships in North America.
Countries within North America - compare and drill down
| Country | 2025 size (native) |
|---|---|
| US | USD 3641.2 Million |
| Canada | USD 263.5 Million |
| Mexico | USD 87.8 Million |
Country market size visualization
Reasons to Buy this Report
- Market Size & Growth Validation : Obtain precise market valuation data for North America ($2,033.7M in 2026) with verified forecasts through 2031, enabling accurate business planning and investment decisions for regional expansion strategies.
- Country-Level Competitive Intelligence : Access granular market data for the US ($3,641.2M), Canada ($263.5M), and Mexico ($87.8M) to identify high-opportunity markets and tailor go-to-market strategies for specific North American segments.
- Technology Trend Analysis : Understand how cloud computing, AI infrastructure, and digital transformation initiatives are reshaping busway demand across North America, enabling product development aligned with regional market needs.
- Investment & Expansion Planning : Leverage 11.9% CAGR projections and market forecasts to justify capital allocation, facility expansion, and partnership development across North American data center ecosystems.
- Competitive Positioning : Benchmark your organization against regional market dynamics and identify white-space opportunities in emerging North American markets like Mexico and secondary US metropolitan areas.
Frequently asked questions
What is the projected market size for data center busways in North America by 2031?
North America's data center busways market is forecast to reach $3,992.5 million by 2031, up from $2,033.7 million in 2026.
What is the CAGR for North America's data center busways market?
North America's data center busways market is expected to grow at a compound annual growth rate (CAGR) of 11.9% from 2026 to 2031.
What factors are driving growth in North America's data center busways market?
North America's market growth is driven by increased cloud computing adoption, AI infrastructure expansion, hyperscale data center development, and enterprise digital transformation initiatives.
Why is North America a key market for data center busways?
North America leads globally in data center infrastructure investment, cloud services, and technology innovation, making it a critical market for advanced power distribution solutions.
How much will North America's data center busways market grow in absolute terms?
North America's market will grow by approximately $1,958.8 million between 2026 and 2031, nearly doubling in size over the five-year forecast period.
RESEARCH METHODOLOGY
The study involved four major activities in estimating the current market size of data center busways. Exhaustive secondary research was done to collect information on the market, the peer market, and the parent market. The next step was to validate these findings, assumptions, and sizes with industry experts across the value chain of data center busways through primary research. Both top-down and bottom-up approaches were employed to estimate the complete market size. After that, market breakdown and data triangulation were used to estimate the size of the segments and sub-segments of the market.
Secondary Research
The research methodology used to estimate and forecast the data center busways market begins with capturing data on the revenues of key vendors in the market through secondary research. In the secondary research process, various secondary sources, such as Hoovers, Bloomberg Businessweek, Factiva, World Bank, Uptime Institute, JLL Data Center Outlook, AFCOM, and industry journals, were referred to for identifying and collecting information for this study. These secondary sources included annual reports, press releases, and investor presentations of companies; white papers; certified publications; articles by recognized authors; notifications by regulatory bodies; trade directories; and databases. Product portfolios and business developments of market participants were also taken into consideration to determine market segmentation and competitive positioning.
Primary Research
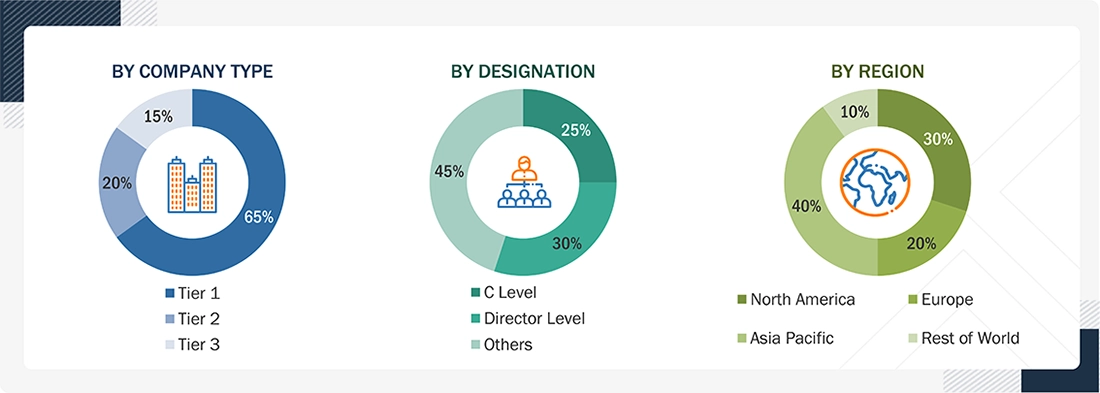
The data center busways market comprises several stakeholders, such as busway manufacturers, power distribution equipment suppliers, data center developers, colocation providers, and regulatory organizations in the supply chain. Various primary sources from both the supply and demand sides of the market were interviewed to obtain qualitative and quantitative information. Primary sources from the supply side included industry experts such as Chief Executive Officers (CEOs), vice presidents, marketing directors, technology and innovation directors, and related key executives from various key companies and organizations operating in the data center busways market. Primary sources from the demand side included directors, marketing heads, and purchase managers from various end-use industries. The following is the breakdown of the primary respondents:
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
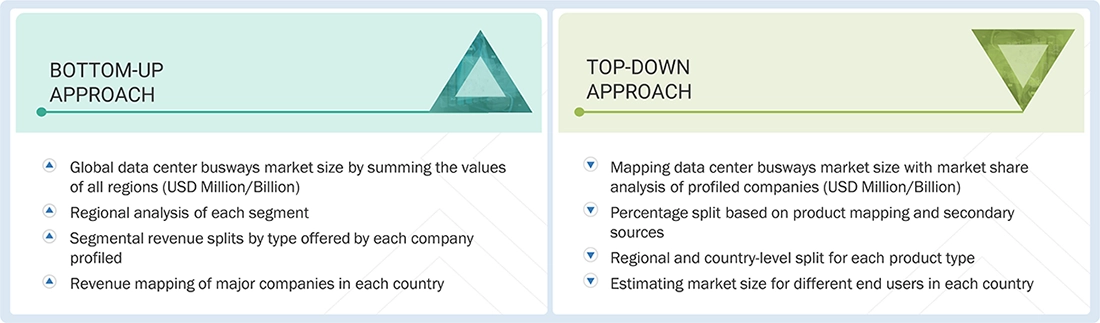
Both the top-down and bottom-up approaches have been used to estimate and validate the total size of the data center busways market. These approaches have also been used extensively to estimate the size of various dependent subsegments of the market. The research methodology used to estimate the market size included the following.
The following segments provide details about the overall market size estimation process employed in this study:
- The key players in the market were identified through secondary research.
- The market shares in the respective regions were identified through primary and secondary research.
- The value chain and market size of the data center busways market, in terms of value, were determined through primary and secondary research.
- All percentage shares, splits, and breakdowns were determined using secondary sources and verified through primary sources.
- All possible parameters that affect the market covered in this research study were accounted for, viewed in extensive detail, verified through primary research, and analyzed to obtain the final quantitative and qualitative data.
- The research included the study of annual and financial reports of the top market players and interviews with industry experts, such as CEOs, VPs, directors, sales managers, and marketing executives.
Global Data Center Busways Market Size: Bottom-Up Approach and Top-Down Approach
Data Triangulation
After arriving at the overall market size using the market size estimation processes as explained above, the market was split into several segments and sub-segments. To complete the overall market engineering process and arrive at the exact statistics of each market segment and subsegment, the data triangulation and market breakdown procedures were employed, wherever applicable. The data was triangulated by studying various factors and trends from both the demand and supply sides in various sectors.
Market Definition
Data center busways are modular electrical power distribution systems used to deliver power from upstream electrical infrastructure to IT equipment within data center facilities. These systems provide a flexible, scalable, and efficient alternative to conventional cable-based power distribution architectures, enabling simplified installation, capacity expansion, and maintenance. Data center busways are deployed across enterprise, colocation, and hyperscale facilities and are available in various configurations based on power source, conductor type, and ampacity requirements. They are increasingly adopted to support higher rack densities, artificial intelligence workloads, and growing power demands in modern data center environments.
Key Stakeholders
- Data center busway manufacturers
- Data center busway traders, distributors, and suppliers
- Data center busway developers, operators, colocation providers, and hyperscalers
- Governments and research organizations
- Associations and industrial bodies
- Research and consulting firms
- Research & development (R&D) institutions
- Investment banks and private equity firms
Report Objectives
- To analyze and forecast the market size of the data center busways market in terms of value
- To provide detailed information regarding the major factors (drivers, restraints, challenges, and opportunities) influencing the market
- To analyze and forecast the global data center busways market on the basis of IT load type, power ampacity, power source, conductor type, data center type, and region
- To analyze the opportunities in the market for stakeholders and provide details of the competitive landscape for market leaders
- To forecast the size of various market segments based on five major regions: Asia Pacific, Europe, North America, the Rest of World, along with their respective key countries
- To track and analyze the competitive developments, such as acquisitions, partnerships, collaborations, agreements, and expansions in the market
- To strategically profile the key players and comprehensively analyze their market shares and core competencies
Available customizations:
With the given market data, MarketsandMarkets offers customizations according to the client-specific needs.
The following customization options are available for the report:
- Additional country-level analysis of the data center busways market
- Profiling of additional market players (up to 5)
Product Analysis
- Product matrix, which gives a detailed comparison of the product portfolio of each company.
Get the Full Data Center Busways Market Report
Full forecast, segment splits, and company analysis for all Data Center Busways Market.
- US Data Center Busways Market
- Canada Data Center Busways Market
- Mexico Data Center Busways Market
- Germany Data Center Busways Market
- UK Data Center Busways Market
- France Data Center Busways Market
- Netherlands Data Center Busways Market
- Rest Of Europe Data Center Busways Market
- China Data Center Busways Market
- Japan Data Center Busways Market
- India Data Center Busways Market
- Australia Data Center Busways Market
- Rest Of Asia Pacific Data Center Busways Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report