US Data Center Thermal Management Market (2026-2031)
The US Data Center Thermal Management Market was valued at $5547.7 Million in 2026 and projected to reach to $15819.8 Million by 2031, representing a compound annual growth rate of 19.1%. The US data center thermal management market is positioned for exceptional growth through 2031, fueled by unprecedented demand for computing capacity driven by AI, machine learning, and cloud services.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
US Data Center Thermal Management Market Trends and Insights
- This represents a compound annual growth rate of 19.1%, significantly outpacing global trends.
- The US market's accelerated growth is driven by the nation's leading position in cloud computing infrastructure, artificial intelligence deployment, and hyperscale data center construction, all demanding advanced cooling solutions. US data centers face mounting thermal challenges as computational density and power consumption intensify across the forecast period.
- The US market benefits from substantial capital investment in next-generation cooling technologies, including liquid cooling systems, AI-optimized thermal management, and energy-efficient solutions.
- Major US technology companies and data center operators are prioritizing thermal efficiency to reduce operational costs and meet sustainability mandates, positioning the US as a critical growth engine for the global thermal management sector..
Key Market Statistics
- CAGR (2026-2031) 19.1% CAGR
- Market Size, 2026 ~USD 5547.7 Million
- Forecast, 2031 ~USD 15819.8 Million
- Country US
US Data Center Thermal Management Market Overview
Explosive US Market Growth :
The US data center thermal management market is projected to grow from $5,547.7 million in 2026 to $15,819.8 million by 2031, representing a 19.1% CAGR that significantly exceeds global growth rates of 16.1%.
AI and Cloud Infrastructure Demand :
The US market is driven by the nation's dominant position in cloud computing and artificial intelligence deployment, with major tech companies investing heavily in data center expansion and cooling infrastructure.
Regional Market Leadership :
As the world's largest data center market, the US accounts for a disproportionate share of global thermal management spending, with concentrated demand from hyperscale operators in key tech hubs.
Energy Efficiency Regulations :
Stringent US environmental regulations and corporate sustainability commitments are driving adoption of advanced cooling technologies, creating premium market opportunities for innovative thermal solutions.
US Data Center Thermal Management Market Dynamics
- Major technology companies are expanding data center footprints across the country, necessitating sophisticated cooling solutions to manage heat dissipation and operational costs.
- The market will benefit from increasing adoption of liquid cooling, immersion cooling, and AI-optimized thermal management systems.
- Regulatory pressure for energy efficiency and corporate net-zero commitments will accelerate investment in next-generation cooling technologies.
- The competitive landscape will intensify as established HVAC manufacturers and specialized thermal solution providers vie for market share in this high-growth segment..
Market Ecosystem

DATA CENTER THERMAL MANAGEMENT MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Microsoft deploys advanced thermal management solutions, including direct-to-chip liquid cooling, precision cooling, and AI-driven thermal monitoring, across its Azure data centers to support high-density AI and cloud workloads while maintaining optimal operating temperatures. | Improved cooling efficiency | Reduced Power Usage Effectiveness (PUE) | Higher rack densities | Enhanced server reliability | Lower operating costs |
 |
Meta integrates liquid cooling infrastructure, intelligent airflow management, and heat recovery technologies in its AI data centers to efficiently cool large GPU clusters and improve energy performance. | Enhanced thermal performance | Lower energy consumption | Improved infrastructure scalability | Support for next-generation AI workloads |
 |
Google utilizes AI-powered thermal management systems that dynamically optimize cooling equipment, airflow, and chiller operations across its global data center network to maximize energy efficiency. | Lower cooling energy consumption | Improved equipment reliability | Reduced carbon emissions | Optimized facility performance |
 |
NVIDIA's DGX and AI factory deployments rely on advanced thermal management technologies, including direct-to-chip liquid cooling, CDUs, heat exchangers, and intelligent cooling controls, to manage the high thermal output of GPU-intensive AI systems. | Efficient heat removal | Higher computational performance | Reduced thermal bottlenecks | Support for ultra-high-density GPU deployments |
 |
Equinix provides colocation facilities equipped with advanced thermal management infrastructure, including liquid cooling, precision air cooling, and intelligent environmental monitoring, enabling customers to deploy AI and HPC workloads efficiently. | Enables AI-ready colocation services | Improves cooling reliability | Supports high-density rack deployments | Reduces customers' operational costs |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Equipment Machine And Tooling
- Wastewater Treatment
- Air Cooled Heat Exchangers
- Diaphragm Pumps
- Fiberglass
- HVAC System
- Alfa Laval Corporate AB
- Johnson Controls International plc
- Daikin Industries,Ltd.
- Veolia
- Carrier Global Corporation
Infrastructure Material
- Alumina Ceramics
- Ceramic Coatings
- Monolithic Ceramics
- Polyphenylene Sulfide (PPS)
- Titanate Ceramics
- Saint-gobain
- Simpson Manufacturing Co., Inc.
- Sika ag
- DOW CHEMICAL COMPANY
- Basf se
Key Takeaways
- The US data center thermal management market will nearly triple from $5.5B in 2026 to $15.8B by 2031, driven by AI and hyperscale infrastructure expansion.
- US market CAGR of 19.1% significantly exceeds the global average of 16.1%, reflecting the nation's dominance in cloud and AI computing.
- Liquid cooling and advanced thermal solutions are becoming standard in US data centers to manage increasing power densities and operational costs.
- US regulatory focus on energy efficiency and sustainability is accelerating adoption of innovative thermal management technologies across the forecast period.
Data Center Thermal Management Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2026 |
| Fastest Growing Segment | LIQUID COOLING (Technology) |
| Forecast Period | 2026-2031 |
| Growth Rate | CAGR of 16.1% from 2026 to 2031 |
| Largest Segment | HARDWARE (Solutions) |
| Market Size Base Year (Billions) | ~USD 13.22 (2026) |
| Revenue Forecast (Billions) | ~USD 27.89 (2031) |
| Segments Covered | Technology, Solutions, Components, Data Center Type, End-Use Industry, Component |
US Data Center Thermal Management Market Report Segmentation
6 segment dimensions are covered across the global market.
By Technology
- Air Cooling
- Liquid Cooling
By Solutions
- Hardware
- Services
By Components
- Air Conditioning
- Chilling Units
- Control Systems
- Cooling Towers
- Economizer Systems
- Liquid Cooling Systems
- Other Components
By Data Center Type
- Colocation Providers
- Enterprise Data Centers
- Hyperscale Data Centers
By End-Use Industry
- Bfsi
- Energy
- Government & Defense
- Healthcare
- It & Telecom
- Manufacturing
- Other End-Use Industries
- Research & Academic
- Retail
By Component
- Services
- Solution
- Solutions
Target Audience
- Data Center Operators & Facility Managers : Need market intelligence to optimize cooling infrastructure investments, reduce operational costs, and meet energy efficiency targets. US-specific data enables benchmarking against peers and justifying capital expenditures to stakeholders.
- Thermal Management Solution Providers : Require detailed US market sizing and growth forecasts to guide product development, sales strategy, and market entry decisions. Understanding regional demand drivers helps prioritize innovation in liquid cooling, immersion, and AI-integrated solutions.
- Cloud & AI Infrastructure Companies : Need comprehensive market analysis to plan data center expansion strategies and cooling technology investments. US market insights inform decisions on facility locations, cooling architecture, and vendor partnerships for hyperscale operations.
- Private Equity & Investment Firms : Seek validated market data to evaluate investment opportunities in thermal management companies, data center operators, and cooling technology startups. US-specific CAGR and market projections support due diligence and valuation models.
- HVAC & Equipment Manufacturers : Need regional market intelligence to identify growth opportunities, assess competitive threats, and develop US-focused product strategies. Market data supports sales forecasting, channel partner recruitment, and market share expansion planning.
Reasons to Buy this Report
- Market Size & Growth Validation : Quantified US market data with precise valuations ($5.5B to $15.8B) and 19.1% CAGR enables accurate financial forecasting, investment planning, and ROI projections for thermal management solutions targeting American data centers.
- Competitive Positioning Strategy : Understand the US-specific competitive landscape, identify market gaps, and benchmark against regional competitors. Gain insights into which thermal technologies are gaining traction among US hyperscalers and enterprise data center operators.
- Regulatory & Compliance Insights : Navigate US-specific environmental regulations, energy efficiency standards, and sustainability mandates that drive thermal management adoption. Align product development with regional compliance requirements and corporate ESG commitments.
- Customer Segmentation & Targeting : Identify and prioritize high-value US customer segments including hyperscale operators, cloud providers, and enterprise data centers. Develop targeted go-to-market strategies based on regional demand drivers and purchasing patterns.
- Technology Adoption Trends : Analyze which cooling technologies (liquid, immersion, AI-optimized) are gaining adoption in US data centers. Make informed R&D investment decisions and product roadmap prioritization based on regional market preferences and emerging opportunities.
Frequently asked questions
What is the current size of the US data center thermal management market?
The US data center thermal management market is valued at $5,547.7 million in 2026 and is projected to grow to $15,819.8 million by 2031.
What is the CAGR for the US data center thermal management market?
The US market is growing at a compound annual growth rate of 19.1% from 2026 to 2031, outpacing the global CAGR of 16.1%.
Why is the US market growing faster than the global average?
The US leads in cloud computing, AI infrastructure, and hyperscale data center deployment, requiring advanced thermal solutions to manage higher computational densities and power consumption.
What thermal management technologies are driving US market growth?
Liquid cooling systems, AI-optimized thermal management, immersion cooling, and energy-efficient solutions are key technologies accelerating adoption in US data centers.
How are US regulations influencing the thermal management market?
US regulatory mandates on energy efficiency and sustainability are compelling data center operators to invest in advanced thermal management solutions to reduce operational costs and environmental impact.
RESEARCH METHODOLOGY
The research methodology used to estimate the current size of the data center thermal management market consisted of four major activities. Extensive secondary research was performed to acquire detailed information about the market, peer markets, and parent markets. These findings, assumptions, and metrics were verified through primary research with experts from both the demand and supply sides of the data center thermal management value chain. Both top-down and bottom-up approaches were used to estimate the total market size. The estimation of market sizes for various segments and subsegments in the market was finalized using complete market segmentation and data triangulation techniques.
Secondary Research
The research methodology for estimating and forecasting the data center thermal management market begins with gathering data on key vendors' revenues by doing secondary research. The secondary research process involves consulting a range of secondary sources, including Hoover's, Bloomberg Businessweek, Factiva, the World Bank, and industry-specific journals. These secondary sources encompass annual reports, press releases, investor presentations, white papers, certified publications, articles from recognized authors, regulatory notifications, trade directories, and databases.
Primary Research
The data center thermal management market comprises several stakeholders, including raw material suppliers, processors, end-product manufacturers, and regulatory organizations, throughout the supply chain. The demand side of this market is characterized by the development of various data centers, including mid-sized data centers, enterprise data centers, and large data centers. The supply side is characterized by advancements in technology and a wide range of diverse applications. Various primary sources from both the supply and demand sides of the market were interviewed to obtain qualitative and quantitative information. The following is the breakdown of the primary respondents:
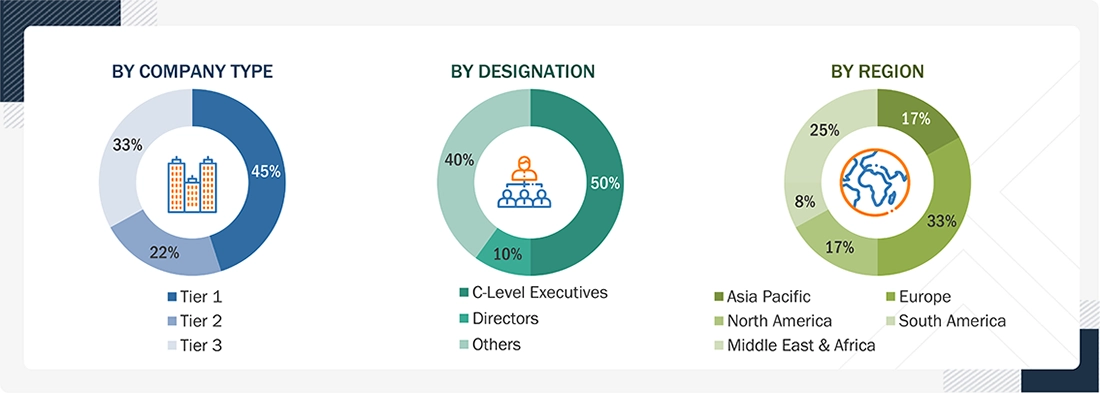
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
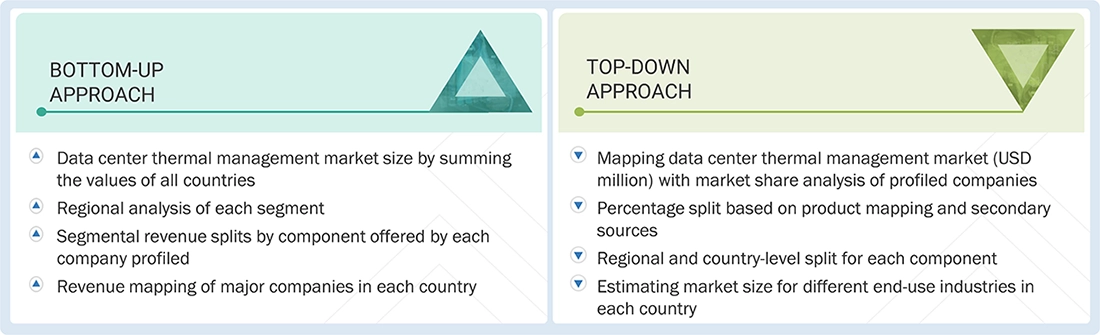
The top-down and bottom-up approaches have been employed to estimate and validate the total size of the data center thermal management market. These approaches have also been used extensively to estimate the size of various dependent market subsegments. The research methodology used to estimate the market size included the following:
The following segments provide details about the overall market size estimation process employed in this study:
- Extensive primary and secondary research was done to identify the key players.
- The value chain and market size of the data center thermal management market, in terms of value, were determined through primary and secondary research.
- All percentage shares, splits, and breakdowns were collected through secondary sources and verified through primary sources.
- All possible parameters that affect the market were covered in this research study and are viewed in extensive detail, verified through primary research, and analyzed to obtain the final quantitative and qualitative data.
- The study of reports, reviews, and newsletters of top market players, along with extensive interviews for opinions from key leaders, such as CEOs, directors, and marketing executives, is included in this research.
Data Center Thermal Management Market: Top-Down and Bottom-Up Approach
Data Triangulation
After estimating the overall market size using the above estimation, the market was split into various segments and subsegments. Data triangulation and market segmentation techniques, along with the market engineering process, were employed to obtain precise market analysis data for each segment and its subsegments.
Research Methodology: The research methodology used to estimate and forecast the global market size began by aggregating data and information from various levels, including country-level data.
Market Definition
Data center thermal management refers to the technologies, equipment, software, and strategies used to monitor, control, and optimize the temperature and heat dissipation within a data center to ensure the reliable, efficient, and continuous operation of IT infrastructure. It encompasses a wide range of cooling solutions, including air cooling, liquid cooling, precision cooling systems, chillers, computer room air conditioners (CRACs), computer room air handlers (CRAHs), coolant distribution units (CDUs), heat exchangers, cooling towers, pumps, airflow management systems, containment solutions, sensors, and intelligent thermal monitoring platforms.
Key Stakeholders
- Data center thermal management providers, processors, and technology providers
- Data center operators including hyperscale data centers, colocation data centers, and enterprise data centers
- Research institutions, standards organizations, and regulatory agencies such as ASTM, ISO, IAEA, and national materials authorities
- NGOs, governments, investment banks, venture capitalists, and private equity firms
Report Objectives
- To define, describe, and forecast the market size of data center thermal management, in terms of value and volume
- To provide detailed information regarding the key factors, such as drivers, restraints, opportunities, and industry-specific challenges, influencing the growth of the data center thermal management market
- To analyze and forecast the size of various segments (component, data center type, end-use industry, solution, technology, and type of cooling) of the data center thermal management market based on five major regions - North America, Europe, Asia Pacific, South America, Middle East & Africa; along with key countries in each of these regions.
- To analyze recent developments and competitive strategies, including expansions, partnerships, and acquisitions, to understand the market's competitive landscape.
- To strategically profile the key players in the market and comprehensively analyze their core competencies.
Available customizations:
With the given market data, MarketsandMarkets offers customizations according to the client-specific needs.
The following customization options are available for the report:
- Additional country-level analysis of the data center thermal management market
- Profiling of additional market players (up to 5)
Product Analysis
- Product matrix, which provides a detailed comparison of each company's product portfolio.
Get the Full Data Center Thermal Management Market Report
Full forecast, segment splits, and company analysis for all Data Center Thermal Management Market.
- China Data Center Thermal Management Market
- India Data Center Thermal Management Market
- Japan Data Center Thermal Management Market
- South Korea Data Center Thermal Management Market
- Canada Data Center Thermal Management Market
- Mexico Data Center Thermal Management Market
- Germany Data Center Thermal Management Market
- UK Data Center Thermal Management Market
- France Data Center Thermal Management Market
- Italy Data Center Thermal Management Market
- Netherlands Data Center Thermal Management Market
- UAE Data Center Thermal Management Market
- Saudi Arabia Data Center Thermal Management Market
- South Africa Data Center Thermal Management Market
- Brazil Data Center Thermal Management Market
- Rest Of Europe Data Center Thermal Management Market
- Rest Of Asia Pacific Data Center Thermal Management Market
- Rest Of The GCC Countries Data Center Thermal Management Market
- Rest Of South America Data Center Thermal Management Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report