UK IT Service Management (ITSM) Market (2023-2028)
The UK IT Service Management (ITSM) Market was valued at $645 Million in 2023 and projected to reach to $1364 Million by 2028, representing a compound annual growth rate of 16.2%. The UK ITSM market is poised for substantial growth, expanding from £645 million in 2023 to £1,364 million by 2028.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
UK IT Service Management (ITSM) Market Trends and Insights
- This robust expansion reflects the UK's increasing reliance on digital transformation and cloud-based service delivery models across public and private sectors.
- The UK market is driven by enterprises seeking to optimize IT operations, reduce costs, and enhance service quality through integrated ITSM platforms and automation tools. The UK's strong technology infrastructure and regulatory environment position it as a leading ITSM market within Europe.
- UK organizations are increasingly adopting AI-powered incident management, self-service portals, and advanced analytics capabilities to streamline IT service delivery.
- The forecast period (2023-2028) will see accelerated adoption among mid-market and enterprise organizations in the UK, particularly in financial services, healthcare, and public administration sectors. Key growth catalysts for the UK market include the shift toward hybrid work models, heightened cybersecurity requirements, and the need for IT service continuity.
- The UK's emphasis on digital government initiatives and compliance with evolving data protection regulations further supports sustained demand for comprehensive ITSM solutions..
Key Market Statistics
- CAGR (2023-2028) 16.2% CAGR
- Market Size, 2023 ~USD 645 Million
- Forecast, 2028 ~USD 1364 Million
- Country UK
UK IT Service Management (ITSM) Market Overview
Strong Market Valuation :
The UK ITSM market reached £645 million in 2023, demonstrating substantial investment in service management solutions across British enterprises and public sector organisations.
Accelerated Growth Trajectory :
With a CAGR of 16.2% through 2028, the UK market is outpacing the global average of 15.9%, indicating heightened digital transformation momentum within the country.
Cloud-Driven Adoption :
UK organisations are increasingly migrating to cloud-based ITSM platforms, driven by cost efficiency, scalability, and the need for remote service delivery capabilities post-pandemic.
Sector-Wide Modernisation :
Both public and private sectors in the UK are prioritising ITSM investments to streamline operations, enhance customer experience, and meet regulatory compliance requirements.
UK IT Service Management (ITSM) Market Dynamics
- This expansion is underpinned by accelerating digital transformation initiatives across UK enterprises, increased adoption of hybrid and multi-cloud environments, and growing demand for integrated service management platforms.
- Financial services, healthcare, and government sectors are leading investment in ITSM solutions to enhance operational efficiency and service quality. Looking ahead, the UK market will be shaped by emerging technologies including AI-driven automation, advanced analytics, and self-service capabilities.
- Organisations are increasingly seeking ITSM vendors that offer seamless integration with existing IT ecosystems, robust security features, and compliance with UK data protection regulations.
- The competitive landscape will intensify as both established vendors and innovative startups vie for market share among UK-based enterprises..
Market Ecosystem
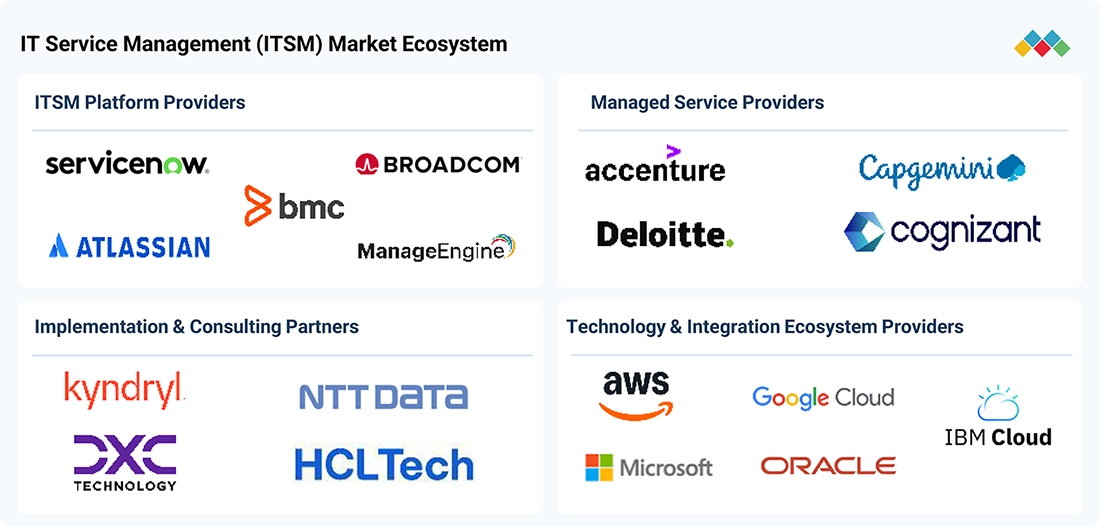
IT SERVICE MANAGEMENT (ITSM) MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Mindsprint deployed ServiceNow ITSM Pro and related workflow automation to create a unified service-management environment, automate ticket routing, improve incident handling, and expand employee self-service. | Up to 95% of incidents automatically remediated | 57% reduction in time to close P0/P1 incidents | 30% reduction in MTTR | 99% ticket-routing accuracy | 40% incident deflection through self-service |
 |
The University of Aberdeen modernized legacy ITSM using Freshservice and Freddy AI to automate routine service-desk activities, improve ticket management, expand self-service, and increase support capacity. | 81% reduction in ticket-resolution time | 10,200 tickets deflected | 208% increase in ticket capacity | Automation generated an estimated 405 working days of annual staff-time savings |
 |
EnerSys implemented ServiceDesk Plus to improve request categorization, automated ticket dispatch, technician assignment, workflow management, and SLA control across its service environment. | Average ticket-resolution time reduced from 48 hours to 5–6 hours | 98.9% SLA compliance | Improved request routing and service visibility |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Software And Services
- Natural Language Processing (NLP)
- Machine Learning
- Supply Chain Management
- Predictive Analytics
- Image Sensors
- International Business Machines Corporation
- MICROSOFT CORPORATION
- Oracle Corporation
- SAP SE
- Amazon.com, Inc.
Cloud Computing
- Software as A Service (SaaS)
- Natural Language Processing (NLP)
- Platform as A Service (PaaS)
- Machine Learning
- Supply Chain Management
- International Business Machines Corporation
- MICROSOFT CORPORATION
- Oracle Corporation
- Amazon.com, Inc.
Digitalization And Iot
- Sensors
- Remote Monitoring
- Supply Chain Management
- Passenger Information System (PIS)
- Platform as A Service (PaaS)
- International Business Machines Corporation
- Cisco Systems, Inc.
- MICROSOFT CORPORATION
- Oracle Corporation
- HUAWEI TECHNOLOGIES CO LTD
Key Takeaways
- The UK ITSM market is projected to more than double from £645M (2023) to £1,364M (2028), driven by digital transformation and cloud adoption.
- UK enterprises are prioritizing AI-powered automation and self-service capabilities to enhance IT service delivery and operational efficiency.
- The UK's regulatory landscape and hybrid work environment are key drivers accelerating ITSM platform adoption across sectors.
- Mid-market and enterprise organizations in the UK financial services, healthcare, and public sectors represent the highest-growth customer segments.
IT Service Management (ITSM) Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2023 |
| Fastest Growing Segment | SERVICES (Component) |
| Forecast Period | 2023-2028 |
| Growth Rate | CAGR of 15.9% from 2023 to 2028 |
| Largest Segment | CLOUD (Deployment Model) |
| Market Size Base Year (Billions) | ~USD 10.57 (2023) |
| Revenue Forecast (Billions) | ~USD 22.1 (2028) |
| Segments Covered | Offering, Solution, Service, Organization Size, Deployment Model, Vertical, Component, Module, System, Enterprise Size, End-Use Vertical |
UK IT Service Management (ITSM) Market Report Segmentation
11 segment dimensions are covered across the global market.
By Offering
- Services
- Solutions
By Solution
- Configuration & Change Management
- Dashboard, Reporting, And Analytics
- Operations & Performance Management
- Service Desk Software
- Service Portfolio Management
By Service
- Managed Services
- Professional Services
By Organization Size
- Large Enterprises
- Services
- Smes
- Solutions
By Deployment Model
- Cloud
- On-Premises
By Vertical
- Bfsi
- Education
- Energy & Utilities
- Energy And Utilities
- Government & Public Sector
- Government And Public Sector
- Healthcare
- Healthcare And Life Sciences
- It & Ites
- It And Ites
- Manufacturing
- Media & Entertainment
- Media And Entertainment
- Other Verticals
- Retail & Consumer Goods
- Retail And Consumer Goods
- Telecommunications
By Component
- Services
- Solutions
By Module
- Cmdb
- Others*
- Service Catalog
- Service Definition
By System
- Servers
- Software And Applications
- Storage
By Enterprise Size
- Large Enterprises
- Smes
By End-Use Vertical
- Bfsi
- Government And Public Sector
- Healthcare And Life Sciences
- Manufacturing
- Others*
- Retail And Consumer Packaged Goods
- Telecom And Ites
Target Audience
- ITSM Software Vendors : Vendors need UK market data to refine product positioning, identify high-growth segments, benchmark against competitors, and develop localised sales and marketing strategies for British customers.
- Enterprise IT Leaders : CIOs and IT directors in UK organisations require market insights to evaluate ITSM solutions, understand industry benchmarks, and justify investment decisions to executive leadership.
- Management Consultants : Consulting firms advising UK clients on digital transformation and IT modernisation need market data to support recommendations, validate business cases, and identify emerging best practices.
- Investment & Private Equity Firms : Investors evaluating ITSM companies or IT service providers in the UK market require detailed forecasts, growth drivers, and competitive landscape analysis to assess investment opportunities.
- Government & Public Sector Buyers : UK public sector procurement teams need market intelligence to understand vendor capabilities, evaluate solutions, and ensure alignment with government digital strategy and compliance requirements.
Reasons to Buy this Report
- UK-Specific Market Intelligence : Gain detailed insights into the UK ITSM landscape, including market size, growth rates, and regional dynamics specific to British enterprises and public sector organisations.
- Competitive Positioning Strategy : Understand UK market trends, customer preferences, and competitive dynamics to develop targeted go-to-market strategies and identify growth opportunities within the British market.
- Investment Decision Support : Access comprehensive forecasts and market projections through 2028 to inform capital allocation decisions, M&A strategies, and expansion plans in the UK ITSM sector.
- Sector-Specific Insights : Discover adoption patterns and investment priorities across UK financial services, healthcare, government, and enterprise sectors to tailor solutions and messaging accordingly.
- Regulatory & Compliance Context : Understand how UK data protection regulations, GDPR compliance, and government digital strategies influence ITSM adoption and vendor selection criteria.
Frequently asked questions
What is the current size of the UK ITSM market?
The UK ITSM market was valued at £645 million in 2023 and is expected to reach £1,364 million by 2028, growing at a CAGR of 16.2%.
What are the primary drivers of ITSM growth in the UK?
Key drivers include digital transformation initiatives, cloud migration, hybrid work adoption, regulatory compliance requirements, and the need for enhanced IT service continuity in the UK.
Which UK sectors are leading ITSM adoption?
Financial services, healthcare, public administration, and large enterprises in the UK are driving the highest adoption rates for ITSM solutions.
How is AI impacting the UK ITSM market?
UK organizations are increasingly deploying AI-powered incident management, predictive analytics, and intelligent automation to improve service delivery and reduce operational costs.
What is the forecast growth rate for the UK ITSM market?
The UK ITSM market is forecast to grow at a CAGR of 16.2% between 2023 and 2028, significantly outpacing global average growth rates.
RESEARCH METHODOLOGY
This research study on the IT Service Management (ITSM) market involved extensive secondary and primary research. Secondary sources included company annual reports, SEC and regulatory filings, investor presentations, product documentation, pricing pages, press releases, white papers, technology journals, government publications, industry associations, cloud adoption databases, IT service management standards and frameworks, and paid databases. Primary sources primarily included industry experts from ITSM software vendors, managed service providers, system integrators, consulting organizations, cloud service providers, enterprise users, and related technology companies. In-depth interviews with market participants and subject-matter experts were conducted to gather and validate critical qualitative and quantitative information and assess the market’s growth prospects.
Secondary Research
During the secondary research process, multiple sources were reviewed to identify and collect information relevant to the study. These sources included annual reports, regulatory filings, investor presentations, earnings transcripts, press releases, product portfolios, acquisition announcements, pricing pages, customer references, and technology documentation from ITSM vendors.
Additional information was gathered from recognized journals, industry associations, government websites, technology publications, cloud provider materials, and certified publications. Data relating to enterprise IT spending, cloud adoption, digital transformation, service desk modernization, IT outsourcing, managed services, artificial intelligence adoption, workflow automation, cybersecurity spending, and enterprise software expenditure across major countries was also extracted from relevant secondary sources.
Secondary research was used to develop preliminary market estimates, understand competitive positioning, identify vendor offerings, establish market segmentation, analyze technology trends, and determine regional adoption patterns.
Primary Research
During the primary research process, respondents from both the supply and demand sides were interviewed to obtain qualitative and quantitative information about the market. Supply-side participants included chief executive officers, vice presidents, directors, product managers, ITSM platform leaders, engineering executives, business development executives, marketing executives, service-management specialists, implementation consultants, and solution architects.
Breakup of Primary Profiles:
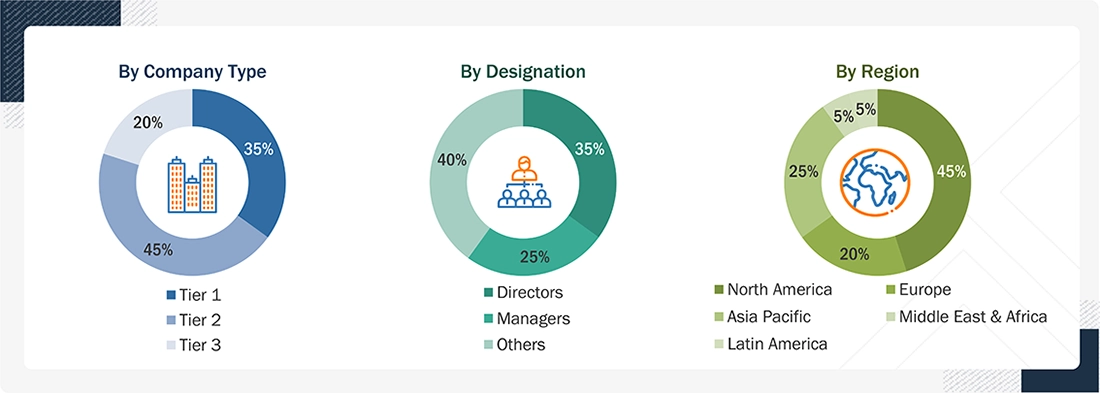
Note: Tier 1 companies’ revenues are more than USD 1 billion; Tier 2 companies’ revenues range between USD 100 million and USD 1 billion; and Tier 3 companies’ revenues range between USD 10 million and USD 100 million. Other designations include sales, marketing, engineering, product, operations, consulting, and research managers.
Source: Industry Experts
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
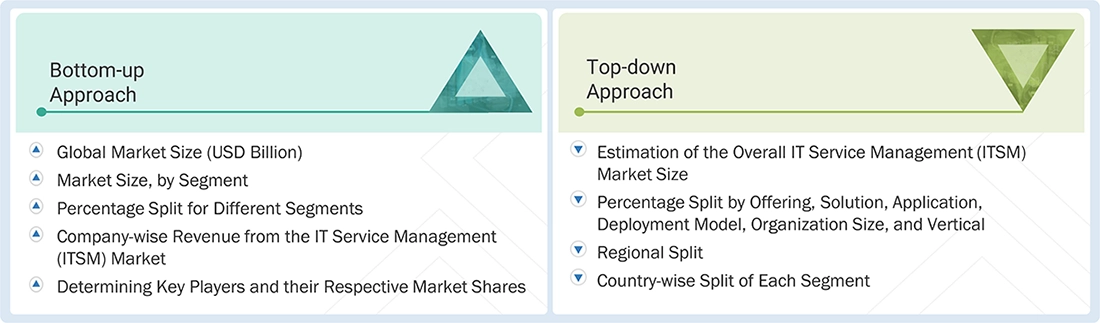
Multiple approaches were used to estimate and forecast the IT Service Management market. The first approach involved estimating market size based on revenues generated by companies from ITSM software products, platform subscriptions, associated professional services, and managed services.
Market Size Estimation Methodology: Top-down Approach
The top-down approach involved preparing an exhaustive list of vendors offering ITSM platforms, service desk software, workflow automation, configuration and change management, service management analytics, managed services, and related offerings.
Market Size Estimation Methodology: Bottom-up Approach
The bottom-up approach assessed the adoption of IT Service Management platforms across major verticals and countries contributing significantly to the market. Enterprise deployments were evaluated across service desk software, incident & problem management, change & release management, service request & catalog management, configuration management, knowledge & self-service management, and service level management. Adoption levels across large enterprises and SMEs were estimated and extrapolated using cloud maturity, enterprise IT spending, service-management penetration, workforce size, service volumes, SaaS adoption, and managed service utilization.
Regional splits were determined through primary and secondary sources. The process included analysis of regional ITSM penetration, enterprise software spending, cloud adoption, digital transformation activity, IT outsourcing, service desk modernization, and managed services adoption. Strategic analysis of major global and regional ITSM vendors, together with their organic and inorganic developments, was also incorporated into the market estimates.
IT Service Management (ITSM) Market : Top-Down and Bottom-Up Approach
Data Triangulation
After determining the overall IT Service Management market size using the top-down and bottom-up estimation approaches, the market was divided into segments and subsegments. Data triangulation and market breakup procedures were applied to validate each market segment and subsegment. Vendor revenues, customer adoption patterns, deployment preferences, application penetration, service revenues, regional indicators, pricing structures, and primary interview findings were compared to identify inconsistencies and refine the estimates. The final market size was then used to estimate individual segments by applying validated percentage splits across the market segmentation. The resulting figures were cross-checked against supply-side revenues, demand-side ITSM adoption indicators, enterprise technology spending, cloud software penetration, managed services usage, product pricing, and regional economic conditions.
Market Definition
The IT Service Management market comprises software solutions and associated services that enable organizations to design, deliver, manage, support, govern, and continuously improve IT services across enterprise environments. ITSM platforms provide structured workflows for incident and problem management, change and release management, service request and catalog management, configuration management, knowledge and self-service management, service-level management, and service portfolio management. These platforms help enterprises standardize service processes, improve service availability, automate repetitive support activities, increase employee productivity, and strengthen governance across increasingly complex technology environments.
ITSM platforms include capabilities such as service desk software, CMDB, service catalogs, workflow orchestration, AI-enabled virtual agents, automated ticket classification and routing, knowledge recommendations, SLA monitoring, service analytics, change-risk assessment, and increasingly agentic and autonomous service-management capabilities. The market includes on-premises and cloud deployment models and supports enterprises operating traditional infrastructure, public cloud, private cloud, hybrid environments, SaaS applications, distributed endpoints, and modern digital workplaces.
Key Stakeholders
- ITSM platform providers
- Service desk software providers
- Service portfolio management vendors
- Configuration and change management vendors
- Managed service providers
- Professional service providers
- System integrators
- Cloud service providers
- IT operations management providers
- IT asset management providers
- AI and automation technology providers
- Enterprise software and workflow automation vendors
- Consulting organizations
- CIOs, CTOs, and enterprise IT leaders
- IT service management and service desk teams
Report Objectives
- To define and describe the IT Service Management market by offering, solution, services, application, deployment model, organization size, vertical, and region.
- To provide detailed information on major factors influencing market growth, including drivers, restraints, opportunities, and challenges across the ITSM ecosystem.
- To strategically analyze micro-markets with respect to individual growth trends, adoption patterns, and their contribution to the overall ITSM market.
- To analyze market opportunities for stakeholders and present the competitive landscape of ITSM platform vendors, managed service providers, enterprise software vendors, and technology partners.
- To project the market size and its submarkets in terms of value across North America, Europe, Asia Pacific, Middle East & Africa, and Latin America.
- To analyze major countries within each region based on cloud adoption, enterprise IT spending, digital maturity, ITSM penetration, and service-management modernization.
- To strategically profile leading companies and evaluate their product portfolios, platform capabilities, geographic presence, growth strategies, and market positioning.
- To examine competitive developments, including product launches, platform enhancements, partnerships, collaborations, acquisitions, investments, and geographic expansions.
- To assess the impact of generative AI, agentic AI, autonomous service desks, enterprise service management, workflow automation, cloud migration, and ITSM–ITOM convergence on market development.
- To analyze adoption across incident & problem management, change & release management, service request & catalog management, configuration management, knowledge & self-service management, and service level management.
- To assess deployment trends across on-premises and cloud environments.
- To identify high-growth segments, emerging use cases, and evolving technology requirements across the ITSM market.
Available customizations:
With the given market data, MarketsandMarkets offers customizations as per the company’s specific needs. The following customization options are available for the report:
Product Analysis
- The product matrix provides a detailed comparison of the product portfolios, ITSM capabilities, deployment models, AI capabilities, and integrations of each company.
Geographic Analysis based on feasibility
- Further breakup of the North American IT Service Management market
- Further breakup of the European IT Service Management market
- Further breakup of the Asia Pacific IT Service Management market
- Further breakup of the Middle East & Africa IT Service Management market
- Further breakup of the Latin American IT Service Management market
Company Information
-
Detailed analysis and profiling of additional market players (up to five)
Get the Full IT Service Management (ITSM) Market Report
Full forecast, segment splits, and company analysis for all IT Service Management (ITSM) Market.
- Canada IT Service Management (ITSM) Market
- US IT Service Management (ITSM) Market
- Germany IT Service Management (ITSM) Market
- France IT Service Management (ITSM) Market
- Netherlands IT Service Management (ITSM) Market
- Italy IT Service Management (ITSM) Market
- China IT Service Management (ITSM) Market
- Japan IT Service Management (ITSM) Market
- Australia IT Service Management (ITSM) Market
- Singapore IT Service Management (ITSM) Market
- South Africa IT Service Management (ITSM) Market
- Brazil IT Service Management (ITSM) Market
- Mexico IT Service Management (ITSM) Market
- Rest Of Europe IT Service Management (ITSM) Market
- Rest Of Asia Pacific IT Service Management (ITSM) Market
- Rest Of Latin America IT Service Management (ITSM) Market
- GCC IT Service Management (ITSM) Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report