Germany Liquid Handling System Market (2025-2030)
The Germany Liquid Handling System Market was valued at $932.1 Million in 2025 and projected to reach to $1397.2 Million by 2030, representing a compound annual growth rate of 8.4%. Germany's liquid handling system market is positioned for sustained expansion, driven by the country's robust pharmaceutical manufacturing base and leading biotechnology research institutions.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Germany Liquid Handling System Market Trends and Insights
- Germany's strong pharmaceutical and biotechnology sectors are driving demand for advanced liquid handling automation, particularly in drug discovery, diagnostics, and clinical laboratories.
- The country's emphasis on precision medicine and high-throughput screening capabilities positions Germany as a key market within Europe's healthcare infrastructure. The 8.4% compound annual growth rate reflects Germany's commitment to laboratory automation and efficiency improvements across healthcare institutions.
- Germany's investment in research and development, coupled with stringent quality standards in pharmaceutical manufacturing, accelerates adoption of sophisticated liquid handling systems.
- By 2030, Germany is expected to solidify its position as a leading adopter of liquid handling technologies in Europe, driven by increasing regulatory compliance requirements and the need for reproducible, contamination-free sample processing in clinical and research environments..
Key Market Statistics
- CAGR (2025-2030) 8.4% CAGR
- Market Size, 2025 ~USD 932.1 Million
- Forecast, 2030 ~USD 1397.2 Million
- Country Germany
Germany Liquid Handling System Market Overview
Market Valuation Growth :
Germany's liquid handling system market is valued at $932.1 million in 2025, with a projected CAGR of 8.4% through 2030, reaching $1,397.2 million. This growth outpaces the global average of 8%, reflecting strong regional demand.
Pharmaceutical & Biotech Leadership :
Germany's world-class pharmaceutical and biotechnology sectors are primary growth drivers. Major hubs in Frankfurt, Munich, and Berlin are investing heavily in automated liquid handling solutions for drug discovery, development, and manufacturing processes.
Precision Medicine & Diagnostics :
German clinical laboratories and diagnostic centers are increasingly adopting advanced liquid handling automation to support precision medicine initiatives and high-throughput testing capabilities, particularly in genomics and personalized healthcare applications.
Regulatory Excellence & Standards :
Germany's stringent regulatory environment and commitment to quality standards drive demand for sophisticated liquid handling systems that ensure accuracy, traceability, and compliance with EU and German pharmaceutical regulations.
Germany Liquid Handling System Market Dynamics
- The shift toward automation in clinical diagnostics and drug development laboratories continues to accelerate, with German companies prioritizing precision and efficiency.
- Investment in Industry 4.0 initiatives and digital laboratory solutions further supports market growth.
- By 2030, the market is expected to reach $1,397.2 million, reflecting strong adoption across research institutions, contract research organizations, and pharmaceutical manufacturers throughout the country..
Market Ecosystem
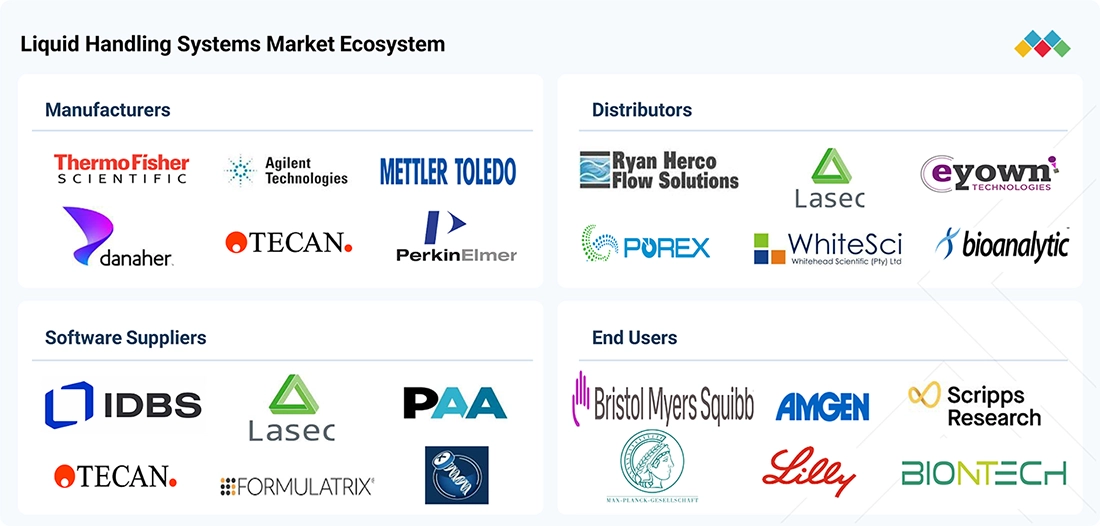
LIQUID HANDLING SYSTEM MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Thermo Fisher excels in integrating automated liquid handling with high-content imaging, enabling seamless dispense-to-image workflows for advanced cell-based assays. | Delivers up to ~90% time savings and higher throughput by automating cell-based workflows, combining precise liquid handling with integrated high-content imaging for faster, consistent results and reduced manual effort. |
 |
Danaher’s core strength in the liquid handling systems market lies in high-throughput genomic, proteomic, and cellular workflow automation, enabling efficient NGS library prep, advanced sample processing, and large-volume dispensing for large-scale research and screening applications. | Provides adaptable automation across miniaturized acoustic dispensing for reagent savings and reliable tip-based systems, enabling labs to scale throughput and workflows seamlessly as their demands increase. |
 |
Encore Multispan system, combining multispan pipetting and robotics to automate high-throughput sample prep, compound management, and screening workflows. | Delivers higher throughput and productivity through dual pipetting banks and extended-reach robotic arms, enabling seamless automation of both upstream and downstream workflow steps. |
 |
High-throughput, modular Fluent Automation Workstations, which seamlessly integrate advanced pipetting, detection, and handling capabilities across plates, tubes, and tips for scalable and versatile lab workflows. | Delivers highly modular and configurable automation, with multi-arm systems that adapt to diverse labware, combine multiple pipetting technologies, and integrate detection tools enabling tailored, scalable workflows for varied research needs. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Analytical And Scientific Instrumentation
- Environmental Testing
- Gas Chromatography
- Polymerase Chain Reaction (PCR)
- Automated Liquid Handling Systems
- Flow Cytometry
- Thermo Fisher Scientific Inc.
- Danaher Corporation
- Agilent Technologies, Inc.
- Merck KGaA
- Shimadzu Corporation
Key Takeaways
- Germany's liquid handling system market will grow from $932.1M (2025) to $1,397.2M (2030), representing a 50% increase over five years.
- Germany's 8.4% CAGR outpaces the global average of 8%, reflecting strong regional demand in pharmaceutical and biotechnology sectors.
- Germany's advanced healthcare infrastructure and R&D investments position the country as Europe's leading market for liquid handling automation.
- Regulatory compliance and precision medicine initiatives in Germany are key drivers accelerating adoption of automated liquid handling solutions.
Liquid Handling System Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | PIPETTES (Product) |
| Forecast Period | 2025–2030 |
| Growth Rate | CAGR of 8% from 2025 to 2030 |
| Largest Segment | AUTOMATED SYSTEMS (Type) |
| Market Size Base Year (Billions) | ~USD 5.04 (2025) |
| Revenue Forecast (Billions) | ~USD 7.4 (2030) |
| Segments Covered | Type, Product, Application, End User |
Germany Liquid Handling System Market Report Segmentation
4 segment dimensions are covered across the global market.
By Type
- Adme Screening
- Automated Systems
- Compound Weighing & Dissolution
- Disposable Tips
- Dna/Rna Purification
- Electronic Pipettes
- Electronic Systems
- Elisa
- Fully Automated Systems
- Gene Expression Analysis
- Genotyping
- Hts
- Maintenance, Installation, And Calibration Services
- Maintenance, Installation, And Calibration Services
- Manual Pipettes
- Manual Systems
- Microplate Reagent Dispensers
- Microplate Washers
- Next-Generation Sequencing (Ngs)
- Next-Generation Sequencing (Ngs)
- Other Clinical Diagnostic Application
- Other Clinical Diagnostics Applications
- Other Consumables
- Other Drug Discovery Applications
- Other Environmental Testing
- Other Genomics Applications
- Polymerase Chain Reaction (Pcr)
- Polymerase Chain Reactions
- Reagent Containers
- Sample Preparation
- Samples Preparation
- Semi-Automated Pipettes
- Semi-Automated Systems
- Semi-Automated Pipettes
- Semi-Automated Systems
- Training And Education Services
- Training And Education Services
- Tubes & Plates
- Tubes And Plates
- Wastewater Analysis
- Water Analysis
By Product
- Accessories
- Burettes
- Consumables
- Liquid Handling Workstations
- Other Products
- Pipettes
- Software & Services
By Application
- Cell & Gene Therapy
- Clinical Diagnostics
- Drug Discovery
- Environmental Testing
- Food Testing
- Forensic Testing
- Genomics
- Other Applications
- Proteomics
By End User
- Biotechnology & Pharmaceutical Companies
- Environmental Testing Laboratories
- Food & Beverages Industry
- Food & Beverages Industry
- Forensic Laboratories
- Hospitals & Diagnostic Laboratories
- Hospitals & Diagnostics Laboratories
- Other End Users
- Research & Academic Institutes
Target Audience
- Pharmaceutical Manufacturers : German pharma companies need market intelligence to optimize automation investments, benchmark against competitors, and align liquid handling system procurement with precision manufacturing and regulatory compliance requirements.
- Biotechnology Research Institutions : German biotech firms and research centers require detailed market data to evaluate technology solutions, justify capital expenditures for lab automation, and stay competitive in drug discovery and development.
- Clinical Laboratory Operators : Diagnostic centers and clinical labs in Germany need market insights to assess automation ROI, understand technology trends, and make informed decisions about upgrading liquid handling capabilities for high-throughput testing.
- Equipment Manufacturers & Suppliers : Liquid handling system vendors and equipment suppliers require Germany-specific market data to identify growth opportunities, understand customer needs, and develop targeted sales and product strategies for the region.
- Healthcare Investors & Consultants : Investment firms and management consultants need comprehensive Germany market analysis to evaluate portfolio opportunities, assess market attractiveness, and provide strategic guidance to healthcare and life sciences clients.
Key Companies in the Germany Liquid Handling System Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| THERMO FISHER SCIENTIFIC INC. | United States | Public Company | Pipettes (manual and electronic),Consumables (tips, reservoirs, plates),Automated liquid handling systems, |
| DANAHER CORPORATION | United States | Public Company | Automated liquid handling systems,Electronic and manual pipettes,Consumables (tips, plates, reagents-linked), |
| PERKINELMER | United States | Public Company | Automated liquid handling systems,Electronic pipettes and semi-automated tools,Manual pipettes, |
| METTLER-TOLEDO INTERNATIONAL INC. | Switzerland | Public Company | Pipettes,Consumables,Accessories, |
| AGILENT TECHNOLOGIES, INC. | United States | Public Company | Automated liquid handling systems and sample preparation platforms,Consumables (tips, plates, sample prep, lab supplies),Accessories and plate management hardware, |
| QIAGEN | Netherlands | Public Company | Automated liquid handling systems (integrated with sample prep/PCR/NGS),Consumables for liquid handling workflows (kits, reagents, plastics),Manual and electronic pipettes and accessories, |
| CORNING INCORPORATED | United States | Public Company | Consumables (tips, plates, reservoirs, vessels),Pipettes and liquid handling instruments,Accessories (racks, controllers, storage, adapters), |
| SARTORIUS AG | United States | Public Company | Pipettes (manual and electronic),Consumables (tips and related),Accessories (dispensers, stands, calibration tools), |
| LONZA | Switzerland | Public Company | Pipettes,Consumables,Accessories, |
| EPPENDORF SE | Germany | Private Company | Pipettes (manual and electronic),Consumables (tips, tubes, plates),Automated pipetting systems, |
| BROOKS AUTOMATION INC. | United States | Public Company | Automated liquid handling–adjacent systems (automated stores, cryogenic, controlled thaw),Sample tubes, consumables, and instruments,Sample repository and management services, |
THERMO FISHER SCIENTIFIC INC.
Thermo Fisher Scientific Inc. is a leading American public company founded in 1956 with 125,000 employees, providing life sciences research tools, diagnostics, and laboratory equipment globally.
DANAHER CORPORATION
Danaher Corporation is an American multinational public company founded in 1969 with 59,000 employees, operating across diverse industrial and life sciences sectors.
PERKINELMER
PerkinElmer is an American public company founded in 1937 with 11,000 employees, specializing in diagnostics, life sciences research, and environmental testing solutions.
METTLER-TOLEDO INTERNATIONAL INC.
Mettler-Toledo International Inc. is a Swiss public company founded in 1991 with 16,600 employees, manufacturing precision instruments and weighing solutions for laboratory and industrial applications.
AGILENT TECHNOLOGIES, INC.
Agilent Technologies, Inc. is an American public company founded in 1999 with 18,000 employees, providing analytical instruments, software, and services for life sciences and diagnostics.
QIAGEN
QIAGEN is a Dutch public company founded in 1984 with 5,500 employees, specializing in molecular diagnostics, sample preparation, and life sciences research technologies.
CORNING INCORPORATED
Corning Incorporated is an American public company founded in 1851 with 67,200 employees, manufacturing specialty glass, ceramics, and optical materials for diverse industries.
SARTORIUS AG
Sartorius AG is a public company founded in 1870 with 14,242 employees, providing laboratory and bioprocess equipment, filtration systems, and weighing solutions.
LONZA
Lonza is a Swiss public company founded in 1897 with 20,000 employees, offering contract manufacturing, cell therapy, and specialty ingredients for pharmaceuticals and biotechnology.
EPPENDORF SE
Eppendorf SE is a German private company founded in 1945 with 4,358 employees, manufacturing laboratory equipment including centrifuges, pipettes, and bioreactors.
BROOKS AUTOMATION INC.
Brooks Automation Inc. is an American public company founded in 1978 with 2,900 employees, providing automation solutions and software for life sciences and semiconductor industries.
Reasons to Buy this Report
- Market Size & Growth Validation : Confirm Germany's liquid handling market valuation at $932.1M (2025) and validate the 8.4% CAGR projection to $1,397.2M by 2030 for strategic planning and investment decisions.
- Competitive Landscape Intelligence : Understand key players, market share distribution, and competitive positioning specific to Germany's pharmaceutical, biotech, and diagnostic sectors to identify partnership and expansion opportunities.
- Sector-Specific Demand Drivers : Gain insights into Germany's precision medicine initiatives, regulatory requirements, and Industry 4.0 adoption rates that directly influence liquid handling system procurement and technology preferences.
- Regional Market Segmentation : Access detailed breakdowns by application (drug discovery, diagnostics, clinical labs), product type, and end-user segments within Germany to target high-growth niches and customer segments.
- Strategic Entry & Expansion Planning : Leverage Germany-specific market data, regulatory insights, and growth forecasts to develop localized go-to-market strategies, distribution partnerships, and investment roadmaps for the region.
Frequently asked questions
What is the current size of Germany's liquid handling system market?
Germany's liquid handling system market is valued at $932.1 million in 2025, with strong growth anticipated through 2030.
What is the projected market size for Germany by 2030?
Germany's liquid handling system market is forecast to reach $1,397.2 million by 2030, representing significant expansion from 2025 levels.
What is Germany's market growth rate for liquid handling systems?
Germany's liquid handling system market is growing at a compound annual growth rate of 8.4% between 2025 and 2030.
Why is Germany a key market for liquid handling systems?
Germany's robust pharmaceutical, biotechnology, and clinical laboratory sectors, combined with stringent quality standards and R&D investments, drive strong demand for advanced liquid handling automation.
What factors are driving growth in Germany's liquid handling market?
Key drivers include regulatory compliance requirements, precision medicine initiatives, high-throughput screening adoption, and Germany's commitment to laboratory automation and efficiency improvements.
RESEARCH METHODOLOGY
The study involved four major activities to estimate the current size of the liquid handling systems market. We conducted extensive secondary research to gather information on the market, peer markets, and parent markets. The findings, assumptions, and market estimates were subsequently validated through primary research with industry experts across the value chain. Both top-down and bottom-up approaches were employed to estimate the overall market size. The report then segmented the market and triangulated data to estimate the size of key segments and subsegments across product types, applications, end users, and regions.
Secondary Research
The secondary research process involved the extensive use of industry databases, company websites, annual reports, investor presentations, SEC filings, white papers, financial reports, trade publications, and commercial databases such as Bloomberg Businessweek, Factiva, and D&B Hoovers. Secondary research gathered comprehensive technical, market-oriented, and commercial information on liquid handling systems, including their applications across pharmaceutical and biotechnology companies, hospitals, diagnostic laboratories, academic and research institutes, and other end users. It was also used to identify key market players, establish detailed market classification and segmentation, assess industry and technology trends, and identify key market developments and growth opportunities. Secondary research also helped develop a database of key industry participants and stakeholders.
Primary Research
During the primary research process, we interviewed supply- and demand-side stakeholders to obtain qualitative and quantitative insights for the study. Supply-side respondents included industry experts such as CEOs, vice presidents, marketing and sales directors, product managers, technology and innovation directors, and other senior executives from leading liquid handling system manufacturers and solution providers. Demand-side respondents included professionals from pharmaceutical and biotechnology companies, hospitals, diagnostic laboratories, academic and research institutions, CROs, and other laboratory end users. Primary research validated market segmentation and estimates, identified and assessed key market participants, and provided insights into technology adoption, application trends, purchasing criteria, competitive dynamics, and key market drivers and challenges influencing the liquid handling systems market.
A breakdown of the primary respondents is provided below:
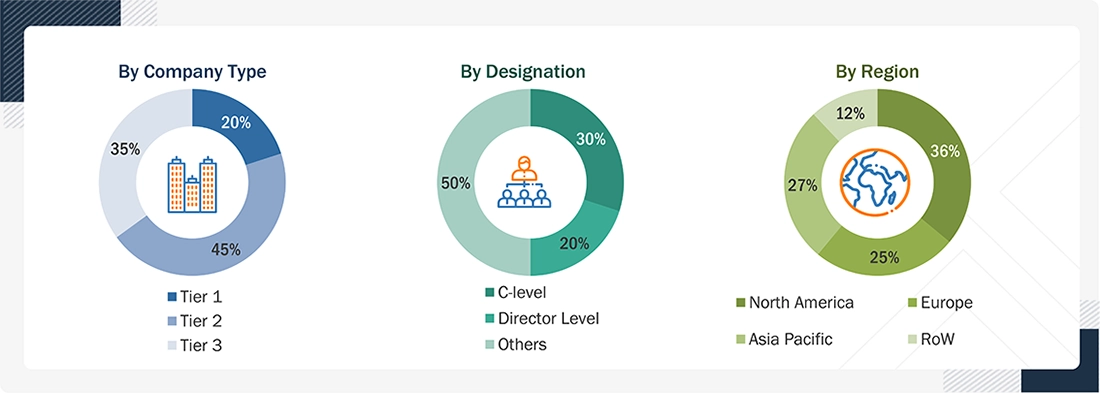
*Others include sales managers, marketing managers, business development managers, product managers, distributors, and suppliers.
Note: Companies are classified into tiers based on their total revenue. Tier 1 = >USD 400 million, Tier 2 = USD 200 million, and Tier 3 = <USD 100 million.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
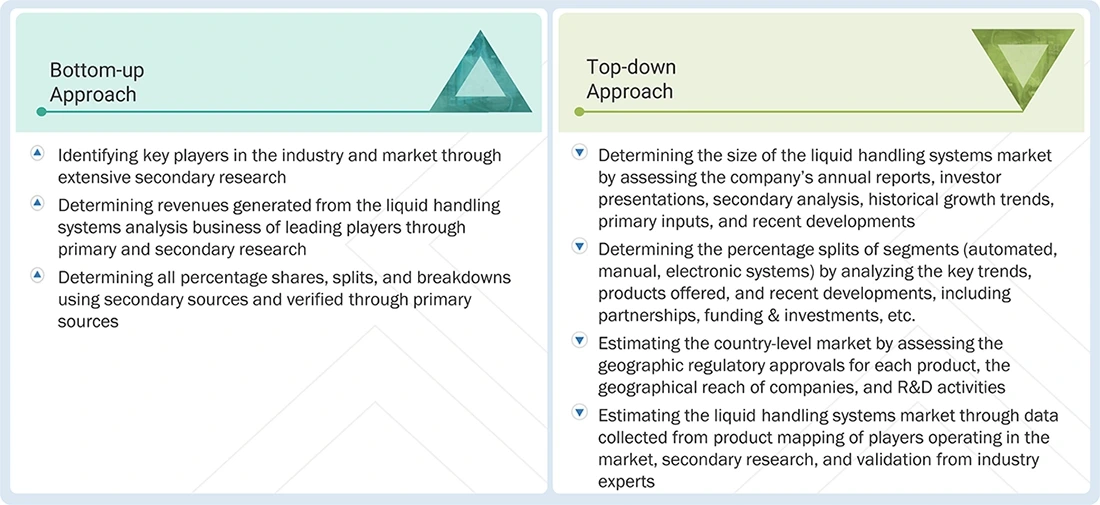
In this report, the liquid handling systems market size was determined using the revenue share analysis of leading players. For this purpose, we identified key market players and determined their revenues from the market business through insights gathered during the primary and secondary research phases. Secondary research included reviewing the annual and financial reports of the top market players. In contrast, primary research included extensive interviews with key opinion leaders, such as CEOs, directors, and key marketing executives at hospital procurement and biobanking divisions.
Segmental revenues were calculated by mapping the revenues of major solution/product providers to estimate the global liquid handling systems market value. This process involved the following steps:
- Generating a list of major global players operating in the liquid handling systems market.
- Mapping annual revenues generated by major global players from the liquid handling systems storage consumables segment (or nearest reported business unit/product category).
- Revenue mapping of major players to cover a major share of the global market, as of 2025.
- Extrapolating the global value of the liquid handling systems market, with specific attention to the healthcare end-user segment.
Liquid Handling System Market : Top-Down and Bottom-Up Approach
Data Triangulation
After arriving at the overall market size from the market size estimation process explained above, the global liquid handling systems market was split into segments and subsegments. We used data triangulation and market-breakdown procedures to complete the overall market engineering process and arrive at exact statistics for all segments and subsegments, including the hospitals and diagnostic laboratories end-user category. The data was triangulated by studying various factors and trends from both the demand and supply sides. Additionally, the liquid handling systems market was validated using top-down and bottom-up approaches.
Market Definition
The liquid handling systems market comprises manual, semi-automated, and automated instruments and solutions designed to accurately aspirate, dispense, transfer, and handle liquid samples and reagents in laboratory environments. These systems are widely used across pharmaceutical and biotechnology research, clinical diagnostics, life sciences, chemical analysis, and drug discovery to improve precision, reproducibility, and workflow efficiency. Liquid handling systems support a broad range of downstream applications, including next-generation sequencing (NGS), polymerase chain reaction (PCR), mass spectrometry, cell analysis, flow cytometry, genomics, epigenetics, and proteomics.
Key Stakeholders
- Manufacturers of liquid handling products
- Liquid handling product distributors
- Venture capitalists and investors
- Genomics and proteomics associations
- Drug discovery and development research centers
- Hospitals and diagnostic laboratories
- Research & consulting firms
- Contract manufacturers of liquid handling systems and consumables
- Research institutes and contract research organizations (CROs)
- Government associations
Report Objectives
- To define, describe, and forecast the size of the liquid handling systems market based on type, product, application, end user, and region
- To provide detailed information regarding the major factors influencing the growth potential of the global liquid handling systems market (drivers, restraints, opportunities, challenges, and trends) from a healthcare industry perspective
- To analyze the micromarkets with respect to individual growth trends, prospects, and contributions to the global liquid handling systems market, with emphasis on hospitals and diagnostic laboratories
- To analyze key growth opportunities in the global liquid handling systems market for key stakeholders and provide details of the competitive landscape for market leaders
- To forecast the size of market segments and/or subsegments with respect to five major regions: North America (US and Canada), Europe (Germany, France, the UK, Italy, Spain, and the Rest of Europe), Asia Pacific (Japan, China, India, Australia, South Korea, and the Rest of Asia Pacific), Latin America (Brazil, Mexico, and the Rest of Latin America), and the Middle East & Africa
- To profile the key players in the liquid handling systems market and comprehensively analyze their market shares and core competencies
- To track and analyze the competitive developments undertaken in the global liquid handling systems market, such as product launches, agreements, expansions, and mergers & acquisitions
Available customizations:
Based on the market data provided, customizations are offered to meet the company's specific needs. The following customization options are available for the present global liquid handling systems market report:
Product Analysis
- Product matrix, which gives a detailed comparison of the product portfolios of the top five companies.
- Detailed analysis and profiling of additional market players (up to five).
Geographic Analysis
- Further breakdown of the Rest of Europe liquid handling systems market into Russia, Belgium, the Netherlands, Switzerland, Austria, Finland, Sweden, Poland, and Portugal, among others.
- Further breakdown of the Rest of Asia Pacific liquid handling systems market into Singapore, Taiwan, New Zealand, the Philippines, Malaysia, and other APAC countries.
- Further breakdown of the Latin American liquid handling systems market into Colombia, Chile, Argentina, and Peru, among others.
Get the Full Liquid Handling System Market Report
Full forecast, segment splits, and company analysis for all Liquid Handling System Market.
- Canada Liquid Handling System Market
- US Liquid Handling System Market
- UK Liquid Handling System Market
- France Liquid Handling System Market
- Italy Liquid Handling System Market
- Spain Liquid Handling System Market
- China Liquid Handling System Market
- Japan Liquid Handling System Market
- India Liquid Handling System Market
- South Korea Liquid Handling System Market
- Australia Liquid Handling System Market
- Brazil Liquid Handling System Market
- Mexico Liquid Handling System Market
- Rest Of Europe Liquid Handling System Market
- Rest Of Asia Liquid Handling System Market
- Rest Of Latin America Liquid Handling System Market
- GCC Liquid Handling System Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report