South America Mining Machinery Market (2023-2030)

The South America Mining Machinery Market was valued at $11.3 Million in 2023 and projected to reach to $21.9 Million by 2030, representing a compound annual growth rate of CAGR 9.9%. South America's mining machinery market is poised for substantial expansion through 2030, driven by increased mining activities in Peru, Chile, and Brazil, coupled with infrastructure modernization initiatives.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
South America Mining Machinery Market Trends and Insights
- This robust expansion, driven by a compound annual growth rate of 9.9%, substantially outpaces the global average of 4.1%, positioning South America as a high-growth region within the automotive and transportation sector.
- South America's mining sector expansion, supported by increased commodity demand and infrastructure investment, fuels demand for advanced machinery and equipment. The forecast period through 2030 reflects South America's strategic importance in global mining operations, with regional economies increasingly investing in mechanization and technological upgrades.
- South America's rich mineral reserves and growing operational efficiency requirements drive machinery modernization across copper, lithium, and iron ore extraction.
- South America's market trajectory indicates sustained momentum, with regional players and international manufacturers capitalizing on infrastructure development and rising production capacities to capture market share..
Key Market Statistics
- CAGR (2023-2030) CAGR 9.9%
- Market Size, 2023 ~USD 11.3 Million
- Forecast, 2030 ~USD 21.9 Million
- Geography South America
South America Mining Machinery Market Overview
Exceptional Growth Trajectory :
South America's mining machinery market is experiencing a 9.9% CAGR, nearly 2.4x faster than the global average of 4.1%, reflecting strong regional demand and investment in mining infrastructure.
Market Doubling by 2030 :
The region's market is projected to nearly double from $11.3 billion in 2023 to $21.9 billion by 2030, demonstrating robust expansion opportunities across the automotive and transportation sector.
Key Mining Nations Leading Growth :
Peru ($3.171B), Chile ($3.150B), and Brazil ($3.029B) are the primary drivers of South America's mining machinery demand, supported by abundant mineral resources and active extraction operations.
Strategic Regional Positioning :
South America's high-growth status positions it as a critical market for mining machinery manufacturers seeking to capitalize on emerging opportunities in Latin America's resource-rich economies.
South America Mining Machinery Market Dynamics
- The region's abundant mineral reserves and growing investment in extraction technologies create favorable conditions for market growth.
- Rising commodity prices and renewed focus on sustainable mining practices are expected to accelerate demand for advanced machinery solutions. The 9.9% CAGR significantly outpaces global trends, indicating South America's emergence as a high-priority market for industry stakeholders.
- Government support for mining sector development, coupled with technological advancements in equipment efficiency, will further propel market expansion.
- Strategic partnerships and localized manufacturing capabilities will be essential for capturing market share in this dynamic and rapidly evolving region..
Market Ecosystem
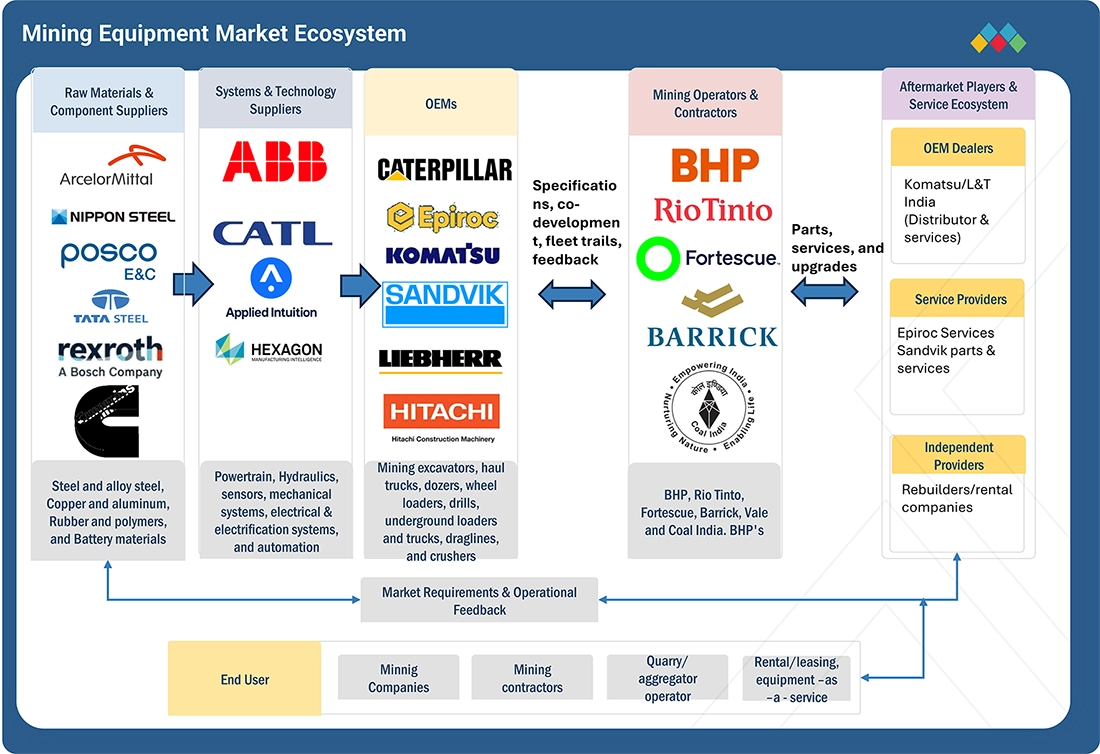
MINING EQUIPMENT MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Cat MineStar Command for Hauling: Caterpillar’s autonomous haulage solution coordinates mining trucks across loading, haulage, and dumping routes, enabling near-continuous operations. | Improves equipment utilization and haul-cycle consistency, reduces exposure to hazardous areas, and supports fuel efficiency and higher equipment availability. |
 |
In April 2026, Komatsu commissioned its 1,000th ultra-class autonomous haul truck named FrontRunner Autonomous Haulage System, a 290-tonne-payload 930E-5AT, at Nevada Gold Mines. | Improves haulage productivity and operating consistency, reduces idle time, and supports safer, more predictable mine production. |
 |
In June 2026, Sandvik launched an underground drilling machine named DD423iE, a battery-electric model featuring 50% greater battery capacity and tramming range and 80% higher battery-drilling performance than its predecessor. | Reduces diesel emissions during operation, supports lower ventilation demand, improves drilling productivity, and reduces charging-related downtime. |
 |
In July 2026, Hitachi Construction Machinery partnered with Pronto to advance OEM-agnostic autonomous haulage solutions that can be retrofitted to trucks from different manufacturers. | Enables mixed-fleet automation, improves haulage coordination and equipment utilization, and gives mine operators more flexibility when adopting autonomous operations. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Key Takeaways
- South America's mining machinery market is projected to grow from $11.3B (2023) to $21.9B (2030), representing a 9.9% CAGR that significantly exceeds global growth rates.
- South America's market expansion is driven by increased commodity demand, infrastructure investments, and regional focus on operational efficiency and mechanization.
- South America's rich mineral reserves in copper, lithium, and iron ore create sustained demand for advanced machinery and equipment modernization.
- South America's high-growth trajectory positions the region as a critical market for both regional and international mining machinery manufacturers through 2030.
Mining Machinery Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2023 |
| Fastest Growing Segment | LITHIUM NICKEL MANGANESE COBALT (NMC) (Battery Chemistry) |
| Forecast Period | 2023-2030 |
| Growth Rate | CAGR of 4.1% from 2023 to 2030 |
| Largest Segment | DIESEL (Propulsion) |
| Market Size Base Year (Billions) | ~USD 24.76 (2023) |
| Revenue Forecast (Billions) | ~USD 32.8 (2030) |
| Segments Covered | Machinery Category, Type, Application, Power Output, Propulsion, Battery Chemistry, Mining Category |
South America Mining Machinery Market Report Segmentation
7 segment dimensions are covered across the global market.
By Machinery Category
- Crushing, Pulverizing, & Screening
- Mineral Processing
- Surface Mining
- Underground Mining
By Type
- Articulated Dump Truck
- Articulated Dump Trucks
- Crawler Dozer
- Crawler Dozers
- Crawler Excavator
- Crawler Excavators
- Drills
- Electric & Hybrid Load-Haul-Dump (Lhd) Loaders
- Electric & Hybrid Mining Trucks
- Electric Shovels
- Hydraulic Excavators
- Mining Dozers
- Mining Trucks
- Motor Grader
- Motor Graders
- Rigid Dump Truck
- Rigid Dump Trucks
- Wheel Loaders
By Application
- Coal
- Metal
- Mineral
By Power Output
- 500-2,000 Hp
- <500 Hp
- >2,000 Hp
By Propulsion
- Cng/Lng/Rng
- Diesel
By Battery Chemistry
- Lithium Iron Phosphate (Lfp)
- Lithium Nickel Manganese Cobalt (Nmc)
By Mining Category
- Surface Mining
- Underground Mining
Target Audience
- Mining Machinery Manufacturers : Identify expansion opportunities in South America's high-growth market and develop region-specific product strategies to capture increasing demand.
- Equipment Distributors & Dealers : Understand market size and growth potential by country to optimize inventory, establish partnerships, and plan distribution network expansion.
- Mining Companies & Operators : Assess machinery market trends and pricing dynamics to make informed procurement decisions and budget planning for equipment investments.
- Investment & Private Equity Firms : Evaluate South America's mining machinery sector as an investment opportunity with strong growth fundamentals and attractive market valuations.
- Automotive & Transportation Analysts : Track regional market performance and forecast trends to support strategic planning and stakeholder reporting on Latin American sector developments.
Countries within South America - compare and drill down
| Country | 2025 size (native) |
|---|---|
| Brazil | USD 3029 Million |
| Chile | USD 3150 Million |
| Peru | USD 3171 Million |
| Argentina | USD 581 Million |
Country market size visualization
Reasons to Buy this Report
- High-Growth Market Opportunity : Capture growth in a region expanding at 9.9% CAGR—more than double the global rate—providing superior ROI potential compared to mature markets.
- Detailed Country-Level Intelligence : Access granular market data for Peru, Chile, Brazil, and Argentina to identify the most lucrative sub-markets and tailor regional strategies accordingly.
- Competitive Positioning Insights : Understand market dynamics specific to South America's mining machinery sector to benchmark against competitors and identify differentiation opportunities.
- Investment & Expansion Planning : Leverage comprehensive forecasts through 2030 to make informed decisions on market entry, capacity expansion, and resource allocation in South America.
- Sector-Specific Trend Analysis : Gain actionable insights into mining machinery demand drivers, technology adoption, and regulatory factors unique to South American markets.
Frequently asked questions
What is the current size of South America's mining machinery market?
South America's mining machinery market was valued at $11.3 billion in 2023 and is expected to reach $21.9 billion by 2030.
What is the projected growth rate for South America's mining machinery market?
South America's mining machinery market is projected to grow at a compound annual growth rate (CAGR) of 9.9% from 2023 to 2030.
How does South America's growth compare to the global mining machinery market?
South America's 9.9% CAGR significantly outpaces the global average of 4.1%, making it one of the fastest-growing regions for mining machinery.
What factors are driving growth in South America's mining machinery market?
South America's market growth is driven by increased commodity demand, infrastructure investments, mechanization initiatives, and modernization of mining operations across copper, lithium, and iron ore sectors.
Which minerals are most important to South America's mining machinery demand?
South America's primary focus is on copper, lithium, and iron ore extraction, which collectively drive the majority of regional mining machinery demand.
RESEARCH METHODOLOGY
The research study involved extensive use of secondary sources such as company annual reports/presentations, industry association publications, magazines, directories, technical handbooks, World Economic Outlook, trade websites, technical articles, and databases to identify and collect information on the mining equipment market. In-depth interviews were conducted with various primary-source experts from related industry players such as mining equipment OEMs, technology providers, and Tier-1 suppliers to obtain and verify critical information and assess the growth prospects and market estimations.
Secondary Research
In the secondary research process, various sources were used to identify and collect information on the global mining equipment market. These included mining industry organizations and associations, mineral production and trade statistics, mining company publications, equipment manufacturers and suppliers, and technical mining publications. Key sources included the International Council on Mining and Metals (ICMM), World Mining Data, national mining authorities, the US Geological Survey (USGS), and the Indian Bureau of Mines (IBM), along with OEMs such as Caterpillar, Komatsu, Sandvik, Epiroc, Liebherr, and Hitachi Construction Machinery. Additional information was collected from company annual reports, investor presentations, project announcements, equipment orders, and mine-development updates, among others. These sources were used to assess mining activity, equipment demand, production capacities, technological developments, regional trends, and competitive strategies. The collected data were analyzed to estimate overall market size and segment-level distribution, and the findings were further validated through primary research.
Primary Research
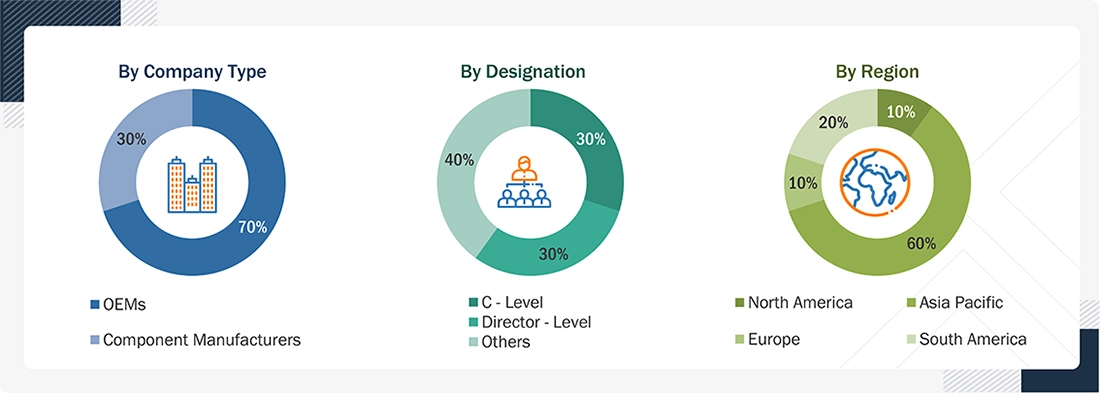
Extensive primary research was conducted after obtaining an understanding of the mining equipment market through secondary research. Several interviews were conducted with market experts from both the demand (mining companies, mining operators and contractors, fleet operators, mine developers and project owners, and others) and supply (mining equipment OEMs, Tier-1 component suppliers, technology providers, and others) players across five major regions-namely, North America, Europe, Asia Pacific, South America, and the Middle East & Africa. Approximately 70% of primary interviews have been conducted with OEMs and 30% with Tier-1 players and others on the demand and supply sides. Primary data has been collected through questionnaires, e-mails, and telephonic interviews. In the canvassing of primary data, various departments within organizations, including sales, operations, and administration, were covered to provide a holistic viewpoint in the report.
After interacting with industry participants, the brief sessions were conducted with highly experienced independent consultants to reinforce the findings from the primaries. This, along with the opinions of in-house subject matter experts, led to the findings as described in the remainder of this report.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
A detailed market estimation approach was followed to estimate and validate the size of the mining equipment market and other dependent submarkets, as mentioned below:
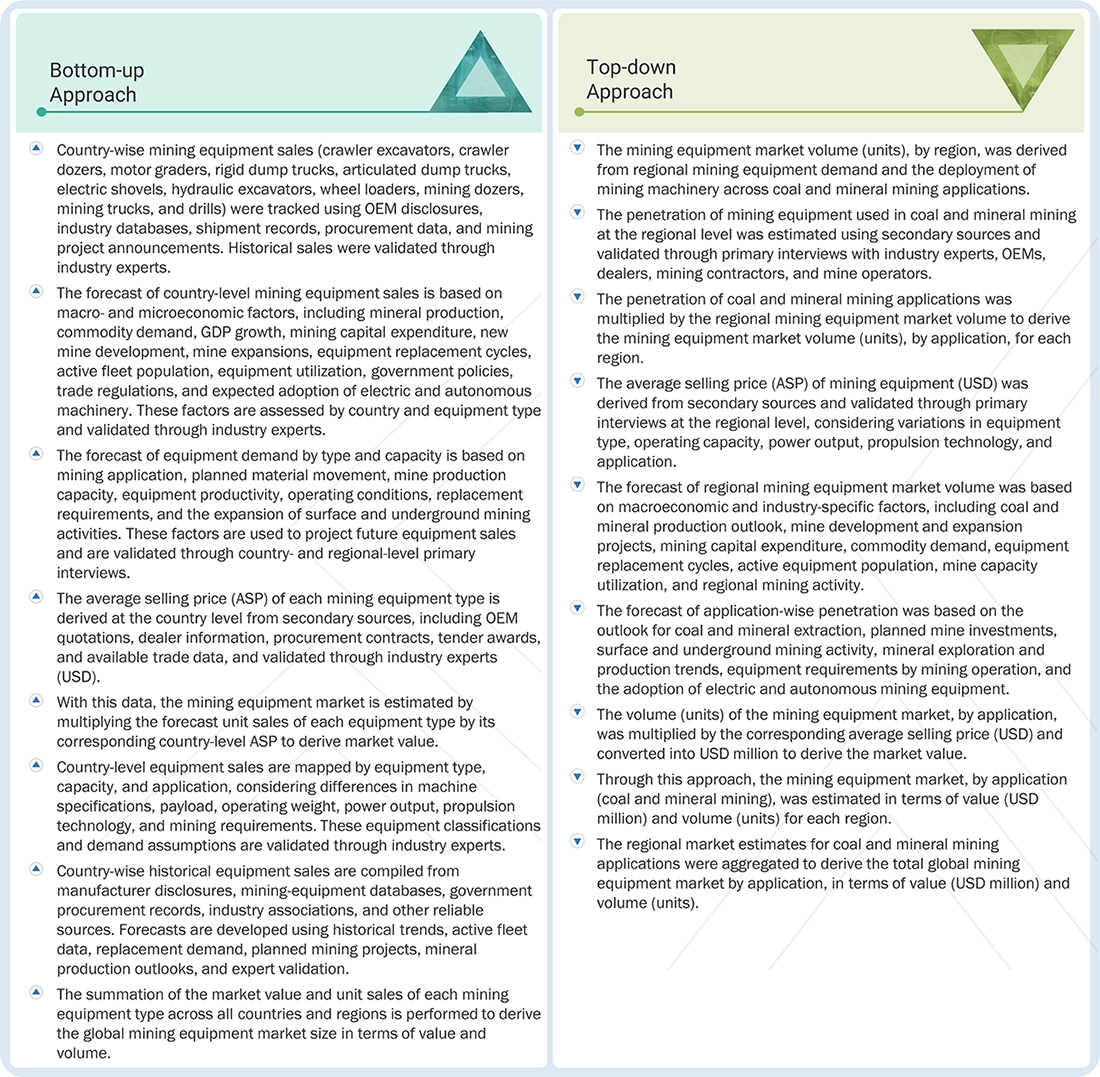
Bottom-up Approach
- The bottom-up approach was used to estimate and validate the mining machinery market size. Historical unit sales of crawler excavators, crawler dozers, motor graders, rigid dump trucks, articulated dump trucks, electric shovels, hydraulic excavators, wheel loaders, mining dozers, mining trucks, and drills were tracked at the country level using OEM annual reports, manufacturer shipment disclosures, industry paid databases, dealer records, procurement contracts, government data, and mining project announcements. Where direct sales data was unavailable, estimates were developed using active equipment populations, historical shipment trends, manufacturer delivery announcements, and mine-level fleet information.
- Country-level unit sales were forecast through 2033, based on historical demand patterns, equipment replacement cycles, fleet expansion requirements, planned mine openings and expansions, mineral production outlooks, mining capital expenditure, and changes in material movement requirements. Forecasting assumptions accounted for equipment lifespan, utilization rates, mine capacity, project commissioning timelines, commodity demand, regional mining activity, and the adoption of electric and autonomous equipment. Replacement demand was assessed separately from incremental fleet additions to avoid double counting.
- Average selling prices (ASPs) were estimated for each equipment category, country, and relevant capacity class using OEM quotations, dealer inputs, public tender awards, procurement contracts, and available trade data. These prices were validated through primary interviews, considering differences in operating weight, payload capacity, power rating, machine configuration, propulsion technology, and regional pricing.
- Forecast ASPs incorporated assumptions regarding equipment price inflation, raw-material and component costs, exchange-rate movements, localization, import duties, technology upgrades, electrification, automation, and changes in equipment size and product mix.
- At the end, the country-level equipment unit sales were multiplied by the corresponding ASPs to calculate country-level market values for each equipment category. The resulting volumes and values were aggregated across countries and regions to derive the global mining equipment market size and forecast through 2033.
Top Down Approach
The mining equipment market volume (units), by region, was derived from regional mining equipment demand and machinery deployment across coal, metal, and mineral mining applications. The penetration of coal, metal, and mineral mining applications at the regional level was estimated using secondary sources and validated through primary interviews with industry experts. The forecast of regional application-wise penetration was based on coal, metal, and mineral production outlooks, expected coal and mineral extraction trends, planned mining investments, surface and underground mining activities, among others. The application-wise penetration rates were multiplied by regional mining equipment volume to derive the market volume (units) for coal, metal, and mineral mining. The average selling price (ASP) of mining equipment (USD) was derived from secondary sources and validated through primary interviews, considering variations in equipment type, operating capacity, power output, propulsion technology, and application. The volume of mining equipment by application was multiplied by the corresponding ASP and converted into USD million to derive market value. Finally, regional estimates were aggregated to determine the global mining equipment market by application (coal and mineral mining), in terms of value (USD million) and volume (units).
Mining Equipment Market: Top-Down and Bottom-Up Approach
Data Triangulation
After arriving at the overall market size of the global market through the above-mentioned methodology, this market was split into several segments and subsegments. The data triangulation and market breakdown procedures were employed, wherever applicable, to complete the overall market engineering process and arrive at the exact data for the market by value for the key segments and subsegments. The extrapolated market data was triangulated by studying various macro indicators and regional trends from both the demand and supply participants.
Market Definition
- Mining Machinery: Mining machinery is used for the extraction of raw materials in open-cast mining environments. It refers to the specialized equipment and machinery used in various stages of the mining process, including exploration, extraction, processing, and transportation of minerals and ore deposits. It can range from large-scale mining trucks, excavators, and drilling machines for open-pit operations to underground mining machinery.
- Surface Mining Machinery: Surface mining machinery refers to a broad range of tools used mostly in open-pit or open-cast mines to remove minerals and ores from the surface of the ground. When the mineral ore reserves are close to the surface and can be economically mined utilizing sizable machinery, this mining machinery is employed.
- Underground Mining Machinery: Underground mining machinery is made specifically to operate in the constrained and difficult conditions of underground mines, where access and space are limited. Deep within the Earth, these machines are essential for drilling, transporting, and processing metals and minerals. They are designed to resist challenging underground environments, which include little light, excessive humidity, and small areas.
Key Stakeholders
- Mining Companies
- Mining Machinery/Equipment Manufacturers
- Tier 1 & Component Suppliers
- Mining Operators and Contractors
- Mine Developers and Project Owners
- Fleet Owners and Fleet Operators
- Technology Providers
- Government and State-Owned Mining Enterprises
- Consulting companies in the Heavy Machinery Sector
- Heavy Equipment Associations
- Rental Machinery Suppliers
- Government and Research Organizations
- Regulatory Authorities
Report Objectives
- To analyze and forecast the market size for mining machinery from 2022 to 2033 in terms of volume (units) and value (USD million/billion)
-
To define and describe the mining equipment market by:
- By machinery category [crushing, pulverizing, and screening machinery; mineral processing; surface mining (crawler excavators, crawler dozers, motor graders, rigid dump trucks, and articulated dump trucks); and underground mining (electric shovels, hydraulic excavators, wheel loaders, mining dozers, mining trucks, and drills)]
- By propulsion [diesel and compressed natural gas (CNG)/liquified natural gas (LNG)/renewable natural gas (RNG)]
- By application (mineral, metal, and coal)
- By power output (<500 HP, 500-2,000 HP, and >2,000 HP)
- Autonomous mining machinery by mining category (surface mining and underground mining)
- Electric & hybrid mining machinery by type [mining trucks and load-haul-dump (LHD) loaders]
- Electric & mining machinery by battery chemistry [lithium iron phosphate (LFP), lithium nickel manganese cobalt (NMC), and others (lithium titanate oxide (LTO), lithium manganese oxide (LMO), and solid-state battery)
- By region (Asia Pacific, Europe, North America, South America, and the Middle East & Africa)
- To provide detailed information regarding market dynamics, including drivers, restraints, opportunities, and challenges, which influence the growth of the market
-
To provide:
- Trends/disruptions impacting buyers
- Case studies
- Patent analysis
- Supply chain analysis
- Market ecosystem
- Regulatory analysis
- OEM analysis
- Brand comparison
- Company valuation
- Investment & funding scenario
- Technology trends
- Unmet needs and white spaces
- Interconnected market and cross-sector opportunities
- Pricing analysis
- Future technology roadmap
- To understand the dynamics (drivers, restraints, opportunities, and challenges) of the market
- To understand the competitive evaluation matrix for key players in the mining equipment market and position the players as stars, emerging, pervasive, and participants according to their product portfolio and business strategies
- To analyze the market share of leading players in the mining equipment market and evaluate the company evaluation matrix
- To strategically analyze the key players' strategies/right to win and company revenue
- To analyze the opportunities in the market for stakeholders and provide details of the competitive landscape for market leaders
- To provide an analysis of recent developments, collaborations, partnerships, product launches & enhancements, and other activities carried out by key industry participants in the mining equipment market
Available customizations:
With the given market data, MarketsandMarkets offers customizations in accordance with the company’s specific needs.
-
Autonomous Mining Machinery Market, By Level of Automation
- Semi-Autonomous
- Fully Autonomous
-
Mining Machinery Market, By Country & Machinery Category
- Crushing, Pulverizing, Screening Machinery
- Mineral Processing Machinery
Get the Full Mining Machinery Market Report
Full forecast, segment splits, and company analysis for all Mining Machinery Market.
- China Mining Machinery Market
- India Mining Machinery Market
- Japan Mining Machinery Market
- Indonesia Mining Machinery Market
- Australia Mining Machinery Market
- France Mining Machinery Market
- Germany Mining Machinery Market
- Italy Mining Machinery Market
- Spain Mining Machinery Market
- UK Mining Machinery Market
- Russia Mining Machinery Market
- Canada Mining Machinery Market
- Mexico Mining Machinery Market
- US Mining Machinery Market
- Brazil Mining Machinery Market
- Chile Mining Machinery Market
- Peru Mining Machinery Market
- Argentina Mining Machinery Market
- South Africa Mining Machinery Market
- Saudi Arabia Mining Machinery Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
