Asia Pacific Road Safety Market (2025-2030)
The Asia Pacific Road Safety Market was valued at $1118 Million in 2025 and projected to reach to $2318.4 Million by 2030, representing a compound annual growth rate of 15.7%. The Asia Pacific road safety market is poised for exceptional growth, driven by rapid urbanization, increasing vehicle ownership, and stringent government safety mandates across the region.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Asia Pacific Road Safety Market Trends and Insights
- Asia Pacific's 15.7% compound annual growth rate significantly outpaces global trends, driven by rapid urbanization, increasing vehicle ownership, and heightened regulatory focus on traffic safety across the region.
- Government initiatives and smart city investments are accelerating adoption of advanced road safety technologies throughout Asia Pacific. Asia Pacific's market growth reflects rising awareness of road fatalities and injuries, particularly in developing economies where vehicle populations are expanding fastest.
- The region's diverse regulatory landscape—spanning stringent safety standards in developed markets like Australia and Japan to emerging frameworks in Southeast Asia—creates varied opportunities for road safety solutions.
- Asia Pacific stakeholders are increasingly investing in intelligent transportation systems, vehicle-to-infrastructure communication, and real-time monitoring platforms to address safety challenges. By 2030, Asia Pacific is expected to capture a substantial share of global road safety innovation, with technology providers and infrastructure developers competing intensely to serve the region's growing demand for integrated safety ecosystems..
Key Market Statistics
- CAGR (2025-2030) 15.7% CAGR
- Market Size, 2025 ~USD 1118 Million
- Forecast, 2030 ~USD 2318.4 Million
- Geography Asia Pacific
Asia Pacific Road Safety Market Overview
Fastest Growing Regional Market :
Asia Pacific's 15.7% CAGR significantly outpaces the global growth rate of 13.1%, positioning the region as the fastest-expanding road safety market worldwide through 2030.
Rapid Urbanization & Vehicle Growth :
Accelerating urbanization and surging vehicle ownership across Asia Pacific are driving unprecedented demand for advanced road safety solutions, particularly in emerging economies.
Strong Regulatory Push :
Governments across Asia Pacific are implementing stringent traffic safety regulations and mandatory safety standards, creating substantial opportunities for compliance-driven technology adoption.
Market Valuation Doubling :
The region's market is projected to more than double from USD 1,118.0 million in 2025 to USD 2,318.4 million by 2030, reflecting exceptional investment potential.
Asia Pacific Road Safety Market Dynamics
- Countries like China, India, and Japan are leading adoption of intelligent transportation systems, connected vehicle technologies, and advanced driver assistance systems.
- The region's younger demographic and rising middle class are accelerating demand for safer mobility solutions. Investment in smart city infrastructure and digital transformation initiatives further accelerates market expansion.
- Public-private partnerships and government funding for road safety initiatives create favorable conditions for technology providers.
- By 2030, Asia Pacific will represent a critical growth engine for the global road safety market, with emerging economies driving innovation and adoption of next-generation safety technologies..
Market Ecosystem
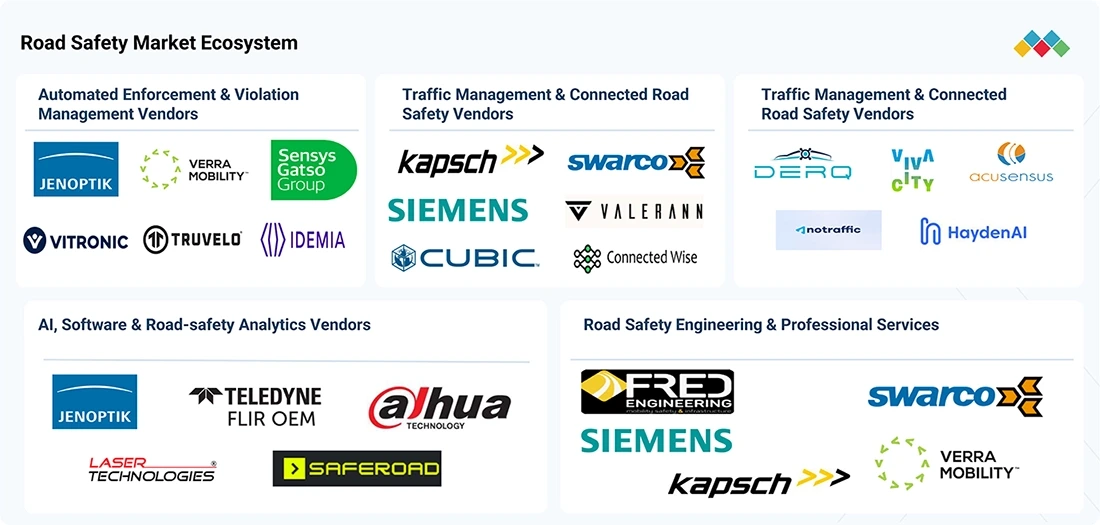
ROAD SAFETY MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Victoria Police deployed JENOPTIK’s mobile distracted-driving enforcement solution to detect mobile-phone use and seatbelt violations using camera-based technology and AI analytics. The system supports automated identification of unsafe driver behavior and evidence generation for enforcement. | Improved detection of distracted driving and seatbelt violations, more efficient enforcement, and enhanced road-user safety through automated evidence collection and analytics. |
 |
Kapsch TrafficCom, together with SCAIL, is deploying India’s first C-ITS project on a highway near New Delhi. The system provides connected-vehicle warnings for roadworks, maintenance vehicles, hazardous locations, traffic queues, and temporary virtual signage using real-time connectivity and AI-based situational awareness. | Earlier warnings of road hazards, improved work-zone safety, faster driver response, and enhanced protection of road users through connected infrastructure. |
 |
Sensys Gatso provides automated traffic enforcement as a managed service, combining speed, red-light, school-zone, and work-zone enforcement with hardware, software, data, analytics, and citation processing. Municipal and government authorities have deployed its solutions to improve traffic safety and driver compliance. | Higher enforcement coverage, improved compliance with speed limits, reduced risky driving behavior, and lower operational burden for public authorities through managed enforcement services. |
 |
Verra Mobility manages automated speed and red-light enforcement programs for government and transportation agencies. In Hawaii, the company expanded its program under a 10-year contract to 187 dual-enforcement cameras across major islands, following reported reductions in red-light violations and crashes at existing sites. | Improved traffic-law compliance, reduced dangerous driving, expanded automated enforcement coverage, and enhanced safety at high-risk intersections and roadways. |
 |
Teledyne FLIR thermal cameras are used for pedestrian detection and automatic emergency braking applications, particularly in darkness, glare, fog, and other challenging visibility conditions. Their thermal sensing technology can complement radar and visible cameras to improve vulnerable road user detection. | Improved nighttime and adverse-weather pedestrian detection, earlier AEB response, enhanced vulnerable-road-user protection, and reduced limitations of conventional vision sensors. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Cyber Security
- Cloud Security
- Biometric Systems
- Data Loss Prevention (DLP)
- Multi-Factor Authentication
- Security Analytics
- International Business Machines Corporation
- MITSUI BUSSAN SECURE DIRECTIONS INC
- Cisco Systems, Inc.
- MICROSOFT CORPORATION
- Allot Ltd.
Network Security
- Cloud Security
- Critical Communication Network
- Surveillance System
- Video Surveillance Systems
- Biometric Security and Authentication System
- Cisco Systems, Inc.
- International Business Machines Corporation
- Fortinet, Inc.
- MICROSOFT CORPORATION
- PALO ALTO NETWORKS, INC
Public Safety
- Face Recognition
- Cloud Security
- Surveillance System
- Voice Recognition
- Biometric Security and Authentication System
- Zensar Technologies Limited
- International Business Machines Corporation
- Allot Ltd.
- Cisco Systems, Inc.
- MICROSOFT CORPORATION
Key Takeaways
- Asia Pacific road safety market will more than double from $1,118.0M (2025) to $2,318.4M (2030), reflecting 15.7% CAGR growth.
- Asia Pacific's growth rate of 15.7% significantly exceeds the global average, positioning the region as a primary driver of market expansion.
- Rapid urbanization and vehicle proliferation across Asia Pacific are creating urgent demand for intelligent transportation and real-time safety monitoring solutions.
- Asia Pacific's diverse regulatory environment and smart city initiatives are accelerating technology adoption and creating competitive opportunities for road safety providers.
Road Safety Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | MANAGED SERVICES (Service) |
| Forecast Period | 2025–2030 |
| Growth Rate | CAGR of 13.1% from 2025 to 2030 |
| Largest Segment | ROADWAY (Transportation Mode) |
| Market Size Base Year (Billions) | ~USD 6.7 (2025) |
| Revenue Forecast (Billions) | ~USD 12.39 (2030) |
| Segments Covered | Offering, Solution, Solution Type, Component, Service, Type, Deployment Model, Enforcement Type, Data Type, Professional Service, Managed Service, Application, End User, Area Of Application, Transportation Mode |
Asia Pacific Road Safety Market Report Segmentation
15 segment dimensions are covered across the global market.
By Offering
- Services
- Solutions
By Solution
- Component
- Solution Type
By Solution Type
- Alpr/Anpr
- Enforcement Solution
- Enforcement Solutions
- Incident Detection & Response
- Pedestrian Safety
- Traffic Monitoring & Control
By Component
- Hardware
- Software
By Service
- Managed Services
- Professional Services
By Type
- Analytics-As-A-Service
- Back-Office Processing
- Consulting
- Outsourced Operations
- Road Safety Audits
- Services
- Solutions
- System Integration
- System Maintenance
- Training
By Deployment Model
- Cloud-Based Platforms
- Fixed Installations
- Mobile/Trailer-Mounted Systems
- Portable/Temporary Solutions
By Enforcement Type
- Automated Enforcement
- Hybrid Enforcement
- Manual Enforcement
By Data Type
- Integrated Big Data
- Sensor Data
- Video & Image
By Professional Service
- Consulting
- Road Safety Audits
- System Integration
- Training
By Managed Service
- Analytics-As-A-Service
- Back-Office Processing
- Outsourced Operations
- System Maintenance
By Application
- Accident Prevention
- Driver Behavior Monitoring
- Emergency Response
- Insurance Risk Assessment
- Pedestrian & Vru Protection
- Public Awareness/Training
- Traffic Optimization
- Violation Management
- Work Zone Safety Management
By End User
- Construction Companies
- Government
- Government & Municipalities
- Highway Authorities
- Law Enforcement Agencies
- Private
- Private Toll Operators
- Smart City Integrators
By Area Of Application
- Inter-Urban
- Rural
- Urban
By Transportation Mode
- Airway
- Maritime
- Railway
- Roadway
Target Audience
- Technology & Safety Solution Providers : Vendors of road safety technologies, ADAS, and intelligent transportation systems need Asia Pacific market data to identify growth opportunities and develop region-specific product strategies.
- Automotive Manufacturers : OEMs require detailed insights into Asia Pacific safety regulations, consumer preferences, and market dynamics to optimize vehicle safety features and meet regional compliance standards.
- Government & Transportation Agencies : Public sector organizations planning road safety initiatives, infrastructure investments, and policy frameworks benefit from comprehensive market analysis and regional benchmarking.
- Investment & Private Equity Firms : Investors evaluating opportunities in Asia Pacific's high-growth road safety sector need market sizing, growth projections, and competitive landscape analysis for informed decision-making.
- Consulting & Strategic Planning Teams : Business strategists and consultants advising clients on Asia Pacific expansion require detailed market forecasts, regional trends, and country-specific insights for strategic recommendations.
Key Companies in the Asia Pacific Road Safety Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| BLUJAY SOLUTIONS | United Kingdom | Private Company | Transportation & Fleet Management (incl. MobileSTAR),Control Tower, BluIQ Analytics & Actionable Intelligence,Customs, Compliance & Augmented Global Trade, |
| JABIL | United States | Public Company | Sensors and Cameras Hardware,Traffic Control and Smart Signals Platforms,RSUs and Connectivity Modules, |
| THE 3M COMPANY | United States | Public Company | Traffic Control (signage, markings, work-zone materials),Sensors, RSUs, Smart Signals (hardware adjacencies),Cameras, ANPR, ALPR, Enforcement, |
| DHC SOFTWARE CO., LTD. | United States | Public Company | Traffic Control & Smart Signals,ANPR/ALPR & Enforcement,Incident Response & Emergency Management, |
| ZENSAR TECHNOLOGIES LTD | India | Public Company | AI, ML, Analytics,Incident Response & Violation Management Platforms,Traffic Control & Smart Signals Integration, |
| JENOPTIK | Germany | Public Company | Speed and Red-Light Enforcement Systems,ANPR/ALPR and Data Analysis Software,Traffic Control, Smart Signals, and RSUs, |
| KAPSCH TRAFFICCOM | Austria | Public Company | Traffic Control & Smart Signals,ANPR/ALPR & Cameras,Incident Response, RSUs & Sensors, |
| SENSYS GATSO GROUP | Sweden | Public Company | Traffic Control & Enforcement (speed, red-light, section control, school zones),ANPR/ALPR & Vehicle Access Control,Back-office Software (Flux, Puls, Xilium) & Analytics (AI/ML), |
| VERRA MOBILITY | United States | Public Company | Enforcement (speed, red-light, school bus, bus lane),Violation Management, ANPR/ALPR Analytics,Parking & Work Zone Safety Solutions, |
| TELEDYNE FLIR | United States | Private Company | Traffic Control & Smart Signals,Enforcement (ANPR/ALPR & Violation Management),Incident Response & Work Zone Safety, |
| MOTOROLA SOLUTIONS | United States | Public Company | Cameras & Sensors (fixed/mobile, including in-vehicle video),AI/ML & Video/ALPR Analytics,Incident Response & Command Center Software, |
| IDEMIA | France | Private Company | ANPR/ALPR & Enforcement Platforms,AI/ML Analytics & Incident Response,Cameras & Sensors (via partners/OEM bundles), |
| SIEMENS | Germany | Public Company | Traffic Control & Smart Signals,Enforcement, ANPR & ALPR,Sensors, Cameras, RSUs, |
| CONDUENT | United States | Public Company | Enforcement & Violation Management (incl. ANPR/ALPR-enabled back office),Traffic Control & Smart Signals (software, analytics, integration),Incident Response & Work Zone Safety Solutions, |
| CUBIC CORPORATION | United States | Private Company | Traffic Control & Smart Signals,Cameras, Sensors, RSUs,ANPR/ALPR & Enforcement, |
| DAHUA TECHNOLOGY | China | Public Company | Cameras (fixed, PT/PTZ, thermal, explosion-proof),ANPR/ALPR and Enforcement Solutions,Traffic Control, Smart Signals, RSUs, and Sensors, |
| LASER TECHNOLOGIES | United States | Private Company | Enforcement (laser speed and distance devices),Traffic Control & Incident Response (range-based measurement tools),Software (data collection and reporting), |
BLUJAY SOLUTIONS
Blujay Solutions is a UK-based private company founded in 1972 with 600 employees. The company specializes in supply chain and logistics software solutions.
JABIL
Jabil is a US-based public company founded in 1966 with 135,000 employees. The company provides electronics manufacturing services and supply chain solutions globally.
THE 3M COMPANY
The 3M Company is a US-based public company founded in 1902 with 60,500 employees. It is a diversified technology and manufacturing conglomerate known for innovative products across multiple industries.
DHC SOFTWARE CO., LTD.
DHC Software Co., Ltd. is a US-based public company founded in 2001 with 10,757 employees. The company develops and provides software solutions for enterprise applications.
ZENSAR TECHNOLOGIES LTD
Zensar Technologies Ltd is an India-based public company founded in 1963 with 10,066 employees. It offers IT services, digital transformation, and software development solutions.
JENOPTIK
Jenoptik is a Germany-based public company founded in 1846 with 4,020 employees. The company specializes in optics, photonics, and industrial technology solutions.
KAPSCH TRAFFICCOM
Kapsch TrafficCom is an Austria-based public company founded in 1892 with 3,041 employees. It develops intelligent transportation systems and traffic management solutions.
SENSYS GATSO GROUP
Sensys Gatso Group is a Sweden-based public company founded in 1958 with 268 employees. The company manufactures traffic safety and enforcement systems.
VERRA MOBILITY
Verra Mobility is a US-based public company founded in 1987 with 1,895 employees. It provides mobility and enforcement solutions for traffic and parking management.
TELEDYNE FLIR
Teledyne FLIR is a US-based private company founded in 1978 with 4,179 employees. The company specializes in thermal imaging and infrared technology solutions.
MOTOROLA SOLUTIONS
Motorola Solutions is a US-based public company founded in 1928 with 23,000 employees. It provides communications, software, and services for enterprise and government customers.
IDEMIA
IDEMIA is a France-based private company founded in 1987 with 6,800 employees. The company specializes in identity and security solutions including biometrics and digital services.
SIEMENS
Siemens is a Germany-based public company founded in 1847 with 310,312 employees. It is a global conglomerate providing electrification, automation, and digitalization solutions across multiple sectors.
CONDUENT
Conduent is a US-based public company founded in 2016 with 48,000 employees. It provides business process services and digital transformation solutions for government and commercial clients.
CUBIC CORPORATION
Cubic Corporation is a US-based private company founded in 1951 with 6,100 employees. The company develops transportation systems, defense electronics, and software solutions.
DAHUA TECHNOLOGY
Dahua Technology is a China-based public company founded in 2002 with 22,131 employees. It manufactures and provides video surveillance, security, and smart technology solutions.
LASER TECHNOLOGIES
Laser Technologies is a US-based private company founded in 1985 with 78 employees. The company specializes in laser-based technology and precision measurement solutions.
Countries within Asia Pacific - compare and drill down
| Country | 2025 size (native) |
|---|---|
| China | USD 662.3 Million |
| Japan | USD 326.3 Million |
| India | USD 319.6 Million |
| South Korea | USD 296.2 Million |
| UAE | USD 258.7 Million |
Country market size visualization
Reasons to Buy this Report
- Regional Growth Outpacing Global Trends : With a 15.7% CAGR versus 13.1% globally, Asia Pacific offers superior growth opportunities. This analysis provides strategic insights to capitalize on the region's accelerating market expansion.
- Country-Level Market Intelligence : Detailed breakdowns for China, Japan, India, South Korea, and UAE enable targeted market entry strategies and competitive positioning within Asia Pacific's diverse economies.
- Regulatory & Policy Landscape : Comprehensive coverage of government safety mandates and regulatory frameworks across Asia Pacific helps identify compliance-driven opportunities and market drivers specific to each country.
- Emerging Market Opportunities : Identify high-growth emerging markets within Asia Pacific where road safety adoption is accelerating, enabling early-mover advantages in underpenetrated segments.
- Technology Adoption Trends : Understand regional preferences for intelligent transportation systems, connected vehicles, and ADAS technologies to align product development and go-to-market strategies.
Frequently asked questions
What is the projected size of the Asia Pacific road safety market by 2030?
The Asia Pacific road safety market is projected to reach USD 2,318.4 million by 2030, growing from USD 1,118.0 million in 2025.
What is the CAGR for the Asia Pacific road safety market?
Asia Pacific's road safety market is expected to grow at a compound annual growth rate of 15.7% between 2025 and 2030.
What factors are driving growth in the Asia Pacific road safety market?
Key drivers include rapid urbanization, increasing vehicle ownership, government safety regulations, smart city investments, and rising awareness of road fatalities across Asia Pacific.
How does Asia Pacific's growth compare to the global road safety market?
Asia Pacific's 15.7% CAGR significantly outpaces the global average of 13.1%, making the region a critical growth engine for the road safety market.
Which technologies are gaining traction in the Asia Pacific road safety market?
Intelligent transportation systems, vehicle-to-infrastructure communication, real-time monitoring platforms, and integrated safety ecosystems are experiencing rapid adoption across Asia Pacific.
RESEARCH METHODOLOGY
The research study for the road safety market involved extensive secondary sources, directories, journals, and paid databases. Primary sources included industry experts from core and related industries, preferred road safety providers, third-party service providers, consulting service providers, end users, and other commercial enterprises. In-depth interviews with primary respondents, including key industry participants and subject matter experts, were conducted to obtain and verify critical qualitative and quantitative information and assess the market’s prospects.
Secondary Research
In the secondary research process, the study referred to various authoritative and industry sources to identify and collect information. The secondary sources included annual reports; investor presentations; company press releases; product documentation; technical specifications; government publications; regulatory documents; transportation and road-safety databases; procurement and tender documents; and certified publications and standards related to road safety, intelligent transportation systems, traffic enforcement, connected vehicles, and road infrastructure. Relevant information was also collected from organizations and institutions such as the World Health Organization (WHO), United Nations Economic Commission for Europe (UNECE), United Nations Road Safety Collaboration (UNRSC), World Bank, International Transport Forum (ITF), International Organization for Standardization (ISO), International Telecommunication Union (ITU), Institute of Transportation Engineers (ITE), Intelligent Transportation Society of America (ITS America), European Commission, European Road Safety Observatory (ERSO), Federal Highway Administration (FHWA), National Highway Traffic Safety Administration (NHTSA), US Department of Transportation (USDOT), and European Transport Safety Council (ETSC). Government and regulatory sources from major countries and regions were also reviewed, including the US Department of Transportation, Transport Canada, the European Union and national transport ministries, the UK Department for Transport, India's Ministry of Road Transport and Highways (MoRTH), and relevant state and municipal transportation authorities. Technical standards and guidance related to automated enforcement, intelligent transportation systems, connected and cooperative mobility, V2X communication, vulnerable road users, traffic-control systems, road infrastructure, vehicle safety, and data management were also considered, including standards and publications from ISO, SAE International, IEEE, ETSI, and other recognized transportation and technology organizations. The analysis also reviewed company-level information from leading road-safety technology providers to assess product portfolios, product launches, partnerships, contracts, deployments, technology developments, geographic presence, and competitive strategies.
Secondary research was used to gather key information on the industry’s value chain, the market’s monetary chain, the overall pool of key players, market classification and segmentation aligned with industry trends to the bottom-most level, regional markets, and key developments from market- and technology-oriented perspectives.
Primary Research
Primary research for the road safety market was conducted with a diverse set of stakeholders across the supply and demand sides of the market to validate market assumptions, technology adoption trends, pricing structures, purchasing criteria, and competitive dynamics. Interviews were targeted toward company executives, technology and innovation leaders, system integrators, road-safety solution providers, enforcement technology vendors, highway and transportation authorities, law-enforcement agencies, and other industry experts. The discussions focused on the adoption of automated enforcement, ANPR/ALPR, AI-based video analytics, incident detection, traffic monitoring, connected road infrastructure, pedestrian and VRU protection, and road-safety services.
The primary research process was designed to understand how road-safety technologies are evaluated, purchased, deployed, and operated across different end-user groups. Discussions with government and municipal stakeholders, highway authorities, and law-enforcement agencies provided insights into procurement processes, regulatory requirements, deployment priorities, system integration requirements, and operational challenges. Industry participants provided perspectives on technology roadmaps, product development, competitive positioning, pricing structures, contract models, recurring service opportunities, and the transition from standalone enforcement equipment toward integrated road-safety platforms.
Primary interviews also examined the key demand drivers and adoption barriers influencing the market. Stakeholders highlighted factors such as increasing road fatalities, government road-safety initiatives, stricter traffic enforcement, smart-city investments, expansion of intelligent transportation systems, and the growing availability of AI-enabled sensing and analytics. Discussions also assessed implementation challenges, including infrastructure readiness, interoperability with legacy systems, data privacy and security, regulatory approvals, public acceptance, budget constraints, system maintenance, and the availability of skilled personnel. Stakeholder research on automated enforcement similarly indicates that public acceptance, perceived legitimacy, and evidence of safety benefits can influence deployment decisions.
The research further evaluated technology-specific adoption and commercial use cases across automated speed enforcement, red-light enforcement, ANPR/ALPR, AI-powered violation detection, driver behavior monitoring, incident detection and response, smart traffic signals, road-weather monitoring, connected intersections, V2X communication, and VRU protection. Interviews assessed the maturity of these technologies, current commercial deployments, expected adoption timelines, and the extent to which AI, computer vision, edge computing, IoT sensors, and connected infrastructure are changing conventional road-safety operations. Evidence from recent research on AI-powered enforcement also indicates growing deployment of automated systems for real-time violation detection and their potential influence on driver behavior and traffic safety.
The findings from primary research were subsequently triangulated with secondary research, company disclosures, government publications, regulatory documents, industry standards, procurement information, and other authoritative sources. Primary interview inputs were used to validate market segmentation, estimate technology and solution adoption, assess vendor positioning, identify emerging applications, and refine assumptions about market growth and demand potential. The research also supported the bottom-up assessment of market opportunities by evaluating the typical composition of hardware, software, services, and managed-service contracts across different road-safety applications and end users. This combined approach helped ensure that the final market estimates and forecasts reflect both quantitative market indicators and qualitative insights from participants directly involved in the road-safety ecosystem.
Breakdown of Primary Research
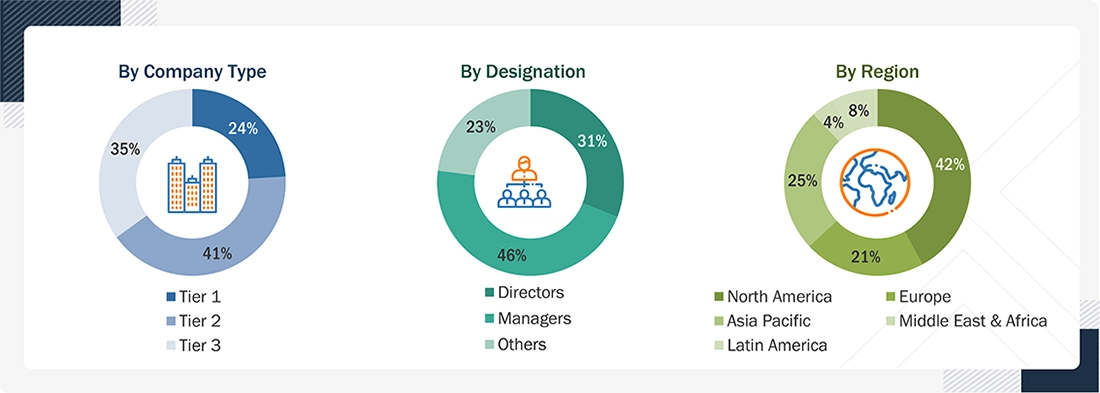
Note: Three tiers of companies are defined based on their total revenue for the year ended 31st December 2025; Tier 1 companies’ revenue is more than USD 500 million; Tier 2 companies' revenue ranges between USD 500 million and 100 million; and Tier 3 companies’ revenue is less than USD 100 million
Source: MarketsandMarkets Analysis
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
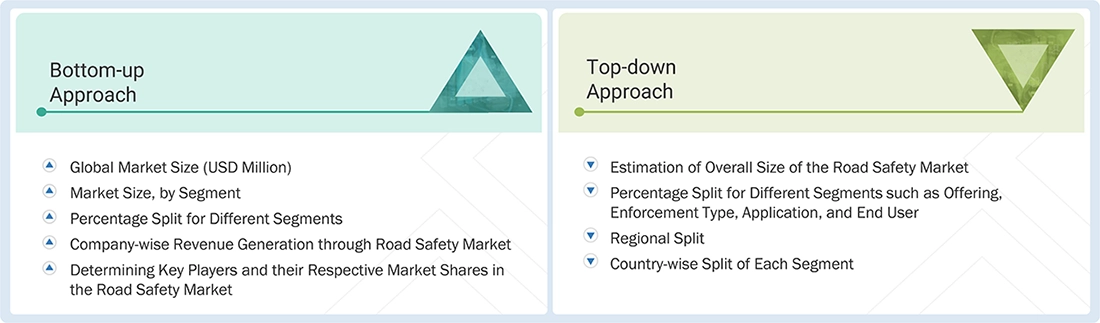
The top-down and bottom-up approaches were used to estimate and forecast the road safety market and its dependent submarkets. This multi-layered analysis was further reinforced through data triangulation, which incorporated primary and secondary research inputs. The market figures were also validated against the existing MarketsandMarkets repository for accuracy.
Data Triangulation
The market was divided into several segments and subsegments after determining the overall market size using the market size estimation processes described above. To complete the overall market engineering process and determine the exact statistics for each market segment and subsegment, data triangulation and market segmentation procedures were employed, wherever applicable. The overall market size was then used in the top-down approach to estimate the size of other individual markets by applying percentage splits to the market segmentation.
Market Definition
The road safety market comprises technologies, solutions, and services designed to prevent road crashes, detect unsafe driving and road conditions, and improve the safety of vehicles and road users. It includes automated enforcement, ANPR/ALPR, incident detection, traffic monitoring, intelligent sensing, pedestrian and vulnerable road-user protection, and connected road-safety systems. The market also covers AI-enabled analytics, V2X applications, safety-specific traffic infrastructure, and related managed and professional services. It excludes general traffic management, mobility, tolling, and transportation solutions where road safety is not the primary purchased function.
Position sensors play a crucial role across automotive and electric vehicles, manufacturing and industrial automation, robotics, aerospace & defense, healthcare equipment, packaging machinery, and consumer electronics. These solutions enable precise motion measurement, position feedback, equipment control, automation, and safety functions. Position sensors are commonly integrated into steering and braking systems, actuators, motors, machine tools, robotic systems, material-handling equipment, and automated production lines. A typical position-sensing system may consist of a sensing element, signal-conditioning or processing circuitry, output interface, and associated control electronics, with its configuration varying according to the sensing technology, measurement range, accuracy requirements, application, and operating environment.
Key Stakeholders
- Government agencies
- Road safety Original Equipment Manufacturers (OEMs)
- Road safety service providers
- System integrators
- Consulting firms
- Research organizations
- Resellers and distributors
- Managed service providers
- Regulatory authorities and associations
- Information Technology (IT) service providers
- Consultants/Consultancies/Advisory firms
- Training providers
Report Objectives
- To define, describe, and forecast the road safety market by offering, enforcement type, application, and end user
- To provide detailed information related to major factors (drivers, restraints, opportunities, and industry-specific challenges) influencing the market growth
- To analyze the micro markets with respect to individual growth trends, prospects, and their contribution to the total market
- To analyze the opportunities in the market for stakeholders by identifying the high-growth segments of the road Safety market
- To analyze opportunities in the market and provide details of the competitive landscape for stakeholders and market leaders
- To forecast the market size of segments for five main regions: North America, Europe, Asia Pacific, the Middle East & Africa, and Latin America
- To profile the key players and comprehensively analyze their market ranking and core competencies
- To analyze competitive developments, such as partnerships, product launches, and mergers & acquisitions, in the road safety market
Available customizations:
With the given market data, MarketsandMarkets offers customizations as per your company’s specific needs. The following customization options are available for the report:
Product analysis
- Brand/product comparative analysis of additional vendors
Geographic analysis
- Inclusion of additional European countries, with breakdown by offering, enforcement type, application, and end user segments
- Inclusion of additional Asia Pacific countries, with breakdown by offering, enforcement type, application, and end user segments
- Inclusion of additional Middle Eastern & African countries, with breakdown by offering, enforcement type, application, and end user segments
- Inclusion of additional Latin American countries, with breakdown by offering, enforcement type, application, and end user segments
Company information
- Detailed analysis and profiling of additional market players (up to five)
Get the Full Road Safety Market Report
Full forecast, segment splits, and company analysis for all Road Safety Market.
- US Road Safety Market
- Canada Road Safety Market
- UK Road Safety Market
- Germany Road Safety Market
- France Road Safety Market
- Italy Road Safety Market
- Spain Road Safety Market
- China Road Safety Market
- Japan Road Safety Market
- India Road Safety Market
- South Korea Road Safety Market
- UAE Road Safety Market
- South Africa Road Safety Market
- Qatar Road Safety Market
- Brazil Road Safety Market
- Mexico Road Safety Market
- Argentina Road Safety Market
- Rest Of Latin America Road Safety Market
- Ksa Road Safety Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report