Canada SCADA Market (2025-2030)
The Canada SCADA Market was valued at $741.4 Million in 2025 and projected to reach to $1137.2 Million by 2030, representing a compound annual growth rate of 8.9%. Canada's SCADA market is positioned for sustained growth as industries prioritize operational resilience and digital modernization.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Canada SCADA Market Trends and Insights
- This 8.9% compound annual growth rate reflects Canada's increasing investment in industrial automation, critical infrastructure modernization, and digital transformation across utilities, manufacturing, and energy sectors.
- Canada's strategic focus on grid reliability and smart infrastructure positions the nation as a key player in North American SCADA adoption. The Canadian SCADA market benefits from robust regulatory frameworks, aging infrastructure requiring upgrades, and heightened cybersecurity awareness among operators.
- Canada's energy sector, particularly hydroelectric and oil & gas operations, drives significant demand for real-time monitoring and control systems.
- Between 2025 and 2030, Canada is expected to see accelerated deployment in water management, power distribution, and industrial process control, supported by government initiatives and private sector investment in Industry 4.0 technologies. Canada's geographic advantages and skilled workforce further strengthen its position in the SCADA ecosystem.
- The market's growth trajectory reflects both domestic demand and Canada's role as a technology hub for North American industrial solutions..
Key Market Statistics
- CAGR (2025-2030) 8.9% CAGR
- Market Size, 2025 ~USD 741.4 Million
- Forecast, 2030 ~USD 1137.2 Million
- Country Canada
Canada SCADA Market Overview
Market Valuation Growth :
Canada's SCADA market is valued at $741.4 million in 2025, with projections reaching $1,137.2 million by 2030, representing an 8.9% CAGR driven by infrastructure modernization and industrial automation investments.
Critical Infrastructure Modernization :
Canadian utilities and energy sectors are prioritizing grid reliability and smart infrastructure upgrades, with SCADA systems playing a central role in managing electrical distribution, water treatment, and pipeline operations across the nation.
Digital Transformation Adoption :
Manufacturing and industrial facilities across Canada are accelerating digital transformation initiatives, integrating advanced SCADA solutions to enhance operational efficiency, predictive maintenance, and real-time monitoring capabilities.
Regulatory and Compliance Drivers :
Stringent Canadian regulations on critical infrastructure protection, cybersecurity standards, and environmental compliance are compelling organizations to upgrade legacy SCADA systems with modern, secure, and compliant solutions.
Canada SCADA Market Dynamics
- The 8.9% CAGR reflects strong demand from utilities, energy producers, and manufacturing sectors investing in grid modernization, renewable energy integration, and industrial IoT capabilities.
- Government initiatives supporting critical infrastructure security and the transition to smart grids further accelerate market expansion. Looking ahead to 2030, Canada's SCADA market will be shaped by increasing cybersecurity requirements, cloud-based SCADA solutions, and integration with AI-driven analytics.
- The shift toward distributed energy resources and smart city initiatives in major urban centers will create additional growth opportunities.
- Organizations across sectors will continue upgrading aging infrastructure while adopting next-generation SCADA platforms to meet evolving operational and regulatory demands..
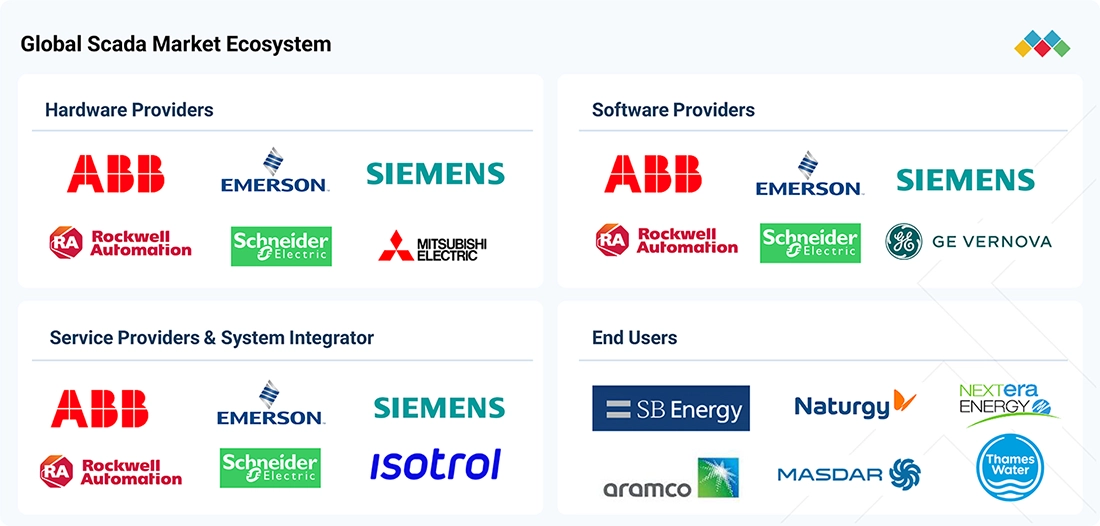
Market Ecosystem
SCADA MARKET SIZE, SHARE & TRENDS: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Rockwell Automation provides FactoryTalk SCADA and HMI solutions for manufacturing, enabling real-time monitoring, process visualization, alarm management, and integration of plant automation systems | Improves production visibility | Enables faster decision-making | Supports scalable plant monitoring | Reduces troubleshooting time |
 |
ABB provides Symphony Plus SCADA for monitoring and controlling distributed infrastructure across water, hydropower, and renewable energy applications, integrating data from remote field devices and control systems. | Enables centralized asset monitoring | Improves operational reliability | Supports secure remote operations | Enhances visibility across distributed assets |
 |
Schneider Electric offers EcoStruxure Geo SCADA Expert for remote monitoring and control across energy, water, chemicals, and renewable energy applications, with real-time data and alarm management. | Enables reliable remote control | Improves alarm management | Supports multi-protocol integration | Enhances operational visibility |
 |
Siemens provides SIMATIC WinCC SCADA systems for monitoring and controlling automated processes across manufacturing, infrastructure, and process industries, with plant-wide visualization and data integration. | Improves process visibility | Supports IT/OT integration | Enhances operational efficiency | Enables scalable monitoring |
 |
GE Vernova provides iFIX and CIMPLICITY SCADA solutions for electric utilities, enabling real-time monitoring and supervisory control across substations, distribution networks, and control centers. | Improves grid visibility | Enables faster response to disturbances | Enhances operational reliability | Supports scalable utility operations |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Automotive Electronics And Electrical Equipment
- Battery Electric Vehicle (BEV)
- Light Commercial Vehicles (LCVs)
- Fuel Cell Electric Vehicle (FCEV)
- Sensors
- Hybrid Electric Vehicle (HEV)
- BOSCH LIMITED
- Continental ag
- DENSO Corporation
- Panasonic Holdings Corporation
- Texas Instruments Incorporated
Industrial Automation
- Sensors
- Image Sensors
- Manufacturing Execution System (MES)
- Actuators
- Flow Sensors
- ABB India Limited
- Siemens ag
- Emerson Electric Co.
- HONEYWELL INTERNATIONAL INC.
- SCHNEIDER ELECTRIC SE
Industrial Iot
- Sensors
- Pressure Sensors
- Flow Sensors
- Gas Sensors
- Image Sensors
- Siemens ag
- ABB India Limited
- HONEYWELL INTERNATIONAL INC.
- Emerson Electric Co.
- SCHNEIDER ELECTRIC SE
Key Takeaways
- Canada's SCADA market will grow from $741.4M (2025) to $1,137.2M (2030) at an 8.9% CAGR.
- Canada's energy and utilities sectors are primary drivers of SCADA adoption and infrastructure modernization.
- Cybersecurity regulations and aging infrastructure upgrades accelerate SCADA deployment across Canada.
- Canada's skilled workforce and regulatory environment position it as a North American SCADA innovation hub.
SCADA Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | CLOUD-BASED (Software) |
| Forecast Period | 2025–2030 |
| Growth Rate | CAGR of 9.2% from 2025 to 2030 |
| Largest Segment | UTILITIES (End User) |
| Market Size Base Year (Billions) | ~USD 12.91 (2025) |
| Revenue Forecast (Billions) | ~USD 20.05 (2030) |
| Segments Covered | Offering, Component, Hardware Type, Software, Service, End User, Process Industries, Utilities, Discrete Manufacturing |
Canada SCADA Market Report Segmentation
9 segment dimensions are covered across the global market.
By Offering
- Hardware
- Services
- Software
By Component
- Communication System
- Human Machine Interface (Hmi)
- Programmable Logic Controller (Plc)
- Remote Terminal Unit (Rtu)
By Hardware Type
- Remote Terminal Unit (Rtu)
By Software
- Cloud-Based
- On-Premises
By Service
- Managed Services
- Professional Services
By End User
- Discrete Manufacturing
- Process Industries
- Utilities
By Process Industries
- Chemicals
- Food & Beverages
- Oil & Gas
- Other Process Industries
- Pharmaceuticals
By Utilities
- Power
- Telecommunications
- Transportation
- Water & Wastewater
By Discrete Manufacturing
- Automotive
- Other Discrete Manufacturing
- Semiconductor & Electronics
CANADA: SCADA MARKET, BY END USER, 2025–2030
| Segment | 2025 | 2026 | 2027 | 2028 | 2029 | 2030 | CAGR (%) |
|---|---|---|---|---|---|---|---|
| DISCRETE MANUFACTURING | 53.8 | 57.8 | 62.3 | 67.4 | 73.4 | 80.3 | 8.3 |
| PROCESS INDUSTRIES | 356 | 380.3 | 407.9 | 439.6 | 476.1 | 518.2 | 7.8 |
| UTILITIES | 331.5 | 362.2 | 397.2 | 437.6 | 484.3 | 538.7 | 10.2 |
| TOTAL | 741.4 | 800.2 | 867.4 | 944.6 | 1033.8 | 1137.2 | 8.9 |
Target Audience
- SCADA Solution Providers : Vendors and software developers need Canada-specific market data to identify growth segments, tailor product offerings to local regulatory requirements, and develop targeted sales strategies for utilities and industrial clients.
- System Integrators & Consultants : Integration firms require detailed market insights to understand client demand patterns, competitive positioning, and emerging technology trends in Canada to deliver relevant solutions and win new contracts.
- Industrial & Utility Operators : Facility managers and operations teams need market intelligence to evaluate SCADA modernization investments, benchmark against industry standards, and justify capital expenditures to stakeholders.
- Investment & Private Equity Firms : Investors evaluating opportunities in Canada's industrial technology sector require validated market sizing, growth projections, and sector dynamics to assess portfolio companies and identify acquisition targets.
- Government & Policy Makers : Canadian regulatory bodies and infrastructure planners need market data to inform critical infrastructure policies, cybersecurity standards, and investment priorities for grid modernization and industrial resilience.
Key Companies in the Canada SCADA Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| TECH MAHINDRA LIMITED | India | Public Company | Application development, modernization, and digital engineering,Cloud and infrastructure services,AI, analytics, and AIOps platforms, |
| LENOVO | China | Public Company | Small form factor PCs and embedded signage controllers,Thin clients and dedicated media players,Tablets and smart devices for kiosks/PoS, |
| SCHNEIDER ELECTRIC | Canada | Public Company | Low- and Medium-Voltage Electrical Distribution (switchgear, control gear, wiring devices),Building Management, Power Metering, and Smart Controls,Industrial Automation, Drives, and Microgrids, |
| SIEMENS | Germany | Public Company | Digital Industries (automation, PLM, industrial software),Smart Infrastructure (electrification, buildings, grid),Mobility (rail, rolling stock, automation, services), |
| ABB | India | Public Company | Electrification,Motion,Automation, |
| ROCKWELL AUTOMATION | United States | Public Company | Intelligent Devices,Software & Control,Lifecycle Services, |
| EMERSON ELECTRIC CO. | United States | Public Company | Final Control,Measurement & Analytical,Control Systems & Software, |
| GE VERNOVA | United States | Public Company | Power (gas, nuclear, hydro, steam),Wind (onshore and offshore),Electrification (grid, power conversion, solar and storage, software), |
| HONEYWELL INTERNATIONAL INC. | United States | Public Company | Industrial Automation,Building Automation,Energy and Sustainability Solutions (UOP and related), |
| MITSUBISHI ELECTRIC CORPORATION | Japan | Public Company | Factory Automation (FA) systems and FA digital solutions,Building systems, air conditioning, refrigeration, and life-related equipment,Energy systems, public utility, and power transmission and distribution, |
| OMRON CORPORATION | Japan | Public Company | Industrial Automation (sensors, safety, motion, robotics, panel, vision, software),Device & Module Solutions (relays, switches, connectors, components),Healthcare (cardiovascular, respiratory, pain management, remote monitoring), |
| YOKOGAWA ELECTRIC CORPORATION | Japan | Public Company | Control Business (DCS, PLCs, software, lifecycle services),Field Instruments (flow, pressure, analyzers, recorders),Measuring Instruments (waveform, optical, power, signal), |
TECH MAHINDRA LIMITED
Tech Mahindra Limited is a large Indian public company founded in 1986 with 119,337 employees, operating as a major IT services provider.
LENOVO
Lenovo is a Chinese public company founded in 1984, operating as a global leader in computing and technology solutions.
SCHNEIDER ELECTRIC
Schneider Electric is a Canadian public company with roots dating back to 1836, employing 158,122 people in energy management and automation.
SIEMENS
Siemens is a German multinational public company founded in 1847 with 310,312 employees, operating across industrial automation, digitalization, and infrastructure sectors.
ABB
ABB is an Indian public company with origins dating to 1883, employing 111,900 people in power and automation technology.
ROCKWELL AUTOMATION
Rockwell Automation is a United States-based public company founded in 1903 with 26,000 employees, specializing in industrial automation and digital transformation.
EMERSON ELECTRIC CO.
Emerson Electric Co. is a United States public company established in 1890 with 71,000 employees, providing process management and automation solutions.
GE VERNOVA
GE Vernova is a United States public company founded in 2023 with 78,000 employees, focused on energy and industrial technology.
HONEYWELL INTERNATIONAL INC.
Honeywell International Inc. is a United States public company founded in 1885 with 101,000 employees, operating in aerospace, building technologies, and industrial solutions.
MITSUBISHI ELECTRIC CORPORATION
Mitsubishi Electric Corporation is a Japanese public company established in 1921 with 150,386 employees, operating across industrial automation, power systems, and electronics.
OMRON CORPORATION
Omron Corporation is a Japanese public company founded in 1933 with 26,050 employees, specializing in automation and sensing technology.
YOKOGAWA ELECTRIC CORPORATION
Yokogawa Electric Corporation is a Japanese public company established in 1915 with 18,313 employees, focused on industrial automation and control systems.
Reasons to Buy this Report
- Market Size & Growth Validation : Obtain precise Canadian market valuation ($741.4M in 2025) and verified 5-year forecast data to support investment decisions, business planning, and competitive positioning in Canada's expanding SCADA sector.
- Sector-Specific Opportunity Identification : Understand which Canadian industries—utilities, manufacturing, energy, and water management—are driving SCADA adoption and where the highest growth opportunities exist for solution providers and integrators.
- Regulatory & Compliance Insights : Access detailed analysis of Canadian cybersecurity standards, critical infrastructure protection regulations, and compliance requirements shaping SCADA system procurement and implementation strategies.
- Competitive Landscape Intelligence : Benchmark your offerings against market trends, identify emerging competitors, and understand customer preferences specific to Canada's SCADA market to refine go-to-market strategies.
- Strategic Planning & Risk Mitigation : Leverage comprehensive market data to forecast demand, allocate resources effectively, and make informed decisions about market entry, expansion, or partnership opportunities in Canada.
Frequently asked questions
What is the current size of Canada's SCADA market?
Canada's SCADA market is valued at $741.4 million in 2025 and is expected to reach $1,137.2 million by 2030.
What is the growth rate of Canada's SCADA market?
Canada's SCADA market is growing at a compound annual growth rate (CAGR) of 8.9% from 2025 to 2030.
Which industries drive SCADA adoption in Canada?
Canada's energy sector, utilities, water management, and manufacturing industries are the primary drivers of SCADA market growth.
What factors support SCADA growth in Canada?
Aging infrastructure requiring modernization, cybersecurity regulations, digital transformation initiatives, and government support for smart infrastructure drive Canada's SCADA market expansion.
How does Canada's SCADA market compare to North America?
Canada represents a significant portion of the North American SCADA market, with strong growth driven by its energy sector and regulatory environment.
RESEARCH METHODOLOGY
The research process for this study involved the systematic gathering, recording, and analysis of data on customers and companies operating in the SCADA market. This process involved the extensive use of secondary sources, directories, and databases (Factiva and OANDA) to identify and collect valuable information for the comprehensive, technical, market-oriented, and commercial study of the SCADA market. In-depth interviews were conducted with primary respondents, including experts from core and related industries, as well as preferred manufacturers, to obtain and verify critical qualitative and quantitative information and assess growth prospects. Key players in the SCADA market were identified through secondary research, and their market rankings were determined through a combination of primary and secondary research. This research involved studying the annual reports of top players and conducting interviews with key industry experts, including CEOs, directors, and marketing executives.
Secondary Research
Various sources were utilized in the secondary research process to identify and collect information relevant to this study. These include company annual reports, press releases, investor presentations, white papers, technology journals, certified publications, articles by recognized authors, directories, and databases.
Secondary research was primarily used to gather key information on the industry’s value chain, the total pool of market players, market classification by industry trends at the most detailed level, regional markets, and key developments from both market- and technology-oriented perspectives.
Primary Research
Primary research was also conducted to identify the segmentation types, key players, competitive landscape, and key market dynamics, including drivers, restraints, opportunities, challenges, and industry trends, as well as the key strategies adopted by players operating in the SCADA market. Extensive qualitative and quantitative analyses were conducted across the complete market engineering process to present key information and insights throughout the report.
Extensive primary research has been conducted following the acquisition of knowledge about the SCADA market scenarios through secondary research. Several primary interviews were conducted with experts from the demand side (industry and region) and the supply side (product type, price tier, distribution channel, technology) across four major geographic regions: North America, Europe, Asia Pacific, and RoW. Approximately 60% and 40% of the primary interviews were conducted from the supply and demand sides, respectively.
These primary data have been collected through questionnaires, emails, and telephonic interviews.
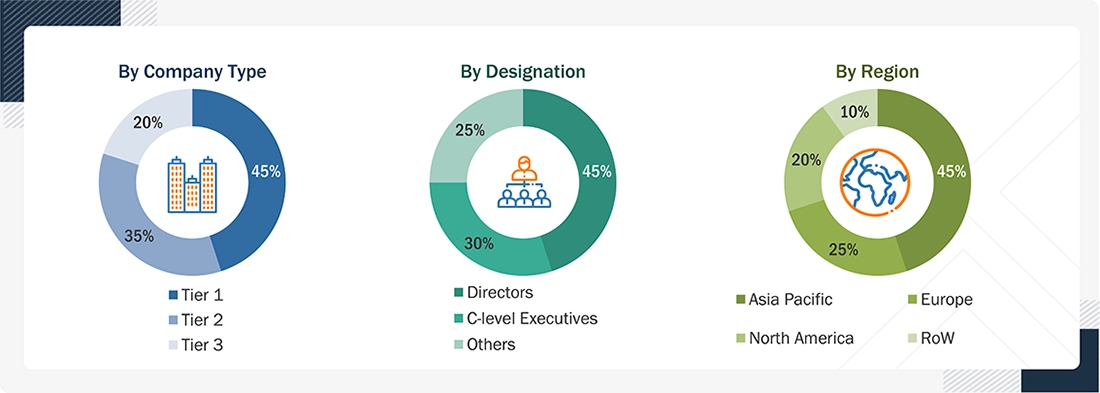
Notes: The three tiers of companies have been defined based on their total/segmental revenue as of 2025: Tier 1 = > USD 1 billion, Tier 2 = USD 1 billion–USD 100 million, and Tier 3 = < USD 100 million.
Other designations include sales, marketing, and product managers.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
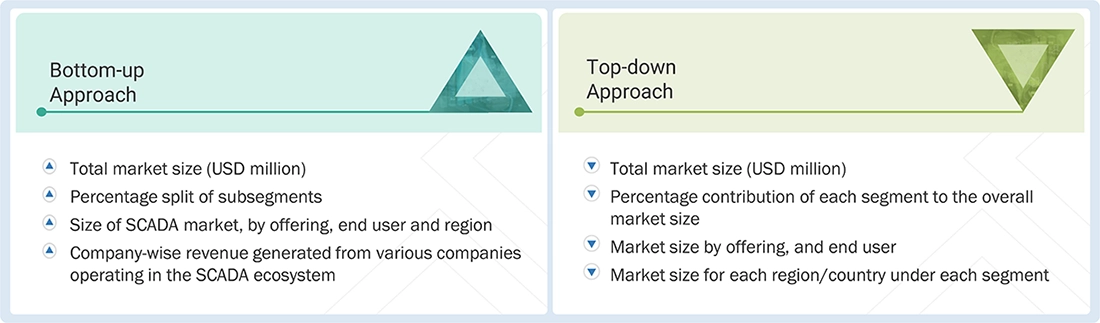
In the complete market engineering process, top-down and bottom-up approaches, along with several data triangulation methods, were used to estimate and validate the size of the SCADA market and various other dependent submarkets. Key players in the market were identified through secondary research, and their market share in each region was determined through a combination of primary and secondary research. This research methodology involved analyzing the annual and financial reports of the top players and conducting interviews with experts (including CEOs, VPs, directors, and marketing executives) to gather key insights (both quantitative and qualitative).
All percentage shares, splits, and breakdowns were determined using secondary sources and verified through primary sources. All possible parameters affecting the markets covered in this study were accounted for, examined in detail, verified through primary research, and analyzed to obtain final quantitative and qualitative data. This data was consolidated and supplemented with detailed inputs and analysis from MarketsandMarkets and presented in this report.
SCADA Market : Top-Down and Bottom-Up Approach
Data Triangulation
After determining the overall market size through the estimation process, as explained above, the total market was divided into several segments and subsegments. To complete the overall market engineering process and obtain precise statistics for all segments and subsegments, the data triangulation procedure was employed, as applicable. The data was triangulated by studying various factors and trends from the demand and supply sides. Additionally, the market has been validated using both top-down and bottom-up approaches.
Market Definition
The SCADA (Supervisory Control and Data Acquisition) market comprises integrated hardware and software systems designed to monitor, control, and optimize industrial and infrastructure operations through real-time data acquisition and centralized supervision. These solutions are widely deployed across process industries such as oil & gas, chemicals, pharmaceuticals, food & beverage; discrete manufacturing sectors including automotive, semiconductor, and electronics; and utility segments encompassing power, water & wastewater treatment, telecommunications, and transportation. SCADA systems utilize components such as programmable logic controllers (PLCs), remote terminal units (RTUs), and human-machine interfaces (HMIs), and are increasingly supported by technologies like industrial IoT, cloud platforms, and advanced analytics.
Key Stakeholders
- Application providers
- Automation consultants
- Integrators of automation systems
- Distributors and providers of SCADA
- Companies developing and integrating industrial software
- Companies providing industrial control systems (ICS) cybersecurity
- Vendors of SCADA software packages
- Suppliers of SCADA components
- Providers of professional services/solutions
- Research organizations and consulting companies
- Technology investors
- Technology standards organizations, forums, alliances, and associations
Report Objectives
- To describe and forecast the SCADA market, in terms of value, based on offering and end user
- To define and forecast the market size, in terms of value, with regard to four main regions: North America, Europe, Asia Pacific, and RoW (Rest of the World)
- To describe and forecast the market size for SCADA, by offering and region, in terms of volume
- To provide detailed information regarding drivers, restraints, opportunities, and challenges influencing the growth of the market
- To understand the impact of artificial intelligence (AI) on the market
- To strategically analyze micromarkets with respect to individual growth trends, prospects, and contributions to the total market
- To analyze opportunities for various stakeholders by identifying high-growth segments of the market
- To strategically profile key players and comprehensively analyze their market position in terms of ranking and core competencies, along with detailing the competitive landscape of the market
- To analyze competitive developments, such as acquisitions, product launches, developments, and partnerships in the market
- To provide a detailed overview of the ecosystem analysis, case study analysis, patent analysis, trade analysis, technology analysis, average selling price (ASP) analysis, AI/Gen AI impact analysis, Porter’s five forces analysis, macroeconomic outlook, and regulatory landscape pertaining to the SCADA market.
Available customizations:
With the given market data, MarketsandMarkets offers customizations according to the company’s specific needs. The following customization options are available for the report:
Get the Full SCADA Market Report
Full forecast, segment splits, and company analysis for all SCADA Market.
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report