Europe Sepsis Diagnostics Market (2024-2029)

The Europe Sepsis Diagnostics Market was valued at $87.5 Million in 2024 and projected to reach to $116.8 Million by 2029, representing a compound annual growth rate of 6.0%. Europe's sepsis diagnostics market is positioned for sustained growth through 2029, driven by increasing clinical demand for rapid detection technologies and rising hospital-acquired infection rates across the region.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Europe Sepsis Diagnostics Market Trends and Insights
- This growth in Europe reflects increasing clinical demand for rapid sepsis detection, driven by rising hospital-acquired infection rates and heightened awareness of sepsis mortality across European healthcare systems.
- Europe's mature healthcare infrastructure and regulatory frameworks support adoption of advanced diagnostic technologies. The European market benefits from strong investment in point-of-care testing and molecular diagnostics platforms.
- Europe's aging population and prevalence of chronic conditions contribute to higher sepsis incidence, creating sustained demand for diagnostic solutions.
- Reimbursement policies across European nations and integration of sepsis protocols into clinical guidelines further accelerate market expansion through 2029..
Key Market Statistics
- CAGR (2024-2029) 6.0% CAGR
- Market Size, 2024 ~USD 87.5 Million
- Forecast, 2029 ~USD 116.8 Million
- Geography Europe
Europe Sepsis Diagnostics Market Overview
Market Valuation & Growth :
Europe's sepsis diagnostics market is valued at $87.5 million in 2024 and is projected to reach $116.8 million by 2029, representing a steady 6% CAGR, reflecting strong regional demand for rapid diagnostic solutions.
Hospital-Acquired Infection Drivers :
Rising hospital-acquired infection (HAI) rates across European healthcare systems are accelerating the adoption of sepsis diagnostics, as clinicians seek faster detection methods to improve patient outcomes and reduce mortality.
Regulatory & Clinical Awareness :
Heightened awareness of sepsis mortality and stringent European regulatory frameworks are driving healthcare providers to invest in advanced diagnostic technologies that enable early intervention and clinical decision-making.
Regional Market Leadership :
Germany leads Europe's sepsis diagnostics market with $94.8 million in market size, followed by the UK ($54.4M) and France ($52.7M), indicating strong adoption in Western European healthcare systems.
Europe Sepsis Diagnostics Market Dynamics
- Healthcare systems are prioritizing sepsis management protocols, supported by regulatory initiatives and clinical guidelines that emphasize early diagnosis.
- The market benefits from advanced healthcare infrastructure, high diagnostic adoption rates, and strong reimbursement frameworks in major European economies. The 6% CAGR reflects a mature yet expanding market where innovation in point-of-care testing and molecular diagnostics is gaining traction.
- European hospitals are increasingly integrating sepsis screening programs into standard protocols, supported by growing awareness of sepsis-related mortality.
- Investment in healthcare technology and digital health solutions further accelerates market expansion, positioning Europe as a key growth region for sepsis diagnostic providers..
Market Ecosystem
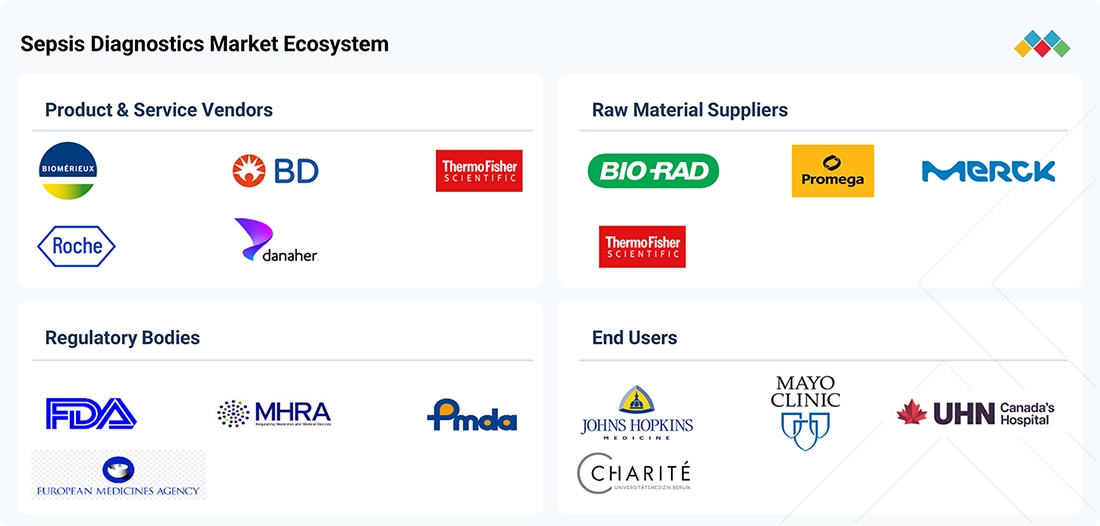
SEPSIS DIAGNOSTICS MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Provides integrated sepsis diagnostics solutions across automated blood culture, rapid syndromic molecular testing, microbial identification, and antimicrobial susceptibility testing through platforms used in hospital microbiology laboratories | Enables faster bloodstream infection detection, rapid pathogen identification, improved antimicrobial selection, and stronger antimicrobial stewardship support |
 |
Supports sepsis and bloodstream infection diagnostics through blood culture systems, specimen collection products, microbiology automation, and antimicrobial susceptibility testing solutions used across hospitals and reference laboratories | Improves laboratory workflow efficiency, supports high-volume microbiology testing, reduces turnaround time, and helps clinicians optimize antibiotic therapy |
 |
Through its diagnostics businesses, provides molecular diagnostics, clinical chemistry, immunoassay, and laboratory automation solutions that support infectious disease testing and sepsis-related clinical decision-making | Supports rapid pathogen detection, biomarker-based assessment, automated laboratory workflows, and improved diagnosis of suspected sepsis cases |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
In Vitro Diagnostics
- Polymerase Chain Reaction (PCR)
- Enzyme-Linked Immunosorbent Assay (ELISA)
- Dna Microarrays
- Assay Kits
- Microarrays
- ROCHE HOLDINGS AG
- Thermo Fisher Scientific Inc.
- Danaher Corporation
- Abbott Laboratories
- Biomerieux s.a.
Key Takeaways
- Europe's sepsis diagnostics market reaches $87.5M in 2024 and grows to $116.8M by 2029 at 6.0% CAGR
- Europe's aging demographics and hospital-acquired infection rates drive sustained demand for rapid diagnostic solutions
- Mature healthcare infrastructure and favorable reimbursement policies in Europe support technology adoption
- Point-of-care and molecular diagnostic platforms are key growth drivers across European healthcare systems
Sepsis Diagnostics Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2024 |
| Fastest Growing Segment | POINT-OF-CARE TESTS (Test Type) |
| Forecast Period | 2024–2029 |
| Growth Rate | CAGR of 7% from 2024 to 2029 |
| Largest Segment | BLOOD CULTURE (Technology) |
| Market Size Base Year (Billions) | ~USD 0.63 (2024) |
| Revenue Forecast (Billions) | ~USD 0.89 (2029) |
| Segments Covered | Technology, Product, Method, Pathogen Type, Type, Test Type, End User |
Europe Sepsis Diagnostics Market Report Segmentation
7 segment dimensions are covered across the global market.
By Technology
- Biomarkers
- Blood Culture
- Flow Cytometry
- Immunoassays
- Microfluidics
- Molecular Diagnostics
By Product
- Assays & Reagent Kits
- Blood Culture Media
- Instruments
- Software
By Method
- Automated Diagnostics
- Conventional Diagnostics
By Pathogen Type
- Bacterial Sepsis
- Fungal Sepsis
- Other Pathogen Types
By Type
- Dna Sequencing
- Gram-Negative Bacteria
- Gram-Negative Bacterial Sepsis
- Gram-Positive Bacteria
- Gram-Positive Bacterial Sepsis
- Microarrays
- Peptide Nucleic Acid-Fluorescent In Situ Hybridization
- Polymerase Chain Reaction
By Test Type
- Laboratory Tests
- Point-Of-Care Tests
By End User
- Hospitals And Specialty Clinics
- Pathology And Reference Laboratories
- Research Laboratories, Academic Institutes, And Cros
EUROPE: SEPSIS DIAGNOSTICS MARKET, BY END USER, 2022–2029
| Segment | 2022 | 2023 | 2024 | 2025 | 2026 | 2027 | 2028 | 2029 | CAGR (%) |
|---|---|---|---|---|---|---|---|---|---|
| HOSPITALS AND SPECIALTY CLINICS | 107.6 | 113.8 | 120.9 | 128.7 | 137.6 | 147.6 | 158.8 | 171.1 | 7.2 |
| PATHOLOGY AND REFERENCE LABORATORIES | 59.6 | 62.2 | 65.2 | 68.5 | 72.3 | 76.5 | 81.2 | 86.3 | 5.8 |
| RESEARCH LABORATORIES, ACADEMIC INSTITUTES, AND CROS | 7.2 | 7.3 | 7.4 | 7.5 | 7.6 | 7.7 | 7.8 | 8 | 1.6 |
| TOTAL | 174.4 | 183.3 | 193.4 | 204.6 | 217.5 | 231.9 | 247.9 | 265.4 | 6.5 |
Target Audience
- Diagnostic Device Manufacturers : Manufacturers need Europe-specific market data to develop region-tailored sepsis diagnostic products, understand regulatory requirements, and identify optimal market entry points across major European healthcare systems.
- Healthcare Providers & Hospital Networks : Hospital administrators and clinical procurement teams require market insights to evaluate sepsis diagnostic solutions, benchmark adoption rates, and make informed purchasing decisions aligned with clinical protocols.
- Investment & Private Equity Firms : Investors seeking growth opportunities in European healthcare diagnostics need detailed market analysis to identify acquisition targets, assess market potential, and evaluate return on investment in sepsis diagnostics.
- Regulatory & Policy Advisors : Healthcare policy makers and regulatory consultants use market data to understand sepsis diagnostic adoption trends, inform clinical guidelines, and develop reimbursement strategies across European markets.
- Market Research & Consulting Firms : Research organizations require comprehensive Europe-specific data to support client advisory services, competitive analysis, and strategic recommendations in the sepsis diagnostics sector.
Key Companies in the Europe Sepsis Diagnostics Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| CEPHEID INC. | United States | Private Company | GeneXpert instruments and Xpert test cartridges,SmartCycler system and associated reagents,Collaborative and specialized assays (e.g., TB, Ebola, USPS BDS), |
| NANOSPHERE, INC | United States | Private Company | Infectious disease molecular assays,Pharmacogenetic and human genetic assays,Protein and ultra-sensitive multiplex assays, |
| TOSOH CORPORATION | Japan | Public Company | Basic chemicals and chlor-alkali (caustic soda, VCM, EDC, sodium bicarbonate),Polymers and petrochemicals (PE, EVA, PVC pastes, synthetic rubber, functional polymers),Advanced materials (battery materials, quartzware, silica glass, thin films, zeolites, zirconia), |
| BIOMÉRIEUX | France | Public Company | Clinical microbiology (ID/AST, blood culture, culture media),Syndromic and molecular diagnostics (BIOFIRE, SPOTFIRE, ARGENE, NUCLISENS, EMAG),Immunoassay and sepsis markers (VIDAS, Hybiome CLIA), |
| BECTON, DICKINSON AND COMPANY | United States | Public Company | Medical Essentials (syringes, needles, vascular access, sharps, basic disposables),Connected Care (infusion, medication management, pharmacy automation, informatics),BioPharma Systems (prefillable drug delivery systems), |
| DANAHER CORPORATION | United States | Public Company | Biotechnology (bioprocessing and related tools),Life Sciences (instruments, genomics, and reagents),Diagnostics (clinical instruments and consumables), |
| T2 BIOSYSTEMS, INC. | United States | Public Company | T2Dx instrument,T2Candida panel,T2Bacteria panel, |
| DIASORIN S.P.A. | Italy | Public Company | Immunodiagnostics – Infectious & Gastrointestinal Diseases, Hepatitis & Retroviruses,Immunodiagnostics – Endocrinology & Metabolic Disorders,Tumor Markers and Oncology Assays, |
| THERMO FISHER SCIENTIFIC INC. | United States | Public Company | Life Sciences Solutions,Analytical Instruments,Specialty Diagnostics, |
| BRUKER CORPORATION | United States | Public Company | BSI BioSpin (NMR/EPR and preclinical imaging),BSI CALID (mass spectrometry and molecular diagnostics),BSI Nano (X-ray, AFM, electron microscopy tools), |
| QUIDELORTHO CORPORATION | United States | Public Company | Labs (clinical chemistry and immunoassay),Transfusion Medicine,Point of Care, |
| SYSMEX CORPORATION | Japan | Public Company | Hematology analyzers and reagents (XN-Series, XN-V, ProCyte Dx),Coagulation systems and reagents,Blood gas, electrolyte, and urinalysis analyzers, |
| ABBOTT LABORATORIES | United States | Public Company | Medical Devices,Diagnostic Products,Nutritional Products, |
| SIEMENS HEALTHINEERS | Germany | Public Company | Imaging,Diagnostics,Varian (Oncology), |
| QIAGEN N.V. | Netherlands | Public Company | Sample technology consumables (nucleic acid stabilization/purification),Immune response and infectious disease assays (incl. TB IGRA),Oncology and sexual/reproductive health assays, |
| SEEGENE, INC. | South Korea | Public Company | Respiratory disease detection,Gastrointestinal disease detection,STI and HPV detection, |
| PHC HOLDINGS CORPORATION | Japan | Public Company | Diabetes Management,Healthcare Solutions (EMR, receipt, pharmacy, wellness),Diagnostic and Life Sciences Equipment, |
CEPHEID INC.
Cepheid Inc. is a private molecular diagnostics company founded in 1996 in the United States with 1,700 employees. The company develops and manufactures diagnostic systems and tests.
NANOSPHERE, INC
Nanosphere, Inc. is a private diagnostic company founded in 1998 in the United States with 148 employees. The company focuses on molecular diagnostic technologies.
TOSOH CORPORATION
Tosoh Corporation is a Japanese public company founded in 1935 with 14,850 employees. The company operates across multiple business segments including diagnostics and healthcare products.
BIOMÉRIEUX
bioMérieux is a French public company founded in 1963 with 14,894 employees. The company specializes in in vitro diagnostics for infectious diseases and industrial microbiology.
BECTON, DICKINSON AND COMPANY
Becton, Dickinson and Company is a United States public company founded in 1897 with 72,000 employees. The company is a global medical technology manufacturer producing diagnostic systems, devices, and reagents.
DANAHER CORPORATION
Danaher Corporation is a United States public company founded in 1969 with 59,000 employees. The company operates a diversified portfolio of businesses including diagnostics and life sciences.
T2 BIOSYSTEMS, INC.
T2 Biosystems, Inc. is a United States public company founded in 2006 with 113 employees. The company develops rapid diagnostic technologies for infectious diseases.
DIASORIN S.P.A.
DiaSorin S.p.A. is an Italian public company founded in 1968 with 3,242 employees. The company manufactures and distributes in vitro diagnostic products.
THERMO FISHER SCIENTIFIC INC.
Thermo Fisher Scientific Inc. is a United States public company founded in 1956 with 125,000 employees. The company is a global leader in serving science with laboratory equipment, reagents, and diagnostic solutions.
BRUKER CORPORATION
Bruker Corporation is a United States public company founded in 1960 with 11,085 employees. The company manufactures scientific instruments and analytical systems for research and diagnostics.
QUIDELORTHO CORPORATION
Qiagen N.V. is a Netherlands public company founded in 1984 with 5,500 employees. The company develops and manufactures molecular diagnostics and sample preparation technologies.
SYSMEX CORPORATION
QuidelOrtho Corporation is a United States public company founded in 1979 with 6,500 employees. The company develops and manufactures rapid diagnostic tests and point-of-care solutions.
ABBOTT LABORATORIES
Sysmex Corporation is a Japanese public company founded in 1968 with 10,861 employees. The company manufactures and sells in vitro diagnostic systems and reagents.
SIEMENS HEALTHINEERS
Siemens Healthineers is a German public company founded in 1896 with 72,369 employees. The company develops and manufactures diagnostic imaging, laboratory diagnostics, and point-of-care testing systems.
QIAGEN N.V.
QIAGEN N.V. is a Netherlands public company founded in 1984 with 5,500 employees. The company develops and manufactures molecular diagnostics and sample preparation technologies.
SEEGENE, INC.
Seegene, Inc. is a South Korean public company founded in 2000 with 216 employees. The company develops and manufactures molecular diagnostic products and multiplex PCR technologies.
PHC HOLDINGS CORPORATION
PHC Holdings Corporation is a Japanese public company founded in 1948 with 8,647 employees. The company manufactures and sells medical devices and diagnostic equipment.
Countries within Europe - compare and drill down
| Country | 2025 size (native) |
|---|---|
| Germany | USD 94.8 Million |
| UK | USD 54.4 Million |
| France | USD 52.7 Million |
| Italy | USD 30.3 Million |
| Spain | USD 18.6 Million |
Country market size visualization
Reasons to Buy this Report
- Regional Market Segmentation : Gain detailed insights into Europe's sepsis diagnostics market with country-level breakdowns for Germany, UK, France, Italy, and Spain, enabling targeted market entry and expansion strategies.
- Growth Trajectory & Forecasting : Access comprehensive 5-year forecasts (2024-2029) with 6% CAGR projections to support strategic planning, investment decisions, and competitive positioning in the European market.
- Clinical & Regulatory Context : Understand the drivers behind Europe's sepsis diagnostics adoption, including HAI rates, regulatory frameworks, and clinical awareness initiatives that shape market dynamics and opportunities.
- Competitive Landscape Intelligence : Identify market leaders and emerging players across major European markets, with insights into regional preferences for diagnostic technologies and clinical adoption patterns.
- Investment & Partnership Opportunities : Discover high-growth segments and underserved markets within Europe to identify strategic partnerships, acquisitions, and expansion opportunities in the sepsis diagnostics sector.
Frequently asked questions
What is the current size of Europe's sepsis diagnostics market?
Europe's sepsis diagnostics market is valued at $87.5 million in 2024.
What is the projected market size for Europe by 2029?
Europe's sepsis diagnostics market is forecast to reach $116.8 million by 2029.
What is the growth rate for sepsis diagnostics in Europe?
Europe's sepsis diagnostics market is expected to grow at a compound annual growth rate of 6.0% from 2024 to 2029.
What factors are driving growth in Europe's sepsis diagnostics market?
Key drivers include rising hospital-acquired infection rates, aging populations, mature healthcare infrastructure, favorable reimbursement policies, and increased adoption of point-of-care and molecular diagnostic technologies across Europe.
Which diagnostic technologies are most prevalent in Europe's sepsis market?
Point-of-care testing and molecular diagnostics platforms are the primary technologies driving growth in Europe's sepsis diagnostics market.
RESEARCH METHODOLOGY
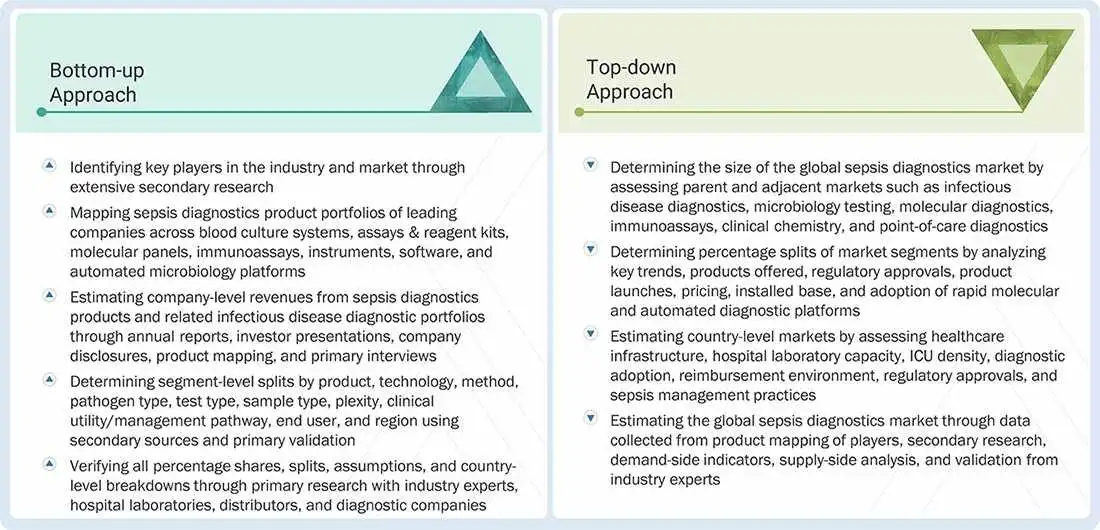
This study involved four major activities to estimate the current size of the sepsis diagnostics market. Exhaustive secondary research was conducted to gather information on the market, its peer markets, and its parent market. These findings, assumptions, and sizing were then validated with industry experts across the value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the total market size. Following this, data triangulation was used to estimate the market size of segments and subsegments.
Secondary Research
Secondary research was primarily used to identify and gather information for the extensive, technical, market-oriented, and commercial study of the global sepsis diagnostics market. The secondary sources used in this study include publications from government and public health organizations such as the World Health Organization (WHO), Centers for Disease Control and Prevention (CDC), National Institutes of Health (NIH), National Center for Biotechnology Information (NCBI), Food and Drug Administration (FDA), European Medicines Agency (EMA), European Centre for Disease Prevention and Control (ECDC), and other regional health authorities. Secondary sources also included corporate and regulatory filings such as annual reports, SEC filings, investor presentations, and financial statements; company websites; product brochures and catalogs; press releases; peer-reviewed journals; clinical guidelines; sepsis-related publications; and infectious disease databases, among others.
These sources provided key information on major players, product portfolios, global product revenues, market classification, sepsis diagnostics technologies, product launches, regulatory approvals, clinical adoption trends, antimicrobial stewardship initiatives, and regional and country-level market developments. Secondary data were collected and analyzed to estimate the size of the global sepsis diagnostics market, and the findings were validated through primary research.
Primary Research
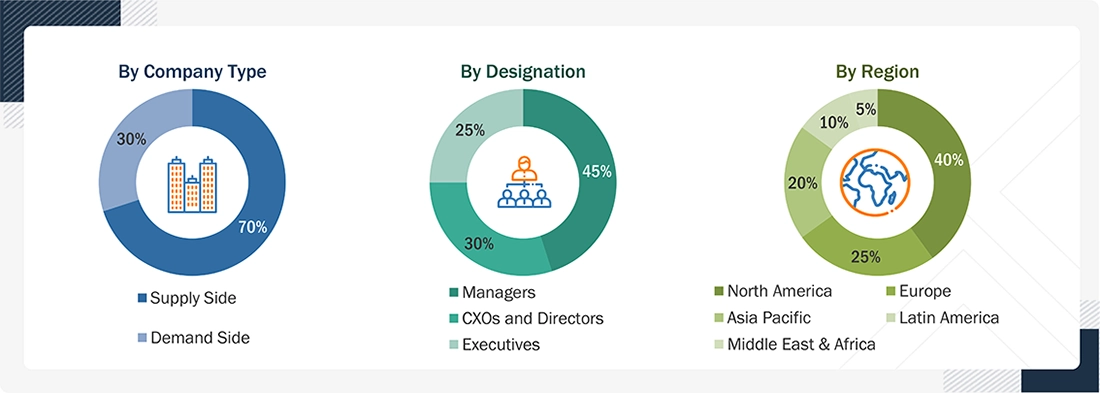
In-depth interviews were conducted with primary respondents, including key industry participants, subject-matter experts, C-level executives of key market players, product managers, laboratory directors, infectious disease specialists, microbiologists, pathologists, hospital procurement professionals, consultants, and other stakeholders to obtain and verify critical qualitative and quantitative information and to assess market prospects. Primary sources from both the supply and demand sides of the market were interviewed to gather qualitative and quantitative information. The following is a breakdown of the primary respondents:
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
The global size of the sepsis diagnostics market was estimated using multiple approaches. A detailed market estimation approach was used to estimate and validate the market value and other dependent submarkets. These methods were also used extensively to estimate the size of various subsegments in the market, including product, technology, method, pathogen type, test type, sample type, complexity, clinical utility/management pathway, end user, and region.
The market size estimate included revenues from blood culture media, assays and reagent kits, instruments, and software used in sepsis diagnostics. It also included technologies such as blood culture/microbiology testing, immunoassays, molecular diagnostics, flow cytometry, mass spectrometry, and clinical chemistry and blood gas analysis. Company revenues, product mapping, installed base, test volumes, average selling prices, adoption rates, disease burden, hospital testing patterns, and regional laboratory infrastructure were analyzed to estimate the market size.
Data Triangulation
After estimating the overall market size through the market size estimation process, the total market was divided into several segments. To complete the overall market engineering process and arrive at the exact statistics for all segments, the data triangulation procedure was employed; it involved analyzing various factors and trends from both the demand and supply sides.
On the supply side, company revenues, product portfolios, installed base, product launches, regulatory approvals, geographic presence, and diagnostic platform adoption were analyzed. On the demand side, sepsis incidence, bloodstream infection burden, hospital admissions, ICU testing volumes, laboratory test utilization, antimicrobial stewardship requirements, and adoption of rapid molecular and biomarker-based diagnostics were considered. The final estimates were validated through primary interviews and cross-checked against secondary research.
Market Definition
Sepsis diagnostics refers to in vitro diagnostic products, platforms, and testing solutions used for the early detection, diagnosis, pathogen identification, risk stratification, antimicrobial stewardship support, and prognosis/outcome prediction of sepsis and bloodstream infections. These diagnostics help clinicians identify infection, determine the causative pathogen, assess disease severity, support antimicrobial treatment decisions, and monitor patient condition in emergency departments, ICUs, hospitals, specialty clinics, and diagnostic laboratories. The market includes blood culture media, assays and reagent kits, instruments, and software used across technologies such as blood culture/microbiology testing, immunoassays, molecular diagnostics, flow cytometry, mass spectrometry, and clinical chemistry and blood gas analysis. It also includes laboratory and point-of-care tests used for bacterial, fungal, parasitic, and polymicrobial sepsis, as well as other sepsis-related diagnostic applications.
Key Stakeholders
- Manufacturers and distributors of sepsis diagnostics products
- In vitro diagnostic (IVD) companies
- Blood culture and microbiology testing companies
- Molecular diagnostics companies
- Immunoassay and biomarker testing companies
- Mass spectrometry and microbial identification platform providers
- Clinical chemistry and blood gas analyzer manufacturers
- Point-of-care diagnostics companies
- Hospital laboratories
- Pathology and reference laboratories
- Hospitals and specialty clinics
- Emergency departments and intensive care units
- Infectious disease specialists, microbiologists, and pathologists
- Research laboratories and academic institutes
- Clinical research organizations (CROs)
- Contract research and diagnostic service providers
- Regulatory authorities and government health agencies
- Public health organizations
- Group purchasing organizations and hospital procurement teams
- Diagnostics suppliers and raw material providers
- Market research and consulting firms
- Venture capitalists and investors
Report Objectives
- To define, describe, segment, and forecast the global sepsis diagnostics market, by product, technology, method, pathogen type, test type, sample type, plexity, clinical utility/management pathway, end user, and region
- To provide detailed information regarding the major factors influencing market growth (such as drivers, restraints, opportunities, and challenges)
- To analyze micromarkets with respect to individual growth trends, prospects, and contributions to the overall sepsis diagnostics market
- To analyze market opportunities for stakeholders and provide details of the competitive landscape for key players
- To forecast the size of the market segments with respect to six regions: North America(US and Canada), Europe (Germany, France, the UK, Switzerland, Italy, Spain, and the Rest of Europe), Asia Pacific (China, Japan, India, South Korea, Australia, and the Rest of Asia Pacific), Latin America (Brazil, Mexico, and the Rest of Latin America), the Middle East [GCC and the Rest of Middle East], and Africa
- To profile the key players and comprehensively analyze their product portfolios, market positions, and core competencies
- To analyze company developments such as product launches & approvals, partnerships, acquisitions, agreements, collaborations, expansions, and other developments
- To benchmark players within the market using the proprietary “Company Evaluation Matrix” framework, which analyzes market players on various parameters within the broad categories of business and product excellence strategy
Available customizations:
With the given market data, MarketsandMarkets offers customizations as per the company’s specific needs. The following customization options are available for the report:
Geographical Analysis
- Further breakdown of the Rest of Europe Sepsis Diagnostics market, by country
- Further breakdown of the Rest of Asia Pacific Sepsis Diagnostics market, by country
Company Information
- Detailed analysis and profiling of additional market players (up to five)
Segment Analysis
- Cross-segment analysis
Get the Full Sepsis Diagnostics Market Report
Full forecast, segment splits, and company analysis for all Sepsis Diagnostics Market.
- US Sepsis Diagnostics Market
- Canada Sepsis Diagnostics Market
- Germany Sepsis Diagnostics Market
- UK Sepsis Diagnostics Market
- France Sepsis Diagnostics Market
- Italy Sepsis Diagnostics Market
- Spain Sepsis Diagnostics Market
- Japan Sepsis Diagnostics Market
- China Sepsis Diagnostics Market
- India Sepsis Diagnostics Market
- Australia Sepsis Diagnostics Market
- South Korea Sepsis Diagnostics Market
- Brazil Sepsis Diagnostics Market
- Mexico Sepsis Diagnostics Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
