Italy Smart Learning Market (2024-2029)

The Italy Smart Learning Market was valued at $16052.6 Million in 2024 and projected to reach to $45164 Million by 2029, representing a compound annual growth rate of 23.0%. Italy's smart learning market is positioned for exceptional growth over the next five years, driven by substantial government investments in educational technology infrastructure and digital curriculum development.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Italy Smart Learning Market Trends and Insights
- Asia Pacific's 23.0% compound annual growth rate significantly outpaces global trends, driven by rapid digital adoption, increasing smartphone penetration, and government investments in educational technology across the region.
- The market encompasses AI-powered learning platforms, adaptive learning systems, virtual classrooms, and intelligent tutoring solutions tailored to Asia Pacific's diverse educational needs. Asia Pacific's dominance in the smart learning sector reflects strong demand from both developed and emerging economies within the region.
- Countries across Asia Pacific are prioritizing digital transformation in education, supported by rising middle-class populations and increased EdTech funding.
- The forecast period through 2029 indicates sustained momentum as Asia Pacific continues to lead global smart learning innovation and adoption, with particular strength in mobile-first learning solutions and cloud-based educational platforms..
Key Market Statistics
- CAGR (2024-2029) 23.0% CAGR
- Market Size, 2024 ~USD 16052.6 Million
- Forecast, 2029 ~USD 45164 Million
- Country Italy
Italy Smart Learning Market Overview
Market Size & Growth :
Italy's smart learning market is valued at USD 16,052.6 million in 2024, with a robust 23% CAGR projected to reach USD 45,164 million by 2029, significantly outpacing the global average of 18.3%.
Digital Transformation in Education :
Italian educational institutions are rapidly adopting smart learning technologies, driven by government initiatives to modernize classrooms and increase digital literacy across primary, secondary, and higher education sectors.
Rising EdTech Investment :
Increased funding from both public and private sectors in Italy is accelerating the deployment of learning management systems, interactive platforms, and AI-powered educational tools in schools and universities.
Mobile & Cloud Adoption :
Growing smartphone penetration and cloud-based learning solutions are enabling remote and hybrid education models across Italy, particularly following post-pandemic educational shifts toward flexible learning environments.
Italy Smart Learning Market Dynamics
- The country's commitment to EU digital education initiatives and modernization of its education system are creating significant opportunities for EdTech providers and solution developers.
- Increasing adoption of AI-powered personalized learning, virtual classrooms, and data analytics platforms is reshaping how Italian students engage with educational content.
- The market's 23% CAGR reflects strong demand from both public institutions and private educational providers seeking to enhance learning outcomes and operational efficiency.
- Strategic partnerships between technology vendors and Italian educational institutions are expected to accelerate market penetration and innovation across the region..
Market Ecosystem


OVERVIEW

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
The global smart learning market is estimated to reach USD 80.69 billion in 2025. It is projected to grow to USD 178.62 billion by 2030, registering a CAGR of 17.2% during the forecast period. The market is gaining traction as education and training providers adjust to more flexible and technology-enabled learning models. Learning delivery is no longer limited to physical classrooms and fixed schedules. Instead, institutions are supporting a mix of in-person, remote, and hybrid formats across schools, universities, and corporate training programs. This shift is driving the demand for platforms that can manage digital content, assessments, and learner progress across multiple environments. As learning models continue to diversify, smart learning platforms are becoming a central part of modern education and workforce development strategies.
KEY TAKEAWAYS
-
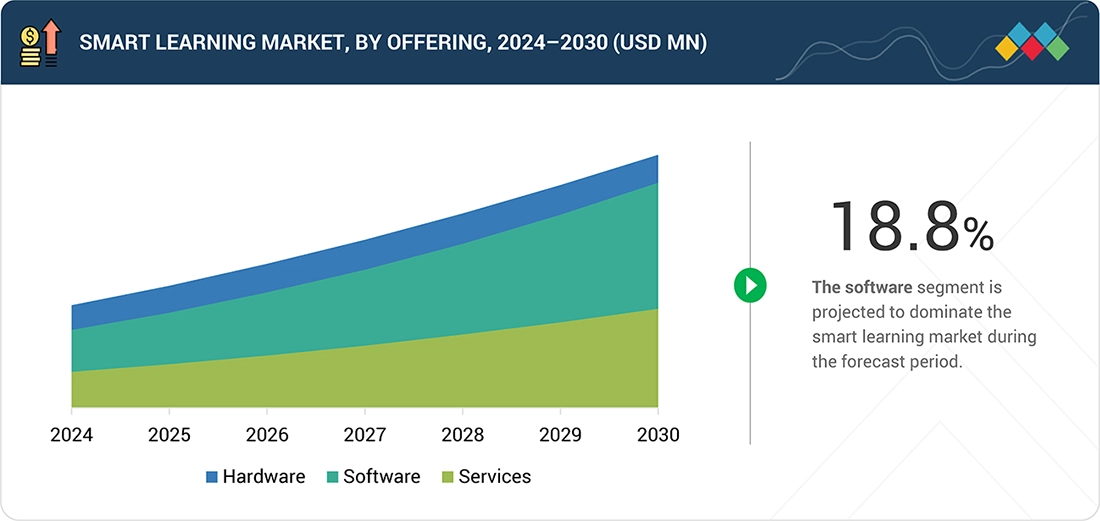
By OfferingThe software segment is projected to achieve the highest CAGR of 18.8% during the forecast period.
-
By Learning TypeThe synchronous learning segment is projected to grow at the highest rate during the forecast period.
-
By End UserThe enterprises segment is projected to dominate the smart learning market during the forecast period.
-
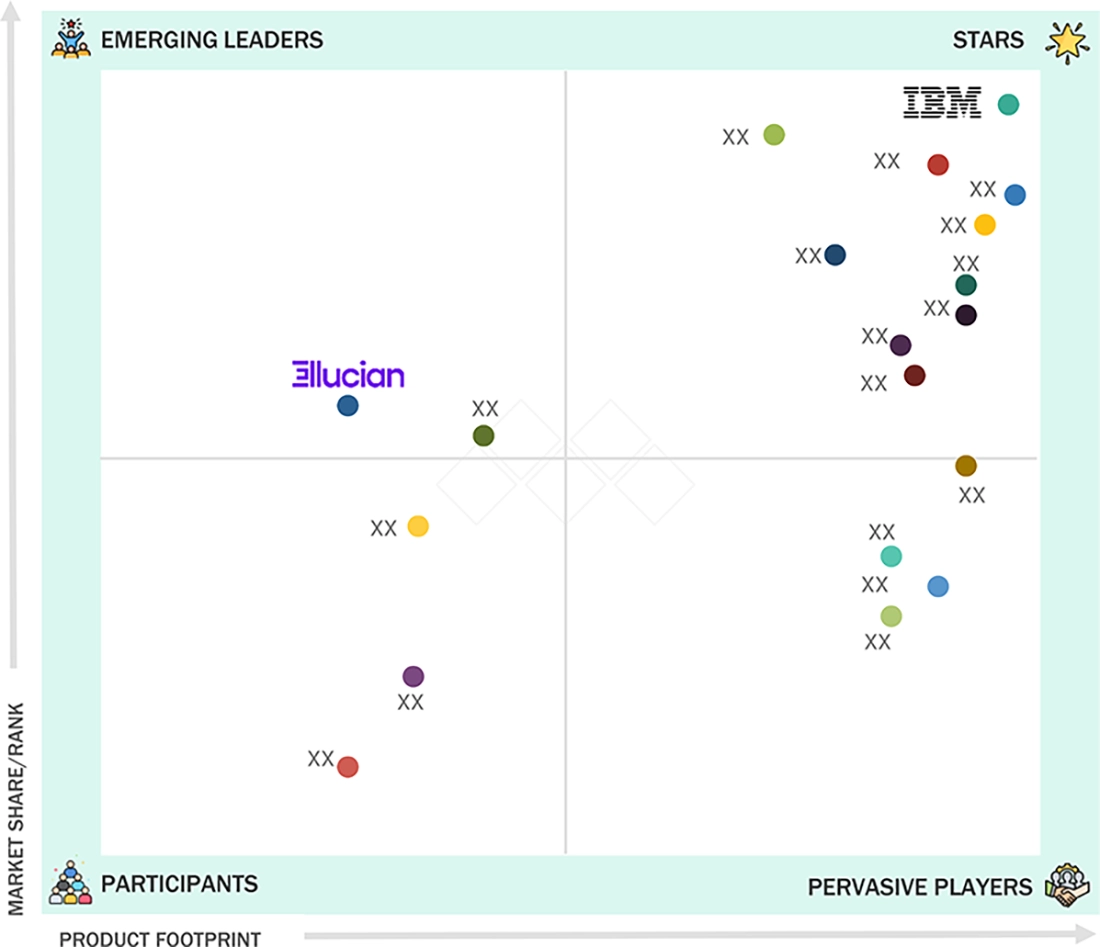
Competitive Landscape - Key PlayersIBM (US), Cisco (US), Anthology (US), SMART Technologies (Canada), Oracle (US), and Microsoft (US) were identified as some of the star players in the smart learning market, given their strong market share and product footprint.
-
Competitive Landscape - Startups/SMEsKnowledgewhere (US), Instructure (US), and Paradiso Solutions (US) have distinguished themselves among startups and SMEs in the smart learning market.
The global smart learning market is driving growth as educational institutions and enterprises are increasingly serving learner groups that are large, diverse, and geographically dispersed. Organizations are adopting smart learning platforms that allow content to be delivered in a consistent format, while giving learners flexibility in how and when they engage. Moreover, centralized progress tracking also makes it easier to monitor participation and outcomes across locations. As budget pressure and performance accountability grow, smart learning systems are being used to support more efficient delivery without compromising learning standards in distributed environments.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
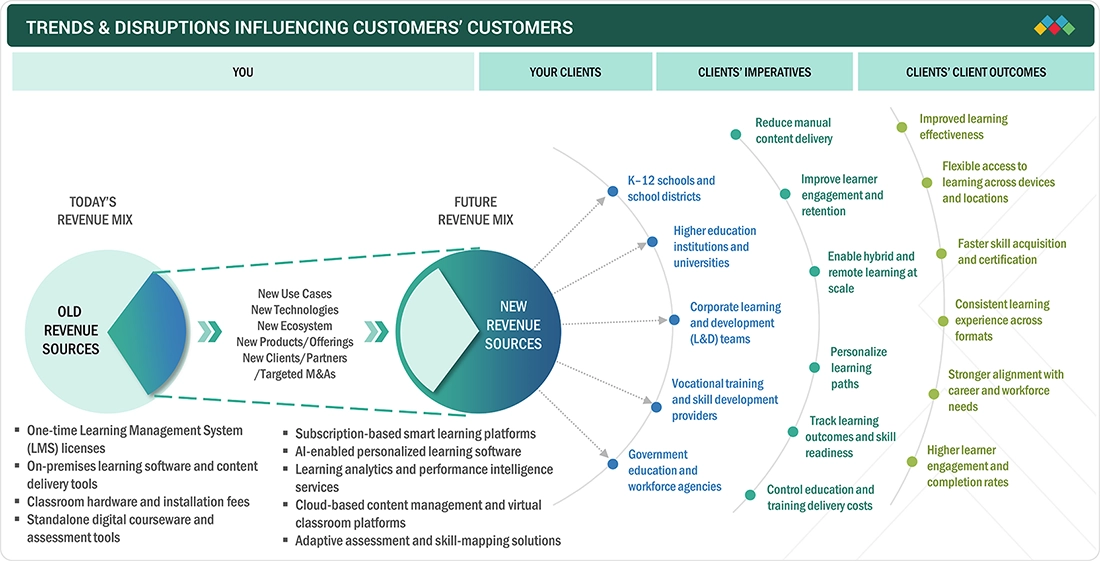
The smart learning market is gradually moving away from one-time software and hardware purchases toward subscription-based platforms and data-led services. Cloud-based learning systems are increasingly being deployed by schools, universities, enterprises, and public agencies to support hybrid delivery, personalization, and performance monitoring. This shift has been shaped by the need to reach learners across locations, improve engagement, and link training outcomes more closely to workforce needs. As a result, spending is increasingly directed toward adaptive content, learning analytics, and scalable digital platforms that offer consistent learning experiences while improving cost visibility and outcome measurement.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Level
-
Shift toward flexible and hybrid learning models

-
Rising demand for scalable digital learning infrastructure


Level
-
Fragmented digital infrastructure across institutions

-
Budget constraints in public education and smaller institutions


Level
-
Growing demand for data-informed teaching and learning decisions

-
Increasing adoption of cloud-based learning platforms in emerging markets


Level
-
Managing data privacy and trust in digital learning environments

-
Ensuring consistent learning quality across digital and physical formats

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Shift toward flexible and hybrid learning models
Learning environments are shifting away from fixed, classroom-only delivery models as institutions expand blended and remote formats. This change reflects the need to support learners who are spread across campuses, homes, and workplaces at the same time. As delivery becomes more distributed, coordinating content, assessments, and learner progress across locations becomes harder using static tools. These operational gaps are pushing institutions to adopt smart learning platforms that centralize content delivery and progress tracking. By bringing instructional data into a shared system, these platforms reduce coordination effort and improve consistency. As hybrid learning becomes part of routine operations rather than a temporary adjustment, scalable digital learning platforms are increasingly viewed as essential infrastructure.
Restraint: Fragmented digital infrastructure across institutions
Despite wider interest in smart learning, many institutions still operate with disconnected systems built over long investment cycles. Learning platforms, administrative databases, and content tools often sit in parallel, with limited links between them. This fragmentation increases administrative workload and complicates efforts to gain a unified view of learner progress and outcomes. Smaller institutions and public education systems face additional constraints due to budget limits and uneven access to reliable connectivity. As long as legacy platforms remain in use without integration frameworks, the adoption of fully connected smart learning environments tends to progress gradually rather than at scale.
Opportunity: Growing demand for data-informed teaching and learning decisions
As learning activities increasingly move online, institutions are gaining access to detailed information on participation, performance, and engagement. However, turning this information into practical insight remains a challenge. Smart learning solutions that support analytics, adaptive content delivery, and early identification of learning gaps are gaining attention as institutions look to improve outcomes rather than simply digitize content. These capabilities help educators adjust instruction, support at-risk learners, and align training with skill requirements. As accountability around learning outcomes grows in academic and corporate settings, platforms that translate learning data into actionable decisions represent a clear growth opportunity.
Challenge: Managing data privacy and trust in digital learning environments
Smart learning platforms depend on ongoing collection of learner data, ranging from assessment results to usage behavior. As these systems are adopted more widely, questions around consent, data handling, and regulatory compliance are becoming harder for institutions to manage, particularly in regions with evolving education and data protection policies. Analytics-driven personalization can offer clear instructional benefits, but it also requires tighter controls around how data is stored, shared, and accessed. For many institutions, especially in public education, these requirements influence platform selection and slow deployment timelines. In the absence of consistent governance frameworks, advanced features are often rolled out cautiously or avoided altogether due to higher levels of stakeholder and regulatory scrutiny.
SMART LEARNING MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Microsoft deployed Teams for Education and Microsoft 365 learning tools across public school districts and universities to support remote and hybrid instruction. The platform enabled virtual classrooms, assignment management, and collaboration between students and teachers, ensuring continuity of learning during periods of campus disruption. | Improved learning continuity | Better student-teacher collaboration | Standardized digital classroom experience |
 |
Universities globally adopted Canvas Learning Management System (LMS) to manage online and blended courses. Canvas was used to centralize course content, assessments, grading, and student engagement analytics across departments and campuses. | Simplified course management | Improved learner engagement | Scalable hybrid learning delivery |
 |
Pearson implemented its digital curriculum and assessment platforms across high education institutions to support online learning and continuous assessment. Digital content delivery replaced traditional print materials, enabling faster updates and flexible access for students. | Wider access to learning content | Faster curriculum updates | Improved assessment consistency |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
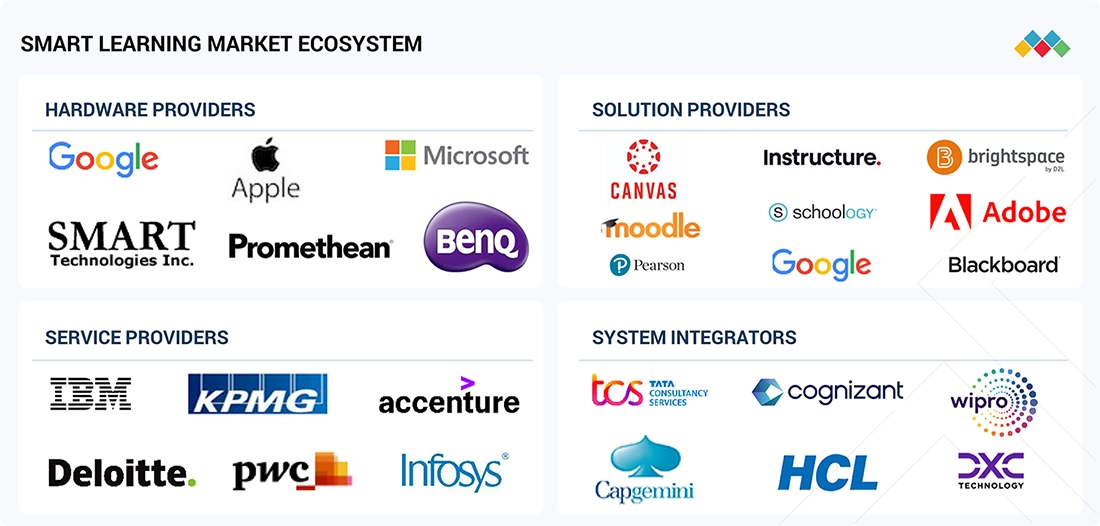
The smart learning ecosystem includes hardware providers (Google, Apple, Microsoft, SMART Technologies, BenQ, and Promethean) that supply devices and classroom equipment used for digital instruction; solution providers [Instructure, D2L (Brightspace), Blackboard, Moodle, Adobe, Google, and Pearson] that offer learning management platforms, digital content, and assessment tools; service providers (IBM, Accenture, Infosys, PwC, and KPMG) that support deployment, cloud migration, and ongoing platform management; and system integrators (Tata Consultancy Services, Wipro, Cognizant, HCL, DXC Technology, and Capgemini) that focus on implementation and system integration across education institutions and enterprises.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Smart Learning Market, By Offering
The software segment is projected to achieve the highest growth rate during the forecast period. Schools buy software packages for classrooms with interactive screens and student devices. Businesses deploy these packages for employee training across offices. Moreover, software providers bundle management tools with delivery platforms, and this one-stop approach cuts procurement time for buyers. As a result, pure content or hardware sales trail since customers want integrated setups.
Smart Learning Market, By Learning Type
The asynchronous learning segment is projected to lead the smart learning market during the forecast period. Asynchronous setups let students access materials and complete work on their own schedules. Platforms deliver video lessons, quizzes, and assignments through learning management systems. Workers complete modules during breaks or off-hours. This format fits busy schedules in schools and companies. Students review tough topics multiple times and progress tracking works through automated grading.
REGION
Asia Pacific to be fastest-growing region in global smart learning market during forecast period
Asia Pacific is projected to grow at the highest rate in the global smart learning market during the forecast period. This growth is supported by sustained public investment in digital education infrastructure across China, India, and several Southeast Asian economies. Online learning platforms are being expanded to improve access for students in remote and underserved areas. The demand for training is also rising, particularly among manufacturers and service providers to support automation and new production technologies. Additionally, upgrades to network infrastructure are allowing more frequent use of video-led instruction and interactive course formats, especially in urban and industrial centers. Moreover, digital learning content is increasingly being adapted to local languages and curriculum requirements rather than delivered as standardized global material. These developments are closely tied to the region’s large learner population and the practical need to deliver education and training at scale, rather than to isolated technology adoption alone.
SMART LEARNING MARKET: COMPANY EVALUATION MATRIX
In the smart learning evaluation matrix, IBM (Star) leads with substantial market share and broad platform capabilities, powered by Watson AI analytics and skills training solutions adopted across corporate upskilling and higher education sectors. On the other hand, Ellucian (Emerging Leader) is strengthening its position through its high education-focused platforms, including student information systems, learning analytics, and cloud-based campus solutions that support integrated academic and administrative workflows. While IBM commands through comprehensive AI-driven ecosystems and enterprise scale, Ellucian displays solid potential to advance toward the leaders’ quadrant as institutions prioritize data-driven decision-making and unified digital campus environments.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- IBM (US)
- Samsung (South Korea)
- Adobe (US)
- Anthology (US)
- SMART Technologies (Canada)
- SAP (Germany)
- Microsoft (US)
- Cornerstone OnDemand (US)
- Pearson (UK)
- BenQ (Taiwan)
- Google (US)
- McGraw Hill (US)
- Huawei (China)
- Cisco (US)
- Oracle (US)
- D2L (Canada)
- Ellucian (US)
- Alphabet (US)
- Upside LMS (India)
- Edsys (India)
- echo360 (US)
- Knowledge Anywhere (US)
- Instructure (US)
- SkyPrep (Canada)
- Paradiso Solutions (US)
- CYPHER Learning (US)
- Schoology (US)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2024 (Value) | USD 67.07 Billion |
| Market Forecast in 2030 (Value) | USD 178.62 Billion |
| Growth Rate | CAGR of 17.2% from 2025–2030 |
| Years Considered | 2019–2030 |
| Base Year | 2024 |
| Forecast Period | 2025–2030 |
| Units Considered | Value (USD Billion) |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered |
|
| Regions Covered | North America, Europe, Asia Pacific, Middle East & Africa, and Latin America |
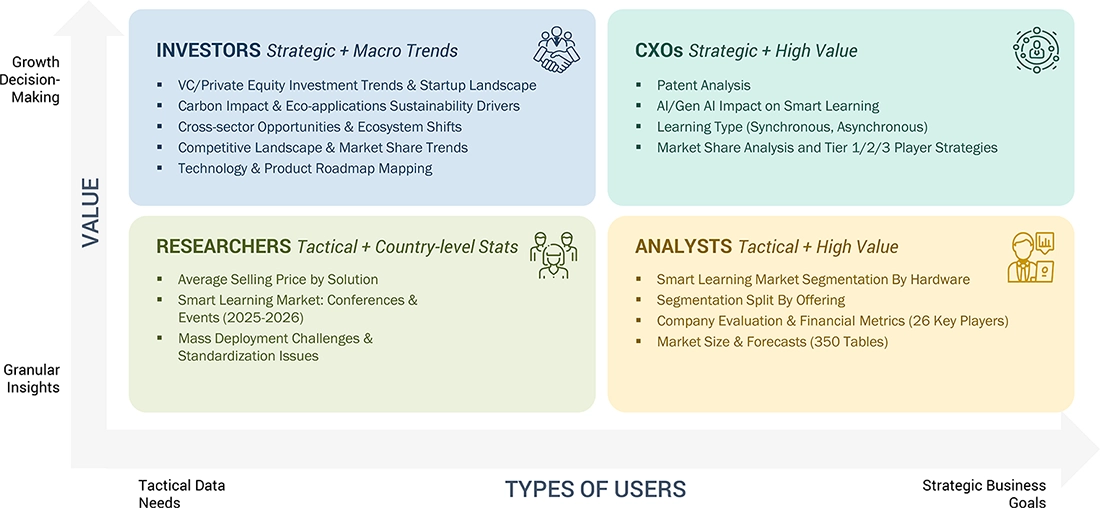
WHAT IS IN IT FOR YOU: SMART LEARNING MARKET REPORT CONTENT GUIDE
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Leading Service Provider | Regional Analysis of smart learning market including breakdown of the North America smart learning market, of the Europe smart learning market, of the Asia Pacific smart learning market, and of the Middle East & Africa smart learning market, and of the Latin America smart learning market |
|
RECENT DEVELOPMENTS
- July 2025 : Instructure and OpenAI announced a global partnership to integrate OpenAI's AI technology directly into the Canvas Learning Management System (LMS). This collaboration, part of Instructure’s IgniteAI initiative, would allow educators to create "LLM-Enabled Assignments," which are custom, GPT-like experiences.
- June 2025 : Pearson and Google Cloud formed a multi-year partnership to accelerate the development of new AI-powered educational tools. This collaboration would leverage Google’s AI models, including Gemini, to create personalized learning experiences for K–12 students and provide educators with data-driven insights.
- October 2024 : Transact Campus and Anthology announced a strategic partnership to enhance their higher education solutions. The collaboration would create seamless, integrated payment and credentialing systems that work with Anthology's products, including its student information system (Anthology Student) and CRM (Anthology Reach).
- September 2024 : Cisco Philippines and Mapúa University partnered to launch the country's first digital classrooms, leveraging AI-powered collaboration tools to redefine hybrid learning. The classrooms, equipped with Cisco Webex Boards and AI features, support Mapúa's flexible "Tri-x" teaching model, allowing students to seamlessly participate in face-to-face, synchronous, or asynchronous lessons.
Related Ecosystem
Digitalization And Iot
- Sensors
- Remote Monitoring
- Supply Chain Management
- Passenger Information System (PIS)
- Platform as A Service (PaaS)
- International Business Machines Corporation
- Cisco Systems, Inc.
- MICROSOFT CORPORATION
- Oracle Corporation
- HUAWEI TECHNOLOGIES CO LTD
Software And Services
- Natural Language Processing (NLP)
- Machine Learning
- Supply Chain Management
- Predictive Analytics
- Image Sensors
- International Business Machines Corporation
- MICROSOFT CORPORATION
- Oracle Corporation
- SAP SE
- Amazon.com, Inc.
Key Takeaways
- Asia Pacific smart learning market will nearly triple from USD 16.05B (2024) to USD 45.16B (2029), representing 23.0% CAGR growth.
- Asia Pacific's growth rate of 23.0% significantly exceeds the global average of 18.3%, positioning the region as the fastest-growing smart learning market.
- Mobile-first and AI-driven learning solutions dominate Asia Pacific adoption, supported by high smartphone penetration and government EdTech initiatives.
- Asia Pacific's diverse economies and large student populations create sustained demand for scalable, affordable smart learning platforms through 2029.
Smart Learning Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2024 |
| Fastest Growing Segment | LMS/LCMS (Standalone Solution) |
| Forecast Period | 2024–2029 |
| Growth Rate | CAGR of 18.3% from 2024 to 2029 |
| Largest Segment | ACADEMIC (End User) |
| Market Size Base Year (Billions) | ~USD 66.98 (2024) |
| Revenue Forecast (Billions) | ~USD 155.2 (2029) |
| Segments Covered | Offering, Hardware, Solution, Standalone Solution, Service, Learning Type, End User, Academic End User, Enterprise End User, Academic, Enterprise |
Italy Smart Learning Market Report Segmentation
11 segment dimensions are covered across the global market.
By Offering
- Hardware
- Services
- Solutions
By Hardware
- Interactive Displays
- Interactive Whiteboards
- Smart Boards
- Smart Table
- Smart Tables
By Solution
- Integrated Solutions
- Standalone Solutions
By Standalone Solution
- Adaptive Learning Platform
- Classroom Management Software
- Language Learning Software
- Lms/Lcms
- Lms/Lcs
- Student Information System
By Service
- Consulting
- Implementation
- Support And Maintenance
By Learning Type
- Asynchronous Learning
- Synchronous Learning
By End User
- Academic
- Enterprises
- Government
By Academic End User
- Higher Education
- K12
By Enterprise End User
- Large Enterprise
- SME
By Academic
- Higher Education
- K12
By Enterprise
- Large Enterprises
- Smes
Target Audience
- EdTech Companies & Startups : Require market intelligence to identify growth opportunities, understand competitive dynamics, and develop go-to-market strategies for expanding their smart learning solutions across Italy's rapidly growing education sector.
- Educational Institutions : Need market insights to benchmark technology investments, evaluate vendor solutions, and align digital transformation initiatives with industry trends and best practices in Italian smart learning adoption.
- Investment & Private Equity Firms : Seek comprehensive market data to evaluate investment opportunities, assess portfolio company growth potential, and identify acquisition targets within Italy's high-growth smart learning market segment.
- Technology Vendors & Solution Providers : Require detailed market analysis to understand customer segments, technology preferences, and revenue opportunities to optimize product positioning and sales strategies in the Italian education market.
- Government & Policy Makers : Need market intelligence to inform education policy decisions, allocate digital transformation budgets effectively, and evaluate the impact of technology initiatives on learning outcomes across Italian institutions.
Reasons to Buy this Report
- Market Entry Strategy : Gain detailed insights into Italy's smart learning landscape to develop targeted market entry strategies, identify key stakeholders, and understand regulatory requirements specific to the Italian education sector.
- Competitive Intelligence : Analyze competitor positioning, market share distribution, and technology adoption trends among Italian EdTech providers to benchmark your offerings and identify competitive advantages in this high-growth market.
- Investment Decision Support : Access comprehensive market data and growth projections to support investment decisions, funding allocation, and partnership opportunities within Italy's expanding smart learning ecosystem.
- Product Development Roadmap : Understand Italian customer preferences, pain points, and emerging technology demands to inform product development priorities and ensure solutions align with local market needs and educational standards.
- Revenue Forecasting : Leverage accurate market sizing and segment-level forecasts to project revenue potential, identify high-growth segments, and optimize resource allocation for maximum ROI in the Italian smart learning market.
Frequently asked questions
What is the current size of the Asia Pacific smart learning market?
The Asia Pacific smart learning market was valued at USD 16,052.6 million in 2024 and is projected to grow to USD 45,164.0 million by 2029.
What is the CAGR for Asia Pacific smart learning market?
Asia Pacific's smart learning market is growing at a compound annual growth rate of 23.0% from 2024 to 2029, outpacing the global CAGR of 18.3%.
Which countries in Asia Pacific are driving smart learning adoption?
Major markets across Asia Pacific including China, India, Japan, South Korea, and Southeast Asian nations are driving adoption through government EdTech initiatives and rising digital literacy.
What technologies are leading the Asia Pacific smart learning market?
AI-powered adaptive learning platforms, mobile-first solutions, virtual classrooms, intelligent tutoring systems, and cloud-based educational tools are leading adoption in Asia Pacific.
What factors are accelerating smart learning growth in Asia Pacific?
Key drivers include high smartphone penetration, government education digitalization policies, increasing EdTech investment, large student populations, and demand for personalized learning solutions across Asia Pacific.
RESEARCH METHODOLOGY
Get the Full Smart Learning Market Report
Full forecast, segment splits, and company analysis for all Smart Learning Market.
- CANADA Smart Learning Market
- US Smart Learning Market
- UK Smart Learning Market
- GERMANY Smart Learning Market
- CHINA Smart Learning Market
- JAPAN Smart Learning Market
- UAE Smart Learning Market
- BRAZIL Smart Learning Market
- MEXICO Smart Learning Market
- France Smart Learning Market
- Nordic Countries Smart Learning Market
- Rest Of Europe Smart Learning Market
- Spain Smart Learning Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
