GCC Space Cybersecurity Market (2024-2029)
The GCC Space Cybersecurity Market was valued at $142.7 Million in 2024 and projected to reach to $243.1 Million by 2029, representing a compound annual growth rate of 11.2%. The GCC space cybersecurity market is positioned for sustained growth through 2029, with valuations expanding from USD 142.7 million to USD 243.1 million.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
GCC Space Cybersecurity Market Trends and Insights
- This growth trajectory reflects the GCC's strategic investments in satellite infrastructure, space exploration initiatives, and heightened awareness of orbital security threats.
- The GCC region's commitment to diversifying its economy beyond hydrocarbon sectors has accelerated space sector development, creating substantial demand for advanced cybersecurity solutions to protect critical space assets and ground-based operations. The GCC's space cybersecurity market is driven by increasing satellite launches, emerging space agencies, and regional partnerships with international space organizations.
- GCC nations are prioritizing the protection of communication satellites, Earth observation systems, and emerging space infrastructure against evolving cyber threats.
- The market's 11.2% CAGR significantly outpaces global growth, underscoring the GCC's accelerated digital transformation and space sector maturation between 2024 and 2029. Key market participants are establishing regional hubs within the GCC to address localized security requirements and regulatory compliance needs.
- The GCC's investment in indigenous space capabilities and technology transfer agreements is expected to further propel demand for specialized cybersecurity solutions tailored to space operations and satellite management systems..
Key Market Statistics
- CAGR (2024-2029) 11.2% CAGR
- Market Size, 2024 ~USD 142.7 Million
- Forecast, 2029 ~USD 243.1 Million
- Country GCC
GCC Space Cybersecurity Market Overview
Rapid Market Expansion :
The GCC space cybersecurity market is growing at 11.2% CAGR, outpacing the global average of 9%, driven by regional satellite programs and space infrastructure investments across UAE, Saudi Arabia, and other member states.
Strategic Satellite Initiatives :
GCC nations are accelerating space exploration programs and satellite deployment, creating critical demand for advanced cybersecurity solutions to protect orbital assets and ground-based command centers from emerging threats.
Economic Diversification Focus :
As GCC countries pivot away from hydrocarbon dependency, space technology and cybersecurity represent key pillars of Vision 2030 and similar national transformation agendas, attracting substantial government funding and private investment.
Orbital Security Awareness :
Heightened recognition of space-based vulnerabilities and geopolitical tensions has elevated cybersecurity prioritization among GCC space agencies, defense ministries, and commercial satellite operators in the region.
GCC Space Cybersecurity Market Dynamics
- This 70% increase reflects the region's commitment to building sovereign space capabilities and protecting critical orbital infrastructure.
- Government procurement initiatives, particularly from UAE and Saudi Arabia, are driving adoption of advanced threat detection and encryption technologies.
- The GCC's geographic location and strategic importance in global space commerce further amplify cybersecurity investments. Looking ahead, the market will be shaped by increasing satellite constellation deployments, cross-border space partnerships, and regulatory frameworks emerging across member states.
- Private sector participation is expected to accelerate as commercial space ventures expand.
- Integration of AI-driven security solutions and quantum-resistant encryption will become standard requirements.
- Regional collaboration through GCC-wide cybersecurity standards will create economies of scale, while talent development initiatives will strengthen the local security ecosystem..
Market Ecosystem
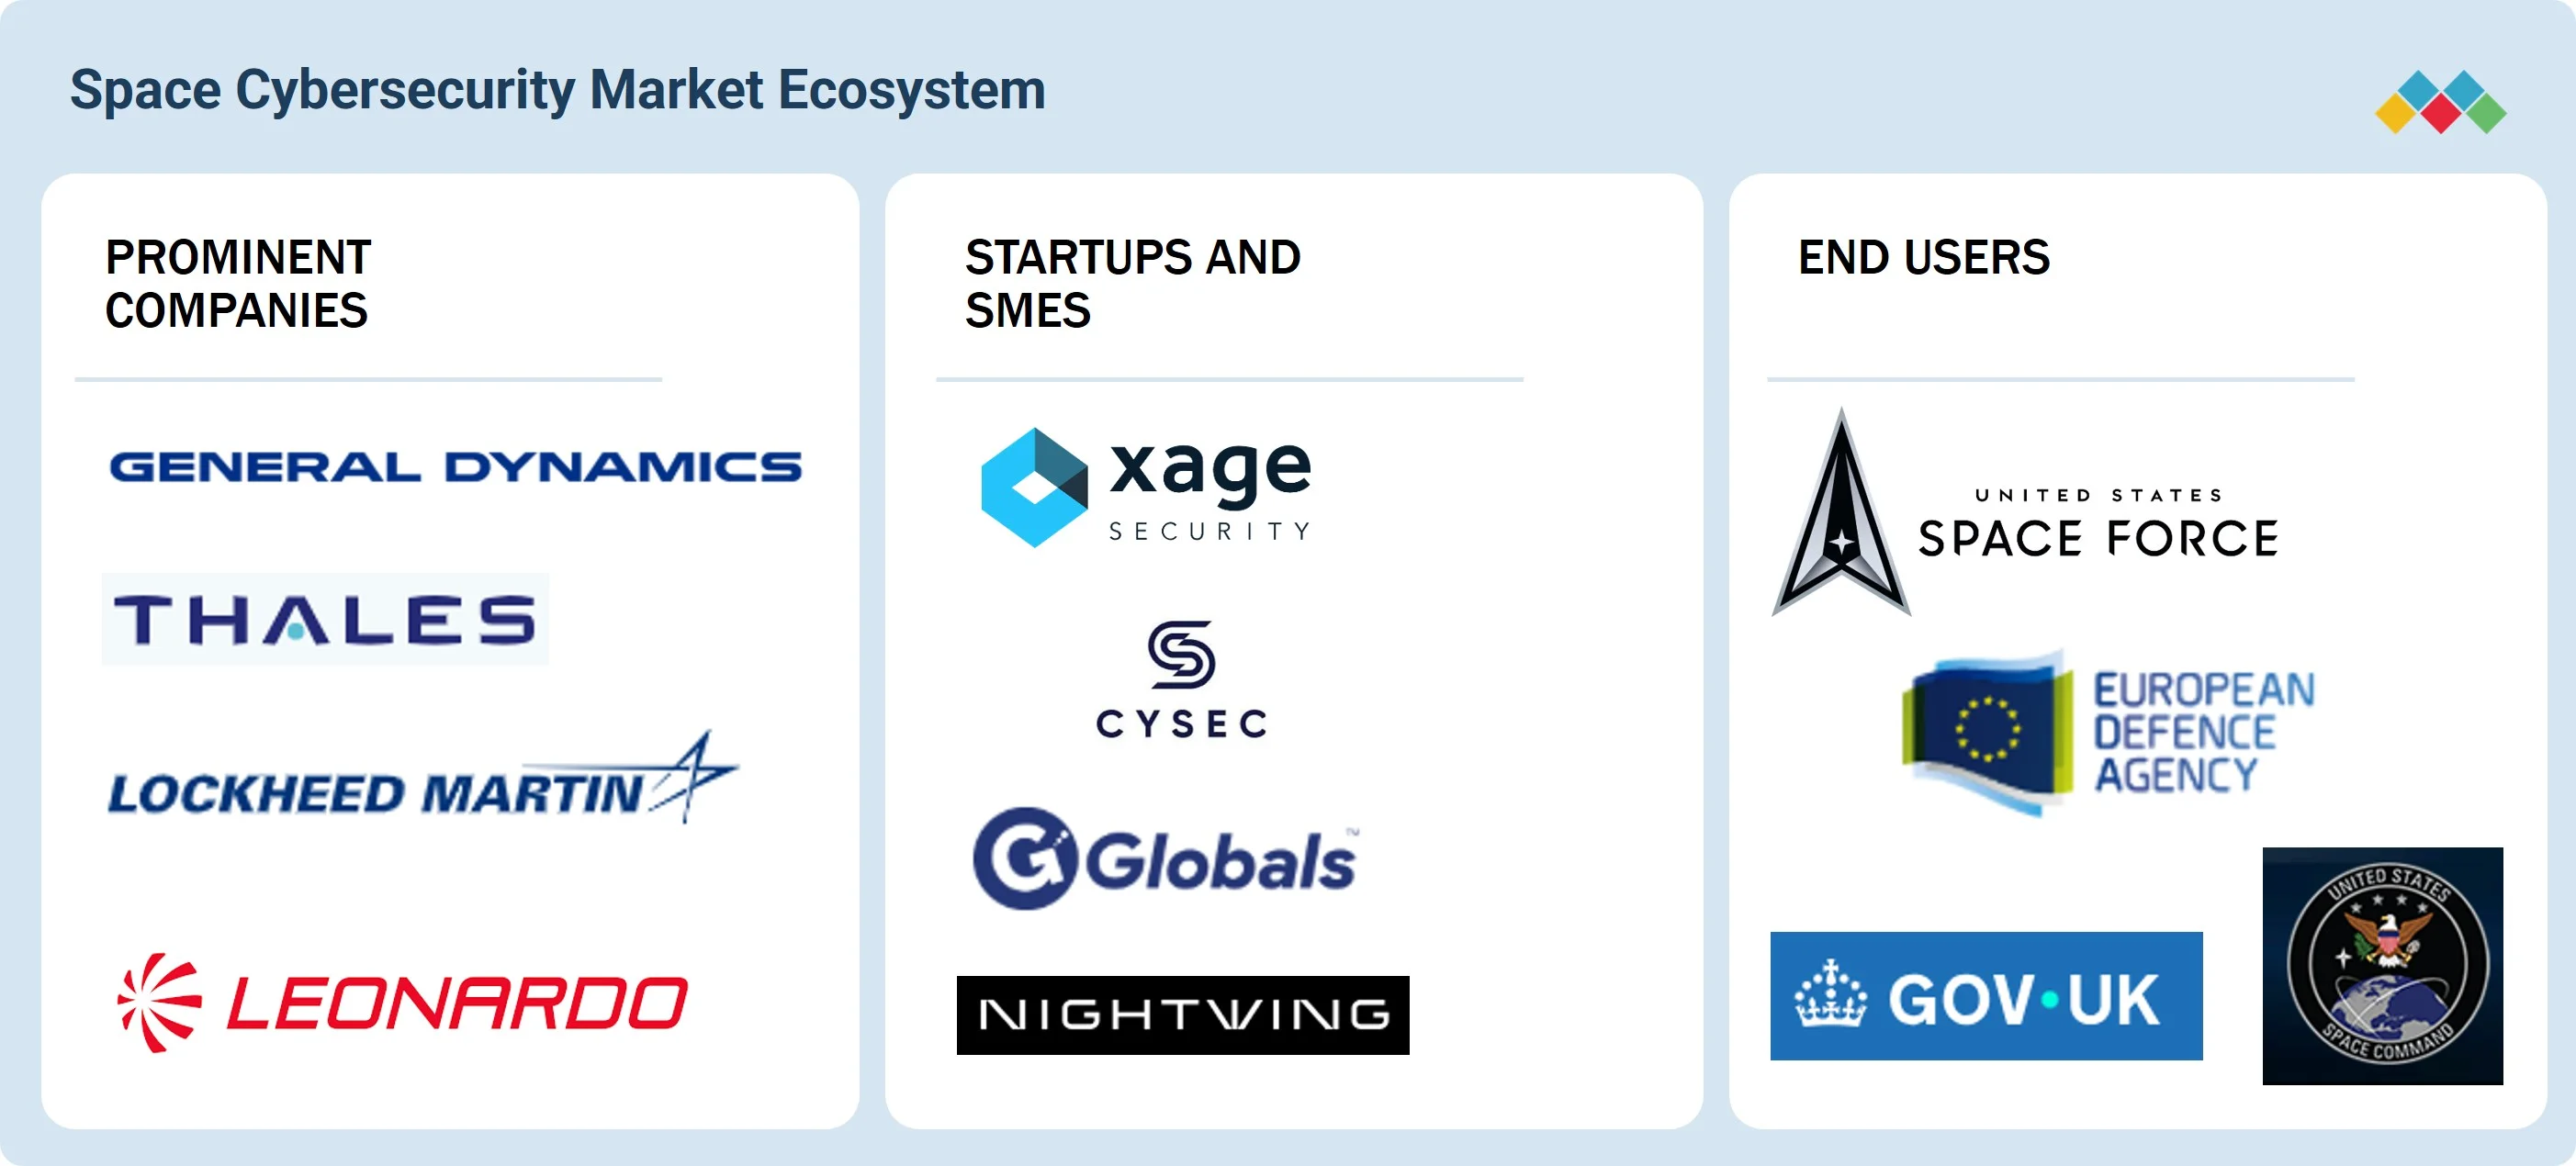
SPACE CYBERSECURITY MARKET SIZE, SHARE & TRENDS: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Thales conducted a cybersecurity assessment of an ESA satellite during the CYSAT 2023 exercise, demonstrating how vulnerabilities in onboard software could allow unauthorized access and modification of satellite imagery. The exercise involved accessing the satellite's application environment, identifying security weaknesses, and demonstrating the potential impact of cyberattacks on operational satellite systems. | Helps satellite operators identify security vulnerabilities, strengthen onboard software protection, improve access controls, and reduce risks of unauthorized satellite commands and data manipulation. Supports cybersecurity testing before operational deployment. |
 |
General Dynamics Mission Systems provides high-assurance space encryption technologies, including certified End Cryptographic Units (ECUs) used in US Air Force and US Space Force programs. These systems protect satellite telemetry, tracking, command, and mission data communications between spacecraft and ground infrastructure. The company has delivered more than 100 certified space ECUs for military space missions. | Protects classified satellite communications against unauthorized interception and data manipulation. Supports secure command transmission, mission data confidentiality, and reliable communication between satellites and ground control systems. |
 |
Viasat's KG-255XJ ground-to-space encryption solution received NSA Type 1 certification in May 2023. The system protects classified telemetry, tracking, command, and mission data exchanged between satellite operations centers and orbiting satellites. Its configurable encryption architecture supports multiple satellite communication requirements through a common security device. | Provides secure satellite command and data transmission while supporting multiple cryptographic functions. Reduces the complexity of integrating encryption across satellite networks and supports protection of sensitive government and defense space communications. |
 |
Leonardo led a consortium of 19 European companies responsible for developing, integrating, and validating the European Space Agency's Cyber Security Operations Centre, inaugurated in May 2025. The facility operates across ESA sites in Germany and Belgium and supports cybersecurity monitoring of satellites, ground stations, mission control infrastructure, and other digital systems. | Strengthens cybersecurity monitoring across ESA infrastructure, supports identification and response to cyber threats, and improves coordination between mission-critical and corporate security operations. The dual-site architecture also provides operational redundancy and service continuity. |
 |
Booz Allen Hamilton provides space cybersecurity engineering, satellite software security assessments, zero-trust architecture development, and cybersecurity testing for government and commercial space missions. Its capabilities include satellite digital twins, dynamic security testing, software assurance, and cybersecurity assessment and authorization aligned with national security requirements. | Helps identify software and system vulnerabilities before satellite deployment, improve security architecture, and strengthen protection of ground and orbital systems. Satellite testbeds support cybersecurity validation without exposing operational spacecraft to testing risks. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Space
- C-Band
- Small Satellite
- Antennas
- Ka-Band
- Microsatellite
- AIRBUS
- L3Harris Technologies, Inc.
- Thales group
- Northrop Grumman Corporation
- LOCKHEED MARTIN CORPORATION
Key Takeaways
- GCC space cybersecurity market valued at USD 142.7M in 2024, expanding to USD 243.1M by 2029 at 11.2% CAGR
- GCC's space sector diversification and satellite infrastructure investments are primary growth catalysts for cybersecurity demand
- GCC nations prioritize protection of communication and Earth observation satellites against emerging orbital cyber threats
- GCC's growth rate of 11.2% CAGR significantly exceeds global average, reflecting accelerated regional space sector maturation
Space Cybersecurity Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2024 |
| Fastest Growing Segment | SERVICES (Offering) |
| Forecast Period | 2024–2029 |
| Growth Rate | CAGR of 9% from 2024 to 2029 |
| Largest Segment | SOLUTIONS (Offering) |
| Market Size Base Year (Billions) | ~USD 4.52 (2024) |
| Revenue Forecast (Billions) | ~USD 6.96 (2029) |
| Segments Covered | Offering, Solution, Type, Service, Platform, Satellite Orbit, End User, Launch Vehicle |
GCC Space Cybersecurity Market Report Segmentation
8 segment dimensions are covered across the global market.
By Offering
- Services
- Solutions
By Solution
- Application Security
- Cloud Security
- Data Backup & Recovery
- Encryption & Tokenization
- Endpoint Security
- Identity & Access Management
- Log Management & Siem
- Network Security
- Other Platforms
- Other Solutions
By Type
- Antivirus & Anti-Malware
- Cloud Access Security Broker
- Design, Consulting, And Implementation
- Endpoint Detection & Response
- Intrusion Detection & Prevention Systems
- Medium & Heavy Launch Vehicles
- Network Access Control
- Network Firewall
- Other Application Security Solutions
- Other Endpoint & IoT Security Solutions
- Other Network Security Solutions
- Patch Management
- Risk & Threat Management
- Secure Development Tools
- Security Posture Management
- Small Lift Launch Vehicles
- Support & Maintenance
- Training & Education
- Virtual Private Network
- Web Application Firewall
By Service
- Managed Services
- Professional Services
By Platform
- Command & Control Centers
- Ground Stations
- Launch Vehicles
- Other Platforms
- Satellites
- Spaceports & Launch Facilities
By Satellite Orbit
- Geo
- Leo
- Meo
By End User
- Commercial
- Defense
- Government
By Launch Vehicle
- Medium & Heavy Launch Vehicles
- Small Lift Launch Vehicles
Target Audience
- GCC Defense & Space Agencies : Government entities managing satellite programs and orbital infrastructure require market intelligence to justify cybersecurity budgets, benchmark regional spending, and align procurement with emerging threat landscapes.
- Cybersecurity Solution Providers : International and regional security vendors need GCC-specific demand forecasts, customer segmentation, and competitive positioning data to develop localized offerings and capture market share in this high-growth region.
- Commercial Satellite Operators : Private space companies and telecom firms operating satellites in GCC airspace require risk assessments and security solution benchmarking to protect assets, comply with regulations, and maintain operational resilience.
- Investment & Private Equity Firms : Investors evaluating space technology and defense sector opportunities in the GCC need market sizing, growth projections, and competitive dynamics to assess portfolio companies and identify acquisition targets.
- Systems Integrators & Consultants : Regional IT and defense consultancies require detailed market data to advise clients on cybersecurity strategy, vendor selection, and technology roadmaps aligned with GCC space infrastructure development plans.
Key Companies in the GCC Space Cybersecurity Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| THALES | France | Public Company | Defence & Security Systems (air defence, C4ISR, EW, mission systems),Aerospace & Air Traffic Management,Digital Identity & Security (banking, IAM, biometrics, secure IoT), |
| LOCKHEED MARTIN CORPORATION | United States | Public Company | Aeronautics,Missiles and Fire Control,Rotary and Mission Systems, |
| LEONARDO S.P.A. | Italy | Public Company | Helicopters,Defense Electronics and Security,Aircraft and Aerostructures, |
| SPACEX | United States | Public Company | Launch Services (Falcon 9 / Falcon Heavy / Dragon missions),Starlink Connectivity (consumer, enterprise, government),AI Platform & X (Grok, enterprise AI, ad and subscription revenue), |
| BOOZ ALLEN HAMILTON INC. | United States | Public Company | AI Solutions for Federal Missions,Cyber Solutions and Operations,Cloud, Data Platforms, and Software Modernization, |
| NORTHROP GRUMMAN | United States | Public Company | Space Systems,Mission Systems,Aeronautics Systems, |
| AIRBUS | Netherlands | Public Company | Commercial Aircraft (Airbus segment),Helicopters,Defence and Space, |
| BAE SYSTEMS | United Kingdom | Public Company | Electronic Systems,Air,Platforms & Services, |
| OHB SE | Germany | Public Company | Space Systems (satellites and payloads),Access to Space (assembly and space/aviation products),Digital (mechatronics, launch procurement, IT services), |
| MAXAR TECHNOLOGIES | United States | Private Company | Satellite imagery and access programs (WorldView, Vivid, Access Programs),Geospatial analytics and AI platforms (Tensorglobe, Cortex, Forge, Nexus),3D terrain, digital twins, and modeling/simulation (Vivid Terrain, 3D models, digital twin solutions), |
| GENERAL DYNAMICS CORPORATION | United States | Public Company | Aerospace (business jets and services),Marine Systems (submarines and surface combatants),Combat Systems (land systems and munitions), |
| CISCO SYSTEMS, INC. | United States | Public Company | Networking (campus, data center, branch, wireless, interconnect),Security (network security, SASE, identity, threat detection and response),Collaboration (WEBEX suite, devices, contact center, CPaaS), |
| LEIDOS | United States | Public Company | National Security & Digital (AI/ML mission software, cyber, intel, logistics, digital modernization),Defense Systems (air and missile defense, ISR, space payloads, threat systems),Health & Civil (air traffic control, health mission software, managed health, civil IT and logistics), |
THALES
Thales is a French multinational defense and aerospace company founded in 1893, employing 82,111 people. Operating as a public company, Thales provides advanced technologies and services across defense, security, and aerospace sectors.
LOCKHEED MARTIN CORPORATION
Lockheed Martin Corporation is a U.S.-based defense contractor founded in 1912 with 123,000 employees. As a public company, it is a leading provider of advanced aerospace, defense, and security solutions.
LEONARDO S.P.A.
Leonardo S.p.A. is an Italian defense and aerospace company established in 1948 with 65,455 employees. The public company specializes in advanced technologies for defense, security, and space applications.
SPACEX
SpaceX is a U.S. aerospace manufacturer and space transportation company founded in 2002 with 22,000 employees. Operating as a public company, SpaceX develops rockets and spacecraft for commercial and government missions.
BOOZ ALLEN HAMILTON INC.
Booz Allen Hamilton Inc. is a U.S.-based management and technology consulting firm founded in 1914 with 30,900 employees. As a public company, it provides consulting, analytics, and digital solutions to government and commercial clients.
NORTHROP GRUMMAN
Northrop Grumman is a U.S. defense and aerospace company founded in 1939 with 95,000 employees. The public company specializes in advanced systems, technologies, and services for defense, security, and space markets.
AIRBUS
Airbus is a multinational aerospace corporation founded in 1998 with 166,876 employees, headquartered in the Netherlands. As a public company, Airbus is a leading manufacturer of commercial aircraft, helicopters, and defense systems.
BAE SYSTEMS
BAE Systems is a British multinational defense, security, and aerospace company founded in 1979 with 111,400 employees. As a public company, BAE Systems provides advanced defense technologies and services globally.
OHB SE
OHB SE is a German aerospace and technology company founded in 1993 with 3,974 employees. The public company focuses on space systems, satellite technology, and aerospace solutions.
MAXAR TECHNOLOGIES
Maxar Technologies is a U.S. space technology and intelligence company founded in 1957 with 4,600 employees. Operating as a private company, Maxar provides satellite imagery, geospatial intelligence, and space infrastructure solutions.
GENERAL DYNAMICS CORPORATION
General Dynamics Corporation is a U.S. defense contractor founded in 1899 with 117,000 employees. As a public company, General Dynamics provides advanced technologies and systems for aerospace, defense, and security applications.
CISCO SYSTEMS, INC.
Cisco Systems, Inc. is a U.S. technology company founded in 1984 with 86,200 employees. As a public company, Cisco designs, manufactures, and sells networking equipment and IT infrastructure solutions.
LEIDOS
Leidos is a U.S. science and technology company founded in 1969 with 50,000 employees. Operating as a public company, Leidos provides engineering, IT, and research solutions to government and commercial clients.
Reasons to Buy this Report
- Regional Market Sizing & Forecasts : Obtain precise GCC-specific market valuations (USD 142.7M in 2024, USD 243.1M in 2029) with country-level breakdowns for UAE, Saudi Arabia, Qatar, and other member states to guide regional expansion strategies.
- Government Procurement Intelligence : Access detailed insights into GCC defense ministry budgets, space agency procurement cycles, and Vision 2030 initiatives to identify contract opportunities and align product offerings with regional security priorities.
- Competitive Landscape Analysis : Understand key players operating in the GCC space cybersecurity ecosystem, including local integrators, international vendors, and emerging startups, with market share and positioning data specific to the region.
- Technology Adoption Trends : Discover which cybersecurity technologies (AI, quantum encryption, threat intelligence platforms) are gaining traction among GCC satellite operators and space agencies to prioritize R&D and product development.
- Investment & Partnership Opportunities : Identify joint venture prospects, government-backed funding initiatives, and strategic partnerships within the GCC space sector to accelerate market entry and establish regional presence.
Frequently asked questions
What is the current market size of space cybersecurity in the GCC?
The GCC space cybersecurity market was valued at USD 142.7 million in 2024 and is projected to grow to USD 243.1 million by 2029.
What is the expected growth rate for GCC space cybersecurity?
The GCC space cybersecurity market is expected to grow at a compound annual growth rate (CAGR) of 11.2% from 2024 to 2029.
Why is the GCC space cybersecurity market growing faster than the global average?
The GCC's rapid growth is driven by strategic investments in satellite infrastructure, space exploration initiatives, economic diversification beyond hydrocarbon sectors, and heightened awareness of orbital security threats.
What are the primary cybersecurity concerns for GCC space assets?
GCC nations prioritize protection of communication satellites, Earth observation systems, and ground-based space operations against evolving cyber threats and unauthorized access attempts.
How are GCC nations addressing space cybersecurity challenges?
GCC nations are establishing regional cybersecurity hubs, forming international partnerships, implementing localized regulatory frameworks, and investing in indigenous space capabilities with integrated security solutions.
RESEARCH METHODOLOGY
This study used four main activities to estimate the current size of the space cybersecurity market. First, detailed secondary research was conducted to collect information on cybersecurity solutions and services, protected space assets, satellite deployments, space infrastructure, government and defense programs, procurement contracts, cybersecurity investments, and ongoing technology developments. The collected information and key assumptions were then validated through primary interviews with industry participants and experts across the value chain. Demand-side analysis was used to estimate cybersecurity spending by offering, asset type, application, end user, and region. Finally, market breakdown and data triangulation were used to calculate the size of each segment and subsegment.
Secondary Research
Secondary research included information from government procurement portals, space agencies, defense ministries, cybersecurity authorities, company annual reports, regulatory filings, investor presentations, product documents, press releases, technical papers, and industry publications. Sources such as NASA, ESA, NIST, CISA, and official government databases were used to review satellite deployments, cybersecurity requirements, space infrastructure protection, procurement activity, and ongoing space security programs. Government budget documents and procurement records were used to track cybersecurity investments, contracts, and technology development programs. Company filings and official product information were used to study cybersecurity solution portfolios, revenues, contracts, technologies, applications, customers, and geographical presence.
Primary Research
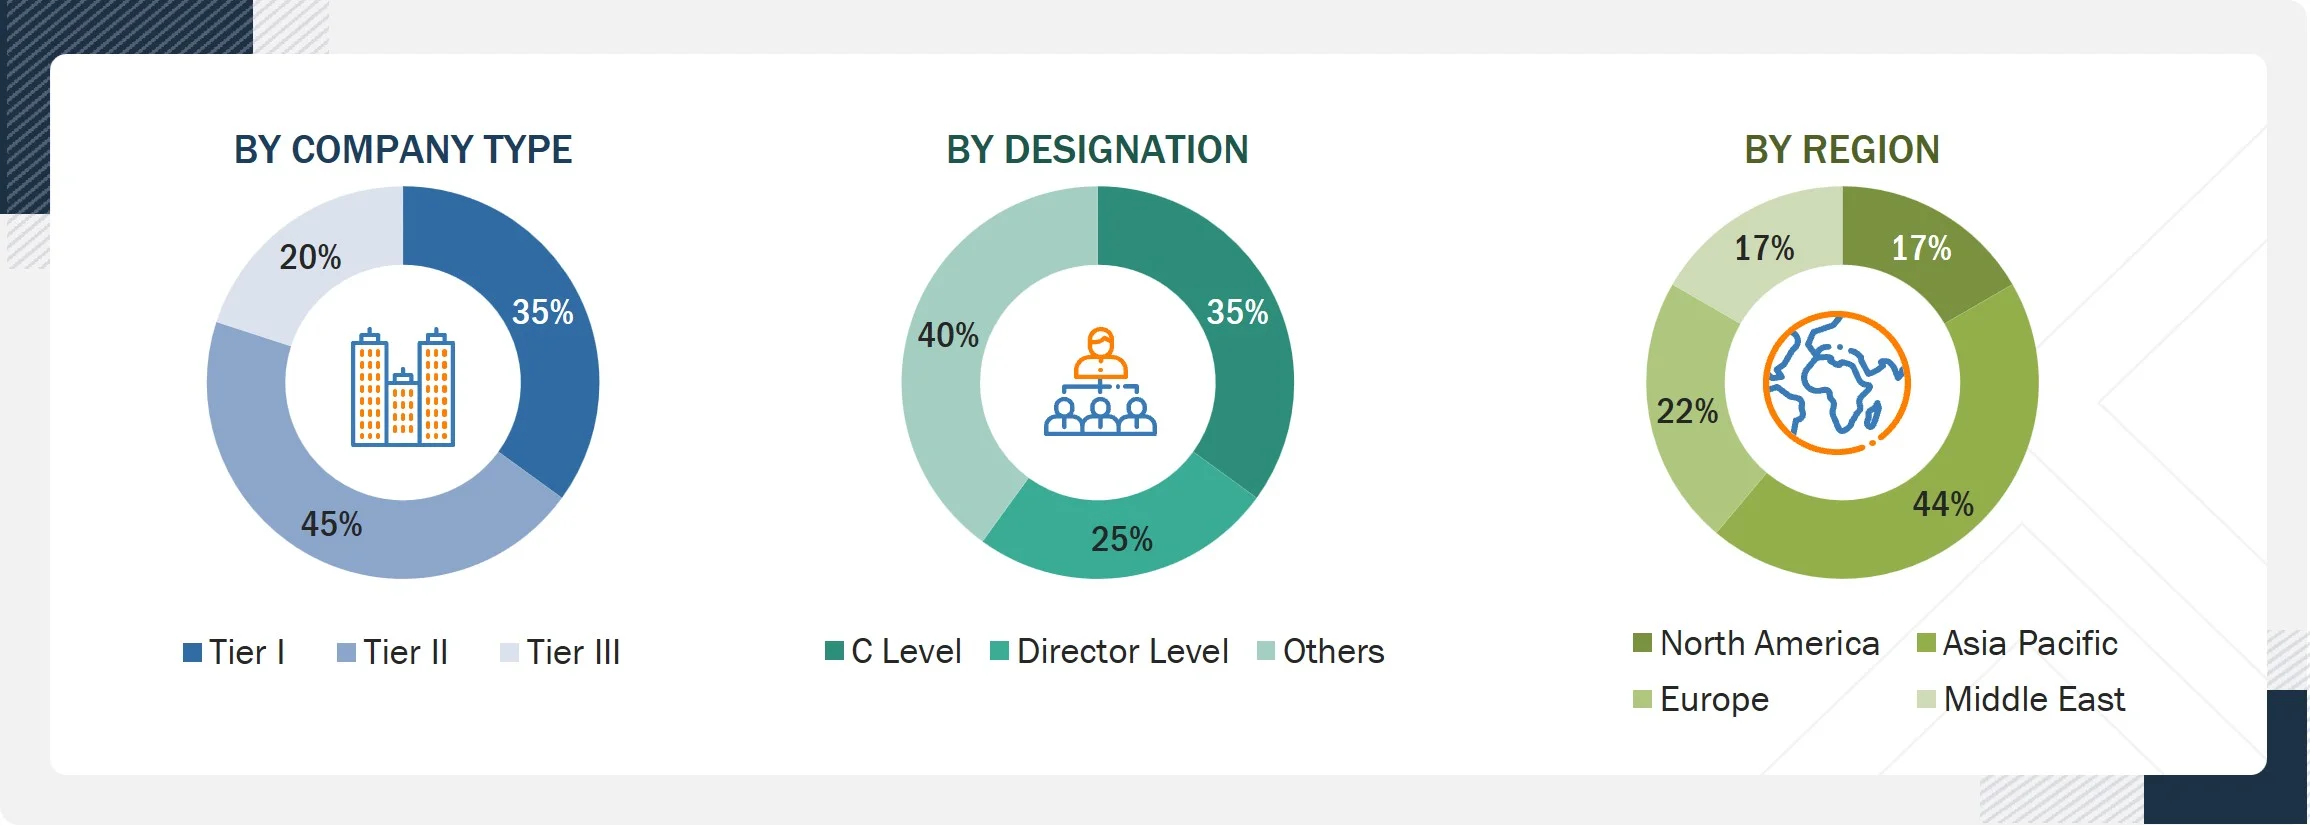
Primary research was conducted after completing the secondary research. Interviews were carried out with space cybersecurity solution providers, satellite manufacturers, system integrators, cybersecurity service providers, commercial satellite operators, defense organizations, space agencies, ground-station operators, and other industry participants. The interviews covered major countries across North America, Europe, Asia Pacific, Middle East, and the Rest of the World. Primary information was collected through questionnaires, emails, and telephone interviews and was used to validate market estimates, cybersecurity spending patterns, procurement trends, satellite protection requirements, technology adoption, applications, and segment-level assumptions.
Following is the breakup of the primary study:
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
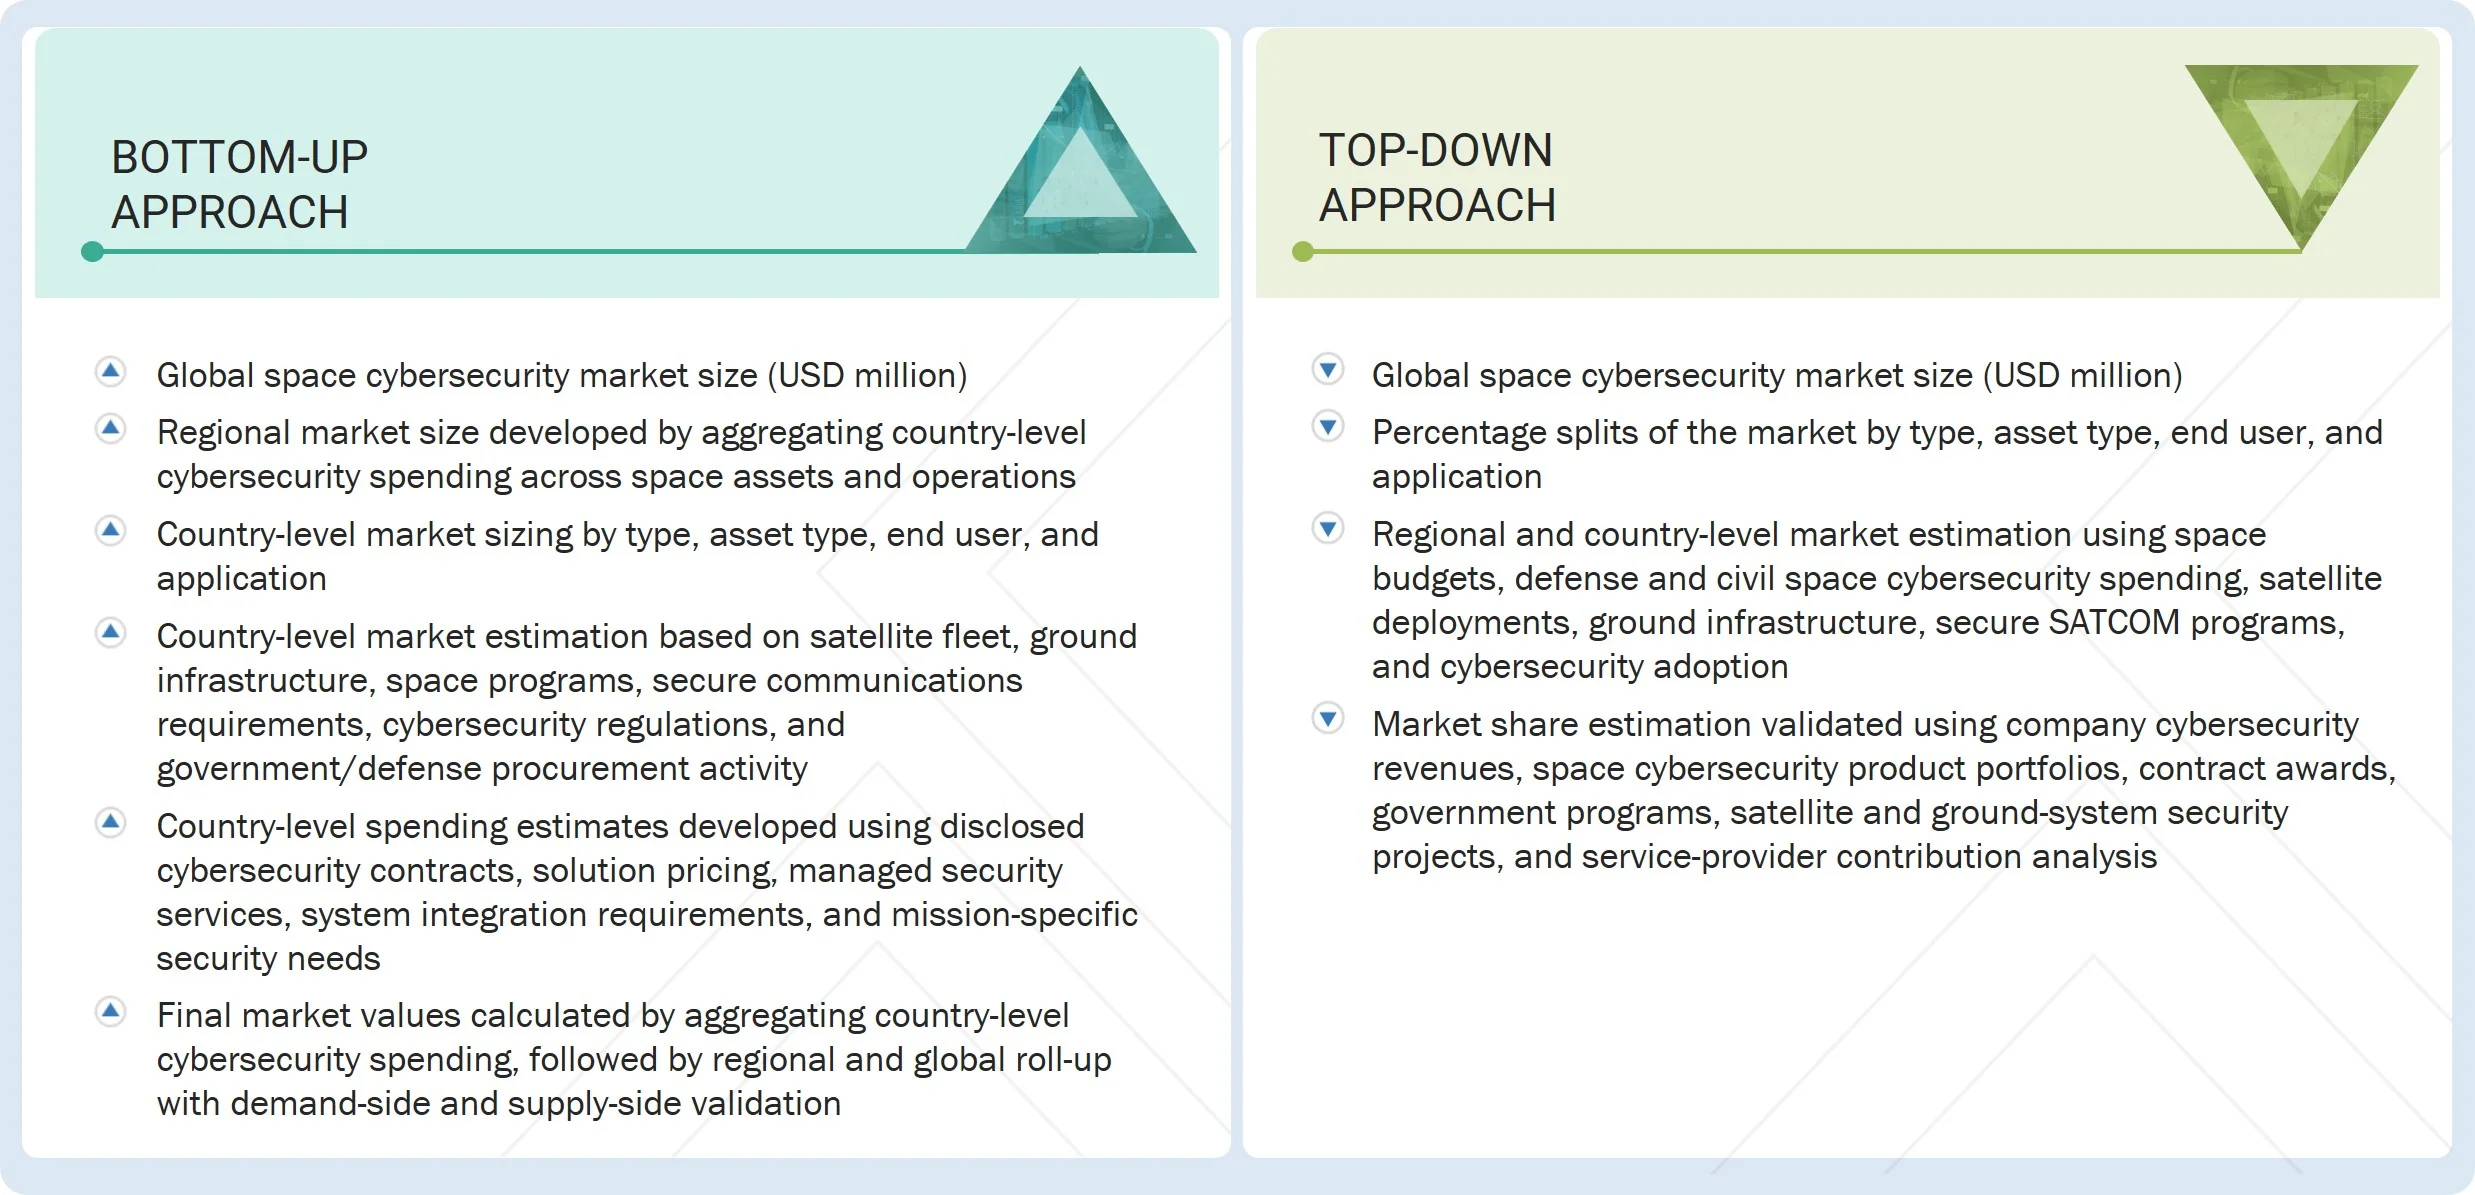
The top-down and bottom-up approaches were used to estimate and validate the size of the space cybersecurity market. The research methodology used to estimate the size of the market included the following details:
- Key space cybersecurity companies were identified through secondary research. Their market positions were estimated using company revenues, cybersecurity solution portfolios, contract activity, satellite security programs, regional presence, and participation in government and commercial space projects. Annual reports, financial filings, product documents, procurement records, space agency publications, government budget documents, and interviews with company executives, cybersecurity specialists, system integrators, satellite operators, and other industry participants were used for the analysis. Companies such as Thales, Lockheed Martin Corporation, Airbus SE, Viasat, Inc., General Dynamics Corporation, and CGI Inc. were assessed based on their cybersecurity offerings, secure communication technologies, space-related contracts, and service capabilities.
- Market shares, segment splits, regional shares, and growth rates were first estimated using secondary sources and then checked through primary interviews. The analysis covered the offering, asset type, end user, and application segments, along with cybersecurity spending, protected space assets, satellite deployment volumes, security software adoption, managed security services, and regional demand patterns. The assessment included network security, endpoint and IoT security, cloud security, encryption, identity and access management, security monitoring, and professional cybersecurity services.
- Demand for space cybersecurity across defense, commercial, and government end users was considered. The analysis included cybersecurity requirements for satellites, launch vehicles, ground stations and gateways, spaceports and launch facilities, command and control centers, and other critical space infrastructure. Spending on new cybersecurity deployments, existing system upgrades, software licenses, security integration, threat monitoring, and managed security services was evaluated. For example, the European Space Agency's Cyber Security Operations Centre, inaugurated in May 2025, represents investment in cybersecurity monitoring, incident response, and protection of operational space infrastructure.
- The collected information was compared and combined through data triangulation. Final market values were calculated using company-level space cybersecurity revenues, cybersecurity contract values, software licensing and service revenues, security expenditure per protected asset, satellite deployment activity, installed space infrastructure, regional cybersecurity spending, and primary-interview validation. Top-down estimates based on supplier revenues and space security budgets were reconciled with bottom-up estimates based on protected assets, security adoption rates, and average cybersecurity expenditure to determine market size across segments and regions.
Space Cybersecurity Market Size: Bottom-up & Top-Down Approaches
Space Cybersecurity Market : Top-Down and Bottom-Up Approach
Source: MarketsandMarkets Analysis
Data Triangulation
After determining the overall market size, the space cybersecurity market was divided into its main segments and subsegments. Data triangulation and market breakdown were used to develop estimates for each segment and subsegment. The analysis considered factors from both the demand and supply sides, including government and defense cybersecurity budgets, satellite deployment volumes, protected space assets, cybersecurity procurement contracts, software licensing, managed security services, company participation, and regional security requirements. Asset-specific indicators such as cybersecurity spending on satellites, launch vehicles, ground stations and gateways, spaceports and launch facilities, command and control centers, and other critical space infrastructure were also assessed. Segment-level estimates were reconciled across offerings, asset types, end users, applications, and regions to ensure consistency with the overall market size.
Market Definition
The space cybersecurity market includes all measures and technologies designed to protect space-based assets like satellites, ground stations, and other space infrastructure from cyber threats. This market covers the development and deployment of solutions that ensure the security of data transmission, communication networks, and mission-critical operations. It addresses the unique challenges posed by the space environment, such as the vast distances, harsh conditions, and the strategic importance of space assets, making cybersecurity a crucial element for military, commercial, and governmental space missions. As space technology becomes integral to various sectors, the scope of this market continues to expand, encompassing a wide range of applications from secure satellite communications to the protection of space infrastructure from sophisticated cyber-attacks.
Key Stakeholders
- Cybersecurity Technology & Component Providers
- Satellite & Spacecraft Manufacturers
- Payload & Onboard Computing Providers
- Ground-System & Ground-Station Providers
- Space Cybersecurity OEMs & System Integrators
- Satellite Operators & Service Providers
- Cloud, Network & Data Infrastructure Providers
- Secure Communications & Cryptography Providers
- Testing, Certification & Cyber Range Providers
- Managed Security Service Providers & SOC Operators
Report Objectives
- To define, describe, segment, and forecast the size of the space cybersecurity market based on type, asset type, end user, application, and region
- To forecast the size of the market segments across five regions: North America, Europe, Asia Pacific, Middle East and the Rest of the World
- To identify and analyze key drivers, restraints, opportunities, and challenges influencing the growth of the market
- To identify industry trends, market trends, and technology trends in the market
- To analyze micro markets with respect to individual technology trends, growth prospects, and their contribution to the overall market
- To strategically profile key market players and analyze their market position and core capabilities
- To provide a detailed competitive landscape of the market and analyze competitive strategies such as product launches, partnerships, agreements, and collaborations adopted by key players
- To assess the financial position of key players along with their key products, unique offerings, and recent developments
Available Customizations:
MarketsandMarkets offers the following customizations for this market report:
- Additional country-level analysis of the space cybersecurity market
- Profiling of other market players (up to 5)
Product Analysis
- Product matrix, which provides a detailed comparison of the product portfolio of each company in the space cybersecurity market
Get the Full Space Cybersecurity Market Report
Full forecast, segment splits, and company analysis for all Space Cybersecurity Market.
- Canada Space Cybersecurity Market
- US Space Cybersecurity Market
- UK Space Cybersecurity Market
- Germany Space Cybersecurity Market
- France Space Cybersecurity Market
- Italy Space Cybersecurity Market
- Japan Space Cybersecurity Market
- India Space Cybersecurity Market
- Australia Space Cybersecurity Market
- Malaysia Space Cybersecurity Market
- Israel Space Cybersecurity Market
- Rest Of Europe Space Cybersecurity Market
- Rest Of Asia Pacific Space Cybersecurity Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report